199
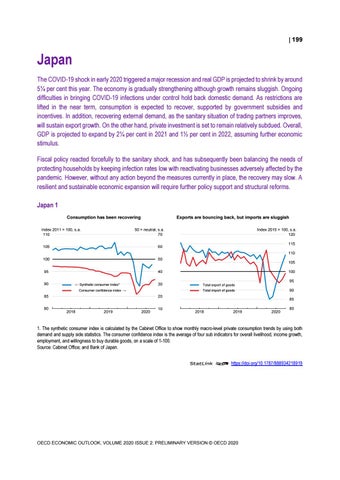
Japan The COVID-19 shock in early 2020 triggered a major recession and real GDP is projected to shrink by around 5¼ per cent this year. The economy is gradually strengthening although growth remains sluggish. Ongoing difficulties in bringing COVID-19 infections under control hold back domestic demand. As restrictions are lifted in the near term, consumption is expected to recover, supported by government subsidies and incentives. In addition, recovering external demand, as the sanitary situation of trading partners improves, will sustain export growth. On the other hand, private investment is set to remain relatively subdued. Overall, GDP is projected to expand by 2¼ per cent in 2021 and 1½ per cent in 2022, assuming further economic stimulus. Fiscal policy reacted forcefully to the sanitary shock, and has subsequently been balancing the needs of protecting households by keeping infection rates low with reactivating businesses adversely affected by the pandemic. However, without any action beyond the measures currently in place, the recovery may slow. A resilient and sustainable economic expansion will require further policy support and structural reforms. Japan 1 Consumption has been recovering Index 2011 = 100, s.a. 110
Exports are bouncing back, but imports are sluggish
50 = neutral, s.a. 70
105
60
100
50
95
40
Index 2015 = 100, s.a. 120 115 110
90
105 100 95
30
← Synthetic consumer index¹
Total export of goods
Consumer confidence index →
80
90
Total import of goods
85
20
2018
2019
2020
10
85 0
2018
2019
2020
80
1. The synthetic consumer index is calculated by the Cabinet Office to show monthly macro-level private consumption trends by using both demand and supply side statistics. The consumer confidence index is the average of four sub indicators for overall livelihood, income growth, employment, and willingness to buy durable goods, on a scale of 1-100. Source: Cabinet Office; and Bank of Japan. StatLink 2 https://doi.org/10.1787/888934218919
OECD ECONOMIC OUTLOOK, VOLUME 2020 ISSUE 2: PRELIMINARY VERSION © OECD 2020
200
Japan: Demand, output and prices 2017
2018
Current prices YEN trillion
Japan GDP at market prices Private consumption Government consumption Gross fixed capital formation Final domestic demand Stockbuilding1
Net exports1 Memorandum items GDP deflator Consumer price index2
_ _
Core consumer price index3
_ _ _ _ _ _
Unemployment rate (% of labour force) Household saving ratio, net (% of disposable income) General government financial balance (% of GDP) General government gross debt (% of GDP) Current account balance (% of GDP)
2020
2021
2022
Percentage changes, volume (2011 prices)
545.9 302.6 107.1 129.9 539.6 1.2 540.8 96.9 91.8 5.1
Total domestic demand Exports of goods and services Imports of goods and services
2019
0.3 0.0 0.9 0.6 0.3 0.0 0.3 3.5 3.7 0.0
0.7 0.1 1.9 1.3 0.8 0.1 0.8 -1.6 -0.7 -0.2
-5.3 -6.1 1.9 -4.7 -4.1 0.0 -4.1 -14.4 -7.6 -1.2
2.3 2.6 1.5 0.2 1.8 0.0 1.8 5.2 0.9 0.7
1.5 1.4 -0.4 2.4 1.2 0.0 1.2 4.8 1.7 0.5
-0.1 1.0
0.6 0.5
0.9 0.2
0.4 0.2
0.6 0.4
0.2 0.5 0.2 0.1 0.4 2.4 2.4 2.8 2.9 2.8 4.3 5.3 7.1 4.6 4.5 -2.3 -2.6 -10.5 -5.5 -3.5 224.2 225.3 241.6 243.3 243.9 3.6 3.6 3.0 3.6 3.9
1. Contributions to changes in real GDP, actual amount in the first column. 2. Calculated as the sum of the seasonally adjusted quarterly indices for each year. 3. Consumer price index excluding food and energy. Source: OECD Economic Outlook 108 database.
StatLink 2 https://doi.org/10.1787/888934218938
Japan 2 Wages have declined
Government expenditure was temporarily boosted
Index 2015 = 100¹ 104
% of GDP 55
103
50
General government net lending → ← General government total receipts
% of GDP 0
← General government total expenditures
-2
102 101 100 99 Nominal wages
98
-4
40
-6
35
-8
30
-10
Real wages
97 96
45
2018
2019
2020
0
25
2013 2014 2015 2016 2017 2018 2019 2020 2021 2022
-12
1. Nominal wages refer to total cash earnings per employee. Real wages are nominal wages deflated by the consumer price index of all items less imputed rent. Three-month moving average. Source: Ministry of Health, Labour and Welfare; and OECD Economic Outlook 108 database. StatLink 2 https://doi.org/10.1787/888934218957
OECD ECONOMIC OUTLOOK, VOLUME 2020 ISSUE 2: PRELIMINARY VERSION © OECD 2020
201
After a state of emergency, the economy is gradually reopening Confronted with the first wave of COVID-19 infections in March, the Japanese government declared a state of emergency from 7 April to 25 May. This enabled prefectural governors to order school closures, restrict the use of public facilities and request non-essential businesses to close. Even though confinement was not legally imposed, economic activity dropped dramatically as businesses closed or shifted to telework and households shielded themselves. This helped bring the spread of the coronavirus under control while the capacity for testing and medical care was stepped up. A second wave of infections between late-July and mid-August saw a limited rise in new cases of COVID-19 and a comparatively low death rate. While limiting the number of infections considerably below the health system’s capacity to cope with them, central and local governments gradually lifted the restrictions on large-scale events and other activities involving close personal interaction. Against this backdrop, it is assumed that the government will not need to impose comprehensive confinement measures and that the health situation will improve with the advent of a vaccine.
Consumption and exports are recovering, but investment is lagging Consumption appears to have recovered well with consumer sentiment picking up. Due to the rapid recovery of large trading partners, Japan’s exports have also started to recover, while imports have so far remained sluggish. Due to government subsidies for firms and employees, the unemployment rate has barely risen. However, wages have plummeted for many workers and will take time to recover, while job creation remains anaemic. Notwithstanding a recovery in industrial production, forward-looking indicators suggest continued weakness in investment, due to a low capacity utilisation rate and huge uncertainty about future growth. Consumer price inflation will be zero or slightly negative in the near term because of low demand, but is projected to edge up and turn positive as consumption and employment improve.
Government measures are protecting businesses and supporting households Since the onset of the pandemic, the government has launched several supplementary budgets, with a wide range of measures to support households and protect businesses and employment. These include cash handouts of JPY 100 000 to every resident, cash transfers to heavily affected business owners, expanding the Employment Adjustment Subsidy which provides firms with financial support to cover the cost of special paid leave, additional cash benefits for single-parent households and a rent subsidy to help heavily affected firms. The Bank of Japan has also acted to support the economy, expanding its policy to ensure financial stability by providing smooth and adequate financing through enhanced purchases of various assets and introducing interest-free loans against private debt as collateral. In addition, some public financial institutions provide interest-free loans to firms. The supplementary budgets also finance distinct measures for the recovery stage, including subsidies to support domestic services, and funding for digital transformation and supply-chain adjustments. For example, the authorities started promoting domestic tourism by providing coupons to households or reimbursing fixed amounts as digital cash. Furthermore, the government expanded the programme from October, by including dining in restaurants, visiting local shopping areas and travelling to and from Tokyo, which had been excluded thus far.
OECD ECONOMIC OUTLOOK, VOLUME 2020 ISSUE 2: PRELIMINARY VERSION © OECD 2020
202
The outlook is uncertain Following a sharp contraction in 2020, the economy is projected to recover slowly, with annual growth of around 2¼ per cent in 2021 and 1½ per cent in 2022. The recovery of major trading partners is set to support exports, whereas weak real income growth is likely to hold back private consumption. In addition, the Tokyo Olympic and Paralympic Games in summer 2021 are assumed to go ahead, which will temporarily boost consumption and exports though by less than anticipated earlier given the decline in international travel. Currently, the authorities are managing to limit the number of infections, but the risk of a larger-scale resurgence remains elevated. The sanitary situation will weigh on consumer sentiment until a vaccine becomes widely deployed, and will determine the size of the potential onsite audience for the Olympic and Paralympic Games. On the other hand, the recently signed Regional Comprehensive Economic Partnership (RCEP), through the effects of tariff reductions and rules of origin simplification, will support stronger trading relationships between members. The OECD projections assume an additional fiscal impulse worth around 0.5% of GDP in 2021-22, which would avoid an even sharper decline in public demand Without additional fiscal support from the supplementary budget, the recovery would be slower. However, the additional fiscal support will further push up public debt, which has reached unprecedented levels, exceeding 240% of GDP. The projections also assume that the Bank of Japan will maintain its stance, holding down interest rates on government bonds, until its inflation target is achieved.
Enhancing resilience, productivity and sustainability The immediate priority for policy is to support the recovery and react to further sanitary shocks to shield households and businesses. In designing policies, the government should focus on structural reforms that will enhance resilience, productivity and sustainability, as the economy continues to recover but remains exposed to pandemic-related threats. For those purposes, policies that promote flexible working styles are essential. This will require actions to adjust the social security system to allow for more flexibility in work and childcare, to reinforce the education system and to strengthen investment. Digitalisation, one of the new government’s main targets, can support these ambitions. Actions to facilitate teleworking and allow individuals to easily access online education and government services, including social security benefits, will support investment and job creation while enabling households to minimise their exposure to the pandemic. These actions should be inclusive and ensure that they cover the most vulnerable and those severely affected by COVID-19. In the longer term, action will still be needed to address underlying fiscal trends. The review of the government’s economic and fiscal framework in 2021 will be an opportunity to take stock of the impact of the coronavirus on the public finances and review progress to meeting mid-term targets. Finally, fiscal policy during the recovery ought to support reductions in greenhouse gas emissions, notably through increased research and development, use of renewable energy and energy efficiency.
OECD ECONOMIC OUTLOOK, VOLUME 2020 ISSUE 2: PRELIMINARY VERSION © OECD 2020