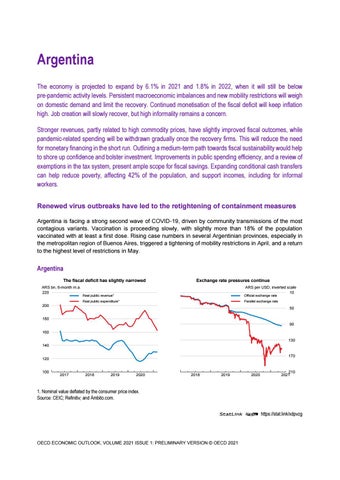
Argentina The economy is projected to expand by 6.1% in 2021 and 1.8% in 2022, when it will still be below pre-pandemic activity levels. Persistent macroeconomic imbalances and new mobility restrictions will weigh on domestic demand and limit the recovery. Continued monetisation of the fiscal deficit will keep inflation high. Job creation will slowly recover, but high informality remains a concern. Stronger revenues, partly related to high commodity prices, have slightly improved fiscal outcomes, while pandemic-related spending will be withdrawn gradually once the recovery firms. This will reduce the need for monetary financing in the short run. Outlining a medium-term path towards fiscal sustainability would help to shore up confidence and bolster investment. Improvements in public spending efficiency, and a review of exemptions in the tax system, present ample scope for fiscal savings. Expanding conditional cash transfers can help reduce poverty, affecting 42% of the population, and support incomes, including for informal workers. Renewed virus outbreaks have led to the retightening of containment measures Argentina is facing a strong second wave of COVID-19, driven by community transmissions of the most contagious variants. Vaccination is proceeding slowly, with slightly more than 18% of the population vaccinated with at least a first dose. Rising case numbers in several Argentinian provinces, especially in the metropolitan region of Buenos Aires, triggered a tightening of mobility restrictions in April, and a return to the highest level of restrictions in May.
Argentina The fiscal deficit has slightly narrowed ARS bn, 6-month m.a. 220
Exchange rate pressures continue ARS per USD, inverted scale 10
Real public revenue¹
Official exchange rate
Real public expenditure¹
Parallel exchange rate
200
50
180 90 160 130 140 170
120 100
2017
2018
2019
2020
0
0
2018
2019
2020
210 2021
1. Nominal value deflated by the consumer price index. Source: CEIC; Refinitiv; and Ámbito.com. StatLink 2 https://stat.link/xdpvzg
OECD ECONOMIC OUTLOOK, VOLUME 2021 ISSUE 1: PRELIMINARY VERSION © OECD 2021
4
Argentina: Demand, output and prices 2017
2018
GDP at market prices Private consumption Government consumption Gross fixed capital formation Final domestic demand Stockbuilding1 Total domestic demand Exports of goods and services Imports of goods and services Net exports1
2020
2021
2022
Percentage changes, volume (2004 prices)
Current prices ARS billion
Argentina
2019
10 660.2 7 114.6 1 886.5 1 616.3 10 617.4 325.2 10 942.6 1 206.8 1 489.2 - 282.4
-2.6 -2.2 -1.7 -6.0 -2.8 -0.9 -3.7 0.5 -4.5 0.7
-2.1 -6.6 -1.0 -16.0 -7.1 -2.0 -8.7 9.0 -19.0 4.5
-9.9 -13.1 -4.7 -13.0 -11.9 1.5 -10.1 -17.7 -18.1 -0.3
6.1 2.2 0.8 18.2 4.0 4.0 7.7 6.8 14.2 -0.8
1.8 1.0 -1.1 0.8 0.6 0.0 0.3 11.3 3.8 1.3
_ _
40.0 -4.8
50.6 -0.7
39.8 0.6
42.4 2.6
40.4 3.0
Memorandum items GDP deflator Current account balance (% of GDP) 1. Contributions to changes in real GDP, actual amount in the first column. Source: OECD Economic Outlook 109 database.
StatLink 2 https://stat.link/vtwp9h
Economic activity is recovering slowly Economic activity fell by 9.9% in 2020. The second half of 2020 and first months of 2021 saw a gradual pick-up in growth amid a reopening of activities, but new mobility restrictions imposed as of April are slowing the recovery. Employment decreased sharply during 2020 in line with economic activity. Informal workers and those working in services were the hardest hit. Tight currency restrictions presently limit imports, while higher commodity prices and a strong recovery in China are buoying exports. Annual inflation is hovering around 40%, despite weak domestic demand and strict price controls. High inflation and significant labour market slack are weighing on household incomes, holding back private consumption. The delay in the agreement with the IMF and uncertainties surrounding upcoming debt repayment obligations have created pressures on the value of public securities, some of which were restructured in September 2020.
Policies have supported household incomes and firms Bold and timely measures have been taken to contain the pandemic and support households. Cash transfers and reinforced unemployment benefits have supported the poor and vulnerable. Wage subsidies and lower payroll tax liabilities have helped some firms, partially compensating for the costs of a generalised ban on dismissals. The COVID-19 response included additional spending in social programmes of 2.2% of GDP. Higher commodity prices and the associated export tax revenues are limiting immediate pressures on the parallel exchange rate and the need for monetary financing in the short term.
OECD ECONOMIC OUTLOOK, VOLUME 2021 ISSUE 1: PRELIMINARY VERSION © OECD 2021
5
Growing macroeconomic imbalances limit the recovery GDP is projected to grow slightly above 6% in 2021 and below 2% in 2022. Rising macroeconomic imbalances will weigh on domestic demand and limit the recovery. The reopening of domestic activities and vaccination will proceed slowly, with herd immunity expected to be achieved in 2022. High unemployment, stagnant wages and rising informality erode Argentines’ purchasing power, especially for low-income households. Tight capital controls, a policy mix of price controls and import restrictions and higher corporate taxes will weigh on investment and imports. Risks to the outlook are tilted to the downside and include a disorderly unwinding of macroeconomic imbalances. Ongoing negotiations with external creditors aim to restructure debt repayments falling due in 2021. Low international reserves provide little scope for support in the case of renewed pressures on the currency, and a sudden devaluation would further fuel already high inflation. The current wave of COVID-19 infections and the possible appearance of new variants, together with the slow vaccination process could lead to prolonged lockdowns. On the upside, a swifter domestic and international vaccination campaign, a faster recovery in neighbouring Brazil, as well as a more competitive exchange rate could further support exports.
Reducing imbalances and facilitating structural change are key for the recovery Accelerating the vaccination process would help to limit setbacks in the fight against COVID-19. Reducing macroeconomic imbalances will be key to rekindle confidence, and this will require prudent fiscal policies, less monetary financing of the deficit, strengthening the credibility and independence of the central bank, and eventually a removal of foreign exchange controls. A credible medium-term fiscal strategy centred on improvements in public spending efficiency and reducing tax exemptions and subsidies would improve the fiscal position and pave the way for reducing macroeconomic imbalances. Broadening the personal income tax base while enhancing tax progressivity would further support this. A stronger and more inclusive recovery will require fostering formal job creation and strengthening social protection, building on existing cash transfer schemes, while simultaneously reducing the cost of creating formal jobs, especially in the hardest hit sectors.
OECD ECONOMIC OUTLOOK, VOLUME 2021 ISSUE 1: PRELIMINARY VERSION © OECD 2021