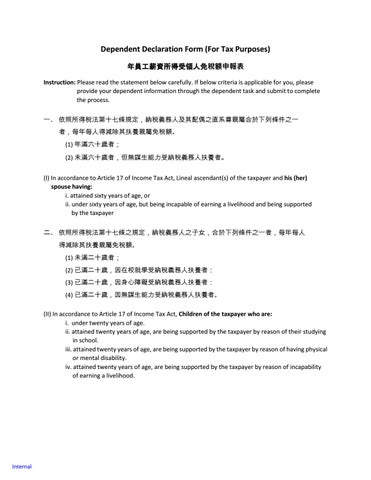
Dependent Declaration Form (For Tax Purposes) 年員工薪資所得受領人免稅額申報表 Instruction: Please read the statement below carefully. If below criteria is applicable for you, please provide your dependent information through the dependent task and submit to complete the process. 一、 依照所得稅法第十七條規定,納稅義務人及其配偶之直系尊親屬合於下列條件之一 者,每年每人得減除其扶養親屬免稅額。 (1) 年滿六十歲者; (2) 未滿六十歲者,但無謀生能力受納稅義務人扶養者。 (I) In accordance to Article 17 of Income Tax Act, Lineal ascendant(s) of the taxpayer and his (her) spouse having: i. attained sixty years of age, or ii. under sixty years of age, but being incapable of earning a livelihood and being supported by the taxpayer 二、 依照所得稅法第十七條之規定,納稅義務人之子女,合於下列條件之一者,每年每人 得減除其扶養親屬免稅額。 (1) 未滿二十歲者; (2) 已滿二十歲,因在校就學受納稅義務人扶養者: (3) 已滿二十歲,因身心障礙受納稅義務人扶養者: (4) 已滿二十歲,因無謀生能力受納稅義務人扶養者。 (II) In accordance to Article 17 of Income Tax Act, Children of the taxpayer who are: i. under twenty years of age. ii. attained twenty years of age, are being supported by the taxpayer by reason of their studying in school. iii. attained twenty years of age, are being supported by the taxpayer by reason of having physical or mental disability. iv. attained twenty years of age, are being supported by the taxpayer by reason of incapability of earning a livelihood.
Internal
三、依照所得稅法第十七條之規定,納稅義務人及其配偶之同胞兄弟姐妹合於下列條件之 一者,每年每人得減除其扶養親屬免稅額。 (1) 未滿二十歲者; (2) 已滿二十歲,因在校就學受納稅義務人扶養者: (3) 已滿二十歲,因身心障礙受納稅義務人扶養者: (4) 已滿二十歲,因無謀生能力受納稅義務人扶養者。 (III) In accordance to Article 17 of Income Tax Act, brothers and sisters of the taxpayer and his (her) spouse who are: i. under twenty years of age. ii. although having attained twenty years of age, are being supported by the taxpayer by reason of their studying in school. iii. although having attained twenty years of age, are being supported by the taxpayer by reason of having physical or mental disability. iv. although having attained twenty years of age, are being supported by the taxpayer by reason of being incapable of earning a livelihood.
四、 依照所得稅法第十七條之規定,納稅義務人其他親屬或家屬,合於下列條件之一者, 每年每人得減除其扶養親屬免稅額。 合於民法第一千一百十四條第四款及第一千一百二十三條第三項之規定,未滿二十 歲,或滿二十歲以上而因在校就學、身心障礙或無謀生能力,確係受納稅義務人扶養者。 (IV) In accordance to Article 17 of Income Tax Act, other relatives or family members of the taxpayer within the meaning of sub-paragraph 4, Article 1114 of the Civil Code and paragraph 3, Article 1123 of the Civil Code, who are under twenty years of age or over twenty years of age and are incapable of earning a livelihood and are supported by the taxpayer. (please refer Article 1123 and 1114 as below)
Internal
附註:民法第一千一百十四條:左列親屬,互負扶養之義務: 一、直系血親相互間。 二、夫妻之一方,與他方之父母同居者,其相互間, 三、兄弟姐妹相互間。 四、家長家屬相互間。 民法第一千一百二十三條:家置家長。 同家之人除家長外均為家屬。 雖非親屬,而以永久共同生活為目的同居一家者,視為家屬。 Note: Article 1114 of Civil Code: The following relatives are under a mutual obligation to maintain one another: • Lineal relatives by blood; • One of the husbands and wives and the parents of the other party living in the same household; • Brothers and sisters; • The head and the members of a house. Article 1123 of Civil Code: • Each house shall institute a head. • Persons belong to the same house, except the head of the house, the members of the house. • Persons who are not relatives but who live in the same household with the object of maintaining the common living permanently are deemed to be the members of the house.
Internal