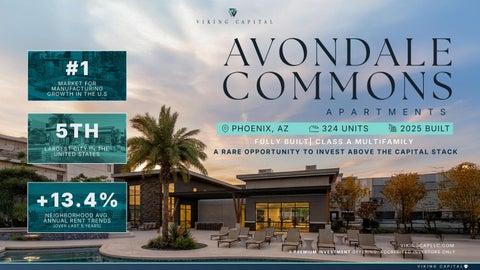
#1 MARKET FOR MANUFACTURING GROWTH IN THE U.S
AVON DA L E C O M M ON S A P A R T M E N T S
5TH LARGEST CIT Y IN THE UNITED STATES
PHOENIX, AZ
324 UNITS
2025 BUILT
FULLY BUILT| CLASS A MULTIFAMILY A RARE OPPORTUNITY TO INVEST ABOVE THE CAPITAL STACK
+13.4% NEIGHBORHOOD AVG. ANNUAL RENT TRENDS (OVER LAST 5 YEARS)
V I K I N G CA P L LC .C O M A PREMIUM INVESTMENT OFFERING: ACCREDITED INVESTORS ONLY V I K I N G
C A P I T A L
D I S C L O S U R E S This presentation is for informational purposes only and does not constitute an offer to sell or a solicitation to purchase any security. Any offering is made only through the applicable Private Placement Memorandum (PPM), subscription documents, and related offering materials. Investments involve risk, including the possible loss of principal. There is no guarantee of returns, distributions, or investment objectives. Any projected, targeted, or estimated returns are forward-looking statements and are not guarantees of future performance. Real estate investments are illiquid and may not be suitable for all investors. Preferred equity investments are subordinate to senior debt and involve additional risks. Past performance is not indicative of future results. Tax, legal, and retirement account information provided is for educational purposes only. Investors should consult their own professional advisors. Investing through a self-directed IRA involves specific rules and requirements. Investors should consult their custodian and advisors before investing. Please review all offering documents carefully and conduct your own due diligence prior to making any investment decision. The material contained in this Offering Memorandum is confidential, furnished solely for the purpose of considering an investment in the Property and is not to be used for any other purpose or made available to any other person without the written consent of Viking Capital LLC. The material has been obtained from sources Viking Capital deems to be reliable; however, Viking and its affiliates make no representations or warranties regarding the accuracy or completeness of this material. Among other considerations, prospective investors should recognize that this Offering Memorandum contains forward-looking statements (including projections as to construction schedules and costs, operating results, and economic trends), all of which are inherently speculative and many of which are based on future events not within the control.
V I K I N G
C A P I T A L
MEET OUR TEAM
Vikram Raya
CEO, Founder
Dr. Vikram Raya is an experienced investment strategist, entrepreneur, and capital markets leader with over a decade of experience sourcing and scaling institutional-grade real estate investments. As a Co-Founder, he leads the firm’s investment strategy, capital deployment, and strategic partnerships across high-growth, supply-constrained markets. A Georgetown University graduate, Vikram brings a disciplined, performancedriven approach to the full investment lifecycle, from market selection and operator diligence to fund design and investor alignment. Since founding, he helped grow Viking Capital into a nationally recognized multifamily platform, acquiring over $1 billion in assets, managing more than 5,000 units, and raising over $250 million in equity.
Chris Parrinello SVP, Capital Markets & Head of Investor Relations
Chris Parrinello is a capital markets executive focused on institutional capital formation, portfolio construction, and long-term investor alignment within private real estate. As Senior Vice President of Capital Markets and Head of Investor Relations at Viking Capital, he leads capital strategy and investor engagement, working closely with RIAs, family offices, and high-net-worth investors to integrate multifamily real estate into diversified portfolios. His approach emphasizes risk-adjusted returns, capital stack structuring, and transparency throughout the investment lifecycle. Chris has raised over $350 million in private capital and played a key role in scaling Viking Capital’s investor platform to more than 1,100 investors, supporting the firmʼs growth and institutional positioning. He is an active contributor within the investment community, frequently speaking on alternative asset allocation, capital markets strategy, and the role of private real estate in modern portfolio construction. V I K I N G
C A P I T A L
ABOUT VIKING CAPITAL
2015 YEAR FOUNDED
6,522 TOTA L U N I T S AC Q U I R E D
$1.02B
Viking Capital is a multifamily real estate-focused investment firm. The original and institutional holding company for Viking Capital was established in 2015 and was created to serve the unique needs of institutional partners, family offices, high-net-worth investors, and advisory groups seeking access to high-performing multifamily investments. Viking Capital focuses on acquiring, developing, and optimizing highquality multifamily communities in growth markets throughout the United States. The firm’s strategy is rooted in disciplined market selection, operational precision, and a long-term commitment to quality—delivering consistent value to investors and an elevated standard of living for residents. By combining institutional rigor with community-forward thinking, Viking fosters sustainable, income-producing assets designed to outperform across market cycles.
C U M U L AT I V E AU M
V I K I N G
C A P I T A L
CYCLE-TESTED PERFORMANCE Viking Capital is a multifamily investment firm focused on disciplined execution, risk management, and long-term value creation across different market cycles.
6,522
Units
TOTA L U N I T S AC Q U I R E D
7,000 6,500 6,000 5,500 5,000 4,500 4,000 3,500 3,000 2,500 2,000 1,500 1,000 500 200 0
Rates & Supply
DFW SAN ANTONIO
Economic Downturns
PHOENIX
NASHVILLE
ATLANTA
COVID-19
HOUSTON SAN ANTONIO SOUTH BEND WASHINGTON, DC DALLAS AUSTIN ATLANTA
2015
2017
2018
2020
2021
2022
2023
2024
2025 V I K I N G
C A P I T A L
Viking Capital’s Track Record Disclaimer: This track record reflects all Viking Capital exits and corresponding performance metrics to date. While these results were achieved during a historically favorable period for multifamily dispositions, they demonstrate the firm’s disciplined execution, value creation, and successful realization strategies. Past performance was influenced by market conditions and is not necessarily indicative of results in the current or future economic environment. Please note that all properties marked with an asterisk () represent joint venture partnerships.*
Exit Date
Units
Projected Hold Period (Yrs)
Hold Purchase Period Price (Yrs)
Sale Price
Total Cap.
Deal Name
Location
Acq. Date
Projected IRR
Realized IRR
Projected CoC
Realized CoC
Projected EM
Realized EM
Reserve at Walnut Creek*
Austin, TX
2019
2022
284
4
3
$36.3M
$46.825M $40.615M $15.75M $24.865M 68.50%
15%
27.90%
8.27%
7.20%
2.37x
2.14x
19.61%
35.20%
Estates at Las Colinas*
Dallas, TX
2019
2022
415
4
3
$61.75M
$79.19M
$65.175M
$19M
$46.3M
75%
19.80%
22.20%
9%
6%
2.27x
1.73x
25.30%
25%
The Avery*
Dallas, TX
2017
2022
304
4
5
$40.8M
$59.25M
$43.78M
$15M
$30.6M
75%
18%
19.20%
8.70%
5.50%
2.1x
1.9x
22%
21.60%
Ascent at Riverdale I
Atlanta, GA
2017
2019
118
4
2
$4.125M
$6.732M
$5.9M
$1.95M
$3.3M
80%
17.85%
34.70%
9.50%
9.50%
2.03x
1.76x
22.64%
38%
Wildcreek*
Atlanta, GA
2015
2018
242
4
3.25
$15.3M
$20.963M
$16.6M
$5.75M
$11.475M
75%
20.67%
15.20%
9.16%
9.12%
2.03x
1.65x
20.70%
20%
Hills at East Cobb*
Atlanta, GA
2018
2021
268
4
3
$33.25M
$39M
$35.6M
$9.4M
$26.2M
79%
16.50%
4.80%
8.38%
7.83%
2.09x
1.1x
21.91%
3.30%
Villas of South Cobb I*
Atlanta, GA
2016
2018
188
4
2.5
$12.4M
$15.32M
$14.22M
$4.3M
$9.92M
80%
17.80%
25.10%
8.80%
8.13%
2.01x
1.48x
20.20%
19%
Villas of South Cobb II*
Atlanta, GA
2016
2019
152
4
2.5
$10.25M
$13.35M
$12M
$4.313M $7.687M
75%
17.20%
25.30%
8.90%
8.18%
2.03x
1.48x
20.73%
19%
Equity
Debt
LTV
Projected Realized AAR AAR
V I K I N G
C A P I T A L
CURRENT PROPERTIES
OPEN RAISE AVONDALE COMMONS
Property Details
A
Asset Class
Avondale, AZ
2025
Year Constructed
324
No. of Units
OPEN RAISE PEORIA GATEWAY
Property Details
B
Asset Class
Atlanta MSA, GA
1988
Year Constructed
188
No. of Units
ELEVATE ON MAIN
Property Details
B+
Asset Class
South Bend, IN
2000
Year Constructed
400
No. of Units
2026
A
Year Constructed
Asset Class
ELEVATE AT STEWARTS MILL
Property Details
Phoenix, AZ
200
No. of Units
PARK 33
Property Details
B+
Asset Class
2018
188
No. of Units
ELEVATE WOODSTOCK
Property Details
B
Asset Class
Atlanta, GA
1986
Year Constructed
Property Details
B
Asset Class
Nashville, TN
1985
Year Constructed
232
No. of Units
ELEVATE GREENE
South Bend, IN
Year Constructed
THE HAMILTON PREMIER APARTMENTS
120
No. of Units
Property Details
B
Asset Class
Atlanta, GA
2005
Year Constructed
252
No. of Units
AVONDALE HILLS
Property Details
A
Asset Class
B+
Asset Class
Stockbridge, GA
1999
Year Constructed
368
No. of Units
2022
Year Constructed
240
No. of Units
Property Details
A
Asset Class
ELEVATE EAGLE’S LANDING
Property Details
B+
Asset Class
MARBELLA PLACE
Property Details
Atlanta MSA, GA
THE TOWNHOMES AT BLUEBONNET TRAILS
Atlanta, GA
2006
Year Constructed
176
No. of Units
A
Asset Class
Washington, DC
2010
Year Constructed
2020-2021 Year Constructed
114
No. of Units
A
Asset Class
Houston, TX
2007
Year Constructed
49
No. of Units
Property Details
B
Asset Class
192
No. of Units
Marietta, GA
1980
Year Constructed
AUSTIN/ SAN ANTONIO TX
2012
A
Year Constructed
Asset Class
252
No. of Units
ELEVATE AT HUEBNER GROVE
KINGS COVE
Property Details
Property Details
Property Details
B
Asset Class
VERITAS AT EAST COBB
THE GRIFFIN
Property Details
Dallas-Fort Worth, TX
VILLAS AT SUNDANCE
192
No. of Units
1981
B
Asset Class
1960
Atlanta MSA, GA
1998
Year Constructed
Property Details Asset Class
Atlanta, GA
Year Constructed
B+
Asset Class
B
210
No. of Units
THE HYPE
Property Details
Property Details
268
No. of Units
ELEVATE AT THE POINTE
San Antonio, TX
Year Constructed
ELEVATE AT DAWSON FOREST
14
No. of Units
Atlanta, GA
1969
Year Constructed
181
No. of Units
A P A R T M E N T S
PROPERTY SUMMARY W MCDOWELL RD & N AVONDALE BLVD, AVONDALE, AZ
324
UNITS
2025
YEAR BUILT
337,159
RENTABLE SF
935
AVG UNIT SF
4
CONSTRUCTION
STORY + TOWNHOMES
606
STRUCTURED PARKING SPACES
AERIAL IMAGE V I K I N G
C A P I T A L
INVESTMENT HIGHLIGHTS
324 UNITS
PHOENIX, AZ
202 5 Year Built
16% 21% ~2x IRR
AAR
Equity Multiple
V I K I N G
C A P I T A L
V I K I N G
C A P I T A L
FOUR YEARS OF DEVELOPMENT COMPLETE- NOW IS LEASE UP
V I K I N G
C A P I T A L
PROJECT WINS
A Stronger Project Today Loan Extension Completed All loan documents signed
Avoided an Expensive Refinance
Funding finalized
No bridge financing needed
Project is moving forward
Saved $1.5 M in fees
Improved Interest Rate Floating rate now at 6.1%, down 4.5 points from the initial pricing
Loan Extension Completed
Construction Complete
Favorable terms secured on ~$3M in remaining construction obligations
Fully built project
Reduced near-term carrying costs and improved liquidity to supports lease-up
Now focused on leasing, stabilzation, and execution
V I K I N G
C A P I T A L
STRATEGIC ENTRY POINT
Most Investors Fund Risk. Very Few Enter After It.
CONSTRUCTION
100% COMPLETE
Why This Rare Opportunity Exists Today.
9:1
GROCAPITUS
INVESTOR APPROVAL
Rising interest rates and inflation drove construction costs above plan, requiring additional equity to complete lease-up and stabilization. Viking provided new capital senior to existing equity, with the recapitalization approved by existing investors at a 9:1 vote.
LOAN EXTENSION SECURED
Better than refinance – lower rate, zero costs, full amount preserved.
Why This Matters: We avoided approximately $1.5M in refinancing costs Kept the full $75M loan Cut the interest rate by ~600 basis points. This directly improves cash flow and your return.
TERM |
ORIGINAL LOAN | REFINANCE OPTION | NEW EXTENSION SOFR+750 (~11%)
SOFR+400 (~7.5-8%)
SOFR+250 (~6%)
Loan Amount
$75M
Reduced / uncertain
$75M (full)
Maturity
Expired
New 3-5 yr term
Sept 2028
Refinance Cost
N/A
$1.5-$2M+
$0
Rate
V I K I N G
C A P I T A L
MAJOR PROJECT WIN
FAVORABLE TERMS NEGOTIATED ON $3M IN CONSTRUCTION COSTS The successful extension included favorable terms on roughly $3M of remaining construction obligations. That reduces near- term carrying costs and puts more liquidity behind leasing and marketing—right as the project needs it most to reach stabilization. MORE CASH FOR LEASE UP & MARKETING
DEAL STRUCTURE
The Avondale Commons investment is structured to strategically optimize returns while maintaining downside protection.
WHERE YOU SIT IN THE DEAL
HIGH RISK
EXISTING EQUITY Your preferred equity position —
SUBORDINATE PREF EQUITY
PROTECTED, CONTRACTUAL, AND FIRST IN LINE.
VIKING PREFERRED EQUITY SENIOR LOAN
YOUR POSITION
MINIMUM RETURN
VIKING EQUITY
SENIOR LOAN
PREFERRED
16% IRR
$18M
$75M
First to be paid before any equity distributions to sponsors or common investors
Contractuall minimum internal rate of return on your investment
Viking has already raised $12 M. ONLY $6M in allocations left.
LOW RISK
Full loan amount maintained with improved terms — no reduction in financing
V I K I N G
C A P I T A L
CAPITAL STRUCTURE OVERVIEW
PREMIUM POSITION IN THE CAPITAL STACK EXISTING LP EQUITY
$27M
Existing sponsor and developer equity capital already invested in land acquisition, construction, and completion.
LAST
EXISTING EQUITY SUBORDINATE PREFERRED EQUITY
$4.5M
Existing preferred equity already invested in land acquisition, construction, and completion sits ahead of the original equity.
3RD
VIKING EQUITY
$18M
Viking’s equity establishes strong alignment of interest with investors and underpins the projectʼs execution strategy and governance oversight.
2ND
New capital enters at a structurally advantaged position in the capital stack. $31.5M existing equity remains fully invested— continuing to support the asset while absorbing downside first.
DEBT
$75M
Senior loan financing secured at favorable terms, providing efficient leverage and stability within the overall capitalization.
1ST HIGHEST PRIORITY IN THE CAPITAL STACK
PROTECTED BY $31.5M JUNIOR TO YOU
V I K I N G
C A P I T A L
HOW VIKING CAPITAL STACKS AGAINST THE REST
Risk & Return Comparison Viking Capital Equity
Common Equity
Senior to all existing equity
First loss position
Paid first Lowest
Paid last Highest
Returns
Class B: 80/20 Reserve Class: 90/10
No Cap on backend profits
Taxation
Up to 90% Bonus Depreciation $31.5 M in equity junior to this position
K1 w/ depreciation losses No structural protection
Capital Stack Position Payment Priority Risk Profile
Downside Protection
V I K I N G
C A P I T A L
RETURN PROFILE
VIKING CAPITAL— PREFERRED EQUITY OUTCOMES Three scenarios — all anchored by your contractual 16% minimum
SCENARIO
IRR
CASH-ON-CASH
Minimum (Contractual)
16%
3.0%
16%+
Growing Distributions
Current trajectory — leaseup on schedule
8–10%
Agency refinance at stabilization unlocks equity
Base Case Upside (Agency Refi)
18–22%
NOTES Floor — contractual
V I K I N G
C A P I T A L
PROFORMA YEAR 1 (Sept. 2026)
YEAR 2 (Sept. 2027)
YEAR 3 (Sept. 2028)
YEAR 4 (Sept. 2029)
YEAR 5 (Sept. 2030)
PER UNIT (YEAR 3)
Gross Potential Income
$6,574,198
$7,017,270
$7,223,298
$7,442,908
$7,669,291
$22,294
Loss to Lease
($1,544)
-
-
-
-
-
($4,969,638)
($932,575)
($450,448)
($372,145)
($383,465)
($1,390)
Concessions
($471,551)
($665,459)
($305,982)
($111,227)
($76,693)
($944)
Other Rent Loss
($212,082)
($334,969)
($107,946)
($74,429)
($76,693)
($333)
Effective Gross Rental Income
$919,383
$5,084,267
$6,358,923
$6,885,107
$7,132,441
$19,626
Total Other Income
$236,093
$833,771
$858,251
$884,344
$911,243
$2,649
Total Net Income
$1,155,476
$5,918,038
$7,217,174
$7,769,451
$8,043,683
$22,275
Real Estate Taxes
$275,816
$303,291
$310,393
$316,693
$323,086
$958
Insurance
$81,488
$111,039
$113,639
$115,946
$118,286
$351
Contract Services
$115,143
$195,298
$199,871
$203,928
$208,044
$617
Utilities
$214,239
$292,969
$300,529
$307,219
$313,681
$928
Management Fee
$106,900
$157,442
$180,429
$194,236
$201,092
$557
Repairs and Maintenance
$29,100
$63,660
$65,151
$66,473
$67,815
$201
General/Admin
$99,132
$188,803
$193,225
$197,147
$201,126
$596
Advertising and Leasing
$187,436
$200,042
$204,726
$208,882
$213,098
$632
Payroll
$491,434
$702,243
$718,689
$733,277
$748,077
$2,218
Total Expenses
$1,617,169
$2,247,173
$2,319,098
$2,376,314
$2,427,214
$958
175.90%
44.20%
36.50%
34.50%
34.00%
Net Operating Income (NOI)
($461,693)
$3,670,865
$4,898,076
$5,393,137
$5,616,469
NOI per Unit
($1,425)
$11,330
$15,117
$16,646
$17,334
INCOME
Vacancy
EXPENSES
% EGI
$15,118
*Subject to change before closing V I K I N G
C A P I T A L
RETURNS
5 YEAR PROJECTED RETURNS BY CLASS
CLASS B $100K
AVG COC
5.2%
EM
1.86X
$7,000
AAR
17.2%
$60,000
PREF
7%
AVG COC
5.2%
EM
1.93X
YEAR 1 3%
YEAR 2 4%
YEAR 3
YEAR 4
YEAR 5
5%
7%
7%
ANNUAL DISTRIBUTION $3,000
$4,000
$5,000
$7,000
-
-
-
ANNUAL RETURN
EQUITY SPLIT 80/20
-
T O T A L E X P E C T E D R E T U R N O F C A P I T A L $186,000
RESERVE CLASS $500K
YEAR 1
YEAR 2
YEAR 3
YEAR 4
YEAR 5
3%
4%
5%
7%
7%
ANNUAL DISTRIBUTION
$15,000
$20,000
$25,000
$35,000
$35,000
AAR
18.6%
EQUITY SPLIT 90/10
-
-
-
-
$335,000
PREF
8%
ANNUAL RETURN
T O T A L E X P E C T E D R E T U R N O F C A P I T A L $965,000
PROJECTIONS MAY VARY BASED ON PROPERTY PERFORMANCE V I K I N G
C A P I T A L
BONUS DEPRECIATION
Bonus depreciation for Viking investors ORIGINAL PROJECTION
40-50% What was originally underwritten and communicated
Secured Rate Up Up to to
90%
EXAMPLE OF LOSS PER $100K
$90K
Paper loss allocated per $100,000 invested — usable against passive income
Funding deadline Sept. 10th
TIMING MATTERS, INVEST BEFORE SEPTEMBER 10TH V I K I N G
C A P I T A L
KEY RISKS
RESOLVED vs. REMAINING Three of four major risks have been fully resolved. One remains active on track. REFINANCE RISK
FORECLOSURE RISK
RESOLVED
RESOLVED
Loan extended at SOFR+250 – no refinancing required until Sept. 2028
Lender relationship secured, extension executed – no foreclosure risk
RESOLVED
RESOLVED
CAPITAL CALL RISK
LEASE-UP EXECUTION
RESOLVED
ACTIVE
$3M is being raised externally – no additional capital required from existing investors
Ongoing – currently ahead of schedule at 30% pre-leased with Mark Taylor onboarded
RESOLVED
ACTIVE - AHEAD OF SCHEDULE
V I K I N G
C A P I T A L
BEST-IN-CLASS PROPERTY MANAGEMENT INCOMING
Proactive upgrade to maximize lease-up velocity and long-term performance.
NEW MANAGER
WHY THE CHANGE
PORTFOLIO UPGRADE Ranked #1 property management firm in Phoenix – proven track record in multifamily lease-up
This is a proactive, portfolio-wide upgrade – not a reaction to any failure or underperformance
Why this matters: Better leasing velocity, stronger tenant quality, lower vacancy, and improved NOI – all of which directly support your preferred return and the path to distributions. V I K I N G
C A P I T A L
AHEAD OF SCHEDULE ON LEASE-UP
Strong early momentum — velocity accelerating into summer leasing season.
Currently Occupied
25% Units occupied and generating rental income today
Pre-Leased
Monthly Velocity
30%
15–20
Signed leases with move-ins scheduled
New leases signed per month and accelerating
90-Day Outlook: We expect 45–60 additional leases in the next 90 days. At that pace, the property should have (CofO) within 90 days and cash flow by December.
V I K I N G
C A P I T A L
UNIT MIX
3 BR 2.5 BA 16 Units 5%
3 BR 2 BA 16 Units 5%
1 BR 1 BA 176 Units 55%
2 BR 2.5 BA 16 Units 5%
2 BR 2 BA
100 Units 30%
Avondale Commons offers spacious townhomes and right-sized apartments designed for growing families and young professionals.
V I K I N G
C A P I T A L
SITE PLAN
POOL & OUTDOOR AREA MIXED USED BUILDING
RESTAURANT
LUXURY APARTMENTS
RESTAURANT
RETAIL
V I K I N G
C A P I T A L
WHY WE LOVE THIS DEAL
OFF MARKET ADVANTAGE:
FLIGHT TO QUALITY
We secured this deal off-market, at a major discount, allowing us to negotiate favorable terms and avoid the bidding war environment typical in Phoenix today.
This mix of modern apartments and townhomes offers the high-quality housing today’s renters demand.
LOW ENTRY BASIS:
HIGHER PREFERRED RETURN
Our preferred equity position is secured well below construction cost, providing a strong margin of safety and favorable upside potential.
16% IRR net to the deal is built into the structure, providing additional risk mitigation and investment confidence.
PATH OF PROGRESS & CLOSE TO STRONG ECONOMIC DRIVERS:
SAFETY IN THE CAPITAL STACK
Avondale is experiencing explosive growth, driven by major employers like Intel, AI tech firms, and healthcare giants migrating to the West Valley.
HIGH DEMAND, LIMITED SUPPLY Strong renter demand paired with a low pipeline of new deliveries supports long-term rent growth.
ECONOMIES OF SCALE: With another new build underway in Peoria, we’re unlocking economies of scale across operations, allowing us to streamline costs, share resources, and enhance overall returns for both projects.
Viking’s equity position places our investors ahead of the existing preferred and common equity, reducing downside risk.
BIGGER TAX ADVANTAGES Reallocating up to 90% of bonus depreciation creates larger upfront paper losses, lowering your tax bill immediately.
INVESTOR-FIRST CONTROL Viking holds full governance authority to protect investor interests at every stage.
V I K I N G
C A P I T A L
PROPERTY LOCATION
WESTGATE
WINGWAM GOLF CLUB
Glendale
Avondale
DESERT SKY MALL
AVO N DA L E C O M M O N S
PHOENIX CHILDREN’S EMERGENCY DEPT.
TALKING STICK RESORT AMPITHEATRE
HARKINS THEATRES ESTRELLA FALLS
GATEWAY CROSSING
RETAIL & RESTAURANTS
Goodyear GOODYEAR BALL PARK
PHOENIX/GOODYEAR AIRPORT
AVID HOTEL RETAIL & REHAB CENTERS AKOS MEDICAL CAMPUS PHASE 2
V I K I N G
C A P I T A L
AVONDALE CATALYST FOR GROWTH
40% RENTER OCCUPIED
+4.5% +3.6% WAGE GROWTH OVER THE YEAR
POPULATION GROWTH OVER THE PAST 2 YEARS
83.1%
55.9%
PLENTIFUL JOBS WITHIN 45 MINS.
WHITE COLLAR JOBS
V I K I N G
C A P I T A L
AVONDALE DEMOGRAPHICS
$102,820 AVERAGE HOUSEHOLD INCOME
100,130
2M ANNUAL VISITORS
235,099
POPULATION
DAILY TRAFFIC COUNT ALONG INTERSTATE 10
≈21,500
~47%
FAMILY HOUSEHOLDS
POPULATION UNDER 30 YEARS OLD
~33
~3.3%
MEDIAN AGE
UNEMPLOYMENT RATE
V I K I N G
C A P I T A L
PHOENIX TOP EMPLOYERS
BANNER HEALTH
AMAZON
HONEYWELL
AMERICAN EXPRESS
EMPLOYS 55,000
EMPLOYS 36,000
EMPLOYS 7,111
EMPLOYS 7,000
ST JOSEPH’S HOSPITAL
ASU
SROUTS
WELLS FARGO
EMPLOYS 5,000
EMPLOYS 18,500
EMPLOYS 13,526
EMPLOYS 15,000
V I K I N G
C A P I T A L
PHOENIX’S PHOENIXʼS
BOOMINGgrowth
PHOENIX POPULATION HAS GROWN
10,000,000
9,000,000 8,000,000
FOUR TIMES THE NATIONAL AVERAGE.
7,000,000
3,000,000 2,000,000 1,000,000 2020
2010
2000
1990
1980
1970
1960
1950
1940
1930
1920
1910
1900
1890
1880
0
2040
4,000,000
G R O W T H
5,000,000
2030
P R O J E C T E D
6,000,000
2025 Population 4.83 M 2040 Population Estimate
8.7 M
V I K I N G
C A P I T A L
PHOENIX SNAPSHOT
ARIZONA HIGHER EDUCATION Arizona State University ranks 9th globally in the Times Higher Education Impact Rankings 2024. ASU excels in sustainable development goals, leading in multiple areas such as sustainable cities and communities, and life on land. The University of Arizona is known for its strong research output and quality of education, placing it in the top 10% of universities globally.
V I K I N G
C A P I T A L
INVESTMENT HIGHLIGHTS
2025 16% 21% ~2x Year Built
IRR
AAR
Equity Multiple
SCAN CODE TO BOOK A CALL
AVONDALE COMMONS PHOENIX, AZ Class A Multifamily Opportunity
OPEN TO ACCREDITED INVESTORS
324 UNITS
2025 BUILT V I K I N G
C A P I T A L