Insider 2022 NAPA 401(k) SUMMIT
SPECIAL SUPPLEMENT TO NAPA NET THE MAGAZINE
You have fiduciary duties We have insight and tools to help Your 401(k) clients count on you to help keep their plans in compliance. John Hancock’s online collection of fiduciary resources will help you educate plan sponsors about their duties under ERISA—and establish processes for planning and compliance. Sample our resources for retirement plan fiduciaries.
retirement.johnhancock.com/fiduciary
John Hancock Retirement Plan Services, LLC, 200 Berkeley Street, Boston, MA 02116 NOT FDIC INSURED. MAY LOSE VALUE. NOT BANK GUARANTEED. © 2021 John Hancock. All rights reserved. MGTS-I 45553-GE 9/21-45553
MGR0825211770405 | 25071
FOR INTERMEDIARY USE ONLY. NOT FOR DISTRIBUTION WITH PLAN SPONSORS OR THE PUBLIC.
1
NAPA 401(k) Summit Insider Summer 2022
Table of Contents 2
What’s on Your Mind
24
(Letter from the Editor)
Social ‘Standings’
4
26
Who Are the ‘Summit Insiders’?
6
‘Shop’ Talk
14
Practice(s) Management
18
Over Blown?
20
Income ‘Oriented’
Partner ‘Shifts’
(TPAs & DC Wholesalers)
28
Team Works
30
‘Tell’ Tales
34
What Do you Wish (More) Plan Sponsors Understood (Better)?
napanet
Special Supplement To
the magazine
Editor-in-Chief Nevin E. Adams, JD nadams@usaretirement.org Art Director Ethan Duran eduran@usaretirement.org Director of Conference Sales Gwenn M. Marsh gmarsh@usaretirement.org Digital Sales Tony Descipio tdescipio@usaretirement.org Cover Triff / Shutterstock.com Copyright 2022, National Association of Plan Advisors (NAPA). All rights reserved. This publication may not be reproduced in whole or in part without written permission of the publisher.
QR Code to Digital Version* Use your phone to link directly to the Online Version!
38
What ‘Nobody’ is Talking About…
napa-net.org/industry-intel/summit-insider
* ios 13 and Android 9 users can scan using your phones built in camera utility.
2
NAPA 401(k) Summit Insider Summer 2022
Letter From the Editor
What’s on Your Mind(s)? I spend a lot of time and energy trying to keep up on the trends and happenings that shape our industry, the events and environments that both encourage—and sometimes undermine—our individual and collective efforts to expand and improve the nation’s retirement system.
However, there’s nothing quite like the size and scope of the NAPA 401(k) Summit for bringing us together, in a single location for a concentrated focus on the most important issues of the day. Throughout its history, it’s proven to be a unique opportunity to not only plant the seeds for new ideas and innovations, but to gain a solid “boots on the ground” sense for what is working, what’s not, and what could work, if only… This is now our fifth “Summit Insider”—a way that we can leverage all that collective brainpower and perspective to provide, at a single point in time, a shared perspective on industry trends, opportunities, and yes, threats. It’s a chance to get a sense from the nation’s leading retirement plan advisors of the things that are seen as “over-hyped,” and for that same group to offer some friendly advice to industry partners (potential and current), clients and prospects, regulators—and even those of us who write and advocate on their behalf—to provide a “reality check.” This year’s Summit Insiders told us: • ESG remains the most over-hyped trend— though cryptocurrency made a strong first appearance in this list. • “Their fiduciary responsibilities” was the thing most wished plan sponsors knew “better.” • “Attracting and retaining talent” alongside “scaling your practice” were seen as the big issues for advisor practices over the next 12 months. “Cybersecurity” was the big external issue over that time period, and “wealth management” the big practice focus issue. • Plan sponsor interest in retirement income solutions hasn’t really changed in the past two years—which puts it in “minimal” or “occasional” interest category.
• While “service” has long been the most-cited aspect of a successful TPA partnership, this year’s Insiders put some context to that umbrella notion, highlighting the importance of a TPA being “knowledgeable regarding rules/regulations/correction procedures” as the most significant aspect. Timely/accurate nondiscrimination testing was ranked second. • Among support from DC wholesalers, “product insights” was the most-cited support received, though it ranked a distant fourth in terms of support desired. “Client support” and “prospect introductions” were most desired. Thanks once again to all who took the time to share those (your?) perspectives and insights on the pages that follow. Thanks for being part of the NAPA 401(k) Summit— and thanks especially to the sponsors of this year’s NAPA Summit Insider! See you (all) in San Diego April 2-4 for the 2023 NAPA 401(k) Summit!
Nevin E. Adams, JD
Editor-in-Chief nadams@usaretirement.org
05/22
WHAT HAPPENS TOMORROW STARTS TODAY Working closely with retirement plan advisors and plan sponsors, Transamerica proudly helps people take steps toward a brighter future. Explore our resources and see how we can light the path toward a more secure retirement.
Contact us today to learn how we can help. transamerica.com
2202060 © 2022 Transamerica Retirement Solutions, LLC
4
NAPA 401(k) Summit Insider Summer 2022
Who Are the Summit Insiders? By pretty much any standard, the 2022 NAPA 401(k) Summit was a resounding success, in no small part a result of bringing together the nation’s leading retirement plan advisors and those who support them. This year roughly 425 advisors and home office personnel responded to this year’s Summit Insider survey. As one might expect, it was a diverse group based on tenure, age and target market(s). Here’s a demographic snapshot:
How long have you been a retirement plan advisor/working with retirement plans?
Age
14%
7%
15%
30%
21% 16% Less than 5 years 5-10 years
24%
27%
10-15 years 15-20 years More than 20 years
16%
With what size retirement plans do you TYPICALLY work/support?
What are the total assets under advisement for which you are responsible? 6%
30%
40-50 50-60 Over 60
30%
4% 5% 7%
Under 30 30-40
9% 7%
16%
8%
8%
18%
17%
23% 23%
18% Less than $5 million in assets $5-$10 million in assets
Up to $10 million in assets $10-$50 million in assets
$10-$25 million in assets $25-$50 million in assets $50-$100 million in assets
$50-$100 million in assets $100-$250 million in assets $250-$500 million in assets
$100-$250 million in assets > $250 million in assets
$500 million - $1 billion in assets $1-$5 billion in assets > $5 billion in assets
©2021 American Century Proprietary Holdings, Inc. All rights reserved.
Is there more to investing than money? She’s counting on it. Investing and breakthrough medical research. Who knew?
americancentury.com/expectmore
NAPA 401(k) Summit Insider Summer 2022
Ardea-studio / shutterstock.com
6
7
NAPA 401(k) Summit Insider Summer 2022
‘Shop’ Talk Advisors work, live, struggle and thrive in a complicated environment, bounded in (and
sometimes freed by) a variety of external boundaries and constraints— and permissions. We asked the 2022 NAPA 401(k) Summit Insiders to weigh in on some of those key elements—and to assess whether they would be “game changers” (for good or ill), much ado about not that much—or if it was simply too soon to say. On some things there were of like minds—others not-so-much. We’ve organized those questions (and responses) by broad categories: Products & Services, the Competitive Environment, Regulatory Radar and Legislative Aids.
employer plans is still relatively new—and doubtless constrained by both some missing regulatory guidance—and the impacts of COVID. Of course, those who see the development as a positive game changer now (slightly) outpace those who feel it’s (still) too soon to say—a modest reversal from the fall of 2021. And those who see it as a negative remain a distinct minority.
Cryptocurrency in Defined Contribution Plans 11%
11%
Products & Services MEPs/PEPs
36%
2%
33% 33%
33%
35%
While overall optimistic, there was a clear sense of hesitancy in declaring the MEP/PEP as a clear game changer. Then again, while the construct has been with us for a while (at least in theory), the emergence of pooled
Legend
Printing/Showing Lifetime Income Disclosures on Statements
42%
5%
27%
clear, though that failed to quell an announcement by the nation’s largest recordkeeper that it planned to provide a crypto option on its platform—and an even more recent lawsuit challenging the actions of the Labor Department. Considering that activity—and the controversy the Labor Department’s action (and subsequent statements) have engendered—well, you’d have to first acknowledge that we fielded this survey after the Labor Department’s action, but before the bulk of the responses. It is perhaps not surprising that so many viewed the advent as a positive game changer—that so many viewed this as “much ado about not much” suggests that there remains a significant ambivalence about the appropriateness of this asset on 401(k) menus.
Though cryptocurrency has been with us for a while, it really hadn’t been a big focus for 401(k) plans. But somewhere between a series of Super Bowl ads and the beginning of March, the activity of industry marketers caught the eye of the Labor Department— which then decided that it needed to get out in front of the issue, and issue a “Compliance Assistance Release” with messaging that was both unusually strong and delivered via what was to many an unfamiliar medium. But if the medium was unusual, the meaning and implications were
33%
There were three lifetime income enhancements in the SECURE Act, and if this one. is already in play with many recordkeepers (and therefore, perhaps explains why a fifth of Summit Insider respondents say it’s “not much,” though that’s down from 28% in the previous Insider), the potential to help nudge the focus
• Too Soon to Say | • Positive Game Changer | • Much Ado About Not Much | • Negative Game Changer
8
NAPA 401(k) Summit Insider Summer 2022
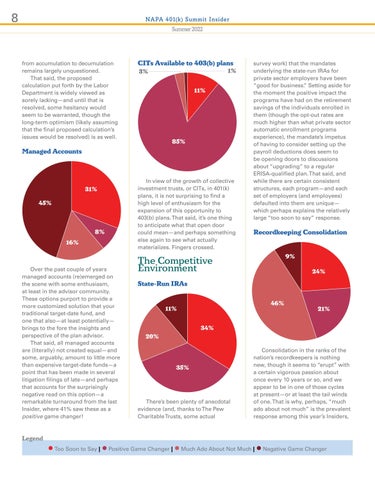
from accumulation to decumulation remains largely unquestioned. That said, the proposed calculation put forth by the Labor Department is widely viewed as sorely lacking—and until that is resolved, some hesitancy would seem to be warranted, though the long-term optimism (likely assuming that the final proposed calculation’s issues would be resolved) is as well.
CITs Available to 403(b) plans
1%
3% 11%
85%
Managed Accounts
31% 45%
8% 16%
Over the past couple of years managed accounts (re)emerged on the scene with some enthusiasm, at least in the advisor community. These options purport to provide a more customized solution that your traditional target-date fund, and one that also—at least potentially— brings to the fore the insights and perspective of the plan advisor. That said, all managed accounts are (literally) not created equal—and some, arguably, amount to little more than expensive target-date funds—a point that has been made in several litigation filings of late—and perhaps that accounts for the surprisingly negative read on this option—a remarkable turnaround from the last Insider, where 41% saw these as a positive game changer!
Legend
In view of the growth of collective investment trusts, or CITs, in 401(k) plans, it is not surprising to find a high level of enthusiasm for the expansion of this opportunity to 403(b) plans. That said, it’s one thing to anticipate what that open door could mean—and perhaps something else again to see what actually materializes. Fingers crossed.
survey work) that the mandates underlying the state-run IRAs for private sector employers have been “good for business.” Setting aside for the moment the positive impact the programs have had on the retirement savings of the individuals enrolled in them (though the opt-out rates are much higher than what private sector automatic enrollment programs experience), the mandate’s impetus of having to consider setting up the payroll deductions does seem to be opening doors to discussions about “upgrading” to a regular ERISA-qualified plan. That said, and while there are certain consistent structures, each program—and each set of employers (and employees) defaulted into them are unique— which perhaps explains the relatively large “too soon to say” response.
Recordkeeping Consolidation 9%
The Competitive Environment
24%
State-Run IRAs 46%
11%
21%
34% 20%
35%
There’s been plenty of anecdotal evidence (and, thanks to The Pew Charitable Trusts, some actual
Consolidation in the ranks of the nation’s recordkeepers is nothing new, though it seems to “erupt” with a certain vigorous passion about once every 10 years or so, and we appear to be in one of those cycles at present—or at least the tail winds of one. That is why, perhaps, “much ado about not much” is the prevalent response among this year’s Insiders,
• Too Soon to Say | • Positive Game Changer | • Much Ado About Not Much | • Negative Game Changer
9
NAPA 401(k) Summit Insider Summer 2022
whereas last fall “negative game changer” was the predominant sense, though those still sensing the impact might not yet be fully realized remained a distant second. Indeed, consolidation generally means disruption in service, support, and perhaps additional revenue generation for advisors—although how much, and how, is largely dependent on which side of the consolidation trend you’re sitting— and how well/seamlessly it happens.
Rollovers 7%
4% 14%
75%
Defined contribution plans held just under $11 trillion in assets as of year-end 2021, according to the Investment Company Institute, while IRAs represented just under $14 trillion—much of which is said to have originated in those defined contribution plans. Regardless, rollovers—either as an accumulation “pile” or as a decumulation starting point—are adding up, and are of increasing value to a growing number of advisory and wealth management practices. That said, the ability of retirement plan advisors to solicit/advise on rollovers has been buffeted about by the uncertainties attendant with the fluxes in the fiduciary rule(s),
Legend
generating confusion, and caution by firms that ordinarily might have gone “all in” in continuing to help and advise ex-participants that they had long counseled while part of a retirement plan. But the new definition of fiduciary (see p. 10, DOL’s Fiduciary Reproposal) levelled the field—acknowledging that that rollover conversation on the part of an advisor outside the plan can be viewed as the first of an ongoing relationship sufficient to establish that advisor as a fiduciary. Before the new provisions of PTE 2020-02, it might have fallen short of the five-part test, providing that advisor outside the plan with an advantage compared with the fiduciary advisor working with the plan. But under the new rule, the plan advisor—with an intimate understanding of the plan’s current fee structure and services—is arguably better positioned than the external advisor to document that a rollover is indeed in the best interest of the participant. That doubtless accounts in no small part for the robust acknowledgement that this is a “positive game changer”—nearly double the support this category received in last year’s Insider.
Considering that this particular brand of litigation has been with us since 2011, “too soon to say” seems an odd commentary, certainly at first blush. That nearly as many would view it as a “positive game changer” seems almost counterintuitive—until/ unless one views the allegations made with regard to the breaches of fiduciary duty as factual, and is willing to set aside concerns about the “new” generation of entrants from the plaintiffs’ bar to this arena as well intentioned, if not well crafted. There’s little doubt, however, that the awareness of, and heightened sensitivity to, fiduciary responsibilities has put most on their better, if not best, behaviors—and perhaps, despite the time, cost, and emotional strain those actions have laid on the hearths of those named in the suits—the rest of us have an opportunity to do better as well.
Social Security Reform/ Funding 9%
1%
8%
Excessive Fee Litigation 7%
82%
8% 43% 42%
Considering the looming funding crisis (though the Social Security Board of Trustees recently estimated it was a year further away than that estimated a year ago), and the integral role those benefits play not
• Too Soon to Say | • Positive Game Changer | • Much Ado About Not Much | • Negative Game Changer
10
NAPA 401(k) Summit Insider Summer 2022
only for those who haven’t saved for retirement, but for those who have, it’s little wonder that remedying that situation would be supported by the vast majority of Summit Insiders. That said, one might well wonder if the response would be more varied if the prospective remedies were presented (cutting benefits, raising withholding, or cutting benefits via means-testing or raising the age of eligibility). Yet, despite the commonality of agreement that something needs to be done, it remains to be seen what—and when those remedies might emerge—and by whom.
Regulatory Radar DOL’s Fiduciary Reproposal
13%
14%
24% 49%
It’s been said that elections matter— and there is perhaps no truer testament to that than the “evolution” of the Labor Department’s so-called “fiduciary rule.” The Obama administration’s attempt to bring those standards current to the new realities of defined contribution (and IRA) plan dominance came to an abrupt halt when the Fifth Circuit ruled the Labor Department had overstepped its bounds, leaving the Trump administration to thread a path created by the restoration of the old rules alongside some new guidance
Legend
intended to complement new rules that were never allowed to take hold. Subsequent guidance from the Trump administration was allowed to go into effect by the Biden administration on Feb. 16, 2021—much to the surprise (and relief) of many. For the moment PTE 2020-02 (flavored by a set of FAQs and DOL official comments) provides the path for ERISA fiduciaries (and those that would avoid its strictures)—but change is in the air, albeit one almost certainly informed by a comment period and review. And yet—though there have been points of clarification—and, more recently, a pair of lawsuits challenging the clarifications that have arisen (organizations that believe their ability to sell annuity products is undermined by the expanded fiduciary definition)— the Biden administration’s version outside of those statements and FAQs remains unarticulated. That said, and in some contrast to the dominant “too soon to say” sentiment that prevailed in the previous Insider, nearly half this year see it as a positive game changer— roughly twice the number who were inclined to dismiss it as “much ado about not much.”
Anticipated Shift in DOL’s Approach on ESG
11%
12%
As last year’s Summit Insider went to press, we were still anticipating an updated ESG rule from the Biden administration—and, as of mid-October we got them. Not surprisingly they took a markedly different approach that that set out by the Trump administration. Indeed, in releasing the new rule the Labor Department said it was concerned that the 2020 rules created uncertainty and were having the “undesirable effect” of discouraging ERISA fiduciaries’ consideration of climate change and other ESG factors in investment decisions, even in cases when it is in the financial interest of plans to take such considerations into account. That said, there’s some concern that in shifting the emphasis to not only consider, but to arguably emphasize that focus, the Labor Department may have “overcorrected.” Considering the significant shifts in emphasis— and in a fairly short period of time—advisors are understandably of mixed minds on the subject. Granted, most of the Summit Insiders view the shift, and the (still) anticipated final ESG rule from the Biden administration positively, whereas in the 2021 survey Insiders were much more inclined to say it was “too soon to say” (a distinctly minority opinion among this year’s respondents. However, more than a third see even this anticipated shift (and we still don’t have the final regulation) as “much ado about not much.” We’ll just have to wait and see.
35% 42%
• Too Soon to Say | • Positive Game Changer | • Much Ado About Not Much | • Negative Game Changer
11
NAPA 401(k) Summit Insider Summer 2022
Legislative ‘Aids’? SECURE 2.0
implementation)—but a negative assessment nearly twice the size of those expecting a positive outcome… well, time will tell.
19% 46%
SECURE Act’s Expansion of the Retirement Income Safe Harbor
24%
11%
Better—or perhaps more accurately—known as the Securing a Strong Retirement Act of 2021, the legislation was passed by the U.S. House of Representatives in March (and by a vote of 414-5!). The sweeping retirement legislative proposal contains a myriad of provisions designed to build on and carry forward the groundwork laid by the Setting Every Community Up For Retirement Enhancement (SECURE) Act enacted in the waning days of 2019. As we head to press, the U.S. Senate is moving ahead with its own version (the RISE & SHINE Act), and there’s a pretty solid expectation that the two could be reconciled and be passed into law before the year is out. That said, that so many (nearly half) of the Summit Insider respondents viewed these proposals as a negative game changer was a bit of a surprise. Granted, there’s a lot in this bill with an impact that remains uncertain, not the least of which could be said to be the passage of the legislation itself (not to mention the timeframe(s) for
Legend
safe harbor expansion will prove to be sufficient to overcome the traditional reluctance on the part of plan fiduciaries to embrace these options.
Legislation to Allow Student Loan Repayment Matching
7%
5% 19%
11%
12%
23%
63% 60%
One of three elements in the SECURE Act designed to shift participant focus from accumulation to decumulation, this particular element (the other two being the reporting of a monthly lifetime income amount on participant statements and allowing for the portability of “in plan” lifetime income benefits) was intended to alleviate the long-standing concerns plan fiduciaries have had regarding their selection of a lifetime income provider whose responsibilities might entail on-going services two or three (or even four) decades past the time of their selection In last year’s Insider, just over half of respondents viewed this particular element as a positive game changer—and this year, somewhat more do, nearly two-thirds, in fact. That optimism notwithstanding, it remains to be seen if this particular
From the moment word came out about Abbott Lab’s private letter ruling from the IRS that provided a “green light” for the organization to provide non-elective contributions as a match for student loan repayments back in 2018, HR managers across the nation have been trying to see how/if a similar approach might apply to make it easier for those burdened with student loan debt to more effectively benefit from workplace retirement plan savings opportunities. Indeed, the sheer depth and breadth of the impact that student loan debt is said to have on retirement plan participation has been a wake-up call of sorts—and the prospects for this kind of solution still looks to be very well received by advisors.
• Too Soon to Say | • Positive Game Changer | • Much Ado About Not Much | • Negative Game Changer
12
NAPA 401(k) Summit Insider Summer 2022
among small businesses) that this provision in SECURE 2.0 would draw the positive game changer label from the vast majority of this year’s Summit Insider respondents. After all, a provision that would basically make the offering of a workplace retirement plan essentially cost-free to an employer obviates one of the most common objections raised to adding these programs—though only one. In that regard, “too soon to say” may well turn out to be an accurate read as well.
19% 43% 23%
way that could undermine retirement savings, rather than being additive. And, if that’s how it turns out, that would certainly be a negative game changer for retirement.
Increasing the small-employer pension plan start-up credit to cover 100% of the cost to emall employers to implement a 401(k) plan for the first three years
29%
1% 15%
In last year’s Insider, this concept was viewed as a “positive game changer” by a strong majority—but this year, the sentiment is decidedly less positive—in fact, those who view it as a negative game changer nearly outnumbered the positive by a factor of two. What’s behind that shift? Well, it could be that, despite the widely acknowledged need for such a financial buffer that recent legislative proposals have positioned these in a
Legend
28% 8%
29%
14%
6%
85%
It’s not surprising—particularly in view of the current coverage gap (which one finds almost exclusively
Perhaps reflecting the uncertainty of impact of a provision that would require automatic enrollment of participants, the “take” on this provision/proposal was decidedly “mixed.” In fact, just 14% saw it as a positive game changer, with respondents nearly equally split between the other three assessments. Ultimately, of course, the question here might not be so much “what if” but “if.” SI
• Too Soon to Say | • Positive Game Changer | • Much Ado About Not Much | • Negative Game Changer
Ardea-studio / shutterstock.com
Legislation to Expand Emergency Savings Accounts
Expanding automatic enrollment in 401(k) plans by requiring 401(k), 403(b) and SIMPLE plans to automatically enroll participants in the plans upon becoming eligible, with the ability for employees to opt out of coverage
In the changing world of investing, there’s still no substitute for trust. The best way to put your clients first is to choose a company that puts you first. Get investing solutions that cross asset classes and investing styles, and address multiple goals — all paired with an unmatched heritage of trust and history of retirement-focused investments.
Learn more at MassMutualInvestments.com
FOR FINANCIAL PROFESSIONALS. NOT FOR USE WITH THE PUBLIC. MassMutual Investments is the marketing name for certain products and/or services of Massachusetts Mutual Life Insurance Company (MassMutual) and its affiliates. © 2022 Massachusetts Mutual Life Insurance Company (MassMutual®), Springfield, MA 01111-0001. All rights reserved. www.MassMutual.com. MM202503-300842
14
NAPA 401(k) Summit Insider Summer 2022
Practice(s) Management We asked Summit Insiders to share with us what they thought would be the big issues for their practice over the next 12 months—and we’ve sorted them out here by “inside” factors, external influences and practice focus. For most, it’s the “inside” factors that loom largest—except for cybersecurity.
‘Inside’ Factors Attracting & Retaining Talent
Great Resignation – Your Firm/Team
Succession Plan
9%
6%
22%
10% 19%
44%
31%
58%
26%
25% 28%
Scaling Your Practice
Mental Health in Your Workplace
22%
Diversity/Inclusion Initiatives
6% 14%
11%
51% 32%
22%
14% 25%
25%
32% 39%
29%
Very important Important Somewhat important Not important
15
NAPA 401(k) Summit Insider Summer 2022
External Influences Cybersecurity
Adoption of Retirement Income
Shift to ESG
3%
4%
12%
12%
21%
21% 35% 52%
32%
33%
35%
40%
Great Resignation Among Clients
The 2022 Elections
TPA Partnerships
13% 17%
23%
24%
20%
20%
36% 24% 31%
28% 28%
Very important Important Somewhat important Not important
36%
16
NAPA 401(k) Summit Insider Summer 2022
External Influences Advisor Firm Consolidation
Recordkeeper Consolidation
11%
13%
18%
34% 26%
35%
34%
29%
Practice Focus Wealth Management
E-Delivery
9%
Fee Compression
12%
33% 46%
33%
7%
10%
21%
36%
29%
24%
40%
Very important Important Somewhat important Not important
Whether you need a retirement plan for a small entrepreneur or a large multi-location organization,
Retirement Right
SM
provides the investment options, service models and pricing flexibility to meet your clients’ needs.
To learn more call our sales desk at (877) 401-7253 or visit us at www.GetRetirementRight.com/contact. For Producer Use Only. Mutual of Omaha Retirement Services is a marketing name for the Retirement Plans Division of Mutual of Omaha Insurance Company. 600471
18
NAPA 401(k) Summit Insider Summer 2022
Over Blown? When it comes to over-hyped trends, ESG investments once again (as it did in 2021 and 2020) not only topped the list, but once again drew nearly twice as much support in that category as the No. 2 choice—which this year went to a new “entrant”—cryptocurrency. Robo-advice slipped in intensity, but still held on to the No. 3 slot.
Indeed, it’s hard to find a topic on this list that hasn’t at some point gone from being a trend, or an opportunity, to a point where a sizeable minority feels that it has “jumped the shark” and traversed into ignoble territory. That said, what may today be viewed as passe can just as easily reemerge as an opportunity—or
a threat. Consider the relatively low ranking for topics like fee compression, and consolidation— which are trends that seem a long way from “over.”
Hurca / shutterstock.com
The most over-hyped industry trend(s)
19
NAPA 401(k) Summit Insider Summer 2022
What do you find to be the MOST over-hyped “trend” in the industry?
ESG Investments
36%
30%
2022
2021
Managed Accounts
6%
8%
2022
2021
ETFs
2%
2021
Health Savings Accounts (HSAs)
1%
3%
2022
2021
Litigation
0% 2022
17% 2022
N/A 2021
Collective Investment Trusts (CITs)
6% 2022
8% 2021
Private equity
5%
2022
2% 2022
N/A 2021
Fee Compression
1%
2022
1%
2021
Advisor Consolidation
1%
2021
Robo-advice
Cryptocurrency
0% 2022
1%
2021
10% 2022
17% 2021
Financial Wellness
2% 2022
5% 2021
MEPs/PEPs
9% 2022
2022
4% 2021
Passive Investment Strategies / Vehicles
1%
2022
2% 2021
2021
Retirement Income Strategies
2% 2022
3(38) Services
2%
11%
3% 2021
Aggregators
2% 2022
2% 2021
Recordkeeper Consolidation
1%
2022
1%
2021
20
NAPA 401(k) Summit Insider Summer 2022
Income ‘Oriented’ It’s widely said that 10,000 Boomers are heading into retirement every day—and survey after survey
indicates that they are interested in some kind of “solution” to provide a dependable stream of income. Of course, there’s been a traditional reluctance to bring those solutions “inside” the workplace retirement plan (born largely out of fiduciary and product complexity concerns, though the former has arguably been at least partially mitigated by provisions in the SECURE Act). That said, the issue looms ever larger—so much so that it was a big focus of the 2022 NAPA 401(k) Summit. As a series of new offerings comes to market, while advisory firms are snapping up wealth management practices, and target-date fund glidepaths are increasingly found to be crafted with a “through,” rather than a “to,” retirement date focus—we took a reading from our Summit Insiders on the current environment—and how, if at all—things had changed in recent months.
How would you rate your plan sponsor clients’ level of interest in in-plan retirement income products? 7%
Generally speaking, how does that level of plan sponsor interest in in-plan retirement income compare with two years ago?
67%
It hasn’t really changed
9% 35% 24%
It’s higher/more
14%
35%
It’s a mixed bag—higher for some, lower for others, unchanged for still others
8%
It’s lower/less
1%
Minimal Occasional Non-existent Frequent High
0
10
20
30
40 50 Percentage
60
70
80
What do you wish those building retirement income solutions (better?) understood about building retirement income solutions that people would buy? You cannot lock people in, it has to be portable. Would need to be super convenient and in human language for them to understand. We need to know how it works. And it needs to be portable and easily interpreted to plan participants.
Universal portability on all open architecture platforms needs to be achieved. Partnerships are better than everyone going it alone, but we need to know we can take the product to nearly any RK before we will start using it. Understand it’s a process not a product.
This is a challenging topic but important. Fees, investment flexibility and guarantees are what the average person needs. Must be portable (difficult). The communication and overcoming the “annuity” dirty word is important. But, annuities are actually good for most people for a portion of their retirement. That is why pension plans used to be a part
21
NAPA 401(k) Summit Insider Summer 2022
Visual Generation / shutterstock.com
of the three-legged stool. So DC Plans with in plan income guarantees must take that place. Think about our client the participant not your fund/annuity company and then solve the problem...
their own products and ‘block out’ competition. There needs to be an ‘open architecture’ approach to retirement income solutions now. We can have this process mimic the way TDF were adopted. RK required use of proprietary products.
They want transparency, simplicity and flexible options.
They need to be easy to describe; make them look like a pension.
The issue is not the product itself. The issue is still an income and savings gap and the confusion for many who think these products are employer funded pensions.
They should have flexible income options, be portable and have reasonable fees.
They need to be easy for participants to understand and for advisors to communicate.
The internal ROR of the product and what income would be provided based on age, etc.
They need to make it extremely simple to understand. (This came up a lot.)
They must be portable and platform agnostic. The greater challenge is the education around them, as decumulation & retirement income is so individually driven.
The demand from plan sponsors is not that high unless they are sold on the concept. The demand from participants is not that high in general.
The people building them understand them very well. The advisors recommending them and the people buying them need a whole lot more education on them.
The average person isn’t so concerned with the granular detail of how the product works. They need general knowledge and simple examples on how this solution benefits them over the other options they have.
They need to keep costs down, have portability, and not try to be all things to all people. It’s an option within a retirement plan that will be attractive to some. They need to get the providers to adopt a platform or approach that allows these products to be recordkept on all platforms, otherwise the platforms will develop
The lack of understanding the average participant has about these products. Matching those who have
the need and where the product fits is very difficult. “Guarantee” often appeals to those too young and/or with small balances that don’t benefit.
Spend less time developing and marketing a product solution and
22
NAPA 401(k) Summit Insider Summer 2022
SIMPLICITY AND DOING THE RIGHT THING FOR THE “PARTICIPANTS IS MOST IMPORTANT. AND REMEMBER, A FORMAL RETIREMENT INCOME PRODUCT IS NOT IN THE BEST INTEREST OF ALL PARTICIPANTS.” focus on the tools and resources in place to assist participants with the income planning process. Simplicity is key. Most participants don’t know (and don’t want to know) how this stuff works. They just want to know how much they have to live on. Simplicity and automation are key. Using technology, it has to “just happen” for the participant. Many don’t understand the complexity and they never will. Stop focusing on insurance or proprietary products—build a bucket strategy using technology that can easily be implemented within the same account (maybe we create a separate menu for those in retirement to use in the bucket strategy?). Having institutionally priced immediate annuities will be beneficial, but annuities (deferred or immediate) will never be the silver bullet. Similar to annuities, there needs to be a VERY clear demonstration/ illustration of the cost-benefit of these products. WE can’t have them be GIANT revenue streams (i.e., Stable Value and Fixed Accounts) for the companies building and selling them. Nothing wrong with making money, but there needs to be a more clear explanation of what the ROI would be on these products. Portability. (This also came up a lot.) Plain English to explain them. One size doesn’t fit all, there is a need
for different guaranteed rates with different fee structures. It’s a process, not a product. Unfortunately, we are getting inundated with product. If you’re building a product, recognize that it may not work for everyone in a company. Treat us like the consultants and researchers we are... contrast and compare what you’re selling with other valid approaches; not the latest, greatest life-changing, shiny new product you want to sell our clients. Market risk is less important than longevity and complexity risk Make the product simple, portable, and LOW cost. People have worked hard for that savings and don’t need corporations taking high fees from it. Make the process to engage interesting and easy. Take the mystery out of the math behind it. It’s a great question. I think we need to do a better job engaging plan sponsors and participants on what the desired solution might look like. I have to imagine the architects of some of the solutions make assumptions perhaps based on data. I think we need to hear it from the end user/recipient/beneficiary. If it is too complex for advisors, participants are going to be lost if the solutions are not easy to understand. While the solution itself is not easy, the rollout to participants needs to be. It needs to be a very simple message
that a participant can easily grasp why they need this solution... think less about words and more about visuals. I think they need to focus on the Plan Sponsor’s responsibility to be able to adjust service providers over time. I think it’s difficult to create a meaningful retirement income solution which applies to all participants because each participant is unique. I don’t see how it’s possible, but some way needs to be developed that lets people change their mind in the future. For once, try to build the solution as if you were the one buying it, not the one benefiting from the sales of it. Everyone is different. One size does not fit all. Things that have never happened before now happen all the time. Monte Carlo simulation is based on the normal curve and the normal curve is the wrong curve to use for forecasting. We are going to live a lot longer and current forecasts for retirement needs are going to fall short. Eliminate the rusty handcuffs. A retiree should not be penalized or inconvenienced by these products if they have an emergency liquidity need. Clear explanation of how the income would work and impact the client. A very clear and concise directive when complete. SI
Get there.
You’re an expert at helping clients meet their goals with confidence. Imagine what you could do with more freedom to build the right plan, every time. 800-345-6363 | ascensus.com Ascensus, LLC provides administrative and recordkeeping services and is not a broker-dealer or an investment advisor. Ascensus® and the Ascensus logo are trademarks of Ascensus, LLC. Copyright ©2022 Ascensus, LLC. All Rights Reserved. 777794-PSG-861300 (6/22).
24
NAPA 401(k) Summit Insider Summer 2022
Social ‘Standings’ Most advisors have approached social media with caution, if not trepidation, with the latter often
grounded in the structures, strictures and concerns of regulatory compliance. But with the maturation of certain platforms, the emergence of a new generation of advisors and the sense, even among more seasoned professionals, that these platforms present opportunity—well, things have changed. And continue to change every day. We asked Summit Insiders which social media platform(s) they used regularly for business outreach/ expansion—more than one could apply, of course. The clear winner—LinkedIn!
Pod ‘Castes’
And speaking of “new” opportunities, there’s a growing number of podcasts that can help educate you—your plan sponsor clients—and participants—on a variety of retirement plan topics. We asked Summit Insiders if they had tapped into this resource as of yet. Most hadn’t.
23%
54% 23%
Facebook 20% LinkedIn 84% Instagram 6% None at this time 15%
Twitter 11% Tik-Tok 1%
Yes Yes, but only occasionally No
“This is something I’ve been wanting to do,” commented one respondent. “I’m sadly not up to speed with what’s out there... but will start paying more attention,” noted another. And still another said, “I would be interested to hear favorites from other NAPA members.” So, here’s the list of those mentioned most often: • Nevin & Fred (though some actually referred to it as Fred & Nevin!) • Retireholi(k)s (which some called 401(k)holics) • Josh Itzoe/Fiduciary U • 401k Fridays/Rick Unser • Dave Ramsey • 401(k) Specialist pod(k)ast • Ary Rosenbaum • Animal Spirits • Kitces & Carl • Engaged Pod with 401JA(k)E
Here’s to greater possibilities together As defined contribution plan sponsors navigate a world of increasing complexity, we see greater possibilities when we face challenges together. For more than 30 years, we’ve partnered with plan sponsors and their consultants to help optimize participant outcomes. Let’s invest in greater possibilities together.
invesco.com/dcadvisor
NA2247880
NAPASUMM-AD-1-E
Not a Deposit Not FDIC Insured Not Guaranteed by the Bank May Lose Value Not Insured by any Federal Government Agency This is not to be construed as an offer to buy or sell any financial instruments. Invesco Distributors, Inc.
06-22
26
NAPA 401(k) Summit Insider Summer 2022
Partner ‘Shifts’—TPAs & DC Wholesalers It’s been well established in previous Summit Insider reports that service is the dominant reason for hiring
(and terminating) a relationship with a third-party administrator, a.k.a TPA. We asked Summit Insiders to provide some context for what “service” includes. Knowledgeable regarding rules/ regulations/correction procedures
329
Timely/accurate non-discrimination testing
278
Timely/accurate filing of required government reports
243 190
Timely distribution of plan notices Proper loan/distribution calculation/processing
170 141
Eligibility validation
138
Compensation definition validation Reconcilement of contributions to trust deposits
119
DC Wholesaler Support Defined contribution wholesalers—or as our annual
accolade acknowledging the best of this “breed” calls them, Advisor Allies—have long been a vital support partner for the nation’s retirement plan advisors. Indeed, the most successful wholesalers do more— they are true partners, often working side-by-side with advisors—which is why we have and so we now acknowledge that expanded role with a new name: Advisor Allies.
We asked Summit Insiders to weigh in on the support/ services from DC wholesalers they prized most:
And then, for contrast, we asked which type of support those same Summit Insiders got most often from the DC wholesalers they work with:
3% 16% 25%
29% 39%
Client support Market intel Marketing materials Product insights Prospect introductions/referrals
22%
17% 23% 6%
19%
27
NAPA 401(k) Summit Insider Summer 2022
Respondent Perspectives on the TPA Relationship You totally missed the main reason that we have issues. It is the availability and responsiveness of the TPA representatives. Not having a question answered or issue resolved in a timely manner vastly overwhelms the above issues. We’ve really struggled with our TPA partnerships, the fees TPAs charge are outrageous for the services they provide. The outrageous fees and the lack of consistent service compels us to use a bundled product whenever possible. Unfortunately, most of the TPAs we have worked with have not provided “value” in the client relationship. They most provide another contact, finger pointing, and add an overall complexity to plans that really don’t require their expertise. TPAs can absolutely add value if they owned correction calculations and procedures as well as their expertise with complex plans. TPAs’ sole purpose is to do all the above. As such, they should do all of those things well from a service standpoint. TPAs just tend to be defensive and not helpful to our practice. We bundle most of our business unless required to use a TPA (MEP, design complexity, etc.)—the value of a TPA is diminished, especially as it relates to bundled service providers. TPAs in general are becoming less important for plan admin tasks and more important for consulting and guidance. Simply being responsive and attentive to a client’s needs... be there, respond to them, answer their questions. All the things listed above are things they should be doing. Some of these TPAs
are becoming aggregators and getting too big for the staff they have. The client loads get too high, and then you throw the talent pool issue in the mix, and we have TPA consultants that are completely being reactive. “Service” = Having “urgency” and accountability for their compliance work. It is also the ability to partner and communicate with us as advisor. Knowing their own plan document and how to administer provisions in concert with the recordkeeper. When this fails, then TPA needs to change. Proactive engagement and a strong advisor relationship. Transparency of how they are receiving funds from the r/k and full disclosure to the advisor of invoices sent to the client. often, the r/k can cover the needed admin support and therefore the TPA has to go above and beyond in strengthening the relationship with the client and advisor. That is, they need to truly demonstrate that they are adding value. Over time we have been moving out of TPA relationships and moving to one particular TPA. Basically, we can count on them to do a terrific job for our clients. Are on top of everything all the time! Our TPA partners cover all the bases very well. Surprising to see this as a question (as if some don’t). It’s all of those, but the real answer is being available, responsive and timely in communications. Pick up the phone or answer that email. It is helpful for a TPA to respond to phone calls and emails. There are TPAs out there (and not the national low-cost) ones, but smaller firms that may take 5+ days to respond to a
PROACTIVE “SERVICE!
CURRENTLY THOSE I WORK WITH THIS DOES NOT EXIST, JUST A REACTIVE SERVICE MODEL UNLESS IT’S BILLING!” call or email. It’s frustrating when a client may have specific plan related question that I can’t answer and need their input. Including the advisor in communication!! I lean on TPAs and actuaries for assistance with complex plan designs. The downside is that when recordkeeping and compliance is unbundled, the recordkeeping system doesn’t get the necessary data to fuel the participant messaging and calculators, and the demographic reports the plan sponsor reviews. To me, “service” is defined by when my plan sponsor or I have an issue, can we get in touch with our named contact? How quickly will that contact resolve my issue? Do they have the knowledge/experience to consult? Are they flexible, i.e., offer more than one path to resolution? For me, it is being consultative, teamoriented and personable... in addition to all of those listed. All of the above plus PROACTIVE communication. SI
28
NAPA 401(k) Summit Insider Summer 2022
Team Works It’s often said that retirement plan benefits help to attract and retain qualified talent.
But for the advisor firms that support those programs, attracting and retaining qualified talent is an essential part of fulfilling their mission. We asked Summit Insiders two questions relevant to that process—on both there was a remarkably even three-way split:
How do you/have you determined when/who to hire? (More than one response was permitted) By need for specific skill set/expertise
201 When we identify individuals who would be a good complement/cultural fit.
188 By client load metric/complexity
187 It just depends.
77 Not something we’ve really considered.
45
With regard to diversity & inclusion, which of the following best describes your firm/team’s current approach? We are conscious of diversity in workforce but not a formal initiative.
157 We have a formal initiative focused on diversity/inclusion.
132 We are more focused on skill, regardless of diversity profile.
128
SUPPORTING ADVISERS WHO BELIEVE IT’S TIME FOR A BETTER DEFAULT OPTION!
PRO Managed Account Personalized Allocations
Actively Managed Investments
Proactive Account Monitoring & Adjustments
Savings Rate & Retirement Advice Recommendations
Periodic Retirement Progress Reporting
Online Participant Advice Tool
To learn how you can use Personalized Retirement Outcomes (PRO) as your client’s QDIA, email FisherPRO@fi.com
FOR DC PLAN SPONSORS AND ADVISERS. INVESTING IN SECURITIES INVOLVES THE RISK OF LOSS.
30
NAPA 401(k) Summit Insider Summer 2022
It’s hard but totally worth it!
‘Tell’ Tales
What would the person you are today tell the person you were when you got into the advisor business? As parents—as colleagues— as human beings, we all have experiences that we like to share with those who haven’t yet had the benefit of that experience. We asked Summit Insiders to take that inclination one step further—and asked what would the person they were today—would tell the person they were when they got into the advisor business. Here’s a sampling:
About selling…
The sales cycle is LLLLLLOOOONNNGGGGGG!!! What you bring to the table is valuable. Don’t let a prospect diminish that to get a lower fee. Saying no to clients and prospects that are not a good fit will allow you to do more and better serve those who are good fits. Sales is sometimes more valued by organizations than operational excellence. Prioritize time for prospecting each and every week. Keep being aggressive. Be more confident and just ask for the business. Be 100% passionate! Don’t be afraid to ask, and don’t be afraid to hear “no”! Be methodical and consistent in your marketing efforts. Treat clients like you would treat you own mother.
It’s going to take longer than you think, but it will be worth it just the same. It’s a touch business and fees are going to go down.
Get your fees line with what you do, girl!
About clients
Clients are more sticky than you think.
It’s a great business, so good choice :-)
Client experience is very important to the success of the practice.
This is an amazing business and I should have gotten into earlier. Besides making a good income we are changing people’s lives for the better.
Be proud of the service you provide!
About running your business… Build your own book.
Be patient and set parameters on who you want to work with. The industry is small and your reputation will precede you—good or bad.
Build in scale right from the start. Build a fee only practice from the beginning. Bring on an understudy.
Go to NAPA and learn from the advisors who have laid the groundwork. Thankfully, my former boss did encourage me to take a licensing test (QPFC) which is why I started attending NAPA.
About this career…
Work for a true fiduciary firm. Be conflict free and do what is right for clients/participants. Work for a large firm, get trained and then either start your own firm or go work for an RIA. Start networking as early as possible.
Better to be patient and do it right or give the correct information than be fast. Believe it, the only business we’re in is the relationship business. Know this, and apply it to all of your activities, the rest will be a breeze. Be truthful and have integrity above all else. Hire staff before you think you can afford them. Run from plans that are a mess.
Pay attention to other industry specialists, e.g. TPAs. You never know when a topic they are discussing, e.g. Prevailing Wage, is going to be relevant in a conversation you are having with a prospect. You’re a Fiduciary in this business. Always act like it!
Target scalability as a strategy, not quantity. Surround yourself with experts in complementary fields and leverage DCIO Partners who offer tremendous support including analytical tools, product insight and market intel.
31
NAPA 401(k) Summit Insider Summer 2022
Keep hiring young people. Make it scalable, or avoid it like the plague.
value is to our clients. Learn how retirement plans are administered, investments will be only a small part of your conversations.
Enjoy yourself and surround yourself with people who are different than you are :) Compliance first!
Lock in your fee for just 3 years to create the opportunity for a fresh conversation about how services have/have not evolved and whether the relationship is still a good mutual fit.
Keep your provider relationships to 5 or less. Keep your fund lineups consistent. Take your CPFA early. Attend NAPA every year and implement 2 new ideas each year.
Choose your team members wisely. Build a business not a practice. Charge what you are worth.
Get ready for a bumpy ride!
Continue to do what is best for the client and understand their personal situation.
Get credentialed and be a student of the business.
Focus on building relationships instead of chasing AUMs.
Building relationships is probably the most important aspect to client retention and referrals. Seek opportunities to learn. There are a lot of bright minds in the Retirement Industry who are generous with sharing their knowledge. Try to become a subject matter expert.
Focus on due diligence. Understand why you do your job and what our
Focus more on building relationships with COIs.
Building a business requires patience and persistence. Keep going.
Learn to say no and be intentional with your schedule. GoodStudio / shutterstock.com
Learn how to say no early and often.
32
NAPA 401(k) Summit Insider Summer 2022
THE WORK YOU PUT IN NOW WILL BE REWARDED “THROUGHOUT YOUR CAREER. JUST KEEP GOING.” Be a sponge, learn everything you can and never be afraid to admit when you don’t know something. Automate, delegate and lead.
For you
You need a lot of knowledge. It will be expected. It will be a challenge to be paid for it. You just made one of the best decisions of your life! You don’t have to know the answers, you just have to know where to find them. You don’t have to know everything/be an expert on everything. You just have to know the right people to ask, when things come up that you don’t know.
life to the fullest. Read good books and learn from history and historical figures. Life is short so enjoy it and stay out of the weeds. Be honest with yourself. Have awareness and plan forward. You should’ve made the move to the advisory side of the business years earlier when you were originally considering it.
Make good connections in and outside of your industry. Seek out entrepreneurs. Knowledge and wisdom will nature evolve, but never ever forget to be kind and patient. Keep the passion for helping those living paycheck to paycheck. Keep doing the right thing, always!
Trust your gut. Ask questions. Don’t accept the first answer.
Attend as many conferences as possible—networking is key.
Think long term and learn to learn. Always trust your gut. Think long term—be strategic—focus on service with integrity and always remain accountable
Always keep doing what is best for the client. Always put the client first.
You are not as smart as you think you are, listen more talk less.
Take all of the licensing exams you ever think you may need now instead of waiting until you have a family and a full workload.
You are constantly learning! Take advantage of all of the tools and resources that are at your fingertips.
Stay the course in the retirement plan business. Adapt the team approach earlier.
Don’t be afraid to advocate for yourself and to take as many certifications as you feel are necessary.
Work smarter not harder.
Stay calm.
Why didn’t you do this sooner?!?!?
Start sooner.
You’re gonna love your life. Hire help sooner and give them the authority to do the job completely.
Should have gotten the CPFA 5 years ago.
You think you know everything now— just wait until you learn how wrong you are!
Play the lottery more. You are bound to have won by now if you had...
Life only gets more complicated and expensive.
Don’t be afraid to say you don’t immediately know something. Better to double check than be wrong. Document everything you do. Do NAPA Practice Builder, CPFA and other 401(k) designations early and right away.
Get credentialed and educated early. Be the turtle not the hare. SI
Do the work... be responsible for your actions... set boundaries... live
No one is an expert, learning is ongoing.
Helping you manage your fiduciary duties Sponsoring a retirement plan is one of the more challenging endeavors an employer can undertake. Your retirement plan advisor can help you answer your biggest questions: •
How do you know if your plan is effectively preparing your employees for retirement?
• •
Is your process to select and monitor service providers or investments prudent?
•
Does your company have the resources and knowledge to handle these responsibilities alone? Do you understand your fiduciary liability to effectively sponsor a retirement plan?
Learn more about Raymond James and find an advisor. *Raymond James’ Retirement Plan & Institutional Advisory Council membership is based on assets under management, number of qualified group retirement plans, designations obtained, and compliance record. Membership is not an endorsement, is not representative of any one client’s experience, and is not indicative of future performance. No fee is paid in exchange for this membership.
RAYMONDJAMES.COM © 2021 Raymond James & Associates, Inc., member New York Stock Exchange/SIPC © 2021 Raymond James Financial Services, Inc., member FINRA/SIPC Raymond James® is a registered trademark of Raymond James Financial, Inc.
34
NAPA 401(k) Summit Insider Summer 2022
What Do you Wish (More) Plan Sponsors Understood (Better)? Plan sponsors, as often as not, have that role—and its associated complexities (and legal liabilities) “dumped” on them. For most, it occupies a
fraction of their time and focus— which makes the support, direction and even encouragement of those who work with them all the more essential. That said, there are times when those who support them struggle to get their attention and obtain their understanding and appreciation for what goes into that support. Which is why, once again, we gave the Summit Insiders “voice” to articulate what they wished (more) plan sponsors understood (better)…
About Working Together
When in acquisition mode that telling your advisor in advance is very important. The plan governance process and how important it is to document every decision/discussion made on behalf of the plan. There is help for most aspects of running the 401k plan, you don’t have to do it all on your own. When DOL and IRS come calling, an attorney is really the best first call to make. We rely on them for more than they realize sometimes.
we discuss, especially fiduciary responsibilities. We simply want to do our best to help you stay out of trouble. TPAs are valuable. Big box record-keepers are mostly selfadministration. The need to provide accurate information in a timely manner. The need to have consistent, documented process.
About Fees
You pay for what you get. If everything is about low cost, there will likely be other challenges that will need to be addressed at some point. You cannot get everything for free. The lack of action in managed accounts to justify their fees. The fee disclosures and best practices to help participants hit good retirement outcomes. That cheap doesn’t mean better.
THE VALUE “WE CAN BRING
TO THEIR EMPLOYEES THROUGH FINANCIAL WELLNESS AND ONE-ON-ONE PLANNING.”
That “cheaper” is rarely “better” (yes, this came up a lot).
About What Advisors (Can) Do You can’t shortcut your duties to the plan. You need to hire providers that have an understanding of ERISA and not just your golf buddy. Working with a specialist advisor will improve everything about your plan—and cost less. The work that we do on their behalf and how much we genuinely care. The value we can bring to their employees through financial wellness and one-on-one planning. The value we bring to the table! :-)
The difference between plan advisors and financial advisers.
Value of service versus lowest fee.
We need their input more proactively to better understand what their workforce needs
The difference between our role and the role of the recordkeeper.
Value of an advisor beyond fund performance.
We are not trying to be a pain in the backside with some of the things
You get what you put in! Be a proactive partner.
Understand we are their partner, not just an interchangeable vendor.
35
NAPA 401(k) Summit Insider Summer 2022
The value of an advisor who really understands the retirement market (technical side), not just the investment platform. The time involved in working on their fund line ups. For us it’s pretty customized so can be time consuming.
sezer66
/ shutterstock.com
The shadow work that the advisors undertake. The most important thing is getting more people saving more money. Fees and funds are not important when you don’t have any money. No matter how many fiduciary services you outsource, that plan sponsors will always have a fiduciary responsibility.
The influence they can potentially have on retirement outcomes. Importance of compliance with plan document and ensuring they are following provisions. How to read their plan document.
About Me/Us
The amount of due diligence and work that is completed behind scenes on their behalf. The limited time we have. The importance of working with a specialist, not just an investment advisor. The amount of work that goes on behind the scenes. That there is
work being done to protect them as fiduciaries. Everyone does not have the same resources to serve them and ensure they are protected. That employee education should be mandatory if they want improved participation and employee appreciation of benefits. One thing that I’ve noticed with only a few plan sponsors is they get the impression that they are our ‘only clients’ and expect a ridiculous turnaround. Sometimes it can be difficult to respond right away if we are visiting other clients, conference calls, etc. But really, as mentioned our job is to make them understand items or at least make their job a heck of a lot easier.
36
NAPA 401(k) Summit Insider Summer 2022
WHAT THEIR EMPLOYEES REALLY THINK OF THEIR “PLAN AND HOW MUCH THEY VALUE MATCHING CONTRIBUTIONS.” How complex our job is. If you spend more than 10 minutes in a committee meeting on investments, you’ve spent too much time. Focus all your energy on making the benefits the best they can possibly be within your budget and the rest falls into place. This typically means more time on the employees themselves and what they need and less on what you think they need. I wish they understood the difference between a 3(21) and a 3(38) better. How much work we do between review meetings. How much work I do “behind the scenes” for them (this came up a lot).
About Themselves/Their Role
The level of loyalty and appreciation an employee will have for a company when good financial literacy and financial wellness components are in place. The importance of one or two key decisions and how they may impact many people a decade or two down the road. The impact they can make on their employees lives by offering a plan that has systematic savings for retirement. Your retirement benefits are a reflection of how important your people are to you. That ESG means different things to different people (and that includes the subjectivity allowed by different investment managers).
Why this matters. So many (smaller) plan sponsors still turn a blind eye to their retirement benefits. Wish they cared more about making decisions that actually help their people like auto enroll/auto escalate. What they are doing/taking on is not a simple task but we are here to help! What a priority their (k) plan is considering their liability. To look at the broad picture, and always keep the participants up front. The seriousness of their fiduciary responsibility. They should understand the basics of how their plan works and the liability/ risk associated with their choices.
put in 4% per year. Nothing counts more than performance. Their responsibilities as fiduciaries to the plan. The value of providing education and participant investment advice. The value of having retirement plans and other corporate benefits. The true value of financial wellness programs for employees. The true cost of aging employees who can’t afford to retire and continue to work. That they must actually read their plan document. I wish they thought more about autoenrollment.
Their retirement plan responsibilities are not always urgent but they are always important.
How much they can change employee lives by having a great plan.
Their responsibilities when sponsoring a plan.
Having a great retirement plan doesn’t need to be complicated.
Their employees need help and encouragement to save more now. Times have changed and employees no longer resist features like autoenrollment and auto-escalation.
Fiduciary responsibilities (this came up a lot).
The use of a 401k can achieve an ROI rather than just be an expense. There are so many hidden fees that the fees the sponsor sees are misleading. Math is commutative. if the plan performance is 4% per year participants need to put in 10% of their salary. If the plan performance is 10% per year, participants need only
Auto-features. Huge mental block that they are being “too big brother” and that their employees will revolt. Definitely not the case, and in my experience with clients who have auto-features, employees see it as a positive. They are handling other people’s monies and futures. Help your employees prepare for their retirement. Make a difference! SI
NAPA 401(k) Summit
SAVE THE DATE April 2-4, 2023 | San Diego, CA
WWW.NAPASUMMIT.ORG
38
NAPA 401(k) Summit Insider Summer 2022
What ‘Nobody’ is Talking About… There’s a lot to talk about in supporting and serving retirement plans, everything from the day-to-day issues of payroll deposits and reconcilement to cybersecurity measures, from ESG (re)considerations to—well, you name it. That said, there is inevitably an unacknowledged elephant in the corner of every discussion room— and we asked our Summit Insiders to speak up—and tell us, “what is nobody talking about that everybody should be talking about?” Here’s a sampling: Why are we removing the in-plan Roth conversion while attempting to add new Roth features in SECURE 2.0? Why are we not fighting to keep that provision? While everyone is trying to solve the retirement coverage crisis, in some aspects they’re going in the wrong direction. Some small employers fear being perceived as ‘stupid’ for not understanding our Retirement System. It is far too complicated and while legislation like the Secure Act and Secure 2.0 are needed, in many ways they’re making a complicated system more complicated. I think we should be looking to simplify within the current structure. Do we really need to have State Run IRAs, 403(b) plans, Simple and SEP IRAs? Couldn’t we simplify the current 401(k) system to allow for greater flexibility, additional safe harbors, etc.? Where things are going in the industry with client expectations and how the new rules are going to affect us.
What changes need to be made to Social Security so that participants understand there will be some form of Social Security available to them when they retire. We are not talking about how inflation will affect your retirement income as we should. Treat retirement planning like wealth management.
The way that fund companies share revenue. The rush of private equity in the market has changed the landscape of the entrepreneurial spirit. The RK firms actively and aggressively competing with advisors in offering advice (conflicted) to participants. The retirement plan crisis we are facing.
WE NEED TO “KILL THE WORD
RETIREMENT AND FOCUS ON FINANCIAL INDEPENDENCE AND INCLUSION. OTHERWISE, THE KILLER APPS THAT ARE COMING ARE GOING TO EAT OUR LUNCH.” Their role as a fiduciary on a committee. The value of backdoor Roths as an executive benefit that also works for key employees.
The potential PEPs have to revolutionize plan coverage for America’s workers. The negative effects of fee compression. The industry consolidation is making it so larger vendors are competing with retirement plan advisors. Will end up being all bundled again. The implementation costs of items in the Secure 2.0 proposed legislation. The impact of extremist ideologies on our industry and the economy in general. Everyone needs to keep that in mind when they go to the voting booth. The impact of all the advisor aggregation and recordkeeper consolidation. The drastic and unforeseen impact that COVID has had on workplace benefits and the service providers that administer these benefit programs. The massive consolidation taking place is only beginning and
39
NAPA 401(k) Summit Insider Summer 2022
the migration process of existing clients to the new Recordkeeper is a tremendous headwind and detractor to margins. The decumulation phase is equally important as the accumulation phase. The dangers of ESG. Everyone’s afraid to go against the “wisdom” of this. Too extreme. The danger of crypto currency in 401k plans.
lemono
/ shutterstock.com
The conflicts in some areas where “researchers” are paid to sell products, or offer “educational” programs to sell territories. These conflicting entities damage the industry’s reputation.
benefit after fees on the qualitative and quantitative side.
Reducing government regulations in our industry.
That recordkeeper retirement income needs calculators do not factor in taxes and often underestimate the amount of Social Security that lower income people will receive.
Recordkeepers moving back to the old proprietary fund requirements to offset tighter margins in core recordkeeping.
Sorry rollover chasers! There are fewer and fewer reasons for participants to move money out of DC plans. PTE 2020-02 is going to force recordkeepers to innovate with respect to managing things related to terminated balances. Roth conversations and tax management during retirement. Risk in target-date fund allocations.
That cheaper doesn’t mean better just because a certain law firm continues to threaten the industry. That’s it’s not all about fees. It’s net
Recordkeeper consolidation is leading to lower service levels. Really telling during the family feud session... We don’t really speak the language of sponsors and don’t know what their concerns are. We are a push industry, and need to do a better job of listening and speaking the language of plan sponsors. Raising the 402g limits. Is saving only $20,500 per year going to be enough to retire on comfortably?
Retirement readiness. Retirement income products (they are talking but not in enough detail).
PEPs are not being pushed by advisors because they are not incentivized to do so. PEPs are a
40
NAPA 401(k) Summit Insider Summer 2022
Lifetime Income.
CONTINUED “DISCUSSION
OF THE NEED FOR PLANNING FOR HEALTH EXPENSES AND LONGTERM CARE, PARTICULARLY HOME CARE IN RETIREMENT.” superior solution to the standalone 401(k) and in time, the majority of plans will be and should be part of a PEP. PTE 2020-02 compliance. Payroll services. Opportunity to drive value for the client by exploring plan designs like Profit Sharing, Cash Balance, and non-qual solutions..
Larger demographic trends and how they will inform where the business goes next. Lack of regulation around cryptocurrency. Lack of financial education of the everyday person. Lack of access to the private markets for the average saver. Inflation. Independent Annual Audits are costing employers more time and money. Each year the process has ratcheted up to include extremely lengthy and detailed questionnaires combined with the need to create separate and distinct process and procedure documentation/manuals. Concerned about the provider consolidation and with that, the ability for these acquiring providers to assimilate all the new plans, systems and staff. I’m concerned with the idea that corporate retirement plans are being used to solve all financial problems with employees. How to profitably get more companies to start plans. Coverage.
Mental health. Margins compressing further in prolonged down market now that the Fed is stepping back. Managed accounts. Moreso as to how they are technically better than target dates. Managed Account fees. Looking for/training the next generation of retirement plan experts/ advisors.
How are recordkeepers going to handle the student repayment situation. How advisors/firms that act as 3(38) will have to shift in the event of ESG legislation/policies. How advisors can cost costs on inplan managed accounts and keep most of the revenue for themselves. Greater emphasis on DEI focused benefits and employee engagement strategies.
Future possible litigation from forced under savings in auto features (starting at 3%). Fun ways to engage participants and focus on happiness. Financial literacy needs to start in grade school. Fee disclosure—both 408(b)2 and 404(a)5. They are not really transparent and way too hard to understand. Still have the ability to hide fees, which should be fixed. Faith Based Funds in plans, many more questions about this than ESG. Also, portability from job to job. Everyone talks about scale but nobody talks about how. Eligibility and who tracks it and how? Do your clients really understand when people become eligible? What are the processes you have in place to review this BEFORE compliance testing is run??? Deferred compensation programs have been put on the back burner. Cyber security for record keepers is talked about all the time, we should be talking to individuals about protecting themselves from cyber attract on total financial matters and market to plan sponsor for individual policies paid or partially paid by the employer or payroll deductions to again simplify their lives. Compliance. Cash balance plans for small business owners. After Tax use for emergency savings. Why put legislation in place when you can build into the plan? SI
When it comes to in-plan retirement income solutions, what do advisors and plan sponsors want? Fiduciary protection Flexible implementation Fee transparency Portability Non-proprietary products Withdrawal options
Checks every box (and then some) Guarantees are subject to the claims-paying ability of the issuing companies.
Learn more at incomeamerica.com
INSURANCE INVESTMENTS RETIREMENT
Put some PEP in your retirement plan client’s step Pooled Employer Plans from Securian Financial • Fiduciary protections • Flexible plan design • Individual plan pricing • Audit savings
Learn more Call 1-877-876-4015 today.
Securian Financial’s qualified retirement plan products are offered through a group variable annuity contract issued by Minnesota Life Insurance Company. Securian Financial is the marketing name for Securian Financial Group, Inc., and its subsidiaries. Minnesota Life Insurance Company is a subsidiary of Securian Financial Group, Inc. Securian Financial Group, Inc. securian.com 400 Robert Street North, St. Paul, MN 55101-2098 ©2022 Securian Financial Group, Inc. All rights reserved. F97076-1 Rev 5-2022 DOFU 5-2022 2199627