July 2021
The Danish Property Federation’s Market Statistics – Consensus Forecast • In 2021, the professional investment property market expect that the total return decreases to 5.7 percent • Retail may be past the worst period • In 2020, retail had an average value increment of minus 2.8 percent • Higher expectations to Aalborg
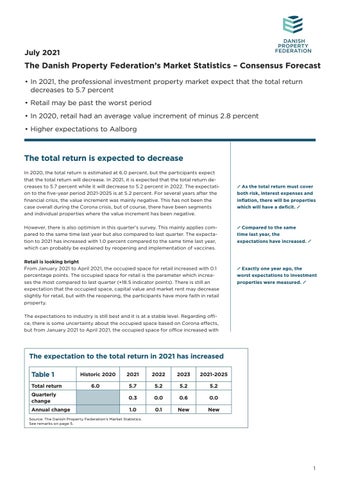
The total return is expected to decrease In 2020, the total return is estimated at 6.0 percent, but the participants expect that the total return will decrease. In 2021, it is expected that the total return decreases to 5.7 percent while it will decrease to 5.2 percent in 2022. The expectation to the five-year period 2021-2025 is at 5.2 percent. For several years after the financial crisis, the value increment was mainly negative. This has not been the case overall during the Corona crisis, but of course, there have been segments and individual properties where the value increment has been negative. However, there is also optimism in this quarter’s survey. This mainly applies compared to the same time last year but also compared to last quarter. The expectation to 2021 has increased with 1.0 percent compared to the same time last year, which can probably be explained by reopening and implementation of vaccines. Retail is looking bright From January 2021 to April 2021, the occupied space for retail increased with 0.1 percentage points. The occupied space for retail is the parameter which increases the most compared to last quarter (+18.5 indicator points). There is still an expectation that the occupied space, capital value and market rent may decrease slightly for retail, but with the reopening, the participants have more faith in retail property.
As the total return must cover both risk, interest expenses and inflation, there will be properties which will have a deficit.
Compared to the same time last year, the expectations have increased.
Exactly one year ago, the worst expectations to investment properties were measured.
The expectations to industry is still best and it is at a stable level. Regarding office, there is some uncertainty about the occupied space based on Corona effects, but from January 2021 to April 2021, the occupied space for office increased with
The expectation to the total return in 2021 has increased Table 1 Total return
Historic 2020 6.0
2021
2022
2023
2021-2025
5.7
5.2
5.2
5.2
Quarterly change
0.3
0.0
0.6
0.0
Annual change
1.0
0.1
New
New
Source: The Danish Property Federation’s Market Statistics. See remarks on page 5.
1
The Danish Property Federation’s Market Statistics - Consensus Forecast, July 2021
/ Office were best in 2020, while retail, unsurprisingly, had the lowest return. /
0.4 percentage points. The expectations to residential are unchanged occupied space and market rent, while the capital value may increase slightly as there are still investors who are asking for ownership of properties. Progress in Aalborg Aalborg is the city of opportunities and this survey shows a relative progress for Aalborg compared to the other areas in the country. Property owners know Aalborg as the city with the highest residential vacancy. The vacancy in April 2021 is 8.1 percent in the municipality of Aalborg against a national average of 5.0. But as long as moving to Aalborg is still expected, the expectations to the values may be improved. The participants expect the best capital value development in this prioritised sequence: Copenhagen, Aarhus, the Triangle Area, Odense, Aalborg and the rest of the country. Decreasing total return in 2020 The historical total return decreased with 1.5 percentage points from 2019 to 2020. It was especially retail which had a poor total return of 0.4 percent in 2020, which was primarily due to the fact that the value increment for retail was -3.8 percent.
Figure 1. The participants’ expectations To 2021
18 %
expect a total yield of 7 percent or more.
29 %
expect a total yield of 5 percent or below.
Development in total yield from 2010 to 2023
33 %
16 %
expect a total yield between 7 and 6 percent.
expect an increase in total yield.
44 %
expect a decrease in total yield.
38 %
22 %
expect a total yield between 6 and 5 percent.
expect an unchanged total yield.
The record worst measurement is now one year ago (The indicator values between -100 and 100) Table 2
Capital value July 2021
Occupied space
Quarterly change
Annual change
Market rent
July 2021
Quarterly change
Annual change
July 2021
Quarterly change
Annual change
Office
21.1
5.2
33.9
0.0
14.9
20.9
12.2
4.8
23.9
Retail
-27.8
11.6
24.5
-14.4
18.5
17.0
-28.9
11.5
15.3
Industry
25.6
-2.1
22.1
14.4
1.7
11.0
22.2
-4.4
19.9
Residential
18.9
-4.5
21.2
1.1
-2.1
3.4
6.7
0.3
13.6
Source: The Danish Property Federation’s Market Statistics. The participants have answered: ”Much lower”, ”lower”, ”unchanged”, ”higher” and ”much higher” on the question: ”What are your expectations to the development of [sector] buildings with prime location in a year compared to today?” The answers are given a value in order to achieve an indicator between -100 and 100. An indicator of 100 means that everybody has answered “much higher”, and -100 means that everybody has answered “much lower”. Indicator zero states expectations to unchanged conditions. An indicator of 21.1 may for example be obtained by 21.1 percent of the participants answering ”much higher” and the remaining corresponding ”unchanged” or that 42.2 percent answering “higher” and the remaining answering ”unchanged”.
2
The Danish Property Federation’s Market Statistics - Consensus Forecast, July 2021
The property market in 2020 was primarily dominated by the Corona situation. But the uncertainty has not stopped the investors’ demand for properties – on the contrary. Properties are still a rather safe investment. The exception is retail property, which due to closure and uncertainty about the future, had to depreciate the capital value in 2020. Some residential properties were also affected by political measures against thorough refurbishing (§5(2)), which meant that almost half of the older residential properties built before 1965 had a negative value increment – despite a generally increasing demand for properties.
Totalt return
Direct return
Value increment
6.0
3.6
2.4
Office
7.8
4.3
3.5
Retail
0.4
4.2
-3.8
Industry
5.0
4.9
0.1
Residential
6.1
2.3
3.8
Table 3 Total
Figure 2. Half of the participants expect a total return in 2021 between 4.5 and 6.0 percent 20% 18% 16% 14% 12% 10% 8% 6% 4% 2% 0%
2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023
Source: The Danish Property Federation’s Market Statistics. Total return of investment properties. From 2011 to 2019, the total return from the Danish Property Federation’s market statistics is shown, while 2000 to 2010 is own calculations based on data from the IPD Danish Property Index. 2020 to 2022 shows the average of the answers in the Danish Property Federation’s market statistics - expectations. 50 percent of the answers are within the blue lines.
3
The Danish Property Federation’s Market Statistics - Consensus Forecast, July 2021
Figure 3. Aalborg is in decline regarding expectations to capital value Regionalindikator indicator Regional Least regional regionalvækst growth Mindst
Middel regional vækst growth Medium regional Anholt Anholt
Størst regional vækst
Largest regional growth
Rømø
Rømø
Source: The Danish Property Federation’s Market Statistics.
4
The map shows the areas in Denmark where the capital value of investment properties are expected to increase the most compared to the other areas. We have asked about the Triangle area, Copenhagen, Aarhus, Aalborg, Odense and the rest of Denmark. The answers have formed an indicator. If an area is light blue, at least 70% of the respondents have agreed that this area is doing better than the others.
The Danish Property Federation’s Market Statistics - Consensus Forecast, July 2021
About the survey These are the expectations for July 2021 from the Danish Property Federation’s market statistics. The aim is to create information for a more transparent property market. The survey is published every quarter and is completely and utterly dependent on the participating companies being willing to report data every quarter. Without these companies, the survey would never become a reality.
45 market players have participated in this survey. 51 percent of the participants are property owners. In addition, 11 percent are property administrators, 20 percent are commercial brokers, 7 percent are banks/mortgage providers and 11 percent are other players.
The following companies have contributed Aberdeen Asset Management, Agat ejendomme, ATP Ejendomme, BBN Consult, Bertélco Ejendomme A/S, CBRE, Chr. Hjorth Erhvervsejendomme, Colliers, Copenhagen Capital, Cura Management, DADES, Danbolig erhverv Johnny Hallas, Danica Ejendomme, DEAS, EDC Erhverv Poul Erik Bech, EK-Ejendomsadministration A/S, Elf Development, EY, Fokus Asset Management, Heimdal Nordic, Heimstaden, Hosta Ejendomme, Jeudan, Jorcks Ejendomsselskab, Jyske Bank, Karberghus, Keystone, KFI Erhvervsdrivende Fond, KLP ejendomme, Lintrup & Norgart, Lokalebasen.dk A/S, Lundsgaard Erhverv, Lægernes Pensionskasse, M7 Real Estate, M. Goldschmidt Ejendomme, NCC Construction Danmark A/S, Newsec Advisory, Newsec Property Asset Management Denmark, Niam, Nordea, Nordicals, Nykredit, P+, Patrizia, PBU – Pædagogernes Pension, Pensam, PensionDanmark, PFA Ejendomme, PKA, Probus Ejendom og Investering, Prodomus, PwC, Qvortrup Administration, Realdania, Realkredit Danmark, Sampension, Sinding Gruppen, Taurus Ejendomsadministration, Thor Stevnss Real Estate, Thylander Gruppen, TLK, Topdanmark Ejendom, Wiborg & Partnere and Øens Advokatfirma og Ejendomsadministration.
Further information If you wish to know more about this publication please contact Director in the Danish Property Federation
Morten Marott Larsen mml@ejd.dk Phone +45 28 45 56 51
Remarks for table 1 The table indicates the average total return based on the replies for the years 2021-2025. The total return is in percent and measures the return on investment on investment properties in relation to the size of the investment in a given period. The total yield includes two types of yield: Direct return and return on value. The direct return is the period’s ongoing net operating results divided by the investment size in the beginning of the period. Return on value is the value increment in the given period divided by the size of the investment at the beginning of the period. The total return is before any financial costs and inflation. The historic total yield may change slightly in the future when new data is added to the market statistics.
5