Vanguard Markets | Monday, February 16, 2015 | Issue 029
But retain your confidence in Nigeria. Indeed, increase your level of confidence in Nigeria; this economy is resilient. - Godwin Emefiele, CBN Governor, February 12, 2015
THE EXPERTS’ CONSENSUS
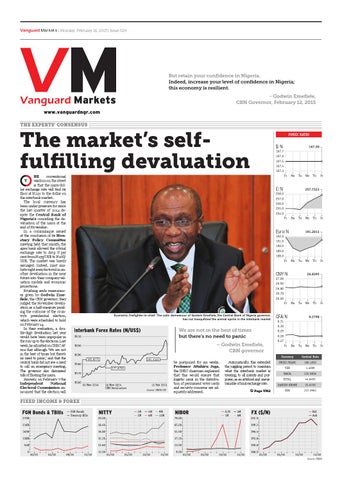
The market’s selffulfilling devaluation HE conventional wisdom on the street is that the naira-dollar exchange rate will find its floor at N220 to the dollar on the interbank market. The local currency has been under pressure for since the last quarter of 2014 despite the Central Bank of Nigeria’s conceding the devaluation of the naira at the end of November. In a communiqué issued at the conclusion of its Monetary Policy Committee meeting held that month, the apex bank allowed the official exchange rate to drop 8 per cent from N155/US$ to N168/ US$. The market was barely assuaged. Indeed, most analysts right away factored in another devaluation in the near future into their company valuation models and economic projections. Brushing aside reassurances given by Godwin Emefiele, the CBN governor, they judged the November devaluation as a half-measure pending the outcome of the country’s presidential election, which were scheduled to hold on February 14. In their evaluation, a double-digit devaluation last year would have been unpopular in the run-up to the elections. Last week, he admitted on CNBC Africa that although ‘We are not in the best of times but there’s no need to panic,’ and that the central bank did not see a need to call an emergency meeting. The governor also dismissed talk of floating the naira. Anyway, on February 7 the Independent National Electoral Commission announced that the election will
FOREX RATES
$/N
167.50
167.7 167.6 167.5 167.4 167.3 Fr
Mo
Tu
We
Th
Fr
T
£/N
257.7323
258.0 257.0 256.0 255.0 254.0 Fr
Mo
Tu
Euro/N
We
Th
Fr
191.2013
192.0 191.0 190.0 189.0 188.0 Fr
Mo
Tu
CNY/N
We
Th
Fr
26.8395
27.00 26.90 26.80 26.70 26.60 Fr Economic firefighter-in-chief: The calm demeanour of Godwin Emefiele, the Central Bank of Nigeria governor, has not tranquilized the animal spirits in the interbank market
We are not in the best of times but there’s no need to panic – Godwin Emefiele, CBN governor be postponed for six weeks. Professor Attahiru Jega, the INEC chairman explained that this would ensure that logistic jams in the distribution of permanent voter cards and security concerns are adequately addressed.
Automatically, this extended the juggling period to maintain what the interbank market is treating, to all intents and purposes, as an artificial and unsustainable official exchange rate.
! Page VM2
Mo
Tu
CFA/N
We
Th
Fr
0.2798
0.31 0.30 0.29 0.28 0.27 Fr
Mo
Tu
We
Th
Currency
Central Rate
SWISS FRANC
180.1850
YEN
1.4089
WAUA
235.9858
RIYAL
44.6405
DANISH KRONE
25.6799
SDR
237.0963
Fr
FIXED INCOME & FOREX
Source: FMDQ
VM2
BUSINESS
VM | Monday, February 16, 2015 | Issue 029
JAYWALKER
Victims of politics The savaging of truth and its fraternal twin, context explains why media stories and campaign speeches are awash with absolute figures and incomplete comparisons.
How tall is the problem? This high? Thomas Piketty, author of Capital in the 21st Century, freely shared the data and illustrations he used in his book.
Obiora Onyeaso obiora.onyeaso@customsstreet.com
MONG the calamities of war may be jointly numbered the diminution of the love of truth, by the falsehoods which interest dictates and credulity encourages.’ So wrote Samuel Johnson, an Englishman of letters in The Idler, a collection of essays that appeared in the 18th century. In On War, his posthumously published book, Carl von Clausewitz, a Prussian general, military theorist and contemporary of Emperor Napoleon Bonaparte, pointed out that ‘war is the continuation of politics by other means.’ Closer in time, Hiram Warren Johnson, a US Senator speaking in 1918 is reported to have said that ‘The first casualty when war comes is truth.’ These three
A
quotes drawn from three different centuries describe the weather in this season of Nigerian politics. Truth is not the only victim of war and politics, two sides of the same coin. Context also suffers because struggles for predominance do not admit for shades of grey. When the stakes are high things are either black or white. Nuances are well and good in academia. They have no space in the minefield called Nigerian politics. Nowhere is the maxim that you are either for us or against us truer. The savaging of truth and its fraternal twin, context explains why media stories and campaign speeches are awash with absolute figures and incomplete comparisons. Figures on unemployment, oil theft, government expenditure are hardly given with the attenuating circumstances that should couch their interpretation. Trends are deemed not worth glancing at either. Political campaigns are organized polemics. Therefore, it is fair game when all kinds of accusations, failures, and plots are attributed to the other side. The theme of the 2015 elections was supposed to be issue-based politics. No-one takes that seriously again.
Under the banner of issuebased politics, personalities whose track record command attention have joined the fray. A recent example is Professor Charles Chukwuma Soludo, the former governor of the Central Bank of Nigeria (2004-2009). In January, he authored Buhari vs Jonathan: Beyond the Election, a critique of the financial implications of the manifestoes of the ruling Peoples Democratic Party, and the main opposition party, the All Progressives Congress. In the same piece, he shared his opinion on the economic stewardship of the President Goodluck Jonathan administration.
Almost immediately after its publication, an avalanche of rejoinders and comments flooded in. Just as quickly, the essence of his points evaporated in the cacophony of brays from those who chorused ‘How dare he?’ in disgust, on one side, and those who clamoured ‘Encore! Encore!’ in didn’t I tell you so backslapping, on the other. Whatever the merits of the points he marshalled one expected that he, a professor of economics, would have provided more data and more than simplistic explanations. Far and above the data one would have liked to see charts that would aid readers visualize the trends in the areas he discussed.
Take the extract below supposed to incriminate Peter Obi, a political rival against whom he contested the Anambra State gubernatorial elections in February 2010. ‘While ex-governor Peter Obi gloated about savings, there is no signature project to remember his regime except that his regime took the first position among all states in Nigeria in the democratization of poverty—- mass impoverishment of the people of Anambra. According to the National Bureau of Statistics, poverty rose under his watch in Anambra from 20% in 2004 (lowest in Nigeria then) to 68% in 2010 (a 238% deterioration!).’ On poverty in Anambra, it would have been educating to compare the rise in poverty he refers to with factors such as the state’s monthly receipts from the federal government, its internally generated revenues, the state government’s own development agenda, and the figures from other states in similar conditions as Anambra all shown as charts for easy visual digestion. Instead, the professor dumped these numbers on readers’ heads under the assumption that they would spare him the bother of explaining them at a deeper level. Contrast Soludo’s piece with that of another professor of economics. Thomas Piketty, a Frenchman, is the author of Capital in the 21st Century, a best-selling book about the growing inequality in developed economies. At its publication, Piketty widely publicised that all the data used in the book will be freely available at www. quandl.com/PIKETTY,
and the charts at http:// piketty.pse.ens.fr/files/ capital21c/en/Piketty2014FiguresTablesLinks. pdf. He and his colleagues at the Paris School of Economics where he teaches, Facundo Alvaredo, Tony Atkinson, and Emmanuel Saez maintain the world’s most extensive database of incomes. It is accessible to the public at http://topincomes.parisschoolofeconomics.eu. Piketty made it easy for critics to question the validity of his data and causal links to his conclusions rather than his political motives if any. Understandably, the space afforded by a book far exceeds the limited space in a newspaper. But the medium is not the point. It is that readers are better informed when provided the context of claims. Unless, of course, the purpose is to mislead or incite. Indolence may also be cited but no-one who knows Soludo’s industry will dare accuse him of that. In conclusion, issue based politics is meaningless without the caveats that any serious intellectual enterprise admits. Otherwise, it is reduced to the sordid level of ideological bar brawls. Spectators find it amusing when professional politicians swing chairs at one another in the public space of ideas. It is quite another when one of Nigeria’s most respected academics in the field of economics dispenses wide sweeping value-loaded generalizations that lose their way in detours to settling personal scores. The brutality of politics should not be allowed invade the sanctity of the ivory tower. ;
THE EXPERTS’ CONSENSUS
The market’s self-fulfilling devaluation W Continued from Page VM1 Analysts doubt that the CBN has the circus skills to keep all its balls in the air that long. They surmise that sooner, rather than later, and very likely before the March 28 election date, it will bow to the market reality. Other analysts cut the CBN more slack on the date of devaluation, only going so far as to place it before the end of the year. For example, analysts at
Dunn Loren Merrifield ‘see the possibility of a further devaluation of the currency in the current year to ease the rapid depletion of the reserves if current economic realities persists.’ In the circumstances, there is the likelihood of ‘further adjustment of the mid-point of the official exchange rate to the range of N190/US$.’ At N190/US$ that would be a 13 per cent devaluation on the current N168/US$ exchange rate.
In its latest update on the country’s foreign reserves, the CBN disclosed that between January 28 and February 10 it had dropped by US$1 billion to $33.4 billion. One does not have to look very far to find the reason for the interbank market’s scepticism about the official exchange rate. According to analysts at CSL Stockbrokers, the last time the naira was devalued in 2008/9, the average exchange rate of N149/US$ was
27.4 per cent lower than in the first nine months of 2008, when it averaged N117.62/ US$ on the interbank market. On Thursday, the naira now traded at N204/US$, that is, 25.5 per cent lower than the average exchange rate of N162.52 in the first nine months of 2014. Therefore, what the market has experienced is a replica of the 2008/9 situation. But it would not stop there. There is still a couple of inches to fall. Political un-
certainty around the credible elections, and the volatility in oil prices remain. This could push the drop further by 10 per cent to N200/US$. This is the base case in CSL Research’s scenario. At this level, the market would have fully adjusted to the new reality. The naira would then enjoy stability underpinned by ‘three principal factors that should support the currency at a lower level.’ These are a decline in import costs partly due to
a lower petroleum import bill, fewer outflows visible in the ‘net errors and omissions’ item in national accounts, that is, a decline in capital flight, and increased imports, traceable to both portfolio and foreign direct investments as Nigerian assets become cheaper. The question on everyone’s lips now is: How long the CBN can go in holding back the waves as King Canute once tried to do with futility? ;
BUSINESS
VM | Monday, February 16, 2015 | Issue 029
VM3
REWIND
Let there be light
Growth on shaky ground HE Nigerian economy grew by 6.33 per cent in 2014, a clear 84 basis points higher than the 5.49 per cent growth it recorded in 2013. This ‘highlights the sustained resilience of the Nigerian economy’ according to Kate Isabota, analyst at Dunn Loren Merrifield. In a report titled Growth encircled by vulnerabilities, she advocates that the federal government must push ahead with
T
Technicians at Geregu II Power Plant in Ajaokuta, Kogi State uncrating new equipment.
HE pieces are all coming together in the federal government’s bid to provide an enabling business environment for companies operating in the Nigerian Electricity Supply Industry (NESI). Epileptic power supply is a major drain on economic productivity and citizens’ quality of life on Nigeria. It also ratchets up the cost of doing business in the country. Poor investment levels, unattractive tariffs, and huge aggregate technical, commercial and collections (ATC&C) losses among others were to blame. To assist these companies meet the shortfalls in their revenues and pay down certain legacy debts, the Central Bank in partnership with
T
1st disbursement
2nd disbursement
banks has provided an intervention fund. In his speech delivered at the disbursement of the N213 billion Nigerian Electricity Market Stabilization Facility (NEMSF), Godwin Emefiele, the CBN governor envisaged that the beneficiaries will ‘invest the funds in the necessary improvements in generation plant maintenance, transmission upgrades and distribution networks including transformers and better metering for end consumers.’ Loans offered by NESF have a 10 per cent per annum rate of interest and will be repaid over 10 years from a reset of the Multi-Year Tariff Order (MYTO). Two disbursements have been made so far from the facility. ;
Company
Amount
Ibadan DISCO
N11.36b
Eko DISCO
N5.16b
Jebba Hydroelectric
N816.83m
Kainji Hydroelectric
N678.85m
Shiroro Hydroelectric
N234.81m
Enugu DISCO
N10.25b
Kano DISCO
N7.63b
Port Harcourt DISCO
N6.58b
Eko DISCO
N43.3m
Egbin Power Plant
N5.1b
Transcorp Ughelli Power Plant
N3.9b
Geregu II Power Plant
N938.99m
Jebba Hydroelectric
N2.38b
Shiroro Hydroelectric
N1.97b
Kainji Hydroelectric
N684.44m
Total
Total
reforms and investment in the country’s agricultural and industrial sectors to maintain this growth rate. Among the report’s predictions for 2015 are ‘a further devaluation in the current year as N168/US$ does not reflect the true position of the naira particularly in view of current economic realities’, and threats to future growth due to ‘dwindling oil prices coupled with lower oil production’. ;
Not yet uhuru for Dangote Flour HE latest results from Dangote Flour Mills raises more questions about the company’s future strategy than it answers. Alex Ibhade, an analyst at DLM observes that while ‘the revenue growth signals notable progress, and recovery can be expected… the company appears to have a long road ahead in terms of recovery in order to reach the revenue and net profit levels attained in 2009. Dangote Flour faces a number of stubborn threats. Its sales revenue has struggled to surpass cost of sales despite a drop in wheat prices. To plaster the shortfall in revenues the company may be financing its operations from reserves. Its balance sheet has also suffered evident in an 11.40 per cent shrinking in fixed assets and 60.30 per cent drop in cash and bank balances. Short-term loans rose by 48.50 per cent, while shareholders’ funds fell 48.18 per cent from N12.91 billion to N6.69 billion. ;
T
Turnover
FY2014
FY2015E
FY2016E
FY2017E
41, 268.00
51,585.00
63,449.55
72,966.98
25.00%
23.00%
15.00%
(46,426.50)
(56,470.10)
(64,210.94)
19.43%
21.63%
13.71%
5,158.50
6,979.45
8,756.04
115.30%
35.30%
25.45%
(7,737.75)
(8,882.94)
(9,485.71)
2.64%
14.80%
6.79%
0.00
0.00
0.00
0.00
0.00
0.00
(2,579.25)
(1,903.49)
(729.67)
-59.90%
-26.20%
-61.67%
Change % Cost of Sales
(38,872.00)
Change % Gross Profit
2,396.00
Change % SG&A
(7,539.00)
Change % EBITDA
0.00
Change % Operating Profit
(6,432.00)
Change % Other Income
0.00
0.00
0.00
0.00
Change %
(6,130.00)
(2,063.40)
(1,268.99)
(0.00)
EBIT
(6,130.00)
(2,063.40)
(1,268.99)
(0.00)
-66.34%
-38.50%
-100.00%
(4,085.94)
(3,441.53)
(1,935.45)
-55.99%
-15.77%
-43.76%
Change % Profit Before Tax
(9,285.00)
Change % Taxation Profit After Taxation Change %
0.00
0.00
0.00
0.00
(6,279.00)
(4,085.94)
(3,441.53)
(1,935.45)
-15.77%
-43.76%
-34.93%
Source: Dangote Flour Mills, Dunn Loren Merrifield Research
N18.26b
Introducing The Financial Services Plans and Products Guide
N39.5b
Vanguard Markets will soon introduce a special section on Plans and Products offered by companies in the Financial Services sector. The section will cover the suite of packaged offerings provided by • Banks • Insurance companies • Asset management companies • Fund managers • Pension funds • Mortgage companies
The section will be aimed at individuals, households, and businesses who wish to 1. Learn about available options in each plan and product category, for example, Fixed Deposit accounts, Mortgage Loans, Car Loans 2. Compare the features of plans and products in each category, for example, interest rates, minimum deposits, penalties 3. Discover the most suitable plan or product that best matches their situation, for example, retirement savings,
home ownership, education savings, salary payments The section will provide answers to questions that customers have on • How to save better • How to spend smarter • Where to find the best financial planning deals To feature your company’s products in the section, contact Obi Onyeaso at obiora.onyeaso@customsstreet.com or call 0803 437 1224.
N57.75b
Published by
EDITOR: MIDENO BAYAGBON GROUP BUSINESS EDITOR: OMOH GABRIEL
In Association With
CONTENT DIRECTION: OBIORA TABANSI ONYEASO DESIGN & ILLUSTRATION: PUBLICAN MEDIA
Vanguard Markets features unbiased, in-depth coverage of corporate and market developments across a wide range of business sectors. Every week, Vanguard Markets delivers essential business analysis and commentary on Nigerian companies, regional economies, and global markets. Vanguard Markets is published by Vanguard Media Limited in association with Customs Street Advisors Limited, a specialist communications consultancy.
Vanguard Media Limited, Vanguard Avenue, Kirikiri Canal, P.M.B.1007, Apapa. Website: www.vanguardngr.com ISSN 0794-652X
VM4
MARKET DATA
VM | Monday, February 16, 2015 | Issue 029
TRADING UPDATE Declined Unchanged Advanced
MARKET REVIEW – FEBRUARY 09 – 16, 2015
SECTOR PRICE CHANGES – FEB 09 – 16, 2015 TOP DECLINERS
TOP GAINERS
WTD
TOP GAINERS
WTD
TOP DECLINERS
AIRLINE SERVICES AND LOGISTICS PLC
19.3
VITAFOAM NIGERIA PLC
5.23
SEPLAT
15.3
ETERNA PLC
4.76
NATIONAL SALT COMPANY NIGERIA PLC
CADBURY NIGERIA PLC
10.21
JULIUS BERGER NIGERIA PLC
4.1
RED STAR EXPRESS PLC
2.63
TRANSNATIONAL CORPORATION OF NIG PLC
-18.57
R. T. BRISCOE (NIG.) PLC
2.44
ASHAKA CEMENT PLC
-18.45
IKEJA HOTEL PLC
-17.71
THE OKOMU OIL PALM COMPANY PLC CEMENT COMPANY OF NORTHERN NIGERIA PLC
9.95
WTD -20.53
GUARANTY TRUST BANK PLC -19.05
8.97
WTD
FLOUR MILLS NIGERIA PLC
-15.2
UAC OF NIGERIA PLC
-13.55
UNITED BANK FOR AFRICA PLC -12.28 GUINNESS NIGERIA PLC
-11.62
ACCESS BANK OF NIGERIA PLC
-11.33
Agriculture Conglomerates Construction/Real Estate Consumer Goods Financial Services Healthcare ICT Industrial Goods Natural Resources Oil & Gas Services
2 2 2 16 20 5 0 4 0 5 5
2 2 7 12 36 4 11 14 5 4 9
1 1 0 3 1 1 0 3 0 2 4
DASHBOARD Friday Ticker 7UP ABCTRANS ACCESS AGLEVENT AIICO AIRSERVICE ASHAKACEM BETAGLAS CADBURY CAP CCNN CONOIL CONTINSURE COURTVILLE CUSTODYINS CUTIX DANGCEM DANGFLOUR DANGSUGAR DIAMONDBNK ETERNA ETI FBNH FCMB FIDELITYBK FIDSON FLOURMILL FO GLAXOSMITH GUARANTY GUINNESS HONYFLOUR INTBREW JBERGER LINKASSURE MANSARD MAYBAKER MOBIL MRS NAHCO NASCON NB NEIMETH NEM NESTLE NIGERINS NNFM OANDO OKOMUOIL PAINTCOM PORTPAINT PRESCO PRESTIGE PZ REDSTAREX ROYALEX RTBRISCOE SEPLAT SKYEBANK SOVRENINS STANBIC STERLNBANK TOTAL TRANSCORP UAC-PROP UACN UBA UBCAP UBN UNILEVER UNITYBNK VITAFOAM WAPCO WAPIC WEMABANK ZENITHBANK
5-day
Close
Change, %
Volume
Open
Week Hi
149.17 0.54 5.32 1.18 0.75 2.04 17.37 28.50 40.00 36.82 9.62 30.97 0.80 0.50 3.93 1.57 141.90 3.60 6.14 3.50 2.39 16.15 6.37 2.00 1.25 2.93 29.40 212.10 41.00 17.00 114.01 3.00 18.44 42.18 0.50 2.82 1.41 153.00 48.02 4.53 6.17 130.00 0.71 0.53 751.00 0.50 17.15 13.24 29.29 1.50 3.83 29.80 0.50 26.00 3.80 0.50 0.80 368.00 1.82 0.50 24.90 2.32 130.43 2.28 11.35 34.58 3.00 1.33 8.80 34.01 0.50 3.42 79.00 0.50 0.94 15.62
-4.99% 5.88% -4.83% 0.00% -1.32% 4.62% 0.00% 0.00% 12.58% 0.00% -2.04% 0.00% -2.44% 0.00% 2.34% 1.95% -1.88% -4.76% -4.95% -3.05% -4.78% -0.06% -4.93% 0.50% 2.46% 0.00% 3.16% 5.00% 2.50% -4.82% -4.19% 0.00% 5.25% -0.17%
1,123 220 157,759 206 45,814 842 1,870 0 1,896 174 4,501 181 6,960 442 14,762 5 56,955 3,592 9,257 60,895 1,412 416,402 279,277 161,514 59,032 2,419 25,466 4,240 70 1,142,218 2,700 1,304 33 1,250 0 355 105 91 5 448 6,096 126,599 60 5,546 679 92 0 10,398 19,737 0 0 1,216 82 5,129 430 156 60 816 155,637 0 5,408 16,400 1,473 557,568 11 4,949 141,507 16,486 8,246 37,066 3,500 360 31,136 10,767 108,854 324,120
152.86 0.55 6.00 1.26 0.81 1.71 20.24 31.49 38.24 37.00 9.50 32.60 0.87 0.50 4.00 1.47 159.80 4.00 6.90 3.95 2.54 16.61 7.00 2.09 1.27 3.20 34.20 210.00 40.21 21.00 128.90 3.07 20.55 42.65 0.50 2.95 1.43 157.60 48.02 4.75 7.55 141.81 0.72 0.57 815.25 0.50 17.15 14.93 27.90 1.43 3.83 30.45 0.50 27.36 3.70 0.50 0.82 333.90 1.97 0.50 24.23 2.35 142.41 2.80 11.35 40.90 3.42 1.45 9.00 35.50 0.50 3.25 88.80 0.51 0.94 16.28
157.50 0.55 6.08 1.26 0.85 2.04 20.24 31.49 42.98 37.97 10.31 32.60 0.90 0.50 4.00 1.57 160.01 4.38 7.55 3.98 2.70 17.00 7.00 2.09 1.29 3.20 36.00 212.10 42.10 22.00 130.00 3.28 20.55 44.40 0.50 2.96 1.44 157.60 48.02 4.75 8.12 148.00 0.72 0.59 815.25 0.50 17.15 15.48 29.29 1.50 3.90 31.97 0.50 29.00 3.90 0.53 0.88 405.00 2.00 0.50 25.93 2.39 149.90 2.91 11.35 40.90 3.70 1.50 9.40 35.70 0.50 3.59 89.00 0.53 0.95 16.99
0.00% 0.71% 3.28% 0.00% 0.67% -0.16% 0.77% 0.00% -3.64% -1.05% 0.00% 0.00% -2.29% 4.91% -1.91% 0.00% 0.97% 1.33% 0.00% -4.76% -3.16% 4.60% 0.00% 1.06% 1.75% -6.70% -5.79% 0.00% -5.05% 0.33% -4.32% -2.22% 2.29% 0.00% 0.00% -1.16% 0.00% 3.30% -0.45%
4-Week
Week Lo Change, % 149.15 0.51 5.32 1.18 0.74 1.71 17.37 28.50 35.53 36.82 9.10 29.50 0.80 0.50 3.81 1.47 139.10 3.60 6.14 3.49 2.39 15.98 6.37 1.94 1.15 2.93 26.60 192.00 40.00 16.69 114.00 3.00 17.52 40.52 0.50 2.82 1.35 147.56 48.02 4.42 5.88 128.27 0.71 0.53 746.25 0.50 17.15 13.24 26.05 1.43 3.83 28.00 0.50 25.75 3.70 0.50 0.76 333.90 1.70 0.50 23.79 2.21 130.43 2.19 11.35 34.58 2.90 1.33 8.80 33.25 0.50 3.25 78.51 0.50 0.89 15.42
-2.41% -1.82% -11.33% -6.35% -7.41% 19.30% -14.18% -9.50% 4.60% -0.49% 1.26% -5.00% -8.05% 0.00% -1.75% 6.80% -11.20% -10.00% -11.01% -11.39% -5.91% -2.77% -9.00% -4.31% -1.57% -8.44% -14.04% 1.00% 1.96% -19.05% -11.55% -2.28% -10.27% -1.10% 0.00% -4.41% -1.40% -2.92% 0.00% -4.63% -18.28% -8.33% -1.39% -7.02% -7.88% 0.00% 0.00% -11.32% 4.98% 4.90% 0.00% -2.13% 0.00% -4.97% 2.70% 0.00% -2.44% 10.21% -7.61% 0.00% 2.77% -1.28% -8.41% -18.57% 0.00% -15.45% -12.28% -8.28% -2.22% -4.20% 0.00% 5.23% -11.04% -1.96% 0.00% -4.05%
Volume
Open
Change, %
Volume
3,375 1,995 2,756,270 1,610 266,413 90,565 11,025 42,021 4,637 1,794 14,448 1,776 18,372 597 99,622 914 83,274 103,066 102,377 433,007 6,636 1,125,194 2,916,892 914,071 232,152 23,369 72,306 9,073 3,325 2,264,103 6,412 11,888 8,475 24,317 50 895 7,704 374 13 7,452 25,303 453,711 692 60,013 51,730 245 299 193,838 29,090 1,393 769 5,546 1,973 57,901 1,812 12,359 23,253 3,260 474,952 122 26,527 108,759 1,863 1,678,510 1,295 38,155 845,449 82,659 136,857 42,992 3,599 18,588 55,197 90,721 143,200 1,892,968
160.35 0.52 5.12 1.23 0.76 1.73 19.95 28.50 39.90 37.65 9.27 36.21 0.96 0.50 3.71 1.47 153.00 3.91 5.25 4.15 2.69 14.59 7.60 2.10 1.34 3.35 35.64 226.98 40.00 17.90 125.95 3.02 21.89 43.50 0.50 2.99 1.60 149.21 50.54 5.05 5.99 139.00 0.69 0.55 815.00 0.50 17.15 15.98 24.68 1.50 3.70 28.22 0.50 26.00 3.85 0.50 0.84 310.00 2.22 0.50 25.88 2.46 147.52 2.98 8.09 31.00 3.52 1.51 8.54 32.20 0.50 3.60 76.00 0.57 0.95 16.48
-6.97% 3.85% 3.91% -4.07% -1.32% 17.92% -12.93% 0.00% 0.25% -2.20% 3.78% -14.47% -16.67% 0.00% 5.93% 6.80% -7.25% -7.93% 16.95% -15.66% -11.15% 10.69% -16.18% -4.76% -6.72% -12.54% -17.51% -6.56% 2.50% -5.03% -9.48% -0.66% -15.76% -3.03% 0.00% -5.69% -11.88% 2.54% -4.99% -10.30% 3.01% -6.47% 2.90% -3.64% -7.85% 0.00% 0.00% -17.15% 18.68% 0.00% 3.51% 5.60% 0.00% 0.00% -1.30% 0.00% -4.76% 18.71% -18.02% 0.00% -3.79% -5.69% -11.58% -23.49% 40.30% 11.55% -14.77% -11.92% 3.04% 5.62% 0.00% -5.00% 3.95% -12.28% -1.05% -5.22%
66,674 45,481 9,727,780 8,660 531,336 388,461 29,154 116,344 25,294 11,482 35,339 12,760 271,265 20,203 762,981 10,660 245,950 429,221 2,258,778 3,220,952 42,073 3,367,429 9,283,643 3,904,951 3,839,497 126,367 517,985 62,487 38,709 5,708,174 184,300 55,142 79,907 40,697 400 47,967 24,656 3,187 1,224 73,900 291,804 906,018 26,097 153,253 70,598 6,425 385 10,054,013 143,307 4,360 11,127 238,292 9,811 254,621 19,223 23,035 88,474 50,352 1,741,561 5,073 498,606 603,860 5,943 3,883,901 42,470 243,589 3,461,390 491,545 206,361 754,780 65,005 280,079 125,686 629,253 351,391 5,127,188
5-Week trading1
52-Week price range Low 81.23 0.51 4.50 1.18 0.65 1.56 13.87 15.49 33.10 33.01 8.00 29.50 0.80 0.50 1.90 1.21 139.10 2.88 4.70 3.47 2.39 12.40 6.37 1.94 1.15 2.32 26.60 81.21 38.22 16.69 114.00 2.87 17.52 40.52 0.50 1.96 1.33 112.54 41.84 3.56 5.68 128.27 0.67 0.52 746.25 0.50 17.15 13.18 23.20 1.33 3.52 20.88 0.50 16.60 3.44 0.50 0.58 252.93 1.70 0.50 19.00 2.09 130.43 2.19 8.09 26.00 2.90 1.33 6.48 27.00 0.50 3.23 66.50 0.50 0.85 14.54
Close ( )
High 197.94 0.92 10.18 1.75 0.91 3.12 34.60 31.49 86.50 49.00 15.98 79.51 1.24 0.77 4.35 2.18 250.02 9.97 12.00 7.05 5.35 20.28 16.52 4.64 2.40 3.90 78.18 259.94 72.45 31.80 214.99 4.50 32.20 76.45 0.50 3.79 2.27 182.00 70.00 5.89 13.50 189.00 1.99 0.90 1,200.00 0.54 23.08 36.89 42.98 1.99 5.77 46.30 0.63 41.06 5.35 0.64 1.36 735.00 4.16 0.50 35.00 2.74 195.50 7.08 21.31 67.85 8.26 3.04 10.89 55.00 0.50 5.02 136.73 1.02 1.21 25.80
YtD
Liquidity Rating2
-6.18% -5.26% -15.42% -9.92% -10.71% 20.00% -16.53% 7.95% -4.76% -1.29% -2.63% -9.97% -17.53% 0.00% 11.97% 17.16% -25.32% -18.18% 1.66% -35.78% -20.07% -11.26% -26.78% -20.00% -21.88% -21.02% -24.89% -6.61% -13.52% -32.49% -31.03% -9.09% -16.97% -26.81% 0.00% -9.32% -6.62% -1.46% -4.99% -9.40% -1.59% -20.25% -6.58% -18.46% -24.57% 0.00% -1.15% -24.34% 17.16% 2.04% 3.23% 15.86% 0.00% 9.47% 1.06% -3.85% -4.76% 4.69% -28.06% 0.00% -8.05% -4.13% -12.47% -28.97% 18.60% 1.71% -30.56% -20.83% 3.53% -9.52% 0.00% -10.70% -2.47% -21.88% 2.17% -13.22%
LEGEND 5-week trading bar: This bar shows the volume of the company’s shares traded during the 5 most recent weeks. Each alternate colour bar represents a consecutive week. The bar is to be read from left to right. The first bar on the left (light blue) represents the traded volume five weeks ago. The next bar (grey) represents the volume 4 weeks ago. The 5th and last bar (light blue) signifies the volume of shares exchanged last week. The purpose of the Weekly Trading bar is to give readers an instant view of trading volumes as they compare on a week-by-week basis. 1
Liquidity Rating: This indicates the level of demand for a company’s shares based on the number of deals rather than volume done over the past week. Stocks are graded according 5 categories. Blue spheres are used to represent liquidity. • Category 5: This is the highest liquidity rating shown by 5 blue spheres. Stocks that have traded more than 20 deals per day on at least 4 days in the past week are awarded this score • Category 4: This is shown by 4 blue spheres. It indicates that the stock has 2
traded between 12 to 19 deals per day on at least 4 days in the past week • Category 3: Shown with 3 spheres, this liquidity classification represents those stocks that have traded 8 to 11 deals per day on at least 4 days in the past week • Category 2: Shown with 2 spheres it identifies those stocks that traded 4 to 7 deals per day on at least 4 days in the past week • Category 1: This is shown by one blue sphere to represent stocks on which 3 deals and/or below were traded per day on at least 4 days in the week.
MARKET DATA
VM | Monday, February 16, 2015 | Issue 029
VM5
MARKET SNAPSHOT 3-MONTH PRICE TREND OF BELLWETHER STOCKS
ACCESS
5.32 0.68
4.50 YtD
10.18 -0.97 -15.42%
3M
-2.68 -33.50%
Dec
1W
Jan
CONTINSURE YtD
-0.17 -17.53%
3M
-0.13 -13.98%
1W
Jan
FCMB -0.50 -20.00%
3M
-1.41 -41.35%
Dec
16.69 -8.18 -32.49%
3M
1W
Dec
3M
Dec
1W
3M
Dec
19.00 -2.18 -8.05%
3M
F
Dec
-51.29 -31.03%
1W
0.67 2.77%
3M
-46.00 -28.75%
3M
1W
F
1W
09/02
Dec
Jan
OKOMUOIL 4.29 17.16%
3M
F
1.39 4.98%
3M
Dec
1W
Jan
UNILEVER
F
3M
-2.50 -41.67%
Dec
F
34.01 1.49
FLOURMILL -9.74 -24.89%
3M
Dec
3M
Dec
1W
-1.49 -4.20%
F
6.17 1.38 3M
-2.13 -25.66%
Dec
Jan
PRESCO
-1.38 -18.28%
F
29.80 0.65 3M
3.29 12.41%
Dec
1W
Jan
UACN
-0.65 -2.13%
F
67.85 3M
-11.42 -24.83%
Dec
Jan
WAPCO
1W
-6.32 -15.45%
F
79.00 9.80 3M
-1.75 -2.17%
-1.08 -6.27%
1W
1W
Dec
Jan
FO YtD
3M
9.11 4.49%
Dec
1W
Jan
INTBREW YtD
3M
-10.56 -36.41%
Dec
1W
Jan
3M
-30.00 -18.75%
Dec
1W
Jan
3M
Dec
1W
Jan
3M
-0.16 -1.39%
Dec
1W
Jan
ZENITHBANK YtD
13/02 F
11.35 0.00 0.00 0.00%
13/02
M T W T
F
15.62 0.66
14.54 -9.80 -11.04%
F
-1.36 -4.97%
M T W T
09/02
Nov
25.80 -2.38 -13.22%
6.37 0.63
-2.33 -26.78%
-3.51 -35.53%
3M
Dec
Jan
-6.41 -13.52%
41.00 0.79 -9.00 -18.00%
3M
09/02
Jan
13/02
M T W T
F
09/02
Nov
Dec
Jan
13/02
M T W T
F
09/02
Nov
Dec
Jan
3M
-4.98 -24.17%
13/02
M T W T
F
Dec
Jan
Dec
13/02
M T W T
JBERGER -15.45 -26.81%
42.18 0.47 -21.66 -33.93%
3M
-0.47 -1.10%
1W
09/02
Nov
Dec
Jan
NESTLE YtD
13/02
M T W T
F
751.00 64.25 1200.00
-244.60 -24.57%
-151.49 -16.79%
3M
-64.25 -7.88%
1W
09/02
Nov
Dec
Jan
SEPLAT
13/02
M T W T
F
368.00 34.10
252.93 YtD
F
76.45
735.00 16.50 4.69%
-90.96 -19.82%
3M
34.10 10.21%
1W
09/02
Nov
Dec
Jan
13/02
M T W T
F
1. 52-week low price 2. Year low price 3. Current price 4. Year high price 5. 52-week high price 6. Current price 7. 5-day price change 8. 1-year price change 9. 3-months price change 10. 1-week price change 11. Daily price movement over 3 months. 12. 30-day moving average 13. Daily price movement over last week
1 2 TICKER
4
3
19.23
1W
09/02
Nov
0.79 1.96%
1W
09/02
Nov
YtD
F
72.45
-0.66 -4.05%
1YtD
25.23 0.01
5
27.406 0.23 0.92%
3M
2.90 12.99%
Jan
13/02
M T W T
F
7 0.01 0.04%
1W
9
11
Dec
13/02
M T W T
GLAXOSMITH
8
Nov
-0.63 -9.00%
1W
09/02
Nov
YtD
F
16.52
13/02
21.31 1.78 18.60%
FBNH YtD
13/02
M T W T
LEGEND
UAC-PROP YtD
-11.81 -8.33%
26.00 1.36 4.80 22.64%
Jan
746.25
M T W T
09/02
Nov
F
41.06 2.25 9.47%
Dec
13/02
M T W T
189.00
PZ YtD
-2.11 -10.27%
130.00 11.81 -33.00 -20.25%
09/02
Nov
40.52
09/02
Nov
F
0.12 1.26%
1W
13/02
18.44 2.11
NB YtD
2.10 1.00%
32.20 -3.77 -16.97%
-1.37 -12.47%
3M
38.22
M T W T
09/02
Nov
F
259.94 -15.00 -6.61%
-0.26 -2.63%
13/02
212.10 2.10
09/02
Nov
-0.46 -2.77%
M T W T
13/02
M T W T
136.73 -2.00 -2.47%
3M
8.09
09/02
Nov
-2.05 -11.26%
YtD
6.37
09/02
Nov
F
16.15 0.46
13/02
M T W T
34.58 6.32 0.58 1.71%
YtD
9.62 0.12 15.98
13/02
20.28
16.60
09/02
Nov
ETI
-0.18 -0.49%
M T W T
13/02
M T W T
46.30 4.08 15.86%
Jan
128.27
1W
1W
13/02
M T W T
09/02
Nov
YtD
-0.07 -2.28%
13.50 -0.10 -1.59%
Dec
CCNN 8.00
09/02
Nov
17.52
Jan
NASCON
YtD
F
3.00 0.07 -0.43 -12.54%
0.42 1.15%
13/02
M T W T
09/02
Nov
YtD
-4.80 -14.04%
4.50 -0.30 -9.09%
3M
81.21
1W
Jan
HONYFLOUR
YtD
F
29.40 4.80 -20.61 -41.21%
-0.48 -1.29%
13/02
M T W T
09/02
Nov
YtD
-0.45 -11.39%
78.18
66.50
1W
1W
Jan
13/02
M T W T
1.21 3.69%
3M
YtD
12.40
09/02
Nov
YtD
F
3.50 0.45
26.00 -11.98 -8.41%
55.00 -3.58 -9.52%
-1.95 -35.78%
36.82 -0.18 49.00
13/02
7.05
13/02
195.50 -35.58 -21.43%
YtD
1.76 4.60%
M T W T
13/02
M T W T
09/02
YtD
-4.60 -2.92%
130.43 11.98
-18.58 -12.47%
DIAMONDBNK
20.88
1W
Jan
27.00 -0.42 -12.28%
F
29.29 1.39
09/02
Dec
Jan
5.68
M T W T
2.32 8.60%
1W
13/02
42.98
Nov
Nov
-14.89 -11.55%
M T W T
-9.99 -6.13%
Dec
CAP 33.01
09/02
Nov
2.87
182.00
Nov
YtD
F
153.00 4.60
-2.27 -1.46%
-3.00 -6.98%
13/02
114.01 14.89
Jan
MOBIL
YtD
-0.02 -1.57%
M T W T
13/02
M T W T
1W
1W
Jan
Dec
130.43
-1.70 -36.17%
-0.45 -26.47%
3M
26.60
09/02
Nov
YtD
F
214.99
35.00
3.00 0.42 3M
3M
-2.00 -4.76%
13/02
1.25 0.02
09/02
Nov
YtD
-17.90 -11.20%
M T W T
13/02
8.26 -1.32 -30.56%
-0.35 -21.88%
YtD
3.47
2.40
TOTAL
Jan
2.90
FIDELITYBK
24.90 0.67 -2.70 -9.78%
UBA YtD
F
-1.69 -11.32%
M T W T
09/02
Dec
Jan
23.20
1W
Jan
STANBIC
Dec
13/02
13.24 1.69
09/02
Nov
F
-0.13 -4.41%
M T W T
-7.66 -36.65%
1W
13/02
36.89 -4.26 -24.34%
-45.21 -24.16%
112.54
Jan
13.18
YtD
-4.00 -19.05%
M T W T
-0.18 -6.00%
OANDO
3M
09/02
Nov
YtD
F
250.02 -48.10 -25.32%
40.00 1.76 86.50
13/02
141.90 17.90
GUINNESS
09/02
Nov
Nov
F
3.79 -0.29 -9.32%
YtD
-2.87 -14.18%
M T W T
13/02
2.82 0.13
1.96
DANGCEM
114.00
1W
1W
Jan
17.00 4.00
Jan
MANSARD
Dec
CADBURY 33.10
09/02
Nov
31.80
09/02
Nov
YtD
F
-0.09 -4.31%
M T W T
-7.00 -29.17%
-8.01 -31.56%
1.15
Jan
GUARANTY
3M
13/02
M T W T
09/02
YtD
-0.07 -8.05%
4.64
Nov
YtD
F
2.00 0.09
1.94
-3.44 -16.53%
139.10
09/02
Dec
YtD
34.60
13/02
M T W T
1.24
Nov
YtD
-0.68 -11.33%
0.80 0.07
0.80
17.37 2.87
13.87
09/02
Nov
ASHAKACEM
10 13
12 May
21/07
June
July
25/07
M T W T
F