SETTING UP BUSINESS IN KENYA
Branch Office The following documents would be required & must be translated into English and certified by an Advocate or Notary Public in the country of origin:
• Memorandum and Articles of Association of the Foreign Company (Original + Certified Copy required);
• Certificate of Incorporation (Original + Certified Copy required);
• List and Particulars of Directors and Company Secretary;
• List and addresses of potential other people authorized to accept service and conduct business;
• Notice of Location of Registered Office and proof of at least one Local Representative
• A Statement of all existing charges entered into the company affecting properties in Kenya (known as a Prescribed Fee) if required;
• Declaration of beneficial ownership
For an individual investor:
• Passport (original)
• Passport Photo of the Investor (recent, coloured passport size photo) For an authorized representative
• Passport (original)
• Passport Photo of the Investor (recent, coloured passport size photo)
Costs:
• The Registration Fee is Kshs. 7,550/=
I) Business Name Search
Continue on page 3...
You will need to perform a Business Name Search to find out whether the business name is available to be registered. This process takes 1-3 days to be completed. It will cost you Ksh. 250 per name.
II) Business Name Registration Form (BN/2)
Once Business Name has been approved, you will need to prepare the following information to fill out the form;
Suitable for foreign companies looking for a presence in Kenya to initiate business or maintain contacts with business partners, especially in cases of uncertain success.
Sole Proprietorship
Continuation of page 2
• Nature of Business – One needs to come up with one specific nature of business, e.g., Tours & Travel, Computer Repairs, Mobile Phone & Accessories Shop, etc. General words such as “shop” or “retail”, trade” are not sufficient for the Company Registry to proceed to register your business. You will need to avoid things like “General Supplies,” which are popularly used but will not be approved.
• Date of Commencement – One needs to write down the date on which you started your business using that name. If you haven’t yet started, then you will need to indicate when you will begin using that Business name to trade. Make sure that the date is not too far in the future; this could affect your application, and you might be told to apply at a later date.
• Address of the principal place of business (Plot No./Land Office Reference Number, Section, and Name of Street or Road, Name of Building) – For the plot number, please find the electricity bill or water bill of your business premises. If you don’t have business premises, you can use your home residential plot number/land reference number for registration, that’s if you are starting your business from home, but you will need to update the records at the Company Registry once you have a Business Premises.
• Postal Address – If you don’t have one, you can register your very own postal office box for Ksh. 2,500 at the nearest Postal Office. Note that the payment is made via the e-citizen.
• Address of any other place of business (Branch Office under the above name) – Only applicable to businesses that are currently operating a business in other counties or have other branches under the same business name.
• Full Names of you and any other partners – Any person who has changed his name must give all former names unless the change occurred before he attained the age of two years. For a sole proprietor business, it only requires 1 person. For Partnership Business, it only requires a minimum of 2 people and a maximum of 20 people.
• Nationality – You will be required to enter your nationality as indicated on your identification, e.g., Kenyan, German, British, American, Chinese, South African, etc.
• Age – Make sure you give your correct age.
• Gender – Male (M) or Female (F).
• Usual place of residence – Where you currently reside, e.g., Nairobi, Nakuru, Kisumu, London, Paris, etc.
• Other business occupation – You will need to enter your occupation, e.g., engineer, farmer, hair stylist, web designer, etc. If you don’t have one, you can write either “Businessman” or “Businesswoman”.
III)
All you will need to do now is submit the documents to eCitizen. The registration is normally completed within 7 days.
Cost
Registration fees are KShs. 950
• A physical box costs Kshs 2,560
• Most sole proprietors now use M-Post (Virtual Box), which links your postal address to your mobile number.
• The registration period now is 1-2 business days.
Partnerships Limited liability partnership (LLP)
If you want to register an LLP, you should first begin with a name search, which is done online on the eCitizen portal. Afterwards, you are required to fill out an LLP1 form.
A partnership deed that outlines the agreement between the partners of a firm, the terms and conditions of partnership among them should be prepared and signed by both partners. However, although it is a requirement, it is not submitted during registration. The letter of consent of the manager to act as manager of that partnership is also required and submitted.
There is no requirement for a resident director or a company secretary.
Registration
• To register a Limited Liability Partnership (LLP), log into your E-Citizen account, click on the reserved name, and there will be a link prompting you to register the LLP. Click on it, and you will be required to fill in the details on the link. The details include: the name(s) of the partner, ID Number, KRA PIN Number, email address, mobile number, the physical address of the LLP, and the nature of the business. Each of the partners/proprietors will be required to attach a copy of their KRA PINs and a passport photo.
• Once you have filled in all the details, the system will generate a form called Statement of Particulars (LLP1), which you will be required to download and print. Once printed, the form should be signed by each partner and then upload the signed form back onto the system.
• The process is usually done within 1-2 working days.
Cost: Registration fees for LLP is Kshs. 25,000.
This kind of entity is among the best for a person who wants to start a business in Kenya as a foreigner. It can be wholly owned by a foreigner and some argue that a work permit may not be required in its formation.
Limited Liability Company
Continue on page 6...
Registration procedure is the same as registering a sole proprietorship, with a few addendums.
As it stands, there are five common ways for foreigners to set up or own a limited company in Kenya.
I. Register a Foreign Company With a Kenyan Partner as Director
• This is one of the easiest ways for a foreigner to set up a company in Kenya. A foreigner owner who has a Kenyan partner will not be required to provide a KRA PIN and Alien ID which take enormous time and effort to acquire.
• Kenyan partner can be a family member, friend or business partner. Do you already have a Kenyan business partner whom you can start the business together?
• He or she needs that have a copy of ID, a copy of iTax KRA PIN, passport photo, and other details.
II. Register a Foreign Company with Nominee Director
• This option will make it easier for you to register your company conveniently and with ease. This route will provide you with a service where a nominee will act as a director of your company during the registration process to meet the requirements needed to set up a company.
• Please note that to replace a director of your company, it usually costs around Kshs 10,000 - Kshs20,000.
• Duration: up to 1 - 2 weeks
III. Opening a Branch of an Existing Foreign Company
• To open a branch or subsidiary in Kenya of an existing foreign company, you will need to register for a Certificate of Compliance. You must provide a copy of your Certificate of Incorporation of the parent company, a copy of Memorandum and a Company Tax Registration Certificate of the existing foreign company.
• These documents need to be certified as genuine by a Public Notary. You will also be required to provide details of the intended/actual physical location of your business in Kenya.
• A certified copy of the board resolution authorizing the establishment of the branch office and the appointment of the local agent in Kenya to represent you in the application process; who will be able to provide their ID and KRA PIN as well as sign Form 238 on your behalf. You will also need to have an Alien ID, in order to open an eCitizen account as a foreigner.
• Once you register a branch in Kenya, you will require a bank account for business transactions and a KRA Pin for compliance purposes.
• This process may take 2-4 weeks
IV. Register a Foreign Company Fully Owned by Foreign Nationals
• Foreign owners intending to register their company without a Kenyan partner will be required to provide a KRA PIN for the application. In order to acquire this document as a foreigner, they will first have to get an Alien ID, for which they become eligible for after three months of consecutive residency in Kenya.
• Alien ID application can take up to five weeks to be processed. Alternatively, foreign owners who already have $100,000 and above to invest in Kenya, they can apply at (https://www.investkenya.go.ke/) to facilitate obtaining a KRA PIN for the directors that will facilitate the registration of the company while avoiding the need to have an Alien ID.
Under the Companies Act, 2015, foreigners can own 100% of shares in a Private Limited Company (PLC).
Continuation of page 5
V. Acquire an Existing Company Previously Owned by Kenyans
• Through acquisition or merger, foreigners can pay an agreed amount for a target Kenyan business and start the process of changing ownership by adding and removing directors and shareholders.
• This process will be more rigorous if buying a public limited company as opposed to a private company limited by shares.
Resources For Foreign Limited Company
• Alien ID Card – This is a document for foreign nationals which enables them to have an ID recognized by Kenyan government institutions and gives access to services such as KRA PIN and applying for a work permit, opening a business bank account, applying for Company KRA PIN, making tax returns and much more. Required for foreigners residing in Kenya for more than 90 days. Enables access to KRA PIN, work permits, business bank accounts, and government services. Cost: KES 5,000 per year. Application via eFNS portal (https://fns.immigration.go.ke).
• Single Entry Visa – It is meant for any person who is looking to enter Kenya to carry out business activities. Valid for 90 days. The cost: 51 USD. Must be applied for online before travel at https://etakenya.go.ke.
• Work Permit – There are different types or classes of work permits available in Kenya. For business owners who have registered their companies in Kenya and are looking to work in Kenya, they will need to apply for Class G permit which is valid for two (2) years and subject to renewal. Required for business owners who have registered companies in Kenya with minimum investment of USD $100,000. Processing fee: KES 20,000 (non-refundable). Issuance fee: KES 250,000 per year. Permits are renewable annually. Application via eFNS portal.
• KRA PIN – This is the most important document your company must obtain to do any business in Kenya. Kenya Revenue Authority (KRA) PIN can be used to open a business bank account, perform tax returns on rental income, applying for Government tenders, purchase of land, buying and selling a property and many other business transactions.
• The cost to register a foreign company is Ksh 7,550.
• Other additional costs may apply depending on the nature and form of the business.
Public Company
Limited by Shares
Continue on page 8...
1. Choosing a name is a necessary step
• Your business name must be unique.
• The proposed names will be rejected if they are the same or similar to business names already registered in Kenya.
• You can present a maximum of 3 (three) options
You need to fill out form CR14, found on https://ecitizen.go.ke
The Registry will check if it is too similar to names already registered.
• The Registry will check if a name is prohibited for other reasons (such as being offensive)or names that suggest a connection to the government.
• Words must be in full: initials are not accepted as a Company Name.
• The approval for a reserved Company Name lasts for 30 days
• It can be renewed for a further 30 days if necessary.
• Renewal is applied for at the Attorney General’s office.
2. Directors and Shareholders Information
• Submit the identification details of directors and shareholders in full, which include: full names, addresses, and nationality.
• Define their roles and responsibilities within the company structure.
Public Company
Limited by Shares
Continuation of page 7
3. Prepare Memorandum and Articles of Association and a Statement of the Nominal Capital
The Memorandum and Articles of Association lay the foundation for establishing a company. It defines the rules and structure of the business.
The Memorandum of Association gives information regarding the business, including the wish to form a company or the agreement to become a member of the company (i.e., a guarantor for a Company Limited by Guarantee).
Additionally, include specific documents such as tax identification numbers or specific licences, depending on the nature of the business.
The Articles of Association give the specific objectives of the company, i.e., the specific functions which the company intends to carry out, as well as the responsibilities of the Directors, Secretary, etc.
There is a model memorandum available for each specific Company Structure, which makes the process of registering your business easier:
• For a Company Limited by Shares, download Form CR3.
• Form CR2 is a model article for Memorandum of Articles of Association.
• The Statement of Nominal Capital can be downloaded in a separate document.
4. To Register your Company you must disclose the details of the Directors and, if required, the Company Secretary
• Details of the Director(s) running the Company must be disclosed. i.e. The Director(s) personal and contact information is required, including certified copies of Identity Documents.
• Private Companies with a Share Capital of less than Kshs. 5,000,000/= (Five Million Kenya Shillings) are NOT required to have a Company Secretary.
• All Public Companies must have a Company Secretary.
• It requires a minimum of seven shareholders and two directors.
• Where a Company Secretary is required, the personal and contact information must also be disclosed.
Commercial Register
A company is expected to file its resolutions, written memorandum and agreements affecting the Company’s constitution within 14 days of passing of such a resolution. There are penalties ranging from Kshs. 200,000 to Kshs. 15,000,000 for companies that fail to comply. For instance, Section 873 of the Act provides that where a company fails to comply with its lodgment obligations, the Registrar or any member or creditor may give notice to the company requiring it to comply with the obligation and if the company fails to comply within 14 days after service of the notice, the registrar, member or creditor of the company may apply to the court for an order directing the company and any specified officer of the company to comply within a specified time. The court may also order that all costs of or incidental to the application are to be borne by the company or by any officers of it responsible for the default.
Beneficial ownership Kenya introduced section 93A of the Companies Act of 2015 in July 2019, through the Statute Law (Miscellaneous Amendments) Act. This Act provides that companies incorporated or registered in Kenya should keep a register of beneficial owners with the relevant information relating to such owners. Under the Regulations, a beneficial owner is a natural person who directly or indirectly:
• holds at least ten percent (10%) of the issued shares of the company;
• exercises at least ten percent (10%) of the voting rights in the company;
• holds the right to appoint or remove a director of a company; or
• exercises significant influence or control over a company.
Failure by a company to comply with the disclosure requirements is an offence which on conviction attracts a fine not exceeding KES 500,000 payable by the company and each officer of the company in default. Further, if the non-compliance continues, the company and the officers shall be liable an additional fine not exceeding KES 50,000 per day.
Trade Register Notification The Kenya National Chamber of Commerce and Industry (KNCCI) is a membership based trade support institution (TSI) working to protect commercial and industrial interests of Kenyan business community. KNCCI advocates for the creation of a favorable commercial, trade and investment environment that supports enterprise expansion. The membership of KNCCI constitutes small, micro enterprises (MSEs), medium and large enterprises.
Joining is optional not a mandatory requirement.
Bank Account Theoretically banks can offer financial products to non-residents, although each bank decides for itself which accounts it makes available and the conditions attached to them. This means that in some cases the restrictions placed on opening accounts might make it hard to do so in practice if you’re not a resident.
• Passport or another proof of ID such as a national identity card and a copy of this document
• Proof of your home address
• Passport size photograph - occasionally more than one is needed
• Application from
• Reference from an employer or an intermediary who already holds an account with the bank and will act as your ‘introducer
• KRA PIN to prove you’re registered to pay tax
Transfer of Goods and Machinery
Personnel arriving for a new contract into the country are exempted from paying taxes on their personal effects/household goods and one motor vehicle under part A paragraph 4 of the 5th Schedule of the East Africa Community Customs Management Act 2004 , provided that the contract is for a term not less than two years.
Used household goods and personal effects are duty exempt provided goods have been owned and used by the client for a minimum of one year and goods are imported within three months of the Work Permit being issued.
Duties and Taxes Payable:
Taxes are payable depending on the value of the imported item(s) and the duty rate applicable outlined under different legal documents as given below.
• Import Duties
Depending with the item to be imported, the Import tax rates vary between 0%, 10% and 25% as provided by the East Africa Community Common External Tariff (CET). However, Sensitive items Attract duty higher than 25%. The sensitive items are listed in the schedule 2 of the EAC Common External tariff.
• Excise Duties
Excise Duty depends on whether the imported item is excisable or not. The Excise duty rates are prescribed under the Excise Duty Act 2015, Tax Laws (Amendment) Act 2025.
Excise duty extended to excisable services provided by non-residents through digital platforms (e.g., streaming, online services).
The Tax Laws (Amendment ) Act 2024, has adjusted the excise duty rates of goods and services with effect from 27th December 2024. The Act digital platform that would be paid to KRA by the non-residents.
Value Added Tax (VAT)
The normal rate of VAT is 16%. However, the Items exempted from VAT as provided by the VAT Act of 2013 attract a rate of 0%.
The Amended Tax Laws have introduced the following changes: The Act stipulates that the time of supply for exports is now recognized after receipt of the certificate of export or customs document, not at dispatch.
• Input VAT relief applications: Must be filed within 6 months of the effective date of the amended Act.
• Administrative/Procedural Updates
• The Tax Procedures (Amendment) Act, 2024, introduced stricter timelines and penalties for late filings.
• Kenya Revenue Authority (KRA) is empowered to enforce compliance more aggressively, especially for digital services.
Import
An import declaration fees of 2.5% and Railway development Levy of 1.5% are levied on value of imports as provided by the miscellaneous Fees and Levies Act of 2016, has introduced excise duty on excisable services provided by non-residents offering excisable services.
Transfer of Capital Foreign entities are free to transfer funds into Kenya and to remit sales and investment proceeds from Kenya.
Capital Gains Tax (CGT) was re-introduced with effect from 1st January 2015. The tax rate is 5% of the net gain on the transfer of property. There are exemptions on certain classes of shares and on specific transfers of property. CGT is a final tax and cannot be offset against other income taxes.
The CBK Regulations permits any person leaving or entering Kenya may take out or bring into Kenya currency up to a maximum of five hundred thousand (500,000) shillings, or the equivalent of five thousand United States dollars (US$5,000), in foreign currency.
The gains referred to in the tax are any incremental differences in the conversion into local currency.
Visa and Residency Permit
Work/Residence Permits are issued to any Non-Kenyan wishing to engage in employment in Kenya whether in gainful employment or voluntary service.
The Work/Residence Permits issued by the Department are classified from A to M inclusive.
They are issued under Kenya Citizenship and Immigration Act 2011 of Laws of Kenya. There are different classes, further information can be found on https://immigration.go.ke/
General Requirements are:
• Duly filled and signed application Form 3.
• Covering letter from employer/self/organization depending on the class (as applicable)
• Copies of the National Passport.
• Two coloured Passport size photographs.
NOTE:
• Application fees are only payable upon receipt of an approval notification.
• Duly completed Entry Permit applications should be submitted at immigration Aliens counter 9 located at Nyayo House Ground floor (south wing) for acknowledgement.
• Applications for renewal of entry permits should be done three months prior to expiry date.
• These permits are normally issued for period of two years.
Work Permit Work/Residence Permits are mandatory and are issued to any Non-Kenyan wishing to engage in employment in Kenya whether in gainful employment or voluntary service.
Labour Laws Paid absences required by law
In addition to public holidays, an employee is entitled to fully paid sick leave of up to 7 days followed by up to 7 days on half pay in each period of 12 months and fully paid holiday or vacation leave of not less than 21 days in each period of 12 months. Female employees are entitled to fully paid maternity leave of 3 months in addition to their annual leave, whilst males are entitled to 2 weeks paternity leave.
Standard working hours
The statutory number of days of work in a week is six (6) days with a minimum rest period entitlement of one (1) day. An employer shall regulate the working hours of each employee in accordance with the provisions of Employment Act and any other written law.
Severance pay
If employment of an employee is terminated on account of redundancy, the employee is entitled to severance pay at the rate of 15 days for each year served plus one month’s notice or pay in lieu of notice plus any accrued leave or leave pay which is due to the employee.
Health, welfare and life insurance schemes
Under the Employment Act, an employer is under an obligation to provide medical treatment to an employee taken ill or make full reimbursement of the costs incurred. As a result, many employers participate in medical insurance schemes for their employees.
Participation in this fund is mandatory and is intended to provide a state retirement benefit for salaried workers. The employer pays a standard contribution of approximately 12% of the salary. One-half of the contribution is deductible from the employee’s salary, while the other is contributed by the employer to an upper limit of KES 12,960 for employees earning above KES 108,000. This is for the FOURTH year of implementation of the new NSSF rates set to increase progressively for the next 5 years pursuant to the NSSF Act 2013.
The employee contributes a fixed sum, which must be deducted by the employer from the employee’s salary before receipt of the same. The minimum contribution to SHA is 2.75% on gross salary per month. The contributions are used to offset the costs of medical treatment, but only cover a fraction of the actual costs
The Finance Act 2023 introduced deductions made by employees to AHL and SHIF at the rates of 1.5% and 2.75% of their gross income respectively
The amended NSSF Act introduces a tiered contribution system, replacing the previous flat-rate contributions. This means, the contributions are now categories into Tier 1 & Tier 2 depending on employees income. These changes in NSSF are in effect from February 2025.
NHIF has been rolled out and SHA is implemented and fully in service. Salaried employees are required to remit 2.75% of their Gross pay monthly.
Social Systems PPension schemes are generally personal arrangements made by the employees with the employer with specific amounts or percentages contributed by the employee and a corresponding amount to be contributed by the employer to a dedicated pension scheme/organization. Arrangements generally terminate with employment of the employee.
The Act has increased the limit for tax free pension from KES 240,000 per annum to KES 360,000. Tax contributions of up-to 15,000 for post-retirement medical funds are now tax deductible.
The NSSF Act has increased the Lower Limit from KES 7000 to KES 8000 and the upper limit from KES 36000 to KES 72000.
Contributions have thus increased from KES 480 to KES 540 from both the employer and the employee, bringing it to a total of KES 1080 for Tier I and from KES 3,480 from both the employer and the employee to KES 5,940; a total of KES 11,880 for Tier II.
The Act exempts payments made to NSSF from being taxed or any other contribution to a post-retirement benefit scheme as long as the individuals have attained the retirement age outlined in their respective postpension benefit scheme, those who have withdrawn due to extenuating circumstances such as ill-health, and those who have withdrawn from their pension schemes having been members for 20 years.
Housing Levy On 19th March 2024, the Kenyan president signed into bill the AHL (Affordable Housing Levy) following a series of court proceedings which had rendered it unconstitutional.
Taxpayers are expected to remit 1.5% of their gross salary or gross income for non-salaried employees before the 9th of the next month.
There are multiple pension providers in Kenya and a company may take upon itself a policy of remitting pension contributions.
For more information: https://www.rba.go.ke/the-tax-lawsamendment-act-2024-a-detailed-analysisof-the-amendments-benefiting-theretirement-benefits-sector/
The new NSSF rates pursuant to NSSF Act 2013.
These changes are set to take effect as from February 2026 in compliance with the fourth-phase of the NSSF Act 2013 which states that the pension scheme rates will increase after every 5 years.
Corporate Income tax
• Non-resident companies (branch) 30%*
• Resident companies (and subsidiaries) 30%
• 3% of gross turnover from businesses whose turnover is more than Kshs. 1,000,000 and does not exceed or is not expected to exceed Kshs 25,000,000 in any given year.
• Branches of foreign entities pay tax at the rate of 30%
• The Finance Act 2023 introduced an income tax on the repatriated income for branches of foreign companies and PEs at a rate of 15%.
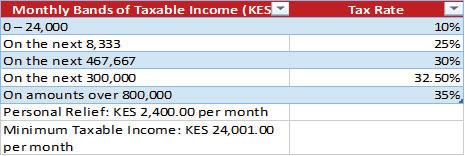
PAYE The Act abolished relief funds for AHL and retirement pension schemes.
Capital Gains Tax The CGT rate is 15%. For individuals, the tax is imposed on the transfer of land and shares. For companies, the tax is applicable to the transfer of money, goods, choses in action, land and every description of property, whether movable or immovable; or property acquired or held for investment purposes other than a motor vehicle
VAT
• The Finance Act 2023 made amendments to VAT as follows.
• The VAT rates applicable are 16%,zero rated and exempt;
• Liquefied petroleum gas, supply of locally manufactured mobile phones, electric vehicles and motorcycles are some of the zero-rated products.
• Some services such as Health care, education and insurance are exempt from VAT.
Digital service tax (DST) – SEP( Significant Economic Presence) Tax
• The Act replaced DST with SEPT which applies to non-residents whose incomes comes from providing services through a digital platform and whose services benefit Kenyan citizens.
• The government assumes that 10% of the gross turnover is the profit made and therefore taxes 30% of that profit as SEPT.
• SEPT is filed on a monthly basis on or before the 20th of the following month.
The finance act 2023 made a provision to reduce the branch corporation rates as well as TOT caps.
A Minimum Top-Up Tax (MTT) of 15% has been introduced in Kenya to ensure multinational companies (MNCs) pay a fair share of taxes on their profits. This tax is in line with the (OECD) Pillar Two framework, which requires an effective tax rate of at least 15% on profits made by MNCs. The MTT applies to MNCs with a consolidated annual revenue of at least EUR 750 million over the past four years, and the tax is calculated based on 10% of their gross turnover.
Tax Losses The Finance Act, 2025 reintroduced a five-year limit on carrying forward tax losses under the Income Tax Act (Cap 470), effective July 1, 2025. This replaced the indefinite carry-forward regime that had been in place since 2021.
eTIMS
• KRA on 11th of January 2024 released new Regulations for the Electronic Tax Invoice Management (eTIMS) enrollment.
• KRA requires that everyone, including the informal sector, that caries out business operations in Kenya and even NGOs onboard for eTIMS.
• Once on boarded, businesses will be required to capture any manually generated invoices and receipts issued from Jan. 1, 2024 retroactively in the system
• The KRA emphasizes that as of January 1, 2024, any business expenses not supported by a valid electronic tax invoice will not be tax deductible.
• Valid transactions such as employee emoluments, imports, interest, airline passenger ticketing, investment allowances including internal accounting adjustments, fees charged by financial institutions, and services provided by a foreigner without a permanent establishment in Kenya or those exempted by KRA are exempt from eTIMS regulations.
Legal provisions:
• VAT Act 2013 – Section 43(4)
• Tax procedures Act 2015 – Section 75
• The VAT (Electronic Tax Invoice) Regulations, 2020
Excise Duty Mobile to Bank transactions and vice versa have been re-introduced with an additional tax of 15% excise duty. The Excise duty has been removed in the wake of COVID 19 to encourage cashless transaction.
Fringe and employment benefits
tax
Generally, non-cash benefits are taxable on the cost incurred by the employer or the fair market value (depending on which is higher). The taxable value is added to the emoluments for tax purposes. Tax exemption will be granted on:
• Non-cash employment benefits which have increased from KES 3,000 to KES 5,000 per month.
• Employee meal benefits provided by a cafeteria or canteen run by the employer or a third-party who is a registered tax payer which have been increased from KES 4,000 to KES 5,000 per month
Motor Vehicles The benefit is the higher of 2% per month of the initial cost of the vehicle or the prescribed rates. For leased vehicles the benefit is the cost of leasing.
Housing For non-executive directors the benefit is the higher of 15% of total income (emoluments – for a whole time service director), market value and rent paid. For agricultural employees, it is 10% of emoluments and for other employees it is the higher of rent paid and 15% of emoluments.
Loans to employees These are taxed at the corporate tax rate on the difference between the interest rate prescribed by the Commissioner and the actual rate paid by the employee.
The Act has increased the deductible interest payments for loans borrowed from certain accredited institutions from KES 300,000 p.a. to KES 360,000
Other benefits Other taxable benefits include:
Furniture – 1% of cost per month and
Telephone – 30% of cost per month.
Employee share ownership plans (ESOPs) Is the difference between the market price of shares and offer price at date option is granted.
Other taxes: Land rates Land rates are based on a percentage of the site value.
Single business permit Depending on the nature of business undertaken, this permit costs between KES 2,000 and KES 100,000
Dividends Dividends are taxed on a withholding tax basis which is a final tax.
Expenses are therefore not allowable on the dividends’ income or on any other income of the taxable person.
Dividends are tax-exempt for resident companies controlling more than 12.5% of shareholding. Dividends received by financial institutions are exempt.
Compensating tax May arise if non-taxed income is distributed, e.g. capital gain or profits on capital allowances. It is worked out through an annual dividends tax account which traces the movement of dividends received or paid and taxes paid.
Interest deductions/ payments
The Act has introduced a provision that prohibits a deduction of interest paid/ payable to related non-resident and third parties in excess of 30% of earnings before interest, taxes, depreciation and amortization (EBITDA). Any amount above 30% of EBITDA shall be disallowed.
Previously, the thin capitalization restriction was based on a debt-to-equity ratio of 3 to 1
Withholding tax
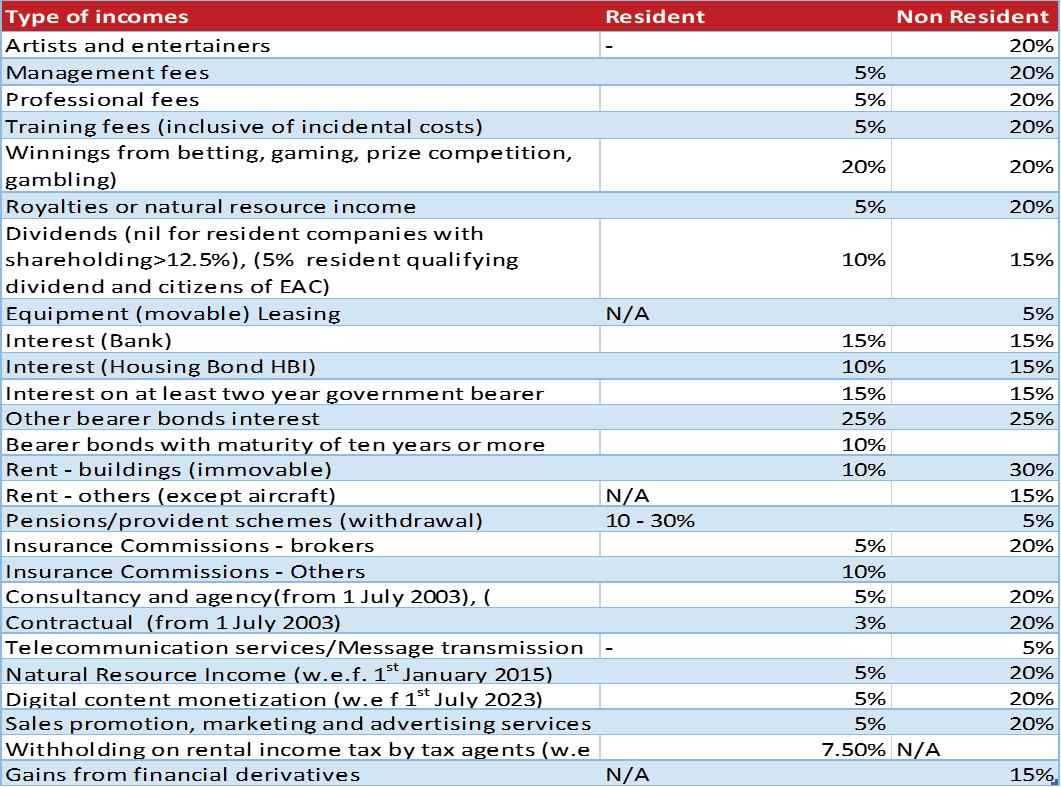
Withholding tax for Multinationals 15%
Gains from financial derivatives Gain from financial derivatives (other than those traded on the Nairobi Securities Exchange) are subject to withholding tax of 15%.
Financial derivative is a financial instrument, the value of which is linked to the value of another instrument underlying the transaction which is to be settled at a future date.
The Finance Act 2023 introduced he new schedule of the withholding tax rates.
Country by Country Reporting(CBC)
A threshold for CbC reporting with effect from 1 January 2023. For companies with gross revenues of KES. 95 billion or more, including extraordinary and investment income. Parent entity or a constituent of a MNE group that is tax resident in Kenya, and that has a gross turnover of over KES. 95 billion, is be required to file a CbC report of its financial and economic activities in Kenya as well as other jurisdictions in which the MNE has a taxable presence. The report must contain all information of the group’s revenue, profit or losses before tax, income tax paid, income tax accrued, accumulated earnings, number of employees, tangible and intangible assets, cash and cash equivalents and any other information as requested by the Kenya Revenue Authority.
This guide has been prepared by JM ASSOCIATES, an independent member of Antea
JM ASSOCIATES
8th Floor, West Park Towers Mpesi Lane Off, Muthithi Road, 23598-00625, Nairobi, Kenya.
Phone: +254 733 818 835 mwangi@jmassociates.co.ke www.jmassociates.co.ke
Mallorca, 260 àtic
08008 – Barcelona
Tel.: + 34 93 215 59 89
Fax: + 34 93 487 28 76
Email: info@antea-int.com www.antea-int.com
SETTING UP BUSINESS IN KENYA
This publication is intended as general guide only. Accordingly, we recommend that readers seek appropriate professional advice regarding any particular problems that they encounter. This information should not be relied on as a substitute for such an advice. While all reasonable attempts have been made to ensure that the information contained herein is accurate, not Antea Alliance of Independent Firms neither its members accepts no responsibility for any errors or omission it may contain whether caused by negligence or otherwise, or forany losses, however caused, sustained by any person that relies upon it.
© 2026 ANTEA