Market Research · Investor Briefing Volume 01 · Deep Learning Software
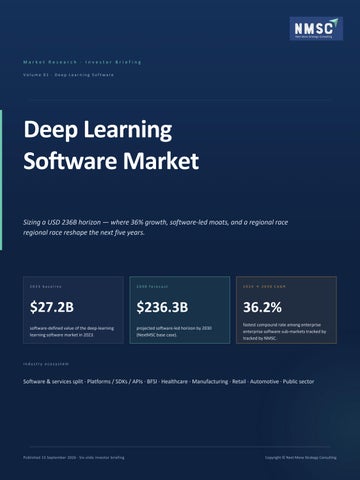
Deep Learning Software Market Sizing a USD 236B horizon — where 36% growth, software-led moats, and a regional race regional race reshape the next five years.
2023 baseline
2030 forecast
2024 → 2030 CAGR
$27.2B
$236.3B
36.2%
software-defined value of the deep-learning learning software market in 2023.
projected software-led horizon by 2030 (NextMSC base case).
fastest compound rate among enterprise enterprise software sub-markets tracked by tracked by NMSC.
Industry ecosystem
Software & services split · Platforms / SDKs / APIs · BFSI · Healthcare · Manufacturing · Retail · Automotive · Public sector
Published 15 September 2026 · Six-slide investor briefing
Copyright © Next Move Strategy Consulting
02 / 06 · Market sizing & triangular view
A software-led curve, with USD 236B & 36% CAGR at the centre. Three independent research views converge inside one band — narrower software scope vs. scope vs. broader deep-learning totals disagree by definition, not by measurement.
Deep learning market
Forecast comparison · Annual grain
Regional anchor · 2024
DL software focus (NMSC)
Five anchor points · value in USD billion
North America leads leads
526.7
North America
≈ 34%
Europe
≈ 22%
Asia Pacific
≈ 23%
Rest of World
≈ 21%
132.3
96.8 236.3 64.9
27.2
2023
2024
2025
2026
2030
'30 SW
Caveat · region splits vary by source (Grand View reports ≈ 33.6% NA in
Two scopes share the same x-axis. Bars are USD billion, not adjusted for currency or methodology. Source values follow in values follow in the footer.
2024).
Three things investors should remember
01
02
03
Software is now the dominant component
Two scopes, one curve shaped differently
North America still earns the rent
Software segments account for ~47% of the
Narrow software scope (NMSC, 36.2% CAGR)
deep-learning stack in 2024, originating from
and broader deep-learning scope (Grand
Grand View; remaining 53% splits services,
View, 31.8% CAGR) disagree by definition —
hardware and platforms.
not by defect in measurement.
NA leads with ≈ 34% share, but Asia-Pacific is the fastest-rising region (smartphone, robotics, IoT, ML convergence) through 2030.
Source: NextMSC (Deep Learning Software Market, 2024) · Grand View Research (2025 update) · Mordor Intelligence (2026). Region splits illustrative; check the full illustrative; check the full report for licensed figures.
Copyright © Next Move Strategy Consulting
03 / 06 · Growth drivers & high-growth pockets
Five structural drivers, shaped by verticals & regions. The 36% CAGR is decomposable. Each row below contributes one structural reason the curve the curve bends the way it does.
Verticals gaining adoption
D-01
Generative-AI production conversion Pilots across healthcare, manufacturing, and finance are exiting sandbox — computing-power and data-
Automotive ADAS to autonomy, after-sales analytics — analytics — leads the segment today.
center capacity are the catalysts the cited report pinpoints.
Retail & e-commerce D-02
Cloud, IoT & smart-device convergence Increasing AI + IoT + smart-device deployment across consumer & industrial surfaces expands data
Personalisation, dynamic pricing, recommendation engines.
Healthcare
expands data volume, model retraining cadence, and inference-software pull-through.
Early detection, risk prediction, hospital ops — significant-growth trajectory.
D-03
Manufacturing
Big-data analytics & image recognition
Predictive maintenance and quality vision vision are the cited pain points.
Image recognition leads application growth (Precedence); big-data analytics is the named inflection inflection vector on Mordor's roadmap — adds compute intensity per workload.
BFSI Risk, fraud, AML, KYC — software-led deflection at scale.
D-04
Falling training cost, rising model output
Regional opportunity
Improving compute power and declining hardware cost unlock downstream software spend — the unit-
Asia Pacific is the fastest-rising region per
spend — the unit-economics tailwind under every beneficiary vertical.
the report — smartphone, robotics, IoT & ML are the named acceleration vectors.
D-05
Europe is data-analytics- and cybersecurity-
Skill-gap & services monetization
led.
Cited "lack of skilled professionals" is a constraint — but a monetization lane for managed-services,
North America retains the lion's share
services, training, and support & maintenance, which are split out in the report.
through the forecast window.
Source: NextMSC Deep Learning Software Market · Precedence Research · Mordor Intelligence · Fortune Business Insights. Drivers paraphrased — full causal chain in the full causal chain in the licensed report. Copyright © Next Move Strategy Consulting
04 / 06 · Competitive scenario
Four tiers of competitors, and where the rent is collected. A representative roster — anchored in nextmsc's reported "key players" list and the 2024-2026 2024-2026 acquisition-record fragments found in adjacent reports. Tier 01 · Compute & foundation
Tier 02 · Platforms & frameworks
Hyperscalers & compute-mojo leaders
Software platforms & dev frameworks
NVIDIA · Microsoft · Google · Amazon Web Services · IBM
Intel · Qualcomm · Samsung · Clarifai · Nuance Communications
Vertically integrated stacks — silicon → cloud → foundation models. Margins live
Communications
here.
SDKs, frameworks, GPU/NPU tooling, and the long tail of vertical SDK distribution.
Tier 03 · Data & MLOps
Tier 04 · Foundation-model labs
Lakehouse, fine-tuning, MLOps
Frontier labs & partnerships
Databricks · Hugging Face ecosystem · Palantir Foundry
OpenAI · Anthropic · Meta AI · selected startups
Cross-cloud data abstraction, fine-tuning and operational stacks — the application-
Revenue acceleration, partnership restructuring, and adjacent-model bets
layer moat play.
reshape the leaderboard year-on-year.
2024 → 2026 strategic moves on record
JUN 2024 · ALLIANCE
JAN 2025 · ALLIANCE
2023 → 2024 · ACQUISITIONS ACQUISITIONS
HPE × NVIDIA co-developed AI Compute
IBM × Red Hat hybrid-AI stack
Codified deep-learning roll-up across stacks
Joint turnkey AI factory offering pairs HPE servers with NVIDIA accelerators — extending the silicon-stack distribution channel into enterprise on-prem.
Deepened the OpenShift-AI and watsonx integration pathway — an explicit enterprise-bid against the hyperscaler stack.
Sony acquired iSIZE (Nov 2023), FairPlay acquired acquired Quater4 (Jan 2024) — application-layer layer consolidation across media & sports analytics. analytics.
Roster and dated moves above are an illustrative cut — NMSC's full key-players list and licensing map appear in the licensed rep ort. licensed report.
Where rent accrues
What to watch
Open question
Compute-tier margins remain the
Tier-1 partnerships, sovereign-AI contracts,
Will foundation-model labs remain vendor-
structural prize; vertical software is
and which application-layer acquisitions clear
agnostic — or be absorbed into the
where differentiation compounds.
antitrust thresholds in 2026-2027.
hyperscaler stack by 2028?
Source: NextMSC key-players list · Fortune Business Insights industry developments (2023-2024) · Grand View Research recent developments.
Copyright © Next Move Strategy Consulting
05 / 06 · Strategic outlook & investment lens
The 2026 → 2030 frame: two calls, two flags. Software-led scope reaches USD 236B by 2030. The investment question is not whether the curve whether the curve bends up — but where the durable moats live along it.
Two calls · where to lean in
01
02
Application-layer software over horizontal copilots
Asia Pacific — fastest-rising regional demand
Vertical-AI applications with proprietary workflow data — healthcare,
Smartphone proliferation, robotics, IoT and machine learning converge
healthcare, BFSI compliance, retail — capture defensibility; raw "copilot
across APAC — the report's named acceleration lane and the highest-
"copilot for all" plays race to the bottom on margin.
CAGR regional read.
Two flags · where to be careful
F1
F2
Algorithm complexity & talent scarcity
Standards, hardware complexity & lock-in
Both NextMSC and Mordor cite complex algorithms and a thin pool of
Mordor cites the absence of unifying standards and the rising complexity
skilled professionals as structural restraints on adoption velocity —
of hardware paired with complex algorithms — concentration risk in
buyer-side execution risk is real.
tooling long-term.
The investor lens
Treat software-led scope as the cleaner read; let the breadth-scoped TAM constrain gross-margin gross-margin expectations; underwrite management against the named two flags.
Source: synthesis across NextMSC, Mordor Intelligence, Grand View Research, Fortune Business Insights. Forward statements are illustrative theses.
Copyright © Next Move Strategy Consulting
06 / 06 · Thank you
Thank you. Connect with us for an in-depth read on the Deep Learning Software Market, or to commission a tailored strategic deep-dive.
Read the complete report →
nextmsc.com/report/deep-learning-software-market
Official Website
Contact Number
nextmsc.com
+1 857 758 5017
info@nextmsc.com
Reports, custom research requests, and
Direct line to senior research consultants
For report purchase, partnership
executive briefings across 30+ verticals.
— briefing, scoping, custom data cuts.
enquiries, or analyst briefings.
Follow NMSC
gen-dedup-9cb8d97fbad94c450f3e644ccd69f008.png
in
f
linkedin.com/company/ next-move-strategyconsulting
facebook.com/ Next-Move-StrategyConsulting-112736100079742
𝕏
◎
YouTube
Twitter / X
youtube.com/channel/ UCJuVRxfBo-Dsog7 BgDE4uPQ
twitter.com/ nextmsc?lang=en
instagram.com/ nextmsc
Headquarters · mailing
Next Move Strategy Consulting — global research & strategy advisory · MarketsandResearch.ai partner network · serving network · serving institutional & enterprise clients.
Six-slide investor briefing · Deep Learning Software Market
Copyright © Next Move Strategy Consulting