GLOBAL MARKET RESEARCH BRIEFING · 2026 –2035
Solid Electrolyte Market From pilot lines to gigafactories: a USD 15.18 billion opportunity powering the solid-state battery era E X E CU T I VE S U MMAR Y
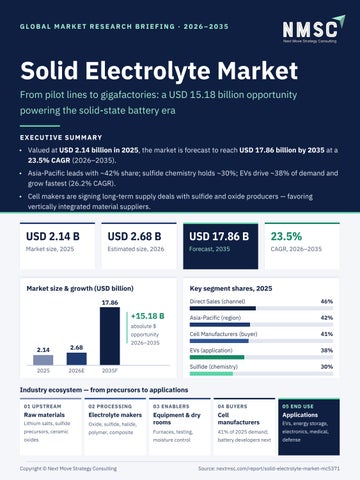
• Valued at USD 2.14 billion in 2025, the market is forecast to reach USD 17.86 billion by 2035 at a 23.5% CAGR (2026–2035). • Asia-Pacific leads with ~42% share; sulfide chemistry holds ~30%; EVs drive ~38% of demand and grow fastest (26.2% CAGR). • Cell makers are signing long-term supply deals with sulfide and oxide producers — favoring vertically integrated material suppliers.
USD 2.14 B
USD 2.68 B
USD 17.86 B
23.5%
Market size, 2025
Estimated size, 2026
Forecast, 2035
CAGR, 2026–2035
Market size & growth (USD billion)
Key segment shares, 2025
17.86
+15.18 B
Direct Sales (channel)
46%
Asia-Pacific (region)
42%
Cell Manufacturers (buyer)
41%
EVs (application)
38%
Sulfide (chemistry)
30%
absolute $ opportunity
2.14
2.68
2025
2026E
2026–2035
2035F
Industry ecosystem — from precursors to applications 01 UPSTREAM
02 PROCESSING
03 ENABLERS
04 BUYERS
05 END USE
Raw materials
Electrolyte makers Oxide, sulfide, halide,
Cell manufacturers
Applications
Lithium salts, sulfide
Equipment & dry rooms
precursors, ceramic
polymer, composite
Furnaces, testing,
41% of 2025 demand;
electronics, medical,
moisture control
battery developers next
defense
oxides
Copyright © Next Move Strategy Consulting
EVs, energy storage,
Source: nextmsc.com/report/solid-electrolyte-market-mc5371
02 · MARKET LANDSCAPE
Market Segmentation Chemistry, application and buyer mix: where today's revenue sits and where 2035 value builds
Key segment insights • Sulfide is set to become the largest chemistry by 2035 (USD 6.07 B), driven by near-liquid ionic conductivity. • Composite (27.8%) and halide (27.4%) are the fastest-growing chemistries. • EVs expand ~10× to USD 8.22 B — nearly half of the 2035 market. • Energy storage systems grow second-fastest among large applications (24.4% CAGR).
Solid electrolyte replaces liquid electrolyte · Image: Britannica
Segment sizing by chemistry (USD billion) CHEMISTRY
2025
2035
CAGR 2026–35
Sulfide
0.64
6.07
25.2%
Oxide
0.71
5.18
21.6%
Polymer
0.47
3.04
20.0%
Halide
0.21
2.32
27.4%
Composite
0.11
1.25
27.8% ▲
TOP BUYER TYPE
Application outlook, 2035 (USD B · CAGR) EVs
8.22 · 26.2%
Energy Storage
3.04 · 24.4%
Consumer Electronics
2.86 · 19.2%
Industrial Battery
1.25 · 20.2%
Aerospace & Defense
0.89 · 20.8%
Research & Prototyping
0.89 · 25.8%
Medical Device
0.71 · 20.0%
2035 SCALE
41% · USD 0.88 B Cell manufacturers, 2025
TOP SALES CHANNEL
46% · USD 0.98 B Direct sales, 2025
TOP PRODUCT FORM
~20% · USD 0.43 B Powder, 2025 (primary feedstock)
Copyright © Next Move Strategy Consulting
Source: nextmsc.com/report/solid-electrolyte-market-mc5371
03 · GROWTH DRIVERS & OPPORTUNITIES
EV Safety Sets the Pace Range and safety mandates, public R&D and supply-chain localization drive a 23.5% CAGR — Asia-Pacific leads
Growth opportunity map — 2035 size (USD B) · CAGR
Europe 3.21
Country hotspots (2035) China · USD 4.79 B 27.1% CAGR — fastest
21.9%
1.25
APAC 8.39
N. Am. 3.93
U.S. · USD 2.94 B · 22.7%
22.4%
Japan · USD 1.34 B · 22.5%
25.0% ▲
Germany · USD 1.08 B · 22.9% 1.08
S. Korea · USD 1.06 B · 23.4%
LATAM · 23.4%
Canada · USD 0.99 B · 22.5%
MEA · 21.7%
UK · USD 0.78 B · 22.9% Bubble size ∝ 2035 market size. Pacific-centred projection. Map: public domain.
Impact on CAGR (percentage points)
High-growth segments (CAGR)
EV range & safety requirements
+5.8
Government battery R&D programs
+3.4
Electronics energy-density demand Critical-minerals localization Aerospace & defense investment
+2.1 +1.6 +1.2
Dry-room manufacturing cost Interfacial resistance, cycle life Limited commercial capacity Lithium & sulfide precursor supply
−2.4 −1.8 −1.3 −0.9
Composite chemistry
27.8%
Thin film form
27.7%
Halide chemistry
27.4%
Sputtering target form
27.0%
Licensed manufacturing
26.4%
EV application
26.2%
Battery developer buyers
25.9%
Whitespace opportunities through 2035 Halide electrolytes
Licensed manufacturing
Thin film deposition
Unlock high-voltage nickel-rich
Localize sulfide & oxide supply in
Miniaturized, leak-proof micro-
cathodes; premium EV cell
Europe and North America without
batteries for implantable medical
partnerships for oxidative stability.
dry-room capex.
devices and wearables.
Copyright © Next Move Strategy Consulting
Source: nextmsc.com/report/solid-electrolyte-market-mc5371
04 · COMPETITIVE SCENARIO
A Pre-Consolidation Race Diversified materials conglomerates and single-chemistry startups compete to lock in cell-maker supply agreements
Competitive positioning matrix SCALING SPECIALISTS
R&D / pilot → Commercial-scale supply
Solid Power
Market structure INTEGRATED LEADERS
20
33
Mitsui Mining & Smelting
companies profiled
countries covered
• Fragmented, pre-consolidation: pilot-stage makers compete with diversified conglomerates.
Idemitsu Kosan QingTao Energy
Ampcera
Ohara (oxide)
NICHE INNOVATORS
Ganfeng Lithium
• Two archetypes: Japanese & Korean materials majors vs. single-chemistry solid-state startups. • Innovation focus: sulfide & oxide conductivity, dry-room scale-up, composite hybrids.
POSCO JK Solid Solution
• Investor lens: favor diversified chemistry portfolios with signed supply agreements.
Mitsubishi Chemical
R&D DIVERSIFIERS
Single-chemistry focus → Diversified materials portfolio Indicative placement derived from NMSC company descriptions; not a share ranking.
Key strategies in play Capacity expansion
Partnerships
Licensing & M&A
• Solid Power: sulfide capacity to 75 t/yr by end-2026
• Solid Power with Samsung SDI and BMW
• M&A activity is partnership- and licensing-driven
• Idemitsu Kosan: expanded sulfide production
• Ganfeng & POSCO JK: joint development for regional manufacturing
• Licensed manufacturing: fastest channel (26.4% CAGR)
• QingTao, Ampcera: expanded facilities
• Long-term cell-maker supply deals
• Targets regional capacity & supply contracts
Mitsui Mining & Smelting
Solid Power
Ganfeng Lithium
Major supply agreement for A-SOLiD electrolyte; customer's all-solid-state program targets 2027–2028.
Dual pilot lines plus a continuous facility to reach 75 t/yr, supplying tier-one battery makers and OEMs.
Ganfeng LiEnergy begins small-scale production of 500 Wh/kg solid-state cells for high-end EVs and aerospace.
Latest developments · May 2026
Copyright © Next Move Strategy Consulting
Source: nextmsc.com/report/solid-electrolyte-market-mc5371
05 · LET'S CONNECT
Thank You Connect with our analysts for in-depth insights, custom segment data and strategic guidance on the solid electrolyte opportunity. Inside the complete report
20
33
Top 10
2025–35
Company profiles
Countries covered
Company market shares
Segment & regional
forecasts
→
Click here for the complete report Contact us WEBSITE
www.nextmsc.com
PHONE
+1 857 758 5017
info@nextmsc.com
Follow us
Copyright © Next Move Strategy Consulting
YouTube
Twitter / X
Source: nextmsc.com/report/solid-electrolyte-market-mc5371