MARKET RESEARCH BRIEFING | GLOBAL | 2025 –2035
Polysulfide Sealant Market Sealing the infrastructure renewal cycle — a USD 220 million absolute dollar dollar opportunity between 2026 and 2035
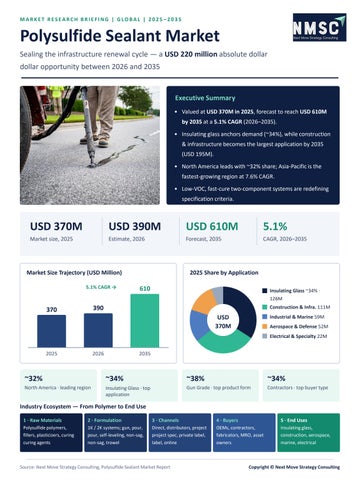
Executive Summary • Valued at USD 370M in 2025, forecast to reach USD 610M by 2035 at a 5.1% CAGR (2026–2035). • Insulating glass anchors demand (~34%), while construction & infrastructure becomes the largest application by 2035 (USD 195M). • North America leads with ~32% share; Asia-Pacific is the fastest-growing region at 7.6% CAGR. • Low-VOC, fast-cure two-component systems are redefining specification criteria.
USD 370M
USD 390M
USD 610M
5.1%
Market size, 2025
Estimate, 2026
Forecast, 2035
CAGR, 2026–2035
Market Size Trajectory (USD Million) 5.1% CAGR →
2025 Share by Application
610
Insulating Glass ~34% · 126M Construction & Infra. 111M
390
370
USD 370M
Industrial & Marine 59M Aerospace & Defense 52M Electrical & Specialty 22M
2025
2026
2035
~32%
~34%
~38%
~34%
North America · leading region
Insulating Glass · top application
Gun Grade · top product form
Contractors · top buyer type
Industry Ecosystem — From Polymer to End Use 1 · Raw Materials
2 · Formulation
3 · Channels
4 · Buyers
5 · End Uses
Polysulfide polymers, fillers, plasticizers, curing
1K / 2K systems; gun, pour, pour, self-leveling, non-sag,
Direct, distributors, project project spec, private label,
OEMs, contractors, fabricators, MRO, asset
Insulating glass, construction, aerospace,
curing agents
non-sag, trowel
label, online
owners
marine, electrical
Source: Next Move Strategy Consulting, Polysulfide Sealant Market Report
Copyright © Next Move Strategy Consulting
02 | GROWTH DRIVERS & HIGH-GROWTH SEGMENTS
Infrastructure Renewal Sets the Growth Growth Floor Key Insights • Water & civil infrastructure renewal is the primary driver, adding +1.3% to CAGR across North America and Europe.
• Energy-code-led insulating glass output adds +1.1%, favouring automationready gun and pour grades. • Maintenance-led buyers grow fastest: Asset Owners 8.1% and MRO Providers 8.0% CAGR. • Silicone / polyurethane substitution (−0.9%) pushes demand into immersionand fuel-resistant niches.
Demand Drivers & Restraints — Impact on CAGR (percentage points) +1.3%
Water & civil infrastructure renewal +1.1%
Insulating glass unit production +0.9%
Aerospace fuel-tank & airframe sealing
+0.8%
Airport runway & pavement joints +0.6%
Marine, oil & gas maintenance
+0.5%
MRO outsourcing by asset owners
−0.9%
Silicone & polyurethane competition
−0.5%
VOC & emission compliance costs
−0.4%
Sulfur raw-material price volatility
High-Growth Segments — Size 2025 → 2035 and CAGR (2026–2035) S eg m ent
C ateg o ry
2025 (US D M )
2035 (US D M )
C AG R
A sset O wners
Buyer typ e
30
64
8.1%
M RO Pro vid ers
Buyer typ e
52
110
8.0%
S elf- Leveling G rad e
Pro d uct fo rm
52
107
7.7%
Electrical & S p ecialty
A p p licatio n
22
43
7.1%
A ero sp ace & D efense
A p p licatio n
52
95
6.3%
C o nstructio n & Infrastructure
A p p licatio n
111
195
5.8%
Low-VOC formulations
Fast-cure 2K systems
IG line automation
Niche repositioning
Green-building specs favour certified systems
Less downtime on runways, bridges, water plants
Robot-ready viscosity & cure profiles
Fuel, chemical & immersion resistance
Source: Next Move Strategy Consulting, Polysulfide Sealant Market Report
Copyright © Next Move Strategy Consulting
03 | REGIONAL & WHITESPACE OPPORTUNITIES
Asia-Pacific Doubles While the West West Holds Share Growth Opportunity Map — 2025 → 2035 (USD Million) and CAGR 2026–2035 Europe · 3.2% 96 → 134
North America · 3.3% 119 → 168 · ~32% share
Asia-Pacific · 7.6% 96 → 195 · fastest
Middle East & Africa · 7.4%
Latin America · 6.4%
CAGR above 5.1% Mature, below 5.1%
26 → 52
33 → 61
Fastest-Growing Countries (CAGR)
Regional Insights
India
13.5%
Saudi Arabia
9.2%
• Asia-Pacific adds ~USD 99M, the largest regional gain, regional gain, as IG manufacturing and infrastructure
infrastructure build-out expand. UAE
7.4%
• India (USD 13M → 43M) is the fastest-growing country Argentina
7.4%
market at 13.5% CAGR.
South Korea
6.7%
Brazil
6.1%
China
5.6%
U.S.
3.1% · largest, 92M
• GCC water and marine diversification lift Saudi Arabia (9.2%) and UAE (7.4%). • North America stays the largest region, anchored by water renewal and aerospace sealing.
Whitespace Opportunities for Suppliers Water infrastructure rehab
Potable-water-certified, immersion-grade grade grades for recurring MRO contracts contracts
Automated IG lines
Space systems sealing
Robot-compatible sealants for long-term term fabricator supply, esp. Asia-Pacific
Extreme-temperature qualified grades for for satellite & launch vehicles
Source: Next Move Strategy Consulting, Polysulfide Sealant Market Report
Copyright © Next Move Strategy Consulting
04 | COMPETITIVE SCENARIO
Qualification Depth Is the Moat in a Consolidated Field Moderately consolidated
20
Top 10
Top profiled players hold the majority of global revenue
Companies profiled
Market share available
Competitive Positioning Matrix Market Positioning SPECIALIZED FORMULATORS
DIVERSIFIED LEADERS
• Players compete on application-specific PPG Industries
qualification, formulation breadth and
Flamemaster
Application qualification depth →
Sika AG
channel depth. • PPG & Sika leverage broad construction-
Pecora
chemical portfolios to serve contractors and
H.B. Fuller
Aerospace & industrial qualification qualification for OEMs / MRO
asset owners globally. Scaled distribution
• Pecora & Flamemaster win on aerospace
and industrial qualification for OEMs and MRO providers.
Other profiled players incl. Master
Pidilite Industries
Bond, Anabond, CICO, Choksey, TKK, NEDEX — detailed positioning
STP Limited
in full report
• Pidilite & STP serve South Asian construction and industrial demand. • Sika differentiates with 2K gun, pour and
South Asian construction & industrial demand
self-leveling lines built for hot and tropical INVESTOR climates.TAKEAWAY
NICHE / EMERGING
REGIONAL SPECIALISTS
Suppliers with project-specification and MRO channel depth are favoured over distributor-only
Portfolio & channel breadth → Archetypes as defined by Next Move Strategy Consulting; qualitative, not to scale
players as infrastructure renewal accelerates.
Key Strategies & Recent Developments PORTFOLIO EXPANSION · MAY 2024
PRICING ACTION · MAR 2026
STRATEGIC PRIORITY
H.B. Fuller expanded engineering adhesives & sealing tech for aerospace, automotive,
H.B. Fuller global price adjustment to manage raw-material cost volatility and and supply continuity
Pair application qualification with low-VOC low-VOC formulation to defend share vs. vs. substitute chemistries
electronics
Leading Companies Profiled PPG Industries
3M Company
Sika AG
H.B. Fuller
Fosroc
MAPEI
Akzo Nobel
Pidilite
Pecora
Euclid Chemical
Bostik Benelux
Soudal
Flamemaster
Master Bond
+ 6 more
Source: Next Move Strategy Consulting, Polysulfide Sealant Market Report
Copyright © Next Move Strategy Consulting
05 | LET'S CONNECT
Thank You Connect with our analysts for in-depth insights, custom segment cuts and strategic guidance on the polysulfide sealant opportunity.
33
20
5
2025–35
Countries covered
Companies profiled
Segmentation axes
Analysis period
Click here for the complete report → nextmsc.com/report/polysulfide-sealant-market-mc5378
Contact Us
Website: https://www.nextmsc.com/ Phone: +1 857 758 5017 Email: info@nextmsc.com
Follow Us gen-dedup-dae309a0981bb10d013075b2b4c5c0a7.png
YouTube
Twitter / X
Custom research, competitive benchmarking and go-to-market advisory for sealants, adhesives and construction chemicals.
Copyright © Next Move Strategy Consulting