RESTATEMENT CHAOS: Strategies for TPAs in the SECURE 2.0 Era JOB HOPPING AND RETIREMENT SAVINGS
CITS FOR 403(B) PLANS: Is This (Finally) the Year?
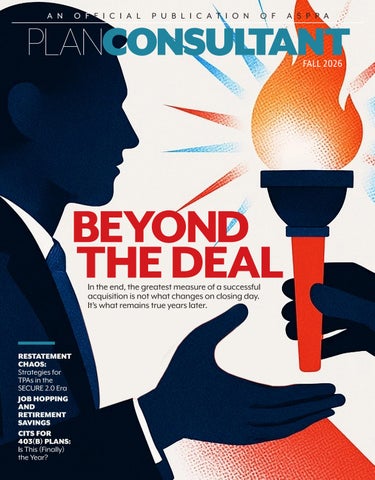
RESTATEMENT CHAOS: Strategies for TPAs in the SECURE 2.0 Era JOB HOPPING AND RETIREMENT SAVINGS
CITS FOR 403(B) PLANS: Is This (Finally) the Year?
In the end, the greatest measure of a successful acquisition is not what changes on closing day. It’s what remains true years later.
Former employee retirement accounts can create ongoing work for the plans and partners who support them.
Addresses change. Checks go uncashed. Participants become hard to reach. Eligible balances may need to move out of the plan.
Inspira Financial helps retirement plan professionals support what comes next, with automatic rollover IRA solutions and related services that help address account transitions, participant communications, search efforts, benefit distributions, and uncashed check resolution.
Because when employment ends, account administration often continues.
Explore retirement rollover solutions
26|A LEGACY WORTH PRESERVING: LESSONS FROM ALL SIDES OF A TPA ACQUISITION
In the end, the greatest measure of a successful acquisition is not what changes on closing day. It’s what remains true years later.
By Dina Hamad
32| THE WHY AND HOW OF ALTERNATIVE INVESTMENTS IN RETIREMENT PLANS
It requires balancing diversification needs with fiduciary and operational considerations.
By Amy Reuter
36| RESTATEMENT CHAOS: STRATEGIES FOR TPAS IN THE SECURE 2.0 ERA
Know the deadlines and meet them, and don’t count on extensions from the IRS or self-correction options.
By Theresa Conti
08|FROM THE PRESIDENT A Year to Remember — And A Future to Celebrate By Shannon Edwards By Shannon Edwards
11|NEWLY AND RECENTLY CREDENTIALED MEMBERS
68|INSIDE ASPPA
From Hours to Seconds: ‘Ask ERISA’ Reinvents ERISA Research By John
Sullivan
70|ASPPA INITIATIVES
Women’s Retirement Security: A Day, and More By Plan Consultant Staff
06|LETTER FROM THE EDITOR From Coverage Gap to Tipping Point By John Sullivan
10|REGULATORY / LEGISLATIVE UPDATE
A New Opportunity for SECURE 3.0 — and the Future of Retirement Savings By Brian H. Graff
12|ACTUARIAL / DB
A Roadmap to the AFTAP: How the Certification Impacts Plan Administration By Kerry Smith
14|ADMINISTRATION The Ownership Change Nobody Told Their 401(k) About By Olivia Schwarts
18|BUSINESS PRACTICES
Job Hopping and Retirement Savings: Help Employees Keep Their Momentum By Shannon Edwards
20|COMPLIANCE
2026 Required Amendments: One of the Busiest Document Years in Recent Memory By Wallace Gibson
24|LEGAL ISSUES
Employer-Billed vs. Participant-Paid: Who Really Pays for the Retirement Plan? By
Chad Johansen
40|RECORDKEEPING
Employer Roth Contributions: A Great Idea or More Than Your Client Bargained For? By Colleen Windham
42|STATE-RUN PLANS
State Coverage: More than Auto IRAs By John Iekel
50|SECURE 2.0
Beyond Compliance: Help Plan Sponsors Turn SECURE 2.0 into a Strategic Advantage By Katie Boyer-Maloy
52| EDUCATION AND CE Why Practical Expertise in Pooled Plans Matters and Why We Built the QP3™ By Kizzy Gaul
54| LEGISLATIVE ISSUES
CITs for 403(b) Plans: Is This (Finally) the Year? John Iekel
62|REGULATION
Beyond CITs: The Broader Impact of the SEC’s New PEP Guidance By Kelsey Mayo
46|MARKETING
Your LinkedIn Profile Is Working Whether You Like It or Not By Joe Apfelbaum
58|TECHNOLOGY
Beyond the Billing Battle: Convergence of the Integrated TPA Technology Ecosystem By Travis P. Jack
66|WORKING WITH PLAN SPONSORS
Where Plan Sponsors and Administrators Meet: The Shared Responsibilities By John Iekel
Virtual • May 12-13, 2027
Joe Apfelbaum is CEO of evyAI, an AI-powered LinkedIn platform with more than 23,000 users in 40 countries, and founder of Ajax Union, an Inc. 500 B2B digital marketing agency. He is the author of High Energy Networking and High Energy Prompting, a professional speaker, and a single father of five.
Katie Boyer-Maloy is Director, TPA Distribution with Retirement & Income Solutions | at Principal Financial Group.
Theresa Conti, QKA, APR, ERPA, CBFA has been involved in the retirement plan industry for more than 35 years, she started her firm Sunwest Pensions in 1998 and sold it to July Business Services in 2023.
Shannon M. Edwards, ERPA, QPA, QKC, QKA, is the President of TriStar Pension Consulting. She is a member of the ASPPA Leadership Council and the Plan Consultant Committee.
Kizzy Gaul is Director of Technical Education with the American Retirement Association.
Wallace Gibson, QKA, QPA, ERPA is Senior Manager of Consulting Services with EPIC Retirement Plan Services.
Dina L. Hamad is VP of Corporate Development & Strategic Relationships at Definiti and was the Founder of Retirement Plan Solutions, Inc. (RPSI). She has more than 30 years of experience in the retirement plan industry, with deep expertise in plan administration, consulting, and business growth strategies.
John Iekel is a writer with the American Society of Pension Professionals and Actuaries (ASPPA).
Travis P. Jack is the Managing Member of Metz & Associates, PLLC and oversees the employee benefit plan audit practice. Jack is a member of the Plan Consultant Committee
Chad Johansen is a Partner and Director of Retirement Plan Sales with Plan Design Consultants, Inc.
Kelsey Mayo is Chief Retirement Policy & Regulatory Affairs Officer with the American Retirement Association.
Amy Reuter is Senior Vice President and Trust Officer at Matrix Trust Company, a Broadridge company, where she develops innovative trust and custody solutions across the retirement ecosystem.
Olivia Schwartz is Vice President/Co-Owner of Peak Retirement Group.
Kerry M. Smith, ASA, EA, MAAA is Founder of Traktion Pension LLC.
Colleen Windham, CPA, CPC, TGPC, CBS, QPA, QKC, QKA, QKS is the Director of Retirement Plan Services at Independent Retirement.
Plan Consultant is Published by
EDITOR IN CHIEF
Brian H. Graff, Esq., APM
PLAN CONSULTANT COMMITTEE
Mary Patch, QKA, CPFA, Co-chair; David J. Witz, Co-chair; Lee Bachu; Gary D. Blachman; Katie Boyer-Maloy; Jason D. Brown; Linda Chadbourne, QKA; Theresa Conti; Megan Crawford; Shannon Edwards, ERPA; John A. Feldt, CPC, QPA; Amy Garman; Emily Halbach; Tiffany Hanks; John Iekel; Travis Jack; Chad Johansen; Olivia Schwartz; Kerry Smith; Rickie Taylor; Colleen Windham; Manny Marques; Heidi Salati
EDITOR
John Sullivan jsullivan@usaretirement.org
SENIOR WRITERS
Ted Godbout, John Iekel
ADVERTISING SALES
Tashawna Rodwell trodwell@usaretirement.org
TECHNICAL REVIEW BOARD
Rose Bethel-Chacko, CPC, QPA, QKA; Marianna Christofil; Michael CohenGreenberg ; Sheri Fitts; Drew Forgrave, MSPA; Grant Halvorsen, CPC, QPA, QKA; Jennifer Lancelot, CPC, QPA, QKA; Robert Richter, APM
COVER Apisit Suwannaka / Shutterstock.com
2026 ASPPA OFFICERS
PRESIDENT
Shannon M. Edwards, ERPA, QPA, QKC, QKA
PRESIDENT-ELECT
Manny Marques, CPC. QPA, QPFC, AIF®
VICE PRESIDENT
Genelle Brakefield, QKA, TGPC
IMMEDIATE PAST PRESIDENT
JJ McKinney IV, CPC, QPA, QKA
Plan Consultant is published quarterly by the American Society of Pension Professionals & Actuaries, 4401 N. Fairfax Dr., Ste 600, Arlington, VA 22203. For subscription information, advertising, and customer service contact ASPPA at the address above or 800.308.6714, customerservice@USAretirement.org. Copyright 2026. All rights reserved. This magazine may not be reproduced in whole or in part without written permission of the publisher. Opinions expressed in signed articles are those of the authors and do not necessarily reflect the official policy of ASPPA.
More states (and cities) are offering a retirement plan to workers without access, fueling momentum to help close the nation’s coverage gap. By John Sullivan
While closing the retirement plan coverage gap is a priority for regulators, legislators, and financial professionals, more states are stepping in to do their part.
Indeed, Kansas Deputy Assistant State Treasurer Tom Treacy recently said that states that do not offer a plan “will be left behind.”
Angela Antonelli would agree, and as a research professor and executive director of the Georgetown University Center for Retirement Initiatives (CRI), she’s keeping a close eye on what’s happening.
“We’re incredibly excited to see the number of states that have adopted these facilitated retirement savings programs,” she said recently. “We’re up to 22 now.”
She also noted that Philadelphia will soon implement an auto IRA, and that when other cities adopt a plan, it encourages programs at the state level. She mentioned Seattle and Washington State, and New York City/State, specifically.
“We hope Philadelphia will be the first city in the nation to move on an auto IRA,” she said. “That’s a great start, and 17 of [the 22 states] are auto IRAs, which have the requirement that employers must take some action, which is either adopt a plan of your own or you allow your workers to be auto-enrolled through the state program. So, that’s exciting.”
Antonelli added that more conservative, “red” states, not inclined
to a mandated plan, are nonetheless interested in voluntary arrangements.
“They do want to have something available to the residents to help them be able to save for retirement,” she explained. “But tied to all of that is the ability to take advantage of things like the federal Saver’s Match that’s coming down the pike. Hopefully, we’ll see more conservative states move in 2027 to adopt a voluntary arrangement, thereby increasing the number of states. We’re excited. The momentum is certainly building.”
By “momentum,” she meant the $3.3 billion in assets and the 1.2 million Americans now saving through state programs.
Calling it the tip of the iceberg, she argued that requiring employers to act (either by adopting a plan of their own or using the state program) is encouraging more to offer their own.
Success at the state level has changed the dynamic about understanding the importance of closing the coverage gap, and she believes that having almost half of them now offering a plan could mean we’re close to a “tipping point.”
“You have several other states that realize when you give workers an easy way to save for retirement, again, it results in $3 billion in assets and 1.2 million savers, and they’re thinking, ‘Hey, let’s give our workers a way to save for retirement.’”
And now the federal government has noticed, with President Trump mentioning coverage in his State of the Union speech, something Antonelli called “significant.”
“With the introduction of Trump accounts, a lot of folks are engaged in discussions about how we continue to shape this federal-state relationship when it comes to retirement savings,” she concluded. “I think there’s a general sentiment that the role of the federal government should be to support what we see with our existing provider/employer-based system, as well as what the states can do to help reach smaller employers and lower-income workers.” PC
John Sullivan Editor-in-Chief
Serving as your president has truly been one of the greatest honors of my professional life.
By Shannon Edwards
This year may have flown by, but the progress we made and the gratitude I feel will stay with me forever.
I knew this year would go by quickly. I just did not realize quite how quickly. It is hard to believe I am already writing my fourth and final letter as ASPPA president. What an incredible year this has been! I have had the opportunity to watch so many exciting ideas become real resources, real conversations, and real opportunities for our members.
One of the things I am most proud of this year was the first Women’s Retirement Security Day on July 14.
The American Retirement Association created this day to shine a light on the very real retirement savings challenges women face. Those challenges are often created over many years. Women may earn less during their careers, step away from the workforce to care for children or aging parents, or spend years working without access to a workplace retirement plan. Women also tend to live longer, which means their retirement savings may need to last longer.
But Women’s Retirement Security Day was about so much more than statistics. It was about starting conversations. It was about making it easier and more comfortable for women to talk about money, ask questions, and learn from one another. So many women were taught that talking about money was rude or something we simply should not do. Unfortunately, when we do not talk about money, we also miss opportunities to learn, plan, and help one another.
The response to the first Women’s Retirement Security Day was amazing. Our members shared resources, created videos, hosted conversations, and filled social media with information. News outlets picked up the story, helping the message reach people well beyond the retirement plan industry.
Erika Goodwin, Madison Oakley, and the entire ARA team did a phenomenal job creating this day, spreading the word, and giving all of us meaningful ways to get involved. July 14 may have been the first official day, but when we arrive at the second annual Women’s Retirement Security Day next July, I can’t wait to look back and see what all we have accomplished.
This was also a big year for the tools ASPPA members use every day.
We introduced a newly redesigned ERISA Outline Book with a completely new format, improved navigation, and much easier search capabilities. These updates make the EOB even more useful and accessible.
We also launched AskERISA, an AI-based research tool built on the ERISA Outline Book. In our industry, a fast answer is not enough. We need an answer we can trust. That is what makes AskERISA so exciting. Its answers come from the trusted content in the EOB. It gives our members the speed and convenience of AI, but with answers they can rely on. I am incredibly proud that ASPPA and the ARA are developing thoughtful, practical tools that help our members.
Of course, we still have one very big celebration ahead of us!
ASPPA Annual will take place October 18–21 at the Grand Hyatt San Antonio, and this year we are celebrating ASPPA’s 60th birthday. We will begin Saturday evening with Women in Retirement Cocktails & Conversations featuring Dr. Kiki Ramsey. Sunday morning will offer something for everyone. The TPA Growth Summit
will focus on developing yourself as a leader, building strong internal and external teams, and learning to market your team and communicate your value more effectively. Members preparing for the new Qualified Pooled Plan Professional designation can attend the QP3 Exam Cram. Additional pre-conference technical sessions will also be available for those people who want a little extra continuing education.
ASPPA Annual officially begins Sunday afternoon with the ASPPA Business Meeting followed by the ever-popular Washington Update. From there, the agenda is filled with technical education, technology, new ideas, and, of course, a little edutainment. Then on Tuesday night, we will celebrate 60 years of ASPPA at ASPPA After Dark. You know we are not going to let a milestone this big pass without an amazing party!
Serving as your president has truly been one of the greatest honors of my professional life. ASPPA has helped shape my career. It has introduced me to lifelong friends. It has given me countless opportunities to learn, grow, lead, and serve an industry I love. To have been trusted with this role is something I will always cherish. PC
As conversations accelerate, policymakers need to hear directly from the professionals who help Americans save for retirement every single day. By
Brian H. Graff
Now that Trump Accounts received its patriotic rollout on July 4, the Treasury Department has a “laser focus” on implementing the TrumpIRA.gov executive order (EO), according to Secretary Scott Bessent.
The EO directs Treasury to establish a federal online marketplace by January 1, 2027, that connects workers without employer-sponsored retirement plans to low-cost private-sector Individual Retirement Accounts (IRAs) that can receive the SECURE 2.0’s Saver’s Match. It also instructs Treasury to develop legislative recommendations to enhance what the Department cannot do on its own — such as auto enrollment of workers into these IRAs.
That last piece is the real story.
By personally directing Treasury to develop legislative recommendations, President Trump is signaling that expanding retirement coverage is no longer a technical tax issue confined to committee rooms; rather, it’s a domestic policy priority with a presidential mandate behind it.
And that shift may be exactly what’s needed to finally bring a comprehensive SECURE 3.0 package together.
As I’ve repeatedly pointed out, in our increasingly polarized political discourse, retirement policy remains one of the few bipartisan issues. The original SECURE Act passed during President Trump’s first term with broad bipartisan support. SECURE 2.0 followed during the Biden Administration through collaboration among Republicans and Democrats across multiple congressional committees.
The American Society for Pension Professionals and Actuaries (ASPPA) and the American Retirement Association (ARA) have spent years helping lay the groundwork for the next phase of important retirement policy.
We have worked with lawmakers on both sides of the aisle to develop proposals designed to improve the system, including the Retirement Rollover Flexibility Act, which would permit Roth IRA assets to roll into employer-sponsored plans, and the OPTIONS Act, which would give workers greater flexibility in how employer contributions are allocated.
While critically important, targeted improvements alone are unlikely to drive a broader SECURE 3.0 package. Historically, comprehensive retirement legislation comes together when there is a larger policy objective capable of bringing both parties to the negotiating table.
Retirement coverage expansion may now become that objective. Democrats have long prioritized closing the retirement coverage gap, particularly among small businesses, part-time workers, and lower-income employees. Republicans, meanwhile, increasingly view retirement savings through a populist lens centered on ownership, financial independence, and economic mobility.
Those political motivations may finally be converging, creating both opportunity and risk.
ARA strongly supports efforts to expand access to retirement plans. But any proposal must build upon the success of the existing employer-sponsored system rather than replace or undermine it. The current system works because employers, advisors, recordkeepers, consultants, TPAs, and financial professionals collaborate to help millions
of Americans save successfully for retirement.
As discussions evolve, there will undoubtedly be competing visions for how to address coverage gaps. Some proposals may complement the existing system. Others may move toward greater federalization or create unnecessary disruption. There are also increasingly well-funded outside interests entering the retirement policy arena, each advancing their own preferred vision for the future of retirement savings.
That is why ARA’s advocacy — and the engagement of our members — will be more important than ever.
But we cannot do it alone.
As SECURE 3.0 conversations accelerate, policymakers need to hear directly from the professionals who help Americans save for retirement every single day.
President Trump may have put retirement coverage back on the national agenda, but the future of the employer-sponsored system will still be shaped where it always has been: by the continued expertise, advocacy, and engagement of ARA members across the country. PC
CBS™
Christopher Bishop
Jacob Bourgeois
Earl Correll
Amy Crews
Phil Dianetti
Nicolas Gutierrez
Joseph Hadaway
Barbara Howard
Brendan Incardona
Phuong Jennings
Kimberly Knapp
Autumn Owens
Greg Sarabia
Sabrina Scott
Kara Siemer
Gene Skonetski
Bianca Stevens
Suzann Thompson
Leona Tran
Judy Wong
CPC™
Theresa Lensander
Steven Olson
Judy Simons
QPA™
Nolan Beiter
Nadine Davidson-Oliver
Claire Eyges
John Frisvold
Michelle Glassman
Tyler Jackson
Theresa Lensander
Matthew Nelson
Judy Richardson
Judy Simons
Patrick Spieler
Santiago Uribe Palacios
QKC®
Melanie Bateman
Nicole Becker
Nolan Beiter
Blair Brown
Christian Brunel
Gianna Cacolici
Tiffanie Hill
Michael Kurland
Stephen Martin
Shelia Mclaughlin
Adam Meeker
Adis Mehovic
Tamara Ogg
Carter Parmenter
Jacob Pelloni
Rigoberto Perez
Rikki Phillipson
Judy Richardson
Elena Sanjarova
James Schauer
Sydney Slachetka
Linda Tamburro
QKA®
Matthew Avery
Sherry Barrett
Emily Berkenstock
Gianna Cacolici
Sue Chambers
Victoria Collier
Lance Conrad
Dorothy Dagenais
Nadine Davidson-Oliver
Daena Davis
Quinn Davis
Mollie Delvecchio
Chase Dicristina
Claire Eyges
Melinda Fordham
John Frisvold
Ashlee Garcia
Crystal Giannoulis
Victor Ginzburg
Britain Gladden
Leonardo Hall
Michelle Hammond
Daniel Haupert
Isabella Herrera
Christopher Horwitz
Patrick Jones
Sagar Kandunoori
Andrew Keating
Betsy Kelly
Jordan Kramer
Michael Kurland
Brandon Lake
Matt Larson
Shelbie Lawrence
Antonia Lipovac
Katherine Lucitt
Thomas Mally
Rodney Marek
Kevin McCambley
Jason Miller
Emily Morrison
Elle Moser
Matthew Nelson
Kristin Nicastro
Tyler Nofzinger
Jordan Norley
Terri Pope
Judy Richardson
Tiffany Robbins
Elizabeth Ruiz
Stephanie Sanchez
Traci Segrest
Lori Shady
Judy Simons
Kelsey Struczewski
Misty Terry
Nicholas Teyechea
Rachel White
Hadleigh Wright
Makaylah Zuehlke
Irma Zuniga
QKS®
Stephanie Auvil
Raymond Beattie
Linda Crochet
Jarod Eassa
Christopher Ford
Mark Goldsberry
Anisa Grissom
Heather Hyatt
James Kaiser
Gage Ladnier
Colleen Lukacs
Alexis Martinez
Jennifer Moore
Nick Quinn
Maria Reyes
Tiffany Running
Nick Scaglione
Lisa Shelton
Tenzing Sherpa
Parker Shupe
Stefanie Signorello
Eric Sprung
Nicholas Teyechea
Emily Toboyek
Michelle Togstad
Ronald VanRell
Evan Wolf
The impact of the AFTAP extends beyond the valuation report. By Kerry Smith
If you have a defined benefit plan, or if you have clients with a defined benefit plan, you may have noticed that the annual valuation report often contains a certification called an Adjusted Funding Target Attainment Percentage Certification (AFTAP).
What is an AFTAP and what do you need to know about it?
The AFTAP is a measure of a plan’s funded status that generally compares the value of plan assets to plan liabilities. The plan’s enrolled actuary certifies the AFTAP annually, and the AFTAP is typically included in the annual valuation report.
A presumed AFTAP applies in some cases when the AFTAP is not yet certified. An actuary may complete a
range certification for a portion of the year until an AFTAP certification is completed. The AFTAP is based on several inputs that are determined under the funding rules.
So, what does a plan sponsor need to know regarding the AFTAP?
There are two main results to be aware of. The first is that if the AFTAP falls below certain thresholds, it can trigger significant restrictions.
The second is that participant notices may be required in these cases. Plan sponsors should work closely and communicate with their TPA and actuary on the specifics of their plan.
If a plan’s AFTAP is below 80%, certain funding-based restrictions are triggered under IRC section 436. These funding-based restrictions apply to both single-employer and multiple-employer defined benefit plans.
If the AFTAP is at least 60% but less than 80%, the following restrictions apply:
• Amendments that increase participant benefits are not allowed. In addition, if a plan’s AFTAP is at least 80% but would be less than 80% after reflecting the amendment, the amendment is not allowed.
o A contribution for the current year in addition to the minimum required contribution can be made in both cases to be exempt from the restriction.
o This restriction does not apply in some situations.
• Benefit distributions that are considered prohibited payments are partially restricted for those participants whose annuity starting date begins during a fundingbased restriction. A prohibited payment includes but is not limited to any payment in excess of a life annuity. Only one prohibited payment can be paid during the time period when benefit restrictions are applicable. If the AFTAP is less than 60%, the following restrictions apply:
• Participant benefit accruals are frozen.
o A contribution in addition to the minimum can be made to be exempt from this restriction.
• Prohibited payments, discussed above, cannot be paid.
• Amendments that increase participant benefits are not allowed. See details in the section above.
• Unexpected contingent event (UCE) benefit distributions are prohibited. In addition, if a plan’s AFTAP is at least 60% but would be less than 60% after reflecting the UCE, the UCE benefit distribution is not allowed.
o A contribution for the current year in addition to the minimum funding requirement can be made to be exempt from this restriction.
For plans that are not collectively bargained, the limitations relating to UCEs, plan amendments increasing benefit liabilities, and participant benefit freezes do not apply to new plans in the first 5 plan years of the plan, including years of a predecessor plan.
Additional limitations apply if the employer is in Chapter 11 bankruptcy. A contribution for the prior year by the minimum funding due date can be made, or a security can be provided to avoid the restrictions above.
Like the calculation of the AFTAP, the details surrounding the restrictions are extensive and should be discussed with the plan’s TPA and actuary.
For instance, if a plan has a prefunding or carryover balance, it may elect to reduce these balances to raise the funded percentage in some cases. In other cases, they may be required to reduce these balances.
When funding-based restrictions apply, a notice must be provided to participants and beneficiaries who are affected or could be affected. One exception to this notice requirement is the restriction on plan amendments that increase participant benefits. A notice is also required in certain cases when the restriction is lifted.
The impact of the AFTAP extends beyond the valuation report. Funding-based restrictions can affect the availability of participant distributions, plan design options, participant communications, and overall administration.
Consistent communication among the plan sponsor, financial advisor, TPA, and actuary is essential to ensure the plan is administered properly. PC
Why a simple business transaction can become a major retirement plan compliance issue. By Olivia Schwarts
When business owners think about selling part of their company, bringing on a new partner, purchasing another business, or restructuring their organization, they typically gather the right team around the table.
Attorneys draft the agreements, CPAs analyze tax implications, bankers discuss financing, and insurance professionals evaluate risk.
Yet one advisor is frequently left out of the conversation until long after the ink has dried—the retirement plan administrator.
At first glance, it doesn’t seem like a change in ownership would have much to do with a company’s 401(k) plan. After all, the employees are still working, payroll is still running, and contributions continue to be deposited.
Unfortunately, retirement plans don’t simply follow payroll; they follow ownership.
That distinction is where many employers unknowingly create compliance issues that may not surface for months or even years.
After administering retirement plans for thousands of employees across businesses of every size, we’ve seen one consistent pattern: many of the most expensive plan corrections begin with an ownership change that no one thought to mention.
Most ownership changes represent positive milestones:
• A business is growing.
• An entrepreneur acquires a competitor.
• A family business transitions to the next generation.
• A trusted employee becomes a partner.
• An investor joins the company.
• A new holding company has been formed to prepare for future expansion.
These are exciting moments that deserve to be celebrated.
Ironically, they’re also the moments when retirement plan compliance can quietly become far more complicated.
Unlike many business decisions, ownership changes don’t affect only a company’s legal structure. They often change how the IRS views the employer sponsoring the retirement plan.
And sometimes, those changes happen overnight.
One of the most common misconceptions we encounter is, “They’re completely separate businesses.”
Operationally, that may be true.
One company might manufacture products while another provides consulting services. They may have different employees, payroll providers, offices, and customer bases.
But retirement plan rules don’t focus solely on day-today operations.
Instead, they ask a different question: Who owns the businesses?
Depending on the ownership percentages and relationships involved, businesses that appear entirely unrelated may be required to be treated as a single employer for retirement plan purposes.
That determination can change nearly every aspect of plan administration, from employee eligibility to annual compliance testing.
We’ve seen business owners genuinely surprised to learn that purchasing another company affected employees they hadn’t expected to be included in the same retirement plan analysis.
The ownership transaction wasn’t the problem. The lack of communication was.
Ownership becomes even more complex when family members are involved.
Many entrepreneurs gradually transfer ownership to
children, spouses, siblings, or trusts as part of succession planning.
From a business perspective, these are thoughtful, longterm decisions.
From a retirement plan perspective, however, family ownership can introduce attribution rules that many owners have never heard of.
The IRS doesn’t always stop at legal ownership. In certain situations, ownership may be attributed among family members when determining retirement plan compliance requirements.
That means a transaction intended solely to prepare the next generation for leadership may also affect testing, eligibility, contribution calculations, or determinations regarding highly compensated employees.
None of these outcomes are necessarily negative. They simply need to be evaluated before they become operational issues.
There is one sentence that retirement plan professionals hear all too often:
“We made that ownership change about three years ago.” By the time those words are spoken, options are often more limited.
Perhaps a business purchased another company. Perhaps two entities became part of the same controlled group. Perhaps employees should have entered the retirement plan earlier. Perhaps annual testing should have included additional employees. Perhaps employer contributions should have been calculated differently.
These aren’t problems because someone ignored the rules. They’re problems because no one realized the retirement plan was affected.
Retirement plans operate under thousands of pages of federal guidance. Business owners aren’t expected to know
every nuance of ERISA or the Internal Revenue Code. That’s precisely why retirement plan professionals exist, but they can only evaluate what they know.
One of the greatest misconceptions about retirement plan compliance is that every ownership change automatically requires major changes to the plan.
Fortunately, that isn’t true.
Many ownership transactions have little or no impact. The value comes from asking the questions early.
• Could this acquisition create a controlled group?
• Will employees from both companies eventually need to satisfy eligibility requirements together?
• Should two retirement plans temporarily coexist?
• Will a plan merger be necessary?
• Has a new owner become a highly compensated employee?
• Could contribution calculations change?
• Does this affect annual IRS testing?
Often, the answer is reassuring: nothing changes.
But discovering that answer before the transaction closes provides certainty that simply isn’t available when questions arise during year-end compliance testing.
One of the most preventable situations we encounter is learning about significant ownership changes while preparing the annual Form 5500.
Imagine telling your CPA during tax season that you bought another company two years ago.
The response would likely be immediate; questions would follow, documents would be requested, and tax implications would be reviewed.
Retirement plans deserve the same level of proactive communication.
The annual compliance process should confirm that everything operated correctly, not to uncover major business events that occurred months earlier.
When ownership changes are communicated early, retirement plan professionals can coordinate with attorneys, accountants, payroll providers, and financial advisors before compliance issues arise.
That collaboration often saves both time and money.
The retirement plan industry spends significant time discussing regulations, testing, contribution limits, and correction programs.
Those topics matter, but after years of working with employers, we’ve found that one of the strongest compliance tools isn’t found in the Internal Revenue Code.
It’s communication.
Most retirement plan failures don’t begin with intentional mistakes; they begin with missing information.
A business owner assumes someone else notified the TPA, an attorney doesn’t realize the retirement plan could be affected, an accountant focuses appropriately on taxes. In contrast, retirement plan implications remain outside the scope of the engagement.
No one has done anything wrong. Everyone has simply viewed the transaction through the lens of their own profession.
That’s why successful retirement plan administration works best when advisors communicate with one another.
The most successful plan sponsors don’t think about their retirement plan once a year; they think about it whenever the business changes, including:
• New ownership
• Business acquisitions
• Entity restructures
• Family succession planning
• Partner buyouts
• Stock transfers
• New holding companies
• Business sales
These events should automatically trigger one simple question, “Should we let our retirement plan administrator know?”
The answer is almost always yes.
Sometimes the conversation lasts five minutes; sometimes it uncovers planning opportunities that save significant administrative work. Occasionally, it prevents costly operational failures before they ever occur.
That phone call is almost always worth making.
As TPA’s, we believe retirement plan administration should be proactive, not reactive.
Our role extends beyond preparing annual reports and performing compliance testing. We strive to become part of our clients’ advisory team, working alongside attorneys, CPAs, payroll providers, and financial professionals to identify retirement plan considerations before they become retirement plan problems.
Businesses evolve. Ownership changes. Companies grow through acquisition. Families transition leadership to the next generation.
Those are signs of success, and your retirement plan should evolve with your business rather than struggle to catch up after the fact.
The next time your company contemplates an ownership change, remember that one of the most important advisors at the table may be the one responsible for ensuring your retirement plan continues to operate exactly as the IRS intended.
Because sometimes the most significant compliance risk isn’t making the wrong business decision.
It’s forgetting to tell your retirement plan about the right one. PC
Our role as plan professionals is to help make sure their retirement savings can move forward with them. By
Shannon Edwards
When we talk about today’s workforce, one of the first things I hear is that younger employees do not stay with one employer very long.
They move for better pay, more flexibility, a better opportunity, or simply a job that is a better fit. It certainly feels as though employees are changing jobs more often than they did in the past. However, the numbers tell a slightly different story.
According to the Bureau of Labor Statistics, workers born between 1980 and 1984 held an average of 9.4 jobs between ages 18 and 38. Workers born between 1957 and 1964 actually held 10.2 jobs during those same ages. The 2024 BLS employee-tenure report also found that median tenure was 2.7 years for employees ages 25 to 34, compared with 9.6 years for employees ages 55 to 64.
To me, the research suggests mobility has more to do with age and where someone is in life than with the generation they belong to. We move more when we are younger and building our careers. As we get older, establish ourselves professionally, and take on family and financial responsibilities, we generally stay longer.
Still, every job change creates a point where an employee’s retirement savings can either continue moving forward or lose some momentum.
For most employees today, the 401(k) plan has become the primary workplace retirement savings vehicle. Defined benefit pension plans are much less common in the private sector, so employees carry more of the responsibility for enrolling, deciding how much to contribute, investing the account, and preserving those savings when they leave a job.
A new position may come with higher pay, but that does not always translate into a higher retirement contribution. Vanguard studied employees who moved between plans it administered and found that the median job changer received a 10% pay increase but reduced the retirement contribution rate by 0.7 percentage points. Fifty-five percent lowered their contribution rate after changing jobs.
That finding got my attention. An employee may be doing exactly what we encourage people to do by advancing a career and increasing their income while unintentionally saving a smaller percentage for retirement. Sometimes the employee simply accepts the new plan’s automatic-enrollment default without comparing it with the contribution rate at the former employer.
Eligibility is another important part of the discussion. A one-year waiting period may be permissible, but it can be a real challenge for a mobile
employee. If someone changes jobs several times and encounters a oneyear wait each time, the lost savings can add up.
The employee may miss personal contributions, employer matching contributions, and years of investment earnings. Even one year matters. The employee does not get that year of compounding back.
Fortunately, we are seeing positive movement. In our practice, employers in almost every industry are competing for employees, and many are reducing the traditional one-year waiting period to something much shorter.
Vanguard reported that 77% of the plans in its 2025 data allowed immediate eligibility for employee deferrals, while only 6% required a full year of service.
The SECURE Act and SECURE 2.0 have also expanded access for longterm, part-time employees. Instead of relying only on the traditional 1,000-hour year-of-service standard, the law created an additional path to elective-deferral eligibility based on consecutive years with at least 500 hours of service. SECURE 2.0 reduced that period to two consecutive eligibility computation periods for plan years beginning after 2024.
These changes recognize that all employees do not follow the same fulltime career path.
What happens to the old account is just as important as getting into the new plan. Vanguard’s 2026 report found that 28% of participants with 2025 termination dates took a cash lump sum. Those cashouts represented only 5% of the assets available for distribution, which tells us this is primarily a small-balance issue.
For a plan sponsor, forcing out small balances can be good and advisable plan administration. It reduces the cost and responsibility of maintaining accounts for former employees. For the former participant, however, it can be challenging, especially when the balance is $1,000 or less and is paid directly to the participant in cash rather than being rolled over to an IRA or another qualified plan.
Once that check arrives, it is very easy for retirement savings to become current spending.
SECURE 2.0 permits plans to increase the force-out limit to $7,000. Balances above $1,000 and up to the plan’s force-out limit must be automatically rolled to an IRA when the participant does not make an election.
Balances of $1,000 or less may still be paid directly to the participant. In our practice, we encourage clients to consider lowering the cash-out threshold to $200 or even less, with higher force-out eligible balances going to an IRA.
That still allows the sponsor to remove small accounts from the plan, but it gives more former employees a
chance to keep their retirement money invested. That small plan-design decision can make a meaningful difference in the long run.
Job mobility is part of today’s workplace and, in many cases, is positive. Employees change jobs to improve their careers, increase their income and find better opportunities. Our role as plan professionals is to help make sure their retirement savings can move forward with them.
Shorter eligibility periods, thoughtful automatic-enrollment rates, sensible force-out provisions and clear rollover education can help employees maintain the progress they have already made — and give them a better opportunity to retire with confidence and dignity. PC
It will require careful coordination among plan sponsors, TPAs, document providers, recordkeepers, and legal advisors.
By Wallace Gibson
For retirement plan professionals, 2026 is one of the most significant document compliance years in recent history. With multiple document projects converging, careful planning and coordination are essential.
While the spotlight is on the required interim amendments for legislative changes affecting qualified retirement plans, many sponsors will also be preparing for the Cycle 4 preapproved defined contribution restatement period, and sponsors of pre-approved 403(b) plans will be approaching the end of the Cycle 2 restatement window.
Although these projects all involve plan documents, they serve different purposes and should not be confused. The required interim amendments formally incorporate legislative and regulatory changes that have already been implemented operationally.
The restatement cycles, on the other hand, replace the plan document in its entirety with an IRS-approved document reflecting all cumulative qualification changes.
For most non-governmental defined contribution plans, the primary focus in 2026 will be adopting required interim amendments reflecting provisions enacted under the CARES Act, SECURE Act, and SECURE 2.0.
Governmental plans and certain collectively bargained plans generally have delayed implementation dates for several legislative provisions. Sponsors of those plans should review the applicable effective dates carefully when determining their interim amendment timelines.
An important point often overlooked is that these amendments generally are not implementing new operational rules. Plans have already been required to administer their
operations in accordance with applicable law as each provision became effective.
The 2026 amendments simply bring the written plan document into conformity with those operational decisions.
As a result, much of the work is historical. Plan sponsors must accurately document how the plan has actually operated over the past several years and ensure the written document reflects those decisions.
This process becomes significantly more complicated when service providers, recordkeepers, or third-party administrators have changed during that period.
Operational elections may have been implemented years earlier, but supporting documentation may not have transferred completely during a conversion. Reconstructing those decisions after the fact can become one of the most challenging aspects of the amendment process.
Before beginning the amendment process, sponsors should first confirm how the plan has actually been administered since the last required document update. Reviewing prior operational decisions before completing amendment elections can significantly streamline the process and help ensure the document accurately reflects plan operations.
One of the biggest misconceptions surrounding the 2026 amendments is that every legislative provision simply requires a “yes” or “no” election. In reality, the amendment package generally consists of two very different categories:
• Mandatory qualification changes that must be reflected in the document.
• Optional provisions that require affirmative plan sponsor elections.
Understanding the distinction is essential.
Certain legislative changes are required regardless of whether a plan sponsor made discretionary design choices. It is important to recognize, however, that “mandatory” does not necessarily mean “without choices.” Many required provisions include design elections that allow employers to adopt more generous approaches than the statutory minimum.
For example, while the long-term, part-time employee rules must be addressed, sponsors may elect to provide broader eligibility than required by law. As a result, even mandatory amendments often require thoughtful review rather than simply accepting default language.
Among the most significant mandatory provisions are the revised required minimum distribution (RMD) rules. These include increases in the required beginning age, updated beneficiary distribution requirements under the SECURE Act, and related technical changes affecting plan administration.
Long-term, part-time (LTPT) employee eligibility requirements also represent mandatory qualification changes. Plans subject to these rules must accurately reflect how the employer implemented the LTPT provisions, including any more generous eligibility requirements that were adopted.
Likewise, mandatory automatic contribution arrangement (ACA) requirements established under SECURE 2.0 must be addressed where applicable.
Although many existing plans are grandfathered and therefore exempt, plans subject to the new rules must ensure their documents and practices accurately incorporate the statutory requirements.
Optional provisions frequently receive less attention than the mandatory changes, but they often require substantially
“
WITH CORRECTIONS DURING FUTURE IRS OR DEPARTMENT OF LABOR EXAMINATIONS.”
more analysis. Examples include Roth employer contributions, student loan matching contributions, and new SECURE 2.0 distribution options.
Sponsors that adopted these features must ensure the amendment accurately reflects the decision to adopt the feature, the timing of its implementation, and the related design choices that govern its operation.
Adopting an optional provision is rarely the only decision. Sponsors must often make additional elections regarding eligibility, contribution limits, vesting, implementation timing, administrative procedures, or coordination with existing plan provisions.
Consequently, plan sponsors should avoid viewing discretionary amendments as simple check-the-box elections. Each optional provision should be reviewed carefully to ensure all related design elections are internally consistent, accurately documented, and properly satisfy the employer’s goals.
Because many legislative provisions became operationally effective years before the amendment deadline, one of the greatest challenges in 2026 will simply be identifying exactly how each plan has been administered.
Questions that frequently arise include:
• Which optional provisions were implemented?
• When were they first effective?
• Were temporary provisions adopted and later discontinued?
• Were administrative procedures modified to accommodate legislative changes?
• Do historical board resolutions or committee minutes support those operational decisions?
The answers may involve reviewing historical administrative files, payroll procedures, recordkeeper implementation notes, committee minutes, prior communications, and conversion documents.
Plans that experienced mergers, acquisitions, recordkeeper changes, or TPA conversions may require considerably more effort to reconstruct the historical records than plans that maintained the same providers throughout the implementation period.
Accurate documentation today can help prevent issues with corrections during future IRS or Department of Labor examinations.
Although much of the industry attention focuses on preapproved plans, sponsors of individually designed plans also face important document responsibilities in 2026.
Unlike pre-approved plans, individually designed plans do not follow the IRS six-year remedial amendment cycle for complete document replacements.
Instead, sponsors generally must adopt timely interim amendments to incorporate legislative and regulatory changes while maintaining individually drafted plan language.
Individually designed plans generally must incorporate the same legislative changes affecting pre-approved plans.
However, because each document is drafted individually, amendments often require greater customization and more careful review to ensure consistency throughout.
Sponsors of individually designed plans should work closely with document providers and legal counsel to ensure all required legislative updates have been properly incorporated.
While required interim amendments will occupy much of the industry’s attention, two additional document projects deserve consideration.
With the Cycle 4 restatement period underway, service providers should be prepared to manage the restatement process alongside required interim amendments. Unlike the interim amendments discussed above, the Cycle 4 project replaces the entire pre-approved plan document with a newly IRS-approved document.
Some interim amendment provisions are incorporated into the Cycle 4 documents. However, because certain guidance was not finalized before the IRS review process, additional “snap-on” amendments will still be required to address those later changes.
Sponsors of pre-approved 403(b) plans should also remain focused on the Cycle 2 restatement deadline.
Unlike the qualified plan interim amendments, the Cycle 2 project represents a complete document restatement using the IRS-approved Cycle 2 document. Sponsors should coordinate with document providers to ensure adoption occurs before the applicable IRS deadline.
Organizations sponsoring both qualified retirement plans and 403(b) plans should be particularly attentive, as multiple document projects may require action during the same general timeframe.
Plan Type
Pre-approved non-governmental defined contribution plans
Individually designed qualified plans
Required interim legislative amendments
Interim legislative amendments
Pre-approved 403(b) plans Cycle 2 restatement
Governmental and certain collectively bargained plans
Delayed implementation of certain legislative provisions
Pre-approved defined contribution plans Cycle 4 restatement
Although retirement plan professionals have spent the last several years implementing legislative changes operationally, 2026 marks the point at which many of those decisions must finally be memorialized in the governing plan document. Success will depend less on understanding new legislation than on accurately documenting years of prior operational decisions, identifying discretionary elections made, and confirming that administrative practices align with the written plan provisions.
Adopt amendments reflecting CARES Act, SECURE Act and SECURE 2.0 operational provisions by December 31, 2026.
Adopt individually drafted amendments reflecting required legislative changes by December 31, 2026.
Complete adoption of the IRS-approved Cycle 2 restated document before December 31, 2026.
Review delayed effective dates and applicable amendment timing.
Complete the Cycle 4 restatement during the applicable IRS restatement period.
With required interim amendments, the launch of the Cycle 4 defined contribution restatement program, and the continuing Cycle 2 403(b) restatement effort all occurring within a similar timeframe, 2026 will require careful coordination among plan sponsors, TPAs, document providers, recordkeepers, and legal advisors.
Organizations that gather the necessary historical records, confirm prior operational elections, and coordinate closely with their service providers will be best positioned to complete these projects accurately and efficiently. PC
Words matter, transparency matters, and the way we structure plan expenses can have a meaningful impact on retirement outcomes.
By Chad Johansen
Let’s start with a little pet peeve of mine: words matter. There is not only an actual difference between the words, cost, and fee, but there is also an emotional difference in how these words make people feel.
Nobody likes to pay fees, but most understand there is a cost for service.
I remember being taught the great 401(k) expense shell game of the early 2000s. I felt empowered to lift open the hood and show advisors these tricks. Too often I would step into a meeting with a local investment provider, an advisor, and a potential client and hear the words, “my plan is free.”
This was a stretch of time in the retirement plan industry where investment share classes were robust and held the majority of plan expenses.
I would hear conversations like this: “You are currently paying $2,500 in billed expenses. Well, your plan is now north of a million dollars, and that fee should go away. You also have a 50-basis point wrap fee. That is an evil way for Wall Street to make more money off of your employees. However, our offering eliminates your $2,500 billed expenses and your wrap fee altogether. You will have a great multimanager lineup of investments for your folks to choose from, and this all stems from your purchasing power of exceeding one million in plan assets.”
Now, here comes the shell game: an R-2 share class is chosen with an average investment expense of 1.50%. This share class has enough sub-TA and 12b-1 revenue to cover the $2,500 compliance costs and the advisor’s 50 basis points
in compensation. Overall, there was no cost reduction.
The expenses were all shifted to the participants, while the business gave up the deduction associated with paying them directly. This is what led businesses to believe their plan was free.
The real problem here is the lack of transparency. There are certainly times when a plan needs most or all of its expenses to be borne by participants because the business cannot afford to keep the plan open otherwise.
I understand that. But full disclosure around where the costs are being paid and who is ultimately paying them is critical. As we move into the heart of this article, my goal is to help you build confidence in discussing billed versus participant-paid expenses and to encourage you not to shy away from telling a business when it makes sense to pay for this valuable employee benefit.
There are several ways to explain plan expenses, so let’s keep it simple. A billed expense is a cost the business pays directly, typically by writing a check or paying an invoice. That expense may provide a tax benefit to the employer because it is generally deductible as a business expense.
The bill itself can be structured as a flat annual cost, a per-participant charge, or even an asset-based conversion calculation. An asset-based conversion calculation takes a percentage-based expense and converts it into a client bill.
This preserves the benefit of a tax-deductible business expense, but the bill still grows as plan assets grow. I see this structure used more often in the micro and small-plan market because it keeps the initial billed expense relatively low while the plan is growing and leaves room to reprice the arrangement to a flat-dollar structure later.
A participant-paid expense is a cost deducted from plan assets, meaning it is ultimately paid from participant accounts rather than directly by the business. These expenses can be allocated in several different ways. Still, the most common is an asset-based charge calculated as a percentage of plan assets, typically expressed in basis points and deducted pro rata from participant accounts.
Because the expense scales with asset growth, the total dollar cost can increase significantly over time, even when the scope of services remains relatively unchanged. Participant accounts may also be charged flat-dollar, per-participant, or transaction-based expenses, such as fees for loans or distributions.
The important distinction is that “participant-paid” describes who bears the cost, while “asset-based” describes one method used to calculate or allocate it.
I can’t sit here and tell you one method is right, and one method is wrong. However, if we are truly here to do what is in the best interests of the participants and their beneficiaries, then helping a business understand the difference between the two options is our duty.
Build your approach around clearly explaining the benefits of billed expenses. In the micro and small-plan market, the conversation often comes down to who is going to pay the majority of the cost anyway.
Because the executive team typically holds the largest account balances, they will also bear most of an asset-based expense deducted pro rata from participant accounts— without receiving a personal tax deduction for that cost.
As a general rule of thumb, when the executive team holds 60% or more of the plan assets, a billed expense will likely work in their favor. I use the 60% threshold because many business owners are subject to a combined federal and state marginal tax rate of approximately 40%. The math is fairly simple: if the executives hold 70% of the plan assets, they will effectively pay 70% of any pro rata asset-based charge. If the business instead pays 100% of that expense and receives a 40% tax deduction, the net after-tax cost is approximately 60%.
The executives may therefore incur a lower effective cost while preserving more money in both their own accounts and their participants’ accounts to compound and grow over time.
The conversation changes somewhat as plans grow larger. In a larger plan, ownership and executive balances may represent a smaller percentage of total plan assets, so the tax argument for billing the full expense to the employer may not be as compelling.
However, the overall economics of an asset-based fee often become more important. A charge that appeared reasonable when the plan had $5 million in assets can become significant once the plan grows to $25 million or $50 million, even if the scope of services has not increased at the same pace.
At that point, the consultant should be asking whether the fee is still aligned with the work being performed or whether a flat-dollar or per-participant arrangement would provide better value. Larger plans also tend to have greater negotiating leverage, making it important to periodically convert basis points into actual dollars, benchmark the total cost, and determine whether participants are continuing to receive services that justify the expense.
At the end of the day, there is no single fee structure that works for every retirement plan. The important part is understanding who is paying the cost, how that cost is being calculated, and whether the structure still makes sense as the plan grows.
Words matter, transparency matters, and the way we structure plan expenses can have a meaningful impact on retirement outcomes.
Do not be afraid to tell a business when paying the bill is in its best interest and in the best interest of the participants the plan was created to benefit. PC
LESSONS FROM BOTH SIDES OF A TPA ACQUISITION
IN THE END, THE GREATEST MEASURE OF A SUCCESSFUL ACQUISITION IS NOT WHAT CHANGES ON CLOSING DAY. IT IS WHAT REMAINS TRUE YEARS LATER.
BY DINA HAMAD
WIn my experience, however, the question that lingers long after closing is much simpler: Will the people who placed their confidence in me be better off because of this decision?
That question stayed with me throughout the sale of the company I spent more than three decades building.
Like most entrepreneurs, I didn’t start my business with an exit strategy in mind. I was focused on serving clients, earning the trust of financial advisors who referred business to us, and creating a workplace where talented people could build rewarding careers.
Years later, when I signed the purchase agreement, I realized the defining moment wasn’t the transaction itself. It was recognizing that I was entrusting decades of relationships, hard work, and responsibility to someone else.
Of course, we spent months discussing valuation, due diligence, legal agreements, and transaction structure. Those conversations mattered.
But they weren’t the ones that stayed with me afterward.
Instead, I found myself asking different questions:
• Would employees have
hen people think about selling a TPA, they usually focus on valuation, deal structure, or purchase price. Those are important considerations, and for many founders, selling a business represents the largest financial transaction of their lives.
opportunities beyond what I could provide independently?
• Would clients continue receiving the service they expected?
• Would advisors feel confident introducing the new organization to their clients?
• Would our industry partners continue to view us as dependable and collaborative?
Most importantly, had I chosen the right organization to carry forward what we had spent decades building?
Having experienced the process from both sides of the table, I have come to appreciate that acquisitions are rarely just financial transactions. I say that both as someone who built and sold a TPA and as someone who now works with owners evaluating similar decisions.
They are leadership decisions.
The financial terms establish value, but the people determine whether that value endures.
The retirement plan industry continues to evolve at a remarkable pace.
Technology is reshaping client expectations. Artificial intelligence is changing how work is performed. Cybersecurity has become a
business imperative, and regulatory complexity continues to increase. At the same time, plan sponsors expect faster service, deeper expertise, and increasingly sophisticated technology. Finding and retaining experienced retirement professionals has become equally challenging.
These realities are prompting many owners to ask difficult but necessary questions:
• Can I continue making the investments required to remain competitive?
• Is there a succession plan for my business?
• Can I prepare the company for the future while continuing to deliver exceptional service?
• Would partnering with another organization create opportunities that might not exist independently?
There is no universal answer.
Many companies will continue to thrive as independent organizations. Others will conclude that joining a larger organization creates greater opportunities for employees, clients, and strategic partners.
Neither path is inherently better.
The more important question is whether the decision positions both the business and the people who depend on it for long-term success.
From the outside, acquisitions often appear to revolve around EBITDA, valuation multiples, and purchase price.
Those metrics matter. Buyers have a responsibility to understand financial performance, and sellers deserve fair compensation for the businesses they have spent years building.
But financial statements tell only part of the story.
The most valuable assets in a TPA rarely appear on a balance sheet. They are the employees who consistently go above and beyond, the client relationships cultivated over decades, the confidence advisors place in recommending your company, the partnerships built with recordkeepers, and the reputation earned by quietly doing the right thing year after year.
Technology can be upgraded. Systems can be replaced. Processes can be improved. A reputation cannot.
That is why the best buyers evaluate people, relationships, and culture with the same discipline they apply to financial performance. They are not simply acquiring revenue; they are assuming responsibility for a legacy built over many years.
As buyers, we spend considerable time evaluating operations, technology, growth opportunities, and financial performance. Those factors are important. But one of the most important questions a buyer can ask is: How do we preserve what made this organization successful in the first place?
The goal of an acquisition should not be to replace everything that came before. It should be to build upon the strengths, relationships, and culture that created value in the first place.
Once a fair purchase price has been established, I believe every owner should pause and ask a different set of questions.
Not, what am I receiving? But, what am I leaving behind?
• Will employees have greater opportunities five years from now?
• Will clients experience an even stronger organization?
• Will advisors feel confident recommending the combined company?
• Will the acquiring organization honor the commitments made throughout the process?
And years from now, will I look back knowing I made the right decision?
Sometimes the highest offer is the right one. Sometimes it isn’t. I’ve watched owners accept lower offers because they believed another organization would better preserve their culture, create greater opportunities for employees, strengthen advisor relationships, and provide a better long-term experience for clients.
Those decisions are rarely driven by dollars alone. They are driven by responsibility. Every founder feels a deep obligation to leave the people who trusted them in a better position than when they started.
One of the most important measures of a successful acquisition is not found in the purchase agreement. It is found in the confidence of the people who rely on the organization.
For many TPAs, relationships have been built over decades. Every referral reflects more than confidence in technical expertise alone. It reflects confidence that clients will be well served, questions will be answered, and commitments will be honored.
When ownership changes, clients and partners naturally ask questions:
• Will my clients continue receiving the service they’ve come to expect?
• Will I still have access to knowledgeable professionals who understand their needs?
• Will this organization invest in technology, expertise, and innovation?
• Will this partnership become stronger or simply larger?
Those questions deserve thoughtful answers.
The confidence of financial advisors and partners should never be assumed based on a single transaction. It is earned through communication, consistency, and delivering on promises.
The same principle applies to recordkeeping partners. Long-term success in our industry depends on collaboration. When advisors and partners believe in the future of the combined organization, they become advocates rather than observers, creating continuity for clients and positioning the business for future growth.
One of the greatest lessons I’ve learned is that acquisitions aren’t won when the purchase agreement is signed. They’re won in the months and years that follow.
Employees notice how they are welcomed.
Clients notice how they are treated. Founders notice whether commitments made during negotiations become reality after closing.
Successful integration is not about moving as quickly as possible; it is about moving thoughtfully.
Every organization has its own history, strengths, and culture. The objective is not to erase those differences but to preserve what made the organization successful while introducing new capabilities and opportunities.
The most successful buyers understand that they are not simply integrating systems.
They are integrating relationships. And relationships thrive when people feel respected, informed, and included throughout the process.
The greatest lesson I have learned from sitting on both sides of the table is that businesses are ultimately about people.
Financial statements, technology, and operations matter. But those things alone do not make a business valuable.
The true value of a TPA is reflected in the people whose lives have been touched by the organization over time.
The employee who found a career rather than simply a job.
The client who slept better knowing someone was looking after their retirement plan.
The advisors and partners who confidently introduce your team to important clients because they trust you will not place their reputation at risk.
The participant whose retirement security was strengthened because your team cared enough to do the little things well, year after year.
Those outcomes never appear on a balance sheet. Yet they are often the very reason a business has value in the first place.
Every TPA owner can tell you how many plans they administer, how many employees they have, or what their EBITDA margin is. Those numbers matter. But after spending my career building, selling, and helping acquire businesses, I have come to believe there is another measure that deserves equal consideration: How many people are better off because your company existed?
That is a question every buyer should ask. It is also a question every seller should answer. Because while purchase agreements transfer ownership, they do not automatically transfer the confidence, reputation, and relationships that made the business successful.
Those must continue to be earned.
Looking back today, I don’t remember every provision in the purchase agreement or every revision to the closing documents. What I remember is hoping I had chosen the right steward:
• Someone who would invest in employees.
• Someone who would care for clients with the same sense of responsibility.
• Someone who would strengthen advisor confidence and build meaningful partnerships throughout the industry.
Most of all, someone who understood that what they were acquiring was not simply a business. It was decades of relationships.
Today, after having the privilege of sitting on both sides of the table, I believe valuation multiples or closing dates do not define the most successful acquisitions. They are measured years later.
They are measured when employees are thriving, clients remain loyal, advisors continue recommending the organization with confidence, partnerships grow stronger, and the culture that made the business successful continues to flourish.
Our industry will continue to evolve. Technology will advance. Regulations will change. Consolidation will continue.
What should never change is our responsibility to the people whose confidence we have earned along the way.
If you are fortunate enough to one day decide the future of the business you have built, I hope you negotiate a fair purchase price. But I also hope you ask a different question: Who will care for what I’ve spent a lifetime building?
Because businesses change hands, markets change, and ownership changes. What endures is the impact we have on the people we serve and the values we choose to leave behind.
In the end, the greatest measure of a successful acquisition is not what changes on closing day. It is what remains true years later.
That’s a legacy worth preserving.
Fall Exam
Thursday, November 12
Deadline to purchase Exam: November 11
BY AMY REUTER of Alternative Investments in Retirement Plans
It requires balancing diversification needs with fiduciary and operational considerations.
Are we moving into an era of alts for everyone? As traditional investments have become more concentrated and correlated in recent years, alternative asset classes are attracting increased attention.
The range of non-traditional assets is broad, encompassing everything from hedge funds to privately traded investments to digital assets such as cryptocurrencies.
Within this universe, many investors have been drawn to the expanded opportunity set and enhanced diversification potentially offered by private markets investments.
Alternative investments are no longer a fringe topic in the defined contribution market.
As private markets and other nontraditional strategies move further into the institutional mainstream, 401(k) plan sponsors, advisors, and recordkeepers are asking a more practical question: not only whether alternatives belong in retirement plans, but how to make them available in ways that work within the DC system.
For retirement plan recordkeepers, plan sponsors, and plan advisors, evaluating whether to make investments beyond traditional ones available requires balancing diversification needs with fiduciary and operational considerations. Alternative investments may offer benefits in diversifying opportunities.
The growing interest in alternatives in 401(k) plans reflects several broader market shifts. Institutional investors have used alternatives for years to diversify risk, pursue returns beyond public markets, and gain access to different economic exposures.
At the same time, concerns about the long-term outlook for traditional stock and bond portfolios have prompted sponsors and advisors to revisit what a modern retirement menu should look like.
Data Callout:
• Allocations to private
investments could reach 6.1% of all DC plan assets, or $1 trillion by 2030.1
• Within a decade, up to one-fifth of DC plans could have exposure to private market investments.2
While the trend toward private investments in DC plans is gaining momentum, recordkeepers, plan sponsors, administrators and advisors need to tread carefully.
Expanding exposure to alternative investments requires balancing participant demand with fiduciary responsibilities and the operational realities of retirement plans.
In the DC market, a strategy must also be tradable, valued, administered, and communicated in ways that align with participantdirected plan design. For those considering non-traditional assets for their plan menus, two key questions can help inform the right choice for plan participants.
1. Are non-traditional investments a good fit for the plan?
Start by considering plan participants – their demographics, financial sophistication and their longterm investment goals. Participants’ needs should drive these decisions.
Plan fiduciaries should consider whether:
• Non-traditional and private investments are appropriate for participants’ retirement goals.
• Participants have the requisite investment experience and financial resources to invest in these asset classes.
• There is sufficient demand among participants for these types of investments.
• The investment vehicle is appropriate for participants and their investment experience.
A disciplined, well-documented evaluation process can help plan fiduciaries demonstrate that they have fulfilled their fiduciary responsibilities.
2. What’s the right way to access these asset classes?
Next, seek out investment vehicles that offer exposure to non-traditional investments in a way that fits into the DC operational framework.
Recordkeepers best positioned for this shift will be those that focus not just on product availability, but on operational readiness. Supporting alternatives in DC plans means supporting the trading, valuation, reporting, participant communication, and fiduciary processes that make those products usable in the first place.
Consider whether investments:
• Trade in large, liquid markets and settle in T+1, so participants can easily buy and sell any of the holdings in their plan account.
• Price daily for recordkeepers to
accurately value participants’ accounts and process trades.
• Provide fee transparency and performance information to help investors make informed decisions.
Depending on a plan’s objectives and participants’ experience levels, non-traditional investments may be accessed through structures designed to meet retirement plan operational requirements, coupled with portfolio management options. These various options include:
• Mutual funds and ETFs: Nontraditional exposure can be introduced into diversified portfolios without requiring recordkeepers to reinvent plan operations.
Self-Directed Brokerage Accounts
• Collective Investment Trusts (CITs): Pooled assets bring scale from multiple plans, potentially providing access to a wider range of non-traditional investment options while fitting into the existing operational workflow.
• Unitized or Managed Accounts: Unitizing accounts aligns with the existing operational structure for pricing, cash management, and reconciliation while making non-traditional assets available within a professionally overseen portfolio framework.
• Self-Directed Brokerage Accounts: SDBAs provide another avenue for access, particularly for more engaged
and sophisticated participants who want investments beyond the core menu.
For some plans, access for a broad participant population may look different than access designed for a smaller group of more sophisticated investors. PC
To meet the needs of sophisticated plan participants seeking greater exposure to nontraditional investments, consider providing the option to invest through a self-directed brokerage account (SBDA).
An SDBA can empower more experienced investors to access the unique attributes of non-traditional assets without requiring an overhaul of the larger plan.
Depending on their asset levels, participants may be able to allocate a portion of their plan contributions to private placements and other less liquid investment vehicles.
Adding an SDBA to a DC plan can give eligible participants the freedom to invest according to their needs and preferences.
The future of alternative investments in DC plans will depend not only on whether plan sponsors and participants want them but also whether the industry can deliver them in participantfriendly, plan-compatible structures.
While non-traditional investments may offer attractive diversification, they also require plan fiduciaries to commit to careful suitability analysis, asset class and investment selection, and ongoing monitoring.
Supporting these investments requires additional capabilities and expertise. This can put pressure on providers to understand how to deliver access to non-traditional investments. Fortunately, recordkeepers and plan fiduciaries don’t have to do it alone. Experienced providers can play a central role to help determine which pathways are practical and scalable.
Ultimately, each plan’s approach should reflect its participant demographics, fiduciary responsibilities and operational needs.
For plans that determine private and non-traditional investments are appropriate, access to the right expertise and resources can help support informed decisions and ongoing oversight.
Know the deadlines and meet them, and don’t count on extensions from the IRS or self-correction options.
BY THERESA CONTI
AAnother restatement cycle is indeed upon us, but for all third-party administrators TPAs and document providers I have spoken with, it’s pure chaos. What makes it diffe rent than other restatement cycles?
It would seem that the “convergence” of the Cycle 4 restatements with all the provisions of Secure 2.0 has made it extremely challenging.
The provisions of Secure 2.0 won’t be part of the Cycle 4 restatements but must be managed and amended at the same time. These two converging events make it more difficult for us to help our plan sponsors not only meet the deadline for amending Secure 2.0 and restating the plan for Cycle 4, but also to track what they want and need to adopt.
Let’s be clear: the IRS deadline gives us additional time to restate and amend, but TPAs are now managing SECURE, CARES, and SECURE 2.0 interim amendments, Cycle 2 403(b) restatements, Cycle 4 defined contribution restatements, as well as all the “regular” day-to-day compliance responsibilities.
That also raises concerns about the plan’s operation and its compliance with the plan document. As TPAs, we are responsible for hundreds, if not thousands, of qualified plans. Still, the success of the restatements may depend as much on project management, technology, and client communication as on technical knowledge.
So, let’s talk about the deadlines.
For the interim amendments (such as SECURE and CARES) extended by SECURE 2.0 and IRS Notice 2024-2, the deadline for most plans is December 31, 2026. For Cycle 4 Defined Contribution plans, the expected 2-year restatement window is expected to open on October 1, 2026, and end on September 30, 2028. 403(b) plans must be restated in a Cycle 2 document by December 31, 2026.
As practitioners, one of the hardest things to manage in a restatement period is the additional work. In addition to our normal work, we now need to complete all these document restatements and interim amendments.
Understandably, for some TPAs this will result in additional revenue, potentially allowing for additional hire(s) to help with the project. Many TPAs now charge an annual plan document fee to increase annual revenue, but you also need to manage this project within your normal client work.
What strategy should you use? What should you consider before you start? Having a checklist for both
your client and your internal staff is essential. You need to consider your current staff capacity to determine whether you need additional staff to complete the restatements.
Who from your team will take ownership of the project? How will you train your team members, and what document software and workflow will you use? Hopefully those are already in place, but if you are considering a change, do that sooner rather than later.
Another big piece of the puzzle is communication with clients. There are so many things to collect related to the restatements. First, determine all clients that require the restatement.
Then identify any missing information, especially on takeover plans. Finally, consulting with your client on other plan document changes to incorporate into the restatement will be key.
There will be plan provisions requiring a decision by the plan sponsor. Also, don’t wait until 2028 to get started; you need to allow time for client questions and to execute plan documents before the September 30, 2028, deadline, and we all know that piece often takes longer than actually preparing the restated plan document.
From an internal standpoint, make sure you know what your plan document provider has available and their approach. Based on my research, different plan document providers take different approaches to interim amendments.
How are the SECURE 2.0 provisions being incorporated into the Cycle 4 restatement? Will there be plan provisions that will be “mapped” to the new document? Will you have a “one size fits all” interim amendment that you need to spend time determining which provisions apply? Will you have a
“FIRMS THAT NAVIGATE EACH RESTATEMENT CYCLE MOST SUCCESSFULLY ARE RARELY THE ONES WITH THE LARGEST STAFF—THEY ARE THE ONES WITH THE BEST PROCESSES. EARLY PLANNING, STANDARDIZED WORKFLOWS, AUTOMATION, AND PROACTIVE CLIENT COMMUNICATION CAN SIGNIFICANTLY REDUCE THE STRESS OF OVERLAPPING AMENDMENT AND RESTATEMENT DEADLINES.”
Word document that will need to be modified and tracked? Or will you have some sort of batch-generation capabilities to track interim amendments?
Make sure you leverage ALL available technology for the interim amendment and restatement process.
Use any available batch processing to create, validate, and sign the documents. Use a dashboard or workflow process to track the process so you can easily see the status of creation, review, the date sent to your client, and execution of the final documents.
Also make sure you track any changes that need to be updated to your compliance system and to the plan’s recordkeeper.
Be sure also to consider any takeover plans to ensure you have the information needed to complete both the interim amendments and the restatement. There is also a qualitycontrol/review process you need to consider. Who on your team will be doing all the plan document reviews (along with the other work they need to review before it gets sent to your clients)?
Let’s talk about when you will actually start the restatement process. We want to restate before December 31, 2026, but that’s a short timeframe. For takeover plans coming in, you want to restate
them onto the Cycle 4 document immediately.
That can even be used as a “sales technique” by including the restatement in your takeover fee. By completing the restatement by December 31, 2026, you only need to prepare a “short” version of the SECURE 2.0 interim amendment, as all other provisions of SECURE and CARES are included in the restatement.
Another consideration is that your document provider’s software may not be ready in time for you to complete it this year.
You will likely wait to complete the bulk of your restatements until after January 1, 2027. One advantage of waiting is that the interim amendment might be an opportunity for additional revenue if you don’t bill an annual plan document maintenance fee.
You may already have completed the interim amendments for SECURE and CARES, so there’s no need to rush the restatement.
By waiting, you will also ensure your document provider is ready with the software and has time to educate your team on the restatements, as well as to get past the busy compliance testing season.
A downside of waiting until 2027 to start the restatement is that you are now getting all this work done in
about 18 months instead of 2 years (assuming you wait until after the first quarter of 2027 to start).
When I talked with ASC (Actuarial Systems Corporation), which gave me a LOT of great information, they had some great insights.
“Firms that navigate each restatement cycle most successfully are rarely the ones with the largest staff—they are the ones with the best processes. Early planning, standardized workflows, automation, and proactive client communication can significantly reduce the stress of overlapping amendment and restatement deadlines.”
Some final thoughts: make sure you talk with your document provider to understand what they have available and how to use it effectively. Make sure you communicate early with your clients about decisions that will need to be made, as well as the timing for interim amendments and restatements.
Know the deadlines and meet them! Don’t count on extensions from the IRS or self-correction options. EPCRS may not allow selfcorrection on plan document failures in the future.
Wishing you good processes and preparation in this crazy restatement cycle. PC
Employer contributions as Roth might be a bit confusing or scary to some clients or participants, so are there any other alternatives to present?
By Colleen Windham
“Colleen, I’m glad I caught you; my client heard about that new Roth “stuff” and wants to add it to their plan!”
I’m sure all of us have heard some version of this when working with our clients (or potential new clients).
However, though I can appreciate the excitement and I don’t want to crush their tax-savings dreams, we all know there are additional details to consider. That being said, they are running a business and aren’t likely aware of the things to keep in mind when deciding whether or not this is a good option for their employees.
Since we want to be trusted resources for our clients, what are some talking points we can use to help our clients become more thoughtful while still being IRS compliant?
For clients that are set on offering this provision, it will likely appear in their Secure 2.0 amendment, and if it’s not the TPA’s default choice, the plan sponsor will likely need to sign the amendment and let their workforce know about this new option.
Next, are they comfortable sharing with their employees the extra rules/ caveats that come with this new option? In addition, the employer will need to continue (or start) making employer contributions. Anyone who wants to take advantage of this new
option must already be 100% vested in those funds.
Next, who are the people who want to take advantage of this provision? If it’s a young doctor who was just hired and bought into the practice, he likely isn’t vested in the profit-sharing portion of the plan under the normal 2-6 graded vesting.
He will likely be disappointed to know he won’t be able to participate in this option, unlike the current owners who have been there for 20 years, which could create additional questions or confusion. Lastly, if someone wants to opt out or change their decision, they are required to be able to adjust their election with HR at least once a year.
One of our core values at my firm is “Communicate, Communicate, Communicate,” and this also holds true for discussions about employer contributions as Roth.
Sometimes clients and their employees are very excited, but not quite sure how things will work out during tax time the following year, so we bring value as TPAs, not by providing tax advice, but more educational information and items to consider.
If the client is comfortable with the plan changes and implications, what are some talking points that they can share with their staff?
First of all, this option is separate from regular Roth deferrals, so no staff will be forced into this option and will be able to elect it individually. (Participants who hear about this option might feel caught off guard and worry that all their pre-tax money is automatically going to become Roth, which isn’t the case.)
For individuals (and of course it’s a discussion with their tax advisors or CPAs), are they ready and aware they will be taxed on this money in the year deposited? In the realm of tax planning, are they aware that they may need or want to update their W4 to increase withholding to avoid a surprise tax bill at the end of the year?
Lastly, once the participant has decided to have their employer contributions go into a Roth, it’s irrevocable, and there’s no going back or saying there was a “mistake.” As a result, they need to be fully aware and comfortable with the choice they are making.
All that being said, employer contributions as Roth might be a bit confusing or scary to some clients or participants, so are there any other alternatives to present? In my view, in-plan Roth conversions can be another option in the overall toolkit of planning and saving for retirement.
Of course, this option must be allowed in the plan document (or
“ONCE THE PARTICIPANT HAS DECIDED TO HAVE THEIR EMPLOYER CONTRIBUTIONS GO INTO A ROTH, IT’S IRREVOCABLE, AND THERE’S NO GOING BACK OR SAYING THERE WAS A “MISTAKE.” AS A RESULT, THEY NEED TO BE FULLY AWARE AND COMFORTABLE WITH THE CHOICE THEY ARE MAKING.”
if it’s not, it could be added via an amendment) and allows a bit more flexibility for the client and their participants, as Roth deferrals can be converted as well, not just employer contributions. Additionally, it can be done when the employee feels ready (and of course, has the blessing of their tax advisor, too!)
As such, it gives them more flexibility than the employer contribution as Roth, where it must be decided before the allocation is
completed. Lastly, the participant can do it at any time of the year; they aren’t tied to the Plan Sponsor’s allocation schedule and time constraints.
So, is there a proverbial pot of gold at the end of the rainbow? I would conclude with “sometimes.”
Employer contributions as Roth are absolutely permitted under the Code. They could be a good “fix it and forget it” strategy for some owners or employees who are already making their deferrals as Roth and would prefer to
pay taxes now on contributions rather than in the future when they withdraw them, presumably at retirement.
However, for a lot of participants who aren’t retirement-plan savvy, it could mean additional confusion or concern about available options.
That being said, as TPAs, we have a great opportunity to add value to our clients by educating them on both the pros and cons so they can make an informed decision for their own firm and employees. PC
Auto-IRAs may dominate the conversation, but Washington and Utah are proving there is more than one way for states to expand retirement plan access. By John Iekel
Auto-IRAs are the bread and butter of state-provided programs to close the coverage gap for private-sector employees whose employers do not offer a retirement plan. They are basic sustenance, central to the effort to provide coverage just like a basketful of fresh slices on a checkered tablecloth.
But they are not all that’s on the state coverage menu. Just as the states are varied, so too are the nuances and variations in how they support individuals’ accounts and help them build a more financially secure retirement.
As the first three states to set up an auto-IRA program — California, Illinois, and Oregon — were busy enacting legislation and setting up their programs, the Evergreen State took a different tack. Washington decided instead to make it easier for small businesses to find a retirement plan provider through a new retirement plan marketplace.
Then-Gov. On May 18, 2018, Jay Inslee (D) signed into law a bill creating the Washington Small Business Retirement Marketplace. The law, sponsored by State Sen. Mark Mullet (D-Issaquah) and State Rep. Larry Springer (D-Kirkland), creates a voluntary “marketplace” program and a public website that connect smallbusiness employers with private-sector retirement plan vendors.
Mullet, who sponsored the Senate version (SB 5826), in a statement
about this and a related bill hailed the measure as a program that “addresses critical needs I have heard from many of the employees at my small businesses,” and “will help workers who are early in their careers make better financial decisions, which can set them up to purchase homes and save for retirement down the road.”
The basics. The Washington Small Business Retirement Marketplace is a virtual marketplace through which qualified financial services firms offer retirement savings plans to businesses with fewer than 100 employees — and that includes sole proprietors and selfemployed individuals. Retirement plans listed on the Marketplace must meet certain minimum requirements.
The Washington Department of Commerce operates the Marketplace, and the Washington Department of Financial Institutions is responsible for verifying that retirement plans listed on the Marketplace meet statutory requirements.
Unlike state auto-IRA programs in which private-sector employers that choose not to offer a retirement plan of their own are required to register for the state-provided one, Washington’s Marketplace is voluntary. Small business employers may choose whether to offer marketplace plans to their workers, and workers may choose whether to participate.
Building the Marketplace. To be eligible, firms must offer — at a minimum — a balanced fund and a target-date or similar fund with asset
allocations and maturities designed for an expected retirement date. Annual fees charged to enrollees will be limited to 100 basis points.
Before a plan is listed on the marketplace, the Department of Commerce must approve it for inclusion. And before that happen, either the Department of Financial Institutions or the Office of the Insurance Commissioner must verify that the plan meets the requirements of Washington state law.
To apply to the Department of Financial Institutions for verification, the following information must be submitted concerning a retirement plan:
1. A completed Application for Verification form marked “initial”;
2. A copy of the retirement plan agreement;
3. A copy of the materials routinely used to market the retirement plan to eligible employers and/or individuals;
4. Any additional documents necessary to identify the funds and other investment products offered under the plan, specify the plan’s fees and rollover options, and disclose historical investment performance for the investment products in the plan;
5. The prospectus for each balanced fund, target date fund, and other fund offered under the retirement plan; and
6. A summary of the retirement plan’s investment options, fees,
“THEY (IRAs)ARE NOT ALL THAT’S ON THE STATE COVERAGE MENU. JUST AS THE STATES ARE VARIED, SO TOO ARE THE NUANCES AND VARIATIONS IN HOW THEY SUPPORT INDIVIDUALS’ ACCOUNTS AND HELP THEM BUILD A MORE FINANCIALLY SECURE RETIREMENT.”
and other features. The summary should include, but not necessarily be limited to, the following information:
• The type of retirement plan (e.g., SIMPLE IRA);
• The investment options available in the retirement plan;
• The fee structure applicable to the different investment options in the retirement plan (including fees payable to the financial services firm offering the retirement plan and any other service providers);
• The identity of the custodian of enrollee accounts;
• The rollover options for enrollees in the retirement plan;
• Whether the financial services firm offering the retirement plan will recommend investments to enrollees, and if so, how the firm will communicate to enrollees the option to select investments other than the recommended investments;
• A list of documents an employer must complete to establish the retirement plan and its business
relationship with the financial services firm offering the plan;
• A list of the document’s enrollees must complete to establish their retirement account and their relationship with the financial services firm offering the plan; and
• Disclosure of any other fees associated with the retirement plan.
Required actions. Retirement plans also must meet these criteria.
• The financial services firm offering the retirement plan must
be licensed or hold a certificate of authority, be in good standing with the Department of Financial Institutions, be regulated by a federal agency with authority over banking, securities, or broker-dealer firms, and meet all federal laws and regulations to offer retirement plans.
• The retirement plan must offer a minimum of two product options (1) a target date or other similar fund, with asset allocations and maturities designed to coincide with the expected date of retirement, and (2) a balanced fund.
• The retirement plan must include the option for enrollees to roll over pre-tax contributions into a different individual retirement account or another eligible retirement plan after enrollees cease participating in the retirement plan offered on the Washington small business retirement marketplace.
• The financial services firm offering the retirement plan may not charge the participating employer an administrative fee and may not charge enrollees more than one hundred basis points in total annual fees; however, financial services firms may charge retirement plan enrollees a de minimis fee for new and/or low balance accounts in amounts negotiated and agreed upon by the Department of Commerce and the financial services firm.
• The financial services firm offering the retirement plan must provide information about the product’s historical investment performance.
Earlier this year, Utah Gov. Spencer Cox (R) signed into law a measure to create the Utah
Retirement Plan Exchange.
With that, the Beehive State not only entered the club of states providing a program that covers employees whose private-sector employers don’t have a plan of their own — it did so with its own unique twist.
“Utah HB 250 is not just a step in the right direction; it is a leap towards closing the retirement plan coverage gap in Utah,” said National TaxDeferred Savings Association (NTSA) Executive Director Nathan Glassey.
If it seems like it happened quickly, that’s because it did — it all took just 63 days. Rep. Joseph Elison (R-Washington) introduced House Bill 250 in the Utah House of Representatives on Jan. 20, 2026; the chamber passed the bill on Feb. 10 in a 71–1–3 vote. The Utah Senate followed suit 10 days later, exactly one month after Elison introduced it. And just a little more than a month after that, it was law.
What the exchange is. The Utah Retirement Plan Exchange is a program through which eligible private-sector employers can easily set up a retirement plan or adopt an auto IRA program to provide coverage for their employees. The exchange walks employers through a set of questions that guide them toward establishing the retirement program that best fits their situation.
The Utah Treasury is responsible for establishing and maintaining the publicly accessible online exchange. It is also responsible for creating and disseminating educational resources for eligible employers and eligible employees concerning the exchange, and to ensure that the exchange:
• provides eligible employers access to qualified retirement plans;
• does not include retirement arrangements other than qualified retirement plans; and
• presents each qualified retirement plan with a variety of
forms of information about each plan’s features and procedures.
Small businesses too. The program also is intended to give small businesses a boost in providing coverage to their employees. In an interview with ASPPA Connect, Elison noted that small businesses struggle to provide retirement benefits themselves. Sen. Brady Brammer (R-Highland) in his Feb. 19 testimony about the bill before the Utah Senate’s Business and Labor Committee attested to small business’ needs in that regard, and from personal experience. “I’m a small business owner. One of the difficult things is providing benefits to employees,” he said.
Coming soon. The Utah Retirement Plan Exchange is coming soon. The Office of Economic Opportunity is required to establish the exchange platform no later than Nov. 2, 2026, and is required to begin accepting applications from plan providers on that date as well. And that office is required to ensure the exchange begins operation no later than Jan. 1, 2027.
The bottom line. Elison, the bill’s author, in an interview told PC Magazine that the measure “fills a significant gap” in retirement plan savings in Utah by making the proverbial three-legged stool of retirement financing more stable and solid, and observed that more than 700,000 of his fellow Utahns lack access to employer-provided retirement plan coverage.
Elison sees the measure as a way to address a situation in which traditional pension plans are less widespread than they once were, Social Security is “ridiculously underfunded,” and many Americans have insufficient savings to finance their retirements. And he told PC that he also hopes other states will follow Utah’s example and take a similar approach. PC
Wednesday, September 16 12:00 – 3:00 pm EST
Identity, summary, history, credibility: the four parts of a profile that earn trust before you ever walk in the room. By Joe Apfelbaum
I was in Japan when my phone rang. A woman I had never met was on the other end, and she sounded almost frantic to get on my calendar. I asked her, politely, how she had even heard of me. She told me she had asked ChatGPT who the best marketing guy in Brooklyn was. ChatGPT pointed her to my LinkedIn profile.
That client now spends more than $100,000 a year with my marketing agency. She found me because an AI read my LinkedIn profile, trusted what it saw, and recommended me. That is the world we live in now. LinkedIn has more than 13 billion backlinks pointing into it, which is part of why it is one of the most trusted sites on the internet. Google trusts it. ChatGPT trusts it. When someone Googles your name, your LinkedIn profile is almost always the first result that comes up.
For a third-party administrator, that is not a small thing. The advisors, CPAs, wholesalers, and plan sponsors who are deciding whether to refer business to you are looking you up. Quietly. Before the first call. Before the meeting. Your profile is doing the work whether you have invested in it or not.
I have been on LinkedIn for almost 20 years. I have 56,000 followers, 537 written recommendations, and I post and comment every single day. I have helped tens of thousands of
professionals optimize their profiles. Everything I am about to share is what I have learned in the trenches. Four parts of a LinkedIn profile actually matter. I think of them as Identity, Summary, History, and Credibility.
IDENTITY: WHO YOU ARE
Identity is at the top of your profile, and it is the part most TPA owners get wrong. It includes your banner, your photo, your name, the pronunciation, your pronoun, and your headline. In the three seconds someone scans this section, they are deciding whether to keep reading or move on.
Start with the headshot. You do not need to spend $500 on a photographer anymore. I built evyAI to generate professional headshots in minutes using AI. Even on a free account, you can produce a great one, and we have prompts and templates ready to go. The image needs to look like the person who will walk into a plan sponsor meeting, friendly, professional, and present.
Your banner is real estate, not decoration. Canva has more than 100,000 banner templates you can start from. Put a call to action on it. I put a QR code on mine that matches my brand. If you pay for LinkedIn, you can rotate up to five banners, which I do. Tell people what to do next: visit your site, book a call, join your newsletter.
Your headline is the line that follows you everywhere on LinkedIn. Every time you comment on someone’s post, your headline shows up next to your name. You get more than 200 characters but treat the first few words like they are the only ones that will be read, because for most people they are — the format that works: who you help and how you help them. “TPA helping CPAs and advisors design retirement plans that maximize owner contributions” beats “President at XYZ Pension Services” every time.
One more identity hack. My pronoun on LinkedIn is “LinkedIn Whale.” It is a custom pronoun, and people notice it. It is a small thing that makes me memorable. You can do something similar in your own voice.
Your summary is your About section, your Services section, your Featured posts, and your day-to-day content. This is where you tell people what you stand for and what you actually do.
The About section should not read like a resume. It should sound like you. Open with something that makes the reader want to keep reading. The same rule from your headline applies here: the first two lines are what show before the “see more” cutoff, so they have to earn the click. Talk about who
“I POST EVERY SINGLE DAY, AND I LEAVE COMMENTS ON OTHER PEOPLE’S POSTS EVERY DAY. POSTING IS WHAT BUILDS THE REPUTATION. COMMENTING IS WHAT BUILDS RELATIONSHIPS.”
you serve, what problems you solve, and what makes you different. For a TPA, that might be the kinds of plans you specialize in, the industries you know, or the way you partner with advisors.
The Services section is underused by almost every TPA I look at. List what you actually do: plan design, compliance testing, 3(16) services, cash balance, Form 5500, takeover work. LinkedIn will surface you in search when prospects look for those terms.
Featured posts are how you show, not tell. Pin your best content, a case study, a webinar replay, a client win, a piece of plan design education. And then post. Not occasionally— regularly. I post every single day, and I leave comments on other people’s posts every day. Posting is what builds the reputation. Commenting is what builds relationships.
HISTORY: WHERE YOU HAVE BEEN History is the part of your profile that tells your story over time.
Experience, education, languages, volunteer work, projects, certifications. This is where you show depth. For a TPA, the Experience section should not just list job titles. Each role should have a short description that says what you did and who you served. If you have a QKA, an ERPA, or a CPC, include it. If you sit on an ASPPA committee, put it in. If you have spoken at industry events, put it in. Every line is a signal of credibility. Here is a hack most people do not know. The Education section
displays near the top of your profile, right next to your company logo on mobile. I use that real estate to display my cell phone number. I added a fake “education” entry, where the school name is my contact information. That is why my phone number shows up at the top of my profile. It is one of the highest-converting changes you can make, especially if you want plan sponsors and advisors to be able to reach you with one tap. Projects, volunteer work, and languages all add texture. They show that you are a person, not just a function. The plan sponsor who is choosing between three TPAs is making a human decision. Give them reasons to feel something.
This is the part that takes time, and there is no shortcut. Credibility is what tells Google, ChatGPT, and human beings that you are the real deal.
Start with the basics. Get over 500 connections. Pay for LinkedIn so you get the gold verification icon next to your name. Collect recent recommendations. I have 537 written recommendations on my profile, and I ask for new ones often because freshness matters. Add skills and ask for endorsements. None of this is vanity. It is a credibility signal.
Then comes the part many people skip: be active. Comment on other people’s posts every single day. Comments are how the algorithm sees you, how prospects see you, and how relationships actually form on LinkedIn. A thoughtful comment on a CPA’s post or a wholesaler’s post is worth more than a cold message any day of the week. Seriously, people are afraid of leaving comments; have the courage to show up.
Connections matter too. When I started on LinkedIn almost 20 years ago, I had no idea how to get
followers. One day it hit me: every follower I had was really just me adding connections. So, I started adding. I hit the 30,000-connection cap, which is the maximum LinkedIn allows. I regularly trim and add. Right now, I have a backlog of 1,500 people with connection requests outstanding due to LinkedIn’s connection limits.
You can build to that too, one connection at a time, by reaching out to the advisors, CPAs, wholesalers, and plan sponsors in your world.
The reason ChatGPT recommended me to that woman in Brooklyn is not magic. I post daily, comment daily, have hundreds of recommendations, a verified profile, a large strategic network, and have been doing this for almost two decades. Trust compounds.
An optimized LinkedIn profile can make or break your professional reputation. The plan sponsor
Googling you before the call, the advisor deciding whether to refer their next plan to you, the wholesaler trying to figure out if you are the right partner; they are all looking at the same profile. If it looks abandoned, you lose. If it looks alive, intentional, and credible, you win before the conversation even starts.
You do not have to optimize your profile perfectly on day one. Pick one section a week. Fix your headshot. Rewrite your headline. Add five recommendations. Post three times. Comment on ten posts. In ninety days, you will not recognize your profile, and more importantly, neither will the people who are quietly checking your professional experience and digital presence.
LinkedIn is not a digital business card. It is a 24/7 storefront, a referral engine, and increasingly, the source AI uses to decide who to recommend. Treat it like the asset it is and an essential building block of your digital presence. PC
By bringing forward ideas, sharing industry insights, and helping employers plan for future changes, TPAs can create value that extends well beyond compliance. Here’s how. By Katie Boyer-Maloy
Over the last few years, retirement plan sponsors have spent a lot of time getting their arms around SECURE 2.0. From understanding new requirements to updating administrative processes, the focus has largely been on compliance.
Now, as additional provisions take effect and amendment deadlines approach, many are asking a broader question: How can these latest changes support employees and strengthen their overall benefits strategy?
That’s where TPAs can play a more strategic role.
While plan compliance is always important, many sponsors are seeking guidance on how SECURE 2.0 provisions can support workforce needs, improve employee outcomes, and strengthen their retirement programs over time.
Sponsors continue to navigate provisions affecting long-term parttime employees, automatic enrollment requirements for certain new plans, Roth catch-up contributions for higher-income employees, paper statement requirements, and upcoming plan amendment deadlines.
But most employers don’t want a detailed walkthrough of every SECURE 2.0 provision. They want to understand what deserves their attention, what decisions they need to make, and how those decisions may affect employees and plan operations.
TPAs are uniquely positioned to add value in this space. Instead of leading every interaction with regulations and deadlines, you can help clients focus on the strategic implications of those changes.
What changes are most relevant to their workforce? What opportunities are available? Where should they focus their time and resources?
Some of SECURE 2.0’s most interesting provisions aren’t the required ones. They’re the optional provisions that help employers better align retirement benefits with employee needs.
Take student loan matching contributions. The opportunity is significant. U.S. student loan debt totaled nearly $1.8 trillion in early 2025 and is held by more than 42 million Americans, making it difficult for many workers to balance debt repayment with retirement savings. [1]
For younger employees who may feel forced to choose between paying down debt and saving for retirement, this provision can help bridge that gap.
Enhanced catch-up contribution limits can benefit employees approaching retirement who want to accelerate their savings during their highest-earning years. Roth employer contribution options may appeal to employees seeking greater flexibility in how their retirement income is taxed. While these provisions may appear technical on the surface, they can serve as strategic tools to help employers address workforce challenges, improve employee outcomes, and strengthen the value of their retirement plan.
TPAs can help clients look beyond the mechanics to evaluate which optional features can make the most sense for their organization and employees.
Once sponsors have identified the SECURE 2.0 provisions most relevant to their workforce, the next challenge is execution. TPAs can help turn ideas into action by providing guidance, practical resources, and a framework for decision-making. Consider these approaches:
• Provide strategic guidance. Facilitate planning sessions that help sponsors understand how SECURE 2.0 provisions may influence workforce planning, benefits strategy, and participant engagement.
• Make implementation manageable. Move beyond plan-compliance checklists by offering implementation tools, communication materials, and practical timelines to streamline the process.
• Tie compliance to business outcomes. Help sponsors see how adopting new plan provisions can support broader organizational objectives, including talent attraction and retention, employee financial well-being, and administrative effectiveness.
One of the most valuable planning exercises TPAs can facilitate is helping
sponsors connect plan decisions to workforce needs.
A workforce is rarely one-sizefits-all. Early-career employees may be focused on repaying student loans. Mid-career workers may be balancing family expenses with long-term savings goals. Employees nearing retirement may seek opportunities to maximize contributions and strengthen their retirement readiness. SECURE 2.0 offers features designed to help address the needs of each of those groups.
When TPAs help sponsors evaluate provisions through the lens of workforce demographics and employee financial wellness, the focus shifts beyond plan compliance requirements. The result is a more meaningful assessment of how retirement benefits may improve employee outcomes.
As retirement plans grow more complex, sponsors increasingly
value partners who offer perspective, not just answers. They want help understanding what’s changing, what matters most, and how retirement plan decisions connect to broader workforce and business goals.
This creates a significant opportunity for TPAs. By bringing forward ideas, sharing industry insights, and helping employers plan for future changes, TPAs can create value that extends well beyond compliance and help clients make more informed decisions about their retirement programs.
Ultimately, sponsors aren’t looking for someone who simply understands SECURE 2.0. They’re looking for a partner who can help them translate compliance requirements into a longterm retirement plan strategy. PC
[1]
The value of the QP3™ is not just in what it covers, but in how it prepares professionals to approach the work. By Kizzy Gaul
Pooled employer plans are a growing and increasingly consequential part of the retirement plan landscape.
As Multiple Employer Plans (MEPs) and Pooled Employer Plans (PEPs) have gained traction, the conversation has shifted from “what they are” to “how they actually work.” That shift matters, because growth has introduced complexity.
More professionals are encountering these plans, whether they are supporting them directly or helping clients move in and out of pooled arrangements. With that exposure comes the realization that pooled plans require a different level of practical expertise.
That is the gap ASPPA’s Qualified Pooled Plan Professional™, or QP3™, is designed to fill.
When we set out to build the QP3™, the goal was to create a credential that reflects what practitioners are actually working through today.
In practice, working with MEPs and PEPs rarely presents as a clean, textbook scenario. An employer may want to join a pooled plan and realize that their existing plan design does not align with the pooled plan’s available options. Questions arise about how nondiscrimination testing and reporting are handled during the year an existing plan transitions into or out of a pooled structure. Compliance issues surface and need to be worked across multiple parties. Audit requirements bring documentation, processes, and coordination into sharper focus.
These are not unusual situations. They are the kinds of issues that come up in day-to-day work. And in my experience, they are exactly where professionals feel the most uncertainty if they do not have a structured way to think them through.
The QP3™ was designed around these realities so that professionals are not encountering them for the first time without a framework.
A key design decision was to center the QP3™ on practical application.
The credential follows the lifecycle of a pooled plan. It starts with evaluating when a pooled structure makes sense and understanding the distinctions between single-
“LOOKING AHEAD, POOLED PLANS WILL CONTINUE TO EVOLVE. THIS WILL BE DUE IN PART TO REGULATORY DEVELOPMENTS AND INCREASING EXPECTATIONS FOR GOVERNANCE, DOCUMENTATION, AND OVERSIGHT. IN MY VIEW, THAT MAKES PRACTICAL, APPLIED EXPERTISE EVEN MORE IMPORTANT THAN IT IS TODAY.”
employer plans, Groups of Plans, multiemployer plans, MEPs and PEPs.
It continues through onboarding employers, setting expectations and operating the plan across multiple participating businesses. It also addresses governance, nondiscrimination testing, compliance, corrections, reporting and audit considerations.
Just as importantly, it focuses on transitions as employers move into and out of pooled arrangements. That is an area where complexity tends to surface.
The value of QP3™ is not limited to professionals working within a pooled plan structure.
A large portion of the industry interacts with these plans from adjacent roles. Professionals help employers evaluate whether a pooled arrangement is appropriate. TPAs support clients through the operational realities of joining or leaving a pooled plan.
Internal teams manage data, reporting, and legacy issues that do not disappear simply because the structure changes. Many professionals are asked to resolve compliance questions that carry across plan types.
In those moments, the questions tend to become more complex, not less. Who is responsible for correcting a historical issue? How are reporting obligations allocated? What happens to participant data and records as plans change structure? These are the questions that require judgment, not just rule recall.
This is where QP3™ makes the biggest difference.
From my perspective, the value of the QP3™ is not just in what it covers, but in how it prepares professionals to approach the work.
It signals job-ready expertise. The QP3™ reflects more than familiarity with pooled plans. It reflects the ability to step into situations such as onboarding employers, managing transitions, resolving compliance issues, and working through them in a structured and informed way.
It is grounded in how the work actually gets done. The content is intentionally focused on operational decision-making, coordination across multiple parties, and scenarios that do not fit neatly within a single rule or checklist. That is where most realworld challenges tend to sit.
It strengthens governance and risk awareness. Pooled plans introduce shared responsibility in ways that are not always intuitive. The QP3™ helps professionals understand where risk sits and how to manage it through process, documentation, and oversight.
It builds fluency across plan structures. Professionals rarely practice in just one environment. Being able to move between singleemployer plans, MEPs, and PEPs, and to explain the differences clearly to clients, is becoming increasingly important.
It also prepares professionals for the realities of managing multiple employers within a shared structure. The QP3™ focuses on where breakdowns can occur and how to design processes that hold up as the number of participating employers grows.
On a personal level, I am excited to be part of the team bringing the QP3 to the ASPPA community. ASPPA has always been grounded in practical, applied education. It is a community of professionals who want to understand how things work in practice, not just what the rules require.
That perspective shaped this credential from the beginning. It reflects the conversations I have had with colleagues and clients and the kinds of situations that come up repeatedly when working with pooled plans.
Looking ahead, pooled plans will continue to evolve. This will be due in part to regulatory developments and increasing expectations for governance, documentation, and oversight. In my view, that makes practical, applied expertise even more important than it is today.
Registration for the QP3™ will be available soon. Watch for updates on the ASPPA website. Once open, candidates will be able to enroll, access study materials and the practice exam, and begin working toward the credential.
For those attending the ASPPA Annual in San Antonio, I will be leading a live exam cram for attendees enrolled in the QP3™.
This session is designed to reinforce key concepts, work through more complex scenarios, and help candidates approach the exam with confidence. Details on the exam cram, including how to add it to your schedule, will be available on the ASPPA Annual website I hope to see you in San Antonio! PC
We examine the years-long legislative effort to allow 403(b) retirement plans to invest in collective investment trusts (CITs), highlight growing bipartisan and industry support, and the remaining securities law changes needed. By John Iekel
Are CITs on the 403(b) Horizon? Maybe. But we’ve heard that before. Will this time be the charm?
“Today, there is no rational basis why CITs are not available in 403(b) plans and accessible to teachers, hospital workers, charity and nonprofit employees,” argued Reps. Josh Gottheimer (D-N.J.) Bill Foster (D-Ill.), and Frank Lucas (R-Okla.), in a 2024 “Dear Colleague” letter concerning a measure that would have allowed 403(b) plans to invest in collective investment trusts (CITs) and insurance contracts in which other retirement plans could invest. They added that CITs in 401(k) and 401(a) plans had “grown dramatically in recent years.”
The American Retirement Association certainly supports the idea. “There are over 15 million 403(b) plan participants that would benefit from gaining access to CIT investments in their plans,” American Retirement Association CEO Brian Graff said in a March 2025 statement concerning the progress of legislation in the House of Representatives that provided for CITs to be included as investment options in 403(b)s.
The legislation that prompted Graff’s statement was not the first introduced that would allow CITs
to be included among 403(b) fund investment options, nor was it the last. “Over the years, Congress has tried to harmonize some of the rules that cover 401(k) and 403(b) plans,” noted the Congressional Research Service (CRS) in a 2025 report.
CITs are pooled investment funds maintained by banks or trust companies available only to certain qualified retirement plans and are an example of a group trust.
Unlike mutual funds or ETFs, which must register with the Securities and Exchange Commission (SEC), CITs are regulated by the Office of the Comptroller of the Currency (OCC), a federal banking agency within the U.S. Treasury Department, and by state banking regulators.
Since CITs are exempt from SEC registration requirements, they typically have lower fees than mutual funds. CITs, which are not retail products, also typically have lower administration, marketing, and distribution costs than retail products like mutual funds.
The CRS has observed that annuity contracts offered by insurance companies and custodial accounts invested solely in mutual funds registered with the Securities and
Exchange Commission (SEC) have been the only investment options for 403(b)s. Not only that, assets of 403(b) custodial accounts could not be commingled in group trusts with assets other than those of regulated investment companies.
Currently, 403(b) plan participants do not have the same access to the variety of investment options that are available to savers using other plans, including 401(k) plans, 457(b) plans, and the federal Thrift Savings Plan.
So CITs were an investment option for 401(k)s, but not 403(b)s. That is, until the SECURE 2.0 Act of 2022 came along.
Section 128 of SECURE 2.0 amends the Internal Revenue Code (IRC) to allow 403(b)s to invest in group trusts such as CITs. Among the changes the provision makes is that it modifies the types of contributions 403(b) participants may withdraw in hardship distributions to mirror the rules for 401(k) plan hardship distributions.
But it’s not quite that simple. While SECURE 2.0 amended the IRC, it did not make corresponding amendments to securities laws — the Securities Act of 1933, the Securities Exchange Act of 1934, and the Investment Company Act of 1940. Such amendments, as the CRS observed, are necessary for 403(b) plans to participate in CITs.
The preamble to the Retirement Fairness for Charities and Educational Institutions Act explains the rationale behind efforts to address that circumstance:
“There are close similarities between 403(b) plans and 401(k) plans, except for the fact that 403(b) plans may only be maintained by nonprofit charities or public educational institutions. While 403(b) plans were historically considered retail arrangements directly marketed to individual employees, these plans have shifted to employerprovided arrangements comparable to 401(k) plans. Unfortunately,
outdated restrictions in the Internal Revenue Code and federal securities laws prohibit 403(b) plans from having access to the same low-cost investments as 401(k) plans.”
Hill activity to address that ensued.
Rep. Frank Lucas (R-Okla.) had introduced the Retirement Fairness for Charities and Educational Institutions Act on May 2, 2023. It called for the Securities Exchange Act of 1934 to be amended to allow 403(b)s to invest in CITs. It would have permitted 403(b) plans to invest in non-registered variable annuities. The House
Financial Services Committee reported the measure to the House on Dec. 12, 2023, but it went no further than that.
At the same time Lucas’ bill was working its way to the committee and staying put for most of 2023, another bill that Rep. Patrick McHenry introduced on April 24 of that year was working its way through Congress as well — H.R. 2799, the Expanding Access to Capital Act of 2023.
That measure didn’t start as a vehicle to expand 403(b) investments to include CITs. It sought to reduce various securities regulations for certain companies, brokers, and
advisors, and to enable more investors to invest in specified types of ventures. But eventually, the Retirement Fairness for Charities and Educational Institutions Act, an amendment to H.R. 2799, was introduced. That amendment sought to amend federal securities laws to allow 403(b) plans to invest in CITs and insurance contracts in which comparable retirement plans such as 401(k)s could invest. The House passed that amendment by a wide margin, 301-125, on March 7, 2024; the House then passed the full H.R. 2799, 212-205.
The bill may have passed the House, but after it was referred to the Senate four days later, it took a nap and did not progress further.
Legislation that would have allowed 403(b)s to invest in CITs
appeared in the congressional hopper again early in 2025. Sen. Katie Britt (R-Ala.) introduced S. 424, the Retirement Fairness for Charities and Educational Institutions Act, on Feb. 5, 2025. This bill, like its predecessors, would allow 403(b) plans to include CITs in their investment menus.
On the other side of the Capitol Building, Reps. Frank Lucas (R-Okla.), Josh Gottheimer (D-N.J.), Bill Foster (D-Ill.), and Andy Barr (R-Ky.) introduced the House version (H.R. 1013) on the same day. Their bill was referred to the House Financial Services Committee.
“ARA fully supports this legislation that will boost the retirement savings of hard-working employees at hospitals, universities, and other nonprofit organizations,” ARA CEO Brian Graff said. “Under the bill, 15
million workers at these organizations throughout the country will now have access in their retirement plan—called a 403(b) plan—to the same lowercost investments that are available to 401(k) plan participants.”
So what is the status of those two bills? S. 424 was immediately referred to the Senate Committee on Banking, Housing and Urban Affairs as soon as it was introduced. And there it has stayed. H.R. 1013 was referred to the House Committee on Financial Services; on May 20, 2025, the committee passed it in a 43-8 vote. Six months later, the committee reported it to the full House. The chamber has not yet acted on it.
While the House Committee on Financial Services was preparing to vote on H.R. 1013, Rep. Ann Wagner (R-Mo.) introduced H.R. 3383, the
“BY MODERNIZING THESE RULES, THE INVEST ACT WILL REDUCE COSTS, IMPROVE DIVERSIFICATION, AND ENHANCE FLEXIBILITY IN ASSET SELECTION, ALL WHILE MAINTAINING STRONG REGULATORY OVERSIGHT AND FIDUCIARY SAFEGUARDS.”
Incentivizing New Ventures and Economic Strength Through Capital Formation Act of 2025, or INVEST Act.
Section 202 of that bill would align the investments 403(b) plans, church plans, and governmental plans described in Section 3(a)(2)(C) of the Securities Act of 1933 can hold with the broader range of investments available to 401(k)s.
In a letter to Speaker of the House Mike Johnson (R-La.), House Majority Leader Steve Scalise (RLa.), Majority Whip Tom Emmer (R-Minn.), House Minority Leader Hakim Jeffries (D-N.Y.), and Minority Whip Katherine Clark (D-Mass.), American Retirement Association Executive Director and CEO Brian Graff expressed strong support for Section 202 of the INVEST Act.
“This critical provision will enhance retirement security for American workers such as public school teachers, charity workers, and other retirement savers who wish to invest in collective investment trusts (CITs) under their 403(b) plans, a longstanding option already available to private-sector employees through 401(k) plans,” wrote Graff.
“The regulatory distinction between 403(b) and 401(k) plans,” wrote Graff, “needlessly restricts investment choices for public school teachers, charity workers, and other nonprofit employees.” He also noted that CITs would expand flexibility in investment strategies, which he said would make it possible for retirement
savers to “diversify their savings across a broader range of securities.”
“By modernizing these rules, the INVEST Act will reduce costs, improve diversification, and enhance flexibility in asset selection, all while maintaining strong regulatory oversight and fiduciary safeguards,” Graff told the legislators.
The House passed the bill on Dec. 11, 2025, in a 302-123 vote. It was sent to the Senate and was referred to the Committee on Banking, Housing, and Urban Affairs.
THE INDUSTRY WEIGHS IN
Leaders of a variety of companies, associations, and organizations, as well as nonprofit organizations and industry groups, have called on leadership of both chambers of Congress to express support for legislation that would allow plan sponsors of 403(b)s to include CITs in their investment lineups.
In a Dec. 9, 2025 letter, corporate and organization leaders wrote to Senate Banking, Housing, and Urban Affairs Committee Chairman Tim Scott (R-S.C.) and ranking member Elizabeth Warren (D-Mass.) to express support for “providing parity with other retirement savings arrangements, including 401(k) plans, that already have access to low-cost collective investment trusts (CITs) and non-registered insurance company separate accounts.”
Leaders of the National Association of Insurance and Financial Advisors, the Investment
Company Institute, The SPARK Institute, Mercer, T. Rowe Price, State Street Investment Management, The Vanguard Group, Inc. were among the signatories to a July 13 letter to Capitol Hill.
And the National Association of Christian Lawmakers (NACL) in early June approved a resolution urging President Trump, the Securities and Exchange Commission (SEC) and Congress to take immediate action to ensure “retirement fairness for pastors, faith-based workers, nonprofit employees, educators, and other public-service professionals.”
The resolution, which passed at the NACL’s most recent meeting on June 6, highlights what it describes as a “longstanding inequity” affecting approximately 14.5 million Americans who rely on 403(b) retirement plans.
It notes that 403(b) plans collectively hold approximately $1.5 trillion in retirement assets and serve as the primary retirement savings vehicle for these faith-based workers, but that higher fees and limited investment options result in reduced retirement savings over time, with studies indicating that workers may lose thousands of dollars in retirement wealth over the course of their careers.
The NACL resolution urges the SEC to use its existing authority to permit eligible 403(b) plans to invest in CITs and calls on Congress to enact any necessary statutory reforms to eliminate remaining legal and regulatory obstacles. PC
The firms that will lead the next growth cycle in retirement plan administration are unlikely to be those with the newest software alone. By
In the 2025 Spring issue of Plan Consultant, we explored the pervasive operational friction plaguing modern Third-Party Administrators (TPAs), “Winning the Billing Battle,” and explored how firms addressed challenges from fragmented legacy platforms to the administrative challenges of manual invoicing.
Historically, the industry has treated billing as an isolated, laborintensive chore rather than a core component of firm workflow.
Driven by pricing compression and the market perception of plan administration as a commodity, many firms are converging on the concept that the ultimate weapon in this battle isn’t a better spreadsheet or an isolated tracking tool but rather moving towards system connectivity with the goal of full system integration.
For many Third-Party Administration (TPA) firms, billing is one of the more operationally complex functions within the organization.
Unlike many professional service firms that invoice standardized services or hourly time, TPAs administer retirement plans with highly customized pricing arrangements that often evolve throughout the client relationship. Participant-based fees, recurring
Travis P. Jack
administration, consulting engagements, plan amendments, distributions, revenue-sharing offsets, and project work all influence what ultimately appears on a client’s invoice.
Billing is no longer simply an accounting exercise. It has become the operational intersection of sales, client service, compliance, finance, and technology.
Many firms have improved portions of the billing process by implementing prospective billing, strengthening communication between operations and accounting, expanding electronic payment options, and documenting internal procedures.
Yet, conversations across the industry suggest that billing remains one of the few operational processes that touch nearly every department while relying heavily on manual coordination. Increasingly, the discussion has shifted from improving the invoice process itself to improving the operational systems and associated software that produce it.
Billing begins long before an invoice is generated. Every proposal establishes pricing rules that must follow the client throughout the relationship. One client may be billed annually, another quarterly, another
by participant count, while others include consulting retainers, assetbased fees, revenue-sharing offsets, or project-based work. Multiple plans may be consolidated into one invoice or billed separately.
The operational challenge is ensuring those pricing decisions remain accurate as the client moves from sales to onboarding, administration, compliance, accounting, and collections. Every manual handoff introduces opportunities for inconsistent fee schedules, missed billable work, and invoice adjustments.
Most major software providers in the Third-Party Administrator (TPA) software ecosystem have been rapidly innovating in the client experience, secure data exchange, tracking, and the automation of common TPA tasks.
They have been bridging gaps in functionality by building interfaces (APIs) and partnering with vendors in related spaces. Many of the development cycles and releases have focused on data automation for operational functions, such as payroll integrations and automated workflows, to streamline and make the census data collection process more efficient.
“RATHER THAN REQUIRING WHOLESALE CONVERSION, FIRMS CAN BEGIN WITH THE FUNCTIONALITY CURRENTLY CREATING THE GREATEST OPERATIONAL PAIN POINT.”
Often, billing is not included in the main software functionality.
Third-party API connectors or middleware can help “bridge” data gaps, utilizing integration platforms like MindCloud, Portable, or Zapier, which are commonly used to push data to firm accounting and billing software. A new market entrant, P4 Technologies, initially developed for internal use at 401KInABox, is a fully integrated technology solution with a billing module as a focal point, connecting to the operational and task workflows of the practice management modules.
Where the new entrant P4 seems to excel is the automation of revenuesharing allocations to the client invoice level. Billing remains one of the largest administrative burdens in the TPA industry. Recordkeepers distribute reports in different formats, with varying payment schedules and terminology. Accounting teams spend considerable time matching plans, reconciling files, applying offsets, and maintaining accurate client balances.
Modern billing platforms are beginning to automate much of this process. Platforms such as P4 illustrate how imported recordkeeper files can be matched using contract identifiers, revenue-share credits automatically categorized, and offsets applied directly to client invoices. Rather than creating another spreadsheet process, the system becomes the reconciliation engine itself.
Beyond reducing administrative effort, this automation provides
better audit trails, improves cashflow visibility, and gives leadership a clearer understanding of gross revenue, offsets, and realized collections.
Historically, many firms have managed invoicing, billing, and collections as disparate, siloed functions — utilizing a fragmented patchwork of emails, static PDFs, and disconnected accounting software.
In contrast, modern integrated platforms like P4 Technologies establish this entire lifecycle during the initial plan setup. By converging automated communications, clientfacing portals, and frictionless electronic payment systems into a single ecosystem, firms can achieve real-time accounting visibility within a unified operational workflow.
Collections no longer begin when an invoice becomes overdue. They begin during the sales process through clear engagement letters, transparent pricing, consistent billing schedules, and well-defined client expectations.
Technology also plays a growing role. Clients increasingly expect online portals that allow them to review invoices, pay electronically via ACH or credit card, access prior invoices, and receive automatic payment confirmations.
Automated reminders reduce manual follow-up while improving the overall client experience. The goal
is to make paying an invoice as simple and frictionless as all other digital interaction clients experience today.
TECHNOLOGY SHOULD FIT THE FIRM, NOT THE OTHER WAY AROUND
One of the more interesting developments discussed during recent conversations with technology providers was the industry’s movement toward modular implementation. Historically, firms were expected to replace their entire technology ecosystem at once. Today, both current industry leaders and new platforms such as P4 Technologies are taking a different, more modular approach.
Even though P4 has a fully integrated ecosystem, its modularity allows it to fill gaps in certain areas and complement other systems.
Rather than requiring wholesale conversion, firms can begin with the functionality currently creating the greatest operational pain point. Some organizations start with billing and payment processing. Others implement CRM, workflow management, reporting, or client portals first. Additional modules can then be added over time.
This philosophy significantly reduces implementation risk while allowing firms to modernize at a pace consistent with their operational readiness. Just as important, APIdriven integrations allow firms to preserve investments in accounting software and other business
applications instead of forcing a single-vendor ecosystem.
AVAILABILITY TO DRIVE MANAGEMENT DECISION VELOCITY
Dashboards are highly specific to a particular organization’s needs and software capabilities; however, they are likely to include billing, revenue, and collection data as key operational metrics, helping to consolidate real-time data and speed up strategic decisionmaking for the firm’s executive team.
Many of the available providers don’t have a fully comprehensive dashboard that includes billing-related metrics; firms may consider alternatives such as integrations with Custom Power BI dashboards or other options that are growing in popularity.
Many software options can integrate directly with an API or may require robotic process automation (RPA) to bridge integration gaps when aggregating operational data.
Possible related metrics for monitoring operational progress related to the billing process:
• Total revenue billed
• Revenue collected
• Outstanding receivables
• Daily collections
• Aging reports
• Revenue by service category
• Cash flow trends
Modern platforms are increasingly making progress in this important area. They are closing in on consolidating firms’ operational data into real-time in application dashboards that show collections, aging, recurring revenue, ad hoc fees, payment activity, and outstanding balances.
Some providers are even exploring AI-powered reporting, in which managers can query billing information in natural language rather than building reports manually. The objective is to transform billing data into part of the firm’s overall operational intelligence, alongside other key operational metrics.
Billing will always involve invoices, but the industry’s greatest opportunity lies in improving everything that happens before the invoice is created.
Technology alone will not solve billing challenges, yet thoughtfully implemented technology can eliminate manual handoffs, reduce lost revenue opportunities by reconciling operational activities and time spent versus what was billed, automate reconciliation, improve collections, and provide leadership with better information.
The firms that will lead the next growth cycle in retirement plan administration are unlikely to be those with the newest software alone. They will be the organizations that combine disciplined operational process improvement with flexible technology, using billing not simply to collect revenue but to better understand and manage the health of their business. PC
An SEC staff statement clarifies securities law treatment of pooled employer plans — but leaves questions about MEPs.
By Kelsey Mayo
The Securities and Exchange Commission recently issued a staff statement addressing two securities law questions affecting multiple employer plans (MEPs).
Much of the discussion surrounding the statement has focused on its impact on collective investment trusts (CITs), but the impact of the guidance is broader than that. It addresses both the application of Section 3(c)(11) of the Investment Company Act of 1940 and Rule 180 under the Securities Act of 1933 to pooled employer plans (PEPs). It raises questions regarding MEPs that are not PEPs.
The guidance is significant because it addresses a recurring problem in retirement policy: securities law is often an afterthought when Congress acts on retirement plan matters. When Congress created PEPs under the SECURE Act, it directed that PEPs be treated as single-employer plans for many purposes. Still, it did not make corresponding changes to the federal securities laws.
That omission raised important questions about whether the securities law rules that historically applied to MEPs would apply to PEPs in the same way.
The SEC staff statement explains how the Division intends
to apply those existing securities law provisions to PEPs. In doing so, it provides important regulatory certainty while also highlighting a key limitation: the analysis is expressly limited to PEPs and does not extend to all types of MEPs.
The Investment Company Act of 1940 regulates entities engaged primarily in investing, reinvesting, and trading securities.
At a high level, it is designed to regulate pooled investment vehicles—such as mutual funds—by requiring registration and imposing rules governing governance, custody of assets, disclosure, affiliated transactions, and ongoing compliance.
Retirement plans are certainly investment and trading vehicles, and if a plan were treated as an “investment company,” it would have to comply with the complex securities law regime. Employer-sponsored retirement plans historically have operated outside that framework by relying on statutory exclusions, including Section 3(c)(11) of that Act, which excludes certain employee benefit plan trusts from the definition of an “investment company.”
The SEC staff has interpreted Section 3(c)(11) as excluding plan trusts that are either for employees of a single employer; for employees of employers so closely
related as to be regarded as a single employer (e.g., a parent and its subsidiaries); or established and controlled by employers and/or a union representing the employees of such employers.
Traditional single-employer retirement plans fit comfortably within that framework. Multiple employer plans do not. In its 1983 E.W. Scripps Company SEC staff no-action letter, the staff took the position that a trust covering employees of various related employers could rely on the Section 3(c)(11) exclusion, but a trust covering employees of various unrelated employers (e.g., a MEP) could not.
The SECURE Act introduced an additional layer of complexity by creating the PEP. PEPs are a special type of MEP that meets certain requirements.
While Congress directed that PEPs be treated as a single employer plan for specified purposes under ERISA and the Internal Revenue Code, it did not amend Section 3(c)(11) or otherwise address the Investment Company Act.
As a result, an interpretive question arose—are PEPs treated as a single employer plan or a multiple employer plan for purposes of the definition of “investment company”?
The SEC staff resolved this issue in the recent staff statement. The staff concluded that it would not object
if an ERISA-covered pooled employer plan relies on the Section 3(c)(11) exclusion, provided the applicable statutory requirements are satisfied.
In reaching that conclusion, the staff relied on Congress’s decision to treat PEPs as single employer plans under the retirement laws and effectively harmonized the securities law analysis with that statutory framework.
Importantly, the staff’s analysis is limited to PEPs. It does not conclude that every MEP may rely on the same reasoning. Therefore, MEPs that are not PEPs are left in the same position as they were—they must conclude they are not investment companies under the applicable definition or comply with the comprehensive securities regime.
The staff statement also addressed a similar question related to an exemption under the Securities Act of 1933.
The Securities Act of 1933 generally governs the offer and sale of securities to investors. Its core purpose is to require securities offered to the public to be registered with the SEC unless an exemption applies. Covered securities must also comply with the accompanying regulatory regime, which includes investor disclosures.
Collective investment trusts (CITs) holding plan assets generally do not register as securities by relying on an exemption in Section 3(a)(2) of that Act for CITs holding qualified plan assets.
However, there is a relic of retirement plans past in that statute: CITs that accept assets from plans covering “selfemployed individuals” cannot rely on the exemption in Section 3(a)(2).
These old “Keogh” plans generally ceased to exist decades ago, but the statute has never been updated to reflect the modern retirement plan universe. Instead, the SEC issued Rule 180, which provides an exemption from Securities Act registration for CITs that accept assets from plans covering self-employed individuals.
However, like Section 3(c)(11), Rule 180 was drafted around a traditional employer-sponsored plan model. The Rule 180 exemption applies only to plans that cover “employees of a single employer or employees of interrelated partnerships.” In addition, the CIT issuer must have reasonable grounds for believing that the employer is capable of evaluating the investment and adequately representing participant interests.
MEPs again do not fit that framework neatly. A MEP may include numerous unrelated employers, each with varying degrees of financial sophistication.
Before the SEC staff statement, CIT providers responded to this uncertainty in different ways. Many CITs elected not to permit investments by MEPs and PEPs, thereby allowing self-employed individuals to participate.
As PEPs grew in popularity, this limitation became more and more troublesome, eventually resulting in a request for guidance from the SEC.
The SEC staff statement provides important clarity for PEPs. It concludes that a CIT may rely on Rule 180 even if it accepts assets from an ERISA-covered PEP that covers selfemployed individuals.
The staff further concludes that the PEP’s pooled plan provider, rather than each participating employer, may satisfy Rule 180’s sophistication requirement.
As with the Section 3(c)(11) analysis, however, the guidance is expressly limited to PEPs. MEPs that don’t meet the PEP requirements cannot rely on this statement when investing in a CIT.
While the statement is extremely significant for PEPs, its limitation to only PEPs has very significant implications.
Throughout the staff statement, the SEC consistently referred to PEPs. It did not refer more broadly to MEPs. As noted above, that distinction is meaningful because not every MEP is a PEP. That may be by intentional choice or a legacy design for plans established before PEPs were created.
The staff statement made clear that its conclusions were grounded in the congressional intent behind the creation of PEPs. The statement repeatedly refers to Congress’s intent that PEPs be treated as single-employer plans and to the fact that they were created to remove legal barriers preventing the broader use of MEPs.
As a result, the rationale for the staff statement does not neatly apply to MEPs that are not PEPs—a conclusion that was confirmed in informal conversations with SEC staff after the staff statement was released.
The SEC staff statement was helpful guidance for PEPs and a pragmatic response to how older securities-law provisions should apply to newer retirement plan structures. By not addressing securities laws when SECURE was enacted, Congress created a gap that could undermine the intent and effectiveness of PEPs.
The SEC staff statement helps close that gap for PEPs by aligning the securities-law treatment of PEPs with Congress’s retirement-policy objectives.
But the statement also underscores the limits of administrative interpretation. Because the staff grounded its conclusions in the SECURE Act’s specific treatment of PEPs as single-employer plans, the same reasoning does not automatically extend to MEPs that are not PEPs.
Those plans remain subject to older securities-law frameworks that were not drafted with modern MEP structures in mind.
So, while the guidance provides welcome certainty for PEPs and should make CIT access more practical for those arrangements, it also means that organizations working with non-PEP MEPs may need to re-evaluate their compliance position. PC
How do they effectively overlap when providing employer-based retirement plan coverage?
By John Iekel
Imagine that providing and running a retirement plan is a Venn Diagram. On one side are plan administrators, and on the other are plan sponsors.
Plenty of functions are unique to each. But then there’s that intersection in the middle, that shared mix of interests and duties.
Perhaps it’s a marriage of convenience. Maybe it’s synergy. It could be an intersection of shared goals, a kind of harmonic effort with a common purpose.
But whatever it is, there are broad — and sometimes more specific — functions and responsibilities they both fulfill to satisfy regulatory and fiduciary duties and to reflect an ultimate commitment to the well-being of the business and plan participants.
So, what’s in that intersection between those two key players in providing employer-based retirement coverage?
The federal government and its agencies are equal opportunity in their compliance expectations. Some of those expectations are unique to parties that perform specific functions. Still, in the end, certain information simply must be provided concerning a retirement plan and the business through which it is offered. It almost
doesn’t matter who the source of that raw data and final information is.
For instance, plan administrators are asked to voluntarily provide information so the DOL can obtain the data it needs, panelists noted in an August 2025 panel discussion held by the Berwyn Group. But while some of those requests may be voluntary, panelists indicated that in the end they may not really be — they observed that the DOL can audit plan sponsors, which suggests that compliance is in the best interest of both parties, voluntary or not.
So it is that one of the panelists, National Coordinating Committee for Multiemployer Plans’ Director of Research and Education Mariah Becker, said of the decision regarding whether or not to voluntarily disclose information, “On its face, this is a thing that would be very helpful.”
Becker added that the request for information — for instance, from the Pension Benefit Guaranty Corporation (PBGC), which issues demands to plan administrators and plan sponsors in its efforts to serve and protect retirement plan participants — relates to fiduciary concerns about protecting participant privacy and data.
And, consistent with a shared need to fulfill fiduciary duties, Becker indicated that both plan
administrators and plan sponsors express concerns about those duties.
“I’m hearing strong concerns regarding security and how data is used,” she said.
Pentegra further found that plan sponsors that sought and secured fiduciary support were more confident that their retirement plan is achieving successful outcomes, with more than 50% agreeing that “because we chose the right 3(16) and 3(38) fiduciaries, we are confident in our plan design and the focus on participant outcomes.”
Finch, a firm that seeks to support the infrastructure of the employment sector, suggests that plan administrators and plan sponsors share the need to comply with the provisions of SECURE 2.0.
To be more exact, they argue that the law’s focus on participant eligibility and plan participation will make eligibility checks “more critical and complex” and will prompt a rethinking of how compliance is handled. And this, they continue, will result in increased data sharing between sponsors and administrators.
Plan administrators and plan sponsors also share a need to communicate effectively. October
Three argued that effective communication is not only important for service providers and the plan sponsors with which they work — ultimately, it’s also important for plan sponsors and participants in the plans they sponsor.
In addition, October Three argues that effective communication is part of staying in compliance with applicable laws and regulations.
Cynthia Ventura, the Director of Engagement Consulting for Fidelity Investments, in an interview with The Cerrado Group’s Executive Director Theresa Conti, said that communication between service providers and plan sponsors comes in several forms and that it can focus on means to gather key information that would help in running the plan and making sure it serves participants well.
For instance, it can include (1) online tools and data that complement the data the recordkeeper already has and (2) personal campaigns that have a frequent message based on age or behaviors.
Ventura also suggested that service providers and plan sponsors set up an annual calendar to facilitate interaction and communication meetings.
That calendar, she said, should do more than simply show due dates of plan-related events; it should be complemented with communication campaigns.
Ventura also told Conti that correct data and the ability of the TPA, recordkeeper, and plan sponsor to work together will improve communication and plan administration.
She argued that plan sponsors and retirement plan professionals should work together to provide participants
with information on financial wellness.
This, she said, should include topics relevant to their lives, such as budgeting and life events that may pose some challenges. Further, calendars should include a quarterly touchpoint for participants, with monthly communications about events that concern them, such as retirement.
In a 2024 study conducted by Pentegra, more than 50% of plan sponsors indicated that they turn to a professional fiduciary to outsource plan governance and oversight.
When asked what resources they used to help manage fiduciary responsibility for their retirement plan, more than 6 in 10 plan sponsors said they work with a professional investment advisor and 3(16) administrative fiduciary; among the reasons is that it provides an objective check on decision-making.
And they appreciate what those fiduciaries do.
The results of Pentegra’s study suggest that plan sponsors are glad they enlisted other professionals to help them in fulfilling their fiduciary duties.
Pentegra reported that plan sponsors that use outsourced
fiduciaries highly value the service as an important backstop and that such assistance provides sponsors “with greater peace of mind and a compliant, well-run plan.”
The relationship between the TPA and the plan sponsor is valuable, Ventura also told Conti. She stressed that a third-party administrator (TPA) can help a plan sponsor with participation information and plan specifications — especially safe harbor and employer non-elective contributions.
Ventura added that TPAs typically know more about what is going on and how a recordkeeper could help participants, and that if a TPA functions as a 3(16), that would further heighten the connection with a plan sponsor.
Finch further argues that TPAs that offer “significantly better service to their clients will win the long race of new customer acquisition and increased customer loyalty.”
And they add that this will aid in reaching the ultimate goal for which a retirement plan is established in the first place — helping participants to build a financially secure retirement. PC
Its intuitive interface means users can simply log in, ask a question, and receive an answer (with citations included) within seconds. By John Sullivan
Rest in peace, generic internet search.
The American Society of Pension Professionals and Actuaries (ASPPA) launched Ask ERISA™ recently, its innovative and engaging research tool for advisors, plan consultants, and home office teams.
Powered by the organization’s highly regarded and widely used reference resource, the ERISA Outline Book (EOB), users “can ask a question in plain English and immediately receive a clear, cited answer in seconds,” according to Ask ERISA developers.
Every answer traces back to EOB source material, which can be verified before going deeper with a particular ERISA-focused topic.
“ASPPA — and the American Retirement Association (ARA) as a whole — sits atop a significant amount of technical
knowledge, and the EOB is its peak,” Matt Scanlon, ARA’s Chief Marketing & Communications Officer and Ask ERISA’s project lead, explained. “It contains 14,000 pages of intensely technical ERISA knowledge and requires an intensely technical person to navigate it successfully, which is often a specialty position at a firm. It’s something Ask ERISA now democratizes.”
Employing closed-corpus large language model (LLM) technology, Ask ERISA users can ask a retirement plan question and receive an answer in laypeople’s terms drawn exclusively from the EOB, with citations.
“What differentiates this tool from others online is that it only draws from one source; it doesn’t draw from the internet,” Scanlon said. “It doesn’t try to make up an answer that will please you. If you ask it, like, who the 40th president of the United States was, it has no idea. The only thing that it knows
about and is focused on is ERISA knowledge that’s contained in the EOB.”
He added that if the answer is unsatisfactory or still too technical, users can prompt Ask ERISA to rephrase it in a way that’s easier to understand.
Asked about the reason for releasing Ask ERISA, and specifically why now, Scanlon mentioned the rapid advancement in language models in the two years since the project’s inception.
“At that time, you could ask a model like ChatGPT a retirement plan question and often get an answer that was laughably bad and obviously made up,” he said. “Those models have improved significantly since, and you can get relatively high-quality answers, but you don’t know where they came from and if they’re verified.”
Ask ERISA provides high-quality, accurate answers with “baked-in EOB citations” on which users can click to verify and reference in their work.
“The homework is already done,” Scanlon emphasized. “Typically, if you have an answer but you don’t know its provenance, you’re back to square one and still have a research problem to solve. Ask ERISA answers the question and solves the research problem at the same time.”
Its intuitive interface means users simply log in, ask a question, and receive an answer with citations. Every question and resulting conversation is stored in an audit trail, making any follow-up questions much easier to ask. They can also
be sorted, labeled, and renamed into timestamped project folders, which are searchable.
Not that developing any part of Ask ERISA was easy. Scanlon noted that, while comprehensive, the EOB is “long and complicated.”
“Being able to compose accurate answers out of all that information is a real challenge on two fronts,” he said. “In the larger scope of these LLM tools, platforms like ChatGPT must read billions of pages, so 14,000 pages is a drop in the bucket. But on the other end of the spectrum, for Ask ERISA, the EOB is the only world it knows.
Getting it to retrieve fluent and accurate answers within that defined scope of knowledge was initially difficult, he said, but the team really turned a corner in the past 12 months.
Beta testing among TPAs, compliance professionals, and other industry experts yielded an A+, confirming its July 30th release date.
Scanlon concluded by recognizing those who helped in getting Ask ERISA to where it is today.
“Our Chief Information Officer, Darren Bailey, came on board 10 months ago and did an amazing job helping us to get it off the ground,” he said. “Technically, he’s just a wizard. Also, I’d like to thank the ASPPA Leadership Council and the ARA board for supporting us in the project. They trusted us to develop something useful, and that trust is going to pay off.”
Retirement security is not only about individual responsibility, but also access, opportunity, education, and support. By Plan Consultant Staff
It can be daunting for almost anyone to build a retirement without support, but women face a steeper climb. Accordingly, the American Retirement Association (ARA) set the first Women’s Retirement Security Day for July 14 this year and the second Tuesday of every subsequent July.
So, what is Women’s Retirement Security Day? The quick answer is that it’s a National Day of Action built around a question most women have wrestled with largely on their own: how to retire with enough money to last.
There are a variety of factors behind the greater effort required for women to prepare for a financially secure retirement.
Pay gap. Women who worked full-time, year-round earned about 81 cents for every dollar men earned in 2024. For good measure, that ratio has widened for two straight years, down from 83 cents. That figure falls still further to 76-78 cents when part-time and seasonal workers are included in the calculations.
And the gap is more pronounced still for women of color. Data the Census Bureau prepared in 2024, analyzed by Equal Rights Advocates, shows what they earn for every dollar paid to a white, non-Hispanic man working full-time:
• Asian American women: 96 cents
• Native Hawaiian and Pacific Islander women: 67 cents.
• Black women: 65 cents
• Latina women: 58 cents
• Native American women: 58 cents
Pay gap trends. The trajectory doesn’t suggest improvement in the pay gap anytime soon. In 2024, men’s median full-time earnings rose 3.7% to $71,090, while those of women stayed essentially flat at $57,520.
Caregiving. Interrupted careers and gaps in work to care for others are other factors that affect women’s retirement security. Women leave paid work to raise children or care for aging relatives far more often than men do, spending about 12 years out of the workforce over a lifetime. One analysis says that women lose $58,000 in retirement income across employer plans and Social Security.
Savings. Women are 15% less likely than men to believe their savings are on track, the campaign’s research found. Their median 401(k) balance runs 65% below men’s, $21,638 against $62,040, and they contribute 43% less each year.
Longevity. Women’s lifespans are longer than those of men, on average — 81 and 76, respectively. This accentuates the consequences of the disparity in pay and savings.
Big implications. The pay gap is noteworthy, but it means more than disproportionate paychecks. Why? Because pay levels, in turn, affect the retirement plans that draw on compensation, as well as Social Security accounts. And interruptions in work history and greater longevity heighten the disadvantages women face in building a financially secure retirement.
“Women continue to face unique challenges, such as longer life expectancies, career interruptions and wage gaps,” said Erika Goodwin, ARA’s Director of Advocacy Engagement.
WHY DID THE ARA CREATE WOMEN’S RETIREMENT SECURITY DAY?
“Women’s Retirement Security Day was created to acknowledge these challenges and elevate solutions, resources, and partnerships that can help close the gap,” said Goodwin, adding, “It also aims to spark more everyday conversations about retirement — building awareness, encouraging action, and helping more women achieve financial security.
She continued, “Women’s Retirement Security Day is designed to reach the public, especially women, by informing, engaging, and empowering them to take steps toward a more secure retirement.”
“At the same time, it brings in the broader community that supports those outcomes, including employers, financial professionals, industry leaders, and nonprofit organizations that provide trusted resources and actionable guidance,” she continued, adding, “Because improving retirement security doesn’t happen in isolation, this day is grounded in the belief that it takes a community working together to educate, spark conversation, and drive meaningful action to help more women achieve financial security.”
The first Women’s Retirement Security Day was July 14, 2026. How will the American Retirement Association celebrate it?
The ARA marked Women’s Retirement Security Day in collaboration with industry organizations and partners through a coordinated set of activities designed to raise awareness, engage stakeholders, and highlight actionable resources.
Leading up to the day, the ARA provided a suite of materials to support partner engagement, including educational resources and tools to help organizations host their own activations, such as financial literacy sessions or community conversations. Those resources included materials from ARA organizations such as the Plan Sponsor Council of America and the National Taxdeferred Savings Association, as well as from industry partners. Organizations and individuals could access a list of resources through ARA’s website and tailor their participation to align with their missions and audiences.
On the day itself, the ARA, together with partner organizations, highlighted storytelling content that brings real experiences to life, reinforcing that it is a shared effort to elevate solutions and resources, not a single organization acting alone.
Women’s retirement security is, of course, more than one day. And the effort to raise awareness of it and boost its profile is consistent with the mission of the organization that fostered it.
Goodwin outlined how it fits in with the ARA. “The American Retirement Association’s mission is to ensure every American can achieve a secure retirement, and we have long championed policies that expand access and improve outcomes,” she said.
Goodwin went deeper and offered some personal insight into the day and the significance of the reasons the ARA gave for creating it.
During my tenure at the American Retirement Association, I’ve met advisors, consultants, third-party administrators, attorneys, plan sponsors, business leaders, and educators who all work towards the goal of helping working Americans retire with dignity.
Having initially worked at ARA as a conference planner, I have been “in the room,” staffed many continuing education sessions, and put what I heard in those rooms into action. I know that through my workplace retirement plan, I have access to a retirement plan advisor who helps me to visualize what is possible and make choices and actions that will get me closer to my goal of a fully funded retirement account.
Growing up, retirement wasn’t something I heard discussed regularly. The women and men I’ve met through my work at ARA have become informal mentors and role models. From them, I’ve learned how retirement plans work, why saving early matters, that women can be leaders in business and finance, and that retirement is a goal even I, who started saving later in my career, can envision and plan for. They helped me believe retirement security is attainable. Looking back, I realize these women (and men) formed a retirement community around me.
“At its core, this initiative is about bringing people together. It provides a platform for industry leaders, policymakers, nonprofits, and individuals to collaborate, share ideas, and drive practical solutions,” Goodwin said, continuing, “Together, these efforts are designed to spark meaningful dialogue, encourage practical action, and help more women take steps toward a secure retirement.”
“Women’s retirement journeys are rarely identical,” said Goodwin. “Women face unique retirement challenges, including lower lifetime earnings, caregiving interruptions, longer life expectancy, limited access to workplace retirement plans, and competing financial priorities.
“No one gets to the goal of retirement alone,” she concluded. “But some things remain consistent. People matter. The conversations we have. The examples we see. The encouragement we receive. Retirement security is not built in isolation. Retirement security is not just about individual responsibility. It is also about access, opportunity, education, and support.”