The Private Advantage
Why the Companies With the Most Freedom to Think Differently May Be the Ones Best Positioned to Shape What Comes Next
There is a moment in the life of most ambitious companies when the pressure to perform for the quarter collides with the instinct to build something lasting. For most publicly traded firms, the quarter wins. Every time.
Dr. Violina Rindova has spent decades studying the exceptions. The companies that play a longer game. The founders who act on conviction before the data confirms them. The organizations that discover not just better ways to compete, but entirely new arenas in which to compete. And what she has found, consistently across her research, is that the firms with the most freedom to think this way tend to share one thing in common: they are private.
“Private firms can choose a strategic direction that reflects their subjective point of view,” says Rindova, Associate Dean for Research and PhD Program and Dean’s Leadership Circle Endowed Chair at UC Irvine’s Paul Merage School of Business. “They have more discretion in designing their processes and business models. That higher level of discretion
allows them to make more distinctive strategic choices, and distinctiveness is the central quality of great strategies.”
The observation sounds intuitive. But the implications, when you follow them through Rindova’s body of research, are anything but obvious.
The Problem with Playing to the Gallery
To understand why private status matters strategically, you have to understand the strategic constraints of public status.
Publicly traded companies are monitored and evaluated on a quarterly basis. Their runway for making large, bold bets is compressed. And the dynamics of analyst evaluations compound the problem: research has shown that when a new technology or business model disrupts an industry, analysts commend outside entrants who
adopt it — because that reads as a growth play — and penalize incumbents for similar moves. The reasoning? Incumbents risk cannibalizing their core market. Private companies escape this bind. They can act on their strategic judgments. They can pursue an unconventional direction before the market ratifies it. And in an era of technological disruption — when first-mover advantage belongs to whoever is willing to act ahead of complete information — that capacity is not a luxury. It is a strategic asset.
The examples are everywhere once you look for them. IKEA built an empire on a radically different conception of furniture retail. In addition to introducing a radically novel business model, it created a complex ownership structure of foundations and corporations, designed to maintain independence and long-term ownership. Patagonia enshrined its environmental values
into ownership structure itself. In 2022, founder Yvon Chouinard transferred 100% of the company’s voting stock to the Patagonia Purpose Trust (protecting values) and 100% of nonvoting stock to the Holdfast Collective (a nonprofit dedicated to fighting the climate crisis). Enterprise Rent-A-Car grew to capture half the U.S. rental car market before it ever opened an airport location — because its leadership believed in meeting customers where their problems actually occurred, not where the industry assumed they would go. “It acted on different beliefs,” Rindova says. “The entire industry was concentrated in airports. Enterprise was the only player to establish local presence for a very long time.”
Today Enterprise is the 7th largest private company in the U.S., with revenues of $39B for its 2025 fiscal year. To put its scale in perspective, its revenue is more than triple that of its largest publicly traded competitor, Avis Budget Group (~$11.4B).
The Science of Conviction
Rindova’s research is not simply an argument for the virtues of private ownership. It is a systematic investigation into the logics that allow companies to transform markets — and the conditions under which those logics can flourish.
Her landmark study of Italian design manufacturer Alessi, published in Administrative Science Quarterly, traces the company across three decades of strategic experimentation. Alessi began as a B2B manufacturer of steel serving tools for the restaurant and hotel industry — competent, profitable, and entirely unremarkable. In 1970, Alberto Alessi, the founder’s grandson, took over product development with a conviction that the company could be something else entirely: a producer of objects that were simultaneously industrial and artistic. Products that belonged in both a kitchen and a museum.
What followed was not a clean transformation. It was a series of experiments, failures, and progressively refined attempts to blend two worlds that are supposed to be apart — industrial manufacturing and cultural production.
“What I like about that story,” Rindova says, “is that you can see the progression. First, they try to enter an existing market — and they fail. Then they try to improve their position in their own market — which works, but it’s incremental, not gamechanging. And then they create a new market. That’s the gamechanging strategy.”
The first attempt nearly bankrupted the company. Alessi commissioned renowned sculptors, including Salvador Dalí, to design art multiples for mass production. The sculptors produced work that was incompatible with large-scale steel
manufacturing. Prototyping clogged the factory floor for two years. Sales suffered.
But Alberto Alessi did not abandon his conviction. He refined the strategy. He brought in industrial designers who could work within manufacturing constraints while still pushing aesthetic boundaries. He created new product categories — “applied art” — that gave critics and consumers a coherent way to understand what Alessi was building. By the close of the 20th century, more than 600 Alessi products had entered the permanent collections of museums around the world, while the company sustained revenue growth through economic downturns that flattened its competitors.
“What I like about that story,” Rindova says, “is that you can see the progression. First, they try to enter an existing market — and they fail. Then they try to improve their position in their own market — which works, but it’s incremental, not game-changing. And then they create a new market. That’s the game-changing strategy.”
The research shows that organizations can combine different industry logics purposefully to create new hybrid practices, and to conceive of new ways to serve markets. The key word is purposefully. Alessi did not stumble into its position. It developed what Rindova and her co-authors identify as “recombinant strategies” —
deliberate choices about how to take elements from different worlds and synthesize them into something new.
The insight travels far beyond kitchenware.
Acting on Conviction in an Age of Disruption
Rindova’s newer research extends this framework into contexts that feel urgently contemporary. A working paper currently under review at a top management journal, traces a German startup from its origins as a classroom idea to a position at the forefront of predictive maintenance in global railway transportation.
The company began with a conventional technology commercialization strategy. It had venture capital backing, proprietary technology, and a methodical approach: explore the landscape, evaluate the options, make a choice. Over the course of its development, it examined more than 100 potential
markets before pivoting to pursue what Rindova describes as “a big possibility” — reimagining the railway infrastructure maintenance to increase the reliability of railway transportation across Europe –where rail is both the primary and most sustainable mode of transit.
The parallels to Alessi are not coincidental. In both cases, a private company reached a juncture where the rational, data-driven path pointed one direction and conviction pointed another. In both cases, acting on conviction required tolerating ambiguity that public market structures would not have permitted.
“The freedom to experiment and the ability to act on conviction,” Rindova says, “is highly consistent with how we think about entrepreneurship. And in disrupted environments, all firm leaders need to be able to think like entrepreneurs and take entrepreneurial action — to adopt a novel set of practices, to address customers in new ways, to act
ahead of complete information. Taking that action ahead — how far ahead, and in what direction ahead — I think, that’s actually the critical set of strategic leadership competences in the world of disruption.”
Her broader research agenda on strategy under uncertainty reinforces the point. Rindova and her collaborator Luis Martins have argued that firms need what pragmatist philosopher John Dewey termed moral imagination — the ability to look at a situation and see how it could be different from what it is today — and that this imagination is cultivated from values and ideals, empathetic understanding of stakeholders, and pragmatic problem-solving. UC Irvine’s purpose, in this framing, is not a mission statement. It is a strategic orientation that shapes how a firm
sees the landscape of possibility.
Private firms, by the nature of their governance, are more able to operate from that orientation without having to defend it quarter by quarter.
What This Means for Companies in Orange County and Beyond
Southern California — and Orange County in particular — is home to one of the densest concentrations of private businesses in the country. Many are family-owned or founderled. Many operate in industries that are being reshaped by technological disruption. And many, Rindova suggests, may not be fully leveraging the strategic discretion they enjoy.
“To the degree that private businesses recognize the distinctive ways in which they can compete,
they are in a position to build different ecosystems, to tap into different resources, to have a purpose-driven approach — by which I don’t mean a particular social cause, but their unique understanding of what is possible in their industry,” she says.
“Recognizing that they have this latitude, it is important for them to consider how distinctiveness informs their strategic priorities.”
The challenge is that most private companies benchmark themselves against industry competitors — comparing on traditional economic drivers of performance — cost, differentiation, scale. They may not be thinking of their private status as a source of competitive advantage — the advantage of making strategic choices when you are not playing to the expectations of public markets.
The relationship with capital matters here too. Rindova points to companies like Cirque du Soleil, whose founder committed to remaining private specifically to preserve creative independence — and then partnered with private capital to scale globally on his own terms. Or Italian motorcycle maker Ducati, which before its acquisition by Audi, worked closely with private equity firms that specialized in consumer-centric businesses and understood the brand’s cultural logic. Private capital, she argues, can be a genuine strategic partner at the level of vision — not just a
source of growth financing.
“A distinctive point of view can hold a strong appeal for a variety of stakeholders,” Rindova adds. “Employees can be mobilized by distinctive values and purpose. Capital can be attracted to it. You can essentially tap corners of the market that are neglected.”
The Counterfactual
Rindova has one more example she mentions in conversation — one she traces back to her own doctoral research. Starbucks.
The company began with a founder’s deep belief that Americans would pay for a different kind of coffee experience. It defined a category before that category had a name. It went public in the early 1990s in what became one of the highest-grossing IPOs in 1992. And then, over time, it began accommodating Wall Street — replacing hand-crafted beverages with automated machines, optimizing for throughput, drifting away from the experience that had made it irreplaceable.
“They had to cut corners,” Rindova says. “They replaced baristas with automatic machines. And one after another, they lost what made them great in the first place.”
The Starbucks story is not an argument against going public. It is an illustration of the trade-off that public status imposes — and a reminder of what gets surrendered when a company stops acting on its
private beliefs, and starts performing to external expectations that may or may not reflect its unique strategy.
For the private businesses of Orange County and Southern California, the message is clarifying. The freedom to think differently, to hold a conviction, to build toward a possibility that the market hasn’t confirmed yet — that is not a liability to be managed until the IPO. It is, in the hands of strategists who understand it, one of the most
durable competitive advantages in a world of disruption.
Dr. Violina Rindova has spent a career studying the companies that understood this. She is now doing it from Irvine.
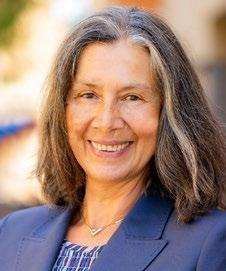
Violina Rindova is Associate Dean for Research and PhD Programs and Dean’s Leadership Circle Endowed Chair at UC Irvine’s Paul Merage School of Business. She has published over 70 academic articles in Administrative Science Quarterly, the Academy of Management Journal, Strategic Management Journal, and Strategy Science, among others, and has been covered by The Economist, The New York Times, and the Washington Post.
Violina Rindova
UC Irvine’s Merage School Launches Private Business Initiative
The Paul Merage School of Business at the University of California, Irvine announced the launch of the American Lending Center and Sunstone Private Business Initiative, a multi-year effort to strengthen the long-term success of privately held firms across Southern California and beyond. The initiative is made possible through a founding multi-year partnership commitment from American Lending Center (ALC) and Sunstone.
The only initiative of its kind on the West Coast housed within a business school, the American Lending Center and Sunstone Private Business Initiative brings together Merage School faculty expertise, graduate student talent, and industry partnerships to address the distinct challenges facing private businesses. The initiative will operate across three core areas: thought leadership, including an executive event series on the most pressing issues in private business; organizational capacity building, through faculty-guided student consulting and capstone projects; and leadership development, delivered via bespoke non-degree programs designed for executives at privately held firms.
“Privately held businesses are the backbone of regional economies, yet they’ve been underserved by academic institutions,” said Ian O. Williamson, Ph.D., Dean of the Paul Merage School of Business. “This initiative changes that. Thanks to the visionary support of American Lending Center and Sunstone, we are building a dedicated platform that will connect the intellectual resources of the Merage School directly to the needs of private business leaders. We are proud to launch this in partnership with organizations that share our commitment to the Southern California business community.”
The initiative will launch publicly with the Future of Private Business
event on May 6, 2026, a highprofile thought leadership gathering featuring a panel of senior private business leaders moderated by Dean Williamson. The event will include a VIP reception and a broader panel discussion open to founders, CEOs, and C-suite executives from firms ranging from $10 million to $1 billion in revenue.
Additional events and programming are planned across the full five-year platform.
“Privately held businesses are the backbone of regional economies, yet they’ve been underserved by academic institutions,” said Ian O. Williamson, Ph.D., Dean of the Paul Merage School of Business. “This initiative changes that. Thanks to the visionary support of American Lending Center and Sunstone, we are building a dedicated platform that will connect the intellectual resources of the Merage School directly to the needs of private business leaders. We are proud to launch this in partnership with organizations that share our commitment to the Southern California business community.”
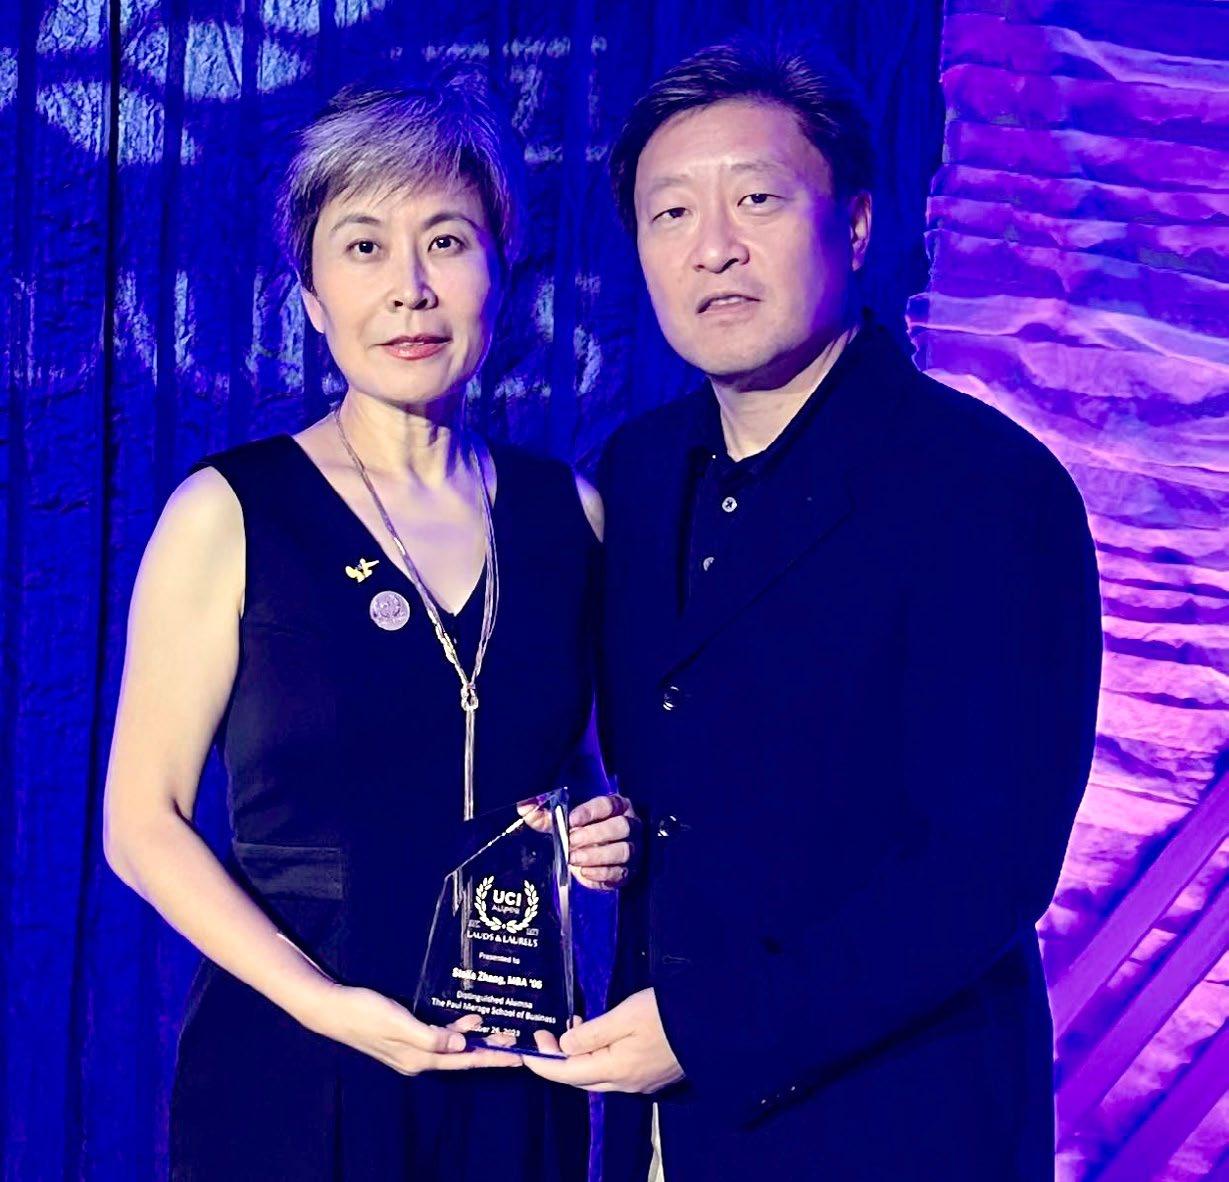
“Private businesses are the engines of job creation and community investment, and they deserve a dedicated resource that meets them where they are,” said Stella Zhang, Chair of the Board of Directors of the Stella and John Foundation and Chief Operating Officer at
American Lending Center. “The Merage School has built something exceptional here. This initiative will give private business leaders access to world-class faculty, talented students, and a peer network that can genuinely move the needle. We are honored to help bring it to life.”
“Sunstone was built on the belief that strategic support and access to capital can unlock the potential of great businesses,” said John Shen, founder of Sunstone and Secretary of the Stella and John Foundation. “Partnering with UC Irvine and the Merage School allows us to extend that mission in a meaningful way. Together, we can help the private businesses that define this region grow stronger, lead better, and plan smarter.”
The initiative draws on a deep bench of Merage School faculty experts spanning corporate governance, strategic management, private equity and debt, technology strategy, supply chain, leadership development, and economic impact analysis. Through student consulting engagements and capstone projects, private businesses will gain direct access to top graduate talent guided by faculty researchers.
Out of Sight, Out of Tax
How Small Retailers are Quietly Routing Around the IRS — and What It Means for the Future of Private Business
The tax gap is now nearly $700 billion a year. A new study from UC Irvine researchers reveals how small business owners are finding an unexpected escape hatch — and why closing it may require rethinking the entire system.
A Loophole Written in Code
Picture a small retailer. Maybe it’s a nail salon in Anaheim, a food truck in Santa Ana, or an alterations shop in Irvine. The owner works long hours, juggles vendors, manages staff, and tries to keep the lights on. Taxes are the last thing on her mind — and in many ways, that’s exactly the problem.
The United States loses nearly $696 billion per year to the tax gap — the difference between taxes owed and taxes actually paid. A significant portion of that shortfall traces to small businesses, where income is harder to verify and cash-based transactions are common. For years, the IRS has relied on thirdparty reporting — think your W-2 from an employer, or a 1099 from a platform — as its most effective tool for closing that gap.
But a new study from UC Irvine’s Paul Merage School of Business suggests that when you patch one hole in the reporting net, some small business owners will find the next uncovered exit — with surprising speed.
The Research: Payment Apps, Tax Law, and a Very Convenient Loophole
Associate Professor of Accounting Chenqi Zhu and Ben Lourie, working with two co-authors outside UC Irvine, have been building a research
agenda focused specifically on private firms — the small businesses, family companies, and owner-operated enterprises that make up the overwhelming majority of the U.S. economy but receive a fraction of academic attention.
“In accounting research, we study public firms because they have publicly available mandatory financial reports,” Zhu explains.
“That’s 99% of the papers. We have a unique opportunity to actually take a peek at private business based on anonymous credit card and bank account transactions, and we want to take advantage of that.”
“In accounting research, we study public firms because they have publicly available mandatory financial reports,” Zhu explains. “That’s 99% of the papers. We have a unique opportunity to actually take a
peek at private business based on anonymous credit card and bank account transactions, and we want to take advantage of that.”
Their paper — “Out of Sight, Out of Tax: Strategic Payment Routing and the Limits of Third-Party Reporting” — studies what happened when the IRS announced it would dramatically expand reporting requirements for third-party payment platforms like PayPal and Venmo.
Originally set to take effect January 1, 2022, the rule would have lowered the reporting threshold for Form 1099-K from $20,000 and 200 transactions down to just $600 — regardless of transaction volume. Under the new rule, if a small retailer received income through PayPal or Venmo, those platforms would be required to report it directly to the IRS, similar to how an employer reports wages on a W-2. The intent was clear: reduce underreporting,
shrink the tax gap, create a fairer system.
But one popular payment app was exempt. Zelle, the bank-to-bank transfer service that functions more like a messaging protocol than a payment custodian, does not hold funds — and therefore was not subject to the new reporting requirement. That exemption, written into the technical structure of the law, created an opening.
The Finding: Small Businesses Voted with Their Apps
Analyzing detailed bank account and credit card transaction data from 26,445 small retailers over more than four years, Zhu and her co-authors found a pronounced and rapid shift toward Zelle — one that began almost immediately after the new reporting rule was announced,
before the law even took effect.
Zelle’s share of total paymentapp income among small retailers climbed from 44% in 2020 to 58% by 2024. That shift was not random. The retailers most likely to switch to Zelle were those with lower effective tax rates, greater reliance on cash deposits, more risk-taking behavior (as measured by participation in cryptocurrency and gambling activities), and tighter financial constraints. The pattern, the researchers note, is consistent with strategic tax-avoidance behavior — not simply a preference for a new technology.
“We don’t have a smoking gun showing that those switching businesses are definitely avoiding tax,” Zhu acknowledges. “But the suggestive evidence points toward strategic gaming behavior — and higher Zelle usage is associated with even lower effective tax rates.”
A Law That Never Quite Arrived
One of the most striking dimensions of this study is that the behavioral shift happened not in response to the law itself — but in response to the expectation of the law. The rule was delayed twice, in November 2022 and December 2023, partially implemented with a $5,000 threshold for the 2024 tax year, and ultimately repealed in July 2025 as part of the One Big Beautiful Bill Act. This finding carries its own lesson:
when regulatory signals are inconsistent or unclear, market actors respond to the signal — not just the implementation. For private business owners operating on thin margins with limited legal resources, ambiguity in the rules is itself a form of pressure that shapes behavior.
“Frequent changes in the rule create uncertainty or confusion for small businesses,” Zhu says. “What is more complicated is the different reporting requirements for different platforms, based purely on the technology behind them — from the user’s perspective, Zelle and PayPal don’t feel that different. But because of how the payment technology is structured, they create different reporting requirements.”
Why This Matters for the Future of Private Business
The implications of this research extend well beyond tax policy.
For the vast majority of private
business owners who want to comply with the law, regulatory fragmentation is a burden, not a benefit. Time and energy spent parsing various regulatory requirements is time not spent developing better products, serving customers, or growing a business.
And the costs of noncompliance don’t just flow upward to the IRS.
When some business owners exploit loopholes, the tax burden effectively shifts onto those who don’t.
Public services shrink or costs rise elsewhere — and the businesses that play by the rules pay the price for those who don’t.
“Tax is just one example,” Zhu notes. “What we’re really seeing is a broader pattern. Technology
tends to move faster than regulation, and when there are gaps or inconsistencies, people naturally respond to them. The future of private business would benefit enormously from a fair, clear, and consistent regulatory environment. That doesn’t just help the government — it also makes it easier for businesses to do the right thing.”
The Bigger Picture: Private Business, Finally in Focus
This research is part of a growing initiative at UC Irvine’s Paul Merage School of Business to build a serious, rigorous body of knowledge about private firms — companies that, despite comprising the vast
majority of businesses in the United States, have been largely invisible to academic accounting researchers.
Dean Ian O. Williamson has championed this line of inquiry as central to the school’s mission.
“Private business is where most people work, where most innovation happens at street level, and where most of the regulatory complexity lands hardest,” Williamson has noted. “Understanding how these firms operate — and what they need to thrive — is essential scholarship.”
Zhu and Lourie’s work on small retailers is one of two active projects in this vein. A companion study is examining how small businesses manage cash flows and adopt digital tools like QuickBooks to handle
Chenqi Zhu is an Associate Professor of Accounting at UC Irvine’s Paul Merage School of Business. Her research focuses on tax policy, financial reporting, and the unique challenges facing private firms. Her work on small retailer tax behavior is co-authored with Professor Ben Lourie of the Merage School and two external collaborators and is slated for presentation at the IRS-Tax Policy Center Research Conference in 2026.
“Frequent changes in the rule create uncertainty or confusion for small businesses,” Zhu says. “What is more complicated is the different reporting requirements for different platforms, based purely on the technology behind them — from the user’s perspective, Zelle and PayPal don’t feel that different. But because of how the payment technology is structured, they create different reporting requirements.”
financial operations — another area where private firms are navigating complexity in real time, with limited resources and high stakes.
The tax research is scheduled to be presented at this year’s IRS-Tax Policy Center Research Conference — a notable platform that speaks directly to regulators and policymakers. From there, the team plans to submit to a top accounting journal.
Chenqi Zhu
When Wall Street Gets Excited, Smart Private Companies Should Pay Attention
Research from UC Irvine’s Paul Merage School of Business reveals a surprising hidden advantage for private firms hiding in plain sight: public market hype.
Picture the dot-com era. Tech stocks are soaring. Investors are pouring money in. The frenzy is everywhere. For the private company owner down the street, it might look like a party they weren’t invited to.
But according to groundbreaking research from Devin Shanthikumar, Professor and Associate Dean of Undergraduate Programs at UC Irvine’s Paul Merage School of Business, that private business owner may have been sitting on a golden opportunity and not even known it.
The study, co-authored with Brad A. Badertscher of the University of Notre Dame and Siew Hong Teoh of UC Irvine, published in The Accounting Review, asks a question that seems almost counterintuitive: when public company stocks get overvalued, do private companies actually benefit?
“When you see those prices going crazy, that’s actually a signal. It might feel threatening. But it’s an opportunity.”
The answer, backed by data from more than 50,000 private firms over a decade, is a resounding yes.
The Idea: Excitement Is Contagious
To understand the research, start with a basic fact about public markets: stock prices don’t always reflect reality. During periods of industry-wide excitement, investors push valuations above what the underlying business fundamentals would justify. We saw it with dotcom stocks. We’ve seen it in biotech, in real estate, in electric vehicles.
What the prior research showed is that those overvalued public companies tend to do something predictable: they raise equity capital and invest aggressively. But those investments, it turns out, don’t tend to pay off. For public firms, the misvaluation-driven investment cycle often ends badly.
The question Shanthikumar and her colleagues wanted to answer was whether any of that excitement spills over to the private sector. And if so, which way?
“There are two ways it could go,” Shanthikumar explained. “One is that public companies are crowding out private ones, competing for the same resources, labor, customers. The other is that the excitement is contagious. Banks get excited. Investors get excited. Customers get excited. And private companies end up benefiting.”
The data came down decisively on the second answer.
The Mechanism: A Three-Part Chain
The research maps out exactly how the benefit flows from public market excitement to private company investment returns. It works in three linked steps.
First, when public stocks in an industry become overvalued, that sentiment doesn’t stay contained in stock exchanges. It spreads. Banks become more willing to lend. Suppliers extend better terms.
Prospective employees seek out jobs in the hot industry. Capital becomes more accessible for private firms operating in the same space.
Second, private companies that recognize the moment and act on it invest more. They take on debt to fund expansion, and they put internal funds to work. Importantly, because private firms don’t have access to public equity markets the way their publicly traded counterparts do, they can’t simply issue new shares. What the research found is that roughly 60 percent of the increased investment is funded through debt, with the remainder largely coming from retained earnings and internal resources.
“For public companies, this kind of investment during a hype cycle tends to go sideways,” Shanthikumar said. “But for private companies, it’s the opposite. They’re often capitalconstrained in normal times, so when the environment loosens up and they can actually fund the investments they’ve been wanting to make, those investments pay off.”
Third, and this is where the story becomes truly surprising, those investments actually pay off. In a significant contrast with public firms, where overvaluation-driven investments tend to destroy value, the same investments by private companies produced a nearly
20 percent increase in return on investment in the following year, and a 40 percent increase over two years.
“For public companies, this kind of investment during a hype cycle tends to go sideways,”
Shanthikumar said. “But for private companies, it’s the opposite. They’re often capital-constrained in normal times, so when the environment loosens up and they can actually fund the investments they’ve been wanting to make, those investments pay off.”
What This Means for Private Business Leaders
The practical implications are direct and concrete. Shanthikumar frames it as a strategic intelligence opportunity that most private company owners are not currently using.
“You should be paying attention to what’s happening in the stock prices of your public competitors and peers,” she said. “When you see those prices going crazy,
that’s actually a signal. It might feel threatening. But it’s an opportunity.”
Specifically, the research suggests that periods of public market overvaluation are ideal times for private companies to approach banks and investors more aggressively, pursue capital they might otherwise leave on the table, and move on expansion opportunities they’ve been hesitant about.
“There’s almost no information publicly available about private companies,” Shanthikumar noted. “For public companies, you have SEC filings. For private companies, all of that is private. One of the reasons our study is really unique is that we were able to obtain financial statements for tens of thousands of private companies over time.”
The effect is strongest when the excitement is broad. If the entire industry’s public peers are riding a wave of sentiment, the spillover to private firms is more pronounced than if just one company’s stock is running hot. The research also found the effect holds for both smaller businesses and mid-market and large private companies, meaning it isn’t confined to a particular scale of operation.
A Rare Window Into Private Company Data
One reason this research matters beyond its findings is the data it required. Private company financial information is notoriously difficult to access. Unlike public firms, private companies have no obligation to disclose financial statements, and comprehensive datasets are rare.
The research team worked with Sageworks Inc., a financial services company that collects anonymized financial data from private firms as part of its business services. This gave the researchers access to 10 years of balance sheet and income statement data across more than 50,000 companies spanning 2001 to 2010, a period that included the post-dot-com crash, the run-up to the 2008 financial crisis, and the early recovery.
“There’s almost no information publicly available about private companies,” Shanthikumar noted. “For public companies, you have SEC filings. For private companies, all of that is private. One of the reasons our study is really unique is that we were able to obtain financial statements for tens of thousands of private companies over time.”
That data allowed the team to do something rarely possible in private company research: trace not just whether investment changed, but how it was financed, and whether it actually worked.
The Bigger Picture
The research arrives at a moment when private markets are growing rapidly. More capital than ever is flowing into private equity and private debt. More companies are choosing to stay private longer. And as that share of the economy grows, understanding how private firms behave becomes increasingly important, not just for business owners, but for policymakers and economists trying to understand investment cycles.
Shanthikumar sees the democratization of private markets as one of the most pressing open questions in this space. “As more and more of the economy is private, the risks and dynamics are very
different than they are for public firms,” she said. “Private companies are usually more capital-constrained. The risk is that profitable investments don’t get made. Does broader access to private investment help solve that problem? We don’t know yet. But it’s one of the most important questions for this moment.”
For now, what the research makes clear is this: when Wall Street gets excited about your industry, the smart private business owner doesn’t watch from the sidelines. They pick up the phone and call their bank.
Devin M. Shanthikumar is Associate Dean of Undergraduate Programs and Professor of Accounting at the Paul Merage School of Business at UC Irvine. Her research sits at the nexus of psychology, financial markets, and technology, and has been published in leading journals including the Journal of Financial Economics, The Accounting Review, and Management Science. Her work has been cited by publications including The Economist and Bloomberg.
Devin Shanthikumar
The Quiet Revolution in How We Work
New research from Merage School faculty member Manuel Hoffmann finds that generative AI is reshaping the nature of work itself, with profound implications for private companies ready to seize the moment.
Picture the best developer on your team. She writes clean code, closes issues fast, and keeps the whole project moving. She is also, almost certainly, spending a significant chunk of her day not writing code at all. She is assigning tickets, triaging pull requests, nudging teammates, answering questions, and managing the invisible overhead that multiplies whenever a project gains traction.
That is the paradox at the center of the knowledge economy: the reward for good work is more managerial work. And it may now be changing.
“With AI, you don’t need other people as much to solve problems. That speaks to a real potential for reduction in hierarchy.”
Manuel Hoffmann, an assistant professor at UC Irvine’s Paul Merage School of Business and a Microsoft AI Economy Institute Senior Fellow, has spent years studying this tension. His working paper, coauthored with Sam Boysel of the Linux Foundation and Frank Nagle of the Massachusetts Institute of Technology, Sida Peng of Microsoft, and Kevin Xu of GitHub, offers some of the most rigorous evidence yet on how generative AI is changing not just
productivity, but the very structure of work. The findings carry immediate relevance for private businesses navigating the AI moment.
The Experiment
Hoffmann and his colleagues turned to GitHub, the world’s largest open source software platform, and a remarkable natural experiment embedded in the rollout of GitHub Copilot, an AI-powered coding tool developed collaboratively with Microsoft and OpenAI.
When Copilot launched to the general public in June 2022, GitHub quietly granted free access to a subset of its most active developers based on an internal eligibility ranking. Crucially, the developers themselves did not know the precise criteria determining who got access for free. That uncertainty is what makes the study so powerful. Because eligibility near the threshold was effectively random, the researchers could observe, with genuine causal confidence, what happened when skilled developers got an AI coding assistant and others did not.
The dataset covers nearly 190,000 developers observed weekly over two years, yielding millions of data points on how people actually work.
What Changed
The results are striking. Developers with access to Copilot shifted meaningfully toward their core work. Coding activities as a share of
total work increased by more than 12 percent. Project management activities, which include coordinating with others, triaging issues, reviewing contributions, and managing the community overhead that accumulates around successful software, dropped by nearly 25 percent.
The mechanism is intuitive once you see it. AI fills the role that a colleague or collaborator used to fill. When a developer runs into a problem, AI can answer it in seconds. That means fewer issues opened on a shared board, fewer requests routed to another person, and less time spent on the social scaffolding of distributed work. The number of distinct collaborators that Copiloteligible developers interacted with dropped dramatically, roughly 79 percent relative to the baseline. Hoffmann is direct about what this means for organizational structure. When people rely less on others to solve problems, there is less need for the layers of management that exist to coordinate those interactions. Hierarchies, built on the premise that someone needs to direct traffic, become less necessary when the traffic moves more freely on its own.
The Innovation Dividend
The shift away from project management did not produce workers who retreated into routine. It produced workers who explored. Hoffmann and his colleagues
found that developers with Copilot access were significantly more likely to engage with new projects and experiment with programming languages they had not used before. They engaged with roughly 15 more new repositories on average, and expanded their language exposure by more than 21 percent. That exploration was not idle wandering. Developers gravitated toward languages commanding higher market salaries, suggesting they were making active bets on their own professional value. When the cost of trying something new falls, people try more new things. For private businesses, this pattern carries a clear implication: AI, deployed well, does not just help people do existing work faster. It reorients attention toward the work that creates new value.
Hoffmann frames this as a crucial distinction for any organization assessing its AI strategy. “If they’re using it for innovation instead of just cost-cutting, then AI can be an equalizer,” he says. “But for that, they have to be on the innovation side and less on the efficiency side.”
25% drop in project management activity — 12% increase in core coding work among developers with AI access
Who Benefits Most
One of the most consequential findings in the paper concerns which workers benefit the most. The answer, perhaps counterintuitively, is those with lower ability or less experience.
“Lower-ability individuals can learn more quickly how to engage in certain types of work and potentially move up the hierarchy more quickly when they have access to the tools.”
Developers with shorter tenure, fewer platform achievements, and less established reputations showed sharply larger gains in core work and larger reductions in project management overhead when given access to AI. The effect on coding for lower-ability developers was more than four times the effect observed in their higher-ability peers under some measures.
The intuition here runs through a simple dynamic. High-ability workers tend to treat core work and management as complementary: leading the project and doing the work reinforce each other. Lowerability workers experience them as competing demands. When AI
absorbs some of that overhead, less experienced contributors can direct a much greater share of their effort toward the work that builds capability and contributes directly to output. They move up more quickly. For private companies, many of which rely on lean teams where the range of individual talent is wide, this is not a minor finding.
The Linchpin Question
Hoffmann is particularly interested in what happens to the indispensable people inside organizations, the ones whose departure would destabilize everything. In open source software, these are the elite maintainers holding together critical projects that the modern internet depends on. In private business, they are their analogs: the lead engineer who holds the product together, the sales director whose relationships cannot be replicated, the operations person who knows where every body is buried.
These people are typically overburdened precisely because they are trusted. Success creates demand. The research suggests that AI may offer a genuine way to relieve that burden without sacrificing what
makes those individuals valuable. When overhead drops, linchpin contributors can focus on the work only they can do.
There is a secondary benefit Hoffmann points to: betterconnected leadership. A senior person who no longer codes after rising into management can, with AI assistance, more clearly understand what their team is actually doing day to day. That is not about surveillance. It is about closing the comprehension gap between people who make decisions and the technical realities those decisions affect.
What This Means for Private Business
The research was conducted in the world of open source software, but Hoffmann is careful about why the findings travel. The developers in the study were working in distributed teams on projects that had grown beyond any single person’s capacity to manage. The problems they faced, coordination overhead,
burnout among key contributors, the drag of managerial tasks pulling talented people away from high-value work, are not software problems. They are organizational problems. Private companies face them every day.
The research results held across both volunteer contributors and those working on behalf of their employers, a direct signal that these effects are not artifacts of the open source context but patterns likely to replicate inside firms.
For leaders of private companies, the strategic read is straightforward. AI tools are not simply productivity accelerators layered on top of existing structures. They are restructuring agents. Organizations that treat them as such, reconfiguring roles, flattening hierarchies with intention, and pointing the freed-up capacity toward innovation rather than efficiency, will find themselves in a genuinely different competitive position.
The access advantage that
large enterprises once held in sophisticated tooling is rapidly disappearing. A private company with twenty people and the right AI infrastructure can now operate with a coordination capacity that previously required a much larger organizational apparatus. The teams that move fast, build a culture of experimentation, and push decisionmaking closer to the work will have an edge that compounds.
Hoffmann’s research does not promise an effortless transformation. Adoption requires intent, and the benefits are largest for companies that invest in real capability, not just access. But the data is clear on the direction of travel. The nature of work is changing. Organizations that understand how are better positioned to shape what comes next.
Manuel Hoffmann is an Assistant Professor in the Paul Merage School of Business in the area of Information Systems. He founded the AI Lab at UC Irvine to engage with firms, policymakers, the greater public, and researchers to better understand the Future of Work, Future of Health and methodological advances in Artificial Intelligence.
Manuel Hoffmann