Vol 41 Issue 6
OFFICIAL PUBLICATION OF THE ALPHA PHI OMEGA GREATER LOS ANGELES ALUMNI ASSOCIATION
June 2021
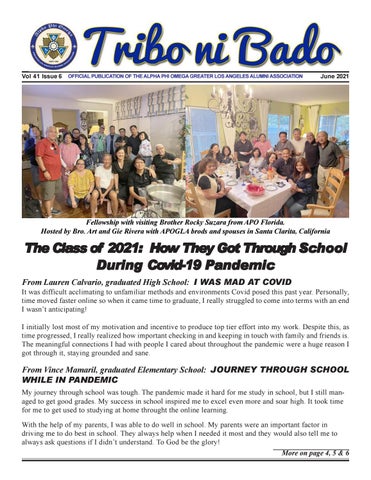
Fellowship with visiting Brother Rocky Suzara from APO Florida. Hosted by Bro. Art and Gie Rivera with APOGLA brods and spouses in Santa Clarita, California
The Class of 2021: Ho w The y Got Thr ough Sc hool How hey hrough School During Co vid-19 P andemic Covid-19 Pandemic From Lauren Calvario, graduated High School: I WAS MAD AT COVID It was difficult acclimating to unfamiliar methods and environments Covid posed this past year. Personally, time moved faster online so when it came time to graduate, I really struggled to come into terms with an end I wasn’t anticipating! I initially lost most of my motivation and incentive to produce top tier effort into my work. Despite this, as time progressed, I really realized how important checking in and keeping in touch with family and friends is. The meaningful connections I had with people I cared about throughout the pandemic were a huge reason I got through it, staying grounded and sane.
From Vince Mamaril, graduated Elementary School: JOURNEY THROUGH SCHOOL WHILE IN PANDEMIC My journey through school was tough. The pandemic made it hard for me study in school, but I still managed to get good grades. My success in school inspired me to excel even more and soar high. It took time for me to get used to studying at home throught the online learning. With the help of my parents, I was able to do well in school. My parents were an important factor in driving me to do best in school. They always help when I needed it most and they would also tell me to always ask questions if I didn’t understand. To God be the glory! More on page 4, 5 & 6
2
PRESIDENT’S MESSA MESSAGE GE We should all be thankful with the blessing of COVID-19 Vaccination, very low number of COVID-19 cases, and to all who practiced COVID19 safety precaution to help slow the spread of the virus; thankful that we are having our first face-to-face APO-GLA GMM since February 2020. Let us pray and be hopeful to be virus free we can continue our face-to-face GMMs and return to our regular service projects such as the volunteering for the LA Regional Food Back and the Operation Gratitude, Beach Clean-up, Blood Donation Drive. Don’t we miss our fun events also – Ladies Night, Easter Egg Hunt, camping, family picnic, Halloween, Thanksgiving and the December Affair, New Year Celebration. There are only six months left for 2021 but I am still hopeful that WE can still do these activities. Mga Kapatid, let me emphasize that even if we are registered as a 501-C7 organization which is under the social club category, we continue to be a service organization practicing the tenets of Alpha Phi Omega. We remain charitable as evidenced by our participation this year to the APOTelemedicine Project and Lipa City Alumni Association Community Pantry. Be proud that we continue to practice charity and service, helping others in our “small” APO-GLA way. We are now preparing for the ACNA Convention in Florida this coming September 2021. Let us all help Bro Art in his candidacy for ACNA Presidency. He is not only our past President, past COB but one of APO-GLA’s Guru for his valuable advice for the betterment of our organization and alumni association. With his knowledge and experience, gained through years of services in the academe, public and business sector and APO, he is the best candidate to be the next ACNA President. Please call your ka-chap, malapit na Brod and Sis, kamag-anak na Brod and Sis and campaign for Lakay Bro Art. I would like everyone to read the Tribo ni Bado and give thanks to Brod Sancho aka Chosy for his dedication and hardwork to publish APO-GLA’s newsletter and the December Affait Souvenir Program. You are truly amazing, Brod Sancho! We are doing our first face-to-face APO-GMM since February 2020. I hope to see you all in the GMM and at the fellowship after the meeting. Let us celebrate June birthdays and the blessing we receive. In leadership, friendship, and service I remain, BroDomel
“Looking Back, Moving Forward: Building A Future Worthy of Our Past”
3
Meet our ne w member ajar do new member:: Sis Sis.. Marilou F Frrancisco-F ancisco-Fajar ajardo Chapter/Batch year: Pledge/Batch Name: Hometown: Profession or field:
Family:
Epsilon, 1992 - University of the East (Recto) Crying Lady/Gluckliche starke tapfere damen (Translation: Lucky strong brave ladies) Bacoor, Cavite Philippine Licensed Dentist Business owner of Ja Fajardo DDS & California Licensed Financial professional Married to Dr. Jose Fajardo Children: Jose Marie, Alexa & Aden
How did you hear about APOGLA?
Sis Hazel Hermoso 5 years ago. Sis Hazel has been inviting me to attend APOGLA. Her aunt & my husband work together.
Words of wisdom to share:
If your intentions are pure and good, work ethic is consistent, words and actions are totally aligned, then the rest is not up to you anymore. It's all about when God wants to give you a breakthrough in life. - Jack Wu
APO ID number:
0121-92-18028
Welcome to APO Greater Los Angeles, Sis. Marilou!
Tribo ni Bado Newsletter In Memoriam
Sis nie De Ono Cr uz Sis.. Ber Bernie Cruz
is a monthly publication of the Alpha Phi Omega Greater Los Angeles Alumni Association exclusively for its members, families and friends. The opinions expressed herein are those of the writers, and are not intended to represent APOGLAAA. Publisher Sancho Sy
Beta Eta ‘72 Past President - APO South Bay Member - APO Greater Los Angeles February 20, 1956 - June 5, 2021
Photos/Graphics by Sancho Sy
Our heartfelt condolences to Sis. Susan De Ono Laset and family for the passing of Sis. Bernie De Ono Cruz Eternal rest grant unto her, O Lord, and let perpetual light shine upon her.
Contributors Fely Montecillo • Dan Nino • Troy Agagon Jen Evangelista • Domel Evangelista Lauren Calvario • Vince Mamaril Marilou Fajardo
4
CONGRA TULA TIONS CONGRATULA TULATIONS
TO
THE
CLASS
OF
2021
SAMANTHA CAJUCOM, graduated Master of Science in Nursing at University of California - San Marcos
GRAHAM CALVARIO, graduated Masters in Mathematics Education at California State University - Long Beach
LAUREN CALVARIO, graduated Magna Cum Laude of her High School at La Salle College Preparatory
ADEN FAJARDO, incoming High School freshman. Class of 2021 at Foothills Middle School
5
CONGRA TULA TIONS CONGRATULA TULATIONS
TO
THE
CLASS
OF
2021
ALEXA FAJARDO, graduated High School at Arcadia High School
VINCE MAMARIL, incoming Seventh Grader
MIKAELA MONASTERIO-DY, incoming First Grader
CHARITY TORRES - incoming freshman
6
CONGRA TULA TIONS T O THE CLASS OF 2021 CONGRATULA TULATIONS And the youngest of them all at 61! Congratulations to Bro. Hero Valentino! for graduating the Certificated Program in HEATING VENTILATION & AIR CONDITIONING at UEI College and successfully completed Training and is now a Licensed Technician in Universal 608 and R-410A Certified
ACN A CONVENTION UPD ATE CNA UPDA
7
FR OM MY POINT OF VIEW FROM BY BRO. DAN E. NINO, CEO/COB, APOPGLA 501 C-3
Excluding the Sale of Main Home From Seller’s Income For many years that I’ve been preparing income taxes, aside from sales tax and tax filing for nonprofit organizations, I found out that I learn something every day. Every tax return is different from each other. The circumstances, the status of tax filers, their gross income, adjusted gross income, tax deductibility, tax exclusions, dependents, etc. are taken into account. But one aspect of the taxation that I found very interesting is the sale of a main home by divorcing owners. As well all know, divorce is a contentious matter. But I was able to assist my client’s tax return to her satisfaction into a win-win situation. There are also times that I serve as personal counselor because they tell me their personal problems. I can’t just ignore their sob stories because I don’t want to appear rude and dismissive. Anyway, according to federal tax laws, a taxpayer may qualify to exclude from their income all or part of any gain from the sale of their main home. A main home is the one in which the taxpayers live most of the time. I found out that closing costs or expenses in selling a main home are example of exclusions or items that are not required to be included as gross income. Fifty percent of the net proceeds directly associated from the sale of a main home should be given each to the divorcing couple. Expenses incurred in the sale of the main house should be equally divided by the sellers or divorcing couples as exclusions when one files his/her income tax return like real estate agent’s commissions, legal fees, escrow charges, County Transfer Tax, Escrow Fees, Document fees, Loan Payoff, Notary Fees, miscellaneous payoff charges, and other costs or fees paid in order to sell the home. For the federal side, just fill out the Sale of a Main Home Worksheet in the Schedule D, Other Menu to see if any of the capital gain from the sale of their main home can be excluded. Generally, if a taxpayer meets the following tests, they can exclude up to $250,000 if filing single or ($500,000 if married and filing a joint return) of the gain from the sale of a main home. The taxpayer must have owned and lived in the home for at least 2 out of the last 5 years leading up to the sale of the home and must satisfy the ownership test and residence test. The required two years of ownership and residency during the five-year period ending on the date of the sale do not have to be continuous nor do they have to occur at the same time. A taxpayer meets the tests if they can show that they owned and lived in the property as their main home for either 24 full months or 730 days (365 × 2) during the 5-year period ending on the date of sale. Here are the frequently asked questions as proffered by the IRS in determining if a taxpayer qualifies to exclude all or part of the gain from the sale of their main home. Refer to IRS Publication 523, the section entitled “Does Your Home Sale Qualify for the Exclusion of Gain? The sale of a main home must be reported on the taxpayer’s federal income tax return if any of the following apply: • There is a taxable gain on the sale of the home • The taxpayer elects to report a gain that is eligible for the exclusion • Reporting a Loss: A loss from the sale of the taxpayer’s main home can not be deducted from income on the tax return. More Than One Home: If you have more than one home, you can exclude gain only from the sale of your main home. You must pay tax on the gain from selling any other home. If you have two homes and live in both of them, your main home is ordinarily the one you live in most of the time. Example One: You own and live in a house in the city. You also own a beach house, which you use during the summer months. The house in the city is your main home; the beach house is not. Example Two: You own a house, but you live in another house that you rent. The rented house is your main home. I hope these tax tips can be helpful next time you prepare your income tax – especially for those divorcing couples. – denino1951@gmail.com
8
CAN C-7 AND C-3 CO–EXIST TO COMPLEMENT EACH OTHER By Bro. Mar Garchitorena Correct me if I am wrong but judging from the last GMM held last May 15, 2021, there are still confusion amongst APOGLA members regarding C-3 and C7. There are members that know the importance of the C-3 and the role it can play in the makeup and character of us being an APO, however there are still some segment within our members who do not see the value of having both a C-3 and a C-7 organizations and there are also some who have more questions that need more enlightenment and need to be answered. That’s the reason why we need to take the time to revisit the issue of APOPGLA (C-3) and APOGLA (C-7) that was decided by the membership over 5 years ago. It is still an unsettled issue because the question of C3/C7 still keep on coming up after all these years had passed. We cannot dictate to APOGLA members what to do. We will leave it to APOGLA and the members to find the answer why we really need both C-3 and C-7 and whether they can co-exist to complement each other. Last year was a banner year for APOPGLA C-3. We had sponsored and completed at least as many as six (6) humanitarian service projects in the Philippines in 2020 alone. This year we are scheduled to undertake another humanitarian mission to help indigenous members of our society in the Philippines. We are launching a pilot program to help the DUMAGATS in Nueva Ecija who are being displaced from their homes and being neglected by the government in the Philippines. The service project is a combination of livelihood/ Medical and educational program. Like our previous projects which had served us well, we are partnering with APO Livestock Association and some local APO chapters in the area to spearhead and to monitor the project in order to bring the service into fruition. We can elect to proceed with just doing these charitable and humanitarian services on our own but it seems that our advocacy is not complete unless we share these opportunities to APOGLA so that they could also experience the feeling of fulfillment and satisfaction of being able to help those underserve and less fortunate segments in our community. Majority of us who are members of APOPGLA (C-3) are also members of APOGLA (C-7) and like any APO, we believe that charitable giving and service to others are essential in our wellbeing as an APO. We know that all APOGLA members also share that same passion and belief of being of service to others. The IRS offers more than a dozen different classifications of nonprofit tax exempt Organizations. Each one is different and as specific requirements, restrictions and purposes. If this not significant, the IRS could have just made everybody a nonprofit (C-3) without being mindful of distinctions. But unfortunately that’s not the case. The IRS has strict governing rules regarding each nonprofit. For the purpose of our discussion, we will not discuss the different kind of nonprofit organizations but limit our focus and discussion on the C-3 and C-7.
The first thing we need to know is the definitions and differences of C-3 and a C-7, A 501C7 is a social club organized for the pleasure, recreation and similar nonprofit activities for the benefit the members. On the hand, a 501C3 is an organization establish for the purpose of Religious, Educational, Charitable, Scientific and Literary activities. A C-3 is the king of all nonprofits because it enjoys more federal and State tax benefits including tax deductibility of donations which are not available to the other nonprofits. A C-7 may be exempt from federal income taxation if they meet the requirements of section 501C7 of the Internal Revenue Code. Here are the exemption requirements of a 501C7 according to the IRS. 1. The club must be organized for exempt purposes. 2. The club must provide an opportunity for personal contact among members and membership must be limited only to those with the same hobby and interest. 3. The club must be supported by membership fees, dues, and assessments. 4. The organization’s net earnings may not inure to the benefit of any person having a personal and private interest in its activities. 5. If the club exceeds safe harbor guidelines for nonmember and investment income, the facts and circumstances must show that it is organized substantially for exempt purposes.. 6. The club may receive de minimis income from nontraditional sources. 7. Although they are generally exempt from tax, social clubs are subject to tax on their unrelated business income which includes income from non members . In addition to being taxed on unrelated income, a social club may lose its exempt status if it receives too much unrelated income. As a simple rule, any activity that benefits solely the membership can be qualified as a valid C-7 activity however, any activity that benefits other than the membership cannot be qualified as a C-7 activity but can be a valid C-3 activity. We, as APO like to enjoy the company and camaraderie of other brods and sis in APO’s as much as possible. At the same time, we also want to do humanitarian services and charitable giving because service is in our DNA. At a very young age, we had been indoctrinated in the advocacy of service. Service to our fellow APO, service to the nation and service to the community. So I think this is where the dilemma and the question lie. Remember, inward service activities are C-7 and outward activities is only in the purview of a C-3, In our case with APOGLA, we want to do both. We want to be a social club and at the same time do service as a charitable organization. The IRS has strict rules and requirements for C-7 nonprofit organization as noted above. However, we believe that we should never be put in a position to pick and choose whether to do humanitarian service or not. It should not be that way. We know it never occurred to many of APOGLA members to ask whether we are permitted under the IRS ruling to do a certain services. Lucky for us, we don’t need to choose because we can
9
CAN C-7 AND C-3 CO–EXIST TO COMPLEMENT EACH OTHER Continued from page 6 have both organizations at our disposal. We can elect to function both ways. We can be a Social Club as well as do charitable services at the same time, if we elect to do so. Our 501C-3 got us covered. We just need to play our cards right. Here’s what we propose to APOGLA members. 1. Accept that APOGLA AND APOPGLA as 2 separate legal entity and organized nonprofit rule. 2. Each organization has role to play so that we avoid and can go around the restrictions and requirements imposed by the IRS 3. We can all elect to be members of both APOPGLA (C-3) and APOGLA(C-7). 4. Each organization can complement its other in terms of service. Any activities that point inward for the benefit of members like Christmas Party, Thanks giving celebration, picnics and camping to name a few, are C-7 and any activities that benefits people other than our members can be classified as a C-3 project in cooperation and coordination with the C-7as defined by the IRS. 5. The role of both APOGLA and APOPGLA should be well defined in a Memorandum of Agreement (MOA). This way we can make sure that each organization preserve its own integrity and totally abide with the restrictions, rules and requirements of the IRS. 6. APOGLA will provide manpower for any activities outside the scope of APOGLA (C-7), 7. APOPGLA can serve as a fundraising arm of the organizations. All donations of any C-7 member collected by C-3 to take advantage of tax deductibility shall be remitted back to APOGLA, if the service project is within the scope and realm of C-7 except for the reasonable retained service fee of the C3 which could be determined by the Commission to be setup later. . 8. All C-3 collection will remain with APOPGLA, if the service projects are in the realm and sponsored of the C3. Any excess collection will be maintained in our general fund unless fund is restricted by the donor.
9. A Commission composed of both APOGLA and APOPGLA will be establish to be able to update and continuously amend or revised the MOA as needed. 10. A common goal and objective should be established that is mutually beneficial to both APOGLA and APOPGLA like a building fund and the pursuit of advancement of our principles of Leadership, Friendship and Service. 11. To register and establish a DBA company that would be used by APOPGLA (C-3) as a trade mark instead of reregistering or changing APOPGLA name to avoid confusion with then name of APOGLA. In this regard, the Board of APOPGLA had already decided to register APO GLOBAL FOUNDATION as our DBA. 12. Create a working committee among members of both APOGLA and APOPGLA to formulate and implement policies in the areas of but not limited to, volunteerism, fund raising and humanitarian services.
Here’s a graph that compare and illustrate the difference between a C-3 and a C-7 for you to judge whether we are doing activities appropriate for C-7
10
GOINGS ON by Sis. Fely Montecillo It’s June! It’s June! It’s June! Forgive me for my excitement. But it’s the month for June brides. Right? And many more . . . It is an ironic month I should say for it contains the summer solstice in the Northern Hemisphere, the day with the most daylight hours, and the winter solstice in the Southern Hemisphere, the day with the fewest daylight hours. Interesting dates in June: Men’s Health month, National Great Outdoors month, Rose month, and National Safety month. To all Brothers and Sisters celebrating their birthdays this month, Happy Birthday to all of you and may you have many more! **************************** Those born in June are under the sign of Gemini which means they look at both sides of an issue. They are also considered social butterflies because they are charismatic, talented and good looking. They are very intelligent, are extremely inquisitive, and have a childlike nature. June borns are great communicators and can easily draw everyone’s attention. So there you are lucky June babies! **************************** Due to many incidents of attacks on Asians, a group has formed against Asian hatred. It is sad that this threat is growing by the day that many of Asian descent are scared to go out now. This of course, includes many Filipinos as there were Filipino victims too. It would be good to join this coalition against Asian hatred don’t you think? **************************** Now that things are starting to go back to normalcy, we are so looking forward to our monthly GMMs. We do miss each other’s company. We are indeed counting the days! **************************** What is fidelity? It’s one value which means faithfulness to something to which one is bound by pledge or duty. Fidelity implies strict and continuing faith-fullness to an obligation, trust, or duty. It also mean faithfulness to a spouse.
11
TREASURER’S REPOR T By Bro. Troy Agagon REPORT 1. 2. 3. 4. 5. 6. 7. 8. 9. 10. 11. 12. 13. 14. 15. 16. 17. 18. 19. 20. 21. 22. 23. 24. 25. 26. 27. 28. 29. 30. 31. 32. 33. 34. 35. 36. 37. 38. 39. 40. 41. 42. 43. 44. 45. 46.
Agagon, Troy Almazan, Alex Almazan, Irma Ambrosio, Ronald Amon, Ophel Amon, Tony Anadilla Jr., Ariston Ang-Gayon, Melody Ansula, Bong Aralar, Eric Arevalo, Lester Arnaldo, Manuel Arroyo, Geoffrey Atienza, Oca Ayo, Toti Bayani, JR Blaza, Christine Bonete, Maria Cajucom, Willy Calvario, Rene Carrasco, Danny Chin, Jun Clarete, Sam Cobarrubias, Bob Conferido, Reuben David, Betta David, Christian David, Ramon De Leon, Malou Dulay, Alex Emperado, Rudy Enguero, Pam Evangelista, Domel Evangelista, Jen Fernando, Ruby Flores, Glenda Flores, Rudy Ford, Rebecca Franco, Rolly Gomez, Tony Gopez, Bernardo Guerrero, Jenny Rose Hermoso, Hazel Jaranilla, Ogie Jove, Nestor Jove, Shirley
47. Jovellanos, Jobee 48. Junio, Virgil 49. Lara, Bobet 50. Layno, Mary Ann 51. Linsangan, Jun 52. Madrigal, Jun 53. Madrigal, Tess 54. Maidin, Yusop 55. Mamaril, Ferdie 56. Mansilla, Beeboy 57. Marte, Rocky 58. Mejia, Francis 59. Mendez, Daemma 60. Mendoza, Armand 61. Miranda, Shane 62. Nino, Dan 63. Noche, Caesar 64. Padua, Rey 65. Pangilinan, Angel 66. Paras, Roland 67. Paredes, Vic 68. Peneza, Jo 69. Petreace, Petchie 70. Posadas, Rey 71. Remorozo, Gerald 72. Reyes, Roehl 73. Rivera, Art 74. Roberto, Marisol 75. Rosal, Justin 76. Rosales, Cesar 77. Rubina-Galang, Emma 78. Serrano, Eric 79. Sevilla, Bobby 80. Sipin, Perry 81. Somera, Herman 82. Sy, Sancho 83. Tarculas, Josie 84. Tarculas, Lito 85. Tecson, Edgardo 86. Turallo, Silver 87. Valentino, Hero 88. Ventura, Beth 89. Yambot, Ferdie 90. Yenko, Rene 91. Zamora, Sammie as of May 15, 2021
Please send your $50.00 Membership Dues to: TROY AGAGON 27447 Elder View Dr., Valencia, CA 91354 All checks must be made payable to: APOGLA
HAPPY BIR THD AY BIRTHD THDA JUNE CELEBRANTS 01 02 03 04 08 09 10 11 14 15 16 17 22 25 28 30
- Jimmy Magsino - Erna Villanueva - Henry Valdecantos - Francis Mejia - Tony Alejan - Jesus Castro, George Ludovico - Jun Sacro, JJ Castro - Tony Mendoza - Rocky Marte - Roehl Reyes - Sancho Sy, Boy Valdecantos, Nelson Jusay - Malene Bonete - Mary Ann Layno - Abe Pangilinan, Melvin Villaver - Jerome Paggao - Shirley Jove
SPOUSE: 01 - Gina Fisico 06 - Rosanne Bacalia 09 - Norma Castro 14 - Meg Ilagan 19 - Evelyn Noche 20 - Jeannie Garcia 21 - Jocelyn Ludovico 24 - Marinette David APO Kids: 01 - Graham Calvario 02 - Louie King Caldoza, Patricia Tecson 04 - Ruby Payaoan 05 - Leonardo Caldoza Jr., Philip Emmanuele Irineo 06 - Lesley Rosales, Rosanne Bacalia 09 - Zenith Villanueva, Josef Madrigal 12 - Katrina Lichauco, Warlord Pascual 13 - James Venturina, Mithi Valentino 18 - Pamela Amon, Blake Atienza, Sean Aralar, Manny Arnaldo 20 - Harris Chicano 24 - Lea Barcelona 25 - Dr.Timothy Almazan, Gilchrist Arroyo, Gabe Oliver, Kasey Lee 26 - Kristel Aquino, Juan Miguel Serrano, Jasmine Rosal 28 - Christoff Yenko, Emily Ayo, Brandon Atienza
JUNE GENERAL MEMBERSHIP MEETING Join us this Saturday, June 19th | 5:00 pm IN PERSON: at Bro. Bodgie Gapido’s Place 1648 Grenoble Avenue West Covina, CA 91791 CONTACT PERSONS: Bro. Domel Evangelista - (323) 302-3871 Sis. Jen Evangelista - (323) 702-2272 See You At Our 1st Face-To-Face GMM Since February 2020
VISIT US ON FACEBOOK: https://www .f ace book.com/tribonibado https://www.f .face acebook.com/tribonibado