LIFESTYLE MAGAZINE
PROPERTY NEWS
mortgages
OCTOBER 2020
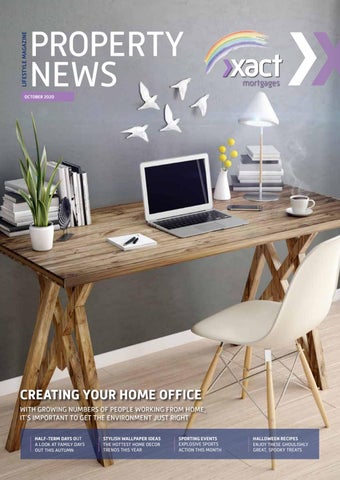
CREATING YOUR HOME OFFICE WITH GROWING NUMBERS OF PEOPLE WORKING FROM HOME, IT’S IMPORTANT TO GET THE ENVIRONMENT JUST RIGHT HALF-TERM DAYS OUT A LOOK AT FAMILY DAYS OUT THIS AUTUMN
STYLISH WALLPAPER IDEAS THE HOTTEST HOME DECOR TRENDS THIS YEAR
SPORTING EVENTS EXPLOSIVE SPORTS ACTION THIS MONTH
HALLOWEEN RECIPES ENJOY THESE GHOULISHLY GREAT, SPOOKY TREATS
COVER STORY
4
7
Creating your home office It is important to create the right home-working environment for you
PROPERTY
8
Stylish wallpaper ideas The hottest home decor trends this year
16
News Our latest mortgage news. Plus meet the team!
TRAVEL
2
Spooky places to visit this year Our guide to 5 of the spookiest locations in and around the UK
LIFESTYLE
6
How to carve a pumpkin Here are some hints and tips to help you out
Half-term days out We take a look at some of the family days out available
10
Halloween party at home A great guide to make it a special celebration at home
13
Power women at the box office These leading ladies are set to take over the box office
SPORT
12
October Sporting Events Let’s have a look at some of the biggest events this month
FOOD
14
Halloween recipes A selection of recipes to ensure your spooky night goes well
5
TOP
CONTENTS
SPOOKY PLACES TO VISIT IN THE UK THIS YEAR
It’s that time of year where we are all looking for a good scare and where better to start than some of the most terrifying places around the UK…
O
n the build-up to Halloween, some of us get comfy on the sofa with a good horror film, while others are more adventurous. If you are the thrillseeker type, check out our guide to 5 of the spookiest locations in and around the UK.
BUCKLAND ABBEY, DEVON
WELCOME TO THE OCTOBER ISSUE!
S
ummer seems a distant memory already! We have been blessed with warm weather throughout which has been a great benefit in these strange times.
experienced before we have helped create a guide to throwing the perfect Halloween party at home including how to carve a pumpkin, some great games and some spooky recipes too.
With the property market thriving, if you’re thinking about moving but haven’t started the process, we have put safety guidelines in place to ensure your safety. And with our expert local knowledge, we have all the tools you need to get you moving – including a FREE personalised website for you to share on social media.
How is it nearly half-term? Never fear though, we have a selection of great half-term, family days out as well as a guide to the top 5 spooky places to visit in the UK. And finally, we take a look at the Power-Women taking over at the box office this month.
This month’s issue provides you with a wide range of articles including the most stylish wallpaper trends for 2021, how to create the perfect home office and the biggest sporting events this month. It’s Halloween month, and knowing it’ll be a Halloween like we’ve never
2
PROPERTY NEWS
Please note, we are doing our best to be accurate, but in these strange times, all the dates and availability at attractions may change, however, were correct at the time of writing.
We’ll start with a celebrity ghost. We all learned about Sir Francis Drake in school. In life, he was a national hero, a sea captain, naval officer and explorer who was famed for his circumnavigation of the world in a single expedition from 1577 to 1580. Buckland Abbey was sold to Sir Francis Drake in 1580 after the expedition and he made it his home. However, many locals feared the intrepid, and recently Knighted explorer, believing he had supernatural powers. Some even said he had made a pact with the Devil which was how he had defeated the Spanish Armada. In death, his ghost is now believed to haunt Buckland Abbey and ride across Dartmoor in a black coach driven by headless horses led by goblins and pursued by barking dogs. Buckland Abbey is run by the National Trust and you can visit it all year round.
Till next time… Jonathan Wheatley Editor
Spooky fact: It has been suggested that the ghost story even inspired Sir Arthur Conan Doyle to write The Hound of the Baskervilles.
CROFT CASTLE, WEST MIDLANDS
TREASURER’S HOUSE,YORK
The Croft family, where the castle got its name, are descendants of the famous Welshman, who is believed to haunt the castle as a seven-foot figure clad in a leather jerkin. Members of staff at the castle have also reported the cries of a wailing baby and a spectral figure wearing a grey doublet. In one of the windows, a woman has been seen wearing a crinoline (a stiff petticoat) who is believed to be a member of the Croft family.
An 18-year old engineer, who later became a policeman, named Henry Martindale has the best-known account of the spooky goings-on in the house. One day, when Martindale was installing a boiler in the cellars, he heard the sound of a trumpet and saw a soldier’s helmet emerge from the wall he was working. As he watched, around 20 further spectral soldiers emerged armed with lances, short swords and round shields.
Croft Castle is also run by the National Trust and you can visit all year round.
Treasurer’s House is also run by the National Trust and you can visit all year round.
Croft Castle is said to be ‘The most haunted house in the Midlands,’ and amongst the seven spectres, it also has a famous resident, Welsh freedom fighter, Owain Glyndwr. Glyndwr was a Welsh leader born in 1359 who instigated a fierce war of independence against the English and was the last native Welshman to hold the title Prince of Wales.
Spooky fact: Members of staff have reported hearing their names being called when no one is around.
PLUCKLEY, KENT
Pluckley in Kent is in the Guinness Book of Records as the ‘Most haunted village in Britain.’ This quaint village is reputed to have between 12-14 ghosts including the spectre of a highwayman in a tree, the ghost of a gipsy woman who drowned in a nearby stream, a phantom coach and horse, the old miller on Mill Hill, the hanging body of a schoolmaster, a colonel, a man smothered in clay, the Lady of Rose Court, the White Lady and the Red Lady. One of the most famous haunted spots is the pub, The Blacksmith’s Arms, which was previously called The Spectre’s Arms and the Ghost’s Arms because of the number of hauntings and strange occurences. The pub is not haunted by just one, but three ghosts: A Tudor maid, a coachman and a Cavalier. Pluckley, Kent, is a village like any other with two pubs, however, to get the full spooky experience you can book a ghost walk with London Walking Tours
Spooky fact: Nearby, the aptly named Screaming Woods, is a real tourist trap with brave tourists choosing to camp overnight.
Treasurer’s House, nestled in the centre of York, has over 2000-years of history running through its veins. Renovated by Frank Green, a wealthy industrialist and passionate collector, Treasure’s House was used to showcase his collections including antique furniture, art and textiles.
Spooky fact: It was revealed that 18-inches below the current cellar floor, archaeologists revealed evidence of an ancient Roman road.
CANNOCK CHASE FOREST, STAFFORDSHIRE
Cannock Chase forest is a natural beauty spot in Staffordshire, however, it also has a horrid history including murder and chilling sightings of a spectre known locally as ‘The Black Eyed Child.’ First spotted over 30-years ago, the sightings have restarted over the past decade. Recent descriptions of the spectre are eerily similar to those in the 80s, where a child, with coal-black pits for eye sockets, haunts the woods. It is a hot-spot for paranormal investigators who have also heard stories around the world regarding other children with the same eerie eyes, however, only in Cannock Chase do the sightings consistently happen during the daytime. Often the sightings will happen after hearing screams. The child will appear with her hands over her eyes, before revealing her ghastly form. Cannock Chase Forest is run by Forestry England and boasts a children’s play area, orienteering trails and Go Ape.
Spooky fact: During the 1960s three young girls were murdered in what became known as ‘The Cannock Chase Murders.’
LIFESTYLE MAGAZINE
3
CREATING THE PERFECT
HOME OFFICE SPACE With growing numbers of people regularly working from home, it’s important to get the environment just right
CHOOSE THE RIGHT SPACE
With an ever-growing number of Brits now working from home each week, especially those whom after Covid-19 may not be going back to the office, it is important to create the right working environment. With the benefits from homeworking ranging from saving money on the commute to being in for deliveries and the school run, it is easy to see why so many people have jumped at the chance. But what should you consider when converting a room into a home office?
4
PROPERTY NEWS
Choosing the right space is the first important decision to make. It’s not just about fitting into any space; you will, after all, be spending most of your working day in there! If you’re able, choose a room that has some natural light coming in and that will be big enough to accommodate a desk, chair and storage – depending on your needs, of course. Once in, decide the best layout. For some, a view into the garden is nice, for others, however, it can be a distraction. It is worthwhile trying out a few different layouts before settling on one.
CREATE THE PERFECT ENVIRONMENT
As you will be spending a good deal of time working in your chosen room, it’s vital that you create the perfect environment so that your productivity isn’t impacted. An uncomfortable and incorrectly positioned chair can lead to repeated shuffling to get comfortable, leading to distraction and a lack of desire to lock yourself away in your office and get the job done. Likewise, try to remove other distractions such as TVs. The same ethos applies to your desk. Work out how much space you need. Is it just a laptop you need the space for, or will you be using it to organise paperwork? Perhaps you need two screens? Whatever your needs, ensure you have a desk that is up for the job. When it comes to decorating your room, go for it. A simple, plain room may look like your office back at work, but now you are at home you can install some of your own personality into it. Why not get some printed wallpaper to give the impression of a library or go for your favourite calming colour.
KIT IT OUT
OK, so you know what you need, now it’s time to kit out your office. With internet shopping, you no longer need to rely on a trip to Ikea to get the office furniture you need. It’s always a good starting point but why not try the likes of www.wayfair.co.uk, www.officefurnitureonline.co.uk or www. ryman.co.uk to name but a few. Of course, you can always stay local with second-hand furniture shops or even Facebook Marketplace for everything you need. Again, work out what you need before you buy so you don’t end up buying more than you need. Another handy tip is to invest in some shelves. These are great space savers and also create a really nice,
stylish backdrop for Zoom and Skype meetings when full of books.
STORAGE DELIGHTS
Keep it tidy and keep it simple! There are plenty of storage solutions out there for your home office space. And if floor space is limited, utilise wall space instead with bookcases or wall storage. Buying a desk with storage drawers and cupboards can also be highly beneficial. Also, try to keep your office stuff in your new office. You don’t want to be rushing all over the house looking for stationery equipment or paperwork in the middle of a busy task you need to concentrate on. Folders, units, shelves and drawers are a necessity now that you are working from home to keep organised.
GET CONNECTED If your broadband speed isn’t up to scratch it can be frustrating. Employers are likely to call you back into the office if your speed can’t handle the work you need to do. Alternatively, if you use Skype for business, a poor broadband speed could seriously hinder any meetings you have planned.
As you will be spending a good deal of time working in your chosen room, it’s vital that you create the perfect environment so that your productivity isn’t impacted.
Slow broadband speed is a big turn off. Luckily rural countryside areas are finally catching up with inner-city speeds. Comparison websites such as Uswitch and Compare the Market will show you the best deals and estimated speeds in your area in minutes. Not only do you need a fast broadband speed, but you also want one that is consistently good from morning to evening. So check reviews on websites in regards to reliability and not just speed.
LIFESTYLE MAGAZINE
5
HOW TO CARVE
A PUMPKIN
THIS HALLOWEEN
With Halloween coming up, there is nothing that symbolizes this holiday better than a carved pumpkin…
W
hether you want to create a simple jack-o-lantern or something a little more artistic, here are some hints and tips that will help you out. As anyone who has ever carved a pumpkin already knows, it can be a messy job and tougher than first expected.
USE THE RIGHT PUMPKIN
When picking a pumpkin make sure you get to the shops early and pick one that is fresh, unbruised and has both a sturdy stem and a flat bottom. You’ll want the flat bottom, especially so that it stays stable when carving and doesn’t roll when you have finished and put it on show.
CUT FROM THE BOTTOM
Yes, you read that right, when making your first cut, choose to create the lid at the bottom of the pumpkin. This will help stop your pumpkin from caving in at the sides and you will also avoid the fiddliness of putting the lid back on after it has been cut.
SCOOP OUT THE PULP AND THIN THE WALLS
Ensure when you are inside the pumpkin that you scoop out all the pulp and seeds. You can get a special
6
PROPERTY NEWS
‘pumpkin’ claw for this job, alternatively, a great tool most people have at home already for this job is an ice cream scoop. When scooping out also thin down the inner wall of the ‘face’ area so it will be easier to cut.
When making your first cut, choose to create the lid at the bottom of the pumpkin
SKETCH OUT YOUR DESIGN
On a piece of A-4 paper, sketch out your spooky design. Ideally do this to the size of the pumpkin, covering the whole piece of paper so when the time comes you can tape the sketch onto the ‘face’ of the pumpkin. You will then be able to use this as a guide when it comes to actually cutting out the pumpkin.
MAKE ROUGH CUTS FIRST
Holding the pumpkin in your lap for stability, start by making the largest,
OTHER HINTS AND TIPS Use the scraps of the pumpkin to make a tongue, hair accessories etc, for the pumpkin. Spread petroleum jelly on the cut edges to seal in moisture and keep your jack-o-lantern fresh. Create a chimney. When you first light a candle inside, let it burn for a few minutes and then check where it has blackened. Then simply create a small hole in that area to act as a chimney.
simplest rough cuts using a serrated kitchen knife. By getting the bigger pieces out of the way, you can then go back and neaten up the edges and details later using a small saw or sharp non-serrated knife.
AUTUMN HALF-TERM DAYS OUT With half-term already approaching, we thought we’d take a look at some of the awesome family days out available this year
Treat the little-ones this half term, especially after starting school and the craziest of the past 6-months, with a day out at Legoland, Windsor. Legoland is the ultimate experience for kids of all ages, and let’s face it, what child doesn’t love Lego!
The York Dungeon is a journey through 2000 years of York’s darkest history, bringing together iconic characters, immersive sets and thrilling special-effects in a unique actor-led experience. While there you will meet characters such as the Black Jester, Jorvik and Guy Fawkes, and visit locations such as the Torture Chamber and the Courtroom.
The theme park offers day passes and annual passes as well as mini-staycations and short breaks which are great for half term and getting away. They have also introduced new attractions such as the World’s First DUPLO Coaster, DUPLO Playtown, The Frog Prince at the DUPLO Valley Theatre alongside favourites like LEGO NINJAGO The Ride, Miniland, Viking River Splash and expect there to be spooky goings-on throughout the park in October.
Aimed at older children, the York Dungeon is a great and informative day out, while educational at the same time (just don’t tell the kids) and fits in nicely with Halloween coming up. In all, there are 9 live actor shows, specially designed sets and gripping storytelling from a professional cast. Tickets need to be booked online and cost £11.95 for children (aged 5-15 years) and £15.10 for adults. The Dungeons also offer similar attractions in London, Edinburgh and Blackpool.
incredible underwater world as part of their mission to inspire a love for the ocean and its creatures.
There are a dozen Sealife centres in and around the UK and they are some of the most beloved and well-visited attractions in the UK. Each year, they welcome over 20 million explorers into their
Each centre offers expert daily talks, self-guided tours and workshops and multimedia experiences like Shark Mission and Art Aquarium alongside all your favourite sea creatures including sharks, seahorses, penguins, turtles, clownfish, jellyfish, rockpool creatures and rays. You will need to book online for tickets and they offer general admission, adult and child tickets, annual passes and the Merlin Annual Pass which gets you into other great attractions too.
LIFESTYLE MAGAZINE
7
STYLISH WALLPAPER IDEAS AND TRENDS
Looking at decorating a living room, home office or bedroom this year? Let’s take a look at some of the hottest trends!
S
tylish and trendy wallpapers have never been more popular. A few years ago, the trend was for neutral shades of paint etc, however, times have changed and, as such, so has interior design, with modern design now leaning towards expressions of individuality. And there is no better way to show your individuality than with printed wallpaper.
ABSTRACT WALLPAPER PATTERNS In a digital world, it is no surprise to see geometric, abstract patterns coming to the forefront of interior design. They offer a futuristic, yet stylish dĂŠcor for home offices and bedrooms. Check out this design from www.iwantwallpaper. co.uk by Debona.
8
PROPERTY NEWS
ORIGINAL PRINTS With day-to-day life more stressful than ever, designers are advising not to bring the stress home with you. Fill your home, especially your living room, with original wallpaper prints offering custom designs, unexpected colours and unusual textures. Here’s one we think you’ll love from www. contrado.co.uk
ECO-FRIENDLY MATERIAL We’re all trying to do our bit for the environment, so why not try an eco-friendly wallpaper. Naturalism works really well with eco wallpapers and they work perfectly in rooms which receive ample sunlight. www.farrow-ball.com offer some great, naturalist, ecofriendly wallpapers with their handcrafted ‘greener’ options.
LUXURY WALLPAPER Luxury, designer wallpaper is a sure-fire way to add some flair to your home. The wallpaper will immediately turn any room into a sophisticated one. Again, geometric patterns are in favour for the future with lots of golds and dark greens. Head over to www.grahambrown.com to find a huge selection of some of the most stylish luxury wallpaper available anywhere.
LIFESTYLE MAGAZINE
9
HALLOWEEN PARTY AT HOME H
Halloween will, like most of 2020, be a different experience this year, however, we have a great guide to make it special at home‌
alloween has always been about Trick-or-Treat, pumpkins and decorating your house, however, this year, with Trick-or-Treating all but off the schedule, we thought we would look at the ways to have a great Halloween party at home with your immediate family.
DECORATIONS First things first, you will need to get a whole lot of decorations. Budget shops such as Poundstretcher and B&M are great places to pick up one-off decorations for your house. To make it a family affair, why not make DIY decorations. This is a great way to keep children entertained and build excitement for Halloween this year. Glow in the dark paint and stickers are great to stick onto black paper and then cut off to make dangling decorations such as skeletons, ghosts and witches which look great hanging from doors, in windows and in the centre of the room.
10
PROPERTY NEWS
Start putting the decorations up early to create a build-up to the event itself which will help get the kids excited and forget about the potential lack of Trick-or-Treating this year‌
TRICK-OR-TREATING With Trick-or-Treating probably off the menu this year due to social-distancing, why not create an Easter-style egg hunt around your home with a spooky candy hunt? You can set up clues that lead around the house with spooky goings-on around the home, almost like Scooby-Doo. Kids will love finding sweets and treats amidst all the spooky decorations.
FAMILY PARTY GAMES After the Trick-or-Treat hunt, why not have some fun and games as a family, while enjoying those sweet treats.
BEAN BAG TOSS This game is really simple and utilises carved pumpkins and Trick-or-Treat buckets. Each player has three shots to get their bean bags into either the buckets or carved pumpkins for a certain amount of points. And even better, once you have finished, you can add a tealight and put the pumpkin on show!
EYEBALL PONG Similar to beer pong for adults, paint spooky eyes on table tennis balls and take it in turns to bounce the eyeballs on a table and into a cup. Have a prize for the most balls in a cup each turn – obviously not beer if you’re playing with the kids!
GHOST AND PUMPKIN BOWLING Dependant on whether a new toilet roll shortage has started again, paint ghoulish faces onto 10 toilet rolls and stack them in a pyramid. Then, using a pumpkin with a spooky face painted on and with the stalk cut off, see how many toilet rolls you can knock over each go.
PARTY TIME Now is the time for some classic fun and games. Turn the family-friendly, spooky music loud and dance around the house. You can incorporate musical statues at any time, stopping the music and watching who freezes like a ghost! See who can dance like a zombie or a mummy the best and let the kids go crazy working off the sweets in their systems.
CHILLOUT TIME After all that fun and excitement, now is the time to chill. There are a huge number of familyfriendly spooky films on Sky, Netflix and Amazon Prime. Some of the classics include Casper the Friendly Ghost, The Haunted Mansion and The Witches. Perfect for a family cuddle on the sofa under a blanket whilst eating all those sweet treats, including some of the fabulous recipes on pages 14&15. It may not be the same as going out in the local community and Trick-or-Treating with friends, however, with the current, ongoing situation, we hope some of these ideas will help you celebrate Halloween and create a fun evening for the kids this year!
LIFESTYLE MAGAZINE
11
OCTOBER SPORTING EVENTS With the emergence of Autumn and a busy sports calendar now reopen, let’s have a look at some of the biggest events this month…
LONDON MARATHON
NATIONS LEAGUE
Virgin Money, who host the event, has set up a virtual event this year taking place on the same day. General entries are now closed, however, you can still enter by running for a charity. Entrants will have 23 hours 59 minutes and 59 seconds to complete the 26.2 miles by walking, jogging or running.
England were drawn against Belgium, Denmark and Iceland who they will play both home and away, with the four group winners qualifying for the UEFA Nations League Finals which feature semi-finals, a third-place match and the final. At the end, the ten group winners advance directly to the World Cup finals for 2022.
The 2020 London Marathon will be a marathon like no other due to Covid-19. This year, only elite athletes will run the 26.2-mile course through the capital. The course will be spectator free and follow a different course from the usual one. However, non-elite athletes will still have a chance to compete in the 40th race.
MARATHON & VIRTUAL EVENT
The Nations League kicks off again this month. It is the second edition of UEFA’s newest national-team competition. 55 teams have been split into four leagues according to their position in the 20/21 UEFA Nations League Access List and the teams were then split again into four pots in each league.
FIXTURES
Virgin Money London Marathon 4th October 2020.
England V Belgium 11th October 2020 @ 17:00
CORRECT AT TIME OF GOING TO PRINT
England V Denmark 14th October 2020 @ 19:45
12
PROPERTY NEWS
FORMULA 1
The Formula 1 season is in full swing and is showing no let-down in October, with three races over the month. As it stands, Lewis Hamilton is top of the driver standings closely followed by Valtteri Bottas and Max Verstappen, while Mercedes are top of the Team Standing ahead of rivals Red Bull. First up this month is the Eifel Grand Prix on the 9th to the 11th October. The race will be held at the Nürburgring this year. After this, we have the Portugal Grand Prix which will be held on the 23rd to the 25th October at Portimao. Before finishing with the Italian Grand Prix on the 31st October till the 1st November in Imola.
RACE LIST Eifel Grand Prix. 11th October 2020. Nürburgring. Portugal Grand Prix. 25th October 2020. Portimao. Italian Grand Prix. 1st November 2020. Imola.
POWER WOMEN AT THE BOX OFFICE October is the month where some of the most powerful women in the world are taking over at the Box Office.
I
t’s been a strange year, especially for cinema where most movies stopped production during the Covid-19 pandemic. With cinemas now open, studios are finally ready to unleash their big guns. And there are none bigger than the following leading ladies.
WONDER WOMAN 1984
First up is the long-awaited Wonder Woman sequel, Wonder Woman 1984. Patty Jenkin’s sequel has been delayed due to Covid-19 more times than anyone cares to remember, but as of writing, it is due to be released this month. Wonder Woman 1984 will pick up in the 1980s, where she will be united with Chris Pine’s Steve Trevor from the first film. When released it will be the second DC film of the year after February’s other girl-power blockbuster Birds of Prey
starring Margot Robbie. This time, Diana Prince, aka, Wonder Woman will be facing off against Pedro Pascal, from Game of Thrones fame, as Max Lord, and Kristen Wiig, from Bridesmaids, as Cheetah. Gal Gadot is back as Woman Woman after her previous outings in the first Wonder Woman, Justice League and Batman V Superman. Warner Bros is hoping the sequel will do similar business as the original which took $822 million worldwide in 2017.
BLACK WIDOW
Next up is Marvel’s Black Widow. Scarlett Johansson has played the character since she was first introduced in Iron Man 2 way back in 2010. Since then she has appeared in 8 further MCU movies, where we have had clues to her background, but nothing
concrete. Black Widow promises to change that with an in-depth look into Natasha Romanoff’s background. For the movie, we are going back in time, for obvious reasons, (spoiler alert) to the aftermath of Captain America: Civil War from 2016. New characters are going to be introduced including David Harbour, Stranger Things, Rachel Weisz, The Mummy, and Florence Pugh, Little Women. Originally due to be released in May, the official release date now is the 28th of October. The bad guy has already been announced as Taskmaster, a character more famous from the comics as he has yet to be seen on the big screen. He can mimic any physical movement he sees, except anything supernatural. But who is the actor behind the mask? That is a question that is still yet to be answered.
LIFESTYLE MAGAZINE
13
Make the most of your Halloween party this year with these ghoulishly great, spooky recipes.
SPOOKY HALLOWEEN RECIPES
N
o Halloween party is complete without a scary selection of creepy cupcakes, candy apples and devilish dinners. Here we have put together the best selection of recipes to ensure your spooky night goes off without a hitch.
70g butter 50g peanut butter 150g golden caster sugar 1 medium egg 1tsp vanilla extract 180g plain flour ½ tsp bicarbonate of soda 20 peanut butter cups, Maltesers or Rolos 100g milk chocolate Icing sugar 8 red apples 400g caster sugar 1tsp lemon juice 4tbsp golden syrup 8 sticks, chopsticks and lolly sticks
SPIDER BISCUITS Preheat oven to 180c/160c fan and line two baking sheets with parchment. Cream the butter, peanut butter and sugar together until fluffy, then beat in the egg and vanilla. Once combined, stir in the flour, bicarb and ¼ tsp salt. Scoop 20 tbsps of the mixture onto the trays leaving enough space between each. Bake for 10-12 minutes or until firm at the edges but soft in the middle. Leave to cool before topping each biscuit with a peanut butter cup, Malteser or Rolo. Melt the milk chocolate before scraping into a piping bag and then add the legs onto each spider before finally adding icing eyes.
CANDY APPLES Remove the stalks from the apples and put them in a heatproof bowl. Pour over boiling water and cover and leave for 3-4 minutes. Remove with a slotted spoon and pat dry. Push the sharpest end of each stick into the stalk-end of each apple. Tip the sugar into a large saucepan, add the lemon juice and 100ml water. Bring to a simmer and cook until the sugar has dissolved. Add the golden syrup and simmer again. Test the toffee by dropping a small amount into cold water, if it doesn’t harden immediately and become brittle when removed, it’s not ready yet. Dip each apple into the toffee. Lift out and allow any excess to drip off before placing on baking parchment to set.
14
PROPERTY NEWS
135g pack of lime jelly 700ml apple juice 300ml lemonade 435g can lychees in syrup 10 cocktail cherries 10 raisins
EYEBALL COCKTAIL Make the jelly following the pack instructions and chill until set. Combine the apple juice with the lemonade in a large jug and chill. Drain the lychees and poke a hole in each cherry with one of the cocktail sticks. Put the cherry inside the lychee, then push the raisin into the cherry. These are your eyes. Press each one onto the end of a cocktail stick and set aside. When the jelly has set, use a whisk to break it into small chunks. Spoon the cocktail into glasses and tup up with the apple and lemonade mix. Put an eyeball into each glass before serving.
TO DECORATE:
HAUNTED GRAVEYARD CAKE
1 egg white 50g icing sugar 200ml single cream 200g dark chocolate 125g rich tea finger biscuits 100g double chocolate cookies 25g white chocolate silver balls to decorate
Preheat the oven to 110c/90c fan. Whip the egg whites in a bowl until stiff
FOR THE CAKE:
Turn the oven up to 180c/160c fan. Tip the cocoa powder, self-raising flour
85g cocoa powder 200g self-raising flour 375g light brown muscovado sugar 4 eggs 200ml milk 175ml vegetable oil
peaks form. Whisk in the sugar a tbsp at a time and keep whisking until the mixture is thick and resembles shaving foam. Spoon the mixture into a large freezer bag and cut a 1.5cm hole in one of the corners. Cover a baking sheet with some baking parchment and carefully squeeze a small circle of whipped egg white out of the bag, pulling upwards as you do to make a ghost shape. Repeat until you run out of the mixture. Bake for 1 ½ hours until crisp. and sugar into a large bowl, breaking up any sugar clumps. Mix together the eggs, milk and oil in a bowl then pour over the dry ingredients and stir evenly until smooth. Grease and line a deep baking dish with parchment and then pour the mixture in and bake for 30 minutes. Leave to cool and turn out onto a serving plate. Heat cream in a saucepan until just boiling. Place the dark chocolate in a large bowl and pour over the hot cream. Stir until melted, then use a clean brush to paint a layer over 7 rich tea finger biscuits, then set aside to cool. Pour the remaining chocolate over the cake and smooth over with a knife. Whizz or bash the chocolate cookies until small crumbs form and then sprinkle over the cake. Place the white chocolate in a bowl over a pan of simmering water. Once melted, spoon into a freezer bag and wait for 10 minutes until it is no longer runny. Put a tiny hole in the corner of the bag and pipe two blobs onto each ghost and place a silver ball onto each to make eyes. Write on the gravestones, leave to set and then push the biscuit gravestones into the cake.
All recipes are from the www.bbcgoodfood.com website Images for illustrative purposes only
LIFESTYLE MAGAZINE
15
Autumn 2020
Mortgage & Protection news
mortgages
The newsletter from Xact Mortgages Limited
Even in a normal marketplace it makes sense to seek advice for your mortgage and protection needs - and this, of course, isn’t a normal marketplace.
»
For this reason, you may feel confused about identifying the best way forward. With our extensive knowledge of the overall marketplace, this is where we can help. You may also have concerns, for example, if you’ve been furloughed, are a first-time buyer, are self-employed, or have taken a mortgage payment holiday. Whilst we can’t resolve every issue, we’re fairly adept at finding solutions. Although, even in our shoes, it can be hard to keep up. With lenders withdrawing from certain markets, then returning; products that were available at 8am, then unavailable at 8.15am; and so on.
Housing mini-boom On the upside, the Chancellor recognised early on that the property sector can be the perfect engine to help the economy to recover. It’s partly for this reason that the Stamp Duty reduction was introduced (see box item), which could deliver a saving of up
Xact Mortgages Limited 6 The Square, First Floor Solihull B91 3RB Tel: 0121 712 6230 Email: sales@xactmortgages.co.uk Web: www.xactmortgages.co.uk
Lots to Consider to £15,000 until 1 April 2021, when the
previous rates will be reapplied. If you then add the pent-up demand from the lockdown period, along with a reassessment by many on how they want to live their lives, it helps to create a buoyant property marketplace. Figures from Rightmove endorse this. Homemovers have put more property on the market, and agreed more sales than in any other month since tracking this data for the last 10 years - worth a record £37bn! More recently, Nationwide’s house price figures set out a 3.7% UK-wide annual growth for August, and a monthly rise of 2%, equating to the highest monthly increase since February 2004. (Sources: Rightmove, August 2020; Nationwide, September 2020 release)
Continued on the next page
You may have to pay an early repayment charge to your existing lender if you remortgage.
STAMP DUTY Applicable to a residential property purchase in England and Northern Ireland. Up to £500,000 The next £425,000
0% 5%
(the portion from £500,001 to £925,000)
The next £575,000
10%
(the portion from £925,001 to £1.5m)
The remaining amount
12%
(the portion above £1.5m) ■ This is applicable on purchases up to 31 March 2021, and thereafter it reverts to the rates in place prior to 8 July 2020. ■ Add a 3% surcharge to the above for those buying an ‘additional’ property. (Source: GOV.UK, 8 July 2020)
HM Revenue & Customs practice and the law relating to taxation are complex and subject to individual circumstances and changes which cannot be foreseen.
■ Xact Mortgages Limited is an appointed representative of PRIMIS Mortgage Network (PRIMIS), a trading name of First Complete Limited which is authorised and regulated by the Financial Conduct Authority. PRIMIS is only responsible for the service and quality of advice provided to you in relation to mortgages, protection insurance and general insurance products. Any other product or service offered by Xact Mortgages Limited may not be the responsibility of PRIMIS and may also not be subject to regulation by the Financial Conduct Authority. ■ This firm usually charges a fee for mortgage advice. The amount of the fee will depend upon your circumstances and will be discussed and agreed with you at the earliest opportunity. ■ Your property may be repossessed if you do not keep up
repayments on your mortgage.
Lots to Consider
(contd)
Continued from the previous page
What does it mean for you? The positive developments above need to be balanced by what may be ahead. We can’t lose sight that we’re in a recession, and there will be further job losses as the furlough scheme stops in October. Plus, as the mortgage payment holiday initiative nears an end, this too may bring problems. These events are likely to have an impact on the property marketplace. Also, no-one quite knows how COVID-19 will play out. However, it’s not as if the government and lenders aren’t aware of the issues and both are keen to deliver support. With regard to what’s on offer from lenders, there are still some excellent mortgage deals out there. The lower the percentage of loan that you need, the greater the likelihood that there will be a wider range
of products on offer, a decent rate and the possibility of being accepted for a loan. BUT - rates are starting to creep up.* AND - the strict rules applicable to ‘evidencing of income’ and ‘affordability’ still apply across the board. (Source: *Moneyfacts, 7 September 2020 release)
Other positive initiatives In addition to the colossal amount of money that the government has pumped in to help us through this crisis, there are additional initiatives that would also be of interest to existing and potential homeowners. The government intends to make the planning process easier for those that might want to add, for example, additional space above their current home, subject to
neighbour consultation. Additionally, it wants to deliver greater freedom to adapt the use of vacant buildings and land in town centres to create new residential properties. The smaller renovation projects may be easily covered from existing savings, or even money saved from not going on an overseas holiday! For the bigger projects, then talk to us about a mortgage or remortgage to help raise the funds needed. Finally, from the end of September, you can apply for government vouchers under the Green Homes Grant. Against certain criteria, this will provide £2 for every £1 homeowners and landlords spend to make their homes more energy efficient, up to £5,000 per household. Or, in the case of those on the lowest incomes - up to £10,000. It’s applicable in England - but similar schemes may exist elsewhere in the UK. Do get in touch to see how we can help. You may have to pay an early repayment charge to your existing lender if you remortgage. n Your property may be repossessed if you do not keep up repayments on your mortgage.
UPDATE... Furloughed Workers n In total, around 9.6m jobs were furloughed. By September, this number had reduced to around 4m. (Sources: GOV.UK, August 2020, Office for National Statistics, September 2020)
n From 1st July, furloughed workers were able to return to work part-time, with the employer paying for the days worked, and the furlough scheme covering the rest. That said, until the end of October - the furloughed worker could receive 80% of their wages up to the capped monthly figure of £2,500, if furloughed 100% of the time. n From August, employers were asked to pay NI and employer pension contributions.
n In September the level of contribution changed. HMRC reduced its payment to 70% of wages for the hours the employee does not work (with employers contributing the 10% difference). n In October, this scenario will reduce to 60% of wages, with employers paying 20%. n After the planned ending of the scheme in October, the government has created a Job Retention Bonus to help ensure as many furloughed workers as possible return to (and remain in) the workplace. This will provide a one-off bonus of £1,000 for the business. It would apply to each furloughed employee (who’s paid over £520/month) that’s still employed as of 31 January 2021.
FUTURE MORTGAGE ISSUES n For those that have been on furlough, different lenders have set different criteria with regard to assessing income and affordability. n Some may want the employer to top up the salary to qualify, or may restrict the loan-to-value offered to around 85%. n Others may want to see a fixed ‘return to work’ date.
In short, it’s a complex situation, but options may well exist with lenders who are happy that you meet their criteria.
So do talk to us and let us do the legwork for you.
Screen Time! We can provide advice on both your mortgage and insurance requirements in a way that best meets your needs - by phone, email, videoconferencing or possibly a socially-distanced meeting.
»
One key piece of advice - unless there are mitigating circumstances - is not to sit on your lender’s Standard Variable Rate (SVR) once you come to the end of your deal period. As the chart below shows, you’ll be paying around twice as much in interest! Average Fixed Rates vs. Standard Variable Rate (SVR) 7 September 2020 2-year fixed rate
2.24%
5-year fixed rate
2.50%
SVR
4.44%
what we’ve established with regard to your financial position and particular needs. Also, we’d endeavour to help reduce the hassle of filling out forms. Plus hold your hand throughout the process, and liaise with the various parties along the way. So, irrespective of whether you’re new to property buying, or an old hand, we have experience of dealing with all types of clients, enabling us to work towards identifying a suitable product for you.
What if life goes wrong?
(Source: Moneyfacts, 7 September 2020)
Naturally, there are fees to pay with a new deal, so you need to do the maths. Our discussions would also cover issues such as the merits of a fixed vs. tracker mortgage, and the length of the mortgage deal, such as the 2 or 5-year plans above.
The process Of course, you can undertake this yourself. However, you don’t want to make too many unnecessary applications, which may have a negative impact on your credit rating. That’s why it makes sense to ask us to assess the wider marketplace in light of
The current challenging times may well have focused your thoughts on having some protection insurance in place. This could be life cover to deliver a lump sum to your family, if the insured person dies. Or insuring yourself against suffering a critical illness, or being off work long-term due to illness or injury.
Already have cover in place? Even here it’s worth having a conversation (if it’s not a policy that we’ve recently set up), as there’s been so much innovation over the last few years. With many policies
now fully recognising mental health issues, plus lots of value-added benefits, such as medical advice and fitness support. Also, as a consequence of the current crisis, you may even be thinking about saving money and cancelling a policy. This could then prove to be more expensive, with more caveats, and an age weighting, should you return to start a new one with the same insurer. The insurers are mindful of this and some will allow you to stop paying premiums for an agreed period, with certain rules. As with all insurance policies, terms, conditions and exclusions will apply. You may have to pay an early repayment charge to your existing lender if you remortgage. n Your property may be repossessed if you do not keep up repayments on your mortgage.
UPDATE...
Mortgage Payment Holidays n Around 2m mortgage customers (including buy-to-let borrowers) have taken a mortgage payment holiday*, and for those that haven’t, they may be able to apply for one up to the 31 October 2020. n However, whilst it shouldn’t affect your credit rating, do consider if it’s the most suitable route forward for you: (i) As it’s not so much a ‘holiday’, but more a mortgage payment ‘deferment’. (ii) You need to agree this with your mortgage lender, so you can’t just stop making payments. (iii) Lenders may ask if you participated and may factor that into future loan applications.
THE FUTURE n Whilst over 70%* of participants have
A record 98.3% of all PROTECTION CLAIMS are met - equating to a sizeable £15.8m a day in payouts, and how that plays out for the key sectors are as follows: LIFE COVER n 99.6% of all Life claims n Average payout of:
£77,535 (term) £3,465 (whole of life)
CRITICAL ILLNESS n 91.6%
of all Critical Illness claims n Average payout of £67,573
INCOME PROTECTION n
87.2% of all Income Protection claims n Average payout of £17,729
(Source: Association of British Insurers, 2019 data, May 2020 release)
returned to making full mortgage payments, the Financial Conduct Authority recognises that some may require further help and has asked lenders to deliver structured payment plans. n However, this support will come at a price, including being flagged on your credit file. (Source: *UK Finance, August 2020)
Finding a Way... In a recession, lender’s enthusiasm to lend to First-Time Buyers tends to wane. The upside for the first-time buyer is that property prices generally drop - yet the opposite is occurring at the moment!
»
That said, the government recognises that the first-time buyer is an important cog in helping to keep the property market moving. To assist this process there are various government schemes across the UK that are designed to help get the first-time buyer onto the property ladder. When you consider that the average monthly rental price for a new tenancy in the UK stands at £985, this may motivate many to want to buy a property and possibly pay less per month in the process. (Source: HomeLet Rental Index, August 2020)
Getting the Deposit together So, what’s stopping all renters jumping on board? Some will prefer the flexibility renting provides, others will be worried about the stringent controls that are now in place for mortgage lending. But possibly the biggest stumbling block is getting together the deposit. According to Moneyfacts, the average deposit for those buying their first home has risen to £47,059, equating to around a fifth of the average UK house price. Of course, there are mortgage deals available that require a
SHARED OWNERSHIP ■ A new Affordable Homes scheme announced in
September, will also deliver a new model for Shared Ownership for purchasing new homes, and will: - reduce the minimum initial share you can buy in a property from 25% to 10%. - allow people to buy additional shares in their home in 1% instalments, with heavily reduced fees. - introduce a 10-year period for new shared owners where the landlord will cover the cost of any repairs and maintenance. This scheme is applicable to England only, other parts of the UK will deliver different support.
smaller deposit, but this is where the lender’s enthusiasm has waned. Back in March (the month when lockdown started) there were 1,184 mortgage products requiring a 10% deposit, or less. By September, this had reduced to 76!! Rates have also increased. Back in March the average interest rate for a two-year fixed rate mortgage with a 10% deposit was 2.57% it’s now 3.54%. (Source: Moneyfacts, 7 September 2020) However, if you consider that the average first-time buyer loan is around £176,000*, then a 3.54% rate would equate to a repayment mortgage of about £800 per month. Unlike the £985 rental payment figure mentioned earlier, this lower amount would include paying off part of the capital borrowed, as well as the interest owing. (Source: *UK Finance, January-June 2020)
Look at alternative funding options If you’re lucky enough, then there is the Bank of Mum & Dad to help get some, or all, of that deposit together. In fact, nearly one in four housing transactions (175,0000) will be backed by the Bank of Mum & Dad in 2020, equating to an average of around £20,000 each to help those borrowers with their deposits, and possibly gain access to better interest rates. (Source: Legal & General, September 2020) Alternatively, there are Guarantor Mortgages, which might be a more suitable route for family support. Or consider Shared Ownership, in which case you buy a percentage of the property now, and can purchase more into the future (see box item).
Talk to us With so much to consider, do have a conversation with us as early as possible in the decision-making process. We are working with these issues day-in/day-out, and fully understand the options on offer. And, as part of our offering, we would endeavour to help navigate you through the affordability, evidencing of income and credit rating hoops. ■ Your property may be repossessed if you do not keep up repayments on your mortgage.
Mortgages for the
Self-Employed Self-Employed workers have been hit hard by the onset of Coronavirus. In addition to the likely loss of business income, many would have fallen through the net with regard to obtaining government funding to help see them through. (see box item below)
»
The upshot of this is that we’ve seen a record quarterly drop of 238,000 in the number of workers that are self-employed - an amount that now stands at 4.76m. (Source: Office for National Statistics, Labour market overview, August 2020)
That said, it’s quite likely that many self-employed workers would have been fairly adept at swiftly restructuring their offering to ensure revenue continued to flow in. And, following lockdown, may be reassessing how and where they live, and looking to fund renovations, or seek a new property.
Stricter lending requirements However, even prior to COVID-19, the self-employed - which still represents almost 15% of the total workforce - had sizeable hoops to jump through to secure a loan.
Self-Employment Income Support Scheme ■ You may have been one of the 2.7m Self-Employed
workers that benefited from the First Grant. (Source: GOV.UK, 17 August 2020)
■ Either way, you can claim for the Second and Final
Grant up until 19 October 2020. ■ Eligible individuals can claim a taxable grant worth
70% of their average monthly trading profits, paid out in a single instalment covering three months’ worth of profit, and capped at £6,570 in total. To check if you qualify, please go to: www.gov.uk/guidance/claim-a-grant-through-the-selfemployment-income-support-scheme
The issue with lenders is that unlike assessing a payslip, the income stream of the self-employed is not as clear cut. This is compounded by the way some self-employed organise their payments to ensure they’re tax-efficient (such as more income via dividends than salary). This could work against them when wanting to demonstrate to a lender they have the ability to fund the loan they wish to take out. The term ‘self-employed’ can also present a problem for lenders, as it pulls together a whole host of different individuals. This could mean that a myriad of workers with differing income streams and earning potential are lumped together, resulting in the computer possibly saying: ‘no’.
Impact of COVID-19 Beyond this, the economic impact of the pandemic means that even more information is now required, such as: ■ wanting to know if the client has experienced a reduction in their self-employed income due to COVID-19. ■ is in receipt of the government Self-Employment Income Support Scheme, or a Bounce Back Loan. ■ were any of their staff furloughed (if applicable). ■ more recent bank statements, as the latest accounts would probably apply to the period prior to COVID-19. In short, mortgage providers are looking for proof the business is viable, and to understand how the pandemic has affected the work and income of the applicant.
How we can help We are already dealing with other self-employed workers, and know our way through this particular mortgage maze, and would approach the lenders that we know are more sympathetic to your particular situation. ■ Your property may be repossessed if you do not keep up repayments on your mortgage.
LANDLORDS have proved to be a fairly resilient group, and may have built up a greater resolve than most to face the current recession.
»
As it stands, in this strange property market, the average monthly rental income across the UK is still holding up at £985, up 1.5% year on year. In fact, 11 of the 12 regions all showed an increase, with the exception of Greater London - albeit the average rental value there was £1,653 - 100% higher than the figure for the rest of the UK (£825). (Source: HomeLet Rental Index, August 2020)
Financial stability of tenants The main concern for landlords into the near future will be hoping those rental payments continue to come through, as there’s the likelihood that some tenants will fall on hard times as the furlough scheme comes to an end, raising the possibility of void periods. However, it’s not just a case of ‘sit and wait’, as there are a number of initiatives landlords could undertake to help recessionproof their business.
Time to remortgage? Buy-to-Let mortgage rates remain low although - as with the residential sector - rates are starting to creep up. So, if you haven’t already assessed what’s on offer, perhaps it’s time to take stock. Dependent on the deal you’re on, there may be savings to be made. (Source: Moneyfacts, 8 September 2020)
Alternatively, you may want to consider pooling together your properties into one mortgage, but do be aware there are benefits and disadvantages of this course of action. The same can be said about considering a Limited Company structure to help mitigate the tax changes. As well as talking to your accountant about these issues, do get in touch with us, as we can look at your particular situation and help identify what may work best for you.
Make new investments, and/or restructure Landlords will also benefit from the short-term reduction in Stamp Duty fees. As was the case previously, the 3% surcharge still needs to added, but the current charges could deliver a substantial saving on a property purchase ahead of 1 April 2021.
With regard to purchasing additional properties, the normal disciplines apply, such as: - don’t buy a property that you’d like to live in yourself. You need to love the deal, not the property. - research the area and understand market conditions. - decide on the type of renter you want. Properties that can be let, for example, to multiple tenants, such as Houses in Multiple Occupation (HMOs) could help to spread the risk of any rental voids, as you’ll receive an income from various people. - shying away from student rents, in the current climate, and possibly being drawn to a slightly different form of renting holiday lets. The rise of the ‘staycation’ will increase the demand for this type of property. But again, talk to us, as this is a different form of borrowing compared to the normal buy-to-let loan process. There is no guarantee that it will be possible to arrange continuous letting of the property, nor that the rental income will be sufficient to meet the costs of the mortgage. The value of your Buy-to-Let property and income from it can go down as well as up. You may also require advice on the legal and tax issues. The Financial Conduct Authority does not regulate legal and taxation advice, and most Buy-to-Let mortgages. HM Revenue & Customs practice and the law relating to taxation are complex and subject to individual circumstances and changes which cannot be foreseen. You may have to pay an early repayment charge to your existing lender if you remortgage. ■ Your property may be repossessed if you do not keep up repayments on your mortgage.
Tel: 0121 712 6230 Email: sales@xactmortgages.co.uk
Steve Froggatt HOW LONG HAVE YOU BEEN WITH XACT? Been with Xact for 5 years WHAT DO YOU LOVE MOST ABOUT YOUR JOB? Helping people find the best deal in as simple a way as possible SOMETHING ABOUT YOU THAT PEOPLE WOULD BE SURPRISED TO KNOW? I met Nelson Mandela on an Aston Villa club tour in 1994 FAVOURITE FOOD? Italian FAVOURTIE TYPE OF HOLIDAY? Whale watching and shark cage diving in South Africa
Conor Brown HOW LONG HAVE YOU BEEN WITH XACT? 18 Months WHAT DO YOU LOVE MOST ABOUT YOUR JOB? Helping people get the best deal for their mortgage but also love making sure that everyone is fully protected SOMETHING ABOUT YOU THAT PEOPLE WOULD BE SURPRISED TO KNOW? I lived in America for 18 months FAVOURITE FOOD? Sunday Roast – so many flavours on one plate FAVOURTIE TYPE OF HOLIDAY? Disney Land as it is a real family holiday. I can’t wait to take my family there. However, I have always dreamt of going to Bora Bora
Colin Jones HOW LONG HAVE YOU BEEN WITH XACT? 5 years WHAT DO YOU LOVE MOST ABOUT YOUR JOB? Speaking to clients on a daily basis and giving them the peace of mind that should the worst happen they will be financially secure. SOMETHING ABOUT YOU THAT PEOPLE WOULD BE SURPRISED TO KNOW? I am a qualified Golf Instructor FAVOURITE FOOD? Italian FAVOURTIE TYPE OF HOLIDAY? Hawaii
Web: www.xactmortgages.co.uk
Meet our Advisors Lee Heycock HOW LONG HAVE YOU BEEN WITH XACT? Since December 2017 WHAT DO YOU LOVE MOST ABOUT YOUR JOB? Solving problems for people who are looking to move but don’t think its achievable SOMETHING ABOUT YOU THAT PEOPLE WOULD BE SURPRISED TO KNOW? Prior to Xact I served in the Infantry as a LCpl in the Royal Anglian Regiment where we toured Afghanistan, Nigeria and Kenya FAVOURITE FOOD? Sushi, looking forward to the new Japanese restaurant opening in Solihull! FAVOURTIE TYPE OF HOLIDAY? A cruise around Italy and the Greek Islands
Mike Hodgkinson HOW LONG HAVE YOU BEEN WITH XACT? 19 September 2001…Day one WHAT DO YOU LOVE MOST ABOUT YOUR JOB? I love putting smiles on our customers faces SOMETHING ABOUT YOU THAT PEOPLE WOULD BE SURPRISED TO KNOW? I have a gold medal for ballroom dancing watch out strictly here I come FAVOURITE FOOD? Sunday Roast FAVOURTIE TYPE OF HOLIDAY? Cornwall, have been lucky enough to travel most of the world, Cornwall is still the best
Dane McCarthy HOW LONG HAVE YOU BEEN WITH XACT? Since January 2018 WHAT DO YOU LOVE MOST ABOUT YOUR JOB? I enjoy interacting with all types of people on a daily basis FAVOURITE FOOD? Steak FAVOURTIE TYPE OF HOLIDAY? Anywhere in Scotland
The information contained herein is of a general nature and should not be relied upon as legal or financial advice and is not intended as a substitute for the same. You should seek professional advice tailored to your needs and circumstances before making any decisions. The contents of this newsletter are believed to be correct at the date of publication (October 2020).
mortgages
MAKE THE MOST OF YOUR TIME Don’t let the clocks be the only thing changing this month… Move with us and we will ensure your property move is as easy as possible, offering you exceptional customer service and innovative marketing options.
TAKE ADVANTAGE OF THE STAMP DUTY HOLIDAY
T: 0121 712 6230
E: sales@xactmortgages.co.uk W: xactmortgages.co.uk