

January has a habit of arriving heavy with expectation, ushering in a proverbial ‘clean page’ and no shortage of confident predictions about what the year ahead will bring. This year, as many of us are collectively wrapping up warm to combat Storm Gore i’s cold snap, the mortgage market itself looks set for a far more gradual thaw.
The past year did not deliver clarity so much as consolidation. Rates stabilised, activity levels found their feet, and sentiment improved in fits and starts rather than in sweeping turns. As a result, the industry enters 2026 be er conditioned than it has been for some time –more inventive in some places, and far more realistic about what real progress actually looks like.
While expectations of further base rate easing are building following December’s cut, 2026 is unlikely to be defined by dramatic shi s in pricing alone. Indeed, competition among lenders will remain healthy, but product design, criteria flexibility and service will increasingly do the heavy li ing where headline pricing cannot.
Housing supply, of course, remains the most stubborn subplot. The Government’s ambition to deliver 1.5 million homes continues to loom large, but delivery remains some distance behind rhetoric. As the second year of the parliamentary term draws to a close, that gap leaves ministers on increasingly unsteady ground – particularly against a political backdrop that is becoming
Jessica Bird Managing Editor
Jessica O’Connor Deputy Editor
Marvin Onumonu Reporter
Brian West Sales Director brian.west@astormedia.co.uk
Millie Sweetman Commercial Development Executive
Laura Strelconoka Campaign Manager
Ryan Fowler Publisher
Felix Blakeston Associate Publisher
Helen Thorne Accounts
nance@astormedia.co.uk
Orson McAleer Designer
Bryan Hay Associate Editor Subscriptions
subscriptions@theintermediary.co.uk
more fragmented, with Reform looming menacingly in the background and a reenergised Green Party under Zack Polanski a racting fresh a ention, particularly from idealistic Gen Zs like me, still harbouring the hope of owning our first home before the age of 50.
Against this backdrop, buy-to-let and the specialist sector are likely to remain important barometers of market health. This year, the rental market continues to contend with regulatory pressure from the newly passed Renter’s Rights Act, along with issues around constrained supply, bringing both opportunity and challenges alike. Specialist finance, meanwhile, shows li le sign of slowing its expansion, increasingly stepping in where mainstream criteria draw firm lines.
All of this makes our January State of the Nation feature particularly timely, as it cuts through the noise to assess where the market genuinely stands as we move into the new year. Elsewhere in this issue, we explore how lenders are approaching the 2026 market, the ever-increasing use of technology, and how advisers are positioning themselves for a year where client needs are broader, and o en more nuanced, than they first appear.
As the year gets underway, one thing is clear: the market may not be predictable, but it is moving. Our job, as ever, is to help you make sense of where it is headed.●
Jessica O’Connor

Shinwell | Adrian Moloney | Alistair Ewing
Alan Fletcher | Alex Curtis | Alpa Bhakta
Andrew Peters | Andy Mellor | Andy Neo
Averil Leimon | Charlotte Skinner
Claire Cherrington | Craig Hall | Dave Harris David Latimer | David Whittaker
Edward Checkley | Enzo Mora | Eric Bierry
Fran Afonso | Grant Hendry | Grant Holmes
Greg Bell | Greg B Davies | Helen Pierson
Ian Coulson | I hikar Mohamed | Jake Sandford
James Carter | James Wellman | Jerry Mulle
Julie Turner | Karl Rowlands | Laura Stone
Laura omas | Mark Blackwell | Mark Harris
Michael McCartney | Michelle Niziol | Nick Mendes
Oliver Lodge | Phil Saville | Philip Emanuel
Ray Palmer | Rebecca Wilkins | Richard Dana
Sebastian Murphy | Stephanie Dunkley
Steve Goodall | Terry Woodley | Tom Renwick
Tom Worbey | Tomer Aboody | Toni Smith
Tony Sutton | Wes Regis | William Reeve
Feature 20
STATE OF THE NATION
Sesame Bankhall Group gathers the expert view on the market at the start of a new year
A look at the practical realities of being a broker, from attracting the right talent to the monthly case clinic
This month The Intermediary takes a look at the housing market in Hull
On the Move 82
An eye on the revolving doors of the mortgage market: the latest industry job moves
OSB GROUP
Adrian Moloney discusses the launch of Rely, the use of technology and the group’s future plans
SUROS CAPITAL
Ray Palmer shares insights regarding the rise of luxury asset-backed lending
JLM MORTGAGE SERVICES
Sebastian Murphy shares his thoughts on the mortgage market, from regulatory barriers to current opportunities
LHV BANK
The LHV team discuss the bank’s recent growth and how it supports brokers through the case journey
SOPHISTICATED SUSSEX FINANCE LTD
Julie Turner talks opportunities, challenges and upcoming plans for her business



Andy Neo discusses the challenges and opportunities for

The regulator’s road map has landed, the Budget is behind us, and we’ve rounded off 2025 with a base rate cut to 3.75%. So, what does that mean for market activity next year? Here’s our top three expectations for 2026.
We now know that the Financial Conduct Authority (FCA) intends to consult on loan-to-income (LTI) limits, responsible lending rules and affordability for Retirement Interest Only (RIO) mortgages in the first half of 2026 with policy statements expected in the la er half of next year. These changes will allow lenders to innovate and, according to the FCA, “enable the mortgage market of the future.”
Not all changes in the Budget will a ect the market straight away [...] This, along with December’s base rate cut – and the expectation that there will be further cuts this year – is going to improve sentiment”
But lenders aren’t waiting for regulation to innovate. The lending market is teeming with people coming up with all sorts of ideas and I’ve not seen innovation on this scale and at this speed in all my time working in the industry.
Significant changes already this year include inroads in foreign national criteria, higher loan-to-values (LTVs) for new-build lending and in
particular flats. We’re certain, from the conversations we’re having with banks and building societies, that there’s more to follow. We know of one building society eyeing a move into slightly-higher-than-high-street levels of adverse credit – recognising the demand and the margins in this market. Another is weighing up an interest-only proposition for firsttime buyers which could offer a 35- to 40-year term with the first 10 years on interest-only, providing the mortgage is advised.
Our tip: Expect to see lenders pushing into market segments you wouldn’t expect them to operate in.
This year we’ve seen more lenders sign up to the same external system that allows them to make changes to their score criteria in a much simpler way. Rather than lenders making their own internal so ware changes which can be time consuming and costly, the external provider makes changes to their system. That way, all lenders signed up to the so ware can choose to adopt the credit scoring changes by tagging it on to their systems straight away.
This is the kind of technological innovation the market has been crying out for.
Lenders can quickly mirror others’ changes at a lower cost and scale quickly which we think is one of the reasons behind much more rapid innovation in 2025.
In 2026 – we expect to see more lenders adopt similar or the same technology which will make them more fleet of foot and able to respond quickly to broker feedback on what the market really needs.
A handful of builders told us that their web traffic died a death in the run up to the Budget and the December lull kicked in right at the start of the
HELEN PIERSON is director at Mortgage Advice Bureau New Homes
month. We’ve started to see an upli in our own mortgage enquiries but developers are telling us they don’t expect any significant progress until the New Year.
The Budget depressed a lot of people. Although it wasn’t as bad as feared, neither was there any major reason to feel optimistic.
There was a general feeling of ‘let’s enjoy Christmas – celebrate and be happy’, with thoughts of moving house postponed until at least midJanuary which is when developers expect to see enquiries begin to filter through.
We are expecting a busy Q1, but this January may get off to a slightly slow start.
Not all changes in the Budget will affect the market straight away – the ‘Mansion Tax’, for example, won’t take effect until 2028. This, along with December’s base rate cut – and the expectation that there will be further cuts this year – is going to improve sentiment, and that’s what drives demand.
From the end of January up until April – expect an active new-build market with developers ready to make some big deals at the end of April and into May to get sales over the line.
Continued base rate cuts next year, which may not directly feed into lower mortgage rates, will help to buoy sentiment among buyers and that, along with product innovation, will keep the market moving steadily into the la er part of H1. ●
For years, property data in the mortgage market has been something of a paradox. Lenders have always needed it, surveyors have always produced it, and brokers have always been affected by it. But much of the most powerful insight has historically arrived late in the process, o en a er a case is already emotionally and financially commi ed.
The rapid evolution of specialist data products like our own around cladding, construction risk and complex property types signal a very different future where property intelligence plays a central, proactive and real-time role in lending decisions.
I feel what we have achieved with our cladding and non-traditional housing datasets is more than a commercial success story. It is a glimpse into how the mortgage industry’s relationship with property risk is changing and this will bring about meaningful change for lenders, brokers and consumers.
The industry has long relied on traditional valuation reports to identify risks around cladding systems, structural materials and forms of construction that fall outside standard appetite.
But this approach has constraints, not least because it is manual, caseby-case and dependent on the timing of the physical inspection. The new generation of data products changes that dynamic.
Our datasets capture known cladding risks, construction classifications and historical valuation outcomes across large portfolios, creating a form of property intelligence that lenders can query instantly. Instead of waiting for a
valuer to identify a potential cladding concern or non-traditional build on a specific case, lenders can understand the risk profile before issuing making a decision, and increasingly before a full underwriting review.
One of the most powerful implications of these new datasets is that lenders can look beyond the four walls of a single property and see pa erns across their entire portfolio.
If lenders can understand not only the risk of this flat, but their exposure to all flats with similar characteristics, they gain a far more accurate view of balance-sheet resilience. They can moderate or increase appetite in real time, avoid over-concentration and make strategic decisions based on actual, rather than assumed, risk distribution.
What this means for brokers is earlier certainty and fewer surprises. While technology-led changes in lender decisioning sometimes feel like a black box, the growth of these property intelligence tools has the potential to bring the opposite more clarity, not less.
As lenders integrate new datasets into their pre-application or earlystage checks, brokers could receive earlier signals about which property types are unlikely to be accepted, where appetite is tightening due to portfolio exposure or which risks are emerging across the market.
In a world where data moves upstream, decisions move with it. This reduces the risk of late-stage declines, reworked applications and consumer frustration. It also allows brokers to guide clients with more confidence at the earliest stages of the journey.
Mortgage underwriting has traditionally been governed by
STEVE GOODALL is managing director at e.surv
The industry has long relied on traditional valuation reports to identify risks [...] but this approach has constraints”
static rules and criteria documents updated periodically. But property risk is dynamic. Housing ages, and occupants’ needs change. Construction methods evolve, cladding issues emerge, remediation programmes progress, and the performance of non-traditional housing types varies over time.
The evolution of our data products shows that the future of mortgage lending will be defined not solely by digital identity, income verification or automation, but by a deeper understanding of the asset securing the loan.
I believe that property data will become broader, deeper and more interconnected and that lenders will make decisions earlier using richer insight. This means that brokers will navigate lenders with greater foresight and underwriting will become more dynamic and portfolio-aware.
As property risk becomes more transparent, the entire mortgage value chain – from lenders to brokers to surveyors will operate with greater clarity, fewer surprises and more informed decision-making. The be er we understand the homes we lend against, the be er outcomes we create for consumers. ●
As the mortgage market moves into 2026, the balance of risks points towards gradual adjustment rather than a sharp shi in direction. Mortgage rates have eased from recent highs, competition between lenders remains evident, and refinancing activity is picking up. However, the conditions for a further rapid decline in pricing appear limited.
Market expectations continue to centre on Bank Rate reaching a low point somewhere between 3.00% and 3.25% during the course of this cycle, implying a small number of further reductions over the year ahead. That outlook is now well understood and largely reflected in wholesale funding markets.
As a result, many of the most competitive fixed mortgage rates already incorporate expectations of further easing. Mortgage pricing is inherently forward-looking, driven less by individual policy decisions and more by where markets believe interest rates will se le over the medium term.
From this point, fixed rates are therefore likely to fall by less than any further reductions in Bank Rate and may ultimately stabilise, or even edge higher relative to base, as expectations converge on a cyclical floor.
This dynamic helps explain why base rate changes do not always translate into immediate or uniform shi s in mortgage pricing. Unless expectations move decisively towards a materially lower terminal rate, the scope for further broadbased reductions in fixed rates remains constrained. From here, changes in pricing are more likely to be incremental, reflecting finetuning rather than a step change in market conditions.
For many households, 2026 is likely to feel more like a year of adjustment
than outright relief. A large volume of fixed-rate mortgages are due to mature over the year ahead, supporting elevated levels of refinancing activity.
The experience for borrowers will vary significantly depending on when they last fixed. Those coming off shorter-term deals arranged a er rates had already begun to rise should see some improvement in pricing, even if repayments remain higher than they were earlier in the decade. By contrast, borrowers reaching the end of longerterm fixes agreed when rates were near historic lows will still face higher repayments, even a er recent easing. For this group, refinancing represents a financial reset rather than a return to earlier conditions.
Competition between lenders remains one of the defining features shaping outcomes in the current market and continues to limit how far mortgage rates can rise. Funding conditions are relatively stable, balance sheets are generally robust, and lenders are keen to secure refinancing volumes in what remains a subdued transaction environment.
However, this competition is playing out in a market that is not expanding rapidly. Housing transactions remain below long-term averages and affordability constraints persist despite lower rates. In that environment, lenders are more likely to compete selectively rather than through across-the-board price cuts.
Sharper pricing is most likely to be concentrated at lower loanto-value (LTV) levels and among borrowers with strong affordability and straightforward income profiles. Pricing for higher LTV lending or more complex cases may improve more gradually. This reflects a disciplined approach to deploying capital and managing risk, rather than any broad tightening of credit standards.
NICK MENDES is mortgage technical manager at John Charcol
Beyond mortgages, there are early signs that the housing market is beginning to stabilise. Real house prices declined over 2025, but easing mortgage rates, some relaxation in affordability assessments, and incremental improvements in lending criteria are starting to provide support.
Modest price growth over 2026 now appears more likely than a renewed period of broad-based declines, although outcomes will continue to vary significantly by region and property type. More affordable areas are likely to perform more robustly, while higher-priced markets and flats may continue to lag behind houses.
Credit performance is also expected to remain relatively resilient. As cost and rate pressures ease, arrears should continue to trend lower, while any increase in possessions is likely to reflect a gradual normalisation from historically low levels rather than a deterioration in borrower resilience.
Taken together, these developments point to a market that is gradually finding its footing. Lender competition remains strong, refinancing activity is elevated, and the direction of interest rates is broadly supportive. However, the phase of rapid mortgage rate adjustment now appears to be behind us.
From here, progress is likely to be incremental, shaped less by shortterm policy decisions and more by how lenders compete for volume as interest rates approach their expected floor. For borrowers and lenders alike, 2026 looks set to be defined by greater clarity and a more stable, predictable backdrop than in recent years. ●
With the Financial Conduct Authority (FCA) recently easing some remortgage affordability rules, moving to a new deal is suddenly simpler for certain clients. As long as certain criteria are met, lenders can apply a Modified Affordability Assessment (MAA), essentially a lighter version of affordability checks.
This gives some borrowers greater flexibility to shop around and avoid being tied to the same lender if their circumstances change.
Although this may be welcome news for many mortgage customers, it remains for lenders to decide whether to apply the MMA, and standard checks will continue to apply where a borrower’s circumstances fall outside the permi ed criteria or have changed beyond the expected range.
So, with remortgaging potentially becoming easier for eligible clients, what does this mean for lenders and brokers? Could retention be trickier than ever?
In our H2 2025 Mortgage Lender Benchmark, we asked brokers about the trends they’re seeing this year when it comes to clients remortgaging to a new lender versus simply switching their deal.
The responses throw up some interesting results. Just under a third of brokers said they’re seeing about the same number of product transfers (PTs) and external remortgages.
A further 25% reported slightly more product transfers, while 17% saw slightly more external deals. Only 16% said they mostly stick to product transfers, and about 11% are mainly
seeing external remortgages.
The takeaway? Product transfers remain slightly more popular, with the simplicity of staying with the same lender still popular for certain clients. But there appears to be a growing appetite for external remortgages.
Brokers are weighing the practical benefits of product transfers against the potential advantages of finding clients a be er deal elsewhere. And if the FCA continues to ease affordability rules, that balance could shi further.
So, why are product transfers still favoured over remortgages? Because they’re fast, predictable, and hasslefree. More than 52% of brokers said retention and pricing were the main reasons they recommend a product transfer versus a remortgage.
Speed and service come next, with over 47% highlighting these factors. This is no surprise, given that product transfers usually involve less paperwork and no revaluation.
Despite the FCA’s eased rules, nearly a third of brokers said affordability barriers still make transferring products more favourable than remortgaging.
Meanwhile, around a quarter mentioned criteria fit and client preference.
The FCA’s review suggests further changes may be coming to responsible lending rules, potentially opening the door to even greater flexibility in affordability checks. If that happens, 56% of brokers predict a small shi towards external remortgages, while 16% foresee a large shi . Meanwhile, 27% expect no change.
For any serious shi , it seems the FCA may indeed need to ease things
JAKE SANDFORD is head of data and analytics at Smart Money People
further. Even with the current policy changes, half of brokers told us that meeting full affordability requirements remains the biggest blocker to remortgaging, suggesting the policy only helps a small proportion of clients.
Aside from affordability, packaging and document burdens were flagged by just over 42% of brokers. Valuation delays, lender service-level agreements and client reluctance were also mentioned.
These challenges help explain why product transfers continue to lead the way. As creatures of habit, brokers will stick with what works unless external switching becomes genuinely easier.
Looking ahead, retention via product transfers could be under real threat, especially if further affordability policy changes come in.
If remortgaging becomes even slightly easier, more brokers will feel confident exploring external options, and lenders won’t be able to rely on simplicity alone to keep clients from moving.
In the end, whether the rules change or not, lenders need to ensure their rates and propositions remain competitive. Understanding brokers’ needs and helping them meet their clients’ expectations will remain crucial for staying ahead of the competition. ●
In a challenging residential market, speed and certainty have never ma ered more.
Affordability pressures, conveyancing and mortgage approval delays are all contributing to extended lead times and a growing risk of sales falling through.
For housebuilders, these delays can impact on cashflow, build schedules and overall profitability.
One of the biggest causes of failed transactions in new-build developments is inadequate buyer qualification at an early stage. This is where new build specialist mortgage brokers like The Mortgage Brain step in. Unlike general advisers or high street lenders, specialist brokers working within new-build environments are focused on earlystage qualification. Their role begins as soon as a potential buyer expresses interest, usually before reservation.
By carrying out detailed affordability assessments and lender suitability reviews at the outset, specialist brokers can quickly establish whether a buyer is proceedable.
This means developers gain early clarity on which sales are robust, which may require further support or should not proceed at all.
We work directly with developers, providing dedicated advisers who are experienced in the sales environment. Our advisers understand the specific development, pricing structures, incentives and timelines, allowing them to align financial advice with the realities of the build programme.
If there is a build issue, we make sure a mortgage offer is valid throughout that process. So if a property won’t be ready for nine
months, we’ll find the right mortgage offer to cover that time. If a buyer goes direct to a lender or a non-specialist new build broker, they might find their mortgage offer expires and they have to start the whole process again.
Having dedicated advisers also improves coordination between sales teams, buyers, lenders and solicitors. Clients deal with the same adviser throughout the process and any issues are identified early, and conversations happen quickly. This integrated approach helps keep deals alive and progressing.
Where The Mortgage Brain works exclusively with a developer, our conversion rates are consistently higher than industry averages meaning that the vast majority of reservations progress to completion.
A sale that takes several months to progress provides far more opportunity for circumstances to change – interest rates adjust, buyer confidence weakens or financial situations alter. For developers, each fall-through represents lost time, additional marketing costs and uncertainty in sales forecasting.
Speed is not just about ge ing a mortgage offer; it is about keeping the entire transaction moving. Specialist new build brokers help reduce lead times by managing the mortgage process proactively, ensuring documentation is complete, and lender queries are addressed quickly. This benefits both sides of the transaction. Buyers experience a smoother, less stressful journey, while developers enjoy greater certainty and faster progression from reservation to exchange.
ENZO MORA is CEO and founder of e Mortgage Brain
Technology is another key differentiator. We use tech-enabled platforms to track buyer progress, manage documentation and share updates in real time.
We’re now working with our investor The Be erHome Group, South Africa’s biggest mortgage broker with 50% of the new-build market, to strengthen our digital offering. This allows all parties to remain aligned throughout the transaction.
Open communication is critical in preventing fall-throughs. When everyone understands where a sale stands and what needs to happen next, delays are reduced. Rather than relying on fragmented email chains or slow updates, a tech-enabled approach creates transparenc.
Our role becomes especially valuable in more complex cases, such as selfemployed buyers, those with nonstandard income, or purchasers using low deposit schemes or incentives. By managing these conversations early and transparently, newbuild brokers help prevent misunderstandings and last-minute withdrawals. For developers, this level of certainty translates into stronger sales pipelines and reduced reliance on remarketing.
For buyers, it means confidence, clarity and a smoother route to owning their new home. In a market where certainty is scarce, specialist mortgage brokers are becoming one of the most valuable partners a developer can have. ●
The Intermediary sits down with Sebastian Murphy, group director at JLM Mortgage Services, about being an outspoken voice for the industry, and to get his take on some of the issues facing this market
Are you the most outspoken man in mortgages?
I don’t think so. ‘Outspoken’ makes it sound as if I’m arriving at these subjects from a very extreme place, or that what I’m saying is far removed from what advisers see each day. I may be wrong, but I don’t believe that’s the case.
I’m an adviser myself. I work with clients every day. We have a strong set of appointed representative (AR) firms across a growing
network, and I sense-check that what I say reflects what others are also seeing.
I also read widely in the trade press. There are plenty of people who hold similar views. Bob Hunt and Richard Howes at Paradigm, to give two examples, often seem to say things that line up with my own thoughts. I don’t see myself as ‘out on a limb’. I’m just trying to express what many advisers already feel but may not always get the chance to say. AMI, for example does a strong job in a very tough environment. I speak to Steph Charman regularly, plus we’re acutely aware that AMI’s biggest wins are often the ones no one ever sees. They stop bad ideas before they reach the policy stage. They point out flaws or knock back potential ideas that would cause serious problems for advisers or clients. It’s very hard to take credit for things that didn’t happen.
Steph and the team are dealing with the regulator at every level, and that means they sometimes have to work in a way that advisers don’t see. I’m in a different position. I can say things they can’t say, because I’m speaking as an adviser on the front line, not a trade body. Both matter.
Do you worry this might impact the business?
It depends whether you think those who I speak out against are the sort who would try to punish me, or the business, for raising such concerns. I’m not doing it with any sort of personal malice so I don’t see why hearing those views would result in a corresponding response.
I’m genuinely trying to secure improvements or to highlight, what I believe, are bad decisions.
These are serious commercial and regulatory issues. If lenders are pushing direct business at the cost of the adviser who brought the client to them, that hits firms’ retention and income. If I flag that, it’s not personal. It’s trying to protect advisers
from decisions that take income away from them.
Lenders, or the regulator, may not love hearing criticism, but the good ones respect facts. I don’t lob insults about, and I always try to give credit where it’s due. Being a large network, we have a great relationship with lenders, who have some amazing people working within them, who absolutely support advisers and advice.
I also think that, on big issues, having some grey hairs or just more than 10 or 15 years’ experience in this market matters a lot. We remember when lenders have tried things in the past which didn’t work. When we see the same mistakes being made by those who don’t have that experience, it’s important to call it out.
On this, I try to be clear about what is happening and why it matters. Many lenders, even when they disagree, will at least engage. As for the regulator, if anything I’d hope they would appreciate that advisers who speak up are trying to protect consumers. That is supposed to be the whole point.
Incredibly important. Most advisers in this country will never be in a room with the FCA’s chief executive Nikhil Rathi. If you get the chance to raise an issue, you should take it. Frankly, parts of his recent speech really worried me.
It felt like the regulator was showing a kind of collective amnesia. Consumer Duty only came in a couple of years back and has clearly been a resounding success due to the good outcomes outlined by the regulator.
It put advisers under more pressure to explore wider client needs. That all made sense because advisers are the only regulated contact most consumers will ever have. Most people do not have an IFA. Yet very quickly the tone has shifted. We now see the removal of the advice interaction trigger. We see the FCA sounding relaxed about lenders using tech solutions or AI to capture direct business, as if that is on the same level as regulated advice.
Nikhil said they had shown their Discussion Paper (DP) to the big banks before publishing it. That is maddening. Adviser reps did not get an early look, banks did. No wonder there were worrying elements. Add in a Government that has held mortgage round-tables with banks and building societies but no adviser voices, and you start to worry. The FCA’s own figures say advisers
On the positive side, the year showed strong demand from first-time buyers. After the debacle in the lead up to last year’s Budget, with so much gossip which never came to fruition, at least we have certainty now and that allows people who have been waiting to act”
account for around 90% of new business, and half the adult population shows a sign of vulnerability.
Positively, the FCA’s recent roadmap does appear to recognise the folly of some of the proposals posited in the DP, such as enhanced advice, and the like. If it is truly supportive of delivering holistic advice, then I am supportive of that commitment.
How it goes about doing this, and what it might be comfortable with lenders doing direct via AI and the like, is another thing entirely though.
Last year, Apple itself found “fundamental limitations” in AI models; the BBC found that 45% of AI queries produced wrong answers, with AI systems being described as “dangerously selfconfident” – the regulator should take this into account when determining just what AI can, or rather, cannot do.
On the positive side, the year showed strong demand from first-time buyers. After the debacle in the lead up to last year’s Budget, with so much gossip which never came to fruition, at least we have certainty now and that allows people who have been waiting to act.
BBR cuts, and decent swap rate levels, have meant lenders have been in the market with better pricing as the year has gone on, and even with bumps in the data, rate cuts are still expected. That has helped confidence.
Another positive is that, despite some of the language, I feel advisers have grown stronger.
Consumer Duty forced many firms to tighten processes, improve client contact, and be more open in how they talk about value. It raised standards in a way that has been good for the industry. Looking ahead, that is going to be vitally important.
On the negative side, some lender behaviour has slipped. We’ve seen product pulls with little notice, even after many promises they would do better. We’ve also had a huge rise in down valuations, and no clear explanation. Advisers are left with delays, clients frustrated, and lenders are left with a process that makes little sense when values don’t match anything else on file.
Then there is the whole issue of product transfers, proc fees, the direct push for this business, which will only ramp up. Advisers still
do a full review, carry the same responsibility and take the same risk. Yet some lenders are clearly motoring in what I believe is the wrong direction.
We need to face the fact some lenders are simply driven by shareholder value, and that means they’ll chase direct business to secure higher margins or lower costs. We see it already with borrowers receiving multiple notifications early in the process with a shiny button to click.
I would like to see clear warnings, much like on cigarette packets. If the FCA is serious about consumer protection, that is the level of clarity we need.
‘Retired maybe, but I’ve no problem keeping it up monthly!’
He may be retired but that doesn’t mean he can’t meet his mortgage repayments.
Later life borrowers often have complex income and don’t credit score the same way as younger borrowers do. That’s where lenders like us, who manually underwrite and use common sense, can help.
Why choose us?
— We take into account earned income up to age 75
We’ll consider up to 90% of pension pots and investments split over the term for affordability, as well as fixed pensions and rental income. Other income can be considered
— We lend in retirement with higher maximum ages than most lenders.
The biggest opportunity is the continued demand for advice. Whether it’s first-time buyers, remortgagers who now have more options again, or older clients who need a more rounded discussion about later life lending, demand for advice is there.
We also have a chance to push for better standards. I’ve said many times that a single, advanced mortgage qualification for all advisers would help remove confusion and raise the bar. The sector needs clarity. We do not need separate silos or rules that suggest some clients only get partial advice. It would appear the regulator agrees.
The threats are uneven lender behaviour, regulatory mixed messages, and a risk of more poor decisions being made without talking to advisers first. However, it’s clear the lobbying power of some of the big banks and lenders in courting the regulator have worked. We have to keep highlighting these decisions, pointing out their flaws, and importantly, offering solutions and showing the continued value of advice.
I will continue to voice my opinions, and hope all others who have the opportunity do the same. ●
For the year ahead, there is a sense of momentum across the lending and mortgage market. The demand is there. The government has an aspiration for growth. Lenders want to lend. For brokers, this means opportunity. Now we just need all those stars to align.
The last few years have tested both borrowers and lenders. However, confidence is beginning to return, and we should use that stability to improve how lending works in practice, making decisions that be er reflect real affordability, cu ing unnecessary application friction, and widening access for customers.
One of the most encouraging developments is the Financial Conduct Authority’s (FCA’s) clearer reform agenda for the mortgage market. Its roadmap signals a real intent to widen access for first-time buyers and underserved borrowers while also addressing later-life lending, improving disclosure and advice through innovation and strengthening support for vulnerable consumers. Combined with a growing appetite across lenders and brokers to innovate, this could start to make a real difference in 2026.
If the rule review creates space for more flexible, well-underwri en lending, the industry should use it to improve real outcomes, not by weakening standards but by modernising how affordability and eligibility are evidenced.
We’re seeing a growing appetite across lenders and brokers to challenge the status quo, including products that would have seemed ‘le field’ a few
years ago. But innovation must be practical not performative. It should solve a real customer problem and be carefully balanced with risk, keeping lending sustainable over the long term. What ma ers is what works consistently over time.
One of the clearest examples is affordability and whether we recognise the payment behaviour customers are already demonstrating. Many renters demonstrate, month a er month, that they can manage payments equal to, or even higher than, a typical mortgage. Yet those same payments don’t always carry enough weight in lending decisions. Rental payments should be treated as a critical input into affordability.
If we’re serious about widening access, we need to get be er at recognising financial resilience where it already exists. That also means being open to alternative data streams that can evidence responsible money management while reducing the amount of paperwork customers are asked to upload and re-upload. The goal isn’t to remove checks, it’s to remove friction that adds li le value.
Personalisation will be an important part of that. A market that works well is one where there’s a credible path for more “unique but viable” customer situations and where brokers can see that path clearly.
Even the best lending ideas struggle to land in an environment that feels volatile. Greater market and fiscal stability would go a long way towards rebuilding confidence across the housing sector for buyers, lenders, and developers alike.
Alongside that, the industry needs a more joined-up approach across the entire home-buying journey. It
will take a genuine collective effort from estate agents, brokers, lenders, conveyancers, and regulators to tackle customer challenges together, rather than each part of the process trying to solve them in isolation.
Of course, none of this works without supply. The lack of homes built specifically for first-time buyers remains the single biggest barrier to home ownership in 2026 and beyond.
The challenge here also reached a low, with data showing housebuilding slowed considerably in 2025 rather than ramped up, with builders, like seemingly everyone, being affected by tough conditions, making it difficult to keep up with the demand.
Without meaningful progress here, even the most innovative lending solutions can only go so far.
Ultimately, I’d like to see 2026 remembered as a year where we focused less on rigid process and more on good outcomes - using policy, data, and broker insight to recognise different income pa erns, different life stages and different paths to financial resilience. I’d like to think 2026 will be the year the industry unlocks the power of data to make the home buying journey easier for those who have previously found it more challenging - from applications through to opening the front door.
If we can innovate responsibly, use data more thoughtfully and work together across the sector, 2026 can be the year we genuinely widen access to home ownership. ●
The outlook for 2026 feels more positive than the autumn of 2025, which was plagued by uncertainty amid pre-Budget speculation of a raid on the housing market in the form of increased taxes.
What came to pass wasn’t as bad as many had feared, although there was a notable lack of encouragement or impetus from the Government to help first-time buyers – the lifeblood of the market – onto the property ladder through some form of revised Help to Buy scheme or stamp duty concession.
Improving transaction levels by encouraging first-time buyers to purchase their first home, enabling second-steppers and beyond to move up the ladder, is crucial to a thriving housing market which also benefits the wider economy.
With the Budget out of the way, confidence has improved and the prospects are brighter. December’s base rate cut to 3.75% meant interest rates finished the year one percentage point lower than they started, which has had a huge impact on buyer and seller activity.
Affordability is improving, albeit
slowly, as the cost of living remains high. Lenders remain keen to lend and have money available to do so; what’s more, the subdued market at the end of last year means they are keen to make up business.
At the time of writing, HSBC, Barclays and Halifax had already reduced rates in January, with the rest of the ‘big six’ expected to follow before long.
Lenders remain keen to lend and have money available to do so; what’s more, the subdued market at the end of last year means they are keen to make up business"
Market expectations are for one to three base rate reductions this year with base rate finally settling between 3% and 3.5%, as the Bank of England closely monitors inflation, the labour market and wage growth.
MARK HARRIS is chief executive at SPF Private Clients
This will provide a welcome shot in the arm for the housing market, and will be particularly helpful to the 1.8 million homeowners who are due to remortgage this year, according to UK Finance.
Those on 5-year fixes in particular will be moving off super-low rates and while rock-bottom deals are no longer available, with leading 2-year fixes starting from just over 3.5% and their 5-year equivalents starting from just over 3.7%, and further gradual falls expected, the situation is not as dire as it might have been.
More than the numbers
Those lenders that can’t compete on rate and jockey for position at the top of the ‘best buy’ tables are likely to focus on attracting business by improving their criteria instead.
Smaller building societies and specialist lenders will continue to focus on their particular niches and borrowers would do well to consult a whole-of-market mortgage broker when taking out a home loan to ensure they don’t miss out on any hidden ‘gems’.
In the first week of this month, Nationwide and Halifax reported on their house-price indices for December, indicating that price growth has slowed and, in some areas, prices are falling.
Nationwide reports that the average price fell to 0.6% in December from 1.8% in November and is forecasting
an average UK house price this year of 2% to 4%. Meanwhile, Halifax reported a 0.6% dip in prices in December, following a 0.1% drop the previous month, and forecasts a “modest rise” in prices this year of between 1% and 3%.
The increase in available stock has put buyers in a stronger negotiating position and this is keeping a lid on price increases, while affordability pressures persist, even with the rate reductions.
National average house prices are useful to a degree, but they can conceal significant regional differences which buyers may wish to pay closer attention to. Northern Ireland saw a 7.5% increase in house prices last year with an average price of £221,062, compared with a 1.3% fall in prices in London and an average price of £539,086, according to Halifax.
This underlines the impact of affordability on buyer budgets with homebuyers in the south finding it particularly difficult to raise the deposits they need and satisfy lenders that they can afford their monthly mortgage repayments.
2025 was a year of uncertainty for landlords as the Renters’ Rights Act made its way through Parliament.
We now know the first phase is due to become law on 1 May, which at least will enable landlords to plan ahead. On the lending front, mortgage pricing has eased, with more product choice for landlords buying via a limited company or moving existing portfolios into such a structure as more investors go down this route.
With the Chancellor announcing additional tax on rental income in the Budget, it is increasingly difficult for landlords to make money if they have an investment property in their own name. We had countless enquiries last year from landlords considering incorporation.
The timing of an incorporation is
very important as the mortgage broker needs to work with the landlord’s accountant to ensure it is done in the most tax-efficient way, but this is an area of business we expect to keep us busy in 2026.
In terms of the outlook for mortgage brokers, independent advice will be
more important than ever. Keeping on top of what’s available, particularly rate changes, and making sure clients get the best product for them will keep us busy in 2026.
Here’s hoping for a more positive and productive year for the housing market. ●
BANKHALL GROUP GATHERS THE EXPERT VIEW FROM ADVISERS AS WE MOVE INTO 2026
director
2025 definitely felt like a year of transition for the mortgage market. After the volatility of recent years, the market nally started to stabilise. That’s not to say it wasn’t without its challenges – many of our advisers in the Sesame network spoke of a tough market – but many also reported their best year, demonstrating their resilience and positivity.
with signi cant growth in the remortgage and product transfer market.
of
As we move into 2026, there’s an air of cautious optimism. With rates gradually coming down and a ordability improving, it is looking to be a strong year for the market.

UK Finance forecasts gross lending will rise by 4% to £300bn this year,
What’s clear from our Sesame members is that the role of the adviser is evolving yet remains as important as ever. Clients are more informed and cautious, meaning advisers must provide deeper, clearer, more strategic guidance. The emphasis now is on holistic advice, education, and longterm planning, particularly for complex, high-net-worth (HNW), later-life or self-employed clients. Our role in the Sesame Network is to support our advisers to harness the opportunities ahead, providing them with brilliant service and ensuring customers get the right advice and outcomes. There’s an unprecedented opportunity with the
As we move into 2026, there’s support the opportunities ahead, There’s an unprecedented opportunity with the

product transfer market, and the power of the intermediary is proactivity and the ability to do a whole-of-market search to ensure that the customer ends up with the best possible outcome.
The relaxation of stress testing rules saw lenders start to innovate last year and introduce higher loan-to-income (LTI) products, and my wish for 2026 is for more please! We’ve seen the return of 100% mortgages, which has been great to see, and I’d like to see the same innovation and exibility applied to self-employed borrowing, particularly in the HNW space.
Similarly, we’re hoping to see more innovation in the protection market. There’s so much more we could be o ering beyond income protection and critical illness. We’re seeing lenders launching new products to meet specialist needs, and it would be fantastic to see that in the protection space too.
On regulation, there are two really big pieces coming up in the Mortgage Market Review and the Protection Market Study. We’re yet to understand the output of them, so it will be interesting to see what is delivered in 2026. What’s important from any future regulation is that we maintain the fundamentals of Consumer Duty, with the customer sitting in the middle of any proposed changes.
Our priorities for 2026 are to support our advisers by simplifying tasks with the aid of technology and arti cial intelligence (AI), so they can go faster, spend more time with clients, and continue to be proactive with advice and guidance, enabling them to harness the growth opportunities ahead.
Introduction by Claire Cherrington, director at PMS/ Bankhall
If I was to sum up 2025, I would say it was very much a year of adjustment in the market. We saw lots of repricing, with lots of rebalancing between product transfers and remortgages, and that’s a very di erent backdrop to what we’ve seen previously.
We saw a ordability improving as a result of base rate reductions, and the changes in stress rates that the Financial Conduct Authority (FCA) brought in, but that didn’t necessarily play through into customer con dence. A key role for intermediaries in 2026 will be helping clients feel con dent about decisions that they’re making and to reassure them now is a good time to get on or move up the property ladder. It was positive to see rst-time buyers accounting for a higher percentage of residential transactions,
and hopefully this will continue this year.
At PMS, we think 2026 is going to feel better than 2025. We’re expecting a good acquisition market with housing transactions to broadly hold up, but the actual value of those housing transactions to be slightly higher. We’re also expecting some modest house price growth, and with interest rates continuing to fall, further a ordability improvements.
As one of the UK’s largest mortgage clubs, we’re committed to supporting ambitious rms to grow and evolve. Technology and AI will play a central role in how we do that in 2026.
Last year, AI moved from being experimental to playing a much bigger role for some in terms of infrastructure. We’re seeing advisers really starting to think di erently about how they leverage it. We also started to see lenders using it in di erent ways and new propositions come to market. As a result, there have been improvements and e ciencies in processes, both lender and provider-side.
As some of our PMS advisers outline later in this feature, AI isn’t the death of the adviser. AI is going to become a way of living, providing the tools that underpin everything we do. Firms should be thinking about where it can t into business processes, and how they can use them to improve client engagement.
Like Toni, I believe there’s an opportunity to take a more holistic approach to nancial planning. There are fundamental changes coming through for inheritance tax planning, with pensions going to be included, and that opens up a real opportunity for brokers to talk about how the client is protected in that situation. And I think what you could see, particularly in the wealth market, is independent nancial advisers (IFAs) coming closer together with the mortgage market to provide the right solutions for clients.
p
Richard Dana CEO, Tembo Money, London
Tembo is a savings and mortgage app focused on helping rst-time buyers on their home buying journey, from when they put the rst pound into one of our ISAs through to when they buy the house.
Our whole USP is about helping people take that rst step into home ownership.There’s a big pain point when you look at rst-time buyers. 30 years ago, there were 600,000 a year. Last year, there were around 350,000 or so. That’s a big reduction, and the overall population has gone up, so that doesn’t really make sense. Plus, there’s real pressure in the rental market - we think there’s about two to three million people who would really like to buy, but they can’t because of a ordability.
So, there’s a big opportunity to help more people in 2026. We’ve seen lots of innovation from lenders, with increasing LTI caps for example, which is helping.
The challenge is consumer con dence. If you actually look at the data, the economy is not, perhaps, in as bad a situation as some people say, but there’s been this consumer con dence issue, as people don’t quite know what’s around the corner.
Despite that, I feel pretty bullish it’s going to be a big year in 2026. Rates have settled and we’ve come through the rst year of the new Government, so I hope we can start to have more business-as-usual economic behaviour.
Oliver Lodge Director and protection specialist, Bespoke Financial
Yorkshire Ltd
Yorkshire
At Bespoke, we’re protection specialists, and our approach is to educate a client about the value of why they need that cover. Many clients come to me initially and say, “I want life cover” and my rst question is “why do you want it?” Once they understand what could happen in other areas of their life, it opens up the protection conversation.
2025 was another successful year for us.
We get a lot of recommendations and repeat business because we only ever sell to clients that understand that value of the protection we’re providing.
We also do a lot in the community, giving back to charities and clubs locally, and that has helped to build our reputation.
There’s a lot of doom and gloom in the press, but when we do reviews with clients, we’re nding that people have disposable income, thanks partly to large pay rises over the last couple of years.
You only have to go into town on a weekend to see pubs and restaurants are full and I think there’s more money out there than people think. That means there’s a big opportunity for 2026. As the cost of living has increased along with these pay rises, it’s even more important to cover yourself.
As protection specialists, our job is to help people understand what would happen if they did suddenly stop earning and how we can help them protect their income. This year we’re looking to expand into new complementary lines.
James Wellman Director, Lime, Gloucester
At Lime, we pride ourselves on being approachable. We’re a small rm but we’re always there for our clients, and we give back to our community. Last year I visited schools and clubs to talk about the importance of nancial education. I think as brokers we have a responsibility to share our knowledge.
2025 was a really good year for us. It felt like a year of recalibration, with a resettling of rates. What stood out is the growing importance of the protection conversation.
With Consumer Duty rmly embedded, the days of simply arranging a mortgage and moving on are gone. As advisers, a good job isn’t just nding somebody a cheap rate - it’s making sure their family is protected.
There is much more emphasis across the industry on protection, and clients are more open to the conversation.
As a company, we’ve only been going three years; but this year, for the rst time, we’ll have opportunities for remortgages and product transfers. Being able to service existing clients, do reviews and potentially move them onto a
lower rate will be a great thing to do. In terms of market trends, falling rates are positive, but there are mixed signals. We’ve heard reports of house prices stagnating or coming down slightly, which could impact loan-to-value ratios and new-build sales.
However, this creates a natural trade-o , as homes become accessible. There will be winners and losers and, as advisers, we’ll be here to nd the right solutions for our clients.
Michael McCartney
Director and senior mortgage broker, We Do Mortgages Ltd, Essex
We’ve been established for 10 years, and our specialism is moving families. People are more cautious now compared to a few years ago.
Pre-Covid, the goal for most people was maximum a ordability, biggest house and the most money they could borrow.
Now, because of the uncertainty in the economy, people are more conservative with their a ordability, and I think that’s a good thing.
Our focus in 2025 was on building a more e cient business model.
We developed our own AI-supported CRM system to relieve the administrative workload for our brokers and enhance the client journey.
When I speak to people in the industry about AI, there are divided opinions, but they always lead to the same answer.
On one hand you’ve got brokers who are dismissive of tech because they say people like to deal with people.
Then I speak to tech companies, they will simply say to you, technology should enable more conversations, not get in the way of them. I know brokers’ time is better spent talking to a client and supporting them, rather than reviewing documents. So, this year we’ll continue to look for ways to integrate AI into our business model, simply to allow them to do just that!
We’ll also continue to help families nd their next home, regardless of external factors. I’m less concerned with what the Government or the economy is doing and more concerned about sitting with an individual and their family, asking about their personal circumstances and what it is they want to achieve, and helping them realise their goals.
Managing director, The Lending Channel Perth
2025 was a massive year for us - our best in 15 years in business. A lot of that growth was driven by investing in more sta .
We grew our commercial mortgages book by bringing in two bank managers from the high street last year, which has strengthened client relationships. We also expanded our appointed representative (AR) network and built out our residential mortgage broker proposition. We’ve always done the more complex areas of nance, but we’ve not been known for doing traditional vanilla mortgages, and that’s gone well.
We’re feeling positive about 2026. Last year, many clients were hedging their position, waiting to see what would happen with rates before committing. That hesitation has eased as the rate environment has settled. There is growing acceptance that rates are not going to get back to the arti cially low rates of a few years ago. While further small reductions are possible, we’re telling clients that rates are what they are.
There will be a lot of borrowers coming o ultra-low xed rates this year so there’s still quite a bit of mortgage shock coming. Finally, buy-to-let remains challenging, especially in Scotland.
You’ve got rent controls coming in and there’s extra regulation in Scotland in terms of the second home tax at 8%. Having said that we managed to grow our buy-to-let footprint last year, despite the di culties, so there are opportunities.
Michelle Niziol CEO, IMS Property Group, Bicester
I primarily operate across residential mortgages and remortgaging, with a strong focus on selfemployed, complex income and high-networth clients. We also do signi cant work in buy-to-let and portfolio lending, alongside protection planning as part of every mortgage journey.
The market has stabilised compared to the volatility of recent years, but a ordability remains the key challenge. It is not just about rates, but stress testing, tighter criteria, and wider cost pressures. Clients are more cautious and better informed, which means advice needs to be clearer, more strategic, and proactive.
Remortgaging and product transfers are performing particularly well, as borrowers seek certainty and protection from future volatility. We are also seeing strong demand for complex cases, including portfolio landlords and clients navigating major life changes.
The current environment has reinforced the need for brokers to move beyond being transactional. We have leaned further into holistic advice, longer term planning, and proactive rate monitoring, which is where advisers add the most value.
Philip Emanuel
Group business development director Cornerstone Group, Cardi
For Cornerstone Finance Group, the past year has reinforced that success in today’s market is a journey, not a destination. While 2025 was still shaped by global uncertainty, it also encouraged advisers and clients to re-engage more thoughtfully with nancial advice. Against this backdrop, we have still seen substantial and continual growth, driven by sustained investment in training.
We are focused on adviser development, helping advisers build multiple income streams and expand their specialisation across mortgage, protection, and wider nancial advice. It’s not just about numbers but about giving advisers the tools and con dence to deliver deeper, more consistent advice over time.
Technology will increasingly support that evolution. AI is expected to in uence areas such as product transfer, and as consumers become more informed, advice remains the true di erentiator.
Trust, human relationships and showing up regularly for clients will matter more than ever. Looking ahead to 2026, our priority is increasing the depth and amount of advice each adviser can provide, with a growing emphasis on specialist and multi-product lending. Our model will continue to adapt because progress comes from committing to the journey together.
Andy Mellor Managing director, The Insurance Surgery Maccles eld
For The Insurance Surgery, the past year has been de ned by focus, specialism, and a deliberate shift in how the business grows. We operate in a niche part of the protection market, supporting cases many brokers and insurers struggle to place. That specialism remains at the heart of everything we do.
One of the most signi cant changes has been where our business comes from. We have moved away from a predominantly online-led model towards building deeper relationships with referral partners, particularly protection and mortgage brokers. This partner- rst approach has been transformational, helping us navigate the market and delivering strong momentum through collaboration and trust. Our strength lies in doing something few others can and doing it well. Transparency and visibility sit at the centre of our proposition, giving both clients and partners con dence throughout. Maintaining that edge is critical. Looking ahead, the priority is sustaining momentum without complacency. Outstanding service is non-negotiable because our partners rely on us to deliver for their clients. While wider market conditions will always uctuate, we continue to see opportunity and excitement ahead. Our model is built for growth, grounded in human expertise, the future remains very positive.
Fran Afonso Director and protection specialist, Amavi Mortgages, Uck eld
The market’s tough but I’ve seen tougher – I started when interest rates were 18%. Lenders are still lending; it’s just a matter of nding the right one. A lot of it is your own knowledge. If you’re expecting an answer to come out of a computer, then you’re not really doing your job as an adviser.
I work mainly with high-net-worth individuals, most of whom are self-employed. A lender won’t always see things the same way as an accountant, and they are still very rigid in how they assess income.
I have asset-rich clients who are earning income from investments, but a lot of lenders still don’t accept investment income. I’d like to see lenders be more open this year to this type of lending.
I’m also seeing more borrowers over 60, but I’m having to dig deep to nd lenders for them. I had a rst-time buyer recently at 72, who wanted a 90% mortgage.
When they came to me, I was like, holy moly, what am I going to do with this? But do you know what? I got their mortgage.
There are a lot more options now for later life lending. It’s easy to default to equity release. But the right thing is to nd a lender that will provide the right solution for the client.
Looking ahead, I think interest rates have settled. I’ve had clients tell me they’re holding o because they’re waiting for rates to keep falling back to where they were, so I’ve had to manage their expectations.
Grant Holmes Managing director, Bentley Holmes, Surrey
Most of our business is mortgage, however, in the last 12 months we have been working to increase our protection penetration. We see this as both an opportunity and a responsibility to look after our clients.
The market continues to be challenging. There were a large number of buyers waiting for the Budget before making any decisions. With the Bank of England rate reduction in December and the start of a New Year, this will hopefully see lenders reduce rates and encourage buyers to start committing to new purchases. At the top end of the market, we have seen quite a few clients move overseas but not sell their UK homes and so there is not the usual chain of properties forming.
First-time buyers have remained fairly active, largely driven by the cost of renting, so despite mortgage rates still feeling high, they are often better o than paying rent.
We are also active in the buy-to-let space and
see many clients moving away from buy-to-lets being held in personal names to setting up special purchase vehicles, whether it be to hold one or two buy-to-lets to dozens of buy-to-lets.
Looking ahead the remortgage market is a huge opportunity over the next 12 months. There are going to be lots of people coming o very low rates from ve years ago who need expert advice to nd the best deals and help soften the rate shock of higher interest rates.
Phil Saville Sales and marketing director, iMAB, Hertfordshire
Since the 2022 miniBudget, borrowers have become more educated about mortgages. Rate movements are widely reported, meaning customers often approach us with a clearer understanding of a ordability. While a more educated customer is de nitely a good thing, it’s a double-edged sword.
Falling rates mean advisers are regularly revisiting and amending cases, which creates a compliance burden and a massive challenge for advisers to nd that additional time. The good news is that lenders have responded by improving product switching, making it easier for frequent rate changes.
There was some speculation about possible changes to Stamp Duty in the Autumn Budget, but this didn’t happen.
As a result, we need to nd other ways to support more rst-time buyers onto the ladder, to keep the market moving.
Fortunately, lenders are increasingly stepping up through innovation, which was a standout positive in 2025.
The big lenders had a light bulb moment, introducing reduced stress tests, improved a ordability models, and targeted schemes for rst-time buyers.
These changes are helping us place business, whereby a year or two ago, we may have had to say no.
Looking ahead, world events remain a key risk. With economies more interconnected, one little thing happens, and there’s a huge domino e ect, particularly given ongoing geopolitical tensions. However, with record mortgage volumes and a signi cant remortgage wave due in 2026, falling rates and lender creativity, I’m optimistic. p
Charlotte Skinner
Managing director, The Surrey Mortgage Company, Epsom, Surrey
I have been trading for 11 years and 2025 was our best year yet. I put that down to a combination of factors. Firstly, we’ve developed a strong network over the past decade and most of our business comes from referrals. With rates easing over the past few months, we also feel many buyers have decided now is the right time to move forward rather than wait for a return to pre-2022 levels.
Buyers are also more informed than ever, which is great to see, although it has meant increased ongoing work as rates change and clients quite rightly expect us to keep searching for the best deal. This has been our biggest challenge. We have taken a proactive approach and continually monitor the market for our clients, and while this has come with an added administrative workload, we’ve invested heavily in our systems and are expanding our administration and adviser team this month. This means we can manage the extra demand e ciently and continue to focus on delivering the best outcomes for our clients. I work with a large number of high-net-worth clients and while the new mansion tax caused some initial jitters when it was announced, I don’t think it will impact the housing market as much as some people fear. Buyers will simply start to factor it into their purchasing decisions. A ordability improved signi cantly in 2025 following changes to stress testing rules and the move towards higher LTIs from lenders. If rates continue to fall and lenders continue to ease their criteria, this should continue to improve in 2026.
Rebecca Wilkins Managing director Cutting Edge Mortgages Northumberland
I’m a big advocate for innovation and we’re investing signi cantly in AI to make things faster and smoother for our brokers. AI won’t ever replace advice, but we do need to use the tools available to make the
process for the client and the broker easier.
Last year, one of our biggest challenges was a ordability. It’s always something that you have to wrangle with, but it felt nigh impossible for some clients, especially self-employed, to get anywhere near the loan amounts that they were looking for.
For similar reasons, building buy-to- let portfolios was also a challenge because you couldn’t raise as much on the existing portfolio due to the constraints on the rental income calculations.
It’s a worry for the rental market because landlords are getting squeezed. The private rental sector is so important to the housing market and smaller landlords are getting pushed into looking at other areas of making money. What we’re nding going into 2026 is that putting a portfolio into a limited company is better way forward.
Having said that, several lenders recently said they had their biggest year for rst-time buyers in 2025. So perhaps landlords leaving the market is opening the door for rst-time buyers.
Alongside AI, our main drive for 2026 is to make sure that every client is spoken to about protection. We are building a new team of protection only advisers and we want all clients to not only get the house that they’re looking for, but make sure it’s protected for any future events.
James Carter Principal Independent James Surrey
For Independent James, the past year has reinforced the importance of supporting clients through an increasingly complex but opportunityrich market. Working with a diverse client base of business owners, sole traders and those in the entertainment industry gives us a unique insight into how employment patterns and income structures continue to evolve.
While many of these clients have complex nances, their needs are often rooted in straightforward residential borrowing, where timing, preparation and clear guidance make all the di erence.
The focus for us has always been on the client experience. As technology becomes more embedded in the advice process, we are
doubling down on the areas AI cannot replicate like rapport, judgement, and hands-on support. That includes helping clients navigate surveys, understand risks, prepare for bids, and connect with trusted professionals around the edges of the transaction.
Technology plays a role in streamlining administration, but the human touch remains central to our proposition.
Looking ahead, the market appears fundamentally resilient, with strong underlying demand. Sellers seem to be becoming more realistic, and there is a sense of steady momentum returning.
Edward Checkley Managing director Private Finance London
2025 was stable in many respects. We didn’t have any huge market shifts a ecting rates overnight and we actually started to see rates coming down.
At Private Finance, we specialise in complex, large loans solutions, generally for higher earners and we nd there’s demand whether markets are good or bad, because we’re o ering solutions that the average bank or broker can’t.
2025 was an exciting year, we had some great hires and landed some big, complex transactions. Our industry is all about people and if you get great people and you support them, then they’ll do well.
Our focus is on sharing knowledge and enhancing processes through technology to enable our brokers to do a great job.
There were some positive changes in lender criteria last year and I hope to see that continue in 2026.
Complex and specialist lenders were saying we’re not going to compete on rate, because we can’t, but we’re going to do better expat lending, or we can do better self-build lending, or we’re going to open up income multiples.
There’s a lot of pent-up demand in the market, so we’re expecting an increase in volumes this year. A lot of people were waiting on the sidelines last year but now the budget is out of the way, and the base rate has dropped, I expect buyers to take action.
David Latimer Managing director DL Mortgage Services Ltd Sale
For DL Mortgage Services, the past year has proven the value of straighttalking, human advice in a market that often feels increasingly automated and impersonal. Our work continues to centre on residential purchases, remortgages and product transfers, alongside protection.
First-time buyers remain both a challenge and an opportunity. Rising rents are pushing many towards home ownership, yet saving for a deposit is harder than ever. That’s where clear, practical advice really matters, helping clients understand their options and nd routes around the obstacles and onto the ladder. At the same time, the buy-to-let market has faced ongoing pressure which has in uenced investor con dence and activity.
One of the biggest shifts we’ve seen is the gap left as local bank branches continue to close. People still want to sit down, ask questions and feel supported, and we’re well placed to o er that personal service, whether face to face or over the phone. Clients with complex cases, in particular, bene t from advice that looks beyond a simple score or tick-box approach.
Looking ahead, improving a ordability and falling rates should bring renewed con dence, especially among rst-time buyers. While developing technologies will play a role in the year ahead, our focus remains on relationships, accessibility and service, because real advice is built on listening, not clicks ●
In the vast majority of these articles I tend to write about our industry, or landlord issues or wider buy-to-let (BTL) trends, but this time I want to focus on something a little different and a little bit more personal.
It is about how we, as lenders and those that work for lenders, communicate with you, brokers, and perhaps how we might be able to improve on this in order to get to the right outcomes quicker and with more clarity.
A recent experience of mine brought this to the surface and made me realise that even those of us who work with brokers every day might not be as strong at communication as we think we are.
A day that changed my view
Late last year I spent a day in media training with Alex Hammond and
John Fitzsimons from Fleet’s PR agency, Square 1 Media.
I will be honest. I did not expect to gain much from it. I write the odd piece for the trade press and speak to journalists occasionally, so I thought I had a decent grasp on the basics. Within the first hour it became clear how wrong I was.
One of the first things that struck me was how rarely we stop to think about what we are saying. When you’ve worked in this industry for a long time, when you speak to brokers or indeed other industry people, you can all too often drift into auto mode.
You handle questions without thinking, you give familiar answers, and you rely on instinct more than conscious thought. It gets the job done, but it can also allow weak habits to creep in, and it sometimes means the message you give is not as clear or helpful as it should be.
At the start of the session I
WES REGIS is national account manager at Fleet Mortgages
struggled far more than I expected. The moment I tried to switch off my normal auto pilot and move into more deliberate thinking, I could feel my mouth racing ahead of my brain. To my surprise, I found myself slipping into a defensive style that is nothing like how I speak on panels or when dealing with brokers. It was discombobulating to be put in such an uncomfortable place
But, in a way, the discomfort actually helped. It pushed me out of my usual pattern and forced me to slow down, take a breath and shape what I wanted to say rather than fall back on old habits.
Once I relaxed and took guidance from Alex and John around thinking more clearly about what I really wanted to say, how I might handle a seemingly difficult question, then my answers improved.
I was getting across the answers and the messages that I wanted to get across, rather than fumbling my way around to try and reach them. They had more structure, but still sounded
like me. I found a better balance that I have since carried into my work.
Lender communication
As the day went on, it became clear just how often those of us who work in a sales capacity, or talk every day to you, the broker, may well talk first and think second.
Of course, there’s no malice in this, we may talk fast or engage quickly, because we want to help and move things forward, but might that sometimes mean the message becomes muddled or incomplete? I have a feeling it might.
It also reminded me there is a big difference between an official communication we as a lender might send out and the real conversations that follow. Emails, product notes and updates are absolutely necessary and work.
However, the moments that may matter more are the conversations between brokers and the people who work at lenders. If those conversations are inconsistent or rushed, you’re likely to be feel it straight away.
From my experience brokers want clarity and honesty. They want one message, not three different versions depending on who they speak to. This is a longstanding issue in the market and something many lenders have to keep working on.
Broker-facing business
This is why I think every lender, or indeed any business which is brokerfacing, may want to revisit how they train their teams. Our day with Square 1 Media may have been labelled as media training, but the lessons reached far wider than that. The focus on conscious thinking, clearer structure, and the impact your words
can have would be useful for anyone who deals with brokers in any part of the business.
Role play is never the most comfortable activity, but it works. It gives people the chance to hear themselves, reflect on how they come across, and adjust before they go back into the real world. And in a market that relies so heavily on trust and confidence, that extra layer of thought makes a marked difference.
With the new year underway, businesses may feel this is right time to look at their overall communication. You may think you have consistency across your teams, but in practice this can slip without anyone noticing.
A broker may get one message from a BDM, a different wording from an underwriter, and something else again from a case manager. Even small differences can cause confusion.
Brokers want clarity and honesty. This is [...] something many lenders have to keep working on”
If we want broker trust, we need to close these gaps. It means slowing down, thinking through what we want to say, and making sure our messages match across the business.
So, as we move further into 2026, I would suggest a simple aim: talk better, with more thought, and with more consistency. It is still good to talk, but the talk should have purpose, clarity and a shared understanding behind it. ●
For more than a decade, brokers have been the dominant force in UK mortgage distribution.
But as regulation evolves and technology advances, some lenders appear to be questioning the role brokers play in the market. That may prove a costly miscalculation.
The rise of the intermediary channel was not accidental. The Mortgage Market Review (MMR) effectively required most residential borrowers to take advice when it was introduced in 2014. At the same time, growing complexity in the buy-to-let (BTL) market meant brokers became the most effective – and o en the only viable – way for lenders to distribute products at scale.
That model has served the industry well. Yet increasingly, some lenders – high street names, I should add – seem, by their actions, to be questioning the value of brokers in the market of tomorrow.
This is most evident in the product transfer (PT) market, where some lenders appear to be reducing their reliance on intermediaries. Dual pricing, cuts to procuration fees and more aggressively engaging with borrowers approaching the end of their deals all point to a desire to bypass the broker altogether.
I can see why PTs are an a ractive target for large lenders with established direct channels. These customers are already on the lender’s books and improvements in technology make them easier and cheaper to reach.
But this should give the industry pause. Circumventing the advice process increases the risk of poor borrower outcomes. The only way to be confident that a product transfer is genuinely suitable is through full advice, which includes scouring the wider market to ensure a be er deal is not available elsewhere.
It also undermines the broker distribution channel that underpins both the residential and buy -to-let markets. If the pendulum swings too far, the consequences could be severe. I know this because we have been here before.
In the years following the financial crisis, many lenders a empted to push more business through direct channels. The rationale was familiar: tighter margins, a desire for control and the belief that intermediaries were an avoidable cost.
In practice, lenders soon discovered it was extremely difficult to generate sustainable volumes without brokers. When they eventually returned, the broker market they found was weaker than the one they had le behind. Years of reduced support and inconsistent commitment had eroded capacity and rebuilding that infrastructure took significant time and effort.
The fact that similar dynamics appear to be emerging again is worrying. If major lenders move beyond just testing boundaries and materially shi focus towards direct channels, the market will be poorer for it.
Much of this thinking is being driven by advances in technology, particularly artificial intelligence (AI), which is o en presented as a solution to almost everything. Its cheerleaders envisage a world in which algorithms materially reduce – or even remove –the need for brokers altogether.
That strikes me as an overly optimistic and simultaneously undesirable outcome. AI undoubtedly has potential. Used properly, it can support skilled professionals and speed up decision-making. But there are serious questions about whether it will ever deliver the efficiencies some anticipate or whether it will make the market function more efficiently.
At Keystone, AI will never make an
DAVID WHITTAKER is CEO at Keystone Property Finance
underwriting decision. Our approach to technology is about supporting brokers and reducing administrative burden, not replacing human judgement. Nor would we ever want it to. I am less confident that mainstream lenders would make the same commitment – and that should concern both brokers and borrowers.
Regulation has not helped brokers, either. The FCA’s removal of the advice requirement in most residential cases now allows borrowers to transact on a non-advised basis if they wish. It also indicates that the regulator might be truly and worryingly agnostic when it comes to advice.
My concern is that lenders in both the residential and buy-to-let markets will interpret this as a green light to rebalance direct and intermediated business, without knowing whether the efficiencies promised by AI will ever fully materialise. History suggests that is a risky bet.
As we found a decade or so ago, a strong broker market is only truly appreciated once it is no longer there. And once capacity is lost, it cannot simply be switched back on.
The pendulum between direct and intermediated business will always swing back and forth. But we should not forget the reasons why it has swung so far in brokers’ favour over the past decade.
Many lenders publicly profess their commitment to the broker market. Over the next few years, we will discover which of them genuinely mean it. ●
The 1st May 2026. That date will be circled in red across the calendars of le ing agents, landlords, and property professionals up and down the country. It’s the date on which the long-awaited Renters’ Rights Act – a piece of legislation first proposed by the UK Government in 2019 – is fully implemented.
However, agents and landlords who believe there are four months to go until the new rules come into force are mistaken. Because in December, as many businesses downed tools for the holidays, those paying a ention might have spo ed the unofficial start of the Renters’ Rights Act implementation.
On the 27th December, a day characterised for most of us by turkey le overs and searching through the dregs of the Quality Street tin, councils across England were granted stronger investigatory powers over the private rental sector (PRS).
Put in place by the recently passed Act, Local Authorities now have far stronger powers to investigate dubious PRS practices. This includes being able to enter properties to assess conditions, demand access to certain
documents, investigate evictions which could be illegal, and dig into the business practices of landlords, agents, and even building contractors.
What’s more, enforcing these new powers is now a duty for Local Authorities. It’s not something they can leverage if they choose to - it’s an area of enforcement they are legally bound to deliver. This means tougher enforcement action should be expected. And sector professionals need to get prepared.
The direction of travel is clear: from now on, enforcement will become more proactive and far less forgiving of poor processes. Not having the right documentation in place or unwi ingly breaching the new rules due to ignorance won’t cut it as an excuse. Property businesses need to be across the details, clued up on compliance, and ready to respond to a Local Authority enquiry at any moment.
Ge ing on the wrong side of the new Act, and by association those enforcing it, could be incredibly costly. Even the ‘entry level’ penalties will make your eyes water; landlords could be fined £7,000 for a first-time or minor breach, rising to £40,000 for repeat offences. And councils can
WILLIAM REEVE is CEO at Goodlord
now choose to prosecute instead, with the courts able to issue unlimited fines. Crucially, illegal evictions are also now subject to civil penalties for the first time. In short, the stakes are high.
Those who don’t yet have their house in order are already exposed. The Act is creeping into reality and, in less than 16 weeks, will be implemented in full. And lots of industry professionals are on the back foot. According to a survey of over 700 le ing agents by Goodlord conducted towards the end of 2025, one in three agents (31%) had yet to start preparing for the seismic shi in the rental landscape that the Act will bring.
The window to get organised is closing, but it’s not too late to act. Landlords and agencies, who have had their head in the sand until now, need to put a plan in place. That means reading up on the legislation, understanding how it affects you and your business, and making a list of the documents, processes and policies that require review and action. This could feel like a mammoth task, but it’s not one that can be avoided. And there are tools, platforms, and experts which can be leveraged to help ease the burden and keep you compliant in the long-term.
As the old saying goes: “it ain’t over ‘til it’s over.” So, whilst the starting gun has been sounded on the most consequential piece of legislation to hit the sector in a generation, it’s not too late to get ahead in the race. But the era of avoidance is well and truly over. It’s time to get moving. ●
Jessica O’Connor speaks with Adrian Moloney, group lending distribution director at OSB Group, about the launch of Rely, and how the market is shaping the group’s strategy for 2026
In a buy-to-let (BTL) market that has spent the last few years oscillating between resilience and reinvention, lenders have been forced to decide what they want to be. For some, the response has been to retreat into narrower appetites and smaller niches. For others, it has been to place bigger bets, by investing in technology and propositions, and designing journeys that reflect a customer base that is not just borrowing differently but behaving differently.
OSB Group’s launch of Rely – its new investor-focused brand – sits firmly in the second camp. It is not simply a new name. It is a consolidation of buy-to-let identity and a signal that OSB wants to compete not only on product breadth, but on decisioning speed, broker usability, and the ability to adjust quickly as market conditions change. To examine this innovation, The Intermediary sat down with Adrian Moloney, group intermediary director
OSB Group
at OSB Group, to discuss why the business chose this moment to bring Rely to market, how the platform fits into OSB’s long-term brand architecture, and what he expects from the wider market in 2026.
When asked what prompted OSB to launch Rely at this exact moment, Moloney is clear: the work behind the launch has been long in the making.
He says: “This wasn’t an overnight project. This has been going on for a couple of years, as we looked at how we could modernise and transform our business as a whole, in terms of both our technology and what we fundamentally do.”
Like much of the specialist lending market, OSB Group has grown through mergers and acquisitions, creating both reach and complexity. Its multiple brands – Precise, InterBay and historically Kent Reliance for Intermediaries – exist to serve different borrower segments across the full scope of the lending market. However, balancing these different brand identities can also create confusion, as Moloney describes a buy-to-let set-up that, over time, had become multithreaded.
“As a result of acquisitions over the years we ended up with three brands that did buy-tolet in InterBay, Precise and Kent Reliance for Intermediaries,” he says.
Rather than keeping buy-to-let split across multiple propositions, OSB took the opportunity to create a single investor brand with a more coherent product and platform narrative.
Moloney adds: “We looked at the journey and the experience and the offering, and realised by combining all three, whilst doing different things, we were able to bring the best of those lenders into one brand.”
In Moloney’s framing, Rely acts as both a consolidation and an upgrade. He notes that a new platform should not merely replicate an old one with new branding but combine institutional knowledge with renewed design thinking. In fact, he does not position Rely as a finished product. Indeed, OSB intends it to evolve its proposition gradually over time.
He explains: “There will be further iterations of Rely. So, Rely day one will not be Rely day seven – we aim to continuously improve the offering on there to keep up with market demands.”
The launch of Rely is intended to address two of the specialist buy-to-let market’s most persistent gaps: the pace and predictability of straightforward cases, and the capacity for underwriters to spend meaningful time on complexity.
As Moloney explains: “For the first time ever within our brands, we have a platform that doesn’t necessarily need an underwriter to look at some of the deals.”
This is supported by “years’ worth of data,” which OSB intends to utilise in order to “drive a lot of the decisioning.”
The early proof point of this, he notes, is the platform’s speed.
He explains: “We announced that we have already provided an offer within two working hours. The case hit the correct valuation pathway which could be automated, it hit the right score, and it didn’t need supporting documents, so the offer was able to be produced.”
Where specialist buy-to-let has historically relied on manual review for virtually every application, Moloney argues that this automation is now doing what is routine, so that in turn, expertise can be deployed where it matters most.
He says: “Before we launched Rely, literally every case had to be manually underwritten. So now, our new system is doing the ordinary for us so that people can do the extraordinary.”
This blended model, he suggests, brings OSB into a more modern operational tier, using “tech to do the easy parts” while “for the more complex parts we can use our experienced people to look at it.”
He explains: “It allows our underwriters to really focus on those more complex cases, or those larger portfolios where the properties are a little bit more detailed. It’s given us that great flexibility.”
Broker input has been central to Rely’s development, not as a post-launch consultation exercise but as a foundational part of how the platform and brand were designed.
Moloney explains that, while OSB Group had a clear internal vision around Rely’s system architecture, that thinking was deliberately
tested and refined through direct engagement with buy-to-let brokers operating across both specialist and mainstream markets.
He explains: “We built this system, and ultimately the brand, with feedback from brokers. We brought in the help of buy-tolet brokers that deal with both the specialist market and the mainstream buy-to-let market to ask them: ‘What is it you want?’”
That feedback translated into tangible changes. One recurring message was that lenders were asking for too much documentation, prompting OSB to strip out unnecessary requirements and embed a more proportionate approach directly into the platform. Brokers also highlighted the need for greater transparency around valuation routes, leading OSB to build a clearer, more predictable valuation pathway into the borrower journey.
Limited company lending proved to be another focal point ripe for change. As Moloney puts it: “Limited company lending is a predominant part of the buy-to-let market at the moment, we’ve seen that grow massively over the past few years.
“Because of this, we’ve seen increased questions around tax, and brokers were questioning why there was a need for a separate legal panel for limited companies. Because of this, we’ve now reviewed that as well, which ultimately helps us speed up the completion process.”
Beyond the initial build, Moloney remains clear that broker engagement does not stop at launch.
“Brokers are an integral part of the build of the brand and the platform, and their feedback is integral to the delivery. I regularly say brokers are our business,” he says.
That philosophy is backed by investment in field-based sales teams, telephony support, and underwriting resource, alongside a commitment to continual listening.
With Rely built in-house, he says OSB can now respond to broker feedback far more quickly, adjusting processes and functionality in line with real-world use.
Moloney adds: “We’re constantly engaging with them. In fact, just as part of the launch process, we get daily feedback from the field about what they like, what they’d like to come next, what’s good, what could be better.
“They’re integral to the success of this brand.”
With Rely positioned as OSB Group’s single buy-to-let brand, Moloney frames its arrival →
not as a response to short-term disruption, but as a reflection of deeper structural shifts already reshaping the buy-to-let market.
As of late, the market has been defined by two parallel stories, that of increasing professionalisation and increasing regulation. In light of this, Moloney notes the continuing shift toward limited companies and professional landlords, alongside increased competition in that area as lenders chase perceived growth.
“There’s a clear drive to limited companies,” he says. “You’ve seen more competition in that space. Some high street brands have come into that market in 2025 because that’s a major growth area. A lot of people have got bigger portfolios that are in it as a business, and we support them really well.”
Despite this growth, regulation sits in the background as a constant source of uncertainty. Now, with the much-discussed Renters’ Rights Act just recently passed through law, and set to be implemented early next year, Moloney is quick to highlight the potential for landlord uncertainty.
He adds: “The Renters’ Rights Act has just come through, and we are getting some clarity around that. No doubt you might see some people exit the market as a result of that, and then you wait and see what the rules would be.”
However, he argues larger landlords may see that potential mass-exodus as further opportunity: “But for those bigger landlords, they see it as an opportunity to increase their portfolio potentially and market share as people exit the market.”
At the same time, Moloney stresses that despite this uncertain outlook, yields remain attractive in many areas of the market.
He says: “You’re still seeing strong yields and strong returns. You do see, and we see it ourselves, people doing much more in the multiple occupancy space or higher yielding properties.
“And actually, through our InterBay brand, we’ve seen a number of landlords look to expand into things like commercial and semicommercial as well. So, I think when you look at the investor market as a whole, which isn’t just buy-to-let, there’s still big opportunities. We wouldn’t have spent a lot of time building Rely up if we didn’t believe there were further opportunities down the line.”
However, Moloney is careful not to frame buyto-let as exclusively a ‘big landlord’ market.
While the move towards professionalisation is real, he argues that new landlords continue to bravely step onto the playing field, and therefore, are in need of increased support.
He notes: “We all talk about professionalisation, but there are still new landlords coming to market. One of the good things about Rely is that we can support people who want to enter the buy-to-let property market, want to build portfolios, want to start that off.”
In terms of the future of the buy-to-let market, he is quick to point to positive industry data that flies in the face of ongoing landlord pressure – supporting the view that buy-to-let is certainly not a market that is shrinking into irrelevance.
Moloney says: “If you look at the gross lending figures for buy-to-let this year, it looks like we’ll probably be up on last year. That’s certainly a positive.”
Indeed, even if refinancing is a major component of this figure, he notes that the purchase market still remains strong.
He adds: “If you look at the latest forecast that’s come out from UK Finance for next year, they’re saying the market should be similar or slightly above it.”
However, the clearest demand indicator remains the widespread reliance on rental stock.
Moloney notes: “One in five people in the UK still live in rented accommodation. That tells you there’s going to be demand, right?
“Landlords are smart. They look at the return on their investment. Definitely if you’ve got the experience, you can get the asset, particularly HMO or MUFBs which are really popular – they can maximise those returns.”
Indeed, he remains bullish on opportunity in the private rented sector (PRS), even as competition intensifies: “I think there’s still good opportunities […] competition will be hard.”
He adds: “That’s good news for the landlord because, of course, the more people you’ve got out there fighting for business, that means that rates could potentially be quite competitive.”
Looking ahead to the wider market in 2026, Moloney expects the mortgage sector to be shaped by a convergence of factors rather than a single dominant force, with regulatory followthrough and heightened lender competition all playing defining roles. After what he describes as a challenging and operationally intense 2025, it is clear there is a palpable sense across the
sector of moving into a new phase.
He says: “As I sit here going into 2026, we’re all probably glad 2025 is over. In some ways, getting a new lender to market was quite hard, but for us, having an established investor brand out there now, having the industry experience with the team that we have, and a new platform that can get things to market a lot quicker – I think there is plenty of opportunities.”
Indeed, rate expectations also loom large in his outlook, with Moloney pointing to the recent December Base Rate reduction as an overwhelming sign of positivity, along with the seasonal behaviour that typically follows.
He adds: “Every lender hits off the start of the year hard because they want to build pipeline for the year and get ahead of that.”
For intermediaries, however, the most powerful driver of activity may be structural rather than cyclical. Moloney highlights the scale of fixed rate expiries due in 2026, noting “a record number of fixed rate reversions, potential product transfers, potential remortgages,” creating significant demand for advice and lender support across both buy-tolet and residential landscapes.
Specifically within the owner-occupied market, he sees product transfers continuing to dominate volumes, describing them as “a big opportunity” for brokers, even as questions remain around execution-only rules and the risk of channel conflict for lenders operating both direct and intermediary routes – but he remains confident in brokers’ ability to navigate that complexity.
Moloney argues that intermediaries have already proven their value, pointing to “a swing massively in favour of distribution through brokers rather than through direct channels,” and praising the role of advisers as they “have done a phenomenal job of supporting borrowers” in the post-Mortgage Market Review (MMR) landscape.
As the conversation turns to what comes next for OSB, Moloney is careful to strike a balance between ambition and realism.
“If you talk about a couple of years ahead, that’s a long time,” he says. “But I think it would be fair to say that we’ve been blown away with the success of the Rely launch.”
The immediate priority now, he explains, is simplification and focus.
This involves retiring legacy propositions, further consolidating buy-to-let under the single Rely brand, and building out a clearer
We all talk about professionalisation, but there are still new landlords coming to market. One of the good things about Rely is that we can support people who want to enter the buyto-let property market, want to build portfolios, want to start that off”
structure across the group’s specialist offerings.
Beyond Rely itself, the strategy is underpinned by a longer-term platform vision already underway. Moloney outlines future plans to migrate other brands onto the same technology, starting with Precise’s residential offering.
He explains: “That will give us a bigger offering in terms of products, but it also enables us to bring in this valuation technology that we use on Rely to speed up the process of the residential offerings.
“Further down the line, the plan is to bring commercial and bridging onto that platform as well. Then you’ve got a real consistent approach up front of speed, reduction in keying, reduction in paperwork, and a lot clearer role in terms of the valuation pathway. This is phase one of a really exciting pathway for OSB’s brands.”
For brokers, he believes this clarity of structure matters as much as innovation itself.
“I think the fact that we’ve got that clarity of where the brands support the market is really important for brokers,” he says, noting that early feedback suggests the strategy is resonating.
He adds: “Having this brand clarity between our offerings is what they want […] and that gives us the reassurance that we’ve done the right thing.”
Looking ahead, with a new lender launched, a simplified house of brands and a broker-only model firmly in place, OSB’s focus now turns to building on those foundations. As Moloney sums up: “2026 will be an exciting year.” ●
TERRY WOODLEY managing director of development nance at Shawbrook
In the lead-up to the Autumn Budget, the UK property development sector was operating under a cloud of cautious anticipation. Our research captured the overall sentiment from the industry in this period – with 45% of developers holding a negative outlook on the economy, and 79% reporting difficulty accessing Government support.
There was hope that the Government would share a plan to deliver on the structural ‘building blocks’ the industry has been crying out for. But the Budget ended up feeling like a missed opportunity. Rather than providing a catalyst for growth, the Budget announcement le critical issues unaddressed.
As we move into 2026, it is clear that developers cannot wait for a ‘cavalry’ that may never arrive. Success over the next 12 months will depend on how the sector navigates three persistent challenges: planning inertia, the cost of talent, and a stagnant sales market.
The Government’s ‘build, baby, build’ mantra has always been contingent on planning reform. A fi h of mid-sized developers cited a reduction in red tape and regulation as a key priority, and while the Budget included mention of this in the long-term, it provided no immediate relief from the endemic red tape.
We must be realistic - planning reform is a slow solution to an urgent crisis. Even with the appointment of new advisers and the promise of streamlined processes, these structural changes will likely take years to deliver tangible benefits. In 2026, developers will still find themselves navigating a complex, under-resourced system.
The strategy for the year ahead must be one of ‘proactive patience’. This means accounting for longer lead times in financial planning and ensuring that projects are futureproofed against shi ing requirements. Those who thrive will be the ones who treat planning not as a hurdle to be cleared, but as a core risk to be managed with robust contingencies.
One of the most disappointing aspects of the recent policy landscape has been the lack of movement on the skills gap. Despite the Government’s ambition to train 60,000 more skilled construction workers by 2029, we are yet to see a notable shi in the workforce.
23% of developers were looking to the Government for support with hiring talent and training younger workers, but the Budget’s tax hikes and the rise in the National Living Wage has had quite the opposite effect.
For 2026, this creates a dual pressure: a lack of skilled labour coupled with rising operational costs. In the year ahead, successful project management will depend on careful people management and cost efficiencies. Developers must ensure their financial partners understand these inflationary pressures and offer the flexibility required to keep sites moving.
The engine of the housebuilding industry is the first-time buyer, and currently, that engine is at risk of stalling. Without a successor to the Help to Buy scheme or a revised incentive package, the ‘entry-level’ of the market is struggling under the weight of high inflation and interest rates. The absence of support for firsttime buyers in the Budget suggests that 2026 will be a year of sales market
uncertainty, and a potential that it will stagnate.
For developers, this requires a shi in thinking. We are already seeing a move toward more diverse models, such as Build to Rent (BTR) or professionalised house in multiple occupation (HMO) schemes, to tap into the persisting rental demand where homeownership is out of reach.
Financial planning for 2026 must account for potentially slower sales and ongoing uncertainty. This is where the choice of a funding partner becomes critical. Working with a lender who understands the cyclical nature of the market – and who won’t disappear when the sales curve fla ens – will be the difference between a stalled project and a successful completion.
Despite the disappointments of the Budget, there does remain hope. Ahead of the announcement, 72% of developers expressed trust in the Government to contribute to small and medium-sized enterprise (SME) growth in the year ahead. While that trust may have been rocked, the underlying resilience of the sector remains.
UK developers are among the most adaptable in the world - they have spent years building in spite of the system, not because of it. Success in 2026 will be delivered by developers who are proactive, resilient, and supported by partners who truly understand the complexities of the landscape. ●
When HSBC UK re-entered the broker market in 2022, it became clear how the landscape had changed and how brokers now play a central role for many small to medium enterprises (SMEs) accessing finance.
More than 20 years ago, when I first worked closely with brokers, the market was very different. This shi has been one of the most important learnings for us as a bank over the last three years. For many businesses brokers are now the first port of call.
The quality of propositions coming through intermediaries is now on par with what we see directly, and in some cases the credit quality is stronger. SMEs are be er advised, be er prepared and clearer about what they need which allows for a positive experience for clients, brokers, and lenders alike.
Our initial approach was deliberately measured, to ensure the relationship with brokers was developed in the most effective way. Following an initial 18-month pilot with term lending products, we broadened our offering to include, trade, invoice finance, and asset finance with a focus on SME and midcorporate businesses.
What followed has exceeded our expectations. In 2023, around £60m of the bank’s lending came through intermediaries, rising to £0.25bn in 2024. In 2025, we surpassed £500m.
But this growth isn’t accidental, it reflects sustained investment in people, technology and relationships from HSBC UK. We now have 14 dedicated business development managers (BDMs) covering the intermediary market, who are
supported by a wider network of relationship managers and directors across the bank.
For brokers, that means complete simplicity with one point of contact who can bring the full capabilities of HSBC UK to the table.
It’s important also to consider scale, and why it ma ers here. With hundreds of relationship managers and sector expertise supporting them, our BDMs are not selling individual products. Their role is to present a one-stop-shop, helping brokers and their clients determine how different parts of the bank fit together, from lending and cash management through to specialist sectoral support.
Our focus on brand and clarity has been equally important. We recognised the need for brokers to understand what a lender stands for, and where it is competitive. For us, that meant being clear on ‘why HSBC’.
The answer? We can combine local decision-making for UK SMEs with the strength, experience and international reach of a global bank.
Yet, challenges do still present themselves. We’re conscious that some
IAN COULSON is head of commercial brokers at HSBC UK
SMEs and intermediaries still see a disconnect between global banking and domestic SME lending. Our continued focus is on aligning the two, ensuring local and global work in parallel, and providing a banking option that remains relevant to earlystage and mid-market businesses, while also continuing to support clients with international ambitions.
Looking ahead, growth is the continued ambition for us. Working with more brokers, widening the net and building long-term relationships that go beyond individual transactions will support our aim of being the leading high street lender for intermediaries by 2028.
For this growth to continue, brokers remain a central part of the journey. They bring insight, reach, and trusted relationships with SMEs across the UK. For banks that want to support growth, intermediaries are no longer options, they are essential. ●
The Government’s ambition to invest
£13bn in retrofi ing to create ‘zero bill’ homes represents a significant opportunity to improve comfort, cut energy costs, reduce fuel poverty and accelerate progress towards net zero.
However, to deliver on that promise, creating the conditions for zero bills homes must start at the point of construction and not be treated as an a erthought years later.The announcement focuses on retrofi ing existing homes with low-carbon technologies, including heat pumps, solar panels and ba ery storage.
While these technologies are welcomed and play an important role in helping to reduce our reliance on fossil fuels, retrofi ing existing properties o en presents challenges.
In many cases, households face disruption, complex installation processes and costs of £20,000 to £25,000 and even then, results can be quickly undone if the property itself is not already well insulated and airtight.
Fundamentally, low-carbon technologies can only deliver true energy savings when the home itself is designed to minimise energy demand. Designing net zero homes properly from the outset is far more costeffective and far less disruptive than a empting to resolve performance issues later down the line. Improving the thermal performance of homes remains one of the quickest ways to cut bills, reduce carbon emissions and create healthier places to live.
That’s why future-proofing new homes from the outset ma ers. Longterm energy performance, not shortterm compliance, is what ultimately protects households and ensures
public investment delivers real value for the future.
Action must go beyond retrofi ing technologies alone and focus much more on building energy-efficient, future-proofed homes from the very start of construction. When homes are designed with high levels of insulation, natural materials and integrated renewables, zero energy bills become achievable without the need for costly upgrades.
We must not forget that building net zero homes is not just about reducing energy bills or meeting carbon targets. Well-designed, energy-efficient homes are also healthier home environments for those living in them, and that benefit is o en overlooked.
Poorly built housing contributes to damp, mould and poor indoor air quality, all of which can cause health issues in both the immediate and long term.
According to the Health Foundation, cold homes are estimated to cost the NHS more than £1bn each year, as they exacerbate respiratory and cardiovascular conditions and can both cause and worsen mental health issues.
Homes that are properly insulated and airtight, with controlled ventilation and improved air quality, reduce condensation and mould, protect homeowners and generally provide be er overall wellbeing.
At Greencore Homes, we’re proving that our homes can deliver exceptional energy efficiency, low running costs and comfort from day one.
Our homes are built to Passivhaus standards using natural, nontoxic materials to ensure superior insulation, airtightness and comfort. Standard features include triple-glazed
windows, air source heat pumps, optimised solar PV panels and EV charging points, reducing bills and carbon while giving people homes that are healthier and more comfortable to live in.
Warm homes should be treated as critical national infrastructure – every year of delay is a missed opportunity to improve living standards, strengthen energy security and accelerate the UK’s progress towards net zero.
We don’t just stop at the homes themselves; sustainability is at the core of everything we do. By taking a landscape-led approach to each and every development and ensuring we incorporate sustainability practices from day one of a design, we are able to enhance local ecology and create climate positive communities.
We adhere to Bioregional’s One Planet Living Framework when designing each of our developments as part of our commitment to creating sustainable and thriving places to live.
Delivering zero bills depends on embedding energy efficiency, strengthening building fabric with low-carbon materials and designing health and wellbeing advantages into homes from day one. ●
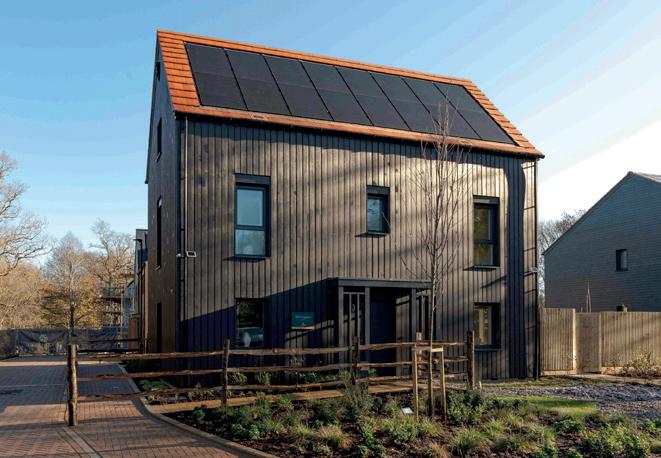
For all the turbulence the UK property market has faced in recent years, one thing has remained, for the most part, the same: global investors continue to look to the UK for bricks-andmortar investment opportunities.
According to a recent survey we ran among 300 UK mortgage brokers, 93% of mortgage brokers have worked with non-UK resident borrowers in the past five years.
Yet only 2% say sourcing mortgages for these clients is “not challenging at all,” while the remaining 98% describe it as anywhere from slightly to extremely challenging.
In other words, the demand is not the problem, even if the market has slowed somewhat since the end of the non-dom tax regime.
The challenge lies in converting that demand into completed transactions – something that requires brokers and lenders to work together to navigate the complexities of non-UK resident finance.
Unless the market can respond with be er-aligned products, support and expertise across brokers and lenders, the UK might risk losing a valuable pool of buyer demand – especially in the Prime Central London (PCL) market, in which global investors are particularly active.
In spite of shi s in political leadership, tax policy, and global economic conditions, the UK remains a powerful draw for overseas buyers.
More than three-quarters of brokers (77%) say demand from non-UK residents has increased in the past five years.
This diverse range of investors
shows that the appeal of UK property is known around the world, and that’s largely down to some key advantages. For example, the UK education system remains world-renowned and continues to a ract families seeking long-term residency or investment near major universities.
What’s more, the legal system is viewed as robust and predictable, while cities like London retain their appeal as global financial and cultural centres.
As such, for many investors, the UK appears to be a relative haven of stability despite recent policy shi s.
Yet the fact that international demand persists – and is in many cases rising – suggests that the UK’s core appeal remains intact.
What’s clear from the data is that the complex financial profiles of overseas buyers – whether that’s income from multiple jurisdictions, assets held in overseas structures or irregular income flows – cause mainstream lenders to step back from these type of cases.
This creates a service gap that specialist lenders can fill, as it means that brokers require access to flexible, bespoke mortgage solutions to help them convert client interests into converted deals.
But as complexity deepens, it’s important to remember that education and communication are now just as important as product availability.
Clients are increasingly navigating an ever-growing list of cross-border tax changes, currency movements and shi ing regulations.
Therefore, lenders who can help brokers provide clarity, responsiveness and proactive updates can contribute
ALPA BHAKTA is CEO at Butter eld Mortgages
to maintaining investor confidence and, ultimately, demand.
These issues are particularly pronounced in the Prime Central London (PCL) market, where international buyers remain a key demographic.
It means that, for brokers operating in this space, ensuring that they have the right tools at their disposal will be essential in helping the market find its feet again a er months of uncertainty.
Encouragingly, transaction data indicates that this is already happening – Knight Frank recently reported that clarity following the Autumn Budget caused exchanges across the PCL sector to rise around 5% higher than the five-year average.
However, with the implementation of some recent tax changes still to come in the next couple of years, lenders and brokers must work closely together to provide the necessary support that international buyers need.
As we look ahead, the fundamentals that underpin the UK’s global appeal remain firmly in place.
With inflation easing, interest rates expected to fall and greater political clarity beginning to filter through, there is every reason to believe that international demand will continue to strengthen.
If lenders and brokers can combine their expertise, the market, and particularly PCL, will be well positioned to turn renewed confidence into meaningful activity in the year ahead. ●
Ispend an inordinate amount of time speaking with financial counterparties and industry partners about the long-term shape of the UK housing market.
Ever increasingly, those conversations are framed by a broader concern coming out of the City: If institutional investment isn’t enough to cover what we need, is Britain’s vast pool of pension capital next? Can this be invested in a way that is productive, resilient, and visibly beneficial to the domestic economy? Or to mitigate some of the risk of that, is now the time to aggressively expand private credit and specialised markets? This includes opening up the powerhouse that is our traditional and regulated domestic mortgage broker market to what could not only be the missing link between private credit and our home builders, but could also be a market that is set to exponentially ‘boom’ in the coming months and years.
UK pension schemes manage trillions of pounds, yet only a relatively small proportion find their way into UK infrastructure or productive domestic assets.
For years, capital has flowed efficiently into global equities and liquid markets, but the result has been a growing disconnect between longterm savings and long-term national needs.
Housing, infrastructure, and small and medium-sized enterprise (SME) growth all sit squarely in that gap, and, through a process perhaps of kismet or a simple twist of fate, our sector has stepped into the breach to fill the missing link between capital and housing growth.
From my perspective as partnership director at Invest&Fund, I believe specialised private credit, such as our asset class, is one of the most understated and underexplored opportunities in the market.
The private credit show is not new, but its specialised application by our sector to UK housing and SME development has matured significantly. It offers something that traditional bank lending o en struggles to provide, patience, flexibility, and deep sector understanding. The UK does not suffer from a lack of demand for homes; it suffers from structural friction in how those homes are financed and delivered. Small and medium-sized housebuilders, who once accounted for a far greater share of housing supply, have been disproportionately squeezed by planning delays, rising costs, and constrained bank appetite. Yet these builders are essential if we are serious about boosting delivery, improving design quality, and building in the right places.
Where private credit ts in the housing puzzle
This is where specialist lenders like Invest&Fund sit. We are an institutionally backed private credit platform, purpose-built to support SME housebuilders and propertybacked businesses across the UK.
Our capital is long-term, and our underwriting is grounded in the realities of development rather than tick-box credit models. That alignment ma ers, not just commercially, but strategically.
But capital alone does not solve the problem. Distribution, advice, and access are just as important. This is where intermediaries play a crucial role.
Our broker partners sit at the sharp end of the market. You understand local developers, regional dynamics, and the nuances of individual projects be er than a few others do.
You see, every day, where good businesses struggle to access the right kind of funding, not because they are bad bets, but because they fall outside the narrow parameters of high-street lending. Working with specialist
ALAN FLETCHER is partnership director at Invest&Fund
lenders is not about replacing banks; it is about complementing them.
Brokers who engage with platforms like ours help match the right capital to the right opportunity. In doing so, you are not only supporting your clients’ growth but also contributing to a much larger market opportunity: the revival of SME-led housebuilding at scale.
That opportunity is significant. Estimates suggest that if SME builders were able to regain even part of their historic market share, tens of thousands of additional homes could be delivered each year.
That would ease pressure across the housing system, from affordability to rental supply, while supporting regional economic growth. It is difficult to think of many sectors where the alignment between investor returns, and social impact is as direct as in this one. As previously stated, maybe it was just a twist of fate, but what started as an interesting narrative about the ba le to save the UK housing market has become reality.
For brokers, the message is not that you need to become infrastructure experts or institutional allocators. It is simply that by engaging with specialist lenders like us, you can help unlock a market that is growing in relevance and importance.
In doing so, you are part of a broader shi : reconnecting British investment with British growth. That, to my mind, is exactly the kind of investment story the UK needs more of. ●
the rise of luxury asset-backed
Ray Palmer’s pathway into finance is somewhat unconventional, compared to many in this industry, which perhaps reflects the complex and specialist nature of his current work. His career started in logistics, distribution and retail. He entered lending following a pivotal meeting with Paul Aitken, which led to the creation of Borro, an early online pawnbroking platform.
Taking the leap into financial services with a background in logistics proved invaluable, helping Palmer meet challenges that arose in terms of securely transporting customers’ valuables as the pawnbroking world made the shift into a digital future. Palmer’s journey with Borro moved from London to New York and back, until 2019 when he reconnected with Aitken to acquire Suttons & Robertsons, a pawnbroker founded in 1770, specialising in luxury assets.
This acquisition would provide the bricks and mortar foundation for Suros Capital, the luxury asset short-term lender that launched in November 2020, with the aim of sourcing and supporting larger deals.
As the role of luxury asset lending evolves and brokers increasingly look for new ways to support their clients, The Intermediary sat down with Palmer to understand the product, the assets, and everything brokers need to know.
While Suros Capital came from a consumer-facing foundation, Palmer is clear that its success as a lender comes from its work with intermediaries.
Palmer says: “There are limitations to what you can achieve just through marketing and footfall. We knew the bigger transactions would come from the intermediary market.
“If you’re looking to borrow £100,000-plus you don’t typically just go on Google and see what turns up. Normally, you’ve got somebody that looks after your financial affairs.
“The more sophisticated clients – it’s that audience that we knew we needed to reach out to, alongside the bricks and mortar stuff.”
The company was launched with a database of around 2,000 intermediaries, enabling a fast
launch and market penetration. Beyond this, it engaged in an early strategy of marketing and targeted networking to build up this all-important broker base. Of course, launching in 2020 brought with it its own set of unique market conditions. Nevertheless, in the face of widespread shutdowns due to the pandemic, pawnbroking was considered an essential service. Meanwhile, Suros Capital found itself on an upswing as lockdowns meant some cohorts accumulated more savings, while new lending use-cases emerged. For example, Palmer points to entrepreneurs refinancing debt, or capitalising on PPE-related opportunities to turn the Covid-19 disruption to their advantage. Palmer explains: “We even lent to a client on their classic car collection, who was looking at procuring PPE and selling it under contracts from Government.”
Following on from this unique start, and despite fluctuating demand since the pandemic, Suros Capital has doubled its growth since early 2023.
It is difficult to define what counts as a ‘typical’ deal in a side of the market that is, by its nature, so varied.
Commonly used asset categories might include luxury cars, jewellery, watches, art and gold. Recently, Palmer has also seen an increase in lending based on wine. There are seemingly few limits on what can be considered a viable asset, although Suros has to be careful of where to draw the line. Examples of this include luxury yachts, which have in the past proven hard to guarantee will remain in the same condition through the term of the loan, and a high-performing racehorse, which was not deemed a wise security, despite being valuable.
Indeed, with a Damien Hirst already being kept under tight security in the vault, one wonders where the racehorse would even fit.
The client profile and loan uses are perhaps easier to predict. Suros Capital uses these assets to help borrowers act tactically in various ways, often to support business concerns, pay tax bills, make other investments, or make the most of opportunistic purchases where timing is critical. This can also be a helpful tool when it comes to
property transactions, either to leverage better value from the deal, or make up for the unexpected costs that often arise during a deal.
Palmer says: “I often see asset-backed finance as an opportunity to dovetail with, say, property transactions and provide a top-up – like a mezzanine – so that a deal can get done.
“You could even argue that it’s the equivalent, in some cases, of adding 5% to 10% to the loan-tovalue (LTV). So, if there’s a £1m house and they can only get £700,000 out of it and need £800,000, the extra can come from somewhere else and suddenly they’ve got 80% LTV, which you wouldn’t get in bridging, or at least you’re going to pay a heavy price for it.
“It’s not always going to be the solution in its own right, but it’s going to be part of a solution to give people the money they need.”
Around 45% of the lender’s book goes to businesses, namely those with simple corporate structures, including those that deal in luxury items looking to leverage their own stock much like others would with machinery or equipment. The individuals, meanwhile, tend to be “sophisticated, and typically high net worth [HNW].”
Palmer adds: “There are HNW and business purpose exemptions in consumer credit, which means you’re dealing with a more sophisticated client in the first place. They know what they’re getting into, unlike your ‘average Joe’ who just walks into a mortgage broker.”
With such variety even just among the assets being used to leverage deals, specialist expertise is paramount at Suros Capital. At its core, the business has a combined 100-plus years of in-house expertise in areas such as watches and jewellery. This includes the ability to value items, as well as identify fakes, understand market fluctuations, and model risks.
Palmer says: “They can pick these things up and, even by the feel, spot fakes. And of course, they’re aware of changes in the market and everything else.”

Phillips, and some more of the provincial houses around the country.
“We also have a panel of experts that we can turn to when it comes to cars, wine, art.”
Human expertise is an important part of the process, but Palmer also points to the increasing use of data as part of valuation, particularly when it comes to art. ArtNet, for example, is a database of all auction results going back 30 years, while Overstone Art Services uses a combination of AI tools and expert insights to independently measure financial risks and indicators.
Much more so than in the world of property, these valuations must take into account a flurry of market trends.
“For example, the biggest thing in diamonds right now is the influx of synthetic stones, grown in laboratories,” Palmer explains. “They’re devaluing the diamond market for rarer, naturally occurring stones.”
In the art world, meanwhile, authentication challenges outweigh the hurdles around pricing a piece, particularly with fine art where some foundations will no longer authenticate, due to the legal and reputational risks of getting it wrong.
The art world has also seen consecutive annual declines in the current period, as well as a shift away from the Old Masters and towards more contemporary and modern names. Palmer does predict that the art market will likely return to form once prices reduce enough to attract new buyers.
Gold has seen its values shoot up 50% in 2024, with a substantial rise in borrowers leveraging gold collections rather than selling them. Palmer points to examples of multi-million-pound gold holdings being used to fund business launches.
Palmer says: “Gold is a safe-haven investment vehicle when markets are in turmoil. Look at currency – when that’s going bad, people turn to gold. That’s where we’ve stepped in. People want to leverage gold that they’ve maybe bought and collected over time – they don’t want to liquidate it, as they still feel that it’s going to continue to grow as an investment over time.”
The watch market saw a peak in late 2023, followed by a sharp correction and then stabilisation and renewed
auction houses – Sotheby’s, growth.
For those areas that need external valuation, Suros partners with big names. Palmer explains: “When it comes to other assets that are out of our remit, we are in touch with all of the auction houses – Sotheby’s, Christie’s, Bonhams,

All of these patterns will affect how much a borrower is able to lend, in addition to the terms and criteria on offer.
much a borrower is able to lend, in addition to the terms and criteria on offer. uses
Suros Capital uses different LTVs based on, for example, the ease of liquidation of an asset, and uses covenants to manage depreciation risk that, for example, account for additional cash or assets if the value
drops below 20%. Underpinning all of this is the matter of the physical asset itself. Not only are these items valuable, they often also have sentimental, historical and cultural weight.
Suros, Palmer says, aims to return items to its clients “in at least the same condition, if not an enhanced condition.”
This might be as simple as ensuring the correct storage for a painting, or might stretch to having a watch detailed, vehicle serviced or jewellery polished.
Palmer adds: “Because that was my original background, I’ve always been the one that tends to find solutions and put those in place.”
To this end, asset logistics and protective handling are central parts of the value proposition, including global partnerships with specialist storage and shipping firms, to address the complex challenges in this market that more ‘mainstream’ lenders simply do not face.
Myths and misconceptions
When Palmer first got into the world of pawnbroking, he had many of the same misconceptions that are still around today.
He says: “I thought, isn’t that back street, blacked out windows, hand over your stuff and never see it again, kind of stuff?
“That was something we really tried to destroy, especially in the Borro days. Instead, it was all about what could your asset do for you. We even did TV campaigns where a guy went on holiday and said, ‘my watch got me this holiday’.
“For the broker market, I guess they feel that we’re expensive, compared with bridging. Let’s say bridge lending is 1% a month – we’re typically at 3% a month. But if someone borrows £100,000 from us for six months, and £700,000 at 1% for a year, when you blend it all together, the incremental cost to the borrower is not as significant as 3% sounds.”
This is about more than just rate and cost. For example, in the worst-case scenario, this might mean the difference between losing a watch and losing a family home.
Palmer says: “Sometimes it’s sentimental, and people don’t want to let it go. But if there isn’t so much of an attachment, it’s an asset and it served a purpose.”
Whether due to negative misconceptions or simply a lack of awareness of this option, the luxury asset-backed lending market is often hampered by brokers failing to present clients with the products available to them. Indeed, it is rare to find brokers discussing luxury assets with their clients, even those that are HNW and prime candidates.
Palmer suggests that questions around
The luxury
asset-backed lending market is often hampered by brokers failing to present clients with the products available to them.
Indeed, it is rare to find brokers discussing luxury assets with their clients, even those that are HNW and prime candidates”
household and personal assets should be part of the initial fact-find.
He adds: “Often when they do their fact find and look at assets and liabilities, a lot of these things just get forgotten about, because they don’t know how to handle it. It’s about education, because more property deals will get done if brokers are aware of these extra bits that you can bolt on.”
To this end, Suros Capital is active in providing training sessions to help explain the opportunities that brokers might be missing to help their clients even further, as well as establishing strong relationships with larger intermediary firms, such as Loans Warehouse.
Overall, Palmer says the push should be for brokers to offer holistic solutions, rather than defaulting to property-only thought processes and losing out on potential deals and deeper client relationships.
In order to reward brokers and help push this product further into the forefront of their awareness, Suros Capital is offering a 3% proc fee for business introduced in Q1 2026, to start the year off on the right foot.
For Suros, this is just the start of things to come, with plans to modernise its systems and optimise its websites for the new normal of AI searching, as well as blueprints for a US expansion of the business in early 2026 alongside continued UK growth. Within this, the lender plans to grow the proportion of business lending within its portfolio.
In the end, as the business grows both its lending and its reach, Palmer simply calls for brokers to be open to all the products available to their clients, and to factor assets beyond just property into their conversations, to make the most of the year to come. ●
The Intermediary speaks with Andy Neo, key account manager –South Coast and Central London at Together
and why did you become a BDM?
I became a business development manager (BDM) through a combination of hard work and a little bit of chance. A er graduating with a degree in Business, I realised the subject was broad and didn’t point to one speci c career path. I began my journey at NatWest, spending seven years in lending sales and commercial banking.
During that time, I discovered that a relationship manager role suited my skill set perfectly. When the o ce I worked in closed, I pivoted to a bridging lender in a sales support
role, which gave me deeper insight into the industry.
From there, I moved to Signature Property Finance, where I spent three years honing my skills in the bridging and development space, managing the process from cradle to grave. In this role, I instructed valuers and worked directly with clients and brokers, and the experience I gained from it really helped me to understand the inner workings of how a lender operates and all the stages integral to a loan being drawn down and repaid. Eventually, I felt ready for a new challenge, worked my way up the ladder, and ultimately joined the intermediary team here at Together.
Looking back, those tough days when I was inexperienced or faced challenging situations really shaped my BDM style today.
A er three years in bridging and development nance, an opportunity arose at Together. I had always admired the company for its strong history in the market and its wide range of exible products. I wanted to broaden my expertise beyond bridging and development nance, learn how a large lender operates, and continue growing
professionally. I had always aspired to join a large rm with big ambitions, and the great thing about Together is that although it’s a juggernaut of a company, it still retains that small-to-medium size feel where your contributions are recognised. What’s more, Together actively encourages growth and development, which is key to creating the best teams and culture.
Joining Together was one of the best decisions I’ve made. I’ve now been here for four years and absolutely love my role.
Together stands out for many reasons, most notably as the largest non-bank lender in the UK. Our agship product, unregulated bridging, is fast, exible, and consistently pushes boundaries in monthly lending volumes.
What really sets us apart is our approach: we assess deals on their individual merits rather than applying a one-size- ts-all model. is makes the role incredibly rewarding, as you can in uence decisions and apply your experience to make sure the brokers’ client is getting nance tailored to their speci c needs.
On top of that, the team at Together is exceptional, I can honestly say I’ve never worked with a better group in my 15 years in the industry.
e biggest challenge for BDMs today is staying organised and reliable when clients need us. e role is highly varied; balancing meetings, travel, and product changes, so being able to pivot quickly while maintaining trust is essential.
ings do go wrong from time to time, but if you’ve built strong
relationships and trust, you can work together to put things right.
Another ongoing challenge is keeping up with market trends and volatility, which requires constant attention and adaptability.
I’ve noticed some BDMs struggle when positioning their lender’s products.
Personally, I believe if you know your products inside out and understand where they t in the market, it becomes much easier to shi the focus onto those areas.
e mortgage market is always evolving, which means there are constant opportunities to build new relationships.
For me, relationship-building has always been the cornerstone of success. While emails, calls, and visits are important, establishing genuine, positive working relationships delivers the greatest results.
When brokers see that you’re reliable and know your products inside out, trust follows, and that trust drives business.
Looking ahead to 2026, if the Bank of England base rate continues to fall, we could see increased con dence and more opportunities for growth across the industry.
I always start by setting clear expectations for both parties and identifying potential pitfalls early in the process. By discussing possible hurdles upfront, we can address them before they impact the customer.
I also make sure we agree on what the best outcome looks like for the borrower from the outset, so everyone is aligned and working toward the same goal throughout the case.
Don’t become overly xated on rate. It’s easy to chase the cheapest product, valuation, or legal fees, but that doesn’t always lead to the best outcome. Experienced property professionals o en understand this – they may choose the path of least resistance or be prepared to handle obstacles later on. For example, a bridging loan that’s 0.5% cheaper but takes six weeks longer could jeopardise the entire deal and cost more in other areas.
If the numbers still work at a slightly higher cost and the borrower is comfortable with the margin, that can o en be the smarter choice.
What would you like people to know about you outside of work?
I’m a big golf fan, something I picked up later in life when football became a bit too demanding physically! Golf season in the mortgage industry is my favourite time of year, especially the Together Golf Day. I’m also a massive Arsenal supporter, and I’m convinced this year is our year! ●
Together
Established in 1974
Products
◆ Regulated rst and second charge
◆ CBTL rst and second charge
◆ Regulated and unregulated bridging rst and second charge
◆ Commercial and semi-commercial term
◆ BTL and homeowner business loans rst and second charge
Contact details
Andy.Neo@togethermoney.com 07716 093 019
TOMER ABOODY is director at MT Finance
While few will mourn the passing of 2025, which was a tough year for many, the bridging finance sector demonstrated remarkable resilience, defined by the exceptional agility, efficiency, and adaptability it is known for. Despite broader economic concerns, bridging finance proved itself once again as a strategic tool for borrowers seeking speed and flexibility,
Looking ahead to this year the outlook is more promising. The most recent HMRC figures show that transactions continue to rise as buyers take advantage of lower mortgage rates, with many who put off decisions to move until they discovered what the Chancellor had in store, deciding now is the time to buy. Although confidence in the Government is low following two damaging Budgets, needs-based buyers have to move and simply can’t wait for the political or wider economic situation to improve.
We hope to see further market activity in the form of an increase in transactions this year, encouraged by lower bank rates. However, the high cost of moving remains an issue, and is deterring many from doing so. Stamp Duty in particular is a huge barrier to mobility and with the Chancellor missing an opportunity to reduce or reform it in the Budget, the hope is that further interest rate reductions this year will encourage transactions instead, enabling the housing market to function more effectively. We have long called for a restructuring of Stamp Duty to encourage downsizing in particular, freeing up larger family homes for those trying to move up the ladder,
and once again an opportunity to do that has been missed.
With Nationwide and Halifax both pointing to a fairly flat property market in terms of prices towards the end of last year and not much growth expected this year, although this won’t be welcomed by homeowners, it is be er for all concerned.
While the interest-rate environment is more positive, with lenders keen to offer a ractive mortgage rates, it doesn’t take away from the fact that wages aren’t rising quickly enough to combat the higher cost of living. One can only buy what one can afford, so fla er property prices are a good thing for the market as a whole. However, a non-rampant housing market is not enough to provide the impetus needed when encouraging buyers and sellers to transact, and in particular, when persuading first-time buyers to take the plunge. The Government must do more to encourage transactions through targeted stimulus for firsttime buyers, perhaps in the form of a resurrected Help to Buy scheme. Encouragement for developers and housebuilders is also lacking, and without it, the Government’s new homes target is unlikely to be reached.
Looking ahead, the momentum from 2025 is set to usher in a new era of specialisation, technology, and sustainability for the industry, especially in bridging. We expect to see the widespread adoption of technological advancements and streamlined digital platforms as lenders, including ourselves, look at ways to improve our processes. On our part, we will continue enhancing operational efficiency to significantly accelerate application processes, changing how we assess property
values, risk, and exit strategies.
Lenders remain keen to lend and increased competition is likely to feature this year, which is good news for borrowers as it should drive product innovation, resulting in more customised loan structures, higher loan-to-value (LTV) products, and a proliferation of niche offerings. We also anticipate that bridging will be used more widely, moving beyond traditional residential and investment property transactions to include commercial-to-residential conversions and strategic business finance and debt consolidation. With more brokers entering the bridging space and educating themselves as to its benefits, we expect this year to bring further market expansion beyond traditional specialist finance circles into mainstream mortgage advisory. Whether supporting investors capitalising on opportunities, property developers requiring flexible funding, or existing borrowers navigating market challenges, bridging finance will continue to cement its position as an essential component of the UK property finance landscape.
We strongly believe that another focus for 2026 should be a responsibility to contribute positively to society. It’s vital not to forget the importance of social initiatives and at MT Finance these form part of our broader ESG strategy, reflecting our values and our commitment to our community. We plan to build on the strong momentum of 2025, expanding our community engagement, sustainable practices and embedding ESG principles into the heart of everything we do – we encourage others to do the same. ●
The la er part of Q2 and the early weeks of Q3 were full of conversations that all began in much the same way: residential borrowers asking whether to wait, brokers doing their best to steady nerves, and landlords holding back until the Budget dust se led.
None of this was surprising. It was driven far more by the timing of the Budget, the intense speculation leading up to it and a wider sense of uncertainty which had li le to do with rates or products, and everything to do with people wanting to make the right call at the right time.
That same pa ern came through clearly in the Twenty7tec search data for November. Total buy-to-let (BTL) searches fell more than 13% month on month and purchase activity hit its lowest point of the financial year.
Residential searches also dipped, down 14.64% month on month and 2.91% year-on-year, but remortgaging remained the most resilient part of the market. Residential remortgage searches reached 533,653, falling 12.52% month-on-month but rising 12.51% year-on-year.
Total remortgage searches stood at 691,861, down 14.51% month on month but 7.93% higher than last year. The sustained rise in year-on-year remortgage activity reflects the steady flow of borrowers reaching the end of fixed terms and seeking stability through the winter.
Moving into 2026, there is li le to suggest that the momentum in the remortgage market will fade, and in truth the opposite feels far more likely. At a recent event, I heard that the number of residential and BTL products due to mature in 2026 sits at a record high.
I don’t have the precise figure to hand and it was shared informally, but when you think about where the market was five and even two years ago, it’s not hard to understand why this expectation holds weight.
Among this wide mix of borrowers, there will be many whose circumstances are no longer as simple as they were two or five years ago and the reality is that life has changed for a large number of people since they last fixed.
Back on track
Some may have moved from PAYE to self-employment, and others may now rely on more than one income stream. Then there are the ones who have been through a separation and need to keep the family home on a different footing and others who have encountered a credit issue during a difficult period but have since stabilised.
Every broker will recognise these scenarios straight away. They are no longer considered to be outlier, but everyday cases.
That ma ers, because tight loan-toincome (LTI) caps still dominate much of the mainstream. Those rules work well for simple profiles, but they leave less room for clients whose finances don’t follow a single pa ern. And that gap between mainstream criteria and real-life cases is only widening.
This is why specialist lenders will play an even bigger role in the 2026 remortgage market. On the residential side, flexible assessments and manual underwriting are becoming essential to support borrowers with layered income, up to 100% of secondary income, one year’s accounts for selfemployed clients, and structured options for borrowers with recent credit issues. For someone coming to the end of their deal with a more
GRANT HENDRY is director of sales at Foundation Home Loans
complex story than last time, these details make all the difference.
BTL will follow a similar path. Landlords did pause in November, with buy-to-let remortgage searches falling month-on-month, but they still rose more than 5% year-on-year. Many landlords want to refinance before exploring further investment with some needing to adjust loan structures and others looking to release capital to improve their properties, notably to improve energy efficiency.
Portfolio landlords, in particular, will rely on lenders who can work with multi-unit blocks, houses in multiple occupation (HMOs) and mixed-use stock, and who understand the balance between yield, cost and long-term planning. We also expect continued demand for early remortgaging, especially from landlords who used bridging or bought at auction and now need a longerterm option.
So while early 2026 may not bring a surge in new purchases, it will bring a steady rise in clients who need lenders to look at them in a more rounded way. Remortgaging is where those needs come to the surface, and it’s where the specialist market will continue to show its value.
In short, potential and existing homeowners want clarity and a fair assessment of their real circumstances. Landlords want stability while they plan ahead. Brokers want lenders who can work through the grey areas rather than turn away from them. And these are just some of the reasons why the remortgage market will continue to set the pace in the months ahead. ●
For many years, it has been possible to view the introduction of UK Government guarantee schemes as merely reactive responses to economic shocks – from the Enterprise Finance Guarantee, which supported businesses in the wake of the 2008 Credit Crunch, to the more recent pandemic-era loan programmes.
That narrative has changed, however, with the recent Government Spending Review. By commi ing funding to the Growth Guarantee Scheme (GGS) until March 2030, the Government has finally placed this initiative on a long-term footing.
We are moving away from piecemeal extensions and towards a recognition that a stable guarantee scheme is essential for a growing economy.If you look at the US or Germany, they have operated significantly larger, permanent guarantee programmes for decades. These aren’t emergency measures; they can be engines of GDP growth. The GGS is our opportunity to replicate that success.
The scheme has already proven its worth, hi ing the £2.5bn lending milestone in July 2025, with 69% of that capital flowing to businesses outside London and the South East.
Despite the scheme’s success, it remains misunderstood by some in the intermediary market.
The GGS aims to help small and medium enterprises (SMEs) access finance for investment and growth through loans of up to £2m, with a wide range of products supported by a broad variety of accredited lenders, including term loans, overdra s, asset
finance, commercial mortgages and asset-based lending.
The GGS provides a 70% Government guarantee to the lender, with the borrower remaining fully liable for the loan. This risk reduction allows us to look at deals where the borrowing proposition is viable but perhaps lacks the collateral or track record for a standard commercial loan.
That support is invaluable in sectors where operators may be strong candidates but lack the track record or collateral to meet conventional threshold.
Eligibility is broad, with UK-based SMEs of up to £45m turnover able to apply, provided they are not classified as businesses in difficulty.
Importantly, the GGS complements rather than replaces standard commercial lending. If we can offer a borrower a more suitable loan outside of the scheme, we will always do so.
Recent Atom cases – such as supporting a first-time pub owner to purchase their freehold using business goodwill in place of a traditional deposit – demonstrate how the combination of lender flexibility and the scheme’s framework can unlock opportunities that would otherwise be missed.
Broker feedback has been central to shaping our broader commercial mortgage proposition and that has been reflected in our GGS criteria, too. Brokers told us that experienced professionals in the care and education sectors were finding it difficult to raise finance for their first acquisition, despite having the skills and commitment needed to succeed.
We will now consider applications from first-time buyers for all GGS-
eligible businesses. We are specifically targeting sectors with high barriers to entry but strong underlying demand, such as day nurseries and dental practices.
These are vital community services where capable professionals o en struggle to make the transition from operator to owner due to strict lending criteria.
We have also updated our approach for Care Quality Commission (CQC) ratings of ‘Requires Improvement’ within the care sector. Previously, we required applicants with this rating to evidence a successful track record of turning around care homes.
However, brokers told us clearly: the material backlogs on CQC inspections are making this challenging. Operators might have improved a home’s standards many months ago, but are still waiting for the inspection to prove it. We have therefore waived the requirement to evidence this track record.
By listening to those insights, we were able to make changes that will allow more businesses to access the funding they need.
The Growth Guarantee Scheme may not have seen the same fanfare as its predecessors, but its value is undeniable. With the scheme now secured until 2030, we have a longterm runway to support UK SMEs. However, no Government scheme, however well-funded, works in isolation.
To reach its full potential, it requires the active engagement of brokers and the agility of lenders – and at Atom we are ready to do our part. ●
The news that Lloyds Banking Group is closing its invoice factoring operation marks another important moment for the UK’s small to medium enterprise (SME) finance landscape. Although banks continue to provide invoice discounting, Lloyds is not alone. Over recent years, NatWest Group and Barclays have stepped back from invoice factoring, while HSBC has tightened its criteria.
Individually, these decisions may make commercial sense for large banking groups refining their portfolios and focusing capital where returns are most predictable.
Collectively, however, they raise a more fundamental question: who will provide reliable working capital support to UK SMEs at a time when cash flow pressure is increasing rather than easing?
Invoice finance plays a pivotal role for many businesses because it provides cashflow management and effective credit control, helping customers manage debtor performance, reduce risk, and maintain healthier working capital cycles.
This integrated credit control service is particularly valuable as it ensures timely payments, mitigates the risk of bad debts, and gives operational insight that goes far beyond simply releasing cash.
Many SMEs are profitable on paper but constrained by cash flow in practice. Long payment terms remain common across the UK economy, and businesses must o en pay wages, suppliers, and VAT long before invoices are se led.
Rising costs in recent years have
increased this pressure, particularly for firms operating on tight margins or experiencing growth.
Invoice finance addresses a structural issue rather than a temporary one. It allows businesses to unlock cash already earned while benefiting from professional credit management, enabling them to reinvest in people, stock, and growth.
Used effectively, invoice finance is a proactive tool that supports both operational stability and business ambition.
When major banks withdraw from specialist products like invoice factoring, the immediate effects can appear limited.
Existing facilities are run down, new applications are declined, and life moves on.
The longer-term impact is more significant. Choice reduces. Competition narrows.
Businesses with seasonal trading pa erns, complex debtor books or rapid growth plans find it harder to access funding that reflects how they actually operate.
As the Federation of Small Businesses (FSB) has warned, many SMEs are already operating under sustained pressure.
Removing access to flexible working capital does not eliminate risk; it simply transfers it back onto business owners’ personal finances or forces them to slow growth, delay hiring or turn away work.
Large banks are built for scale, standardisation and capital efficiency. Invoice finance, by contrast, is operationally intensive and relationship driven.
GREG BELL is chief executive at Skipton Business Finance
It requires a deep understanding of individual businesses, their customers, their trading cycles and their future plans.
Specialist providers are designed around this reality. They invest in credit expertise, client service teams and systems that support day-to-day trading rather than applying broad, one-size-fits-all models. Decisions are grounded in how businesses actually operate, not just how they fit into predefined templates.
Just as importantly, specialists tend to commit for the long term. Invoice finance is not a peripheral product; it is their core purpose. That long-term commitment brings stability, which SMEs value just as highly as price.
Cost will always be part of the funding conversation. But for SMEs, certainty and continuity are o en more important. A competitively priced facility that is withdrawn or reshaped mid-journey can be far more damaging than one that is consistently delivered over time.
The recent exits by large banks highlight a familiar challenge. When economic conditions shi or strategic priorities change, non-core products are o en the first to be reconsidered.
For businesses relying on invoice finance to meet payroll or supplier commitments, that uncertainty can be disruptive and distracting.
Long-term providers take a different view. They focus on supporting businesses through growth, volatility and change, recognising that resilience is built over years, not quarters.. ●
easoned landlords are increasingly viewing mixed-use properties as an a ractive and profitable asset class. Faced with higher interest costs, tighter regulation and sustained pressure on margins, many are finding that mixed-use offers a more flexible and resilient way to diversify portfolios.
This shi is being driven by a combination of tax advantages, strong yield potential and changing market dynamics. For brokers, it is an important trend to understand.
Mixed-use is no longer a niche play; it is becoming a core strategy
for professional landlords seeking value, income stability and long-term growth in a more challenging market.
One of the most significant advantages is the difference in Stamp Duty costs compared to purely residential properties. Mixed-use properties do not a ract the 5% surcharge applied to additional residential properties.
For example, a portfolio landlord buying a residential property valued at £500,000 would pay £40,000 in Stamp Duty, while the equivalent mixed-use property would cost only £14,500. That’s a saving of £25,500, which directly improves return on investment, as well as providing
options for further investment in properties with the remaining funds.
Combined with the ability to achieve higher yields than standard buy-to-let (BTL), mixed-use becomes a powerful diversification tool.
These assets also bring the benefits of diversified risk, with income streams from both commercial and residential markets. Commercial tenants o en sign longer leases, providing predictable income, while residential units offer confidence in quick occupancy. This blend creates resilience, especially valuable in uncertain economic conditions.
As high streets evolve and demand for traditional retail space changes,
TOM WORBEY is senior product manager (lending) at Redwood Bank
landlords have spo ed opportunities to repurpose or convert parts of these properties to meet new market needs, such as flexible workspaces, houses in multiple occupation (HMOs) or additional flats. This adaptability adds long-term growth potential.
The changing face of UK high streets has created a supply of competitively priced mixed-use properties. Declining demand for some retail spaces means landlords can acquire assets at a ractive valuations, o en below the cost of comparable residential properties. For investors seeking value and flexibility, this represents a significant opportunity.
Mixed-use properties are becoming a key part of many landlords’ strategies, but for brokers, the opportunity comes with complexity. It’s not just about knowing why these assets are a ractive, it’s about understanding how lenders decide whether a property qualifies for residential or commercial interest rates.
This decision can significantly impact affordability and the client’s return on investment. Some lenders will treat a mixed-use property as semi-commercial or residential if certain criteria are met, while others will apply full commercial pricing. The challenge? Each lender uses a different yardstick.
Broadly, lenders assess eligibility using one of three methods:
Floorspace ratios
Capital value split
Rental income distribution
Here’s what each approach means in practice and why it ma ers when placing a deal.
Floorspace: When size decides the rate
Lenders who operate via floorspace will o en qualify an asset as semicommercial if more than 50% of the floorspace is residential. This is particularly useful for welllocated mixed-use assets with strong commercial tenancies but larger residential spaces that typically have lower yields.
Illustrative example:
A city-centre property with a retail shop on the ground floor and flats above. Even if the shop earns more rent, the flats take up more space, so the lender treats the property as “mostly residential”. This approach focuses on physical use, not income.
Capital value:
Looking at what’s worth more
Some lenders focus on the value split. If the residential element represents most of the property’s total value, the lender may offer semi-commercial rates, even if the commercial unit earns more rent.
Brokers should confirm with the lender whether they plan to use Vacant Possession valuation of the commercial unit(s) or a Market Value valuation reflective of the lease of the property.
The difference is significant: the former, while reducing the value of the commercial element, may allow a client to qualify for a semicommercial product with more favourable pricing or affordability treatment, whereas having a value reflective of the lease value of the property could potentially increase the capital value weighting of the property to commercial, resulting in higher rates and affordability assessment.
Illustrative example:
Imagine a property in central London with a ground-floor retail unit and three flats above:
Vacant Possession approach: The valuer treats the property as one mixed-use asset. Total valuation might come in at £2.3m, with £1.3m of the value coming from the residential value.
Market Value approach: The
valuer may reflect the value of the commercial lease, resulting in the total value of the property being £2.7m, with £1.4m coming from the commercial value.
It’s important to consider that while there is a £400,000 difference in value, and potential for a larger loan amount available from using the Market Value approach, there are additional ramifications, including whether the lender applies residential-style pricing, or if a higher LTV results in a further price increase. This is why it is important for brokers to clarify the valuation method upfront.
Rental income:
Following the money
Lenders may base decisions on income split. If the residential part generates most of the rent, that’s a win for residential treatment, even if it’s smaller in size.
A property has 40% residential floorspace but earns 55% of its income from the flats upstairs. This o en happens with smaller mixed-use properties or those with HMOs above a shop. Here, the lender focuses on current income, not size or value.
Mixed-use properties offer compelling advantages for landlords, from tax efficiency and higher yields to diversified income streams and longterm flexibility. But when it comes to finance, the same property can be viewed very differently depending on the lender.
Floorspace, capital value and rental income each tell a different story, and each can lead to a different pricing and affordability outcome. For brokers, understanding which metric a lender prioritises is critical. It can be the difference between securing residential-style pricing and falling into a full commercial assessment.
As mixed-use becomes a more prominent part of landlord strategies, brokers who understand lender criteria and valuation approaches will be be er placed to structure deals effectively, manage client expectations and deliver stronger outcomes in an increasingly complex market. ●
The Intermediary speaks with the LHV Bank team, including Ryan Lunn, head of lending operations, Kevin Glover, head of SME product, risk and financial crime, and Sue Gibney, lending manager and team leader, about the bank’s recent growth and how it supports brokers through the application journey
When a new case comes in, where does the process really begin?
Ryan Lunn (RL): The reality is that it very rarely starts with a full submission. More often than not, it begins with a broker checking whether a deal is workable and, just as importantly, whether the timelines are realistic.
From our point of view, that first exchange is about orientation rather than detail, because it sets up how the wider team will support the case as it moves forward in the process.
We are careful about being clear early, because it helps us manage expectations properly and helps brokers do the same with their clients. When that foundation is in place, the case tends to run with less friction later on.
do you manage momentum when circumstances change mid-process?
Kevin Glover (KG): Change is part of everyday [small to medium-sized enterprise (SME)] lending, and it affects everyone involved in a deal. It can come from clients, from documentation, or from what happens once third parties get involved. The question is not whether change happens, but how it is handled when it does, and whether the response improves decision-making or distorts it.
We are disciplined about not creating unnecessary noise around a case and staying focused on what actually improves the outcome for everyone involved.
RL: In practical terms, that distinction is really important once a case is moving. If teams feel
that speed is the only measure of progress, judgement tends to suffer, and the case becomes harder to control.
When it is clear that considered decisions are valued, momentum becomes more consistent, and that benefits brokers because updates are clearer and the process feels more dependable for them. We are also careful about where time and effort are spent, because there is real value in focusing on deals that are likely to complete.
KG: 2025 was an extremely positive year for us and strong performance brings higher expectations, which is understandable. What matters is how that pressure shows up in day-to-day calls, because brokers feel it when decision-making becomes more inconsistent.
My role is to keep product risk and operational reality aligned, so the process does what it says it will do. Credibility is hard to build and easy to lose, so when those elements pull together, decisions are easier to make, easier to explain and easier for the team to stand behind.
RL: When leadership is clear about priorities and acknowledges pressure openly, people stop second-guessing themselves and start making clearer decisions. That clarity feeds through into how brokers experience the case.
It also helps us manage capacity in a responsible way, so service remains strong for the deals we are progressing. Ultimately, it comes back to being reliable, and brokers value that more than anything.
Where does case structuring have the biggest impact?
Sue Gibney (SG): If I am honest, structure is where most deals either hold firm or start to wobble. A structure that reflects how a borrower actually runs their business gives the whole team something solid to work with and helps keep the case stable when details move.
Those conversations are not always quick, and they can involve challenging assumptions, but that is the point of doing it properly. We are always trying to arrive at a structure that makes sense in the real world, not just on paper.
What typically causes friction later in the process?
SG: In terms of avoiding friction, early visibility changes the tone of a case for everyone. It allows people to plan rather than react. Even partial information helps, because it gives us something to work with and gives the broker something to manage. When there is some warning, conversations tend to stay constructive, and the structure can be adjusted without everything feeling urgent. That is a big part of how we protect results.
How has the broker experience changed as your team has grown?
RL: Consistency has become a much bigger part of the experience. Brokers want to feel that whoever
they speak to understands the background of the case, not just the latest update, and growth in the team supports that. It also improves coverage across regions and deal types, which matters when brokers need fast, practical answers. When there is depth across lending and operations, cases are less likely to loop back.
KG: It has also changed how we work together day-to-day. With workloads spread more evenly, there is more time to explain context rather than just outcomes, and that improves communication with brokers. It also makes internal hand-offs more effective, because information is captured and shared properly rather than held in someone’s head. That is how service stays consistent, even when volumes are strong.
What practical advice would you give brokers when working with LHV Bank?
SG: When a deal is live, sharing context early makes a real difference for the whole team. Deals rarely stand still, and small changes can have wider effects if they come late, so it helps if we understand what is driving a change as soon as possible.
That allows us to support the case properly and keep communication clear. From a broker’s point of view, it leads to clearer updates and fewer difficult conversations towards the end. More importantly, it creates a process that feels consistent rather than reactive, which is what most brokers are looking for when timelines tighten. ●
Anew year inevitably brings with it a lot of talk about fresh starts, and resolutions to do things in a different – hopefully more efficient – way over the coming 12 months.
In my view, a clear priority for all advisers in 2026 should be to ensure they are doing more than paying lip service to later life lending products.
Now is the time to proactively embrace this area of the market, rather than wait for the prompting of the regulator.
Looking in the mirror is not always a comfortable experience a er the festive and New Year period, but it’s important to give an honest appraisal before se ing off on a healthier path. It’s not about guilt, but rather spo ing opportunities for improvement.
That’s as true from a professional perspective as it is from a personal one. Now is the time for advisers to consider – honestly – whether they are offering a complete service to their older clients, whether they are delivering the full range of options those clients would benefit from.
Traditional remortgages may work for some, but undoubtedly there will be plenty of other clients over the age of 55 who might benefit from more specialist options, from retirement interest-only (RIOs) to lifetime mortgages.
If that look in the mirror uncovers an uncomfortable truth, then now is the time to do something about it, whether that’s upskilling or working with a specialist partner.
Specialists need to look carefully at their own practices, too, ensuring they are including the full range of options when considering next steps for clients. Are they giving enough prominence to products that include the ability to make full or
partial interest repayments, or those that include no early repayment charges (ERCs) and can provide more flexibility for customers down the line, even if the initial rate may be slightly higher?
This market has seen huge innovation, and we need all advisers –whether specialists or mainstream – to have comprehensive conversations with customers make the most of the broad spectrum of solutions available.
I’d strongly argue this is the time for advisers to be proactive about adding specialist later life lending products to their suite of options, rather than waiting for encouragement from the regulator.
The Financial Conduct Authority’s (FCA) Discussion Paper has, appropriately enough, prompted a lot of discussion within the mortgage market about where the industry needs to up its game and deliver for all clients.
This has been further supported by the publication of the regulator’s Mortgage Rule Review Feedback Statement (FS25/6) which pinpoints later life lending as a priority, including a focus on improving the advice offered to older borrowers.
One area crying out for reform, and identified by the FCA, is the divide between mainstream mortgage advice and later life lending advice.
The idea advice should be siloed in this way is completely outdated and must be removed. Alongside this, there is an evident need for a single qualification structure, which will provide advisers with the foundation they need for addressing all the later life needs of their clients, irrespective of the eventual path they opt for.
Just as we should aspire to an environment where advisers are offering a holistic approach to their clients, I’d hope the regulator will see the need to tackle these two areas
DAVE HARRIS is CEO at more2life
collectively rather than consecutively.
If it does, 2026 may prove to be an incredibly significant one for older clients and the advisers they rely on.
However, there is li le benefit to be had from waiting for the final pronouncements from the regulator. The opportunity is there to be grasped in the here and now, not 12 months down the line. We are already seeing it from some networks and advice firms, but in my view, still not enough.
The coming year is likely to see yet more product innovation, as providers build even more options that provide flexibility over repayments, charges and the ability to secure lower interest rates by commi ing to regular contributions.
These innovations are all designed to open up later life lending to a much wider audience, tailored to meet the specific needs of individual homeowners as a natural step from mainstream solutions to those for older borrowers.
Combined with the improved integration of technology, which is helping advisers keep on top of cases, prove compliance, and deliver faster decisions, the later life lending market has never been be er positioned to support older clients.
The worst thing advisers can do is sit back and wait for the regulator to tell them what to do.
That approach delivers a poorer outcome for clients, while leaving advisers at risk from rivals who have recognised the opportunities from embracing later life lending.
The time for change is now. I hope that when 2027 comes around, and advisers once more look in the mirror, they can honestly say they are delivering the full range of options to their older clients. ●
Arguably, lifetime mortgages place the valuation process under greater scrutiny than most areas of the residential market. Shi s in demand over the last three to five years have only sharpened that focus.
The market disruption that followed the 2022 mini-Budget highlighted this clearly. Rapid rate rises reduced affordability and tightened loan-tovalue (LTV) limits, slowing activity across the sector.
While volumes fell for a period, the underlying need to access housing wealth did not change. Pension income remained under pressure; household costs rose and property continued to hold a growing share of personal wealth. As rates eased, demand returned, bringing valuations back to the centre of lending decisions.
Recent UK Finance data shows 39,950 new loans advanced to older borrowers in Q3, up 18.4% year-onyear. The value of this lending was £6.5bn, up 24.7% compared with the same quarter a year previously. Within this, there were 6,040 new lifetime mortgages advanced in Q3 2025, a year-on-year increase of 3.4%.
Managing expectations
Later life lending now represents close to 8% of all residential loans and as volumes grow, the consistency and accuracy of valuations become even more important.
The valuation process itself is familiar one. Surveyors rely on the comparable method, using recent sales, local market knowledge and clear evidence to reach a fair market value.
Access to historic sold data, floor plans and images allows surveyors
to test assumptions and apply adjustments where properties differ in size, condition or layout. What changes in later life lending is the weight given to certain risks.
Unlike mainstream lending, where risk reduces over time, lifetime mortgages place the property at the heart of the lender’s exposure for the full term of the loan. Condition, maintenance and saleability therefore take on greater significance.
Issues such as roof condition, damp, poor upkeep, cladding concerns or restrictive lease terms are assessed not just for their current impact, but for how they may affect a sale many years in the future. Expectation management also plays a key role in valuation outcomes. Many later life borrowers have owned their homes for decades, may have limited insight into current market values and consequently may have unrealistic expectations about the value of their much-loved family home.
Online estimates o en overstate value or fail to reflect local conditions. When the reported value differs from expectation, it can feel like a reduction rather than a fair assessment. Early guidance from advisers, grounded in sold price evidence, can help align expectations.
Our valuers also need to be empathic and suitably sensitive in their approach when visiting the homes of later life borrowers, especially as they will be one of potentially only a few people to visit the property during the lending process. Therefore, our valuers also need to be mindful of any potential customer vulnerabilities and ensure that any related concerns are also reported to our clients in this respect under the relevant terms of our contractual obligations, coupled with the lender’s guidance notes.
ANDREW PETERS is associate director of technical services at Countrywide Surveying Services
Regional differences further shape valuation considerations. In London, the South East and the South West, higher property values o en support larger advances but also bring greater scrutiny due to higher exposure.
In many Northern regions, lower average values mean tighter margins, making accuracy even more important.
Capacity and expertise also affect valuation quality. High-demand areas can stretch surveyor availability, and later life lending requires an understanding of specific lender criteria and long-term risk. Training new surveyors takes time, and experienced professionals still need support to apply guidance consistently across complex cases. Therefore ongoing investment in skills and oversight remains essentia.
Looking ahead, lifetime mortgage demand is expected to continue its gradual increase. As more people reach retirement with wealth tied up in property, valuations will play an even greater role in protecting both customer outcomes and lender security.
For lenders, the priority is clear. Strong valuation practice, consistent standards and early alignment of expectations are critical. When valuations are robust, they provide the confidence needed to support sustainable growth in the later life market and ensure the homes securing these loans remain sound for the long term. ●
There are many factors involved in the rise of second charge mortgages. Apart from the ebbing of negative sentiments towards the channel which has been down to a concerted campaign to educate the intermediary market over the past few years, there has been a series of changes that are having a positive effect on how brokers perceive the second charge channel.
In 2025, more than 1.8 million fixed rate mortgages matured by the end of the year. Remortgages have therefore inevitably been a major driver for new business during the year. However, the uncertainties caused by the global financial situation have also meant that many people have looked at spending money on their existing properties rather than moving house to deal with expanding families and other requirements.
The need for money to finance home improvements and also funds to consolidate loans and other credit has meant that there has been a greater focus on other sources than straight remortgaging. Second charge funding has become a serious challenger as a flexible source of finance that does not disturb a client’s existing first charge mortgage.
People with cheap fixed rate mortgages should be more reluctant to remortgage out of a cheap fixed rate into a more expensive alternative, just to raise capital without exploring the alternative of a second charge mortgage, with the help of their financial adviser.
This is a crucial part of the transaction. Every adviser should be able to assess a client’s needs without a bias towards either remortgaging or a second charge option.
Consumer Duty puts the onus squarely on advisers to consider every option for their clients before making a recommendation. Do clients get to
see all of the options set out in front of them to understand why the adviser is advising a certain route?
In the real world, it is unlikely that many clients get to see how advisers reach the decision as to what to recommend. They are usually just given the recommendation without any a empt to show alternatives or how the recommendation was arrived at.
There is nothing particularly wrong with that approach provided the adviser can explain – if asked – whether there are alternative approaches, what they are and why they have been discounted from the final recommendation.
Personally, I would like to see brokers offering their clients all the alternatives first and then explaining why they have decided on their choice of recommendation. Of course, this isn’t a perfect world and while I can wish all I want, many brokers can claim with some justification that there is just not enough time to enter into long explanations as to the merits of each alternative. A er all, the service offered by advisers is predicated on the assumption that they have already done the necessary research to reach a recommendation, so why should they have to explain how they arrived at their conclusion?
Amid all the negative press which continues to swirl around, including regional conflicts such as Ukraine where a resolution still seems a long way away as I write, the poor state of the world economy and closer to home the almost daily negative news about the state of the country, I still feel that there is much to look forward to in 2026, especially in the second charge sector.
2025 ended on a high with a circa 20%-plus increase in new business volumes over the previous year and from my experience of working in
LAURA THOMAS is regional sales manager at Equi nance
the sector over the past 10 years, the momentum that has been building up over that time is now undeniable.
Changes in regulatory responsibility, smarter product design and interest rates which have moved closer than ever to their first charge sibling in 2025, have all had a positive effect on the increase in second charge lending.
For me though, the main driver behind the inexorable rise in new second charge business has been about the wider acceptance of second charge among the intermediary base. Ongoing education by lenders and packagers has led to wider awareness and consequently greater confidence in opting for a second charge option to the whole issue of capital raising.
As we look forward to a new year, I predict that second charge lending will continue to be one of the winners for intermediaries and their clients. ●
Few areas of lending have evolved quite as significantly, or been quite as misunderstood, as second charge loans. Having worked in the second charge market for almost 43 years, I’ve seen it move from an industry best described as the Wild West, with far too many cowboys, to a regulated mainstream product that all mortgage brokers should have in their locker.
When I first started working in this market, it was dominated by fewer than 100 brokers nationwide. Both national and local newspapers carried multiple advertisements with headings such as “Fast Loans”, usually including both interest rates and the equivalent weekly repayments.
In 1985, a change to the Consumer Credit Act introduced a 17-day cooling-off period for loans to reduce high-pressure sales tactics. However, this did nothing to reduce the size of the market, with the biggest brokers completing over 250 loans a day in 1987/88.
When the very dodgy brokers and lenders bent the rules, the Office of Fair Trading would react like a sedated tortoise. Second charge lenders eventually decided that selfregulation was the only way forward and established the Finance Industry Standards Association (FISA), run by an ex-broker with former police detectives as his deputies. FISA did a good job of eliminating many of the remaining cowboys, o en by carrying out what can only be described as a police raid, but it was closed in 2009 when its funding from lenders dried up.
One excellent outcome for clients was the FISA booklet, issued to all borrowers with the initial loan
documentation, explaining every aspect of the borrowing commitment. It is something the Finance & Leasing Association (FLA) should revisit, as it was of great benefit to customers, particularly as it was wri en in plain English rather than by someone who had swallowed a thesaurus.
The market suffered from Rule of 78 se lement penalties (Google it if you don’t know) and lump-sum payment protection insurance sold to people who did not need it, but it had cleaned up its act well before second charges fell under FCA control in 2016.
In the lead-up to 2008, second charge loans were everywhere: The internet, the most prominent page in every Yellow Pages, sponsored shirts at Premier League clubs, and adverts in every break on every TV channel. One broker even had their own Sky channel. I once stopped at the services on the M6 and found myself staring at a second charge advert above the urinal. Public awareness was at its maximum. So, where are we now? The second charge market is growing, with the FLA reporting £2.045bn for the 12 months to October 2025. However, this is still only around a third of its size prior to the 2008 crash.
Cooling-off periods and single premium PPI are distant memories, and Rule of 78 is remembered only by those of us old enough to have lived through it. I haven’t seen a press advertisement in over 20 years, and most brokers looking to arrange volume in the second charge market are chasing the same networks and directly authorised (DA) brokers as their competitors. This approach does not expand the market for what is now a mainstream product.
Very few firms are trying to a ract customers directly, and even fewer are doing so legally. If you have Facebook
TONY SUTTON is managing director at Specialist Hub
look at some of the second charge adverts and you’ll quickly realise that many of those brokers haven’t read the rules on financial promotions.
The market is ripe for expansion – but it must be done properly. The treatment of vulnerable customers has improved massively, although there is still room for improvement. Technology is now used extensively, with new enquiries submi ed electronically and approved within seconds.
The rise of dynamic pricing has been a major benefit, with interest rates determined by a range of behindthe-scenes factors. As a result, we are o en seeing rates significantly lower than those offered by lenders with published pricing. In most cases, we no longer require a physical valuation as automated valuation models (AVMs) have removed the need for expensive surveyor visits.
There is also no need for solicitors to be involved, asking da questions and delaying ma ers. Second charge lenders have always had in-house legal procedures, enabling them to complete loans on the day signed agreements are received.
The responsibility for all brokers offering second charges is simple: do it properly. Be fully compliant when generating enquiries, ensure borrowers understand the bad as well as the good, treat them fairly, and comply with the rules – especially Consumer Duty.
If you don’t, you could be the reason for the FCA’s next issue with second charges – and the FCA is not a sedated tortoise. ●
The Government’s recently published Financial Inclusion Strategy has brought a welcome focus to how we, collectively, can improve financial inclusion for individuals and communities who have historically been underserved.
At Paymentshield, experience accessibility is a core principle embedded into our digital strategy. It shapes how we design, build and deliver our products, services, and digital experiences.
Our aim has been two-fold: first, ensuring our products cater to a wide range of people and support financial resilience; and second, making sure the ways people engage with those products – online, in documentation, or through customer service – are accessible and user-friendly.
Improving accessibility doesn’t only benefit customers – it also supports advisers, many of whom have their own accessibility needs and all of whom want confidence that the products they recommend offer an inclusive experience.
Financial resilience through insurance is a key focus within the Government’s strategy. It highlights the persistent protection gap among tenants – a challenge we have long been commi ed to addressing – and flags income protection as another overlooked area.
Earlier this year, we enhanced our mortgage protection product and made it available again to new customers, reaffirming our commitment to supporting people when their income comes under pressure.
In the new year, we’ll also be conducting research to be er understand the extent of income vulnerability among consumers, helping advisers more easily identify
and support clients who may be exposed without realising it.
Alongside this, we’ve been strengthening our home insurance panel. A panel with breadth and depth is essential for serving a wider and more diverse pool of customers, particularly those whose risk profiles fall outside traditional parameters.
Of course, designing inclusive products is only half the equation. A central part of financial inclusion is ensuring that when people engage with those products – at the point of sale, when adjusting a policy, or when making a claim – the experience is accessible, intuitive, and supportive. This is where experience design plays a crucial role.
Over the past year, we’ve introduced significant improvements across our digital estate, spanning customerfacing platforms and our Adviser Hub. Our goal has been clear: to put human-centred design at the forefront and remove friction that could prevent someone from understanding, buying, or managing their insurance.
Accessibility enhancements include both technical and content improvements. We’ve refined our back-end code and implemented Accessible Rich Internet Applications (AIRA) landmarks to improve screenreader compatibility, helping users navigate pages more easily. We’ve also adjusted colours and contrast ratios across our estate to improve clarity for users with visual impairments or cognitive processing differences.
We’ve streamlined our online forms by reducing the number of fields and removing unnecessary steps, making journeys quicker, clearer, and less cognitively demanding. At the same time, improved text-link visibility ensures key actions and navigation routes are easy to spot.
We have also rolled out the Crownpeak accessibility platform
KARL ROWLANDS is UX manager at Paymentshield
across our customer-facing website, giving users a suite of personalisation options, and this capability will soon extend across the Adviser Hub.
Finally, we have trained Plain Numbers Practitioners within the business to help make key policy information easier for our customers to understand and reduce the risk of misinterpretation at moments when clarity is essential.
These changes may sound technical, but their impact is human. They ensure people with a wide variety of needs can navigate our products with confidence.
While advisers may not always have considered accessibility when assessing a provider’s service, it is increasingly a differentiator.
According to Scope, more than 16 million disabled people live in the UK, and many face challenges navigating digital journeys. Ensuring clients have access to accessible services isn’t simply best practice, it’s essential.
The improvements we’re making mean advisers can be confident that they’re recommending a provider commi ed to serving every customer fairly and inclusively.
For advisers with accessibility needs themselves, our improved design and assistive tools make it easier to work efficiently and without barriers.
As we head into 2026, we’ll continue listening, testing, improving, and building on the foundations we’ve laid, so that we set the standard for accessibility and insurance.
Our goal remains clear: to ensure that every adviser and every customer can access the protection they need in a way that feels intuitive, supportive, and fair for all. ●
Our homes are generally our largest financial investment. Winter weather in the UK is unpredictable. One week may bring snow and freezing temperatures, the next heavy rain or high winds.
In fact, this New Year we may see snow, which could increase the risk of property damage if homes are not properly protected. Storms and cold snaps can lead to costly damage that could disrupt homeowners’ lives.
This is why referring your clients to Safe and Secure Home Insurance is essential. Our expertise ensures they have the right cover in place to anticipate and respond to weather risks.
Many homeowners underestimate how winter weather can affect their property. Burst pipes, roof damage, blocked gu ers and storm-related issues are common.
At Safe and Secure, we provide clients with expert guidance
on policies that cover risks comprehensively. This goes beyond simple claims. It is about preparing for what could happen, ensuring they have protection tailored to their property type, location and personal circumstances.
As we move into 2026, there will be an inevitable increase in home purchases from February onwards, many of which will be first-time buyers. These clients o en need extra guidance to understand their responsibilities and the importance of adequate insurance. By explaining home insurance, we empower these new homeowners to make informed decisions. Referring first-time buyers to us ensures they start their homeownership journey with confidence, protecting both their property and their financial investment.
Homeowners may not know the difference between standard and specialist coverage. Safe and Secure helps them understand the scope of
STEPHANIE DUNKLEY is development director at Safe&Secure
protection, including emergency repair services and what is covered versus excluded. We also ensure clients are aware of excesses, claim limits and the support available through insurance-approved contractors.
Your clients trust you with their mortgage decisions. By connecting them with Safe and Secure, you provide added value through expert home insurance advice.
Tailored policies and proactive support reduce the likelihood of claims, safeguard property value and provide peace of mind for your clients.
This strengthens your professional relationship, enhances your credibility and ensures a smoother mortgage and remortgaging service over the years for you and your clients.
Winter can present sudden challenges. Safe and Secure Home Insurance acts as a partner for both brokers and homeowners, delivering rapid response and expert guidance when clients need it most.
From emergency repairs to navigating claims efficiently, we ensure clients feel supported every step of the way. By referring your clients to a home insurance broker like Safe and Secure, you give them access to high-quality protection, professional support and peace of mind. ●
If the UK mortgage and insurance sector has a longrunning paradox, it is that we live in a country where millions of households rely on debt to sustain their biggest commitments yet a significant proportion remain financially vulnerable should illness, injury or loss of income strike.
The Association of Mortgage Intermediaries’ (AMI) latest ‘Protection Viewpoint’ highlighted that gap. Despite high consumer trust in advisers, protection uptake remains stubbornly low.
In a world shaped by data, automation and artificial intelligence (AI) driven personalisation, it is tempting to believe that technology alone will close that gap. But the reality is more human.
Protection is not simply a product sale but an emotionally loaded conversation about resilience and the unpredictability of life. AMI’s analysis confirms what advisers see daily: the protection gap persists, in part, not because consumers believe insurers will not pay out – claims statistics overwhelmingly show they do – but because people struggle to internalise their own vulnerability. In behavioural terms, the protection gap is driven by optimism bias – ‘it won’t happen to me’ – present bias – ‘I’ll sort it later’ – and the simple discomfort of imagining worst-case scenarios.
AI can identify the signals of vulnerability and protection need, but it cannot replace the human-centred conversations required to dismantle these defences.
I think it is a fair bet that a customer never buys income protection because a chatbot deemed them a ‘high-risk persona’. They buy it because an adviser has helped them visualise
what would actually happen if income stopped, and how small, structured payment commitments today can safeguard much larger ones tomorrow.
Protection discussions require empathy and the ability to translate financial risk into personal relevance without triggering fear.
A good adviser listens for the subtext. The client who says, “I’m healthy; I don’t need cover,” might actually be saying, “I’m worried about cost.” Borrowers who dismiss income protection may be conveniently ignoring the pressures on income brought about by the rising cost of living.
AMI’s report stresses that advisers feel more supported than ever by providers, but many still lack confidence in navigating emotionally complex conversations. If the industry wants to shi the dial, investing in adviser training around behavioural coaching and emotional quotient (EQ) led advice may prove as important as product innovation.
One of the strongest messages within AMI’s publication is that life does not stand still. Mortgages shi . Families grow. Jobs change. Financial resilience rises or falls with each new responsibility.
Too o en, protection is treated as a single-point transaction rather than an evolving structure that should flex with the customer’s life. This is where advisers who already sell protection need be er tools.
The role is not simply to ‘sell’ but to steward clients through evolving commitments helping them revisit cover levels, understand offse ing risks, and see protection as a long-
CRAIG HALL is director, strategic prtnerships, nancial services at LSL Property Services
term financial hygiene measure. While advisers remain the frontline of consumer understanding, closing the protection gap cannot fall on them alone. AMI has been vocal about the need for wider public education that demystifies protection and provides clearer signposting around support.
There is a role for Government here, particularly in articulating the limitations of state safety nets. Many consumers still assume that statutory sick pay, employer benefits or the welfare system would carry them through extended illness or loss of income. The reality is far more precarious.
Year a er year, UK insurers pay out billions in life, Critical Illness and Income Protection claims. Yet this message rarely cuts through the noise of consumer mistrust or misunderstanding.
If the industry wants to build belief, it must communicate in human terms: real stories, real outcomes, anonymised but relatable. Data changes minds; stories change behaviour.
As AMI’s Protection Viewpoint makes clear, advisers who are confident and emotionally a uned can transform consumer understanding of risk. But they cannot do it alone. A coordinated effort that includes government signalling, industry education, provider transparency and adviser empowerment will be essential.
Protection works. Claims statistics prove it. The task now is to ensure more households understand that before life forces them to learn it the hard way. ●
We were recently able to announce an important partnership with Yorkshire Building Society. The society has taken a significant step forward in its digital transformation journey with the adoption of our Lender Hub platform – a move that enables the society to integrate real-time property and energy efficiency data to enable instantaneous, risk-adjusted decisioning.
The partnership marks a notable moment not only for the Yorkshire Building Society, but for the wider market, as lenders increasingly turn to richer datasets and smarter workflow tools to improve outcomes in mortgage lending.
For a sector navigating complex regulatory demands, rising climaterisk scrutiny, and shi ing customer expectations, the ability to access trustworthy property intelligence at pace is becoming essential. Yorkshire Building Society’s decision to expand its digital capabilities with Cotality is indicative of a broader industry shi .
For Yorkshire Building Society, the partnership aligns directly with its transformation strategy. It has been steadily modernising its mortgage processes in recent years, with a sustained focus on improving member experience while strengthening overall risk management.
Incorporating EPC data into mainstream decisioning is the next step in this journey, not the end.
The deal will deliver both efficiency and sustainability, but also plays to broader lender priorities. As intermediaries will know, mortgage approvals are increasingly influenced not just by valuation accuracy but by the growing need to understand how resilient a property may be to tightening environmental standards.
Lenders are preparing for future
regulatory changes around energy performance, while homebuyers and remortgagers increasingly want clarity on energy-efficiency costs. Building societies like the Yorkshire Building Society, with their memberled ethos and deep regional ties, are particularly a uned to this shi .
While the mortgage market has long used data services, their role has shi ed from passive analytics to active enablers of the customer journey. With the integration of Cotality’s lender hub services, Yorkshire Building Society gains access to a system that blends advanced modelling techniques with real-world market data to produce valuations in seconds.
These capabilities ma er. Faster valuation outcomes mean quicker time to offer, fewer manual interventions, and reduced reliance on full physical inspections – particularly in lower-risk scenarios. Data services will also produce huge efficiencies for all in the value chain when it comes to managing and handling post valuation queries. At a time when speed remains a competitive differentiator for lenders and a service expectation among brokers, Data offers an important lever for balancing precision with efficiency.
Data services are not only about speed. They support stronger risk governance. By delivering valuation estimates, comparables, confidence scores and property a ributes within a unified workflow, lenders can calibrate decisions with consistency.
The integration of EPC information and more granular energy-efficiency indicators may ultimately prove just as valuable. Lenders across the UK are preparing for a mortgage landscape where climate-risk assessments and energy-performance transparency become the norm. Even with shi ing Government timelines, the direction
MARK BLACKWELL is COO at Cotality
of travel is unambiguous: be er data, clearer reporting, and increasing regulatory interest in heat demand, insulation levels and carbon-reduction pathways.
For brokers, this trend is already filtering into conversations with landlords, homeowners and remortgagers seeking to understand what their properties’ EPC profiles mean for borrowing. For lenders, the ability to view energy performance characteristics at the point of decisioning brings several advantages from long-term risk modelling and capital planning to supporting customers with retrofit pathways.
For brokers working with Yorkshire Building Society, the announcement signals a further enhancement of the society’s service proposition. Faster valuations mean quicker movement from application to offer which is a benefit that is particularly relevant in competitive purchase chains or where customers need clarity on borrowing capacity at speed.
It also reflects a wider pa ern intermediaries should watch closely: the increasing fusion of valuation intelligence, energy data and risk analytics within mainstream mortgage processing.
As lenders adopt richer datasets, brokers may increasingly encounter more nuanced underwriting questions around EPC status, retrofit potential, property comparables and automated confidence scores. Being fluent in these areas will become a differentiator in its own right.
Ultimately, the partnership between Yorkshire Building Society and Cotality underscores a shi in how lenders think about property risk, sustainability and operational performance. ●
For years, the mortgage industry has been told that technology will transform everything: faster decisions, automated workflows, seamless customer journeys, instant certainty.
Technology is undeniably reshaping parts of the market – from income verification to automated valuation models (AVMs), digital ID, and open property data – but the o en unspoken truth is that digital tools cannot deliver their full potential when the underlying process remains fundamentally fragmented.
In the UK, the house purchase journey is a patchwork of regulated and non-regulated participants.
Each holds a slice of the workflow, each carries a degree of liability, and each is governed by its own rules, systems and commercial incentives.
We have digitised documents, automated tasks and improved data quality, but we have seldom stepped back to ask the more radical and perhaps necessary question which is are we using technology to improve the process or to digitise its flaws?
Mortgage processing remains slow not because we lack innovative tools or technology but because the sequence, responsibilities and regulatory interfaces were designed for a world that has moved on. The current value chain still relies on asynchronous hand-offs and multiple points of duplication. Information rarely flows freely, and when it does, it o en arrives too late.
Open property data, for example, has the potential to transform risk assessment, improve underwriting accuracy and shorten time to offer. Yet even with the richest data available, if lenders, surveyors and conveyancers
are engaged late in the journey a er transaction pressures have already mounted delays will likely persist.
One of the most intriguing lessons from global housing markets is that transaction efficiency is rarely the product of superior technology alone. Scotland, Northern Europe and Australia demonstrate that structural design ma ers just as much as digital innovation. While none offer a panacea, they all shine a light on how some of what we do may be improved.
Scotland offers a model centred around early transparency and front-loaded information. The Home Report provides a reliable valuation, condition survey and EPC upfront, reducing post-offer surprises. The legally binding nature of the offer also limits gazumping, fall-throughs and uncertainty. Technology enhances these steps, but it is the process design that creates predictability.
Nordic markets emphasise trust, simplicity and centralised information. Buyers and sellers operate within clear frameworks, supported by comprehensive property registers and standardised documentation.
Australia provides an example of highly structured transaction timelines and greater symmetry of information between parties. Digital tooling supports the process, but it does not define it. Instead, certainty is built into the legal and procedural architecture of buying a home.
These markets remind us that digital innovation is most effective when embedded in a system that minimises friction, clarifies responsibility and reduces perceived liability. The UK’s fragmented ecosystem, by contrast, amplifies
JERRY MULLE is UK managing director at Ohpen
liability concerns at every turn.
The growing availability of open property data such as energy performance information, planning history, digital deeds, price indices, flood risk metrics and more creates an extraordinary opportunity. But data alone cannot fix a system where stakeholders operate in silos and o en duplicate each other’s efforts.
One of the most consistent barriers to innovation is perceived liability. Even when data and technology reduce uncertainty, participants still act as though the risks are unchanged.
Surveyors may be cautious about AVMs despite overwhelming accuracy data. Conveyancers may request additional reports even when core information is already available. Lenders may resist early binding decisions because of concerns about missing data or property surprises.
A re-engineered process would redistribute these liabilities more proportionately, supported by transparent standards and shared confidence in the quality of data. Technology can help, but only if the system accepts what the technology provides.
The future of mortgage processing should not be defined by technology but enabled by it. The real transformation will come when the industry resists the urge to replicate analogue workflows in digital form. If we simply digitise a fragmented process, we will get a faster version of the same frustrations.
The opportunity is clear: technology can improve speed; redesigned processes can transform outcomes. Both are necessary. Only together will they deliver the mortgage journey that the modern market seeks. ●
In the next few years, the most successful mortgage brokers won’t be human or machine, but a blend of both. Artificial intelligence (AI) is the main driver behind this change, bringing with it a wealth of benefits for professionals in the industry and their clients.
The ‘90/10 Rule’ is o en used in the world of tech and automation to highlight a dividing line between what we can reliably automate and what still requires human insight. For example, in generative AI circles, some argue that the first 90% of progress is relatively straightforward, while the final 10% – the edge cases, nuance and oversight – is much harder to complete.
In the world of mortgage brokering, this rule suggests that 90% of routine tasks – such as data collection, document handling, rule-based checks, and underwriting criteria – can and will be automated. The remaining 10% requires human judgement, negotiation, persuasion, risk tolerance, and empathy. This puts the modern broker in a unique position where they can benefit from leveraging AI in their work.
Will AI replace brokers?
Several emerging trends point to 2026 as the year when fully supported AI is on the way for the mortgage industry.
Some key motivators for this come from new technology, which includes: Rapid AI adoption in mortgage workflows: Automated underwriting, risk forecasting, document parsing, fraud checks, and affordability assessments are already mainstream or emerging.
Generative AI and large-language models (LLMs): Newer AI components – chat agents, natural language summarisation and
decision support – are bringing Open Banking and Financial Conduct Authority (FCA) compliant automation into areas previously considered so , such as client Q&A or scenario explanation.
Competitive pressure: Brokers who cling to manual workflows will suffer in speed, accuracy, and profitability when compared to brokers using AI. The risk for brokers who don’t adapt could result in them being le behind.
Pu ing all of this together, it is quite likely that we will find hybrid human and AI brokers by 2026. Most industry experts are predicting that this is more than just feasible, but inevitable for high performers in the industry.
What can be automated?
90% is a big chunk of a broker's day-today activity, so it helps to know exactly where AI will be ready to step in.
Below are some of the main functions that AI is already taking on, or soon will, in the broker’s process: Document intake and verification: AI systems can scan PDFs, extract income, assets, bank statements, tax returns, categorise deposits, and flag discrepancies with ease.
Automated underwriting and scenario simulation: AI models can run multiple scenarios across lenders’ guidelines instantly, identify possible risks and highlight the best paths forward for clients. Fraud checks, AML flagging and risk scoring: Machine learning models can flag suspicious pa erns, credit concerns, inconsistent data, or overleveraged profiles.
Client relationship management and lead handling: AI can profile leads, automate drip campaigns, triage high-value prospects, and even suggest marketing strategies.
IFTHIKAR MOHAMED is director at WIS Group and co-founder at MortgagX
AI chat assistants and client portals: Natural language agents can answer common borrower questions, track status, request missing documents, and maintain engagement around the clock.
Regulatory compliance and auditing: AI can also check disclosures, flag missing or contradictory forms, cross-verify with rulesets, and generate audit trails.
Even in a firm that leans into AI, there are certain areas and capabilities where human value is irreplaceable. There will always be room for human involvement, especially for tailored services like brokerage and mortgage advice. Some of the main areas where brokers will continue to outshine AI include:
Advisory and negotiation: Understanding life goals, advising on trade-offs (rate vs term, cashout, refinancing), cra ing bespoke structures, and pushing back on lenders.
Relationship and trust: Building deep rapport, handling emotion, explaining nuance, defusing stress, and building confidence are things
safely reserved for human brokers.
Edge cases, exceptions and appeals: When a file falls outside program boundaries (such as bankruptcy, non-standard income or financial gaps), human judgement must steer the path.
Strategic oversight, QA and governance: Humans cra risk limits, check model biases, audit AI decisions, and intervene when necessary.
Business development and partnerships: Creating alliances, negotiating lender access, branding, and high-level growth strategy remain human domains.
Transitioning to AI isn’t always an easy sale, especially with brokers who have spent decades honing their approach to the industry. Below are some of the common challenges of
transitioning to AI in the mortgage industry:
Cultural resistance: Many brokers see technology as a threat, not an enabler. This can result in poor uptake of new, useful technology like AI.
So ware compatibility and integration issues: Certain legacy systems will struggle to integrate cleanly with certain AI modules. Data quality and trust: AI works only as well as the data it’s fed. This means poor document quality or silos may limit performance. Skills and training gaps among advisers: Staff must learn to trust, audit, and oversee AI outputs.
To succeed, brokers must start modestly. This might mean automating a few low-risk workflows, validating performance, training staff to collaborate with AI, and building
governance scaffolding to work with the FCA guidelines. Over time, you can scale from the bo om up.
The 90/10 Rule gives us an interesting way to view AI in the mortgage industry. It proposes that in the near future, the best mortgage brokers won’t be fully human or fully AI, but smart hybrids. By 2026, the bulk of the work – document handling, scenario simulation and lead scoring –will be handled by AI. The remaining human effort will be reserved for judgement, relationships, negotiation, and oversight.
Brokers who understand this shi , adopt early, and work with AI will vastly outperform those clinging to manual models. The future of the mortgage industry is part-AI, and by 2026, the brokers who aren’t part-AI will struggle to compete. ●
Consumers are used to algorithms that perfectly curate every part of their lives.
Netflix instantly greets viewers with personalised recommendations based on the movies and shows they’ve watched before. Spotify creates custom playlists for listeners’ different moods and moments throughout the day. The list goes on.
Banks and financial institutions hear these comparisons all too o en, but they reflect a broader shi : personalisation has become the baseline across all digital experiences. Banking services have already made substantial digital progress.
Today’s banking customers are looking for guidance on reaching their financial goals. Instead, many are still receiving static product offerings.
This personalisation gap isn’t due to a lack of awareness or trying on banks’ part - it’s about execution. The manpower required to roll out personalised banking services at scale, both from a technological and advisory perspective, has historically made it economically infeasible – and nearly impossible – for many banks.
With AI, banks have an opportunity to deliver the level of personalisation they want, and that consumers now expect. But it’s not a simple ‘plug and play’, banks need to first ready their data and teams for AI.
Banks have a unique vantage point on customers’ financial lives; they can see how customers make and spend their funds. Historically, however, this visibility was limited only to a customer’s activity within a single institution.
With the rise of open banking and data sharing across organizations, banks are gaining an even clearer view of how consumers engage across their entire financial journey – not
just a single account. For example, with permissioned open banking and data sharing between institutions, a bank financing a mortgage can qualify customers quickly – namely, verify income – and personalise mortgage recommendations based on a customer’s complete financial history.
Banks now have more than enough data to fuel AI-driven personalisation. But AI is only as effective as the data and teams behind it.
Here, we will walk through how financial institutions can unlock the full potential of AI to deliver personalised banking experiences that rival the tailored services customers have become accustomed to in their daily lives. Banks are using AI to analyse data at a scale that was previously una ainable. Insights that teams used to have to wait weeks for can now be generated in minutes, enabling them to create more personalised financial customer experiences faster.
As the volume of data available to banks continues to grow, from open banking to their own internal systems, the risk of duplicate data, missing data or errors grows as well. When data isn’t clean or connected, AI operates with critical gaps – which means the insights it generates have gaps as well. Financial institutions need to centralize their data so that AI is not working off a fragmented view of a customer but has complete visibility to garner more reliable, actionable insights.
Banks can then leverage these insights to confidently market products to relevant audiences and provide the personalised financial advice customers crave, but many say they don’t currently receive.
While AI can uncover who individual customers are, predict their behaviour, and understand the context of financial decisions like marriage or
ERIC BIERRY is CEO at SBS
starting a family, it’s these findings, combined with the teams behind AI, that create personalised banking experiences.
How teams use AI-driven insights to engage and connect with customers is what ultimately builds banks’ longterm relationships with them.
To do this in the best possible way, banks need to invest in ongoing AI training for all employees and bring in more AI specialists to maximize their adoption and impact. If teams don’t know how to use AI tools, they’ll default to using them for basic tasks, if at all. Customers expect consistent, individualised interactions from their bank. To obtain these relevant experiences, many grant banks grant access to their data through open banking or directly within their banking systems.
As banks leverage AI to deliver these experiences, transparency is critical–for both customers and employees. Customers need to understand how AI informs decisions around personalised product recommendations and tailored financial advice. For employees, it’s important to reinforce that AI is meant to be a collaborator –not a replacement.
This level of personalised advice, enabled by AI, that banks can offer at scale was previously reserved for private banking clients with substantial investable assets – a profitable segment, but one that couldn’t be scaled economically.
The banks that prepare their data, teams, and customers for AI are the ones that will deliver customer value through personalisation, retain their customer base and create long-lasting loyalty. Those that don’t will lose ground to competitors who do. ●
The Chartered Insurance Institute (CII) has delivered a timely reminder: identifying vulnerable customers requires more than good intentions. It demands structured, evidence-based assessment that can be applied consistently across your client base. For advisers navigating Consumer Duty obligations, this presents both a challenge and an opportunity, because the tools to meet these standards already exist.
The problem with relying solely on financial snapshots
Here’s what keeps advisers up at night: two clients walk through your door with near-identical financial circumstances – same income, same portfolio size, same retirement timeline. Yet one navigates market downturns with relative calm while the other panics at the first hint of volatility. Traditional financial data capture the first part of that equation brilliantly. They’re useless at explaining the second.
The CII’s emphasis on capability, comprehension, and resilience acknowledges this gap. These aren’t abstract concepts but behavioural realities that determine whether your clients can actually act on your advice.
Psychological traits including Composure under stress, Confidence in decision-making, Impulsivity, and Familiarity Preference directly predict how clients will respond when markets turn or life circumstances change. Measuring these factors is foundational to fair treatment.
No one doubts that experienced advisers develop strong intuitions about their clients. But the CII’s call for repeatable, evidence-
based processes acknowledges an uncomfortable truth: even excellent advisers are inconsistent diagnosticians. It’s not a lack of competence or training, but rather how human judgement works under complexity and time pressure.
Ask three advisers to assess the same client’s vulnerability and you’ll o en get three different answers. Ask the same adviser on different days and their assessment may shi . Suitability technology doesn’t replace adviser judgement; it removes the noise at the assessment stage so advisers can focus their expertise where it ma ers most: tailoring solutions, explaining tradeoffs, and providing emotional support through difficult decisions.
The technology enables you to separate diagnosis from prescription. Diagnosis benefits from systematic, repeatable measurement. Prescription requires the human skills that define good advice, namely understanding context, explaining complexity, and building trust. Ge ing diagnosis right means your prescription can be more precisely targeted and more likely to work in practice, not just on paper.
The CII correctly notes that vulnerability shi s over time. Bereavement, redundancy, health shocks, or relationship breakdown can temporarily overwhelm a client’s decision-making capacity. Waiting for these vulnerabilities to show up in portfolio decisions or missed review meetings means you’re intervening too late.
Behavioural monitoring tracks the interaction between stable personality traits and changing life circumstances. It doesn’t mean repeatedly testing your clients. It means understanding how their established behavioural
GREG B DAVIES is head of behavioural science at Oxford Risk
Identifying vulnerable customers requires more than good intentions. It demands structured, evidencebased assessment that can be applied consistently across your client base”
pa erns will respond to new stresses, and watching for early signals such as withdrawal from engagement, decision avoidance, increased anxiety, that suggest intervention is needed. This shi s vulnerability management from reactive to genuinely protective.
Behavioural assessment isn’t technically complicated. Most tools integrate straightforwardly into existing processes – a few minutes during onboarding, periodic check-ins, ongoing observation. The real shi is conceptual: accepting that understanding your clients’ behavioural capacity is as fundamental as understanding their financial capacity.
The CII has set the standard. And behavioural science gives you the practical means to meet it. For advisers commi ed to genuine client protection under Consumer Duty, the challenge is how quickly they can build behavioural data into their assessment process ●
Marvin Onumonu speaks with Julie Turner, founder and mortgage broker at Sophisticated Sussex Finance Ltd
led you to become a broker?
I initially came from a completely different industry. My entire early career was rooted in travel, which I entered at just 16 through the Youth Training Scheme (YTS) scheme, earning £27 a week in a small travel agency in Eastbourne.
It feels like a lifetime ago now, but that experience gave me a strong grounding in customer service and the rhythm of a busy sales environment. After that, I spent time travelling – something I was
deeply passionate about – and when I eventually returned to the UK, I continued progressing within the travel sector.
I managed several travel agencies before moving into a long-term backoffice role for a large travel company, where I stayed for 17 years.
When the pandemic hit in 2020 and the travel industry came to a standstill, I was made redundant. It was a huge turning point, but it also gave me rare time to reflect.
During that redundancy period, I had what I can only describe as a lightbulb moment: I realised
becoming a mortgage broker could combine everything I valued – flexibility, meaningful client relationships, and an interest in property and finance.
My biggest priority was being able to work around my daughter, who was five at the time, and mortgage advice felt like a perfect match for the next chapter of my career. Five years later, after passing my CeMAP in December 2020, I now proudly run my own firm. If someone had told me all of this back in 2020, I would never have believed it, but here I am – and I absolutely love what I do.
I live in Brighton and Hove – or “Hove, actually,” as we locals always say – and I feel incredibly lucky to call Sussex home. It’s one of those places that genuinely ticks every box: the energy of the city, the beautiful South Downs, and of course, the beach.
I’m only a five-minute walk from the seafront, so a lot of my free time is spent there with my daughter and our toy poodle, Bear.
A fun fact many people are surprised by: I started windsurfing at 13, and at the time I was one of the very few girls locally who could actually master it.
A second fun fact is that I used to work on a cruise ship as a croupier in the casino. I started off swapping money for rolls of coins for the slot machines, then I progressed to cashing in the casino chips and finally was trained to deal blackjack, roulette, poker and craps (dice). It was certainly a fun few years.
At Sophisticated Sussex Finance, our driving force is genuinely helping people. I often say the role is surprisingly similar to my days as a travel agent: you get to know the customer, understand their goals, budgets and future plans, and then guide them through a process that can otherwise feel overwhelming. In travel, I matched people to their ideal holiday.
Now, I match them to the most suitable mortgage – and the responsibility means even more because it shapes their lives long-term. That training in customer care has proved invaluable.
We take pride in the little details, the clear communication, and the patience needed to guide clients through what is often the biggest financial decision of their lives.
We also provide full wrap-around support such as solicitor referrals, survey recommendations, and ensuring protection is understood and prioritised, so clients feel completely looked after.
Our 5-star Google reviews consistently mention our friendly approach, thoroughness, and ability to make clients feel at ease. Those comments mean everything to us and reflect the service standard we work to every single day.
Right now, the landscape is evolving quickly, which actually opens doors for brokers who are proactive and client focused.
Consumers are more aware than ever of the value of personalised advice, especially after the economic uncertainty of recent years. This creates opportunities for brokers to deepen relationships, educate clients, and showcase the difference between using an adviser and going it alone.
Innovation in lending – from more flexible affordability models to specialist products for self-employed borrowers, later-life lending, and deposit-boosting schemes – also means brokers can help a broader range of clients than before. As more people face complex circumstances, brokers who stay informed and adaptable have a real advantage.
The biggest challenge in my local area is affordability. Brighton and Hove is a wonderful place to live, but it’s undeniably expensive, and saving a meaningful deposit can feel almost impossible for many firsttime buyers.
This is why new, innovative mortgage products are so vital. Anything that helps people transition from renting – where monthly costs
Hard work, resilience, and a genuine passion for helping people can take you far”
are often high – to owning a home can have a transformative impact.
Helping clients break into the market, despite the hurdles, is one of the most rewarding parts of the job.
I’m genuinely excited for 2026 and the direction both the market and my business are heading. Each year brings new opportunities, new clients, and new ways to grow.
Watching the business evolve from something I built during redundancy to a thriving brokerage is incredibly motivating, and I can’t wait to see what the next chapter holds.
Is there a message you’d like to send to other brokers?
When you’re starting out, it can feel incredibly daunting – especially when the income isn’t regular and everything depends on your own determination. But consistency truly is the key. Keep showing up, keep offering the best service you possibly can, and keep marketing yourself even when it feels like no one is noticing. If you stay patient and committed, your customer base will grow.
If someone had told me five years ago that I would be the owner of Sophisticated Sussex Finance Ltd, I wouldn’t have believed them. But hard work, resilience, and a genuine passion for helping people can take you far. Dreams really can come true – and this industry has space for all of us to succeed. ●
NHS professional on rotational contract
Ajunior doctor is purchasing a £365,000 property with a 10% deposit. They are on a rotational NHS contract, moving hospital trusts every six to 12 months as part of their training. Their base salary is £38,000 with an additional £7,500 from regular overtime. They have worked continuously in the NHS for three years, though each contract is technically fixed term. They want a 30-year mortgage to keep payments manageable.
The stated income would leave the applicant short of the required borrowing amount. We allow higher levels of borrowing, up to 6x income, for medical professionals. To qualify, applicants must be a GP or Specialist (including anaesthetists, surgeons, and consultants) and registered with the General Medical Council or British Medical Association (BMA). Overtime is usually calculated at 50% of the average earned over the past 12 months. WE+E may consider using a higher proportion of overtime on a case-by-case basis.
Together can support this applicant as they have been in continuous employment for over 12
months. We would require the last six months’ payslips if paid monthly to confirm their average income. While we cannot offer 90% loan-to-value (LTV), we could provide up to 75% LTV, subject to the property being of standard construction.
West One can consider 100% of the overtime, subject to it being regular and consistent (it will need to be reflected in the last two months’ wage slips).
However, this client will only be eligible for a maximum loan value of up to £295,750, meaning we would not be able to assist based on the deposit proposed. If they were able to raise a 19% deposit, they may qualify for our Residential Extra range with lending up to 6.5x loan-to-income (LTI).
Taken at face value, this case would be a no for Gen H – but there are some options. Usually, we would take overtime at 75% weighting, but if it can be evidenced that the overtime is consistent, we could consider exceptionally using 100%. However, that still puts the LTI ratio at 7.2x, which is above our maximum.
The buyer could add an income booster to their loan which would almost certainly make the mortgage affordable and could consider up to a 40-year term to reduce monthly payments further. They should just note that their income booster will be subject to the same checks they would be.
This is something we could consider, given the client’s track record and profession. We can use
the base salary and 100% of overtime where there is a clear history of this income. We can lend to age 75 to help keep payments manageable, and we have no income multiple restrictions, which may allow us to offer higher yet affordable loan amounts, than lenders with strict income multiples.
The society may be able to consider this request, given the applicant’s strong professional standing and positive track record with the NHS. At the Decision in Principle (DIP) stage, 50% of the applicant’s overtime income would typically be taken into account. Should a higher proportion be needed, it may be considered on a case-by-case basis.
This is indeed a case we could consider, but at 85% LTV as this is our maximum presently. If this could work, we’d be more than comfortable with the employment set up and income situation here given the three year history and professional industry. We would request a copy of the current contract, three months’ payslips and last two years’ P60s.
The applicant’s rotational contract, moving hospital trusts every six to 12 months, is perfectly acceptable and not uncommon. Combined with their ability to demonstrate a three-year employment history, they are a good applicant. Sadly, in this instance, even with the additional overtime taken into consideration, their income falls short of our loan-to-income (LTI) requirements. At 90% LTV, UTB requires a maximum LTI of 4.5.
Newly self-employed after long employment
Aclient wants to buy a home worth
£420,000 with a 15% deposit. They were employed for 10 years in the same industry, earning a £60,000 annual salary, before becoming self-employed 10 months ago doing the same work on a contract basis. They do not yet
have first-year accounts but can provide consistent monthly invoices and have a strong contract. They also have £7,000 in credit card balances and a £210 monthly car loan.
Ordinarily, being self-employed for less than a year would make this case unacceptable. However, as a specialist and flexible lender, we’d review the case even further.
We’d need to understand income in more detail, including the last P60 from employment and confirmation from the accountant on the current income level. These could support consideration on an exception basis.
Normally, we require 12 months of trading history for self-employed applicants. However, as this client is working on a contract basis and has been doing so for 10 months, we could consider using the average of the last nine months’ income, subject to tax deductions.
The applicant’s outgoings will be assessed for affordability as usual, and we could support up to 75% LTV assuming the property is of standard build.
West One accepts self-employed individuals who have at least 12 months’ trading history and one year’s tax returns.
Once the client has met this requirement, we would be able to work off the first year’s trading figures and can lend the required amount on our Residential Extra range up to 97.5% LTV, subject to affordability checks. The outstanding debts will need to be cleared with the loan to proceed.
With a good rationale and evidence of a similar level of income, we could consider making an exception for the absence of first-year accounts. However, this buyer still runs into an affordability problem – the LTI ratio is 6x, above our maximum. An Income Booster could help bridge this gap without having to contribute any money to the mortgage or monthly payments.
We would need to see one full year’s accounts before we could consider the application.
The society would be unable to consider this
solely in the applicant’s name, as a minimum of two years’ accounts is required. However, a Joint Borrower Sole Proprietor (JBSP) arrangement may be considered if a family member is available to support, with an appropriate exit strategy in place given the applicant’s recent transition to self-employment.
We can lend up to 85%, so the LTV here is acceptable. Typically, we need one years’ contracting history in order to consider income from this source.
However, given their experience in the field leading up to this, if we could get a copy of the current contract and management information from the accountant, this is a case we could refer to our underwriters for exceptional consideration.
Despite the applicant having a 10-year history in the same industry, UTB requires two years’ finalised accounts to consider a self-employed applicant.
Should the applicant be a limited company director, we may consider one year of finalised accounts with strong projections if they are several months into the current accounting period where management accounts supplied by their accountant can support the projections. Had there been sufficient accounts history, the application would meet our minimum LTI requirements. However, a monthly affordability assessment would need to be completed in our portal DIP journey, taking into account any current unsecured credit commitments.
Expat landlord purchasing in the UK from overseas
ABritish national living and working in Hong Kong wishes to buy a second buy-to-let (BTL) property in the UK. The desired property is located in Manchester, and costs around £285,000 with a 30% deposit.
The buyer earns the equivalent of £78,000 per year and has worked abroad for over four years. They rent their own personal property overseas, have a UK bank account. However, due to living abroad they have limited recent UK credit activity.
The expected rent on the Manchester investment is approximately £1,250 per month, and they plan to manage the property remotely.
This case could be acceptable, subject to underwriting review. As the applicant is based in Hong Kong, we would need to confirm their UK tax position.
If not already paying UK tax, they must register with HMRC for future income assessment. This is one to discuss with a business development manager (BDM) before submission.
Together recently announced that it was lowering rates for non-UK nationals and expats. As long as the applicant has an active UK bank account for mortgage payments and the valuation, credit, and affordability checks are satisfactory, we could offer up to 75% LTV. This is provided the property is of standard construction and not in a building over six floors.
West One will only accept an applicant who is both a first-time landlord and first-time buyer if they reside in the UK, are aged 25 or over, and have a minimum income of £25,000 (minimum income is only required for first-time buyers).
For UK expats, we require that they own at least one other buy-to-let property in the UK already, and they must appoint an acceptable servicing agent in the UK. Based on these requirements, we would not be able to assist this particular client.
This one is a straightforward ‘no’ for us: Gen H doesn’t offer buy-to-let mortgages or accept loans in non-UK currency.
The society may consider this application provided the applicant is a British citizen and not residing under a British National (Overseas) Visa. As part of the underwriting process, the applicant would be required to supply their most recent UK address and National Insurance (NI) number.
Our BTL offering does not currently extend to expat applications. However, we are always exploring opportunities to enhance our product offering and ex-pat applications are something we’re considering catering for in the future.
as the couple are likely to qualify based on their base salaries alone.
Dual income with variable commission
Afirst-time buyer hopes to purchase a newbuild flat for £300,000 with a 10% deposit. The annual service charge on the flat is £3,600, and there is also a ground rent of £350 per year. Although the buyer earns £45,000 and passes initial affordability checks, some lenders reduced maximum borrowing due to the high ongoing charges. Others raised concerns about resale value and potential cladding risks.
We may fall short of the required borrowing level. We lend up to 4.5x joint income. Up to 100% of commission can be considered if there’s at least a six-month track record. Alternatively, the last two years’ P60s can evidence commission income, assessed individually.
Existing credit commitments will also impact maximum borrowing. If an applicant is in their probation period and a first-time buyer, at least six months in the role is required, and their income is disregarded. If not in probation, and with a minimum of three months employment history, income can be accepted.
year-to-date calculations. We could offer up to 75%
If the first applicant can show a 12-month track record of their commission, we could use 100% of this income as an exception. The second applicant is fine by us provided they can show 12 months’ evidence of a similar level of income in a similar role. And at 4.6x LTI, this case might actually work without any exception for applicant one.
If there is a proven track record of commission, we can consider using 100% of this, supported by the P60. For the second applicant, if they are in the same line of work, we can take a view on the probation period. If it is a new industry, they can apply, but we would wait until the probation is completed.
To consider variable commission income, the society would require a consistent 12-month track record. As the second applicant has only been in their current role for four weeks, we would need further details regarding their previous employment history and confirmation of any probationary period. Additional information will be necessary to proceed with the assessment.
Our max LTV is 85%, so could only proceed at this level. If this could work, we could accept all income at 100% using three months’ payslips to confirm salary and last two years’ P60s to demonstrate commission.
We would need two years’ evidence to use commission at 100%, otherwise this would decrease to 50%. We’d also need three years’ working history.
We’ve reduced our residential and commercial stress rates, giving SME borrowers and landlords a much-needed affordability boost.
potential commission, we may consider this case on our Residential Extra range. We can use annual commission figures in assessing affordability, subject to it being regular and consistent. However, it may not be necessary in this case
Fluctuations in month-to-month commissions can be considered as UTB will look at the annualised commission and use up to 75% for affordability purposes further supported by both applicants’ base salaries. This would be dependent on the second applicant evidencing 12 months’ continuous employment, due to only being in their current role for four weeks. Any applicant in role for 6 months or longer does not need to evidence 12 months continuous employment. Unfortunately, at 90% LTV the useable income for the application would not meet our minimum required LTI for the loan amount required. ●
Your face could generate more business for you. It did for our client in a recent experiment. We ran a test on a mortgage broker’s website – two identical web pages, except one showed a mortgage adviser’s photo and one didn’t. Our so ware randomly assigned a page to each visitor, split down the middle.
The page with the adviser photo generated 11% more leads than the page without. As leads converted to application at 15%, the adviser’s face generated an additional mortgage application for every 967 page visitors.
The experiment showed that using an iPhone photo of an adviser on a webpage – a cost-free action –increases leads and applications.
‘Ambiguity aversion’ is where people tend to avoid making choices with uncertain outcomes. Like requesting a call back when they don’t know who will call them. Just as you wouldn’t want to discuss your private financial ma ers with a stranger, your clients feel the same.
The science shows that our brains are uniquely optimised to assess the trustworthiness of faces. It’s something we’ve go en really good at over thousands of years to help us survive. While logos can build reputation and signal competence over time, the human face is the most powerful and immediate trigger for trust.
Eye-tracking studies have shown that when a user lands on a page, their eyes are immediately drawn to a human face. Another result of our evolution, we’re hard wired to look for other human faces.
Another experiment found that users largely ignore generic stock photos of people because they are easily recognisable as filler content. However, when the images
were of actual team members or subject ma er experts, the photos significantly improved credibility and conversion rates.
This suggests the benefit is not just any face, but a perceived ‘authentic’ face that represents the company or the offer.
We checked 15 landing pages of brokers – who we don’t work with –with Google Ads campaigns, and none of them featured a photo of an adviser. Good news for you, if you make this change you can stand out.
Show your face, it’s a personal service! Don’t just hide details of your team on an ‘about us’ page. Don’t assume everyone enters your website via the homepage or will go to your team page. Every page is an opportunity to meet your team.
It doesn’t have to be a super professional photoshoot. Our test was just a black and white photo taken from an iPhone. A professional photographer could capture some excellent additions to your website, but don’t delay when your smart phone takes quality photos. iPhone photos are be er than no photos.
Should you opt to use your smartphone for taking the pictures yourself, consider using a black and white filter. This can help create a consistent look across all your photographs. It might be difficult to get all your team together so it’s a quick and easy option.
If you book a photoshoot, a pro photographer will take some stunning photos in full colour. They’ll normally recommend which ones to use too.
An iPhone photo that looks genuine will do more for you than an artificial intelligence (AI) generated picture that doesn’t look real. Don’t forget that we’ve evolved to easily spot genuine faces, if your image looks fake it might as well be a stock photo. Our photo was underneath the headline just
ALEX CURTIS is founder of e Lead Engine
Our brains are uniquely optimised to assess the trustworthiness of faces. It’s something we’ve gotten really good at over thousands of years to help us survive”
before the main body of text. Our aim was to position the adviser as the author of the text on the page. This positions the adviser as an expert in that particular mortgage scenario.
Not a silver bullet
Remember, while people buy from people, it doesn’t work on its own. While showing your face online is incredibly persuasive, you’ll be disappointed if that’s all the only thing you think about.
The pages in our test incorporated a variety of elements, like recent 5-star reviews, persuasive copywriting, a clear call to action, content tailored to the specific mortgage scenario and a user-friendly layout.
The adviser photos acted as a boost, but it needed a solid foundation to generate results. ●
The old way of handling things was to keep a stiff upper lip at work, with the odd explosion of rage when the pressure built up. Feeling, like lunch, was for wimps. So, how much has this changed?
One client of mine reached senior management level with his best kept secret, a terror of public speaking, undetected. He was great at delegating presentations, selling it as a development opportunity. The emotional cost was immense – the fear of being found out, or anticipating being called to give an address unexpectedly. He finally confessed and asked for help, and we examined his shame about having ‘weak, unmanly’ emotions.
The new leaders coming up the ranks are surely less likely to see things this way, especially as science tells us that emotional intelligence is closer correlated with success than general intelligence.
I have always had an antipathy to the term ‘emotional intelligence’. Intelligence is a tricky and flawed concept, let alone when applied to emotions. The implication is that the higher you score, the be er it is. Yet, we do not want a trauma surgeon overcome by her feelings, or a fire officer distressed about that proverbial ki en up a tree!
I prefer the concept of emotional literacy – the capacity to read
Too often, organisations focus on the rational and intellectual, ignoring the seething emotions present in every meeting or presentation”
emotions. For many, this will feel like trying to understand a foreign language.
It also means using this awareness to manage relationships and make be er decisions. Emotionally literate people are a uned to the emotional climate of their teams, and respond with empathy, clarity, and integrity.
Too o en, organisations focus on the rational and intellectual, ignoring the seething emotions present in every meeting or presentation. It is not the leader’s job to turn therapist, but it is their job to read the room and consider all the data that will determine how well any strategic initiative is carried out.
Daniel Goleman successfully wrote about emotional intelligence in 1995. I recommended his book to a CEO of a Council. He proceeded to slam it on the boardroom table, scan his directors with gimlet eyes, demanding, ‘Who has read this book?’ in a stunning display of completely lacking emotional awareness, as they fidgeted and avoided his gaze like scared schoolboys…
He had yet to learn that, at its core, being emotionally literate includes:
1. Self-awareness – Understanding your own emotions, triggers, values, and how they affect your behaviour and decision-making.
2. Self-regulation – Managing your emotional reactions and staying composed under pressure.
3. Empathy – Sensing others’ feelings and perspectives and taking an active interest in their concerns.
4.Social skills – Building healthy relationships, resolving conflicts, and inspiring and influencing others positively.
5. Motivation – Being driven by purpose and values rather than ego or fear.
So, why is emotional intelligence more relevant than IQ? The key is in the capacity to see the whole picture and
AVERIL LEIMON is co-founder of White Water Group
troubleshoot the issues that might undermine success.
The fact that it’s more humane and makes you be er to work for are just wonderful side effects.
Leaders with high emotional intelligence: build more resilient, loyal teams; reduce stress and burnout; increase engagement and collaboration; and navigate change with grace.
So, where do you start?
Notice your feelings and try to discern what others are feeling in the same situation – try recording your emotional reactions for a week. What were the feelings, the circumstances, and how did you deal with them?
Complete denial? ‘I’m fine’ snarled at anyone who asks? Having a rant at anyone in your path?
Clarify what caused your feelings –was your emotion the only response to the event, or was it shaped by your own fears?
Calibrate your emotion. Was murderous rage the right response to the trivial error someone made, or had there been a build up of frustration which just spilled over at that moment? Find ways to incorporate emotions into feedback.
Remember – how people feel about something is a valuable source of data. The more you can read emotions, the more effective you will be. ●
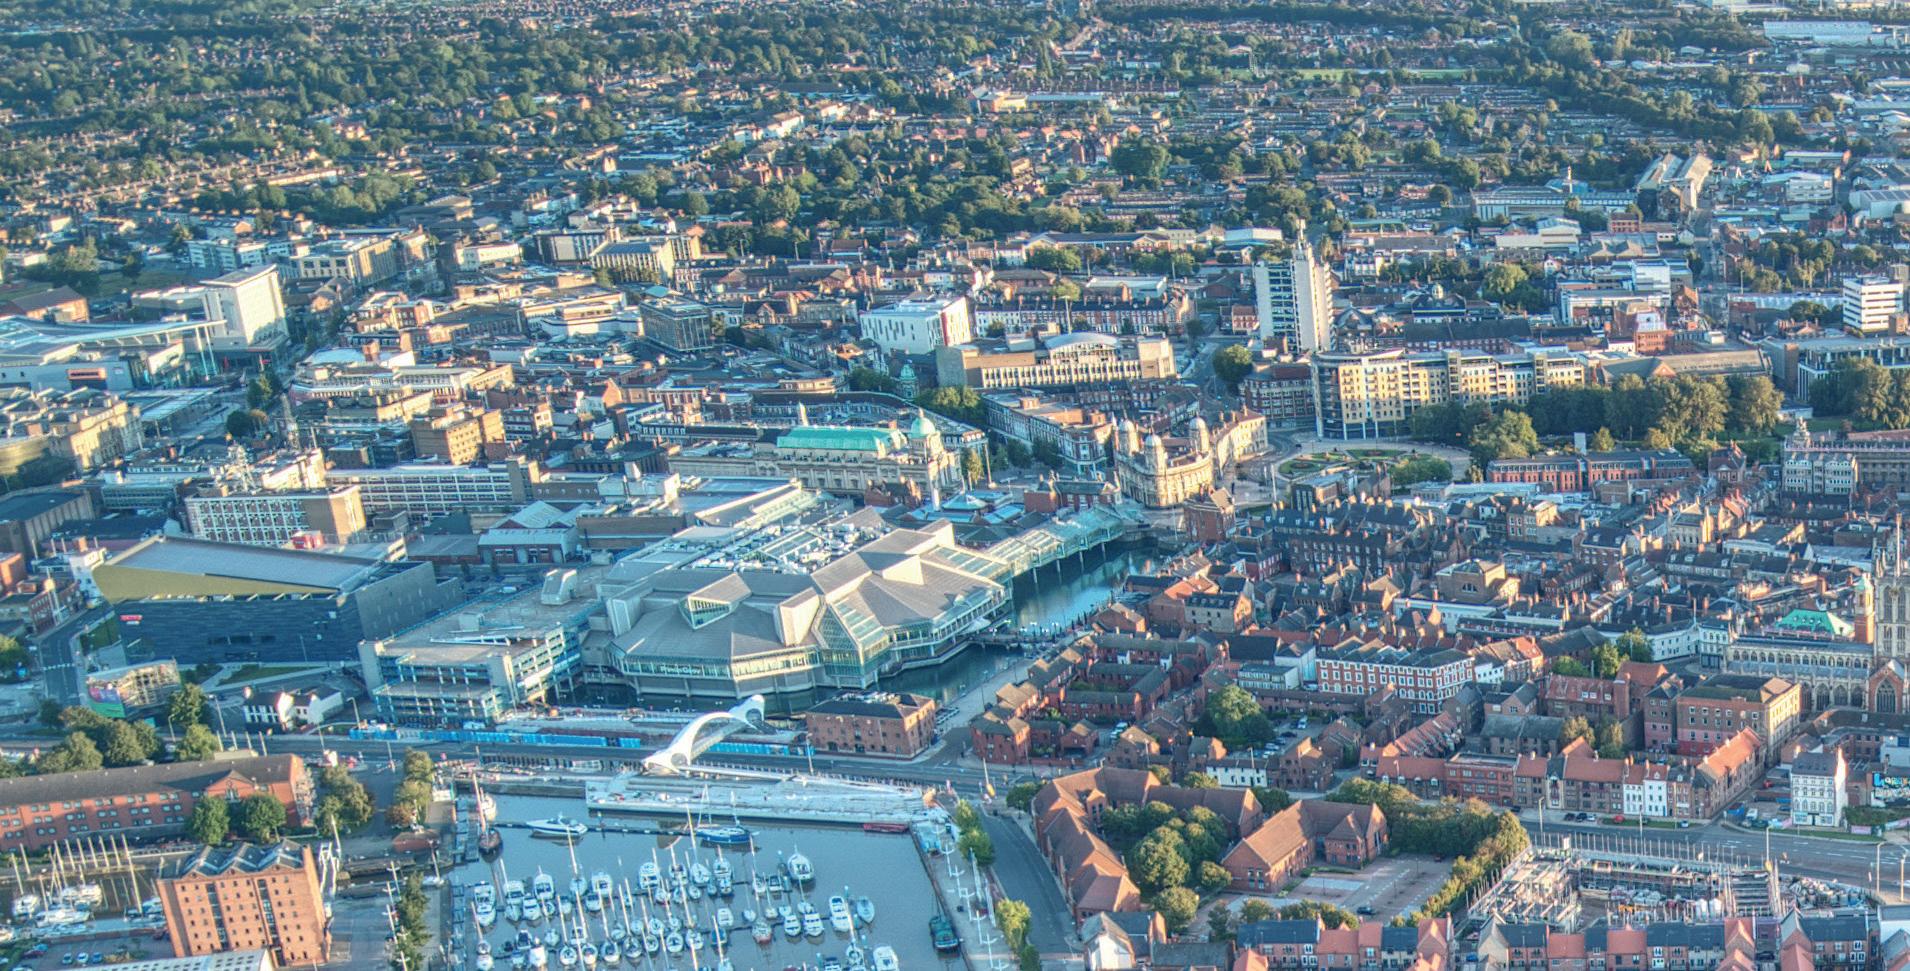
Each month, The Intermediary takes a close-up look at the housing market in a specific region and speaks to the experts supporting the area to find out what makes their territory unique
Defined by its industrial heritage and maritime links, Hull is carving out a quieter but increasingly compelling position in the northern property landscape. As regeneration along the waterfront continues and new employment hubs take shape, the city offers a blend of affordability and opportunity that is drawing the attention of buyers, brokers, and investors alike.
While Hull may not command the national spotlight as loudly as some of its regional neighbours, its housing market is evolving with a steady confidence, as it is shaped by shifting buyer priorities and a growing appeal among first-time purchasers seeking long-term value. This month, The Intermediary explores the forces reshaping Hull’s residential market and the trends that brokers should be watching closely for the remainder of 2025 and beyond.
Hull’s property market has held remarkably steady over the past year, with average prices in the postcode
area now sitting at £195,000. This marks a marginal annual decline of just £401, effectively leaving values unchanged. The median price rests at a lower £167,000, reflecting the city’s broad affordability compared with many other UK regions.
Sales activity has softened in the past year, with transaction volumes falling by 17.1% to around 5,700 sales – an annual drop of around 1,300. Demand remains focused in the lower-to-mid price brackets, particularly the £100,000 to £150,000 band, which accounted for 25.4% of all sales. This was followed by the
New
infrastructure and residential projects continue to reshape the city’s housing the city’s city’s housing the city’s housing landscape. The average at £471,000”
£150,000 to £200,000 range at 22.1%. Hull’s affordability spectrum is broad, with the most accessible area, HU3 3, averaging at just £76,000, while the priciest neighbourhood, HU20 3, commands an average property price £357,000.
By property type, detached homes now boast an average of £328,000, followed by semi-detached at £200,000, terraced properties at £138,000, and flats at £114,000.
Hull’s residential market is showing signs of quiet but meaningful momentum, with brokers reporting a steady uptick in activity even as buyer
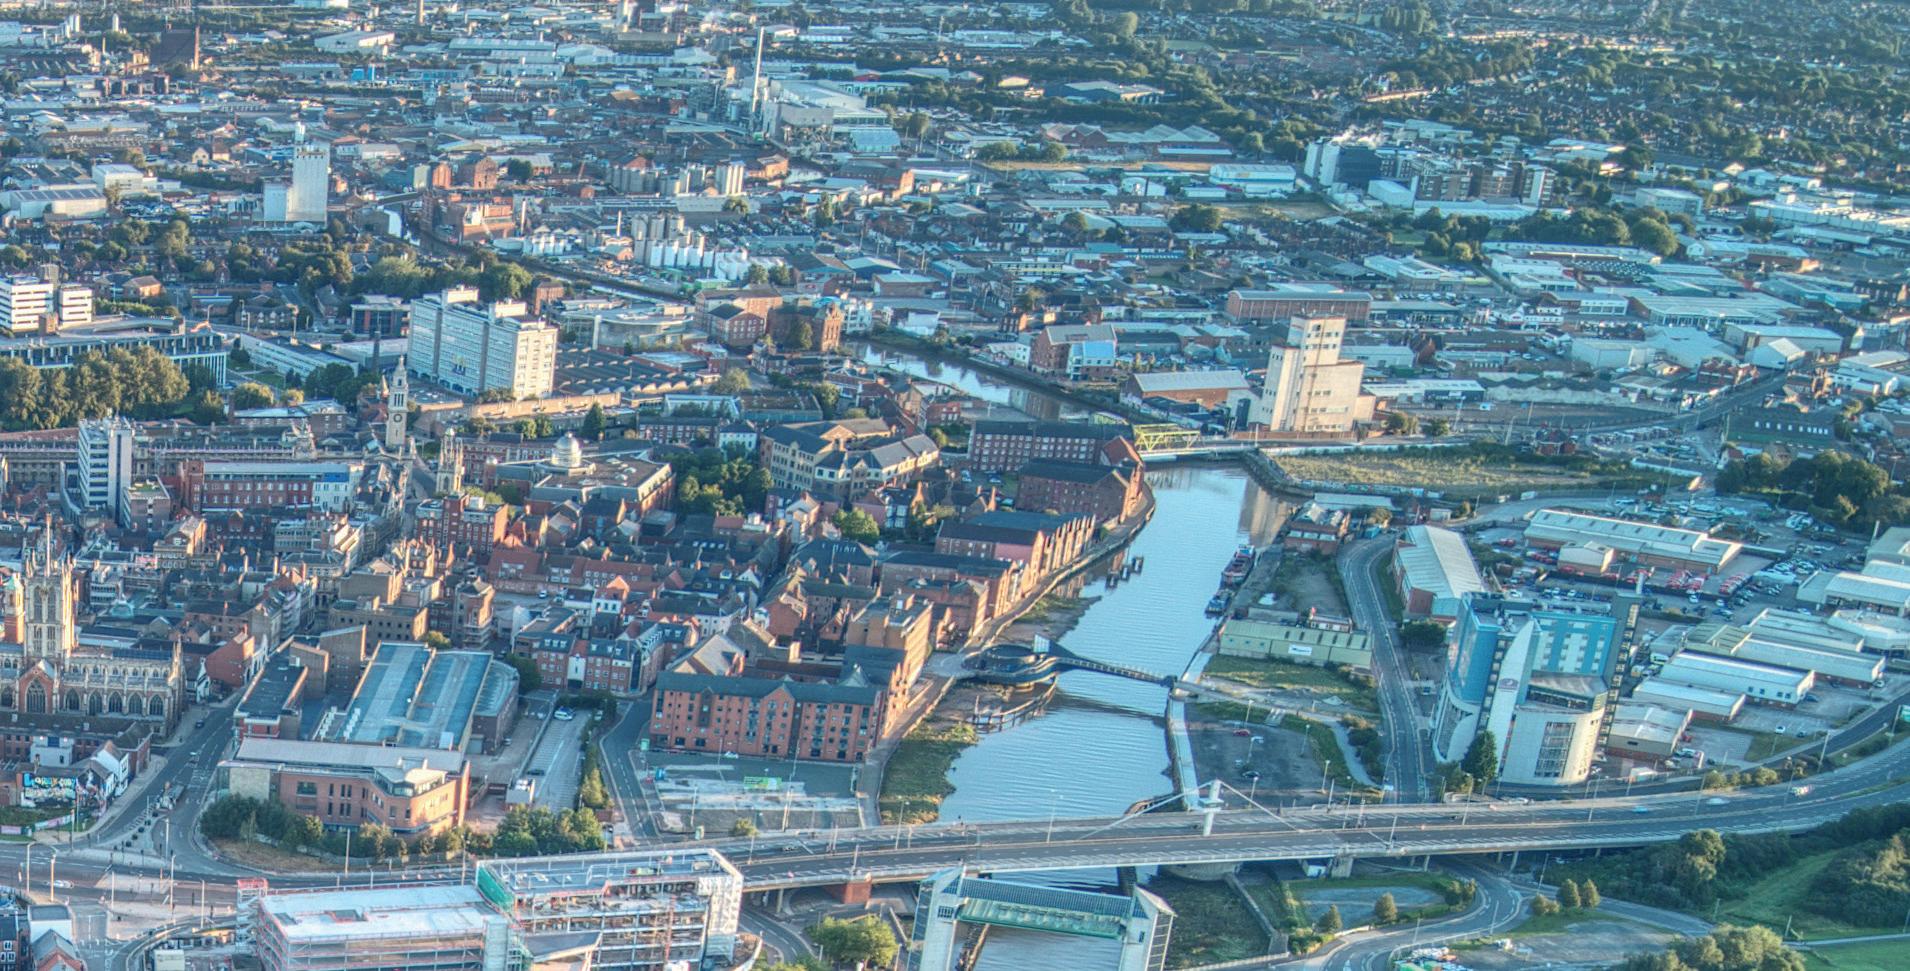
JESSICA O’CONNOR is deputy editor at e Intermediary
behaviour continues to evolve.
According to Kate Cunningham, mortgage adviser at The Mortgage Corner Ltd, the firm has “seen a 16% increase in residential purchase applications compared to the same period last year,” which she describes as “a positive sign of steady, gradual growth.”
Yet beneath that uplift, the profile of applications is shifting. Cunningham explains that “there has been a decline in like-for-like remortgage applications,” but at the same time “a noticeable increase in applications involving capital raising” as homeowners look to fund debt consolidation, home improvements, and other personal financial needs.
For James Green, managing director at Green & Green Mortgage and Protection, the past 18 months have marked a distinct re-emergence of both first-time buyers and home
OKATE CUNNINGHAM mortgage adviser at The Mortgage Corner Ltd
ver the past nine months, we’ve seen a 16% increase in residential purchase applications compared to the same period last year, a positive sign of steady, gradual growth. However, despite the overall rise in purchase activity, there has been a slight decline in applications from first-time buyers.
While overall demand for residential mortgages in recent months remains broadly in line with the same period last year, we’ve observed a shift in the types of transactions being completed.
There has been a decline in like-for-like remortgage applications, but a noticeable increase in applications involving capital raising – often for purposes such as debt consolidation, home improvements, and other personal financial needs.
Within the buy-to-let mortgage market, we’ve seen a rise in clients interested in purchasing property through a limited company structure, largely driven by potential tax advantages. In response, many lenders are expanding their offerings to cater to this growing demand.
As a reputable mortgage brokerage, we take pride in offering tailored advice and securing the most competitive interest rates for our clients based on their individual circumstances. Recently, for residential applications, we’ve seen an increase in recommendations for lenders such as Barclays, Nationwide, and NatWest. This is often due to their higher maximum working age limits for earned income, strong affordability assessments, flexible stance on minor credit issues, and competitive interest rates.
Similarly, within our buy-to-let applications, we’ve seen a rise in recommendations to The Mortgage Works (TMW) due to their flexible approach to larger portfolios and limited company structures. BM Solutions and Virgin Money have also become popular choices, offering more accommodating criteria for smaller landlords, along with competitive interest rates and favourable stress testing.
While we specialise across all areas of the mortgage market, residential lending makes up a significant proportion of our client base. Within this segment, we’ve observed that the average age of first-time
WJAMES GREEN, managing director at Green & Green Mortgage and Protection
e have seen a steady increase in first-time buyers and home movers over the last 18 months as the people of Hull and surrounding areas have adjusted to the cost-of-living increase but also adapted to the current interest rates. The end Autumn Budget of 2022 brought about a huge spike in interest rates overnight which scared off a lot of first-time buyers, leaving them waiting on the sidelines for the rates we enjoyed in COVID to return.
As would-be buyers adjusted to these higher rates and learned that the days of 1% interest rates weren’t coming back, they began to return to the market. The numerous drops in the base rate and the positivity this has brought have encouraged buyers to take that first step. This year has been our busiest yet since we started back in 2020 due to these first-time buyers and people upsizing.
We have seen people now more than we’ve seen since COVID stretch themselves mortgage-wise to buy a bigger home or to remortgage to release equity to extend and improve their homes. Many of our clients are first-time buyers or buyers we initially helped buy their first home move onto a bigger home, so we are seeing more of them increase their borrowing to upsize or improve their current home to accommodate their growing needs.
As our main demographic is first-time buyers, we have a lot of our cases go with the high street big names like Nationwide due to their helping hand scheme but also their cashback for first-time buyers which helps them offset solicitor costs on completion. As most of our client work is fairly ‘vanilla’, i.e. first-time buyers with savings as a deposit and working a full-time job, most of our work is done purely on sourcing. So, the lenders who sit top of the sourcing list. Barclays have repriced in recent weeks and have sat at the top of the list for a while now, along with Halifax. Due to my background in professional sport, we get a lot of professional rugby league players, and we use Halifax a lot with them due to their criteria around fixed-term contracts.
Alot of our clients are professional rugby league players and rugby fans in general. We get a lead from our rugby league player clients when they post on social media about our service.
Buy-to-let has always remained strong in Hull due to the high yields investors can secure here. With a typical two-bed terraced house selling for circa £80,000 and achieving a rental income of £600 per calendar month (pcm), the returns are strong. During the periods of high interest during 2022/2023 we did see a dip in local investors as they waited for the dust to settle on interest rates. But in this time, we saw an increase in out of town investors who were still happy to invest in high yielding areas away from home as putting their money into a property with a lower yield than normal was more beneficial than letting it erode in the bank with inflation in double digits.
movers. He notes that many who stepped back after the 2022 Autumn Budget – when interest rates “spiked overnight,” – are now returning with renewed confidence.
Indeed, he says many borrowers are now stretching their limits in order to
“buy a bigger home or to remortgage to release equity to extend and improve their homes.”
He adds: “Many of our clients are first-time buyers or buyers we initially helped buy their first home move onto a bigger home, so we are seeing more
of them increase their borrowing to upsize or improve their current home to accommodate their growing needs.”
In response to shifting sentiment, Hull’s buyer pool is broadening in distinctive ways. With a postcode population of 467,000 and an average age of 41.5, the region has grown steadily over the past two decades. According to Green, one of the most striking trends this year has been a wave of intergenerational support.
He says: “We have seen a surge of gifted deposits coming from grandparents. Typically, it is the parents that gift the deposit to their children to help them on the ladder but since the Inheritance Tax changes, we have seen more and more grandparents gifting money to their grandchildren to help them now.”
In addition, Hull’s strong sporting identity has also had a surprising influence on buyer profiles. As Green explains: “A lot of our clients are professional rugby league players and rugby fans in general,” with referrals often arriving via players’ social media posts.
However, Cunningham has observed alternative demographic shifts. She cites “a noticeable rise” in borrowers in their 50s and 60s applying for later-life or interest-only retirement mortgages.
Cunningham explains: “Many clients we speak to feel that retiring before the age of 70 is no longer realistic.
“In response, lenders are adopting a more flexible approach to retirement ages, offering longer mortgage terms to help keep monthly payments more affordable.”
She adds: “We’ve also seen lenders increase their income multipliers, enabling some borrowers to access higher loan amounts. However, there are concerning signs in the market –unsecured debt levels are rising, and there has been an uplift in adverse credit cases, both of which suggest that more individuals are facing financial strain.”
When it comes to lender choice in the area, the picture is shaped as much by borrower profiles as by product criteria. Cunningham notes that on the residential side, several major
lenders are popular. She says: “We’ve seen an increase in recommendations for lenders such as Barclays, Nationwide, and NatWest.
“This is often due to their higher maximum working age limits for earned income, strong affordability assessments, flexible stance on minor credit issues, and competitive interest rates.”
She adds that the buy-to-let space shows its own pattern, with a growing reliance on The Mortgage Works “due to their flexible approach to larger portfolios and limited company structures,” while “BM Solutions and Virgin Money have also become popular choices” among smaller landlords seeking favourable stress tests and pragmatic criteria.
For Green, the dominance of high-street names is even more pronounced, largely because his client base is heavily first-time-buyer led.
“We have a lot of our cases go with the high street big names like Nationwide due to their helping hand scheme but also their cashback for first-time buyers which helps them offset solicitor costs on completion,” he explains.
“As most of our client work is fairly ‘vanilla’ […] most of our work is done purely on sourcing. So, the lenders who sit top of the sourcing list. Barclays have repriced in recent weeks and have sat at the top of the list for a while now, along with Halifax.”
Green notes that his clients’ jobs also influence lender choice. He says: “Due to my background in professional sport, we get a lot of professional rugby league players, and we use Halifax a lot with them due to their criteria around fixed term contracts.”
In terms of property development, Hull’s regeneration story continues to gather momentum, supported by a steady pipeline of new-build activity and large-scale infrastructure works.
Newly built homes in the postcode area now average £247,000, with prices up 4% year-on-year, and development activity remains concentrated in key hotspots such as HU17 0 – where 119 new homes were sold between October 2024 and September 2025. Much of this momentum is being driven by ambitious masterplans across the city. As Cunningham explains: “There are
several exciting new developments proposed in Hull that reflect the city’s ongoing growth and regeneration.”
She highlights the East Bank Urban Village, which “aims to deliver 850 new homes over the next 15 years.” She also points to Beal Homes’ Sutton-onHull scheme, set to deliver 418 homes ranging from starter properties to larger detached houses, as well as the Dane Park Road Development, which will bring forward 99 affordable homes by spring 2027.
Infrastructure investment is equally significant. Cunningham notes that “the most notable project underway is the A63 Castle Street improvement scheme,” a major upgrade designed to improve local traffic flow and boost freight efficiency to and from the Port of Hull.
Meanwhile, shifting dynamics in the student accommodation sector are also reshaping future demand. Green explains that the market is likely to see a dip in private student lets as the University of Hull expands its oncampus provision.
He says: “The Lawns has been bought for redevelopment with the intention of modernising the huge building to house 970 students again. These two huge sites will provide thousands of students with more modern and convenient accommodation compared to private accommodation further away from the university campus.”
Hull’s rental and buy-to-let market remains a distinctive part of the local housing landscape, shaped by strong yields and a private rental stock (24.3%) that sits slightly above the national average of 23.6%. As Green puts it: “Buy-to-let has always remained strong in Hull due to the high yields investors can secure here,” noting that a typical two-bed terraced house achieves a rental income of £600 per calendar month (pcm).
While high interest rates in 2022 and 2023 cooled activity among local landlords, Green says there was “an increase in put of town investors who were still happy to invest in high yielding areas away from home. Putting their money into a property with a lower yield that normal was more beneficial than letting it erode in the bank with inflation in double digits.”
Yet beneath the appeal of these
Source: www.plumplot.co.uk
returns, the market is becoming more polarised. Cunningham reports “a noticeable decline in enquiries for new buy-to-let purchases,” even as interest grows among those exploring limited company structures for tax efficiency.
Lenders, she notes, are widening their offerings in response.
At the same time, many longstanding landlords are beginning to exit the sector altogether.
She says: “This trend is largely driven by increased tax burdens and reduced reliefs, rising regulation, financial risks associated with high interest rates and rent arrears, and growing legal and liability concerns, all contributing to reduced profitability in the sector.”
Hull’s housing market may still be working through the aftershocks of economic turbulence, but the direction of travel is clear. Activity is broadening, confidence is rebuilding and both advisers and clients are adapting to new lending norms, whether through later-life borrowing, capital-raising remortgages, or more flexible routes onto the ladder.
Against this backdrop, broker and borrower sentiment is quietly but steadily improving. As Green surmises: “The numerous drops in the base rate and the positivity this has brought have encouraged buyers to take that first step. This year has been our busiest yet.” ●
MT Finance appoints James Briggs as national account manager
MMMT Finance has appointed James Briggs as national account manager. Briggs joins MT Finance with more than 25 years’ experience in senior roles within the specialist finance sector.


Prior to joining MT Finance, Briggs held a number of senior leadership positions, including most recently at Afin Bank.
leadership positions, including

ortgage Brain has strengthened its customer success team with two customer success administrators. Richard BethuneWright and Ashley Cope will support the ongoing migration of users from legacy systems to the newest versions of the product suite, as well as to assist with onboarding.
ortgage Brain has strengthened its customer success team with two customer success administrators. Richard BethuneWright and Ashley Cope will support the ongoing migration of users from legacy systems to the newest versions of the product suite, as well as to assist with onboarding.
Neil Wya , sales and marketing director, said:
Neil Wya , sales and marketing director, said:
In his new position, he will focus on supporting the lender’s growth strategy by developing specialist lending propositions and

“We’re delighted to welcome Richard and Ashley to the Mortgage Brain team.
“We’re delighted to welcome Richard and Ashley to the Mortgage Brain team.
deepening long-term relationships with intermediaries nationwide.
“Their appointments strengthen our commitment to delivering an exceptional experience for our customers as we continue to roll out our latest generation of technology.
“Their appointments strengthen our commitment to delivering an exceptional experience for our customers as we continue to roll out our latest generation of technology.
Gareth Lewis, deputy chief executive officer at MT Finance, said: “We are delighted to welcome James to the team. James’s wealth of experience and deep understanding of the intermediary landscape make him an invaluable asset as we continue to expand our reach.

intermediary landscape make
brokers through


“His background in both commercial and short-term finance aligns perfectly with our growth plans and we look forward to building on this.”
“Both will play a vital role in supporting brokers through migration and onboarding, ensuring every user benefits fully from the [...] Mortgage Brain Hub.”
“Both will play a vital role in supporting brokers through migration and onboarding, ensuring every user benefits fully from the [...] Mortgage Brain Hub.”
CTCAlternative Bridging appoints case manager to bolster broker support
April Mortgages strengthens distribution team ahead of 2026 growth plans
Alternative Bridging appoints case manager to bolster broker support
AAlternative Bridging
lternative Bridging Corporation has strengthened its capacity with the appointment of Thomas Gough as case manager.
AReporting to Mihaela Janko, manager of the case management team, he will focus on progressing applications from offer to completion and maintaining clear and consistent communication with brokers.
management team, he will focus on progressing applications from offer to completion and maintaining clear and consistent communication with brokers.
pril Mortgages has strengthened its distribution capability with a trio of new appointments as it gears up for further growth in 2026. Lewis Chinyou-Robinson has been appointed national account manager.
L&C Mortgages appoints Dan Payne as chief operating o cer
Foundation Home Loans appoints chief commercial o cer
LLoundation Home Loans has appointed Alan Davison (pictured) as chief commercial officer (CCO).
Joining the business with immediate effect, he has more than 25 years of experience in financial services, covering lending, sales and commercial strategy. The appointment is subject to regulatory approval.
&C Mortgages has appointed Dan Payne as COO, reporting to MD Sidney Wager. Payne brings more than 20 years of financial services leadership experience, covering sales planning, distribution and customer experience. He joins from Together Money, where he was group sales director.
&C Mortgages has appointed Dan Payne as COO, reporting to MD Sidney Wager. Payne brings more than 20 years of financial services leadership experience, covering sales planning, distribution and customer experience. He joins from Together Money, where he was group sales director.
atalyst Property Finance has expanded its intermediary support with four senior appointments to its external new business team, led by sales director Spencer Gale.
atalyst Property Finance has expanded its intermediary support with four senior appointments to its external new business team, led by sales director Spencer Gale.
he Building Societies Association (BSA) has appointed Susan Allen (pictured, le ), CEO of Yorkshire Building Society, and Caroline Domanski (pictured, right), CEO of No1 CopperPot Credit Union, as deputy chairs.
Allen said: “This is an exciting time for the mutual sector with many opportunities ahead.
Andy Reid joins as head of national accounts, bringing experience from specialist lenders including TAB, Hampshire Trust Bank and InterBay. He is joined by three business development managers: Gemma Roberts, previously at UTB and Together; Tim Horne, formerly of Paragon and Magellan; and Tony Grillo, who has held roles at Masthaven and Together.
Andy Reid joins as head of national accounts, bringing experience from specialist lenders including TAB, Hampshire Trust Bank and InterBay. He is joined by three business development managers: Gemma Roberts, previously at UTB and Together; Tim Horne, formerly of Paragon and Magellan; and Tony Grillo, who has held roles at Masthaven and Together.
They will work alongside Simon Taylor, chair at BSA, CEO Sarah Harrison.
Janko said: “Case management is where much of the behind-the-scenes work happens, and having experienced professionals like Thomas in the team makes all the difference. His a ention to detail, proactive approach, and understanding of the lending process will help ensure we maintain the smooth, responsive service that brokers expect from us.
Janko said: “Case management is where much of the behind-the-scenes work happens, and having experienced professionals like Thomas in the team makes all the difference. His a ention to detail, proactive approach, and understanding of the lending process will help ensure we maintain the smooth, responsive service that brokers expect from us.
Further bolstering adviser support, Lucy Hughes and Mark Brown have joined April Mortgages as telephone business development managers, increasing the lender’s capacity to provide guidance to advisers on cases.
Chinyou-Robinson said: “It’s been a brilliant year working alongside such a driven, forward-thinking team.
“We have exciting plans ahead, with plans to broaden our offering in the new year and we’re building an excellent team to support us."
“We have exciting plans ahead, with plans to broaden our offering in the new year and we’re building an excellent team to support us."
“As we look to 2026, my focus is on [...] making sure advisers get the service, clarity and support they need to grow their business.“
Payne said: “I’m honoured to join L&C Mortgages, which has a longstanding reputation for excellence and innovation in the mortgage market.
Davison said: “I’m thrilled to be joining Foundation Home Loans at such an exciting time for the business, and seeking to build on what already makes it a highly successful lender – a strong culture, clear focus, and deep commitment to our people and the relationships they hold.”
Payne said: “I’m honoured to join L&C Mortgages, which has a longstanding reputation for excellence and innovation in the mortgage market.
Gale said: “This is a hugely exciting time for Catalyst.
“As we navigate through these changing times, there’s an increasing awareness of the importance of member-owned organisations with their clear social purpose, strong community connections, and unwavering commitment to serving their members’ needs rather than external shareholders.”
“I’m excited to help shape the next chapter of its growth and look forward to working alongside such a talented leadership team.
“I’m excited to help shape the next chapter of its growth and look forward to working alongside such a talented leadership team.
Pete Ball, CEO at Foundation Home Loans, said: “Everyone at Foundation Home Loans is very pleased to be welcoming Alan to the business.
Domanski said: “We know the difference mutuals bring to their members and communities.
“My focus will be on process optimisation to further enhance the experience for our customers and deliver forwardthinking solutions to keep L&C at the forefront of the industry.”
Bringing in Gemma, Tim, Tony, and Andy gives us a powerhouse of experience, regional strength, and ambition. Each of them brings something unique to our growth journey, but what unites them is their drive to support brokers and deliver outstanding service.
Gale said: “This is a hugely exciting time for Catalyst. Bringing in Gemma, Tim, Tony, and Andy gives us a powerhouse of experience, regional strength, and ambition. Each of them brings something unique to our growth journey, but what unites them is their drive to support brokers and deliver outstanding service.
“His deep understanding of the specialist lending market and strong track record in building commercial growth will be invaluable."
“My focus will be on process optimisation to further enhance the experience for our customers and deliver forwardthinking solutions to keep L&C at the forefront of the industry.”



“Our member-owner structure means we can reinvest our surplus into be er returns for members, a diverse range of products and keeping local branches open, rather than being hived off to external shareholders.
incredible momentum, and reflect commitment to continued growth, our customers and
these appointments reflect our stronger broker relationships, and our reach and support for the experience for deliver forward-
“Catalyst is in a period of incredible momentum, and these appointments reflect our commitment to continued growth, stronger broker relationships, and even be er national coverage.
“Catalyst is in a period of incredible momentum, and these appointments reflect our commitment to continued growth, stronger broker relationships, and even be er national coverage.

“With this team in place, our reach and support for brokers across the UK has never been stronger.”
“It is great to see building societies and credit unions working together to double the sector as we support fair and inclusive growth across the UK.”
“With this team in place, our reach and support for brokers across the UK has never been stronger.”