
Sample Read
© Taxmann
Price : ` 1995
Law stated in this book is as amended by the Finance Act, 2026
Published by : Taxmann Publications (P.) Ltd.
Sales & Marketing :
59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser.
All disputes are subject to Delhi jurisdiction only.
CHAPTER V INPUT TAX CREDIT
Eligibility and condition for taking input tax credit.77
7816.79 (1) Every registered person shall, subject to such conditions and restrictions as may be prescribed and in the manner specified in section 49, be entitled to take credit of input tax charged on any supply of goods or services or both to him which are used or intended to be used in the course or furtherance of his business and the said amount shall be credited to the electronic credit ledger of such person.
(2)Notwithstanding anything contained in this section, no registered person shall be entitled to the credit of any input tax in respect of any supply of goods or services or both to him unless,—
(a) he is in possession of a tax invoice or debit note issued by a supplier registered under this Act, or such other tax paying documents as may be prescribed;
80[( aa)the details of the invoice or debit note referred to in clause (a) has been furnished by the supplier in the statement of outward supplies and such details have been communicated to the recipient of such invoice or debit note in the manner specified under section 37;]
(b)he has received the goods or services or both.
81[Explanation.—For the purposes of this clause, it shall be deemed that the registered person has received the goods or, as the case may be, services—
(i)where the goods are delivered by the supplier to a recipient or any other person on the direction of such registered person, whether acting as an agent or otherwise, before or during movement of goods, either by way of transfer of documents of title to goods or otherwise;
77. See rules 36 and 37 of the CGST Rules, 2017.
78.Enforced with effect from 1-7-2017.
79.For notified rate of tax to be levied on specified first intra-State supplies of goods or services, see Notification No. 2/2019-Central Tax (Rate), dated 7-3-2019 and Notification No. 2/2019Union Territory Tax (Rate), dated 7-3-2019.
For notified classes of registered persons in whose case liability shall arise on specified date, see Notification No. 6/2019-Central Tax (Rate), dated 29-3-2019.
80.Inserted by the Finance Act, 2021, w.e.f. 1-1-2022.
81.Substituted by the Central Goods and Services Tax (Amendment) Act, 2018, w.e.f. 1-2-2019. Prior to its substitution, Explanation read as under :
“Explanation.—For the purposes of this clause, it shall be deemed that the registered person has received the goods where the goods are delivered by the supplier to a recipient or any other person on the direction of such registered person, whether acting as an agent or otherwise, before or during movement of goods, either by way of transfer of documents of title to goods or otherwise;”
(ii)where the services are provided by the supplier to any person on the direction of and on account of such registered person.]
82[(ba)the details of input tax credit in respect of the said supply communicated to such registered person under section 38 has not been restricted;]
(
c)subject to the provisions of 83[section 41 84[***]], the tax charged in respect of such supply has been actually paid to the Government, either in cash or through utilisation of input tax credit admissible in respect of the said supply; and
(
d)he has furnished the return under section 39:
Provided that where the goods against an invoice are received in lots or instalments, the registered person shall be entitled to take credit upon receipt of the last lot or instalment:
Provided further that where a recipient fails to pay to the supplier of goods or services or both, other than the supplies on which tax is payable on reverse charge basis, the amount towards the value of supply along with tax payable thereon within a period of one hundred and eighty days from the date of issue of invoice by the supplier, an amount equal to the input tax credit availed by the recipient shall be 85[paid by him along with interest payable under section 50], in such manner as may be prescribed:
Provided also that the recipient shall be entitled to avail of the credit of input tax on payment made by him 86[to the supplier] of the amount towards the value of supply of goods or services or both along with tax payable thereon.
(3) Where the registered person has claimed depreciation on the tax component of the cost of capital goods and plant and machinery under the provisions of the Income-tax Act, 1961 (43 of 1961), the input tax credit on the said tax component shall not be allowed.
(4) A registered person shall not be entitled to take input tax credit in respect of any invoice or debit note for supply of goods or services or both after the 87[thirtieth day of November] following the end of financial year to which such invoice or 88[***] debit note pertains or furnishing of the relevant annual return, whichever is earlier:
82.Inserted by the Finance Act, 2022, w.e.f. 1-10-2022.
83.Substituted for “section 41” by the Central Goods and Services Tax (Amendment) Act, 2018, with effect from a date yet to be notified.
84.Words “or section 43A” omitted by the Finance Act, 2022, w.e.f. 1-10-2022.
85.Substituted for “added to his output tax liability, along with interest thereon” by the Finance Act, 2023, w.e.f. 1-10-2023.
86.Inserted by the Finance Act, 2023, w.e.f. 1-10-2023.
87.Substituted for “due date of furnishing of the return under section 39 for the month of September” by the Finance Act, 2022, w.e.f. 1-10-2022.
88.Words “invoice relating to such” omitted by the Finance Act, 2020, w.e.f. 1-1-2021.
89[Provided that the registered person shall be entitled to take input tax credit after the due date of furnishing of the return under section 39 for the month of September, 2018 till the due date of furnishing of the return under the said section for the month of March, 2019 in respect of any invoice or invoice relating to such debit note for supply of goods or services or both made during the financial year 2017-18, the details of which have been uploaded by the supplier under sub-section (1) of section 37 till the due date for furnishing the details under sub-section (1) of said section for the month of March, 2019.]
89a[(5) Notwithstanding anything contained in sub-section (4), in respect of an invoice or debit note for supply of goods or services or both pertaining to the Financial Years 2017-18, 2018-19, 2019-20 and 2020-21, the registered person shall be entitled to take input tax credit in any return under section 39 which is filed upto the thirtieth day of November, 2021.
(6) Where registration of a registered person is cancelled under section 29 and subsequently the cancellation of registration is revoked by any order, either under section 30 or pursuant to any order made by the Appellate Authority or the Appellate Tribunal or court and where availment of input tax credit in respect of an invoice or debit note was not restricted under sub-section (4) on the date of order of cancellation of registration, the said person shall be entitled to take the input tax credit in respect of such invoice or debit note for supply of goods or services or both, in a return under section 39,––
(i)filed upto thirtieth day of November following the financial year to which such invoice or debit note pertains or furnishing of the relevant annual return, whichever is earlier; or
(ii)for the period from the date of cancellation of registration or the effective date of cancellation of registration, as the case may be, till the date of order of revocation of cancellation of registration, where such return is filed within thirty days from the date of order of revocation of cancellation of registration, whichever is later.]
Apportionment of credit and blocked credits.90
9117. (1) Where the goods or services or both are used by the registered person partly for the purpose of any business and partly for other purposes, the amount of credit shall be restricted to so much of the input tax as is attributable to the purposes of his business.
89.Inserted by the Central Goods and Services Tax (Second Removal of Difficulties) Order, 2018, w.e.f. 31-12-2018.
89a.Sub-sections (5) and (6) inserted by the Finance (No. 2) Act, 2024, w.r.e.f. 1-7-2017. [However, Notification No. 17/2024-Central Tax, dated 27-9-2024 appoints 27-9-2024 as the date of enforcement].
90. See rules 38, 42 and 43 of the CGST Rules, 2017.
91.Enforced with effect from 1-7-2017.
(2) Where the goods or services or both are used by the registered person partly for effecting taxable supplies including zero-rated supplies under this Act or under the Integrated Goods and Services Tax Act and partly for effecting exempt supplies under the said Acts, the amount of credit shall be restricted to so much of the input tax as is attributable to the said taxable supplies including zero-rated supplies.
(3) The value of exempt supply under sub-section (2) shall be such as may be prescribed, and shall include supplies on which the recipient is liable to pay tax on reverse charge basis, transactions in securities, sale of land and, subject to clause (b) of paragraph 5 of Schedule II, sale of building.
92[Explanation.—For the purposes of this sub-section, the expression “value of exempt supply” shall not include the value of activities or transactions specified in Schedule III, 93[except,—
(i)the value of activities or transactions specified in paragraph 5 of the said Schedule; and
(ii)the value of such activities or transactions as may be prescribed in respect of clause (a) of paragraph 8 of the said Schedule.]]
(4) A banking company or a financial institution including a non-banking financial company, engaged in supplying services by way of accepting deposits, extending loans or advances shall have the option to either comply with the provisions of sub-section (2), or avail of, every month, an amount equal to fifty per cent of the eligible input tax credit on inputs, capital goods and input services in that month and the rest shall lapse:
Provided that the option once exercised shall not be withdrawn during the remaining part of the financial year:
Provided further that the restriction of fifty per cent shall not apply to the tax paid on supplies made by one registered person to another registered person having the same Permanent Account Number.
(5) Notwithstanding anything contained in sub-section (1) of section 16 and sub-section (1) of section 18, input tax credit shall not be available in respect of the following, namely:—
94[( a)motor vehicles for transportation of persons having approved seating capacity of not more than thirteen persons (including the driver),
92.Inserted by the Central Goods and Services Tax (Amendment) Act, 2018, w.e.f. 1-2-2019.
93.Substituted for “except those specified in paragraph 5 of the said Schedule” by the Finance Act, 2023, w.e.f. 1-10-2023.
94.Clauses (a), (aa), (ab) and (b) substituted for clauses (a) and (b) by the Central Goods and Services Tax (Amendment) Act, 2018, w.e.f. 1-2-2019. Prior to their substitution, clauses (a) and (b) read as under :
“(a)motor vehicles and other conveyances except when they are used— (i)for making the following taxable supplies, namely:—
(A)further supply of such vehicles or conveyances; or
(Contd. on page 1.49)
except when they are used for making the following taxable supplies, namely:—
(A)further supply of such motor vehicles; or
(B)transportation of passengers; or
(C)imparting training on driving such motor vehicles;
(aa)vessels and aircraft except when they are used—
(i)for making the following taxable supplies, namely:—
(A)further supply of such vessels or aircraft; or
(B)transportation of passengers; or
(C)imparting training on navigating such vessels; or
(D)imparting training on flying such aircraft;
(ii)for transportation of goods;
(ab)services of general insurance, servicing, repair and maintenance in so far as they relate to motor vehicles, vessels or aircraft referred to in clause (a) or clause (aa):
Provided that the input tax credit in respect of such services shall be available—
(i)where the motor vehicles, vessels or aircraft referred to in clause (a) or clause (aa) are used for the purposes specified therein;
(ii)where received by a taxable person engaged—
(I)in the manufacture of such motor vehicles, vessels or aircraft; or
(Contd. from page 1.48)
(B)transportation of passengers; or
(C)imparting training on driving, flying, navigating such vehicles or conveyances;
(ii)for transportation of goods;
(b)the following supply of goods or services or both:—
(i)food and beverages, outdoor catering, beauty treatment, health services, cosmetic and plastic surgery except where an inward supply of goods or services or both of a particular category is used by a registered person for making an outward taxable supply of the same category of goods or services or both or as an element of a taxable composite or mixed supply;
(ii)membership of a club, health and fitness centre;
(iii)rent-a-cab, life insurance and health insurance except where—
(A)the Government notifies the services which are obligatory for an employer to provide to its employees under any law for the time being in force; or
(B)such inward supply of goods or services or both of a particular category is used by a registered person for making an outward taxable supply of the same category of goods or services or both or as part of a taxable composite or mixed supply; and
(iv)travel benefits extended to employees on vacation such as leave or home travel concession;”
(II )in the supply of general insurance services in respect of such motor vehicles, vessels or aircraft insured by him;
(b)the following supply of goods or services or both—
(i)food and beverages, outdoor catering, beauty treatment, health services, cosmetic and plastic surgery, leasing, renting or hiring of motor vehicles, vessels or aircraft referred to in clause (a) or clause (aa) except when used for the purposes specified therein, life insurance and health insurance:
Provided that the input tax credit in respect of such goods or services or both shall be available where an inward supply of such goods or services or both is used by a registered person for making an outward taxable supply of the same category of goods or services or both or as an element of a taxable composite or mixed supply;
(ii)membership of a club, health and fitness centre; and
(iii)travel benefits extended to employees on vacation such as leave or home travel concession:
Provided that the input tax credit in respect of such goods or services or both shall be available, where it is obligatory for an employer to provide the same to its employees under any law for the time being in force;]
(
c)works contract services when supplied for construction of an immovable property (other than plant and machinery) except where it is an input service for further supply of works contract service;
(d)goods or services or both received by a taxable person for construction of an immovable property (other than 94a[plant and machinery]) on his own account including when such goods or services or both are used in the course or furtherance of business.
Explanation 94b[1] —For the purposes of clauses (c) and (d), the expression “construction” includes re-construction, renovation, additions or alterations or repairs, to the extent of capitalisation, to the said immovable property.
94b[Explanation 2.—For the purposes of clause (d), it is hereby clarified that notwithstanding anything to the contrary contained in any judgment, decree or order of any court, tribunal, or other authority, any reference to “plant or machinery” shall be construed and shall always be deemed to have been construed as a reference to “plant and machinery”;]
(e)goods or services or both on which tax has been paid under section 10;
(f)goods or services or both received by a non-resident taxable person except on goods imported by him;
94a.Substituted for “plant or machinery” by the Finance Act, 2025, w.r.e.f. 1-7-2017 [However, Notification No. 16/2025-Central Tax appoints 1-10-2025 as the date of enforcement].
94b.Inserted by the Finance Act, 2025, w.e.f. 1-10-2025
Section 10 of the CGST Act, 2017 - Composition levyNotified rate, turnover and other conditionsSupersession of Notification No. 8/2017Central Tax, dated 27-6-2017
NOTIFICATION NO. 14/2019-CENTRAL TAX, DATED 7-3-2019, AS AMENDED BY, NOTIFICATION NOS. 43/2019-CENTRAL TAX, DATED 30-9-2019, 4/2022-CENTRAL TAX, DATED 31-3-2022 AND 16/2022-CENTRAL TAX, DATED 13-7-2022
In exercise of the powers conferred under the proviso to sub-section (1) of section 10 of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereinafter referred to as the said Act), and in supersession of the Notification No. 8/2017-Central Tax, dated the 27th June, 2017, published in the Gazette of India, Extraordinary, Part II, Section 3, Sub-section (i), vide number G.S.R. 647(E), dated the 27th June, 2017, except as things done or omitted to be done before such supersession, the Central Government, on the recommendations of the Council, hereby specifies that an eligible registered person, whose aggregate turnover in the preceding financial year did not exceed one crore and fifty lakh rupees, may opt to pay, in lieu of the tax payable by him under subsection (1) of section 9 of the said Act, an amount of tax as prescribed under rule 7 of the Central Goods and Services Tax Rules, 2017:
Provided that the said aggregate turnover in the preceding financial year shall be seventy-five lakh rupees in the case of an eligible registered person, registered under section 25 of the said Act, in any of the following States, namely: —
(i) Arunachal Pradesh,
(ii) Manipur,
(iii) Meghalaya,
(iv) Mizoram,
(v) Nagaland,
(vi) Sikkim,
(vii) Tripura,
(viii) Uttarakhand:
Provided further that the registered person shall not be eligible to opt for composition levy under sub-section (1) of section 10 of the said Act if such person is a manufacturer of the goods, the description of which is specified in column (3) of the Table below and falling under the tariff item, sub-heading, heading or Chapter, as the case may be, as specified in the corresponding entry in column (2) of the said Table, namely:—
TABLE
Sl. No.Tariff item, sub-heading, heading or Chapter Description (1)(2)(3)
1.2105 00 00Ice cream and other edible ice, whether or not containing cocoa.
2.2106 90 20Pan masala.
1[2A.2202 10 10Aerated Water.]
3.24All goods, i.e. Tobacco and manufactured tobacco substitutes.
2[46815 3[Fly ash bricks; Fly ash aggregates; Fly ash blocks]
56901 00 10Bricks of fossil meals or similar siliceous earths
66904 10 00Building bricks
76905 10 00Earthen or roofing tiles]
Explanation.—
(i) In this Table, “tariff item”, “sub-heading”, “heading” and “chapter” shall mean respectively a tariff item, sub-heading, heading and chapters as specified in the First Schedule to the Customs Tariff Act, 1975 (51 of 1975).
(ii) The rules for the interpretation of the First Schedule to the said Customs Tariff Act, 1975 (51 of 1975), including the Section and Chapter Notes and the General Explanatory Notes of the First Schedule shall, so far as may be, apply to the interpretation of this notification.
2. This notification shall come into force on the 1st day of April, 2019.
Note : Central Goods and Services Tax (Removal of Difficulties) Order, 2019 provides that the value of supply of exempt services by way of extending deposits, loans or advances in so far as the consideration is represented by way of interest or discount, shall not be taken into account—
(i) for determining the eligibility for composition scheme under second proviso to subsection (1) of section 10;
(ii) in computing aggregate turnover in order to determine eligibility for composition scheme.
1. Inserted by Notification No. 43/2019-Central Tax, dated 30-9-2019, w.e.f. 1-10-2019.
2. Inserted by Notification No. 4/2022-Central Tax, dated 31-3-2022, w.e.f. 1-4-2022.
3. Substituted for “Fly ash bricks or fly ash aggregate with 90 per cent or more fly ash content; Fly ash blocks” by Notification No. 16/2022-Central Tax, dated 13-7-2022, w.e.f. 18-7-2022.
Section 10, read with section 148, of the CGST Act, 2017Composition levy - Notified class of registered persons who shall follow special procedure for furnishing of return and payment of tax
NOTIFICATION NO. 21/2019-CENTRAL TAX, DATED 23-4-2019, AS AMENDED BY, NOTIFICATION NOS. 34/2019-CENTRAL TAX, DATED 18-7-2019, 35/2019-CENTRAL TAX, DATED 29-7-2019, 50/2019-CENTRAL TAX, DATED 24-10-2019, 12/2020-CENTRAL TAX, DATED 21-3-2020, 34/2020-CENTRAL TAX, DATED 3-4-2020, 59/2020-CENTRAL TAX, DATED 13-7-2020, 64/2020-CENTRAL TAX, DATED 31-8-2020, 10/2021CENTRAL TAX, DATED 1-5-2021, 25/2021-CENTRAL TAX, DATED 1-6-2021 AND 11/2022-CENTRAL TAX, DATED 5-7-2022
In exercise of the powers conferred by section 148 of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereafter in this notification referred to as the said Act), the Central Government, on the recommendations of the Council, hereby notifies the registered persons paying tax under the provisions of section 10 of the said Act or by availing the benefit of notification of the Government of India, Ministry of Finance, Department of Revenue No. 2/2019-Central Tax (Rate), dated the 7th March, 2019, published in the Gazette of India, Extraordinary, Part II, Section 3, Sub-section (i) vide number G.S.R. 189, dated the 7th March, 2019, (hereinafter referred to as “the said notification”) as the class of registered persons who shall follow the special procedure as mentioned below for furnishing of return and payment of tax.
2. The said persons shall furnish a statement, every quarter or, as the case may be, part thereof containing the details of payment of self-assessed tax in FORM GST CMP-08 of the Central Goods and Services Tax Rules, 2017, till the 18th day of the month succeeding such quarter:
1[Provided that the due date for furnishing the statement containing the details of payment of self-assessed tax in said FORM GST CMP-08, for the quarter April, 2019 to June, 2019, or part thereof, shall be the 2[31st day of August, 2019]:]
3[Provided further that the due date for furnishing the statement containing the details of payment of self-assessed tax in said FORM GST CMP-08, for the quarter July, 2019 to September, 2019, or part thereof, shall be the 22nd day of October, 2019:]
1. Inserted by Notification No. 34/2019-Central Tax, dated 18-7-2019, w.e.f. 18-7-2019.
2. Substituted for “31st day of July, 2019” by Notification No. 35/2019-Central Tax, dated 29-7-2019, w.e.f. 29-7-2019.
3. Inserted by Notification No. 50/2019-Central Tax, dated 24-10-2019, w.r.e.f. 18-10-2019.
1[Provided that the said persons who have, instead of furnishing the statement containing the details of payment of self-assessed tax in FORM GST CMP-08 have furnished a return in FORM GSTR-3B under the Central Goods and Services Tax Rules, 2017 (hereinafter referred to as the said rules) for the tax periods in the financial year 2019-20, such taxpayers shall not be required to furnish the statement in outward supply of goods or services or both in FORM GSTR-1 of the said rules or the statement containing the details of payment of self-assessed tax in FORM GST CMP-08 for all the tax periods in the financial year 2019-20:]
2[Provided that the said persons shall furnish a statement, containing the details of payment of self-assessed tax in FORM GST CMP-08 of the Central Goods and Services Tax Rules, 2017, for the quarter ending 31st March, 2020, till the 7th day of July, 2020:]
3[Provided also that the said persons shall furnish a statement, containing the details of payment of self-assessed tax in FORM GST CMP-08 of the Central Goods and Services Tax Rules, 2017 for the quarter ending 30th June, 2022 till the 31st day of July, 2022.]
3. The said persons shall furnish a return for every financial year or, as the case may be, part thereof in FORM GSTR-4 of the Central Goods and Services Tax Rules, 2017, on or before the 30th day of April following the end of such financial year:
4[Provided that the said persons shall furnish the return in FORM GSTR-4 of the Central Goods and Services Tax Rules, 2017, for the financial year ending 31st March, 2020, till the 5[31st day of October, 2020]:]
6[Provided further that the said persons shall furnish the return in FORM GSTR-4 of the Central Goods and Services Tax Rules, 2017, for the financial year ending 31st March, 2021, upto the 7[31st day of July, 2021] ]
4. The registered persons paying tax by availing the benefit of the said notification, in respect of the period for which he has availed the said benefit, shall be deemed to have complied with the provisions of section 37 and section 39 of the said Act if they have furnished FORM GST CMP-08 and FORM GSTR-4 as provided in para 2 and para 3 above.
1. Inserted by Notification No. 12/2020-Central Tax, dated 21-3-2020, w.e.f. 21-3-2020.
2. Inserted by Notification No. 34/2020-Central Tax, dated 3-4-2020, w.e.f. 3-4-2020.
3. Inserted by Notification No. 11/2022-Central Tax, dated 5-7-2022, w.e.f. 5-7-2022.
4. Inserted by Notification No. 34/2020-Central Tax, dated 3-4-2020, w.e.f. 3-4-2020.
5. Substituted for “31st day of August, 2020” by Notification No. 64/2020-Central Tax, dated 31-8-2020, w.e.f. 31-8-2020. Earlier, the quoted words were substituted for “15th day of July, 2020” by Notification No. 59/2020-Central Tax, dated 13-7-2020, w.e.f. 13-7-2020.
6. Inserted by Notification No. 10/2021-Central Tax, dated 1-5-2021, w.r.e.f. 30-4-2021.
7. Substituted for “31st day of May, 2021” by Notification No. 25/2021-Central Tax, dated 1-6-2021, w.r.e.f. 31-5-2021.
Section 148 and section 24 of the CGST Act, 2017, read with rule 14 of the CGST Rules, 2017 - Certain Processes - Special procedure for - Notified registered persons who shall follow special procedure for furnishing details of supplying online information and data base access or retrieval services from a place outside India to a person in India
NOTIFICATION NO. 30/2019-CENTRAL TAX, DATED 28-6-2019
In exercise of the powers conferred by section 148 of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereinafter referred to as “the said Act”), the Central Government, on the recommendations of the Council, hereby notifies the persons registered under section 24 of the said Act read with rule 14 of the Central Goods and Services Tax Rules, 2017, (hereinafter referred to as “the said rules”), supplying online information and data base access or retrieval services from a place outside India to a person in India, other than a registered person as the class of registered persons who shall follow the special procedure as mentioned below.
2. The said persons shall not be required to furnish an annual return in FORM GSTR-9 under sub-section (1) of section 44 of the said Act read with sub-rule (1) of rule 80 of the said rules.
3. The said persons shall not be required to furnish reconciliation statement in FORM GSTR-9C under sub-section (2) of section 44 of the said Act read with sub-rule (3) of rule 80 of the said rules. 27
Section 47, read with section 128, of the CGST Act, 2017Returns - Levy of late fee - Waiver of late fee payable by specified classes of taxpayers
NOTIFICATION NO. 41/2019-CENTRAL TAX, DATED 31-8-2019, AS AMENDED BY, NOTIFICATION NO. 48/2019-CENTRAL TAX, DATED 9-10-2019
In exercise of the powers conferred by section 128 of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereafter in this notification referred to as the said Act), the Central Government, on the recommendations of the Council, hereby waives the amount of late fee payable under section 47 of the said Act, by the following class of taxpayers:—
(i) the registered persons whose principal place of business is in the district mentioned in column (3) of the Table below, of the State as mentioned in column (2) of the said Table, having aggregate turnover of more than 1.5 crore rupees in the preceding financial year or the current financial year, who have furnished, electronically through the common portal, details of outward supplies in FORM GSTR-1 of the Central Goods and Services Tax Rules, 2017, for the month of July, 2019, on or before the 20th September, 2019;
(ii) the registered persons whose principal place of business is in the *State of Jammu and Kashmir, having aggregate turnover of more than 1.5 crore rupees in the preceding financial year or the current financial year, who have furnished, electronically through the common portal, details of outward supplies in FORM GSTR-1 of the Central Goods and Services Tax Rules, 2017, for the month of July, 2019, on or before the 1[11th October], 2019;
(
iii) the Input Service Distributors whose principal place of business is in the district mentioned in column (3) of the above said Table, of the State as mentioned in column (2) of the said Table, who have furnished, electronically through the common portal, return in FORM GSTR-6 of the Central Goods and Services Tax Rules, 2017, for the month of July, 2019, on or before the 20th September, 2019;
(
iv) the Input Service Distributors whose principal place of business is in the *State of Jammu and Kashmir, who have furnished, electronically through the common portal, return in FORM GSTR-6 of the Central Goods and Services Tax Rules, 2017, for the month of July, 2019, on or before the 20th September, 2019;
2[(v) the registered persons whose principal place of business is in the *State of Jammu and Kashmir, having aggregate turnover of more than 1.5 crore rupees in the preceding financial year or the current financial year, who have furnished, electronically through the common portal, details of outward supplies in FORM GSTR-1 of the Central Goods and Services Tax Rules, 2017 (hereafter referred to as the said rules), for the month of August, 2019, on or before the 11th October, 2019, for failure to furnish the said FORM GSTR-1 by the due date;
(
vi) the registered persons whose principal place of business is in the *State of Jammu and Kashmir, required to deduct tax at source under the provisions of section 51 of the said Act, who have furnished
*Be read as ‘Union Territory’.
1. Substituted for “20th September” by Notification No. 48/2019-Central Tax, dated 9-10-2019, w.e.f. 9-10-2019.
2. Inserted, ibid.
CENTRAL GOODS AND SERVICES TAX RULES, 2017
NOTIFICATION NO. 3/2017-CENTRAL TAX, DATED 19-6-2017
In exercise of the powers conferred by section 164 of the Central Goods and Services Tax Act, 2017 (12 of 2017), the Central Government hereby makes the following rules, namely:—
CHAPTER I PRELIMINARY
Short title and commencement
1. Definitions 2.
Effective date for composition levy 4.
Conditions and restrictions for composition levy 5.
Validity of composition levy
Rate of tax of the composition levy
Sl. No. Section under which composition levy is opted
Category of registered persons Rate of tax (1)(1A)(2)(3)
CHAPTER III REGISTRATION
Application for registration
8. i ii
See See (Contd. on page 6.28)
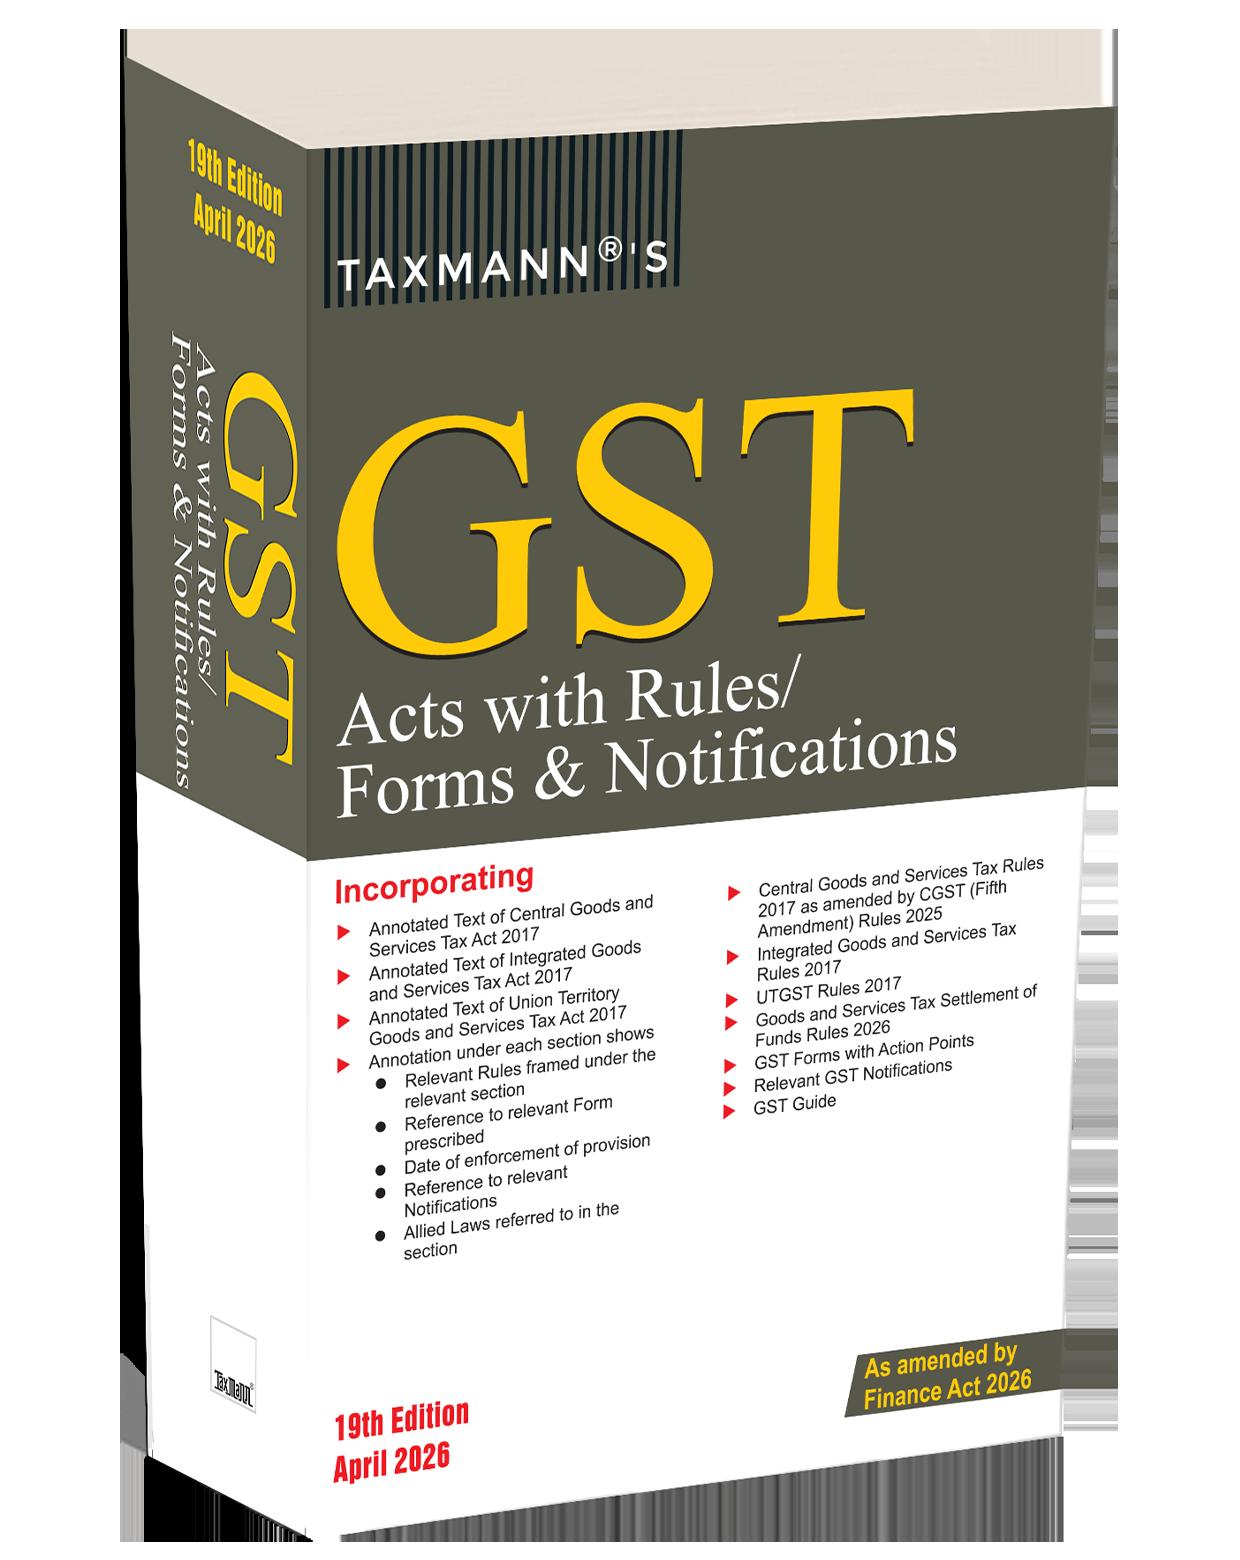
GST Acts with Rules/Forms & Notifications
AUTHOR : Taxmann’s Editorial Board
PUBLISHER : Taxmann
DATE OF PUBLICATION : April 2026
EDITION : 19th Edition | April 2026
ISBN NO : 9789375612384
No. of Pages : 1664
BINDING TYPE : Paperback
Rs. 1,995
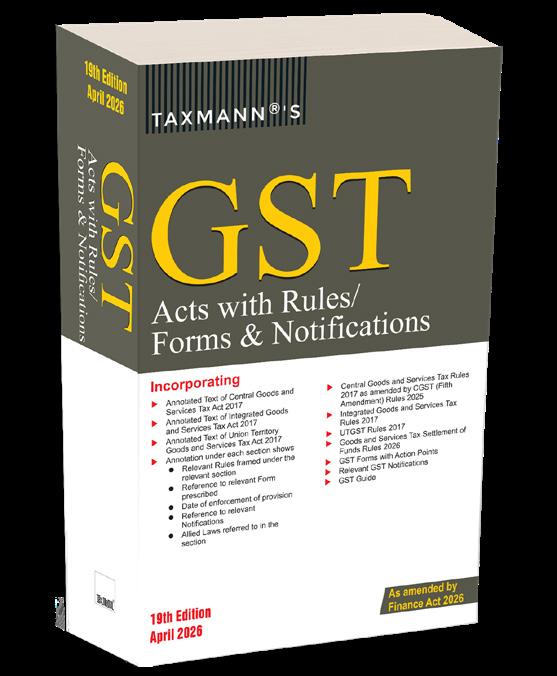
DESCRIPTION
GST Acts with Rules/Forms & Notifications is Taxmann’s flagship section-wise compendium of the complete statutory framework governing GST in India. The publication consolidates the annotated text of all four parent GST enactments—the CGST Act 2017, the IGST Act 2017, the UTGST Act 2017, and the GST (Compensation to States) Act 2017—together with every rule, form, and notification required to interpret, administer, and comply with the law.
The law stated in this Edition is as amended by the Finance Act 2026 and incorporates the ‘Gen 2’ rate restructuring effective from 22nd September 2025 (Nil/5%/18%/40% with special rates of 0.25% and 1.5%), the abolition of the GST Compensation Cess w.e.f. 1st February 2026, and the parallel duties on tobacco and pan masala under the Central Excise (Amendment) Act 2025 and the Health Security se National Security Cess Act 2025. Every section includes a consolidated annotation block that points to the corresponding rule, form, notification, date of enforcement, and allied statutory provision—eliminating the need to consult multiple publications during drafting, compliance, adjudication, or advisory work.
The volume is directed at practitioners who require the complete, unabridged statutory text—not a commentary or digest—in a single authoritative reference. The primary readership includes: This book is intended for the following audience:
• Chartered Accountants, Company Secretaries, and Cost and Management Accountants
• Advocates and Tax Counsel
• In-House Tax and Indirect Tax Teams
• Officers of the Central Board of Indirect Taxes and Customs (CBIC) and State GST Departments
• Academicians and Students
• Researchers, Judicial Officers, and Members of Tribunals
The Present Publication is the 19th Edition | 2026, as amended by the Finance Act 2026, incorporating the CGST (Fifth Amendment) Rules 2025 and all notifications issued to date. This book is edited by Taxmann’s Editorial Board and features the following noteworthy features:
• [Annotated Section-wise Architecture] Each section of the CGST, IGST, and UTGST Acts carries an annotation block identifying the relevant rule, form, notification, date of enforcement, and allied law
• [Complete Statutory Coverage] All four parent Acts, all rules, all forms, and all subsisting notifications (including rate notifications) consolidated in a single volume
• [Finance Act 2026 Amendments] Amendments to sections 15(3)(b), 34(1), 54(3), 54(14), and 101A of the CGST Act and section 13(2) of the IGST Act fully incorporated
• [Gen 2 Rate Restructuring] Rationalised rate structure w.e.f. 22nd September 2025 (Nil/5%/18%/40% with special rates of 0.25% and 1.5%) and abolition of the GST Compensation Cess w.e.f. 1st February 2026
• [Special Regime for Tobacco Products] RSP-based valuation under rule 31D, capacity-based levy under the HSNS Cess Act 2025, enhanced NCCD rates, and export restrictions for pan masala, cigarettes, and specified tobacco products
• [Settlement of Funds Rules 2026] Newly notified GST Settlement of Funds Rules 2026 included
• [CGST (Fifth Amendment) Rules 2025] Latest rule-level amendments and consequential changes to forms and procedural provisions incorporated
• [GST Forms with Action Points] Forms indexed with ‘Action Points’ indicating the compliance triggered by each prescribed form
• [GST Appellate Tribunal Framework] Full text of the GSTAT (Procedure) Rules 2025, GSTAT (Appointment and Conditions of Service) Rules 2023, the Tribunals Reforms Act 2021, and the Tribunal (Conditions of Service) Rules 2021
• [Subject-wise Index] Concept-level look-up appended at the close of each Division
• [Appendix of Allied Statutory Provisions] Text of allied laws (Customs Act 1962, Central Excise Act 1944, Income-tax Act 1961, and others) cross-referred to in the CGST Act
• [Validation Provisions and Removal of Difficulties Order] Validation Provisions of each Act and the CGST (Removal of Difficulties) Order 2020 reproduced in full
• [Guide to GST] Opening section summarising the legislative scheme, rate structure, and year-on-year amendments