
Sample Read
© Taxmann
Price : ` 2495
All available amendments notified upto 31st March, 2026 in Income-tax Rules, 1962 and Income-tax Rules, 2026 have been incorporated
Published by :
Taxmann Publications (P.) Ltd.
Sales & Marketing :
59/32, New Rohtak Road, New Delhi-110 005 India
Phone : +91-11-45562222
Website : www.taxmann.com
E-mail : sales@taxmann.com
Regd. Office :
21/35, West Punjabi Bagh, New Delhi-110 026 India
Printed at :
Tan Prints (India) Pvt. Ltd.
44 Km. Mile Stone, National Highway, Rohtak Road Village Rohad, Distt. Jhajjar (Haryana) India
E-mail : sales@tanprints.com
Disclaimer
Every effort has been made to avoid errors or omissions in this publication. In spite of this, errors may creep in. Any mistake, error or discrepancy noted may be brought to our notice which shall be taken care of in the next edition. It is notified that neither the publisher nor the author or seller will be responsible for any damage or loss of action to any one, of any kind, in any manner, therefrom. It is suggested that to avoid any doubt the reader should cross-check all the facts, law and contents of the publication with original Government publication or notifications.
No part of this book may be reproduced or copied in any form or by any means [graphic, electronic or mechanical, including photocopying, recording, taping, or information retrieval systems] or reproduced on any disc, tape, perforated media or other information storage device, etc., without the written permission of the publishers. Breach of this condition is liable for legal action.
For binding mistake, misprints or for missing pages, etc., the publisher’s liability is limited to replacement within seven days of purchase by similar edition. All expenses in this connection are to be borne by the purchaser. All disputes are subject to Delhi jurisdiction only.
CONTENTS
Table showing Rules of Income-tax Rules, 1962 and corresponding Rules of Income-tax Rules, 2026
Table showing Rules of Income-tax Rules, 2026 and corresponding Rules of Income-tax Rules, 1962
Table showing Forms of Income-tax Rules, 1962 and corresponding Forms of Income-tax Rules, 2026
Table showing Forms of Income-tax Rules, 2026 and corresponding Forms of Income-tax Rules, 1962
Provisions of (A) Income-tax Act, 1961 which are now incorporated in Income-tax Rules, 2026 & (B) Income-tax Act, 2025 which are replicated in Income-tax Rules, 2026
Provisions of the Income-tax Rules, 2026 in respect of which there are no corresponding provisions in the Income-tax Rules, 1962
3CSalary income for the purposes of item (c) of sub-clause (iii) of clause (2) of section 17 of the Act
3DGross total income for the purposes of clause (vi) of Proviso to clause (2) of section 17 of
of
5CGuidelines, form and manner in respect of approval under clause (ii) and clause (iii) of sub-section (1) of section 35
5DConditions subject to which approval is to be granted to a research association under clause (ii) or clause (iii) of sub-section (1) of section 35
5EConditions subject to which approval is
to a University, College or other Institution under clause (ii) and clause (iii) of sub-section (1) of section 35
5FPrescribed authority, guidelines, form, manner and conditions for approval under clause (iia) of sub-section (1) of section 35
6ABA Computation of aggregate average advances for the purposes of clause (viia) of sub-section (1) of section 36
6ABAAInfrastructure facility under clause (g) of the Explanation to clause (viii) of sub-section (1) of section 36
6DDCases and circumstances in which a payment or aggregate of payments exceeding ten thousand rupees may be made to a person in a day, otherwise than by an account payee cheque drawn on a bank or account payee bank draft or use of electronic clearing system through a bank account or through such other electronic mode as prescribed in rule 6ABBA
6DDAConditions that a stock exchange is required to fulfil to be notified as a recognised stock exchange for the purposes of clause (d) of proviso to clause (5) of section 43
6DDB Notification of a recognised
exchange for the purposes of clause (d) of
of section
of bad or doubtful debts in the case of a public company under clause (b) of section 43D
6FBooks of account and other documents to be kept and maintained under section 44AA(3) by persons carrying on certain professions
6GReport
of particulars to be furnished along with return of income for claiming deduction under clause (b) of sub-section (1B) of section 10A
of option, etc., under Explanation 3 to the third proviso to clause (23C) of section 10 or section 11
authority for approval of a University or any educational institution of national eminence for the purpose of section 80G
18AAAAAGuidelines for specifying an association or institution for the purposes of notification under clause (c) of sub-section (2) of section 80G
18ABFurnishing of statement of particulars and certificate under clause (viii) and clause (ix) of sub-section (5) of section 80G or under sub-section (1A) of section 35
of audit report for claiming deduction under section 80-I or 80-IA or 80-IB or section 80-IC
authority for purposes of sub-section (2) of section
(2)
21AC Furnishing of authorisation and
etc., for the purposes of section 94A
21ACAConditions and activities for the Finance Company located in any International Financial Services Centre for section 94B
21AIComputation of exempt income of specified fund for the purposes of clause (4D) of section 10
21AIAOther conditions required to be fulfilled by a specified fund referred to in clause (4D) of section 10 of the Act
21AJDetermination of income of a specified fund attributable to units held by non-residents under sub-section (1A) of section 115AD
Computation of exempt income of specified fund, attributable to the investment division of an offshore banking unit, for the purposes of clause (4D) of section 10 of the Act
21AJAADetermination of income of a specified fund attributable to the investment division of an offshore banking unit under sub-section (1B) of section 115AD of the Act
29AForm of certificate to be furnished along with the return of income under sub-section (4) of section 80QQB, sections 80R, 80RR and 80RRA, and sub-section (3) of section 80RRB and the prescribed authority for the purposes of sub-section (4) of section 80QQB and sub-section (3) of section 80RRB
29BAApplication for grant of certificate for determination of appropriate proportion of sum (other than Salary), payable to non-resident, chargeable in case of the recipients
29CDeclaration by person claiming receipt of
30Time and mode of payment to Government account of tax deducted at source or tax paid under sub-section (1A) of section 192
31AAStatement
44FAForm and manner of filing appeal to the High Court on ruling pronounced or order passed by the Board for Advance Rulings under sub-section (1) of section 245W
44GApplication seeking to give effect to the terms of any agreement under clause (h) of sub-section (2) of section 295 and the procedure for giving effect to the decision under the Agreement
46AProduction
47Form
of making permanent account number
or classes of person to whom
139A
114BTransactions in relation to which permanent account number is to be quoted in all documents for the purpose of clause (c) of sub-section (5) of section 139A
for the purposes of clause (vii) of sub-section (1) of section 139A
for the purposes of sub-section (6A) of section 139A and prescribed person for the purposes of clause (ab) of Explanation to section 139A
and manner in which persons referred to in rule 114C shall furnish a statement containing particulars of Form No.
115ARate of exchange for conversion of rupees into foreign currency and reconversion of foreign currency into rupees for the purpose of computation of capital gains under the proviso to clause (a) of sub-section (1) of section 48 of the Income-tax Act, 1961
121AForm of statement to be furnished by producers of cinematograph films or persons engaged in specified activity
R.12AC OF 1962 RULES v. R. 165 OF 2026 RULES 378
Rule 12AC of the 1962 Rules : Updated return of income/Rule 165 of the 2026 Rules : Furnishing of updated return of income under section 263(6) read with sub-section (2) of said section
CORRESPONDING PROVISION
u Rule 12AC of the 1962 Rules corresponds to rule 165 of the 2026 Rules as under:— 1962 Rules 2026 Rules
Rule 12AC(1)
Rule 12AC(2) & its Table
Rule 12AC(2), Explanation
Rule 12AC(3)
TEXTUAL COMPARISON
Rule 12AC of the 1962 Rules : Updated return of income
(1)The return of income to be furnished by any person, eligible to file such return under sub-section (8A) of section 139, relating to the assessment year commencing on the 1st day of April, 2020 and subsequent assessment years, shall be in the Form ITR-U and be verified in the manner indicated therein.
(2) The return of income referred to in sub-rule (1) shall be furnished by a person, mentioned in column (2)of the Table below in the manner specified in column (3) thereof:––
Sl. No. Person Manner of furnishing return of income (1) (2) (3)
1. Individual, or Hindu undivided family or a firm or limited liability partnership or an association of persons or a body of individuals, whether incorporated or not, or a local authority or an artificial juridical person in whose case accounts are required to be audited under section 44AB of the Act or a Company or a political party required to furnish a return in Form ITR-7.
2. Individual, or Hindu undivided family, or firm, or limited liability partnership, or an association of persons or a body of individuals, whether incorporated or not, or a local authority or an artificial juridical person, or a person required to file a return under sub-section (4A) or sub-section (4B) or
Electronically under digital signature.
Rule 165(1)
Rule 165(2) & its Table
Rule 165(3)
(A) Electronically under digital signature;
(B) Transmitting the data electronically in the return under electronic verification code.
Rule 165 of the 2026 Rules : Furnishing of updated return of income under section 263(6) read with sub-section (2) of said section
R.165(1) The return of income to be furnished by any person, eligible to file such return under section 263(6), shall be in the Form ITR-UN and be verified in the manner indicated therein.
R.165(2) & its Table
ITR-UN shall be furnished by a person mentioned in column 2 of the following Table in the manner specified in column 3 thereof: —
TABLE
Sl. No. Person Manner of furnishing return of income 1 2 3
1. Company Electronically under digital signature.
2. Any person whose accounts are required to be audited under section 63
3. Any person other than person referred 1 in Sl. Nos. 1 & 2
(a) Electronically under digital signature; or
(b) transmitting the data electronically in the return under electronic verification code.
(a) Electronically under digital signature; or
(b) transmitting the data electronically in the return under electronic verification code; or
Rule 12AC of the 1962 Rules : Updated return of income
Manner of furnishing return of income
(1) (2) (3)
sub-section (4C) or sub-section (4D) of section 139, other than a person mentioned in column (2) of Sl. No. (1) above.
Explanation For the purposes of this sub-rule, “electronic verification code” means a code generated for the purpose of electronic verification of the person furnishing the return of income as per the data structure and standards specified by Principal Director General of Income-tax (Systems) or Director General of Income-tax (Systems).
(3) The Principal Director General of Income-tax (Systems) or Director General of Income-tax (Systems) shall specify the procedures, formats and standards for ensuring secure capture and transmission of data and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to furnishing the return in the manners specified in column (3) of the Table.
Rule 165 of the 2026 Rules : Furnishing of updated return of income under section 263(6) read with sub-section (2) of said section
Manner of furnishing return of income
1 2 3 (c) transmitting the data in the return electronically and thereafter submitting the verification of the return in Form ITR-V.
R. 165(3) For the purposes of sub-rule (2), the expression “electronic verification code” means a code generated for the purpose of electronic verification of the person furnishing the return of income as per the data structure and standards specified by the Principal Director General of Income-tax (Systems) or Director General of Income-tax (Systems).
Rule 12AD of the 1962 Rules : Return of income under section 170A/Rule 177 of the 2026 Rules : Modified return of income in respect of business reorganisation under section 314
CORRESPONDING PROVISION
u Rule 12AD of the 1962 Rules corresponds to rule 177 of the 2026 Rules as under:— 1962 Rules 2026 Rules
Rule 12AD(1) Rule 177(1)
Rule 12AD(2) Rule 177(2)
Rule 12AD(3) Rule 177(3)
Rule 12AD(4)
TEXTUAL COMPARISON
Rule 12AD of the 1962 Rules : Return of income under section 170A
(1) The modified return of income to be furnished by a successor entity to a business reorganisation, as referred to in section 170A, for an assessment year,
Rule 177 of the 2026 Rules : Modified return of income in respect of business reorganisation under section 314
R. 177(1) The modified return of income to be furnished by a successor entity to a business reorganisation, as referred to in section
Rule 12AD of the 1962 Rules : Return of income under section 170A
Rule 177 of the 2026 Rules : Modified return of income in respect of business reorganisation under section 314 shall be in the Form ITR-A and verified in the manner specified therein. 314, for a tax year, shall be in the Form ITR-A and verified in the manner specified therein.
(2) The return of income referred to in sub-rule (1) shall be furnished electronically under digital signature.
(3) If the assessment or reassessment proceedings for an assessment year relevant to a previous year to which the order of the business reorganisation applies have been completed or are pending on the date of furnishing of the modified return in accordance with the provisions of section 170A, the Assessing Officer shall, pass an order modifying the total income of the relevant assessment year determined in such assessment or reassessment, or proceed to complete the assessment or reassessment proceedings, as the case may be, in accordance with the order of the business reorganisation and the modified return so furnished.
(4) The Principal Director General of Income-tax (Systems) or Director General of Income-tax (Systems) shall specify the procedures, formats and standards for ensuring secure capture and transmission of data and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to furnishing the return in the manner specified in sub-rule (2).
R. 177(2) ITR-A shall be furnished electronically under the digital signature.
R. 177(3) If the assessment or reassessment proceedings for a tax year to which the order of the business reorganisation applies have been completed or are pending on the date of furnishing ITR-A, the Assessing Officer shall, pass an order modifying the total income of the relevant tax year determined in such assessment or reassessment, or proceed to complete the assessment or reassessment proceedings, as the case may be, in accordance with the order of the business reorganisation and the ITR-A so furnished.
Rule 12AE of the 1962 Rules : Return of income under section 158BC/Rule 180 of the 2026 Rules : Return of income in respect of block assessment under section 294(1)
CORRESPONDING PROVISION
u Rule 12AE of the 1962 Rules corresponds to rule 180 of the 2026 Rules as under:—
1962 Rules 2026 Rules
Rule 12AE(1)
Rule 12AE(2) & its Table
Rule 12AE(2), Explanation
Rule 12AE(3)
Rule 12AE(4)
TEXTUAL COMPARISON
Rule 12AE of the 1962 Rules : Return of income under section 158BC
(1) The return of income required to be furnished by any person under clause (a) of sub-section (1) of section 158BC, relating to any search initiated under section 132 or requisition made under section 132A on or after the 1st day of September, 2024 shall be in the Form ITR-B and be verified in the manner indicated therein.
Rule 180(1)
Rule 180(2) & its Table
Rule 180(3)
Rule 180(5)
Rule 180(4)
Rule 180 of the 2026 Rules : Return of income in respect of block assessment under section 294(1)
R. 180(1) The return of income required to be furnished by any person under section 294(1)(a), relating to any search initiated under section 247 or requisition made under section 248 shall be in the Form ITR-BN and be verified in the manner indicated therein.
Rule 12AE of the 1962 Rules : Return of income under section 158BC
(2) The return of income referred to in sub-rule (1) shall be furnished by a person, mentioned in column (2) of the Table below in the manner specified in column (3) thereof: ––
TABLE
Sl. No. Person Manner of furnishing return of income (1) (2) (3)
1. (a) person whose accounts are required to be audited under section 44AB of the Act;
(b) Company;
(c) Political party.
2. Any person other than a person mentioned in column (2) of Sl. No. (1) above.
Electronically under digital signature.
Rule 180 of the 2026 Rules : Return of income in respect of block assessment under section 294(1)
R. 180(2) & its Table ITR-BN shall be furnished by a person, mentioned in column 2 of the following Table in the manner specified in column 3 thereof:
Sl. No. Person Manner of furnishing return of income (1) (2) (3)
1. Company Electronically under digital signature.
2. Any person other than a company (A) Electronically under digital signature; or (B) transmitting the data electronically in the return under electronic verification code.
(A) Electronically under digital signature;
(B) Transmitting the data electronically in the return under electronic verification code.
Explanation.—For the purposes of this sub-rule, “electronic verification code” shall have the same meaning as assigned to it in Explanation to sub-rule (2) of rule 12AC.
(3) The Principal Director-General of Income-tax (Systems) or Director-General of Income-tax (Systems) shall specify the procedures, formats and standards for ensuring secure capture and transmission of data and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to furnishing the return in the manners specified in column (3) of the Table.
R. 180(3) For the purposes of sub-rule (2), “electronic verification code” shall have the meaning assigned to it in rule 165.
R. 180(5) The Principal Director-General of Income-tax (Systems) or Director-General of Income-tax (Systems) shall specify the procedures, formats and standards for ensuring secure capture and transmission of data and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to furnishing the return in the manners specified in column 3 of the Table in sub-rule (2)
(4) In a case where claim of credit of the tax payments is made against undisclosed income of the block period other than by way of self-assessment tax for the block period, claim of such credits and the allowability thereof shall be subject to the verification by and satisfaction of, the Assessing Officer.
R. 180(4) In a case where claim of credit of the tax payments is made against undisclosed income of the block period other than by way of self-assessment tax for the block period, claim of such credits and the allowability thereof shall be subject to the verification by and satisfaction of, the Assessing Officer.
Rule 12C of the 1962 Rules : Statement under sub-section (2) of section 115U/Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
CORRESPONDING PROVISION
u Rule 12C of the 1962 Rules corresponds to rule 145 of the 2026 Rules as under:—
1962 Rules
Rule 12C(1) & (2)
Rule 12C(3)
TEXTUAL COMPARISON
Rule 12C of the 1962 Rules : Statement under sub-section (2) of section 115U
(1) The statement of income paid or credited shall be furnished by the 30th November of the financial year following the previous year during which such income is paid or credited, to the Chief Commissioner or Commissioner of Income-tax, within whose jurisdiction, the principal office of the Venture Capital Company or the Venture Capital Fund, as the case may be, is situated.
(2) The statement of income paid or credited which is to be furnished under sub-section (2) of section 115U by the Venture Capital Company or the Venture Capital Fund, as the case may be, shall be in Form No. 64, duly verified by an accountant in the manner indicated therein and shall be furnished electronically under digital signature.
2026 Rules
Rule 145(1) & its Table: Sl. No. 1
Rule 145(2)
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
R. 145(1) & its Table Sl. No. 1
The statement of income credited or paid or distributed by an entity as referred to in the column B of the following Table shall be furnished by the person responsible for crediting or paying or distributing such income on behalf of such entity to the Principal Commissioner or the Commissioner of Income-tax, within whose jurisdiction the principal office of such entity is situated, electronically in the Form No. mentioned in the column C, duly verified by an accountant, as defined in section 515(3)(b), in the manner indicated therein; and to the recipient of such income mentioned in column D in the Form No. mentioned in the column E of the said Table:
TABLE
Sl. No. Type of entity Form for furnishing statement to Principal Commissioner or Commissioner of Incometax
Person to whom statement is to be furnished Form for furnishing statement to recipient of income
A B C D E
1. Venture Capital Company or the Venture Capital Fund.
74. The person who is liable to tax in respect of such income.
75.
R. 145(2) The statement to the Principal Commissioner or the Commissioner of Income-tax shall be furnished by the 15th June of the financial year succeeding the tax year during which the income is paid or credited or distributed and the
Rule 12C of the 1962 Rules : Statement under sub-section (2) of section 115U
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9) statement to the recipient of income shall be furnished by the 30th June of the financial year succeeding the tax year during which the income is paid or credited or distributed.
(3) The Director General of Income-tax (Systems) shall specify the procedure for filing of Form No. 64 and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to the statements so furnished.
Rule 12CA of the 1962 Rules : Statement under sub-section (4) of section 115UA/Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
CORRESPONDING PROVISION
u Rule 12CA of the 1962 Rules corresponds to rule 145 of the 2026 Rules as under:— 1962 Rules 2026 Rules
Rule 12CA(1)
Rule 12CA(2)
TEXTUAL COMPARISON
Rule 12CA of the 1962 Rules : Statement under sub-section (4) of section 115UA
(1) The statement of income distributed by a business trust to its unit holder shall be furnished by the person responsible for making payment of the income distributed on behalf of a business trust to —
(i) the Principal Commissioner or the Commissioner of Income-tax, as the case may be, within whose jurisdiction the principal office of the business trust is situated by the 15th day of June of the financial year following the previous year during which the income is distributed electronically under digital signature, in Form No. 64A duly verified by an accountant in the manner indicated therein; and
(ii) the unit holder by the 30th day of June of the financial year following the previous year during which the income is distributed in Form No. 64B after generating and
Rule 145(1) & its Table: Sl. No. 2
Rule 145(2) & (3)
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
R. 145(1) & its
Table Sl. No. 2
The statement of income credited or paid or distributed by an entity as referred to in the column B of the following Table shall be furnished by the person responsible for crediting or paying or distributing such income on behalf of such entity to the Principal Commissioner or the Commissioner of Income-tax, within whose jurisdiction the principal office of such entity is situated, electronically in the Form No. mentioned in the column C, duly verified by an accountant, as defined in section 515(3)(b), in the manner indicated therein; and to the recipient of such income mentioned in column D in the Form No. mentioned in the column E of the said Table:
Rule 12CA of the 1962 Rules : Statement under sub-section (4) of section 115UA
downloading the same from the web portal specified by the Principal Director General of Income-tax (Systems) or the Director General of Income-tax (Systems) or the person authorised by him and duly verified by the person paying the income distributed on behalf of the business trust in the manner indicated therein.
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
TABLE
Sl. No. Type of entity Form for furnishing statement to Principal Commissioner or Commissioner of Income-tax
Business trust.
R. 145(2) & (3)
Person to whom statement is to be furnished Form for furnishing statement to recipient of income
Unit holder.
(2) The statement to the Principal Commissioner or the Commissioner of Income-tax shall be furnished by the 15th June of the financial year succeeding the tax year during which the income is paid or credited or distributed and the statement to the recipient of income shall be furnished by the 30th June of the financial year succeeding the tax year during which the income is paid or credited or distributed.
(3) The statement to the recipient of income shall be furnished after generating and downloading the same from the web portal specified by the Director General of Income-tax (Systems) or the person authorised by him and duly verified by the person paying or crediting or distributing the income in the manner indicated therein.
(2) The Principal Director General of Income-tax (Systems) or the Director General of Income tax (Systems), as the case may be, shall specify,—
(i) the procedure for filing of Form No. 64A and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to the statements of income paid so furnished under this rule; and
(ii) the procedure, formats and standards for generation and download of statement in Form No. 64B from the web portal specified by him or by the person authorised by him and he shall be responsible for the day-to-day administration in relation to the generation and download of certificates from the web portal specified by him or the person authorised by him.
Rule 12CB of the 1962 Rules : Statement under sub-section (7) of section 115UB/Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
CORRESPONDING PROVISION
u Rule 12CB of the 1962 Rules corresponds to rule 145 of the 2026 Rules as under:— 1962 Rules 2026 Rules
Rule 12CB(1)
Rule 12CB(2)
TEXTUAL COMPARISON
Rule 12CB of the 1962 Rules : Statement under sub-section (7) of section 115UB
(1) The statement of income paid or credited by an investment fund to its unit holder shall be furnished by the person responsible for crediting or making payment of the income on behalf of an investment fund and the investment fund to the—
(i) unit holder by 30th day of June of the financial year following the previous year during which the income is paid or credited in Form No. 64C after generating and downloading the same from the web portal specified by the Principal Director General of Income-tax (Systems) or the Director General of Income-tax (Systems) or the person authorised by him and duly verified by the person paying or crediting the income on behalf of the investment fund in the manner indicated therein; and
(
ii) Principal Commissioner or the Commissioner of Income-tax, as the case may be, within whose jurisdiction the Principal office of the investment fund is situated by 15th day of June of the financial year following the previous year during which the income is paid or credited, electronically under digital signature, in Form No. 64D duly verified by an accountant in the manner indicated therein.
Rule 145(1) & its Table: Sl. No. 3
Rule 145(2) & (3)
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
R. 145(1) & its Table Sl. No. 3
The statement of income credited or paid or distributed by an entity as referred to in the column B of the following Table shall be furnished by the person responsible for crediting or paying or distributing such income on behalf of such entity to the Principal Commissioner or the Commissioner of Income-tax, within whose jurisdiction the principal office of such entity is situated, electronically in the Form No. mentioned in the column C, duly verified by an accountant, as defined in section 515(3)(b), in the manner indicated therein; and to the recipient of such income mentioned in column D in the Form No. mentioned in the column E of the said Table:
TABLE
Sl. No. Type of entity Form for furnishing statement to Principal Commissioner or Commissioner of Income-tax
Person to whom statement is to be furnished Form for furnishing statement to recipient of income
B C D E 3. Investment fund. 79. The person who is liable to tax in respect of such income. 78.
Rule 12CB of the 1962 Rules : Statement under sub-section (7) of section 115UB
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
R. 145(2) & (3)
(2) The statement to the Principal Commissioner or the Commissioner of Income-tax shall be furnished by the 15th June of the financial year succeeding the tax year during which the income is paid or credited or distributed and the statement to the recipient of income shall be furnished by the 30th June of the financial year succeeding the tax year during which the income is paid or credited or distributed.
(3) The statement to the recipient of income shall be furnished after generating and downloading the same from the web portal specified by the Director General of Income-tax (Systems) or the person authorised by him and duly verified by the person paying or crediting or distributing the income in the manner indicated therein.
(2) The Principal Director General of Income-tax (Systems) or the Director General of Income-tax (Systems), as the case may be, shall specify the,—
(i) procedure for filing of Form No. 64D and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to the statements of income paid or credited so furnished under this rule; and (ii) procedure, formats and standards for generation and download of statement in Form No. 64C from the web portal specified by him or by the person authorised by him and he shall be responsible for the day-to-day administration in relation to the generation and download of certificates from the web portal specified by him or the person authorised by him. —
Rule 12CC of the 1962 Rules : Statement under sub-section (4) of section 115TCA/Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
CORRESPONDING PROVISION
u Rule 12CC of the 1962 Rules corresponds to rule 145 of the 2026 Rules as under:— 1962 Rules 2026 Rules
Rule 12CC(1)
Rule 12CC(2)
Rule 145(1) & its Table: Sl. No. 4
Rule 145(2) & (3)
TEXTUAL COMPARISON
Rule 12CC of the 1962 Rules : Statement under sub-section (4) of section 115TCA
(1) The statement of income paid or credited by a securitisation trust to its investor shall be furnished by the person responsible for crediting or making payment of the income on behalf of a securitisation trust and the securitisation trust to—
(i) the Principal Commissioner or the Commissioner of Income-tax, as the case may be, within whose jurisdiction the principal office of the securitisation trust is situated by the 15th day of June of the financial year following the previous year during which the income is paid or credited electronically under digital signature, in Form No. 64E duly verified by an accountant in the manner indicated therein; and
(ii) the investor by the 30th day of June of the financial year following the previous year during which the income is paid or credited in Form No. 64F after generating and downloading the same from the web portal specified by the Principal Director General of Income-tax (Systems) or the Director General of Income-tax (Systems) or the person authorised by him and duly verified by the person paying or crediting the income on behalf of the securitisation trust in the manner indicated therein.
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
R. 145(1) & its Table Sl. No. 4
The statement of income credited or paid or distributed by an entity as referred to in the column B of the following Table shall be furnished by the person responsible for crediting or paying or distributing such income on behalf of such entity to the Principal Commissioner or the Commissioner of Income-tax, within whose jurisdiction the principal office of such entity is situated, electronically in the Form No. mentioned in the column C, duly verified by an accountant, as defined in section 515(3)(b), in the manner indicated therein; and to the recipient of such income mentioned in column D in the Form No. mentioned in the column E of the said Table:
TABLE
Sl. No. Type of entity Form for furnishing statement to Principal Commissioner or Commissioner of Income-tax
Person to whom statement is to be furnished Form for furnishing statement to recipient of income
B C D E
4. Securitisation trust.
72. The person who is liable to tax in respect of such income.
73.
R. 145(2) & (3) (2) The statement to the Principal Commissioner or the Commissioner of Income-tax shall be furnished by the 15th June of the financial year succeeding the tax year during which the income is paid or credited or distributed and the statement to the recipient of income shall be furnished by the 30th June of the financial year succeeding the tax year during which the income is paid or credited or distributed.
Rule 12CC of the 1962 Rules : Statement under sub-section (4) of section 115TCA
Rule 145 of the 2026 Rules : Statements under sections 221(4), 222(2), 223(5) and 224(9)
(3) The statement to the recipient of income shall be furnished after generating and downloading the same from the web portal specified by the Director General of Income-tax (Systems) or the person authorised by him and duly verified by the person paying or crediting or distributing the income in the manner indicated therein.
(2) The Principal Director General of Income-tax (Systems) or the Director General of Income tax (Systems), as the case may be, shall specify,—
(i) the procedure for filing of Form No. 64E and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to the statements of income paid or credited so furnished under this rule; and
(ii) the procedure, formats and standards for generation and download of statement in Form No. 64F from the web portal specified by him or by the person authorised by him and he shall be responsible for the day-to-day administration in relation to the generation and download of certificates from the web portal specified by him or the person authorised by him.
Rule 12D of the 1962 Rules : Prescribed income-tax authority under section 133C/Rule 156 of the 2026 Rules : Prescribed income-tax authority under section 259
CORRESPONDING PROVISION
u Rule 12D of the 1962 Rules corresponds to rule 156 of the 2026 Rules as under:— 1962 Rules 2026 Rules
Rule 12D Rule 156
TEXTUAL COMPARISON
Rule 12D of the 1962 Rules : Prescribed income-tax authority under section 133C
The prescribed income-tax authority under section 133C shall be an income-tax authority not below the rank of Assistant Commissioner of Income-tax who has been authorised by the Central Board of Direct Taxes to act as such authority for the purposes of that section.
Rule 156 of the 2026 Rules : Prescribed income-tax authority under section 259
R. 156 The prescribed income-tax authority under section 259 shall be an Income-tax authority not below the rank of Assistant Commissioner of Income-tax, who has been authorised by the Central Board of Direct Taxes to act as such authority for the purposes of that section.
COMPARATIVE
STUDY OF PROVISIONS OF INCOMETAX RULES 2026 & INCOME-TAX
RULES 1962
AUTHOR : Taxmann's Editorial Board
PUBLISHER : Taxmann Publications
DATE OF PUBLICATION : April 2026
EDITION : 2026 Edition
ISBN NO : 9789375619581
NO. OF PAGES : 912
BINDING TYPE : Paperback
2,495
DESCRIPTION
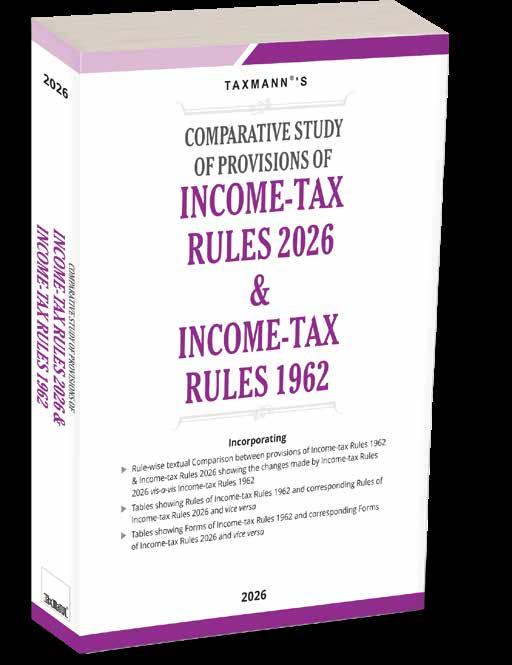
Comparative Study of Provisions of Income-Tax Rules 2026 & Income-Tax Rules 1962 is the definitive transition reference for India's subordinate tax legislation. It reproduces the operative text of both sets of Rules side by side, word for word, marking every deletion, modification, and new insertion directly within the text — making the legislation its own annotation. All amendments notified up to 31st March 2026 in both sets of Rules have been incorporated. This book is the procedural companion to Taxmann's Comparative Study of Provisions of Income-Tax Act 2025 & Income-Tax Act 1961, which maps the substantive transition at the Act level. Together, they provide complete coverage of what has changed, what has been retained, and what is new—across both the parent statute and the subordinate rules that give it operational force. Neither volume is complete without the other.
This book is designed for practitioners and professionals who must work across both legislative frameworks simultaneously—either to advise clients on transition-period compliance, to interpret provisions that straddle both regimes, or to understand the precise scope of change introduced by the 2026 Rules. The primary readership includes:
•Chartered Accountants, Tax Advocates, and Company Secretaries
•Corporate Tax and Legal Teams
•Tax Administrators and Revenue Officers
•Researchers, Academics, and Students
The Present Publication is the 2026 Edition, incorporating all amendments notified upto 31st March 2026 in both Income-tax Rules 1962 and Income-tax Rules 2026. It is edited/authored by Taxmann's Editorial Board, with the following noteworthy features:
•[Word-to-Word Two-Column Parallel Comparison] The 1962 Rules appear on the left; the corresponding 2026 Rules on the right. Every sub-rule, clause, sub-clause, item, sub-item, proviso, and Explanation is aligned directly opposite its counterpart—enabling precise, granular comparison without cross-referencing across separate volumes
•[Visual Change Identification System] A two-layered typographic coding makes every legislative change immediately identifiable:
oBold + Strikethrough in the 1962 column — language deleted or modified in the 2026 Rules
oBold text in the 2026 column — language newly inserted, simplified, or changed relative to the 1962 Rules
•[Cross-Reference Tables—Rules] Two tables map rule renumbering in both directions:
oTable 1 | Rules of Income-Tax Rules 1962 Corresponding Rules of Income-Tax Rules 2026
oTable 2 | Rules of Income-Tax Rules 2026 Corresponding Rules of Income-Tax Rules 1962
oEach entry carries both the rule number and heading under both frameworks
•[Cross-Reference Tables—Forms] Two tables map form renumbering in both directions:
oTable 3 | Forms of Income-Tax Rules 1962 Corresponding Forms of Income-Tax Rules 2026
oTable 4 | Forms of Income-Tax Rules 2026 Corresponding Forms of Income-Tax Rules 1962
•[New Provisions Without 1962 Counterpart] A dedicated section lists all Rules 2026 provisions with no corresponding 1962 rule—providing practitioners a clean view of the net legislative additions under the new framework
•[Migration of Provisions from the Income-Tax Act] A reference section identifies provisions previously embedded in the Income-Tax Act 1961 or 2025 that have been relocated into the Rules—a structural shift with direct implications for interpretation, applicability, and the ease of future amendment