CA. Naveen Wadhwa Vice-President –Taxmann’s Advisory & Research
CA. Naveen Wadhwa Vice-President –Taxmann’s Advisory & Research
On April 16, 2026, Wipro Limited announced a major share buy-back programme, proposing to acquire up to 60 crore fully paid-up equity shares, representing approximately 5.72% of its total paid-up equity share capital. The buy-back price is set at Rs. 250 per share, which represents a premium of approximately 16.30% over the volumeweighted average market price for the 60 trading days preceding the board meeting notification and 28.51% over the 10-day VWAP.
Unlike the Infosys buy-back of 2025, where promoters chose not to participate, Wipro’s promoter group, led by Azim Premji and related entities holding approximately 72.62% of the equity, has expressed its intention to participate in the buy-back. This decision carries significant tax consequences, particularly given the amendments introduced by the Finance Act, 2026.
The tax considerations are equally important for non-promoter investors evaluating whether to tender their shares in the buy-back or sell them in the open market. This article provides a comparative analysis of the tax implications under both scenarios.
A buy-back occurs when a company repurchases its own shares from existing shareholders, typically at a premium to the current market price. The tax treatment for such transactions has undergone significant changes over the years.
The most recent change has been brought about by the Finance Act, 2026, which has substituted sub-sections (2) and (3) of Section 69 of the Income Tax Act, 2025 (ITA 2025), corresponding to Section 46A of the ITA 1961. Under the amended provisions, effective from April 1, 2026, the consideration received by a shareholder on the buy-back of shares is once again treated as capital gains in the hands of the shareholder. This marks a departure from the regime that prevailed between October 1, 2024 and March 31, 2026, during which buy-back proceeds were taxed as “deemed dividends” under Section 2(22) (f) of the ITA 1961.
Under the current regime (effective April 1, 2026), the capital gains are computed as the difference between the buy-back price (full value of consideration) and the cost of acquisition. For listed equity shares, if held for more than 12 months, the gains are treated as long-term capital gains (LTCG) and taxed under Section 198 of the ITA 2025 (corresponding to Section 112A of the ITA 1961) at 12.5% on gains exceeding Rs. 1,25,000. If held for 12 months or less, the gains are short-term capital gains (STCG) taxed under Section 196 (corresponding to Section 111A) at 20%.
A notable feature of the Finance Act, 2026 amendment is the levy of an additional tax on promoters who tender shares in the buy-back. For promoters who are not domestic companies, the additional tax rate is 10% on STCG and 17.5% on LTCG. For promoters that are domestic companies, the additional rates are 2% on STCG and 9.5% on LTCG. A 12% surcharge is levied on this additional tax. The final tax liability of promoters on the buyback of listed shares will be as follows:
* The LTCG will be taxable when it exceeds Rs. 1,25,000.
Where the buy-back results in a capital loss (i.e., the cost of acquisition exceeds the buyback price), such loss can be set off against other capital gains in accordance with the provisions of the Act. A short-term capital loss can be set off against both short-term and long-term capital gains, while a long-term capital loss can be set off only against longterm capital gains. Unabsorbed capital losses can be carried forward for eight tax years.
As w.e.f. 01-04-2026, the buyback of shares results in capital gains, the tax liability shall remain the same, notwithstanding that the shares are sold in the buyback or in the open market. However, for promoters, the tax liability will be lower if the shares are sold in the open market rather than tendered in the buyback. Where shares are sold on the exchange, STCG and LTCG are taxed at 20% and 12.5%, respectively, rather than at 22% (promoter co.) or 30% (other promoters).
The following computation illustrates the tax implications for different investors under both scenarios – shares tendered in the buy-back vs. retained and sold later in the market. The analysis assumes that the expected market price after the buy-back settles at Rs. 220 per share.
Taxability If Shares Are Tendered in the Buy-back
[P = A × B]
[Q = O – P]
Excess benefits if shares are tendered in the buy-back rather than sold in the market [U = N – T]
Note – Surcharge and health & education cess have not been considered in the computation of tax to simplify the illustration. For Mr A and Mr B, the exemption of Rs. 1,25,000 under Section 198 has been considered by limiting the exemption to the extent of the capital gain.
The comparative analysis above shows that, under the revised regime, tendering shares in the buy-back is more favourable for promoters and non-promoters than selling in the open market. This is primarily because the buy-back price of Rs. 250 offers a significant premium over the expected post-buy-back market price of Rs. 220. The capital gains tax treatment ensures that the tax incidence is computed only on the actual profit, making the buy-back an attractive proposition for shareholders.
The shift from the deemed dividend regime back to the capital gains regime is a welcome change that aligns the tax treatment more closely with the economic substance of the transaction.
Disclaimer – This article aims to provide a comparative understanding of the tax implications and does not suggest any particular course of action.
Founded 1972
Evolution From a small family business to a leading technology-oriented Publishing/Product company
Expansion
Launch of Taxmann Advisory for personalized consulting solutions
Aim
Achieve perfection, skill, and accuracy in all endeavour
Growth
Evolution into a company with strong independent divisions: Research & Editorial, Production, Sales & Marketing, and Technology
Future
Continuously providing practical solutions through Taxmann Advisory
Editorial and Research Division
Over 200 motivated legal professionals (Lawyers, Chartered Accountants, Company Secretaries)
Monitoring and processing developments in judicial, administrative, and legislative fields with unparalleled skill and accuracy
Helping businesses navigate complex tax and regulatory requirements with ease
Over 60 years of domain knowledge and trust
Technology-driven solutions for modern challenges
Ensuring perfection, skill, and accuracy in every solution provided
Income Tax
Corporate Tax Advisory
Trusts & NGO Consultancy
TDS Advisory
Global Mobility Services
Personal Taxation
Training
Due Diligence
Due Dilligence
Advisory Services
Assistance in compounding of offences
Transactions Services
Investment outside India
Goods
Transaction Advisory
Business Restructuring
Classification
Due Diligence
Training
Advisory
Trade Facilitation Measures
Corporate
Corporate Structuring
VAT Advisory
Residential Status
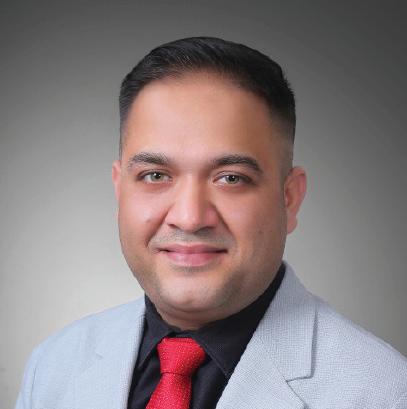
Naveen Wadhwa Research and Advisory [Corporate and Personal Tax]
Chartered Accountant (All India 24th Rank)
14+ years of experience in Income tax and International Tax
Expertise across real estate, technology, publication, education, hospitality, and manufacturing sectors
Contributor to renowned media outlets on tax issues
Vinod K. Singhania
Expert on Panel | Research and Advisory (Direct Tax)
Over 35 years of experience in tax laws
PhD in Corporate Economics and Legislation
Author and resource person in 800+ seminars
V.S. Datey
Expert on Panel | Research and Advisory [Indirect Tax]
Holds 30+ years of experience
Engaged in consulting and training professionals on Indirect Taxation
A regular speaker at various industry forums, associations and industry workshops
Author of various books on Indirect Taxation used by professionals and Department officials
S.S. Gupta
Expert on Panel | Research and Advisory [Indirect Tax]
Chartered Accountant and Cost & Works Accountant
34+ Years of Experience in Indirect Taxation
Bestowed with numerous prestigious scholarships and prizes
Author of the book GST – How to Meet Your Obligations', which is widely referred to by Trade and Industry
Manoj Fogla
Expert on Panel | Research and Advisory [Charitable Trusts and NGOs]
Over three decades of practising experience on tax, legal and regulatory aspects of NPOs and Charitable Institutions
Law practitioner, a fellow member of the Institute of Chartered Accountants of India and also holds a Master's degree in Philosophy
PhD from Utkal University, Doctoral Research on Social Accountability Standards for NPOs
Author of several best-selling books for professionals, including the recent one titled 'Trust and NGO's Ready Reckoner' by Taxmann
Drafted publications for The Institute of Chartered Accountants of India, New Delhi, such as FAQs on GST for NPOs & FAQs on FCRA for NPOs.
Has been a faculty and resource person at various national and international forums
the UAE
Chartered Accountant (All India 36th Rank)
Has previously worked with the KPMG
Taxmann Delhi
59/32, New Rohtak Road
New Delhi – 110005 | India
Phone | 011 45562222
Email | sales@taxmann.com
Taxmann Mumbai
35, Bodke Building, Ground Floor, M.G. Road, Mulund (West), Opp. Mulund Railway Station Mumbai – 400080 | Maharashtra | India
Phone | +91 93222 47686
Email | sales.mumbai@taxmann.com
Taxmann Pune
Office No. 14, First Floor, Prestige Point, 283 Shukrwar Peth, Bajirao Road, Opp. Chinchechi Talim, Pune – 411002 | Maharashtra | India
Phone | +91 98224 11811
Email | sales.pune@taxmann.com
Taxmann Ahmedabad
7, Abhinav Arcade, Ground Floor, Pritam Nagar Paldi
Ahmedabad – 380007 | Gujarat | India
Phone: +91 99099 84900
Email: sales.ahmedabad@taxmann.com
Taxmann Hyderabad
4-1-369 Indralok Commercial Complex Shop No. 15/1 – Ground Floor, Reddy Hostel Lane Abids Hyderabad – 500001 | Telangana | India
Phone | +91 93910 41461
Email | sales.hyderabad@taxmann.com
Taxmann Chennai No. 26, 2, Rajan St, Rama Kamath Puram, T. Nagar
Chennai – 600017 | Tamil Nadu | India
Phone | +91 89390 09948
Email | sales.chennai@taxmann.com
www.taxmann.com
Taxmann Bengaluru
12/1, Nirmal Nivas, Ground Floor, 4th Cross, Gandhi Nagar
Bengaluru – 560009 | Karnataka | India
Phone | +91 99869 50066
Email | sales.bengaluru@taxmann.com
Taxmann Kolkata Nigam Centre, 155-Lenin Sarani, Wellington, 2nd Floor, Room No. 213
Kolkata – 700013 | West Bengal | India
Phone | +91 98300 71313
Email | sales.kolkata@taxmann.com
Taxmann Lucknow
House No. LIG – 4/40, Sector – H, Jankipuram Lucknow – 226021 | Uttar Pradesh | India
Phone | +91 97924 23987
Email | sales.lucknow@taxmann.com
Taxmann Bhubaneswar
Plot No. 591, Nayapalli, Near Damayanti Apartments
Bhubaneswar – 751012 | Odisha | India
Phone | +91 99370 71353
Email | sales.bhubaneswar@taxmann.com
Taxmann Guwahati
House No. 2, Samnaay Path, Sawauchi Dakshin Gaon Road
Guwahati – 781040 | Assam | India
Phone | +91 70866 24504
Email | sales.guwahati@taxmann.com