The Lok Sabha passed the Finance Bill 2026 [hereinafter called ‘Finance Bill (Lok Sabha)’] on March 25, 2026. While the Finance Bill, as passed by the Lok Sabha, largely retains the proposals made in the Finance Bill, certain noteworthy modifications have been made to provisions relating to share buybacks, capital gains, assessment, and more.
A snippet of all changes made in the Finance Bill, 2026, as passed by the Lok Sabha, viz-a-viz the Finance Bill, 2026, presented originally in the Lok Sabha, is presented hereunder.
The Finance Bill 2026, as introduced in the Lok Sabha, has proposed that consideration received on buy-back shall no longer be treated as a dividend but shall be chargeable to tax under the head “Capital gains”. This has been achieved by omitting Section 2(40)(f) [corresponding to Section 2(22)(f) of the ITA 1961] and substituting the sub-sections (2) and (3) of Section 69 of the ITA 2025 [corresponding to Section 46A of the ITA 1961].
Further, recognising the distinct position of promoters in the buy-back decisions, the Finance Bill proposed an additional tax in such cases. As a result, promoters will face an effective tax rate of 30%, and promoter companies an effective tax rate of 22%, on the capital gains arising from the buy-back. However, the Finance Bill 2026 was silent on the levy of a surcharge on the additional tax.
The relevant Finance Bill provides the power to levy a surcharge on the tax. The following are the relevant provisions of the Finance Bill 2026 that provide the levy and the rate of surcharge:
• Section 3(4) of the Finance Bill 2026 provides the rate of surcharge in respect of the tax payable on the special income computed under specified chapters or provisions of the ITA 2025.
• Section 3(4) of the Finance Bill 2026, read with Paragraph F of Part III of the First Schedule, provides that where the total income includes dividend income or capital gains under Sections 196, 197, or 198 of the ITA 2025 [corresponding to Sections 111A, 112 and 112A of ITA 1961, respectively], the surcharge on the tax attributable to such income is restricted to 15%.
• Paragraph F of Part III of the First Schedule to the Finance Bill, 2026, sets out the surcharge rate on the tax payable on normal income, which can reach 37%.
• Section 3(6) of the Finance Bill, 2026, levies the surcharge at the flat rate of 12% in respect of tax payable on certain incomes.
The Finance Bill (Lok Sabha) has inserted a reference to additional tax payable on buyback of shares under Section 69 in Section 3(6) of the Finance Bill 2026. Accordingly, a surcharge at the rate of 12% shall be levied on additional tax payable on buy-back of shares, irrespective of the amount of the total income.
The Finance Bill (Lok Sabha) has amended Section 69(2) to clarify that the additional tax proposed under Section 69 of the ITA 2025 will be payable only when the buyback is in accordance with the provisions of Section 68 of the Companies Act, 2013.
Section 68 of the Companies Act, 2013 deals with the ‘Power of company to purchase its own securities’. Section 68(1) provides that a company may purchase its own shares or other specified securities out of:
(i) its free reserves,
(ii) the securities premium account,
(iii) the proceeds of any shares or other specified securities.
Such a purchase by a company of its own shares or specified securities is called ‘buyback’. The company’s power to buy back is subject to the provisions of sub-section (2) of Section 68 of the Companies Act 2013.
In addition to Section 68, the Companies Act 2013 allows a company to buy back its securities under:
a) Sections 230 to 232 of the Companies Act, 2013;
b) Section 235 of the Companies Act, 2013;
c) Section 242(2)(b) of the Companies Act, 2013.
Thus, in such cases where the buyback is not done under Section 68 of the Companies Act, 2013, the capital gains will continue to be computed and taxed under Section 69, but the additional tax in such cases may not be payable under this provision.
Clause (37A) of Section 10 of the ITA 1961 provided capital gains exemption in respect of transfer of a ‘specified capital asset’ to an assessee, being an individual and Hindu
undivided family, who was owner of such asset as on 2nd day of June, 2014 and transfers such ‘specified capital asset’ under the land pooling scheme covered under the Andhra Pradesh Capital City Land Pooling Scheme (Formulation and Implementation) Rules 2015 made under the provisions of the Andhra Pradesh Capital Region Development Authority Act, 2014 and the rules, regulations and Schemes made under the said Act.
The ITA 2025 did not contain any corresponding provision to grant such a capital gains exemption to individuals or HUFs from Tax Year 2026–27. To address this, the Finance Bill (Lok Sabha) inserts Sl. No. 38D in Schedule III of the ITA 2025 to provide an exemption on capital gains arising from the land pooling scheme. However, the Finance Bill (Lok Sabha) has made the exemption time-bound, limiting it to 5 years. Accordingly, it will be available only to eligible persons who receive the reconstituted plot or land on or before 31-032031 under the Andhra Pradesh Capital City Land Pooling Scheme, subject to prescribed conditions.
Section 245 of the ITA 1961 deals with set-off and withholding of refunds in certain cases. Sub-section (1) provides that where any refund is due or found to be due to the assessee under any provision of the Act, the tax authorities may, in lieu of payment of the refund, set off the amount to be refunded or any part of that amount against the sum payable by him under this Act.
The provision permits adjustment of refunds only against sums payable “under this Act”, i.e., the ITA 1961. This created a significant gap during the transitional period. If a taxpayer was entitled to a refund arising out of proceedings under the ITA 1961, but had outstanding dues under the ITA 2025, the Assessing Officer had no statutory authority to set off the refund against such dues.
The Finance Bill (Lok Sabha) amends Section 245(1) of the ITA 1961 to expand the scope of refunds to be adjusted. The amended provision provides that a refund determined under the ITA 1961 may be set off not only against any sum payable under that Act but also against any sum payable under the ITA 2025.
Section 438 of ITA 2025 (corresponding to Section 245 of the ITA 1961) provides a similar power to the AO to set off a refund against any sum payable under the Act. The Finance Bill (Lok Sabha) made the consequential amendments to Section 438 of ITA 2025, providing that a refund determined under ITA 2025 may be set off not only against any sum payable under ITA 2025 but also against any sum payable under ITA 1961.
Section 254(3) of the ITA 1961 provides that a copy of the order passed by the ITAT shall be shared with the assessee and the Principal Commissioner or Commissioner.
The Finance Bill (Lok Sabha) has introduced a new sub-section (3A) to Section 254, which states that the ITAT, which is required to send a copy of its order to the assessee and the Principal Commissioner or Commissioner, must now send the order to the jurisdictional Principal Commissioner or Commissioner electronically through the designated portal for orders passed on or after 01-10-2026. The copy of the order will be shared with the assessee as per the existing procedure.
Section 363 of ITA 2025 (corresponding to Section 254 of the ITA 1961) contains similar provisions. The Finance Bill (Lok Sabha), with effect from 01-04-2026, made a similar amendment to Section 363 by substituting sub-section (10), requiring an order passed by the ITAT to be sent electronically to the jurisdictional Principal Commissioner or Commissioner via the designated portal.
Section 144B of the ITA 1961 provides the manner in which scrutiny assessment under Section 143(3), best judgment assessment under Section 144, and income escaping assessment under Section 147 shall be conducted in a faceless manner. Section 144B(6) provides the manner of authenticating and the mode of delivery of all communications made by the NFAC, assessment unit, verification unit, technical unit, or review unit.
The Finance Bill (Lok Sabha), with retrospective effect from 01-04-2022, has amended subclause (b) of Section 144B(6)(i) to allow the assessment unit, verification unit, technical unit, or review unit to authenticate the electronic records by way of an electronic communication.
To make an assessment, reassessment, or re-computation in Section 147, a notice is required to be issued to the assessee under Section 148, requiring him to furnish a return of his income or the income of any other person in respect of which he is assessable under this Act. The assessee shall be required to furnish the return of income within such period as may be specified in the notice. Section 148(1) provides the maximum time limit of not exceeding three months from the end of the month in which such notice is issued to furnish the return. However, the provision was silent on the minimum time to be allowed to the assessee to furnish the return of income.
The Finance Bill (Lok Sabha) has amended Section 280 of the ITA 2025 and its corresponding Section 148 of the ITA 1961 to provide that a minimum of 30 days must be given to the assessee to furnish the return of income in response to the notice issued by the AO.
Section 149 of the ITA 1961 provides the time limit for issuing a show cause notice under Sections 148A and 148.
Section 150(1), with a non-obstante clause, overrides the general time limits prescribed in Section 149 for issuing notices under Section 148. This provision enables issuing a notice under Section 148 for re-assessment at any time for the purpose of giving effect to any finding or direction contained in an order passed by any authority in any proceeding by way of appeal, reference or revision or by a Court.
While Section 150(1) grants a broad power, Section 150(2) imposes a restriction on that power. It states that the provisions of sub-section (1) (i.e., the power to issue notice “at any time”) shall not apply in any case where the assessment, reassessment, or recomputation relates to an assessment year in respect of which such reassessment could not have been made at the time the order (which was the subject-matter of the appeal, reference, or revision) was made, by reason of any other provision limiting the time within which any action for reassessment may be taken. This provision ensures that this power cannot be used to revive an assessment year that was already time-barred when the original order (which was the subject of appeal or revision) was made.
The existing provision covered the scenario where an order (the subject of appeal or revision) was made but did not cover the situation in which proceedings for assessment, reassessment, or recomputation had been initiated by the Assessing Officer, but no order had been passed. Further, Section 150 did not specify the time limit within which the notice under Section 148 pursuant to the findings or directions contained in any order of the court or authority must be issued.
Under the ITA 2025, Section 283 contains similar provisions regarding the powers to issue notices pursuant to findings or directions in any order of the court or authority, and the restrictions on exercising such powers.
The Finance Bill (Lok Sabha) has made the following amendments to Section 150 of the ITA 1961 and Section 283 of the ITA 2025.
The Finance Bill (Lok Sabha) has inserted clause (b) to Section 150(2) to impose a restriction on the power given in Section 150(1) in the situation when the assessment year was already time-barred at the time the assessment proceedings (subject matter before the court) were initiated. If the proceedings were initiated at a time when the limitation period to issue notice for an assessment year had expired under the general provisions (like Section 149 or Section 153), then even if a subsequent court order gives a finding or direction, Section 150(1) would be rendered inapplicable.
A new sub-section (3) of Section 150 is inserted to provide the time limit within which the notice under Section 148 pursuant to the findings or directions contained in any order of the court or authority. It is provided that the notice under Section 148 shall be issued within 3 months from the end of the quarter in which the certified copy of the order of the authority or the Court, as the case may be, is received by the jurisdictional Principal Commissioner or Commissioner.
An amendment similar to that made to Section 150 of the ITA 1961 has been made to the corresponding provisions of Section 283 of the ITA 2025.
Courts have, in several cases, invalidated approvals granted by tax authorities in assessment or reassessment proceedings on various grounds. A primary issue has been the mechanical nature of such approvals, where authorities merely record “Yes” or “approved” without
demonstrating proper satisfaction or application of mind. Judicial precedents require that the approving authority must reflect conscious consideration of the material on record, and any form of superficial or rubber-stamp approval has been consistently struck down. Further, approvals must comply with the authentication requirements under Section 282A of the ITA 1961 and Rule 127A of the Income-tax Rules, 1962. Approvals lacking essential elements such as signature, date, or proper authentication, even if issued electronically, have been held invalid, thereby vitiating the entire proceedings. There is also divergence among judicial views on the nature of such approvals, with some rulings treating them as administrative, while others consider them quasi-judicial and require a meaningful and reasoned application of mind.
The Finance Bill (Lok Sabha) has inserted a new Section 292BC into the ITA 1961 and a subsection (3) into Section 522 of the ITA 2025 to validate approvals issued by the tax authorities without sufficient reasons, and orders lacking proper authentication or a digital signature, only when such approval was granted electronically.
Schedule VII of the ITA 2025 deals with “persons exempt from tax.” It sets out a list of eligible persons whose entire income is exempt from income tax, subject to the fulfilment of the prescribed conditions.
The Finance Bill (Lok Sabha) has expanded the list of eligible persons in this Schedule by inserting SI. No. 49, which pertains to the ‘New Development Bank’. The exemption is subject to the condition that information is provided in the prescribed form and manner.
The New Development Bank (NDB) is a multilateral development bank established in 2015 by Brazil, Russia, India, China, and South Africa (BRICS) to mobilise resources for infrastructure and sustainable development projects in emerging markets and developing countries (EMDCs)1. The bank shall support public or private projects through loans, guarantees, equity participation, and other financial instruments, and shall cooperate with international organisations and other financial entities, and provide technical assistance for projects supported by the bank2 .
An eligible start-up (company or LLP) can claim a deduction under Section 80-IAC of the ITA 1961 for the profits and gains arising from the eligible business. The deduction can be claimed up to 100% of the profits and gains derived in 3 consecutive years out of the 10 assessment years beginning from the year of incorporation.
1 https://www.ndb.int/about-ndb/ 2 https://en.wikipedia.org/wiki/New_Development_Bank
Section 80-IAC defines an “eligible start-up” as a Company or a Limited Liability Partnership that satisfies the prescribed conditions. One such condition is that its turnover must not exceed Rs. 100 crores in the previous year for which the deduction under this section is claimed.
Recently, the Department for Promotion of Industry and Internal Trade (DPIIT), vide notification G.S.R. 108(E), dated 04-02-2026, has revised the turnover limit for an entity to be recognised as a startup to Rs. 200 crores. A new category of startups, Deep Tech Startups, was also introduced, with a higher turnover limit of Rs. 300 crores.
Section 140 of ITA 2025 (corresponding to Section 80-IAC of the ITA 1916) contains similar provisions. The Finance Bill (Lok Sabha), with effect from 01-04-2026, has increased the turnover limit from Rs. 100 crores to Rs. 300 crores. Hence, a start-up, whose turnover in the relevant tax year does not exceed Rs. 300 crores, will be eligible for a deduction under Section 140.
Section 536 of the ITA 2025 contains the repeal and saving provisions relating to the transition from the ITA 1961 to the ITA 2025. It formally repeals the ITA 1961 with effect from 1 April 2026, while safeguarding the continuity of legal proceedings, rights, and obligations that arose under the old law.
Clause (2)(g) of Section 536 deals with the computation of interest for the period commencing on or after 01-04-2026 in cases involving refunds or tax payments relating to any tax year beginning before 01-04-2026, where such payment/refund arises on or after 01-04-2026.
The Finance Bill (Lok Sabha) has amended Clause (2)(g) of Section 536 to provide that the provisions of the ITA 1961 governing interest on refunds or defaults will continue to apply for the period after 01-04-2026. However, the rate of interest will not remain the same as under the repealed ITA 1961. The applicable rate shall be the one prescribed under the corresponding provisions of the ITA 2025. In other words, the ITA 1961 mechanism for computing interest on refunds is retained, but the rate specified in ITA 2025 will apply. Further, such substitution of the interest rate will take effect on the date the new rate is modified under the ITA 2025.
Thus, for pending proceedings from earlier tax years, interest for the period from 01-042026 to the date of actual payment will be calculated in accordance with the provisions of ITA 1961, with the rates provided under ITA 2025.
Section 222 of ITA 1961 provides that where an assessee is in default, or is deemed to be in default, in making payment of tax, the Tax Recovery Officer (TRO) may prepare, under his signature, a statement in Form No. 57 specifying the amount of arrears payable by the assessee, which is called a “certificate”. After issuing such a certificate, the TRO shall proceed to recover the amount mentioned in it from the assessee in accordance with the provisions of the Second Schedule. For this purpose, the TRO is empowered to use one or more of the following modes of recovery, including:
(a) attachment and sale of the assessee’s movable property,
(b) attachment and sale of immovable property,
(c) arrest of the assessee and detention in prison, and
(d) appointment of a receiver to manage the assessee’s movable and immovable properties.
Additionally, the TRO may initiate or continue recovery proceedings under this section even if recovery proceedings through any other mode have already been taken.
The Finance Bill (Lok Sabha), with effect from 30-03-2026, has omitted one of the recovery modes, which is ‘arrest of the assessee and detention in prison’. Hence, from March 30th , 2026, the TRO cannot arrest the assessee and detain him in prison for tax recovery.
Consequential changes have been made to the Second Schedule to the ITA 2025 ‘Procedure for Recovery of Tax’ to remove the reference from the relevant rules or omit the rules governing the arrest and detention of the defaulter from the tax recovery procedure.
Further, similar amendments have been made to Section 413 of ITA 2025 to omit one of the recovery modes, which is ‘arrest of the assessee and detention in prison’.
Section 147 of the ITA 2025 provides for a 100% tax deduction on income from an Offshore Banking Unit (OBU) of a scheduled or foreign bank in a Special Economic Zone for 10 consecutive tax years. This benefit has been extended to 20 consecutive years vide the Finance Bill, 2026.
It has been represented that certain OBUs have their ten-year deduction period expired as of March 31st, 2025, and would not be eligible to claim the extended deduction benefit, as there will be a break in the continuity of the deduction.
Hence, the Finance Bill (Lok Sabha) amends Section 147 to allow such OBUs to claim a deduction for a period of ten consecutive tax years commencing from the tax year beginning on April 01, 2026. The benefit will not be available for the previous year, 2025-26.
The Finance Bill 2026, as introduced in the Lok Sabha, proposed to insert a new entry, 38A, in Schedule III to allow an exemption for the disability pension, including the service and disability elements, with effect from the tax year 2026–27.
Considering the practical difficulties that could have arisen in its implementation, the Finance Bill (Lok Sabha) has deferred the exemption’s applicability. It is provided that the exemption under new entry 38A shall apply on or after such date as may be notified by the Central Government in this behalf, and pending such notification, the entire disability pension, that is, disability element and service element of a disabled officer of the Indian armed forces, shall be exempt from income-tax.
The Finance Bill, 2026, provides for a series of amendments to the First Schedule of the Customs Tariff Act, 1975 (‘CTA 1975’), to be implemented in a phased manner. These amendments are covered across multiple Schedules to the Finance Bill. The following table summarises the timeline and corresponding Schedules governing such amendments.
S. No. Effective Date Schedule of Finance Bill, 2026 Amending the First Schedule to CTA 1975 (Rates)
1. Will be applicable from the date of accent of president Second Schedule
2. 1st April, 2026 Third Schedule
3. 1st May, 2026 Fourth Schedule
4. 1st May, 2026 Fifth Schedule
Additionally, changes have been carried out in the Fourth Schedule by substituting tariff item codes, wherein “4104 21 90”, “4104 31 90” and “4104 91 90” have been replaced with “4106 21 90”, “4106 31 90” and “4106 91 90” respectively. This amendment rectifies an apparent error in the Finance Bill, where incorrect/non-existent HSN codes were inadvertently specified, and ensures alignment with the correct and existing tariff classification framework.
Founded 1972
Evolution From a small family business to a leading technology-oriented Publishing/Product company
Expansion
Launch of Taxmann Advisory for personalized consulting solutions
Aim
Achieve perfection, skill, and accuracy in all endeavour
Growth
Evolution into a company with strong independent divisions: Research & Editorial, Production, Sales & Marketing, and Technology
Future
Continuously providing practical solutions through Taxmann Advisory
Editorial and Research Division
Over 200 motivated legal professionals (Lawyers, Chartered Accountants, Company Secretaries)
Monitoring and processing developments in judicial, administrative, and legislative fields with unparalleled skill and accuracy
Helping businesses navigate complex tax and regulatory requirements with ease
Over 60 years of domain knowledge and trust
Technology-driven solutions for modern challenges
Ensuring perfection, skill, and accuracy in every solution provided
Income Tax
Corporate Tax Advisory
Trusts & NGO Consultancy
TDS Advisory
Global Mobility Services
Personal Taxation
Training
Due Diligence
Due Dilligence
Advisory Services
Assistance in compounding of offences
Transactions Services
Investment outside India
Goods
Transaction Advisory
Business Restructuring
Classification
Due Diligence
Training
Advisory
Trade Facilitation Measures
Corporate
Corporate Structuring
VAT Advisory
Residential Status
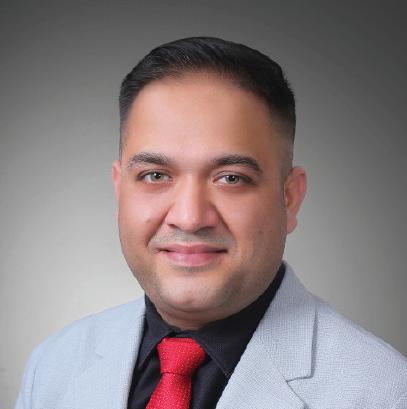
Naveen Wadhwa Research and Advisory [Corporate and Personal Tax]
Chartered Accountant (All India 24th Rank)
14+ years of experience in Income tax and International Tax
Expertise across real estate, technology, publication, education, hospitality, and manufacturing sectors
Contributor to renowned media outlets on tax issues
Vinod K. Singhania
Expert on Panel | Research and Advisory (Direct Tax)
Over 35 years of experience in tax laws
PhD in Corporate Economics and Legislation
Author and resource person in 800+ seminars
V.S. Datey
Expert on Panel | Research and Advisory [Indirect Tax]
Holds 30+ years of experience
Engaged in consulting and training professionals on Indirect Taxation
A regular speaker at various industry forums, associations and industry workshops
Author of various books on Indirect Taxation used by professionals and Department officials
S.S. Gupta
Expert on Panel | Research and Advisory [Indirect Tax]
Chartered Accountant and Cost & Works Accountant
34+ Years of Experience in Indirect Taxation
Bestowed with numerous prestigious scholarships and prizes
Author of the book GST – How to Meet Your Obligations', which is widely referred to by Trade and Industry
Manoj Fogla
Expert on Panel | Research and Advisory [Charitable Trusts and NGOs]
Over three decades of practising experience on tax, legal and regulatory aspects of NPOs and Charitable Institutions
Law practitioner, a fellow member of the Institute of Chartered Accountants of India and also holds a Master's degree in Philosophy
PhD from Utkal University, Doctoral Research on Social Accountability Standards for NPOs
Author of several best-selling books for professionals, including the recent one titled 'Trust and NGO's Ready Reckoner' by Taxmann
Drafted publications for The Institute of Chartered Accountants of India, New Delhi, such as FAQs on GST for NPOs & FAQs on FCRA for NPOs.
Has been a faculty and resource person at various national and international forums
the UAE
Chartered Accountant (All India 36th Rank)
Has previously worked with the KPMG
Taxmann Delhi
59/32, New Rohtak Road
New Delhi – 110005 | India
Phone | 011 45562222
Email | sales@taxmann.com
Taxmann Mumbai
35, Bodke Building, Ground Floor, M.G. Road, Mulund (West), Opp. Mulund Railway Station Mumbai – 400080 | Maharashtra | India
Phone | +91 93222 47686
Email | sales.mumbai@taxmann.com
Taxmann Pune
Office No. 14, First Floor, Prestige Point, 283 Shukrwar Peth, Bajirao Road, Opp. Chinchechi Talim, Pune – 411002 | Maharashtra | India
Phone | +91 98224 11811
Email | sales.pune@taxmann.com
Taxmann Ahmedabad
7, Abhinav Arcade, Ground Floor, Pritam Nagar Paldi
Ahmedabad – 380007 | Gujarat | India
Phone: +91 99099 84900
Email: sales.ahmedabad@taxmann.com
Taxmann Hyderabad
4-1-369 Indralok Commercial Complex Shop No. 15/1 – Ground Floor, Reddy Hostel Lane Abids Hyderabad – 500001 | Telangana | India
Phone | +91 93910 41461
Email | sales.hyderabad@taxmann.com
Taxmann Chennai No. 26, 2, Rajan St, Rama Kamath Puram, T. Nagar
Chennai – 600017 | Tamil Nadu | India
Phone | +91 89390 09948
Email | sales.chennai@taxmann.com
www.taxmann.com
Taxmann Bengaluru
12/1, Nirmal Nivas, Ground Floor, 4th Cross, Gandhi Nagar
Bengaluru – 560009 | Karnataka | India
Phone | +91 99869 50066
Email | sales.bengaluru@taxmann.com
Taxmann Kolkata Nigam Centre, 155-Lenin Sarani, Wellington, 2nd Floor, Room No. 213
Kolkata – 700013 | West Bengal | India
Phone | +91 98300 71313
Email | sales.kolkata@taxmann.com
Taxmann Lucknow
House No. LIG – 4/40, Sector – H, Jankipuram Lucknow – 226021 | Uttar Pradesh | India
Phone | +91 97924 23987
Email | sales.lucknow@taxmann.com
Taxmann Bhubaneswar
Plot No. 591, Nayapalli, Near Damayanti Apartments
Bhubaneswar – 751012 | Odisha | India
Phone | +91 99370 71353
Email | sales.bhubaneswar@taxmann.com
Taxmann Guwahati
House No. 2, Samnaay Path, Sawauchi Dakshin Gaon Road
Guwahati – 781040 | Assam | India
Phone | +91 70866 24504
Email | sales.guwahati@taxmann.com