Colleagues - The Official SV Partners Newsletter - Issue 51 March 2026
COLLEAGUES
PAYDAY SUPER
Biljana Vuckovic (Senior Manager) | Melbourne
From 1 July 2026, Australia’s superannuation system will take a major step forward with the introduction of “Payday Super.” This reform is designed to ensure workers receive their super contributions faster and more transparently than ever before.
Why Is This Change Happening?
The reform aims to:
• Ensure workers receive their super sooner
• Reduce unpaid or late super
• Improve transparency and tracking
• Strengthen retirement savings over time
When super is paid earlier and more frequently, it starts earning investment returns sooner. Over decades, this can significantly increase retirement balances due to compound growth.
How the Current System Works
Under the existing framework:
• Employers calculate super contributions each quarter
• Payments must reach employees’ super funds by quarterly deadlines
• Delays sometimes go unnoticed until months later
How Payday Super Will Work
From 1 July 2026:
• Super contributions must be paid at the same time as salary and wages.
• Payments will be processed through payroll systems in real time.
• Reporting will align more closely with Single Touch Payroll (STP) processes.
This means if your employees are paid on a Friday, your super contribution must also be processed that same day.
Employers will need to:
• Update payroll systems
• Improve cash flow management
• Ensure compliance with tighter deadlines
While there may be initial administrative adjustments, modern payroll software is expected
to streamline the process.
How Payday Super Increases Director Penalty Notice (DPN) Risk
• Each missed payment can create a super shortfall liability
• Non-payment becomes visible much earlier
• The ATO can identify compliance issues faster
• Missing one pay cycle immediately creates a shortfall
• Errors cannot be quietly corrected before quarter-end
• This removes a buffer period that previously protected directors
Directors will need to:
1. Fund super every pay cycle
2. Ensure payroll systems automatically remit super
3. Monitor real-time cashflow
4. Act quickly if payments are missed
Failure to do so may result in:
• Super Guarantee Charge (SGC)
• Administrative penalties
• Director Penalty Notices
• Personal recovery action by the ATO
If super obligations are not reported or paid within statutory timeframes, the DPN can become a “lockdown” DPN.
Payday Super doesn’t change the existence of DPNs, but it increases the likelihood that directors will be exposed to them because super liabilities will arise and be detected much more frequently and much sooner.
For more, scan the QR below to read New Payday Super and its Cash Flow Compression by Adam Thorpe (Associate Director | Brisbane)
A NEW HOPE FOR LIQUIDATORS: CLAWING-BACK STATE TAXES FOR THE BENEFIT OF CREDITORS
Matthew Hudson (Director), Nicholas Davies (Senior Accountant) and Henry Luders (Graduate) | Brisbane
One of the first tasks upon appointment as liquidator is to assess the asset pool and identify recoverable claims. Whilst no two insolvencies are alike and assets are never guaranteed, if the Company was trading, claims against statutory bodies (such as the Australian Taxation Office or a State revenue authority) represent a reliable pathway to achieving a return for creditors. A recent decision from the Federal Court of Australia has further strengthened that pathway.
To this effect, the Federal Court of Australia has issued a unique denial to a statutory body seeking a defence under section 588FG (2) of the Corporations Act 2001 (Cth) (Act). The relevant case is Kirk v Commissioner of State Revenue [2026] FCA 192; given the demands on your time, we have done the heavy lifting and broken it down below.
Key Points
• The total unfair preference quantum claimed by the Liquidator against the Queensland Revenue Office (QRO) was $2,820,166.58.
• The Court ruled in favour of the Liquidator, awarding $2,820,166.58 plus interest.
• Substantive evidence to the state of mind of relevant persons will be necessary rather than providing a limited recollection of the events for a successful defence. In other words, the Court will not look favourably on poorly explained absences of key personnel or information.
• The QRO was required to prove that it had no reason to suspect, and/or had no knowledge, that the companies were insolvent at the time the QRO received each payment. Whilst proving the absence of something is inherently difficult, the Court held that the QRO fell short of discharging that burden.
Background
Prior to the appointment of the Liquidator on 2 February 2022, the companies of ARG Workforce Pty Ltd (Workforce) and ARG Payroll Pty Ltd (Payroll) operated labour hire businesses, which formed part of a wider group of companies known as ARG Group. Both companies had been subject to investigation by the QRO with regard to their statutory liabilities and were subsequently issued notices of default assessment. This was followed by various warning notices and final payment reminders over the following two years.
Workforce and Payroll made various payments to the QRO that amounted to $2,474,375.01 and $345,791.57, respectively. These payments occurred during the six month relation-back period, being the period leading up to the appointment of the Liquidator. The Liquidator formed the view that these transactions may be clawed back as unfair preferences, pursuant to ss 558FA and 588FE of the Act. The QRO sought to rely upon a good faith defence under s 588FG(2) of the Act.
Issues
The key issues before the Court were firstly whether the circumstances in which QRO become involved in the transactions was in good faith. Secondly, whether QRO in its dealings and investigations had reasonable grounds for suspicion that Workforce and/or Payroll were insolvent and whether a reasonable person given the circumstances would have no justification for not having such a suspicion.
Findings
The Court examined what the QRO's officers actually knew and believed at the time each payment was received. Under s 588FG(2)(a), the QRO bore the burden of positively establishing that it acted with honesty and propriety at the time of each transaction. It could not simply assert good faith; it had to prove it and failed to do so.
The affidavit evidence filed by six QRO employees added little beyond what the documentary record already showed. The witnesses stated they had no recollection of their dealings with Workforce or Payroll. Given that the character and sufficiency of evidence is a key consideration in assessing whether the onus has been discharged, this fell short of what was required. Another challenge before the Court was to assess whether those witnesses provided were the only QRO employees whose state of mind and knowledge was of relevance.
Given the determination that the criteria under s 588FG(2)(a) were not established, little time was spent on s 588FG(2)(b). However, the Court noted that the onus on the defendant (i.e. QRO) in establishing this criteria is strenuous, due to the requirement to prove negative propositions. This would require understanding of the knowledge of all relevant QRO employees at the time of transaction. For similar reasons encompassed in the assessment of the s 588FG(2)(a) criteria, the Court was unconvinced that first limb of the s 588FG(2)(b) criteria had been satisfied and therefore consideration of the second was redundant.
Ultimately, the Court ordered the plaintiffs claim be paid in full plus interest. This is a significant win for the insolvency profession and the general body of creditors. The decision sets a clear precedent for future unfair preference recoveries against statutory bodies. The timeframe for an appeal is still active however its success is unlikely.
Please contact the SV Partners team for a confidential discussion on how we can assist.
CAPITAL GAINS TAX AND BANKRUPTCY
Hillary Orr - Consultant | Adelaide
Recent changes to the way Capital Gains Tax (CGT) on assets subject to CGT is treated in a bankruptcy may cause some significant issues for bankrupts. The changes and associated implications are discussed in this article.
Background
Prior to 2021 a trustee realising an asset of a bankrupt estate that attracted CGT was not liable for the CGT component of any realisation. The bankrupt was responsible for the capital gain. This practice arose from the interpretation of s106 – 30 of the Income Tax Assessment Act 1936 (ITAA) which considered the asset to still be the bankrupt’s asset even though it vested in the trustee.
In 2021 the Australian Taxation Office (ATO) reviewed the provisions of s160-30 and s254 of the ITAA and determined that a trustee was liable to account for the tax on any gain. It was recognised that the changes could create difficulties for the trustee in calculating the gain without knowing the personal circumstances of the bankrupt during the period of ownership of the asset and identifying any allowable deductions. This is particularly relevant in circumstances where the bankrupt is uncooperative.
The practice adopted by trustees prior to 2021 had been in place for decades. As a consequence, there was concern by trustees about the historical position and the challenges that would be faced in accounting for CGT. In 2022, a Queensland trustee applied to the ATO for a tax ruling as to whether he was liable in his capacity as trustee for CGT on two properties he sold. The ATO determined that he was liable and that s254 of the ITAA applies to trustees in bankruptcy. The trustee appealed the tax ruling which served as a test case for the issue. The appeal decision was handed down in July 2024 and determined that a trustee was liable.
How Is the Capital Gain Calculated
Although the calculation of CGT liability is uncharted water as the process is in its infancy there are some underlying issues that can create problems for bankrupts.
A trustee must register for a separate tax file number for the bankrupt estate where there is likely to be a capital gain on the sale of an asset. Annual tax returns for the bankrupt estate are required to be lodged and capital gains recorded in the year in which they are generated. The trustee receives the benefit of the tax thresholds when the CGT liability is calculated.
The CGT liability does not arise until an income tax assessment is made.
A bankrupt is required to include the capital gain in their income tax return which will also include income from other sources. While they receive a credit for the tax paid by the trustee there will always be a shortfall for the bankrupt, if they have generated any additional income during the year, because the bankrupt does not receive the benefit of the tax-free threshold to which the trustee is entitled.
If the bankrupt does not declare the capital gain in their income tax return the ATO will issue an amended assessment once it receives a tax return from the trustee. If the additional tax payable is significant it could result in the bankrupt needing to declare themselves bankrupt.
General Comments
We note that the timing of the CGT event is critical and where the CGT event occurred prior to the bankruptcy, any debt owing on the CGT will be subject to the bankruptcy and therefore not otherwise payable.
A mortgagee in possession is not subject to the CGT provisions and in some cases, a better result may occur for all parties if the mortgagee takes control of the sale process.
If any of your clients become bankrupt and have an interest in property which is likely to be subject to CGT, we recommend that the bankrupt and/or their advisors liaise with the trustee to assist with the quantification of any allowable deductions.
Please do not hesitate to contact us if you require further information in relation to this topic.
CASE STUDY: MT ISA RODEO
Matter managed by Michael Brennan (Director | Townsville)
Behind every matter is a turning point, where uncertainty meets clarity. The situations are often complex, time-sensitive and high stakes but with the right approach, they can lead to clear, practical outcomes.
Today, we are sharing a recent case study that highlights how we work alongside clients and stakeholders to navigate these challenges and deliver results.
Preserving an Icon: Saving the Mt Isa Rodeo Through Strategic Intervention
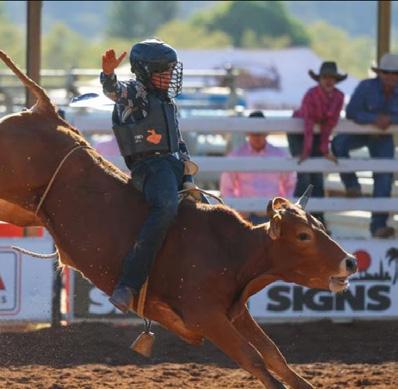
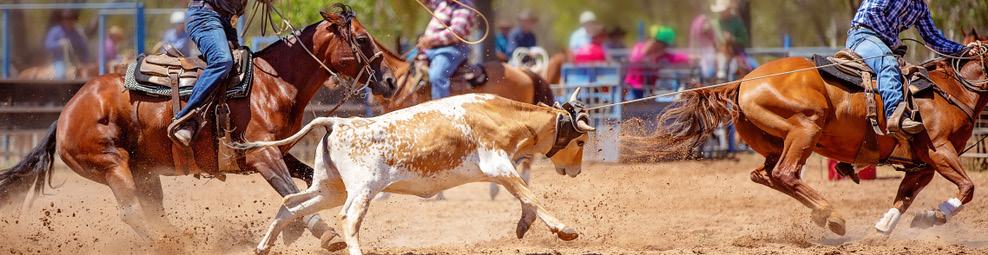
The Mt Isa Rodeo is an iconic outback event, renowned as the largest rodeo in the southern hemisphere. From humble beginnings, it grew into a cornerstone of regional tourism and community identity. When financial pressure placed the future of the 2025 event at risk, SV Partners was appointed to help stabilise the situation and preserve this much-loved institution.
Challenges Faced
At the time of appointment, the organisation faced a critical funding shortfall and was unable to meet the costs required to proceed. The challenge extended beyond financial distress as the Rodeo was operating under intense public scrutiny, with strong community sentiment and reputational stakes for all stakeholders involved.
Strategic Approach
SV Partners took a collaborative, solutions focused approach. By prioritising stakeholder engagement and working closely with government representatives, advisors, and community stakeholders, the team helped reset confidence and create a viable path forward. Recognising the importance of narrative in a high-profile matter, specialist communications expertise played a key role in maintaining transparency and trust throughout the process.
Results and Impact
The outcome was a funding led solution that ensured the continuity of the Rodeo. SV Partners helped secure $2 million in funding, enabling the event to continue operating and transition into public ownership. In addition, $1 million in value was realised, with creditors estimated to receive returns of approximately 40 cents in the dollar.
This engagement demonstrates SV Partners’ ability to navigate complex, high profile matters where technical expertise, strategic thinking, and stakeholder alignment are equally critical. Most importantly, it ensured the survival of an iconic Australian event for future generations.
MEET OUR TEAM
Our team are highly experienced and skilled professionals that are equipped to handle even the most complex of scenarios in a sensitive manner. With a team of leading experts situated around Australia, our specialists work within a diverse range of industries and understand that each business is unique and require timely and cost-effective solutions.