
LAW&TAX
Greek Freak and celebrity trademarks
• Basketball star’s nickname is at the centre of legal proceedings against retailers to enforce his rights
Gaelyn Scott
ENSafrica
One ofthe biggest names inUS basketball right nowis Giannis Antetokounmpo.
Antetokounmpo is huge in every way and he’s the NBA’s current MVP(Most Valuable Player). Foryears Antetokounmpo has beenall over thesportsnewsbutnowheis making intellectual property news too. That’s because he’s become involvedin trademark disputes.
Thename GiannisAntetokounmpo hardlyrolls off the tongue. Whichmay be why the basketball star has a nickname, the Greek Freak.
If you’re thinkingthis doesn’t sound like a very nice name, the moniker does, of course, refer to both the star’s heritage andhis sporting
prowess. It’sthe nickname that is at thecentre of the trademark proceedings. Nicknames are common in the worldof sport. Kobe Bryant wasThe Black Mamba orjust plainMamba, whereas LebronJames is King James.The world’s greatest male tennisplayer is Fed-ex, followedclosely by Rafa. Themost charismaticof the currentcrop ofheavyweight boxers isthe Gypsy King, whereasthe most newsworthy footballmanager is the Special One. In SAwe like togive our
WHEN YOU HAVE TO SCRAPE BY ON AN ANNUAL SALARY OF $25M IT’S NOT A BAD IDEA TO CREATE ADDITIONAL REVENUE STREAMS
sports personalities nicknames too. Remember Biff (Graeme Smith), Rhoo aka The Chief (LucasRadebe) and Nasty Booter (Naas Botha)?
IngolfwehadtheBigEasy (Ernie Els) andthe big daddy of them all,the Black Knight (Gary Player), who has recently been involved in legal proceedings for unpaid royalties witha companyrun by his sonMarc (awkward), These proceedings have resulted in PlayerSnr getting a $5m payout.
In some casesit may be the sportsperson or team who creates the nickname, but in others it’s the fans, as famously happened in the case of Bafana Bafana,a name eventually and reluctantly acknowledged by the SA Football Association after ithadbecome clear it wasn’t going to go away.
But back tothe Greek Freak. What Antetokounmpo
is doingis institutinglegal proceedings to enforce his rights againsta numberof companiesin theUSusing his nickname without approval.In anarticlethat appearedon June3 in The TMCA headlined “The Greek Freak Flexes His Trademark Muscles”, we’re told these proceedings involvevarious online retailers, and the unauthorised goods feature the nickname and Antetokounmpo’s likeness.
So what exactlyis going on here? Well,when you have toscrape byon an
annualsalaryofnomorethan $25m it’snot abad ideato create some additional revenue streams.
And thatis whyAntetokounmpo has obtained trademark registrations for the name Greek Freak.
Healsohaspendingapplications for Greek Fr34K, with 34 being his vest number. He claims to have commercialised his nickname by licensing it, togetherwith his image, to various companies.
This storyillustrates the extraordinary commercial opportunities that come the
way of famous sportsmen andwomen, andindeedall celebrities. These opportunities aren’t limitedto the celebrities’ real names; they might extend to nicknames, likenesses, signatures,catchphrases and squad numbers. What the smart,or welladvised, celebrity does is register their name, nickname, signature,likeness, catchphraseandthe likeasa trademark. They register in the countrieswhere theyfeel they are most likely to need
ON THE BALL
BUSINESS LAW & TAX
E-commerce risk protection
• Tips, tools and methods to use to grow brands in the burgeoning online sales business
Maureen Makoko Adams &Adams
Covid-19 has completely changed dayto-day life when it comes to purchasing goods.
With online shopping increasingly becomingthe “new normal”,it isimportant forbrand ownerstoconduct full self-reflectionon how they dobusinesses locally and internationally. This includes consideringbrand protection, brand related risks ofrunning ane-commerce businessand any steps that maybe taken to mitigate those risks.
China is deemedto be the largest andfastest growing e-commerce marketin the world withmore than 632-million internetusers. It is estimatedthat China’s e-commerce salesmake up 3.2% ofthe country’s GDP which is compared to 2.7% in the US. Itis also estimated that China’s e-commerce represents more than 50% of the totalglobal e-commerce spending.
Inaddition, Chinahasthe highestnumberofintellectual property applicationsin the world with 1.862-million invention patentapplications, 25-million trademark applications between2007 and 2019 and481,793 intellectual property disputecases recorded in 2019 alone.
ThisindicatesthatChinais a lucrative marketfor brand owners lookingto expand their businesses.
BRAND RELATED RISKS IN CONDUCTING AN E-COMMERCE BUSINESS IN CHINA
Thelatesttrendsinintellectualpropertyenforcementhave shown thatthe following risks are prevalent in e-commerce business in China:
● Intellectual propertylitigation is on therise in China as multinationalcompanies and competitorsare becoming more activein enforcing their rights;
● Chinese e-commerce platforms adoptstrict selfpolicing policiesin accordance with thenew e-com-
Greek
Freak and trademarks
mercelaw tolimit theirown liability. Thismeans e-commerce platformowners take great care inhow they deal with e-commercebusinesses that are operating on their platforms; and
● IP squattersand extortionists arehijacking foreign brands andexploiting new technology tolodge complaints againstthe legitimate brand ownerson e-commerce platforms.This has devastatingandcostlyconsequences for affected brands.
WHAT CAN FOREIGN BRAND OWNERS DO |TO SAFEGUARD THEIR RIGHTS?
Beloware tipsthat canbe adoptedtominimisetherisks highlighted above:
● Ensureallthebrandsinthe business arecleared foruse andregistration andareregistered. China follows a first to file system.This means the
CAREFULLY REVIEW THE IP POLICY AND OTHER BYLAWS OF THE E-COMMERCE PLATFORM THAT WILL HOST THE BUSINESS
firstperson orentitythat applies for atrademark will obtain registration regardless whethersuch personor entityisnot theownerofthat trademark.Brandownersare welladvised toconduct trademark searches,file trademark applications, policeuse oftheir brandsin China and bequick to take actionif anyinfringements occur. It is possible to register brandswithout aphysical presence in China.
● Carefullyreview theIP policy and other bylaws of the e-commerceplatform that willhost thee-commerce business before entering into binding agreements.
On January1 2019,the NewE-Commerce Lawof theRepublic ofChinawas promulgated. Thenew lawis aimedat safeguardingthe legitimaterights andinterests ofe-commerce entities,regulating e-commerce conduct,
CONTINUED FROM PAGE 1
protection. These will certainly becountries thatare commercially important, and they mayalso becountries where piracy is very likely. They registertrademarks
maintaining market order andpromoting thecontinuousand sounddevelopment of e-commerce.
One crucial featureof the new law is that online businessesare nowrequiredto registertheir businessesand acquire allcompulsory licences beforeactively trading one-commerce platforms.
The framework of the newlaw iscomprehensive. Individual chapterscover: e-contracts ande-payments; guarantees for e-commerce transactions; data protection
forthegoods andservicesin respectof whichtheyare most likelyto enterinto licensing arrangements, such as clothing, sporting goods and cosmetics, but licensing opportunities might also exist for a host of services.
andpromotion ofconsumer protection, faircompetition andmechanisms fordispute resolution; cross-border commerce;and theprovision of substantial civil and criminal penalties.
ENSURE ALL THE BRANDS IN THE BUSINESS ARE CLEARED FOR USE AND REGISTRATION AND ARE REGISTERED
ROYALTIES
The nextstep isto enterinto licence agreementswith manufacturing orserviceorientated companiesthat thenuse thetrademarkson goods or services.
The celebrity then
These are all-important provisionsthat aforeign company will haveto take into consideration before engagingin ane-commerce business in China.
● Diversifythe businesson multiple e-commerceplatformsto havebackup inthe eventthat thebusiness encountersproblems onone platform.
In China, thereare more than a dozen different crossborder e-commerceplatforms covering different products. It ispossible, and wouldbe prudent,for afor-
receivesroyaltypaymentsfor the use of the trademarks.
The wisecelebrity monitorsthemarkets toensureno unauthorised users are using the trademarks.
eigncompany venturinginto the territory todiversify its e-commerce business by conductingits businesson morethan oneplatform, depending on its products. If one ofthe platformsis adverselyaffected, thecompany willhave flexibilityand beableto carryontradingon the other platform under the same brand.
These are sometools a companymay usetogether withothermethodstoprotect andgrowitsbrandinChinese e-commerce. Verified by Lita-Miti Qamata
If they do find unauthorised use,they enforcetheir rights.Theylet itbeknown that they willnot tolerate any infringements of their rights. Fameis fleeting,andwise celebrities know they need to act quicklyif theywant to make a real fortune.
THE WHOLE PACKAGE
BUSINESS LAW & TAX
Dis-Chem price ruling lacks clarity
• Competition Tribunal’s departure from peremptory wording of act resulted in narrowed
Jeremy de Beer & Aidan Scallan ENSafrica
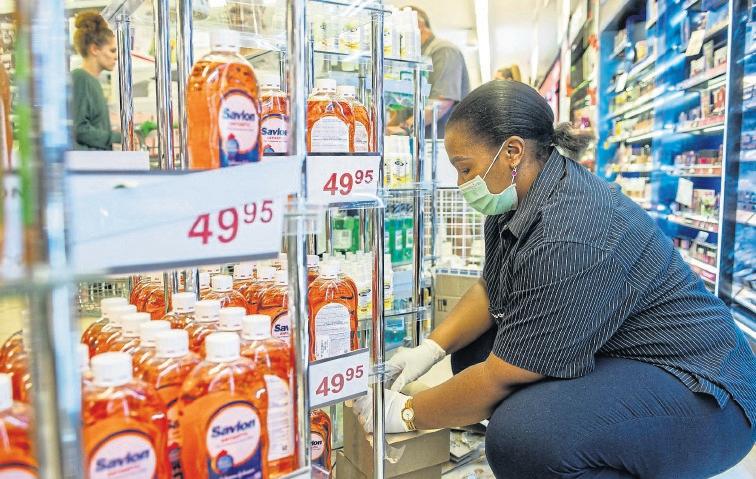
The Competition Tribunal recently handed downits decision against Dis-Chem PharmaciesLimitedinrespectofa Covid-19-related complaint alleging that Dis-Chem charged anexcessive price for varioussurgical face masks during March 2020.
This was thesecond findingby thetribunal inrespect of aCovid-19 excessivepricing complaint(where the parties contestedthe allegation), the first being made against Babelegi Workwear and Industrial Supplies CC.
Thesematters havecontroversially introducedthe concept of “price gouging” into SAcompetition law,and whilethis mayassist inthe fight against “pandemic profiteering”, a closer analysis of the decisionin Dis-Chem raises a numberof concerns regarding theassessment required infuture excessive pricing cases.
Inboth theDis-Chemand Babelegi decisions,it was accepted that price gouging is aspeciesofexcessivepricing.
Price gougingis broadly understood to be an unfair increase inthe priceof essential goods duringa time ofcrisisthat has resulted in supply or demand shocks.
Many jurisdictions, particularlyin theUS, havecreated “simple tests” to determine
whether price gouging has occurred by comparing the pre-crisis prices with the prevailingprices ofafirm, and assessing whether there were anycost increasesthat justified the price increases.
Thistestwasincorporated into the Competition Act, 1998 (as amended) through Consumer Protection RegulationspublishedonMarch19 2020 to assist the authorities in establishing cases of excessive pricing. However, theapplication ofthis simpletest isdifferent inSA insofarasexcessive pricing underthe actentails an abuse of dominance, thereby introducing an
THE TRIBUNAL ALSO DISMISSED DISCHEM’S RELIANCE ON THE FACT ITS PRICES WERE STILL LOWER
THAN THOSE OF ITS COMPETITORS
important prerequisitebefore the simple test can find application: the establishment of dominance within the relevant market.
In theDis-Chem case,the tribunal departed from the traditional approach to establishing dominance as it did notmake anyattemptto assess competitive factors in that market to determine market power and dominance. Instead, the tribunal
assessment
accepted a somewhat circularargumentadvancedbythe Competition Commission based on inferential reasoning, that because Dis-Chem was able to charge what it did (which itwould nothave been able to do but for the peculiar circumstancesof Covid-19),meansithad“temporary market power” and was therefore dominant.
Essentially, the tribunal foundthatthe existenceofan excessive price proved that Dis-Chem had dominance. While Dis-Chem conceded it is correct, inprinciple, that market power can be inferredfrom afirm’s economic behaviour,it saidthis muststill beassessedwith regard to the competitive factorsinthe relevantmarketas required by the act.
Notably, thetribunal alluded tothe likelihoodthat in crisis situationsmore than one store in close proximity toa competitor could enjoy market power vis-à-vis consumers; an unprecedented approach. Having “established” dominance by way of temporarymarketpower,the tribunal then proceeded to determine whether the price was excessive.
Section 8(1)(a) ofthe act prohibits a dominant firm from charging an excessive price to the detriment of consumers or customers. To determine whether a price is excessive, section 8(3) states that regard mustbe had to whether (i) suchprice is higher than a competitive
COUNTING THE COST
price and(ii) thedifference is unreasonable takinginto accountall relevantfactors, someof whichare listedin section 8(3).
An assessment of excessive pricingtherefore requires,first, adetermination thata firmis dominant; second,an assessmentof what thecompetitive priceis; andthird, anassessmentof whether thedifference betweenthe pricecharged and the competitive price is reasonable,having regardto the factors set out in section 8(3).
Itishere thatthesimple price-gouging test would apply,with theregulations providing that the simple test wouldbea“relevantandcritical factor” in terms of section 8(3), andprima facieindicate excessive pricing. Section 8(2)provides thatwherea primafacie caseofexcessive pricingexists, thedominant firm must show that the price wasreasonable, thusreversing the onus.
MANY JURISDICTIONS CREATED ‘SIMPLE TESTS’ TO DETERMINE WHETHER PRICE GOUGING HAS OCCURRED
The tribunal noted that though the simplepricegouging test “is supportedby ample authority”, theregulations couldnot beapplied directly as they were only promulgatedafter thecomplaintperiod, andnothingin theregulations rebutsthe presumption that legislation cannot applyretrospectively. However, because the list of relevantfactors providedin section8(3) isnonexhaustive, thetribunal usedthisleeway to “import” the simple pricegouging test from the regulationsandapplyitasoneofthe relevant factors
The tribunalarguably erredinits approachtothe factors in section 8(3) thereafter.The wordingof thesectionis peremptory:allrelevantfactors mustbetaken intoaccount indetermining whether a price is excessive. Whilethe tribunalwascorrect infinding that notall the listed factors will be relevant ineverycase, itdidnot engagewith severalfactors relied on by Dis-Chem to determine whether they wereindeed relevant,but focused only onfactors that bear relevance inthe simple test for price gouging.
In restricting itselfto indirectlyapplying thesimple price-gougingtest tothe exclusionof otherpotentially relevantfactors, thetribunal showeda departurefromthe
peremptorywording ofthe act and focusedon whether theprices werehigherthan the comparatorprices, namely the pricesthe firms charged pre-Covid-19,rather thancompetitive prices,as required by the act. This fundamentally changedthe inquiry,as thoughitisevidentthatprices increased, itis notclear to what extentcompetition failed, ifany. Thetribunal also dismissed Dis-Chem’s relianceonthe factthatits prices were still lower than those of its competitors, so there couldnot be “detriment to consumers” as required by section 8(1)(a).
Further, the tribunal did not justify whythe other factors Dis-Chem sought to rely on were irrelevant or of insignificant weight. By excluding these, thetribunal ultimatelyended upapplying theregulations afterfinding thatapplying themwould contravene the rule of law. Unfortunately, theincorporationand applicationof pricegouging hasarguably resultedinsomeconfusionas tohow excessivepricing caseswill bedeterminedin future. Thismay bebecause bothDis-Chem andBabelegi wereheard onanurgent basis, when thetribunal couldhave benefitedfrom more time andargument on these novel points of law.
Fraud, arbitration and spelling out what you intend
Michael Gradidge ENSafrica
Is adispute resolutionclause in acontract thatcame about astheresult offraudand misrepresentation regarded asinvalid? Thisis aquestion the SA SupremeCourt of Appeal(SCA) recentlyconsidered in Namasthetu Electrical (Pty) Ltdv City of Cape Town and James Robert Garner NO.
Inthis case,Namasthethu had been awarded a contract
to render servicesto the City of CapeTown througha tender process. However, therewere laterallegations thatNamasthethu hadmade fraudulent representations during the process. As such, thecitysought tocancelthe contract, and Namasthethu disputed this.
STICKING POINT
Thesticking pointwas whetherthedisputehadtobe adjudicatedby arbitrationin accordancewith aclausein
the contract, or whether this clausewas invalidbecause the contract was induced by fraud. Ifinvalid, thenthe disputewould needtoproceed in court.
Logically,it wouldseem that ifthe contractis invalid because it was induced by fraud,then theclausereferring any disputesto arbitrationwouldalsobeinvalidand the dispute should proceed to court.However, thispresupposes that the allegations of fraudare true.If not,the
contract and thearbitration clause would bevalid and thedispute shouldhavebeen referred to arbitration.
Thecourt confirmedits previousapproach thatfraud invalidatesthe contractas well as thearbitration clause. It restated the general principlethat disputesregarding thevalidity orenforceability ofcontracts inducedbyfraud are not generallyintended to be arbitrable.
However, the court (referringto Englishauthority)held
thatineachcase, itisaquestionof interpretationofthe arbitrationclause todetermine if theparties intended thatadisputeastothevalidity ofthecontract inthefaceof fraud shouldbe submittedto arbitration rather than court.
Ifthe partiesintendthis, thelanguageofthearbitration clause would have to be clear and unequivocal.
The courtfound thatsuch aclear provisionwasnot foundin thecontract inthis case and the referral to
arbitrationwas invalid.Asa result,it confirmedthe previous decision to set aside the arbitration award.
CLEAR WORDING
It is clear from this case that if partiestoacontractwantdisputesregardingthevalidityof the contract when fraud is alleged to bereferred to arbitrationrather thanproceedto court,they shouldexpressly provide for thisin the contract, inclear andunequivocal wording.
A worker wearing a protective face mask replenishes stocks of sanitising products inside a DisChem store. /Waldo Swiegers/Bloomberg
Distressed M&A: moving fast matters
• Buyers need to consider whether it is better to buy an asset inside or outside of business rescue
Tony Lee & Justin Balkin
While a buyer may be able to acquire a goodasset atasignificantly discounted pricethrough the business rescueprocess, a buyerwould needtoconsider whetherit isbetter to acquire theasset insideor outside ofthe business rescue process.
A buyer and a seller should both makeuse of an experienced legal M&A restructuring teamto help them navigatethis complex aspect of the distressed M&A process.
FAIR AND FLEXIBLE PRICING MECHANISM
Akey issuewhennegotiating anM&A dealis theagreed pricing mechanism and related adjustments.There is almost always agap in expectations onprice and even more so in a distressed M&A scenario.
Thinkhowbest tousethe pricing mechanismssuch as the locked box (fixed price plus aninterest component), working capital,capex and net debtadjustments and earn-out (upfront payment plus aperformance related component) tobridge this valuation gap.
Buyers are not willing to
overpay for a distressed asset and willsee thedistressed sale asan opportunityto acquire the asset cheaply.
No one likes the idea of selling cheap, andsellers are going to wantto attempt to maximise value.
An earn-outmechanism can providesome protection onboth sidesbecausethe buyer canreceive downside protection ifthe asset acquired doesnot maintain the same levelof performance asbefore Covid-19, andthe sellerhasa chanceto receiveapurchasepricesimilar to the oneit would have received beforeCovid-19 if performance improves.
Aworking capital,capex and/or netdebt adjustment mechanism post-implementation may also provide some downside andupside protection if there isa negative or positive changeto thefinancial positionat closing compared withthe financial position whenthe initial acquisition valuation is done.
Boththesepricingmecha-
THE
TRIGGERING
OF THE FAILING FIRM DEFENCE DOES NOT MEAN THAT THE TRANSACTION WILL AUTOMATICALLY RECEIVE APPROVAL
nismstendto speedupthe negotiations because of their inherent upside and downside protections.
AVOID MAKING A MEAL OF A MAC
Justas buyerswill wantto preserve “walk-away” protections by including a material adverse change (MAC) condition, sellers aregoing to resist these “free options” Backward andforward negotiations on a MAC clause are time consuming.
AMAC shouldbe usedto protect a buyer for a significantdeterioration ofthetarget asset between signing a completion.It shouldbeused for thispurpose only,and not as an opportunityto walk away because of buyer’s remorse
Less significant deteriorationsinthetargetassetcanbe catered for ina well-crafted price mechanism.
BE NIMBLE
The buyer should do a targeted due diligenceon the main issues andthen usewarranties and indemnities (W&I) more extensively.
W&I insurancecover should be taken out to allocate risk. The premium payable canbe factoredinto the price.
Beware thatW&I insurance policies will include standard exclusions relating
TWO BECOME ONE
to the impactof Covid-19 as well as mandatory and/or advisory restrictionsissued by government authorities. Buyerswillwant toshiftthe exclusion risk tothe seller and theseller willneed to understand the consequence of takingon thisrisk asan uninsured warranty.
COMPETITION REGULATORY APPROVAL
If required, thesubmission of a mergernotification tothe competition authorities is a joint obligation. A notifiable transaction cannot be implemented until approval has been obtained. This could delay implementation of the transactionas wellasreceipt of much-neededfunds bya distressed seller.
The buyer andthe seller will needto worktogether to submit the merger notification assoon aspossible. Itis usefulto engageanexperienced competition law team toassist innavigatingthis complex regulatory requirement.Inpractice,itispossible to submitthe mergernotification before the acquisition agreement is signed, provided that the elements of the transaction giving rise to the change of control are clear.
For example,the merger notification can be submitted onthe basisof acomprehen-
Traders need to brush up on new
Virusha Subban & Prenisha Govender Baker McKenzie Johannesburg
Until now, SA’sborder management,which includesthe tasks of securingthe country’sborders andprotecting itsnationalinterests,hasbeen managedby multipleorgans of state.
Despite thismultiparty involvement, border management has been an ongoing challengeand hasresultedin increasinglevels ofcrossborder crime. Thetrade in illicitcigarettes, forexample, is one of the many crossbordercrimes SAhas hadto
deal within recentyears, with suchtrade increasing during thenational lockdown.On July 21, however, the BorderManagement Authority Act 2 of 2020 came into force.
The actrecognises the need forintegrated andcoordinated border management,in alignmentwiththe constitution, as well as international and domestic law.
Theact seekstooversee themanagementoflegitimate trade and tosecure crossborder travel,prevent illegal cross-border movementand the smugglingand trafficking of humans,protect the
country’s environment and natural resources,and shield thecountryfromharmfuland infectious diseases,pests and substances.
In particular, the act aims to ensure effectiveand efficientborderlawenforcement functionsat portsofentries andalong thecountry’s borders.Toachieve this,itprovides forthe establishmentof the BorderManagement Authority, theappointment and employmentof border officials, andthe establishment ofan interministerial consultative committee,border technicalcommittee and advisory committees.
sive signed termsheet. When the acquisition agreement is signed, it canbe submitted to the competition authorities as confirmation that the change of control structure has not changed.
Merging partiescan seek to expedite the investigation process on thebasis that a failure to speedily implement the transaction willresult in the demiseof thetarget firm (with knock-on impact for competition and the public interest,inthe formofjob losses).Oneofthefactorsthat is considered in assessing whether ornot amerger transaction islikely tosubstantially prevent or lessen competition is whether the businessor partof thebusiness of a party to the merger has failedor islikely tofail (the “failing firm defence”).
Thetriggeringofthefailing firmdefence doesnotmean that the transaction will automatically receive approval.
Mergers thatsubstantially lessen competition will generally be prohibited. Conversely, when afirm is likely tofailandexitthemarket,this may actually lead to a less competitiveenvironmentrelativetotheimplementationof amerger (wherethefailing firmis absorbedandsustained by anacquiring firm). Amergerbetweenanacquir-
ing firm anda failing firm could thuspotentially neutralise or lessenthe competitive harm causedby the failing firm’s exit.
The Competition Commission,in itsrecentpresentation to parliament, stated thatit isimproving itsprocedures to better manage the expected surge in merger notifications from the Covid19 crisis. Whilethe Competition Commission will still investigate the transactions submitted toit, thisis aclear indicationthattheregulatoris willing toassist insupporting distressed M&A. Theparties toadistressed M&A willneed tomove quicklyand beable tonavigate the complexities and challenges in executing the transaction. Byleveraging outside expertise (such as M&AlegalcounselwithM&A restructuring experience)the buyer and the seller can makeinformeddecisionsthat are likelyto resultin asuccessful transaction with fewer setbacks along the way. Ifyourcompany isonthe brink of financial distress and you are considering selling assets or ifyou are buying assets from a distressed company, it is advisable to get an experienced M&A legal restructuring team on board sooner rather than later.
border agency
Organsofstatesuchasthe SA Revenue Servicewill now be separatefrom theBorder Management Authority.The act does,however, require the authorityto co-operate and co-ordinateits border law enforcement functions with other organsof state, border communities and/or any other persons.
THE ACT RECOGNISES THE NEED FOR INTEGRATED AND CO-ORDINATED BORDER MANAGEMENT
The implementationof the actisexpected toresultin more efficientborder management, which will benefit commercialcrossborder traders.
However,one ofitsaims will be to curb the occurrence ofcross-border crime, with variousobligations and duties imposedon border officials to accomplish this
It is importantfor crossborder transporters, importers andexporters to familiarise themselveswith the act and bemindful of the duties, functionsand powers
of border officials and the circumstances inwhich they may search, seize,arrest and detain goods. With theAfrican Continental FreeTrade Area agreement expectedto be operational soon, boosting cross-border tradein the process, the implementation ofthe actandthe moreefficient managementof trade and movementacross the country’s borders isto be welcomed. However, only time willtell ifthe measures introducedin theact willbe effective in helping SA win the battleagainst cross-border crime.
/123RF ANDRII DODONOV
BUSINESS LAW & TAX
Threat of the other viruses
• Many organisations lack proper protection against cybercrime, even as more staff work remotely
Suad Jacobs ENSafrica
As Covid-19 forces morepeople across the globe to work from home,we are becoming increasingly reliant on technologyto live, work and play.
However, many organisations are ill-equipped to deal with employeesworking remotelyand thecybersecurity risks that come with it.
After SA’s ProtectionofPersonalInformation Act, 2013 came into effect on July 1 2020, it has never been more importanttoensurethesecurity of organisational data. How can companies protectthemselves fromcyberattacks? One way is by implementing theglobal standardssetoutinISOStandards27001, 27005and 27032. Organisationshaveawide arrayof systems,controls, processesand proceduresto safeguardclient dataand company intellectualproperty, such as firewalls, regularpassword changesand multifactor authentication. However, these safeguards can be rendered ineffective if employees compromise them by,for example,accessingwebsites thatareinfected with viruses.
Occasionally, and perhaps dueto economicpressures experiencedby staff (especially nowduring thepandemic),employees mayalso find themselveson theother sideofthe lawbyintentionallycolluding withcyber criminalstomanipulatecompanysystems andclientdata with the promise of financial reward.
Companies such as Life Healthcare,Honda, theWorld Health Organisation, Nedbank,Amazon andMicrosoft haveall experiencedincidentsof cyberattacksin 2020. However,the lawis not necessarily wellequippedto dealwiththe problem.
For example, SA’s current legislation dealingwith cybercrime, primarily the Electronic Communications andTransactions Act,2002, has not kept up with the dynamic and constantly evolvingnatureoftechnology and associated cybercrime.
To worsen things, the new CybercrimesBill, whichwill codify numerousexisting offences and create a variety ofnew offences,has stillnot been passed by parliament.
Further complicating matters is that the effective investigation andprosecution ofthesetypes ofcrimeis complex, requiring specialist skills,and raiseschallenging
issues of cross-jurisdictional co-operation among law enforcement agencies. As such, implementingmeasures toprevent acyberattack fromhappening inthe firstplaceshouldbeatoppriority for companies.
The InternationalOrganisation for Standardisation (ISO) hasissued anumber of standardsthat provideinformationsecurityriskmanagement and cybersecurity guidelines fororganisations. Thefocus ofthesestandards isto tackleinternetsecurity issuesand providetechnical guidancein addressingcommon internet security risks.
RISK ASSESSMENT
ISO27032 recommendsthat anorganisation conductsa riskassessment toidentify relevantrisks. Among the issues thatshould beconsidered are:
● Identifying criticalassets: It is not cost-effective to protect all assetsequally. It is thereforeessential thatcritical assetsare identifiedso that particular care may be taken to protectthem. The designationshould bemade from a business context by consideringwhat theimpact
RUNNING
APPROPRIATE ANTIVIRUS AND ANTISPYWARE SOFTWARE ON SERVERS IS ALSO RECOMMENDED
PROTECT YOUR ASSETS
onthebusiness wouldbeif theassetwere tobelostor degraded.
● Identifying relevant risks: Current risks facedin a business context, aswell as additionaland evolvingrisks, threats and attacks that may becomerelevant whenparticipating incyberspace, should be considered.
● Systemor serviceretirement: Obsolete systemsor services should beretired and all security-related informationshould beinvalidated to ensure thatinterfacing or related systems arenot compromised.
● Consistency: The approachto riskmanagement shouldapply acrossthe entire cyberspace.
The cybersecurity controlsrecommended byISO 27032include serverprotec-
CONSUMER BILLS
tion controls.These areused toprotect serversagainst unauthorisedaccess andthe hosting of malicious content.
These controls include server configuration to ensurethat thereareappropriateaccesscontrolsonprogramsand systemdirectories,enabling audittrailson systemsand theregularly conductof such audit trails.
Running appropriate antivirus and antispyware software onservers isalso recommended.
Policies that govern informationsecurityriskmanagementshould beintroduced, on topof basicpolicies governingthe creation,collection,storage andtransmission of data, as well as corporatepolicy statementsand penalties relating tothe misuseof cyberspaceapplications.
Organisations should includeawareness andtrainingas partof theircybersecurityso thattheyregularly andcontinually raisetheir employees’ awareness to cybersecurity threatsand how toidentify anddeal with these threats.
Having a robust and organisation-specific cybersecurityplan isvitalconsidering that SA has enacted Protectionof PersonalInformation Act.It obligesorganisations to report data breachesand itis thereforeessential foran organisationtotake steps tomanage the riskof a cyberattack and tomitigate against any harm caused. Cyberattacks can have a cripplingeffect onorganisations. Not only can they cause significantdamage toreputation,affect businesscontinuityandresult inthelossof sensitive and confidential information, but damages may alsohave to bepaid to individualswhose datahas been breached.
End-user controls include usingthe latestsupported software applicationswith themost updatedsecurity patchesto ensurethatprogrammes aresecure andany known vulnerabilities have beendealtwith.Antivirusand antispywaretools shouldbe installed and appropriate safeguards implemented. Further controlsinclude usingphishing filtersand enabling personalfirewalls and host-based intrusion detection systems.
Declare violence against the vulnerable a disaster
The latest political game is to say a lot about violence against women and children as the scourge of SA and to do nothing useful about it. There is something that can be done in a way in which we now have lots of experience. The situation must be declared a disaster under the Disaster Management Act.
A disaster, according to the act, includes a progressive human-caused occurrence which causes death or injury and a significant disruption to the life of a community. The definition saysa disaster must be of a magnitude that exceeds the ability of those affected by the disaster to cope with its effects using only their own resources. What could better describe the situation in SA?
Some women are scared to go out and others are scared to go home. Parents of young
girls are racked with anxiety about how to bring up their children safely. Those affected clearly cannot cope with this disaster using only their own resources. Huge resources are needed. Once the disaster is declared, the law allows the government to apply its resources to manage the disaster with a special emphasis on prevention. There is a great deal that can be done.
Speak to women who have been to a magistrate’s court to get protection orders against abusive men. The women get the protection
order but there is nowhere for them to go. Shelters throughout the country have been closed down, leaving the women to go back to their homes to experience worse abuse.
We have seen under the current disaster how factory buildings have been turned into hospitals and havens. There is no reason why the same thing can’t be done to provide shelter for abused women and children.
The police, who seem to have endless time to harass innocent people or overzealously pursue minor misdemeanours under the current disaster, can apply their time, energy and commitment to deal with the issue.
If we can find the resources for courts and justice department officials to deal with the hundreds of thousands of people who have been charged under the
Covid-19 disaster management regulations, we can presumably find the resources to deal with a scourge that directly affects more than half the population and indirectly affects all of us, disastrously.
A major part of the criminal court system must be applied to deal with the disaster. Judicial officers must be properly trained to intervene in cases to prevent the complainant from being revictimised by aggressive lines of questioning.
Judicial officers should adopt a more investigative or inquisitorial approach, directing questioning rather than letting the case unfold before them for better or, often, for worse.
Cases must be properly investigated and endless postponements have to be avoided. The bench should be occupied by at least as many femalejudicial officers
as men to give broad perspective to the issues.
What we need most of all are regional laboratories that can deal effectively and immediately with DNA testing, with properly trained law enforcement officers to gather, preserve and submit the specimens for testing and as evidence. The greatest advance in criminal law in recent times has been the ability to prove guilt or innocence by DNA tests. The absence of immediate testing in this country is a disaster in itself. This commitment alone would make a difference to the number of convictions.
JUDICIAL OFFICERS SHOULD ADOPT A MORE INVESTIGATIVE OR INQUISITORIAL APPROACH
Wouldn’t it be encouraging if we were to witness our president going on television once a month to tell us about the latest actual and financial commitment to dealing with the abuse of women and children? If anything needs a national command council it is this problem. Those on the council can then be tested against their plans and their solutions. Perhaps we can have daily headlines about the number of events reported and the number that have led to a conviction with the same prominence we are now have with the pandemic. We have the legislation, we have the experience and we have the problem. It’s time to deal with this disaster for what it is.
a
PATRICK BRACHER
● Patrick Bracher (@PBracher1) is
director at Norton Rose Fulbright.
/123RF RAWPIXE
BUSINESS LAW & TAX
When sure contracts can’t be trumped
• Good faith, fairness and reasonableness do not provide a freestanding basis for courts to intervene
Dale Hutchinson, Michael Katz & Julius Oosthuizen ENSafrica
The powerof a court tostrike down orrefuse to enforce a contract it considersto be unfair, undulyharsh or unreasonable, hasbeen a controversial one inSA law for some time.
It has long been accepted thata courtmaydo sowhen the contractor itsenforcement is contraryto public policy. However,this hastraditionallybeen inrespectof harmto thegeneralpublic rather thanindividual contracting parties,and courts will only exercise such powers in the clearest of cases.
This approachtraditionally emphasisedthe fundamental notion ofsanctity of contract that contracts freelyentered into should be enforced. However, this raised questionsabout the role of good faith (which embraces notionsof fairness, justice and reasonableness) in SA law of contract and, particularly, thedefence of bad faith(exceptio doli),that many thought to still be available whena partysought to enforcea contractualrightin unconscionable and inequitable circumstances.
In 1988, the then Appellate Division foundthe exceptio doli to be an anachronism thathadnever formedpartof SA modernlaw. Subsequent judicialattempts totreatgood faithasaninformingprinciple of contractlaw werestymied bya SupremeCourt ofAppeal(SCA) judgmentin2002. This judgmentheld thatgood faith an abstractvaluethat underliesthe lawofcontract finds expression in the various rules anddoctrines of contractlaw, andshapesand controls itsdevelopment, but doesnot giveacourt thediscretion to strikedown or refuseto enforceanotherwise valid contract term.
The question aroseas to whether this conservative approach was consistent with the spiritand values of the constitutionand, particularly, the values of ubuntu.
Thefirst opportunityfor the ConstitutionalCourt to pronounce on the issue came
in the2008 Barkhuizen case, overachallenge toatimelimitation clausein ashortterm insurancecontract. A majorityruledthattheconstitution appliesindirectly to contract through common law,and thevehicle forintroducing greaterequity intothe law of contract was public policy rather than good faith.
Inaddition, suchpublic policyis rootedin thevalues of theconstitution and imports thenotions offairness, justiceand reasonableness, whichare reflectedin the values ofubuntu and must be weighedagainst the “profoundly moral principle” ofsanctity ofcontractwhen deciding on its enforcement.
Atwo-stage testwas adopted.First,a clauseina contract, whichappears so unreasonable as tobe contrary to public policy, will be struck down. Second, if the clause survives that test and is accordingly valid, a court mightstillrefuse toenforceit,
THE VALUES EMBRACED BY UBUNTU CAN PLAY A VITAL ROLE IN DEVELOPING THE COMMON LAW OF CONTRACT
if itwouldbe contrarytopublic policy in the particular circumstances of the case.
The ConstitutionalCourt again emphasised the need to infuse contractlaw withthe valuesofubuntu,fairnessand reasonableness in subsequent cases.In the2014 Botha v Rich,it refused to allow cancellation ofa contractforthe purchaseofimmovable property on instalments, when the purchaser hadpaid nearly80% ofthe purchase price and then defaulted on payment, holding thatto allowcancellation would be a disproportionate sanction for the breach.
Meanwhile, theSCA was steadfastin itsview that,until the Constitutional Court ruled otherwise, a court could not refuse toenforce anotherwise valid contract term merely on the ground that, in itssubjectiveopinion,todoso
would be unfair.It kept stating that valuessuch as fairness, justice and reasonableness are not self-standing requirements for the validity or enforcement of contracts, andthat toholdotherwise would introduce an undesirable levelof uncertainty into contractual relations.
This divergence between theSCAandtheConstitutional Courtcaused confusionin courts. An unequivocal judgment of the Constitutional Court on the issue was sorely needed, and presented itself recentlyinthe caseofBeadica CCv Trusteesfor thetime being of the Oregon Trust.
In this case,the National Empowerment Fundhad entered into an agreement witha franchisor,Sale’s Hire CC, to fund the acquisition of franchise businesses by former long-time senior employees of Sale’s Hire CC, as a broad-based blackeconomic empowerment (BBBEE)initiative. The employees established closecorporations which concluded10-year franchise agreementswith Sale’s Hire CC, as well as lease agreements with the Oregon Trust, of which Mr Sale (thesole memberof Sale’s Hire CC) was a trustee.
The leases werefor five years, with arenewal option for a further five years which (as isusual), hadto beexercisedin writingno laterthan six months before the expiry ofthefirst lease.Thelessees failed to exercise their renewal rights timeously and were given noticetovacate the premises shortly before the expiry of their leases. They thenbrought an urgent application before the Western Cape High Court for an order thatthe renewal options had been validly exercised, and prohibiting the trust from evicting them.
Relying on Bothav Rich, Davis J grantedthe order, holding that termination of theleaseswould resultinthe collapse of the applicants’ businessesand thefailureof the BB-BEEinitiative a disproportionatesanctionforthe failure ofthe lesseesto complywiththestricttermsofthe renewal clauses. The decision wasoverturned bythe SCA,which deniedthatSA lawrecognisedsuchaprinci-
ple of disproportionality, and held that noconsiderations of public policy made the renewal clauses unenforceable.
The ConstitutionalCourt granted leave toappeal but, seven to three,ruled against the lessees. The majority judgment, delivered by Theron J, addresses theissueof the properconstitutional approach to the enforcement of contracts, specifically the public policy grounds on whicha courtmay refuseto enforce a contract term and the role of ubuntu
This approachdelivers a much greater degreeof harmonyandcertaintyinthelaw ofcontract,byeffectingareconciliation of the seemingly divergent approaches of the SCA and the Constitutional Court. Themajority doesso by essentially endorsing the approachoftheSCA,butwith certain qualifications, and by limitingthe effectof thedecision in Botha v Rich. The key principlestoemergefromthe judgment are the following:
LIKE ALL LAW, CONTRACT LAW IS SUBJECT TO THE CONSTITUTION AND MUST CONFORM WITH ITS RIGHTS AND VALUES
● Thefreedomofcontracting partiesto regulatetheirown affairs, even totheir detriment,isfounded ontheconstitutionalvalues offreedom anddignity; andtheassociated principle ofsanctity of contractis thebedrockof economicactivity andvital for economic development. The ruleof lawrequires that the law be clear and ascertainable, sothat partiescan regulate conduct accordingly, withconfidence thatthe application of the legal rules
willproduce reasonablypredictable outcomes.
● Like alllaw, contractlaw is subjectto theconstitution andmust conformwithits rights and values.
● The constitutionapplies indirectlyto contractthrough thecommon lawrequirementthata contractmustbe inaccordance withpublic policy,which todayisrooted in theconstitution andthe values it espouses.As stated inBarkhuizen, acontract termcontrarytopublicpolicy will bedeclared invalid.Even if theterm is valid,the court may refuse to enforce it
● A careful balancing act is required:the principlethat contractsfreely enteredinto must be honoured is not the only,nor eventhemost important, principle informingthejudicialcontrolofcontracts;it cannotbeprivileged over other constitutional rightsand values.Ubuntu, whichencompasses thevaluesof fairness,reasonablenessand justice,isnow recognised as constitutional value,andin thescalesof publicpolicy, mayoutweigh sanctity of contract.
● However, abstractvalues such as good faith, fairness andreasonableness donot providea freestandingbasis uponwhich acourtmay intervenein contractualrelationships. A court may not refuse toenforce acontract term simply onthe basis that enforcementwould, inits subjectiveview, beunfair, unreasonable or unduly harsh. Itis only wherea contractterm,oritsenforcement, is sounfair, unreasonableor unjust that itis contrary to publicpolicy,thatacourtmay refuse to enforce it.
● Botha v Richwas concerned witha particularstatutoryregime the protectionofpersons whobuyland underinstalment salecontracts, governed by the Alienationof LandAct, 1981,and
did not introduce a generally applicabletest ofdisproportionality as groundfor not enforcing a contract.
● Thepower ofthe courtto refuse toenforce acontract onpublic policygrounds should be exercisedonly in worthy cases,but that it shouldbedonewith“perceptive restraint” should not lead courts toshrink fromtheir constitutionalduty toinfuse publicpolicy withconstitutional values. The idea that publicpolicy isconcerned only with harm to the general public, ratherthan to individualparties,is alientoSAlaw of contract.
● Theparty whoattacksthe contractor itsenforcement onpublic policygrounds bearsthe onusofestablishing the facts. Where the party has failed to comply with a valid contractterm,itmustprovide an adequate explanation ● Courts are boundby section39(2) oftheconstitution topromote thespirit,purport and objects of the Bill of Rightswhen developingthe commonlaw. Thevalues embraced by ubuntu can play a vital role in developing the common lawof contractto ensure its harmonisation with the requirementsof the constitutionbut thecourts must exerciseresourcefulness and restraintin so developingthe commonlaw. Prudentand disciplinedreasoning isrequired toensure certainty of the law.
In the circumstances of thecase, andindismissing theirappeal, theConstitutionalCourt inparticular emphasisedthat theapplicants had notprovided an adequate explanationfor noncompliancewith theprovisionsoftheir leases.Itwill thereforebe watchedwith interest how the courts apply the aboveprinciples incircumstanceswhere anapplicanthas givenreasonsfor noncompliance.
PAPER
/123RF ZIMMYTWS
BUSINESS LAW & TAX
Digital economy: where do we draw tax lines?
• South African businesses and regulators need to be part of the debate for a new tax era
Michael Hewson Graphene Economics
As theworld continues to evolve tobe more centred around digital services, everything from the way wepurchase and consume media, tothe way we bank is affected.
But as the way we buy and sell changes, the implications are deeperthan just developing securepayment gateways.In fact,theentire way thattax workswill also need to shift.
Questionsof howtaxation shouldchange inthedigital eraare underwayglobally and arebeing ledby the Organisation forEconomic Co-operation andDevelopment (OECD). It’s notjusttax revenue authoritiesthat are looking at this issue given that 60%-70%of transactions worldwide occurwithin multinational entities,these companiesare alsotakingan active part in the dialogue. Ultimately, taxation affects almost everyone,so although it’smaybe notanexciting subjecttomany people,itis an important one.There’s no real consensusat the
moment aboutdigital taxation. SA businesses and regulatorsneed tobepart ofthe debatetopositionthecountry asbest aspossiblefor anew tax era.
COMPLEXITIES OF DIGITAL SERVICES
Traditional tax models generallyfall intooneof twocategories: residencetax and source taxation. Residence tax isbased on theideathatpeopleandcompanies shouldcontribute towards thepublic services provided for them by the countrywhere theylive,no matter wheretheir income originates. Sourcetaxation, ontheotherhand,isbasedon the idea thatthe country where the income is generated is providingthat opportunity and thereforeshould be able to levy tax.
However, it’s difficultto
TRANSFER PRICING OPERATES ON THE BASIS THAT PROFITS SHOULD BE TAXED IN THE COUNTRIES WHERE VALUE HAS BEEN CREATED
useeither ofthese modelsin relation todigital services because consumersin one country might accessa productor servicewithoutthe supplier of thatproduct or service physicallybeing present in the country.
Thinkabout music.Previously,youwould gotoa music shop andbuy a CD. Now, youprobably subscribe toastreaming service.Inthe case ofpurchasing aphysical CD, you were paying VAT, but now you’re notpaying any tax inSA althoughyou are still purchasingand consuming the product in SA.
This iswhy someregulators are trying to clamp down on taxing digital services. For example, SA’sregulation on VAT onelectronic services, which tookeffect onApril 1 2019, widens the definition of what is consideredan “electronic service”
“Electronic services” are now defined as “any services suppliedbymeansofanelectronic agent,electronic communication or theinternet for any consideration”
Thismeans thatforeign suppliers ofelectronic services to SArecipients will be required toregister asVAT vendorsif theymeetcertain
requirements.
The effect is potentially a higher administrative burden on qualifying companies, which might be passed on to the consumerthrough price increases on such services.
Protectionist measures are underconsideration in various Africancountries, but they can backfire. While they mightmake senseinthe short termbecause most African countriescurrently “import”moredigitalservices thanthey“export”,thesesorts of policies candiscourage the growth of services economies orforeign direct investment.
Revenue and other authoritiesneed tobe proactive inengaging onthisissue andlook atissues suchas how to identifydigital transactions,determinetheirvalue andtax them, while encouraging growth of the local digital economy.
Transferpricing (TP)is another areaaffected by evolving taxregulation. TP involves theprices charged, or profitsearned, bymembers oflarge multinational
enterprises forgoods and services exchangedbetween the entities that make up the company.
Forexample, atechnology company basedin China might manufacturecomponents indifferent countries, and distributeits products through local subsidiaries globally. These companies might drivesales through their ownmarketing initiativesor bydevelopingsales channels. TPprinciples dictate howtransactions between thesecompanies within the groupare accounted for,and howprofit isdistributed, dependingon the value created by each entity.
TPgenerally operateson the basis thatprofits should betaxed inthecountries where value hasbeen created. Thetrouble withdigital services is that itcan be difficult to apportion value.
Forexample, ifyou’re using amusic streaming service,where isthevalue created? Is it in the country where the service is based, thecountrywhere itrunsthe bulk of itsoperations or the
countrieswhere themusicis being listened to?
These are thetypes of issuesthatarebeinglookedat by the OECD, which has presented awork planfor further work on the digital economy tothe G20finance ministers. Thefinal consensusset ofoutcomesis expectedto befinalisedby the endof 2020and because SA is a memberof the G20 and an observer of the OECD, it’s likely the country will consider thefinal proposals madebythe OECDinshaping its tax policies.
Whileit willimpacton business,theyshouldnotlose sight of the silver linings. Digitalisationcan helpSA businesses enterinto new markets andachieve higher levels of growth and development than previously available. The important thing isto findwaysof usingdigitalisation to work better and smarter.
Asvalue chainsevolve, companies needto reassess the way they operate to remain competitivein the digital environment.
Judgment on restaurants must be reviewed
Brian Patterson & Nomampondo Banzi ENSafrica
It isan unfortunatereality that manybusinesses have struggled tosurvive during the Covid-19 lockdown.
This isthe positionfour restaurants inSA found themselves in after they were prohibited from operating during a level5 lockdown. They subsequentlyapplied to the high courtfor business rescue. A keyquestion that arose waswhether the restaurants wereobligated to pay theiremployees during the lockdown.
One ofthe considerations in beinggranted business rescue is whether a company has failed topay any amount in terms of an obligation
related to apublic regulation orcontract, withrespectto employment related matters.
While the court found that therequirements tobeput under businessrescue were met, thecourt considered whetheritwasimpossiblefor the restaurantsto havecomplied with their obligations to pay theiremployees’ salaries during lockdown. It pointedout thatthe requirements for the doctrine of superveningimpossibility (that is,to terminateor suspend a contract)are stringent and that, if thereis a proper tender of servicesby an employee, anemployer would generallybe underan obligation to their pay salary. Controversially, thecourt seemed toaccept thatthe level 5lockdown regulations
made itclear thatemployers were not excused from their obligation topay their employees’ salaries.
This was because the regulations containeda listof essential servicesthat were permitted tooperate. This included the “implementation of payrollsystems tothe extent thatsuch arrangement has not been made for the lockdown, toensure timeous payments toworkers”. How-
A KEY QUESTION WAS WHETHER THE RESTAURANTS WERE OBLIGATED TO PAY THEIR EMPLOYEES DURING THE LOCKDOWN
ever, this interpretation of the regulations is incorrect.
The regulations authorised employees who worked withpayroll systems to work to make it possible to pay otheremployees who werepermitted towork.It did not permitemployees of restaurants to work.
As such,the regulations rendered it unlawfulfor the restaurant employeesto tender their services due to statutorily imposedsupervening impossibilityand this excused therestaurants from the legalobligation topay salaries.
So, thoughthere wasno legal impedimenton the restaurantsto paysalaries,it isourcontentionthattheduty to paysalaries didnot arise becauseanytenderofservice
by therestaurant employees would havebeen unlawfulin terms ofthe regulations.The court correctlyrecords the “no work, nopay” principle which means the duty to pay salaries arises upon a tender of servicesby employees.An allegation to thateffect was never made by the restaurantsandthe basisonwhich thecourt foundthatemployees did tender their services is unclear.
The court also argued that the restaurantscould have openedfor thesale ofcold foods once thiswas permitted by theregulations. With respect, the court is not best placed to makesuch a business decision.While the applicants producedevidence to support that contention, courtsare not
empowered tousurp business decisions of employers. The restaurantshad taken a decision to not operate during thenational lockdown andto ratherassesstheir financial positionand commence businessonce the lockdown had ended.
Arguably, therestaurants couldhave beenopenedfor deliveries only inMay and collections anddeliveries in June, in which case employees could have tendered their services and aduty to pay salaries would then arise. However, if the duty to pay salaries arose, that would onlybe inrespectof Mayand June,not Aprilas thecourt held.As such,itis ourview that this judgment should be reconsidered and overturned on appeal.
BUSINESS LAW & TAX
DUES DATE
Diageo case uncorks single-supply VAT issues
The Supreme Court of Appeal delivered its findings in Diageo South Africa (Pty) Ltd v Commissioner for the South African Revenue Service on April 3 2020.
The court had to consider whether a single supply of goods and services to nonresident entities is considered a single supply or deemed to be separate supplies of the constituting parts in terms of the ValueAdded Tax Act, 1991 (the VAT Act), which could give rise to a standard and zero-rate component.
Services supplied to a nonresident who is outside SA when the services are rendered can be zero rated, with certain exceptions.
Section 8(15) deems each part of a single supply to be a separate supply if that “supply of goods or services or of goods and services would, if separate considerations had been payable, (would) have been charged with tax in part at the rate applicable under section 7(1)(a) and in part at the rate applicable under section 11”
Diageo is an SA VAT vendor that imports, manufactures and distributes alcoholic beverages. Diageo entered into agreements to make single supplies of advertising and promotional goods and services (A&P services) to various nonresident entities (brand owners) to advertise and promote their alcoholic products in SA. Diageo supplied A&P services at the zero rate.
The commissioner for the SA Revenue Service (Sars) deemed Diageo to make separate zero-rated supplies of services and standardrated supplies of goods
FERDIE SCHNEIDER
comprising promotional giveaways and samples that were consumed in SA and assessed Diageo for VAT of about R15m. The Tax Court found the promotional goods to be a cognisable supply of goods capable of notional separation from the total A&P services supplied subject to the standard rate and upheld the Sars commissioner’s assessments.
Diageo rendered these services for a fee, based on the costs and expenditure
THE COURT DISAGREED WITH DIAGEO’S CRITICISM THAT THE DEEMING RESULTED IN AN ARTIFICIAL … AND COMMERCIALLY UNREAL OUTCOME
incurred. The advertising and marketing activities included advertising from various channels, brand-building promotions, events, sponsorships and market research. Diageo also used two categories of goods. First, alcoholic beverages of the brand owners taken from trading stock and used for sampling or tasting. Second, items such as branded glasses and T-shirts given to third parties, for no consideration. Diageo also provided aprons and caps to employees at no cost.
The promotional giveaways and samples, items used and the quantities and manner of use and distribution were undertaken as part of an integrated marketing campaign to build and maintain the brand. Diageo’s tax invoices to the brand owners reflected a total fee for services and did not differentiate between goods and services.
The court held that the legal requirements to invoke the deeming provision are, first, a “single supply” of two or more types of goods or services or a combination of goods and services. Second, one consideration must be payable for the single supply. Finally, if the supply of the goods and/or services had been charged for separately, part of the supply would have been standard rated and part zero rated.
The single supply made by Diageo to the brand owners consisted of goods and services, distinctly and clearly identifiable from each other. One consideration was payable to Diageo for that single supply.
The court found that the supply of the A&P services to the foreign brand owners comprised a single supply of goods and services for which a single consideration was payable and, if it had been supplied separately, would have attracted a different VAT rate. The court disagreed with Diageo’s criticism that the deeming resulted in an artificial, insensible and commercially unreal outcome.
The court found the meaning of the deeming provision to be clear and its purpose to ensure that Diageo and VAT vendors in similar positions fulfil their obligation to pay VAT at the
standard rate on goods supplied. The court found Diageo liable for the VAT output tax adjustments in respect of advertising and promotional costs incurred by Diageo constituting goods not exported but consumed in SA. The court dismissed the appeal with costs.
The findings in the Diageo case are interesting for a number of reasons. Section 8(15) of the VAT Act has never, or at least not often, been considered at this level, and though not particularly difficult to interpret, leaves room for interpretation.
What makes the deeming provisions a bit more difficult to interpret is that they deal with fictitious scenarios, necessary to act as “gapstoppers” or in certain instances to address antiavoidance. It also makes it clear that the courts will not necessarily rely on foreign court findings unless the context and purpose of the foreign legislation are closely aligned.
The court also referred to the VAT system’s objective to
tax private domestic consumption, which is not a concept enshrined in the VAT Act. The act also does not contain explicit place-ofsupply rules. VAT place-ofsupply or interjurisdictional rules aim to determine where a supply takes place, which could impact where a person should register for VAT purposes or the rate of the supply. The place of supply needs to be inferred from various sections in the act. Section 8(15) can be seen as one such “inferred” placeof-supply rule.
Finally, though the Diageo case deals with the alcoholic beverage industry, it is clear the deeming of a single supply for a single
WHAT MAKES THE DEEMING PROVISIONS A BIT MORE DIFFICULT TO INTERPRET IS THAT THEY DEAL WITH FICTITIOUS SCENARIOS
consideration into more than one supply with different tax rates can have far-reaching consequences for various industries. SA companies that supply marketing services to foreigners of which goods are supplied for no charge and form part of a zero-rated supply of services may need to rethink their VAT positions.
Certain commentators warn that this case may be applied to zero-rated foodstuffs, which could split the actual zero-rated item from its packaging, transport and other cost. While the item will remain zero rated, other components capable of being carved out could potentially be subject to the standard rate.
Though this is a possible consequence, the application thereof may not be aligned with the intention of the legislator, could lead to absurdities and will have a substantial associated compliance cost.
● Ferdie Schneider is CEO of Sta Konsult.