
When all for one backfires
• Employees present when an assault took place are dismissed
Itayi Gwaunza & Claire Nolan ENSafrica
Agroup of 50 striking employees confront their manager in his office. Analtercation ensues, which culminatesin the manager being violently assaulted. Onlyfive ofthe striking employees are caught “red-handed”, having beenidentified astheperpetrators ofthe violentassault. The restare onlyidentified as having beenthere whenthe assault took place.
Canthe employerdismiss all ofthe strikingemployees whowere presentwhenthe violent assaulttook place, including the45 striking employees whohappened to be there, butwho did not themselves carryout the assault?
Accordingto thedoctrine of common purpose,a person whoassociates themselveswiththeactsofacriminal perpetratoris criminally liable.
WORKPLACE
● Hadassociatedthemselves with the assault through their presence at the scene;
● Had encouragedthose involved in the assault;
● Hadfailedto cometothe assistance of Steffens,
● Had rejoiced in the assault;
● Had heldplacards demanding thatSteffens be removed from his post.
Thiswas consideredin Numsa oboAubrey Dhludhlu & Others andMarley Pipe Systems(SA)(Pty)Ltd.During thecourse ofanunprotected strike, severalMarley Pipe Systems employeessurroundedthe headofhuman resources, MrSteffens, pushedhim outof aglass window,threw rocksathim andpunched andkickedhim while he layon the ground. Hesuffered injuriestohis face, his right arm and body. MarleyPipe Systemstook disciplinary actionagainst 148employees. Ithadidentified theseemployees from photographic andvideo evidenceof eventson theday, clock cards used in its payroll system whichrecorded the names ofemployees who had arrivedand remainedat work,job cardsusedat workstationsandthroughthe evidence ofthe employer’s witnesses. Usingthis evidence, 12employees were identified ashaving participated in the assault of Steffens. Theremaining employees were found to have acted withcommonpurposeonthe basis that they:
Following a disciplinary inquiry, MarleyPipe Systems dismissed all148 employees forparticipating inanunprotected strike andfor the assault on Steffens.
TheNational Unionof Metalworkers ofSA (Numsa), acting on behalf of the 148 employees,pursuedanunfair dismissal disputein the Labour Court.Relying onthe doctrineofcommonpurpose,
the LabourCourt foundthat thedismissal ofall148 employees was fair.
By the time the dispute reached theLabour Appeal Court, Numsahad, ineffect, acceptedthat thedismissalof the12 employeeswhowere identified ashaving participated directly in the assault of Steffens wasfair. Itwas also acceptedthat thedismissalof 95 employees,who hadbeen
identifiedashavingbeenpresent whenthe assaulttook place,andashavingtherefore associated themselves with theassault, wasfair this beingbased onthedoctrine of common purpose.
However, Numsa contended there wasno evidence thatthe remaining41 employeeshad beenatthe sceneofthe assault,thatthey had been awareof the assault, that theyhad intended to make common cause withthe12employees,orthat they had performedan act of association with them.
Accordingly, Numsapursuedanappeal onbehalfof only41 ofthe 148employees on thebasis thatMarley Pipe Systemshad failedtoprove the41were guiltyofassault and their dismissalwas fair based on the doctrine of common purpose.
TheLabour AppealCourt referred to the remarks of the Constitutional Court in a previous matter (that did not directly deal with the doctrine ofcommon purpose), the NationalUnion ofMetalworkers of South Africa obo Nganeziand OthersvDunlop Mixing andTechnical Services (Pty)Limited and Others:
“Evidence,direct orcircumstantial, that individual employees insome form associated themselves with theviolence beforeitcommenced,or evenafter itended,maybesufficienttoestab-
lishcomplicityinthemisconduct. Presence at the scene will notbe required,but prior or subsequentknowledge of the violence andthe necessary intentionin relation thereto will still be required.
Accordingto theLabour Appeal Court:
THE DOCTRINE OF COMMON PURPOSE CAN BE AN EFFECTIVE TOOL IN JUSTIFYING THE FAIRNESS OF THE DISMISSAL
“In Dunlop, the [Constitutional] Courtstated thatassociationwith themisconduct before it commencedor after itended maybe sufficientto establishcomplicity inthe workplacecontext,withitnot requiredthat anemployeebe presentat thescene.However,prior orsubsequent knowledgeofthemisconduct andthe necessaryintention inrelationtoitisstillrequired. Thismoves therequirements to prove common purpose in theworkplace outsideofthe strict requirements set out in the case law from Mgedezi.
“It allows an employee to beheld toaccount forcollectivemisconduct wherethe employeeassociatedwiththe
/123RF MTKANG
BUSINESS LAW & TAX
LATERAL THINKING
Stopping global tax dodgers
• Business Law & Tax Editor Evan Pickworth interviews Peter Dachs, tax executive at ENSafrica, on the new regime for global corporate taxes and efforts by the SA Revenue Service (Sars) to improve its own collection capabilities, especially when confronted with tax dodgers
EP: TheOECD (Organisation for Economic Cooperation and Development) says multinationals have deprived countries of $100bn to$240bn each year 4% to10% of global corporate incometaxes by takingadvantage ofgaps and mismatches between different countries’ tax systems. Doyou thinkSA benefitsin anyway fromthe move to a15% minimum corporate tax bythe G20 (Groupof20countries)?
PD: Since the G7(Group of 7) meeting onJune 5when the G7 finance ministers announced aglobal corporationtax ofatleast 15%,there has beenmuch writtenand spoken aboutthe newproposed globalminimum tax rate.JanetYellen,theUStreasury secretary,called the agreementa “historic day for economic diplomacy”. She statedthat “for decades, the UShasparticipated inaselfdefeating international tax competition, lowering our corporatetax ratesonlyto watch othernations lower theirs in response”
Basedon thisagreement, on July 1 theOECD issued a statementcommittingeachof itscountries toatwo-pillar plan toreshape theglobal tax system. Thisincludes allthe nationsinthe G20 of the world’s biggesteconomies, including China,India, Brazil andRussia.The ideaisfirst that large multinationals should pay tax in the jurisdictions where their revenue is earned and,second, they shouldpaytax ataminimum
rate of 15%.The SA corporate taxrate isnow28% sothe proposed minimumtax rate should not affect SA.
EP: What are the implications of this move by the G20andOECDforus?
PD: The first proposal is that a portion of therelevant multinational’s residual profit shouldbetaxed inthejurisdiction whereits revenueis sourced. This appliesto automated digitalservices businesses and consumer-facing business. Thisso-called Pillar One approachdeals with profit allocationand nexus and will linktaxing rights in respectofthesebusinessesto their sourcesof revenue which do not depend on physical presencein the jurisdiction.
WE SEE A SIGNIFICANT NUMBER OF PEOPLE WHO APPROACH US WITH QUESTIONS RELATING TO EMIGRATION
The idea istherefore that a minimum taxrate ofat least 15% will be levied in relation toall incomederived bythe relevant multinationalcompanies.Thistaxshouldideally beimposed inthejurisdictions where theprofits are earnedin termsof thePillar One nexus rule.
Thisis positiveforSA since SAwill now beable to taxthese businessesin respectof revenues derived fromanSAsourceregardless ofwhether thebusinesses operate thougha “bricks and mortar” office in SA.
EP: So this should level the playingfield againstglobal tech giants, who have been paying lowto notax for sometime,right?
PD:Overthe pastfewyears, various multinationalgroups, basedmainly inthe USand operatingprincipally inthe technologyspace, havepaid littletaxoutsideoftheircountry of residence.The jurisdictionswhere thesemultinationalsgenerate salesand earnprofits havenotbeen able totax thecompanies since they do not operate througha physicalpresence (“bricksand mortar” offices) in those jurisdictions.
TotheireoftheUS,certain countriesin whichthese multinationals derive their profitsthreatenedtoimposea digital services tax on these multinationals.This ledtoa standoff between theUS and some OECD jurisdictions.
These multinationals include various of the USbasedtechnologycompanies. Taxas apercentage ofprofits forFacebook, Amazon,Netflix,Google, Microsoftand
Apple for 2010 to 2019 is only between 10% and 17%.
In addition, although Donald Trump attempted to roll backthetax-exemptstatusof US-basedmultinationals’foreign profits, this has not been effective. Inrespect ofUSheadquartered companies, offshoreprofitsup toa10%of returnon investmentsmade abroad are exempt from US tax. Profits above this amount areeffectively onlysubjectto a 10.5%tax, so half ofthe 21% rateimposedby theUSon domestic profits.
Intermsof thenewproposal, thesemultinationals willnow besubjecttotax ata minimum rate of 15%.
EP: Willcorporate taxesin SAshiftatall theyactually remain high by global standards?
PD: SA’s corporate tax rate is currently set at 28%. There is ageneral trendtowards increasingtax ratesas opposed toa fewyears ago whenthe trendwasthe opposite. Both the UK and the UShave committedto increasingtheir corporatetax rates. SA’s taxrate isrelative-
ly highby globalstandards and it is therefore unlikely to increase. We havenot seen an increase in the SA corporate tax rate since 2012.
EP: Doyou thinkSA digital taxes are keeping pace with thesedevelopments?
PD:In termsofinternational taxlaw,SA didnothavethe right totax foreignmultinationals whichare basedin jurisdictionswith adouble tax agreement withSA and whichdid notoperate through “bricks andmortar” offices in SA. As mentioned above, interms ofthe proposedglobal taxreformsthis willchangeand SAwillbe allowed to tax these entities. Our taxation on digital profits thereforelargely dependson internationaltax lawas opposedto ourowndomestic tax laws.
OVER THE PAST FEW YEARS, VARIOUS MULTINATIONAL GROUPS HAVE PAID LITTLE TAX OUTSIDE OF THEIR COUNTRY OF RESIDENCE
EP:Areyoualreadyseeinga differencein taxpayersand whatis yourmessagefor thosetryingtoevadetax?
PD:Anytaxpayersattempting to evade tax operate outside the ambitof our lawand are thereforesubject tocriminal sanctions. Asmentioned above,itis aquestionofcapacitybuilding andenforcement bySars tobring these tax offenders to book.
When all for one backfires: violence in the workplace
CONTINUED FROM PAGE 1
actionsof thegroup beforeor after the misconduct, even if not presenton thescene; wherethe employeehad prioror subsequentknowledge ofthe misconduct;and heorshe heldthenecessary intention in relation to it.”
The Labour Appeal Court statedthat, indetermining whether commonpurpose was present,a courtis requiredto considerthecircumstantial evidenceavailable toit and toselect the inferencewhich isthemore plausibleor naturalone
fromthose thatpresent themselves.
The Labour Appeal Court acceptedthe followingto have been the proven facts:
● Allemployees hadreported for duty, left their workstationsand embarkedon the strike;
● Allemployees, savefor one employee,were onMarleyPipe Systems’ premises and away from their workstations atthe timeof the assault;
● Thestriking employees,all ofwhom wereNumsa members, moved together towardsSteffens’office,hold-
ingplacards andpresenting written demands which sought his removal;
● Allthe employeessought outSteffens andremained present onthe sceneduring thecourse of,and after,his assault, with none of the strikingemployeescomingto his aid; and
● Apartfrom oneemployee, noemployee tookadvantage of the opportunities availed to them, bothprior toand duringthe disciplinaryhearing, or before the Labour Court, to distance themselves from the events of the day.
Applying the doctrine of
commonpurpose,theLabour Appeal Court found that the mostprobable andplausible inferencefrom theevidence andthe provenfacts wasthat all 41employees hadassociatedthemselves withthe actions ofthe 12employees before, during orafter the assault on Steffens.All 41
THE REMAINING EMPLOYEES HAD ENCOURAGED THOSE INVOLVED IN THE ASSAULT
employeeshad therequisite intentionthat anassault would resultor sawthe possibilityofthe assaultonSteffenstakingplace;despitethis, they actively associated themselves with the assault.
Accordingly, theLabour Appeal Court found that the LabourCourt couldnotbe faulted for findingthat all employees had committed themisconduct forwhich theyweredismissedandthat, becausethe misconductwas serious,dismissal wasthe appropriate sanction.
This decision illustrates that anemployee doesnot
EP: Doyou expectthe recentunrest inSA tolead to more requests for emigrationand becomingnontax resident? If so, what are the maintax risksto be awareof?
PD: Unfortunately wesee a significantnumber ofpeople who approach uswith questionsrelating toemigration Previouslythere weretwo separateprocesses financialemigration whichinvolved the ReserveBank, and tax emigration which tested whetheran individuallost their SA tax resident status. Thesehave nowbeen streamlined into a single processandtheconceptoffinancialemigration hasbeen brought into theambit of the tax rules. Once a person becomesnonresident from a tax perspective, theywill be consideredto havenonresident status froman exchange control perspective too. One of the main tax risks ofbecoming nonresidentof SAisthat thereisadeemed disposalof allassets(excludingimmovable property)at their market value. This triggersa“dry”tax,requiredtobe paid even though no assets have been disposed of. EP:Youradviceonhowcorporates andindividuals shouldact tomitigatetax risksnowthat thetaxfiling seasonisopen?
PD:Takeproper taxadviceto ensurefull compliancewith SA’s complextax laws.As mentioned, ourprescription rules do notapply in circumstances where a taxpayer has not made all the necessary disclosuresrequired interms of SA’s tax law.
need tobe caught “red-handed” tobe foundguiltyofacts ofmisconduct perpetratedby others. The doctrine of commonpurposecanbeaneffective toolin justifyingthe fairness of the dismissal of employeeswho, despitenot being caught “red-handed”, areproventohaveassociated themselves withacts ofmisconductbefore, duringor aftertheir commission,with therequisiteintentionthatthe actsor misconductwould result in,or wherethe employeesmust haveforeseenthe possibilityof,the misconduct occurring.
BUSINESS LAW & TAX
New hoops for estate agents
• Principal requirements of the Property Practitioners Act
Justine Krige Cliffe Dekker Hofmeyr
The PropertyPractitioners Act,No 22 of 2019,which the president has signed intolaw, will repealthe EstateAgency AffairsAct, No112of 1976 in its entirety. Draft regulations were published forpublic comment in March 2020. However,asthings stand,thereis no firm indicationas to when thePropertyPractitionersAct will come into force. When it comesinto force, the act will placea number of new obligationson property practitioners, not all of which are contained in the Estate Agency Affairs Act. So, what are theprincipal obligations of property practitioners under theProperty Practitioners Act?
● Aholder ofaFidelity Fund Certificate(FFC) must: (i) prominentlydisplay his, heror itsFFCin everyplace of businesswhere he,she or it conductsproperty trans-
actions, toenable consumers toeasilyinspect it;(ii)ensure that theprescribed sentence regardingholding aFFCis reproducedonanyletterhead or marketingmaterial; and (iii) inany agreementrelating to propertytransactions, include aprescribed clause guaranteeing thevalidity of the certificate.
● Maintaining a trust account. Every property practitioner must:(i) open and keep oneor more separate trustaccount/s; (ii) appoint an auditor;(iii) provide theProperty PractitionersRegulatoryAuthoritywith all information as regards the trust account/sand auditor appointed; (iv)deposit all trust moneyin therelevant trust account;(v) keepseparate accounting records in respect ofthe trust account/sand causethemto be audited.
● Duty tokeep accounting records andother documents. Everyproperty practitionermustfor aperiodof five years retain: (i) all documents exchangedwith the
authority; (ii) all agreements, mandates and mandatory disclosure forms relating to financing, sale, purchase or lease ofproperty; and(iii) any advertising ormarketing material relating to the carrying on of business as a property practitioner.
● A property practitioner is notentitledtoremuneration in certain circumstances. A property practitioner is not entitled to any remuneration unless the property practitioner and, if a company, everydirector ofsuchcompany,is inpossession ofan FFC. A conveyancermay not pay any remuneration or other money toa property practitionerunlessthepractitioner hasprovided theconveyancer with a certified copy of his, her or its FFC.
● Maintaining mandatory indemnity insurance. The minister may, forthe purposes of providingredress in respect of the contravention of acode ofconduct orother sanctionable conductin terms ofthe PropertyPractitioners Act, prescribe indemnity insurance whicha property practitioner must take out and maintain.
● Complyingwith acodeof conduct. Every property
NEW OBLIGATIONS
practitioner must comply with the prescribedcode of conduct (still to be published by the ministerof human settlements).
● Complying withProperty Sector Transformation CharterCode. Every property practitioner must comply with the Property Sector Transformation CharterCode (still to be published).
● Providing certain mandatory disclosures. To achieve the objectof being a consumer-focused piece of legislationdesignedtoprotect consumers in the property industry, the Property Practitioners Act obliges property
LABOUR PAINS
practitioners to deliver a “disclosure form” to a seller/ lessor before concluding a mandate, and toa purchaser/ lessee before making an offer. The disclosure form must besigned byall parties and attached to the sale or lease agreement. If no disclosure form issigned and attached,theactprovidesthat theagreement mustbeinterpretedasifnodefectsordeficienciesof thepropertywere disclosedto thepurchaser.A property practitioner cannot accepta mandateunlessthe sellerorlessorhasprovideda fully completed and signed disclosure form.
● Limitation onrelationships with other property market service providers. Section 58(2) of the Property Practitioners Act outlaws any type of practicein which a practitioner provides a consumerwith anincentiveto use a particular conveyancer orservice provider.Thisis probably one of the most debated sections of the act, with practical ramifications forthe waypropertypractitioners do business.
These obligationsare clearly intended for the protection of consumers. Any property practitioner in contravention of theact will be required torepay anyfees receivedforapropertytransaction and maybe issued with a fine. Furthermore, any person convicted of an offence interms ofthe actis liable to pay a fine, or to imprisonment forup to10 years.Thus, evenifproperty practitioners do not hold monies in trust, they will need tocomply withthe remaining obligationsin terms of the act.
Property practitioners are advised to familiarise themselves with these requirementsas theymay shortlybe brought into force and effect.
Can companies force workers to be vaccinated?
The much-anticipated department of employment & labour “direction” on Covid-19 vaccination was gazetted on June 11 2021. Mandatory vaccination is permissible or is it?
Employers across the country are grappling with the decision of whether to make Covid-19 vaccination mandatory, ensuring compliance with the June 11 2021 Consolidated Direction on Occupational Health and Safety Measures in Certain Workplaces Gazette.
Annexure C of this gazette is entirely devoted to mandatory Covid-19 vaccination (“Guidelines if an Employer Makes Vaccination Mandatory”).
Helpful as it is, it does not address the question of dismissal in circumstances where an employee persists in their refusal to be vaccinated, if the employer has adopted a mandatory vaccination policy.
Getting the social partners to reach agreement on the question of workplace vaccination considerations can’t have been easy. In fairness, it is a complex, multifaceted challenge. On the one hand, the
Occupational Health and Safety Act compels employers to promote and ensure workplace safety, health and hygiene, which suggests that workplace Covid-19 vaccination should routinely be mandatory.
Yet, on the other hand, our constitution provides for key human rights such as the right to equality, dignity, bodily and psychological integrity, freedom of religion, belief and opinion and fair labour practices, all of which lay the groundwork for the contesting of mandatory workplace Covid-19 policies. So, there we have it.
Employers may establish mandatory vaccination policies, or is that may not?
Hence the current almost paralysis in employer ranks on the workplace vaccination policies being pondered throughout commerce and industry.
At face value, some
industry sectors will have a stronger argument for establishing blanket mandatory vaccination policies than others. For example, most health facilities, in all likelihood, will be able to justify a mandatory policy given the operational difficulty in applying strict social-distancing protocols.
The mining sector, too, should be able to justify a mandatory policy given the enclosed working environment in mines, other than open-cast mines.
It is even quite arguable that in the hospitality sector, such as kitchens and housekeeping, mandatory Covid-19 vaccination policies should be able to withstand scrutiny.
However, our observations over a wide cross-section of other industry sectors is that employers would, by and large, prefer mandatory vaccination policies, but are reluctant to do so for fear of being one of the first test cases on the question of mandatory vaccination policies.
Because, make no mistake, there will be a test case or, more likely, a slew of test cases, and no employer
is particularly enthusiastic about being a party in such a case.
There are three options when it comes to concluding a workplace vaccination policy:
● Vaccination is nonmandatory.
● Vaccination is mandatory.
● Vaccination is mandatory for some employees, but not others.
Section 4 of annexure C of the gazette highlights that when contemplating a mandatory vaccination policy, a “premium is placed on public health imperatives, the constitutional rights of employees and the efficient operation of the employer’s business”
An employer’s risk assessment in accordance with sections 8 and 9 of the Occupational Health and Safety Act will largely influence employer decisions regarding mandatory, or non-mandatory workplace vaccination policies.
If an employer risk assessment concludes the workplace is an inherently hazardous environment that is incapable of limiting the likelihood of workplace infection, a mandatory Covid-19 workplace policy
will be more justifiable than a workplace that can take steps to minimise the likelihood of infection.
This, of course, applies to both employees and any other third parties who may access the workplace.
On a practical level, the workplace risk assessment would focus on the ability to maintain social distancing, ventilation, sanitising protocols, the staggering of working hours and meal breaks, hygiene protocols and the like.
It is quite possible that an employer makes Covid-19 vaccination mandatory for some employees, but not for others.
For example, given the ergonomics of many workplaces, there may be a likelihood that infection will more likely effect the health of employees, or others, in one area of a workplace, more than another.
BECAUSE, MAKE NO MISTAKE, THERE WILL BE A TEST CASE OR, MORE LIKELY, A SLEW OF TEST CASES
Sooner or later, there will be dismissals for refusal to be vaccinated in workplaces with mandatory Covid-19 vaccination policies; it’s inevitable.
It’s clear from annexure C of the gazette that any predismissal procedure will need to include an employer evaluation of the employee’s grounds for refusal, and an assessment of whether it was possible to accommodate the employee in a position that does not require the employee to be vaccinated.
If not, dismissal on grounds of refusal to be vaccinated in a workplace with a mandatory workplace Covid-19 policy will likely amount to dismissal on grounds of either misconduct (refusal to obey a lawful and reasonable instruction) or potentially on grounds of incapacity, in that without being vaccinated, the employee does not have the capacity to meet their employment obligations in not agreeing to be vaccinated.
● Tony Healy is content director at the SA Labour Online Academy www.saloa.co.za
TONY HEALY
/123RF DONSKARPO
BUSINESS LAW & TAX
Ruling clips advertising body’s wings
• High court judge says Advertising Regulatory Board cannot have jurisdiction over nonmembers
Gaelyn Scott ENSafrica
The SA high court judgment inthe case of Bliss Brands vAdvertising Regulatory Board (ARB)has real relevance forintellectual property (IP) owners. Thejudgment dealswith the issue of whether the ARB, the body thatreplaced the now defunctAdvertising Standards Authority (ASA), has jurisdictionover companies that arenot members of the body. Athornyissue Foryears,brandownershave used theadvertising regulation proceduresto resolve trademark and copyrightrelated disputes.A particularly effective weapon available to brandowners is theso-called“adalert”,aprovision that allowsthe advertisingregulationbodytoissue an instructionto itsmedia company membersnot to acceptanadvertthebodyhas ruled against.
Thelegality ofsuch instructions waseventually challenged inthe Herbex case.The SupremeCourtof Appeal ruled the ASA had no jurisdiction overany non-
member andcould not require a nonmember to participate in its processes, or issue anyinstructions, orders or rulings against it. This judgment contributedto the eventual demise of the ASA.
ThecaseofBliss
The ARB ruled against the packaging of a soap product offered by Bliss, after a complaint fromColgate. Colgate claimed Blisswas exploiting its advertisinggoodwill and imitatingitspackaging,issues that aredealt within clauses 8 and 9 of the ARB Code. This despitethe factthat Bliss is not amember of the ARB.TheARB issuedanad alert instructingits members torefusetheadvert.Blissfiled an appeal to the high court, where thecase washeard by judge Denise Fisher.
Theadalert
Thejudge saidclause 3.3of the ARB’smemorandum of incorporation (MOI)creates
THE JUDGE WENT ON TO SAY THAT ‘THE OPERATION OF THE AD ALERT HAS ALL THE FEATURES OF AN INDIRECT BOYCOTT’
ad alert power.What this meansisthateventhoughthe ARB has no jurisdiction over nonmembers,it canissuean order requiring its own members notto acceptan advert theARB hasruled against.
Thejudgesaid the ad alert “has the effectthat the rights of nonmembers are implicatedintheARB’sprocesses” This makes itan effective remedy.Italso makesita coercive remedy, resulting in twochallenges. First,thatthe AdAlerthasnosourceinlaw. Second, that thead alert falls foul ofSection 134of theconstitution.
Isthe adalert sourcedin law?
No.As thejudge said,membershipoftheARBcomprises “the wholeof theprint, digital andbroadcast mediainSA”, with members “obliged to follow the ARB’s prescripts” The judge went on to say that “theoperation ofthe adalert has allthe featuresof anindirect boycott”
Yet,said thejudge, “the ARB has no truck with the law itspurposeistoenforce ‘standards’ which are determined andset bythe membership”.Shewent ontosay that a “private body that exercises public powers is not
permitted to be a law unto itself”
Referring tothe Herbex case, thejudge saidthis is “authority for the proposition that theissuing ofan adalert against nonmembersis unlawful as a general rule” Doesthe adalertcontravenetheconstitution?
Section134oftheconstitution provides that “everyone has the right tohave any dispute thatcanbe resolvedbythe application of lawdecided in afairpublic hearingbeforea court or, where appropriate, another independentand impartial tribunal or forum”
Yet, saidthe judge,the ARB adjudicates on complaints under clause8 of the code (takingadvantage ofan advertising goodwill)and clause 9 (imitation), issues that fall within the realm of IP law. Thejudge wenton tosay that underthe ARBprocedure, the nonmember cannot defend itself in a court on the merits,thecourt’sjurisdiction is ousted, and “decisions on
legal causesof actionakin to passing off, copyright and trademark infringementare made, in large part, by nonlawyers”
The judgeused some strong words.She spokeof “theusurpation ofthecourt’s functions by the ARB” as well as “the tyranny of the ARB’s processes ”
Thejudge alsospokeof lack of independence: “This funding model creates room for theperception ofa lackof independence wherethe complainant is a funder and member and the respondent is a nonmember.”
Whataboutthelawfullimiting of rights, the application ofsection36?
Section 36(1) ofthe constitution allows forthe limiting of rights in certain circumstances.The ARBargued itis best placed toregulate the commercial rights of those seeking tosell andmarket products. Unsurprisingly,the judge disagreed there are remediesunder IPlawand
various pieces of legislation relatingto, interalia,foodstuffs, medicines and tobacco products. There’s also the Consumer Protection Act, 2008.
Conclusion
Thejudge declaredthe “public powers which are assumed by the ARB in relation to the regulation of the advertising of nonmembers” to be “unconstitutional” and “not sourced in law”
The net effect:
● The ARB’sMOI andcode are unconstitutional.
● Clause3.3 oftheMOI, which grants the ARB jurisdiction over nonmembers, is unconstitutional, void and unenforceable.
● The ARBhas nojurisdictionoveranonmemberofthe ARB.
● TheARB maynotissue rulings against orin relation to anonmember orthat member’s advertising. This isa significantjudgment, and we understand there will be an appeal.
How intellectual property ran the Games
Duncan Potgieter & Leanne Mostert
Webber Wentzel
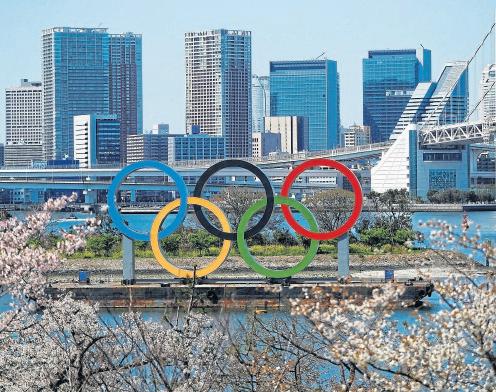
The TokyoOlympics 2020 officially kicked offon July 23 (a year later than initially scheduled) and cameto an end on August 8.
The multisport event quickly overwhelmed news feeds withinteresting facts, figures andfeatures. Less highlightedwas isthekey role playedby intellectual property (IP).
The“elephantintheroom” was a giant:the constant references onsignage, apparel and merchandiseto ayear that was,well, not2021. The simple reasonwas that, althoughthe Olympicshadto be postponeddue tothe devastating effects ofthe Covid-
19 pandemic, the Tokyo organising committee,with the International Olympic Committee (IOC), agreedto maintain the “Tokyo 2020” brand. But why the decision not to rebrand?
To understand this,it is important toappreciate the magnitude ofthe decisionto postpone theGames toa different calendar year. Since its inceptionin1896,themodern Olympics wasonly postponed altogetherin 1916, 1940 and 1944, due to world wars1and 2.Neverbefore have theOlympics been postponed orcancelled due to apandemic. Unprecedented circumstanceshad arisen for the IOC.
Accordingto anarticle by Carlos Castro, head ofIPat the IOC, the IP journey of
each edition ofthe Games starts about10 yearsbefore the Olympicflame leaves Olympia inGreece and makesitswaytothehostcity, whereit lightstheOlympic
Cauldron duringthe opening ceremony. It is common for cities interested in hosting an edition of the Olympics to register trademarks and domain namesat anearly
stage of the Olympic journey to preserve theIP ecosystem needed for a successful bid.
Once selected,a hostcity establishes acommercial plan withthe IOCfor the Olympics which, among other things, sets out the marketing planand supports the operationalplanning and stagingof theGames.From around bid stage until after the closingceremony, IP such as literary and artistic works, relevant designs, logos, emblemsor slogans are created, commissioned, acquired or otherwise secured.
This naturallyincludes the design of theofficial mascots andlogo asubject thathas raised controversyrecently, but whichis perhapsa topic for another day.
Like anyother commercial product, theIP rights associated withthe Olympics protect theintegrity and uniqueness of the brand. The IP protection isalso crucial to ensurethattheIOCcontinues to generaterevenues from the mostwidely viewed sporting event in the world. Since Tokyo2020 was projected tolose about $800m in totalrevenue from ticket sales, there was a greater needto strategically use IP assets and branding on already commissioned medals andsouvenirs atthis year’s Games.This position ultimately promptedthe commercial decision to maintain the “Tokyo 2020” brand established years before thecoronavirus outbreak.
/123RF ISSEI KATO
BUSINESS LAW & TAX
Losses in riots can lead to tax complexities
• Insurance payments at replacement value that exceed tax value means being taxed on recoupment
Nina Keyser & Caroline Theodosiou Webber Wentzel
The destructionof an assetis acapital gains taxevent. To put it in legal terms (drily, thatis) “ you aredeemed tohavedisposed of your asset”
Ifyour officebuilding, which some yearsago cost R900,000 tobuild, burned down(whetherdueto“insurrection” orotherwise), and you receivean insurance payment ofR2m, itis regarded as a capitalgain of R1.1m. If you did nothave insurance against this event, you have incurred a capital loss.
Unfortunately, acapital lossdoes notreducetaxable income. A capitalloss can be used onlyto reduceanother capital gain. That means you have to wait until you have another capitalgain before you can use the capital loss.
If you have a short-term insurance policy covering yourassets,youwillprobably be able to claimonly if you have Sasriainsurance. Thisis a separatepolicy whichprovides cover for special risks excluded byyour short-term insurer.A Sasriapolicycoverslosses arisingfromcivil commotion, riot,strike, lockout, public disorder, rebellion, revolution andterrorism, but not waror war-related activities.
Coverwill beprovidedin termsof theSasriapolicy issued to you,which may not
matchyourunderlyingcover. Butcover issubject tothe underlying policybeing in place andpremiums having been paid.
Sasriaisa VATvendor.If you area VAT-registered business, youcan claimback theVATon yourSasriapremiums from Sars, but you alsohave topayVAT toSars when youreceive any indemnity payments from Sasria. In legal terms, “the indemnity payment is deemed tobe consideration for aservice”. Sarsregularly checkswhetherVATvendors whoreceivedindemnitypay-
COVER WILL BE PROVIDED IN TERMS OF THE SASRIA POLICY ISSUED TO YOU, WHICH MAY NOT MATCH YOUR UNDERLYING COVER
ments declared the VAT due onthosepayments, sinceitis often overlooked. VAT on indemnity payments mustbe paid if1) The insured is registeredfor VAT; 2)The insuredlosswas incurred in carrying on an enterprise; and3) Theinsurer made an indemnity payment. If theinsured assetsare replaced,the VATvendorcan endupin atax-neutralposition. For example,if a machine insuredfor R150,000is destroyed,and
theinsurer paysout R150,000,the insuredwill become liable for output tax intheamount ofR150,000x (15/115)= R19,565.Assuming theinsured businesspurchases areplacement machinefor R150,000,the insuredwill thenalso becomeentitled toclaim input tax of R150,000 x (15/115) = R19,565.As a result, theinsuredwill endupina taxneutralposition,aslongas the insured asset is replaced. Timing isimportant. Replacingthe insureditems inthe sameVAT periodthe indemnity paymentis received will avoid the problem ofhaving topay output VAT in oneperiod, while only being ableto claiminput tax ina laterperiod, whenthe asset is replaced. Indemnity payments could also have income tax consequences. If youhave a formof businessinterruption cover,any insurancepayout that is intended to cover your lostrevenuewill alsobetaxable.Insurance paymentsfor the loss ofdepreciable assets mayresult intaxablerecoupments.For example,ifyou purchased computers for R100,000 inthe previoustax year, and claimed R33,333 as depreciationin yourtax return,your computershave a taxvalue of R66,666.If you insuredyour computersat theirtax value,youwill receiveR66,666 andno recoupmentwill arise.However, if you insured your computersat theirreplace-
ment value, andyou receive aninsurance paymentwhich ismorethan thetaxvalueof the computers, you will be taxed on a recoupment.
Using this example,if you receivean insurancepayout ofR100,000,you willhaveto paytaxon arecoupmentof R33,333. Ifyou receivean insurance payoutof R120,000, you willhave a recoupment of R33,333 and a capital gain of R20,000.
If you decideto take the money and run(legally, of course)you willhave topay the capital gainstax and the income tax on the recoupment.If, however,youdecide toreplacethecomputers,you cangetroll-overrelief(which meansyou onlypay thecapitalgainstax whenyoudis-
poseof thereplacement asset).To qualifyforroll-over relief:
● Youmust “dispose of” the assetby wayof theftor destruction;
● Youmust receive “ proceeds” by way of compensation (ie an insurance payout);
● Theproceeds mustbe equaltoor exceedthebase cost of the asset;
● The full proceedsmust be
INSURANCE PAYMENTS FOR THE LOSS OF DEPRECIABLE ASSETS MAY RESULT IN TAXABLE RECOUPMENTS
used to acquirea replacement asset(s) in SA;
● Thecontracts forthe acquisitionof thereplacement asset(s)must beconcluded within 12 months; and ● The replacement assets must be brought into use within three years. So, the tax consequences ofriotdamage andlosstoa businesscan besurprisingly complex and mustbe carefully considered.
Ironically, even Sars may beout ofpocket. Noteveryone who receivesan insurance payoutwill haveto pay outputVATover toSars,but Sasria is a VAT vendor and willbeentitled toclaiminput VATbackfrom Sarsonallof the indemnity payments made by it.
Violence and the employment relationship
Johan Botes Baker McKenzie
Businesses in SAhave been seekingadvice onhowto dealwiththeimpactofrecent riots, unrest and looting.
Critical querieshave included concerns regarding insurancecover, theabilityto invoke forcemajeure clauses in commercial agreements, ensuring thehealth and safety ofemployees, assisting staff andtheir familieswho are stranded orunable to
procure foodor essential items, andeven dealingwith employees whohave been identified ashaving partaken in the looting.
Businesses are liaising closelywiththeirbrokersand lawyers indealing with insurance companies on payment of claimsrelating to damage caused to property.
The destructionof infrastructure andrisk todrivers have had anegative impact on companies that depend on the transportsystem. These
and other companies wish to understand whether they couldescapedamagesclaims bytheir clientsasa resultof the unforeseenevents outside their control.
Employers havesought guidance onlegal steps required toensure theworkplace safetyof employees required toperform critical functions. Some employers haveevenarrangedairtransport intoaffected areasto eithercollectstrandedstaffor have food, water and other
essential itemsdelivered to them and their families.
Employers havealso been keentounderstandtheirright to takeaction against employees whohave been identified aslooters orvandals on social media.
Footage hassurfaced of drivers ofluxury vehicles merrilytaking partinthe lootingof retailstores. Ina number of cases, the participants areidentifiable through clear footageof theirfaces or vehicle registration numbers.
Employers may well be entitled toterminate theemployment ofsuch employees where theirafter-hours conduct has a negative impact on the employment relationship.
Where a retailer is a client of aprofessional services firm, for example, and a personidentifiedasanemployee of theprofessional services firm was shownon social media to havebeen involved inthe lootingof thesame retail chain,the professional services firmwould have
sound groundsto terminate theemployment ofthelooting employee. No clientwould feelcomfortable tohave service providerswhosestaffparticipated in thewanton destruction andpillaging ofits stores. Theemployer wouldbeentitledtotakedisciplinaryaction against its employee for such nonwork-related conduct, whereit canprove thelink between themisconduct and the ongoing employment relationship.
/123RF
GEMENACOM
BUSINESS LAW & TAX
Penalty for prurient assault
• Court awards damages against employer, manager for sexual abuse of woman sitting alone in her office
Jayson Kent ENSafrica
The plaintiffwas alone inher office on Mondaymorning, November 16, when thesecond defendant entered.
“Aftergreeting her,he walked directly towhere she wassittingatherdesk.Asshe lookedup,hebentdownwith hishead overhersand, putting hismouth overhers, attemptedto forcehistongue into her mouth.She clenched her teeth and tried unsuccessfully to push him away. Aftera minuteor so,he desisted.”
PlaintiffMs Ecouldhave elected touse provisionsof the EmploymentEquity Act, 1998 to seek redress against her employer.However, she chose anotherpotential remedy: a claim for delictual damages in the High Court.
Thetrialinthismatterwas in two parts.The first dealt with whetherthe employer couldbeheld liableforthe actionsof themanagerwho committed theassault described above.The court held the employer could be held vicariously liable.
Thesecondpartofthetrial dealtwith thequestionof what damagesshould be awarded toMs E.Twelve years after the incident, took thehigh court,inPE vBeyers NaudeLocalMunicipalityand Another,awarded MsER4m indamages, payablebyher formeremployer,theDrBeyers NaudeLocal Municipality and the perpetratorof the assault(herthenmanager,Mr Jack) jointly.
This secondpart ofthe judgment should serveas a stern warningto employers in a number of respects:
● Employers arerequired to dealwith sexualoffencesin the workplace in an appropriately seriousand decisive manner to affordproper protection andsupport tothe victim;
● SAcourts arewillingto holdthe employerliablefor the unlawful conductof an employee, especiallywhere that employeeoccupies a senior ormanagerial position; and
● An employeewho isthe victim of such conduct and decides to institutecivil proceedings in thehigh court stands to beawarded damagesthat exceedthecompensation awarded through the CCMAmechanisms providedfor intheEmployment Equity Act.
Thejudge describedthe employer’s stanceas “ an illustration ofhow notto
managea sexualassaultin the workplace”. Whatdid the municipality getso wrongin handling this matter?
Failure tomanage thesituationappropriately Ms Ewas placedon special leaveandwas required,asa first step, to tellMr Jack whohad assaultedheronly two days earlier that she was goingto beabsent from work. Hethen interrogated her on the validityof the reasons for her absence.
Although MsE wastemporarily removedfrom the workplace,MrJackwasnever suspended.
Mr Jack wassubjected to a disciplinaryhearing and found guilty, but he was not dismissed forreasons the judge describedas “mindboggling”
Because Mr Jackwas not dismissed, MsE was,every week, “revictimised” when Mr Jack attended at the office. The municipalityhad undertakento forewarnMsE whenever MrJack wasgoing tobeatthe office,butitfrequently failed to doso. So Ms EwouldencounterMrJackat work unpreparedand began trembling andcrying every
ITS APPROACH OF WASHING ITS HANDS OF THE MATTER, A LA PONTIUS PILATE, FELL WOEFULLY SHORT
timeshe sawor evenheard him.Shecould notsleepand was diagnosed with posttraumatic stress disorder, for which she was prescribed medication.
Eventually, whenMs E could nolonger endurehaving to face Mr Jack at work, she resigned from the municipality afterenduring “horrific circumstances” for almost a year.
Condemning themunicipality’s conduct the judge remarked: “Its approach of washingitshandsofthematter,ala PontiusPilate,fell woefully shortof whatwas required ofan employerin the circumstances.The municipality abdicatedits responsibilities to protect [Ms E] and adopted a supine approach of bovine resignation” and “[Ms E] was thereafter left to fend for herself. The municipalitytook nostepsto support or empower her.
“Shewasofferednocounselling orany otherassistance. Rather, if anything, the
message was thatvictims of sexual assault who were brave enough tocome forward would not receive redress. Theunrepentant perpetrator, Jack, was allowed toroam freein the workplace withunfettered access to [Ms E].
“Although sheno longer reported to Jack, he still exercised a degree of control over her. [Ms E] stated that on one occasion when she applied for leave afterthe assault, the municipality took the stance that itwas Jackwho hadthe authority to approve her leave.”
The court referredto an earlier judgment of the LabourCourt,whichhadheld that anemployer hadeffectively supported the harasser by not sanctioninghim and was unimpressed by the municipality’s “disturbing lack ofappreciation” of its obligation toprovide MsE with a safeworking environment.
Vicariousliability
In determining whether the municipality and/or Mr Jack wereliabletopaydamagesto Ms E, the judge was required to determine whether the municipality should be held vicariously liable for Mr Jack’s conduct.
The courtheld that “there hasbeen, inrecent years,a growing realisationand appreciation of the prevalence and the devastating effects of sexual harassment in the workplace” and referred to severalSA and foreign judgments on the issue, including a minority judgmentof theUSSupreme Court, in whichthe late Ginsberg Jheld thatthe appropriate questionwas whether the employer has “given the alleged harasser authority to take tangible employment actions or to control the conditions under which subordinates do their dailywork. Ifthe answerto either enquiry isyes, vicarious liability is in order, for the superior-subordinate working arrangement facilitating the harassmentis ofthe employer’s making.”
The judgethen determined that, although Mr Jack was acting solelyfor his purposes when he assaulted Ms E, the incident occurred while he waspurporting to renderservice tothemunicipality, and it took place in the workplace.
The judge alsotook into consideration that Mr Jack helda positionofauthority over Ms E. The nature of the employment relationship presented MrJack withthe opportunity to abuse his
COMPANY ACTIONS SPEAK LOUDER
authority over MsE. It was the municipality that had placedMrJackintheposition todoso.The judgeheldthatif anemployerputsanemployee in a special position of trust, the employer must ensure the employeeis worthyofthat trust.Themunici-
SA
COURTS ARE WILLING TO HOLD THE EMPLOYER LIABLE FOR THE
UNLAWFUL CONDUCT OF AN EMPLOYEE
palitywas thusheldvicariouslyliable forMrJack’s “prurient” actions.
Damagesaward
In thiscase, MsE electedto rely onthe commonlaw claim for delictual damages and recover thefull losses she hadsuffered. Butcould she haveachieved thesame objective by using the statutoryremediesprovidedinthe Labour Relations Act, 1995 and the Employment Equity Act, 1998 (EEA)?
For example,she could have claimed the employer’s
conduct constituted unfair discrimination andinstituted a claim inthe Labour Court onthis basisaswell.If afinding of unfair discrimination wasmade, theLabourCourt could order the payment of compensation as well as damages provided that the total amount tobe paid was “just and equitable in the circumstances”
The EEAalso provides other importantremedies. Forexample, thecourtcould order the employer to preventthesameunfairdiscrimination or similar practice from occurringin thefuture. It may also make an order directing the employer to comply with the affirmative action provisions found in chapter 3 of the EEA.
In circumstances where the employee may refer an unfair discrimination dispute (such as acase involving an allegation of sexual harassment)to theCommissionfor Conciliation, Mediationand Arbitration, the commissionermay make “any appropriate arbitration award that gives effect to a provision of the EEA”. It is also given the power to order compensation or damages to an employee.Still, theorderfor
damagesmay notexceedthe amount referred to in section 6 of theBasic Conditions of Employment Act, 1997, ie R211,596.30.
As such,EEA provides potential remedies to an employeewhohasbeensubjected to unfair discriminationequal to,orperhaps more far-reaching, than those provided by common law delictual claims. However,this mustbe qualifiedin one crucial respect,the order must be “just andequitable” and, concerning an arbitration award, “appropriate” SA courtshave often interpreted theterm “just and equitable” to effectively limit the compensation and/or damages granted to the employee.
Reviewed by Peter le Roux, executive in the Employment department.
EMPLOYERS ARE REQUIRED TO DEAL WITH SEXUAL OFFENCES … IN AN APPROPRIATELY SERIOUS AND DECISIVE MANNER
/123RF BORIS15
BUSINESS LAW & TAX
Popia pops up in broad BEE watchdogging
• An enterprise must have a lawful basis for processing personal information of its beneficiaries
Wendy Tembedza & Leigh Lambrechts Webber Wentzel
Under theCodes of Good Practice for Broad-Based BEE (BBBEE), issued interms of theBroad-Based Black Economic Empowerment Act 53 of 2003, an enterprise must maintaina scorecard showing,inter alia,how itis achieving black ownership targets.
Themeasured entitycan earn BBBEE points on the scorecard,as partofthe ownership element,for some collective investment ownership structures.These structuresincludeemployeeshare ownership schemes (Esops) and broad-based ownership schemes (BBOS).
Inthese collectiveinvestmentstructures, thereisan interplay betweenthe ultimate shareholdersof the entityseekingaBBBEErating (the measuredentity), which mayincludeanEsopand/ora BBOS,and theinvestee company, asthe measuredentity. The main players involved in the verification of black ownershipinthis casearethe measured entity,Esop or BBOSandBBBEEverification agent.
The codes require that for the measured entityto be awarded fullpoints foran Esopor aBBOS, thebeneficiariesofthestructure,which is usually a trust, must be defined andidentified. This canbe doneby definingthe beneficiariesasaclassofnat-
ural personscollectively (such as thelocal community of acertain area,learners at schools orcolleges ina particular area)or specifically identifying them ina written record containingtheir details, includingname, age, race group and address. Inboth cases,aregister has to be maintained with the relevant informationof the beneficiariesand itmustbe produced toenable themto be identifiedfor information and verificationpurposes. The measuredentity must obtain therequisite informationfrom thetrust, asit hasto providethedetailsofthespecific beneficiariesto achieve
CHILDREN’S SPECIAL PERSONAL INFORMATION AND PERSONAL INFORMATION NEED ADDITIONAL CONTROLS
anannual ratingby aBBBEE verification agency or audit firm.
The Protectionof Personal Information Act (Popia), whichcameintoforceonJuly 1, has potential implications for measured entities with collective investment ownership vehicles that contribute to their black ownership. Many trustswere established more thana decade ago,before therewas alegal requirement to retain and process the personal infor-
mation of their beneficiaries. In some cases, the beneficiaries maynumber onlya few hundredpeople, butforsome oftheolder andlargerBBOS or Esops,the numbermay run into thousands.
Under Popia,an enterprise, andany relatedtrust, musthavea lawfulbasisfor processing the personal information of its beneficiaries. Theact alsorequires beneficiaries be notified of any sharingof theirpersonal information. The trust or measured entity must ensure beneficiaries are notified that their personalinformation willbeshared withathird party, namely the verification agency and/or their auditors or advisers and, potentially, the measured entity.
In turn,the verification agency isrequired tocomply with Popia in processing beneficiaries’ personal information.
Forexample,adecade-old trustmay havebeenformed to make sustainable investments and willuse the dividends to fundthousands, or tens ofthousands, ofbeneficiaries such as community members or schools. Its investments maystretch across 20 different companies,eachof whichhasto submit itself toBBBEE verification annually. The trust must nowensure ithas a lawful basis, as contemplated in Popia, to share these beneficiaries’ personal informationwith themeasuredentity and the BBBEE verification agent from time to time.
Different typesof infor-
mationaresubjecttodifferent controls. Popiaregulates “personal information” and “special personal information” “Special personal information” includes information about thehealth ordisability of a data subject. If the information pertains to minors, Popia has additional processing requirements.Children’s special personalinformation and personal information need additional controls.
We havediscussed some of the practical examples that large trusts willface in complyingwith Popia.Popiadoes provide guidelines on obtaining exemptions fromthe act, but the thresholdis high (for matterssuch aspublicinterest) and seeking it may not be a practical option.
Under Popia,the responsible party must determine, first,what thejustificationis for collecting the information. Has thetrust madeit clearto the beneficiaries their informationis beingcollectedand held? Is therean agreement
in place with the verification agencies on theprocessing of this information?
Normally, therewould not be a direct relationship between the BBBEE verificationagencyand thetrust.The
UNDER POPIA, THE RESPONSIBLE PARTY MUST DETERMINE, FIRST, WHAT THE JUSTIFICATION IS FOR COLLECTING THE INFORMATION
relationshipis between the measured entitythat hasto completethe BBBEEscorecardand the verification agency,with themeasured entitybeing responsiblefor providingtheagencywiththe information it requires.
Popia also provides that information may not be kept for longer than it is needed, unlessjustified.BBBEEverifi-
cation isannual, sothe verificationagency shouldnot need to keepthe personal informationof datasubjects aftertheaudit hasbeencompleted.However, theremay belegal groundstojustify continued retentionunder Popia. All partiesto the BBBEE verification should ensure they retainrecords of personalinformation ina mannerthat complieswith the act.
Infuture, itwill benecessary toinclude astandard Popia clause inall agreements betweenmeasured entitiesand theirultimate shareholders,who maybe collectiveschemes suchas BBOS or Esops, and between themeasured entitiesand their BBBEEverification agencies.
Employees or other beneficiariesof these schemes shouldsign anagreement consenting to the use of their personaldetails forverification purposes, ifthis clause is not already in place.
Outside-of-work misconduct can get you fired
Jonathan Goldberg & Grant Wilkinson Global Business Solutions
Itiswell known,andlitigated on, thatoutside-of-work conductcan affectyour employment relationship.
If the outside-of-work conduct links backto the employment relationship,the employer is entitledto act against the employee.
This disciplinary action
could include dismissal. Anumber ofothercases haverevolved onsocial mediaposts thathave broughtthe company’s name orreputation intodisrepute. Mostofthiswouldhavetaken place outside of work.
ThisisillustratedinSedick &anotherv Krisray(Pty)Ltd [2011] 8BALR 879(CCMA) wheretwo employeeswere fairlydismissed afterthey hadmade derogatorycom-
mentsabout theiremployer on their Facebookpage. The dismissal was upheld becausethe employeeshad not restricted access to their Facebook platforms.
Anothercase ofsocial mediaabuse, andtheconsequencesthereof,intheworkplace isLucas DyselCrouse Incorporated v Commission for Conciliation, Mediation andArbitration andOthers (C784/2018) [2021]ZALCCT
3 (February 19 2021).
At the forefront, the criminalsystem needstoprosecute these caseswith all these employees.Beyond that there is an employment relationship alsoin playand oneneedsto keepthebasic rulesand disciplineinplace. Alotof theconductwewitnessedcould resultin imprisonment.
Ifwe arebringing lawand order backto SA,not only
shouldthe criminaljustice systemnow workeffectively toprosecute allthese individuals,but allemployers (including municipal employers)need totake decisive disciplinaryaction which inmost cases wouldinclude dismissalto keep thebasic rulesand regulations inplace atthe workplace.
Wecannot haveemployees on national TV looting,
destroying propertyand using theproperty ofthe organisationsto beinvolved inthe mostseriouscriminal conduct.
Thetimeto actisnowand whatis intheemployer realmis thattheyhave employees whoabide bythe rule oflaw when itrelates to serious criminal activities. Most of the conduct we have witnessedis seriouscriminal conduct.
Beware the long arm of our tax law
•
Three-year Sars prescription rule does not apply in cases of taxpayers failing to disclose material facts
Peter Dachs ENSafrica
Whencommentators refer to billions of rand a year beinglost tobase erosion and profit shifting, they are generallytalking about taxpayers whooperate outside the ambit of the law.
However,SA taxlaw catersfor thisgroup.For example, anyonewho deliberately fails todisclose material factsthat shouldhave been disclosed to Sars commits a criminal offence.
Prescription rulesprevent Sars fromissuing further assessments more than three years afterthe original assessments. However, these rules do not apply in circumstances wherethe taxpayer has,for example,notdisclosed materialfacts, resulting in the fullamount of tax notbeingimposedintermsof the originalassessment. This means suchtaxpayers may
bepursued bySars forthe relevanttaxesat anytimein the future.
In terms of our tax legislative process,unlike theUK where tax rules can be amended withno advance warning orconsultation, SA follows atransparent process. Thisgenerally starts with theannual budget speech inFebruary, when proposed taxamendments for the year are outlined. Then,round aboutJune, draft legislationsetting out the proposedamendments is published forpublic comment. After a detailed consultationprocess, thefinallegislationis passedtowardsthe end of that year.
SOUTH
AFRICAN TAX LEGISLATION IS MORE THAN ADEQUATE WHEN COMPARED WITH THAT OF OTHER JURISDICTIONS
Stampingouttaxmischief
However, if some tax mischief is discovered during the year thetax authoritieshave the power toamend the law with immediate effect. We also have a functional advance tax ruling unit that givesrulingsondifficultareas oftaxlawas wellasonmost large, publictransactions. This provides certainty to taxpayers in respectof proposed transactions.
Any SouthAfrican corporate not payingits required share of tax will be subject to the sanctions set out above.
South Africantax legislation is morethan adequate when compared withthat of many other jurisdictions around theworld. Whatis missing is thecapacity to enforceand policethissystem to ensuretax laws are followed, toexpedite taxdisputesand ensuretaxcheats are subject to the relevant criminal sanctions.
This capacitybuilding is urgent and requires people withtaxexpertise inarange
of specialised tax areas. However, once this capacity hasbeenrebuiltourtaxlegislation provides many of the tools required to increase SA’s tax collections. It hasbeen announced recently that Sars is significantly enhancingits highnet worth unit.
When theSars Large Business Centre was reestablishedin2018, oneofits objectiveswas tofocuson high net worth individuals as a “target segment”. To Sars, these are individuals whose gross income exceedsR7m a year and/or whose gross wealth exceeds R75m.
Spotlightonthewealthyand largebusinesses
Sars has recently started issuing letters tohigh net worth individuals,typically
based on information collected from various offshore jurisdictions. These letters typically cover a number of taxyears.Aspects thatareof interest to Sars may include information from the taxpayer regarding confirmation of their offshoreholdings, where the relevantfunds are held,details ofwhofacilitated the investmentsfor thetaxpayer, the sourceof funds used to acquire these assets and incomederived fromthe assets.
In addition,Sars maybe interested in information regarding compliance with therelevant taxobligationsof the taxpayer in relation to such investments or structures.
While prescription means that Sars cannotissue addi-
tional assessmentsmore than threeyears afterthe originalassessment,thisdoes not apply if there has been any fraud, misrepresentation or nondisclosure of material facts by the taxpayer. In those circumstances, Sars can go back beyond the three-year period.
Onanother front,asof March 12020, theforeign employment incomeexemption was capped at R1.25m of an expat’stotal package. I am notsureif thismovewill raise significant tax revenue. Instead itoperates asa disincentive for individuals to traveland workoutsideof SA. Itis importantto notethis applies only to South African tax residents. People who have emigrated from SA and are not taxresident in the country are notaffected by this cap.
Isitmoredifficultforthose wanting to return to SA after workingabroad togettheir tax affairs in order?
In this regard, there are two categories of individuals. Thefirstarethosewhoareno longer considered resident in SAfor taxpurposes. Thereis a fair amountof compliance in respect of their tax position when they comeback to SA andagain becometaxresidenthere.For example,allof their assets willbe valued for capital gains tax purposes and they willonly pay capital gains tax inrespect of any increase in value from the datethatthey becomearesident of SA.
The secondcategory are those who went overseas andare returning,butnever lost their SouthAfrican tax residence. There should not be anycomplexity inrespect oftheseindividualsfromatax compliance perspective.
Tax court ruling clarifies capital gains issue
Megan Landers AJM Tax
Thetaxcourtrecentlyhanded down itsjudgment electronicallyin thematterof MrA (the appellant/taxpayer)vs the Commissionerfor the South AfricanRevenue Service (the respondent/Sars). The matterconcerned an appeal bythe taxpayer against therevised assessmentforthe 2009yearof assessment reflectinga capital gainof R10.6mregarding the disposal ofa business interest thetaxpayer purportedly omittedto disclose to Sars.
InJanuary 2009,thetaxpayer disposed of his shares held in BCD (Pty) Ltd (BCD SA),making himliablefor capitalgains tax(CGT).The issueinthisappealistheproceeds from thesale of the shares and the base cost of those shares.
Intermsof thesaleof shares agreement,the tax-
payerdisposedof allhisBCD SA shares (being53.1% thereof at the time)to the Sail Group foran amountof R66m, andwhich thetax court acceptedas theproceeds that hadaccrued to the taxpayer in respectof that sale.Intermsofthesamesale ofshares agreement,thetaxpayeralso disposedofhis 53.1% shareholdinginterest in BCD Corporation,a company incorporated inthe British Virgin Islands,for R10m, which according tothe taxpayer “shouldhave been lookedat andconsideredas part and parcelof one and indivisible disposalof an asset” by the taxpayer. However, Sars disagrees with thetaxpayer’s contention “that thedisposalof the BCD SAshares and the BCD Corporation shares should be treated,for purposesof capitalgains taxor capital lossestax, asthe acquisition anddisposal of one asset”
Sars contendsthe base costof theBCDSA sharesis simplyR531, beingthesubscription price forwhich the taxpayer originally acquired theBCD SAshareson September 12004. However, the taxpayer argues the base costofthe BCDSAshares shouldbe basedonthe valuation acceptedby the Reserve Bank. In2003,the taxpayer a South Africannontax residentat thetime by application for amnesty of the Exchange ControlAmnesty and Amendment Taxation Laws Act(12 of2003), commenced theprocess ofrepatriatinghis wealthandassets accumulated and earned abroad.To thatend, thetaxpayer disclosedthat he owned an82% interestin the BCD Groupof Companies, consisting atthat stage only ofBCD Corporation valued atR95m, which equates to R61.8m for his 53.1% shareholding.
The tax court accepted the taxpayer’s approachthat the BCD SAshares andBCD Corporation sharesshould betreated asone “asset” beingdisposed ofby thetaxpayer;thatistosaytheshareholder shouldbe treatedas if heholds sharesin onecompany, as thetwo companies are a group.
The tax court, rightfully so, alludedtheretothatforcapital gains tax purposes,when the taxpayer becamea South Africantax residentin2003, he isdeemed tohave disposed ofand reacquired(at market value)his worldwide assets withthe exceptionof
IT CONCERNED AN APPEAL BY THE TAXPAYER AGAINST THE REVISED ASSESSMENT FOR THE 2009 YEAR OF ASSESSMENT
certain assets.The market value established at that time shouldthen betreated asthe basecost (taxvalue) ofthe assetsto determineanycapital gains tax exposure in the future, effectively,resulting in astep-up inthebase costof the BCDCorporation shares from itssubscription priceto the market value thereof as at February 28 2003.
In the end,the calculation translates toR66m (proceeds for the BCDSA shares) plus R10m (proceeds for the BCD Corporation shares) minus R61.8m(basecostforboththe BCD SA and BCD Corporation shares which equates to acapital gainof R14.6m,less R16,000 (annual exclusion which isultimately included in thetaxpayer’s taxable income at aninclusion rate of 25%.
What toremember from thisjudgment?
When a person (who was a taxresident ofanothercountry) commences beinga resi-
dent of SA for tax purposes, theyaredeemed tohavedisposed of andreacquire their worldwide assetsat market value – exceptSouth African immovableproperty onthe day theybecome South African tax resident. The marketvalue establishedwill thenbe treatedas thebase cost(tax value)of the assets to determine any capital gains taxexposure in the future.
Upon subsequent disposal oftheirassets,thecapitalgain or capital loss will be an amountequaltotheproceeds on the disposalless the base cost of theassets (being the market valueestablished when becominga South African tax residentplus any further allowableexpenditureincurredon orafterthe date ofbecoming aSouth African tax resident). Theremay berulesthat limitthebase costsoarrived at to preventcapital losses in the future.
BUSINESS LAW & TAX
Guide to due diligence probe
• Providing the correct documents and ensuring a paper trail will make a company’s life much easier
Justine Krige Cliffe Dekker Hofmeyr
Investorfunding canbe the lifeblood of a startup. However,mostinvestors will want to conduct a due diligence investigation on abusiness before investingany fundsortaking up an equity share. What does thismean for yourbusinessifyouarelooking for funding?These tips should assist.
Whatisa duediligence?A due diligence investigation examines thestructure and operations of the target company,its assetsandliabilities, as wellas anypotential risks itfacesinthemarket.Inshort, are thereany skeletonsin the closet,or risksaroundthe corner?
Thescope ofa duediligence investigationwill vary fromcase tocase.Generally, the moresignificant the investment,themoredetailed and probing the due diligence investigation.
Due diligenceinvestigations typicallycomprise a legal, financialand tax review. This is done by performing acomprehensive analysis of the target company oftenincluding commercial, bankingand finance, litigation, employment,environmental, insurance,tax, intellectual propertyand real estate law aspects.
The assets and liabilities of the target companyand how the businessfunctions are scrutinised. Often various legal, financial andtax teams will work intandem. Due diligence investigations take the proverbial “pulse” of a companytomeasureitslegal, financial and tax health. How is adue diligence investigation undertaken?
The companyunder investigation willtypically be required tomake documentationavailabletothereviewers via a virtualor a physical data room.
THE DUE DILIGENCE REPORT IS TYPICALLY PIVOTAL IN AN INVESTOR’S ULTIMATE DECISION (AND ON WHAT TERMS) TO INVEST
The nature ofthe documents andinformation required will have been set out in an information request. These documentswill depend onthe specificpurpose of the review, but are usuallyamixtureofcompany secretarial documents,constitutional documents, client and supplier agreements, employment agreements and human resource policies,
payroll schedules,business licences,trading termsand conditions, business plans, financialstatements andtax filings, among others.
What are reviewers lookingout for? Generally, reviewers are lookingout for any potential risksfaced by the target company,such as existingdebt obligationsin theformof unpaidtaxor potential administrativefines as a result of statutory noncompliance, as wellas any restrictiveor unusualclauses in agreements, particularly thosethat trigger adverse consequencesin theeventof achange ofcontrol ofthe targetcompany (forexample, if an investor takes up a majority stake).
Dependingontheparticular sector inwhich the business operates, there may be a specificfocus oncertain aspects of the target company’soperations (forexample, an emphasison evidence ofenvironmental legalcompliance in respect of a waste management company).
How isa duediligence investigation ultimatelyrelevant?Ultimately, thereviewers will compilea due diligence report that will give a full pictureof thetarget company. This reportwill enable theinvestor togaugethe commercialviabilityandperformanceof thetargetcompany andmake aninformed
GETTING THE FULL PICTURE
decisionas regardsthe investment.
Itwill alsoinformthe nature andextent ofthe warrantiesand indemnities the investor may want to include inthe investmentagreement
GENERALLY, THE MORE SIGNIFICANT THE INVESTMENT, THE MORE DETAILED AND PROBING THE DUE DILIGENCE INVESTIGATION
CONSUMER BILLS
sothatanyrisksidentifiedare adequatelymitigated.Thedue diligencereport istypically pivotal in aninvestor’s ultimate decision (andon what terms) to invest.
How can the target companyassist? Statutorycompliance(or noncompliance)is akey consideration.Review yourbasic companysecretarialand otherstatutory records, founding documents, employmentcontractsand humanresource policies,supplier andcustomer arrangements,trading termsand conditions,busi-
ness licences and tax filings and,tothe extentthatthese donot complywithlegal requirements, correct these as soon as possible. Ensure the company keeps acomprehensive papertrail and,to theextent possible,as thebusiness concludes key contracts, carefully considerwhether they would be attractive to a potential investor. Businesses thatare structuredcorrectly fromthe outset,andwhich keepup-to-date records,are morelikely tolendthemselves to investment.
Put the brakes on costly, lengthy court action
The Consumer Protection Act establishes a legal framework for a fair market for the benefit of consumers generally and in particular to reduce any disadvantages experienced in accessing the supply of goods by consumers who are lowincome people
We can only wonder what the National Consumer Tribunal would have made of a claim recently heard in the UK court of appeal that related to the sale of a 1962 Ferrari 250 GTO that was sold for $44m.
According to the evidence, only 36 such cars were manufactured by Ferrari between1962 and 1964. At the time they cost $18,000, with each owner having to be personally approved by Enzo Ferrari.
The purchaser was a company that gave the impression in the heading to
PATRICK BRACHER
the sale agreement that it was acting for someone else. The purchaser could easily have been an individual and, if so, the Consumer Protection Act would apply locally to such a R640m deal. It subsequently appeared that the company purchasing the vehicles was acting for itself with a view to reselling the vehicle at a profit, which probably irked the seller. All sorts of disputes arose from the fact that, at the time of sale, the original gearbox was not in the car and was in the possession of a third party. The seller agreed to get possession of the gearbox
and to deliver it to the purchaser and he would get another $500,000 for doing so.
The purchaser did not want to pay the $500,000 until the gearbox had been identified as the original gearbox and wanted it inspected in Italy for authenticity. That suggestion was rejected by the court. The purchaser suggested the gearbox had to be delivered to the purchaser in London rather than California because the contract said the gearbox had to be “turned over ” to the buyer. That argument was also rejected. According to the SA Consumer Protection Act, where the agreement does not expressly provide a delivery address for goods sold, the supplier of the goods must deliver them on the agreed date and at the agreed time, if any, or within a reasonable time after
concluding the transaction. In the absence of different agreed terms, delivery is at the supplier’s cost and delivery takes place at the supplier’s place of business (or residence if there is no place of business). The goods remain at the supplier’s risk until the consumer accepts delivery.
In the Ferrari case, the parties had entered into what one of them said afterwards was a “poorly drawn” contract. Even a poorly drawn contract is better than none because in SA the Consumer Protection Act does not permit patently unfair terms.
The disputes over the Ferrari resulted in court proceedings in California to prevent the possessor of the gearbox parting with possession, and the dispute over the $500,000 and other issues was heard in the London Commercial Court
followed by an appeal to the UK Court of Appeal. Though the seller eventually got his $500,000, the various proceedings must have cost a considerable sum besides the delay the issues took from October 2017 until May 2021 to resolve.
The judges of the court of appeal said it was regrettable that what had begun as a relatively simple dispute between the parties, who had done business together in the past and who shared a love of classic cars, should have mushroomed.
The judge remarked that if the parties were unable to
THE JUDGE REMARKED THE PARTIES SHOULD HAVE ENGAGED A SKILLED MEDIATOR AT AN EARLY STAGE
resolve the matter themselves they should have engaged a skilled mediator at an early stage. Mediation was again urged on them when they applied for leave to appeal, but the parties did nothing about it. The court called this “highly unsatisfactory” There is a lesson to be learnt from this case. Whether you are a lowincome or high-income consumer, formal disputes in front of courts and tribunals are slow, uncertain and expensive. Consumer issues are often relatively simple, and embarking on good-faith mediation can save a lot of time and money no matter how much you think you have of both, and no matter how many principles you think you are fighting for.
● Patrick Bracher (@PBracher1) is a director at Norton Rose Fulbright.
BUSINESS LAW & TAX
Dope can help us to cope with Covid-19
• Legal developments point to a growing attempt to exploit cannabis’ potential amid adequate control
Darryl Bernstein Baker McKenzie
The productionof cannabis for medical andadult use can provide new sources of taxable revenue forcountries seeking torecover financiallyin theaftermath oftheCovid-19 pandemic.
Recent legaldevelopmentsin SApointto agrowingattempt toharnessthe plant’s potentialand ensure adequate controlof thecultivation and saleof cannabis products.
In April2021, the government proposed a draft national masterplan withthe aim ofloosening regulations in the industry to boost economic development.
The plan looks at the prospect ofcreating an export marketfor cannabis producers andhow current legislationcanbeamendedto remove constraintson the commercial cannabis market.The planalsoinvolves increasing investment in cannabis industry research. Othersuggestions in the planare supportforfarmers and indigenousdagga growers in the cannabis value chain,aswell assupportfor manufacturing and product development. Oneof thepriorities in theplanis signingof theCannabis forPrivatePurposes Bill into law by 2023.
SMALL PRODUCERS
Countriesthat wanttomake a success oftheir cannabis production industriesare now looking at ways to reducethe barriersforsmall farmers to help steer the legal
cannabis marketin amore equitable andsustainable direction.
The currentlegislative frameworks for cannabis production tend topush out the smallercannabis producers. Legislators arelooking at waysto givesmallfarmers preferential accessto subsidies andfinancial assistance, special licencesand quotas Inthis regard,thereis aneed for consultationwith small producers and experts in the health care, lifesciences, and legalsectors toensurethe right legislativeframework is in placeto supportall elements of the market.
THE STRINGENT QUALITY CONTROL MEASURES ARE NECESSARY TO ENSURE THE PRODUCT IS SAFE FOR MEDICAL USE
This will also help to ensure the rapid development of thecannabis market is in line with the UN sustainable development goals, especially the the notion that no one gets left behind.
CANNABIS LAW IN SA In SA,requirements forpermitsand licencestoproduce andsellcannabisareonerous andlegaladviceisanecessity to participate in this sector. SA permitsthe cultivation of medical cannabis. A licence can beobtained,but the processes are stringent. The Medicines and Related Substances Act of1965 his-
torically mandated the then Medicines Control Council, now the A Health Products Regulatory Authority (Sahpra), toregulate theavailabilityof qualitymedicinesthat are safe and efficacious for their intended use.
Among otherthings, this mandate requires Sahpra to apply standardsfor themanufacture, distribution, selling and marketing of medicines, medical devices and scheduled substances, including cannabis.
Interms ofthemedicines act, medical practitioners are permittedto applytoSahpra for permissionto accessand prescribe unregistered medicines whenintended totreat their patients, which may include cannabis.
Accordingly, Sahpra acknowledges and permits cannabis products, intended formedicinal purposes,to be made available in exceptional circumstances, to specific patients undermedical supervision.
Potential cannabis growers and producers should note that, under the medicinesactandinlinewith the UN Single Convention, the cultivation, production, manufacturing and use of medicinal cannabis products may only occurthrough a licence issued bySahpra and apermit issuedbythe department of health.
Applicants canapply to Sahprafor alicence tocultivateor growandproduce cannabis and cannabis resin, extract and test cannabis, cannabis resinand/or cannabinoids, and to manufacture medicinescontaining cannabinoids.
PLAN OF ACTION
In thelicensing process, Sahpra will inspect the plans forthefacilityandthequalitycontrol procedures,among other things. In addition, applicants would be required to apply tothe directorgeneral ofhealth fora permit toacquire,possess,manufacture, use or supply cannabis.
The stringentquality control measures are necessary to ensure the product is safe for medicaluse. Althoughno limit is placed on the amount of cannabis that can be grown,aspart oftheapplicationprocess,Sahprawillallocate a permitted quantity.
Recent legal developments include the reassigning of cannabidiol (CBD), which is acomponent of the cannabis plant, from schedule 7 ofthe medicines act (highly regulated substances) toschedule4(substancesthat canbesold withaprescription). In addition, some productswithdelta-9-tetrahydrocannabinol (THC) levels of lessthan 0.001%andless than 0.0075% of CBD were excluded fromthe listaltogether, which means they can be purchased without a prescription.
For licensedcannabis producers in SAthis has now opened a range of potential new marketsfor theirproduct. Thatbeing said,CBD products which donot fall under the exemption namely those CBD products andproductswithTHClevels of morethan 0.001%and morethan0.0075%ofCBD continueto requireapre-
scription by a medical practitioner to be sold.
PERSONAL USE
The laws around personal use of cannabispoint to its increasing acceptance under certain circumstances.In 2018,theConstitutionalCourt legalised theprivate useof cannabis, upholdingthe Western Cape High Court’s 2017ruling, whichfoundthat the criminalisation of the privateuse ofcannabiswas unconstitutional.
The ConstitutionalCourt found that banning private cannabis use was an infringement of a person’s rightto privacyand “ unconstitutional and invalid”. The court also ordered parliament to draft new laws within 24months (thedeadline was September 2020) to reflect the order.
In September2020, the government publishedthe Cannabis for Private Purposes Bill which stipulates that people who deal in cannabis or sellit toa minorare likely to face 15 years of jail time.
The regulationsalso state that anyone whois found guilty of smokingthe substance inpublic ortoo close toa nonconsentingadultcan face upto twoyears injail, while a jail sentence of up to four yearsis tobe expected for those who smoke close to children.
For thoseliving alone,the rules state theycan have unlimited seeds, buta maximumoffourfloweringplants, grown for personal use only.
INTERNATIONAL CONVENTIONS
SA isa signatoryto thethree UN conventions that regulate the international tradein narcotic substances and the country is inregular contact with the International Narcotics Control Board. The threeUN conventions are the SingleConvention on Narcotic Drugs, 1961 (as amended by the1972 protocol); the Convention on Psychotropic Substances,1971; and the Convention Against IllicitTrafficinNarcoticDrugs and PsychotropicSubstances,1988. Thepurposeof theseconventionsistoestablish internationalcontrol measures for psychoactive substances sothey canbe madebeavailableformedical andscientificpurposes,while preventing their illegal use.
RISKS
Countries have different levels oflegislation forcannabis and there is a high risk of breaking laws in some jurisdictions for those transacting across borders in the cannabis industry.
Inlightofthesediscrepanciesin approachtocannabis regulation betweencountries worldwide, and in particular the extraterritorialapplication ofanti-money-laundering legislation, financial institutions shouldconsider whether thecross-border elements of a proposed financing are likelyto trip up the cannabis laws to which they are subject.
Lenders, investorsand underwriters in particular should query whether the borrower hassubsidiaries, assets or operations in other jurisdictions that have not legalised their cannabisrelated businessactivities, and whether the activity in question would be considered illegal in the jurisdiction inwhichthelenderorunderwriter operates.
Lenders, underwriters and other capital providers should consider their own internal risk appetite, including the legal, regulatory, credit and reputational risks of transacting across borders in the cannabis sector.
Despite theserisks, recent legal developments in SA highlight the many opportunities tocapitalise onthe demand for cannabis products as a way to recover from the effects of the pandemic.
Countries use laws such as Fatca to tail fat cats
Peter Dachs ENSafrica
One of the historic difficulties for Sarshas beento identify highnet worthindividuals andascertain allrelevant detailsof theirassetsand structures.But inrecent years the tax-disclosure landscape changed radically. Oneof thegamechangers
hasbeen theCommon ReportingStandards. Thisis anOECD initiativethatintroduceda standardisedmodel for the automatic exchange of informationto allowparticipating jurisdictions to exchange informationabout their tax residents.SA agreed toexchange informationin termsofthis initiativein2017. TheUS equivalentofthe
Common Reporting Standards is the Foreign Account Tax Compliance Act (Fatca). In addition, in terms of the TaxAdministration Act,2011, Sars mayrequest orprovide information to foreign governments underdouble tax agreements or other multilateralor bilateralinformation exchange agreements. Theautomatic exchangeof
information (AEOI) forms part ofthis information exchange. AEOIinvolves the systematic and periodic transmission oftaxpayer information betweencountries for variouscategories of income. Informationabout the acquisitionof significant assets may beused to evaluatethe networthof anindividual.As aresult, thetax
authority ofa taxpayer’s country ofresidence can check its tax records to verify thattaxpayershaveaccurately reportedtheir foreignsourced incomeor assets. Sars receivesinformation from87jurisdictionsinterms of the AEOI regarding South African taxpayers.
The individualtax return also requires information from taxpayersregarding their foreigninvestments and structures, suchas offshore trusts. Forexample, thetax return requires a taxpayer to provide information regarding capitalcontributions or loans used to fund offshore trusts aswell asinformation regarding distributions from such trusts to South African resident taxpayers.
/123RF JENYAOLYA
Deal-makers target tech firms in Africa
• While inbound investment rose in the first half of 2021, the unrest in SA threatens this trajectory
Wildu du Plessis & Marc Yudaken Baker McKenzie
Baker McKenzie’s latest analysis of Refinitiv data shows that the value of mergers and acquisitions (M&A)in the firsthalf of2021 (H12021) soared in SA,and that deal value alsoincreased inNigeriain thefirstsix monthsof 2021, butKenya experienced a slightdecrease inboth deal value and volume in H1 2021.
The valueof M&Atransactions in SAin H1 2021 amountedto $52bn,with169 deals announced. Compared tothefirsthalfof2020,transactions volumes fell8% but dealvalue increased 958% in the first half of 2021.
Refinitivdata showsthe volume ofdomestic transactions increasedslightly to80 deals, a 10%increase year on year. Domestictransactions inSA inH121 wereworth $46.7bn, adramatic 2,148% increase year on year. Further, cross-bordertransactions increased 17% year on year to 89deals, with deal value surging 251% to $5.4bn.
Despitethe excellentstart to2021,the unrestinSA threatenstoaffectthepositive stridesmade interms offoreign investmentinto the
country in the first six monthsofthis year.Forthe sake ofSA’s post-pandemic recovery,the turmoil has to beendedbeforeinvestorsare forced to seek less risky alternatives.
Foreigninvestorswillonly ramp uptheir investmentsif theyareconfidenttheirassets are safe.They needpolitical and economiccertainty and must haveconfidence there is rule of lawin the countries in which they invest.
High-technology companies were the primary targets forinbound dealsin SA,with 12 transactions,representing 200% in deal volume year on yearand adeal valueof $160m, an increaseof 1,997% when comparedto thesame period last year.
It’s no secret African consumershave shownagrowing relianceon technology across multipleplatforms, even well before the pandemic struck. The growth of the digitaleconomy across
AFRICAN CONSUMERS HAVE SHOWN A GROWING RELIANCE ON TECHNOLOGY ACROSS MULTIPLE PLATFORMS
the continent has naturally been acceleratedby thepandemic and this unabated demand for technology has caused extensive crosssector disruption, with the financial, energy, transport, retail, health and agricultural sectors all seeking opportunities to expandtheir tech infrastructure
Fintech is also a popular tech sector for investment across Africa, and specifically inSA,KenyaandNigeria,with health tech, mobility and agritechalsoattractinggrowing interest.
TECH SECTOR
It lookslike SAis leadingthe way in terms of highvaluedeals inthe techsector, and weexpect thistech M&A trend tocontinue asthe continent gearsup tooperate in the post-pandemic new normal.
The US wasthe primary investor for SA companies, with 16 deals (an increase of 60%year onyear) valuedat $496m(an increaseof340% year on year).
This was helpedby TPG Capital LP’s $200m acquisitionof AirtelAfricaPlcMobile (telecommunications), announced in March 2021.
The largestinbound deal in H1 2021 was Temasek Holdings (Pte) Ltd’s (Singa-
AN INTERCONNECTED WORLD
pore) $500m acquisition of Leapfrog Investments (financials), also announced in March 2021.
Twenty-eight deals were recorded in Nigeriain the first half of 2021, and deal value amounted to $1bn. Compared to the first half of 2020, transaction volume rose 17% anddeal value soared 267%.
Refinitiv data reveals domestic transactions decreased 15% to 11 deals, but deal value increased 342% year on yearto $726m. Cross-border transactions increased 13% year on year to 17deals, withdeal valuerising 8% to $296m.
Financialcompanieswere the prime targetsfor inbound deals, with four transactions showing a 100% increase yearonyearanddealvalueof $10m,a 327%increaseyear on year.
Once again, theUS served as the primary investor for Nigerian companies,with fourdeals worth$13m.The largest inbound deal into Nigeria inH1 2021was Mwendo Holdings BV’s (SA) $182m acquisition of Blue LakeVenturesLtd(Mediaand Entertainment), announced in June 2021.
While USinvestors have shown interest in Africa for some time, under President Joe Bidenthe generalconsensusisthatUSengagement with African countries is focusing onstrengthening relationships in a strategic, co-operative way. It has beennoted that Biden will continue with successful bipartisanprogrammes implemented by his predecessors, as well as further encouraging US tradeand investmentinthe continent.
TWENTY-EIGHT DEALS WERE RECORDED IN NIGERIA IN THE FIRST HALF OF 2021, AND DEAL VALUE AMOUNTED TO $1BN
Considering UScompanies were thetop investors in twoof Africa’s largest economies in the first half of 2021,deal-makersareclearly comfortable with Biden’s approach to Africa.
InH12021,deal-makingin Kenya decreased 14%, with 18
deals in theperiod, and deal valuedecreased96%to$11m. Financial companieswere theprime targetsforinbound deals,with fivetransactions, representinga 150%increase year on year, with deals valued at $11m, a78%decrease year on year.
KENYA INVESTMENT
Nigeriaservedastheprimary investorfor Kenyancompanies, with threedeals. The largestinbound dealinto Kenyain H12021 wasLiberty Holdings Ltd’s (SA)$8m acquisitionof LibertyKenya Holdings Plc (insurance), announced in March 2021.
Thedecrease inM&Avolumeandvalue inKenyainH1 2021 is expectedto be temporary as thecountry continuesto implementpandemic recoverypolicies, includinga vaccinerollout strategyfor the adult populationwith a plannedcompletion dateof mid-2022.
The country’s reputation as an East African investment hub, in addition to its strong technology capabilities, meansitis justamatterof timebeforeKenyatakesupits rightfulplaceasoneofthetop targetcountries fortechnology transactions in Africa.