01 · M A RKE T L A ND S C A P E · 2026 – 2 0 3 5
Rear Door Heat Exchange Market Room-neutral rack cooling moves to the core of AI data centers
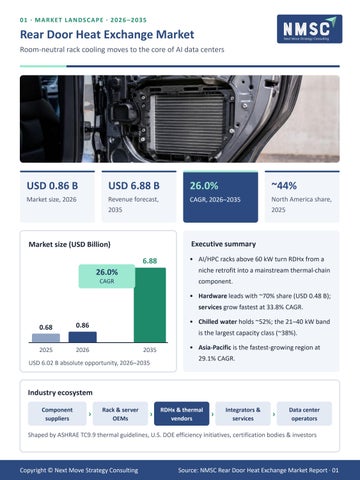
USD 0.86 B
USD 6.88 B
26.0%
~44%
Market size, 2026
Revenue forecast,
CAGR, 2026–2035
North America share,
2035
2025
Executive summary
Market size (USD Billion) 6.88
• AI/HPC racks above 60 kW turn RDHx from a
26.0%
niche retrofit into a mainstream thermal-chain
CAGR
component. • Hardware leads with ~70% share (USD 0.48 B); services grow fastest at 33.8% CAGR.
0.68
0.86
2025
2026
• Chilled water holds ~52%; the 21–40 kW band is the largest capacity class (~38%). 2035
USD 6.02 B absolute opportunity, 2026–2035
• Asia-Pacific is the fastest-growing region at 29.1% CAGR.
Industry ecosystem Component suppliers
›
Rack & server OEMs
›
RDHx & thermal vendors
›
Integrators & services
›
Data center operators
Shaped by ASHRAE TC9.9 thermal guidelines, U.S. DOE efficiency initiatives, certification bodies & investors
Copyright © Next Move Strategy Consulting
Source: NMSC Rear Door Heat Exchange Market Report · 01
02 · G RO W T H D RIV E RS & O P P ORTUNITIE S
Growth Drivers & Opportunities AI rack density alone adds +4.1 points to market CAGR
Catalyst & risk impact on CAGR (2026–2035)
Driver Restraint
Rising AI/HPC rack densities (>60 kW)
+4.1
Hyperscale liquid-cooling retrofits
+2.8 +2.2
OEM factory-integrated shipments
+1.8
Energy-efficiency & PUE mandates OCP rack & CDU standardization
+1.4
Asia-Pacific capacity expansion
+1.2
Direct-to-chip & immersion competition
−1.7
High upfront capital cost
−1.1
Water quality & leak-containment
−0.8
High-growth segments · CAGR 2026–2035
36.8%
35.4%
33.8%
Above 60 kW capacity
OEM sales channel
Services revenue stream
32.7%
31.5%
31.4%
DCIM-integrated control
Server manufacturer buyers
AI infrastructure end users
01
02
03
OEM factory integration
Open Compute alignment alignment
Bundled services for colocation
Pre-installed doors cut on-site
OCP-certified doors shorten
Design, install & maintain
commissioning time for
shorten multi-vendor
packages serve operators
hyperscale buyers; OEM is the
qualification; Open Compute
lacking in-house liquid-cooling
fastest channel.
Compute racks grow at 30.0%
cooling expertise.
Whitespace opportunities
30.0% CAGR.
Copyright © Next Move Strategy Consulting
Source: NMSC Rear Door Heat Exchange Market Report · 02
03 · RE G IO NA L O P P O RTUNITIE S
Growth Opportunity Map Asia-Pacific and MEA outpace the 26.0% global CAGR
Europe USD 0.15 B → 1.36 B 24.7% CAGR
North America USD 0.30 B → 2.61 B 24.2% CAGR · ~44%
Asia-Pacific ▲
share
USD 0.16 B → 2.06 B
Middle East & Africa
29.1% CAGR · fastest
USD 0.04 B → 0.50 B 28.7% CAGR
Latin America USD 0.03 B → 0.35 B 27.8% CAGR
Reg ion
2025
2035
C AG R
Key g rowth d river
N orth A m erica
0.30
2.61
24.2%
H yp erscale A I retro fits, new b uild s
Europ e
0.15
1.36
24.7%
Efficiency m and ates, co lo up g rad es
A sia- Pacific
0.16
2.06
29.1%
H yp erscale & co lo : C hina, Ind ia
M id d le East & A frica
0.04
0.50
28.7%
S overeig n A I, G ulf hyp erscale
Latin A m erica
0.03
0.35
27.8%
C o lo & hyp erscale in Brazil
Values in USD Billion; CAGR 2026–2035
DOMINANT COUNTRY · U.S.
FASTEST COUNTRY · INDIA
USD 0.25 B → 2.09 B
USD 0.03 B → 0.39 B
23.7% CAGR; demand anchored by hyperscale,
29.2% CAGR; one of the fastest data center
colocation and AI capacity, favoring OEM factory-
pipelines globally as vendors localize deployment.
integrated doors.
deployment.
Copyright © Next Move Strategy Consulting
Source: NMSC Rear Door Heat Exchange Market Report · 03
04 · C O M P E T ITIVE S C E NA RIO
Competitive Landscape Integrated thermal-chain portfolios are winning hyperscale
Moderately consolidated Top players serve most hyperscale hyperscale accounts
20
USD 9.5 B
Companies profiled; share data for top 10
Vertiv liquid-cooling-driven backlog, Q3 2025
Reach: regional / enterprise → global hyperscale
Competitive positioning matrix OEM / SERVER PLATFORMS
INTEGRATED THERMAL-CHAIN LEADERS
Lenovo · HPE · IBM · Super Micro
Vertiv · Schneider Electric · nVent
Racks shipped with doors pre-installed for hyperscale
CDUs, rear doors, cold plates & services for
hyperscale buyers
multinational accounts
SPECIALIST POINT SOLUTIONS
REGIONAL INFRASTRUCTURE GROUPS
CoolIT Systems · Coolcentric
Rittal · STULZ · Huawei · Delta
Engineering precision & rapid deployment for
Regional manufacturing & engineering in Europe and
enterprise, colocation
Europe and Asia-Pacific
Portfolio breadth: point solution → integrated thermal chain
Recent strategic moves Mar 2025 Sep 2025 Nov 2025
Vertiv launches CoolLoop RDHx, up to 80 kW per rack
Schneider Electric unveils Motivair-based portfolio portfolio incl. ChilledDoor nVent debuts OCP-spec Project Deschutes CDU at SC25
Dec 2025
Vertiv completes ~USD 1.0 B PurgeRite acquisition
Apr 2026
Vertiv acquires Strategic Thermal Labs
May 2026
Vertiv expands EMEA line with CoolChip CDU 2300
Key strategies • M&A: platform deals for fluid &
cold-plate skills • Launches: 80 kW+ high-density doors • Expansion: STULZ plants in Hamburg & Texas • Standards: OCP-aligned designs
Copyright © Next Move Strategy Consulting
Source: NMSC Rear Door Heat Exchange Market Report · 04
05 · C O NNE C T W IT H U S
Thank You Turn market intelligence into your next strategic move
Connect with our analysts for in-depth insights & strategic guidance
20
38
Top 10
9
Companies profiled
Countries covered
Company market shares
Segmentation axes
Website
www.nextmsc.com
Phone
+1 857 758 5017
info@nextmsc.com
Click here for the complete report → Follow us
Copyright © Next Move Strategy Consulting
YouTube
Twitter / X
www.nextmsc.com · 05