SECTION
BARCELONA 2026
I S S U E
3 8
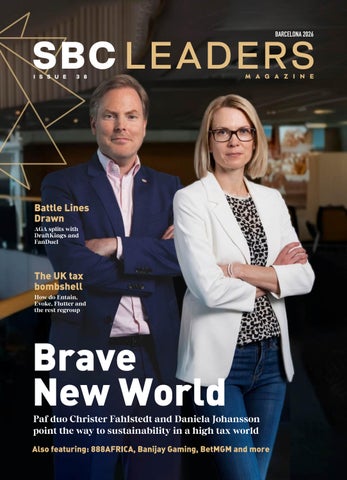
Battle Lines Drawn AGA splits with DraftKings and FanDuel
The UK tax bombshell How do Entain, Evoke, Flutter and the rest regroup
Brave New World
Paf duo Christer Fahlstedt and Daniela Johansson point the way to sustainability in a high tax world
Also featuring: 888AFRICA, Banijay Gaming, BetMGM and more 1
SBC EVENTS 2026
LISBON
FLORIDA
29 September-1 October 2026 Feira Internacional de Lisboa, Lisbon
9-11 June 2026 Broward County Convention Center, Fort Lauderdale
RIO
3-5 March 2026 Riocentro, Rio de Janeiro
MALTA
28-30 April 2026 InterContinental Malta
TORONTO
19-21 May 2026 Metro Toronto Convention Centre
For more information please visit sbcevents.com or scan the QR code
EDITOR’S NOTE
Finding the right path In the UK, the debate over increased taxes has been long and tiresome with neither side covering themselves in glory. The end result is an industry flailing around trying to decide which costs to cut (p.28). In the US, the debate about prediction markets has been just as fierce and just as tiresome, with the end result for now being a split industry (p.22). This one, however, will only be truly settled by years of court cases. In Europe, where many a tax rate has been raised already, debate continues to revolve around over-regulation and the prevalence of the black market, which also casts its shadow over the battles in the US and UK. The regulated gambling industry seems to be lurching from one crisis to the next. It considers itself assailed on all sides – by politicians raising taxes, regulators implementing playing restrictions, the radical public health lobby fighting gambling (rather than just gambling harm) and the media highlighting its worst excesses. This is a time for calm heads. But it is also a time for industry leaders to break from the methods that got them into this mess. It is the ideal time to highlight the philosophy of Paf and its inspiring leadership team (p.12). Paf’s model of sustainable gambling could provide a template that disarms many of the forces that line up against the industry. On a similar note, the Better Gambling Forum (p.36) is engaging a diverse range of stakeholders aimed at providing lawmakers and regulators with a global best practice model for a sustainable and safe gambling industry. These are not radical idealists – in many ways they are business-minded pragmatists. And pragmatism – the quality of dealing with a problem in a sensible way that suits the conditions that really exist, rather than following fixed theories, ideas, or rules – seems in short supply right now. Steve Hoare, Editor, SBC Leaders
The SBC Leaders Magazine is brought to you by SBC - Sports Betting Community: Editorial Team: Andrew McCarron, Craig Davies, Ted Menmuir, Joe Streeter, Conor Porter, Charlie Horner, Jessie Sale, Fernando Noodt Molins, Callum Williams, Viktor Kayed, Martyn Elliott, Lucia Gando, Jessica Welman, Ted Orme-Claye, Steve Hoare, Justin Byers, Kieran O’Connor, Christian Lee, Tom Nightingale, Elisa Marcante, Ana Maria Menezes, Rachael Kennedy, Ricardo Assis Sales Team: John Cook, Rasmus Sojmark, Alyona Gromova, Conall McCabe, Jan Kowalczyk, Camilla Scott, Bob McFarland, Craig Brown, Ed Young Creative Lead | Design and Layout: Jessica Camilleri
3
SBC LEADERS ISSUE 38
12 Paf
36 Better Gambling Forum
28 What next for UK?
© 2025 Sports Betting Community Limited. All rights reserved. All content in this publication, including articles, photographs, and other materials, is protected by copyright under the Copyright, Designs and Patents Act 1988. The copyright in all materials in this publication is owned by Sports Betting Community Limited or its licensors. You may not reproduce, distribute, or otherwise use any of the content without the express written permission of Sports Betting Community Limited (SBC), except as permitted by law. For permissions or licensing inquiries, please contact sales@sbcgaming.com. The views in the publication are not necessarily the views of SBC or those of the advertisers. Although every effort has been made to ensure the accuracy of the information contained in this publication, SBC cannot be held responsible for any errors it may contain. In no event shall SBC be liable for any direct, indirect, incidental, special, consequential, or exemplary damages, including but not limited to, damages for loss of profits, goodwill, use, data, or other intangible losses (even if we have been advised of the possibility of such damages), resulting from the use or the inability to use the material contained in this publication. Produced and published by Sports Betting Community Limited REGISTERED ADDRESS: SBC, 2nd Floor, 212 New Kings Road, London, SW6 4NZ EMAIL: sales@sbcgaming.com | WEB: www.sbcgaming.com & www.sbcleaders.com
4
Contents 06 People
36 Interview:
888AFRICA CEO Christopher Coyne reflects on his career; plus Nicolas Beraud gives his first interview as Banijay Gaming Chairman; plus leaders on the move
Busiest man in gaming unveils global ambition
12 Spotlight: Paf CEO Christer Fahlstedt and Deputy CEO Daniela Johansson on a radical model
18 IMGL analysis: Spain Patricia Lalanda Ordóñez of Spanish law firm LOYRA analyses the Spanish regulator’s new RG algorithm
22 The Hot Topic: US industry splits
DraftKings and FanDuel split with bricks and mortar over prediction markets
28 Analysis:
What next for the UK? The industry got it badly wrong in the debate over increased taxes. Where does it go from here?
82 Comment: Ras Sojmark
Ras: The SBC leader looks to AI and web 3.0 in his new year’s message
PLAYER PROTECTION
35 Column:
Searching for light Steve Hoare on seeds of hope in black market fight
Shawn Fluharty of Better Gambling Forum
PAYMENTS
41 Column:
Slowly, slowly… Rachael Kennedy on the beauty of the pause
42 Feature:
The FCA vs UKGC The UK regulators claim to be in alignment but payments might fall between the gaps
CASINO
49 Column: The death of the middle classes
Joe Streeter studies how midtier operators will deal with the UK tax bombshell
62 Thought Leadership: Vyking CEO Franz Gerhart
The industry is undergoing a fundamental shift away from customer acquisition and towards a focus on platform architecture
SPORTS BETTING
67 Column:
The point of no return Ted Menmuir analyses the first moves made by UK operators after the tax hike
68 Interview:
Paul Witten of SIS Managing director Paul Witten shows US customers unveils new product for betting on American Football in the off-season
72 Interview:
IGT and Xtremepush
50 Interview: BetMGM’s
Joe Bertolone of IGT PlaySports and Xtremepush’s Tommy Kearns reveal details of innovative partnership
Matt Prevost is pulling every lever in BetMGM’s quest for market share
MARKETING
iGaming innovation
54 Interview: Fincore
77 Column:
CEO Mateja Popovic
Paid search set for comeback
CEO implores operators to break free of legacy systems
Jyoti Rambhai on marketers’ responses to hard times
58 Thought Leadership:
78 SBC Summit:
EvenBet Gaming CEO Dmitry Starostenkov on the metaverse opportunity
The highlights and the numbers behind The Greatest Show in Gaming, plus the SBC Awards 2025
EvenBet’s Dmitry Starostenkov
5
Lisbon report
PEOPLE
SBC LEADERS ISSUE 38
My Life IN Gambling CHRISTOPHER COYNE
888AFRICA CEO CHRISTOPHER COYNE surveys a career that has taken in online, land-based, mega-listed operators and startups; from telecoms to restaurants and casinos to sportsbooks; in the UK, Ireland, Australia, the Cayman Islands and Africa. Coyne has covered some ground
1997-2008: BT, John Lewis and GE Capital I wanted to be a doctor but a car crash cut short that ambition. So, I spent my 20s working for these really big companies in a variety of roles before the opportunity to work at Paddy Power came along. Having lived hard and played hard in London for 10 years, the move to Dublin appealed and joining this fledgling online business was really exciting. 2008-2014: Paddy Power I started as Head of eGaming and it was a real spit and sawdust affair. Ultimately, I was promoted to be the Head of PaddyPower.com. We had the most phenomenal few years of becoming not the challenger anymore, but actually the leader.
We just caught the energy of what was betting back in 2008/09/10 and this thing was a rocket ship. You’d wake up every single day, open your device, your laptop, your phone, whatever, and go to the daily report. And there were vertical lines going up. It was such an exciting place to be. 2014-2017: Crown Resorts I got the opportunity of a C-Level job as Chief Marketing Officer of Crown Resorts, a move to Melbourne and working with my best mate Matt Tripp as an executive board member on Crown Bet. Of course, Crown Resorts is the largest land-based casino operator in Australia but I also got to work with all the non-gaming stuff. We brought Nobu to Australia and Heston Blumenthal’s Fat Duck
6
restaurant. While the kitchens were being rebuilt in the UK, he shipped the entire thing to Australia. 2017-2020: The Stars Group As a family, we had a wonderful time in Australia but it was time to come home. Rafi Ashkenazi was building a new C-suite and invited me in as CMO. It was an incredible team. COO Guy Templer was Rafi’s number two. Zeno Ossko ran the sportsbook before Andy Lee took over – and he’s with me now at 888AFRICA. Bo Wänghammar ran the casino, before handing over to Asaf Noifeld. Asaf’s the most talented gaming person I know. He’s an incredibly brilliant product person. I left when Flutter took over – and most of that team left – but Asaf is now running things at FanDuel – he’s a legend.
PEOPLE
Leaders making moves Former LeoVegas executive Lauren Findlay joined Yolo Group as Chief Digital Officer of Yolo. com. She is joined by Chief Marketing Officer Rhiannon Bach, who has had spells at Caesars and Sands Casino. Superbet founder Sacha Dragic is back in the role of sole CEO, which sees joint CEO Jimmy Maymann move to a board position. COO Albert Simsensohn takes over as deputy CEO, with international CCO Eamonn O’Loughlin moving to COO.
2020-2022 GOAT Interactive Working at Stars was incredibly eye-opening about the global nature of gaming. Before I joined, it was live in 130 countries or something. You would get reports from this obscure place with FTDs and revenue every day. So, I was keen on emerging markets and I was planning something in Brazil but eventually teamed up with Premier Bet to supposedly put rocket boosters on its online operation. GOAT was my Dad’s idea because our family were shepherds in County Mayo in Ireland. 2022 - PRESENT 888AFRICA Africa needs investment and Premier Bet couldn’t quite get it done in negotiations with then 888 Holdings. So me and three of my Co-Founders exited Premier Bet. 888 had seen the African opportunity and was keen to invest in my brilliant leadership team – the four of us from Premier Bet (me, Helen Scott-Allen, Martin Nieri, and Alex Rutherford), plus two senior
LeoVegas Group has appointed ex-Fanatics and Sky Betting & Gaming trading head Andy Wright as its MD for the UK and Ireland. Evoke Chair Lord Mendelsohn has been replaced by former KPMG partner Mark Summerfield. DraftKings has named former bet365 Head of Gaming Christian Bogstrand as its new EVP and General Manager of iGaming. Former EY Partner Jonas Groes joins his brother Ebbe Groes as co-CEO of EveryMatrix.
execs I’d worked with at Stars, (Andy Lee and Ian Marmion). We formed a joint venture with 888 (now Evoke). Effectively they own 20% of 888AFRICA now, with an option to increase their shareholding to up to 80%. Me and my team are the majority owners for now.
My Life OUTSIDE Gambling
The Africa opportunity is massive. Africa is 54 countries and we have the experience to choose which ones we can compete in. We see the future of 888AFRICA as a combination of very strong organic growth linked and aligned to an inorganic strategy, and we have mapped a clear plan on potential M&A. So we need the right investment energy to make all of this happen. If we get the right investment, meaning if we have the right investment partner, we believe we will create the next billion dollar-valued iGaming group on the African continent - and a group that is a real contender to the BetWays and the betPawas, who are the two continent leaders.
My beloved family, my beloved Everton and, more recently, an MBA, which I received from Oxford University just last week. I think my early life experience of University left me with an itch to scratch. So many people have told me about the power of an MBA – for your career, as a networking opportunity and as a learning experience. My wife Debbie, my daughter Grace and my son Ruben, my Mum and Dad and Uncle Kevin were there. It was an amazing family moment.
7
PEOPLE
PURCHASING POWER SBC News spoke to NICOLAS BÉRAUD, the founder and CEO of Betclic and now chairman of the newly-created Banijay Gaming, in the hours after the announcement of the French operator’s €4.6bn acquisition of Germany’s Tipico
9
PEOPLE
SBC LEADERS ISSUE 38
B
anijay Group has agreed terms to merge its Betclic business with Tipico Sportwetten to create Banijay Gaming, a business with revenue of over €3bn and adjusted EBITDA of €850m (combined pro-forma results for FY2024).
term, the group has always clearly stated its intention to open up new growth opportunities in Europe and other continents.”
Banijay acquired a 65% stake in Tipico from private equity owners CVC Capital and its founders, with the expectation that it would increase its stake to 72% with further purchases from CVC.
Banijay now joins FDJ United as perhaps one of the less predictable drivers of pan-European consolidation. But the restrictions in France – where politicians and lawmakers have started to talk about regulating online casino games but done little apart from talk – are actually a driver for overseas growth, says Béraud.
“By combining the strengths of Betclic, Tipico and Admiral, we are creating a digital and omnichannel group that is stronger and more resilient,” Béraud told SBC News. “It also diversifies our geographical risks and gives us the means to accelerate our development and strengthen our position in sports betting, our core business. We are entering a new phase in our journey: that of a European group focused on sustainable growth.” Once completed, Banijay Gaming will operate three core brands — Betclic, Tipico and Admiral Austria, serving 6.5 million active customers across six regulated markets: Germany, France, Portugal, Austria, Poland and Côte d’Ivoire.
“
France being highly regulated and heavily taxed automatically limits our room for manoeuvre. Therefore, expanding internationally is a necessity, not an option
“Betclic and Tipico share a common understanding of how to operate in highly regulated environments and this is a strength: this rigour drives us to be better, more innovative and more responsible,” said Béraud. Tipico is very much centred on German-speaking markets, but Betclic has always been more outward-looking. It claims market leadership in Portugal and Cote D’Ivoire and number two position in Poland. What’s next? “Our immediate priority is the convergence and stability of our three organisations,” responded Béraud, when asked about future expansion. “But we have always had an entrepreneurial culture: when the fundamentals are solid, we naturally look towards growth. In the medium
10
“The possible arrival of new players such as Bet365 does not change our trajectory,” he continued.
“France being highly regulated and heavily taxed automatically limits our room for manoeuvre, while current budget debates seem to show that fiscal stability is clearly not yet a reality in France. Expanding internationally is therefore a necessity, not an option,” stated the new Banijay Gaming Chairman. Brazil has been mooted as a possible destination, while Africa’s other French-speaking countries would seem an obvious destination – most being regulated. Banijay has made its ambitions clear. It becomes Europe’s fourth largest listed gaming company behind Flutter, Entain and Lottomatica. With the aforementioned FDJ next and the acquisitive Allwyn at number six, it is clearly a time of much change at the top end of Europe’s betting and gaming markets. “With several major M&A transactions taking place in our industry over the past five years, giving rise to increasingly large operators. This must be taken into account,” added Béraud. “Thanks to our new size, we are gaining investment power, technological agility and marketing strength. This will enable us to continue innovating, promoting responsible gaming and offering the best possible experience to our players.”
SPOTLIGHT
SBC LEADERS ISSUE 38
THE REAL DISRUPTORS Paf CEO CHRISTER FAHLSTEDT and Deputy CEO DANIELA JOHANSSON are the visionaries creating a template for the future of sustainable gambling
12
SPOTLIGHT
Words by STEVE HOARE
A
cross Europe and beyond, gambling taxes are rising. The regulated gambling industry’s only response seems to be to scream “black market” at lawmakers in a generally-doomed attempt to change their minds.
So, the argument goes, tax rises equal weaker products, less generous odds, and more players pushed toward the black market. It ain’t necessarily so, argues Fahlstedt. He has seen no evidence of his players fleeing to the black market in any of the jurisdictions mentioned above.
Paf CEO Christer Fahlstedt has an alternative view. As will become abundantly clear throughout our conversation, Fahlstedt has an alternative view to many accepted norms of industry wisdom. Perhaps though, it’s time the industry listened to some alternative views rather than seemingly flailing from one crisis to the next.
“If we scream too much about tax increases we are not necessarily helping our cause,” he says. “We need to have a joint view. ‘When tax goes higher, please make sure you – the government – protects us from unlicensed operators.’ That’s the deal that has to be made.” But what about the black market argument? It is perceived as fact that you need to lower odds, and cheapen the product if you pay more tax.
“Taxes going up is a trend. It’s going to continue to increase, so it’s just a fact of life,” says Fahlstedt. Paf has very recent experience of these tax rises in many of its key jurisdictions. In Sweden, gambling tax increased from 18% to 22%. In Finland tax more than doubled from 5% to 12% (but this was a return to normal levels after a tax drop during Covid). The government also increased the rate in Latvia and Estonia, although the latter has dropped back again. The result was Paf’s earnings decreasing slightly from €55.1m to €54.3m. Those rates are lower than some other European jurisdictions but Fahlstedt is unconcerned with them rising further . Indeed, he knows they will.
“Nonsense,” says Fahlstedt. “It just means that we get to keep less of what the players have lost. So there’s no impact on the player experience whatsoever.” He accepts that costs need to be cut but says you would take that out of marketing spend before you cut investment on the product. You might increase reliance on AI. There are plenty of things you can do to increase efficiency before the last resort of cheapening the product. “I have a problem with this line of argument,” he continues. “We need to realise our position in the food chain. If you ask the average voter whether we should increase taxes on labour, reduce healthcare services, or increase taxes on gambling, 99% will say: increase the taxes on gambling.”
Similar pressures are building across other regulated markets in Europe and North America as governments seek additional revenue while responding to public unease about gambling harms.
When tax goes higher, please make sure you – the government – protects us from unlicensed operators. That’s the deal that has to be made
13
“
SPOTLIGHT
SBC LEADERS ISSUE 38
Higher taxes are not the industry’s enemy – bad behaviour is – and that includes antagonising politicians and the public. If the sector continues to resist reform, it risks losing legitimacy entirely. This counterintuitive stance frames the broader philosophy shared by Fahlstedt and Paf Deputy CEO and Chief Responsibility Officer Daniela Johansson. Paf’s charitable ownership structure gives it freedoms most operators lack, but the pair are clear that such freedoms don’t exempt them from market realities. Paf competes in the same jurisdictions, faces the same regulatory headwinds and needs to adapt to the same customer trends as everyone else. What sets them apart is their conclusion: the industry must evolve before it is forced to. Done well, that evolution could disarm anti-gambling critics, reduce political hostility, and create a stable long-term operating environment. Done badly – or too late – and the future looks far more restrictive. RADICAL TRANSPARENCY There will be those within the UK industry (particularly),
who will claim to have got in front of regulatory developments – not without some justification. But have they been bold enough?
to around 290, while revenue has doubled through efficiency and technology.
In 2017, Paf began publishing detailed revenue segments that show exactly how much players in different loss brackets contribute to the company’s profits. They remain the only operator in the world to publish this kind of data.
Looking at the chart [below], you will see revenue from those spending over €30,000 ending in 2017. In 2018, the company set a hard cap on what a customer is allowed to spend in a year. Today the limit sits at €17,500 and is trending downward each year. Fahlstedt is aiming for it to drop as low as €8,000.
“This entire industry’s profitability is driven by addiction. If you remove addiction, there is zero profitability left,” he says bluntly. This is precisely why he sees the future moving inexorably toward only “green” revenue – players who lose amounts comparable to other expensive hobbies like owning a horse or a boat. “In the long run,” he says, “the public will not allow more losses than this segment.” The challenge, therefore, is preparing the business for a world where revenue from harmful play must gradually be engineered out. Paf has already taken significant steps: staff numbers down from 400
BEYOND LIMITS
“It’s a clear and concrete example of how we take responsibility,” Johansson says. “It’s also been quite a debated topic, not very popular in the industry but appreciated by regulators and banks.” Younger adults, a demographic proven to be more vulnerable to harm, face much lower caps: €1,800 for 18-19-year-olds and €6,000 for those aged 20-24. And this is an area where other operators have followed. But doesn’t a player just go to another operator when s/he maxes out at Paf? “That’s a fair question,” responds deputy CEO Johansson, “and we actually
TOTAL GAMING PROFITS CUSTOMER SEGMENT (EUR)
2024
2023
2022
2021
2020
2019
2018
2107
0,
0
0
0
219,812,*
6,072,132
9,648,523
13,653,368
15,001 - 30,000
18,271,370
16,277,904
16,890,079
14,026,102
18,284,221
26,214,835
18,087,884
18,436,519
8,001 - 15,000
40,136,117
39,276,018
42,019,085
29,342,290
24,750,155
28,863,944
22,007,735
21,600,129
0 - 8,000
198,084,579
176,351,783
163,851,378
134,369,798
120,684,221
104,547,874
71,470,935
67,150,397
WINNING PLAYERS
-50,743,868
-49,309,516
-46,191,446
-43,161,469
-43,367,676
-31,772,901
-23,056,491
-23,003,994
TOTAL
205,748,198
182,596,189
176,569,096
134,576,721
120,570,733
133,925,884
98,098,586
97,836,418
>30,000
14
SPOTLIGHT
asked our players the same thing in a recent survey. Many of them said that reaching the loss limit made them gamble less often or even stop completely, while some players continued playing with other operators. So even if some do go elsewhere, for many the limit clearly works as intended, it helps them slow down and reflect on their play.”
“We work continuously to support sustainable gaming,” she says. “Our player tracking system enables different kinds of interactions with players who show signs of risk. The loss limit is an important safety net, but it works together with all these other measures.” Paf also prioritises targeted messaging over generic warnings. “General statements like ‘Gambling can be addictive’ don’t make much difference,” Johansson notes. “Personalised messages do.”
And crucially, the limit is backed by research. Paf funded a study with Stockholm University showing that voluntary limit-setting had almost no impact on reducing losses. “That insight made us realise stronger measures were needed,” Johansson says.
A BLUEPRINT FOR BETTER REGULATION
“I’d like to see others publish their customer segments openly and show where their revenues come from,” she adds. “That kind of transparency would strengthen public trust in the industry and align perfectly with good ESG reporting standards.” While the loss limit attracts headlines, Johansson emphasises that it is only one element of Paf’s broader RG architecture.
Fahlstedt is equally outspoken about the structural flaws in European regulation – particularly the freedom that major game suppliers and payment providers are given to operate in both licensed and unlicensed environments. “It’s amazing how much grey or black business circulates through huge listed suppliers,” Fahlstedt says. “And it’s not changing.” He welcomes Tipico’s advances in blacklisting those that do both (noting it probably has the market
NUMBER OF CUSTOMERS PER SEGMENT
power to do so) but he would prefer the authorities to step in with proper, enforceable B2B licensing. If a supplier offers games to licensed Swedish or UK operators, for example, those same games should not be accessible to players in those markets via offshore sites. “That must be a bottom line,” he insists. On the player protection side, he pushes for national, centralised deposit limits managed by regulators, not individual operators. “The authorities are the only ones with the total view – on income, debts, number of children,” he says. “People don’t want to supply this information to gambling operators but the authorities have this information. If they really want to protect people, consolidate the data and decide centrally who can gamble how much.” A WARNING TO FINLAND While Fahlestedt and Johansson seem to be advocating for a radical change in operators’ operating models, the accompanying evolution of the authorities’ enforcement should not be such a leap.
AVG. GROSS GAMING PROFITS PER CUSTOMER (ERU)
2024
2023
2022
2021
2020
2019
2018
2107
2024
2023
2022
2021
2020
2019
2018
2107
0.00%
0.00%
0.00%
0.00%
0.00%
0.05%
0.13%
0.20%
0
0
0
0
54,953
39,175
39,870
44,765
0.18%
0.24%
0.27%
0.25%
0.28%
0.43%
0.48%
0.60%
16,871
16,833
17,235
17,959
19,597
20,561 20,255 20,349
0.63%
0.92%
1.09%
0.89%
0.69%
0.91%
1.09%
1.32%
10,395
10,437
10,587
10,627
10,654
10,655
10,751
10,805
78.66% 71.83% 76.93% 70.52% 72.91% 70.83% 66.74% 73.65%
408
598
585
617
494
498
570
604
20.54% 27.02% 21.66% 28.32% 26.12%
27.78%
31.57% 24.22%
-400
-445
-586
-494
-495
-386
-389
-629
100%
100%
100%
333
445
485
436
359
452
522
648
100%
100%
100%
100%
100%
15
SPOTLIGHT
SBC LEADERS ISSUE 38
HOW TO STAY COMPETITIVE
Paf is based in the Åland Islands, an autonomous region of Finland, which is preparing to launch a new regulatory regime in 2027. The opportunity is there for a clean slate but both Fahlstedt and Johansson express concern that the new regime is too weak.
Paf’s charitable structure enables it to take certain positions that commercial operators will claim they cannot. “The biggest challenge is staying competitive while staying true to our values,” Johansson asserts. “Being an ethical gaming company means making decisions that put people first, even when it impacts the bottom line. That’s why we have taken tough measures that many in our industry avoid, like the yearly loss limits and openly reporting our customer segments. These choices come at a financial cost, but they reflect our values. We are not here to maximise profit at any price, we are here to run a sustainable entertainment company that generates funds for the benefit of society.”
“I would have hoped for stronger measures,” says Johansson. “For example, a central deposit limit system where players set their limit once, and that same limit applies across all licensed operators. That would have been a real step forward for player protection. It’s especially important now, when we’re seeing a lot more young people starting to gamble and a big increase in contacts to helplines from that age group. As a society, we should do more to protect them. They’ve grown up with gambling elements in games, like loot boxes, and can easily open accounts at unlicensed sites. I believe we as a society have failed to protect them.”
Is theirs a model that listed companies could follow? “If I’m a CEO of a listed company, my job is to maximise profits while following the law,” says Fahlstedt. “The law is what needs to change.”
Meanwhile, Fahlstedt fears an incoming backlash similar to what has occurred in the Netherlands. “On January 1st, 2027,” he warns, “Finland will see a marketing blitz it has never seen before. There will be so much gambling advertising that people will be furious. There is no love for gambling companies, but there is hate for gambling advertising.”
Paf’s model is showing regulators – and the industry – what the endgame of sustainable gambling can look like. An operating profit of €57m on turnover of €183m is an end-result that many commercial operators would be pleased with. By way of comparison to a similarly-sized listed operator, albeit not completely likefor-like figures, UK operator Rank’s online division recorded operating profit of £33m on net gaming revenue of £236m in 2024/5.
His recommendation is simple: gambling advertising should be digital-only, where you can fully opt-out, and delivered only to adults actively seeking gambling content. Anything else, he argues, accelerates political hostility. “When we annoy the public, we annoy politicians,” he says. “Then we lose our seat at the grown-ups’ table when we discuss things like the black market.”
If Paf’s charitable remit is unique and gives it the leeway to take a hit on profits where others seek to maximise them, its strategic logic applies to everyone: Firstly, higher taxes are inevitable – so embrace them and demand strong enforcement in return; secondly, public trust is more valuable than a short-term revenue spike; thirdly, mass advertising is a political
Again, the deal with the authorities is that when people search for gambling, they should only find legal options. Google, Facebook and the rest need to step up and help make this happen.
16
SPOTLIGHT
If we scream too much about tax increases we are not necessarily helping our cause
“ Paf CEO Christer Fahlstedt
liability; fourthly, transparency strengthens credibility; and finally, long-term survival depends on reducing harmful play.
from that of its commercial peers. The difference is that it is building the kind of operator regulators want in their market.
Fahlstedt and Johansson are not advocating for a smaller industry. They are advocating for one that can thrive without provoking public outrage or regulatory shockwaves.
Or as Fahlstedt puts it: “We’re turning 60 next year. And we’re going to do another 60. This is the future – and we need to be ready for it.” If the rest of the sector wants the same longevity, they may find that following Paf is not idealism, but a necessity.
Paf may be a charity, but its competitive reality is no different
17
IMGL ANALYSIS
SBC LEADERS ISSUE 38
BEST of INTENTIONS In the first of a series of articles from the International Masters of Gaming Law, PATRICIA LALANDA ORDÓÑEZ, a Partner at Spanish law firm LOYRA, explains the pros and cons of the Spanish regulator’s new RG algorithm
S
pain is undergoing an unprecedented regulatory transformation. At the heart of this shift lies the Royal Decree on Responsible Gambling, passed in 2023, a cornerstone of the new regulatory landscape. In accordance with this regulation, gambling operators are mandated to establish
mechanisms and protocols for detecting risky player behaviour. It is within this framework that the Directorate General for the Regulation of Gambling (DGOJ) has launched a project to implement a single, mandatory algorithm, designed to homogeneously detect such conduct among all licensed operators.
18
IMGL ANALYSIS
“
The regulator’s justification is supported by its data, which points to an “evident under-detection” of problem gamblers under the current model. This model, where each operator applies its own criteria, apparently generates an unacceptable disparity: while some report up to 13.6% of accounts at risk, the majority present figures close to zero.
A player flagged as at-risk must remain under these restrictions for a minimum of six months
A RIGID AND AUTOMATED PROCESS For operators, the implementation of this system is not a guide to best practices, but rather the execution of a strict algorithmic protocol over which they have limited control. The objective of this mechanism is to categorize registered players identified as displaying risky behaviour into “intense gambling behaviour” or “vulnerable” participants. The aim is to automate the detection processes of these players to then apply the regulatory restrictions that must be enforced if this condition persists.
•
The detection model, explained by DGOJ Director Mikel Arana on various occasions, is based on a specific algorithm. This algorithm uses the real behaviour of individuals medically diagnosed with a gambling disorder as a reference for its configuration and design. In this way, a statistical system based on XGBoost is utilized, trained with data from 506 individuals with a clinical diagnosis of pathological gambling. Based on 81 variables inspired by clinical criteria and European standards, risk patterns are identified. The model has been validated with 6,000 real accounts. The algorithm will be mandatory for all operators as of 2026, replacing the internal systems many operators have implemented, although these may still be used in addition to the DGOJ algorithm.
•
•
The process will be executed obligatorily during the first seven days of each month, analyzing the activity of each player over the last 183 days (6 months). The mechanics are structured into four sequential phases: •
the probability of false positives among purely recreational profiles. Detection of “Direct Risk”: Before applying the complex model, a mathematical formula based on three key variables (losses, participation, and deposit frequency) automatically categorizes as “atrisk” those who exceed a predefined threshold. This serves as a fast track for the most evident cases. Variable extraction: For the remaining players, operators must calculate 62 behavioural variables, ranging from economic indicators (net losses, number of deposits) to risk patterns such as “cancelled withdrawals” or intensive play during late-night hours. Execution of the predictive model: Finally, these 62 variables are fed into the XGBoost algorithm. If the resulting risk probability exceeds the threshold of 0.3160608, the player is labeled as “at-risk behaviour.”
Once a player is classified as at-risk, the consequences are automatic and severe. Within a maximum of 24 hours, the operator must prohibit the use of credit cards, suspend any promotion or VIP treatment, and contact the player to inform them of their situation, requiring an active response. If the player does not respond within 72 hours, their account must be suspended.
Filtering of sporadic players: Users with minimal activity (eg. fewer than two deposits in six months) are first excluded from the analysis to reduce
19
IMGL ANALYSIS
SBC LEADERS ISSUE 38
THE SIX-MONTH SENTENCE •
Here lies one of the system’s most controversial points. A player flagged as at-risk must remain under these restrictions for a minimum of six months, with no possibility of early review, even if their behaviour was an isolated incident.
A LAUDABLE GOAL, A QUESTIONABLE METHOD
This approach raises serious doubts about the proportionality and actual effectiveness of the mechanism. The most worrisome aspects of this model can be summarized as follows: •
•
•
increasing vulnerability for those needing protection. Legal uncertainty: A “black box” algorithm from the DGOJ raises the risk of litigation, adding legal complications for operators
The DGOJ’s initiative to standardize player protection is a necessary step to ensure a safe and responsible gaming environment across the Spanish regulated market. However, the proposed solution, based on a single, rigid, and mandatory algorithm, generates more uncertainties than certainties.
Technical obsolescence: A static model without ongoing retraining risks becoming outdated compared to adaptive AI solutions, while monthly evaluations create a fourweek “risk window” that can allow serious gambling issues to escalate unnoticed. False positives: The binary classification system may mislabel non-addicted users, such as VIPs and casual players, leading to stigmatisation. Indicators like “canceled withdrawals” may reflect fund management rather than compulsive behaviour. Leakage to illegal markets: Unfair restrictions might drive players to unregulated operators,
The one-size-fits-all approach clashes with the complexity of human behaviour and the sophistication of current technological tools. For this new paradigm to be truly effective, it would be prudent to consider the sector’s demands: gradual implementation with a pilot phase, a higher frequency of evaluation, mechanisms for managing false positives, and, fundamentally, a clear framework of responsibility. Otherwise, a well-intentioned measure could become an obstacle that harms both operators and the very players it aims to protect.
LOYRA Partner Patricia Lalanda Ordóñez
20
The International Masters of Gaming Law is a member association of the world’s leading gaming lawyers, regulators and advisors. IMGL members are: • The leading gaming lawyers in their jurisdictions • Pre-qualified by invitation-only membership of IMGL • Committed to growing your business successfully wherever you are To find an expert IMGL legal advisor in your market, scan the QR code & filter by jurisdiction
For more information about IMGL, our conferences and the benefits of becoming a member, reach out to Brien@ IMGL.org or visit www.IMGL.org
THE HOT TOPIC
SBC LEADERS ISSUE 38
LEAVING LAS VEGAS 22
THE HOT TOPIC
A split has broken out between the landbased casino establishment and the online gaming industry, which leaves the two sides further apart than at any time since Sheldon Adelson’s influence was at its peak Words by TOM NIGHTINGALE
W
hen is sports betting not betting on sports? When it’s trading on sports.
At the start of 2025, prediction markets were mainly a way for people to stake money on the outcomes of real-world events related to things like the economy, politics, and entertainment awards shows. By the start of 2026, sports event contracts are a big slice of the pie for exchanges such as Kalshi and Crypto.com. They are also the product du jour for some of the biggest names in online gaming, offering a route to expanded sports betting horizons under the federal regulation of the Commodity Futures Trading Commission (CFTC). As gaming operators launch sports contracts, a fissure has emerged between the land-based casino establishment and online operators. FanDuel and DraftKings went as far as to split from the American Gaming Association (or they were expelled from the AGA, depending on which side of the fence you sit) over a fundamental difference of opinion. This has been an uneasy alliance and one that was never built to last but this is the fiercest the rivalry has been since Caesars and friends tried to block PokerStars from entering New Jersey in 2013. TRADING ON THE FUTURE The pair of market-leading sportsbooks, along with several other online-first gaming brands, were prominent first movers. Whether through partnerships with CFTC-licensed exchanges – FanDuel with CME Group, Fanatics and Underdog with Crypto.com, and PrizePicks with both Kalshi and Polymarket – or by acquiring one, as DraftKings did with Railbird, several online gaming operators either already offer sports prediction markets or intend to do so soon. The value proposition for these digital-native operators is evident: more direct reach across the US, more users on their platforms, and more dollars in their pockets.
23
THE HOT TOPIC
SBC LEADERS ISSUE 38
“
It’s not a place we’d like to see this marketplace go, full stop. Officially, it is not something we endorse MGM Resorts International CEO Bill Hornbuckle
While each operator to enter the space has manoeuvred differently, a commonality is that the sports contracts on their respective platforms are targeted towards states where regulated sports wagering is unavailable. This blend of state-conducted betting and federally regulated trading increases operators’ total addressable market to the entirety of the US, something that doesn’t look like happening anytime soon through sports betting legislation.
first to announce a joint venture prediction markets offering with a CFTC-licensed exchange in August.
The horizons are expanded and the game is changed, at least in the immediate term.
“We will immediately unlock a significant incremental addressable market by offering a compelling sports product to the vast majority of the US adult population in those states currently without sports betting,” said Jackson in announcing the launch of sports contracts. “We are exceptionally well-positioned to harness this growth opportunity to extend the FanDuel footprint into new states, and our aspiration is to be the clear market leader.
THE FLUTTER-BY EFFECT For the likes of FanDuel, whose opportunity to grow in sports betting is stunted by the slow pace of state-level legislative expansion, sports contracts are a sideways move that could make all the difference. Before DFS and sports betting operator Underdog began offering them back in September, FanDuel owner Flutter was the
24
That Flutter moved early is unsurprising. Not only does it lead US sports betting, but as CEO Peter Jackson points out, its history of operating the Betfair exchange gives them nous and a positioning that is uniquely advantageous when taking a step like this. If there was one sportsbook that was a sure bet to make this move, it was FanDuel.
“It’s a hugely exciting opportunity and one we will seize.”
THE HOT TOPIC
STATING THE CASE Given their status as de facto duopolists in US sports betting, if FanDuel pursues a potentially lucrative pivot, DraftKings can ill afford to leave it alone. In announcing the launch of DraftKings Predictions, CEO Jason Robins went as far as to say it’s the most bullish he’s ever felt about his company’s future. Like FanDuel, DraftKings is directing the sports side of predictions at states where it is not operational as a sportsbook. Both Jackson and Robins reiterate that part of the reasoning is that the additive revenue potential is much greater where sports betting is not an option. California and Texas, for instance, are the two most populous states by a distance; neither has legal online sports betting, but both now have online sports trading. “FanDuel Predicts will allow us to go after the half of the market that we haven’t previously been able to go after,” notes Jackson.
But another reason for the geotargeting is the issue that continues to hang overhead above all of this: Can federally regulated sports prediction markets and state-regulated sports betting co-exist? That question remains before the courts, contested by Kalshi and others, and seems unlikely to be authoritatively settled anytime soon. How that shakes out will be a key factor in determining where things go next. In the meantime, several states have sounded alarms. Regulators in the likes of Nevada, Illinois, Michigan, Ohio, Arizona, Massachusetts and New York all voice concerns, with some suggesting that even offering sports prediction markets out of state reflects badly on a licensee and could risk jeopardizing their state gaming licenses. THE LAST RESORT FOR CASINOS? As mostly online operators with no great ties to Las Vegas,
25
FanDuel and DraftKings gave up any claims to licences in Nevada in November in favour of exploring the prediction markets opportunity. Robins and Jackson both say they’re confident that discussions with state regulators will not threaten their sportsbook operations, but both clearly felt Nevada was not worth the hassle. For legacy gaming operators with histories rooted in brickand-mortar casinos resorts, like Caesars, PENN Entertainment and BetMGM parent MGM Resorts International, the shoe is on the other foot. These casino operators are cautious, showing little interest in moving while uncertainty lingers. “MGM Resorts’ view is it invites the federal government into a space it’s never been, and it’s not a place we’d like to see this marketplace go, full stop,” says the company’s CEO Bill Hornbuckle. “Officially, it is not something we endorse.”
THE HOT TOPIC
SBC LEADERS ISSUE 38
“As the law stands today, sports prediction markets are, in essence, illegal sports betting,” is how BetMGM CEO Adam Greenblatt puts it, a stance echoed by PENN leader Jay Snowden and Caesars chief executive Tom Reeg. “We will not put any of our state licenses at risk,” maintains Reeg. “We believe what’s happening in prediction markets is sports gambling.” OPPORTUNITY OR EXISTENTIAL THREAT? That underlines a fundamental divide between gaming companies that exist mostly in the digital space and those that remain rooted in land-based gaming and have expanded outwards digitally from there. FanDuel, DraftKings and the other online-focused operators who have made moves evidently feel there’s little to lose at this stage, while state-regulated betting and federal prediction markets remain concurrently viable options. FanDuel and DraftKings have disruption in their DNA going back to their DFS-only days, so the fissure with the AGA is not wholly surprising. In contrast, the historic land-based casino leaders have a deep footprint in online sports betting but casino gambling at their core. With physical assets to protect and a great deal of financial investment in brick-and-mortar gaming, for them, the stakes go far beyond drawing lines on the definition and regulation of sports wagering.
“
FanDuel Predicts will allow us to go after the half of the market that we haven’t previously been able to go after Flutter CEO Peter Jackson
Hornbuckle fears that embracing prediction markets would take sports wagering above state-bystate regulation, which he describes as “something this industry has historically and categorically defended against.” PENN’s Snowden has similarly ominous feelings. “If you can move forward with prediction markets and sports gambling, what would stop you from offering prediction markets and
26
contracts on the next spin of a slot machine, the next hand of blackjack, the next spin of the ball for a roulette table? This is existential.” A LONG ROAD AHEAD As for where we may go next, given the way things have accelerated, the situation may have evolved quickly by the time you have this magazine in your hands. The earlymoving operators clearly don’t think it’s going away, and FanDuel and DraftKings particularly have drawn lines in the sand. The next big question, other than what further court decisions bring, is how states will respond. Regulators who warned licensees beforehand may face a tough choice between either taking sportsbooks to task for offering prediction markets elsewhere in the US, or holding back and letting it happen. FanDuel and DraftKings make up the bulk of taxable online gambling activity and revenue in every state in which they are licensed. Will states feel they can truly afford a regulated sports betting market without the two behemoths? For their part, Jackson and Robins maintain that their companies’ sports betting operations remain the focus. “Prediction markets are having a negligible impact in the states where FanDuel Sportsbook is already available to customers,” says Jackson. “In our existing sportsbook and iGaming states, our primary focus will continue to be the stateregulated market. In the long-term, we firmly believe that stateregulated sports betting and iGaming remains the most valuable long-term opportunity in the US.” Meanwhile, the eyes of so many others will be on how things proceed. Caesars’ Reeg evokes a feeling likely held by many: This isn’t going away anytime soon. “It seems like the path this is on will ultimately be decided at the Supreme Court level,” he reflects. “I would expect we’re going to be in this cloudy period for quite some time.”
ANALYSIS
SBC LEADERS ISSUE 38
The UK gambling industry needs a new compass following the government’s tax judgement, writes SBC Editor At Large TED MENMUIR
28
ANALYSIS
A
s anticipated, the Autumn Statement delivered the expected tax increase on remote gambling that triggers the next cycle of wholesale change for UK gambling licensees. Industry leaders had worked themselves into a public frenzy of frayed nerves, following months of speculation after HMRC published its consultation on “tax treatments on remote gambling licences” in May. The build-up to Chancellor of the Exchequer Rachel Reeves’ announcement, due on Wednesday 26 November, saw an industry fixated on being spurred by the ‘nightmare scenario’ of Labour increasing Remote Gambling Duties above the 50% threshold, recommended by some thinktanks, and a doubling in General Betting Duties (GBD). In retrospect, the vernacular of a nightmare was suitable as the UK gambling industry faced its Judgement Day. Yet the mood music quickly changed from The Terminator soundtrack to the theme tune of Benny Hill. Just hours before the address, the Office of Budget Responsibility (OBR) accidentally published its post-budget report on its website before the budget had been announced. A vexed Reeves took to the despatch box furious at the OBR’s fumble as media quickly leaked the Budget’s fiscal plans. In the Commons, opposition MPs called for “Rachel to just skip to the end.” The leak saw the Budget announcement lose its shine, as everyone was fully aware of what was to come. Reeves’ statement was a meek proceeding to the declaration that from April 2026, the UK gambling industry will have to live with fiscal terms of 40% tax on Remote Games and 25% for online sports bets (excluding UK horse racing) from 1 April 2027.
29
ANALYSIS
SBC LEADERS ISSUE 38
INSTANT REACTION
The new tax plan is framed as an act of “moral arithmetic”. The Chancellor argued that remote gaming “generates disproportionate social harms” and therefore should “bear a proportionate fiscal responsibility”.
Instantly, PLCs such as Flutter Entertainment, Entain, and Evoke, whose UK operations already face mounting compliance and affordability costs, branded the new regime as “damaging”. Every talking head that could be found expressed “disappointment”.
The framing landed well with her backbenchers, less so with the City, where analysts instantly revised forecasts downward for all exposed PLCs. Yet, by the end of the week, to the surprise of observers, shares in listed gambling firms had recovered in lost value, a sign that tax hikes had long been factored in by longterm shareholders.
Flutter CFO Robert Coldrake told investors within hours that the change will carve more than $320m from group EBITDA in 2026 alone. Evoke said the budget would increase duty costs by approximately £125135m. Entain said it equates to an EBITDA impact of approximately £100m in 2026 and approximately £150m from 2027.
Reality bites but the UK industry is not alone. Tax regimes above 50% have become the norm in Europe as France, Germany and Poland have all tightened fiscal screws on online gaming above the 50% mark.
Having to withstand a gut punch to earnings, Flutter and its rivals will likely pull the trigger early on home revisions once more, as the era of UK gambling under cost controls continues to close its decade of regulatory scrutiny and transformation.
LONG-TERM DAMAGE Irrespective of its tax judgement, UK gambling maintains a binding structure like no other market. Since 2005, it has evolved to become the most mature and competitive market in Europe, with deeper product depth, broader sports, and a far more mature consumer base.
Reaction to the Budget from industry stakeholders was instantly bleak, with many noting that the government had effectively kneecapped the gaming segment that generates around 65% of UK online revenues as of 2025. Attention quickly shifted to how operators would absorb the bottom-line shock: scaling back marketing, reducing player promotions, and aggressively renegotiating terms across their value chains, which now appears inevitable.
As such, it is unlikely to morph into the oligopoly model of three or four megalicensees dominating market share. Survival will demand scale, data, compliance infrastructure, and capital reserves that PLCs comfortably muster.
Yet for all the noise, every stakeholder acknowledges the same uncomfortable truth – nobody yet understands what the lived economic reality of such steep tax hikes will be for UK operators, market competitiveness, or future market share dynamics.
More likely is the slow disappearance of the mid-tier, the middle class of operators, which will shrink, either closing shop or being absorbed into the balance sheets of the larger PLCs. This will test whether the Gambling Commission’s long-held view that choice and market depth are the UK sector’s strongest defence against illicit and unlicensed gambling.
Speaking to the iGamingDaily podcast, the excellent Dan Waugh of Regulus Partners summed up the industry’s uncertainty: “We knew remote gambling would be targeted, but 40% is a massive rise. As it stands, the only certainty is that nobody can model what happens next – and certainly not the Treasury.”
Perhaps the new reality is a strong tier one that can afford the very highest compliance and player protection standards, and no smaller operators succumbing to AML fines and creating self-defeating headlines?
The blow cuts deeper because it comes just as Whitehall’s long-running review of the Gambling Act was meant to deliver stability and regulatory certainty. Instead, the new duties effectively reset the playing field, as remote gambling and betting tax are viewed as Labour’s intervention in what had become a “soft-touch” gambling review inherited from the Conservative government.
For the Tier-1 giants, the next five years will require hard revisions around redesigns of value chains, partnerships and commercial relationships as focus won’t just be about cost control but on overall structural control.
30
ANALYSIS
“
As it stands, the only certainty is that nobody can model what happens next – and certainly not the Treasury Expect far tougher scrutiny of affiliate deals, platform arrangements, data vendors and B2B suppliers. Do not be surprised if UK PLCs move toward tighter demands on B2B suppliers launching exclusive “trusted vendor schemes” to stop games supplies to the black market (see Tipico in Germany). Perhaps the budget’s biggest reveal is the lack of leadership across the sector. The industry’s lobbyists and its leadership more generally has largely failed to present a unified, credible voice during the Gambling Act review and allowed the narrative vacuum to be filled by antigambling campaigners and politicians as the Treasury imposed its answer. As Waugh concluded: “We need to ask why these things keep happening to our industry. You have to accept that whatever we are doing, it is not working. There ought to be a process of introspection. It needs a long hard look in the mirror. It requires some hard work and it requires honesty. Things need to change.”
Chancellor Rachel Reeves
Strong voices are needed so that UK gambling can finally articulate its value, modernise its structure, and navigate the UK gambling market back to calmer shores by the 2030s.
31
ANALYSIS
SBC LEADERS ISSUE 38
WHAT THEY SAID ENTAIN Entain expects an EBITDA impact of approximately £100m in 2026 and approximately £150m from 2027. Entain anticipates benefiting from capturing market share as others are now forced to exit the UK market. Stella David, CEO of Entain, commented: “We are deeply disappointed by today’s decision to punitively increase UK gambling taxes, putting at risk an industry which already contributes £7bn annually to the UK economy and supports over 100,000 jobs across the country… The Government must now urgently tackle the black market and the consequences of today’s decision. Entain remains well positioned to deliver sustainable growth, underpinned by the Group’s diverse geographic footprint and strong portfolio of leading positions in attractive markets.”
EVOKE These changes in tax rates would increase duty costs by approximately £125-135m. Evoke CEO Per Widerström said: “We will begin immediately on executing our mitigation plans, which involve a significant reduction in investment into the UK, and, very regrettably, the likely need for thousands of jobs to be cut up and down the country.” Later on LinkedIn he added: “We will not be defined by this challenge. Our size in the UK market makes us resilient and our international business provides diversification. So, we must continue to deliver for our customers - while also re-evaluating our strategy to reflect this new reality. The executive team and I are absolutely united. We are mobilised, focused, and determined to navigate this turbulence and secure a great future for Evoke. This is our moment to demonstrate the strength, unity, and resilience of the great people of Evoke.”
32
ANALYSIS
FLUTTER The adjusted EBITDA impact of these changes for Flutter, before mitigation, is expected to be approximately $320m in 2026 and $540m in 2027. Kevin Harrington, UKI CEO, commented: “At 40%, the UK’s remote gaming duty is now above countries such as the Netherlands, where a recent tax increase saw a rise in illegal gambling and a fall in government receipts. Despite this impact, I am confident that through both our scale and leading position in the UK, as well as the proactive cost initiatives that we are taking, we are well placed to navigate through today’s changes.”
BALLY’S The UK online EBITDA contributes £275m on revenue of £660m. The tax increase has a direct impact of £95m on EBITDA. CEO Robeson Reeves said: “We will look at generosity reductions, marketing reductions such as advertising and cost cutting, which amounts to £35m. In addition, there will be £15m from the transaction synergies… Our growth in sports, expansion into new markets and the full realisation of synergies will alleviate tax rate pressures in the UK… We achieved in Q3 a 43% EBITDA margin, whilst most others are below 25%. Hence, there will be other operators that cannot adapt to this change due to lower margins and lack of scale. This will result in fewer players, and I welcome a less competitive environment. “The point of the combined Bally’s International Interactive and Intralot was to create a platform for both organic opportunities and accretive acquisitions. We believe this improves our prospects. I do understand that the UK government
33
has a need for revenue. My message is I will continue to embrace public-private partnership and regulations, but that the UKGC will have to be extra vigilant to police offshore gambling given that the incentive to do so has increased. The UKGC has been progressive with consideration to grow into areas such as crypto and prediction markets to lead and expand the market rather than zero-sum reallocation. I love our business, and we have been through such experiences over the years and will continue to adapt.”
SBC LEADERS ISSUE 38
PLAYER PROTECTION POWERED BY
ON THE FOLLOWING PAGES 35 36
Column: Steve Hoare on black markets progress Interview: Shawn Fluharty of Better Gambling Forum 34
PLAYER PROTECTION
WHAT TO DO WITH £26M? While the policies of lawmakers and regulators seem to be fuelling the black market, there are slivers of light to be found in the fight against this menace, writes SBC Leaders and Player Protection Hub Editor Steve Hoare
industry but both are building portfolios of licences that build their credibility beyond the stereotype their critics would like to paint them as.
P
olitical debate around the gambling industry has become increasingly divisive over the past few years but over the last two it has also grown increasingly boring. While antigambling campaigners are gonna campaign, the industry seems stuck in a loop, merely responding with ‘what about the black market?’ to every suggestion. To some extent, that has worked. The Gambling Commission, for example, with its public announcement of an investigation into the practices of the world’s biggest gambling supplier, Evolution Gaming, made a very big statement that it would no longer tolerate those who bat for both sides. To varying degrees, the three biggest operators in the world – Bet365, Stake and 1xBet – have indicated that they are increasingly focused on regulated markets. Bet365 will not like being lumped in with the other two but its public announcement of a withdrawal from China was a hugely symbolic move. Stake and 1xBet are seen as crypto cowboys by large swathes of the
Where the black market rhetoric has not worked is in tempering policy. In its recent budget announcement, the UK government accepted that its tax increase would cause a half-abillion-pound leakage to the black market. Throwing the Gambling Commission a consolation £26m to deal with the problem is, say critics, pointless. Just look at the disparity in numbers! On the morning before the budget was announced, the Commission and France’s Autorité Nationale des Jeux (ANJ) announced a cooperation agreement with the regulators of Austria, Germany, Italy, Portugal, and Spain to share information to tackle the illegal sector. All well and good but unless all of the countries are willing to throw £26m at it and convince Interpol to form a black market taskforce, it’s unlikely to have much of an impact.
make the regulated market more attractive. If that’s too much to ask, he would like to see more action from regulators. He likes the tactics of the Spanish and Australian regulators, who fine, name and shame black market operators. While the fines are unlikely to be paid, the announcements start to educate the public about which brands are operating illegally. On a recent webinar during SBC’s Player Protection Digital Day, the Director of the Danish Gambling Authority Anders Dorph spoke about educating influencers about the illegal sector – many of them didn’t even know they were promoting black market operators. If we’re looking for positives, we can see plenty of evidence the education process has begun – politicians and regulators are now aware of the problem – but this is a long-term project. We work in an industry where almost every development is described as a “disaster” or a “crisis”. A calming of the rhetoric might help everyone to be a little patient.
Deal Me Out Founder Jordan Lea has been compiling a report on black market activity in the UK and is close to despair. “You can’t just block them and stop the payment service providers. They’re three years ahead of you,” Lea tells us. Lea believes enforcement is useless and would ideally like to see lawmakers and regulators
35
Scan here for more from Player Protection Hub
PLAYER PROTECTION
SBC LEADERS ISSUE 38
MAN ON A MISSION
36
PLAYER PROTECTION
Better Gambling Forum Chair SHAWN FLUHARTY is trying to reshape how the world thinks about regulated gambling Words by STEVE HOARE
A
s a State Legislator in West Virginia, Head of Government Affairs at Play’n GO and President of the National Council of Legislators from Gaming States (NCLGS), Shawn Fluharty has a lot on his plate. However, he took on one more role earlier this year, which could be his most impactful contribution yet. As chair of the Better Gambling Forum (BGF), Fluharty is hoping to provide a blueprint and best practice framework for regulators and industry that provides the infrastructure for a truly sustainable and safe international gambling industry. Fluharty has long moved between politics, policy and industry. Now, with the BGF, he’s working to bring those worlds together in a way that has rarely been attempted. “The regulated gambling industry deserves a seat at the table globally with every other industry,” Fluharty tells SBC Leaders. “For the first time, we’re sitting down at places like the United Nations and the G7, having real conversations with policymakers and the scientific community about what sustainable gambling looks like.” Fluharty’s path to the BGF is rooted in his belief that responsible gambling can only thrive when it’s built on cooperation, transparency, and credible evidence. As chair of the forum’s steering committee, he leads a group of 12–15 experts from across the gambling, responsible gaming, and research sectors — including figures such as
Jennifer Shatley from the Responsible Online Gaming Association (ROGA). “What’s unique about the Better Gambling Forum,” he explains, “is that it isn’t just another industry lobby. We’re not here to rubber-stamp our own agenda. We’re here to bring in people who haven’t been at the table before – scientists, educators, and addiction experts – and make sure the conversation is balanced and credible.” That distinction matters. Fluharty stresses that credibility is the foundation of the BGF’s mission. “We could have just made this another industry-led group,” he says. “But that’s not what we’re doing. The scientific oversight committee, which operates independently of the steering committee, will hold us accountable and ensure that what we produce is evidence-based, not self-serving.” BRINGING SCIENCE AND INDUSTRY TOGETHER The structure of the BGF is intentionally layered. The steering committee, chaired by Fluharty, guides policy direction and dialogue. Alongside it sits a scientific oversight committee, composed of researchers and academics who will review and validate the group’s work. Additional subcommittees – representing educators, lawmakers, and policymakers – are being formed to provide input from multiple perspectives.
We need scientists, educators, and policy experts who aren’t influenced by profit motives, who can take the data, study it objectively, and feed back findings that improve the entire ecosystem
37
“
PLAYER PROTECTION
SBC LEADERS ISSUE 38
“Think of it almost like building our own small government,” Fluharty says. “You’ve got your main steering committee – that’s your executive branch – and then you’ve got subcommittees that specialise in different areas and report back. It’s transparent, it’s structured, and it’s designed to last.”
criticism – that the industry can’t regulate itself,” he admits. “That’s why our oversight committee is independent. We need scientists, educators, and policy experts who aren’t influenced by profit motives, who can take the data, study it objectively, and feed back findings that improve the entire ecosystem.”
This approach, he argues, is essential for bridging the gap between the rapid pace of technological innovation and the slow-moving machinery of government. “Technology moves at the speed of light,” he notes. “Government moves at the speed of, well, government. So, we need mechanisms that help those two worlds communicate and evolve together.”
That collaboration, he says, is already taking shape. “When I spoke at the G7, I asked the room, which included addiction researchers and policymakers, how many were familiar with Alberta’s iGaming legislation. Maybe three hands went up. That changed that day. We’re bringing these groups together in ways that just haven’t happened before.”
A SEAT AT THE GLOBAL TABLE
A GLOBAL FRAMEWORK FOR SAFER GAMBLING
That communication gap is precisely what the BGF is trying to close. Earlier this year, the forum became the first regulated gambling group to present at the United Nations and the G7 summit in Alberta – a milestone that Fluharty sees as both symbolic and practical.
Over the next 12 to 14 months, the BGF will work toward producing a global framework for responsible gambling – a set of principles and policies that can guide governments, regulators, and operators. Fluharty describes it as a hybrid between policy blueprint and best-practice charter.
“Can you name any other time when the regulated gambling industry was represented at that scale?” he asks. “It’s unprecedented. And it’s opening doors for us to have meaningful dialogue about how we build a sustainable global framework that protects players, shrinks the illegal market, and recognizes the data and expertise the regulated sector brings.”
“Initially, the focus is on policymakers and regulators,” he explains. “But ultimately, we want something that everyone – operators, lawmakers, and researchers – can buy into. It’s about creating a sustainable, evidence-based model that works worldwide.”
The concept of data as “modern currency” comes up often in Fluharty’s thinking. He argues that the regulated gambling industry – with its vast troves of player information, analytics, and behavioural data – has the potential to contribute to global research and policy far beyond its own borders.
Fluharty is quick to add that this is a global mission, not a US-centric one. But he acknowledges the relevance to his home market, where divisions between states and operators often dominate headlines. “There’s a lot of friction in the US right now,” he says. “Something like this can help bridge those gaps – give lawmakers reassurance, close the education gap, and show that there’s a responsible, regulated path forward.”
“Can you think of another industry that has as much real-time data on consumer behaviour?” he says. “If used responsibly, that information can help researchers, regulators, and policymakers make smarter decisions about player protection, addiction prevention, and sustainable growth. That’s what the BGF is about – aligning those capabilities.”
THE EDUCATION GAP Fluharty believes that one of the biggest barriers to progress – both in the US and globally – is misunderstanding. “Lawmakers often don’t realise how much unregulated gambling already happens,” he says. “They think, ‘It’s illegal in my state, so it doesn’t exist.’ But it does. I can open my phone and play right now, and none of that revenue goes back to the state, and none of those players are protected.”
BALANCING INDUSTRY AND OVERSIGHT Fluharty is candid about the need to balance interests. “We know the
38
PLAYER PROTECTION
“
The Better Gambling Forum isn’t just another industry lobby. We’re not here to rubber-stamp our own agenda
He laughs as he recalls the generational divide in state legislatures: “These are the same lawmakers who can’t silence their phones in a committee room, and we’re asking them to understand a casino in their pocket. Of course, they need reassurance. That’s what the Better Gambling Forum can provide.”
worlds,” he says. “I understand how lawmakers think and how the industry works. That helps us bring credible people together and build something that’s going to last.” Ultimately, the Better Gambling Forum’s mission goes beyond setting standards. It’s about reshaping perceptions. “For too long, regulated gambling has been treated like a shadow industry,” Fluharty argues. “But we’re one of the most heavily regulated sectors in the world. It’s time we were part of the global conversation – not as a problem to manage, but as a partner in building sustainable entertainment.”
BUILDING CREDIBILITY THROUGH COLLABORATION For Fluharty, credibility is the BGF’s most valuable asset. “We’ve brought together people who genuinely care – respected figures on both the responsible gambling and industry sides,” he says. “Nobody’s here for a photo op. They’re here because they believe in building a sustainable, regulated model that can stand up to scrutiny.”
He pauses, then adds with conviction: “This is going to have global ramifications. We’re bringing science, policy, and industry together in a way that hasn’t been done before. We’re not just talking about responsible gambling – we’re building the framework that will define it.”
He sees his own role as a bridge between policy and innovation. “I’m sandwiched between those two
39
SBC LEADERS ISSUE 38
PAYMENTS POWERED BY
ON THE FOLLOWING PAGES 41 42
Column: Rachael Kennedy highlights good friction Feature: The payments regulatory gap 40
PAYMENTS
WHEN FRICTION IS A FEATURE, NOT A BUG Payments that pause at the right moments can protect high-risk sectors without breaking the customer journey. The question is where that pause earns its keep, writes Payment Expert Editor Rachael Kennedy
under ‘strong customer authentication’ (SCA) show lower fraud rates than those that are not. Earlier ECB analysis linked the rollout of SCA to a marked decline in card-not-present fraud. Targeted checks changed outcomes.
P
ayments in high-risk sectors have chased speed for years. One-tap top-ups and instant withdrawals are now the norm. At a recent payment fraud event in London however, people asked whether a brief pause at the right moment might be worth more than a marginally faster checkout. The case for that pause is getting stronger. The UK lost £1.17bn to fraud in 2023. Cases rose again in 2024 even as losses held flat, with criminals leaning into highvolume, low-value attacks that exploit predictable flows. That is the reality behind glossy conversion charts. A zero-pause mindset often moves cost from the payment screen to chargebacks, investigations and reputational damage. European data points in the same direction. The European Central Bank (ECB) and European Banking Authority’s joint work on Strong Customer Authentication found that transactions authenticated
Authentication can work without wrecking a session. Several datasets put UK EMV 3-D Secure performance near the top of global tables. Ravelin reports around 93% overall success and 94% challenge success in the UK, with a lower share of “frictionless” flows that reflects issuer caution rather than blanket failure. That does not mean bliss for every merchant, but it does show that well-tuned challenges can clear at high rates when risk merits the extra step. iGaming and betting feel these trade-offs most at a few pinch points. The on-ramp when a new device appears or a first topup lands. The off-ramp when balances are cashed out. The moments where bonuses are converted to withdrawable funds. These are also the moments that attract mules and synthetic identities. The UK’s Financial Conduct Authority and others have flagged a sharp rise in mule activity, with more than 225,000 people identified in 2024. That pressure shows up first at payout. This is not an argument for clunky hurdles. Bad friction exists: repeated KYC loops
41
and unexplained holdups drive players away and add cost. The question is whether a short, well-signposted step at defined risk moments can prevent a larger loss later. The only honest way to judge that is to look at net revenue after fraud and operations cost rather than raw approval rate. In a market where fraud is persistent and adaptive, the metric that matters is what stays in the till once disputes and writeoffs clear. A small, targeted pause will not solve everything but it does change incentives, and it tells would-be abusers that withdrawals and high-risk topups are guarded. It tells genuine customers that balances and identities are protected. For sectors that live with licence obligations and public scrutiny, that can be the most valuable kind of speed.
Scan here for more from Payment Expert
PAYMENTS
SBC LEADERS ISSUE 38
WHO’S REALLY WATCHING GAMBLING PAYMENTS?
42
PAYMENTS
SBC Leaders speaks to the UK’s gambling and financial regulators, who insist their partnership is strong, but questions remain over who truly oversees the money moving between players and operators Words by RACHAEL KENNEDY
W
hen a gambler deposits funds with an online betting operator, the transaction crosses one of the most heavily regulated thresholds in the economy, touching both financial and gambling law. Yet the question of who oversees that moment, and what happens if it goes wrong, remains surprisingly open.
should be considered illegal activity” under the Proceeds of Crime Act. This framing places most responsibility on the firms themselves. Payment institutions are expected to interpret the national risk picture and apply it to their own business models. It means the FCA’s role is largely supervisory and reactive, rather than sector-specific.
In the UK, gambling operators are licensed by the Gambling Commission (UKGC), while the payment providers that move customer funds are authorised by the Financial Conduct Authority (FCA). Between them lies a shared responsibility to stop illegal activity, prevent harm, and protect the integrity of financial flows worth billions of pounds each year.
The FCA points to its 2022 Memorandum of Understanding (MoU) with the Gambling Commission as evidence of active cooperation. The document establishes a framework for “consultation, coordination and information sharing” and sets out how the two regulators will escalate issues which cross their remits. Under the MoU, the FCA and UKGC are required to notify each other of significant developments, designate points of contact, and respond to inquiries “within 10 working days” where possible. If agreement cannot be reached, the issue is escalated through several layers - first to Executive Directors, then to both Chief Executives, and ultimately to HM Treasury and the Department for Culture, Media and Sport for a cross-government view.
But as gambling payments move from cards to open banking and other instant transfer rails, this shared responsibility is looking increasingly blurred. TWO REGULATORS AND ONE MISSING LINK The FCA’s own description of its role in gambling payments underscores the complexity. The FCA “does not provide an independent view on high-risk sectors”, says Matthew Long, Director, Payments and Digital Assets at the FCA, instead relying on His Majesty’s Treasury’s National Risk Assessment (NRA) of Money Laundering and Terrorist Financing to identify and rank risks. The most recent assessment lists casinos as a high-risk category, but not gambling payments more broadly.
A UKGC spokesperson tells SBC Leaders the Commission’s MoU with the FCA “ensures we have a close working relationship” and remains “the best way to achieve a fruitful working relationship.” What the MoU does not do is create shared enforcement powers or a joint supervisory body. It explicitly states that it is “a statement of intent” and “does not give rise to legally binding obligations,” the spokesperson says. Nor do the two regulators exchange enough personal data to require a dedicated data-sharing agreement, though the MoU says that position will be “kept under review”.
Authorised or registered payment firms, Long adds, must conduct their own risk assessments “which must take into account the NRA” and design controls accordingly. Where a client is conducting unlicensed gambling, Long says, “this
43
PAYMENTS
SBC LEADERS ISSUE 38 Under the MoU, the regulators also commit to quarterly meetings and to respond to each other’s requests in a timely way, with formal escalation to senior leadership if needed. This leaves coordination dependent on goodwill and communication rather than a standing structure. In practice, it means that where questions arise about the conduct of a payment provider serving a gambling operator, the FCA and UKGC must decide case-by-case which agency takes the lead.
Long says the FCA supports the expansion of open banking “into a wider series of use cases” and that “appropriate protections for consumers” remain a priority. But he reiterates that firms “authorised or regulated to provide open banking-related activities… are expected to consider the NRA when conducting risk assessments”.
FINTECHS IN THE FRAME
This approach gives open banking providers the same discretion as other payment institutions: to determine their own level of risk and apply controls accordingly.
This lack of clarity is becoming more significant as payment technology evolves. Open banking and realtime account-to-account transfers are now widely used by betting and iGaming operators to reduce friction and speed withdrawals. Each new connection between a gambling site and a consumer’s bank account raises fresh questions about oversight.
The Commission draws a perimeter line here, with the spokesperson saying “our role is to regulate the gambling operator rather than the payments systems”. This places day-to-day oversight of open banking providers and other PSPs with the FCA, while the UKGC focuses on how licensed operators use those rails.
44
PAYMENTS
For critics, this means there is still no single authority ensuring gambling payments are scrutinised with the same rigour as gambling licences.
both consumer protection and financial crime risk. Operators are expected to monitor affordability, PSPs are expected to detect suspicious flows, and banks are encouraged to offer voluntary gambling blocks. Yet there is no unified rulebook defining how these duties fit together.
ENFORCEMENT WITHOUT A MAP Long says that authorised payment institutions must have “effective controls, policies and procedures to protect against financial crime”, but the specifics of how those are applied to gambling are not public. The Commission, meanwhile, ensures licensed operators work with approved payment partners and do not accept credit card deposits or facilitate unlicensed gambling.
Industry observers say this has led to “soft enforcement” – a reliance on dialogue, thematic reviews and joint statements rather than coordinated supervision. In practice, companies often face overlapping but inconsistent expectations from both regulators, with neither side empowered to give definitive guidance.
Both regulators have powers to act where illegal gambling or money laundering is identified. Yet because their remits are defined by separate statutes (the Gambling Act 2005 and the Financial Services and Markets Act 2000) neither has an end-to-end view of the payment chain.
Asked whether the current model is sufficient to protect consumers, the UKGC spokesperson says the Commission “has a close working relationship with the FCA that ensures appropriate collaboration in delivering our respective regulatory roles.” The FCA’s responses from Long suggest it is comfortable operating within that structure, noting that “the FCA operates within the legislative and policy framework set by His Majesty’s Treasury, which determines the regulatory perimeter”. Any change to that perimeter, it said, “falls within HMT’s remit”.
The MoU allows them to share information about investigations, licence breaches or suspected unlicensed activity, but cooperation is voluntary and subject to confidentiality restrictions. Even when information is shared, the receiving regulator must still act within its own legal perimeter. SYSTEMIC FRICTION
This statement leaves the door open for future reform but confirms that the FCA sees its role as set by the government, not by inter-agency negotiation.
This gap matters because payment behaviour is increasingly at the heart of
Companies often face overlapping but inconsistent expectations from both regulators
45
“
PAYMENTS
SBC LEADERS ISSUE 38
“
operators for anti-money laundering (AML) failings and partnered with major banks to block payments to unlicensed websites. On the prospect of joint powers or enhanced data-sharing, the Commission says the MoU remains its preferred tool, rather than seeking new statutory arrangements.
The UKGC is charged with preventing gambling from becoming a source of crime, yet it relies on the financial system to detect and block that activity
However, without direct authority over payment firms, its influence remains limited to the gambling licence itself. If a fintech provider or e-money institution facilitates illegal gambling, the Commission must rely on the FCA to intervene. Both regulators insist that their relationship is constructive and that the MoU enables efficient communication. Quarterly meetings are scheduled to review the arrangement and address any emerging issues.
A QUESTION OF ACCOUNTABILITY
The MoU framework commits both sides to regular reviews and escalation routes, while the Commission’s illegal-market work highlights that effective payment disruption depends on continued cooperation with PSPs and banks.
For the Gambling Commission, the challenge is equally complex. It is charged with preventing gambling from becoming a source of crime and disorder and ensuring games are conducted fairly, yet it relies on the financial system to detect and block much of that activity. In recent years, the Commission has stepped up enforcement against
But as new technologies bring gambling and financial services ever closer, the UK’s dualregulator system may come under increasing pressure to adapt. The question remains unresolved: when money moves between a player and a betting platform, who’s really watching?
46
SBC LEADERS ISSUE 38
CASINO POWERED BY
ON THE FOLLOWING PAGES 50 54 58 62
Interview: BetMGM Chief Revenue Officer Matt Prevost Interview: Fincore CEO Mateja Popovic Thought Leadership: Evenbet CEO Dmitry Starostenkov Thought Leadership: Vyking CEO Franz Gerhart 48
CASINO
THE BIG SQUEEZE The UK gambling sector is entering a new era and with operators large and small facing an uncertain future. Will there be any winners, asks iGaming Expert Editor Joe Streeter
W
hile the industry’s warnings about the black market fell on deaf ears – the Chancellor of the Exchequer did provide a glimmer of consideration for the land-based sector, when she announced her tax rises in November. Salvaging a sustainable future for the land-based sector was a clear narrative in the run up to the budget and even sparked a somewhat bizarre exchange between the Betting & Gaming Council (BGC) and politicians during a disastrous Select Committee hearing that preceded the budget. Labour MP Dame Siobhain McDonagh claimed betting shops have descended from places where people would socialise to hubs for people with drug and alcohol problems that have caused concern in her local constituency.
BGC CEO Grainne Hurst did her best to defend High Street bookies, which prompted a frosty exchange with the MP before Hurst agreed to visit betting shops in McDonagh’s constituency in South London.
channel operators Entain, Evoke and Flutter account for over 80% of the UK’s bookies and to survive this increasingly hostile environment, they are going to make cuts and retail will at least feel some of the pain.
The attacks on the retail sector didn’t stop there, as another Labour MP Meg Hillier accused the gambling industry of “undermining its own shops by making them less welcome”. Hurst was staunch in her defence of the high street though – emphasising that many who work in bookmakers could find easier jobs, but stay in the betting shops as they are passionate about their jobs.
It is not only the big operators that are going to feel the challenges of the tax hikes. Online slots are the most profitable element of UK gambling. An analyst was telling me this week, most operators work with a 20% EBITDA margin. So taking that extra 20% in tax, basically removes the operator’s profit.
The fear ahead of the budget being announced was of tax rises that would have decimated the retail sector – to such an extent that Betfred threatened to close its entire 1,300-strong estate. On the surface, the retail sector got off lightly with bingo tax eradicated and machine gaming duty and retail spared. Whether this will preserve the future of the sector remains to be seen. Retail betting doesn’t operate in isolation. With remote gaming duty hiked from 21% to 40% and remote betting duty boosted to 25%, the government has taken a swing at the fastest-growing portion of the sector. Multi-
49
As some detailed in their postbudget remarks (see p.23) big listed operators could end up benefiting from the decimation of the middle tier of online casino specialists, which could be faced with a stark choice of joining the black market or selling out to the PLCs.
Scan here for more from SlotBeats
CASINO
SBC LEADERS ISSUE 38
GAME CHANGERS
Bet MGM Chief Revenue Officer Matt Prevost
50
CASINO
BetMGM has redefined the role of its suppliers as it seeks to exploit every available opportunity to win back iGaming market share from DraftKings and FanDuel Words by JESSICA WELMAN
W
hen it comes to bidding on the game show The Price is Right, it may sound unconventional, but there are times where, if your opponents seem to all be wagering too high, it strategically makes the most sense for you to go low. Way low. And that is how contestants can win big prizes by bucking convention and guessing that something that is clearly expensive costs one dollar. In slots, conventional wisdom has been that operators can let the slots studios spend the big bucks for the top line intellectual property, develop the games and then the casinos can come in at the end and agree to host them in their casinos or within their online gaming sites. However, BetMGM’s deal with Fremantle is turning that model on its head and, so far, the results have exceeded the online casino company’s expectations. The two groups announced the multi-year partnership in January which grants BetMGM exclusive online gaming rights to the game shows The Price is Right and Family Feud. The terms of the unusual deal were not disclosed but it certainly cost BetMGM more than one dollar. That pretty penny buys more than exclusivity. It also gives BetMGM flexibility to match suppliers with elements of the game shows that best suit their strengths. Even though the suppliers don’t own the IP, BetMGM Chief Revenue Officer Matt Prevost tells SBC Leaders that partners are still eager to participate because it is an opportunity to lean into their strengths.
“
The title is off to a tremendous start, ranking as a top five launch for us this year
51
CASINO
SBC LEADERS ISSUE 38 37
“
a-Bunch punchboard game. There is also the more traditional title from Design Works Gaming, Gold Blitz Ultimate.
I’ve never seen so many people so enthusiastic in one set. It’s incredible. Just pure joy attached with that audience
The synergy goes the other way as well, as the popular television program now includes a new game, The Lion’s Share, sponsored by BetMGM. Prevost notes that being a part of the environment of the live studio is something special and part of what makes the deal so magic. “You still have Drew Carey, doing 200 episodes a year. And, having been to one of those shows, I’ve never seen so many people so enthusiastic in one set. It’s incredible. Just pure joy attached with that audience.”
“We pick a particular variant and we say ‘you’re best at skill games.’ Great. Go build a skill game associated with this IP.”
THE CROWN JEWELS The Price is Right is the crowning jewel of the slot side of the deal for BetMGM, but it is Family Feud that is the star of the show when it comes to live dealer.
These one-off projects have produced a range of results even though the deal only encompasses two shows. Within The Price is Right in particular there is a wealth of options to mine given the range of games that comprise the show.
In August 2025 BetMGM and Playtech unveiled a studio situated at the heart of Sin City, embedded in the gaming floor of the MGM Grand Casino in Las Vegas. Encased in glass, tourists and passers by can stop and watch as dealers sling cards at the blackjack table, spin the roulette wheel and even play the role of Steve Harvey, hosting a version of Family Feud.
“I think, in particular, what lends itself well, which maybe others hadn’t fully developed, was all the mini games within Price is Right. You have this well known brand that is actually a brand, but it’s an amalgamation of many brands,” Prevost notes.
The studio builds on a test of the concept piloted at MGM Grand and Bellagio starting in 2024 where the games were streamed to several jurisdictions. The new studio brings a new level of spectacle to the concept, where friends in Vegas can pop in and wave back to friends, but only if their friends live in certain jurisdictions.
“You have Cliffhanger, Plinko, all these games we grew up watching, and that’s what lends itself naturally to digital. It’s harder to build all these individual mini titles in a land-based environment than it is in digital. We have thousands and thousands of titles and it is easy to deploy.” The first game release, The Price is Right: Big Wheel Bonus leans into the iconic wheel where players try to get to the Showcase Showdown by getting as close to a dollar with their spins as possible. Given slots are comprised of a bunch of spinning wheels, it is a natural place to start, but it is only the beginning.
The Family Feud game also provides an easily recognizable title for BetMGM in the quickly growing game show sub-vertical of live dealer games. In 2024 Evolution’s most popular title was the game show-style Crazy Time and other studios have been deploying similar titles, which combine elements of a traditional table game like roulette with the fun of slot bonus games and the mini games that Prevost noted make the Fremantle titles so unique. For now, the US is not a market serviced by
The Gamecode title was followed by NetEnt’s The Price is Right - Fortune Pick, which incorporated the classics like Cliffhanger and Plinko alongside the Punch-
52
CASINO
the live dealer studio, but Ontario is. Prevost also expects that to expand as online gaming expands across Canada. Current regulations in most states stipulate live dealer studios need to be in the state where they are streaming, but BetMGM still has options for live dealer, such as its dual-play blackjack game from Evolution hosted at Borgata Hotel and Casino in New Jersey. “There are individuals who will tell their friends, ‘Hey, I’m going to be playing roulette at 10 o’clock at night, join me, we’re all playing roulette together.’ And so you’ll see the hands of the guy with, you know, a tattoo on his hand or something, where you’ll see his hands go place the chips, and they’ll know that he’s got friends playing the line.”
crossovers that BetMGM CEO Adam Greenblatt has invoked in earnings calls again and again as the core strength the company can offer over competitors and which helped propel the operator to a 21% online casino market share in Q3 of 2025, according to its latest earnings report.
online slots title Rakin’ Bacon! Jackpots Wheels Bonus and brokered a period where MGM Detroit and Borgata exclusively had the brick and mortar title in their respective markets. The results merited inclusion in Greenblatt’s earnings update.
Prevost echoed those sentiments when talking about the Playtech studio and in how BetMGM extends its unconventional approach beyond a single partnership with Fremantle.
“The title is off to a tremendous start, ranking as a top five launch for us this year,” he noted.
FINDING MARKET SHARE
Online casinos generally take the most popular brick and mortar titles and adapt versions for them online long after they hit the floor. Now, BetMGM is experimenting with close to simultaneous releases across MGM properties and online casinos as well as exclusivity windows to help promote crossover from the digital to the retail space.
Those kinds of omnichannel opportunities are the types of
BetMGM worked with AGS to develop and launch the
53
“There are some people who will be digital and always digital and there will be some people who will always be land-based,” Prevost acknowledges. “And then there’s a group in the middle, and we think we can own the group in the middle.” Based on results, it is working so far, an, in order to keep doing that, BetMGM isn’t pulling its punches. The company is bucking every convention and going against the grain to create an experience they believe none of its competitors can replicate.
CASINO
SBC LEADERS ISSUE 38
MAKING A CLEAN BREAK Fincore CEO MATEJA POPOVIC implores the industry to break free from legacy systems and embrace a cleaner future
W
hat was the moment or realization that made Fincore decide the industry needed this reset?
Connections that make sense. And when you change something, you’re not holding your breath hoping it doesn’t break something three layers away.
Honestly, it wasn’t one big dramatic moment. It was years of seeing the same thing happen over and over again. You’d scratch beneath the surface of a platform and find this archaeological dig. Layers of old decisions, quick fixes, fear-driven choices and everyone just accepted it as normal.
Most operators are running accumulated decisions from years of fast growth, systems built for yesterday’s problem, not the next decade. Over time, those shortcuts become an invisible drag on everything.
I’d see brilliant engineers spending their best energy fixing yesterday instead of building tomorrow. I’d see operators living with systems that felt like they could crack at any moment because the alternative felt too big or too risky. Break Clean came from that realisation. The industry doesn’t need another promise or another layer on top of the mess. It needs clarity. A stable core that can actually support growth.
Clean architecture is the opposite. It’s modular and intentional, giving you control instead of taking it away. You integrate faster, scale faster and innovate without fear. Clean systems create momentum. Many companies claim to innovate, but few are willing to “break clean.” What does that look like technically, culturally, and financially?
In engineering terms, what defines a “clean” system architecture – and how is that different from what most operators are running today?
“Breaking clean isn’t one-size-fits-all. Sometimes you need a full rebuild because the foundations are too tangled or brittle. But more often, it’s surgical. Identifying the one unstable element poisoning everything else. Fix that properly and the system breathes again.
A clean architecture is one you can trust. Predictable behaviour. Clear modules.
Technically, it means going to the root cause, not the symptoms.
54
CASINO
“
As cleaner, more modular tech stacks start embracing real-time data and AI, those still tied to patch culture simply won’t be able to compete
Culturally, it’s about truth and ownership. You need teams who say what’s broken, leadership that rewards clarity, and engineers who take responsibility. If it isn’t clean, it doesn’t ship. Financially, it’s almost always the lowercost path. Patch culture feels cheaper but creates operational debt, regulatory risk, lost momentum. Clean systems pay you back every day.” What could be the cost for the industry of not moving from legacy stacks and patch culture? The cost is bigger than downtime. The real cost is momentum. When systems creak, every decision becomes slower and every new idea feels like a gamble. You see it in teams too. When technology fights you, creativity drops. People focus on what’s safe instead of what’s possible. Then you have outages, compliance incidents, missed milestones. Trust erodes. Boards lose appetite for innovation because the foundations feel unstable. And as cleaner, modular stacks adopt realtime data and AI, those tied to patch culture simply won’t keep up. AI needs clarity and structure. Legacy platforms can’t offer that. Eventually you realise your biggest competitor wasn’t another operator, it was your own architecture.
55
CASINO
SBC LEADERS ISSUE 38
“
When your systems creak under their own weight, every decision becomes slower, every release becomes riskier, and every new idea feels like a gamble
What role does transparency play in how Fincore develops and maintains technology for clients? Transparency is everything. When clients understand how their systems work, really understand, the fear disappears. Integrations stop being scary. Upgrades stop being stressful. For us, transparency isn’t a marketing line. It’s how we work. We show the architecture, the decisions, what’s clean and what needs rebuilding. No surprises. No magic layers. Clean engineering and transparency belong together. One gives clarity. The other gives confidence. You have a slogan reading “Engineered Clean. Built with Fire.” What would you say is the fire? For me, the fire is passion and creativity. Clean engineering isn’t clinical, it takes imagination to strip away noise, solve the hard things properly and build systems that feel effortless. That spark, that pride, that’s the fire. Engineered Clean is the discipline. Built with Fire is the personality. It’s the team refusing ‘good enough’ and going to the root cause, not the patch. One gives stability. The other gives the edge. Looking ahead, how will cleaner, modular architectures unlock innovation? Innovation needs clarity. Predictable systems, clean data, stable foundations.
AI is a perfect example. It needs real-time data, consistent logic and components that can be trusted. Without that, it produces noise, not value. Player protection and compliance are similar. You can’t automate effectively on top of unpredictable systems. If your architecture is clean, you can take advantage of the future that’s coming. If not, you can watch it slip away. What can we expect from Fincore in the near future? Over the last year we’ve shown what clean engineering looks like. Our work with Epic Software, delivering a new e-pull-tab system in a short timeframe, proved transformation doesn’t have to be painful. Our partnership with Everi has supported some of the industry’s most ambitious visions. And our work with The Pools reinforced something we care about: tech replacement doesn’t have to be disruptive. You can build modern capabilities alongside the existing operation and switch over when ready. That momentum is now carrying into some of the biggest initiatives we’ve taken on. So what can people expect? More systems built with clean engineering and real fire, ready for the next wave of AI. The industry doesn’t need louder promises. It needs dependable foundations. And 2026 is the year we help more operators and b2b suppliers make that shift.
56
News and insight every single day.
YOUR DAILY HABIT. Listen every day on Spotify, Apple Podcasts, Youtube, or wherever you get your podcasts.
iGa
iGa
min
min
3:2
3
gD
gD
aily
aily
Ep 4
85:
The 15.1
7
CASINO
SBC LEADERS ISSUE 38
THE HIDDEN METAVERSE
The iGaming metaverse is already here and most of us are looking in the wrong direction EvenBet Gaming CEO DMITRY STAROSTENKOV says the iGaming industry needs to evolve from its narrow view of the metaverse as VR and argues that the real shift is already here with operators fighting for players’ time, rather than market share
58
CASINO
T
he Metaverse still makes many people in our industry think of something that belongs on a long-term innovation roadmap, separated from today’s operational realities. From my perspective, that view is not only outdated, but strategically dangerous. It is not a distant technology project. It is already here, shaping how our players live, what they expect, and how we are competing for their attention. THE NEW BATTLEFIELD Earlier this year, we published EvenBet Gaming’s annual report on the main challenges facing operators and suppliers. Regulation is still at the top of the list. What has changed dramatically is the nature of competition. We are no longer operating in a closed arena where casinos and sportsbooks compete with their peers. When a user unlocks their phone, they are not choosing between brand A and B. They are choosing between playing at all, watching a new series, or doing something else, which draws from the same limited pool of time and emotional energy. We like to talk about market share, but time share is now more relevant. FROM STORES AND PRODUCTS TO MEGAMALLS AND ECOSYSTEMS Retail has already shown us what happens when competition for attention intensifies. It started with specialised shops. Then supermarkets came into play. Finally, megamalls appeared and changed behaviour completely. People from changed going to different stores to “I am
going to the mall,” because it offered almost everything. Online entertainment is also moving from specialist brands to what I call “megamalls of attention” – platforms where users can watch content, play games, shop, socialise, follow creators, and earn rewards inside one ecosystem. Social media and streaming giants understand this. They are building superapps and integrated services that give users multiple paths to stay and keep moving between activities. If iGaming is fighting for attention, we need to become ecosystems. And that is where the metaverse starts becoming a strategy. IF THE METAVERSE IS NOT VR, WHAT IS IT? When we hear “metaverse” and immediately picture a headset, we confuse how experiences are delivered with what they actually are. In business terms, the metaverse is about creating multi-layered, alwaysavailable digital experiences where different types of content, services, and interactions blend into one journey. It is about fusion and depth: more things to do, and more ways to stay involved with them over time. Our players are already living this way. Payments, communication, work, entertainment, and self-expression are deeply digital and interconnected. In this reality, stepping into the metaverse as an iGaming company simply means asking how we add meaningful layers around a play so it is not an isolated event, but part of a larger experience.
There is significant opportunity in extending iGaming-style interaction into the other digital spaces where our users already spend time
59
“
CASINO
SBC LEADERS ISSUE 38
WHEN GAME MECHANICS PLATEAU This issue becomes critical once we admit how mature our core game mechanics already are. Slots still rely on familiar structures. Sports betting’s fundamental proposition remains the same. Crash games were the last true shock, and have already become standard. If we bet our long-term differentiation on discovering the next big mechanic, we are ignoring the odds. It is far more realistic to accept that innovation now needs to happen around the core mechanic. The question is not only what happens inside a single round, but what comes before and after it. This is where meta-layers become decisive. BUILDING META-LAYERS, NOT JUST PROMOTIONS Meta-layers already exist in our world, but often in a primitive form. Missions, quests, loyalty points, and badges are in common use. Too often, though, they are treated as marketing instruments rather than as part of the product’s core architecture. Progression, narrative, collection, social interaction, and rewards should feel like parts of one system rather than isolated campaigns. Casual mobile games are a clear reference. The most successful titles combine a central mechanic with side quests, mini-games, live events, and evolving loyalty mechanics. The user inhabits a world that adapts to their mood, their schedule, and their goals. The iGaming segment needs to take note and integrate metalayers as the skeleton that holds the entire experience together.
FROM SEGMENTS TO STATES Adopting this mindset forces us to rethink player segmentation. Traditionally, we classify users by value, frequency, and product preference. These are useful, but they ignore the player’s situation and emotional state at the moment of interaction. Companies running free casual mobile games learned long ago that the same person behaves differently in different contexts. The same is true in iGaming. If we present the same offering to players with a multiplicity of emotional states, we drive them into platforms that feel more emotionally intelligent. Designing for the metaverse means building one platform that can flex between quick, low-friction micro-sessions and deep, high-commitment journeys, while still staying responsible and compliant. TAKING IGAMING BEYOND ITS OWN WALLS Meta-layers do not have to stop at the boundaries of our platforms. There is significant opportunity in extending iGaming-style interaction into the other digital spaces where our users already spend time. Betting can become a natural layer on top of streaming content, for example by allowing viewers to predict story developments or outcomes while watching a series. If we do not adapt, we will risk becoming a back-end transactional engine while other platforms own the relationship, the data, and the emotion around the experience. In a metaverseshaped world, that is not a position any of us should accept.
60
A STRATEGIC AGENDA FOR LEADERS As a CEO, I don’t see the metaverse as a technology experiment far ahead on the roadmap. It is a strategic filter for decisions we take today. I ask whether we have a concrete plan to add meaningful meta-layers around our existing products, whether our user journeys adapt to different emotional states and time budgets, and whether our content appears in the ecosystems where our players already spend their attention.
CASINO
“
We need to understand depth of engagement across verticals, our share of the player’s wider digital leisure time
I also look carefully at what we measure. Revenue and activity will always be central, but they are not enough. We need to understand depth of engagement across verticals, our share of the player’s wider digital leisure time, and how compelling our products are when they sit alongside streaming, social media, and gaming. A PERSONAL CALL TO ACTION The metaverse, as I understand it, is not waiting for us at some
future hardware milestone. It is emerging from the choices we are making right now about how we build products, platforms, and partnerships. You need a clear answer to a simple question: what genuinely new way can I create, today, for my players to engage with my content? If your honest answer involves a new layer of interaction, a more adaptive experience, or a deeper form of connection or shared play, then you are
61
already building your part of the metaverse. In a world where every digital brand is competing for the same limited attention, this shift in thinking may be the difference between becoming a true entertainment ecosystem and being the browser tab that gets closed. As leaders, we cannot afford to sit back and wait for someone else to define that future for us. We have the opportunity, and I would say the responsibility, to start shaping it today.
CASINO
SBC LEADERS ISSUE 38
62
CASINO
FROM ACQUISITION TO ARCHITECTURE Vyking CEO FRANZ GERHART on the shift from an acquisition arms race to a focus on the ROI from platform architecture
F
or the better part of the last decade, iGaming has been defined by an acquisition arms race. Bonuses, affiliates and media buys scaled faster than the underlying product ever did. Operators chased CPAs instead of sustainable margins. And in a world where capital was cheap and market access was expanding, that model worked – at least for a while.
And that answer starts with product control, real product control, at the architectural level. CONTROL ISN’T ANOTHER TOGGLE. IT’S ARCHITECTURE One of the industry’s biggest misconceptions is that “control” is just a collection of settings: more back-office options, more bonus templates and more configurable skins. But settings are not control, they are permission slips. True control is structural. It’s the ability to plug in your own tools, ship your own UX, decide your own roadmap, and react at the speed of your strategy and not by the speed of your vendor’s global prioritisation cycle.
But the industry has changed. Sustainable success will not come from spend alone. It will come from operators who pair smart investment with smarter product architecture. While CRM, bonuses, and media spend absolutely still matter, and behavioural CRM remains one of the strongest retention levers we have, the real multiplier is the platform layer. Architecture is what turns those tools into outcomes. You simply cannot create sustainable economics on top of a closed, dependency heavy system. And you cannot innovate if your platform forces you to renegotiate every time you want to test a new idea. As operators face rising acquisition costs and pressure on margins, the question is no longer “How do we get more players?” It is “How do we create more value per player?”
63
This is where traditional platform models can struggle. They provide configuration, but not always the level of flexibility operators now expect. And because these systems must support many brands at once, even good ideas can end up waiting in a broader release schedule. From my experience, this is the single biggest operational tax on ambitious operators today: the roadmap dependency that drains velocity, creativity, and, ultimately, ROI. At Vyking, we believe architecture, not feature count, is what decides who wins.
CASINO
SBC LEADERS ISSUE 38
OPERATORS ARE GROWING UP. PLATFORMS NEED TO GROW WITH THEM The iGaming market is split. There are operators who are comfortable being marketing-led turnkey brands. And then there are those who want to build long-term enterprise value by acting like product companies. These ambitious operators are hiring product managers, bringing in engineers, building UX capabilities, and designing their own journeys. They want to own the experience that sits between the content and the customer. But they don’t want to build everything from scratch, and they don’t want to inherit the brittleness of legacy stacks.
“
The acquisition era went to the operators who could shout the loudest. The era ahead will belong to those who build the smartest
That is exactly the gap Vyking exists to fill: the space between off-the-shelf and full in-house. Our open architecture approach, which includes frontend source access, a modular backend, and reverse integration, gives operators control over the layers that actually drive differentiation while relying on a battle-tested core for compliance, wallet, and game integrations. This is why our Core, Edge and Flex tiers matter. They reflect the natural evolution of a growing operator: start fast, scale smart, then own what makes you unique. The only certainty in our sector is uncertainty. New regulations, new payment rails, new content formats, new channels. Closed systems buckle under this level of change. Every new requirement becomes a negotiation. Every market expansion becomes a project and every innovation becomes expensive. Open architecture gives operators the freedom to plug in, swap, extend and test without friction. Want to trial a new KYC provider? Do it. Want to launch a new lobby design for one region only? Ship it. Want to integrate an ML segmentation layer? Bolt it on. You don’t need to predict the future. You just need a platform that won’t limit your response to it.
64
INTRODUCING VYKING PODS And this is where architecture becomes more than philosophy, it becomes acceleration. At Vyking, we are not only rethinking how operators control their product, we’re rethinking how the entire content layer should work. Imagine integrating casino content not through months of engineering effort, but by simply adding a JavaScript library to your website. That’s the future we’re building at Vyking. Our new Pod system which we are developing uses in-memory WebAssembly clusters running on the end user’s device – micro “pods” that handle the full communication cycle locally. The result is a cost-free, integrationless content protocol that removes the bottlenecks operators and studios have been fighting for years. No heavy middleware, no vendor backlogs and no painful certification cycles. If you close a deal with a game studio today, you can be live with their content tomorrow. For the industry, this represents speed, accessibility, and an entirely new way of thinking about platform infrastructure. And for operators, it unlocks an innovation curve that finally moves at the pace of their ambition and not the limitations of legacy systems. The brands who win the next decade won’t be the ones who spend the most. The acquisition era went to the operators who could shout the loudest. The era ahead will belong to those who build the smartest. That’s where margins are made, where retention is earned, and where ROI is created. That’s where Vyking is focused, not as another platform vendor, but as the architectural foundation for operators who want to behave like product companies and build longterm enterprise value. Want to see how open architecture can change your roadmap? Come meet Vyking the team at ICE Barcelona, Stand 1B02.
THE FUTURE OF PLAY Casino, Sports Betting and Beyond
6,000
DELEGATES
250
SPEAKERS
100
SPONSORS & EXHIBITORS
28–30 April 2026 InterContinental Malta
For more information please visit sbcevents.com or scan the QR code
SBC LEADERS ISSUE 38
SPORTS BETTING POWERED BY
ON THE FOLLOWING PAGES 67 68 72
Column: Ted Menmuir on UK tax implications Interview: SIS MD Paul Witten Interview: Joe Bertolone of IGT and Xtremepush’s Tommy Kearns 66
SPORTS BETTING
GAMBLING LICKS ITS WOUNDS Tax determinations across multiple markets dominated industry headlines in 2025. SBC Editor at Large Ted Menmuir argues that the sector’s battle scars and the lessons they leave behind will cut far deeper than economics alone
growth, lobbying, and regulationby-negotiation finally hit a wall.
O
h lord… how things have changed! At the close of last year, Gambling put its feet up for the Christmas break gazing at the imminent opening of Brazil’s Bets market and having just avoided an expected tax bullet from the UK government. In Europe, prospects had brightened as Italy committed to execute its long-awaited “gambling reorganisation”, and France – at last – acknowledged the need to legislate for iCasino. Even in the US, many viewed the incoming Trump administration as “pro-business”, raising hopes for fresh momentum behind stalled state-level iGaming debates. Yes, 2024 was no waltz, yet compared to 2025’s tango, it now feels like a distant rehearsal for the chaos that would follow. This has been the year when optimism met reality; when expansion dreams collided with fiscal walls; and when the industry’s well-worn playbook of
In the UK, shots were fired early as Labour ministers demanded intervention on the “soft touch” legacies of the Gambling Review. Though the government insisted it would not reopen the Review, it promised that Labour would deliver a definitive settlement on the regulatory future of UK gambling. Across Europe, panic buttons were tapped in unison. In the Netherlands and France, with no consultations, governments simply moved, imposing tax increases on gambling licensees – sports betting taking the blow in France – resetting a +50% baseline of what fiscal risk now looks like. The warnings landed early: 2025 would be a difficult year for incumbents. Then came Brazil, the sector’s great hope. Instead of a golden launchpad, operators ran headfirst into an unrelenting reality of banking restrictions, compliance bottlenecks, municipal-versusfederal skirmishes, and a tax framework far sharper than early market narratives had suggested. What was once sold as the industry’s next growth chapter has morphed into a lesson on political sovereignty and fiscal pragmatism as operators moved to implement costly Year-1one multi-million losses on year accounts.
67
By mid-year, a pattern had crystallised: governments everywhere had grown tired of incrementalism. Treasuries needed revenue, regulators needed authority, and gambling – mature, visible, and politically defensible to tax – became the easiest lever to pull. Yet the sector’s leadership cannot claim surprise. For two years, warnings had circled that patience among policymakers was thinning. The assumption that gambling could argue its way out of structural tax reform was – to put it bluntly – misplaced. So here we close 2025 with the industry exhausted, battle-worn, and searching for its footing to close its most problematic decade. There are no soft landings, no gentle glidepaths into 2026. Only more lessons: on fiscal realism, on political humility, and on the need to rebuild trust rather than rely on legacy narratives.
Scan here for more from SBC News
SPORTS BETTING
SBC LEADERS ISSUE 38
EXTENDING THE
SEASON
Managing Director PAUL WITTEN explains how a new SIS product is offering extra American Football action for operators
S
IS recently launched eAmerican Football, which offers two 24/7 streams of live action to its sportsbook partners across the world. Can you start by explaining the inspiration behind it?
Our customers advised us they wanted an American football product to help fill this huge void, and that is exactly what we have developed. Customerdriven demand is always better than an “if you build it, they might come” approach.
The decision was very much customer-driven and focused primarily (but not uniquely) on the US market, where we have long-established and successful partnerships with major sportsbook operators.
You launched eAmerican Football in early December. Was the timing significant?
We have been working closely with our US customers to understand what product they would like to see next within our Competitive Gaming division. That appetite has been driven by the strong success they have already seen with our eBasketball and eSoccer products, which offer quickfire, high-integrity, 24/7 esports betting opportunities. Together, we identified a significant gap in the market for US sports betting, particularly around the football season. US consumers overwhelmingly prefer betting on US sports, but the football season is quite short , leaving a long off-season – from February to September – with limited competitive action for players to engage with.
Absolutely. We have been working very hard behind the scenes in developing this product for the last five to six months, and we really wanted it to be live before the Super Bowl in February. The goal is to allow consumers to become familiar with the product while live football is still running. That way, there will be continuity as they transition into the long offseason, and we hope they will continue to engage with eAmerican Football. Digging into the technicalities, what were the particular challenges in developing this product compared to your existing simulations like eBasketball and eSoccer? The main difference lies in the nature of the sport itself. Soccer and basketball are very much flow-based games where action
68
happens constantly. American football, however, is more like physical chess; it is a strategic, stop-start game with a regular series of set-play opportunities. This created a challenge in terms of our gamers, who compete against each other in a purposebuilt studio in the UK. They do not just need physical capability with a controller in hand; they also need the contextual understanding and a strategic mindset to pick the right offensive and defensive plays at the right time. That learning curve for our gamers was a significant difference compared to our other products. We understand there are differences here in terms of the viewing perspective and market uptime. Can you elaborate? We have been very specific with the views we have selected to optimise uptime, gameplay and engagement. Due to the stop-start nature of eAmerican Football and the way the strategic elements are revealed, the market uptime will be lower than our other products. In eBasketball and eSoccer, we have market uptime in the mid80% range, but for eAmerican Football, it is projected to be in the 60% range. It will be a bit more stop-start, but we think that is the right balance.
SPORTS BETTING
When you hear England soccer captain Harry Kane talking about potentially switching to American football, you can see it is a sport with global appeal
69
“
SPORTS BETTING
SBC LEADERS ISSUE 38
“
Millions of viewers watch people playing these games on platforms like YouTube, and we provide operators with multiple 24/7, high integrity, high quality, low latency streams which they can offer to their customers
On the subject of preparation, how extensive was the testing phase for launch? It was extensive. We have had gamers playing 24/7 for over four months to test not just the data models and market dynamics, but crucially, to ensure the matchups of gamers are as competitive as possible. Ensuring competitive, exciting games are streamed is essential for driving betting engagement. Competitive Gaming is performing successfully for your operator partners. Why do you think products like this are so popular with sports bettors? The key driver is familiarity. People who already bet on American football, or other sports, already know the markets they enjoy. This product offers the same experience. Millions of viewers watch people playing these games on platforms like YouTube, and we provide
operators with multiple 24/7, high integrity, high quality, low latency streams which they can offer to their customers to enjoy. That ease of transition and familiarity is vital. While the primary focus is understandably on the US, do you see eAmerican Football having appeal beyond North America? One hundred per cent. You only have to look at the global efforts with live matches in London, Germany, Dublin, Spain, Mexico, and potentially Brazil. American football as a live product has a growing global audience. Many older fans in Europe grew up watching the sport when it was first introduced on TV. In the UK, this was back in the 1980s when network television first started to broadcast it, and the International Series has been active in London since 2007. When you hear England soccer
70
captain Harry Kane talking about potentially switching to American football, you can see it is a sport with significant resonance and global appeal. While the US is a major focus, we certainly expect eAmerican Football to appeal to the global audience that follows the sport. Finally, how does Competitive Gaming align with SIS’s overall product offerings? It complements our existing business perfectly. While our legacy racing product is a stable, important business facing challenges in attracting a new demographic of bettors, Competitive Gaming represents the diversification and growth element of our revenues both now and in the future. It allows us to innovate and extend our product range into areas that have global appeal and can attract that new demographic, which is crucial for the overall health of the betting industry.
SOMETHING
BIG
IS COMING IN AFFILIATE MEDIA
AFFILIATELEADERS.COM
SPORTS BETTING
SBC LEADERS ISSUE 38
LEADERSHIPFUELLED COLLABORATION
Xtremepush CEO Tommy Kearns
72
SPORTS BETTING
Xtremepush CEO TOMMY KEARNS and IGT Playsports SVP JOE BERTOLONE tell the story of how they transformed a standard commercial relationship into a genuinely differentiated alliance
X
tremepush Co-Founder Tommy Kearns has long operated at the intersection of data, marketing technology, and highvelocity growth. His leadership style blends deep technical understanding with an insistence on measurable, real-time impact; an approach that has shaped Xtremepush into one of the only CRM and loyalty providers capable of unifying behavioral and transactional data at scale.
Xtremepush and sports and igaming giants IGT. Talking to Kearns and Bertolone, the distinction between good working relationships and great ones is clear.
At IGT, Joe Bertolone brings a complementary leadership perspective, informed by decades of experience running large, medium, and small gaming operations across North America. His background gives him a practical, operational lens; one that recognizes the friction operators face daily, the fragility of customer loyalty, and the critical importance of foundational integrations rather than surface-level vendor add-ons.
“Everyone is making regular commercial announcements across the industry,” acknowledges Bertolone. “We’ve got a deal with X, with Y, but what’s different with Xtremepush is that it is truly a deep integration that’s been proven to be a success at the transactional and database level.”
Their collaboration has been allergic to “bolt-on” solutions and has been laser-focused on a foundational approach that unifies the oftenfractured world of land-based and digital gaming environments.
A recurring theme in the conversation is around fragmented tech stacks. Operators can get fatigued by suppliers who promise the world but deliver inefficiently. For IGT, they hear of these frustrations day-to-day and so their approach isn’t just about ticking the CRM box, it’s about finding a vendor that understands their challenges, those of the broader sports betting and gaming environment, and of the complex ecosystems between brands.
Together, Kearns and Bertolone represent the blend of expertise, “humble arrogance,” as Kearns puts it, as well as the operational realism that Bertolone emphasizes, that underpins the success of the Xtremepush and IGT collaboration. NOT ALL RELATIONSHIPS ARE CREATED EQUAL
Kearns expands on the levels that make this, and others, a success story. “This is a technical integration that is second to none in this space, a handson working relationship that drives both engagement and innovation for IGT’s customers.” He adds that from a personal perspective, “it’s great to work with people that you genuinely like breaking bread with on an ongoing basis.” It’s becoming clear that attention to both technical detail and personal alliances are paramount here.
There’s a stark difference between those commercial arrangements that pat one another on the back, and those that have genuine synchronicity, technical alliances, and a true collaborative approach that delivers innovation and revenue gains. One of the latter success stories was conceived in 2022, between Dublinbased CRM and loyalty experts
73
SPORTS BETTING
SBC LEADERS ISSUE 38
THE OMNICHANNEL HOLY GRAIL
level”, rather than treating it as an afterthought. By building profiles, leveraging Xtremepush’s single customer view, based on activity, location, and time, IGT’s customers can offer rewards that resonate on a personal level. Kearns reiterates this importance, that understanding the player at the “one-to-one level” and knowing what they have done in the last day, hour, or even minute, is key.
Few suppliers and operators have successfully bridged the gap between the casino floor and mobile sportsbooks. This has been the key challenge of this relationship from day one. How do you go about solving the data problem at its source, merging two distinct ecosystems for effective, engaging communication?
THE EXPERTS IN THE ROOM
“What IGT has astutely done is seamlessly merge the digital and land-based sectors, from the kiosk to online,” says Kearns. “We’re then able to plug our platform in and unify all these channels into a single customer view, from both a behavioral and transactional perspective, allowing IGT’s customers to respond to granular events in real-time.” The Xtremepush CEO describes this capability as the “holy grail” in the CRM space and adds that “only very few actually accomplish it effectively.”
Technical capability and execution are non-negotiables for a longterm working arrangement of this scale. It’s not the whole picture, though. Cultural fit and industry expertise must also be part of that mix. For a company of IGT’s size and scope to rely on a technology supplier, the company must demonstrate a deep, nuanced understanding of the betting and gaming ecosystem. “We pride ourselves on being the experts in the room,” says Kearns. “In this industry, IGT is one of the biggest brands in the world and we have to be able to stand toe-to-toe and speak their language.” He describes his company’s culture as having the aforementioned “humble arrogance”; they know their world inside-out and he views it as a privilege to deliver that expertise to major brands.
For Bertolone, the operational impact of this data exchange is tangible. “Real-time information flow between IGT and the operator is a game-changer,” he adds. Marketing departments with these deep, cross-channel integrations are empowered to move beyond generic campaigns and instead can understand exactly what a player is doing at any given time, raising engagement levels significantly.
Bertolone agrees: “Xtremepush understands sports betting, right? For us, that’s critically important. They understand the things we’re concerned about.” This shared language allows IGT to present a differentiated, unified front to their operator clients. “Offering Xtremepush as our bundled solution keeps us competitive in the marketplace,” he adds. When operators ask for a digital marketing solution, we don’t have to point them to an unknown third-party; we can offer a deeply integrated, proven solution immediately.
The necessity for these more complex, aspirational integrations stems from the reality that player loyalty is arguably at an all-time low. Bertolone admits that “your customers are only as loyal as the next bonus or bet offer.” So, understanding how to retain those customers and make them more sticky is crucial. His answer lies in programming loyalty at the “foundational
74
SPORTS BETTING
“
He expands that IGT, as you’d expect, has integrated with all types of suppliers in the digital marketing world, but a repeated conversation is that “they keep getting asked for Xtremepush-provided solutions.”
Ultimately, at this level, technology and culture must also translate to revenue gains
ALL ABOUT THE REVENUE Ultimately, at this level, that technology and culture must also translate to revenue gains. Both Tommy and Joe emphasize that this type of agreement is not a “nice to have”, it’s a real commercial driver. Bertolone elaborates “What we look to Xtremepush to do for us is increase revenues by making the entire betting ecosystem really tight between the platform provider and the end user.” He points to an unnamed success story where this integration was pivotal in helping turn a brand from “position number eight to top two within a matter of a year or so” in their category. “Technology integrations like this work when both sides can lean in hard and expect the same back,” Kearns claims. This aligns with the Irish brand’s philosophy of ‘Customers for Life’. “We want to grow with IGT. We want them to be that customer for life, and how we do that is by keeping on leaning into their needs, making sure that we’re driving better solutions together.” Bertolone agrees from his viewpoint, noting that as they go through the onboarding process with new customers, they have a simple pitch: “We have a digital marketing solution for you that we really believe can help us both make money.” He claims that his trust in the solution is a major competitive advantage and sales point of difference. “The companies that are doing this right are doing it foundationally,” Kearns reiterates. “Once you have that tight, coupled integration, then the world becomes our oyster very quickly.”
IGT Playsports’ Joe Bertolone
75
SBC LEADERS ISSUE 38
MARKETING POWERED BY
ON THE FOLLOWING PAGES 77 78
Column: Jyoti Rambhai on downturn strategies Report: SBC Summit, Lisbon 76
MARKETING
PAID SEARCH WILL BE KEY Marketing execs will turn to performance marketing channels like search, affiliate marketing and social as budgets get squeezed, writes Affiliate Leaders Editor Jyoti Rambhai
such as, paid search, affiliate marketing and display, over brand marketing (29%). Focusing spend based on ROI is short-term thinking – something which in times of uncertainty, marketers generally navigate towards. And it’s been like that for a while now.
F
rom record high levels of global inflation to the war in Ukraine, the last few years have been plagued with uncertainty for marketers. Add to that, volatility around US trade policies, AI adoption and the changing media landscape, it’s fair to say there’s still a grey cloud hanging over business optimism. Marketers are generally more optimistic about 2026 being better than last year, however, this isn’t translating into increased budgets. WARC’s latest The Voice of Marketer report – a poll of more than 1,000 marketers worldwide – found that while 59% expect business to be better this year, less than a fifth (19%) believe marketing budgets will increase. The 40 percentage point difference highlights the trend in recent years for marketers to do more with less. Hence why – with lower budgets – 42% said they are more likely to invest in performance marketing channels
WARC’s Insight Director Aditya Kishore says this shortterminism “red flag” is down to “tension between poor macroeconomic visibility and the need to play for long-term business growth”. So what is fuelling this pessimism and what does it mean for affiliates? The first is US trade policies, namely tariffs, with three-fifths (61%) citing the impact they are having on their marketing strategies. The ripple effect from the expanded tariffs – particularly on imports, including now low value goods from China – is leading to supply chain disruptions, lower demand from products and reduced profit margins. It has also slowed investment. In the UK, Rachel Reeves’ budget at the end of November is expected to have a dual impact on marketers. While increased investment from the government could offer growth opportunities for some brands, many will find their marketing budgets squeezed as tax rises will increase
77
operational costs and reduce profit margins. For affiliates in gaming, gambling tax hikes will affect mostly online operators, and could see some leaving the market. Tom Galanis, CEO of marketing agency Tag Media, told SBC News, that a 40% rate will “spell the end for many businesses” that are already “battle weary from persistent jabs from the regulator over the past few years”. Despite the dreary political climate, there is hope for affiliates. WARC forecasts the global ad market to grow by 7.4% to $1.17tn by the end of 2025, with 90% going towards digital platforms. Paid search will remain a key channel with adspend projected to reach $274bn in 2026. However, growth is expected to slow as the search landscape becomes fragmented and consumers shift away from traditional search engines to platforms like ChatGPT, Amazon and TikTok.
Scan here for more from Affiliate Leaders
MARKETING
SBC LEADERS ISSUE 38
SBC SUMMIT 2025 78
MARKETING
A record-breaking 30,000+ delegates from 150 countries visited Lisbon for the SBC Summit, a 20% year-on-year growth in participation. The summit also welcomed over 700 exhibitors and sponsors and over 550 expert speakers
A CEO’S PERSPECTIVE ON AI Gambling CEOs are cautiously embracing AI, integrating it into marketing, player protection, and analytics. Jesper Svensson, Betsson Group CEO, emphasized AI’s problem-solving power: “Problems you thought there was no solution to a few years back can now be solved through technology.” He also noted its dual edge, warning that AI can challenge cybersecurity. Flutter International CEO Dan Taylor sees AI as a core pillar of its business strategy, where speed is a priority when you’re competing on multiple continents. And in today’s world, everyone can be a competitor thanks to AI – not just the top dogs in the market. Betfred CEO Joanne Whittaker cautioned on recruitment, feeling “frightened” at AI’s potential to replace human thinking. Super Group CEO Neal Menashe spoke of the rise of the ‘bet influencers’, who use AI to build up a series of bets on events which they then share with their followers. Taylor responded by citing the example of Australia and Italy, where a quarter of Flutter users access bets from a social platform rather than traditional UI.
79
MARKETING
SBC LEADERS ISSUE 38
HALF MEASURES WILL HURT FINLAND Nordic leaders urged Finland to chart its own path in liberalising online gambling by 2027, but entrenched opinions and regulatory uncertainty persist. While the market’s opening promises high value and competition, parliamentary debates since 2020 highlight years of delay and indecision. Jaakko Soininen, Finnplay’s Managing Director, noted that “the wheels of reform began turning long before the debates in parliament,” after Veikkaus, the state monopoly, admitted it had “lost control of the online gambling market… an open secret that no party wanted to confront.” Legislation is expected by early 2026, launching licensing in 2027, though political caution could push implementation past the April elections. Operators face a draft law lacking key determinations. Paf General Counsel Sverker Skogberg warned, “If we’re serious about building a sustainable market, we need 2.0 regulation almost from the moment this one goes live – not another three-year wait.” Hippos ATG Chief Compliance Officer Antti Koivula cautioned against over-restriction, saying, “A system that drives players to the black market cannot be called responsible.” Marketing could spark public backlash if left uncontrolled, with Koivula joking, “What do I tell my mother-in-law and auntie – not to watch TV for six months?”
80
Employer of the Year: SOFTSWISS
Large operator of the Year: Kaizen Gaming
Medium operator of the Year: Vegas Legends
Small operator of the Year: 8888.bg
Casino Operator of the Year: Betsson Group
Marketing Campaign of the Year: 1xBet
81
COMMENT
SBC LEADERS ISSUE 38
Final word with
RASMUS SOJMARK I
f there’s one thing I’ve learned in this industry, it’s that the future always arrives faster than we expect and before we act.
scrutiny, the ability to provide open, tamper-proof data could be a game-changer. Then there’s Web 3.0, which is a term that still gets blank looks from some corners of the industry. But this next phase of the internet is all about participation, ownership, and identity.
As we head into 2026, we’re surrounded by technology that, even a few years ago, felt almost science fiction. Things such as artificial intelligence, blockchain, Web 3.0 aren’t abstract ideas anymore. They’re real, they’re accessible, and they’re waiting for us to do something meaningful with them.
We’re talking about players who expect to move seamlessly between worlds–opening doors for community-driven platforms, tokenised loyalty programmes, even cross-platform avatars that carry your reputation and history wherever you play.
But here’s the truth: having the technology isn’t enough. What matters is what we do with it. And that’s where I think our industry is standing at a crossroads.
One thing I’m proud of is how SBC has tried to give the industry the tools to understand and adapt to this changing landscape. At the SBC Summit in Lisbon 2025, we introduced the Tech Academies — hands-on learning sessions dedicated to exactly these kinds of topics.
Let’s start with the big one. AI has been the headline act for a while now, but too many companies are still treating it as a nice-to-have rather than a strategic pillar. AI shouldn’t be viewed as just another tech upgrade. It’s actually a mindset shift. It’s about asking: how can we make every part of our business smarter, faster, safer, and more personal?
We wanted to go beyond the big-stage buzzwords and give people a chance to learn by doing: experimenting with AI models, exploring blockchain use cases, and hearing directly from developers building Web 3.0 infrastructure. The response was incredible.
In 2026, the winners will be those who stop experimenting with AI and start embedding it; into product design, compliance, risk management, player protection, and marketing. The tech is there. The question is whether we have the imagination to make it work for us.
It reminded me that our industry isn’t short on curiosity — we just need the right spaces to explore, learn, and collaborate. That’s something we’ll keep building on in 2026 and beyond.
The blockchain hype has faded but it is now being used to improve transparency, verify transactions, and even enable new models of player ownership and loyalty. In an industry that’s constantly under
Stay cool, Rasmus Sojmark, Founder & CEO, SBC
82
THE GREATEST SHOW IN GAMING 40,000
DELEGATES
600+
SPEAKERS
800
EXHIBITORS
29 SEP – 1 OCT 2026 FIL, LISBON
For more information please visit sbcevents.com or scan the QR code
CONNECTING WORLDS THROUGH GAMING June 9–11, 2026
Fort Lauderdale, Florida Broward County Convention Center
10,000
DELEGATES
400+
EXHBITORS
SBCEVENTS.COM #SBCSUMMITSAMERICAS
250
SPEAKERS