01 | MARKET RESEARCH BRIEF
GLOBAL MARKET OUTLOOK 2025 –2035
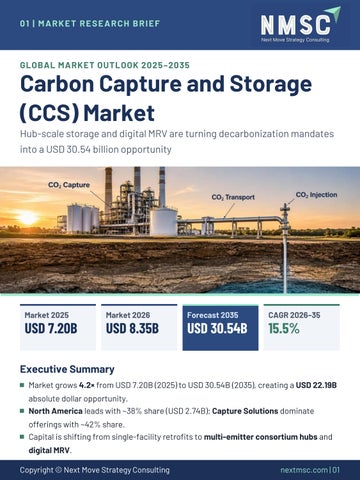
Carbon Capture and Storage (CCS) Market Hub-scale storage and digital MRV are turning decarbonization mandates into a USD 30.54 billion opportunity
Market 2025
USD 7.20B
Market 2026
USD 8.35B
Forecast 2035
USD 30.54B
CAGR 2026–35
15.5%
Executive Summary Market grows 4.2× from USD 7.20B (2025) to USD 30.54B (2035), creating a USD 22.19B absolute dollar opportunity. North America leads with ~38% share (USD 2.74B); Capture Solutions dominate offerings with ~42% share. Capital is shifting from single-facility retrofits to multi-emitter consortium hubs and digital MRV. Copyright © Next Move Strategy Consulting
nextmsc.com | 01
02 | MARKET LANDSCAPE
A USD 7.20B Market Scaling 4.2× by 2035, Led by Capture Solutions Market Size (USD Billion)
Share by Offering, 2025
CAGR 15.5% (2026–2035)
% of USD 7.20B
30.54
Capture
+USD 22.19B
opportunity 2026–35
7.20 2025
8.35 2026
42%
Transport
16%
Storage
14%
Conditioning
10%
Engineering
9%
O&M
6%
Digital
3% · 24.5% CAGR
2035
Industry Ecosystem & 2025 Value Pools Capture
Conditioning
Transport
CO₂ source
Compress
$3.02B
$0.72B
$1.15B
Storage
$1.01B
Digital MRV
Pipeline
Injection
Verify
$0.22B
Enabling services across the chain: Engineering $0.65B · Operation & Maintenance $0.43B
Scope spans post-, pre-combustion, oxy-fuel and direct air capture, plus conditioning, transport, storage, engineering, O&M and MRV software. Oil & Gas is the largest end user (~26%, USD 1.87B); Industrial Emitters lead customer types (~32%, USD 2.30B). Compressors lead equipment (~22%, USD 1.58B); Equipment Supply leads service models (~28%). Report covers 33 countries and 20 companies; the U.S. alone reached ~USD 2.24B in 2025. Copyright © Next Move Strategy Consulting
nextmsc.com | 02
03 | GROWTH DRIVERS & OPPORTUNITIES
Policy Incentives and Mega-Scale Hubs Power the Next Decade Impact on CAGR (percentage points)
■ Driver ■ Restraint +2.8
Government tax credits & funding
+2.2
Mega-scale storage hub development
+1.8
Hard-to-abate decarbonization mandates
+1.4
Blue hydrogen & storage hub investment
Demand for verified carbon removal credits
+1.0
Asia-Pacific decarbonization investment
+0.8 −1.6
High capital intensity, long timelines
−1.1
Equipment supply chain disruption
−0.7
Opposition to onshore pipeline siting
Regional Growth Opportunity Map North America
Europe
13.9%
14.5%
2.74 → 10.23
1.87 → 7.34
CAGR 2026–35 · USD B
Asia-Pacific ★ Fastest
Middle East & Africa
Latin America
1.58 → 8.47
0.65 → 2.97
0.36 → 1.53
16.5%
18.5%
15.5%
Hotspots: China 21.2% CAGR (fastest) · India 18.5% · U.S. largest (USD 2.24B)
Fastest-Growing Segments (CAGR 2026–35) Digital Solutions
24.5%
Membranes
22.5%
Modular Capture
21.3%
Mega Scale
20.4%
Ethanol
20.3%
Consortium
19.9%
Policy is #1: Section 45Q & EU Innovation Fund add +2.8 pts to CAGR. Hub economics: Northern Lights scales 1.5 → 5+ Mt CO₂/yr by 2028. Whitespace: hub capacity fees, MRV platforms, modular capture. Watch-outs: capital intensity (−1.6 pts) and equipment lead times (−1.1 pts). Copyright © Next Move Strategy Consulting
nextmsc.com | 03
04 | COMPETITIVE SCENARIO
Integrated Conglomerates vs. CaptureTechnology Specialists Moderately consolidated: competition on tech, scale & integration. Bankable tech wins: MHI runs 18 commercial capture plants. Strategy mix: partnerships, hub expansions, platform launches.
Capture-tech depth →
Tech Specialists
Integrated Leaders
Carbon Clean Svante
MHI SLB Baker Hughes
Emerging DAC & Solvent Innovators Oilfield Service Majors Value-chain integration (capture → storage) →
20 companies profiled 10
firms with tracked market share
50%
cost-cut goal, Entergy–MHI
$15B+
CCUS debt raised in 2 yrs (IEA)
Key Strategic Moves Mar 2025
Expansion
Northern Lights: USD 714M to reach 5+ Mt CO₂/yr
May 2025
Pilot
MHI capture pilot at KEPCO Himeji No. 2, Japan
Jun 2025
Launch
SLB launches Sequestri end-to-end CCS platform
Oct 2025
Contract
Baker Hughes compressors for Eni Liverpool Bay
Jul 2026
Partnership
Entergy–MHI MoU for power-sector CCS solutions
Key Players Profiled Mitsubishi Heavy
SLB
Baker Hughes
Technip Energies
Fluor
Honeywell
Linde
Air Liquide
Air Products
Siemens Energy
Halliburton
Chart Industries
Carbon Clean
Svante
ABB
John Wood Group
KBR
Koch Engineered
MTR (Membrane)
ION Clean Energy
Copyright © Next Move Strategy Consulting
nextmsc.com | 04
05 | LET'S CONNECT
Thank You Connect with our analysts for in-depth CCS insights, segment-level forecasts and strategic guidance tailored to your investment and growth decisions. Website
www.nextmsc.com
Phone
+1 857 758 5017
info@nextmsc.com
Click here for the complete report →
Click here for the complete report → FOLLOW US gen-dedup-e89ad2adea176ac915ed58b238056f2d.png
gen-dedup-77b6928e12c7b5da7f83bfd2402059fe.png
gen-dedup-0c6ffb19962d999c1a6d0b9e7d627d69.png
YouTube
Copyright © Next Move Strategy Consulting
gen-dedup-036fd5a62df3087f92ce310684f6dd0b.png
Twitter / X
gen-dedup-209db7f0e7dbee923c186029fd555dd5.png
nextmsc.com | 05