MARKET INTELLIGENCE BRIEFING · 2026
Receiver-in-Canal (RIC) Hearing Aids Market Rechargeable, AI-driven and connected: a USD 5.52 Billion absolute growth opportunity through 2035 Forecast 2026–2035 · 33 countries · 17 companies profiled
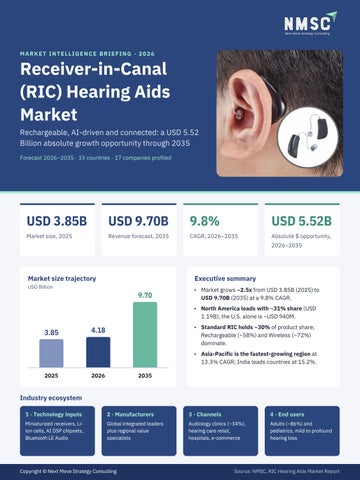
USD 3.85B
USD 9.70B
9.8%
USD 5.52B
Market size, 2025
Revenue forecast, 2035
CAGR, 2026–2035
Absolute $ opportunity, 2026–2035
Market size trajectory
Executive summary
USD Billion
9.70
• Market grows ~2.5x from USD 3.85B (2025) to USD 9.70B (2035) at a 9.8% CAGR.
• North America leads with ~31% share (USD 1.19B); the U.S. alone is ~USD 940M.
3.85
• Standard RIC holds ~30% of product share; Rechargeable (~58%) and Wireless (~72%) dominate.
4.18
• Asia-Pacific is the fastest-growing region at 13.3% CAGR; India leads countries at 15.2%. 2025
2026
2035
Industry ecosystem 1 · Technology inputs
2 · Manufacturers
3 · Channels
4 · End users
Miniaturized receivers, Liion cells, AI DSP chipsets, Bluetooth LE Audio
Global integrated leaders plus regional value specialists
Audiology clinics (~34%), hearing care retail, hospitals, e-commerce
Adults (~86%) and pediatrics, mild to profound hearing loss
Copyright © Next Move Strategy Consulting
Source: NMSC, RIC Hearing Aids Market Report
02 · GROWTH DRIVERS & OPPORTUNITIES
Aging, AI and rechargeability power the next decade Growth catalyst & risk matrix Impact on CAGR (percentage points)
+2.1
Age-related hearing loss prevalence
+1.8
AI-enabled digital signal processing
+1.6
OTC regulatory pathway expansion
+1.4
Rechargeable lithium-ion platforms
+1.1
E-commerce & teleaudiology
+0.9
Government screening programs
−1.2
High device & fitting cost
−0.7
Social stigma of visible devices
• • • •
1.5B+
−1.0
Limited reimbursement coverage
people live with some degree of hearing loss (WHO, cited by NMSC), skewed to adults 60+
Demand: aging demographics (+2.1 pts) and AI DSP (+1.8 pts) carry the largest CAGR uplift. Access: the FDA OTC rule (2022) widens the addressable base for mild-to-moderate loss. Mix shift: Rechargeable rises from USD 2.23B to USD 6.54B by 2035 (12.7% CAGR). Watch-outs: cost and thin reimbursement (e.g., traditional Medicare) restrain uptake.
Highest-growth segments · CAGR 2026–2035
15.9%
14.4%
13.2%
13.2%
E-Commerce
AI Digital
Power RIC
Ultra Power Receiver
Distribution channel
Technology
Product type
Receiver type
12.7%
12.3%
12.2%
12.1%
Rechargeable
Pediatrics
Wireless
Profound
Power source
End user
Connectivity
Degree of hearing loss
Whitespace opportunities Teleaudiology remote fitting
Auracast broadcast audio
Pediatric-specific platforms
Self-fitting RIC + remote care to reach rural demand in APAC & LATAM
Venue-level streaming opens institutional, accessibility-led procurement
Tamper-resistant, growth-adaptable designs for an underpenetrated segment
Copyright © Next Move Strategy Consulting
Source: NMSC, RIC Hearing Aids Market Report
02B · REGIONAL OPPORTUNITY MAP
North America leads; Asia-Pacific grows fastest
EU
9.6%
NA
9.3%
APAC
13.3% MEA
11.5% LATAM
10.8%
Bubble size = 2035 market size · Label = CAGR 2026–2035
Region
2025
2035 (USD B) 1.19
North America
2.65
1.04
Europe
2.37 1.00
Asia-Pacific Middle East & Africa Latin America
3.08 0.35 0.92 0.27 0.68
Key driver
9.3%
OTC regulatory expansion
9.6%
MDR compliance & reimbursement reform
13.3%
Aging population & screening programs
11.5%
Government hearing-health initiatives
10.8%
Rising audiology clinic penetration
Regional takeaways
Fastest-growing countries · CAGR 15.2%
India China
CAGR
13.4%
UAE
11.9%
South Korea
11.6%
Saudi Arabia
11.2%
Brazil
10.6%
• U.S. is the largest country market: ~USD 940M (2025) to ~USD 1,943M (2035). • APAC adds ~USD 2.08B by 2035, overtaking North America as the largest region.
• Europe: Germany (USD 310M), UK (USD 280M), France (USD 210M) anchor demand. • GCC growth is backed by government-led hearinghealth programs.
CAGR 2026–2035
Copyright © Next Move Strategy Consulting
Source: NMSC, RIC Hearing Aids Market Report
03 · COMPETITIVE SCENARIO
Integrated ecosystems set the competitive bar 17
led by vertically integrated majors
companies profiled in the report
Competitive positioning matrix CONNECTED CHALLENGERS
company shares covered in full report
Key strategies GLOBAL INTEGRATED LEADERS
Sonova Demant
Technology & ecosystem integration →
Top 10
Moderately consolidated
Eargo
• Rechargeable by default: Sonova and Demant expanding Li-ion portfolios.
WS Audiology GN Store Nord
Persona Medical Starkey
• Connectivity: Bluetooth LE Audio & Auracast pilots (GN ReSound Nexia, 2024). • M&A: bolt-on buys of teleaudiology software and hearing-screening providers. • Partnerships: audiology clinic ties and reimbursement-channel access are decisive levers.
Huizhou Jinghao Audina
NewSound
• AI chipsets: onboard deep neural networks for speech-in-noise (Starkey Edge AI, Oticon DNN 2.0).
IntriCon
Microson SeboTek
Horentek
Benson Medical
Arphi ELKON REGIONAL VALUE SPECIALISTS
NICHE SPECIALISTS
Scale & premium positioning → Indicative placement based on NMSC competitive archetypes
Recent strategic developments
2024
OCT 2025
JAN 2026
MAY 2026
GN Store Nord
Sonova Holding AG
Demant A/S
WS Audiology A/S
ReSound Nexia
Phonak Infinio Ultra
Oticon Zeal rollout
Signia Active Mini IX
Cross-platform smartphone streaming; Bluetooth LE Audio / Auracast direction for premium RIC.
Next-gen AI power management and advanced wax-management technology for speech clarity.
Global expansion; DNN 2.0 AI sound processing, rechargeability and sameday custom fitting.
Smallest ready-to-wear ITE aid with direct connectivity and full IX platform processing.
Copyright © Next Move Strategy Consulting
Source: NMSC, RIC Hearing Aids Market Report
LET'S CONNECT
Thank You Connect with our analysts for in-depth insights, segment-level data and strategic guidance on the Receiver-in-Canal (RIC) Hearing Aids Market.
USD 9.70B
9.8%
13.3%
market size by 2035
CAGR, 2026–2035
Asia-Pacific CAGR, fastest region
Click here for the complete report → nextmsc.com/report/receiver-in-canal-ric-hearing-aids-market-hc5415
OFFICIAL WEBSITE
CONTACT NUMBER
www.nextmsc.com
+18577585017
info@nextmsc.com
Follow us
YouTube
Full report coverage: 2025–2035 · 33 countries · 17 companies · segmentation by product, power source, technology, receiver, connectivity, hearing loss, channel and end user
Copyright © Next Move Strategy Consulting
www.nextmsc.com