Market Research Report · Forecast 2026 –2035
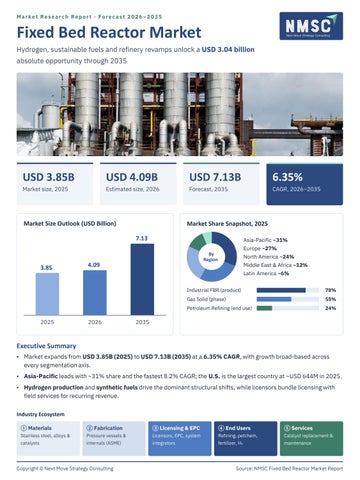
Fixed Bed Reactor Market Hydrogen, sustainable fuels and refinery revamps unlock a USD 3.04 billion
absolute opportunity through 2035
USD 3.85B
USD 4.09B
USD 7.13B
6.35%
Market size, 2025
Estimated size, 2026
Forecast, 2035
CAGR, 2026–2035
Market Size Outlook (USD Billion)
Market Share Snapshot, 2025 7.13
Asia-Pacific ~31% Europe ~27%
3.85
2025
By Region
4.09
North America ~24%
Middle East & Africa ~12% Latin America ~6%
2026
Industrial FBR (product)
78%
Gas Solid (phase)
55%
Petroleum Refining (end use)
24%
2035
Executive Summary • Market expands from USD 3.85B (2025) to USD 7.13B (2035) at a 6.35% CAGR, with growth broad-based across every segmentation axis. • Asia-Pacific leads with ~31% share and the fastest 8.2% CAGR; the U.S. is the largest country at ~USD 644M in 2025. • Hydrogen production and synthetic fuels drive the dominant structural shifts, while licensors bundle licensing with field services for recurring revenue. Industry Ecosystem ① Materials
② Fabrication
③ Licensing & EPC
④ End Users
⑤ Services
Stainless steel, alloys &
Pressure vessels &
Licensors, EPC, system
Refining, petchem,
Catalyst replacement &
catalysts
internals (ASME)
integrators
fertilizer, H₂
maintenance
Copyright © Next Move Strategy Consulting
Source: NMSC Fixed Bed Reactor Market Report
Growth Drivers & High-Growth Segments
Hydrogen and sustainable fuels lead a broadbased demand upswing Key Demand Drivers • Hydrogen capacity buildout is the primary driver (+1.9 pts CAGR impact), backed by U.S. DOE clean hydrogen hubs and national strategies in Europe and Asia-Pacific. • SAF & renewable diesel: EPA Renewable Fuel Standard blending mandates and offtake commitments compress FID timelines for hydroprocessing licensing (+1.5 pts). • Refinery revamp & replacement cycles in North America and Europe sustain equipment orders (+1.2 pts). • Ammonia & fertilizer expansion in Asia-Pacific and MEA (+1.0 pts), plus dynamic, renewables-compatible reactor designs (+0.7 pts). Pilot FBRs: 7.2% CAGR — fastest-growing product
type as licensors scale demo units
Driver Restraint
Growth Catalyst & Risk Matrix — % impact on CAGR
+1.9%
Hydrogen production capacity buildout +1.5%
Sustainable aviation fuel licensing growth +1.2%
Refinery reactor revamp & replacement
+1.0%
Ammonia & fertilizer expansion (APAC, MEA) +0.7%
Dynamic, renewables-compatible reactors
+0.5%
Specialty & pharmaceutical chemicals growth High capital cost of ultra-high pressure systems
−0.9%
Long permitting timelines (NA, Europe)
−0.7%
Catalyst deactivation & downtime costs
−0.5%
Competition from fluidized bed formats
−0.4%
High-Growth Segments — CAGR 2026–2035
Market average: 6.35%
Synthetic Fuels · end use
12.2%
Ultra-High Pressure · operating pressure
11.3%
Hydrogen Production · end use
10.7%
Maintenance & Field Services · revenue
10.2%
Structured Bed Reactor · configuration
10.1%
Ceramic · material of construction
9.9%
Gas-Liquid-Solid Reactor · phase
9.0%
Copyright © Next Move Strategy Consulting
Source: NMSC Fixed Bed Reactor Market Report
Growth Opportunities · Regional Outlook
Asia-Pacific and MEA outpace the market as H₂ as H₂ and ammonia scale Growth Opportunity Map — CAGR 2026–2035 Europe
5.0%
USD 1.04B → 1.71B
North America
4.9%
Asia-Pacific ★ Fastest
USD 0.92B → 1.50B
8.2%
USD 1.19B → 2.57B
Middle East & Africa
7.4%
USD 0.46B → 0.93B
Latin America
5.7%
USD 0.24B → 0.42B
Values: 2025 → 2035 market size. >8% 7–8% 5–7% <5%
Strategic Whitespace Opportunities
10.1%
7.2%
10.2%
Structured Bed Internals Licensing
Modular Pilot Reactors
Field Services Bundling
Rapid-turnaround, skid-mounted pilot units win recurring orders from developers validating novel catalytic processes.
Spare parts, internals and service contracts create lifecycle revenue and cut churn across long-lived installations.
Lower pressure-drop internals capture premium royalty and engineering revenue as H₂ and synfuel reactors are retrofitted.
Regional Investment Signals
Largest Country · U.S.
• Asia-Pacific: refining, fertilizer and H₂ capacity; China, Japan and South Korea formalizing hydrogen roadmaps.
USD 644M → 1.05B
• MEA: GCC blue hydrogen and ammonia export mega-projects drive licensing.
• Europe: Industrial Emissions Directive compliance and sustainable fuel mandates. • North America: refinery revamp cycles and DOE-backed hydrogen hubs.
2025 → 2035 at 4.9% CAGR; revamps & H₂ hubs
Fastest Country · China
~8.4% CAGR 2026–2035; highest growth among 38 countries covered
Copyright © Next Move Strategy Consulting
Source: NMSC Fixed Bed Reactor Market Report
Competitive Scenario
A moderately consolidated market led by process licensors Top 5
20
38
42%
licensors hold majority of
companies profiled in the
countries covered in the
share via direct sales channel
licensing revenue
report
analysis
(2025)
Market Positioning
Competitive Positioning Matrix Specialized Fabricators
Diversified Process Licensors
High-pressure vessel engineering
Full-scope licensing, engineering, commissioning
● Walter Tosto Commercial scale & references →
● Belleli Energy CPE ● Larsen & Toubro
● Honeywell (UOP) ● Axens ● Topsoe ● KBR ● Casale ● Lummus Technology ● thyssenkrupp Uhde
• Players compete on licensing depth, metallurgical capability and commercial operating references. • Honeywell and Topsoe leverage decades of references with multinational refining & fertilizer clients. • Walter Tosto and Belleli win on highpressure vessels for H₂ & ammonia synthesis.
Lab & Pilot Instrument Makers
Systems & Components
R&D-scale reactors
Integrated test units, flow components
● Parr Instrument ● H.E.L Group
● Vinci Technologies
● Vapourtec ● Amar Equipment
● Parker Hannifin
• Regional fabricators serve equipment & revamp demand.
● Premex ● ThalesNano ● Pilon Engineering ● AdiChem
Breadth of offering (equipment → licensing & services) →
Key Strategic Moves EXPANSION · JUNE 2026
PARTNERSHIP · LICENSING
KBR — Singapore SAF plant
KBR × Swedish Biofuels AB
Selected by Keppel & Aster for PureSAF licensing and FEED; up to
Exclusive worldwide licensing of PureSAF technology — the
100,000 tons/year capacity.
report's example of selective tech partnerships.
TECHNOLOGY · GREEN AMMONIA
GEOGRAPHIC REACH · MODULAR
Topsoe — Acwa Power, Saudi Arabia
Honeywell UOP — Lanaz, Iraq
Dynamic ammonia synthesis technology for a 4.4 GW green
Modular naphtha hydrotreating & fixed-bed platforming units; first
hydrogen & ammonia project.
UOP modular use in Iraq.
Strategic takeaway: licensors are bundling technology licensing with maintenance & field services for recurring revenue, while fabricators invest in nickel-alloy and modular skid capability — favoring integrated providers as project complexity rises.
Copyright © Next Move Strategy Consulting
Matrix: indicative, based on NMSC archetypes
Thank You Connect with us for in-depth insights and strategic guidance on the Fixed Bed Reactor Market.
Click here for the complete report
→
nextmsc.com/report/fixed-bed-reactor-market-mc5411
Contact Us OFFICIAL WEBSITE
CONTACT NUMBER
www.nextmsc.com
+1 857 758 5017
info@nextmsc.com
Inside the Full Report
2025–35
9
38
Top 10
Analysis period, base year 2025
Segmentation axes sized
Countries covered
Company market shares
• Investors: USD 3.04B absolute opportunity across hydrogen, synthetic fuels and refinery modernization. • Strategy teams: segment, regional and country forecasts to prioritize capacity and market entry. • B2B decision-makers: 20 company profiles, licensing trends and vendor-selection criteria.
Follow Us LinkedIn
YouTube
Copyright © Next Move Strategy Consulting
Twitter / X