Q U A R T E R LY
ALTERNATIVE INVESTMENTS QUARTERLY
SPRING 2015 VOLUME 9 ISSUE 2
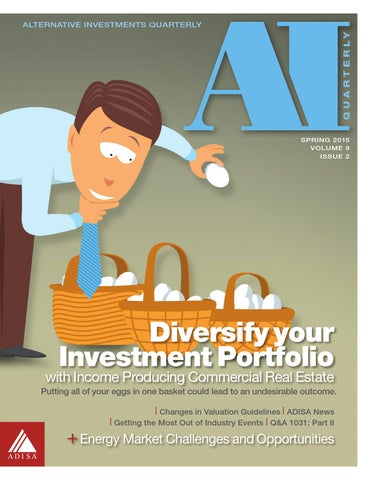
Diversify your Investment Portfolio
with Income Producing Commercial Real Estate
Putting all of your eggs in one basket could lead to an undesirable outcome.
I Changes in Valuation Guidelines I ADISA News I Getting the Most Out of Industry Events I Q&A 1031: Part II
+ Energy Market Challenges and Opportunities
Q U A R T E R LY
SPRING 2015 VOLUME 9 ISSUE 2
ALTERNATIVE INVESTMENTS QUARTERLY
1 Executive Director’s Letter A Tax Issue Important to All of Us
2 ADISA Membership... is growing
ADISA EDITORIAL BOARD Chair I Brandon Raatikka I FactRight, LLC Brandon Balkman I Orchard Securities Linda Dewlaney I Preferred Partnership Services Eric Perkins I Perkins Law PLLC
CONTACT INFORMATION ADISA I 10401 N Meridian St., Suite 202 I Indianapolis, IN 46290
4 Energy Market Presents Challenges and Possible Opportunity
6 Diversify Your Investment Portfolio with Incoming Producing Commercial Real Estate
Direct: 317.663.4180 I Toll Free: 866.353.8422 Fax: 317.815.0871 I E-mail: adisa@adisa.org John Harrison I Executive Director I 317.663.4172 Adam Abubakr I Director of Accounting & Data Systems I 317.663.4177 Tanisha Bibbs I Education & Meetings Coordinator I 317.663.4174 Jennifer Fitzgerald I Director of Marketing I 317.663.4175 Tony Grego I Director of Business Development I 317.663.4173
12 Part 2: 1031 Q&A
14 Changes to Valuation Guidelines for Unlisted REITs and Direct Participation Programs
Design I DesignMark I Susie Cooper
adisa.org
18 Doing Your Due Diligence: How to Get the Most out of Industry Events
Copyright © 2015 By ADISA (Alternative & Direct Investment Securities Association), formerly REISA, formerly the Tenant-In-Common Association.
20
All rights reserved. Readers may copy sections of this publication
ADISA News & Events
for personal use. However, it is a violation of U.S. copyright laws to copy substantial portions of the publication for any reason without permission. The Copyright Act of 1976 provides for damages for illegal copying. If you wish to copy and distribute sections of this publication, contact Jennifer Fitzgerald at jfitzgerald@adisa.org.
Executive Director’s Letter
A Tax Issue Important to Us All By John Harrison, Executive Director, ADISA
Even if your group is not involved in 1031s, they are important to all of us. There are a lot of questions in the air about tax reform and the IRS Section 1031 like-kind exchanges (LKEs), and I’m just back from several meetings in DC with our coalition of associations providing answers to Congress on the great merits of this feature of the tax code. What many in Congress are missing is even an elementary knowledge of the 1031; and we don’t want them to fall prey to agreeing to some curtailment of Section 1031 out of ignorance. Aside from being a boon to the economy at large, Section 1031 is especially important to the alternative investment sector as a whole. Section 1031 has been in the US tax code for almost 100 years as a way to spur continual update and replacement. Sell your old property, buy a like-kind replacement and defer the taxes on the gain. If the provision were gone, folks would simply sit on the land, buildings, and equipment longer to avoid a sudden large tax bill on the gain. This would decrease the overall GDP (to the tune of about $13 billion/year, at least). And, the 1031 is no loophole; the tax gets paid when the replacement asset is sold, or incrementally as the depreciation is foregone, or when an estate is settled. Recently Ernst & Young released a study of how much 1031s mean to the economy.1 ADISA is proud to be a sponsor of the study along with several major associations from agriculture to real estate to equipment.2 The interest in 1031s is growing. In ADISA’s 2015 Spring Symposium alone, we hosted six sessions featuring the best minds out there on the 1031 like-kind exchange: from 1031 exchange foundations to advanced analysis tracking and how 1031s can be used in the energy sector. This topic is big, and those in real estate and others are waking up to its value. According to the Ernst & Young study, the real estate and rental and leasing industries account for approximately 50% of the fair market value of property received in LKEs, most of it in commercial and industrial real estate. Furthermore, almost 15% of non-residential real estate property is connected to LKEs. Several other industries, such as equipment leasing, use 1031 exchanges to aid their growth. Plus, 1031 exchanges only apply to US property, so the advantages stay right here at home. ADISA is proud to boast on the 1031 exchange professionals as one of the most important segments we cover. We hope this well-designed tax treatment is around for another 100 years or more, and we hope you are involved in helping us get the word out to ensure it is! ▲
1—http://www.1031taxreform.com/1031economics/ 2—Study sponsors: ACRA (car rental), ADISA (alternative/direct investment), AED (equipment), ARA (rental), ELFA (equipment leasing), FEA (exchange accommodators), ICSC (shopping centers), ISA (soybeans), NAR (realtors), NAREIT (REITs), NMHC (multifamily housing), RER (real estate)
SPRING 2015 AI QUARTERLY
1
ADISA Membership… is growing
Chart 1
Membership
4000 BD/RIA/RR
Sponsors/Affiliates
3500
Thomas Voekler, ADISA President Kaplan Voekler Cunningham & Frank
3000
ADISA’s membership is approaching
2500
4,000 members and growing. Since 2011, we have nearly tripled in membership, with broker-dealers, RIAs and registered representatives making up approximately 2,000 individuals. (See Chart 1.) Furthermore, our event attendance
2000 1500 1000 500
has seen steady growth. In 2014, ADISA
0
conferences broke attendance records
2011
2012
2013
2014
2015 Q1
from previous years. (See Chart 2.) ADISA connects members directly to key industry experts and decision makers through educational forums,
Chart 2
Event Attendance
sharing timely trends, and valuable tools that help members more effectively conduct business. Our large, diverse events join together industry professionals, experts and leaders through intimate forums, providing timely trends and education. Our focused membership allows for direct and immediate feedback on products, compliance issues and educational needs facing those in the alternative investments industry. ▲
2000 Due Diligence Forum
Spring Symposium
Annual Conference
1800 1600 1400 1200 1000 800
For more information on ADISA membership, please contact adisa@adisa.org or call 866.353.8422.
2
AI QUARTERLY
SPRING 2015
600 400 200 0
2011
2012
2013
2014
REISA is now ADISA
2015 Due
Diligence Forum JULY 14–15, 2015 EDEN ROC HOTEL, MIAMI, FLORIDA
Save the Date adisa.org
SPRING 2015 AI QUARTERLY
3
Energy Market Presents Challenges and Possible Opportunity By Bradford Updike, LLM, JD Mick & Associates, P.C.
4
AI QUARTERLY
SPRING 2015
How far we have come! WTI closed out July 2014 around $102 per bbl oil, with Brent oil pricing of about $108 per barrel (bbl) observed. Over the past three weeks, however, we’ve seen WTI oil prices vacillate between $45 - $50 per bbl, which represents a pricing decrease of about 55% over what we saw last summer. To make matters worse, the energy investment banking community isn’t expecting oil prices to rebound any time soon. Goldman Sachs, widely-seen as one of the most influential banks in commodity markets, sees WTI hovering around the $40 per barrel mark for much of the first half of this year. Based upon a review of oil prices in the futures market, a $60-$65 per bbl pricing level for oil isn’t expected to return until Q2-Q3 of 2016. Not glowing news for an asset sector that raised about $700 million from retail investors in 2014 for drilling and lease development. In absence of a return to better prices, this challenging environment will present immediate challenges to drilling programs across the entire continental U.S. Based upon recent research, areas of the U.S. that are believed to have better economic prospects include the Colorado Niobrara Play and the Permian Basin Bone Spring Play at breakevens of $42-$45 per bbl, with the Wolfecamp and Wolfberry Plays of West Texas also touting break-evens in the low $50s per bbl (field-level economics with no load factored). At the other end of the spectrum, economics within Shale Regions of the Utica, Eagle Ford Shale, and Bakken face greater economic challenges at field-level break-evens of
Over the past three weeks we’ve seen WTI oil prices vacillate between $45-$50 per bbl, which represents a pricing decrease of about 55% over what we saw last summer.
$60 per bbl to $80 per bbl in some areas. As break-evens for retail drilling programs trend 25% to 35% higher than the field-level economics of a play based upon loads and sponsor compensation, drilling sponsors will no doubt be required to sharpen their pencils in 2015 to provide program opportunities with true non-tax economic potential. Short of minimizing the challenges, there are investment opportunities that can fare well in a challenged oil/gas pricing environment. These investment opportunities include income-producing oil/gas assets such as royalties that are acquired at multiples of net cash flows, and investments in undeveloped mineral assets, whose prices per acre are based upon market competition and the public’s perception as to when drilling is likely to occur in the area of interest. Additionally, I would envision that today’s oil/gas pricing environment will present decent private equity investment opportunities, as well-managed up-stream and mid-stream companies will seek to position themselves to either weather the storm or take advantage of opportunities arising from market distress. The big question is, “When will these opportunities present themselves to an eager retail community?” I am reminded by the guidance of an executive of an established royalty program sponsor, who suggested to me back in 2009 that it takes 6-12 months of challenged market conditions for distress to set in and for “market realities” to take hold within the minds of oil/gas asset sellers. Assuming this is true, we are in the top of the first inning of a game that will begin to play out in the later months of 2015 and possibly into 2016. That said, be open-minded and “on the watch” for opportunities in oil/gas programs whose investment strategies sync up with today’s market forces. At the same time, don’t jump into the first royalty programs or 1031 production program “just because.” Patience will be a well-regarded virtue in 2015 and 2016 in the new oil pricing era. ▲
SPRING 2015 AI QUARTERLY
5
Diversify your Investment Portfolio with Income Producing Commercial Real Estate By Glenn R. Mueller, PhD Dividend Capital Group
6
AI QUARTERLY
SPRING 2015
The theory of diversification (Markowitz 1952) suggests that putting all of your eggs in one basket could lead to an undesirable outcome. Therefore, diversifying a portfolio in order to offset periods of decline within one asset class with investments in another should reduce the risk associated with investing in any single asset class. Due to its low, or even negative, correlation to other asset classes, income producing commercial real estate — private real estate in particular— can help offset the risks in investments in other asset classes, thereby potentially strengthening a portfolio overall. Since the global financial crisis of 2007-2009, volatile stock markets have driven investors to be more risk-averse. From January 1926 to April 2009, the S&P 500 Index suffered 10 monthly losses greater than 15.74%, or eight times more often than an investor would expect based on the Normal Distribution of returns assumed by many stock investment strategists and their models. For the 10-year period 2000-2009, a period coined the Lost Decade, the compound annual total return for large cap stocks as measured by the S&P 500 was a negative 0.95%.
Taking a Closer Look at Commercial Real Estate To better understand the
Commercial real estate can help offset the risks in investments in other asset classes, thereby potentially strengthening a portfolio overall.
correlation of commercial real estate to other asset classes, it’s imperative to understand the two primary real estate return indices: NAREIT Equity REIT Index (publicly traded real estate) The FTSE/NAREIT Equity REIT Index is published by the National Association of Real Estate Investment Trusts in conjunction with the international EPRA/FTSE stock index group and is the index of publicly traded Real Estate Investment Trusts (REITs) in the United States. Real estate investment trust returns come from the dividends they pay (REITs must pay out 90% of their taxable income to retain their tax pass-through status like mutual funds) and the change in their stock price. REIT returns include the use of leverage and management’s ability to manage properties as well as purchase and sell properties for a larger overall portfolio profit. NCREIF NPI (private/direct income-producing real estate) The NCREIF NPI, published by the National Council of Real Estate Investment Fiduciaries, is an index of properties owned by institutional investors such as pension funds and endowments. The index is an unleveraged return (e.g., the property’s return is based on the income it generates as though there is no mortgage on the property, as most institutions buy their properties all cash) plus the price appreciation. The price appreciation is based upon quarterly appraisals done on each property and the actual sales price when the property is sold. Because many institutional investors do not use leverage, the return is lower than many private individual investors may experience in their equity investments when they use leverage (via a fixed rate mortgage) on a property.
SPRING 2015 AI QUARTERLY
7
What is Correlation? Correlation measures how returns on two investments move in relation to each other. Measured on a scale of +1 to -1, positively correlated assets tend to move up or down at the same time, while negatively correlated assets tend to move in opposite directions. With perfect positive correlation, a +1 rating (or 100% correlated), two investments always move in the same direction. Conversely, with perfect negative correlation, two investments always move in the opposite direction.
Low Correlation for Diversification Strategy Observing the historic correlations between asset classes can provide some guidance in selecting investments that may perform better when others are lagging. For example, the historic correlation between stocks and publicly traded REITs was below 50% between 1992 and 2006, as seen in Exhibit 1. However, since 2009, the correlation has average about 80%, making public REITs’ diversification benefit less powerful. (Part of this increasing correlation has come from derivative products now available on REITs.)
Exhibit 1
1.0
Rolling 36-month correlation between US stocks and REITs Source: Forbes Magazine Feb 1, 2014 - Correlations using CRSP Total Return & S&P Dow Jones Select REIT reported by Dimensional Fund Advisors.
0.8
0.6
0.4
0.2
0.0
Observing the historic correlations between asset classes can provide some guidance in selecting investments that may perform better when others are lagging.
Jan-14
Jan-12
Jan-10
Jan-08
Jan-06
Jan-04
Jan-02
Jan-00
Jan-98
Jan-96
Jan-94
Jan-92
Jan-90
Jan-88
Jan-86
Jan-84
Jan-82
-0.2
Looking at direct real estate investments using the NCREIF Index, we find that the correlation between the NCREIF and NAREIT indices is a very low 0.09, and thus direct real estate could provide strong diversification benefits in a portfolio with stocks. From Exhibit 2 we can also see that direct real estate has much lower volatility than publicly traded REITs which is another benefit to the investment portfolio. We also note that the return of direct real estate is lower than the publicly traded REITs, but the major reason behind this is that the NCREIF index is an unleveraged return (with no mortgage on the property), while the publicly traded REITs, have historically leveraged their portfolios at close to 50% to achieve their higher return to equity investors. Of course leverage also creates more volatility in the return to equity. An investment vehicle that sits between the two indices is the non-traded REIT, which uses leverage, but is not traded on the stock market. Since non-traded REITs do not price their properties, an annual return comparison is not possible at this point in time. However, a study was done by University of Texas at Austin using Blue Vault Data on Non-Traded REITs—this study found that from inception (beginning in the 1980s) to liquidity event, the 17 non-traded REITs studied had produced an average return of 10.59% (a return in between public & private real estate returns). This supports the premise that leverage can enhance the return to equity.
8
AI QUARTERLY
SPRING 2015
Exhibit 2
Annual Returns for NCREIF Private Real Estate & Public REITs Source: NCREIF Property Index & FTSE/ NAREIT Equity REIT Index
Correlation 0.0889
NAREIT 13.5%
NCREIF 8.9%
50.00 40.00 30.00 20.00 10.00 0.00 -10.00 -20.00 -30.00
2013
2011
2009
2007
2005
2003
2001
1999
1997
1995
1993
1991
1989
1987
1985
1983
1981
1979
1977
1975
1973
1971
-40.00
Bonds Adding bonds to a portfolio also helps portfolio performance by lowering volatility. This suggests that, in the past, even if an investor’s still be providing positive returns or, worst case,
Public Traded ly REITs
performing less negatively. However a recent study by Morgan Stanley shows that when 10-year bond yields fall between the 3% to 6% range for an extended period of time, stock and bond yields become highly correlated (so their prices move in the same direction). This
ds
happened from 2001 to 2011. With the 2013
Bo n
& 14 surge in stock prices and expected rising
oc
ks
6$ range, the diversification benefits of bonds
St
bond yields, the correlations should be watched closely. Thus, if interest rates fall in the 3% to
ct Dire ate Est Real
stocks are underperforming, their bonds may
becomes very low. Unfortunately MOST of the forecasts for bonds expect interest rates to fall in the 3% to 6% range for 2015 through 2017. Additionally as interest rates rise, bond values drop, so investors not only start with low interest rates on their bond investments, but have the potential to lose principal if they must liquidate their bond holdings before the bond matures. It is therefore highly likely that bond returns may not keep up with inflation over the next few years.
SPRING 2015 AI QUARTERLY
9
Exhibit 3
US Treasury Bonds (over 10 yrs) after 1950
US Treasury Bond Yields and Correlation to the Dow Jones Industrial Index
3%
6%
US Treasury Bonds
18 16 14
Source: businessinsider.com, Bloomberg Morgan Stanley Research, 2013.
12 10 8 6 4 2 0
1950
1960
1970
1980
1990
2000
2010
Correlation Coefficient (Dow Jones & US Treasury, every 5 years
1.0 0.8 0.6 0.4 0.2 0.0 -0.2 -0.4 -0.6 -0.8 -1.0 -1.2
1950
1960
1970
1980
1990
2000
2010
Commercial Real Estate Correlation Variance Assets like stocks, bonds and publicly traded REITs, from a valuation perspective, are directly affected by myriad intangible factors such as investor emotions. For example, news in 2011 of turmoil in European markets had a direct impact on investor confidence here in the United States, in turn affecting the valuation of many exchange-traded assets (such as stocks) and the overall strength of the market. Private real estate, which is often represented by the NCREIF Property Index (NPI), however, is valued on factors different from those that can affect publicly traded assets. Private real estate has a low, or even negative, correlation to other asset classes, allowing these investments the potential to help with portfolio diversification. In 2013 NAREIT did a study for institutional investors and found that adding 30% publically traded REITs to a portfolio of direct real estate improved returns and produced a negative return only 1% of the time in the last 35 years. The chart in Exhibit 4 on the following page displays the correlation between six widely used indices across the past ten years. In particular, the NPI, which often serves as a benchmark for private real estate, exhibits consistently low or negative correlation with the other investment indices.
10
AI QUARTERLY
SPRING 2015
Exhibit 4
Real Estate Exhibits Low Correlation to Other Asset Classes (2001–20010) Source: NCREIF, NAREIT, S&P, Russell, Barclays Capital, and MSCI. Clarion Partners Research & Investment Strategy. Note: correlation coefficient among quarterly returns.
NCREIF NPI NCREIF NPI
NAREIT Equity Index S&P 500
Russell 2000
Barclays Agg Morgan Stanley Bond Index EAFE Int’l Stock
1
NAREIT Equity Equity Index
0.29
1
S&P 500
0.23
0.71
1
Russell 2000
0.21
0.77
0.94
1
Barclays Agg Bond Index
-0.17
-0.02
-0.36
-0.39
1
Morgan Stanley EAFE Int’l Stock
0.21
0.69
0.92
0.86
-0.24
1
Summary Income producing commercial real estate has had historically low correlations to the other major asset classes. During both good times and periods of economic turmoil, it has provided diversification benefits to investor’s portfolios. It has grown in popularity with institutional investors over the past five decades (most using an allocation between 5% to 20% of their total portfolio) and has been in the portfolios of wealthy investors as well. Thus, adding private income producing commercial real estate to an investor’s portfolio should help improve performance and lower the long-term volatility of their portfolio returns. ▲
Glenn R. Mueller, Ph.D. is the Real Estate Investment Strategist for Dividend Capital Group. He is also a full professor at the University of Denver’s Franklin L. Burns School of Real Estate and Construction Management and a visiting professor at Harvard University.
SPRING 2015 AI QUARTERLY
11
Question 1: What is the entity of choice for Section 1031 exchange programs post 2007-2011 recession? Starting in late 2007, TIC lending essentially ended. Later, as the recession began to wind down, lenders started making loans to Delaware Statutory Trusts, or DSTs, structured to accomplish tax-deferral under Section 1031. DSTs are widely used today for virtually all fractionalized Section 1031 exchange programs; TICs are no longer a viable structure for 1031 programs. DSTs were formerly known as Delaware Business Trusts and have been in use for many decades. A DST is a flexible, unincorporated entity formed under Delaware law and can be used for many purposes, including real estate ownership. Like Revenue Procedure 2002-22 issued for TICs in 2002, Revenue Ruling 2004-86 issued in 2004 provided much needed guidance on DST qualification for 1031 exchange treatment. To qualify, a DST must satisfy a number of technical requirements and avoid any of the so-called “seven deadly sins”.
Question 2: What was the leading cause for the stratospheric growth in TIC programs “Back in the Day”? Replacement property debt is critical to an exchange program because Section 1031 requires taxpayers to offset debt on the relinquished property with equal or greater debt on the replacement property. Any debt reduction is treated as taxable “boot”. By the time Revenue Procedure 2002-22 was issued in 2002, Wall Street was actively securitizing real estate mortgages into Collateralized Mortgaged Back Securities, or CMBS. Originally, CMBS underwriters were unwilling to finance TIC-owned real estate. Over time, rating agencies established guidelines that helped smooth over most of the rough edges associated with the TIC structure and made TIC-owned real estate much easier to finance in the growing CMBS debt market. In just a couple of years, CMBS became the dominant source of financing for TIC programs, with most TIC properties financed by CMBS debt. To satisfy rating agency requirements for CMBS loans, TIC properties generally were required to use bankruptcy-remote Delaware special purpose entities, or SPEs (typically limited liability companies), to hold title to the TIC interests, use independent trustees/managers to protect bond holders from borrower defaults, and deliver bankruptcy and other legal opinions to help ensure compliance with applicable guidelines. Sponsor incurred substantial additional costs in satisfying these lender requirements; these costs were passed along to the investors in TIC programs. Many people think Revenue Procedure 2002-22 was the primary cause of the phenomenal growth in the TIC industry. Without a doubt, the Revenue Procedure provided much needed tax guidance on the TIC structure. However, the author believes that CMBS financing was the greatest single factor leading to this runaway growth because the TIC industry could not have taken off without billions of dollars of favorable real estate financing.
Question 3: In hindsight, what structural issues may have played a part in the eventual breakdown of the TIC market? How do DSTs differ? The DST structure, when compared to the TIC structure, is more stable during economic volatility by granting the sponsor sole authority to make key decisions instead of requiring unanimous consent of TIC owners. Reserves. TIC programs were structured with substantial reserves intended to be sufficient to carry a property for a reasonable time following one or more potential challenges, for example, loss of a tenant. However, very few TIC programs had sufficient reserves to survive the pernicious, double dip recession of 2007-2011. TIC sponsors agonized over the appropriate amount of reserves to be held in cash in their TIC programs. While prudence dictates holding
12
AI QUARTERLY
SPRING 2015
Part 2: 1031 Q&A with Louis Rogers Capital Square Realty Advisors
sufficient reserves to cover foreseeable needs of a property, it may not be prudent to over reserve because cash on hand essentially has no return to investors and cash funded by investors has the potential to be treated as taxable “boot” in a Section 1031 exchange. Problematic TIC unanimous consent requirement. The problem was exacerbated by the requirement that TIC investors unanimously consent to new or modified leases. One famous illustration involved a well-known sponsor of a large single tenant TIC property where the sole tenant failed; the sponsor found a replacement tenant that had the potential to save the investment but the investors refused to approve a new lease with the replacement tenant. This refusal could have been due to the terms of the new lease being unacceptable, investor passivity (a single investor could block the lease!), an emotional response from investors who were upset over the situation, or possibly even investor ignorance or stupidity. No matter what the reason, unanimous consent is problematic and not easily overcome in time to deal with serious property issues. This could not happen in the DST structure because the sponsor has sole discretion to make property decisions.
Question 4: What is old and what is new? Real estate has not changed; the leading aspects of a sound real estate investment have not changed. A key question then and now—are the tenants going to pay the rent? New positive features of DST programs include tighter legal structure, elimination of TIC unanimous consent requirements, and lower sponsor fees. But the essence of real estate investing has not changed: if the tenants do not pay the rent, the investment is likely to fail. That fundamental proposition is not a tax or legal issue that can be solved with a newfangled legal structure, but is the essence of real estate investing. Structure. Some TIC sponsors emphasized a number of structural “bells and whistles”; clearly, structure is very important but misses the point—even the best legal structure will fail if the tenants do not pay the rent. The underlying real estate investment is the key; target fixation on the nuances of legal structure, while a valid part of prudent underwriting, can be a distraction from the basics of real estate investing. Bottom line: structure is very important but do not overlook the basics—strength of tenants, location, and regional/national economic issues.
Question 5: Have there been any significant breakthroughs in underwriting and due diligence? While we have better computers and real-time market research in 2015, the basics of real estate investing have not changed.
Question 6: With DSTs as the entity of choice for 1031 programs, what are the key attributes of current DST programs? DST interests solve a number of problems experienced by exchangers, especially small investors who frequently struggle with the requirements of Section 1031. The biggest challenges for most exchangers include: sourcing replacement property, conducting customary due diligence, identifying replacement property within 45 days, placing required debt and closing on the replacement property. DSTs solve many of these problems. Reps to the rescue. Instead of actively searching for replacement
property or engaging a realtor, many exchangers enlist the services of a securities representative, or rep, who specializes in the sale of DSTs. Reps are affiliated with FINRA-licensed broker-dealers who have a menu of available DST programs. An investor, working with a rep, can pick and choose from numerous DST programs on the brokerdealer’s platform, making it much easier to locate, identify and close on suitable replacement property in time to satisfy the requirements of Section 1031. Investment Grade Real Estate. DST properties tend to be larger and higher quality than most investors could acquire on their own. Frequently, DST properties are “investment grade,” permitting smaller investors to acquire a higher quality replacement property. Identification. All replacement property must be identified in writing, typically sent to the qualified intermediary or accommodator holding the exchange proceeds. The identification must be sent within 45 days of closing the relinquished property to satisfy Section 1031. Failure to properly identify in time will result in the entire transaction being fully taxable. Due Diligence. Prudence dictates extensive due diligence before committing to a long-term real estate investment. This is problematic in an exchange where the taxpayer only has 45 days to identify all replacement property. Customary due diligence includes the following: Property condition report – independent evaluation of the condition of the property; Phase 1 environmental site assessment – independent review of the environmental condition of the property; Appraisal – independent determination of the fair market value of the property; and Zoning report – confirmation that the property is a proper and lawful use under applicable zoning rules. If the due diligence is expedited, it is possible to obtain the so-called “third party reports” described above in 45 days. Virtually the entire 45-day identification period may be consumed by the due diligence process, which means that taxpayers should have replacement property candidates in sight before closing on their relinquished property. Lender Issues. The due diligence process is further complicated where a lender is involved because the lender will typically order the third party reports and control this aspect of the due diligence process. Lender involvement usually adds time that the taxpayer may not have to spare with only 45 days to identify replacement property. DSTs as turn-key solutions. By comparison, DST programs have already completed the entire due diligence process; all the third party reports are complete and frequently the property has already been acquired by the DST with the necessary loan in place. Sponsors of DST programs source the replacement property in advance: sponsors conduct the due diligence, place the debt, and close on the property. A typical exchanger can easily identify one or more DST replacement properties within the required 45-day period; many exchangers actually close on the DST interests within the 45-day period and never have to identify. The 45-day identification clock starts ticking when the relinquished property is sold for tax purposes (not necessarily the date on the settlement statement), and there are no extensions barring a Presidentially-declared national emergency. What if the timing is bad because the pricing of desirable properties is high, the inventory of available properties is low or the exchanger does not have time to find replacement property? Such an exchanger may fail to qualify because the 45-day identification period
may not be extended. Failure to properly identify in time will result in the entire transaction being fully taxable. What if the exchanger has located several prospective replacement properties and has not decided which property or properties to acquire? Taxpayers may identify three and sometimes more properties using the so-called 200 percent rule or the 95 percent exception to identify more than three properties. However, multi-property identification is problematic for taxpayers who do not have tax counsel on retainer; a number of taxpayers will inadvertently over identify, which results in the entire transaction being fully taxable. Reinvestment of precise equity amount and debt offset. Taxpayers must reinvest the exact amount of net proceeds from the sale of their relinquished property. Any proceeds not reinvested will be treated as taxable boot. Also, taxpayers must offset debt on the relinquished property with an equal or greater amount of debt on the replacement property. These simple rules can create a great deal of mischief in the real world. An exchanger may easily invest the exact amount of net proceeds from the relinquished property in a DST without running the risk of locating a property that is too large or too small. Also, DST interests are encumbered by debt that will offset the debt on the exchanger’s relinquished property. In this way, a DST interest is a simple solution to many of the challenges typically experienced by exchangers. Tax Opinions. In addition, national DST sponsors provide a legal opinion from tax counsel stating that the DST interests should “qualify” for Section 1031 treatment. This is a positive feature of syndicated DST offerings.
Question 7: What has been the reaction of IRS and Treasury to the rise of 1031 exchanges in general and TIC/DST programs? The IRS has consistently supported Section 1031 with guidance, including Revenue Procedure 2002-22, Revenue Ruling 2004-86, and a large number of private letter rulings, technical advice memoranda and the like. Back in 1991, regulations were issued on deferred or delayed exchanges that included the use of a qualified intermediary or accommodator to hold exchange proceeds. This “safe harbor” eliminated concerns about exchangers being taxable due to actual or constructive receipt of sales proceeds. Over time, the cost of using a qualified intermediary or accommodator has declined to the point where even small transactions can be cost-effectively structured 1031 exchanges. As the body of favorable tax guidance grows, a greater number of taxpayers are comforted that a properly structured DST investment qualifies for 1031 treatment and will not subject the taxpayer to an audit. The modern DST is particularly efficient in keeping transaction costs to a minimum, works well for smaller investors, and provides additional comfort of a “should” qualify tax opinion. To twist an infamous quote, “today, even the little people DO NOT have to pay taxes” when they exchange investment property.
Question 8: What do you see for the future of DST programs? The leading 1031 sponsors are very creative in structuring fractionalized real estate offerings to qualify for Section 1031; first TIC offerings and, now, DST offerings. Future structures will evolve and change over time to conform to applicable tax requirements and changing demographics of exchangers (for example, many aging baby boomers seek passive ownership and preservation of principal). From whole properties to TICs, and now from TICs to DSTs, legal structures come and go but sponsors are ever mindful of the importance of qualifying for tax deferral under Section 1031. Large and small real estate investors across the land who may struggle with the technical requirements of Section 1031 are the beneficiaries of these evolving exchange programs. ▲
SPRING 2015 AI QUARTERLY
13
Changes to Valuation Guidelines for Unlisted REITs and Direct Participation Programs By Kathryn I. Tupy, Esq. FactRight, LLC
ACCOUNT STATEMENT
14
AI QUARTERLY
SPRING 2015
On October 10, 2014, the SEC approved FINRA’s proposed changes to NASD Rule 2340 and FINRA Rule 2310 regarding valuations and customer statements. SEC approval means that the proposed rule is consistent with the Security and Exchange Act’s requirements. While separate, these two rules are linked, and affect both broker dealers and their clients. These new rules become effective April 11, 2016.
NASD Rule 2340 Current Rule Currently, NASD Rule 2340 requires broker dealers to send account statements to its customers at least quarterly. These statements must include an estimated value for each non-traded real estate investment trust (ntREIT) and direct participation program (DPP) investment held in the customer’s account. The current rule allows the broker dealer to report the original purchase price as the value of the investment until an estimated value is reported by the issuer, which is required to occur no later than 18 months after an offering closes. The methodology to be used for that valuation is under Rule 2310.
Summary of Changes Under the new SEC-approved rule, the broker dealer must include an estimated per share value, provided that the valuation is reliable, and certain disclosures on a customer account statement. The new rule defines two valuation methodologies that are presumed reliable.
Under the new SEC-approved rule, the broker dealer must include an estimated per share value, provided that the valuation is reliable, and certain disclosures on a customer account statement.
Valuation Methodologies: Net Investment Method This methodology may be used any time from the offering’s effective date until 150 days following the second anniversary of the offering breaking escrow. The “net investment” disclosed by the Issuer Report may be used if it is based: • on the “amount available for investment” percentage in the “Estimated Use of Proceeds” section of the Prospectus; or • on another equivalent disclosure showing the estimated percentage of sales commissions, dealer manager fees, and estimated offering and organization expenses deducted from the aggregate purchase price. • If a range of amounts available for investment is provided, the maximum amount may be used unless the broker dealer has reason to believe that that percentage is unreliable. In that case, the minimum amount must be used. Disclosure using Net Investment Method If this methodology is used, the broker dealer must include a specific disclosure that states “IMPORTANT— Part of your distribution includes a return of capital. Any distribution that represents a return of capital reduces the estimated per share value shown on your account statement.”
SPRING 2015 AI QUARTERLY
15
Appraised Value Method This methodology can be used at any time if an appraised valuation is disclosed in the Issuer Report. The appraised value may be used if: • It is based on valuation of the assets and liabilities of the offering, performed at least annually, by or with the material assistance or confirmation of a third party valuation expert or service; and • Is derived from a methodology that conforms to a standard industry practice. Disclosure using Appraised Value Method This methodology does not have a specific disclosure. However, regardless of the methodology used, the customer account statement must disclose that such securities are not listed on a national securities exchange, are generally illiquid, and even if a customer is able to sell the security, the price received may be less than the per share estimate value provided in the account statement If the broker dealer is able to show that the estimate per share value was not developed in a reasonably reliable way, not created using the methodologies presumed reliable for example, then it does not have to include an estimated per share value for that security on the customer account statement.
Previous proposals contained provisions that would have been difficult to administer, with the potential to create more confusion than necessary. The associations lead the charge in opposition to these provisions, and FINRA listened.
FINRA Rule 2340 Current Rule A broker dealer is not allowed to participate in a public offering of securities in a ntREIT or DPP unless the program’s general partner or sponsor will disclose a per share estimated value, the method used, and the date of the data used to develop the value in its annual investor report.
Summary of Changes Going forward, a broker dealer shall not participate in a public offering of securities in a ntREIT or in a DPP that is not subject to the requirements of the Investment Company Act of 1940 unless the Issuer has agreed to disclose: • a per share estimated value that is developed in a manner reasonably designed to ensure reliability (as described above); • the methodology used to develop that valuation; • the date of the valuation; and • and within 150 days following the second anniversary of the security breaking escrow, an Issuer Report containing a per share estimated value that: • Is based on valuation of the assets and liabilities of the DPP or REIT performed at least annually, by or with a third party valuation expert or service;
• Is derived from a methodology that conforms to a standard industry practice; and
• Is accompanied by a written opinion or report of the issuer, delivered at least annually, that explains the review’s scope, the valuation methodology, and the basis for the reported value.
What Does This Mean? We’ve finally received clarity on future changes to customer account statements that reflect values of ntREITs and DPPs. This process began in 2011, and since that time, FINRA issued several proposals before settling on the changes to Rules 2340 and 2310 as outlined above. If you ever doubt the ability of regulators willingness to collaborate with an industry during the rulemaking process, then look no further than the process leading to these changes as evidence that collaboration is possible. The dialogue between FINRA and leading industry firms and associations clearly shaped how the final rule was written. Previous proposals
16
AI QUARTERLY
SPRING 2015
Now that firm rules are in place we can begin to test both the existing and new product structures against the rules to measure output on client statements. Fortunately, since the industry knew of FINRA’s intention to make changes, a period of “research and development” of new products began in 2011.
contained provisions that would have been difficult to administer, with the potential to create more confusion than necessary. The associations lead the charge in opposition to these provisions, and FINRA listened. Now that firm rules are in place we can begin to test both the existing and new product structures against the rules to measure output on client statements. Fortunately, since the industry knew of FINRA’s intention to make changes, a period of “research and development” of new products began in 2011. The Daily NAV and multi-share class products are a result of this R&D process, and we may see more innovation in the coming months. You can rely on FactRight to continue assisting your firm in understanding new products structures, and how these new rules apply to them. Remember, these rule changes apply only to FINRA member firms, not product sponsors. We advise all broker/dealers to reach out to their non-traded REIT product sponsors and begin a dialogue on how they plan to adjust their product structures in response to the changes. The changes to product structure will continue, and more than ever before, broker/dealers need to be informed and advised on these changes. Here’s why:
Remember, these rule changes apply only to FINRA member firms, not product sponsors. We advise all broker/ dealers to reach out to their non-traded REIT product sponsors and begin a dialogue on how they plan to adjust their product structures in response to the changes.
1. The net investment method of Rule 2340 won’t be an easy, straightforward application, and guidance is needed on many issues. The rule places a burden on firms if they have reason to believe the percentages outlined in the estimated use of proceeds are unreliable. Firms cannot “set it and forget it.” BDs need to maintain constant oversight on the actual use of proceeds if using the net investment methodology for statement valuations. 2. The appraisal methodology provision is vague, but for good reason. When valuing shares, sponsors may use a methodology that conforms to “standard industry practice” when valuing shares of a ntREIT. Uncertainty remains about what qualifies as “standard” when valuing these shares. This approach is needed, however, to cover the variety of assets that may be acquired by ntREITs. 3. Advisors NEED information and education on the coming changes. The new rule will impact ntREITs and DPPs upon its effective date and does not have a “grandfather clause” for products that began raising capital prior to that date. Educational initiatives should begin in 2015. ▲
SPRING 2015 AI QUARTERLY
17
Doing Your Due Diligence; How to Get the Most out of Industry Events By Maksim Netrebov Maks Financial Services
A few short years ago, I made it to my first ADISA Annual Conference. While I was not new to non-traded investments, I was there in a new capacity, as the head of an RIA firm, looking at how REITs, BDCs and MLPs can fit into my practice. More importantly, I was there to learn how the sponsors and their offerings work within a fiduciary practice. When I was asked to contribute the perspective of a smaller RIA, I knew it was a great opportunity to help others who are just getting their feet wet in this investment space. Furthermore, if it helps product sponsors understand the thoughts and process of an
HELLO my name is...
RIA, all the better. So where do you begin? ADISA of course! The Annual Conference is a fantastic place to meet the players in the industry, get a 30,000 foot view of the industry, and to fill up the list of sponsors to follow up with after the conference. For someone new to the space, the best takeways are really the connections and initial conversations. Another organization from which I get a lot out of is The National Due Diligence Alliance (TNDDA), which hosts a conference three times a year where you can take the initial dive into the sponsor offerings in a well-paced agenda. I believe the real
18
AI QUARTERLY
SPRING 2015
value of TNDDA is the closed-door discussion that
What makes these meetings valuable is the opportunity
occurs after the sponsors present. You can have open
to ask your questions and to hear the unscripted
discussion about the sponsors and their openings, by
responses. Most of all, it is an opportunity to meet the
due diligence professionals. Those discussions have
people and to see the process happening right there and
the ability to really make you question your thoughts
then. Similarly, if you go to the store to see and feel an
and preconceived notions you might have of various
item before purchasing, onsite due diligence meetings
offerings. This process can be really constructive to
should serve the purpose to address any issues you may
your due diligence process. To quote Roger Wadsworth,
have thought of throughout your due diligence process.
National Director of TNDDA, “It is where the discussion about the selling agreement takes place.”
You can also top that first hand due diligence with your own experiences of visiting the properties. For instance,
Similar to TNDDA, you will have conferences
for one offering that we were reviewing, I drove down to
organized by due diligence and law firms in the industry.
see the properties that were within an hour or two of my
While I have not attended all of them, the few that I did
office, or were along the way on a road trip. A colleague
attend, my takeaways were similar to TNDDA.
of mine shared a technique he performs with multi-family
For RIAs in particular, there is Summa IQ, which
properties where he will call the leasing office of the
follows a similar process to TNDDA. The difference is,
apartment complex to hear their story. The information
instead of 20+ sponsors with 25 minutes each, there are
received from those first hand experiences will tell you
maybe five to six sponsors with at least an hour deep
more about the sponsor and the offering than the offering
dive into each offering. It is an RIA-centric organization,
documents ever can.
so the sponsors who present typically have an offering
Throughout the year there are numerous events in
which is truly RIA-friendly, and not just their broker-dealer
the industry that you can devote your time to. As a
offering with the registered rep commission stripped out.
smaller broker-dealer or as an RIA, I do not believe
My next step is to look at the third party due diligence
it should be a question of which do you attend. All of
reports that are offered. You can get these reports, all of
the organizations and sponsor events bring something
which are well done, by either contacting the sponsors or
to the table. The challenge is balancing your time,
going directly to the companies doing the reports.
particularly since, most likely, the entire process from
In these reports I look for affirmation of my initial thoughts as well as findings from our own due diligence. Furthermore, I look very carefully at any red flags and follow up items that were brought up in those reports.
discovering the sponsor, doing the due diligence, and signing the selling agreement, all falls on you. As the saying goes, proper prior planning prevents poor performance. Have a plan for your due diligence
Lastly, after initial meetings with the sponsors at the
process and stick with it. Having goals and expectations
ADISA conferences, after the initial looks at the various
for all the industry events will protect your time and
due diligence conferences, and after taking a look at
your sanity as you dive head first into the world of non-
the reports, I will sign up and go to the due diligence
traded and alternative investments.
meetings offered by the sponsors.
Welcome! Come in, the water is warm. ▲
SPRING 2015 AI QUARTERLY
19
ADISA
News
Events
ADISA News & Events The following pages will update you on Regulatory Updates, our 2015 Spring Symposium Highlights, as well as the upcoming 2015 Conferences. ➤
Economic Impact of Repealing IRC Section 1031 Synopsis of Ernst & Young Study Last October, ADISA’s board of directors voted to support the IRS Section 1031 advocacy efforts. The Real Estate Roundtable and Federation of Exchange Accommodators (FEA) commissioned a study, prepared by Ernst & Young, to show the positive impact of the Section 1031 exchanges have had in the United States. Background: Section 1031 of the Internal Revenue Code permits deferral of capital gains and recapture tax on business or investment property that is exchanged for like-kind business or investment property rather than sold for cash. Like-kind exchanges are relied on extensively by small businesses and taxpayers in multiple industries, including real estate, transportation, equipment / vehicle rental and leasing, and construction. These rules are based on the tax policy that it is unfair to tax a “paper” gain when there is continuity of investment in like-kind property; i.e. there has been no “cashing out” by the taxpayer. Section 1031 encourages transactional activity by making it more cost effective to relocate to larger or more appropriate sites and to exchange assets for those that better meet business needs. Ernst & Young conducted an analysis of the macroeconomic impact on the U.S. economy of recent tax reform proposals to repeal §1031 like-kind exchanges and documented these findings in a March, 2015 report titled Economic Impact of Repealing LikeKind Exchange Rules.
20
AI QUARTERLY
SPRING 2015
Major Findings: Repeal of §1031 would subject businesses to a higher tax burden on their transactions, resulting in longer holding periods (the “lock-in” effect), greater reliance on debt financing and lessproductive deployment of capital in the economy. The cost of capital would be increased, discouraging investment, entrepreneurship and risk-taking, and slowing the velocity of investment. Repealing like-kind exchange rules would slow economic growth, shrink investment, and ultimately reduce gross domestic product (GDP), even if the revenue savings were used to lower tax rates. This negative economic impact would be most concentrated in those industries that rely heavily on like-kind exchanges, such as: real estate, construction, truck transportation, equipment / vehicle rental and leasing. The total effect of §1031 repeal on the ten most impacted industries would be a drop in annual GDP of $26 billion (0.14% of total GDP, see Table 1). The total impact on overall U.S. GDP would be a drop of $8.1 billion each year (Table 2). Repeal of Section 1031 Does Not Meet the Goals of Tax Reform: The stated goals of tax reform are economic growth, fairness, efficiency, revenue neutrality, competitiveness, and investment, leading to job creation and a stronger economy. The study concludes that repeal of §1031 would be at cross-purposes with these goals. It would adversely impact the U.S. economy by discouraging investment, causing a reduction in GDP, a contraction in the economy, and would unfairly burden certain industries and taxpayers. Moreover, lower GDP results in lowered tax revenue, thus, repeal of §1031 would not be revenue neutral. ▲
Important Comparisons Estimated tax revenue to Treasury over 10 years
Estimated reduction of overall U.S. GDP over 10 years
(repeal score for years 2014-2023 by Joint Committee on Taxation)
(EY Study)
$40.9 billion
$61- $131 billion
Table 1. Long-run impact of 1031 repeal on economic growth ($billions) of 10 most impacted industries Table 1. Like-kind Annual of Annual Annual Long-run impact of 1031 repeal on economicAnnual growth ($billions) 10 most impacted industries Loss Industry Industry trade contractors Specialty Non-residential real estate Specialty trade contractors Truck transportation Non-residential real estate Residential real estate Truck transportation Heavy and civil engineering Residential constructionreal estate Heavy and civil engineering Air transportation construction Commercial and industrial Air transportation machinery and equipment Commercial and industrial rental and leasing machinery and equipment Oil and gas extraction rental and leasing Automotive equipment rental Oil and gas extraction and leasing Automotive equipment of rental Pipeline transportation and leasing natural gas Pipeline transportation of natural10gas Total, selected industries Total, 10 selected industries
exch. property as % of subLike-kind industry exch. property capital as % of stock subindustry capital 16.0% stock
Direct Annual GDP Direct impact GDP impact -$2.3
Indirect Annual GDP Indirect impact GDP impact -$2.7
Induced Annual GDP Induced impact GDP impact -$3.0
Total Annual GDP Total impact GDP impact -$8.0
percentage Loss of total percentage GDP of total GDP ||||||||||||||||||||||||||||||||||||||||||||
-$4.7 -$8.0 -$4.3 -$4.7 -$3.3 -$4.3 -$2.6 -$3.3
|||||||||||||||||||||||||| |||||||||||||||||||||||||||||||||||||||||||| ||||||||||||||||||||||| |||||||||||||||||||||||||| |||||||||||||||||| ||||||||||||||||||||||| |||||||||||||| ||||||||||||||||||
12.4% 15.2%
-$0.4 -$0.8
-$0.3 -$0.9
-$0.3 -$1.0
-$1.0 -$2.6
||||| ||||||||||||||
12.4% 15.4%
-$0.4 -$0.3
-$0.3 -$0.2
-$0.3 -$0.2
-$1.0 -$0.7
||||||||
15.4% 5.7%
-$0.3 -$0.3
-$0.2 -$0.1
-$0.2 -$0.1
-$0.7 -$0.6
||||||
15.4% 5.7%
-$0.2 -$0.3
-$0.1 -$0.1
-$0.1 -$0.1
-$0.4 -$0.6
|||||
15.4% 21.5%
-$0.2 -$0.1
-$0.1 $0.0
-$0.1 -$0.1
-$0.4 -$0.3
|||
21.5%
-$0.1 -$11.6
$0.0 -$6.7
-$0.1 -$7.6
-$0.3 -$26.0
|
-$11.6
-$6.7
-$7.6
-$26.0
14.8% 16.0% 35.2% 14.8% 14.8% 35.2% 15.2% 14.8%
-$3.3 -$2.3 -$1.5 -$3.3 -$2.4 -$1.5 -$0.8 -$2.4
-$0.7 -$2.7 -$1.3 -$0.7 -$0.5 -$1.3 -$0.9 -$0.5
-$0.7 -$3.0 -$1.6 -$0.7 -$0.5 -$1.6 -$1.0 -$0.5
Note: The 10 sub-industries selected for this analysis include sub-industries with like-kind exchange property of at least 5.0% of subindustry capital stock, and with at least a 1.0% share of economy-wide capital stock. Long-run impacts are scaled to the 2013 US Note: The 10 sub-industries selected includeSource: sub-industries with like-kind exchange property of at least 5.0% of subeconomy. Figures may not appear to for sumthis dueanalysis to rounding. EY analysis. industry capital stock, and with at least a 1.0% share of economy-wide capital stock. Long-run impacts are scaled to the 2013 US economy. Figures may not appear to sum due to rounding. Source: EY analysis.
Table 2. Long-run effect of repeal on GDP each year under revenue-neutral reduction in the corporate income tax rate Table 2. and alternative policy scenarios Long-run effect of repeal on GDP each year under revenue-neutral reduction in the corporate income tax rate Annual GDP Annual and alternative policy scenarios change GDP Scenario
Scenario Increased revenue used to reduce corporate income tax rate Increased revenue used to reduce corporate income tax rate revenue used to increase government Increased spending Increased revenue used to increase government spending revenue used to reduce business sector Increased taxes Increased revenue used to reduce business sector taxes
Annual GDP ($billions) change ($billions) -$8.1
Annual change (%) GDP change (%) -0.04%
|||||||||||||||||||||||||||||||||||||||||||||
-$8.1 -$13.1
-0.04% -0.07%
||||||||||||||||||||||||||||||||||||||||||||| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
-$13.1 -$6.1
-0.07% -0.03%
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||| |||||||||||||||||||||||||||||||||
-$6.1
-0.03%
|||||||||||||||||||||||||||||||||
Note: Long-run dollar figures are scaled to the 2013 US economy. Source: EY analysis. Note: Long-run dollar figures are scaled to the 2013 US economy. Source: EY analysis.
SPRING 2015 AI QUARTERLY Section 1031 Like-Kind Exchange Coalition Synopsis of EY Study 3-13-15
21
“These new rules provide an effective, workable path to raising capital that also provides strong investor protections,” said SEC Chair Mary Jo White. “It is important for the Commission to continue to look for ways that our rules can facilitate capital-raising by smaller companies.”
REGULATION A+ UPDATE SEC Adopts Rules to Facilitate Smaller Companies’ Access to Capital New Rules Provide Investors with More Investment Choices On March 25, 2015, the Securities and Exchange Commission adopted final rules to facilitate smaller companies’ access to capital. The new rules provide investors with more investment choices. The new rules update and expand Regulation A, an existing exemption from registration for smaller issuers of securities. The rules are mandated by Title IV of the Jumpstart Our Business Startups (JOBS) Act. The updated exemption will enable smaller companies to offer and sell up to $50 million of securities in a 12-month period, subject to eligibility, disclosure and reporting requirements. “These new rules provide an effective, workable path to raising capital that also provides strong investor protections,” said SEC Chair Mary Jo White. “It is important for the Commission to continue to look for ways that our rules can facilitate capital-raising by smaller companies.” The final rules, often referred to as Regulation A+, provide for
22
AI QUARTERLY
SPRING 2015
two tiers of offerings: Tier 1, for offerings of securities of up to $20 million in a 12-month period, with not more than $6 million in offers by selling security-holders that are affiliates of the issuer; and Tier 2, for offerings of securities of up to $50 million in a 12-month period, with not more than $15 million in offers by selling securityholders that are affiliates of the issuer. Both Tiers are subject to certain basic requirements while Tier 2 offerings are also subject to additional disclosure and ongoing reporting requirements. The final rules also provide for the preemption of state securities law registration and qualification requirements for securities offered or sold to “qualified purchasers” in Tier 2 offerings. Tier 1 offerings will be subject to federal and state registration and qualification requirements, and issuers may take advantage of the coordinated review program developed by the North American Securities Administrators Association (NASAA). “ADISA is excited to continue looking into this groundbreaking rulemaking proposal, which we hope provides a meaningful capital formation avenue for our members and the alternative investment industry,” said ADISA President Tom Voekler. The rules will be effective 60 days after publication in the Federal Register. For more information, and to view the Regulation A+ Fact Sheet, visit http://www.sec.gov/news/pressrelease/2015-49. html#. VRw2QfnF9Jd. ▲
REISA is now ADISA
2015 Annual
Conference & Trade Show
OCTOBER 12 –14, 2015 THE COSMOPOLITAN LAS VEGAS
Save the Date adisa.org
SPRING 2015 AI QUARTERLY
23
2015 ADISA Spring Symposium
2015 Spring
Symposium MARCH 22–24 HYATT REGENCY NEW ORLEANS
ADISA’s Spring Symposium, held at the Hyatt Regency New Orleans, was a tremendous success with close to 600 attendees who took advantage of an educational program filled with more than 50 informative sessions. Broker-dealers, RIAs, registered representatives and financial advisors, who comprised about one-third of attendees, were able to network with the nearly 50 exhibitors in the Exhibit Hall. Session topics included: 1031 exchanges A fee-based investment boot camp Advisor marketing strategies Crowdfunding Regulatory updates FINRA 15-02 Energy products Due diligence Private equity investments Economic trends JOBS Act In addition, each year, a session from one of the previous year’s conferences is honored as the Best Panel. The Best Panel for 2014 was awarded to “Interval Funds,” with Randy Anderson as the moderator, and Ray Lucia, Terry Davis and Josh Hoffman as panelists.
ADISA President Tom Voekler presents the Best Panel for 2014 to Josh Hoffman and Randy Anderson Following such a successful conference, ADISA is excited to continue this momentum in the alternative investment industry with our 2015 Annual Conference, Oct. 12-14, at the Cosmopolitan Las Vegas, and (for broker-dealers/RIAs only) our Due Diligence Forum, July 14-15, at the Eden Roc Hotel in Miami, Fla. ▲
24
AI QUARTERLY
SPRING 2015
Attendees enjoy the conference and New Orleans at ADISA’s 2015 Spring Symposium.
Future 2015 ADISA Conferences 2015 Due Diligence Forum July 14-15 Eden Roc Hotel Miami, FL
2015 Annual Conference & Trade Show October 12-14 The Cosmopolitan Las Vegas
SPRING 2015 AI QUARTERLY
25
10401 North Meridian Street Suite 202 Indianapolis, IN 46290
ADISA 2015 Annual Conference & Trade Show October 12-14 The Cosmopolitan Las Vegas
adisa.org
SAVE THE DATE