WA Commercial Investment Report
Financial Year Review 2025/26

WA Commercial Investment Report
Financial Year Review 2025/26
The Western Australian commercial property sector recorded a marked slowdown in 2025/26, with total transaction volumes falling 34.4% to $3.19 billion as every asset class recorded a decline on the previous year.
Three interest rate rises through 2026, following the 2025 cutting cycle, extended due diligence periods across the board, with buyers taking longer to transact rather than stepping back from the market altogether.
Industrial remained the largest contributor at $1.2 billion, down 9.1%, with WA’s pricing advantage relative to Sydney and Melbourne continuing to draw interstate interest even as the pace of deal making slowed.
Retail’s $813.4 million result, down 62.1%, reflects a high base from the previous year’s one-off large centre sale rather than a genuine pullback, with convenience and neighbourhood centres continuing to attract solid interest. Office recorded $513.9 million, a comparatively modest 5.0% decline, with limited new supply and rising replacement costs opening a genuine opportunity in premium and near-new stock priced below what new construction can now achieve.
Hotel ($233.9 million), development sites ($331.9 million) and medical/childcare ($98.5 million) all softened, the latter reflecting oversupply and staffing pressures in childcare specifically rather than the broader alternative sector. The Budget’s negative gearing and SMSF changes are expected to redirect private capital toward commercial property over time, though WA’s private investor and syndicate-dominated market continues to move at its own, more deliberate pace.
The commercial office sector recorded transaction volumes of $513.9 million in 2025/26, a 5.0% decline on the previous year but effectively a holding pattern given the scale of movement seen elsewhere in the market.
Activity remained concentrated among the private sector, with buyers taking more time to satisfy themselves on covenant strength and building condition before committing, and settlement timeframes lengthening as a result.
The urgency that characterised the market when rates were falling has given way to a more considered approach, though buyers remain genuinely active rather than sitting on the sidelines.
The more interesting story for office lies in supply economics rather than transaction volume. With limited new stock in the pipeline and replacement costs continuing to climb, any new construction will need to achieve rents well above current benchmarks to make the development feasible. This dynamic is opening a genuine opportunity in premium and high-quality stock, where existing buildings priced below replacement cost offer a rare entry point that new development simply cannot match at today’s construction pricing. For patient capital prepared to look through the current vacancy overhang, this gap between replacement cost and acquisition cost is a major opportunity for buyers.
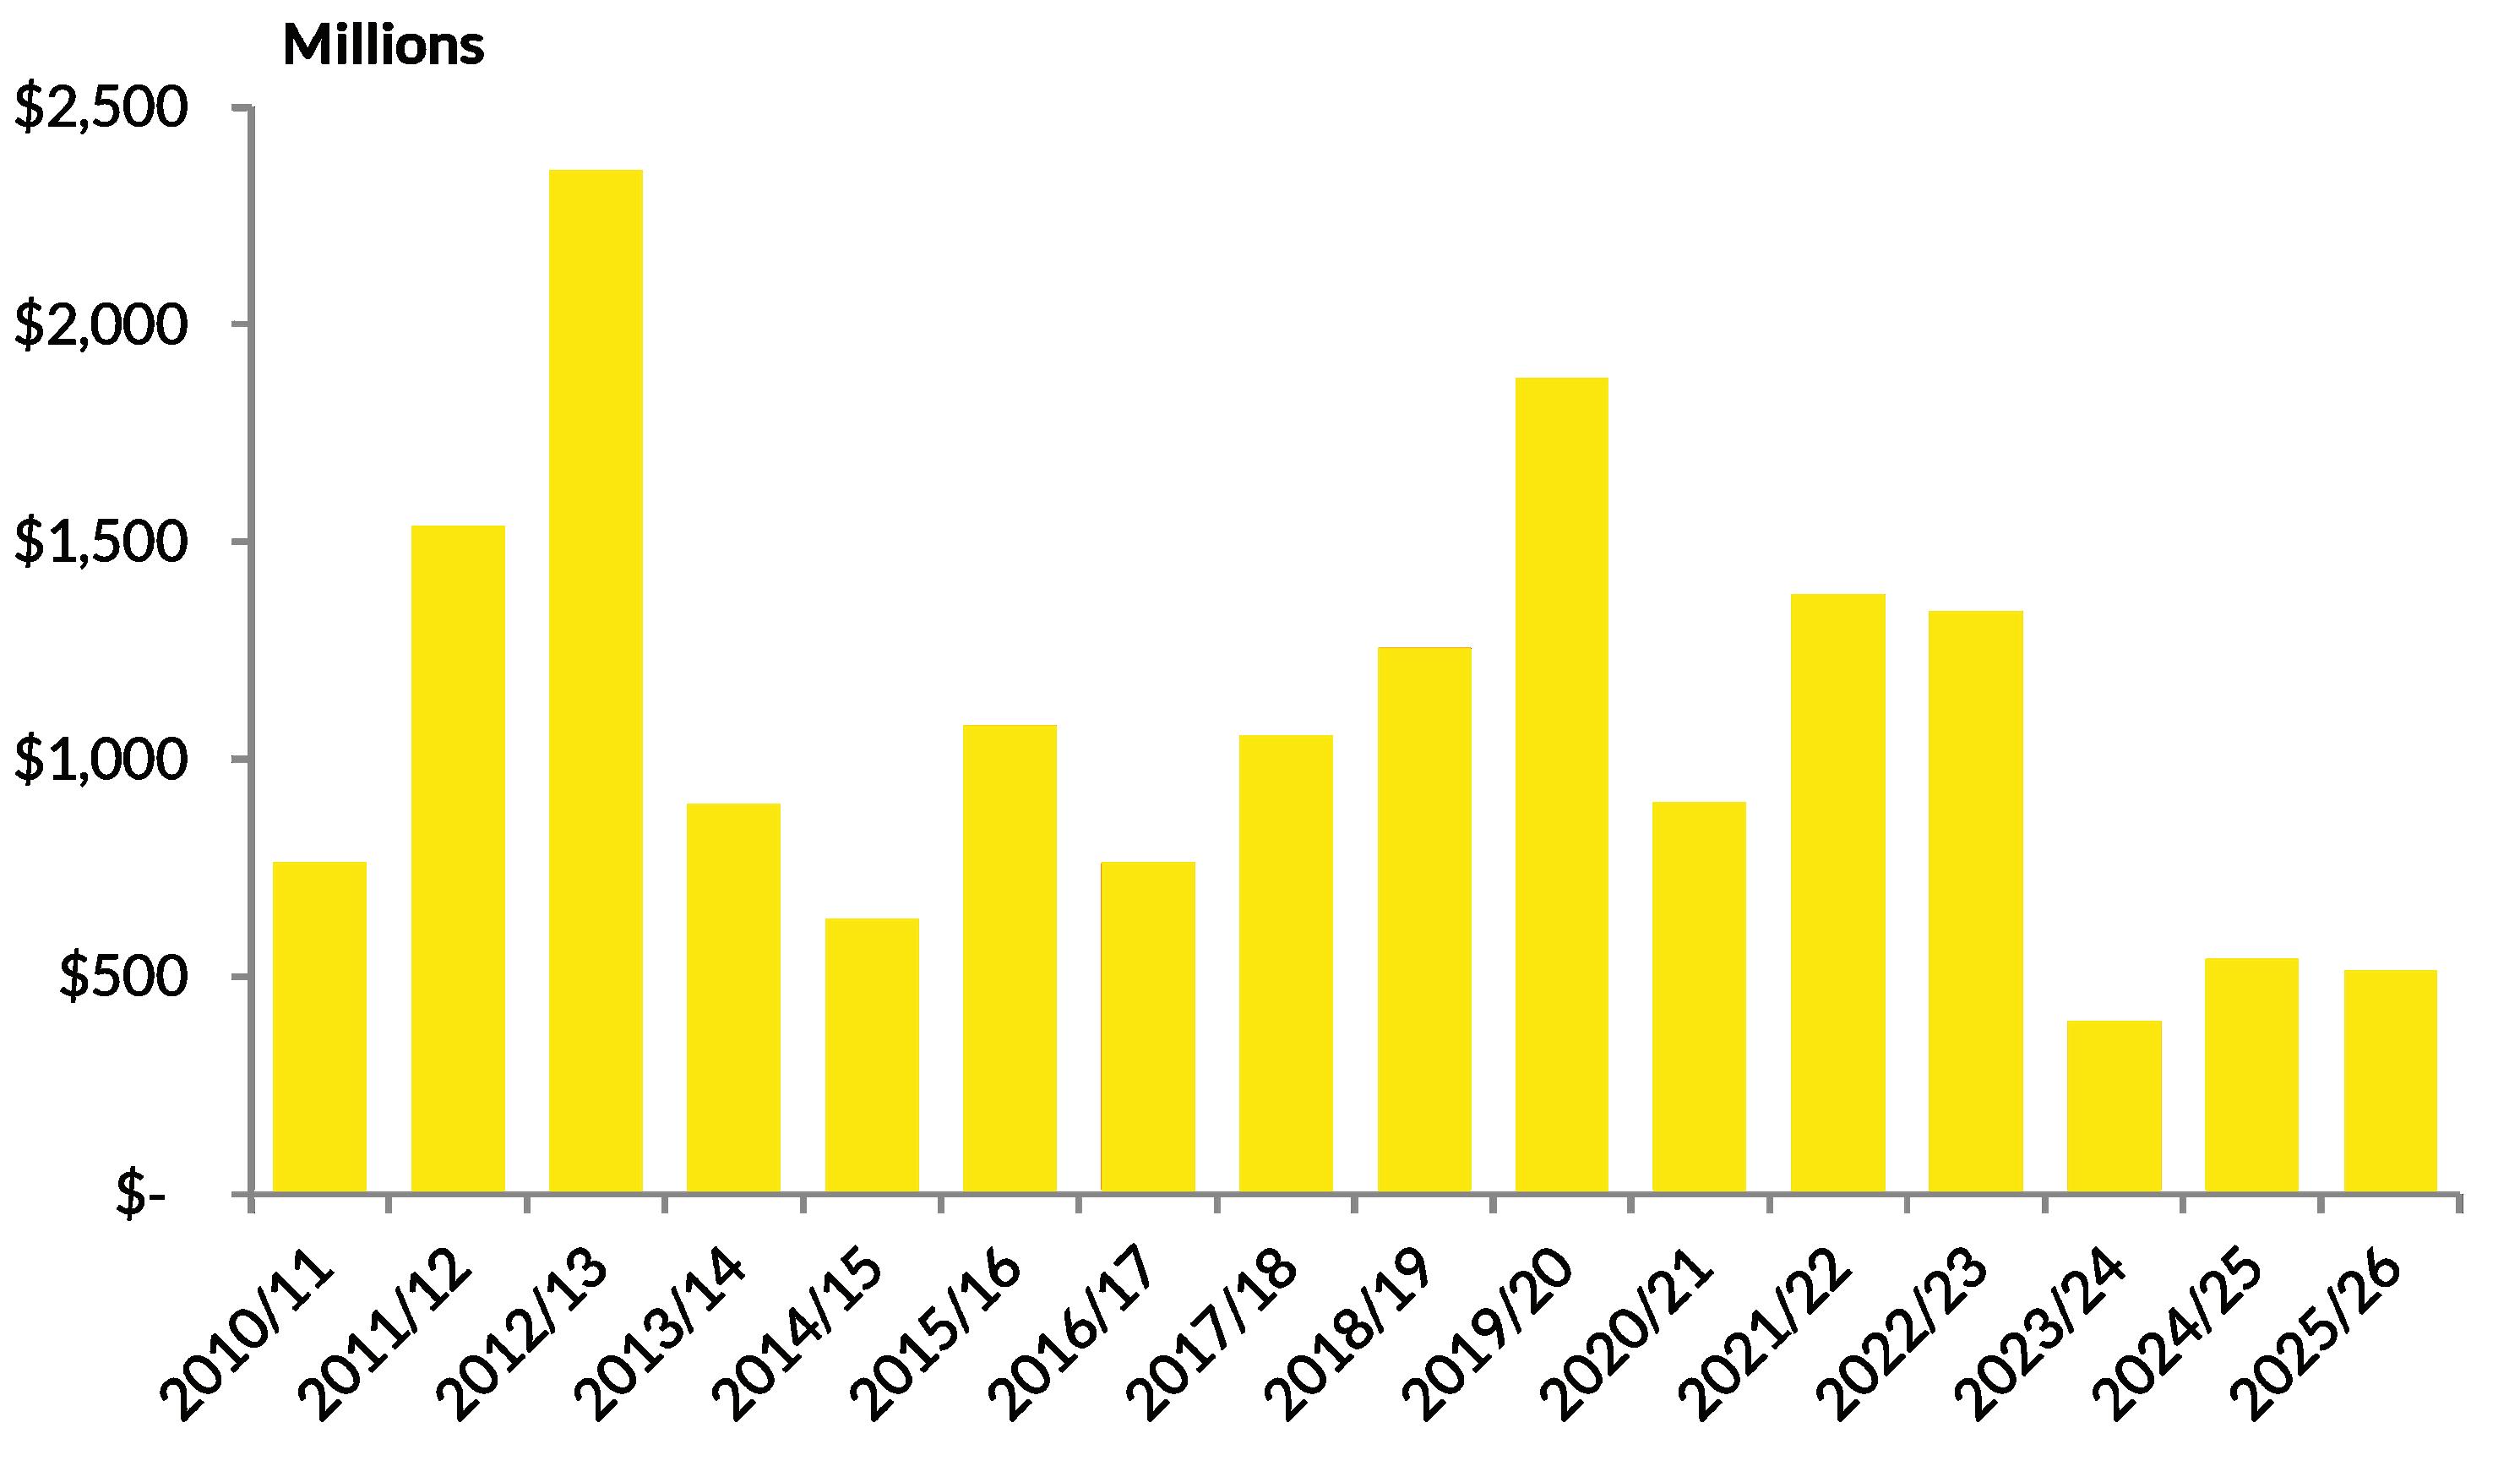
Source: RWC WA, Real Capital Analytics
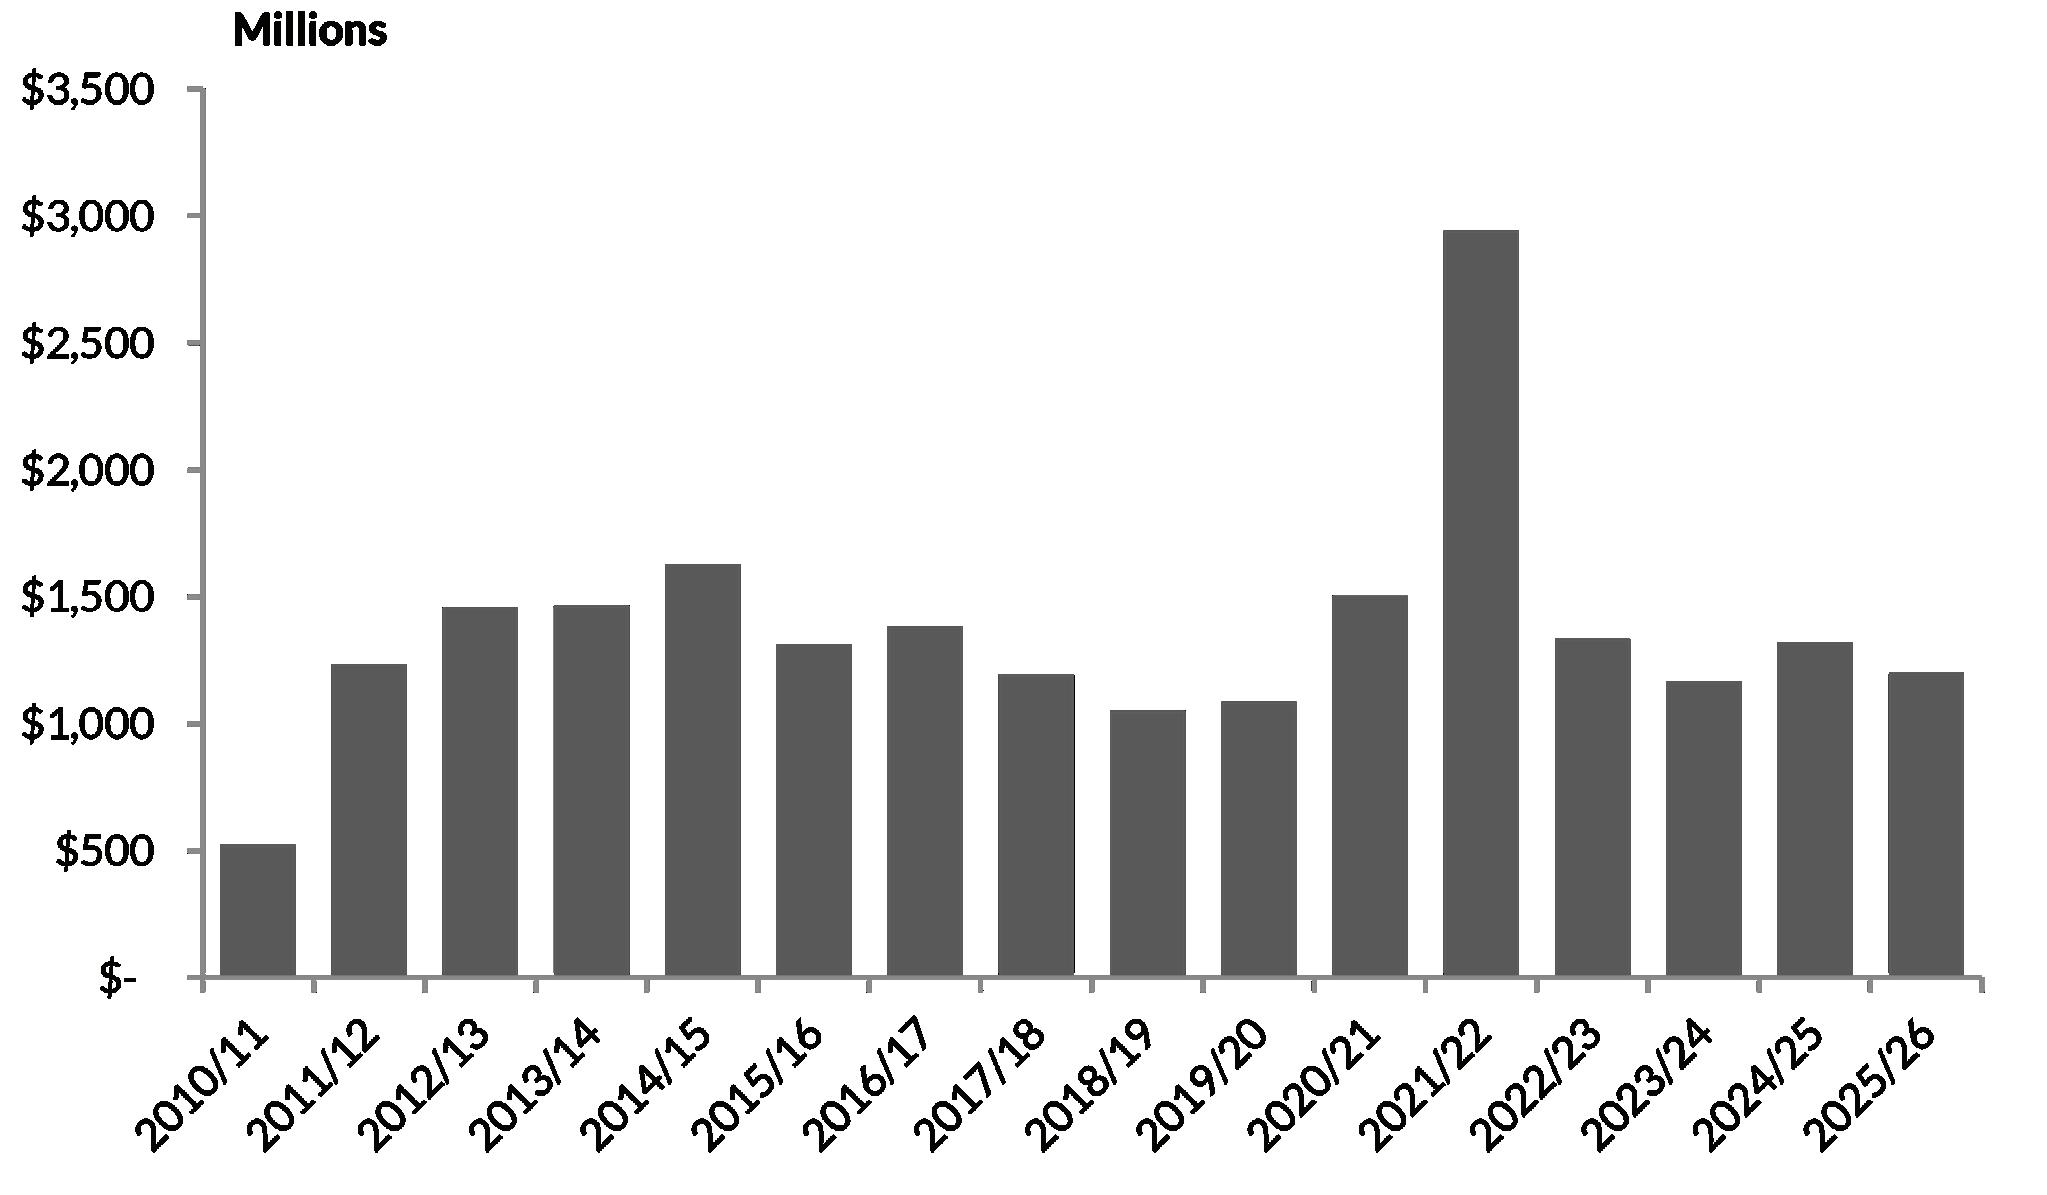
Industrial recorded $1.2 billion in transactions during 2025/26, down 9.1% on the previous year but remaining the largest single contributor to WA’s commercial transaction volume by a wide margin. Demand fundamentals continue to hold up well, with yields still attractive to private investors and owner-occupiers continuing to be active participants alongside private groups.
Western Australia’s pricing advantage relative to the east coast is becoming an increasingly important part of the industrial story. With Sydney and Melbourne industrial assets trading at a premium, WA’s comparatively affordable entry points are drawing renewed attention from interstate buyers, even as deal timeframes have stretched and negotiations take longer to conclude.
The Budget’s changes to negative gearing on established residential property, combined with the removal of SMSF borrowing capacity for residential purchases, are expected to redirect some private capital toward commercial property, and industrial stands to be a primary beneficiary given its relative affordability and straightforward income proposition. Self-managed super funds in particular may increasingly look to commercial property, including industrial, as an alternative structure now that the residential borrowing pathway has closed. This shift will take time to materialise given the deliberative mood among buyers, but the structural incentive is now clearly in place.
Source: RWC WA, Real Capital Analytics
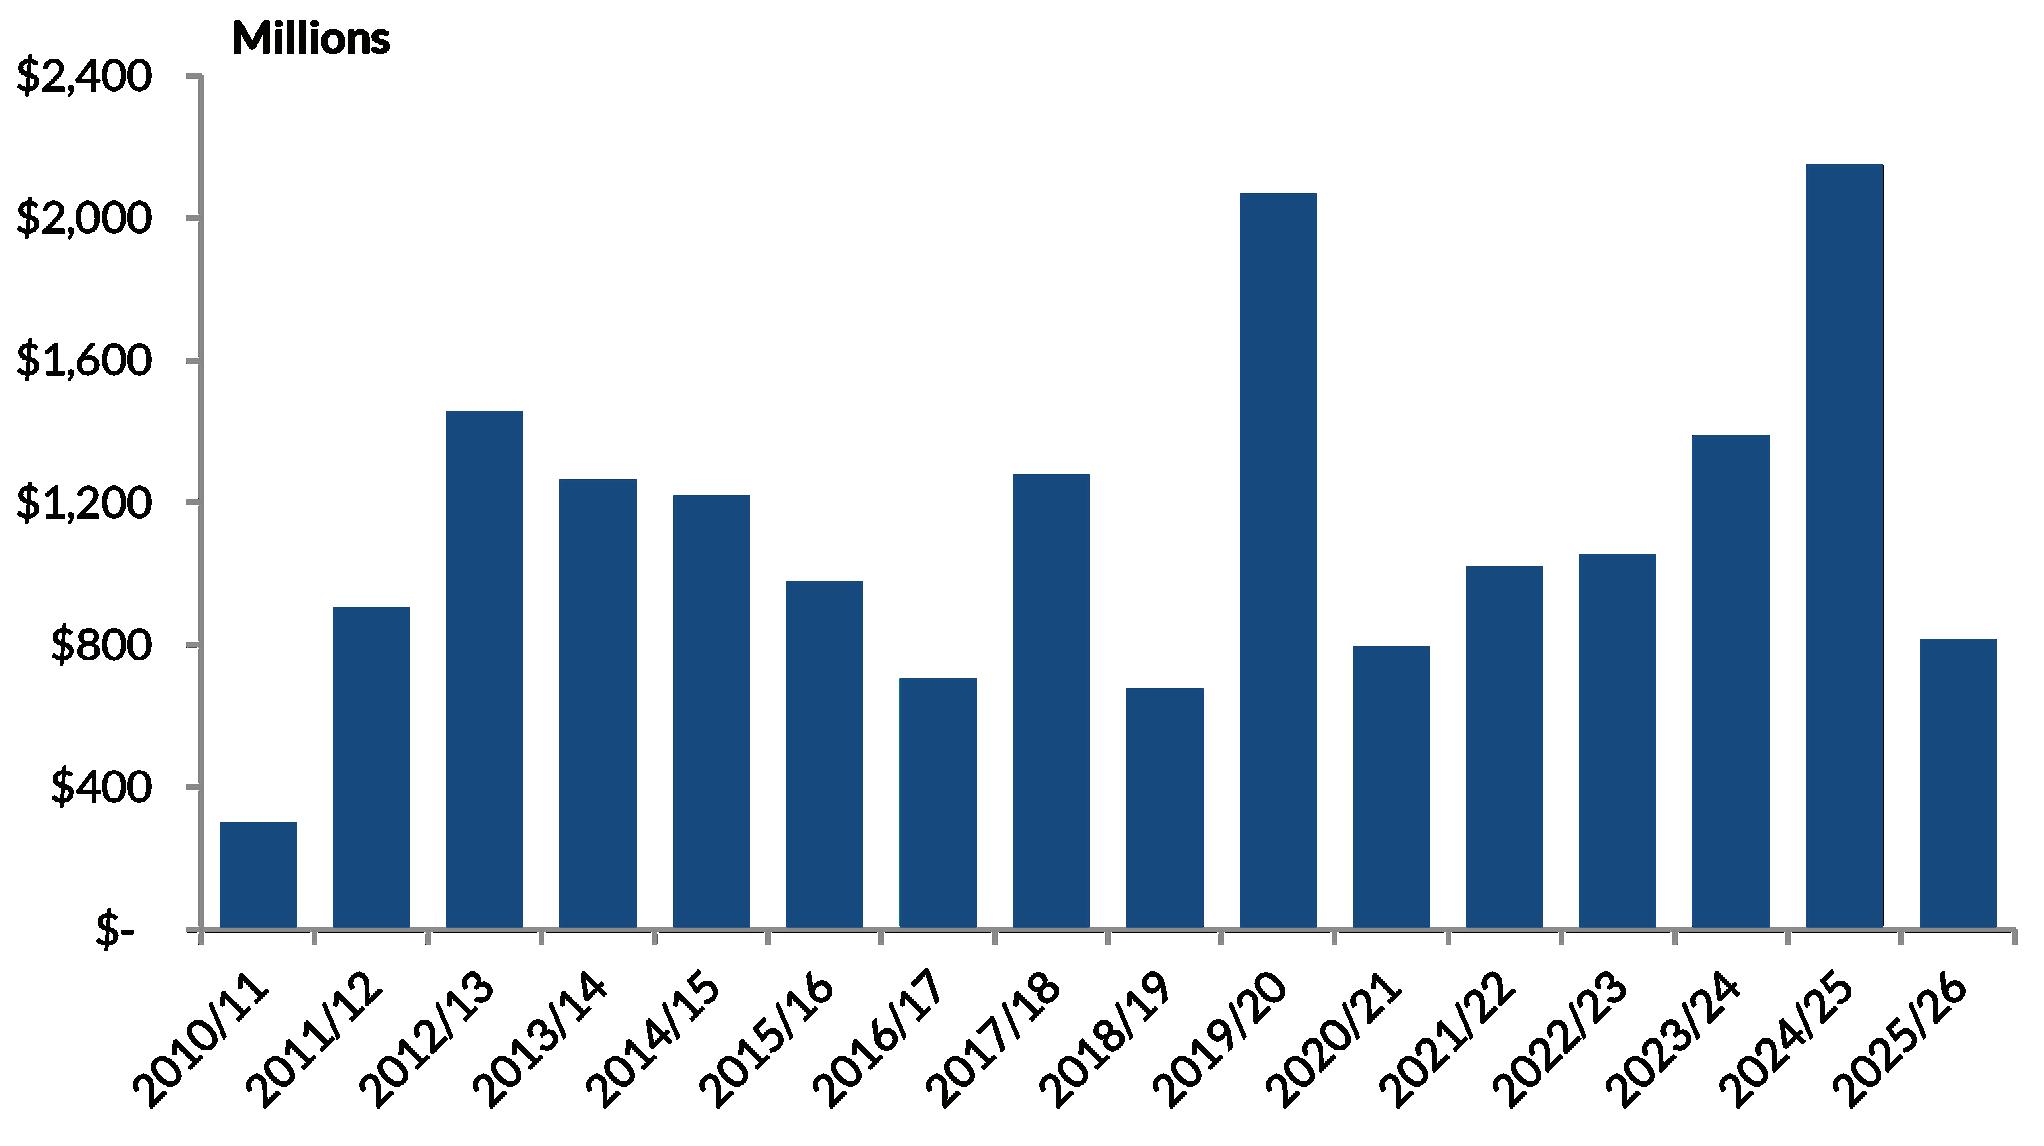
Retail transaction volumes fell sharply to $813.4 million in 2025/26, down 62.1% on the previous year’s exceptional result, which had been elevated by one-off large centre transactions.
Viewed against a more typical baseline, retail activity has held up reasonably well, with genuine ongoing interest in convenience and neighbourhood centre formats.
Population growth continues to underpin retail fundamentals, and this remains most visible at the neighbourhood and convenience end of the market, where supermarket-anchored and essential services-based centres continue to attract buyer interest. Limited new supply across most retail formats is supporting this demand, with investors recognising that well-located centres serving growing catchments offer a defensive income profile that larger discretionary retail assets cannot match in the current environment.
Private investors and syndicates remain the dominant buyer group in WA’s retail market, consistent with the broader ownership profile across the state’s commercial sector, though buyers are applying greater scrutiny to lease covenants and tenancy mix before committing. Looking through the headline decline, the underlying retail story is one of continued, if slower, demand for well-positioned convenience assets rather than a genuine pullback in investor appetite.
Source: RWC WA, Real Capital Analytics
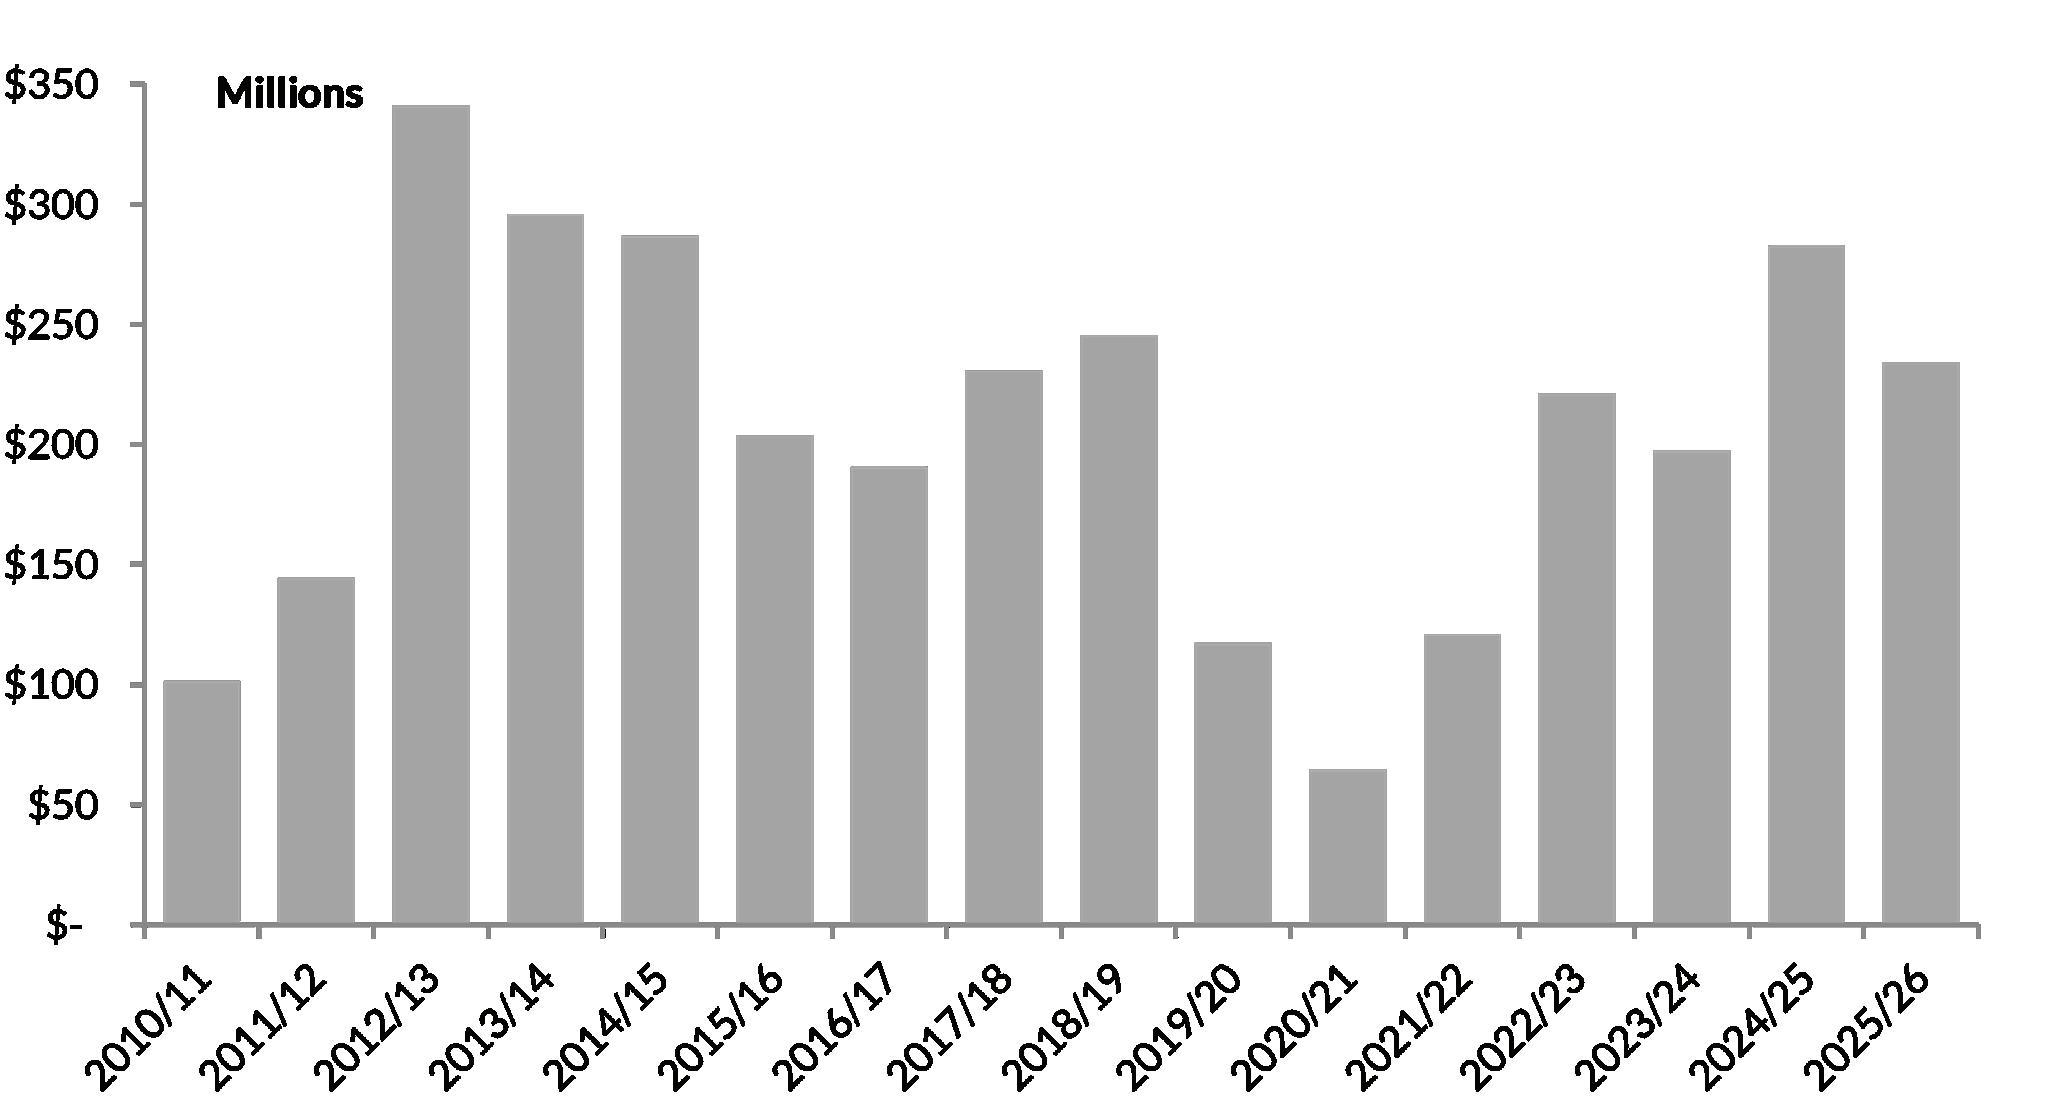
Hotel and leisure transactions totaled $233.9 million in 2025/26, a 17.3% decrease on the previous year, reflecting limited stock availability rather than any softening in investor appetite.
Offshore interest in Perth hotel assets remains consistently strong, with Singapore continuing to be the most likely source of foreign capital pursuing opportunities in the market.
The challenge for this sector continues to be one of supply rather than demand. Quality hotel assets rarely come to market in Perth, and when they do, competition for these opportunities remains intense given the sustained interest from both offshore buyers and domestic investors attracted to the sector’s operational performance. This scarcity of available stock is the primary constraint on transaction volume, rather than any reduction in the number of parties looking to invest.
WA’s broader economic strength continues to support the investment case for hotel assets. Unemployment remains low and population growth continues, both of which underpin the operational fundamentals that make Perth hotels attractive to long-term capital. Growth in local tourism has also spurred demand for the sector, with occupancy levels maintaining recent highs and average daily room rates reaching new peaks. The State government’s commitment to new tourism drawcards via major sporting and concert events is putting the hotel sector at the forefront of investor considerations.
Source: RWC WA, Real Capital Analytics
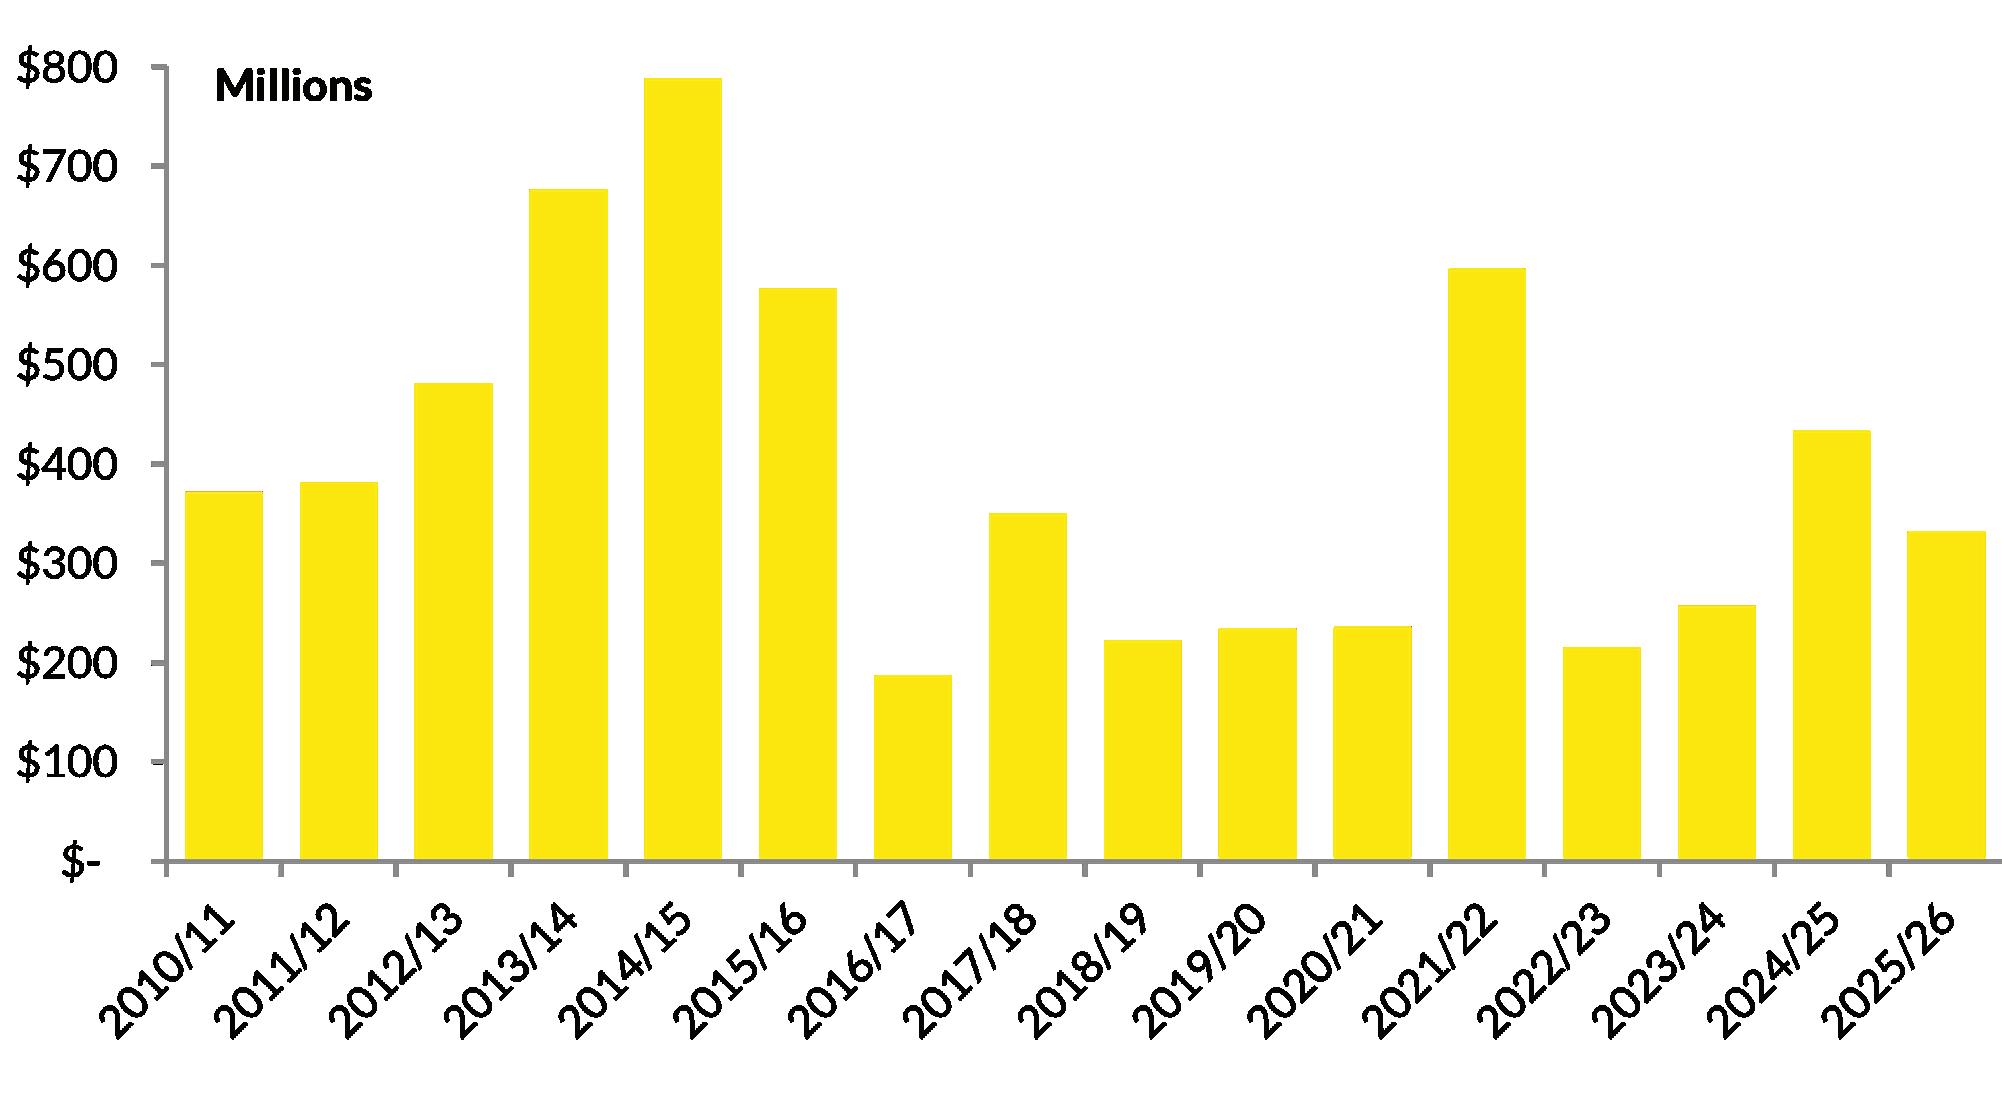
Development site transactions reached $331.9 million in 2025/26, a 23.4% decline on the previous year, consistent with the more cautious approach to acquisitions seen across the broader commercial market.
Buyers remain active, but feasibility assessments have become more rigorous, lengthening the time taken to bring transactions to completion.
Industrial-zoned development sites continue to attract the strongest interest, benefiting from the same pricing advantage and yield attractiveness driving activity in the broader industrial sector. Sites with clear line of sight to end use, whether industrial, residential-adjacent, or mixed-use, are proving easier to transact than speculative holdings, as buyers become increasingly selective given the current construction cost environment.
WA’s continued population growth remains the key demand driver underpinning development site values, supporting the case for well-located sites even as transaction pace has slowed. Private investors and syndicates remain the dominant buyer group, consistent with the broader private capital dominance across WA’s commercial market. Construction sector insolvencies, weak productivity, and escalating material and trade costs continue to weigh on development feasibility, and these pressures show little sign of easing in the near term.
Source: RWC WA, Real Capital Analytics
The healthcare and childcare sector recorded $98.5 million in transactions during 2025/26, down 29.8% on the previous year, with the two components of this sector telling markedly different stories.
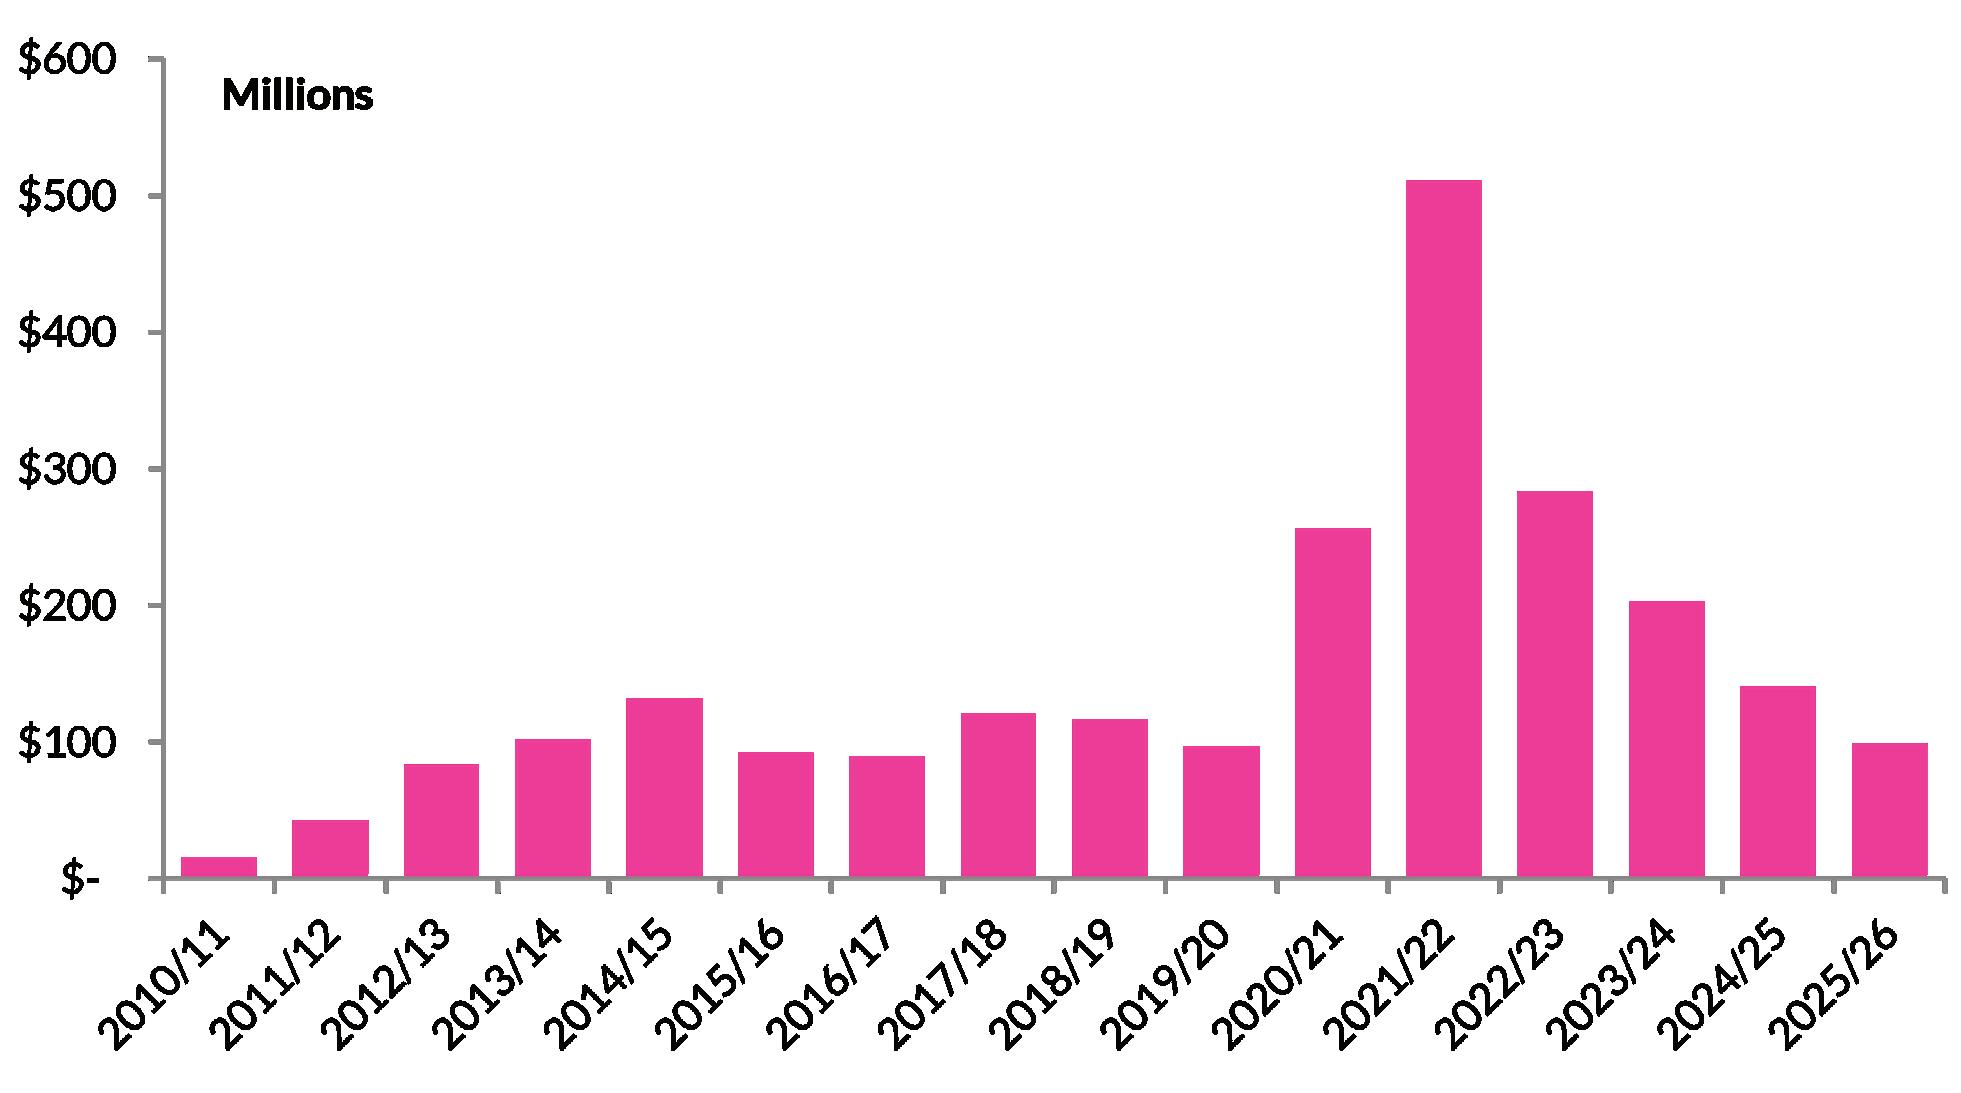
Healthcare property continues to perform well, supported by WA’s population growth, an aging demographic, and increasing demand for preventative healthcare services, all of which underpin sustained investor interest in well-located medical assets.
Childcare, by contrast, is navigating a more difficult period. Oversupply has emerged in a number of established markets where multiple centres were approved in close succession during the development boom of recent years, leaving operators competing for the same catchment of young families. Staffing shortages across the early education sector are compounding this pressure, making operator quality and workforce stability increasingly important considerations for investors assessing lease covenant strength.
Design has also become a differentiator. Large-format centres built to maximise licensed places are proving harder to lease to quality operators than smaller, well-designed facilities that genuinely serve the learning environment, reflecting the staffing constraints operators now face in running larger sites. Investors and developers are increasingly required to engage operators early in the design process rather than building speculatively. Medical property remains the more straightforward proposition of the two, while childcare now demands considerably more scrutiny of location, design, and operator credentials than in previous cycles.
Source: RWC WA, Real Capital Analytics
Western Australia’s commercial property sector enters 2026/27 from a position of underlying economic strength, even as transaction volumes have moderated.
Unemployment remains low and population growth continues, providing the demand fundamentals that underpin all six asset classes regardless of the current pace of deal making.
The more deliberate approach to due diligence seen throughout 2025/26, driven by three interest rate rises through the year, is likely to persist in the near term, though this reflects caution rather than a retreat from the market.
Industrial remains the sector best placed for renewed activity, supported by attractive yields, active owner-occupiers, and a genuine pricing advantage over the east coast that continues to draw interstate capital. The Budget’s changes to negative gearing on established residential property, combined with the loss of SMSF borrowing capacity for residential purchases, are expected to progressively redirect private and self-managed super fund capital toward commercial property, with industrial and well-located retail likely primary beneficiaries given their relative affordability and straightforward income profiles.
Office presents a genuine counter-cyclical opportunity, with replacement costs now sitting well above current pricing for existing stock, a gap that is likely to widen further as construction costs continue to climb. Retail’s convenience and neighbourhood formats should continue to perform, underpinned by population growth and limited new supply.
Hotel transaction activity will likely remain constrained by scarce stock rather than demand, with Singapore-sourced capital remaining the most consistent source of offshore interest. Medical property should continue its steady performance, while childcare requires more considered site selection, design and operator scrutiny than in previous cycles before transaction activity meaningfully recovers.
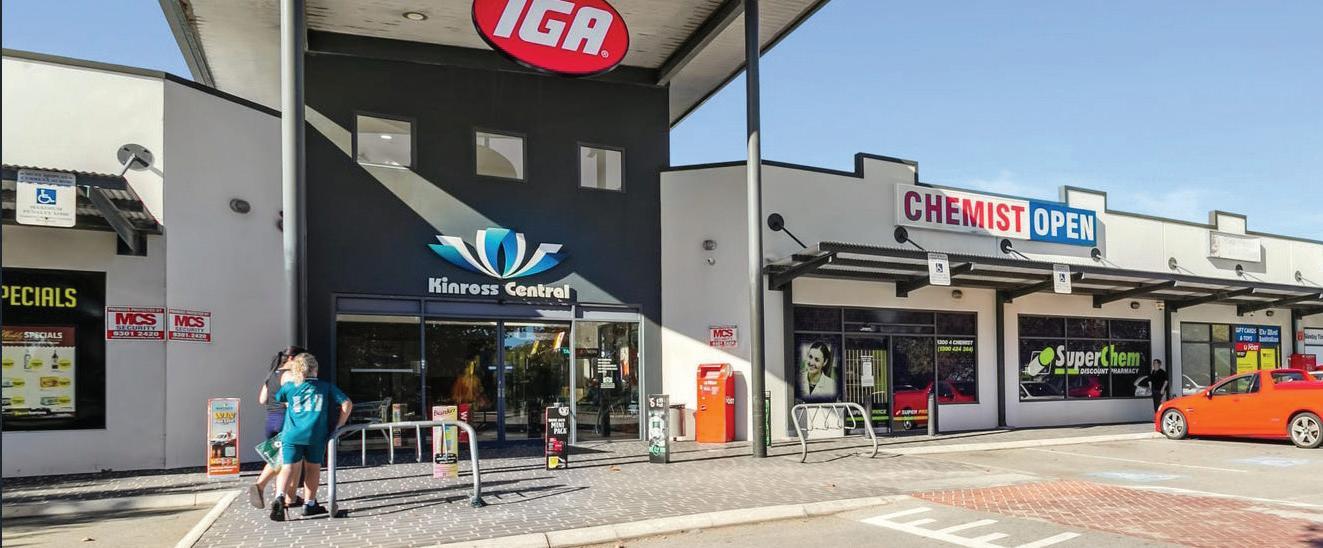
3 Selkirk Drive, Kinross
$1,216 / m²
Kinross Central, established in 2006 features a gross lettable area of 4,093 square metres and is anchored by Tucker Fresh IGA supermarket and complemented by 14 specialty shops, including a bakery, café, beauty salon, and various takeaway food outlets
Brett Wilkins 0478 611 168 brett.wilkins@raywhite.com
Andrew Woodley-Page 0438 939 869 andrew.woodley-page@raywhite.
Stephen Harrison 0421 622 777 stephen.harrison@raywhite.com
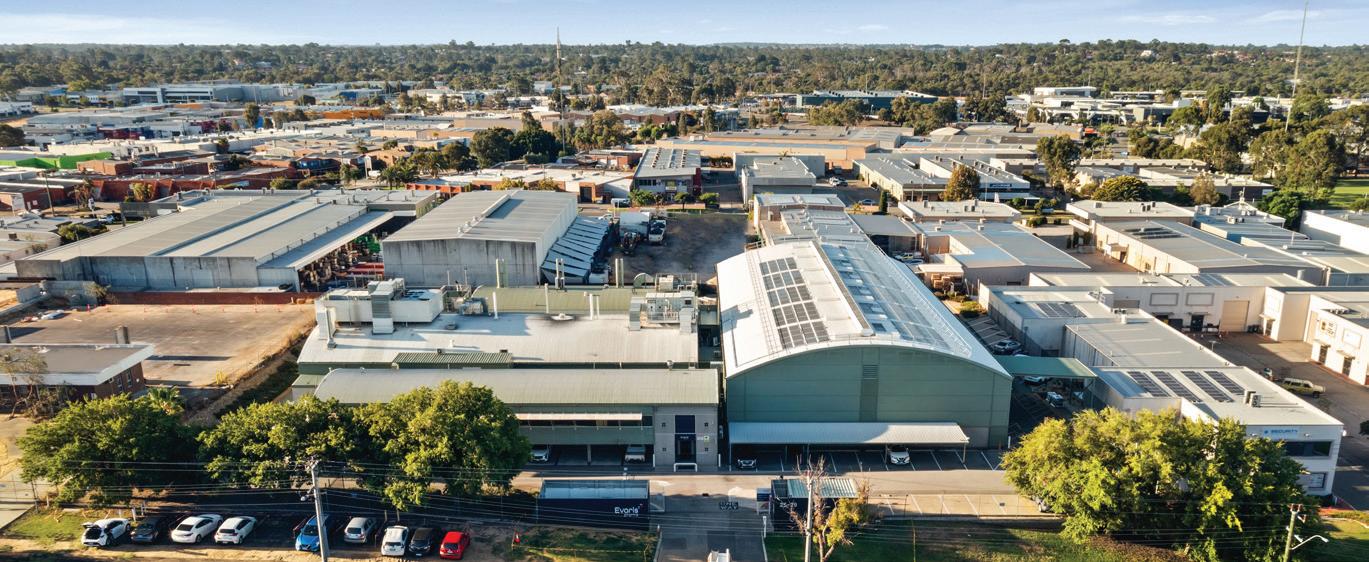
25 Delawaney Street, Balcatta
The asset is one of Perth’s largest and most sought-after pharmaceutical manufacturing facilities. Located in the highly desirable Balcatta industrial precinct, just 10km north of Perth’s CBD, this premium asset offers exceptional connectivity, long-term investment security, and unparalleled tenant strength.
Tom Jones 0478 771 117 tom.jones@raywhite.com
Lachlan Burrows 0499 552 296 lachlan.burrows@raywhite.com
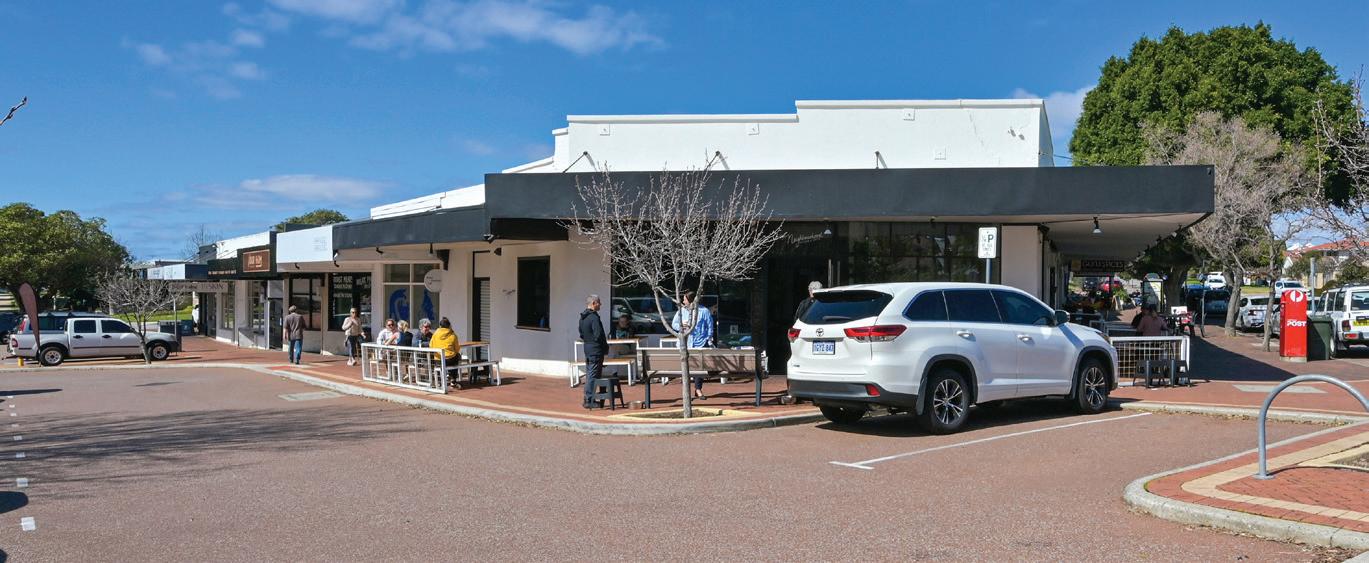
4 Davis Road & 88 Moreing Road, Attadale
Price $5,231,000 Sold Oct 2025
Always bustling, the well patronised retail centre provides essential services and meeting place. The tenancy mix including, café/bottle shop, fish & chips, hairdresser, beauty clinic, physiotherapy, butcher, burger joint & Indian restaurant. The precinct is in high demand and tenancies have a history of filling quickly.
Stephen Harrison 0421 622 777 stephen.harrison@raywhite.com
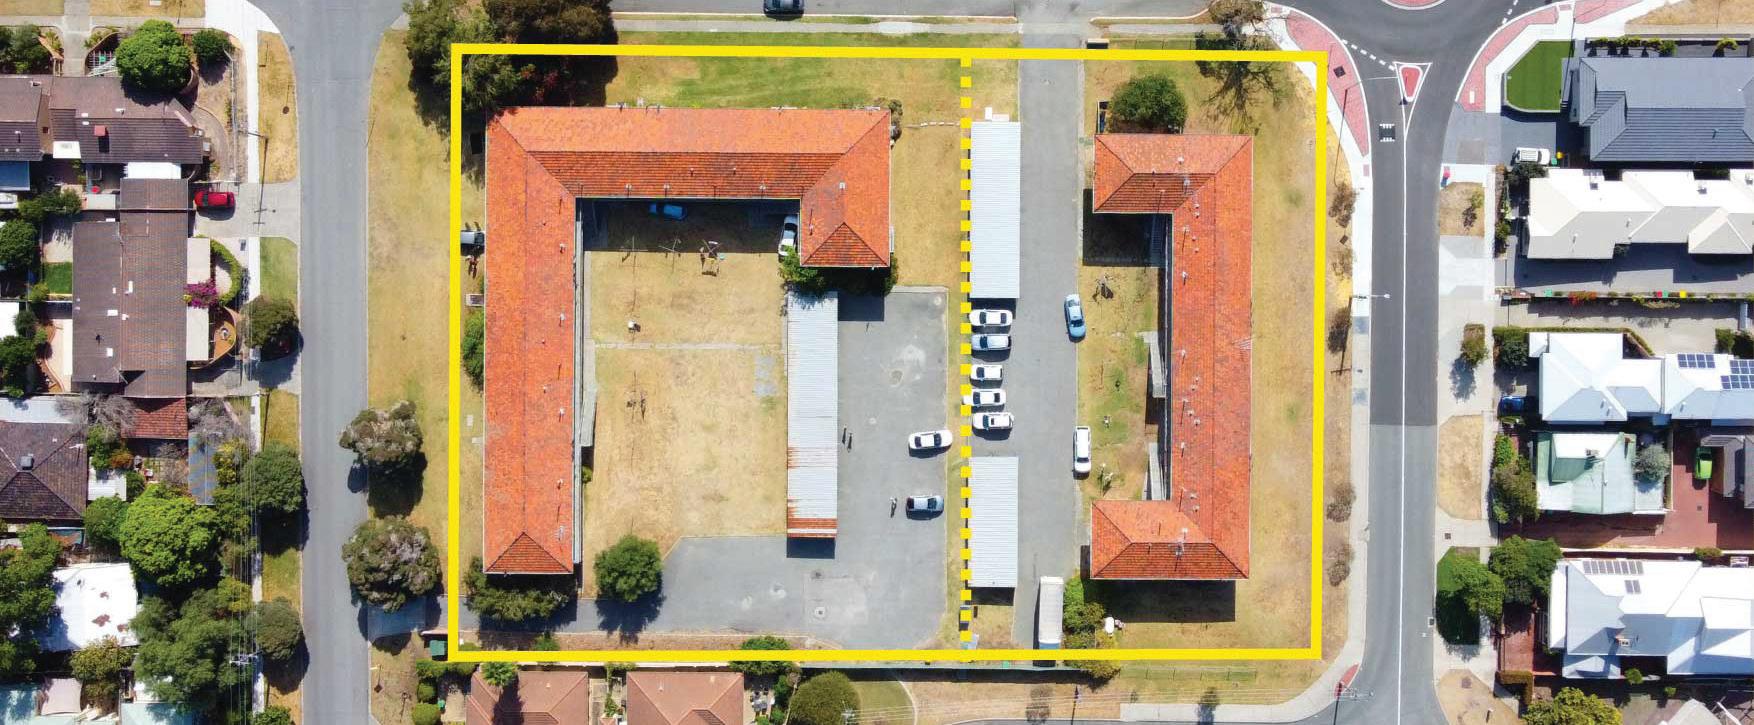
Sale Price $13,200,000
Sale Date March 2026
Land Area 7,088m2
Number of units 36 Price/Land $1,862 per m2
Price per unit $366,666
Asset Type In one line group of units
36 apartments in ‘one line’, consisting of a mixture of one and two bedroom units. With significant income upside and development potential, the property is ideal for light refurbishment, full renovation, or complete redevelopment. Z oned R50 with a 7,088m²
Stephen Harrison 0421 622 777 stephen.harrison@raywhite.com
Tom Jones 0478 771 117 tom.jones@raywhite.com
Lachlan Burrows 0499 552 296 lachlan.burrows@raywhite.com
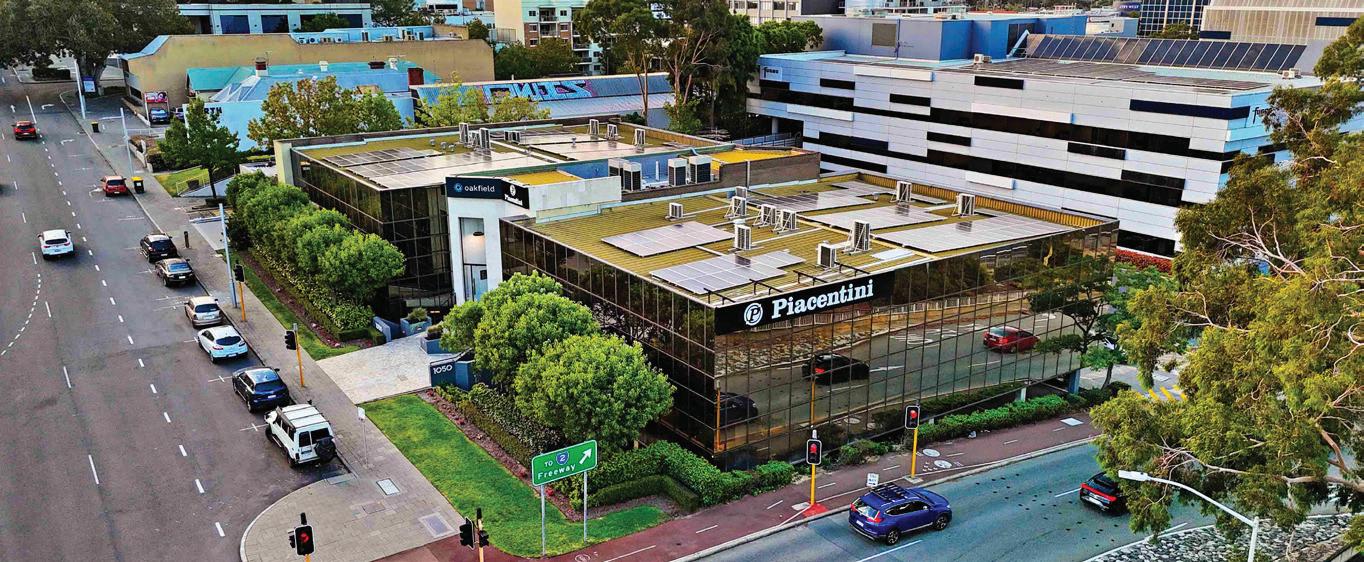
1050 Hay Street, West Perth
Sale Price $11,500,000
Sale Date May 2026 Land Area 1,696sqm
2,192sqm
- passing 6.9%
$6,780/sqm
$5,246/sqm Asset Type Office
This striking building has a total area of 2,192sqm comprising 4 split-level floorplates with wrap around reflective glazing, providing desirable views and excellent natural light. The asset has been meticulously maintained, having undergone significant capital upgrades and refurbishments, and comes with abundant undercroft parking. Long term value is underpinned by its strategic corner 1,696sqm land footprint with future high density redevelopment
Brett Wilkins 0478 611 168 brett.wilkins@raywhite.com
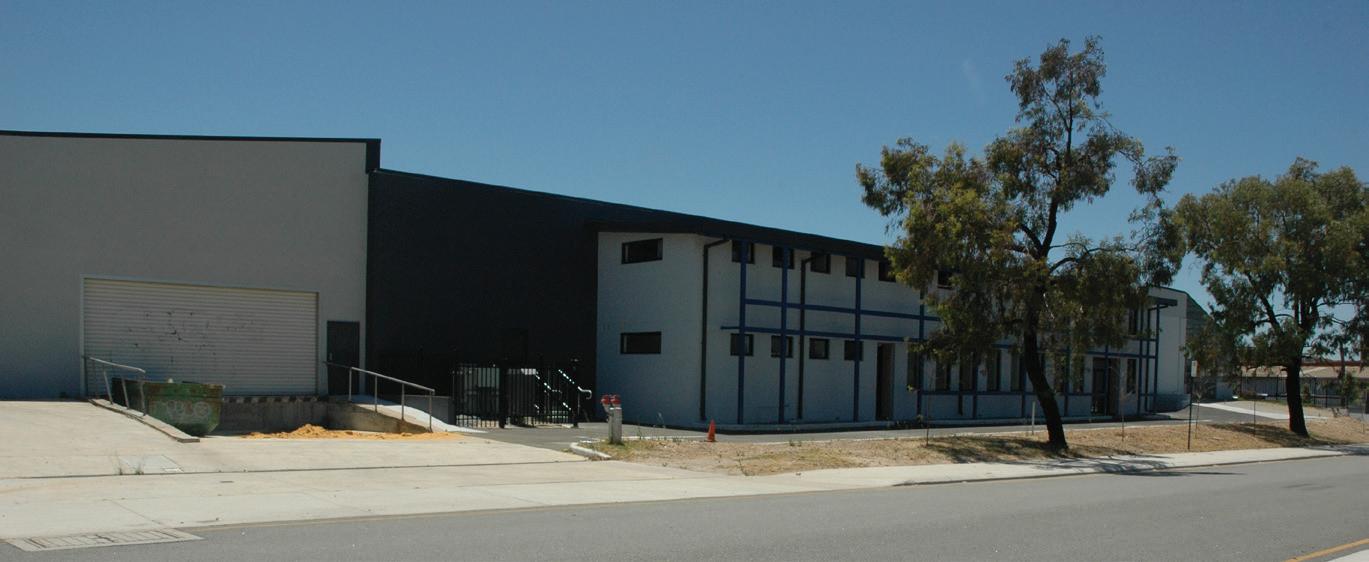
Michael Milne 0403 466 603 michael.milne@raywhite.com Sale Price $6,600,000 Sale Date 2025
Area 7,063 m2
Area 4,076 m2
$934/m2
Area $1,618/m² Asset Type Industrial
41-49 & 64 Robinson Avenue, Belmont
Strategically located in the heart of Belmont’s mixed business precinct, providing ideal office and warehouse solution for any business chasing a refurbished industrial facility. Located on a corner block, the warehouse has multiple entrance points offering a tenant flexibility to operate multiple types of businesses.
Chris Matthews 0413 359 315 chris.matthews@raywhite.com
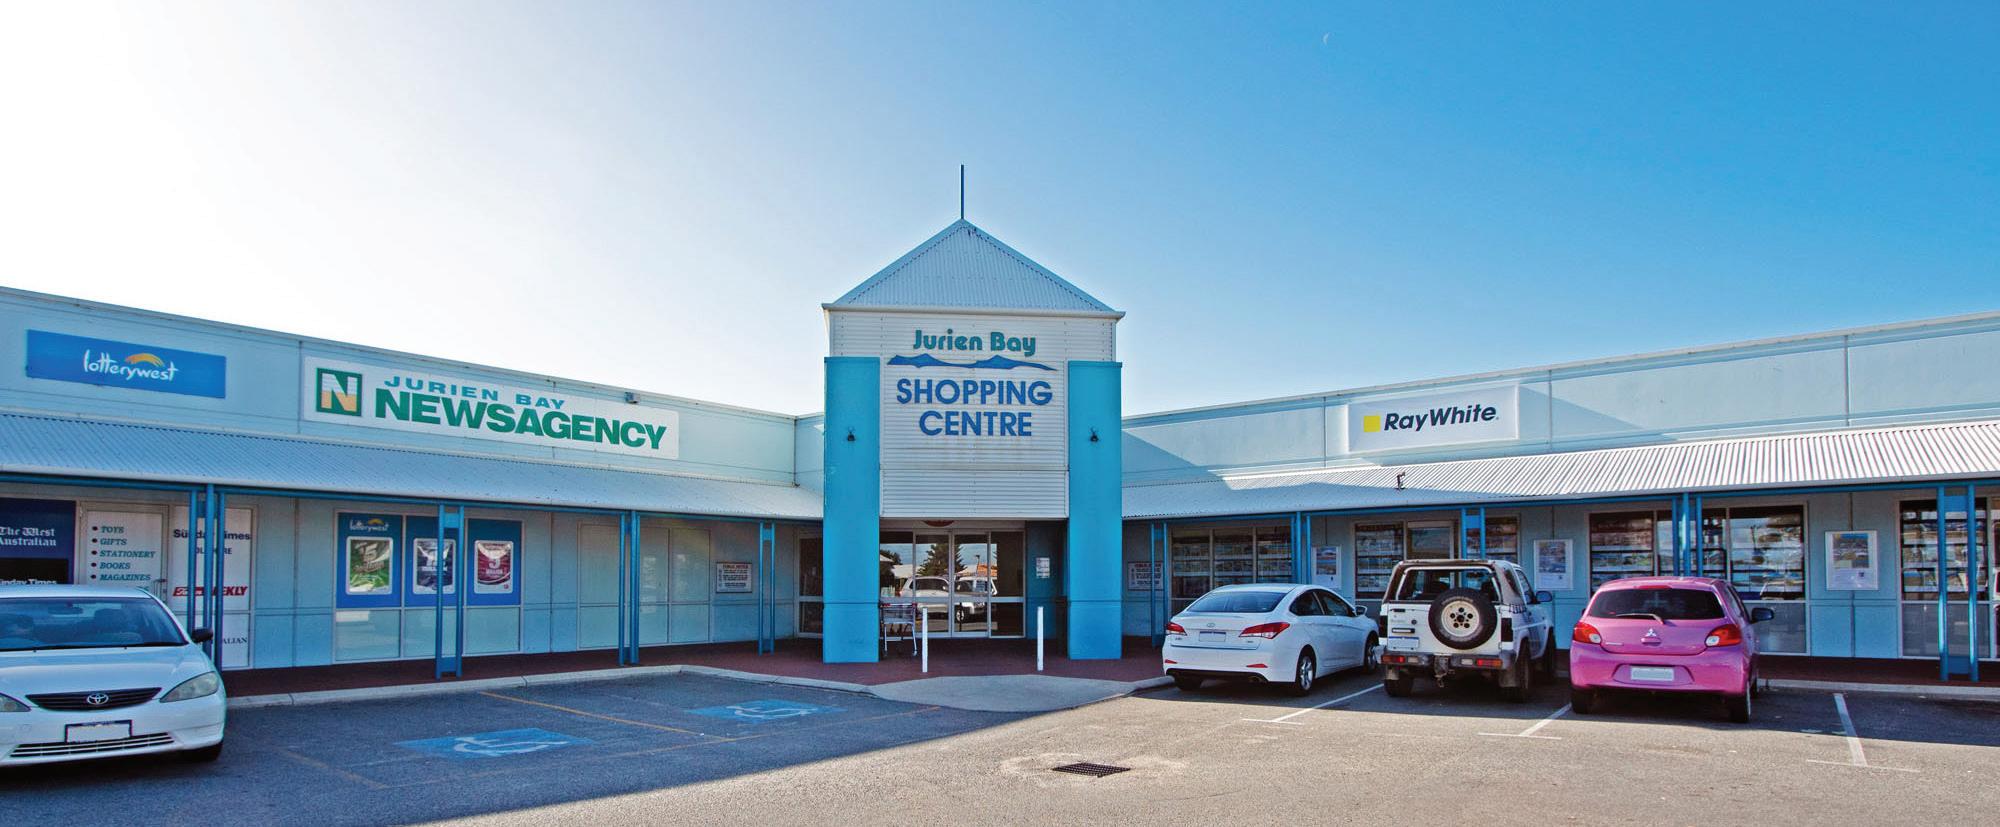
1 White Street, Jurien Bay
Sale Price $8,950,000
Sale Date December 2025
Land Area 5,853 m²
Building Area 2,550 m²
Yield - passing 6.80%
Price/Land m² $1,529 / m²
Price/B. Area $3,510 / m²
Asset Type Retail Shopping Centre
This established neighbourhood centre occupies a commanding main road 5,853 m² site and is anchored by an IGA Supermarket, supported by a core of tenants that deliver a strong mix of convenience and daily needs for the coastal community and tourists alike. The 270 km coastal highway, Indian Ocean Drive, is now well and truly established as the main tourism route connecting Perth’s northern metropolitan extremity to the Brand Highway
Andrew Woodley-Page 0438 939 869 andrew.woodley-page@raywhite.
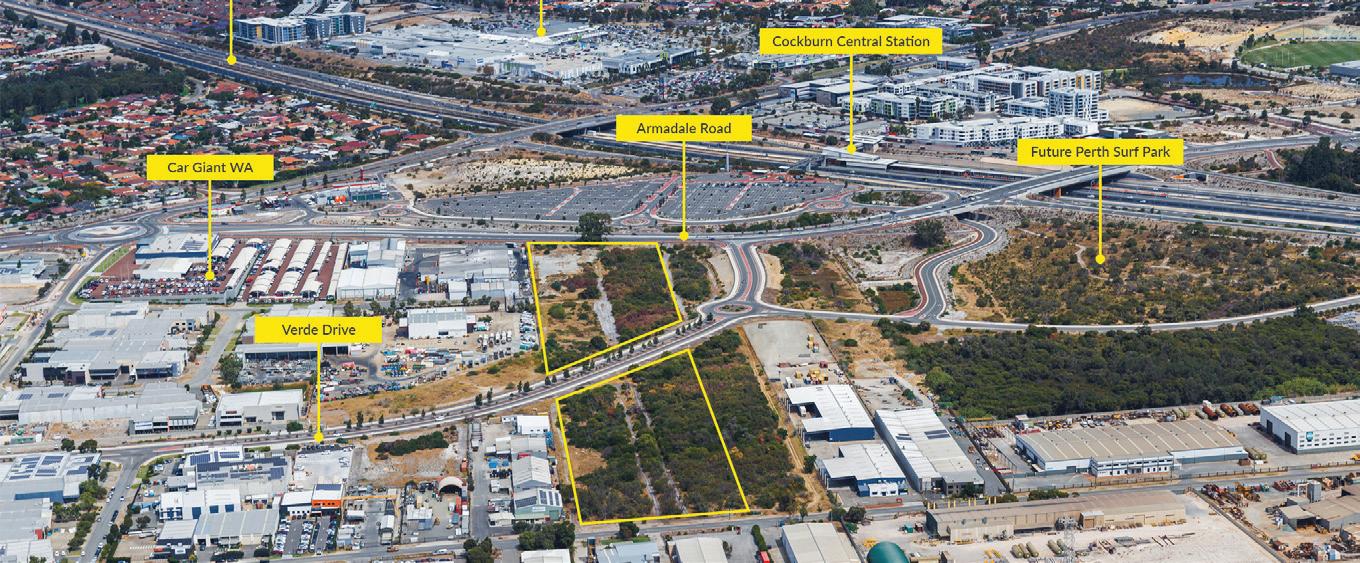
Brett Wilkins 0478 611 168 brett.wilkins@raywhite.com Sale Price $16,250,000
Sale Date February 2025
Land Area 4.73ha Price/Land m² $344/m²
Type Industrial Land
Situated at 49 & 53 Cutler Road, this property represents one of the last large-scale infill land parcels with prime exposure to Armadale Road. Encompassing a vast 4.73ha* of freehold land, it boasts a zoning that accommodates mixed business and industrial usage. Positioned adjacent to the future Perth Surf Park, Cockburn Station, and Kwinana Freeway.
Lachlan Burrows 0499 552 296 lachlan.burrows@raywhite.com
Michael Danagher 0403 049 989 michael.danagher@raywhite.com
Tom Jones 0478 771 117 tom.jones@raywhite.com
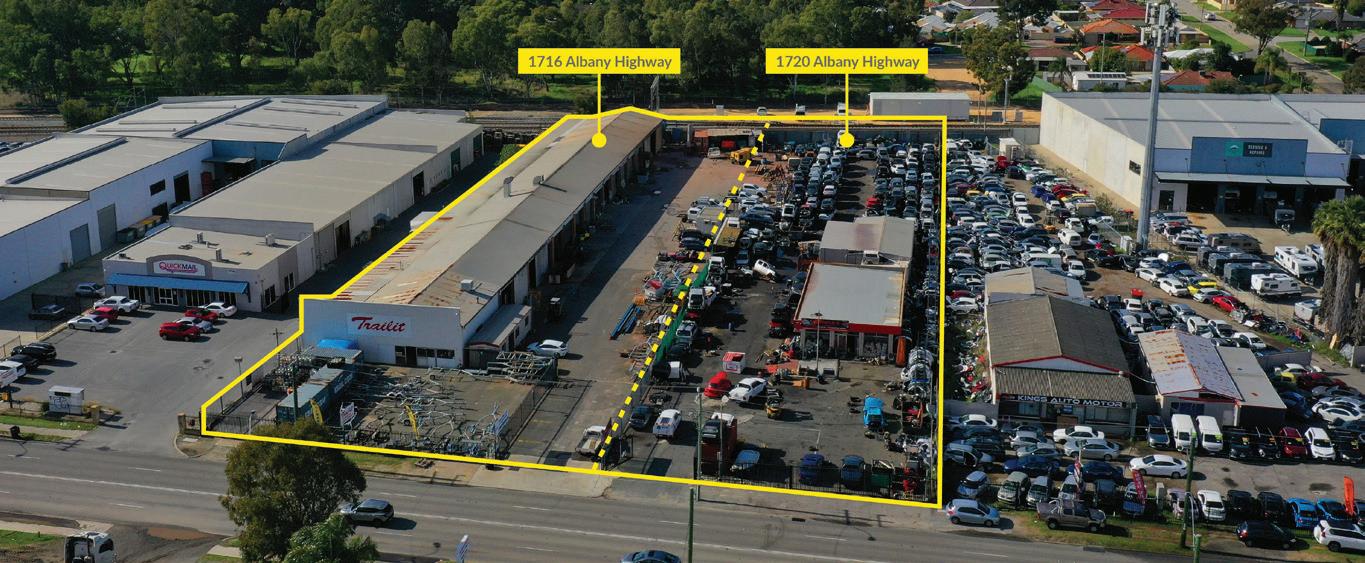
1716-1720 Albany Highway, Kenwick
1716-1720 Albany Highway, Kenwick offers a strategic location within a developing area of Perth’s south-eastern corridor. This stretch of Albany Highway is characterised by its high visibility and accessibility, making it a prime spot for various commercial and industrial operators.
Chris Matthews 0413 359 315 chris.matthews@raywhite.com
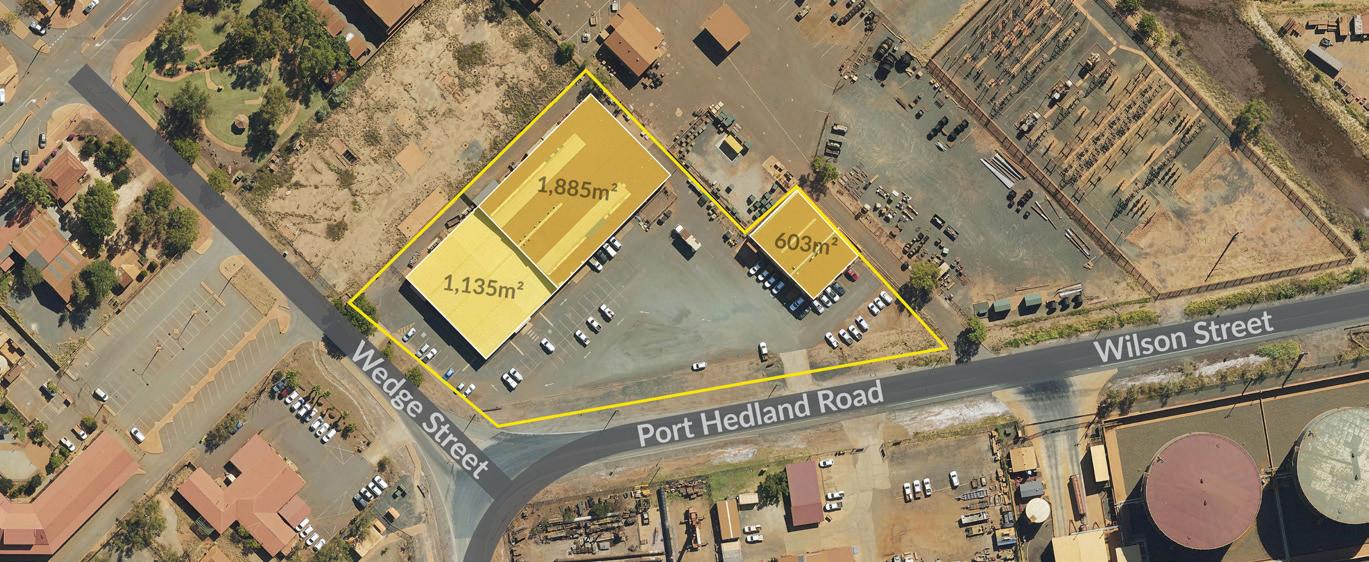
Securely leased industrial investment with two long-standing tenants. The property offers strong income stability, covenant strength, and prime positioning in the West End industrial precinct.
Michael Danagher 0403 049 989 michael.danagher@raywhite.com
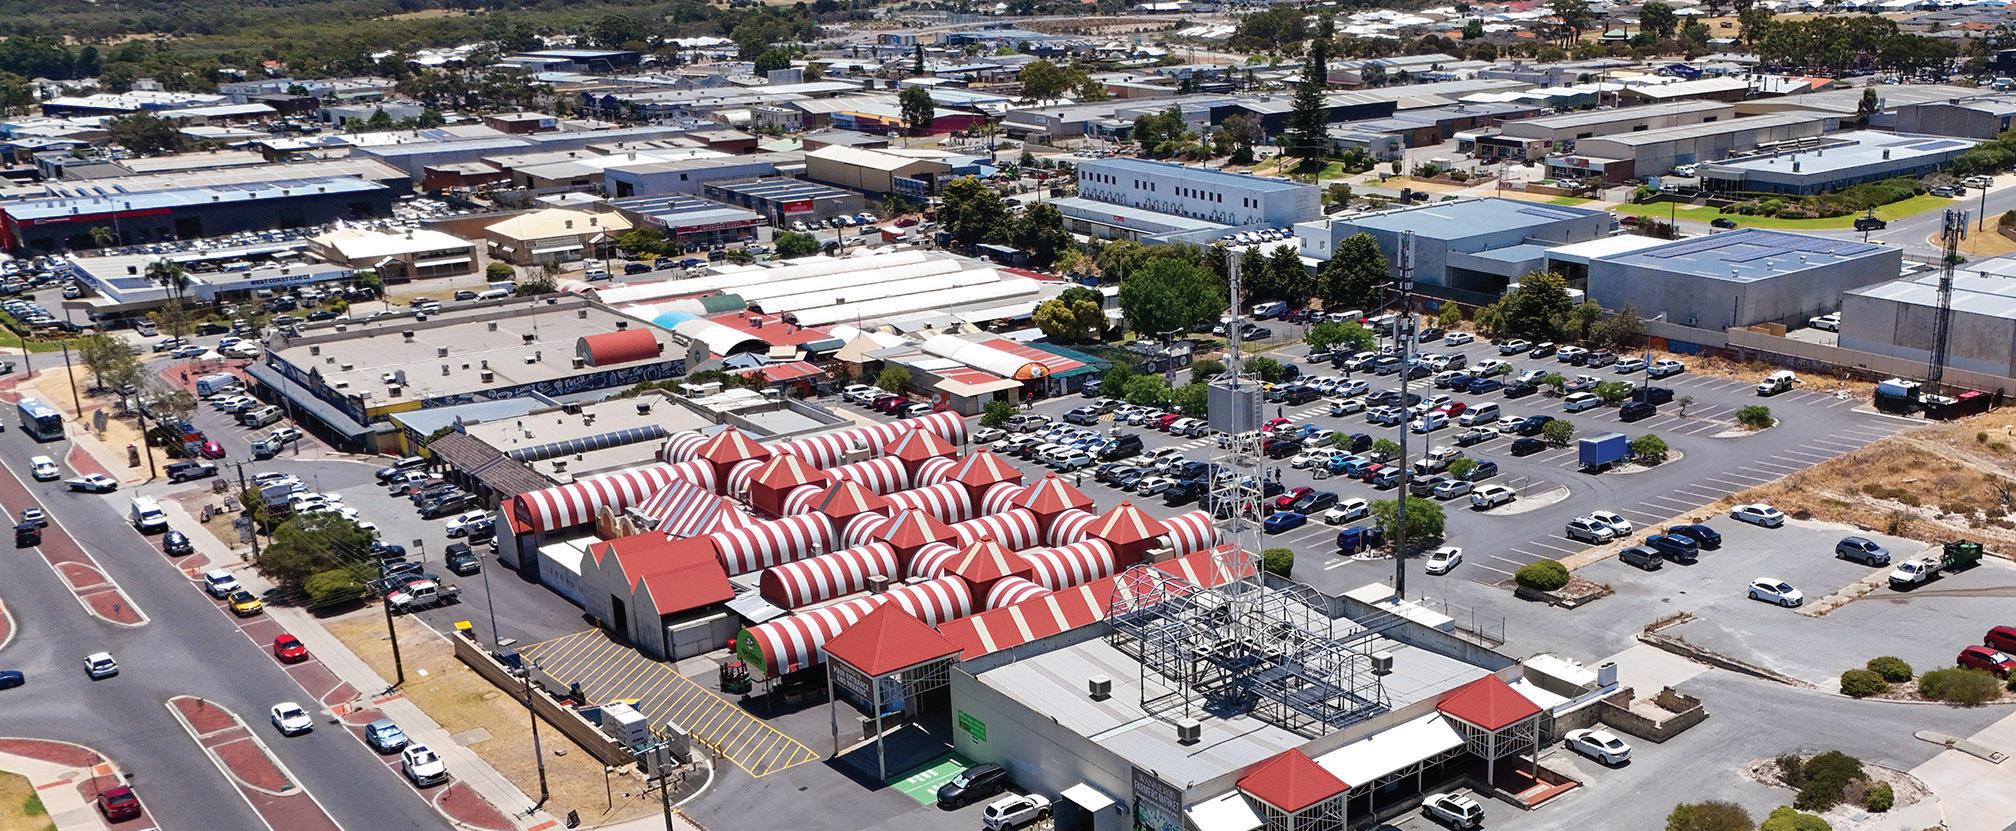
Type Retail Shopping (markets)
The landmark variety market asset occupies a substantial 22,955sqm freehold landholding, zoned Special Use, within a tightly held inner light industrial precinct. The operation has approximately 100 stalls with 2,985sqm of net lettable area, and around 350 car bays. The sale price reflects $403/sqm on land area, and 8.81%pa on the static net income.
Brett Wilkins 0478 611 168 brett.wilkins@raywhite.com
Michael Milne 0403 466 603 michael.milne@raywhite.com
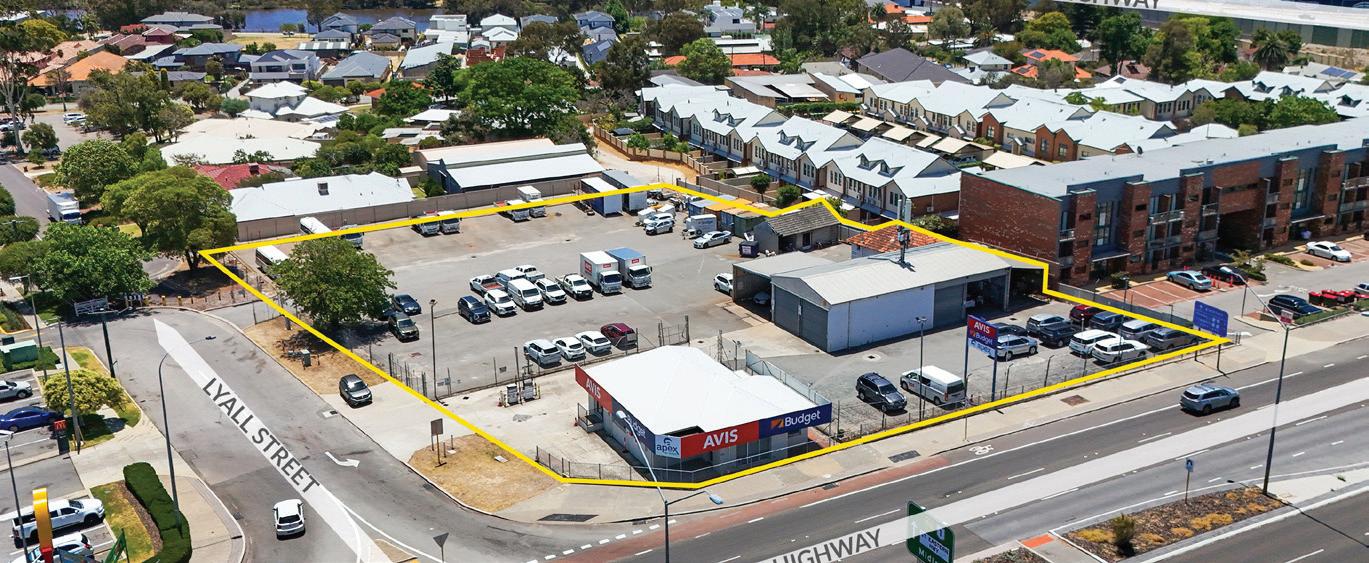
302 Great Eastern Highway, Ascot
Sold June 2026
302 Great Eastern Highway, Ascot presents a compelling opportunity for occupiers and/or developers to acquire a 4,998m² green-titled landholding prominently positioned on the corner of Great Eastern Highway and Lyall Street, Ascot. Located on one of Perth’s key arterial routes, the site offers exceptional exposure, strong passing traffic and direct connectivity to the Perth CBD, eastern suburbs, and Perth Airport.
Brett Wilkins 0478 611 168 brett.wilkins@raywhite.com
Chris Matthews 0413 359 315 chris.matthews@raywhite.com