Strategic Market Intelligence
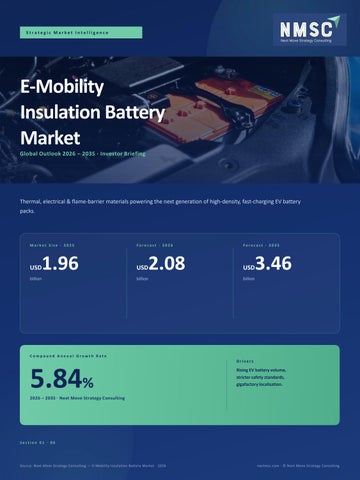
E-Mobility Insulation Battery Market Global Outlook 2026 – 2035 · Investor Briefing
Thermal, electrical & flame-barrier materials powering the next generation of high-density, fast-charging EV battery
packs.
Market Size · 2025
1.96
Forecast · 2026
USD
USD
billion
billion
2.08
Forecast · 2035
USD
3.46
billion
Compound Annual Growth Rate
Drivers
5.84%
Rising EV battery volume, stricter safety standards, gigafactory localisation.
2026 – 2035 · Next Move Strategy Consulting
Section 01 · 06
Source: Next Move Strategy Consulting — E-Mobility Insulation Battery Market · 2026
nextmsc.com · © Next Move Strategy Consulting
Section 02 · Market Snapshot
Market Landscape. Sizing, trajectory and executive snapshot across 33 countries, 15 profiled companies and six material segments.
Market Trajectory
CAGR
5.84%
From USD 1.96B to USD 3.46B Compound Annual Growth Rate 2026 – 2035
▲ Baseline 2025
Forecast 2026
Projection 2035
USD 1.96 B
USD 2.08 B
USD 3.46 B
202520262035 (10-yr forecast horizon) Insulation demand scales 1:1 with GWh shipped — every incremental kilowatt-hour of EV battery capacity requires precise thermal, electrical and mechanical isolation, expanding the addressable insulation spend per pack.
By Material Type
Thermal Insulation dominates 2025
#1 Largest segment
By Form Type
Sheets & Panels preferred by OEMs
Foams, aerogels and phase-change
Easy to automate at scale;
materials lead on thermal-runaway
compatible with pack-level
mitigation.
converting.
By Vehicle Type
10-yrs
Passenger EVs drive volume
Forecasts horizon
Largest 2025 GWh pool; commercial &
Global EV fleet 2019-24: 7,000 → 58,000 (×8)
two-wheelers on an accelerating curve.
Source: Next Move Strategy Consulting — E-Mobility Insulation Battery Market · 2026
By Application
Battery pack-level captures largest spend Combines thermal, electrical & mechanical protection across the
#1 Pack-level default
Largest Spend share
Fire-containment validation required
largest area.
nextmsc.com · © Next Move Strategy Consulting
Section 03 · Demand Catalysts
Growth Drivers. Demand is anchored by secular EV volume, regulatory tightening & gigafactory localisation with a high-ROI assembly model emerging as the principal near-term opportunity.
01
02
Long-Term Anchor
Regulatory Tailwind
Rising EV battery volumes
Stricter safety & lifecycle standards
×8 Global EV fleet growth 2019 → 2024
U.S. DOE & international insurers now demand certified multilayer flame barriers — pushing OEMs toward validated, traceable insulation systems and increasing layer count per pack.
Each incremental kWh of battery capacity requires precise
Suppliers with premium, certified kits command pricing power.
thermal, electrical & mechanical isolation — making every GWh shipped a direct insulation demand unit.
Outcome
Higher insulation content per pack · premium pricing · certified-only suppliers
03
04
Near-Term Supply Opportunity
High-ROI Investment Opportunity
Gigafactory localisation
Pre-qualified modular insulation assembly lines
Regional converting, lamination & kitting capacity near North American, European and Asian gigafactories secures preferredvendor status, shortens qualification cycles, and reduces OEM logistics complexity.
High
Automation + in-line testing + regional
ROI · durable
contracts and recurring revenue via
partnerships capture preferred-supplier multi-year framework agreements.
Beneficiary geographies
Strategic priority
United States · Germany · China · South Korea
Combine automation, embedded test data & gigafactory proximity to capture share.
Watch-out · Growth Inhibitor
Cost pressure on premium insulation materials Aerogels, aramids and high-performance polymer films remain cost-intensive due to complex processing and limited precursor supply chains. Volatile rawmaterial pricing drives OEMs in price-sensitive vehicle segments to down-spec insulation to balance cost per kWh — making process efficiency, vertical integration and modular product design decisive competitive levers.
Investor takeaway
Suppliers that convert this trade-off into total system savings — through automation and waste reduction — defend pricing power in volume categories.
Source: Next Move Strategy Consulting — E-Mobility Insulation Battery Market · 2026
nextmsc.com · © Next Move Strategy Consulting
Section 04 · Competitive Landscape
Competitive Scenario. A dual structure diversified materials giants competing alongside niche specialists with innovation speed, regional converting capacity and M&A shaping the next 24 months.
15 Companies Profiled
Tier 1 · 2 · 3 leaders
3M
Autoneum
BASF
DuPont
ITW Formex
Morgan Advanced Materials
Marian
Alkegen
Von Roll
Zotefoams plc.
Rogers Corp.
The Gund Company
Wacker Chemie AG
OC Oerlikon Mgmt AG
Henkel AG & Co.
Recent Industry Developments
Strategic moves shaping 2024 – 2025
November 2025
Henkel AG & Co. launches dual thermal potting solutions — Loctite SI 5643 & SI 5637 Targeted at improved protection and thermal management in on-board chargers and inverters for EVs. September 2025
3M showcases EV battery protection suite at IAA Mobility 2025 Includes 3M VHB Extrudable Tape and stretch release technology for efficient pack assembly & disassembly. May 2025
Zotefoams debuts supercritical foams at Battery Show Europe ECOZOTE PP and ZOTEK T series — improved temperature regulation, impact protection, recyclability.
Convergence · M&A
Von Roll, 2024 — strategic repositioning across electrical insulation Consolidation activity is accelerating — M&A is used to diversify material portfolios (thermal, electrical, flame barriers) and integrate downstream assembly capabilities to shorten OEM qualification timelines.
Source: Next Move Strategy Consulting — E-Mobility Insulation Battery Market · 2026
▲ Capital flows into cell & pack
Adjacent insulation suppliers attract private-equity follow-on and corporate investment as OEMs secure local supply chains.
nextmsc.com · © Next Move Strategy Consulting
Section 05 · Regional & Country Outlook
Regional Outlook. Asia-Pacific dominates volume; North America & Europe win on safety-led localisation. 33 countries covered across five regional markets.
Asia-Pacific · Largest Volume
#1
China & India drive production volume Gigafactory build-out spans APAC's largest OEMs.
Europe · Recycling & Safety Leader
Latin America · Emerging Hub
Brazil · Mexico · Chile Electric buses & fleet assembly fuel demand for thermal barriers.
Largest regional market
92% / 58%
Certified, recyclable insulation systems
EV sales share
Middle East & Africa · Early Stage
First-mover window opens Mining EVs & localised energy storage open a first-mover wedge.
Norway · Sweden (2024)
Nordics pilot bio-based laminates & recycled barriers.
High-Growth Spotlight
North America · Gigafactory Hub
USA · CA
DOE-aligned insulation supply chains
Lead markets
U.S. federal mandates favour regional, certified converters.
Local-content rules active
India · Two-wheelers & PLI Massive unit-based volume driving a localised converter build-out.
Indonesia · Australia · Taiwan Nickel resources · mining EVs · precision films
Segmentation Snapshot · 2025
Six dimensions, one investment thesis By Material
Thermal · Electrical · Flame/Fire Barrier · Acoustic & Vibration · Structural & Sealing
By Form
Sheets & Panels · Films & Foils · Papers & Fabrics · Tapes & Pads · Molded/Composite Parts
By Chemistry
Polymer-based · Ceramic-based · Fiber-based · Elastomeric · Microporous/Aerogel · Hybrid multilayer composites
By Vehicle
Passenger EV · Commercial EV (LCV · M&HCV) · Two-wheelers · Electric Industrial · Aerospace
By Application
Battery insulation (cell · module · pack) · Power electronics · Electric motor · HV cable/busbar · BMS & connector
Where to Invest · 2026 – 2035
Strategic Priorities
Regional capital allocation map
33 countries covered
Converters near NA & EU gigafactories
Tariffs, content rules, OEM preferences
Test labs that compress OEM qualification
Forecast period
Specialty materials with proprietary chemistries
Source: Next Move Strategy Consulting — E-Mobility Insulation Battery Market · 2026
Regional & country-level forecasts
5 regions analysed
2025 base year · through 2035
nextmsc.com · © Next Move Strategy Consulting
Section 06 · Connect
Thank You. Connect with our strategy team for in-depth insights, custom research, and tailored advisory engagements.
Get In Touch
Phone
Complete Report
+1 857 758 5017
E-Mobility Insulation Battery Market 2026 Visit the full report at e-mobility-insulation-battery-market nextmsc.com/report/
nextmsc.com/report/
info@nextmsc.com
e-mobility-insulation-battery-market
Official Website Custom Research
nextmsc.com
Up to 80 analyst-working hours of free post-purchase customisation — country, regional & segment scope, tailored to your acquirer thesis.
Follow Us
gen-dedup-2e7f0201bb9ae79b837114c82c3e49be.png
gen-dedup-4399209d7dd056b836c7e4bc70f88bc2.png
gen-dedup-84b8c6a277ac4373923cfe3358b48d08.png
gen-dedup-6fca4a63f6d03e6be34906549e75daee.png
gen-dedup-7d7b3b5d224c96a4a11f2566ea9c1f47.png
YouTube
linkedin.com/company/ next-move-strategy-consulting
facebook.com/ Next-Move-Strategy-Consulting
youtube.com/channel/ UCJuVRxfBo-Dsog7Bg
twitter.com/ nextmsc
instagram.com/ nextmsc
Investor Briefing Click here report complete for the
Ready to unlock the E-Mobility Insulation Battery thesis?
Strategic Market Intelligence · 2026 – 2035 Outlook
Click here for the complete report nextmsc.com · info@nextmsc.com · +1 857 758 5017
nextmsc.com · © 2026 Next Move Strategy Consulting
© Next Move Strategy Consulting — All Rights Reserved