Portfolio Construction
Portfolio Construction Guide 2027
PM Capital looks at global equities, Metrics
Credit Partners looks at both real estate and private credit, Macquarie Asset Management explores ETFs, Capital Group examines fixed income and EQT looks at infrastructure.
Global equities - narrow markets and AI winners
PM Capital portfolio manager, Kevin Bertoli, explores how the rise of AI-focused stocks concentrated in the US have widened the gap between equity winners and the rest of the global market.
assets which are supported by the trend of e-commerce.
Infrastructure – the most underappreciated infrastructure themes
Two thematics are standing out in an evolving infrastructure asset class, shares
Sam Franklin, managing director of EQT, as the sector broadens its investment universe to include structural trends.
Fixed income – compelling areas of fi xed income
Welcome to the Money Management
Portfolio Construction Guide for the 202627 financial year where we dive into and demystify six asset classes for advisers.
This guide unfolds over six chapters, each with a manager sharing their insights from their respective field of expertise and how the asset classes can be used in client portfolios.
In this edition, we cover fixed income, global equities, private credit, ETFs, real estate and infrastructure.
ETFs – concentration risk is reshaping index investing
Blair Hannon, head of ETFs at Macquarie Asset Management, believes it is no longer about active versus passive but how the two can be combined in portfolios.
Real estate – a market shaped by supply constraints
Residential development remains the biggest focus for Metrics Credit Partners, says its group CEO and managing partner Andrew Lockhart, followed by industrial
Capital Group fixed income investment director Haran Karunakaran explores why active fixed income investing can identify mispriced bonds and reallocate capital into new opportunities.
Private credit – Built for income, tested by volatility
Group CEO and managing partner of Metrics
Credit Partners, Andrew Lockhart, examines how private credit is becoming both a source of contractual income as well as a way to preserve capital.
Happy reading!
The compelling areas of the fi xed income market
In a broad investment universe, active fixed income investing can create value through identifying mispriced bonds, realising gains as valuations normalise, and reallocating capital into new opportunities.
Real Estate: A market shaped by supply constraints
Higher interest rates may have altered property financing conditions but it can also expand investment opportunities and may support improved pricing dynamics.
Concentration risk is reshaping index investing
It is no longer about active versus passive but rather how the two can be used together in portfolios
Private Credit: Built for income, tested by volatility
Private credit funds have moved into the spotlight and are filling the gap in the market left by traditional lending providers.
Infrastructure: Seeking underappreciated infrastructure themes
Beyond offering stable cashflow, infrastructure is evolving rapidly as an asset class with a focus on transition infrastructure that can drive decarbonisation.
Narrow markets, AI winners and the return of active investing
The rise of AI-focused stocks has widened the gap between winners and the rest of the market so it is more important than ever to separate out the noise.
The compelling areas of the fixed income market
In a broad investment universe, active fixed income investing can create value through identifying mispriced bonds, realising gains as valuations normalise, and reallocating capital into new opportunities.
The global fixed income universe is far broader than many investors realise, according to Haran Karunakaran, fixed income investment director at Capital Group.
“There are different segments of the market, including corporate credit, where companies issue debt; structured credit, where different types of debt are packaged together and sold to investors; and emerging market debt. There’s a whole range of sectors you can invest in.”
Karunakaran believes fixed income is one of the most compelling areas of the market today.
“Many investors, particularly those who aren’t in markets day-to-day, still think of fixed income as a zero-return asset class that hasn’t done much for portfolios,” he said.
And for the majority of the past 15 years,
he agrees, that perception was justified.
“Central bank rates were near zero, bond yields were low, and total returns from bond portfolios were meagre.
“But the reality today is very different. Across fixed income markets, we’re now seeing yields in the mid-to-high single digits. That matters because yields not only provide income today but are also one of the best predictors of future returns from a fixed income portfolio.”
Looking beyond a narrow view of fi xed income
While the opportunity set is broad, Karunakaran notes that many investors struggle to access the full global fixed income universe.
“It often gets simplified to owning a handful of bonds from big-name issuers or focusing on one particular sector, which can create concentration risk. For many, there is also a strong home-bias toward Australian
THE QUALITY OF THE HIGH-YIELD MARKET HAS IMPROVED DRAMATICALLY OVER THE PAST DECADE AND TODAY LOOKS MUCH CLOSER TO INVESTMENTGRADE BENCHMARKS THAN MANY PEOPLE REALISE.”
Haran Karunakaran Fixed income investment director at Capital Group
government or corporate bonds, which is actually only a tiny fraction of global bond market.
“Where investors, particularly active investors like Capital Group, can really add value is through having the breadth of resources to be able to research bonds across all these sectors and across different countries. You’re talking about tens of thousands of entities issuing bonds globally and covering that universe requires significant resources - a lot of people, corporate access and analytical horsepower,” he said.
“But if you do that work, you have the ability to uncover hidden opportunities that may be undervalued and likely to appreciate over time.”
Unlike a traditional buy-and-hold or ‘clipping the coupon’ approach, active fixed income investing can create value through identifying mispriced bonds, realising gains
as valuations normalise, and reallocating capital into new opportunities.
“At Capital Group, that’s what we do. We have around 50 credit analysts focused on bottom-up research, meeting with companies, countries and other debt issuers around the world on a daily basis to identify hidden opportunities and generate value through actively investing in undervalued bonds before rotating into new opportunities once they reach fair value.”
Why global credit stands out
The sharp rise in bond yields since 2022 has transformed the return outlook for fixed income. However, performance has varied considerably across sectors.
“Importantly, where you invest within fixed income matters. Not all fixed income assets have performed equally well. Aussie core bonds, for example, have only returned around 2 per cent per annum over that period, while global investment grade
credit has more than doubled that. 1” Karunakaran said.
“When we think about opportunities today, we see fixed income broadly as very attractive, but global credit stands out in particular. It’s currently yielding around 6 per cent to 7 per cent, which is high by historical standards and presents a compelling entry point for investors. Those yields point to potentially mid to high single-digit total returns over the next five years, making it a very attractive area of the market.”
Beyond its income potential, Karunakaran believes global credit can also play an important defensive role in portfolios.
“It also provides strong defensive characteristics in what we see as an increasingly fragile and uncertain world.”
Capital Group currently favours global bonds over Australian sovereign bonds,
reflecting its view that global opportunities offer more attractive risk-return characteristics. While Australian bonds remain an important portfolio component, the firm sees greater value in global fixed income markets.
“That said, Aussie bonds still have an important place in portfolios. But we do think it makes sense to complement them with a potentially larger allocation to global fixed income, and particularly global credit, which we believe is one of the sweet spots in markets today.”
Navigating an uncertain world
Heightened geopolitical tensions and market uncertainty have reinforced the importance of portfolio defensiveness.
“We’re clearly living in a very uncertain world. We recently held our biannual fixed income macro forum where our 250 fixed income investors from across the globe gathered to discuss what’s happening in
economies and markets and develop a view for the next 12-18 months,” he said.
“The latest forum was particularly challenging because it took place amid the conflict in Iran, which remains very openended. But one of the key themes that emerged was that the while underlying fundamentals of the global economy are relatively strong, there is growing fragility beneath this. The Iran conflict is on front pages, but we also worry about the weakening US consumer, a heavy reliance on fiscal stimulus in Europe and uncertainty around the massive capex going into AI.”
In this environment, Capital Group sees greater value in high-quality credit, which can serve as a defensive anchor within a broader portfolio.
“One reason is that corporate balance sheets have improved significantly since the global financial crisis. Companies have reduced leverage and steadily increased
profitability over the past 10 to 15 years, meaning the corporate sector today is much higher quality and more defensive than it used to be,” Karunakaran said.
The firm is particularly positive on US corporate credit.
“Within that universe, we currently favour the US, partly because the Fed (US Federal Reserve), in our view, is not on the same rate hiking path that the RBA (Reserve Bank of Australia) and other central banks have been forced onto. On top of this, US corporate fundamentals remain very strong. Themes like the AI boom are heavily US-centric and could continue to benefit American companies,” he said.
“While we favour higher-quality, defensive assets, interestingly we still see value in high-yield corporate bonds. While they’re often associated with the ‘junk bond’ label, the quality of the high-yield market has improved dramatically over the past
decade and today looks much closer to investment-grade benchmarks than many people realise.”
The role of emerging market debt Emerging market debt remains an important part of Capital Group’s strategic asset allocation, largely because of its diversification benefits.
“Emerging markets are a really interesting area,” Karunakaran said.
Historically, emerging market debt has been a powerful diversifier in portfolios, sometimes providing outsized returns relative to other credit assets.
“2025 was a good example, with emerging market debt delivering some of the strongest returns in the fixed income universe.
“That said, tactically we’re currently underweight emerging market debt.
Not because we’re concerned about the quality of issuers - in fact, we think emerging market fundamentals have improved materially - but because valuations are now quite tight relative to what we’re seeing in corporate credit markets.”
Why active management matters
Karunakaran argues that active management is particularly important in today’s environment as investors navigate elevated market volatility and shifting economic conditions.
“In sovereign bonds, markets have been grappling with changing central bank expectations, inflation concerns and shifting growth outlooks,” he said.
“At the same time, credit spreads at the index level look relatively tight versus history. But beneath the surface, individual issuers and sectors can still offer compelling value opportunities. Active
management allows investors to take advantage of those discrepancies.”
For Capital Group, active management means having the flexibility to allocate across multiple areas of the fixed income market.
“Duration management is another critical area. In an environment where interest-rate volatility remains elevated, having flexibility around duration exposure is essential. It’s not just about buying 10-year government bonds; we go much more granular to identify which countries and which parts of yield curve are most attractive at any given time.”
The rise of artificial intelligence provides a useful example of why selectivity is increasingly important.
“It’s been a dominant theme in equity markets for years, but it’s only recently become relevant to fixed income as
large hyperscalers have started issuing significant amounts of debt,” he said.
“As credit investors, we need to determine where that debt issuance offers attractive risk-adjusted returns and where risks are too high. Credit investing is asymmetricyou don’t participate fully in upside growth like equity investors do, but you are exposed to downside risks if a company defaults.”
Within AI-related debt issuance, Capital Group favours higher-quality issuers with strong balance sheets and resilient cash flows.
“While there may be questions around future growth rates, their existing businesses are extremely resilient, making them attractive ways to generate 6 per cent to 7 per cent yields today.”
Fixed income’s renewed role in portfolios
Today’s higher-yield environment has fundamentally changed the role of fixed
income in portfolio construction. Investors can now achieve attractive income outcomes through liquid, transparent and diversified portfolios without needing to take excessive risk.
“Historically, advisers had to stretch for returns to meet client income expectations. To generate 4 per cent, 5 per cent or 6 per cent income, investors often had to take on more credit risk, invest in illiquid private assets, or use very concentrated active strategies,” Karunakaran said.
“Today, global credit yields mid to high single digits, which means investors may achieve those return targets through transparent, fully liquid and well diversified portfolios.”
According to Karunakaran, advisers should focus on three key principles: diversification, liquidity and flexibility.
“Many advisers focus heavily on income,
but diversification has somewhat fallen off the radar, partly because bonds struggled to diversify portfolios in periods like 2022,” he said.
“But looking ahead, certain parts of the bond market can once again provide meaningful diversification benefits, particularly fixed-rate bonds in markets where central banks are cutting rates.”
Liquidity, meanwhile, remains a critical but often overlooked portfolio attribute.
“Liquidity is absolutely critical. It’s something investors often don’t think about until a crisis hits - and by then it’s too late.
Having liquidity in portfolios allows investors to be flexible and tactical. If markets experience a major sell-off, liquidity gives you the ability to buy attractive assets at discounted prices.
Ultimately, Karunakaran argues that advisers need to think about fixed income
as more than simply an income-generating asset class.
“Once you recognise those dual objectives – income and diversification - it opens up the full global fixed income universe. Rather than focusing narrowly on Aussie floating-rate bonds or hybrids, advisers should think more broadly about the opportunities available across global fixed income markets and build diversified portfolios that can deliver both income and diversification,” Karunakaran said.
[AI]
HAS BEEN A DOMINANT
THEME IN EQUITY MARKETS FOR YEARS, BUT IT’S ONLY RECENTLY BECOME
RELEVANT TO FIXED INCOME
AS LARGE HYPERSCALERS HAVE STARTED ISSUING SIGNIFICANT AMOUNTS OF DEBT
Haran
Karunakaran Fixed income investment director at Capital Group
Real Estate: A market
shaped by supply constraints
Higher interest rates may have altered property financing conditions but it can also expand investment opportunities and may support improved pricing dynamics.
Australia’s housing shortfall remains a defi ning theme
Australia’s housing shortage has become one of the most significant forces shaping the real estate market, with supply constraints continuing to influence both investment opportunities and financing conditions.
According to Andrew Lockhart, group CEO and managing partner at Metrics Credit Partners, the current imbalance refl ects a combination of long-standing structural issues and more recent disruptions that have compounded the problem.
“Australia’s housing shortfall reflects both structural issues and cyclical disruption. Planning constraints have long limited new supply, and when COVID hit, developer confidence fell, bank funding tightened and construction costs rose sharply, making many projects uneconomic.”
“At the same time, population growth rebounded much faster than expected,
widening the gap between supply and demand.”
While conditions had started to improve, new challenges have emerged.
“Supply was beginning to recover, but renewed geopolitical uncertainty and higher oil prices have pushed construction costs higher again. That is likely to delay the recovery further and keep supply shortages in place for longer.
“Over time, constrained supply is likely to support housing values despite higher rates and recent tax and government policy changes. Longer term, it reinforces the opportunity for private debt to fill the funding gap left by banks and support experienced companies in undersupplied markets.”
Higher rates are reshaping lending markets
Higher interest rates have altered financing conditions across the property sector, but Metrics argues they have not fundamentally changed the
STRUCTURING A LOAN PORTFOLIO SHOULD ENSURE INVESTORS ARE NEVER OVER-EXPOSED TO ONE INVESTMENT, ONE SECTOR OR ONE COUNTERPARTY. RISK SHOULD BE SPREAD ACROSS AN APPROPRIATELY DIVERSIFIED PORTFOLIO OF LOANS.”
Andrew Lockhart Group CEO and managing partner at Metrics Credit Partners
characteristics of high-quality projects.
“Higher interest rates have raised funding costs, but that does not change the quality of a genuinely strong project. Some marginal developments will naturally fall away, and that is as it should be. If a project cannot absorb a more normal cost of capital, it was probably too weak to fund in the first place.”
Instead, Lockhart says the more significant consequence has been the impact on traditional lenders.
“The more important consequence is that higher rates and macro uncertainty can push banks back out of project financing, as we saw through COVID. When that happens, private lenders are in a stronger position.”
“For Metrics, this environment can expand access to investment opportunities and may support improved pricing dynamics.”
Despite the changing backdrop, Lockhart
says its investment approach remains grounded in credit fundamentals.
“Our approach does not need to change materially as we continue to focus on the core fundamentals of managing credit risk: disciplined risk selection, strong structure and portfolio construction –backing appropriately structured debt with the right covenants and security, maintaining diversification, and favouring shorter-dated exposures.
“That gives us better control of risk, reduces spread sensitivity and allows us to recycle capital efficiently as opportunities emerge.”
Residential development remains the core focus
Real estate is often discussed as a single asset class, but Metrics says opportunities vary significantly across sectors, with residential development remaining the largest component of the firm’s lending portfolio.
“Around two thirds of our real estate lending supports residential development. That includes apartments, townhouses, house-and-land projects, and both land acquisition and construction funding.
“We are proud of that because Australia needs more housing supply, and private debt has an important role to play in supporting experienced developers to deliver it.”
Industrial assets represent the nextlargest allocation.
“Industrial is the next largest part of the book, typically around 15-20 per cent. It has been supported by strong underlying demand drivers including population growth, e-commerce and occupier demand for better-quality, more sustainable assets.”
By comparison, retail and office exposures remain limited.
“Retail and office have been a very small
part of the portfolio, which has served investors well given the headwinds in both sectors.”
For the firm, diversification remains a central principle.
“The broader point is that structuring a loan portfolio should ensure investors are never over-exposed to one investment or one sector. Risk should be spread across an appropriately diversified portfolio of loans.”
Understanding the di erence between debt and equity
Metrics describes real estate debt as the more defensive end of the capital structure, offering a different risk-return profile to equity investments.
“Real estate debt sits lower on the riskreturn spectrum than equity. In simple terms, it is the more defensive part of the capital structure. Investors should generally expect debt to deliver lower but more stable returns, while equity
offers higher upside but materially more volatility and downside risk.”
The distinction begins with where each investment sits within the capital stack.
“Senior secured debt has first claim over cash flows and asset value. Junior or subordinated debt sits behind that, and equity sits last. So, if something goes wrong, debt is repaid ahead of equity, and secured debt is repaid ahead of everything else.”
Equity investors, meanwhile, assume greater risk in exchange for greater participation in upside.
“Equity is different because, in exchange for taking the first loss risk, investors participate more fully in any upside. That means the range of outcomes is much wider. If a project performs strongly, equity captures that. If it does not, equity absorbs the risk first.”
Metrics says both debt and equity can
have a place within diversified portfolios, but transparency remains critical.
“Investors need to understand exactly what they own, where it sits in the structure and what risks they are being paid to take.”
Focusing on the risks that matter When assessing investments, Metrics focuses on three key areas: market risk, delivery risk and sponsor risk.
“That framework is simple, but it is effective because it keeps attention on the issues that matter most when you are trying to protect investor capital.
“Market risk is about assessing the likely future demand for the completed project and understanding how exposed an investment is to changes in the economy, policy settings, supply conditions and pricing. We want to understand not just where the market is today, but how resilient the project or borrower is if conditions deteriorate.
“Project delivery risks looks at factors such as labour availability, contractor capability, supply chains and construction costs. We deal with these risks both upfront through underwriting, contingencies and structure, and then through active ongoing portfolio risk management.”
At the same time, experience navigating previous disruptions also remains important.
“Metrics has managed a large loan book through COVID, through volatile economic conditions and periods of geopolitical risk, and through a sharp rise in interest rates. That experience matters, because risk management is not theoretical when conditions become difficult.
“When it comes to sponsor risks, we look closely at track record, financial capacity and alignment of interest. Over time, the best way to manage that risk is to lend repeatedly to counterparties who have demonstrated they can perform, while
ensuring the portfolio is never overly reliant on any one borrower.”
The firm’s approach draws heavily on traditional institutional banking disciplines.
“Our assessment of risk is very similar to what you would see in large corporate and institutional banks, noting a large number of our origination, risk and portfolio management teams have experience working within banks.”
Ultimately, Metrics argues investors should focus on managing risk rather than avoiding it altogether.
“You don’t get paid not to take risk but you must take appropriate risk and manage it effectively, and when assessing the risk of any transaction, debt or equity, it is done with the preservation of our investors’ capital at the forefront of everything that we do.
“At the end of the day, managing investors capital is a privilege.”
Why investors are looking at real estate debt
For investors seeking income and downside protection, Metrics believes real estate debt can provide a compelling alternative to traditional fixed income and listed property investments.
“The main attraction of real estate debt is that it aims to provide stable, contractual income with meaningful downside protection. Returns are supported by loan repayments, security over underlying assets and, in Australia, a legal framework that is generally lenderfriendly.”
The firm also highlights the benefits of floating-rate structures.
“Most loans are also floating-rate, which means returns adjust as base rates move and can provide a degree of inflation protection that traditional fixed-rate bonds do not.”
While listed property remains a common route to gaining real estate
exposure, Metrics argues the risk profile differs materially, something investors need to be more aware of.
“Listed property has historically been a useful way to access real estate, but in practice it often behaves much more like equity than debt. Investors are exposed not just to property assets, but to broader equity market volatility.”
Private real estate debt, by contrast, is primarily designed to be an income investment.
“Private real estate debt is different. It is primarily an income investment and its performance is much more closely linked to the underlying loans.
“For portfolio construction, that can be an important distinction.”
Expanding access to private real estate debt
As the private debt market has matured, investors have gained a wider range of access points to real estate strategies,
with Metrics now offering both listed and unlisted investment options.
“Retail investors can access listed vehicles on the ASX and selected unlisted retail funds via financial advisers or major investment platforms.”
Lockhart says the growing range of structures available gives investors greater flexibility when building portfolios.
“The important point is that investors today have more than one way to access private debt, depending on their liquidity needs, investment horizon and portfolio objectives.”
For Institutional and Investment Professional Use Only
Metrics makes no representation or warranty as to the accuracy, completeness, reliability or currency of the content. It is not intended to be a complete statement or summary of any markets, developments or securities referred to herein.
The content is provided for informational purposes only and is not intended to provide you with financial advice. It has been prepared without taking into account a particular person’s objectives, financial situation or needs.
The content does not purport to identify the nature of a specific market or other risks associated with any investments described within it and does not constitute legal, taxation, investment or accounting advice. If you require financial advice that takes into account your personal objectives, financial situation or needs, you should consult your licensed or authorised financial adviser.
Any opinions expressed in this content are subject to change without notice and may differ from, or be contrary to, opinions expressed by other business areas or companies within the same group as Metrics as a result of using different assumptions and criteria.
The content should not be construed as an offer or solicitation to buy or sell any financial product in any jurisdiction. To the extent permitted by law, Metrics excludes all liability for any loss or damage arising in any way due to or in connection with the publication of the content, including by way of negligence. Forward looking statements should not be relied upon. All investments contain risk and may lose value. Past performance is not a reliable indicator of future performance.
Infrastructure: Seeking underappreciated infrastructure themes
Beyond offering stable cashflow, infrastructure is evolving rapidly as an asset class with a focus on transition infrastructure that can drive decarbonisation.
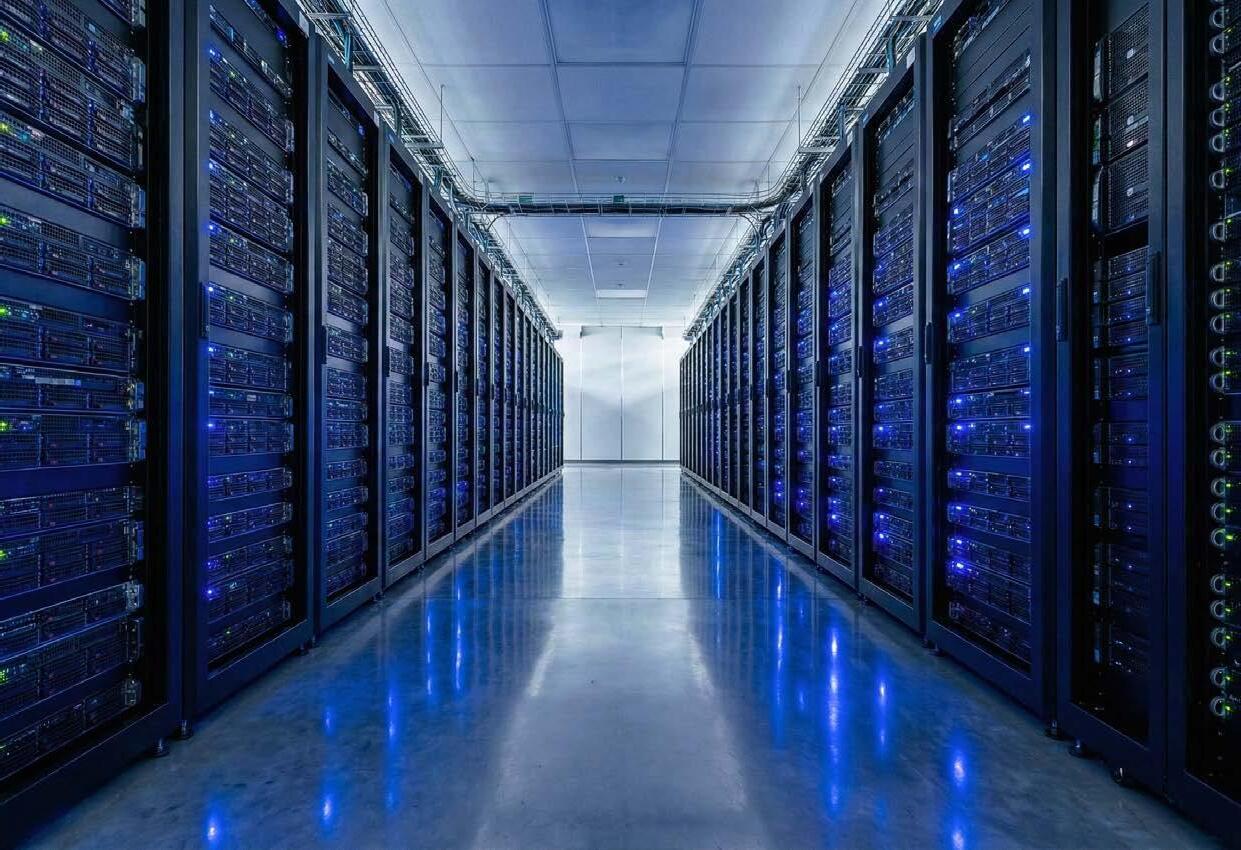
Infrastructure is often viewed as a stable, inflation-protected asset class comprising essential physical assets such as ports, toll roads and airports. But according to EQT Partners managing director Sam Franklin, that definition no longer captures the full picture.
Infrastructure has evolved from a narrow set of traditional assets into a much broader investment universe defined by essential services that underpin modern society.
“Particularly with the rise of artificial intelligence (AI), increasing energy demands and decarbonisation, sustainability - I think that has been the real shift over the last 10, 15 years in our experience.”
Why infrastructure has become mainstream Infrastructure is playing an increasingly prominent role in portfolio construction, a shift Franklin says has been driven by what he describes as “a push and a pull factor”.
On one hand, heightened market volatility has pushed investors toward assets with stronger downside protection.
“The level of volatility that has become almost the new normal over the past five to 10 years in the global macro and markets… has driven people to look for businesses that have a much stronger level of downside protection.
“I think the downside protection of infrastructure comes back to that point of the essential nature of the underlying businesses, the underlying assets that are in the infrastructure portfolio.”
At the same time, infrastructure has become more visible as major structural trends reshape the global economy.
“The rising increase in the need for connectivity, the rising increase in the need for energy infrastructure, the growth of AI… have brought infrastructure as an asset class more front and centre.
“I think those are the two factors that have made it a more interesting and visible asset class for investors - and therefore a more interesting alternative for people to look at.”
THE GROWTH OF AI… HAVE BROUGHT INFRASTRUCTURE AS AN ASSET CLASS MORE FRONT AND CENTRE.
Sam Franklin EQT Partners managing director
The role of infrastructure in a diversifi ed portfolio
Infrastructure offers a combination of lower volatility, downside protection and competitive long-term returns to investors.
As Franklin puts it: “But also at the same time, a really attractive return profile - I think that’s where infrastructure sits. You get a more narrow span of outcomes than you might get in all of those other asset classes.”
“You have lower volatility, downside protection is underpinned by large asset bases, longterm contracts, strong market positions or regulatory frameworks within their markets.
“But there is also potential for growth… linked to long-term macroeconomic growth, population growth, electrification or ageing populations.”
Franklin says infrastructure can potentially provide investors with income, inflation protection and diversification.
“Infrastructure at its heart is about businesses, the essential nature of the
services provided often does give you downside protection, it often gives you inflation protection as well, because often these businesses are passing through any underlying inflation,” he says.
A broad spectrum of investment opportunities
Infrastructure spans a wide range of investment profiles, from growth-oriented assets through to traditional incomegenerating investments.
At one end of the spectrum are emerging opportunities in energy generation and storage.
“On one end of the spectrum of infrastructure, there is a significant amount of generation capacity in energy, for example, storage capacity with the likes of batteries, that has not been built today .. Infrastructure investing in developing these assets into a generating portfolio, that’s actually quite a strong and attractive growth thematic.”
At the other end sit more traditional
infrastructure assets such as ports, toll roads and airports.
“..Where you really just link to GDP, maybe some growth through population growth, inflation protection, where you might be generating more low-single digits, more of a yield profile.”
This breadth gives investors considerable flexibility when allocating capital.
“Infrastructure as a spectrum, you can actually achieve whatever outcome you’re looking for to some extent, not to oversell it,” Franklin laughed.
The
biggest misconception about infrastructure
According to Franklin, the biggest misconception is that investors still view infrastructure as a passive asset class focused solely on stable cash flows.
“People still are thinking about toll roads and airports - businesses that have a very, very stable, but very low return portfolio profile,
primarily underpinned by cashflow generation.
“When [EQT] is talking about infrastructure, we’re talking about the entire spectrum, which is really building out the underlying asset base that can drive decarbonisation .. we’re talking about AI infrastructure - that is a genuine large scale long term growth thematic,” he said.
“[Infrastructure] is actually an area where you can drive real fundamental operational value creation and take advantage of these long term growth targets.”
Why manager selection matters
As infrastructure becomes more operationally intensive, manager selection is increasingly important.
“The ability for a manager to take advantage of those growth tailwinds requires very strong portfolio operation capabilities,” Franklin says. “We need to be matching that amount of capital in order to provide the data infrastructure that they’re demanding.”
“The market is evolving so rapidly: we do require very, very deep global sub-sector, sector expertise, because this evolution is a global evolution.”
Scale, expertise and operational capability are becoming critical differentiators as infrastructure opportunities become more complex.
EQT’s approach to infrastructure investing
EQT approaches infrastructure investing with a long-term mindset grounded in its industrial heritage.
“Focused on delivering outcomes, not for five or 10 years, but for 50 to 100 years and bringing real industrial expertise to their portfolio - that was the heritage and the way EQT was founded.”
A key part of that strategy is partnering with independent operating experts throughout the investment lifecycle.
“One thing that we really pride ourselves on differentiating is that we partner with external, independent operating industrial experts who
we are looking to work with through the entire investment lifecycle,” he says.
“So we are working with these people to identify sector trends and sector thematics, leveraging our internal global sector activities. We are looking to get ahead of those trends from an investment perspective, proactively identify investment opportunities…”
The framework for investing
When assessing potential investments, Franklin says EQT applies a simple but powerful framework: invest in businesses that provide essential services to society.
“We are looking for businesses that we believe are less susceptible to disruption because of the critical nature that they play in the ongoing functioning of communities, countries of the world,” he says. “That’s a really important framework for us.”
Another key characteristic is strong downside protection.
“That might be through significant asset
backing,” he says. “Where the business that you’re buying is really backed by fundamental underlying assets, it might be long-term contracted cash flows or very strong revenue visibility through the cycles of businesses that are not exposed to macroeconomic cycles and which have very strong long-term visibility.”
The firm is also focused on active value creation rather than simply collecting income.
“We’re not looking to just buy a passive asset and kind of clip the ticket, we’re actually looking to take advantage of these longterm tailwinds through active value creation,”
Franklin says
The most underappreciated themes: energy and digital infrastructure
Franklin believes energy and digital infrastructure remain among the most underappreciated investment opportunities for Australian investors.
Decarbonisation continues to drive significant investment in renewable
energy, energy storage and emerging energy technologies, with trillions of dollars still required globally to meet existing commitments.
At the same time, electrification, growing data centre demand and the rise of AI are creating unprecedented demand for new energy infrastructure.
On the digital side, Franklin argues investors often focus on data centres while overlooking the broader ecosystem required to support AI adoption, including connectivity networks, telecommunications upgrades and satellite infrastructure.
“[Energy] is underappreciated … Whether you believe AI is a bubble or it is not, there are fundamental underlying use cases for AI that require significant investment that’s not already been delivered,” he says.
“The global and also developed market demand for energy infrastructure is significantly above what has ever been at any other point in history.”
Franklin points to the substantial digital infrastructure gap that still exists, even under conservative assumptions for AI adoption.
“There is still a significant gap there,” he says. “That trend has a long way to run and it’s not just in the data centre space. These assets require significant adjacent infrastructure buildout - fibre and connectivity to enable data export. More broadly, there is an opportunity for further enhancement of connectivity coverage particularly in vast land masses like Australia.
“And so, things like satellite infrastructure to provide connectivity into more remote regions are really important, fundamental elements that are all going to be underpinned by these long-term tailwinds coming out of the AI revolution. “The level of digital infrastructure required beyond just building big boxes is somewhat underappreciated as well.”
Investing in long-term tailwinds
One of infrastructure’s key attractions, Franklin says, is that the underlying themes tend to endure for decades.
“The good thing about infrastructure is the tailwinds don’t change. We’re only investing in tailwinds that are gonna be around for 20, 30, 50 years rather than maybe consumer trends or things like that,” he says.
“Rising energy needs, increasing demand for connectivity and digitalisation, aging populations, long-term globalisation or deglobalisation at the fringe. These trends won’t change. That’s the reason why infrastructure has a level of downside protection.”
What may change is how those needs are met.
“And so changing tastes in energy, for example, won’t move the needle materially on the investment needs because I think people may be paid too much attention to, say renewable energy in favour or out of favour.
“At the end of the day, the sun is free, the wind is free. It’s the cheapest form of generation. People are going to invest in it regardless of whether or not someone says that climate change is real or not,” Franklin argues.
“WE ARE LOOKING FOR BUSINESSES THAT WE BELIEVE ARE LESS SUSCEPTIBLE TO DISRUPTION BECAUSE OF THE CRITICAL NATURE THAT THEY PLAY IN THE ONGOING FUNCTIONING OF COMMUNITIES, COUNTRIES OF THE WORLD.”
Sam Franklin EQT Partners managing director
For general information only and does not constitute personal financial advice, or an offer, invitation, solicitation or recommendation to invest. For wholesale clients only as defined under the Corporations Act 2001 (Cth). Representations of past performance are not indicative of future performance. Investors should seek independent professional advice before making investment decisions.
Concentration risk is reshaping index investing
It is no longer about active versus passive but rather how the two can be used together in portfolios.
Passive ETFs have proved enormously successful, but the conversation is becoming far more nuanced. Investors who believe they are gaining diversification through broad-based index ETFs may, in reality, be making a concentrated bet on a handful of mega-cap stocks.
“What an index was 20 or 50 years ago is very different to what it is today. Many market-cap indices have fundamentally changed because of the concentration effect,” Macquarie Asset Management’s head of ETFs, Blair Hannon, said.
“The belief that buying an index automatically gives you diversification has changed. Yes, you own 500 companies, but your outcome, at this point, is being driven by the top six to 10 stocks.”
Hannon warns that traditional marketcap indices such as the S&P 500 have
quietly evolved into highly concentrated portfolios, with a significant share of returns now driven by a small cluster of companies.
“In the US, the S&P 500 has become much more concentrated at the top. 10 years ago, the top 10 stocks were just under 20 per cent of the index – now that’s roughly doubled,” he said.
“If the index returned 10 per cent, about half of that – 5 per cent – is coming from roughly six companies. Your outcome is now being defined by a handful of names.”
Active and passive ETFs are no longer rivals
Against this backdrop, Macquarie Asset Management argues the active-versuspassive debate is effectively over.
“It’s not about ‘versus’ anymore – it’s about how you use them together in a portfolio,” Hannon said.
THE BELIEF THAT BUYING AN INDEX AUTOMATICALLY GIVES YOU DIVERSIFICATION HAS CHANGED.
Blair Hannon
Macquarie Asset Management’s head of ETFs
He believes investors relying solely on passive strategies have limited ability to generate alpha from the underlying funds.
“You become an asset allocator to drive returns. That’s fine, but it’s a difficult job.”
“We’ve seen a clear shift towards more index-aware, enhanced, or systematic investing – more data-driven, more breadth, and smaller bets on the upside and downside.”
The challenge of consistent alpha in active ETFs
According to Hannon, the holy grail of active ETF investing is consistency of alpha.
“A manager who gives you 30 per cent excess one year and then hands it all back the next year is not a great client experience.”
A strong active ETF is not only about
standout performance but also requires the fund manager you partner with to have a disciplined process, transparency and adviser support.
“The best thing an adviser can do with an active manager is hold them to account. The job of an active manager is to outperform,” he said.
Hannon further added that consistency remains critical.
“Advisers don’t want to tell clients, ‘This manager hit it out of the park last year and has given it all back this year.’”
“A high-quality active manager should feel like a partner – someone helping you build a portfolio that’s in a better place than if you weren’t allocating to them.”
“There’s no silver bullet – you want managers that are tested through different market cycles, transparent
about what they’re doing, and willing to explain underperformance, not put their heads in the sand.”
Hannon is quick to acknowledge the role passive ETFs have played in improving investor outcomes.
“They lowered fees through scale, and that’s unequivocally beneficial – more money in investors’ pockets is always better,” he said.
“The shift from index funds to exchangetraded funds opened up the next leg of accessibility – suddenly investors could buy international markets, emerging markets, and, more recently, bond markets with a single trade.”
Why bond
indices
behave di erently Advisers are also being urged to recognise that bond indices are constructed very differently from equity indices.
“Bond indices are a different beast. They’re not market-cap weighted –they’re debt-weighted. The most indebted issuers become the biggest weights in the index.”
“From a defensive portfolio perspective, an index that simply gives the highest weights to the most indebted companies is fundamentally at odds with what you’re trying to achieve.”
For that reason, Macquarie Asset Management argues active management in fixed income can be particularly compelling, “especially when you can get an active ETF at a similar price to a passive index fund,” Hannon said.
“A HIGH-QUALITY ACTIVE MANAGER SHOULD FEEL LIKE A PARTNER – SOMEONE HELPING YOU BUILD A PORTFOLIO THAT’S IN A BETTER PLACE THAN IF YOU WEREN’T ALLOCATING TO THEM.”
Blair Hannon
Macquarie Asset Management’s head of ETFs
Private Credit: Built for income, tested by volatility
Private credit funds have moved into the spotlight and are filling the gap in the market left by traditional lending providers.
Private credit has evolved from a new asset class into an increasingly important part of the investment landscape, attracting capital from investors seeking stable income, downside protection and diversification. Its rise has coincided with a period of significant economic disruption, from the COVID-19 pandemic and inflation shock through to higher interest rates, geopolitical uncertainty and increased volatility across public markets.
At the same time, regulatory changes have reshaped traditional lending markets, creating opportunities for private capital providers to fund borrowers in areas where banks have become more constrained.
For Andrew Lockhart, group CEO and managing partner at Metrics Credit Partners, those structural shifts have reinforced the role private credit can play within portfolios, both as a source of contractual income and as a mechanism
seeking to preserve capital through different stages of the economic cycle.
Why private credit has moved into the spotlight
Recent years have highlighted the value of investments capable of generating stable income while navigating an increasingly uncertain market environment, according to Lockhart.
“Since COVID, markets have been marked by inflation, higher rates, geopolitical uncertainty and more volatile public asset prices.”
Against that backdrop of inflation, rising interest rates and heightened market volatility, private credit has offered characteristics many investors have been seeking.
“Private credit’s floating-rate, contractual income profile has been attractive to investors looking for resilience and a degree of inflation protection.”
INVESTORS ARE NOT LOOKING FOR SURPRISES. THEY ARE LOOKING FOR ASSETS THAT CAN CONTINUE TO GENERATE INCOME WHILE SEEKING TO PRESERVING CAPITAL, AND THAT IS PRECISELY WHERE PRIVATE CREDIT CAN PLAY A MEANINGFUL ROLE.”
Andrew Lockhart Group CEO and managing partner at Metrics Credit Partners
Filling the gap left by traditional lenders
The growth of private credit has coincided with a shift in the way lending is provided across the economy, with Metrics arguing that regulatory changes following the Global Financial Crisis (GFC) altered the economics of certain lending activities for traditional banks.
“Private credit is now an important part of how capital is provided across the economy.
“Stricter capital regimes imposed on the banks post-GFC resulted in parts of the lending market becoming less feasible for banks to service on a return on capital basis – particularly corporate and real estate development lending.”
This has created an opportunity for private lenders to step into areas where borrower demand remains strong.
“That is where private credit matters:
it can continue to provide funding to good borrowers of sound credit quality when the banking system is less able to do so.”
Designed to deliver through the cycle
Since defaults inevitably rise when economic conditions weaken, disciplined lending and strong security structures can help support outcomes for investors, making private credit an attractive income generation tool through market cycles.
“Private credit aims to deliver contractual income through the cycle.
“Defaults can rise when conditions weaken, but well-structured lending with appropriate security, covenants and controls imposed on a borrower have historically delivered strong recovery outcomes, including through periods such as the GFC and COVID.”
For this reason, periods of market uncertainty also highlight the
important role of private credit within portfolios.
“In more volatile markets, stability becomes more valuable. Investors are not looking for surprises. They are looking for assets that can continue to generate income while seeking to preserving capital, and that is precisely where private credit can play a meaningful role.”
Finding a place in diversifi ed portfolios
Private credit’s growing popularity has also prompted investors to consider where it fits within a broader portfolio framework. While there is no universal allocation, Lockhart believes the asset class has established a role within the fixed income component of diversified portfolios.
“There is no single allocation that suits every investor. However, private credit is increasingly incorporated within the defensive or income-producing part of portfolios, as an alternative to traditional fixed income assets such as bonds .”
Understanding the risks
Like any investment strategy, private credit is not without risk, which is why there is so much importance placed on investors’ understanding of both the opportunities and the challenges that come with the asset class.
“Private credit, like any other investment, is not risk free and no serious manager should pretend otherwise. Loans can and do go wrong, particularly when conditions are harder.”
The firm’s view is that risk management begins with underwriting, structure and diversification.
“Structuring a loan portfolio should ensure investors are never over-exposed to one investment and that risk is spread across an appropriately diversified portfolio of loans.”
“If that discipline is maintained, losses should be contained even when some individual loans do not perform as expected.”
Lockhart also notes that some of the concerns raised about private credit internationally stem from different market structures.
“The issues that have attracted attention in parts of the US listed credit market have been largely about lending to technology companies during a period of significant technology change and liquidity mismatch. If you hold longdated, illiquid loans and offer frequent redemption, that can create problems.
“In Australia, listed private credit vehicles are generally backed by shorter-dated loans and other liquidity management tools, which means cash flow is better aligned with investor liquidity needs.
“That does not remove risk, but it is a very different starting point.”
Why manager skill matters
As private credit has grown, so too has the importance of manager selection with the ability to manage risk consistently
through changing market conditions emerging as one of the key differentiators between managers in this space.
“Manager skill is critical in private credit, particularly in more challenging conditions.”
Lockhart says successful private credit investing involves more than simply sourcing opportunities.
“At Metrics we often say we do three things: raise capital, originate and deploy capital and manage risk.
“The third aspect, managing risk, is particularly important, as our business is structured with a strong focus on managing risk in a disciplined way to support our ability to meet our commitments to investors.”
At the same time, scale and experience can also provide important advantages.
“Experience and scale matter because they allow you to see more opportunities,
“A GOOD PRIVATE CREDIT INVESTMENT IS ONE WHERE THE RISKS ARE CLEAR, THE STRUCTURE IS STRONG AND THE INVESTOR IS BEING ADEQUATELY COMPENSATED FOR THE RISK THEY ARE TAKING.”
Andrew Lockhart Group CEO and managing partner at Metrics Credit Partners
say no more often and build a portfolio that is properly diversified.
“They also matter when markets are stressed. At Metrics, we have experience managing a large loan portfolio and equity projects through COVID and through periods of economic and geopolitical volatility.
“That is when you see whether a manager really understands risk or not.”
A disciplined approach to credit assessment
The foundation of any private credit strategy is the process used to assess and manage risk, and Lockhart said those standards should remain consistent regardless of the economic backdrop.
“The assessment process should be rigorous in all market conditions, not just when markets are difficult.”
The firm employs a structured framework supported by both internal and external
expertise, with particular attention paid to downside protection.
“Metrics applies a disciplined credit process supported by legal, valuation and technical experts, and our internal framework is aligned to a ratings-based approach.
“We focus on structure from the outset, including equity buffers, guarantees, covenants and other protections that improve downside resilience.”
Where risks are higher, those risks must be reflected appropriately.
“If a transaction clears that hurdle, the risk is reflected in the terms and pricing.
“In more uncertain markets, that often means wider margins, tighter structure and, in some cases, walking away altogether.”
Selectivity remains a key part of the process, with Metrics only funding ~20% per cent of the deals it sees.
Final approval then rests with the firm’s investment committee, keeping the fundamental goals of the firm in focus.
“The final decision sits with an experienced investment committee whose job is to ensure the opportunity fits our risk parameters.
“Importantly, when assessing any transaction, we never lose sight of the fact that we are here to deliver good investment outcomes for our investors.”
What makes a good private credit investment?
As markets continue to adjust to higher interest rates and ongoing volatility, Metrics believes the characteristics of a strong private credit investment remain relatively straightforward.
“A good private credit investment is one where the risks are clear, the structure is strong and the investor is being adequately compensated for the risk they are taking.”
Those investments should also form part of a broader portfolio approach, while also taking into consideration who is actually managing the capital.
“It should sit within a portfolio that is appropriately diversified. It should be managed by a team with the experience, discipline and track record to respond when conditions change and the skillset and resources necessary to manage assets if borrower performance deteriorates.”
For Institutional and Investment Professional Use Only
Metrics makes no representation or warranty as to the accuracy, completeness, reliability or currency of the content. It is not intended to be a complete statement or summary of any markets, developments or securities referred to herein.
The content is provided for informational purposes only and is not intended to provide you with financial advice. It has been prepared without taking into account a particular person’s objectives, financial situation or needs.
The content does not purport to identify the nature of a specific market or other risks associated with any investments described within it and does not constitute legal, taxation, investment or accounting advice. If you require financial advice that takes into account your personal objectives, financial situation or needs, you should consult your licensed or authorised financial adviser.
Any opinions expressed in this content are subject to change without notice and may differ from, or be contrary to, opinions expressed by other business areas or companies within the same group as Metrics as a result of using different assumptions and criteria.
The content should not be construed as an offer or solicitation to buy or sell any financial product in any jurisdiction. To the extent permitted by law, Metrics excludes all liability for any loss or damage arising in any way due to or in connection with the publication of the content, including by way of negligence. Forward looking statements should not be relied upon. All investments contain risk and may lose value. Past performance is not a reliable indicator of future performance.
Narrow markets, AI winners and the return of active investing
The rise of AI-focused stocks has widened the gap between winners and the rest of the market so it is more important than ever to separate out the noise.
Markets may be sitting near all-time highs, but that headline masks a far more uneven reality. A relatively small group of stocks are doing the heavy lifting, while much of the broader market is moving very differently – or not at all.
That divergence is now a defining feature of global equities, according to PM Capital portfolio manager Kevin Bertoli.
“Investors reference the concentration of Magnificent 7 in US indices, but what’s also important to remember is that over 70% of the MSCI World Index today is the US market. So, we have very narrow sector and market leadership.”
In part, that’s because the global economy is as narrow as it has ever been and the mega-cap companies are able to dominate across sectors and geographies. This is being driven by technology leadership. Technology means businesses are more easily able to attract
consumers from any jurisdiction around the world.”
That concentration has created what Bertoli sees as a highly segmented market, increasingly shaped by a small number of dominant themes – particularly artificial intelligence (AI).
The rise of AI winners and everyone else AI has not just created new market opportunities; it has widened the gap between winners and the rest of the market.
“We are in a scenario where there are ‘AIhaves’ and ‘AI-have-nots’. If you’re in the AI-have basket, people are willing to buy you at almost any price – it’s a very large momentum trade,” Bertoli said.
For companies outside that cohort, the picture is very different.
“You’re either a company with a business model which is potentially under threat
“WE ARE IN A SCENARIO WHERE THERE ARE ‘AIHAVES’ AND ‘AI-HAVENOTS’. IF YOU’RE IN THE AI-HAVE BASKET, PEOPLE ARE WILLING TO BUY YOU AT ALMOST ANY PRICE – IT’S A VERY LARGE MOMENTUM TRADE.”
Kevin Bertoli
Capital portfolio manager
PM
from AI, or you’re a business that’s not overly impacted, positively or negatively, by it. If investors perceive AI as a threat, they aren’t willing to take the risk, even though valuation dynamics have changed materially. If a company is in the second basket, you’ve become uninteresting, the story can be quite boring compared to the opportunity in AI, and therefore you’re not really a focus for investors today.”
This uneven attention, he argues, is not confined to a single sector and it is visible across global markets. “The reality is there are a number of sectors that are significantly off their highs. There’s a lot of opportunity when we lift the hood of markets. When today’s market drivers crack, you’re going to see sector rotation, and that’s where active managers can make a difference.”
Why dispersion matters for active investors
In an environment defined by narrow leadership, the role of active management
becomes more dependent on separating signals from noise.
“Investors, whether professional or retail, have never had more information than they have today,” Bertoli said. “With more information, people will try to profit from that information.”
Rather than reacting to short-term narratives, PM Capital’s approach is deliberately long term and valuation driven.
“What we’re trying to do as active and longterm managers of capital is to arbitrage our long-term time horizon and long-term process against the market’s short-term preoccupations.”
That often means moving from areas of excessive enthusiasm into overlooked or misunderstood parts of the market. “We think that’s where the opportunity is for us as investors.”
Bertoli is also direct about the distinction between genuine active management and index-like portfolios that behave differently more in name than in practice.
“We think active management, in some capacity, gets a bad rap, but I think that’s because a large percentage of active managers are actually closet index investors,” he said.
As dispersion across markets increases, he believes the gap between the two will become more visible.
“Looking at the real active managers, I think there’s a unique place for them, given current conditions. The opportunity for active managers is where markets become overly focused on certain things and forget other factors at play.”
Concentration, discipline and long-term ownership
Despite short-term volatility and shifting
narratives, the core discipline of PM Capital’s process remains unchanged.
“That’s probably the most difficult aspect of investing. Staying focused and being patient can be tough. Being invested in a concentrated portfolio often means performance can diverge from the wider market. Concentrated managers, by definition, will have concentrated periods of genuine outperformance” Bertoli said.
PM Capital allocates capital to where it believes the most attractive risk-adjusted market opportunities exist. This flexibility is central to its mandate and allows the firm to avoid being constrained by conventional benchmarks, industry norms, or short-term tracking considerations.
Rather than managing index-relative outcomes or standardised portfolio templates, PM Capital focuses on deploying capital where the firm sees the strongest long-term potential for client outcomes.
This approach may result in a portfolio that looks meaningfully different to the broader market, reflecting its willingness to diverge from consensus positioning.
Alignment is a key feature of the strategy, with the investment team also meaningfully invested alongside clients, reinforcing a focus on long-term decision-making and disciplined capital allocation.
“The concept of alignment is often overused in our industry. To us, it’s more than just having money in a fund, it’s more about managing capital in the same way we would manage our own capital, aligned to what we genuinely believe. This means ensuring we have a product that has flexibility so we can search for and find opportunities where they present themselves, rather than structuring the fund in a way that conforms to external limitations to fit someone else’s model.”
“There are a lot of funds out there today
that have investment teams that are coinvested with clients but have restrictive limitations that go against what those individuals would naturally do. That is not alignment.” Bertoli said.
“That means our portfolios are very different from the broader market.” And in speaking with advisers, this can help them bring much-needed diversification into their broader client portfolios.
PM Capital invests with a long-term ownership mindset, allocating capital with a view to being shareholders for decades, not years. Each position is selected based on the underlying commercial strength of the business and its ability to compound value over time.
Finding opportunities where others aren’t looking
PM Capital takes a contrarian approach to investing, often allocating capital to companies overlooked or avoided by
other market participants. This approach can enhance diversification within client portfolios by providing exposure to return drivers that differ from those of the broader market.
While markets are generally efficient, PM Capital believes they can misprice assets due to disruption, cyclical and structural changes, or misinterpretation of information. These inefficiencies create anomalies the firm seeks to exploit.
“What we’re really looking for is the genuine long-term mispricing in markets. Opportunities we think will play out over 10, 20 years. People call that value investing, but what we’re really looking for at the heart of it is mispriced growth,” Bertoli said.
“When we find these opportunities, we put a lot of capital to work – not a half a percent, or 1%. We’re talking about building a core thematic in our portfolio, across
multiple positions, of up to 15 to 20% of the funds over time.”
PM Capital typically maintains a longterm investment horizon, holding positions for extended periods. Portfolio turnover is relatively low, at around 20-25%, reflecting this patient approach.
Over nearly three decades, this discipline has been consistently applied, with opportunities often emerging during periods of significant market disruption or broader macroeconomic change.
An example of this is PM Capital’s investment in commodities during COVID 19.
“We went from next to nothing in our portfolio in commodities to 30% of our fund in copper and energy positions,” he said.
“There were 10-plus years when we didn’t have a commodity company in our portfolio. That’s pretty unusual for an
Australian asset manager, but if you went back to 2017, 2018, commodity companies had never been cheaper relative to the broader market and presented a really interesting opportunity that the market was overlooking,” Bertoli said.
Over time, however, the investment lifecycle evolves. “We still fundamentally believe in the operating thesis of tight supply, higher copper price. But stocks are up 8 to 10 times. The dynamic has changed. These businesses are no longer misunderstood or unloved. This means we start reducing those positions in our portfolio because the life cycle of investment has played out,” Bertoli said.
Bertoli added that the same framework has been applied across other sectors and points to European banks and alternative asset managers as other examples of mispricing during periods of pessimism or broader investor malaise.
“[European banks were] an unloved sector after almost a decade of negative interest rates across the continent, trading at half-book and mid-single-digit P/Es. The alternative asset managers back in 2015 were underappreciated, some might say irrelevant. Most investors either couldn’t own the sector given they were publicly traded partnerships or didn’t care about them because they weren’t in the index because of their structures. Over time, this dynamic changed and investors started to pay attention to the quality and growth in these businesses.”
Valuation, conviction and experience
PM Capital believes genuine value creation comes from deep understanding, conviction and experience that cannot be easily replicated. Over nearly three decades, its investment process has been refined and improved, while remaining grounded in
a consistent, disciplined and repeatable framework.
“Valuation has always been the cornerstone of our process – it provides the downside protection and allows us to remain patient through periods of market volatility,” Bertoli said.
“This is one of the reasons we believe in running highly focused and concentrated portfolios. The reality is the more you own, the less you understand, and you can’t value what you don’t understand.”
“I think one of the best questions an asset allocator can ask a portfolio manager is to walk them through every stock in the portfolio and explain why it’s owned.”
Knowing the names in a portfolio is the starting point. The real test is whether a manager can articulate the investment case for each holding. That’s because understanding what you own and why you own it is fundamental to building a
resilient portfolio and pursuing strong long-term outcomes.
For PM Capital, the ability to understand businesses deeply and consistently monitor these same businesses over a long period is what enables meaningful position-sizing and long-term conviction. Ultimately, the firm sees opportunity not in market averages, but in the differences between them.
“One of the hardest things to do from a portfolio perspective is to rotate capital through different ideas, different industry themes and different geographies. We’re able to do so because we have a very defined and well-established process and philosophy developed over a long period,” Bertoli said.
capitalgroup.com/au/en/ eqtgroup.com
eft.macquarie.com
metrics.com.au
pmcapital.com.au