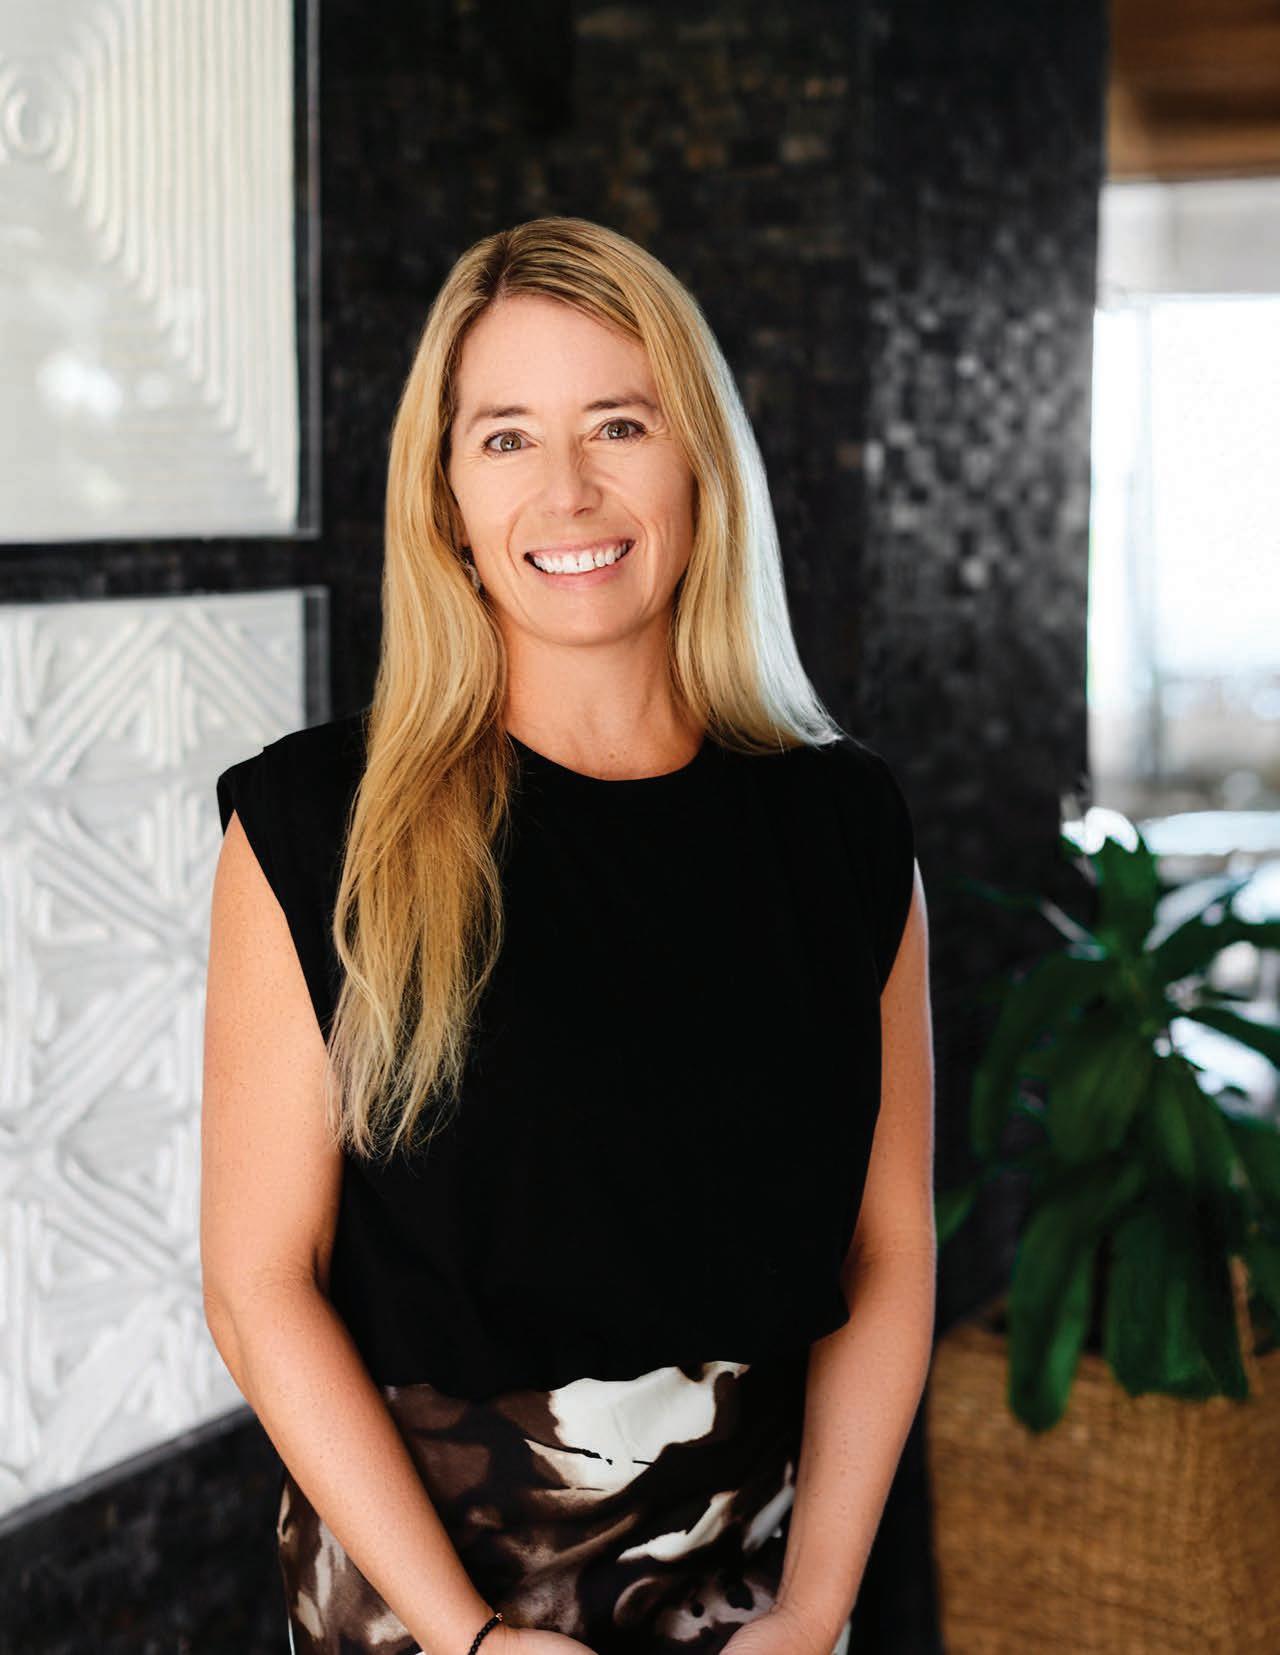
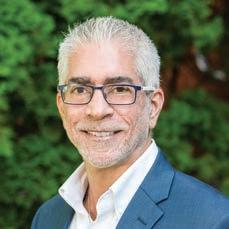
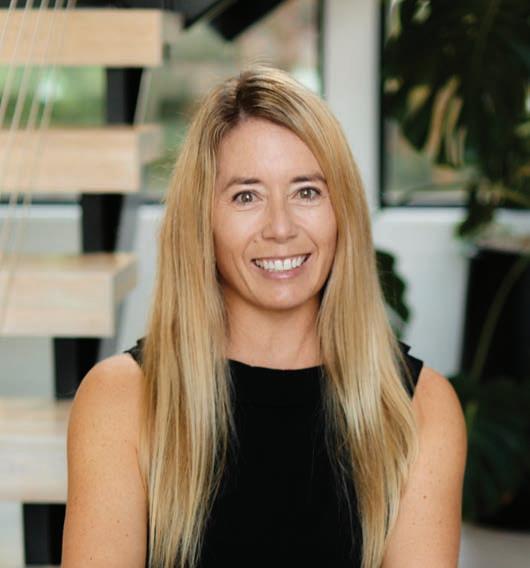
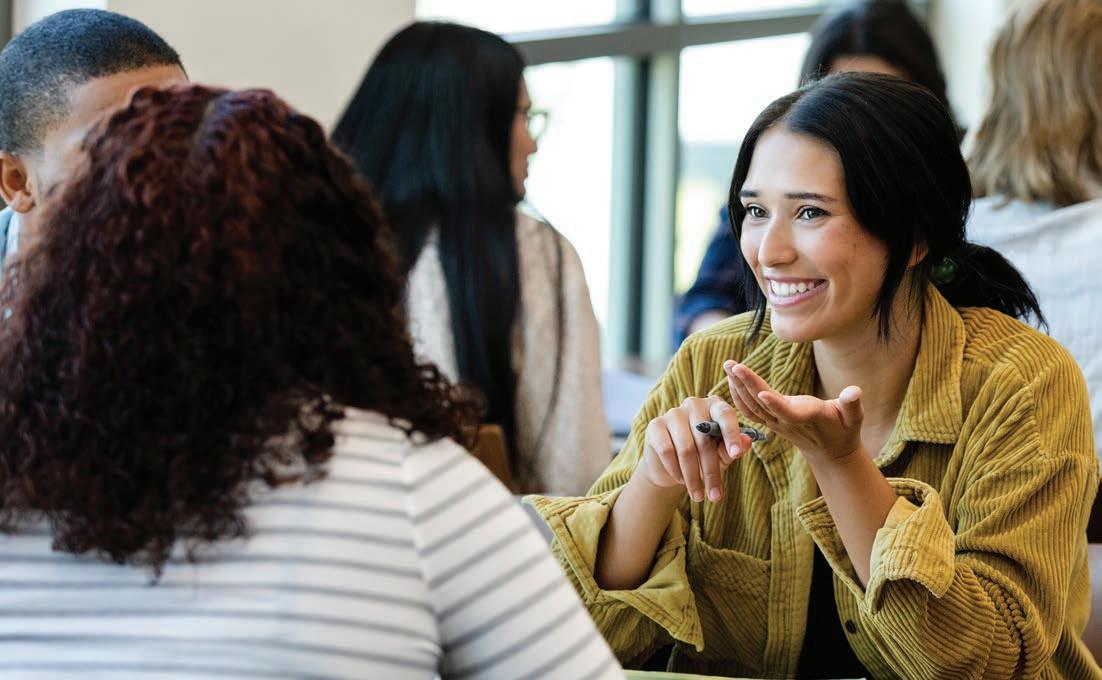
Laura Bren, president of Deeley Insurance Group, talks about agency culture and collaboration.
MULTIGENERATIONAL TALENT
The insurance workforce is changing. Learn how to gain an advantage by adapting your hiring model and introducing elastic hiring.
Conversations about developing multigenerational talent in the independent agency workforce have been circulating throughout our space for years. Something feels different about it this cycle, but the industry’s response keeps landing in the same places without anything really changing.
We keep creating our own barriers to entry. Everything from seemingly arbitrary degree requirements for roles that don’t need them, to credential checklists that screen out capable people before anyone ever talks to them. Perhaps the worst culprits are change-averse agency owners that deliberately ignore technological innovation and never even get to see the potential talent.
Instead, we should point out that independent agencies are not losing the talent war because of how we hire. We’re losing it because too many agencies aren’t all that compelling once you get inside.
The independent agency model offers something a carrier or national broker cannot — genuine ownership of client relationships with real autonomy, and a career arc that rewards judgment rather than just tenure. A talented 25-year-old who lands here and stays has a different ceiling than one who ends up in a regional office somewhere processing renewals based upon random, equitable distribution of tasks. That story is not being told loudly enough, and in too many agencies, it is not being lived loudly enough either.
Multigenerational talent works when experienced people actively develop the next generation as a professional obligation. When we treat what we do as a calling and noble cause, we manifest a culture within independent agencies that few other industries can replicate.
Andrew M. Enders, Esq. Chair of the Board
Heavy Rotation: Hiss Golden Messenger: I’m People; Tom Petty & the Heartbreakers: Hard Promises; Broken Social Scene: Remember the Humans; Kevin Morby: Little Wide Open
INSURANCE AGENTS & BROKERS
650 Wilson Lane, Suite 200 Mechanicsburg, PA 17055
191 Main Street, Annapolis, MD 21401 800-998-9644 | IABforME.com
IA&B BOARD OF DIRECTORS
OFFICERS
Andrew Enders, Esq. - Chair Enders | Harrisburg, PA
Kate Dawson, CISR, CPIA - Vice Chair Ferri Dawson Insurance | Murrysville, PA
MEMBERS
Greg Bennett Famous & Spang Associates Aberdeen, MD
Tony Cusati, CIC Sitter Insurance LLC Erie, PA
Michael Gaetano The Hartman Group Montoursville, PA
Debra McAfee McAfee Insurance Agency, LLC Wilmington, DE
Michael McGroarty, Jr., CIC McGroarty & Bradburn Insurance Pittsburgh, PA
Hunter McHugh McHugh Insurance Group Wilmington, DE
Shayne McIntosh, CIC JPI Insurance Associates Dillsburg, PA
Chris Miller, CIC Miller Insurance Protection Team Jonestown, PA
Jill Nye, CIC, CISR, CPIA Gunn-Mowery, LLC Lemoyne, PA
Lisa Parry, CPIA Parry Insurance Langhorne, PA
Bill Purdy Purdy Insurance Agency, Inc. Sunbury, PA
Kent Reynolds, CIC Blue Ridge Risk Partners LLC Hagerstown, MD
David Rivell, CIC, CRM Element West Chester, PA
Christy Rose Avery Hall Insurance Salisbury, MD
Ashley Stafford, CPIA Element
Michael Thomas Lighthouse Insurance Svcs Gambrills, MD
Kyle Zehr, CIC FIFS, LLC Telford, PA
NATIONAL DIRECTORS
Diana Hornung, CIC (IIABA) IOA National, Inc. | Wilmington, DE
Mark Monroe (IIABA)
Mark J. Monroe Insurance | Downingtown, PA
QUESTION:
ANSWER:
An insurance producer should never, ever sign an application –or any other insurance-related document for that matter – on behalf of a customer.
WHY ALL THE WORRY?
Even if a customer verbally authorized you to sign documents on their behalf, short of having them grant you Power-of-Attorney, it isn’t sufficient. While a producer may know without a doubt the customer provided verbal authorization, after a loss has occurred and a claim has been filed, the customer/ insured (if it’s in their best interest) may disavow having granted the producer authorization to sign on their behalf. In such a case, the first thing a good attorney will do is ask if that’s the customer’s signature
DON'S DISCUSSION
There’s no “rewind” button to go back in time and undo the fact you signed for your customer. The lower than recommended CGL liability or auto liability and property damage limits your customer chose and wanted – that you signed for – are not enforceable. The elections to waive UM/UIM and stacking that you signed – not enforceable. You can see where this is going ... to court.
IA&B Legal & Corporate Affairs Director Don Bankus Are you a member with a question? Contact IA&B to find the answer at advocacy@IABforME.com or 800-998-9644, option 4.
Is it OK if my employees sign applications and related documents on behalf of our insureds?
on the application. As soon as the customer says “no,” it becomes extremely difficult to hold them responsible for the content/elections in the application (and other related documents and forms) they didn’t actually sign.
ARE THERE OTHER POSSIBLE REPERCUSSIONS?
Yes, there are likely some serious ones, such as:
▲ An E&O claim could be filed against you and/or the agency.
▲ “Forging” another person’s signature on insurance documents is an express violation of the state’s producer licensing act. Therefore, you become subject to possible suspension, revocation, or non-renewal of your producer license, fines, etc., not only in the state where you hold your resident license, but possibly in states where you hold non-resident licenses.
▲ You may have put your livelihood in serious jeopardy.
▲ You could subject the agency to termination by the insurance company for the affected insured. The agency’s agreement with the
carrier likely contains provisions whereby it can be terminated for fraudulent acts and/or for violation of certain state insurance laws or regulations.
▲ You could face criminal charges, even under circumstances where you know – for a fact – that the customer provided you with verbal authorization to sign. Even if you successfully defend the criminal charges, you could incur considerable costs.
THE BOTTOM LINE
Because you, as the producer, are not a party to your insured’s contract of insurance, you should never, ever sign documents on a customer’s behalf – even if they ask you to.
This document is not a legal opinion and should not be relied upon as such. The intent of this document is to provide a general background regarding the topic or topics discussed, not to provide legal advice. Producers and agencies should consult an attorney regarding specific situations and specific questions with respect to the topic or topics covered in this document. Neither the Insurance Agents & Brokers nor any of its employees shall be responsible for any errors or omissions regarding any statements made in this document, nor any errors or omissions regarding any statutes, regulations, court rules, and/or any other government documents cited in this document.
Rather listen?
Also available in audio format at IABforME.buzzsprout.com
CLAIMS … TO REPORT OR NOT TO REPORT?
By Bill Wilson
This issue’s topic is primarily about whether an insured should report an auto claim if there are no injuries and not even any visible damage. At the end, an added bonus is an emerging reporting condition for auto coverage that seems to be gaining traction in the marketplace. Read on.
Several years ago, my wife was exiting the expressway onto a local road. There was one car in front of her as she slowed almost to a stop before turning right onto the road. As she looked quickly to the left, there were no vehicles approaching as far as she could see.
So, she kept coasting along the ramp as her head turned back to the direction in which she was traveling.
Unfortunately, for whatever reason, the vehicle in front of her had come to a complete stop even though there was only a yield, not a stop, sign. She slammed on her brakes and came to a quick stop but not before gently tapping the bumper of the other vehicle.
She and the other driver exited their vehicles and examined the bumpers, unable to find even the slightest mark. So, my wife apologized, and they agreed to go on their way after exchanging contact information. Under local law, they had no obligation to report the incident to law enforcement.
When she got home, she asked me if we should report the collision to
our insurance company given that there was no damage or injury and the other party just brushed off the entire affair. I explained this provision in our auto policy:
“DUTIES AFTER AN ACCIDENT OR LOSS...We have no duty to provide coverage under this policy if the failure to comply with the following duties is prejudicial to us...We must be notified promptly of how, when and where the accident or loss happened.”
Her response was, “But there was no damage and nobody was hurt.”
I suggested that this reporting condition doesn’t require that there be any damage or injury, only an accident. Her response was, “But
our insurance premium will go up.”
I advised that this was possible but that it was also possible the other party might file a claim and a premium increase would be the least of our worries if we had no coverage.
So, we reported the incident.
Three days later, my wife got a call from the other driver. She said her husband took the car to a mechanic he knew and was told that the frame was bent but it wasn’t too bad and they really didn’t want to get insurance companies involved, so if we just gave them $300 for their trouble, they’d be fine with that.
Instead, we again gave her the name of our insurance company, told her we had already reported the accident to them, and asked if her number was the one they should call because they’d want to have the car inspected as soon as possible. She said she’d ask her husband.
We never heard from them again.
We followed up with our insurer, the claim was closed, and we never got a premium increase. In fact, our premium went down upon renewal, though I’m pretty sure that had nothing to do with this incident.
If anyone asks me about reporting an auto accident involving potential liability, I tell them to do it. Damage isn’t always immediately apparent to the typical consumer, especially with vehicles today that have numerous sensors, cameras, and other easily damaged equipment. Worse, injuries may not reveal themselves for days or weeks. Even worse, the other party may attempt to defraud you, and without promptly reporting an accident, you may be on your own with no assistance from your insurer.
I believe everyone reading this would probably agree with that approach. Even ChatGPT agrees with me, so I must be right. However, many consumers won’t ask any of us for advice. They may not even want their agent or anyone else connected to the insurer to know what happened. More likely, they’ll get online, do a search, and find advice like this from an auto insurance consumer web site:
“Suppose you are at fault in a collision and cause minimal damage to the other driver’s vehicle and the repair cost is reasonable. In that case, you can ask them if you can pay for the repairs yourself instead of filing an insurance claim with your carrier. If the damage is relatively minor and can be paid out-of-pocket, it may not be worth the hassle or the potential increase in premiums. According to our data, an at-fault accident can trigger an average 57% increase in insurance rates.”
From a service and E&O standpoint, always advise customers to report claims in accordance with the terms of the insurance contract.
Lastly, as I mentioned at the start of this article, some insurers are beginning to require that new drivers of vehicles after policy inception be reported to the insurer in order for coverage to apply … not just for them, but for all insureds. Boomerang children are increasingly common today. If a child (or even an elderly parent) moves in, there may be no coverage for auto use unless they are reported to the insurer. One such carrier’s policy now says:
“You must notify us if there are changes to any information shown on the Declarations or to information that affects eligibility or premium.”
How would a policyholder know what information affects eligibility or premium? Whether such notice requirements would hold up in court remains to be seen, but in the meantime, be vigilant out there.
‘Til next time
Bill Wilson, CPCU, ARM, AIM, AAM is the founder and CEO of InsuranceCommentary. com and the author of six books, including the Amazon 4.8 star “When Words Collide…Resolving Insurance Coverage and Claims Disputes” which BookAuthority ranks as the #1 insurance book of all time. He can be reached at Bill@InsuranceCommentary.com.
Rather listen?
Also available in audio format at IABforME.buzzsprout.com
CE and learn more about personal lines coverage hiccups. Instructor: Nicole Broch
IA&B MEMBERS ATTEND
NATIONAL LEGISLATIVE CONFERENCE
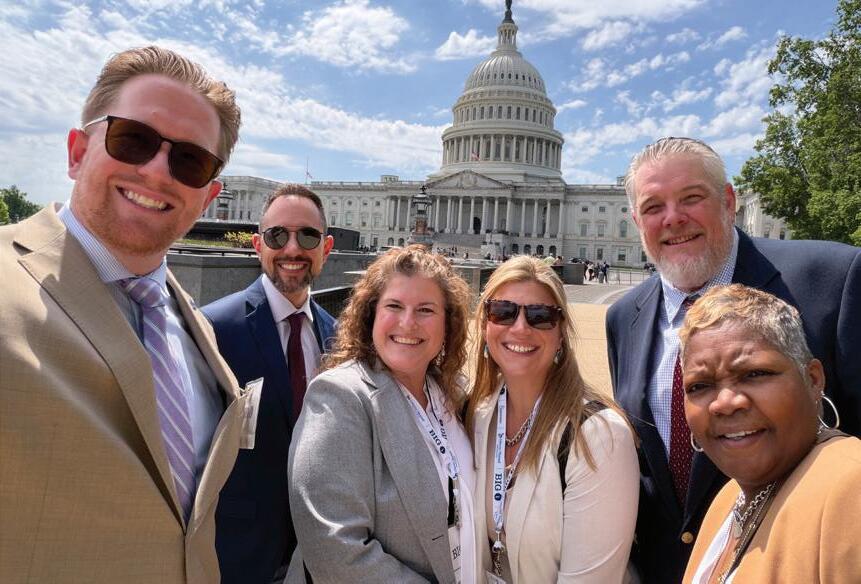
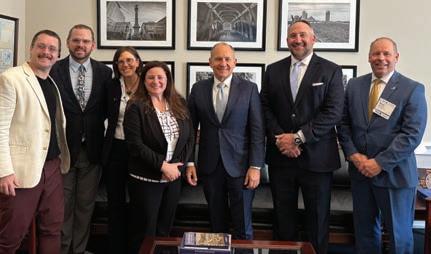
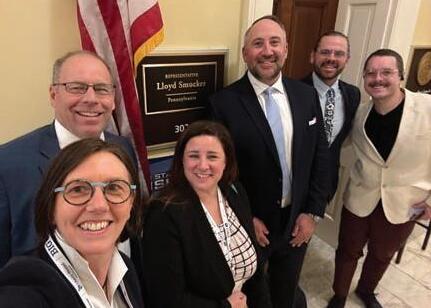
Over three dozen IA&B members from Pennsylvania and Delaware were among more than 700 insurance professionals from across the nation who attended this year’s Big “I” Legislative Conference. In
late April, participants met with their elected officials on Capitol Hill to discuss the following critical issues:
Legal Reform – Urging Congress to support legislation that protects courts by cracking down on lawsuit abuse, a significant and growing problem that adds considerable costs to the insurance industry and, in turn, premiums
Disaster Mitigation – Asking lawmakers to address the insurance market crisis stemming from increasingly frequent and severe natural disasters by encouraging preparedness
Flood Insurance – Pushing for modernization and reauthorization of the National Flood Insurance Program, as well as legislation to encourage participation in the private flood market
Terrorism Risk – Urging Congress to secure the national economy and insurance marketplace by passing a clean, long-term extension of the Terrorism Risk Insurance Act
Health Care – Advocating for the advancement of reforms to lower health insurance costs and increase price transparency for patients, employers, and insurance producers
Learn more about IA&B’s federal and state advocacy efforts –and get involved! Contact IA&B Government Affairs Director John Savant at 717-918-9214 or JohnS@IABforME.com.
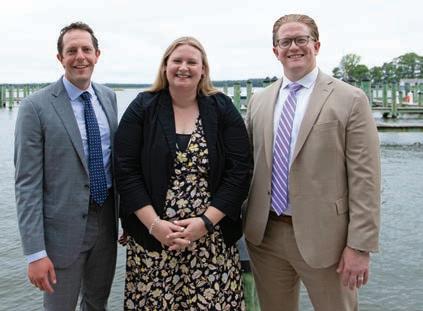
2025 IA&B Young Agent Award winners (l to r): Jimi Honochick, Danielle Webber, Hunter McHugh
NOMINATE YOUR AGENCY’S RISING STAR
Nominate yourself or a colleague for IA&B’s 2026 Young Agent Award, celebrating standout emerging talent across the agency team.
IA&B will recognize three exceptional young insurance professionals—one from each state—who are making a meaningful impact within their agencies and the industry. As long as they are licensed agents, recipients can hold any agency role, including producer, account manager, or client service representative. A panel of judges will select the winners.
Nominations are due by Friday, June 19. IABforME.com/agent-award
Questions? Contact IA&B Public Relations Director Karen Robison at 800-998-9644, ext. 606 or KarenR@IABforME.com.
Snapshots of IA&B members at the 2026 National Legislative Conference
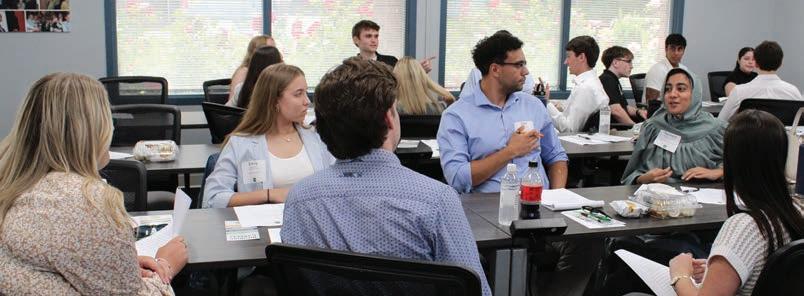
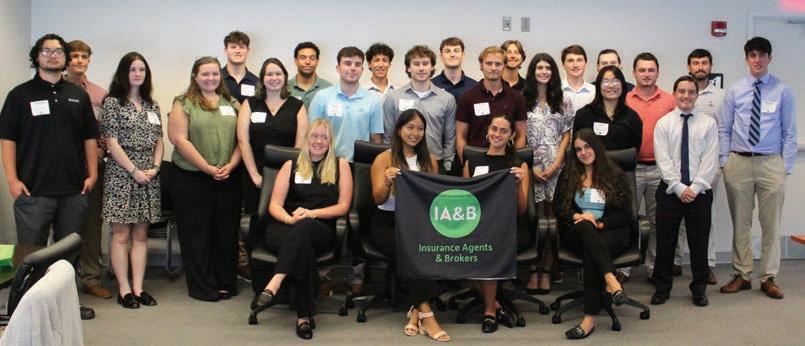
Top: Breakout groups at the 2025 IA&B Intern Day Bottom: IA&B Intern Day brings together interns from agency members and company partners throughout the tri-state region.
ARE YOU HOSTING INTERNS THIS SUMMER?
Send your interns to Insurance Agents & Brokers (IA&B) Intern Day — an opportunity to help round out their summer internship experience. It’s an afternoon for your interns to network with young agents and learn more about different aspects of our great industry.
This is a free event, available exclusively for interns of IA&B member agencies and company partners.
WHO CAN ATTEND: Interns of IA&B member agencies and company partners
WHERE: IA&B Office & Conference Center 650 Wilson Lane Mechanicsburg, PA 17055
WHEN: National Intern Day Thursday, July 30 11:30AM to 4:30 PM
Lunch is included.
Intern Day Includes:
▲ Networking with Other Interns & Professionals
▲ Industry Professional Panel
▲ Professionalism in the Workplace Discussion
▲ Resume and Interviewing Skills Workshop
Registration is open. IABforME.com/intern-day
Questions? Contact IA&B Director of Career Services Heather Ulrich at 800-998-9644, ext. 407 or HeatherU@IABforME.com.
MARYLAND’S 2026 LEGISLATIVE SESSION IN REVIEW
The Maryland General Assembly wrapped up its legislative session in April. Legislation passed this session includes:
▲ Senate Bill 469, which creates an affordability program through the Maryland Automobile Insurance Fund. IA&B opposed the bill and was successful in securing amendments limiting its negative impact on non-MAIF policyholders.
▲ Senate Bill 747, which increases the condo unit owner deductible from $10,000 to $25,000.
▲ House Bill 30, which addresses predatory towing companies by establishing rate regulations for police-initiated light-duty towing, similar to existing rules for medium and heavy-duty towing.
IA&B was also successful in preventing the passage of several bills that would have negatively affected consumers.
Questions? Contact IA&B Government Affairs Director John Savant at 717-918-9214 or JohnS@IABforME.com.
Q& A
with
LAURA DEELEY BREN, CIC, ASLI
Laura Deeley Bren, CIC, ASLI is president of Deeley Insurance Group, a full-service independent agency located in Willards, MD.
Q. You’re celebrating 20 years as president of your agency. What’s a leadership lesson that’s really stuck with you?
A. The most important leadership lesson I’ve learned is to lead with abundance and do the next right thing—for clients, employees, and carrier partners. When decisions are grounded in integrity and longterm relationships instead of fear or scarcity, positive outcomes follow. The more you give—through trust, transparency, and service—the more you receive.
Q. When you’re hiring, what’s the one quality you look for that tells you someone will thrive in your culture?
A. I look for doers—people who combine integrity, curiosity, and a strong work ethic with the willingness to actually roll up their sleeves. We hire people who do the work, not just talk about it. When someone follows through, collaborates naturally, and consistently does the right thing for the team and our clients, they thrive in our culture and help everyone around them succeed.
Q. The past few years have been a roller coaster for everyone. Tell us what you’re seeing today.
A. One of the biggest changes we’ve seen, both in our industry and more broadly, is a growing disconnect between clients and their agents. Whether driven by
the lingering effects of COVID, the Great Resignation, or consolidation across the market, many clients feel like relationships have become transactional instead of consultative.
At the same time, people are hungry for connection and understanding. They want to know why they’re buying coverage and how it actually protects them, not just receive dense policy language and move on. That’s where we’ve really leaned in. We’re very straightforward in how we communicate and how we deliver complicated information. We work hard to simplify insurance without dumbing it down—to explain it clearly and practically, without overwhelming clients with jargon.
Our team honed those communication skills during the hard market, and now we’re seeing the payoff. Clients are more engaged, asking better questions, and genuinely interested in learning. We regularly hear that clients learn more in an hour with one of our Client Advisors than they have from other agents over the course of years. That reinforces our belief that the future of our industry isn’t just about product or price—it’s about clarity, trust, and meaningful relationships.
Q. What is your agency’s superpower?
A. Collaboration. A single account might involve a brand marketing creative building a LEGO model to show how we
approach insurance differently, multiple team members brainstorming coverage and doublechecking details, and leadership rolling up their sleeves to help position a renewal for the best possible outcome. It’s never just one person—it’s a true team effort. You can even find our team serving together each month at a local homeless shelter. That collaborative, service-first mindset is simply how we roll—Deeley deep.
Q. How do you think AI will transform the insurance agency space?
A. AI is going to meaningfully transform the insurance agency space by reducing friction and accelerating growth—not by replacing people, but by empowering them.
For agencies, AI can handle the administrative heavy lifting: organizing information, summarizing policies, moving data between systems, and flagging issues early. That frees advisors to focus on what actually drives value—advising, explaining, and building trust with clients.
Where I see a real gamechanger is talent development. AI can help people who already have the right core values curiosity, empathy, accountability—ramp up faster as insurance professionals. By giving them better tools, clearer context, and consistent guidance, AI shortens the learning curve and helps them gain confidence and competence more quickly without cutting corners.
The agencies that win won’t be the ones chasing automation for its own sake. They’ll be the ones using AI to amplify good people, strengthen communication, and build deeper expertise. The future of the agency model is human at the core, AI at the controls—smarter workflows, faster development, and more time spent doing what matters most: serving clients well.
Q. Your agency utilizes a Work At Home Vintage Employee (WAHVE)—a pre-retired insurance professional who works remotely. Tell us about your experience.
A. We brought on a WAHVE associate as temporary support, but they were such a great fit for our team that it became a four-year stint. We were impressed with their deep experience and flexibility, and especially how they integrated so well into our culture, despite being fully remote.
Q. What words of wisdom would you offer people just beginning their insurance career?
1. Earn your seat. Surround yourself with people who challenge you, hold you accountable, call you out when you are wrong, and celebrate you when you get it right.
2. Be for each other. When your team wins, you win. Be generous with your support and encouragement.
3. Stay curious. Ask why and why not. Even when things are awesome, your insight can help make them better.
Q. What professional accomplishment are you most proud of?
A. My proudest accomplishment is how we show up: seeing the team of professionals we’ve assembled and their unwavering commitment to make a positive impact for our clients, our community, and each other. That makes me pause and say “I think we’ve got it.” We’re creating a destination workplace, our culture is vibrant and authentic, and when you work with us—as a client or employee—you feel the difference.
Q. What do you hope people feel or think when they hear your agency’s name?
A. When people in this community hear our agency’s name, I hope they think of us as energetic yet grounded—a team that brings enthusiasm and momentum, but is also steady, thoughtful, and deeply rooted in doing the right thing.
Ultimately, I want our name to stand for clarity, consistency, and care. If hearing our agency’s name makes someone think, “They’re knowledgeable, they’re real, and they’ll help me make sense of this,” then we’ve earned that reputation.
Q. When you’re not working, how do you enjoy spending your time?
A. Yoga, hiking, travel, and time at the beach. I come from a family of surfers, so if I’m not geeking out solving the world’s insurance problems, you’ll likely find me on a beach somewhere in the world.
PLATINUM PARTNER PROFILE
Insurance Agents & Brokers proudly recognizes Chesapeake Employers’ Insurance Company as one of its Platinum Partners.
Purpose & Partnership Built for What’s Next
What would your clients do with their share of our $60 million policyholder dividend? As Maryland’s only nonprofit workers’ compensation carrier, Chesapeake Employers Insurance has returned $235 million to Maryland employers in policyholder dividends since 2018.
Our purpose – elevating the promise of work and the potential of people – and our unique nonprofit model allow us to operate differently. Because we don’t answer to shareholders, we reinvest in our agent partners, the employers you serve, and our communities, focusing on long-term stability, service, and shared success.
Reinvesting in Our Independent Agent Partners
Independent insurance agents play a vital role in our mission. You are the trusted advisors helping employers protect their workers and their livelihoods. That’s why we’re committed to investing in you through the Chesapeake Agent Advantage Program.
The Chesapeake Agent Advantage Program is designed to help you invest in your people, strengthen your operations, and plan confidently for what’s next. Through this program, we reinvest in our agent partners with:
• Competitive commissions & bonus opportunities
• Agent Impact Dollars to reinvest in your business and your people
• Education and tools to help you succeed
• Curated experiences that bring value beyond the balance sheet
As a purpose-driven carrier with more than a century of experience, our approach is different by design. We measure success not only by results, but by relationships—working alongside agents who share our commitment to doing what’s right for Maryland employers and their workers operating across the Mid-Atlantic.
When you partner with Chesapeake Employers, you gain more than a workers’ compensation carrier. You gain a team invested in your success, a program built to reward meaningful growth, and a partnership designed for the long term.
To learn more about how the Chesapeake Agent Advantage Program can elevate your agency, contact your Marketing Representative or visit www.ceiwc.com/agents.
Thanks to these partners for supporting the independent agent network.
PARTNER & EDUCATION STEWARD
PLATINUM PARTNERS
Chesapeake Employers’ Insurance Company
Erie Insurance
Ironpeak (formerly Iroquois)
Keystone
Millers Mutual Insurance
NJM Insurance Group
Penn National Insurance
Plymouth Rock Assurance
GOLD PARTNERS
EMC Insurance Companies
Farmers of Salem
The Insurance Alliance Network
Liberty Mutual Insurance
MMG Insurance
Nationwide Insurance Company
Openly
POM Insurance Company
SECURA Insurance
Selective Insurance
Multigenerational TALENT
The Competitive Advantage Hiding in Plain Sight
Provided by Work At Home Vintage Experts (WAHVE)
Let’s be honest. Every insurance leader I talk to says some version of the same thing: “We can’t find talent.”
But here’s the tougher question: Are we really short on talent — or are we short on imagination when it comes to how we hire?
The insurance workforce is changing. Fast. Five generations are now working at the same time. And by 2028, one in four U.S. workers will be over 55. That’s not a temporary disruption. That’s a structural shift.
The agencies that adapt will gain an advantage. The ones that don’t will keep fighting the same talent battle year after year.
The “Talent Shortage” Isn’t What You Think
When agencies say they can’t find talent, what they usually mean is:
● They can’t find talent willing to work full-time, in-office, under traditional structures.
● They can’t find talent the way they used to.
But experienced insurance professionals haven’t disappeared. Many don’t want to retire completely. They still want to contribute. They still care about the work.
What they don’t want is to go back to rigid schedules, long commutes, or 60-hour weeks.
That’s not a talent shortage. That’s a hiring model problem.
Why Multigenerational Teams Actually Win
Insurance isn’t built on hype. It’s built on judgment, relationships, and pattern recognition. Those things improve with experience.
Seasoned professionals bring:
● Deep coverage knowledge
● Market-cycle awareness
● Risk instincts you can’t Google
● Credibility with clients
Emerging professionals bring:
● Digital fluency
● New ways of working
● Energy and speed
● Fresh perspectives
When those strengths are combined intentionally, something powerful happens. Speed meets stability. Innovation meets experience. Growth meets continuity.
That’s not theory. That’s performance.
The Bias No One Talks About
Age bias rarely shows up as something obvious. It’s subtle.
It’s the job description that quietly signals “early career.” It’s the assumption that experienced professionals resist technology. It’s the idea that flexibility equals lower productivity.
In insurance, those assumptions are expensive. They narrow the candidate pool. They lengthen hiring cycles. They accelerate knowledge loss.
And in a relationship-driven industry, losing experience isn’t just inconvenient. It’s risky.
The Real Shift: Rethinking the Hiring Model
For decades, hiring has been binary: full-time or retired. In-office or out. All-in or not at all. That model doesn’t match today’s workforce — or today’s business needs.
This is where Elastic Hiring changes the conversation.
What Elastic Hiring Really Means
Elastic Hiring isn’t a buzzword. It’s a workforce strategy.
Instead of forcing experienced professionals into full-time roles they may no longer want, agencies can engage them
Continued on page 14
TALENT
Continued from page 13
in flexible, remote, high-accountability positions that deliver real impact.
It allows organizations to:
● Access highly skilled insurance professionals
● Scale suppor t up or down as workload shifts
● Reduce burnout on internal teams
● Preserve institutional knowledge
● Maintain continuity during transitions
It’s not about lowering standards. It’s about aligning talent capacity with business demand. And in an industry facing a knowledge drain, that alignment matters.
Flexibility Is No Longer Optional
Flexibility used to be a perk. Now it’s a competitive advantage.
Experienced insurance professionals are choosing flexibility over retirement when given the right structure. Agencies that adapt gain access to underwriting expertise, claims experience, account management depth, and compliance knowledge that would otherwise walk out the door.
Agencies that don’t adapt keep competing for the same shrinking early-career talent pool. One strategy expands your options. The other narrows them.
So What Can Leaders Do Now?
You don’t need a massive transformation to get started.
Start here:
● Review job descriptions for language that unintentionally screens out experienced talent.
● Identify roles that don’t truly require full-time, onsite presence.
● Separate business requirements from legacy habits.
Tired of Recruiting, Hiring, or Turnover?
Contact Work At Home Vintage Experts (WAHVE) – your one-stop hiring solution. WAHVE matches “retired” insurance professionals who have remote-work experience to meet your specific staffing needs.
IA&B members receive a 50% discount on the one-time setup fee.
Get started by contacting: Lorrie Maida, WAHVE Sales Director 347-292-6134 Lorrie.Maida@wahve.com
● Pilot a flexible or elastic model in one depar tment.
● Measure productivity, retention, and client impact — not just headcount.
Small shifts can unlock meaningful gains.
Insurance is expertise-driven. It’s relationship-driven. It’s judgment-driven. Letting that experience exit prematurely isn’t just a talent issue. It’s a strategic mistake.
The agencies that thrive over the next decade won’t simply hire younger. They’ll hire smarter. They’ll blend experience with innovation. They’ll design workforce strategies that reflect reality instead of tradition.
Multigenerational hiring isn’t about accommodation. It’s about advantage. And in today’s insurance landscape, experience isn’t a liability. It’s leverage.
Work At Home Vintage Experts (WAHVE) provided this article. WAHVE matches “retired” insurance professionals who have remote-work experience to meet agencies’ specific staffing needs. Learn more by visiting WAHVE.com.
WELCOME NEW MEMBERS
HTA Property & Casualty Insurance, LLC
Exton, PA
For information about membership or benefits, contact:
Tim Wonder, VP-Membership 717-918-9223
TimW@IABforME.com
VISION
A thriving independent insurance agent community.
MISSION STATEMENT
To serve as a driving force to champion independent agency success by educating, consulting, advocating, and fostering community in Pennsylvania, Maryland, Delaware, and beyond.
PRIMARY AGENT
Editor:
Karen Robison
KarenR@IABforME.com
717-918-9209
Contributing editors:
Jennifer Ross, Megan Fioretta
Sarah Haas
Sales Account Executive:
Rebecca Sieg
rebecca.sieg@theygsgroup.com
717-430-2351
SCHEDULE
JUNE 2026
Specialty underwriting is as much art as analysis. These islands of risk demand bold expertise—where the unknown becomes knowable, and the impossible is nothing. Experience the confi dence only Applied delivers.