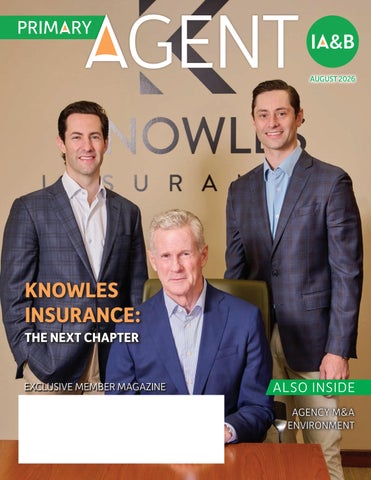
AUGUST 2026
KNOWLES INSURANCE: THE NEXT CHAPTER EXCLUSIVE MEMBER MAGAZINE
ALSO INSIDE AGENCY M&A ENVIRONMENT
Good coverage never goes out of stock. Some businesses sell flowers. Others sell shoes, wine, or the world’s best cinnamon roll. Different products, different customers, and different risks. That’s why flexibility matters. We give you the tools to tailor protection for a wide range of retail operations, so coverage fits the way each business actually runs. Whatever’s on the shelves, we’ve got it covered. Learn more about EMC’s retail expertise
Learn more ©Employers Mutual Casualty Company 2026. All rights reserved.
AUGUST 2026
CONTENTS FEATURED 8
INTERVIEW WITH ROBERT KNOWLES Robert Knowles Jr. discusses the next chapter for Knowles Insurance – young leadership, an informed growth strategy, and a commitment to the core values that have served the agency for four generations.
JOIN US ON SOCIAL MEDIA: Facebook.com/IABforME LinkedIn.com/company/IA_and_B Instagram.com/IA.and.B YouTube.com/@IA_and_B
14
IA&B Podcasts can be found at:
IA&B is the premier resource and champion for independent insurance agents in Pennsylvania, Maryland, and Delaware. Periodical postage paid at Mechanicsburg, PA and at additional mailing offices. Postmaster: Send address changes to Insurance Agents & Brokers, 650 Wilson Lane, Suite 200, Mechanicsburg, PA 17055.
INSURANCE AGENCY M&A ENVIRONMENT The team from IA Valuations clears up some misconceptions triggered by the massive number of mergers and acquisitions in the independent agency system over the past decade.
MONTHLY 2 CHAIR'S MESSAGE
Primary Agent (ISSN 1543-3110), Permit # 638-620, Issue # 2026-08, is published monthly by IA&B Service Group Inc., a subsidiary of IA&B. Copyright 2026. All rights reserved. No material JUNE be reproduced in whole or in part without written consent of the publisher. The information in this publication is general in nature and not intended to serve as legal, accounting, financial, insurance, investment advisory or other professional advice as to any reader’s particular situation. Users are encouraged to consult with competent legal, financial, insurance, investment advisory and/or other professional advisors concerning specific matters before making any decisions. We disclaim any responsibility for any decisions or actions by readers. Statements of fact and opinion in Primary Agent are the responsibility of the authors alone and do not imply an opinion on the part of the officers or the members of IA&B. Participation in IA&B events, activities and/or publications is available on a non-discriminatory basis and does not reflect IA&B endorsement of the products and/or services.
3 CLAIRE-IFICATION 4 COVERAGE CORNER 17 UPCOMING EDUCATION
IA&B works on your behalf to ensure that state legislators and regulators understand the issues affecting agents. YOUR FINANCIAL SUPPORT AMPLIFIES YOUR MESSAGE.
PLEASE CONSIDER CONTRIBUTING. More information at IABforME.com/ political_advocacy
IABforME.com |
1
CHAIR'S MESSAGE Perpetuation is not a single moment in time, but a transfer that substantively shifts direction. What survives when an agency changes ownership, and by what mechanism? Bob Knowles addresses the question directly in his conversation in this month’s issue. When his firm acquired two peer agencies, the sellers were not out for simply the highest bid; they wanted assurance regarding the future of their employees and clients — a concern no valuation model captures. Knowles structured these transactions around compatibility rather than multiples alone. This is the dimension of perpetuation most discussions often omit. Behind every transaction sits a producer who has spent a decade learning a client's operations and a service representative who carries a family's insurance history as given knowledge. These variables might not sit on a balance sheet, but they are mission critical considerations. Too many acquisitions treat this dimension as incidental. Employment continues nominally until an organizational chart dictates otherwise; clients receive correspondence announcing a rebrand. Few inquire whether the people performing the work still recognize the institution they serve. While ownership is a legal structure that is easily changed, what perpetuation tests is different: whether the promise an agency represents survives the transaction. Knowles built his acquisitions around that test, and any agency contemplating its own succession ought to consider the same.
INSURANCE AGENTS & BROKERS 650 Wilson Lane, Suite 200 Mechanicsburg, PA 17055 191 Main Street, Annapolis, MD 21401 800-998-9644 | IABforME.com
IA&B BOARD OF DIRECTORS OFFICERS Andrew Enders, Esq. - Chair Enders | Harrisburg, PA
Kate Dawson, CISR, CPIA - Vice Chair Ferri Dawson Insurance | Murrysville, PA
MEMBERS Greg Bennett
Lisa Parry, CPIA
Tony Cusati, CIC
Bill Purdy
Michael Gaetano
Kent Reynolds, CIC
Debra McAfee
David Rivell, CIC, CRM
Michael McGroarty, Jr., CIC
Christy Rose
McGroarty & Bradburn Insurance Pittsburgh, PA
Avery Hall Insurance Salisbury, MD
Hunter McHugh
Ashley Stafford, CPIA
Famous & Spang Associates Aberdeen, MD Sitter Insurance LLC Erie, PA The Hartman Group Montoursville, PA McAfee Insurance Agency, LLC Wilmington, DE
2
AUGUST 2026
Blue Ridge Risk Partners LLC Hagerstown, MD Element West Chester, PA
Element
Shayne McIntosh, CIC
Lighthouse Insurance Svcs Gambrills, MD
Chris Miller, CIC
Heavy Rotation: Jack White: No Name; American Football: LP4; Old & In the Way: Acoustic Archive Series, Vol. 2; Fruit Bats: the Landfill; Lyle Lovett: The Road to Ensenada
Purdy Insurance Agency, Inc. Sunbury, PA
McHugh Insurance Group Wilmington, DE JPI Insurance Associates Dillsburg, PA
Andrew M. Enders, Esq. Chair of the Board
Parry Insurance Langhorne, PA
Miller Insurance Protection Team Jonestown, PA
Michael Thomas
Kyle Zehr, CIC FIFS, LLC Telford, PA
Jill Nye, CIC, CISR, CPIA Gunn-Mowery, LLC Lemoyne, PA
NATIONAL DIRECTORS Diana Hornung, CIC (IIABA)
IOA National, Inc. | Wilmington, DE
Mark Monroe (IIABA)
Mark J. Monroe Insurance | Downingtown, PA
CLAIRE-IFICATION
CLAIRE-IFICATION IA&B Vice President - Advocacy Claire Pantaloni, CIC, CISR Are you a member with a question? Contact Claire to find the answer at 717-918-9202 or ClaireP@IABforME.com.
that I need to set up my premium accounts a certain way with the bank QUESTION: Istoitgettruemore FDIC protection? If so, how?
ANSWER:
explain this to your bank. It is possible the bank will push back until they see the opinions.
Absolutely. This is an important tool to leverage better protection for your agency and customers, and it won’t cost you anything. First, remember that when you hold funds in a fiduciary capacity, as you do premium funds, you are responsible for the entirety of the amount until the funds have been transferred to their real owners (the carriers, or the insureds). The Federal Deposit Insurance Corporation (FDIC)* is there to protect against a bank’s financial collapse. The principle is that if both the bank and the specific type of account used are insured by the FDIC and the bank goes under, the FDIC will cover your premium funds, up to $250,000 per depositor. In other words, if you don’t do anything special with the account, your premium funds are covered up to $250,000, period. That may not be sufficient since your account could hold more than that throughout the year.
WHAT CAN YOU DO?
This simple change can greatly enhance protections for your fiduciary funds. * If you are using a credit union, a protection similar to the FDIC exists for federal and most state credit unions, through the National Credit Union Share Insurance Fund (NCUSIF). This document is not a legal opinion and should not be relied upon as such. The intent of this document is to provide a general background regarding the topic or topics discussed, not to provide legal advice. Producers and agencies should consult an attorney regarding specific situations and specific questions with respect to the topic or topics covered in this document. Neither the Insurance Agents & Brokers nor any of its employees shall be responsible for any errors or omissions regarding any statements made in this document, nor any errors or omissions regarding any statutes, regulations, court rules, and/or any other government documents cited in this document.
Are you looking for
MARKET ACCESS?
You may be able to leverage better FDIC protection by properly identifying and naming your fiduciary account with your bank. Instead of getting the $250,000 FDIC limit for your entire account, you could get the $250,000 limit to apply for each beneficiary under the account (every carrier whose funds are in the account, and every customer before the due date). To make sure this is reflected on the bank’s records, you must:
Take a look at IMS
▲ Identify the account as a fiduciary deposit account with multiple beneficiaries, but make sure it’s not identified as a trust account; and
• 100% ownership of expirations
▲ Name the account as “[Agency name] for itself and as agent for others.” Use the FDIC opinions reproduced in our white paper (see IABforME.com/white-papers) to
IABforME.com |
• A broad mix of standard and niche markets • No initiation or monthly fees • Low to no volume commitments • Standard commission rates • You will be the agency of record on all policies
IMSaccess.com
Contact Priscilla Williams PriscillaW@IABforME.com 800-998-9644, ext. 803
3
RENTAL CARS REVISITED … AGAIN By Bill Wilson In 2024, my column entitled “Rental Cars Revisited” (issuu.com/primary_ agent/docs/august-2024) presented 10 reasons to buy the rental car loss damage waiver (LDW) rather than rely, as some consumer websites suggest, only on your own car insurance to respond to an accident that results in damage to the rental car. This is what the late, great Don Malecki, CPCU referred to as a “belt and suspenders” approach to risk management. There are some things most auto policies cover that LDWs don’t such as impaired driving, operating a vehicle on unpaved roads, undeclared but permissive drivers, etc. There are some things most LDWs cover that auto policies don’t such as diminished value, unlimited loss of use, excluded vehicles, etc. 4
However, is it possible that an accident in a rental car can result in claims not covered by either LDWs or auto insurance? Yes, it’s possible. If that happens, then someone contemplating renting a car probably must employ either the Avoidance or Assumption risk management approaches. The “Assumption of Risk” approach requires consideration of what I call the “IMAHANH” Doctrine, as discussed below. To illustrate this point, let me tell you about the time my wife and I went to Maui. Everyone told us, “You MUST eat at Mama’s Fish House, an exclusive open-air restaurant right on the beach (where two house salads and ice teas cost us $70). Mama’s Fish House has ONLY valet parking. There are many other AUGUST 2026
restaurants and some hotels that also have no self-parking. Here’s the risk management issue…. If you buy an LDW, it typically is voided if you, in any way, violate the rental agreement. One way that can happen is if the rental car is being operated by an unauthorized driver. Most LDWs consider the named renter to be an authorized driver. Some also consider a spouse or perhaps a co-worker or other traveling companion to be an authorized driver, though there may be an extra charge to be designated as such. Unless the rental agreement includes valets and parking attendants as authorized drivers, letting a valet operate the rental car could void the LDW and result in the renter
COVERAGE CORNER being financially responsible for any damage to the rental car caused by the valet.
if you valet park your own declared auto, this condition doesn’t apply. It only applies to non-owned autos.
So, if that happens, under a belt and suspenders approach, we look to the driver’s auto policy for coverage. As we all know, auto insurance, despite incessant advertising to the contrary, is not a commodity where coverage is the same from one policy and insurer to another.
So, if you can’t reliably transfer this risk of loss to your insurer via an auto policy or the rental car agency via an LDW, what can you do to manage risk of loss? Probably the best risk management approach is Avoidance … don’t valet park a rental car! If you must valet park a rental car, then your default risk management approach could be Assumption of Risk.
Some auto policies don’t extend physical damage coverage to nonowned autos or certain types of non-owned autos such as pickups or vehicles over a certain weight or to vehicles being used for business purposes. Some auto policies have even more onerous exclusions. But let’s assume the policy in question is a plain vanilla ISO Personal Auto Policy (PAP). This is what the ISO PAP says with regard to physical damage coverage on a nonowned auto [emphasis added]: Any private passenger auto, pickup, van or ‘trailer’ not owned by or furnished or available for the regular use of you or any ‘family member’ while in the custody of or being operated by you or any ‘family member’…. When you relinquish possession of a rental car to a valet, it’s certainly no longer being operated by you or a family member, but is it still in the “custody” of you or a family member? According to Webster, “custody” means “immediate charge and control…exercised by a person or an authority.” When the valet takes control of the rental car, is it still in the “immediate control” of the authorized driver? Arguably, it’s not. Under the ISO PAP,
But what if you choose to assume the risk by valet parking the rental car anyway? This is when the “IMAHANH” Doctrine may come into play. Let’s go back to my Mama’s Fish House example. The acronym “IMAHANH” (which kind of sounds like an Hawaiian word) translates to “If Mama Ain’t Happy, Ain’t Nobody Happy.” When I explained our risk management dilemma to my wife, including the Avoidance principle, her response in no uncertain terms was “WE’RE GOING TO MAMA’S FISH HOUSE.” Our decision dilemma was immediately resolved … we were using the Assumption of Risk technique. Our best bet was to hope that nothing happened but, if it did, the rental car company wouldn’t ask a lot of questions and/or the insurance adjuster would not be familiar with this interpretation of that policy provision. A better approach was to understand the exposure in advance and, if we were staying at a hotel or going to a restaurant that only had valet parking available, we should Uber there. In this instance, nothing happened. So, this invoked the “HWHL” Doctrine which is, of course, “Happy Wife, IABforME.com |
Happy Life.” I love happy endings, no matter how perilous the journey to get there. Bill Wilson, CPCU, ARM, AIM, AAM is the founder and CEO of InsuranceCommentary.com and the author of six books, including the Amazon 4.8 star “When Words Collide…Resolving Insurance Coverage and Claims Disputes” which BookAuthority ranks as the #1 insurance book of all time. He can be reached at Bill@InsuranceCommentary.com.
Rather listen? Also available in audio format at IABforME.buzzsprout.com
LIVE CE WEBINAR
|
Earn CE and learn more about personal lines. Instructor: Nicole Broch
PERSONAL LINES: READ THE %^&* FORM! AUG 25 2-3 PM
CE
PA/DE: 1 GEN MD: 1 PC
IA&B Members: $25 (save $30!) Non-Members: $55
Register today. IABforME.com 800-998-9644, option 1
5
NEWS & NOTES
NEW ICCP GRADUATE Congratulations to the latest graduate of the Insuring Careers Certification Program (ICCP): Claire Lucas The Hartman Agency State College, PA Developed by IA&B, ICCP is designed specifically for newcomers to the Property & Casualty insurance industry in Pennsylvania, Maryland, and Delaware. The program breaks down the complex world of insurance into clear, management segments, helping new employees gain confidence and a solid foundation in their careers. Learn more: IABforME.online/ insuring-careers-agencies Questions? Contact VP-Membership Tim Wonder at 800-998-9644, ext. 351 or TimW@IABforME.com.
discussion on advancing more women into leadership roles to strengthen organizations, drive, innovation, and build more inclusive, high-performing businesses. Save your spot. IABforME.com/women-in-insurance 800-998-9644, option 1
REGISTER FOR YOUNG AGENT CONFERENCE DELAWARE MEMBERS ATTEND INDUSTRY RECEPTION IA&B members and staff this summer attended the annual Delaware Insurance Industry Reception, sponsored by IA&B, several insurers, and other industry stakeholders. The reception was attended by several Delaware legislators including Senate Banking, Business, Insurance, and Technology Chair Spiros Mantzavinos, as well as Insurance Commissioner Trinidad Navarro.
WEBINAR FOR WOMEN Don’t miss the next webinar in IA&B’s series for women in insurance: Closing the Leadership Gap One Rung at a Time Aug. 18, Noon-1 PM No cost for IA&B members and partners Julie Webb, CIC, CPCU, founder of JMW Collective, will lead the
6
Pictured (l to r): John Savant, of IA&B; Rebecca Giacometti and Peter Wolff, of Wolff Insurance Agency; Lisa Broadbent, of Broadbent Insurance; DE Insurance Commissioner Trinidad Navarro; and Lee Dotson, of Bellevue Insurance Services
AUGUST 2026
Don’t miss the only conference designed for young insurance professionals in Pennsylvania, Maryland, and Delaware. IA&B Young Agent Conference Oct. 13-14, 2026 Wyndham Gettysburg Gettysburg, PA This conference brings together an energetic, driven group of young agents who are actively seeking to develop their skills and careers. Register by Aug. 31 for early bird pricing. IABforME.online/YAconference 800-998-9644, option 1
Tailored Support. Profitable Growth. True Independence. Meet the team that will be there for you in Delaware, Maryland and Pennsylvania:
Allen Kramer
Kurt Keller
Erin Marshall
Chris Ward
Shanna Muscavage Matt Fawber
Build equity value while remaining 100% independent. Win more new business through optimized markets.
|
Grow top-line commission revenue.
|
Increase profit-sharing revenue with enhanced incentives for profitable growth.
Learn more about the Ironpeak network at ironpeak.com.
Formerly Iroquois¨ IABforME.com |
7
Q&A with
ROBERT KNOWLES Robert Knowles Jr. is president of Knowles Insurance, a full-service independent agency headquartered in Scranton, PA. His sons, Matthew and Jack (pictured), recently joined the agency, marking the fourth generation in the family business. Q. Ownership of Knowles Insurance dates back several generations. Was it always your intention to join the family business? And how did your career unfold? A. After graduating from college, I began my career with Hartford Insurance Group. Joining the family business was not an obvious choice. I understood that family businesses can have some unique challenges, and even at a young age I was thoughtful about that decision. However, I was uncertain about a career in corporate America and thought the independent agency system would be a better fit for me. I really like the entrepreneurial spirit of the agency system and decided to stake my future there. Q. Your agency recently acquired two other independent agencies. What made them the right fit? A. Those agencies were very concerned about the impact a sale would have on their employees and clients. Truthfully, it was much more than just a financial transaction. They wanted to understand our service model, our core values, the knowledge and expertise of our staff, and what life would look like after the sale. Our company has a long history in the industry, and they felt confident we were committed to serving the best interest of their insureds. The integration was seamless because of our team at Knowles. We were thoughtful about minimal disruption in the transition period and primarily focused on the customer experience. Weekly we met to discuss integration issues and address any challenges or concerns. 8
Strategically, we shared many of the same insurance carriers, similar client profile, and commitment to ethics and integrity. Our goal was to find agencies whose values and behaviors were aligned with Knowles'. Their goal was to sell to insurance people committed to the independent agency system. Q. For others who are considering the purchase of peer, retail agencies, what advice would you offer? A. There are several questions you should consider: First, are they a good fit? Do they do business the same way you do business? Would their employees fit into your organization? Do you have shared values? Second, do you have a team and infrastructure that would allow for a successful integration? Lastly, can you provide real value to the selling principal(s), the employees, and the insureds? This is the most important factor when considering an acquisition. Q. Your agency specializes in cyber risk. How is that market evolving? A. Cyber risk is top of mind for many of our clients. Organizations of all sizes are concerned about the potential impact a cyber event could have on their operations, finances, and reputation. What makes cyber risk particularly challenging to manage is its constant evolution. Threat actors continue to develop new attack methods, and policy forms must evolve just as quickly to properly address emerging exposures. We
AUGUST 2026
AGENT INTERVIEW continue to see ransomware, data breaches, and funds transfer fraud as some of the most significant cyber risks facing businesses today. The specific exposures vary based on a company's industry, size, and operations.
We are optimistic about the future of the insurance workforce. Many colleges and universities are offering degrees in insurance and risk management. Today 40% of Knowles' workforce is under the age of 35 years old.
To help our clients manage these risks, we take a datadriven approach. We benchmark cyber insurance limits against peer organizations, model different cyber loss scenarios using specialized risk modeling tools, and help clients understand the financial impact of various cyber events. This allows us to structure insurance programs that align with the organization's actual exposure rather than relying on generic coverage recommendations.
There are endless opportunities for people with an entrepreneurial spirit, and the barriers to success are very limited. It is the reason my son left a career in corporate M&A to launch our acquisition strategy. Both of my sons see great potential in this industry where you can actually build something.
From a market perspective, cyber insurance pricing has been surprisingly stable despite an increase in claim frequency and severity. The primary reason is the significant amount of carrier capital that has entered the market in recent years. Insurers continue to see cyber as a growth opportunity, which has created a competitive marketplace and helped keep rates relatively flat. That said, we expect pricing pressure to increase at some point in the near future as carriers adjust to ongoing loss activity and claims experience. Q. What concerns you most about the future of the independent agency channel? And what gives you optimism?
Q. How are you preparing your agency for the next generation of leadership. A. You can't build a next generation of leadership without existing leadership. I have been blessed to work with people who are great leaders in their own right. Our agency's success is the sum of all parts. Truthfully, most good things that have happened in my career are because of the people I’m surrounded by. I can't take complete credit for navigating the changing landscape of the insurance distribution system. I have been blessed to work with truly amazing people. Continued on page 10
A. As we look at the future of the independent agency channel, our concern is long-term succession planning. So many agencies are challenged to find a perpetuation plan that does not involve the sale of their company. Their options are limited to large aggregation models that focus on short-term results. It is unclear if that route is a good thing for their employees, customers, or their communities. Without a perpetuation plan I would have been faced with the same option set. It is one of the reasons we decided to pursue an acquisition strategy with a long-term orientation. Our strategy focuses on sustainable growth, investment in human capital, and innovative solutions for our clients. We believe this is an attractive succession solution for like-minded agencies. Admittedly, there is a leadership vacuum in the insurance distribution system as more senior people retire. For years insurance sales was thought of as a second-tier career. That has changed as more people understand its complexities and the knowledge and expertise necessary to be successful. IABforME.com |
9
AGENT
Continued from page 9 Regarding the next generation, we are empowering young people to take ownership of the future. My role is changing, and I am excited to let others lead. My son Matthew worked in New York for Chubb and Willis Towers Watson. He understands the industry and brings a wealth of cyber-risk knowledge and large account management expertise to our agency. My son Jack has been in finance for 10 years with experience in investment banking and private investing. His M&A knowledge will inform our acquisition and integration strategy. With the two of them at the helm, they will build a team that can execute our growth strategy and continue to serve our clients.
RIP INTO COVERAGE
SMOOTH OUT YOUR RIDE Insuring Opportunity Through Mutual Success.¨
Trust Harford Mutual Insurance Group to provide comprehensive property and casualty insurance designed to protect what matters most to policyholders— their business.
I believe young people are joining our company because they see a proven track record and young leadership. They want to be part of something bold and exciting. I am glad to know what we have built at Knowles will continue and will grow. We are beginning a new chapter while understanding our commitment to core values that have served us for four generations. Q. When you are not working, how do you enjoy spending your time. A. That is easy to answer — my greatest joy is my family. I never lose sight or gratitude for how lucky I am. I believe relationships are the currency of life and enjoy spending time with friends. Those relationships span many generations and have been the source of great joy and happiness. Beyond that, I work out most days, as life requires energy. And I play golf just to stay humble. 10
Learn more about the other Property & Casualty classes we write. www.harfordmutual.com (800) 638-3669
AUGUST 2026
Learn more at iavaluations.com
BUSINESS PLANNING TO HELP YOUR AGENCY REACH ITS GOALS Strengthen your agency’s future with IA Valuations’ perpetuation-focused expertise. Whether you’re planning an internal transition, preparing the next generation of ownership, or evaluating growth and exit opportunities, our team provides strategic guidance tailored to your long-term goals. We specialize in helping independent agencies build clear, sustainable perpetuation plans that protect value and ensure continuity. From ownership transitions to broader consulting needs, you can trust us to simplify complex decisions and position your agency for lasting success.
INTERNAL PERPETUATION PLANNING
AGENCY LINK: BUY-SELL ADVISING
BUSINESS CONSULTING SERVICES
Jeff Smith, JD, CIC, CAE Chief Executive Officer jeff@iavaluations.com
Jodie Shaw, CLCS, CPIA, TRA Director of Business Development jodie@iavaluations.com
www.iavaluations.com
Jarod Steed Business Planning & Valuation Analyst jarod@iavaluations.com
Craig Niess, CVA, MBA Director of Business Planning & Valuation craig@iavaluations.com
Colleen Elliott Marketing & Communications Manager colleen@iavaluations.com
contact@iavaluations.com
614-607-1657
PLATINUM PARTNER PROFILE
Insurance Agents & Brokers proudly recognizes NJM Insurance Group as one of its Platinum Partners.
Total Insurance Solution We offer workers’ compensation, ProPack Commercial Package Policy, ProEdge Businessowners Policy, commercial auto, and commercial excess and umbrella insurance.*
Strong Regional Presence Our business insurance products are available in Connecticut, Delaware, Maryland, New Jersey, New York, and Pennsylvania.
NJM Insurance Group Founded in 1913 by business owners for business owners. NJM understands customers want to feel secure in their insurer. Our passion for service translates to an earned reputation for the highest levels of customer satisfaction. Plus, our 110+ year commitment to safety shows in the tools and resources we provide so employers can reduce the frequency and severity of accidents in their workplace. We instill confidence in our policyholders by providing coverage that meets their insurance needs, so they can focus on what matters most: growing their business.
12
Value-Based Insurance NJM helps business owners keep insurance costs low with loss prevention resources and time-tested, efficient, and cost-effective claims management.
Financial Strength We have an A+ (Superior) rating by AM Best, with a Financial Size Category of XV ($2 billion or greater). †
Marketing Benefits and Sales Support NJM-appointed agents receive a variety of marketing tools and support, including a co-branded billboard program, access to lead sharing, the ability to co-brand direct mail and marketing materials, and invitations to exclusive events.
AUGUST 2026
Thank You
Thanks to our PLATINUM PARTNERS for supporting the independent agent network. PARTNER & EDUCATION STEWARD
Progressive PLATINUM PARTNERS
Chesapeake Employers' Insurance Company
Franchise Value Model With limited appointments in each geographic area, your agency will have more opportunities to sell NJM Business Insurance.
Erie Insurance
Visit njm.com/become-an-agent to learn more.
Keystone
* Products not available in all states. Commercial excess and umbrella coverage is available only to NJM ProPack or ProEdge policyholders, subject to underwriting approval and underlying coverage requirements.
Millers Mutual Insurance
†
For the latest ratings, access www.ambest.com.
All applications for insurance are subject to underwriting guidelines and approval. Coverage and discounts are subject to policy terms, exclusions, and effective dates; limits and deductibles apply. Coverage is not available in all states. Insurance underwritten by NJM Insurance Company and its subsidiaries, 301 Sullivan Way, W. Trenton, NJ 08628.
Ironpeak (formerly Iroquois)
NJM Insurance Group Penn National Insurance Plymouth Rock Assurance Vesper Risk BECOME A PARTNER TODAY Interested in becoming a partner? Reach out today. Tim Wonder IA&B VP-Membership 717-918-9223 TimW@IABforME.com
IABforME.com |
13
Insurance Agency M&A Environment: TWO TRUTHS AND A LIE By Jeff Smith, JD, CIC Given the massive number of M&A transactions in the Independent Agency (IA) system over the past decade, it has created an abundance of misinformation about the M&A environment for independent agency owners. In an effort to clear up some of the misconceptions, we are going to engage in a game of two truths and a lie.
Truth #1 The IA system is undergoing massive consolidation and an unprecedented wealth transfer. Macro-economic forces are causing agency owners to transition ownership every year. These forces include:
Truth #2 Agency values are at record levels. According to IA Valuations’ data, the average EBITDA valuation multiple is 8.5 across all combined revenue categories, and the revenue multiple in an external sale is 3x regardless of the profile of an insurance agency. Agency values rose another 8.7% in 2025.
■ Record-high agency valuations: 42% increase in eight years
Agencies are realizing higher multiples in large part because of the recent revenue growth from the hard market (10.9% C&F growth), the attractiveness of the recurring revenue model for insurance agencies (average retention rates of 90%+), and the high profit margins they operate on (average 27% EBITDA profitability margin).
■ Billions of dollars of investments being infused into the IA system: estimated $85B invested or available for investment
The Lie
■ Aging principals: 37% of agency principals are over 61
■ AI-fueled technological uncertainty According to Optis Partners, there have been 7,633 M&A agency and broker transactions since 2016. To measure the increase in M&A activity, we looked at fiveyear increments; from 2013 to 2017, there were 2,161 transactions, and from 2021 to 2025, there were 4,455. That represents a 106% increase in M&A transactions over those five-year time frames. While the M&A market has cooled off from its peak in 2021 (33% decrease), we are 14
still in an environment with a bounty of hungry buyers and a decreasing number of sellers.
The lie is that Private Equity (PE) and publicly traded brokers are responsible for the majority of the M&A transactions in the market. While it is true that PE and publicly traded brokers are responsible for the majority of the publicly reported transactions that make headlines in insurance trade journals, this percentage does not reflect the actual number of M&A transactions. These buyers and acquisitions get all of the attention because they are the only ones putting their M&A activity into trackable press releases and public outlets.
AUGUST 2026
M&A ENVIRONMENT
72% of ownership transitions are retail agency to retail agency The truth is, the headlines are only half the story. According to IA Valuations data, 72% of ownership transitions in 2025 were between privately held retail insurance agencies, which includes a split between internal perpetuations and external sales to friendly retail agency competitors. This should be encouraging for every aspiring agency owner and entrepreneur thinking about entering the IA space. Despite all the recent M&A activity in the past 10 years, there are still approximately 39,000 independent agencies, according to the 2024 Agency Universe Study, and retail agency ownership transitions far outnumber the PE/public broker transactions.
Whether you are planning to buy, sell, or hold, the key takeaway from this article should be to have a plan, execute the plan, and ignore the noise. Just because your agency peer is sold or is selling, does not mean that you should. Build a plan and run your own race.
About IA Valuations and Agency Link – Founded in 2017, the IA Valuations team has performed over 400 valuations to independent insurance agencies across the U.S. Our advisors have 30+ years of experience guiding agency owners on maximizing their agency value, planning, and legal needs for ownership transition. In addition, IA Valuations has provided perpetuation planning, financial modeling and business planning for independent insurance agencies. Finally, IA Valuations has advised dozens of agency owners on selling their agencies through our Agency Link process. Agency Link is a platform that connects buyers and sellers together to further the growth and strength of the IA system. To learn more about IA Valuations, please visit IAValuations.com or contact@iavaluations.com.
OCTOBER 13-14 GETTYSBURG, PA YOU ARE INVITED TO JOIN US FOR THESE INCREDIBLE SESSIONS: ▲ E&O Mock Trial ▲ Leadership for Everyone ▲ Responsible AI in Insurance ▲ Understanding Work Styles ▲ Strengthen Content for Leads ▲ Roundtable Discussions ▲ Networking & More
FULL AGENDA & SPEAKER INFO: IABforME.com |
15
Rated A (Excellent) by AM Best
EARN CE WITH IA&B
WELCOME NEW MEMBER Next Level Insurance LLC Phoenix, MD For information about membership or benefits, contact: Tim Wonder, VP-Membership 717-918-9223 TimW@IABforME.com
E D U C AT I O N SCHEDULE AUGUST 2026 Register today! 800-998-9644, option 1 IABforME.com/education CLASSROOM DATE TOPIC
LOCATION
Aug 11-13 Property & Casualty Licensing Study Course
Mechanicsburg, PA
VISION
LIVE WEBINARS DATE TOPIC
TIME
A thriving independent insurance agent community.
Aug 5
CISR-Personal Auto
8 AM-4:15 PM
Aug 5
“Where the H*ll Is My Stuff?” Addressing Supply Chain Exposures with Small Biz Insureds
11 AM-12 PM
MISSION STATEMENT
Aug 5
Bad Machines, Evil People: The Latest in Cyber
1-4 PM
Aug 6
Ethics, Diligence, Success: What Agencies Need to Know
9 AM-12 PM
Aug 6
Retirement Income Solutions – Social Security and Others
1-4 PM
Aug 11
Commercial Property: Claims, Coverages, Consequences
1-4 PM
Aug 12
CISR-Commercial Casualty II
8 AM-4:15 PM
Aug 12
Fun (and Dangerous) as H*ll: Insuring Small Vehicles and Watercraft 11 AM-12 PM
Aug 13
Agency Audits: How to Create Efficient, Profitable and Defensible Workflows
9 AM-12 PM
Editor: Karen Robison KarenR@IABforME.com 717-918-9209
Aug 13
The Contractor’s Property Coverages Workshop
1-4 PM
To serve as a driving force to champion independent agency success by educating, consulting, advocating, and fostering community in Pennsylvania, Maryland, Delaware, and beyond.
PRIMARY AGENT
Aug 18-19 James K Ruble Graduate Seminar
8 AM-5:15 PM
Aug 18
Women Focused Webinar: Closing the Leadership Gap One Rung at a Time
12-1 PM
Contributing editors: Jennifer Ross Megan Fioretta Sarah Haas
Aug 19
CISR-Other Personal Lines Solutions
8 AM-4:15 PM
Aug 20
The Contractor’s Liability Insurance Workshop
9 AM-12 PM
Aug 20
Coverage Essentials: Homeowners Part 1 – Policy Definitions, Liability Coverage and Policy Condition
1-4 PM
Sales Account Executive: Rebecca Sieg rebecca.sieg@theygsgroup.com 717-430-2351
Aug 25
Homeowners Endorsements Insureds Don't Want (But Do Need)
9 AM-12 PM
Aug 25
An Hour with Nicole: Personal Lines: Read the %^&* Form!
2-3 PM
Aug 26
CISR-Commercial Casualty I
8 AM-4:15 PM
IABforME.com |
17
©2026
Risk is everywhere. In everything. With Applied Underwriters by your side, the gears of commerce, innovation, and exploration keep turning. Experience the unrivaled heart and unwavering service that only Applied delivers. Learn more at auw.com or call (877) 234-4450.