Brighton Market Update 2 nd H a l f 2 0 2 6
FUTURE DEVELOPMENTS
OVERVIEW
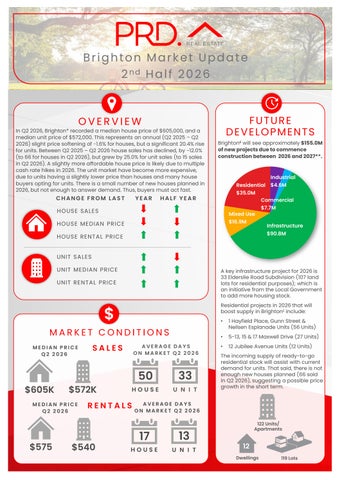
In Q2 2026, Brighton* recorded a median house price of $605,000, and a median unit price of $572,000. This represents an annual (Q2 2025 – Q2 2026) slight price softening of -1.6% for houses, but a significant 20.4% rise for units. Between Q2 2025 – Q2 2026 house sales has declined, by -12.0% (to 66 for houses in Q2 2026), but grew by 25.0% for unit sales (to 15 sales in Q2 2026). A slightly more affordable house price is likely due to multiple cash rate hikes in 2026. The unit market have become more expensive, due to units having a slightly lower price than houses and many house buyers opting for units. There is a small number of new houses planned in 2026, but not enough to answer demand. Thus, buyers must act fast.
CHANGE FROM LAST
YEAR
Brighton£ will see approximately $155.0M of new projects due to commence construction between 2026 and 2027**.
Industrial Residential $4.6M $35.0M
HALF YEAR
Commercial
HOUSE SALE S
Mixed Use $16.9M
HOUSE ME DIAN PRICE
$7.7M Infrastructure $90.8M
HOUSE RE NTAL PRICE UNIT SALE S UNIT ME DIAN PRICE
A key infrastructure project for 2026 is 33 Elderslie Road Subdivision (107 land lots for residential purposes); which is an initiative from the Local Government to add more housing stock.
UNIT RE NTAL PRICE
Residential projects in 2026 that will boost supply in Brighton£ include:
$ MARKET CONDITIONS MEDIAN PRICE Q2 2026
$605K
$572K
MEDIAN PRICE Q2 2026
$575
SALES
AVERAGE DAYS ON MARKET Q2 2026
50
33
HOUSE
U N I T
RENTALS
$540
•
1 Hayfield Place, Gunn Street & Neilsen Esplanade Units (56 Units)
•
5-13, 15 & 17 Maxwell Drive (27 Units)
•
12 Jubilee Avenue Units (12 Units)
The incoming supply of ready-to-go residential stock will assist with current demand for units. That said, there is not enough new houses planned (66 sold in Q2 2026), suggesting a possible price growth in the short term.
AVERAGE DAYS ON MARKET Q2 2026
17
13
HOUSE
U N I T
122 Units/ Apartments
12 Dwellings
119 Lots
%
AVERAGE VENDOR DISCOUNT*
Average vendor discount reflects the average percentage difference between the first list price and final sold price. A lower percentage difference (closer to 0.0%) suggests that buyers are willing to purchase close to the first asking price of a property.
5.0%
4.0%
2.7%
1.4%
1.0%
5.2%
4.4%
1.1%
2.0%
3.9%
3.0%
4.1%
4.0%
-1.0%
-2.0%
-0.5%
-1.0%
-0.8%
0.0%
-0.8%
Change from Listing to Sale Price
6.0%
-3.0% Q1 2025
Q2 2025 Q3 2025 Q4 2025
House
Q1 2026
Q2 2026
Unit
In the past 12 months to Q2 2026 average vendor discount for houses and units have swung to premium of 4.0% and 2.7%, respectively. Market conditions in Brighton* now favour owners, where buyers must offer above the first listed prices. A premium for both houses and units has been the pattern for the past 12 months, and with only a limited number of new houses planned this is likely to continue. The suburb of Brighton has historically tracked on par with the wider Brighton Local Government Area (LGA) for median house and unit prices in the past 5 years. That said, as of the start of 2026#, price growth in the suburb has outpaced the LGA, creating a premium house and unit market. Most of the houses sold in Brighton* in 2026# were in the more affordable bracket of $500,000 to $599,999 (31.6%) and the middle price bracket of $600,000 to $699,999 (23.5%). Similarly, most of the units sold were in the more affordable bracket, of $500,000 to $549,999 (29.0%), and the middle bracket of $550,000 to $599,999 (22.6%). There are ample sales in all the other price brackets for house. Overall, this suggests that Brighton* has a home for all budgets, making it an ideal market for investors and first home buyers alike.
MARKET COMPARISON
Brighton House
$800,000
Brighton LGA House
Brighton Unit
Brighton LGA Unit
$700,000 $600,000 $500,000 $400,000 $300,000 $200,000 $100,000 $0 2022
2023
2024
2025
2026#
The market comparison graph provides a comparative trend for the median price of houses and unit in the past 5 years. The main LGA profiled was chosen based on their proximity to the main suburb analysed, which is Brighton.
$
PRICE BREAKDOWN 2026# UNITS SOLD
HOUSES SOLD 13.3%
11.2%
Less than $499,999 $500,000 to $599,999
20.4%
31.6%
23.5%
9.7%
22.6%
16.1%
Less than $499,999 $500,000 to $549,999
$600,000 to $699,999
$550,000 to $599,999
$700,000 to $799,999
$600,000 to $649,999
$800,000 and above
22.6%
29.0%
$650,000 and above
RENTAL GROWTH 2026 €
House rental yields in Brighton¥ was 4.4% in June 2026, higher than Brighton LGA (4.0%) and Hobart Metro (3.5%). This was paired with a 22.3% increase in median house rental price in the past 12 months to Q2 2026, at $575 per week. The number of houses rented also increased, by 13.2% in the past 12 months, to 86 rentals in Q2 2026. The rental market in Brighton¥ is in high demand, which is beneficial for investors looking for a more affordable option to Hobart.
2 BEDROOMS
+6.7%
3 BEDROOMS
3-bedroom houses have provided investors with +13.5% rental growth annually, achieving a median rent of $522 per week.
+13.5%
Brighton¥ recorded a vacancy rate of 0.2% in June 2026, which is lower than Brighton LGA 1.3% and Hobart Metro 0.7%. Vacancy rates in Brighton¥ have remained stable in the past 12 months, indicating a tight and resilient rental market. Further, a 0.2% vacancy rate is significantly below the Real Estate Institute of Australia’s healthy benchmark of 3.0%, indicating there is quicker occupancy of rental homes in Brighton¥. This creates a conducive environment for investors, especially due to lower house sales price (thus, entry price) in the past 12 months to Q2 2026.
4 BEDROOMS
+7.7%
RENTAL VACANCY RATES 2026
3.50% 3.00% 2.50% 2.00% 1.50% 1.00% 0.50% 0.00%
REIA 'Healthy' Benchmark
%
RENTAL YIELD 2026 §
4.4%
4.0%
3.5%
Brighton (7030)¥
Brighton LGA
Hobart Metro
5.0%
Brighton (7030)¥
Jun-26
Mar-26
Dec-25
Sep-25
Hobart Metro
Jun-25
Brighton LGA
Mar-25
Dec-24
Sep-24
Jun-24
Mar-24
Dec-23
Sep-23
Jun-23
Brighton (7030)
5.6%
5.6%
Brighton LGA
Hobart Metro
PROJECT DEVELOPMENT MAP 2026-2027₳ LEGEND Commercial Infrastructure Industrial Mixed-Use
BRIGHTON
#
Residential
Pr oject £
1
Youth Detention Facility Pontville (State Government)
2
1 Hayfield Place, Gunn Street & Nielsen Esplanade Units (56 Units
3
33 Elderslie Road Subdivision (107 Residential Lots) (State Government)
4
Type
Estimat ed Commence Value µ D ate ψ
Infrastructure $75,000,000
22/03/2027
Residential
$17,000,000
12/02/2027
Infrastructure
$10,000,000
13/10/2026
5-13, 15 & 17 Maxwell Drive Units (27 Units)
Residential
$7,500,000
10/07/2026
5
Mitchell Plastic Welding Bridgewater Manufacturing Facility & Offices (Manufacturing Facilities/Offices)
Mixed Use
$4,400,000
19/02/2027
6
Lots 974 & 975 Scott Road Dwellings & Residential Subdivision (12 Infrastructure Dwellings/12 Residential Lots) (Local Government)
$4,000,000
17/12/2027
7
12 Jubilee Avenue Units (12 Units)
Residential
$3,600,000
23/02/2027
8
3 Woodrieve Road Warehouse (Warehouse/Office)
Mixed Use
$3,500,000
4/06/2027
9
72 Elderslie Road Units (13 Units)
Residential
$3,300,000
12/01/2027
10
Kent Bridgewater Warehouse (Warehouse/Office)
Mixed Use
$3,000,000
27/11/2026
11
6 Woodrieve Road Self Storage Facility Stages 1-3
Commercial
$2,745,000
8/06/2027
12
Greenbanks Road Warehouse & Office Building
Mixed Use
$2,500,000
1/07/2027
13
9 Woodrieve Road Warehouse Buildings
Industrial
$2,264,400
5/05/2027
14
5 Woodrieve Road Storage Units
Commercial
$2,000,000
16/07/2027
15
15 Lukaarlia Drive Warehouses Stages 2&3
Industrial
$2,000,000
15/07/2027
16
14 Klukaarlia Drive Workshop (Workshop/Office)
Mixed Use
$2,000,000
26/07/2027
17
7 Silvergum Street Units (7 Units)
Residential
$1,700,000
3/04/2026
18
30-33 Harvest Lane Workers Accommodation Buildings Derwent Valley Line Rail Resleepering & Rerailing Works Year 2 (State Government)
Commercial
$1,000,000
1/05/2026
Infrastructure
$1,000,000
11/05/2027
Mixed Use
$1,000,000
5/03/2027
19 20
451 Tea Tree Road Farm Stay Accommodation & Cellar Door (Farm Stay Accommodation/Cellar Door)
Your home of the latest property market insights.
RESEARCH SERVICES
OUR KNOWLEDGE
Our research services span over every suburb, LGA, and state within Australia; captured in a variety of standard and customised products, and include:
Access to accurate and objective research is the foundation of all good property decisions.
•
Advisory and consultancy
•
Market analysis including profiling and trends
•
Primary qualitative and quantitative research
•
Demographic and target market analysis
•
Geographic information mapping
•
Project analysis including product and pricing recommendations
•
Rental and investment return analysis
OUR PEOPLE Our research team is made up of highly qualified researchers who focus solely on property analysis.
Natalie Gray +61 417 344 822 nataliegray@prdhobart.com.au
GET IN TOUCH WITH US TODAY PRD Hobart
Your trusted local real estate agency 26 Cambridge Road,
40 High Street,
Bellerive, TAS, 7018
New Norfolk, TAS, 7140
+61 3 6244 5588
+61 3 6261 2555
hello@prdhobart.com.au PRD.com.au/hobart/
REFERENCES * Brighton sales market data and key indicators encapsulates aggregate property market conditions within Brighton Local Government Area (LGA) ** Estimated values are based on construction value provided by the relevant data authority and does not reflect commercial and/or re-sale value. # 2026 encapsulates sales transactions for 2026 only (01/01/2026 – 30/06/2026). € Annual rental growth is a comparison between Q2 2025 (01/04/2025 – 30/06/2025) and Q2 2026 (01/04/2026 – 30/06/2026) house median rent figures. ¥ Brighton rental market data encapsulates aggregate property conditions within the postcode of 7030. § Rental yields shown are as reported as of June 2026. ₳ Project development map showcases a sample of upcoming projects only, due to accuracy of addresses provided by the data provider for geocoding purposes. £ Projects refers to the top developments within the suburb of Brighton Local Government Area (LGA). µ Estimated value is the value of construction costs provided by relevant data authority, it does not reflect the project’s sale/commercial value. ψ Commencement date quoted for each project is an approximate only, as provided by the relevant data authority, PRD does not hold any liability to the exact date. Source: APM Pricefinder, Cordell Connect database, SQM Research, Esri ArcGIS. Disclaimer: PRD does not give any warranty in relation to the accuracy of the information contained in this report. If you intend to rely upon the information contained herein, you must take note that the information, figures and projections have been provided by various sources and have not been verified by us. We have no belief one way or the other in relation to the accuracy of such information, figures and projections. PRD will not be liable for any loss or damage resulting from any statement, figure, calculation or any other information that you rely upon that is contained in the material. Prepared by PRD Research. © All medians and volumes are calculated by PRD Research. Use with written permission only. All other responsibilities disclaimed. © Copyright PRD 2026.