Power agency growth through smarter access to E&S markets
Power agency growth through smarter access to E&S markets
In times of uncertainty, the excess and surplus lines market provides independent agents and their clients, with options that the admitted market cannot. It’s a vital safety valve for the insurance industry and for the insurance-buying public.
The E&S market has fluctuated in last few years, and research by AM Best indicates that while the E&S market continues to grow, it’s growing at a slower pace. In fact, through the third quarter of 2025, E&S premium growth increased by 9.7%—compared to 15.5% through the third quarter of 2024.
Factors such as persistent weatherrelated losses and high repair costs have caused the underwriting criteria in the admitted market to continue to tighten, which has prompted a greater need to write insurance in the nonadmitted market, especially in the following areas:
• Property/catastrophe for coastal and wildfire-prone areas
• Older houses with older roofs
• Cyber security coverage
• Commercial auto and liability, especially for industries with fleets

Markets that continue to be competitive in the E&S market
The U.S. property/casualty sector’s E&S market share reached 9% in 2025—almost doubling since 2017. E&S premiums rose 13.2% (primarily in commercial liability and property lines).
Weather-related claims continue to make it more difficult to write certain homeowners insurance policies in the admitted market. Insured losses in 2025 were between $60-$70 billion (mostly caused by the Los Angeles wildfires and spring floods).
As more businessowners express interest in catastrophe coverage, the competition in the E&S market continues to remain steady—even as prices have moderated in both the admitted and nonadmitted markets. This may be because policyholders are interested in additional limits and policies (e.g., flood, earthquake and wind coverage) to expand their coverage.
The total amount of coverage written in the surplus lines market was $90.3 billion through the year-end 2025—a 7.8% increase from $83.8 billion through year-end 2024. Most of policies written were in liability, which according to various reports accounted for 36.9% to 38.1% of the total premium for 2025.
Educate your clients about p/c underwriting. Common underwriting requirements can include: age/condition, location and risk, construction type, claims history, liability risk and replacement costs.
Educate your clients about commercial property underwriting. Common underwriting requirements can include: construction classifications, loss history, accurate replacement cost estimates, occupancy, fire protection systems and locationbased exposures.
The legality of cannabis fluctuates from state to state and remains illegal at the federal level, which is why few admitted carriers offer insurance coverage for this business. Most of the coverage for each aspect of this business—cultivators, manufacturers, distributors and transporters—is found in the nonadmitted market.
These businesses have the same insurance considerations: property, general liability, cyber security liability, etc. However, the legal and financial challenges in the cannabis industry heightens the risk of liability. So, remind your clients about the importance of directors & officers coverage, as this insurance should protect a cannabis company’s management team if the business is sued by regulators.
Educate your clients about cannabis underwriting. Common underwriting requirements can include: security systems, fire protection systems, inventory security, valid licenses, compliance records, financial records, location, delivery/ transportation.
As cyberattacks and ransomware payouts become more prevalent, admitted carriers have been removing or tightening the cyber security coverage found in standard insurance policies.
Educate your clients about cyber underwriting. Common underwriting requirements include proof of: advanced security (e.g., multifactor authentication, endpoint detection), regular security assessments and audits, incident response plans, employee training and awareness programs, and data encryption and backup procedures.
According to U.S. Treasury’s Financial Crimes Enforcement Network, ransomware payouts totaled more than $4.5 billion in 2024—compared to $1.1 billion in 2023.
Generative artificial intelligence extends traditional analytics. It:
• Unlocks patterns found in unstructured information (e.g., broker notes, loss runs)
• Helps make decisions and risk selection
• Offers higher transactional efficiency AI also introduces challenges, such as: bias, and privacy and security concerns.
For three decades, PIA Northeast members who called the PIA Industry Resource Center with a technical, insurancerelated question most likely had it answered thoroughly and efficiently by Dan Corbin, CPCU, CIC, LUTC, who passed away in December, after a yearslong battle with cancer.
Corbin joined the PIA Northeast team in 1992 as a technical education specialist. In this role, he served as a teacher at PIA-sponsored education seminars, authored technical informational material for association members—including in-depth articles for PIA Magazine. (And, the magazine’s editor-in-chief remembers—with fondness—numerous conversations about the importance of words such as of and with, and the necessity of specific comma placements.) Shortly after he was hired at PIA, he became the association’s director of research, a position he held for nearly 30 years.
His insurance background spanned 45 years, with varied experience as agency owner, commercial service representative, producer, personal lines manager and insurance specialist for a mortgage lender. He was a trusted technical consultant, and he was deeply respected by PIA Northeast members and the association’s staff.
His depth of insurance knowledge, thoughtful guidance, and ability to bring clarity to complex issues made a lasting difference for independent agents throughout the Northeast. And beyond the insurance industry, he was a person of integrity, humility and quiet strength.
Those individuals who knew him will be the first people to tell you what an exemplary man Corbin was:
“Dan’s knowledge, integrity, and commitment to serving independent agents left a lasting impact on our association,” said PIA Management Services President & CEO Jeff Parmenter, CPCU, ARM, CPIA. “I am deeply grateful for Dan’s many years of service and the impact of his work.”
“Dan was not just kind and thoughtful, his intelligence and understanding of the technical aspects of the insurance industry was a PIA member benefit that was valued for decades,” said PIA Northeast Executive Director Kelly K. Norris, CAE.
“If Dan gave you an answer regarding anything insurance, you could take it to the bank. Dan was the most authoritative, knowledgeable insurance expert I ever met. He will be missed by all of us within the insurance community, and I’m sure most of all by his family and friends,” said Jim Berliner, CPCU, CIC, managing partner, The Liberty Company Insurance Brokers LLC, Monroe, Conn.
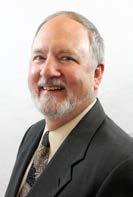
Each year, Corbin responded to hundreds of technical inquiries from PIA Northeast members. Dan was a member of the Chartered Property Casualty Underwriter Society and the Society of Certified Insurance Counselors.
He is survived by his wife, Cindy, his sons: Patrick Fleming, Josh Corbin (Jeanette), Daniel W. Corbin (Laura) and Adam Corbin (Lyndsey), his grandchildren Alaina, Elliana, Jackson and Olivia, his sisters: Nancy Heaney (John), Patty Sharp (Bill) and Kristy Adams (Stan) and his devoted terrier, Carson. Corbin’s legacy lives on—not only in the impact he made, but in the continued commitment of the PIA Industry Resource Center team to serve members with the same rigor, care and expertise he exemplified.
Even with careful planning, one unexpected claim can reach the primary limits, leaving board members at risk.
Brooks Insurance Excess D&O coverage is built exclusively for condominium and co-op boards, ensuring your clients have the proper excess limits in place.

Bradford J. Lachut, Esq. Director of government & industry affairs, PIA Northeast
For many retail agents, the excess and surplus marketplace is not the first stop—it is where they turn when the standard market says no. Or, it’s where they go when: an admitted carrier tightens guidelines; a renewal comes back restricted; a risk doesn’t fit underwriting appetite; or a closing date looms and coverage is urgent.
There is nothing wrong with this. The nonadmitted marketplace exists to provide solutions when admitted carriers cannot or will not write the risk. However, because many retail agents enter the E&S space occasionally, they may not be as familiar with its realities.
When asked what he wished retail agents better understood before entering the E&S marketplace, one wholesale broker offered this perspective:
Wholesale brokers understand that speed matters—often the expiration or closing date is approaching and coverage is needed immediately. Strong, complete, accurate submissions help meet those urgent timelines. Completeness, clarity and timely communication are essential; providing full applications, loss details and a clear narrative of the risk—along with realistic timelines and market expectations—allows wholesalers to secure better terms from their markets. Ultimately, transparent collaboration enables both sides to move quickly and deliver stronger outcomes for the insured.
Urgency is common in E&S placements. However, preparation and partnership are what determine the outcome.
One of the most critical stages in an E&S placement happens before the submission is sent to a wholesale broker.
Retail agents should confirm that the insurer being considered appears on the state’s eligible E&S insurer list—often referred to as the white list. That step helps to ensure the carrier is authorized to write E&S business in the state, and that it meets the applicable financial strength requirements. Skipping this verification can create compliance concerns and potential errors-and-omissions exposures.
Just as important is understanding whether the state requires a diligent effort to place the risk in the admitted market before turning to the E&S market. In many jurisdictions, agents must document declinations from admitted carriers unless the class of business appears on the state’s export list. If the risk qualifies for that list, the diligent-search requirement may be waived. If not, documentation matters.
Wholesale brokers can assist with navigating these rules, but compliance responsibility ultimately rests with the producing agent. Entering the E&S space without understanding these procedural requirements can transform a routine placement into a regulatory problem.
Retail agents who are accustomed to admitted carriers may expect a similar underwriting process in the E&S marketplace. The reality is different—and that difference is what makes the marketplace so valuable.
Nonadmitted insurers have flexibility. They can craft manuscript endorsements, adjust terms creatively, and respond to emerging or distressed risks that fall outside standard appetites. That flexibility allows them to write business admitted carriers cannot.
However, flexibility means underwriting tends to be more individualized and judgment-based. Often, there is less automation and more narrative evaluation. Underwriters are not simply checking boxes; they are assessing the total picture of the risk. That is why submission quality is vital.
In the admitted world, a partially completed application might generate follow-up questions. In the E&S world, it may generate hesitation.
Wholesale brokers emphasize that complete, accurate submissions are not just courteous—they are strategic. A fully developed application, current loss runs and detailed exposure information allow the wholesaler to approach markets confidently. Missing information slows the process.
In particular, loss history deserves context. Five-year currently valued loss runs are standard, but numbers alone rarely tell the full story. If a loss occurred, what happened? What corrective action was taken? Underwriters evaluate management practices as much as claim frequency.
Perhaps the most underutilized tool in an E&S submission is the narrative. A short, well-written explanation of the insured’s operations, why admitted markets declined the account, and what makes the risk well-managed can meaningfully influence underwriting perception. In many E&S placements, storytelling is part of underwriting.
Many E&S submissions arrive with urgency attached: a policy was nonrenewed; a deal is about to close; or a lender requirement surfaced late in the process. Wholesale brokers understand that pressure; it is part of the business.
Realistic expectations matter. Marketing a complex risk requires time to approach appropriate carriers, respond to underwriting questions and negotiate terms. When a submission arrives days before expiration, clarity and completeness are critical.
Transparent communication helps both sides succeed. If there are competing quotes, say so. If certain coverage elements matter most to the insured, explain that early. When wholesalers understand priorities and timelines, they can shape their marketing strategy accordingly.
One of the most important conversations retail producers must have with clients involves the regulatory differences between admitted and nonadmitted coverage.
Admitted carriers are subject to state laws governing cancellation, nonrenewal and notice requirements. Often, those statutes dictate permissible grounds for midterm cancellation and required advance notice periods. Typically, E&S carriers operate outside that statutory framework. Their cancellation and nonrenewal provisions are defined primarily by the policy language itself.
That distinction matters. Cancellation terms may differ. Notice requirements may be shorter. Minimum earned premium provisions may apply. Certain policy conditions may be more restrictive.
Retail agents should review policy forms carefully, and explain these differences to insureds. Clients accustomed to admitted policy protections may not realize that nonadmitted coverage operates differently unless it is discussed directly.
There is a common perception that E&S placements are temporary bridges back to the admitted market. While this can be true (e.g., an account im-
proves its loss history, and standard markets reopen), many risks belong in the E&S space for the long term. Emerging industries, high-hazard operations, distressed properties and accounts that require manuscript coverage often find their natural home in the nonadmitted space.
Viewing E&S as a specialized solution rather than a last resort changes the conversation agents have with clients. It reinforces that the placement reflects the nature of the risk—not a failure of the marketplace.
At its best, the retail-wholesale relationship functions as a partnership. Retail agents bring client relationships, operational knowledge and local insight. Wholesale brokers bring specialized market access and underwriting expertise.
When submissions are thorough, compliance requirements are addressed and communication is transparent, wholesalers can advocate effectively for the risk. They can negotiate stronger terms, avoid unnecessary delays and deliver solutions more efficiently.
Our professional course provides you with an opportunity to earn two hours of CE credit for learning about premium finance. Classes are available at no cost to the agency.*
Our courses are designed to help agents with:
• Knowing how premium finance works, including the loan lifecycle
• Developing the best quote and finance agreement for insureds
• Helping clients understand content in the Premium Finance Agreement
• Communicating the value premium finance offers insureds
*In-person or remote training available in CT, NJ & NY.
Visit afcodirect.com to learn more.


“In a world of customer service outsourcing, I truly appreciate the personal service from the team at Friedlander. Not only does Friedlander offer lower workers’ compensation premiums and dividend options for our insureds, but their customer service is also impeccable. Whether inquiring about prospects, quotes, or billing, the team is knowledgeable and quick to respond. The Elwood Jordans Insurance Agency is a small hometown agency, and I feel we are treated with as much importance as their larger clients.”
Jenny Urbanski, Commercial Service Manager The Elwood Jordans Agency, Inc., Alden, NY
Maria Thomas | 631-834-9829 mariat@friedlandergroup.com (LI, Manhattan, Queens, Brooklyn, Bronx, Staten Island)
Donna Nygard | 914-844-2195 donnan@friedlandergroup.com (Remainder of NY,
and
Utica National Insurance Group
Whether the insurance market is hard, soft or somewhere in between, E&S entertains varied exposures and it plays a vital role in insuring high property values, as well as risks wanting extremely high liability limits.
Using the excess and surplus marketplace presents some significant challenges and issues that can raise the potential for an increase in the agency’s errors-and-omissions exposure. It is vital to develop the appropriate processes to handle challenges.
Being knowledgeable about the coverage you are requesting is essential. Frequently, this market employs nonstandard forms to provide coverage. Do not rely solely on the carrier or wholesaler to fill any gaps in your understanding—your know-how is crucial.
After submitting an application, follow up with the carrier or wholesaler to confirm that it was received and that a proposal will be provided by a specific date. This allows you and your client time to review the terms. As the proposal date approaches, periodic follow-up is recommended to verify that the proposal is on track to be delivered as promised.
Once you receive the proposal, carefully compare it to the coverage you requested in your original submission. It is common for the E&S market to omit certain coverage elements. As the retail agent, you are responsible for ensuring that the coverage delivered matches what the client requested.
Obtain specimen forms from the E&S market, which is known for issuing unique policy forms that can alter coverage significantly. Review these forms, including any endorsements. Pay attention to endorsement titles, as they may reduce coverage even if not specifically labeled as exclusions.
Do not advise your client that coverage is bound until you have received confirmation from the wholesaler or carrier. Typically, retail agents do not have the authority to bind coverage on behalf of the wholesaler or carrier.
Establish procedures to ensure coverage is bound at or before the policy’s expiration date. If coverage is bound after the expiration date, the E&S market may refuse to backdate the coverage, potentially leaving your client exposed.
Review renewals early to determine if there will be significant differences in coverage in the renewal proposal. Unlike the admitted market, where carriers are required to provide conditional renewal notices if coverage will be reduced, the E&S carrier/wholesaler is not held to this requirement, and it is not obligated to inform you of changes.
Review the E&S policy to confirm that the coverage provided matches what was ordered. This final check helps ensure that you and your client receive the expected protection.
The E&S marketplace has different procedures than standard markets. Develop the appropriate procedures because these differences present issues and challenges. Following these procedures can help reduce the chance of E&O problems. This information and any attachments or links are provided solely as an insurance risk management tool. They are derived from information believed to be accurate. Utica Mutual Insurance Company and the other member insurance companies of the Utica National Insurance Group (“Utica National”) are not providing legal advice or any other professional services. Utica National shall have no liability to any person or entity with respect to any loss or damages alleged to have been caused, directly or indirectly, by the use of the information provided. You are encouraged to consult an attorney or other professional for advice on these issues.
Rock into the Annual Conference, June 7-9, 2026, for three groovy days of mind blowing industry insights, killer speakers, and connections that really hit the right note.
JUNE 7-9, 2026 | HARD ROCK, ATLANTIC CITY, N.J.
Industry Insights That Hit Like a Killer Hook. Just like a Stones classic, winning in insurance is all about connection. Build real, lasting relationships with fellow agents and industry icons who’ve got the kind of wisdom you can’t fake.
Experience That’s Loud, Live, and Electric. From the trade show and networking hangouts to lively panels and high‑energy education, Annual Conference brings the vibe of a packed arena— fueling your fire long after you’re back at your desk.
A Setlist of Knowledge. PIA delivers nothing but the good stuff. Our CE sessions sharpen your skills, boost your edge, and keep you leading the pack in an industry that never stops moving.
Networking Lunch featuring CEO Panel
s independent agents, we have all been there. A client calls with a new venture, property change or an exposure that no longer aligns with standard underwriting guidelines: a musician’s hand, a valuable coin collection, a hospital navigating a cyber security breach, a coastal property in hard-hit hurricane regions, etc. While you want to help—and in many cases, coverage is available—placing it may mean multiple submissions, follow-up emails and waiting to hear which markets might be interested. Meanwhile, the client is looking for answers, and your staff is already juggling a full workload.
Situations like these are becoming more common. As business models evolve, weather-related exposures increase, new risks emerge and underwriting becomes more selective, even familiar accounts may move out of standard markets at renewal.
Standard market placements tend to follow predictable workflows. Applications are structured, rating engines are defined and agency staff generally know what information is required before submitting business. Over time, producers, account managers and customer service representatives become familiar with these processes, allowing submissions to move quickly from application to quote to binding.
E&S placements operate differently. By design, the excess and surplus market exists to address risks that do not fit traditional underwriting guidelines. These risks may involve unusual exposures, emerging industries, catastrophe-exposed property or complex operational structures. As a result, underwriting approaches vary widely across markets, and each submission often requires a more customized evaluation.
More business is now landing in the E&S markets than in years past. For many agencies, E&S placement is no longer an occasional task; it is becoming another regular—if not routine—aspect of the insurance business. This new normal is demanding more time and effort on the part of customer service teams, producers and account managers.
Today, CSRs are more involved in gathering information for E&S submissions and managing follow-up. Producers are seeing more renewals that move out of standard markets. Agency owners are spending more time dealing with operational challenges tied to complex placements. All the while, clients are looking for timely responses.
For insurance agents, that means the process rarely follows a single path. A submission that looks appropriate for one market may require a completely different format for another. Supplemental applications may be required, and additional documentation may be needed to clarify exposures. In many cases, underwriting questions arise early in the process, requiring agents or customer service staff to gather more information before a quote can be considered. Even experienced agents can find that a single E&S placement involves multiple submissions, follow-up questions and conversations with wholesalers or underwriters before the account reaches the right market.
For agencies already stretched thin, this added complexity can create real strain, affecting retention for employees and clients alike, along with responsiveness and staff workload.
According to a recent report from Conning, “The Excess and Surplus insurance market has experienced unprecedented growth, achieving a remarkable 21% compound annual growth rate over the past five years and surpassing $104 billion in premiums in 2023.”1
Fortunately, it is possible for independent agents to capitalize on this growth, seizing the opportunity to turn E&S into an additional revenue stream while, simultaneously, strengthening client relationships. This can be accomplished by:
• using technology and digital tools for real-time quoting, binding and data exchange with wholesalers;
• standardizing the submission process with checklists and templates;
• establishing strong partnerships with experts who can help navigate complex niche markets and provide access to the right markets; and
• training staff to recognize risks early in the submission process.
As previously mentioned, complexity can create operational friction inside an agency. Staff may find themselves re-entering the same data into multiple systems. Different wholesalers may require slightly different submission formats, and communication cycles between agents and underwriters can lengthen as questions arise about incomplete or inconsistent information. Each of these steps adds time and effort to the placement process.
As the E&S market continues to grow, retail agents need ways to manage this complexity without slowing down their business.
As independent agents dive deeper into E&S space and look to streamline the process, they underestimate the role of technology at their peril. When it comes to complex coverage needs, complicated submissions and the need for clear communication, the goal of incorporating technology resources is not to replace existing relationships. Rather, the goal is to leverage these tools to speed up and simplify how agents
connect with E&S markets and manage submissions. Doing so ensures agents remain focused on high-level, advisory type work while employing digital tools to handle some of the administrative and time-consuming aspects of the job agents would prefer to automate anyway.
Technology tools that integrate artificial intelligence and data analytics can allow agents to submit business through a single platform and connect them with appropriate markets. We have seen firsthand how technology allows us to combine wholesale brokerage services and manage general agent capabilities within the same system. Doing so replaces the need to navigate multiple wholesaler portals, different submission requirements and repeated data entry, saving agencies’ staff hours of time and limiting room for error.
AI and data analytics can triage a submission request automatically, validate its completeness and package the risk so it is ready for underwriting. This eliminates the need for traditional back-and-forth from the beginning, providing more streamlined customer service. When submissions arrive complete, organized and aligned with market appetite, underwriters can focus more quickly on evaluating the risk itself rather than requesting additional information, improving efficiency for both sides of the transaction. Such tools can route submissions to the appropriate markets and complete the quoting, binding and post-binding process in a standardized way with complete agent oversight. Just a few of the top line benefits this technology can bring to an agency include:
• up-front triage and completeness standards so carriers see fewer half-built submissions;
• smarter routing so agents waste less time, and carriers see risks closer to their appetite;
• standardized packaging and communication: reducing back-and-forth and cycle time; and
• clear accountability: one wholesale/MGA partner for the independent agency, which drives the placement process end-to-end.
For agencies that handle a steady or increasing flow of nonstandard risks, such consolidation can reduce duplication and streamline daily workflows. Fewer systems and fewer handoffs can translate into faster turnaround and greater accuracy. It also can make it easier for agencies to take on complex accounts, which helps grow the business, without
worrying about whether they have the right market access in place. Finally, the increased speed and accuracy of these tech-enabled approaches also serve to better match a rising expectation among insurance consumers that the process will be digital, swift and tailored to their individual needs.
One of the most time-consuming parts of E&S placement is the exchange that happens when submissions are incomplete or sent to markets that are not a good fit. Underwriters may need more information before quoting, or accounts may need to be rerouted after initial review. To help reduce friction, AI tools can guide agents through the submission process to help align accounts with the right markets open to specific risks.
In many cases, agents and CSRs are doing their best to move submissions along quickly—especially when clients are waiting for quotes. Sometimes, this can mean making assumptions about property details (e.g., roof type, square footage, construction features), simply because verifying every data point takes time.
Technology can help reduce these burdens by pulling in validated third-party data from sources automatically (e.g., tax records and real estate databases) to evaluate whether the information submitted is an appropriate fit. Such systems can verify details that are especially important factors in catastrophe-exposed states while also saving agents significant time on the information gathering process.
If responses appear inconsistent—for example, a 2,600 square-foot house with a five-car garage—such tools can flag the submission before it ever reaches the market. This helps prevent delays caused by underwriters having to request corrections later in the process.
This does not eliminate underwriting questions, but it can shorten the path to meaningful conversations and viable quotes. For agents and clients alike, clarity makes a difference by distributing the workload more evenly and reducing the trial-and-error that slows placements.
Personal service continues to be one of the independent agent’s strongest selling points. Our clients value working with someone who knows their business and can respond
when their needs change. But as agencies grow, maintaining that level of service becomes more difficult without strong operational support.
If new business consistently brings more complexity, agents may feel pressure to either slow growth or accept lower service levels. Neither option is ideal—and with the right technology tools neither option needs to be a choice agents need to make.
Simplifying how complex placements are handled helps agencies grow by making it easier to say yes to more hard-toplace opportunities while maintaining responsiveness. Faster turnaround, clearer workflows and better market alignment all contribute to a smoother client experience, and it can preserve the agency’s relationship-driven approach—even when coverage needs are not straightforward.
Insurance risks are unlikely to become simpler in the years ahead. New industries, evolving technology, climate-related exposures and regulatory changes are contributing to a market in which nonstandard risks are becoming increasingly common and proper responses to those risks are needed more than ever.
For independent agents, that makes adaptability increasingly important. The ability to place complex coverage efficiently is becoming less of a specialty skill and more of a core operational requirement. Adding purpose-built technology to aid in the process, technology that improves rather than distracts from or replaces relationships, trust or local expertise, will help reduce administrative friction and allow agents to further invest in their roles as trusted advisers.
E&S placement will likely always involve more steps than standard business. However, it does not have to slow agencies down or limit growth. With the right tools and support, hard-to-place risks can become a growth opportunity rather than an operational drain. For agents navigating tighter markets and increasing complexity, that kind of support can make it easier to grow, serve clients well and build businesses that last.
Moss is CEO of Xchange–powered by SIAA, where he leads the development of E&S and specialty underwriting platforms that connect underwriting markets with SIAA–The Agent Alliance (siaa.com) distribution network through proprietary technology, data-driven product design, and targeted MGA partnerships. Learn more about Xchange (www.siaaxchange.com), or follow the company on LinkedIn (@siaa-xchange).
1 PR Newswire, 2025 (tinyurl.com/3hfyjrty)
Our new 60-Second Appetite Check is a powerful tool designed to identify available commercial lines coverages in less than one minute Our independent agents can get to yes/no (or maybe) simply and FAST, eliminating guesswork about our appetite and saving time in your day!
The enhanced digital journey is just beginning . . .
Group 534: Almost all construction trades eligible
Group 533: All types of woodworkers, lumberyards, and building material dealers
Group 501: Plumbing, heating, cooling, HVAC, and steamfitting contractors
Up front discounts up to 35%, for new businesses that qualify.
Consistent annual dividend payments—unbroken string since the group’s inception.
Staff averaging 40+ years of workers’ compensation experience.
Focused exclusively on New York’s building trades industry.
*
50% of our service fee paid to brokers for the first 3 policy terms.
Hamond Safety Management included service checklist
Payroll and audit assistance
Audit preparation and support
Class code and payroll review assistance
Hearing and claims reviews, testimony support and assistance
OSHA compliance and safety training
Risk management and job-specific safety program development
Underwriting and billing assistance
Policy renewals, review and premium optimization
Please send all quotes to Alan Cohen – Sales & Marketing Specialist (516) 762-4212 • Fax: (516) 488-5940 ACohen@HamondGroup.com • Hamondgroup.com
Thomas J. DeCotis CEO, DeCotis Specialty Insurance
Lloyd’s of London is the oldest and one of the most recognized insurance markets in the world. Despite its long history and daily use across the specialty marketplace all over the world, many retail agents still misunderstand how Lloyd’s actually works.
You’ve probably heard the famous stories about Lloyd’s insuring professional athletes’ body parts, or Bruce Springsteen’s voice being insured for millions. Those headlines helped build Lloyd’s reputation as the market for extreme or exotic placements, but in reality, Lloyd’s plays a practical role in insuring mainstream risks throughout the country.
Today, Lloyd’s represents roughly 16% of the entire U.S. excess and surplus lines market,1 making it a central participant in many placements agents handle every day—especially for coastal property, high-limit liability programs and newer or evolving risk classes. Despite this, some agents continue to view Lloyd’s as a market for unusual risks, while others treat it as a last-resort option.
Receiving multiple Lloyd’s quotes for the same risk through different E&S brokers adds to the confusion and often raises a very reasonable question: If this is Lloyd’s, why are the premiums different?
Other common questions we hear include: Is Lloyd’s AM Best rated? and How are claims actually paid?
Many agents think of Lloyd’s as just another E&S carrier, rather than the underwriting marketplace it really is. A better understanding of the Lloyd’s market allows agents to place business more confidently and explain coverage more clearly to clients, so let’s take a closer look at the most common misconceptions.
Misconception No. 1: Lloyd’s is an E&S lines insurance company. Lloyd’s is not an insurance company in the traditional sense, but rather a distinctive insurance marketplace made of over 90 (as of 2024), different syndicates regulated by the UK Financial Conduct Authority and the Prudential Regulation Authority. A simple way to think of it: It is a collection of smaller insurance companies operating under one administrative umbrella.
Lloyd’s distribution is heavily broker-driven with more than 40% of Lloyd’s gross written premium placed through its global network of coverholders—authorized underwriting partners granted delegated authority (i.e., binding authority) by the syndicates with which they do business. A coverholder also is referred to as a managing general agent.2
There are more than 1,000 coverholders operating in the United States alone, and each conducts business according to its own negotiated contract with specific Lloyd’s syndicates.3 These contracts define the coverholder’s authority, including
classes of business they can write, limits, exclusions, rating parameters and available capacity in geographic areas. Most coverholders have multiple contracts that they use on a quota-share basis to be able to offer higher limits and also spread the risk.
What does this mean for agents? When your clients buy insurance from Lloyd’s, they’re purchasing coverage from a Lloyd’s member syndicate, not from Lloyd’s itself, which acts as a governing body.
This explains why agents sometimes receive multiple Lloyd’s quotes with different premiums—the terms are coming from different syndicates with different underwriting appetites.
Advantage. If one syndicate does not renew a policy, another still may be willing to provide coverage.
Misconception No. 2: Lloyd’s is only for extreme risks. Historically, Lloyd’s became famous for insuring unusual exposures—from satellites to celebrity body parts—and that reputation has held for decades. However, in practice Lloyd’s capacity now is used in a wide range of routine commercial placements, including:
• coastal property;
• habitational risks;
• contractors;
• hospitality accounts;
• excess liability towers; and
• professional liability programs.
In many cases, Lloyd’s participation sits quietly within a layered program, and insureds may never even realize Lloyd’s paper is part of their policy.
Example: A coastal condominium association in Connecticut needed $40 million property limits. The admitted market offered only $5 million. The final solution included three carriers—one admitted primary, plus two excess layers backed by Lloyd’s syndicates. For the client, the experience looked like a standard placement. But without Lloyd’s participation, the limits simply wouldn’t have been achieved.
Misconception No. 3: Lloyd’s coverage is less secure. Some agents still assume Lloyd’s policies carry weaker financial backing. In fact, the opposite is true. Lloyd’s maintains strong ratings4 from the major agencies,5 reflecting its ability to meet ongoing policy and contractual obligations:
• AM Best: A+ (Superior)
• Fitch: AA- (Very Strong)
• Kroll Bond Rating Agency: AA- (Very Strong)
Lloyd’s strong capital position is demonstrated by the reported market-wide solvency ratio of 206% and a central solvency ratio of 468%—both well above regulatory requirements and strong indicators of financial stability heading into 2026.6
A big part of that stability comes from what Lloyd’s calls its Chain of Security—a three-layer financial protection structure:
1. capital held at the individual syndicate level;
2. members’ funds deposited by syndicate investors; and
3. a Central Fund that serves as a marketplace-wide financial backstop.
The Central Fund’s assets ensure that policyholders claims are paid even in the event of large scale disasters or syndicate failures. Lloyd’s administration also places rigorous compliance demands on its syndicates—London brokers and locally based coverholders—to ensure solvency, integrity and statutory adherence.
To put the scale of the market into perspective, on a typical day more than £100 million (about $134 million) in premiums flows into Lloyd’s, while more than £82 million (about $110 million) is paid out in claims—roughly $76,000 per minute going back to policyholders.7
With a long history, Lloyd’s has handled notable claims, including those from the Titanic disaster in 1912, where claims were fully paid within 30 days. This legacy of prompt and fair claims handling continues to strengthen Lloyd’s reputation today.
Misconception No. 4: Claims are paid from London. This is one of the most common misunderstandings. Sometimes agents picture a claim being sent overseas for approval and payment. In practice, most Lloyd’s claims involving U.S. risks are handled domestically through:
• U.S. claims third-party administrators;
• authorized adjusters;
• managing general agents; and
• U.S.-based trust accounts.
Operationally, a Lloyd’s claim often feels no different than dealing with any other E&S carrier.
Example: A logging contractor in New Hampshire experiences a large liability loss involving property damage. The Lloyd’s-backed primary coverage responds, and the claim is investigated locally by a New Hampshire-based adjuster. Then, defense counsel is appointed locally, and payments are issued through U.S. claims channels. From the insured’s perspective, the process looks and feels like a standard company claim.
Misconception No. 5: Lloyd’s always means a higher premium. Usually, higher premiums are tied to higher-risk exposures, and not the Lloyd’s marketplace itself. Because Lloyd’s syndicates have flexibility in rate and form, sometimes it can structure programs more competitively when:
• coverage needs customization;
• limits exceed admitted capacity; and
• multiple layers are required.
In many cases, Lloyd’s participation stabilizes pricing by introducing additional capital into the placement. For agents dealing with difficult renewals, often Lloyd’s capacity expands options rather than increasing cost.
Example: Consider an older brick mill building in New Jersey or New York with a replacement cost of $15 million that was purchased for $3 million. The owner doesn’t want to pay the premium required to insure the full replacement value, but rather, wants to just protect his investment. From the underwriting perspective, a Lloyd’s syndicate also is reluctant to offer a $15 million limit when the insured’s financial stake is significantly lower: that gap has the potential to create a morale hazard. A capable coverholder can offer a $3 million limit with flat coinsurance by applying what is known as Lloyd’s First Loss Scale. This method allows a lower limit to be purchased, with no traditional coinsurance requirement. The rate is surcharged on a scale taking into account the proportion of the limit purchased versus the replacement cost limit.
The result is a practical solution for both sides. The insured wins from more affordable premium while still protecting the core investment. Lloyd’s underwriters have a positive result because the premium is surcharged for the extra risk—in the event of a loss, a smaller policy limit is far more likely to be fully exhausted than a much larger $15 million limit. The First Loss Scale reflects this higher probability in the final rate.
Under a traditional standard-market policy, carrying limits significantly below the building’s full value could trigger coinsurance penalties or underwriting restrictions. Lloyd’s flexibility allows it to price risk more precisely and structure coverage in ways standard carriers often cannot, forgoing coinsurance clauses, working with custom rating structures, etc.
Unlike many admitted carriers, Lloyd’s syndicates often make underwriting decisions on individual risk merit rather
than broad class rules. That means two similar risks may receive different evaluations depending on how clearly the exposures are presented.
Underwriters rely heavily on the clarity and completeness of the information they receive, and the integrity of the retail agent from whom they receive it. A well-prepared submission not only speeds up quoting, but it also can (materially) improve pricing, terms, limits and the willingness to participate.
A strong submission demonstrates that the insured understands its exposures and manages them responsibly. Think of a Lloyd’s submission less as an application and more as a risk presentation:
Start with a clear risk narrative. Underwriters want to understand the story of the account before they look at the numbers.
Provide complete and current loss information. Loss runs alone are not enough. Underwriters are less concerned about whether a claim occurred than about whether the insured learned from it, and implemented controls.
Document risk controls and safety practices. This can go a long way to making an underwriter feel more comfortable quoting a risk—especially on tough classes of business.
In today’s insurance environment, Lloyd’s participation often makes the difference between placing a risk and losing the account. When understood properly, Lloyd’s isn’t complicated. It’s simply a marketplace of strong capital providers working through trusted underwriting partners to solve risks the standard market can’t always handle.
In short, Lloyd’s isn’t a last resort—it’s a core part of the modern placement tool kit.
DeCotis is president and CEO of DeCotis Specialty Insurance, a wholesale broker and managing general agency serving retail agents across the Eastern Seaboard and Southeast. A former president of the New England Surplus Lines Association, he serves on the Rhode Island Governor’s Insurance Council and industry committees with the Professional Insurance Wholesalers Association and the Wholesale & Specialty Insurance Association. DeCotis Specialty Insurance has operated as a Lloyd’s Coverholder for more than 35 years, supporting more than 800 agency partners with personal and commercial specialty solutions.
1 AM Best, 2025 (tinyurl.com/ysdeptrn)
2 AM Best, 2025 (tinyurl.com/2n9znpd2)
3 Lloyd’s of London (tinyurl.com/3bts2f38)
4 Lloyd’s of London (tinyurl.com/bxvvy6z3)
5 AM Best, 2025 (tinyurl.com/hb4463cf)
6 Lloyd’s of London (tinyurl.com/yep5yxjp)
7 Lloyd’s of London (tinyurl.com/559mba8c)

Dave Kahle President, Kahle Way Sales Systems
In almost all my seminars, I ask this question: “How many of you have too much to do and not enough time in which to do it?” You can guess the answers. Almost every hand goes up. The only ones who don’t raise their hands are the people who are a few months away from retirement, and who are starting to check out.
It doesn’t matter what the job title is: salesperson, customer service representative, manager, CEO or entrepreneur. Geography doesn’t matter either. I have seen the same response in Zimbabwe, Ghana, Mexico, Colombia as I do in the U.S. and Canada.
It is not just your job, it’s not your business, it’s not your industry, and it’s not your country. It is almost everyone and everywhere. It is one of the defining characteristics of the 21st century.
Because of the pace of change, the proliferation of media and the speed of communication technology, almost everyone is overwhelmed, stressed and distracted. Chaos reigns all around us. I like to call it the Age of Turmoil.
All this elevates time management to the top of the list of essential survival habits. Not only do we need to master it, but we also need to get it right. Our ability to function in our chaotic environment depends in a large way on the decisions we make about how we use our time.
And that’s the rub for many people, who view successful time management as jamming more tasks into the course of the day. Their view revolves around the concept of efficiency. That’s what gives rise to the practice of multitasking—working on multiple projects or tasks at the same time in the pursuit of efficiency.
Under this view, if you can jam more tasks into the day, you are good at time management. That is a bit of a shadow accomplishment. Efficiency can help you use your time better, but it is limited. The businesspeople in pursuit of efficiency often find themselves successfully completing that which should not have been done in the first place. The leadership
Our ability to function ... depends in a large way on the decisions we make about how we use our time.
expert, John Maxwell, said: “Efficiency is the foundation for survival. Effectiveness is the foundation of success.” And the management theorist, Peter Drucker, once reflected: “There is nothing so useless as doing efficiently that which should not be done at all.”
A better approach is to focus on effectiveness. Whereas efficiency focuses on accomplishing more, effectiveness focuses on accomplishing that which is more important.
Here’s an example: Let’s say you’ve decided to make your living as a housepainter. You invest in all the latest equipment. The big day comes, and you paint your first house. You’re very proud of the fact that you have been incredibly efficient—it took you 35 hours to paint the house, and most painters would have taken 50 hours. As you sit in your truck feeling pretty good about yourself, you begin to create the invoice, you look at the contract and then back at the house, and a sick feeling crawls through your gut. You realize that you painted the wrong house!
You were incredibly efficient, and horribly ineffective. So, what does it mean to focus on being more effective? The specific applications vary from time to time and situation to situation. And, effectiveness is relative to the other things
you could do. For example, what might be the most effective thing to do on Monday, may not rank that high on Tuesday. However, there are some general guidelines. Effectiveness speaks to the importance of the task. Something is important because it supports your higher values and/or moves you closer to your goals. These two issues can be translated easily into criteria to judge and rank every task. You can express the criteria as questions. So—in sorting through a list of tasks—you ask these two questions of the list:
A full-time, onsite position is available in Chittenango, NY for an experienced Commercial Underwriter. This position focuses on underwriting small commercial property and casualty accounts—primarily BOP and CPP policies—with independent responsibility for risk evaluation, coverage analysis, pricing, and agent communication. The role is suited for an experienced commercial lines professional who’s comfortable owning underwriting decisions.
• Which of these items most supports my core values?
• Which of these items moves me closer to attaining my goals?
The answers to these questions will bubble up to the top the one or two things that are most effective.
As you can see, before you can determine that something is effective, you must have done some prior work. You can’t, for example, determine if some task will bring you closer to your goals if you have no goals.
That’s one of the reasons I recommend a system of creating goals that includes annual goals, monthly increments and weekly and daily priority lists.
• 5+ years of underwriting experience (2+ in commercial lines)
• Sound underwriting judgment and strong analytical skills
• Clear written and verbal communication abilities
• Commitment to underwriting discipline and ongoing professional development
Why Choose Madison Mutual?
• 133 years of American integrity and enterprise
• Resilient through every era of progress
• Committed to serving neighbors first
• Old-fashioned customer service and modern insurance solutions
• Honoring the past while protecting the future through dependable financial security.
Send resume and salary requirements to: mail@mminsco.com.
1256 State Route 5 ♦ PO Box 357 Chittenango, NY 13037 www.mminsco.com
The same is true for your core values. You can’t determine if something supports your core values if you don’t know what they are. Taking some dedicated time to identify that which is most important to you is a valuable use of time. It’s always wise to create a written statement that articulates your core values. Putting it on paper forces you to be specific and implies commitment. Then, it allows you to review it and refine it every few years.
With those two pieces in place, you can move from efficiency to effectiveness, turning chaos into control. Apply them with discipline and you’ll have mastered one of the key success strategies of this turbulent world.
Kahle is one of the world’s leading sales authorities. He’s written 12 books, presented in 47 states and 11 countries, and he has helped enrich tens of thousands of salespeople and transform hundreds of sales organizations with his various programs, such as Menta-Morphosis® Learning System and the Kahle Way® Selling System programs. Sign up for his free weekly Ezine (www.davekahle.com/ezine-subscribe). His book, How to Sell Anything to Anyone Anytime, has been recognized by three international entities as “one of the five best English language business books.” Check out his latest book, The Good Book on Business.
Have a question? Ask PIA at resourcecenter@pia.org.
Q. For risks that do not qualify for the excess line market automatically, I continue to hear somewhat conflicting information about the need for and completeness of declinations in the admitted market. Is there some flexibility that makes this less onerous?
A. The requirements for admitted-market declinations are set by statute and regulation and are reflected in the Excess Line Association of New York Part C–Affidavit By Producing Broker. Responsibility for obtaining the required declinations rests with both the producing broker and the excess line broker, and declinations and affidavits still must be filed with ELANY.
That said, New York State Insurance Law Section 2118 has reduced the reporting burden by eliminating several declination-related data elements that previously had to be disclosed on the Part A and Part C affidavits. The following information is no longer required to be reported for declinations:
• affiliation of the representative (company, employee, agent or other);
• name of representative declining the risk; and
• the reason for the declination, including capacity issues, specific underwriting reasons or other explanations.
While the fundamental declination requirement remains in place, these changes provide some meaningful relief by simplifying the information that must be collected and reported.
For more information, PIA Northeast members can access The wholesale option (QS31188), and Excess line essentials (QS31405) in the PIA QuickSource library.—Lachut
Q. What are the cancellation rules for excess line policies? Can an excess line insurer cancel a policy with a short-rate penalty?
A. New York State Insurance Law Section 3426 governing the cancellation of commercial insurance policies does not apply to excess line insurers.
New York State Insurance Law Section 3425 governing the cancellation of personal lines policies does apply to excess line insurers. However, neither Section 3425 or Section 3426 are applicable to cancellations by the insured, which is when a short-rate penalty would occur.
The terms for cancellation of a commercial- or a personal-lines excess line policy are found in the policy provisions, so if the policy states the insurer can cancel with a short-rate penalty, it is permitted to do so. Authorized insurers would need to include short-rate penalties in their rate filings with the New York State Department of Financial Services.—Ritchie
Q. A client is a tenant insured on an ISO commercial general liability policy. The tenant’s lamp started a fire that caused significant damage to the landlord’s building. The two corporations (i.e., the tenant and the landlord) are owned by the same people. The landlord’s insurer has paid $170,000 and it is subrogating against the tenant, who has $100,000 fire legal liability coverage. Will the tenant’s insurer pay the excess $70,000 under the property damage liability limit under his policy?
A. To answer your question: The building your client rents or occupies is excluded property. However, an exception to the exclusion restores some limited fire legal liability coverage represented by the Damage to Premises Rented to You limit. No coverage beyond this limit would be available for this loss under the CGL policy.
However, a better solution is available. Since the two corporations, landlord and tenant, are owned by the same individuals, have the landlord agree to waive rights against the tenant. Under standard ISO policies (CP 00 90), the landlord can do so without violating its duties under the policy. See Conditions I. Transfer of Rights of Recovery Against Others to Us. It states the insured may waive its rights against another
party in writing, after a loss, where the other party is the insured’s tenant. If no subrogation occurs, you will not have an issue with the adequacy of the tenant’s limits.—Lachut
Q. An employee of our commercial auto policyholder had an accident in his personal vehicle. Our policyholder has two policies through two different companies. Company A’s policy is rated based on Symbol 1— making any auto (including hired and non-owned) a covered auto. The second policy, written by Company B, provides liability coverage for non-owned and hired vehicles only. We would like the claim to be paid by Company B, because Com-
no, the loss should be split, one-half with Company A and one-half with Company B. How should this claim be apportioned?
A. The commercial automobile policy specifies that when both it and any other policy covers a loss on the same basis—either primary or excess—the commercial automobile policy will pay only its share. The share is determined by the proportion that the limits of the policy in question bears to any other policy or policies covering the loss on the same basis (primary or excess).
Thus, Company B’s analysis would be correct but only if both companies provided the same limits. Both companies do provide coverage for this loss on an excess basis, and they will be likely to reach an agreement to pay in propor
Your preference in the matter (that Company B pay the entire loss) is not likely to determine the outcome. The loss will be settled according to the policy provisions or, if the “other insurance” provisions of the two policies are in conflict, by some dispute-resolution mechanism.—Lachut
Massachusetts surplus lines fees, maximums
Q. What is the law on the maximum surplus lines fee that can be charged in Massachusetts?
A. The former law in Massachusetts, which set this limit by statute was repealed; and now the state allows “reasonable and customary” fees (see Bulletin 2013-09).
Many of our members report that they see fees ranging from $50 to over $100.—Lachut
OFFICERS
President
Jason E. Bartow, AAI, CPIA, TRA Bartow Insurance Agency & Jebb Brokerage Inc. Deer Park, NY
President-elect
Michael A. Loguercio Jr. Belfor Property Restoration Middle Island, NY
First Vice President
Jorge Hernandez North Franklin Brokerage Inc. Hempstead, NY
Vice President
Eric Cohen
Benefit Quest Inc./Eric Cohen Insurance New York, NY
Treasurer Ed Chadwick Jencap Specialty Insurance Services Buffalo, NY
Secretary
Justin Fries, CIC, CPCU, CPIA Garber Atlas Fries & Associates Inc. Oceanside, NY
Immediate Past President
Richard Andrews, LUTCF Andrews Agency Inc. Ithaca, NY
NATIONAL DIRECTOR
Michael J. Skeele, CIC, CPIA Skeele Agency Inc. DeRuyter, NY
DIRECTORS
Dina Bruno, CPIA Trucordia Long Beach, NY
Peter Buccinna XS Brokers Quincy, MA
Marshall Glass, CPIA Ironpeak Astoria, NY
Leslie C. Rogoff Madison Avenue Brokerage Corp. New York, NY
Richard Signorelli AZBY Brokerage Inc. Bronx, NY
NY-YIP REPRESENTATIVE
Peter Conte, CPIA, MSRE Honig Conte Porrino Insurance Agency Inc. New York, NY
ACTIVE PAST PRESIDENTS
David Dickson Fairport, NY
Jamie A. Ferris, CIC, CRM, AAI, CPIA P.W. Wood & Son Inc. Ithaca, NY
Lynne R. Frank, CPCU Williamsville, NY
Jeffrey H. Greenfield NGL Group LLC Lynbrook, NY
Fred Holender, CLU, CPCU, ChFC, MSFS Lawley LLC Buffalo, NY
John C. Parsons II, CIC, AAI, CPIA, NcSA Parsons & Associates Inc. Syracuse, NY
Gene L. Sandy, CIC Highstreet Insurance Partners Millennium Alliance Group LLC Melville, NY
Richard A. Savino, CIC, CPIA, TRA Broadfield Group LLC Trucordia Warwick, NY
Gary Slavin, CIC, CLTC, LUTCF Massapequa, NY
John Tomassi, CPCU Open Coast Surety Agency LLC New York, NY
Matthew Davoult AFCO Direct Lake Forest, IL
Jennifer P. DeCristofaro Lancer Management Co. Inc. Long Beach, NY
Jeffrey Dende, CIC, CPIA, CRM P.W. Wood & Son Inc. Ithaca, NY
Leslie Driscoll Tronilo-Driscoll Insurance Agency Ozone Park, NY
Khaleedah Francis Sedgwick Claims Mahwah, NJ
Natalie Golubski
Jencap Specialty Insurance Services Buffalo, NY
Sean Grant Jimcor Agencies Montvale, NJ
Christina Kager Piper Insurance Agency Inc. Painted Post, NY
Scott Richards Hilltop Strategies Huntington Station, NY
Frances A. Scott
F.A. Scott Insurance Agency Goshen, NY
Ian Sterling, CLCS Sterling Risk Woodbury, NY
Derek Stork, CIC
Stork Insurance Agency Penn Yan, NY
Shannon van Doorn Lawley LLC Buffalo, NY
pia@pia.org
+ Print design.print@pia.org
education@pia.org
& Industry Affairs govaffairs@pia.org Industry Resource Center resourcecenter@pia.org
Services memberservices@pia.org
publications@pia.org
Insurance Professionals yip@pia.org
11 AFCO Direct
Increase
22 Berkshire Hathaway GUARD Insurance
32 ELANY
10 Empire State Brokerage Services
12 Friedlander Group
23 Hamond Safety Management
15 JENCAP
2 Lovell Safety Management
30 Madison Mutual Insurance Co.
7 Omaha National
24 Parsons & Associates
16-17 PIA Annual Conference
28 PIA E&O Insurance
33 PIA Members’ Choice
14 PIA NumberONE Comp
BC United Risk
8 Venbrook Group
For more information about an advertiser, email ads@pia.org, or call (800) 424-4244 .

Today driving distances on tour are over 320 yards.

In 1985 driving distances averaged 256 yards.

Luke Donald knows the game has evolved. As a winning Ryder Cup Captain, he chooses his players carefully.
At United Risk, we unite elite capability backed by proven results. A magnet for apex underwriting professionals committed to free enterprise and success.