Opportunity Colombia
Your Impact Report, Spring 2026
Opportunity International began our work in Colombia in 1972. Our proven three-pronged interventions of tailored training, financial resources, and support increase incomes, create and sustain jobs, and provide affordable quality education for children and youth. Opportunity’s programs start and end with the client in mind, with interventions tailored to the specific needs of the local demographic and geography As you’ll see below, we’ve exceeded, in some cases, exponentially, the targets we set for 2025 and we are well on our way to a productive 2026. Thanks to your help, over the last three years we’ve impacted over 136,000 people in Colombia (triple our original goal!) and we’re not stopping.
2025 IMPACT in Colombia
EDUCATION
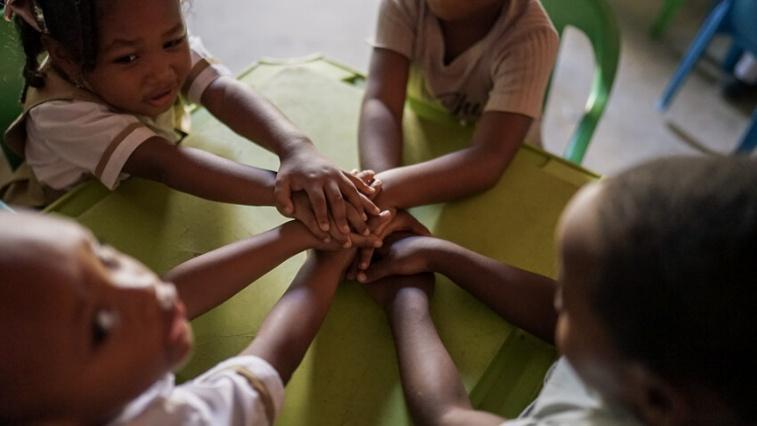
By the end of 2025, 86 schools were participating in EduQuality, impacting 17,200 children (the number decreased from 111 as some schools finished the three-year program); 111 loans have been disbursed at a value of $213,498 impacting 465 children. Between 2023-2025 we did not meet our projected target for education loans due to the economic climate in Colombia. Our microenterprise partnerships have grown and strengthened; we are working with financial institutions on how to support the specific needs of schools, teachers, and parents.
SAVINGS GROUPS
Savings groups provide financially excluded populations with vital access to savings and loans. Through savings groups, members meet and save regularly and then borrow from that pool of savings, paying interest. Generally, at the end of each year, the groups “share-out” their funds such that savers earn interest.
Savings groups’ members are self-selected, and group average between 11-19 members. Each group experiences two eight-month cycles, guided by internal rules and an administrative committee. In Colombia, the average loan size range is US$40-$46.
Results include:
• Creation and strengthening of savings habits
• Creation of strong community networks
• Increased resiliency
• Improved financial literacy (savings and loans)
• Training in other topics as identified by each group (e.g., conflict resolution, leadership)
In 2025, 472 savings groups were created in Bolivar and Atlantico (exceeding goal of 465), with 5,944 active participants—72% women and 9% migrants—as of December 2025. Financial institution partners Aavance, Banco Union, and Crezcamos provided workshops and product socialization sessions encouraging use of digital wallets, group savings accounts, and certificates of deposit.
In 2026, our goal is to establish 320 savings groups; as of FY26Q1 we have 73 active savings groups with 915 clients and $27,300 in active loans. These groups include 557 victims of conflict and impact 1,300 children.
Proud Perseverance
Denis lives with her husband, father, and four sons in the Nueva Jerusalén de Henequén community. For years, saving money felt impossible. "I could buy as many piggy banks as I wanted," she recalls, "but whenever I saved something, I ended up spending it." When her family was hit by unemployment, Denis decided to act. Seeing the women in her neighborhood struggle with their hair, she started selling natural hair treatments. She later learned to make her own products.
Her life took a new direction when she joined the Saving Opportunities savings group. At first, it wasn’t easy. Trusting others and working together took time.
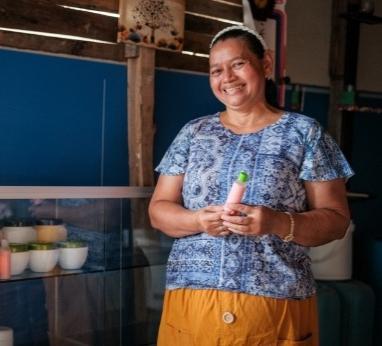
However, the financial education sessions helped her, and her neighbors understand budgeting, cost tracking, and teamwork. Today, Denis proudly says that she has learned the discipline of saving and gained the confidence to call herself an entrepreneur.
Through the group’s collective activities, she contributes to weekly initiatives that boost savings and strengthen friendships and community unity. "Now," she says, "if I need something, I don't think about borrowing from a moneylender; I go to my group." For Denis, the program represents much more than financial growth. It symbolizes family unity, restored confidence, and the joy of realizing that change begins with faith and perseverance.
Innovation
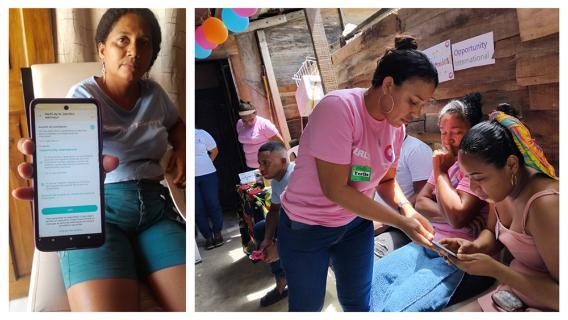
Digital inclusion, especially for our clients, is important. Being able to innovate with apps such as DreamSave an app that digitizes the accounting/attendance work of savings groups allowed us to realize that our clients, even with an educational level below the national average, can quickly learn how to use digital tools.
As of the end of December, 72 local savings and credit groups are registered on the DreamSave platform. Of this total, 65 groups are active and seven groups have transitioned to the graduation or self-management phase, reflecting progress in the consolidation and sustainability of the model.
This digital technology allows us to “speak” with our clients, and improves the time spent in savings groups meetings; sessions that previously could extend to 50 minutes were reduced to 30, allowing more time for the groups to incorporate social connection and engagement. Group record keepers reported that DreamSave allowed them to significantly reduce errors when performing calculations, enabling greater transparency and increased confidence in the data.
MICROENTERPRISE
In 2025, in partnership with five financial institutions, we catalyzed $12.6 million in loans for local entrepreneurs, 240% of our target. That represents 7,926 microenterprise loans enabling individuals to have income-generating businesses. We accomplished that with a philanthropic investment of just over $200,000, demonstrating an astonishing leverage of 62X.
GRADUATION
Known locally as Pathways to Opportunities, the Ultra-Poverty Graduation program in Colombia requires robust human resources including staff coaches who provide training and support in basic finance, family and social wellness, saving, business building, and more
Cohort Two, Cartagena
In the past year for our second cohort of 500 households:
• 4,472 business and personal coaching visits were conducted for families on the entrepreneurial track.
• New community initiatives are participant-driven, with 86% of clients participated in their design and implementations.
• Clients learned basic financial literacy, family wellness, and business promotion.
• Among the 500 families that will graduate in the spring of 2026, the midpoint survey showed that 56% of participants had already moved above the extreme poverty line.
• Within the cohort, 35 savings groups with 538 clients have accrued $44,000 in savings.
We learned from our inaugural Graduation cohort that adding post-Graduation support provides a continuing sense of community, additional stability, accountability, and learning opportunities for participants. While not included in our baseline budget, we have witnessed that this incremental work demonstrates impact and outcomes.
Once our second Graduation cohort graduates in May 2026, a two-member professional team will follow up with the graduates for the next 15 months to support them as they venture out on their own either managing their own businesses or working in various trades and industries and to collect additional data. Starting in June 2026, this additional guidance will strengthen newly earned financial stability and self-sufficiency.
Cohort Three, Barranquilla
In Barranquilla, extreme economic poverty remains a critical challenge. The extreme poverty line for Barranquilla and its metropolitan area was Colombian Pesos COP 239,773 (US$ 65) per capita per month, with women disproportionately affected (34.1%). Food insecurity indicators are particularly severe:
• 66% of households report not consuming three meals per day
• 91% report reduced capacity to purchase durable goods
• 85% report limited or no savings capacity
To launch our third Graduation cohort our first in Barranquilla in late 2025 we hired five livelihood specialists, five psychosocial professionals, and a project coordinator. An experienced project manager who drove implementation of two previous Graduation cohorts in Cartagena leads the project.
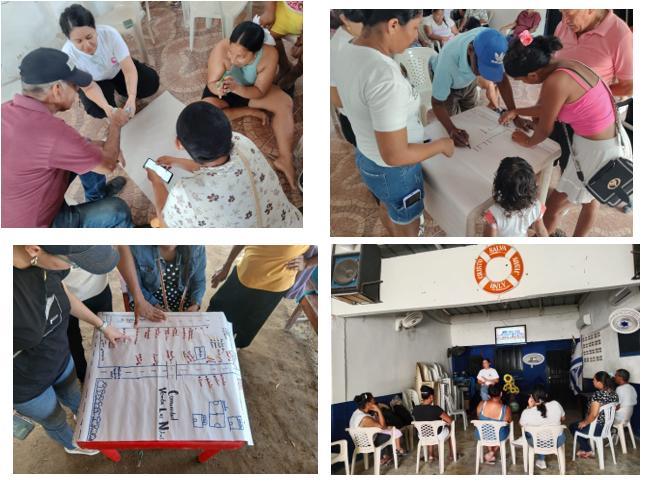
Bringing together diverse stakeholders who understand the needs and challenges in their local community is foundational to the success of the Graduation program in Colombia. We convened 15 strategic partners from government, civil society, academia, and the private sector. Thanks to that meeting, we identified clear coordination mechanisms and complementary services. Over one hundred community leaders also have emerged as essential allies in facilitating access and trust with participating households.
Graduation program outreach sessions with local leaders and stakeholders; staff interview prospective families using a standardized evaluation tool and metrics
2026: EXCEPTIONAL START
*on track; first disbursement spring 2026
Our brothers and sisters in Colombia work hard every day, grabbing onto opportunities to build a sustainable life for their families. Thank you for making this transformational work possible. Our clients aren’t stopping and neither are we; by September 2026, we need to secure an additional $350,000 to reach more children in quality, affordable schools and to enable people to participate in savings groups, one of the first steps families take in the path out of poverty. Thanks for walking with us.
"I don’t just make garments. I’m making my future. Every stitch tells a story of overcoming. When an opportunity arrives, a life changes. Today I can provide for my family with what I do with my own hands. Thank you.”
- A Graduation participant shares her hope, optimism, and gratitude