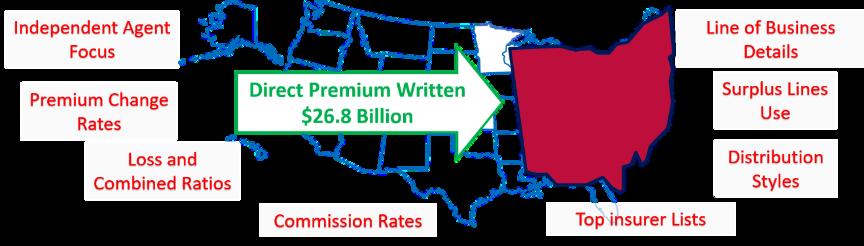
Source: A M Best Company
This issue of The Ohio Agent takes a deeper look at one of the topics shaping nearly every conversation between agents, carriers, and clients today: the Ohio property and casualty insurance marketplace
At OIA, we believe independent agents make better decisions when they have access to reliable data and meaningful context That is why this edition of our magazine, and July’s IA Connect Newsletter, is dedicated to examining the trends, challenges, and opportunities influencing our industry. Using data from Paul Buse with Real Insurance Solutions Consulting and A.M. Best Company, we explore what is happening across Ohio’s P&C market and how those developments impact independent agencies.
The report highlights a marketplace that continues to evolve Ohio’s property and casualty market generated $26 9 billion in direct written premium in 2025, ranking 11 nationally, while premium growth, loss ratios, independent agent market share, commission trends, and surplus lines utilization all tell important parts of the story The data also provides insight into the lines of business that matter most to independent agents, from personal auto and homeowners coverage to commercial and umbrella risks th
As you read through this issue, our goal is not simply to present numbers We want to help you understand what those numbers mean for your agency, your clients, and the future of the independent agency system Whether you are focused on growth, profitability, carrier relationships, or navigating market changes, we hope these insights help you approach the second half of the year with greater clarity and confidence.
This magazine is just the beginning of our marketplace coverage. We’ll continue to break down key findings, trends, and takeaways in IA Connect, providing additional analysis and practical insights for OIA members. Be sure you’re subscribed to OIA’s email communications so you don’t miss future marketplace updates, educational resources, and member-exclusive content.
Written by: Jodie Shaw, Director of Business Development
OIA is excited to welcome Joe Fullenkamp to the team as Chief Executive Officer designate.
Officially joining the team on July 1 , his arrival marks an exciting new chapter for OIA and the members we serve across Ohio st
Fullenkamp brings nearly 30 years of experience in the insurance industry, with a background spanning both personal and commercial lines Most recently serving in leadership roles at Encova Insurance, he has built strong relationships with both agencies and carriers throughout his career That perspective will serve him well as he steps into this role, with a clear understanding of the challenges and opportunities facing independent agents today
“Joe’s extensive leadership in the insurance industry and his vision for the independent agency system make him the strategic and operational leader Ohio agents need,” said Andy Stephey, OIA Board Chair “We are excited to welcome a leader with such strong experience working within carriers and understanding the evolving needs of agents in Ohio and beyond ”
This transition comes at a time of continued momentum for OIA Under the leadership of current CEO Jeff Smith, the association has strengthened its role as a trusted partner to member agencies through expanded business solutions, advocacy efforts, and programs designed to help agencies grow and adapt in a changing market
“I’m incredibly excited for the future of OIA under Joe’s leadership,” said Jeff Smith. “His background and thought leadership will bring tremendous value to our members and the broader insurance community ”
To ensure continuity and a thoughtful transition, Fullenkamp will work closely alongside Smith through 2027 This planned overlap reflects OIA’s commitment to strong leadership perpetuation and long-term stability, positioning the association to continue delivering value to members without disruption.
As he steps into the role, Fullenkamp will lead OIA’s continued focus on advocacy, education, and business solutions while helping to shape new opportunities that support independent agencies across the state. His leadership represents an exciting next chapter for OIA and reinforces our commitment to protecting and advancing the independent agency system in Ohio
Joe is quickly immersing himself in the work of supporting Ohio’s IAs, building relationships, and listening closely to members.
Please feel free to reach out and introduce yourself to Joe in person at any of our upcoming events, by phone at (614) 552-3064, or by email at joe@ohioinsuranceagents.com.
September 29-30 | The Exchange at Bridge Park
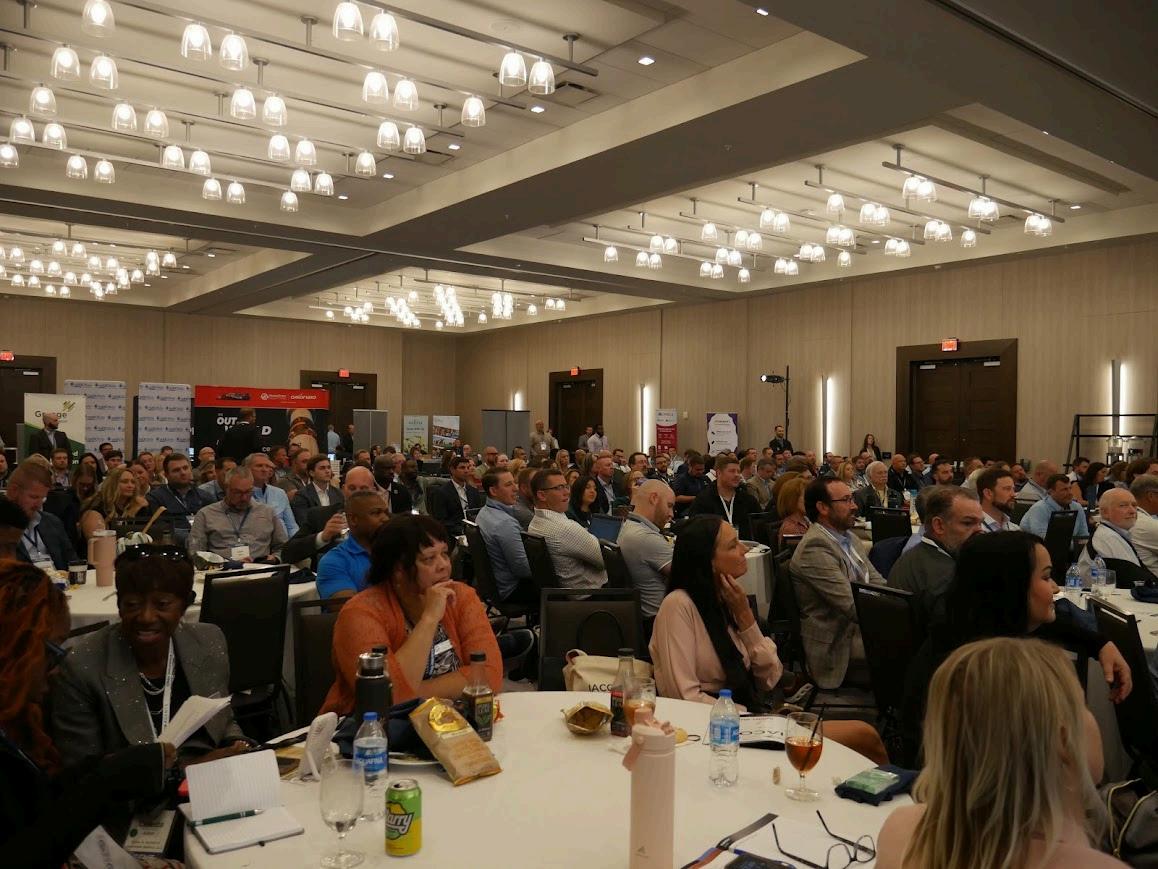
Join us at IACON: Insuring Tomorrow for dynamic keynote presentations, relevant breakout sessions, and valuable networking opportunities. Topics include AI applications for agencies, soft market success strategies, and other timely industry trends shaping the future.
Brandon Smith
Liberty Mutual Agent for The Future Award Recipient
TEDx Speaker
THANK
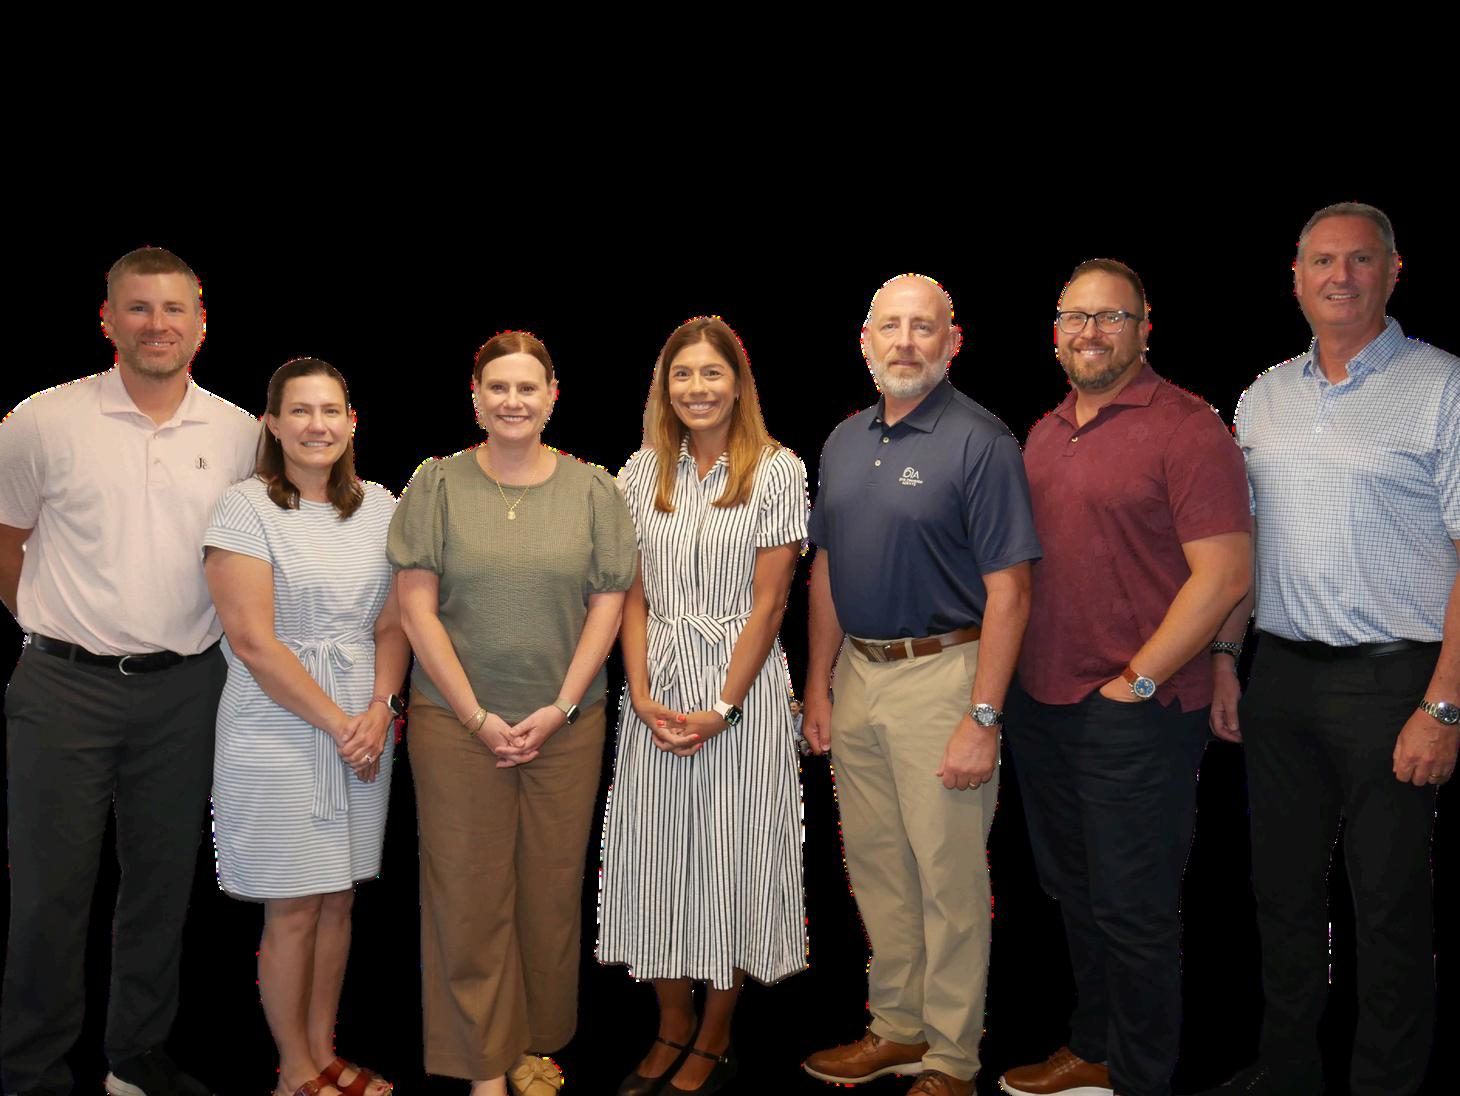

The Ohio Insurance Agents Advocacy Committee (OIA PAC) plays a vital role in advocating for independent insurance agents by influencing legislation, regulations, and industry policies The committee strengthens agents' political influence by supporting pro-business candidates and maintaining a competitive insurance marketplace Key responsibilities include shaping OIA’s advocacy agenda, analyzing legislative and regulatory issues, guiding PAC contributions, and increasing fundraising efforts
Members include: Jeff Sargeant, Diane Keil-Hipp, Meghan Griffith Ragozzino, Patrick Bacon, Nick Bertke, Bill Bishop, Cameron Caryer, Janie Geis, Eric Harmon, Dale Kaprosy, Michael Keenan, Aaron McElwain, Talbott Moon, Nick Roach, and Mark Willis
The Carrier Relations Committee works to strengthen the relationship between independent agents and insurance carriers Its key responsibilities include identifying opportunities to enhance company relationships, monitoring changes that impact agent-carrier dynamics, providing input on industry issues, conducting research on carrier concerns, engaging with high-level carrier representatives, and analyzing survey results to improve partnerships
Members include: Bill Brooker, Greg Carr, John Ferneding, Scott Krebs, Brandon Morgart, Rob Strachan, Shelley Taylor, Jay Wenger
The Finance and Budget Committee ensures the financial health and stability of the organization by overseeing investments, budgets, audits, and financial policies It acts as a steward of financial resources, maintaining adequate funding for member services and long-term sustainability This committee reviews financial statements, investment portfolios, tax returns, and corporate insurance policies, as well as assessing budget alignment with strategic objectives and recommending necessary adjustments to the Board of Directors
Members include: Colleen Heister-Miles, Justin Buren, Kelley Culley, Meghan Griffith Ragozzino, Eric Stolly, Kimberly Hilvers, and Andy Tomlinson
The Governance Committee ensures strong leadership and effective governance by identifying, developing, and supporting future leaders within OIA It maintains a transparent leadership selection process based on competencies and strategic alignment Key responsibilities include recruiting and nominating board candidates, overseeing leadership development, reviewing bylaws and policies, addressing ethical concerns, and selecting award winners The committee also evaluates board positions and governance structures to support OIA’s mission and success Members include: Steve Brown, Brent Phelan, Perk Reichley, Tom Sarno, and Matt Simon
New in 2025, the OIA Innovation Committee will focus on enhancing industry knowledge and business opportunities for independent agents by identifying and evaluating innovative solutions The committee will gather insights on industry trends, analyze potential solutions, explore investment opportunities to strengthen the independent agency system, and identify diverse business prospects for members and OIA
Members include: Adam Anspach, Chris Pipes, Amy Amstutz, Tyler Copeland, Tiffany Morgan, Brad Kernan, Brandon Rapp, Michael Sarno, and Brian Ogle
The Next Gen Agents Advisory Council serves as a voice for emerging professionals in the industry, providing insights to enhance OIA’s resources and initiatives It fosters member engagement, networking, and leadership development while advising the Board and staff on the needs of the next generation of insurance professionals Key goals include identifying career development opportunities, expanding member resources, and cultivating future industry leaders
Members include: Amanda Phelan, Adam Augspurger, Matt DeVries, Kendra Garrett, MacGregor Howey, Rick Jackson, Logan Kirk, Cassie Maddux, Brennan Madison, Mary Modene-Salahat, Julie Schatz, and Bethany Thompson
Written by: Colleen Elliott, OIA Marketing & Communications Manager
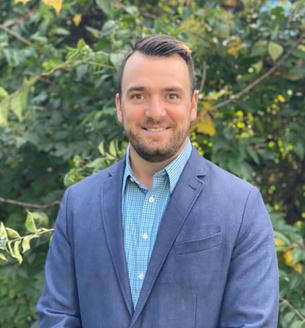
OIA thrives because of the strength and passion of its volunteer leaders, and that impact is only strengthened by individuals who bring fresh perspective and a commitment to growth. Some of the most impactful leaders in the independent agency system are those who chose this industry for the opportunities it provides – and that’s exactly the path Cameron Caryer took We’re excited to welcome him to the OIA Board of Directors, where his focus on relationships, collaboration, and advocacy will help move the association and the industry forward
Cameron began his professional career in corporate sales, where he developed strong relationshipbuilding skills After a few years, he was approached by his wife’s uncle, a former owner of Frost Insurance, about joining the agency He was immediately drawn in by the potential of the industry and the opportunity to shape his own career path and destiny At the time, his corporate role involved a lot of travel, and his family was looking to settle in the area, making the transition a natural fit His background in corporate sales, along with a strong sales and marketing education from the University of Toledo, prepared him well for his shift and helped him build meaningful client relationships early on
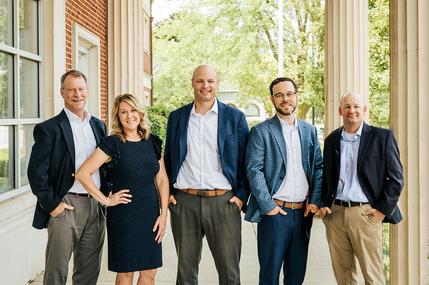
After about five years with the agency, Cameron began buying in as an owner Today, Frost Insurance has five owners. While there are no familial ties between them, the agency has maintained the close, collaborative culture of a family-owned business They focus on bringing in forward thinking individuals who are motivated to grow and drive change, which ultimately lays the foundation and encourages the rest of their staff to want to make progress and not just stick to the status quo
Cameron credits much of his own growth at Frost to their in-depth sales training Starting in personal lines gave him the runway to truly learn about the industry and coverage details before moving into commercial lines
Frost’s company trainings covered not only insurance knowledge but also communicated the value an independent agent provides to their clients, which was invaluable to his development
Before joining the OIA Board of Directors, Cameron was involved with OIA’s advocacy and legislative efforts In 2019, he received Westfield’s scholarship to attend the Legislative Conference in Washington D.C., which he found to be extremely beneficial. The experience allowed him to engage in meaningful conversations and see firsthand how agents are represented at the national level
As the newest Board member, Cameron looks forward to continuing these important conversations that support agents and strengthen the independent agency system He’s passionate about connecting agents, sharing ideas, supporting the IA community, and advocating for its future
Outside of work, Cameron spends most of his time with his wife, cheering his four daughters on at their various sporting events He also enjoys golfing when his schedule allows Additionally, Cameron is active in his church community, where he serves on their board and plays drums in the church band.
Whether supporting his daughters’ teams or advising clients on risk, Cameron has demonstrated his strong commitment to strengthening his local community, the IA community, and the OIA as a whole
Written by: Colleen Elliott, OIA Marketing & Communications Manager
Independent agents are at the core of OIA, but our work is strengthened by the support of dedicated industry partners Their support, from every corner of the industry, helps us enhance the IA system and serve our members.
The newest member of the OIA Foundation Board, Jessica Zinsmeister, was destined to work in insurance “The Cincinnati Insurance Company’s building was the biggest building in my hometown I always knew I would work there someday, I just didn’t know what they did ”
Jessica has been with Cincinnati Insurance Company for almost 20 years and has steered her career through underwriting, management, and now leading their Customer Care Center Like many others in the IA space, she was immediately drawn in by the organization’s connection to their community, the conviction they have for their clients, and the agent advocacy.
The partnership between OIA and the Cincinnati Insurance Company is how Jessica became involved in this community, and she finds that there is perfect alignment between her professional background and the mission of the OIA Foundation: keeping agencies independent, advocating for the future, and providing resources and education to strengthen agents
Insurance is a very relationship-driven industry, and Jessica thrives in that environment She describes herself as a social butterfly and credits both personal and professional connections with shaping her Throughout her career, building relationships and partnerships has given her valuable insight and a strong network to learn from and rely on.
As a self-proclaimed nerd, Jessica has a passion for learning and is most excited to help agents continue developing through the opportunities the OIA Foundation offers Every day, she speaks with newly appointed agents who are looking for guidance and resources, and she values that OIA not only offers a wide range of educational resources, but also helps agents take advantage of these tools through scholarships
Outside of work, Jessica is embracing her newly empty-nester lifestyle She married her high school sweetheart and has two grown children She and her husband are working their way through all the National Parks, starting a garden, and spending time with her pride and joy, Archie the English Bulldog
Jessica is a lifelong advocate of education and insurance, making her role on the Foundation Board a natural fit. She is excited for the opportunity to become more involved with OIA and support agents as they grow and strengthen the independent agency system
By: Jarod Steed, Business Planning & Valuations Analyst
Written by: Jarod Steed, OIA Business Planning & Valuations Analyst
Independent agents are essential household and business risk advisors, and yet they are extremely underutilized in the private passenger auto (PPA) space Only 40% of Ohioans place their PPA premiums through an IA This statistic leads to concerns for the 60% who go a different route: do they truly understand the intricacies of their coverage and the type of provider they are using?
Independent agents are the best risk advisors an Ohio citizen can find They are local, reachable, and knowledgeable, and yet they have historically done the least business, percentagewise, with the most common risk facing Ohioans It will take an industry-wide effort to increase the independent agent's market share of PPA
Of Ohio’s 2025 property and casualty insurance marketplace, Private Passenger Auto (PPA), or personal auto insurance, is the largest line of business (LOB) Across all LOB in Ohio, $26 9B of premium is written; PPA accounts for $9 26B Of this $9 26B, independent agents write just $3 75B (40%) Captive agents write $3 34B, and $2 17B goes direct
PPA has been very profitable historically in Ohio and across the country 2025 saw an adjusted loss ratio of 62% for PPA with the five-year average at a mere 67% The dollars from this profitability often get funneled back into advertising, which is why many consumers are familiar with mascots like Jake from State Farm, the Gecko, Flo, and Limu the Emu (and Doug) Progressive, for example, spent a record-breaking $3 5B on advertising in 2024, when most of their competition was struggling
The majority of these marketing messages focus on price-based storytelling, which shapes the consumer's thought process and can hurt an IA's coverage-based approach
The result of this money being spent on pricebased insurance advertising: consumers gravitate towards direct insurers, leaving independent agents with only a fraction of the market. Meanwhile, independent agents dominate other major lines of business, such as commercial auto (90%) and commercial multi-peril (91%) In fact, the next smallest penetration rate for independent agents is homeowners multi-peril, which is at a 58% penetration rate. It’s clear that the independent agents dominate in more complex lines The idea that PPA business is just a pricebased commodity is something the industry must collectively educate against if IAs are to see their market share increase Instead, the industry needs to educate the consumer about the value of the right coverage and the value of choice in PPA
Another factor that contributes to agents' low penetration rate in PPA is the fact that Ohio has the 49th lowest premium per capita out of 51 for personal lines across the US states and territories. So not only are agents fighting an uphill battle against consumers’ price-driven mindset, but when independent agents do win in PPA, they must sell more policies than agents in other states to make the same amount of commission
This low premium per capita is largely due to the rate environment in Ohio Ohio is well-regulated, and our weather is, simply, insurance friendly
The past half decade has been turbulent in our industry, but the market in PPA has softened One piece of evidence of the softening market is 2025’s average premium increase by 2%, versus the 7% it has been averaging in the last five years. Of the major LOB, PPA had the smallest premium increase in 2025 This deceleration in premium increase signals that carriers in Ohio are satisfied with where their rates are for PPA Carriers, especially the independent agent-friendly ones, need to continue to figure out how they can help their agents get PPA rates that are competitive with those of Progressive, State Farm, and GEICO, particularly as consumer sensitivity to premium has intensified
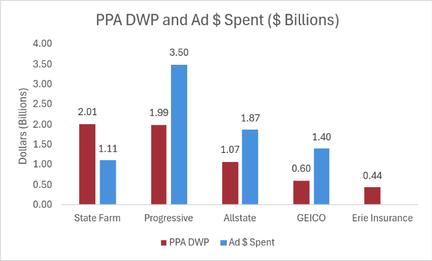
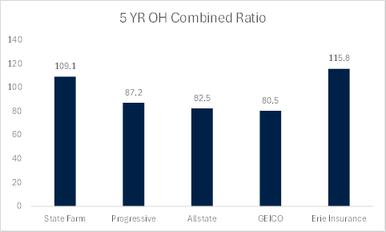
Figures 1 and 2 (show in the bottom left) summarize performance for the top five PPA carriers in Ohio
Of this group, Erie Insurance stands out as the only group that prefers the IA distribution model, showing their heavy investment in independent agents However, their performance in the PPA market has been poor compared to the competition
Erie’s struggle to compete reflects a common struggle of carriers that focus on the IA channel: they can’t compete pricewise against the rest of the top four carriers Many agents are appointed with Progressive as well, and agents constantly say it’s hard to beat their prices. Progressive, Allstate, and Geico’s five-year combined ratios have beaten carriers such as Travelers, Ohio Mutual, Western Reserve, Encova, Westfield, Auto-Owners, Cincinnati, Grange, and more
The carriers being beaten by nationals are many of the leaders in Ohio’s independent agencies. If PPA market share for IAs is to increase, then the IA-forward, Ohio-domiciled carriers, must help their agents by increasing the competitiveness of their PPA offerings in Ohio This all starts with achieving better combined ratios than the nationals.
Looking ahead to 2026, there are two types of factors affecting independent agents focused on writing PPA: controllable and uncontrollable. Starting with factors they cannot control, including macro-economic trends and weather
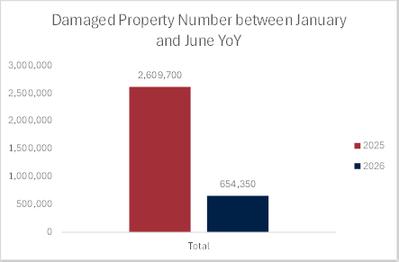
It looks like 2026 so far is on pace to be another insurance friendly weather year. Halfway through the year, the number of damaged properties in Ohio is way down from 2025 The first half of 2025 is when Ohio suffered much tornado activity, and the first half of 2026 has been relatively calm, comparatively. It looks like Ohio insurers should find another profitable year in 2026; however, it is the weather after all
Inflation is another uncontrollable factor that impacts the PPA market Inflation has picked up to 4.2% from May 2025-May 2026, versus being at 3.8% for the prior year's period. This is a highlevel indicator that the cost of auto claims will remain at a similar or increasing severity as the amount of technology and complexity of repairs continues to be on the rise, as well The big PPA insurers have proven their profitability in Ohio when the weather is good and even amidst inflation Because of this, we expect agents' penetration to remain similar in 2026, unless agents and their carrier partners can invest more dollars into flipping the PPA script from a pricebased to a coverage-based decision for consumers.
The mindset shift from price-based to coveragebased consumer decisions is the most influential factor within independent agents' control When a client is fixed on price, they are hard to convince otherwise In this situation, an agent should expand the conversation from just PPA to bundling and/or an umbrella policy. Introducing these policies and communicating their value may help your carrier solutions be more competitive, rather than just quoting a monoline auto policy Agents need to lean into educating their clients on the importance of quality coverage in PPA
Ultimately, increasing independent agent market share in personal auto will not happen by pretending price does not matter It will happen when agents, carriers, and the broader industry help consumers understand what price does and does not tell them A cheap policy may satisfy the legal requirement, but it may not adequately protect a household from the financial consequences of a serious accident
Independent agents are uniquely positioned to change that conversation because they can explain coverage, compare options, identify gaps, and connect auto insurance to the broader protection needs of the client If the independent agency channel wants to win more PPA business, the path forward is not just sharper pricing; it is clearer education, stronger carrier support, and a consistent message that the right coverage matters most when the claim is no longer hypothetical
As part of your membership with OIA, you gain access to annual marketplace data as shown here For the full copy of the 2026 Ohio Marketplace Summary, please contact Jeanie Giesler, OIA Resource Center Advisor, at jeanie@ohioinsuranceagents com
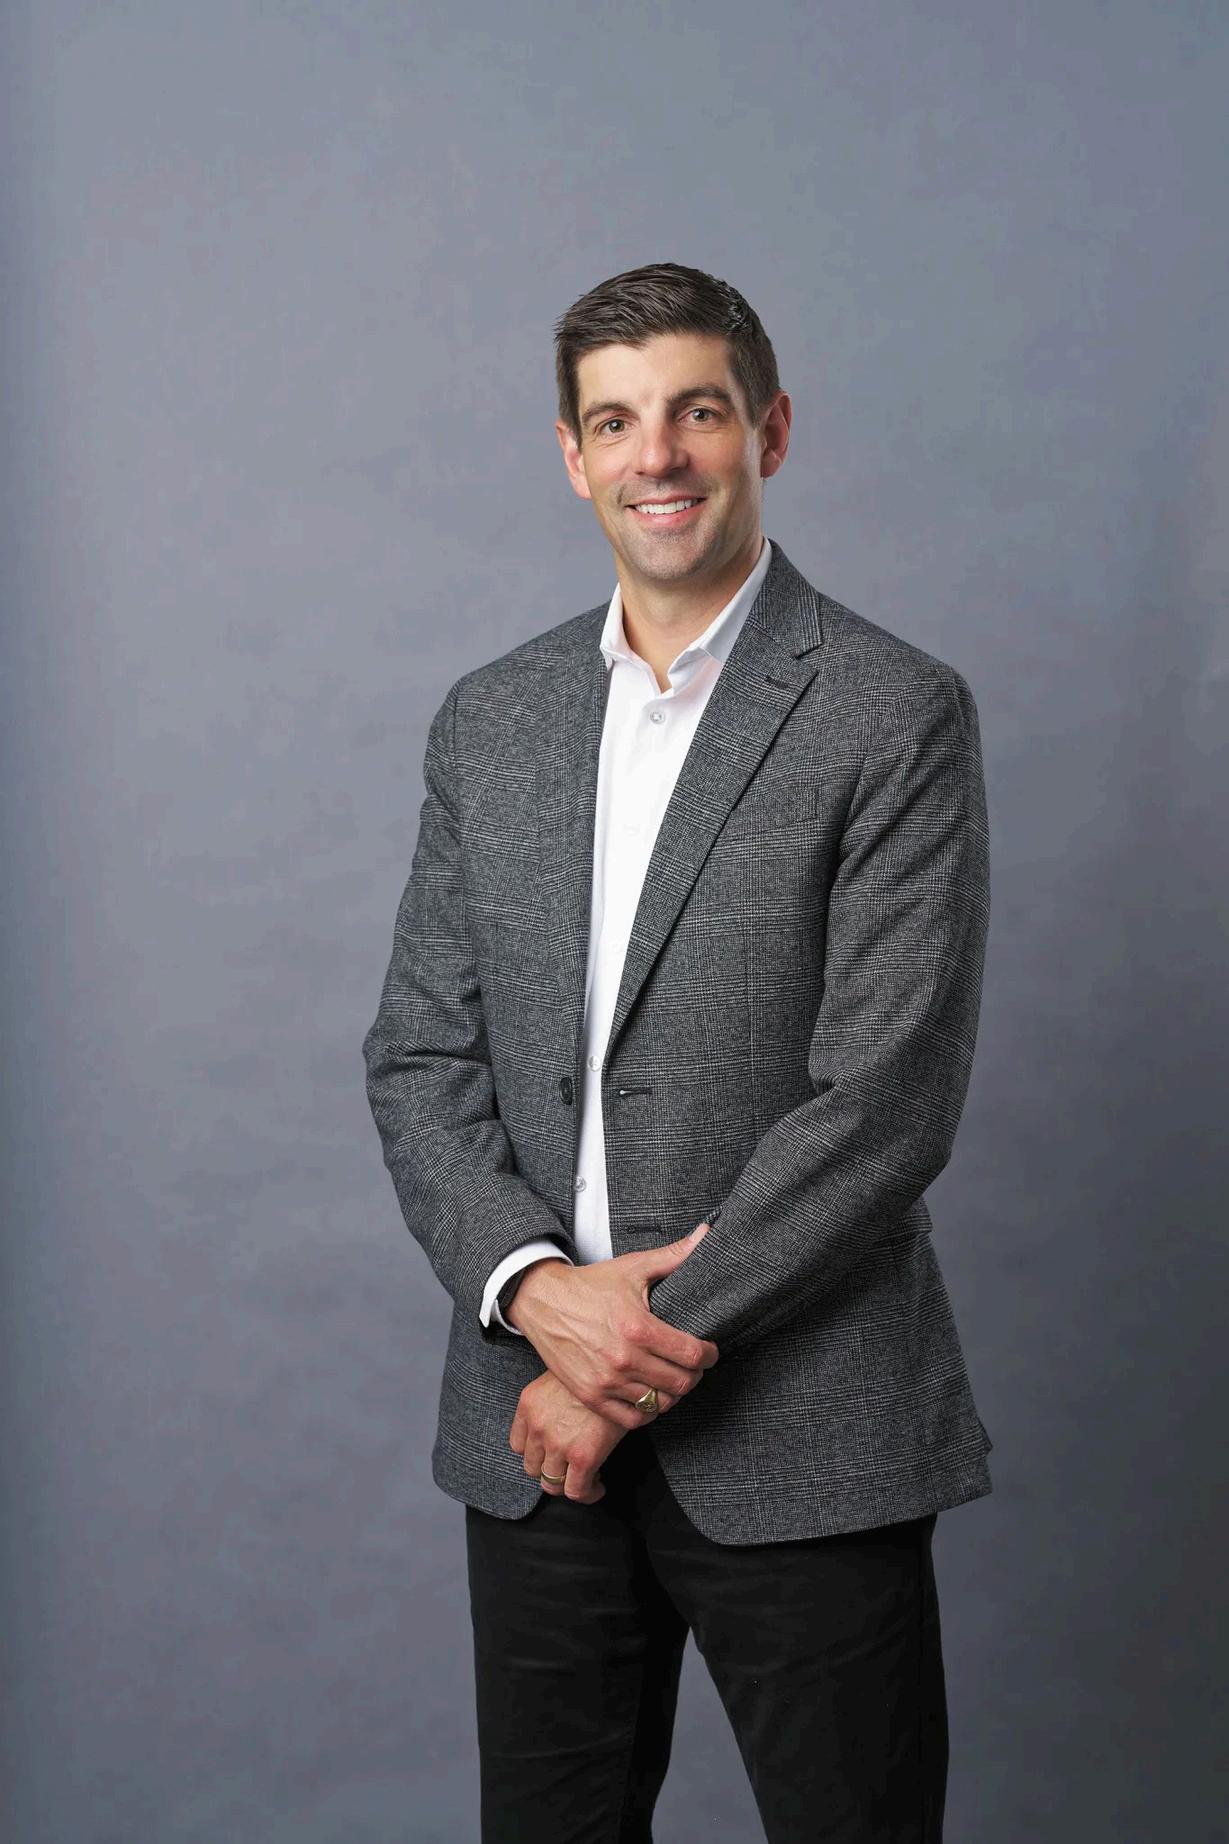
Full Interview by: Olivia Overman, Big “I”
Independent Insurance Agents & Brokers of America’s Declaration of Independents series highlights what makes the independent agency system distinct: ownership, long-term thinking, and a commitment to serving clients and communities with independence at the center That perspective closely reflects the mindset of many OIA members, who are navigating growth, succession, and an active M&A environment while remaining focused on preserving what makes their agencies unique
OIA member Rob Strachan, owner of Strachan Novak Insurance, embodies that independent spirit. Though he grew up in an agency family, he initially set his sights on a carrier career, not the brokerage side Over time, however, his perspective shifted as he recognized the scale of the opportunity in front of him It was not just about building a business, but about continuing a legacy of serving generations of clients. That realization turned a career decision into a longterm commitment to the agency and its future
His story, shared in May’s edition of Declaration of Independents, reflects the crossroads many agency owners and successors face today.
When it came time for ownership transition, his family evaluated multiple M&A paths including private equity, an external sale, and internal perpetuation With the help of trusted advisors, they completed multiple valuations and chose a path that balanced fair market value with longterm legacy and cultural fit This thoughtful evaluation underscores a broader reality within the IA channel: today’s owners are weighing more than just price
Rob also spoke candidly about the personal side of succession While the financial and structural elements can be complex, one of his biggest challenges was internal He focused on proving himself and earning the respect of employees, carrier partners, clients, and the community That intentional approach to leadership development is a common thread among successful perpetuation stories and reflects the level of commitment required to step into ownership
Ultimately, his decision to pursue internal perpetuation higlights one of the defining advantages of the independent agency system: the ability to control your own future. Even in a marketplace shaped by ongoing M&A activity, his experience reinforces that independence remains a viable and meaningful path for those who plan ahead
Beyond ownership, Rob is also helping other agents expand into health and Medicare through Strachan Health Insurance Partners He is passionate about investing in the broader success of the IA channel and this commitment reflects a forward-looking mindset and a willingness to share knowledge for the benefit of others.
Rob’s story is a strong example of the values seen across OIA’s membership It reflects intentional decision-making, a commitment to legacy, and a clear vision for the future of independent agencies.
Elevate your independent insurance agency with IA Valuations’ specialized services. Whether you’re transitioning internally, acquiring, selling externally, or looking for additional consulting services, our team offers expert guidance specific for your agency’s future success. We provide tailored planning and consulting services so you can trust us to navigate the complexities of your agency’s future and help you achieve your business goals.
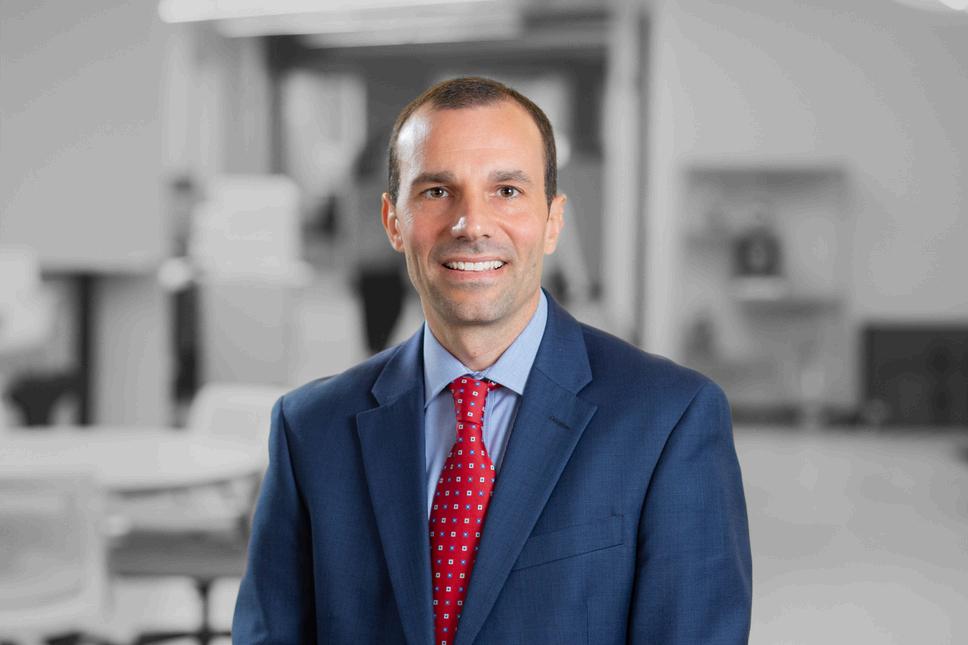
Jeff Smith, JD, CIC, CAE Chief Executive Officer jeff@iavaluations com
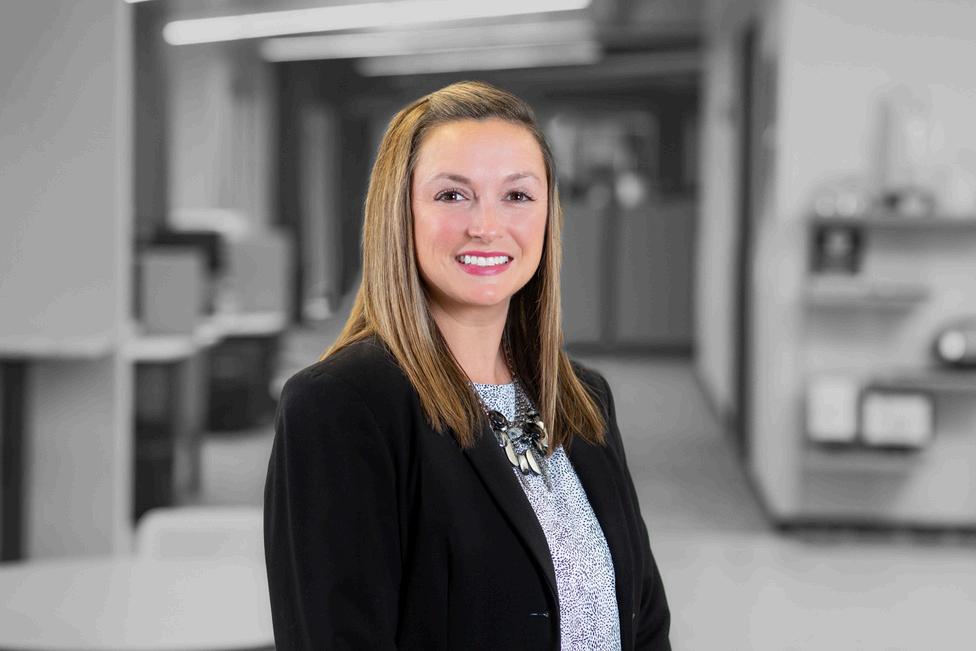
Jodie Shaw, CLCS, CPIA, TRA Director of Business Development jodie@iavaluations com
Craig Niess, CVA, MBA Director of Business Planning & Valuation craig@iavaluations com
Jarod Steed Business Planning & Valuation Analyst jarod@iavaluations.com
Colleen Elliott Marketing & Communications Manager colleen@iavaluations com
Written by: George Christy, OIA Government Affairs Manager
OIA Government Affairs and our dedicated members have made significant strides in the first half of this year, advocating across a wide range of policy areas impacting the insurance industry From tackling legal system abuse to addressing consumer protection concerns, independent agents have been actively engaged at the Statehouse
This year has underscored a key truth: when OIA members show up, policymakers listen
OIA Government Affairs has been involved in a varity of legislative priorities throughout 2026 These efforts reflect the association’s commitment to both protecting the independent agency system and promoting sound public policy that benefits Ohio consumers.
From litigation funding reform to insurance verification systems, and from contractor accountability to regulatory modernization and reform, OIA has maintained a proactive presence. Even more importantly, we have increased member engagement in the advocacy process by bringing agent expertise directly into legislative discussions OIA and our members have not just monitored legislation; we have weighed in and advocated in a meaningful way.
One of the most successful developments this year that OIA has had a role in is the passing of House Bill 105, which addresses Third-Party Litigation Financing (TPLF) reform. This legislation will bring transparency and accountability to a sector that can influence legal outcomes and insurance costs
House Bill 105 Bans investment from foreign entities into Ohio’s legal system and will require that litigation financiers register with the Ohio Attorney General’s Office Additionally, the bill will require disclosure of financing agreements after a case has been resolved
OIA was proud to play a role in supporting this important reform A highlight of this effort was the compelling testimony delivered by Bill Bishop (Associated Insurance Agencies), who brought his perspective as an agency owner to the issue. His insights helped lawmakers better understand how unregulated litigation financing can lead to an overly litigious environment that makes it difficult for small businesses to grow and thrive in our state
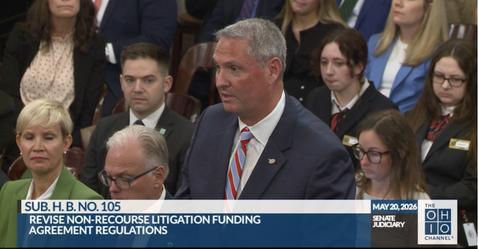
We are grateful for Bill’s engagement on this issue and are proud to see this bill head to the Governor’s desk for signature
Another key issue OIA has engaged with this year is House Bill 769, legislation targeting unscrupulous roofing contractors who exploit insurance claims for financial gain
Insurance agents are often on the front lines when these situations occur, helping clients navigate claims and fraud OIA’s involvement ensured that legislators understood the real challenges faced by both agents and policyholders
OIA member Steve Brown (Payne & Brown Insurance) provided impactful testimony on this bill, sharing firsthand experiences with abusive practices in the roofing industry His testimony highlighted how certain unscrupulous contractors manipulate claims processes, intentionally damage roofs, and leave consumers vulnerable.
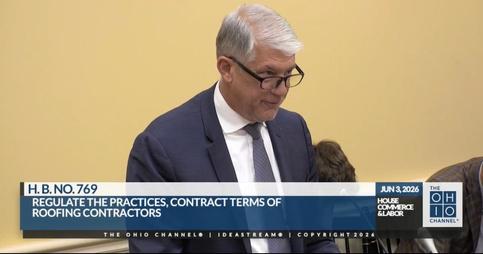
By contributing to this discussion, Steve helped reinforce the need for stronger safeguards and accountability measures, demonstrating how agent voices can influence better policy outcomes
Status: House Bill 769 has had two hearings in the House Commerce and Labor Committee and is expected to have further hearings when the Legislature is back from summer recess.
OIA has advocated for House Bill 678, which focuses on creating an online verification system for auto insurance Ohio has no modernized verification process for proving that Ohio drivers are meeting financial responsibility requirements An online verification system is critical to improving efficiency, reducing fraud, and ensuring compliance
Member Colleen Miles (Heister Associates) provided testimony on this important measure Her remarks offered valuable insight into the reality of the uninsured motorist crisis and how an online system could benefit agents and consumers alike
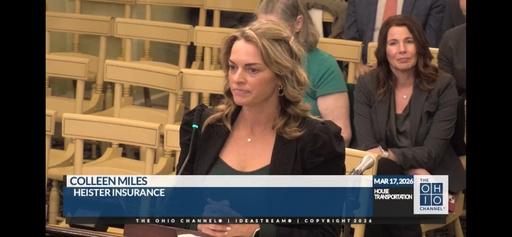
Colleen’s contribution helped ensure that the agent perspective was included when discussing a modern method to track whether Ohio drivers are maintaining financial responsibility
Status: House Bill 678 has received three hearings in the House Transportation Committee The bill is expected to have future hearings when the legislature is back in the fall
What sets 2026 apart so far is not just the breadth of issues OIA has engaged with, but the level of member participation in those efforts Bill Bishop, Steve Brown, and Colleen Miles, along with Heather MacKinnon and Nick Bertke earlier in the year, each stepped forward to share their expertise, lending credibility and authenticity to OIA’s advocacy Their willingness to testify and engaged directly with lawmakers reflects the strength of the OIA membership and its commitment to the profession
These efforts also send a strong message: independent agents are not passive observers of policy They are there to offer their insight and help promote informed, practical solutions that strengthen the industry and protect consumers
As OIA continues its advocacy work, the momentum built provides a strong foundation for future success. We encourage all members to consider how they can get involved, whether through testifying, meeting with legislators, or staying informed on key issues
OIA is making an impact, and your collective voice matters
Written by: George Christy, OIA Government Affairs Manager
The 2026 election cycle is in full swing, with many key races in Ohio across all levels of government
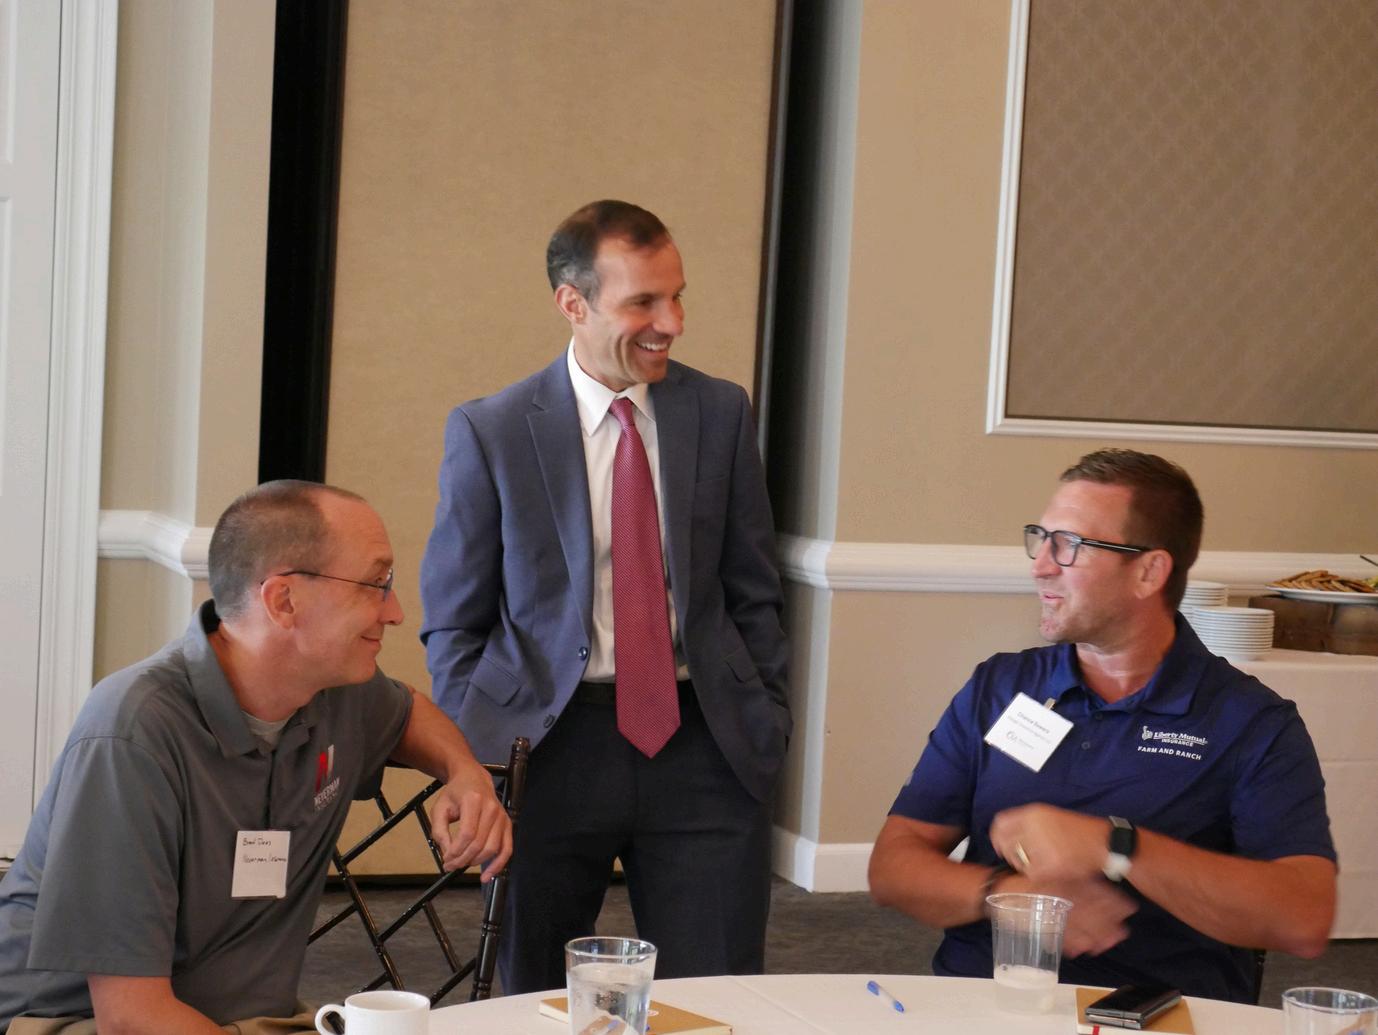
On June 16 , OIA brought members together for two meaningful events in one day, each focused on a different but equally important initiative: advocacy and education th
As part of our ongoing advocacy efforts, OIA proudly hosted a Supreme Court Reception in support of Justice Dan Hawkins in his reelection bid and candidate Colleen O’Donnell in her campaign for the Ohio Supreme Court The event provided a valuable opportunity for agents to hear directly from both candidates as they shared prespectives shaped by their experience in public service Their remarks reinforced the importance of a strong and principled judicial philosophy that upholds consistency and integrity within Ohio’s legal system and supports a stable business environment for independent agents
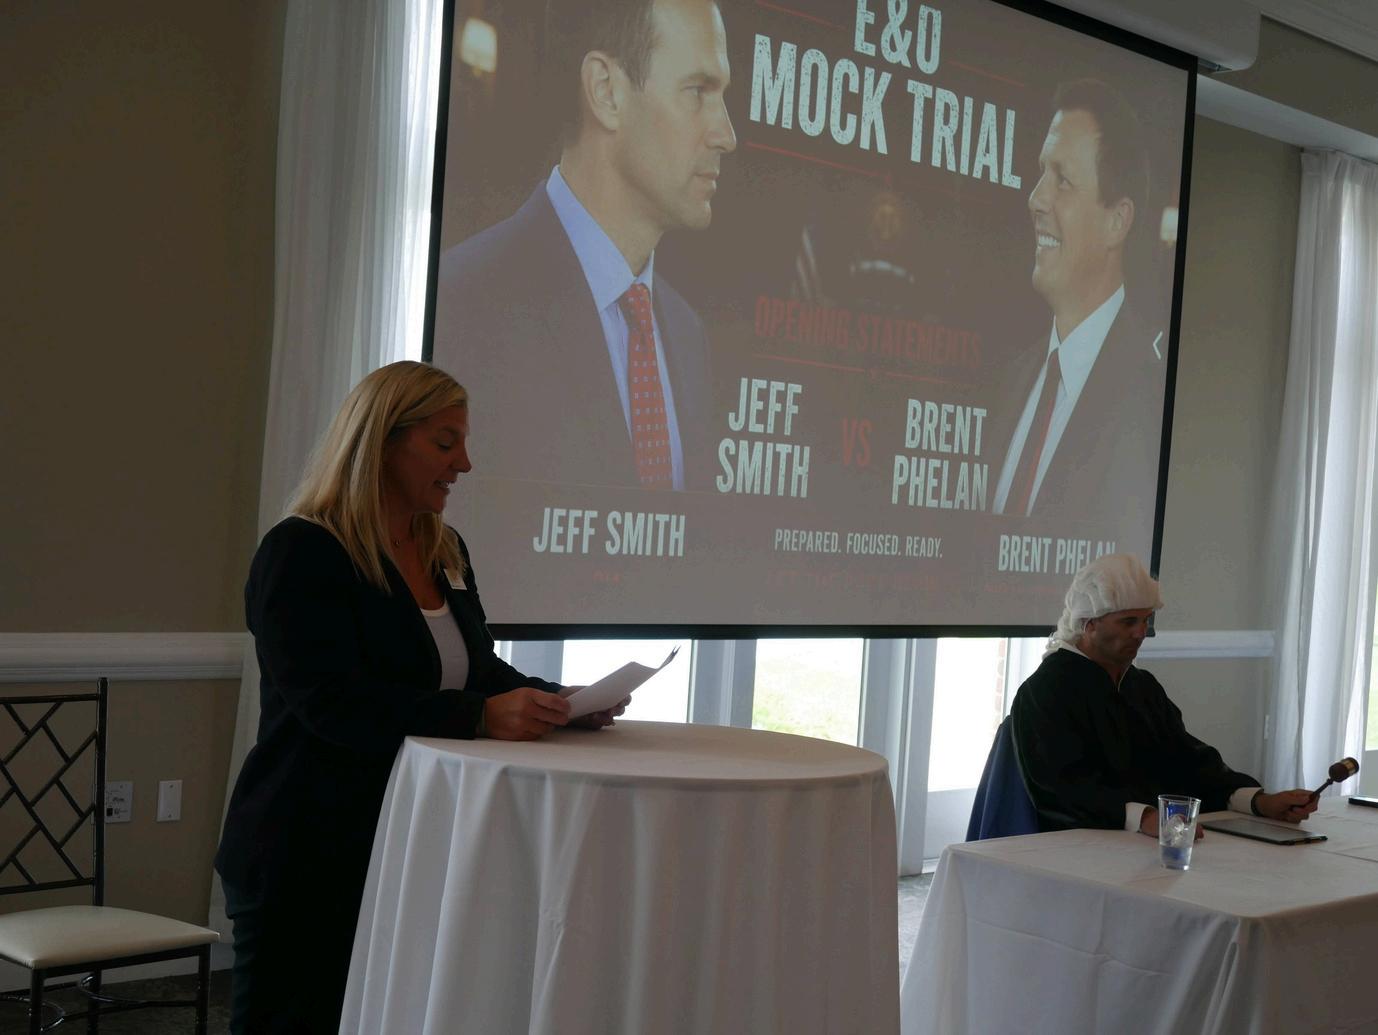
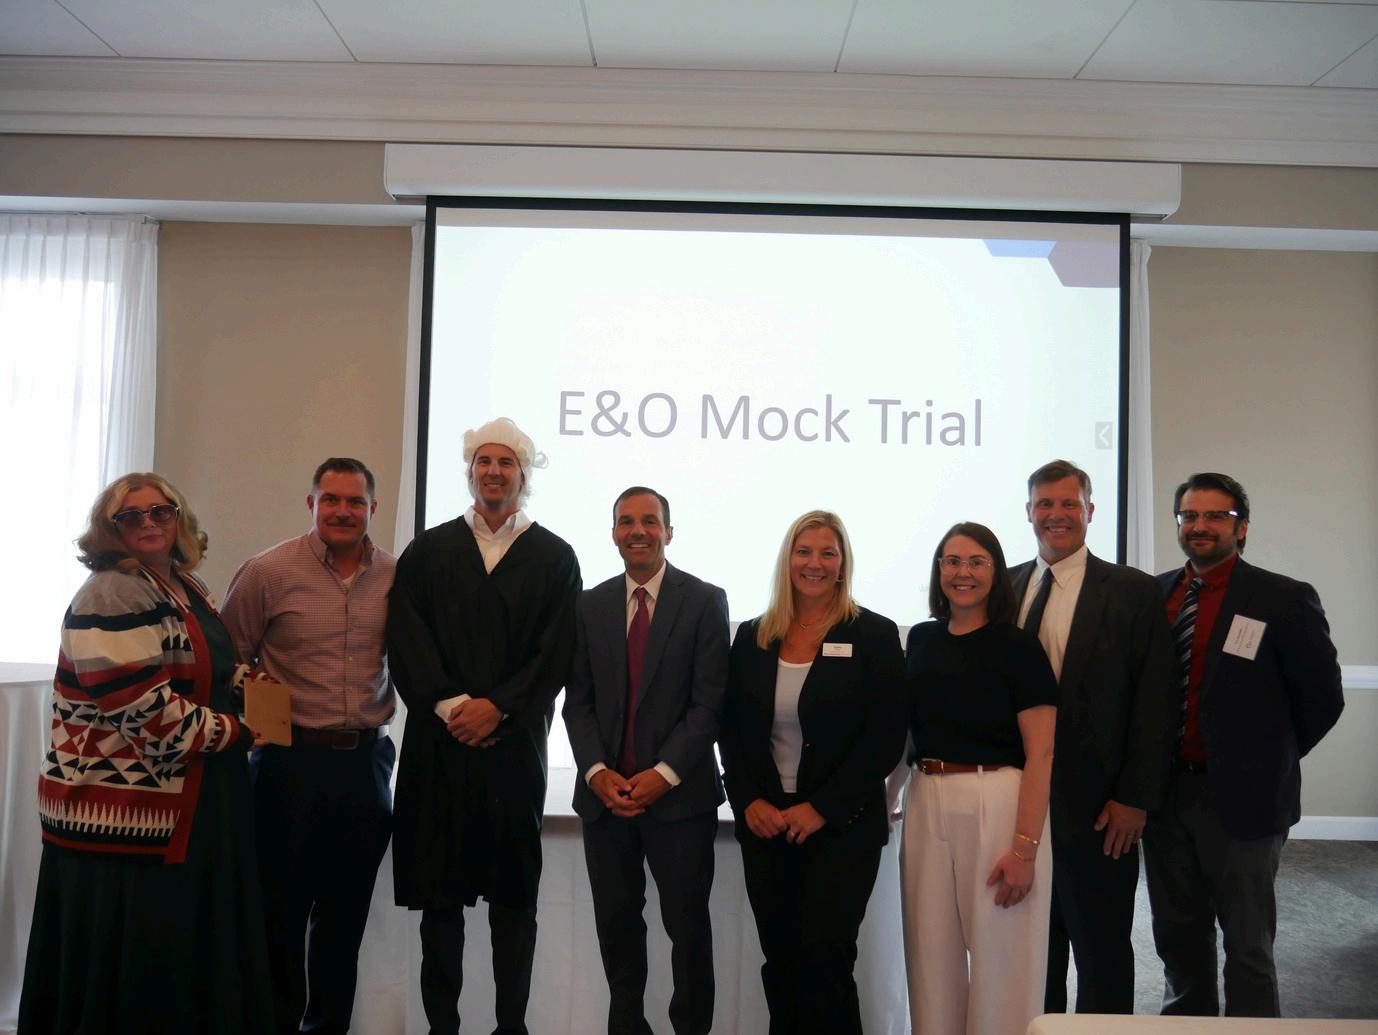
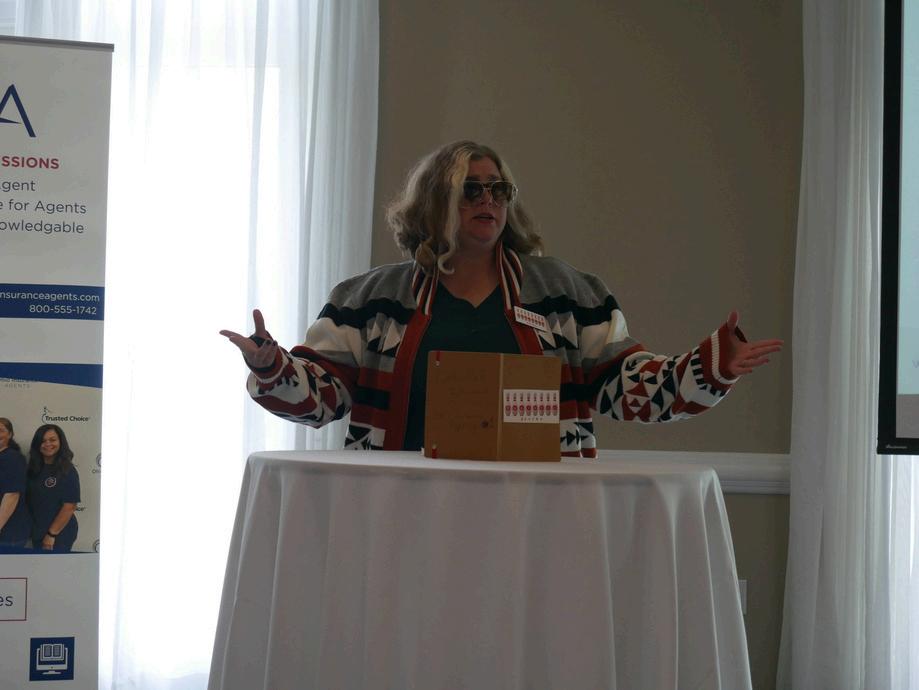
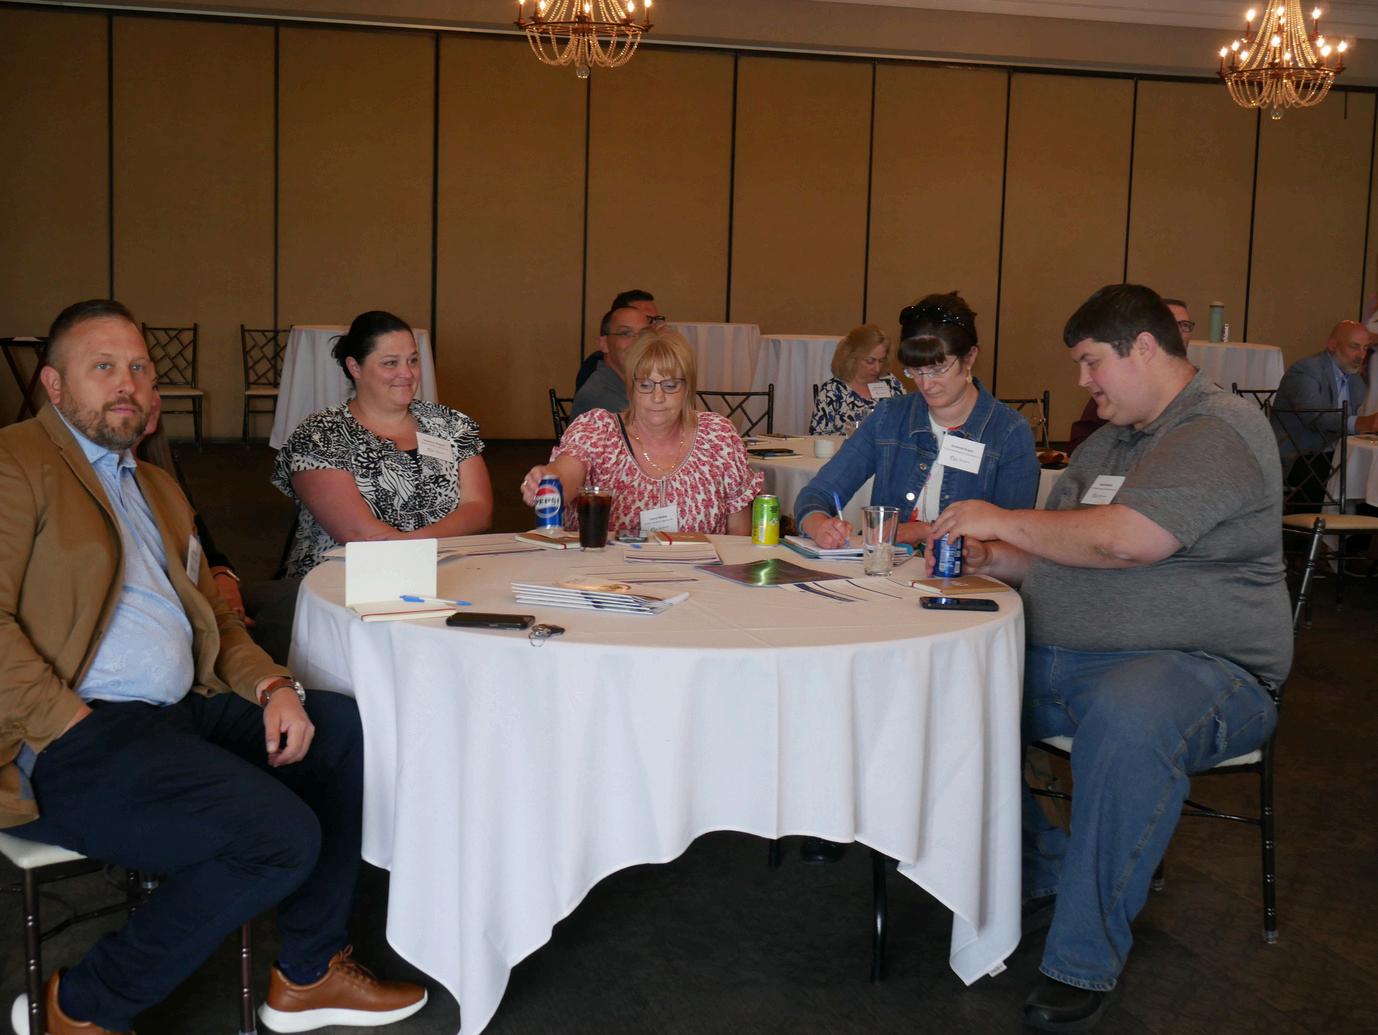
Earlier that same day, agents took part in the 2026 E&O Mock Trial, an immersive educational experience designed to bring real-world risks to life More than a traditional CE session, the mock trial walked attendees through every stage of a claims scenario, from opening statements to cross-examinations and the final verdict Legal experts and industry professionals highlighted how small missteps in documentation, communication, or coverage placement can lead to significant consequences, sparking thoughtful discussion and reflection on everyday agency practices
Together, these events showcased OIA’s commitment to supporting independent agents from multiple angles: advocating on their behalf while also equipping them with the knowledge and tools to better protect their businesses Agents left with practical insights to strengthen risk management strategies alongside a deeper understanding of the legislative landscape
OIA is incredibly grateful to our members who participated in both events and made the day such a success Your engagement is what brings these initiatives to life, and we look forward to continuing to provide opportunities that keep you informed, prepared, and connected.
As the election cycle continues, the Government Affairs team will continue to monitor other races and share our support for candidates who bolster the Independent Agent system in Ohio
For any additional details or questions on any of the bills or initiatives we are covering, please reach out to George Christy at (614) 929-8237 or george@ohioinsuranceagents.com You can also support the OIAPAC or InsurPac by scanning the QR codes below.
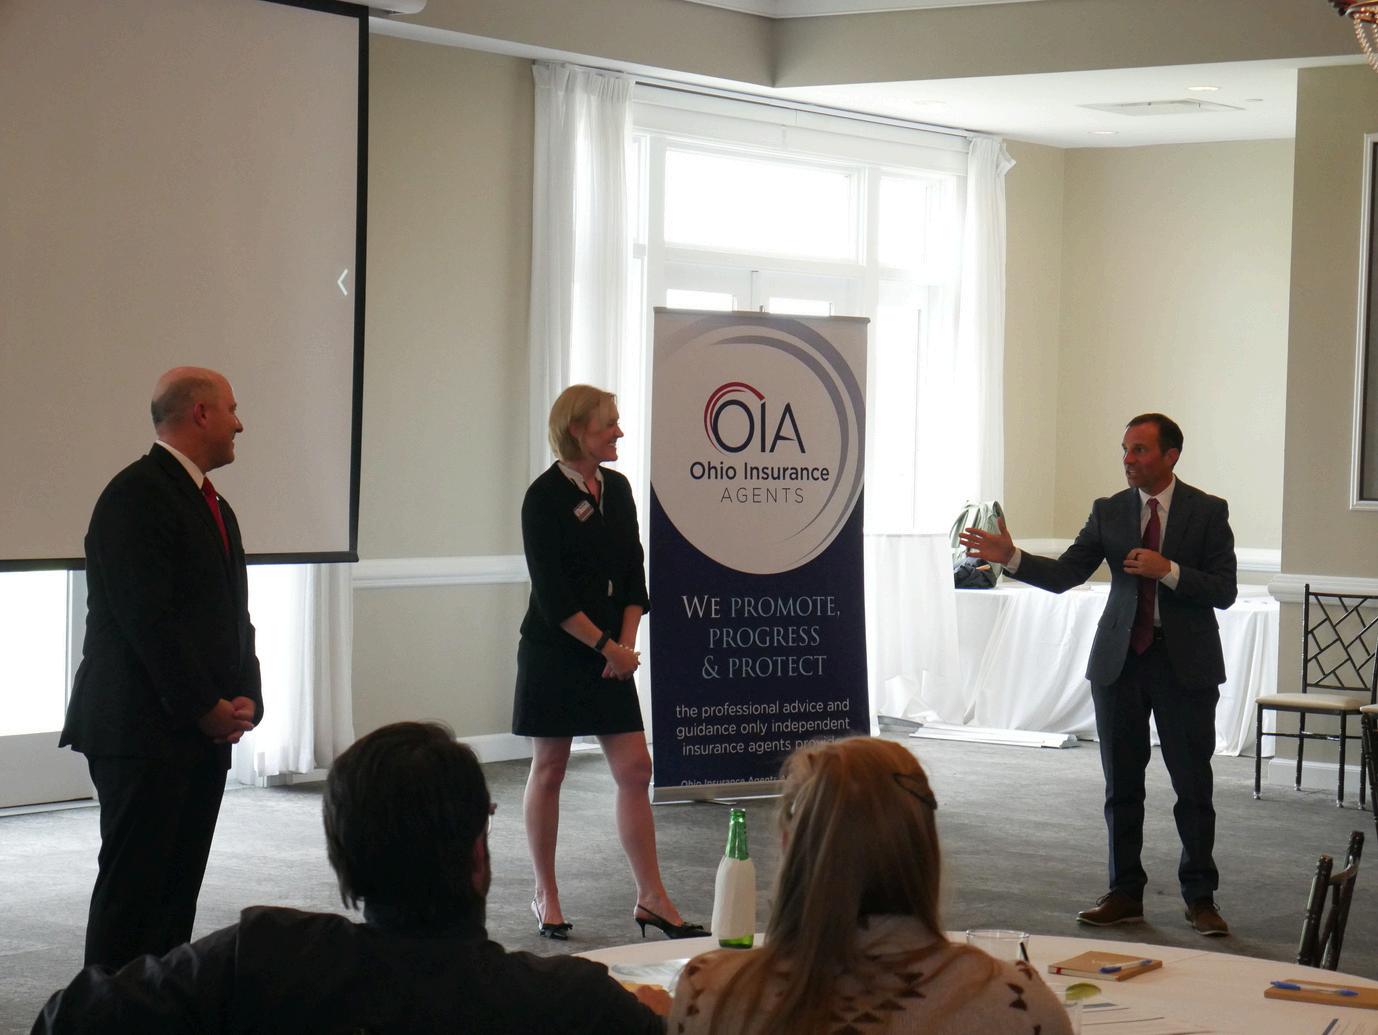
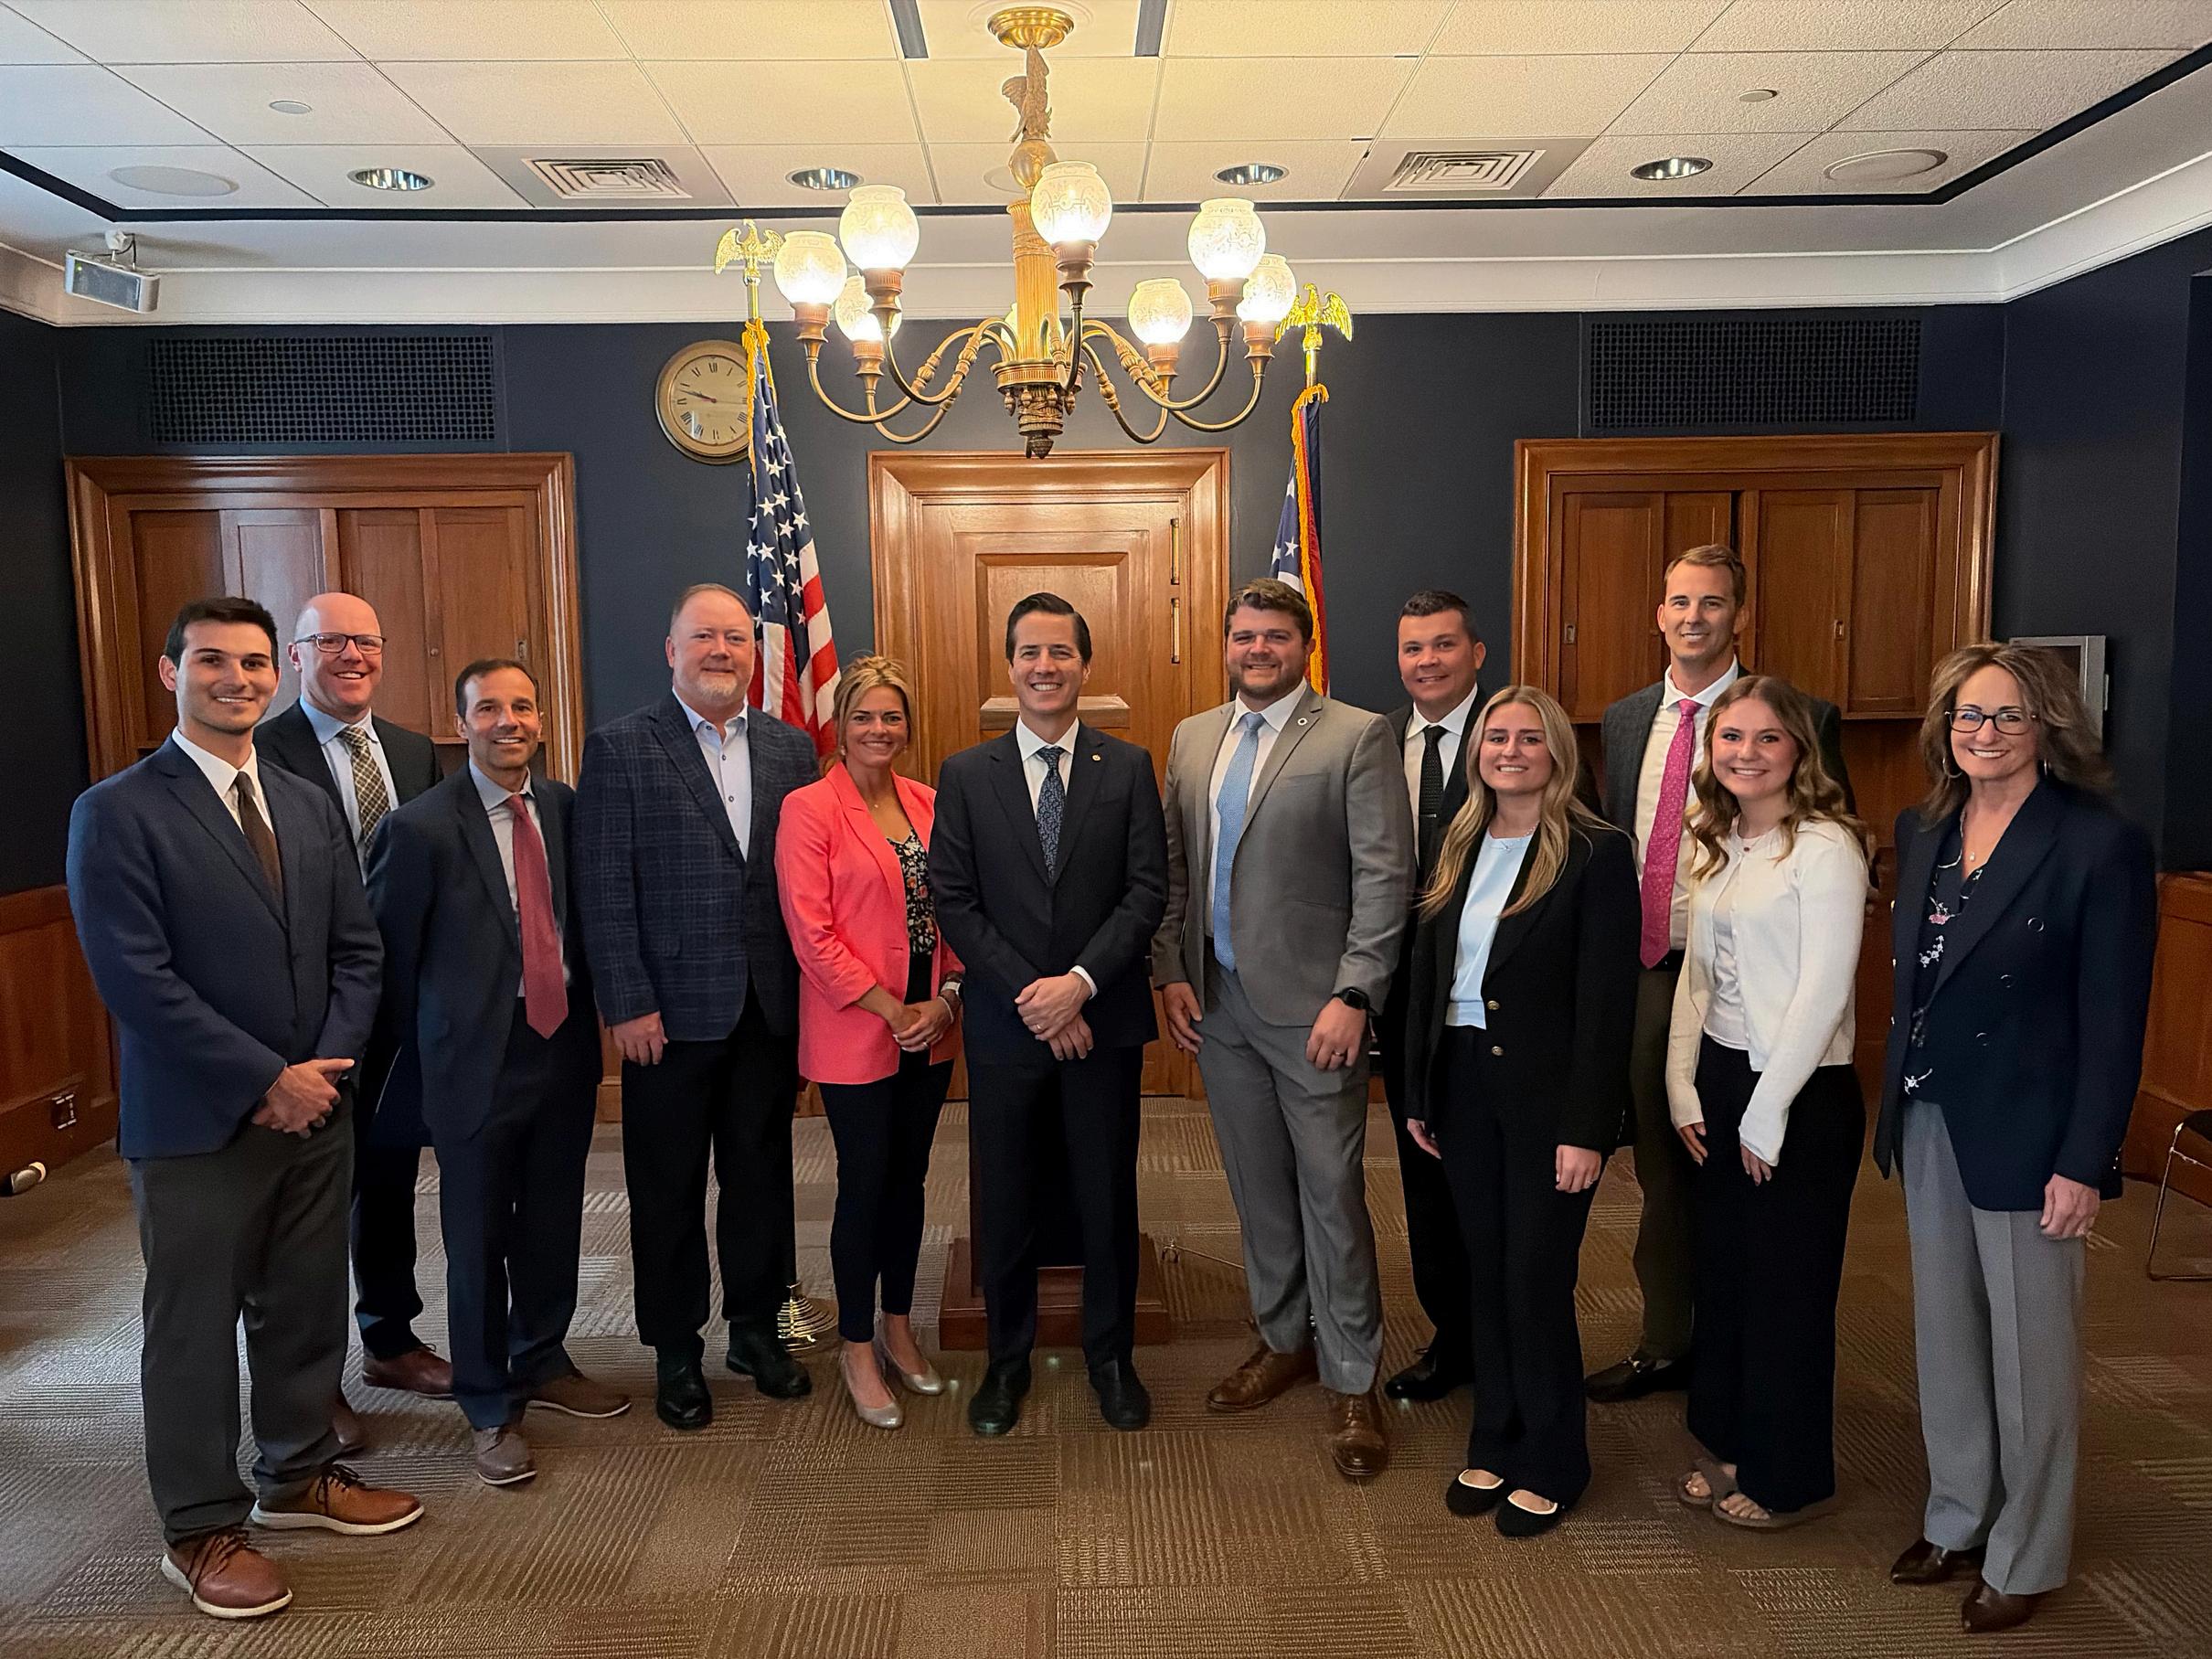
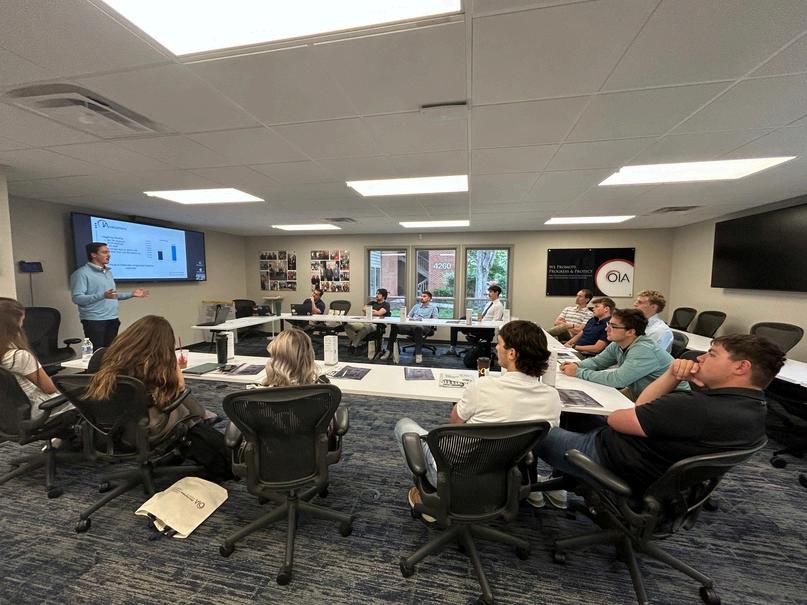
We were proud to welcome 12 exceptional interns to the OIA office for a day centered on connection, learning, and a firsthand look at the independent agency channel in action Through meaningful conversations and real-world insights, these emerging professionals gained a deeper understanding of the industry and the opportunities ahead, while already beginning to make an impact of their own
This experience reflects the ongoing work of OIA’s Next-Gen Committee and our commitment to advancing the independent agency system by developing future leaders This initiative would not be possible without the continued leadership and dedication of the agencies participating in the OIA Intern Program.
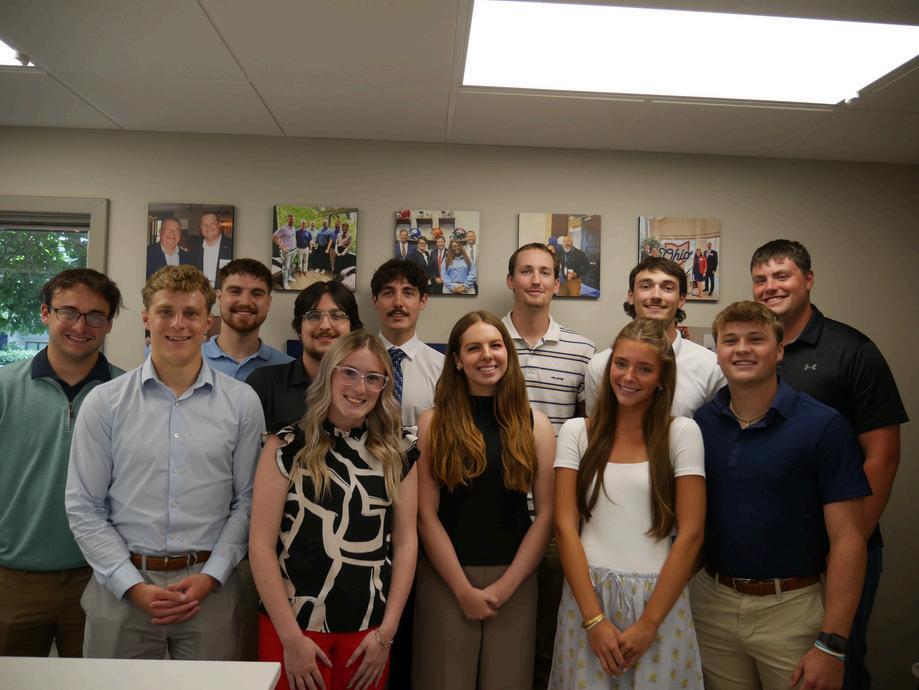
Their investment in developing the next generation of talent is helping to strengthen and sustain Ohio’s independent agency system for years to come
Participating agencies include Wallace & Turner, Inc ; Wichert Insurance; Knight Insurance Group; Bickle Insurance Services; Platt Insurance; Anderson Insurance; Strachan Novak Insurance Services; Frost Insurance Agency, Inc ; Leland Smith Insurance Services; Loy Insurance; Phelan Insurance Agency; and SeibertKeck Insurance Partners
The future of the independent agency system is bright, and it’s already getting to work!
Are you planning to stay in the industry for 20+ years, dreaming of owning your own agency, or looking to connect with like-minded peers through OIA’s Next-Gen group? Scan the QR code or reach out to Colleen Elliott at colleen@ohioinsuranceagents com to get involved and start shaping your future today!
By: Jeff Smith, JD, CIC, CAE, Chief Executive Officer
Written by: Jeff Smith, JD, CIC, CAE OIA Chief Executive Officer
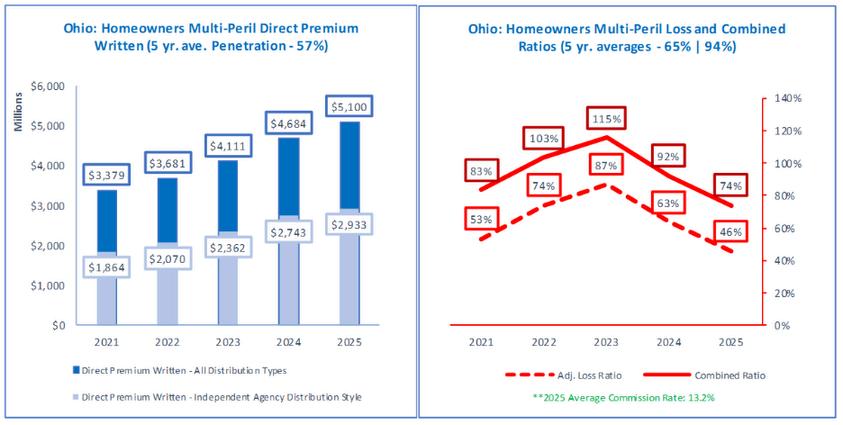
The Ohio Homeowners insurance market has experienced a massive rebound from record high combined loss ratios in 2023 (115%) to record high underwriting (UW) profits in 2025 (74% combined) The 41% drop in loss ratio over a three-year span is one of the largest swings on record It appears the rate increases and coverage changes carriers made in the Homeowners market have paid off big time
Last year we compared the Ohio Homeowners market to a rollercoaster ride. In keeping with that analogy, we are on the downhill of Cedar Point’s Top Thrill Dragster The 74% loss ratio in 2025 is 19% below the 5-year average and shows why Ohio has a reputation for being such a profitable personal lines state After multiple years of a hard market, the Homeowners' line of business is getting back to a more consistent and stable line of business
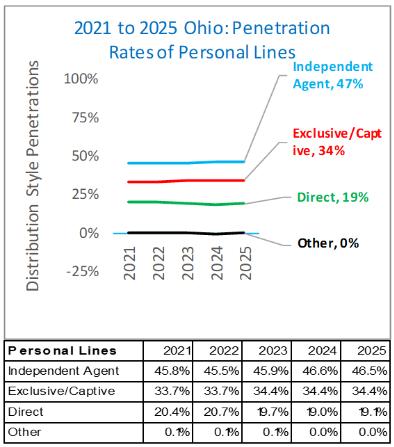
Analyzing the overall performance of IAs in the Personal Lines (PL) market, we see IAs were flat with -0.1% YOY decrease to maintain our control of the PL market with 46 5% of Ohio business
In comparison to the rest of the distribution system, there was essentially no YOY market movement in Ohio’s PL space This is a good sign for IAs in the highly commoditized PL market, particularly with the speculation and uncertainty of the impact AI could have on this line of business While several industry news outlets have communicated that there has been a record amount of online shopping in the PL space, it does not appear that Ohio consumers are switching their distribution choice in any meaningful manner This further shows the resilience of the IA model and that consumers continue to value an insurance advisor to provide an explanation and options during this cyclical insurance market rollercoaster.
In the Homeowners space, IAs continue to write 58% of the Ohio market While the rate increases have subsided based on the recent UW results, depending on the amount of convective storm activity, roof claims, and increasing property values, we could see this change quickly
Homeowners Markets Continues Growth by 9%
Ohio’s Homeowners insurance market rounded out just under $5 1B in written premium, a 9% increase YOY. This makes up 19% of the greater $26.8B insurance market in Ohio The Homeowners market has increased 34% in the past five years, holding firm with the rest of the insurance market
After two years of triple-digit loss ratios (103% in 2022 and 115% in 2023), carriers were able to produce an underwriting profit by decreasing the loss ratio by 23% in 2024 to a combined ratio of 92% and further reduced the loss ratio by another 18% down to 74% in 2025.
In the Homeowners line of business, commissions for agents increased slightly to 13 2%, up from 13 1% in 2024 Surplus lines placement stayed at 0.1% of the market, further showing Ohio’s Homeowners market is one where admitted markets write 99 9% of the business
For three straight years, carriers increased written premiums (33% since 2020), tightened underwriting restrictions, closed off the new business spigot, and non-renewed many homes with aging roofs The results have proven to be successful
As the graphs show below, premium increases have been significant over the past 5 years, but IAs have held steady in their control of their market share
In addition, combined loss ratios appear to be on the decline again 2026 will be a pivotal year to see if this trend continues
A combination of year-over-year rate increases, strong retention driven by hard market turmoil, and moderate storm activity helped carriers exceed the underwriting profits they were targeting in 2025. The 9% increase in premium across the Ohio Homeowners channel along with 74% combined loss ratios created record profitability in the Homeowners line of business for many carriers
State Farm remained the Ohio Homeowners market leader, controlling approximately 21% of the market in 2025 Their combined loss ratio of 76 6% was a 30% YOY improvement from 2024 and could allow them to leverage their market position and reserves to generate additional business In addition, Allstate maintained its position as a solid #2 with over 10% of the market, a 21 5% increase in premium YOY, and an impressive combined loss ratio of 77 4% Particularly impressive for Allstate is its five-year combined loss ratio in Ohio of 88 2%
Similar to 2024, with the exception of two carriers, eight of the top ten Homeowners carriers experienced written premium increases between 5% to 26 4% The two carriers that saw a decline in written premium were the same in 2025; Liberty Mutual (including Safeco and State Auto) saw a 9 3% reduction and Nationwide experienced a 2 4% decline
The top 20 carriers in Ohio continue to write 92% of the state’s written premium. This group remained largely unchanged in 2025.
The IA carriers that performed exceptionally well in 2025 included Grange, with a 5% premium increase combined with a 71 2% loss ratio for the year. Other carriers with notable results include Encova (85.4% combined ratio), Nationwide (68 6%), Cincinnati Insurance (74 5%), AutoOwners (69%), and Progressive (68 1%)
On the bright side, several independent agency carriers with unfavorable UW results from 2024, saw significant improvements in 2025, including Erie (90 8% in 2025 vs 108 5% in 2024), Westfield (70.7% in 2025 vs. 102.2% in 2024), and Ohio Mutual (90% in 2025 vs. 115.5% in 2024).
The story on Ohio Homeowners UW results gets more positive when compared with national averages as Ohio carriers enjoyed an average combined loss ratios 11% lower than their nationwide results. For example, Grange outperformed its five-year national average by 30% in Ohio, Cincinnati by 30 6%, Auto-Owners by 34 6%, Progressive by 14 1%, Westfield by 45%, Western Reserve by 26%, and Encova by 18 5%
With the 41% swing in UW profitability for Homeowners, we expect to see carriers get more competitive and potentially take significant action with rates For example, in May, Nationwide announced it was decreasing Homeowners rates for Ohioans by 18%
In addition, according to APCIA, US P&C carriers have returned over $6 2 Billion to policyholders in Q1 2026 in the form of dividends, premium givebacks, and rate reductions
While the Homeowners market in Ohio had a phenomenal swing from 115% combined loss ratios in 2023 to 74% in 2025, this is not a time for IAs to soften their communication and engagement with their Homeowners clients They must stay proactive in their education and annual reviews as the imminent threat may not only be premium increases; it also is a changing expectation in consumer buying behaviors influenced by evolving technology and AI
It appears that IAs have weathered the worst of the Homeowners market, but it is unlikely to return to the pre-hard market environment While carriers are expected to keep rates flat or possibly reduce rates, we do not expect them to remove the roofing coverage restrictions that have been implemented over the past couple of years
Therefore, agents should continue to make sure their clients are well informed of the coverage changes and ways to reduce exposure while keeping their premiums affordable Proactive communication and education are the best ways to stay on top of client engagement and reduce the risk of your client going somewhere else for their insurance needs.
Much like the final stretch of a roller coaster, this hard market cycle is quickly on the downhill, signaling a return to smoother conditions Another year of underwriting profits and things will start to feel normal again for Ohioans. So far, 2026 has been relatively similar for Ohio homeowners and hopefully that continues through December 31st
Accredited Insurance Lines Professional
The Accredited Insurance Lines Professional (AILP) is a professional designation designed to support the development of agency staff.
Courses on coverage and day-to-day issues serve clients better.
Through a partnership with New Level Partners (NLP), OIA now offers practical, agency focused training that covers:
insurance basics
personal and commercial lines essential communication and customer management skills
Get your team exam-ready We have three distinct learning formats for P&C PreLicensing: hybrid-online, self-study, and in-person options
Hybrid-course dates: Aug 17-21 | Sept 21-25
Fresh, loss-control content focused on preventing errors and ommissions claims while earning premium credit Courses approved by Swiss Re and Utica!
PLUS: Our staff can deliver private courses tailored to your agency’s specific needs. Contact us to explore ready-to-go topics and course details
From Assumptions to Accuracy: Reducing E&O Exposure in Daily Agency Operations with Vertafore
July 15 | 12 to 1pm | 3 credits
Recognizing Fraudulent Claims and the Insureds Who File Them
July 16 | 9am to 12pm | 3 credits
Power of Prevention: Essentials of Service
July 17 | 9am to 12pm | 3 credits
CGL Endorsements That Will Break Your Policy
July 21 | 9 to 11am | 3 credits
C-Suite Savior: Mastering D&O, EPL and Other Executive Liability Policies
July 21 | 1 to 4pm | 3 credits
Strategies for Hiring and Paying a New Producer
July 22 | 12 to 1pm | CE pending
Understanding Commercial Property Gaps and Knowing How to Fill Them
July 23 | 9am to 12pm | 3 credits
IN-PERSON CE OPPORTUNITY: Power of Prevention: Essentials of Service with Arlington/Roe
July 23 | 9am to 12pm | 3 credits | Twinsburg
Ethics in Insurance: Protecting the Client and the Agency
July 23 | 1 to 4pm | 3 ethics credits
Incredble Efficiency: How Farms and Agribusiness Insureds Create Energy and the Risks/Insurance Issues Involced
July 28 | 1 to 4pm | 3 ethics credits
Don’t see a course you’re looking for?
Reach out and let our team know Email: learning@ohioinsuranceagents
By: Alex Bowie, Sr. Manager, Marketing & Communications
After several years of rising costs, tightening underwriting, and uneven results, Ohio’s commercial auto market is finally showing signs of stabilization But while the numbers are improving, the story is far from simple
Premium growth remains strong In 2025, Ohio commercial auto direct written premium reached $2.121 billion, up from $1.929 billion in 2024 and just $1 531 billion in 2021 Growth is not the issue
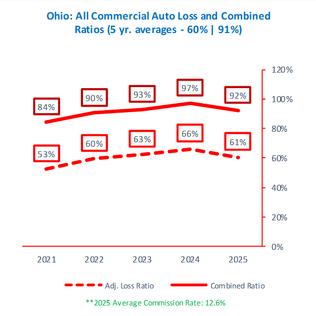
The good news: underwriting results are beginning to rebound The statewide combined ratio improved to 92% in 2025, down from a recent high of 97% in 2024. Loss ratios followed suit, improving from 66% to 61%
Still, the market remains sensitive Loss severity, repair costs, and litigation pressures continue to shape outcomes, and one favorable year does not erase several years of strain. Meanwhile, independent agents continue to dominate distribution, accounting for roughly 90% of the market In a line of business this complex, their role as trusted advisors has never been more important.
The past five years tell a clear story: a line under pressure, now beginning to recalibrate
Premiums climbed steadily from $1.531 billion in 2021 to $2.212 billion in 2025, driven largely by rate increases and exposure growth across key industries like transportation and construction
But underneath that growth, performance told a different story. Combined loss ratios rose from 84% in 2021 to 97% in 2024, while loss ratios climbed from 53% to 66% over the same period
Written by: Alex Bowie, OIA Sr Marketing and Communications Manager
For several years, carriers were playing catch-up –adjusting rates to keep pace with escalating costs Now, that correction is starting to take hold In 2025, both combined ratios and loss ratios improved, signaling that pricing and underwriting
Even so, the market is far from uniform. Some carriers are tightening Others are expanding Some are prioritizing profitability Others are chasing growth That divergence is shaping the next phase of the market
The Ohio commercial auto market is no longer moving in a single direction It’s splitting into distinct strategies – and the top carriers reflect that shift Progressive Insurance Group continues to anchor the market, writing $204 7 million in premium. While slightly down year over year (-4 6%), Progressive maintained strong underwriting discipline with a combined ratio of 86 9%, outperforming the statewide average
The Cincinnati Insurance Companies stand out as one of the most balanced performers. With $137.3 million in premium and a combined ratio of 83 4%, Cincinnati pairs growth (+8 2%) with profitability –an increasingly rare combination in this line discipline may finally be aligning with the underlying risk At the same time, competition remains deep, with 445 active insurers writing commercial auto in Ohio.
Old Republic Insurance Group may be the most disciplined of the group Its 80 0% combined ratio is the lowest among the top five, demonstrating a clear focus on underwriting performance while still achieving +17 1% growth
On the other end of the spectrum, Berkshire Hathaway Insurance Group represents a different strategy. Premium surged +98.2% to $132.0 million, signaling aggressive expansion. GEICO Marine Insurance Company was the leading insurer under this group, growing commercial auto premium from $28 2 million in 2024 to $78 8 million in 2025 in the Ohio market However, a combined ratio of 107.5% indicates that growth is coming at the expense of short-term profitability. Greg Abel, CEO, Berkshire Hathaway, shared in a letter to shareholders “The GEICO team remains focused on pricing risks correctly for both existing and new customers Restoring retention while maintaining underwriting discipline will take time,” according to carriermanagement.com.
Rounding out the top five, Travelers Group delivered steady, measured results with $75 8 million in premium, +9.7% growth, and a solid 83.1% combined ratio.
This is a market of clear tradeoffs: Growth vs discipline
Expansion vs profitability
Market share vs. margin
And carriers seem to be choosing their path with hopes of stabilization over time
Looking ahead, Ohio’s commercial auto market is entering a more balanced – but still cautious –phase. Premium growth will likely continue, though at a more moderate pace Much of the heavy lifting from recent years came from rate increases Going forward, growth will depend more on actual exposure and economic activity
But the bigger question remains: Can profitability hold?
Even with improvement in 2025, the underlying cost environment is still challenging Repair costs remain elevated due to vehicle complexity
Medical inflation continues to drive claim severity
Litigation trends are not easing These pressures mean carriers are unlikely to relax underwriting discipline anytime soon. In fact, the opposite is more likey Expect continued selectivity
Higher-risk classes, especially transportation and delivery fleets, will remain under scrutiny
Capacity may tighten in certain segments, opening the door for carriers with strong specialization, or agents with the right market access
Technology will also play a bigger role in shaping the next phase of the market Telematics, driver monitoring, and data-driven underwriting are no longer optional – they are becoming competitive differentiators Over time, these tools could help bend the loss curve in a more favorable direction
Economic conditions will further influence performance. As long as sectors like construction and logistics remain active, demand for commercial auto will follow Any slowdown, however, could quickly impact exposure growth
One constant remains: the independent agent. With roughly 90% of the market, agents are at the center of these conversations, helping business owners make sense of pricing, risk, and coverage in an increasingly complex environment
The outlook? Cautiously optimistic. The market is improving – but it’s not comfortable yet
In today’s commercial auto market, conversations matter more than ever
Clients are seeing rate changes, tighter underwriting, and shifting carrier appetites – and they want answers The most successful agents will be the ones who can clearly connect those changes to broader market trends Focus on what clients can control:
Driver safety programs
Vehicle maintenance
Use of telematics and monitoring tools
At the same time, position yourself as a strategic partner by exploring multiple carrier options and aligning coverage with each clients’ evolving risk profile The market may be stabilizing, but expertise is still the differentiator
For more than 40 years, RLI has delivered affordable personal umbrella coverage backed by deep underwriting expertise and in-house claims professionals who manage each claim from start to finish.
Our Personal Umbrella Policy stands alone with no underlying carrier requirements, giving independent agents flexibility and customers confidence.
Rated A++ (Superior) by A.M. Best RLICORP.COM
A++ (SUPERIOR) A (STRONG)
With AMBestandan Standard&Poor’s, RLI offers thestability customersexpect when protectingtheir financial assets and future earnings This is not coverage built for the moment. It is coverage built to last.
financial strength from ratingfrom
Discover the RLI difference in Personal Umbrella coverage and how it compares to the competition at OHIOINSURANCEAGENTS.COM
Review our comprehensive member guide to see what OIA membership can unlock for your agency’s growth and development!
OIA delivers a monthly newsletter, straight from our industry professionals to your inbox, packed with the latest news, blogs, resources, and industry updates! Stay informed with legislative highlights, operational tips, and member milestones
Sign up to receive our email communications! To gain access to the newest resources and news affecting the industry, scan this code to receive emails and updates
$35,000 $35,000
AWARDEDLASTYEARFROMTHE AWARDEDLASTYEARFROMTHE
GEORGEHAENSZELFOUNDATIONSCHOLARSHIP
GEORGEHAENSZELFOUNDATIONSCHOLARSHIP
FOUNDATION SCHOLARSHIPS ARE ELIGIBLE* FOR:
VALUATIONS AND PERPETUATION SERVICES
PROFESSIONAL DESIGNATIONS
BUSINESS CONSULTING
EDUCATION COURSES
OIA-SPONSORED OR AFFILIATED EVENTS
PRE-LICENSING EDUCATION
INTERNSHIP SPONSORSHIP
APPLY AND TAKE THE NEXT APPLY AND TAKE THE NEXT STEP IN YOUR CAREER STEP IN YOUR CAREER
*Eiligibility restrictions apply
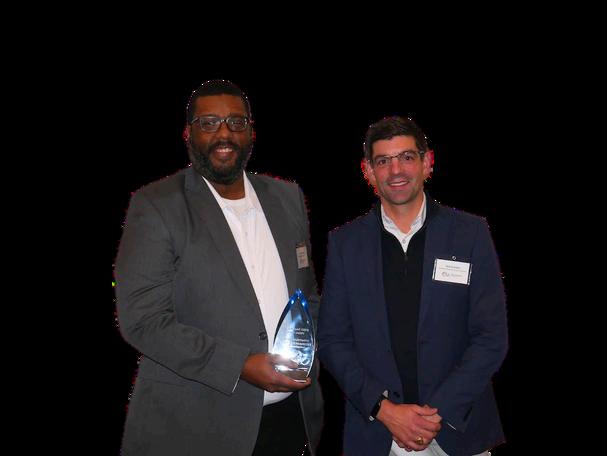
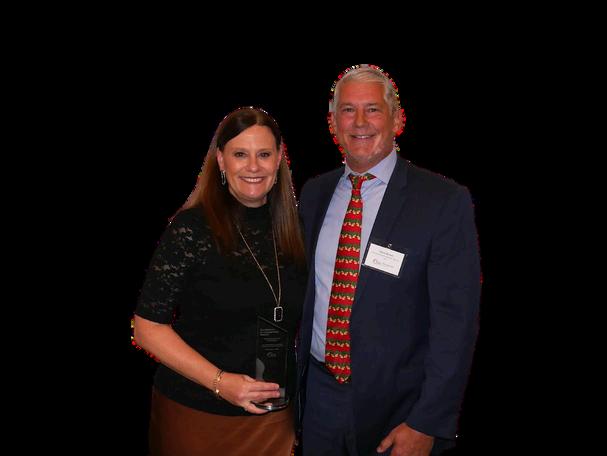
RECOGNIZE AGENT EXCELLENCE ACROSS:
Industry Person of the Year
The Foundation Scholarship has empowered us to adapt and grow, allowing us to strategically plan for both the present and then uncertain future It provided essential funding to reevaluate our agency from a leadership perspective.”
Grayson and Bethany Thompson Agency Owners Mission Insurance Agency
Outstanding Company Achievement
Excellence in Leadership Community Service
Best Agency Video of the Year
Public Service
Culture Catalyst
Our Ohio CRC Binding team is ready to help — connectwithanyofthecontacts listed to get started.
Tony Armor
Office President, Senior Team Leader 317 566 6100 tarmor@crcgroup com COMMERCIAL
Ian Crook Associate Team Lead 614.216.6122 icrook@crcgroup.com
Austin Cummings Associate Team Lead O | 740 907 0057 C | 740 462 8932 acummings@crcgroup com

OIA’s E&O program has focused on protecting Ohio independent agencies for over 60 years. This longstanding commitment to safeguarding our members is a cornerstone of our business Your agency’s insurance protection is important and deserves our exclusive focus Our team has more than 50 years of experience in the E&O industry Let us provide you with helpful information and support so you can select a policy that meets your requirements
We assure you one thing – your agency’s protection will always be our #1 priority Contact us today!
We had had such a long-term relationship with our previous carrier for this coverage However, the ease of doing business with OIA and their guidance calmed our insurance jitters
Kevin Perkins, Perkins Insurance -
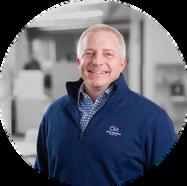
Joe Fullenkamp Chief Executive Officer Designate (614) 552-3064 joe@ohioinsuranceagentscom
Jeff Smith JD CIC CAE Chief Executive Officer (614) 552-3056 jeff@ohioinsuranceagentscom (614) 552-3066 jody@ohioinsuranceagentscom
Jodie
Business Planning & Valuation Analyst 614-552-3065 jarod@ohioinsuranceagentscom
Katie Gratton CIC CISR CPIA Account Executive (614) 552-3042 katie@ohioinsuranceagentscom
552-3068
George Christy Government Affairs Manager (614) 929-8237 rachel@ohioinsuranceagentscom
Stacy Rosenthal CISR CPIA Account Executive (614) 552-3058 srosenthal@ohioinsuranceagentscom
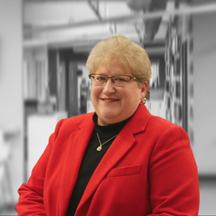
Dawn Kuhn, CPA Chief Financial Officer (614) 552-3055 dawn@ohioinsuranceagentscom
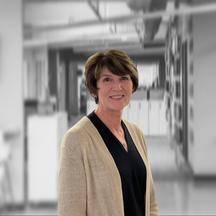
Craig Niess, CVA, MBA Director of Business Planning & Valuation (216) 288-8409 craig@ohioinsuranceagentscom
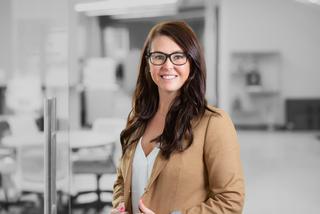
Ashley Fitzsimmons Director of Professional Development (614) 552-3043 ashley@ohioinsuranceagentscom
Teresa Hinkle Account Manager (614) 552-3063 teresa@ohioinsuranceagentscom
Katherine White Governance Manager (614)
Rachel Davis Education Program Manager (614) 552-3086 rachel@ohioinsuranceagentscom
Valeria Ashcraft E&O Account Manager (614) 552-3049 valeria@ohioinsuranceagentscom
Buffy Terry Administrative Manager (614) 552-3066 buffy@ohioinsuranceagentscom