BEER | SPIRITS | WINE
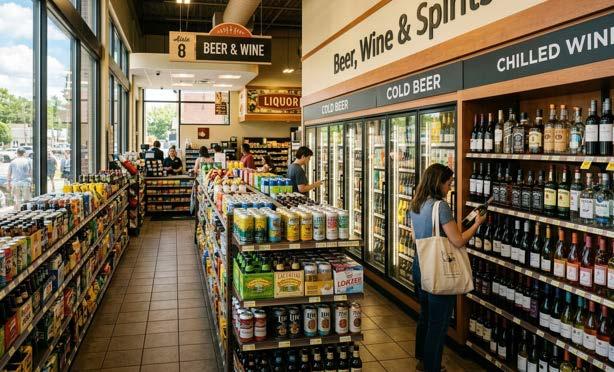
For a long time, beer, wine, and spirits in the convenience channel were treated as a given. You carried the core brands, kept the cold vault full, stayed competitive on price, and let the category do what it does.
That approach still works, to a point.
The category has changed but, more importantly, the customer has changed.
Today’s shopper walks into a convenience store with a very different set of expectations than they did even five years ago. They are more aware of brands, more willing to try something new, and more comfortable buying premium products in a channel that used to be defined by speed and simplicity.
For operators, that creates both an
opportunity and a challenge. The opportunity is clear: beer, wine, and spirits can be one of the most productive categories in the store. The challenge is that it no longer runs on autopilot.
If you look at the category today, a few shifts stand out.
First, there has been a steady move toward premiumization. Customers are trading up—not across the board, but often enough that it matters. Whether it’s a higher-end THC beverage, a better wine, or a recognizable imported beer, shoppers are showing a willingness to spend a little more if the product feels worth it.
Second, the growth of ready-todrink (RTD) beverages has reshaped the set. What started as a niche has become a major part of the category. Spirit-based RTDs, in particular, have expanded rapidly, bringing in customers who may not have traditionally purchased spirits in a convenience setting.
You’re seeing products like High Noon, Cutwater, and other spirit-based canned cocktails perform alongside traditional beer, not
instead of it. This fact changes how space should be allocated and how products are grouped.
Third, variety matters more than it used to. Customers still expect to find the core brands, but they also expect some level of discovery. It doesn’t mean turning your store into a specialty shop, but it does mean being intentional about offering a mix that feels current.
Many operators seem to underestimate how quickly customers notice when a set feels outdated.
One of the more common patterns in stores is over-reliance on a narrow group of high-volume SKUs. It’s understandable because these products drive turns, and turns matter.
But there’s a point where adding more of the same stops adding value.
A stronger approach is to think in terms of balance:
- Core products that drive consistent volume
- Recognizable premium brands that trade customers up
- A small number of newer or trending items that keep the set relevant
For example, in beer, that might mean maintaining your top domestic packages while carving out some space for a few strong craft or import options that have proven demand in your market.
In spirits, it could mean going beyond just the entry-level price points and including a handful of well-known premium brands, par-
ticularly in high-growth categories like tequila and bourbon.
This is also where a good distributor relationship becomes more than just logistics. Partners like United Distributors are working across thousands of accounts and can often see patterns forming before they become obvious in a single store’s data. Used the right way, the insight can help operators make better decisions without overextending inventory.
Execution inside the store still plays a bigger role than many operators expect.
A few practical observations that consistently make a difference:
- Products that are easy to shop
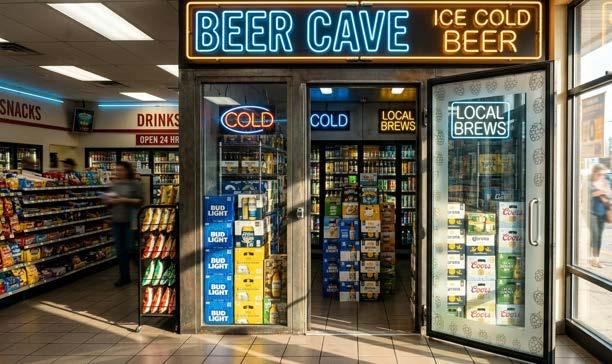
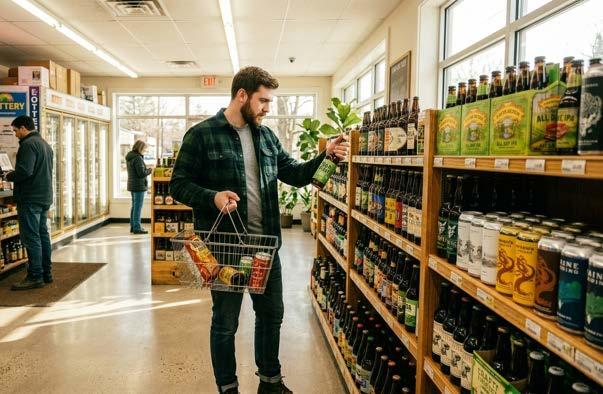
tend to sell better. It sounds obvious, but cluttered or inconsistent sets create friction. Clear segmentation—beer, wine, spirits, RTDs— helps customers find what they want quickly.
- Cold space should reflect actual demand, not just a store’s habit. In many stores, space allocation hasn’t kept up with the growth of RTDs or premium single-serve options.
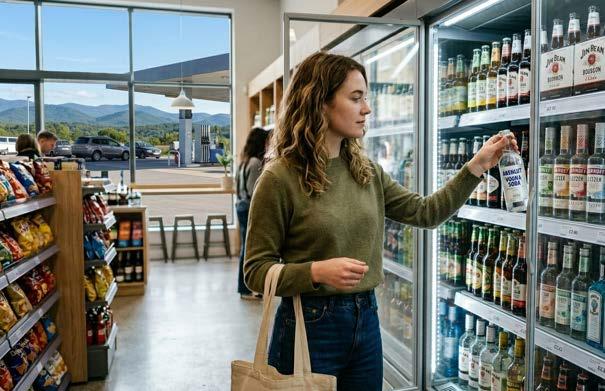
- Placement matters. Eye-level positioning in the cold vault is some of the most valuable real estate in the store. Using that space intentionally, rather than letting it default, can lift sales without adding a single SKU.
- Cross-merchandising is often underused. Simple adjacencies, like placing mixers near spirits or salty snacks near beer, can increase basket size in a way that feels natural.
None of these require a full reset.
They’re small adjustments, but they add up.
Unlike most other categories in the store, alcohol comes with a layer of complexity that can’t be ignored.
Regulations vary by state and locality, and they change over time. In Georgia, for example, rules around Sunday sales, package sizes, and licensing have evolved, and operators need to stay current to avoid costly mistakes.
Age verification is another area where consistency matters. Training staff to follow the same process every time protects the business and builds a culture of accountability.
Shrink and theft can also be a concern, particularly with higher-value spirits. Store layout, visibility, and in some cases locked displays all play a role in managing that risk without making the shopping experience feel restrictive.
These aren’t the most exciting parts of the category, but they are part of running it well.
One of the advantages convenience stores have is proximity. You’re serving the people who physically walk into your store every day. Local insights can be very valuable because of this.
The mix that works in Alpharetta
may not be identical to what works in another part of the state, and certainly not in another region of the country. Demographics, income levels, and even nearby competition all influence what sells.
That’s another area where paying attention, and asking questions, pays off. What are customers asking for that you don’t carry? What products are moving faster than expected? What’s sitting longer than it should?
Over time, these observations are often more useful than any national trend report.
Looking ahead, a few trends are likely to continue shaping beer,
wine, and spirits in convenience:
- Continued growth in RTDs, especially spirit-based options
- Ongoing strength in tequila and American whiskey
- Increased interest in premium and “better for you” products (including low- and no-alcohol alternatives)
- More crossover between categories, with products that don’t fit neatly into traditional definitions
At the same time, value is not going away. Even as some customers trade up, others are paying closer attention to price. A successful set needs to accommodate both.
It can be helpful to step back and look at the category with a simple
question:
Does the current set reflect how my customers actually shop today?
Not how they shopped five years ago. Not how the store was originally set up. Today.
In many cases, the answer is “partially”, and that’s where the opportunity is.
You don’t need to overhaul everything at once. A few thoughtful adjustments can move the category forward in a meaningful way.
Beer, wine, and spirits will continue to be a core part of the convenience business. Those who treat it as an evolving category, rather than a static one, are most likely to get the full value out of it.



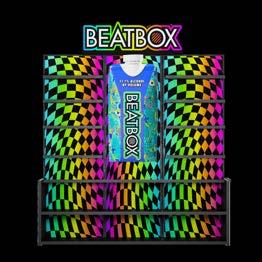
BoldFlavors–15+delicious,nostalgic optionsthatbringthepartytoeverysip.
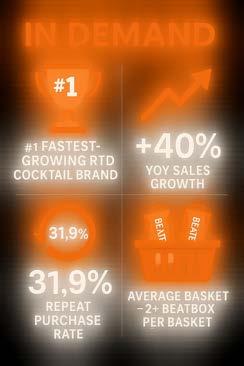
Fastest-SellingintheGame –


High-velocitysalesintheready-to-drinkcategory.
Retail-Proven –Inover135K+stores including7-11,CircleK,Walmart,Krogerandmore.
HighMargin,LowWaste –11.1%ABV witharesealabledesign.
ViralBrand–TikTok,Instagram,Youtubeand +300musicfestivalsandevents.
ShelfAppeal –Bright,boldpackagingthat stopsshoppersintheirtracksin-store.
MultipleSizes-singles,4-pack&6-pack, BigBox3L,Perfectforoneortoshare!





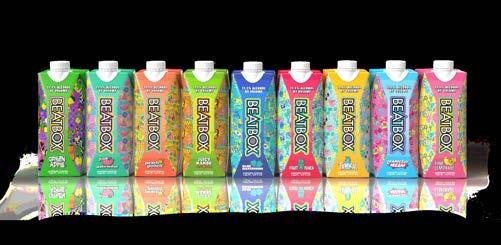
Availablein5,10caseand+displaysizes

Double Salesvelocity when onDisplay
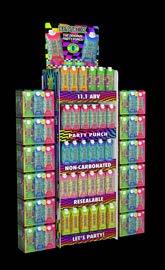
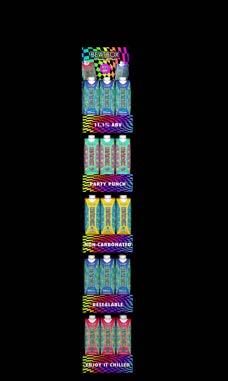
BeatBoxdeliversboldflavors,unstoppableenergy,andserious shelfappeal—builtfortoday’sdrinkersandmadetomovefast.
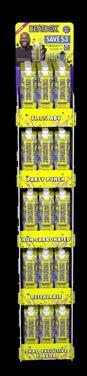
70% ofBeatBox consumer preferBeatBox chilled 95% ofpurchasing decisionsare madebythe subconscious mind




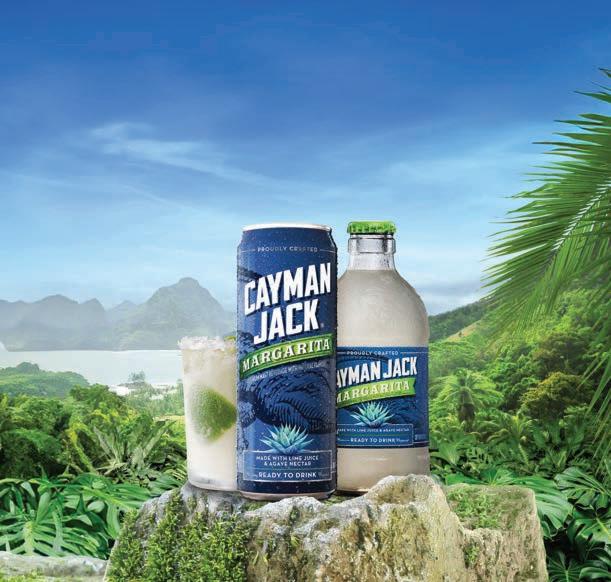

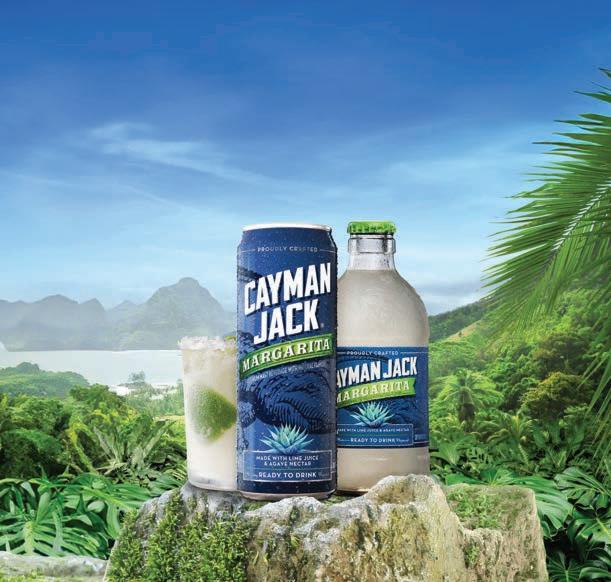
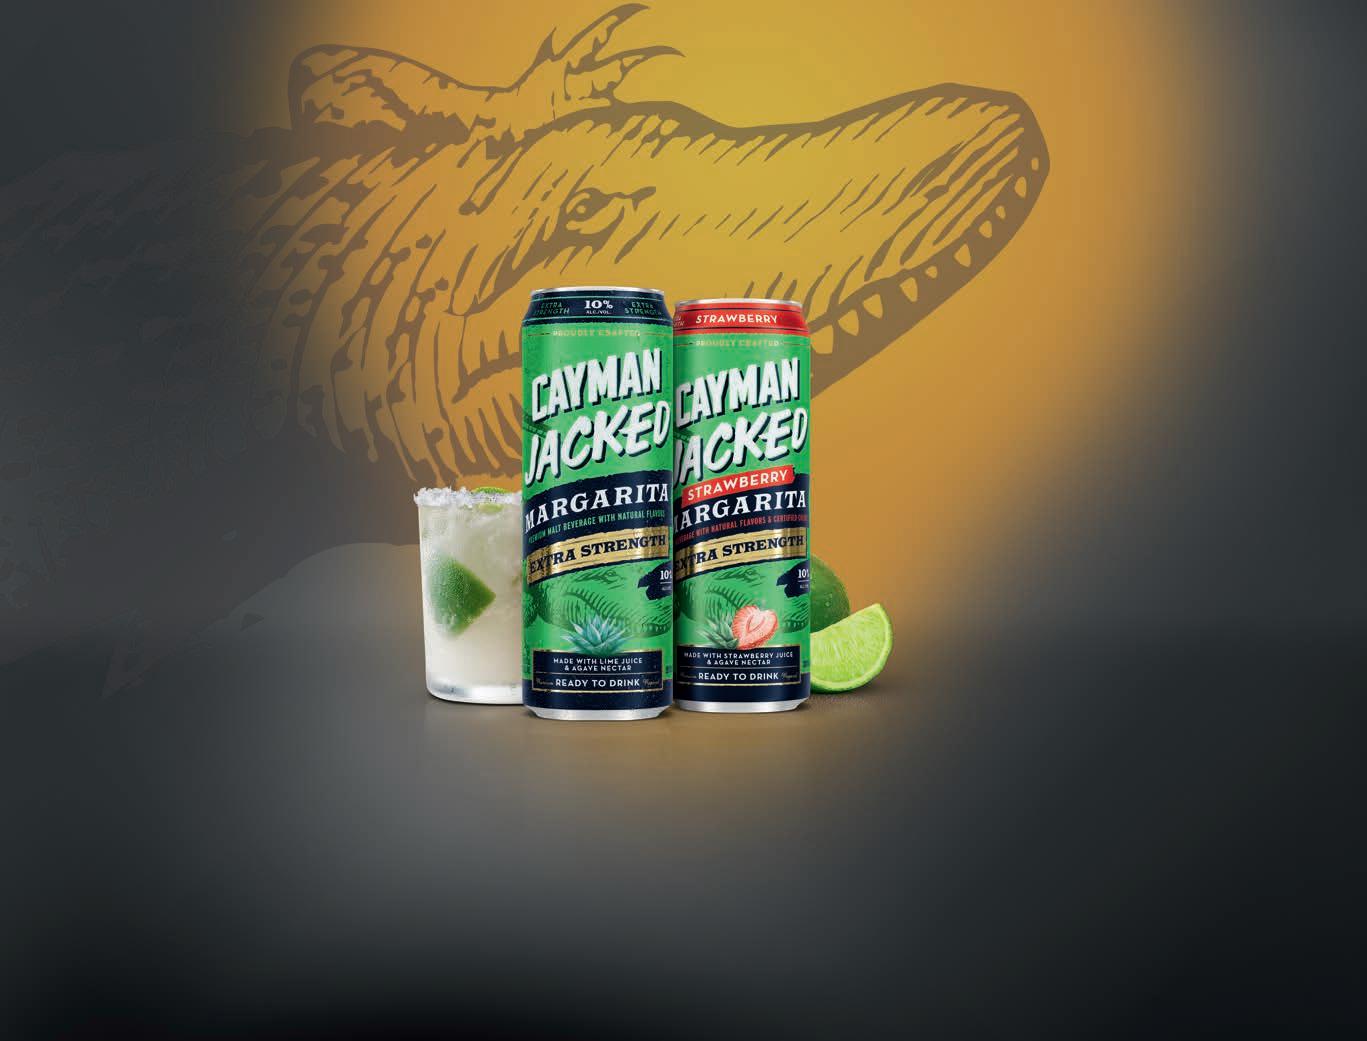
Cayman Jack is the Margarita leader, with the TOP 3 Margarita SKUs in FMB, contributing 58% of all FMB Margarita sales volume! 1
#1 MARGARITA SKU
Cayman Jack Margarita VarietyPack is the #1 MargaritaSKUwithin FMB, with nearly $75MM in annual sales.1
Cayman Jack is growing +20% nationwide, nearly 3X the rate of the FMB segment.1
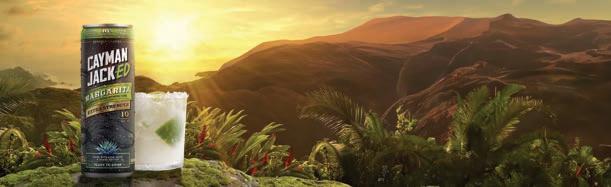
High ABV is having a resurgence and is the largest sub-segment of Convenience, worth $1.3B and growing +4%.1
High ABVconsumers are seeking higher quality, better taste, and flavor adventure –they are searching for broader offerings than basic single flavors or low-quality cocktails.2
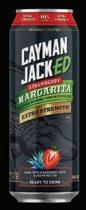
Cayman Jack Classic Margarita single serve is on fire, at +35% growth3 and Cayman Jack Strawberry Margarita single serve is now growing +58% over its launch last year!4 These exceptional flavors translate well to high ABV.





+32% #7
in Georgia Convenience
Year-to-Date
Flavor Brand in Georgia Convenience Year-to-Date

Scan the QR code to view displays available to order or visit our brand support site to place an order today.

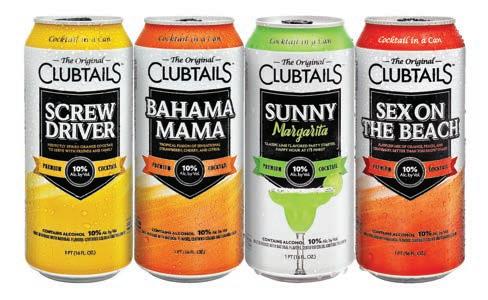













MXD Long Island Iced Tea is driving the category, growing at a rate than competing brands.
Expanding POD distribution has a major impact, stores with multiple PODs are growing more than than those with just one. 25x higher 3x faster
Source: GA Conv CYTD
C-Stores with the top 4 Banquet packs are beating the market by nearly 4 points on total prem reg sales
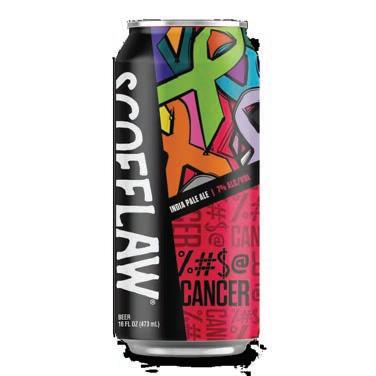
First brewed at Dr. Scofflaw’s, this IPA honors our late partner Scott Selig’s charismatic, tenacious spirit with a bold expression of hops. Scott’s ingenuity created The Works and his memory inspires us daily to fight the good fight. Proceeds from this beer support the Leukemia & Lymphoma Society.
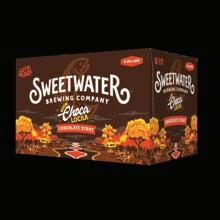
Rotating LTOs available in 6pk-12oz cans for sweater weather: Boom Choca-Locka Chocolate Stout and Festive Ale Winter Warmer
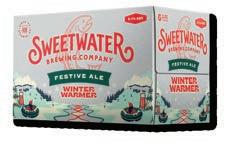
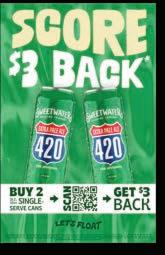
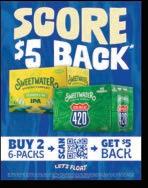
Providing value and increasing customer cart size throughout the season
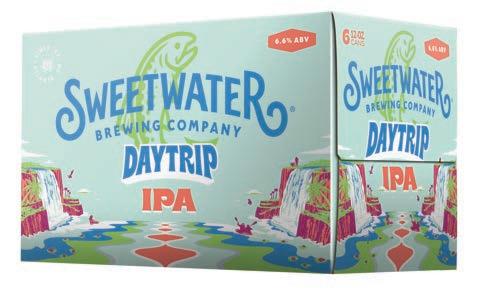
Drift away with this bright, juicy brew and journey to a realm of citrus bliss. Nothing hoppy here – it’s a tropical trip in every sip. Some say this Shangri-la is a myth: an IPA that’s high on refreshment and low on bitterness. But those who know understand. And those who’ve tasted it swear it’s trip worth taking.








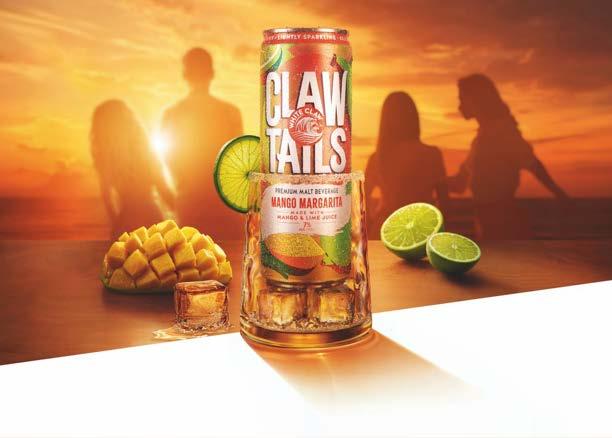
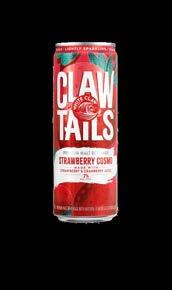
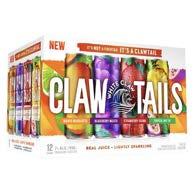
As a single-serve brand, White Claw is the #1 single-serve canned beer brand in the U.S. in 2026!
Surge Singles are leading growth, ranking #1 in growth among all canned beer brands in Georgia Convenience.
Stores carrying a full White Claw single shelf (8+ SKUs) are seeing 4x higher growth rates on White Claw than stores that don’t.*





the strong, juicy flavor of a ripe mango, fused with light tropical notes and a creamy mango finish.
AMINO ACIDS CAMU CAMU CAFFEINE