Market Research Report · ICT & Media
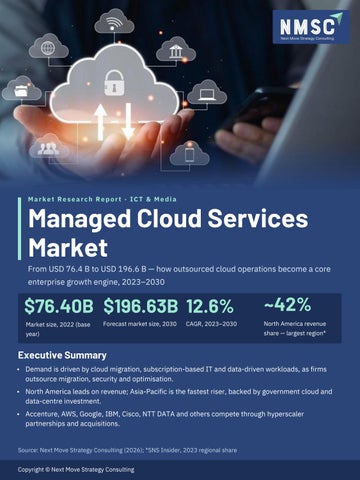
Managed Cloud Services Market From USD 76.4 B to USD 196.6 B — how outsourced cloud operations become a core enterprise growth engine, 2023–2030
$76.40B $196.63B 12.6% Market size, 2022 (base
Forecast market size, 2030
CAGR, 2023–2030
year)
~42% North America revenue share — largest region*
Executive Summary • Demand is driven by cloud migration, subscription-based IT and data-driven workloads, as firms outsource migration, security and optimisation. • North America leads on revenue; Asia-Pacific is the fastest riser, backed by government cloud and data-centre investment. • Accenture, AWS, Google, IBM, Cisco, NTT DATA and others compete through hyperscaler partnerships and acquisitions.
Source: Next Move Strategy Consulting (2026); *SNS Insider, 2023 regional share Copyright © Next Move Strategy Consulting
Managed Cloud Services Market
Market Landscape USD 196.6 B by 2030 — a 2.6x expansion at 12.6% CAGR Global market size, USD billion
Report value
Implied at 12.6% CAGR
196.6 174.6
76.4
2022
108.6
96.5
85.7
2023
2024
2025
122.3
2026
137.7
2027
155.1
2028
2029
2030
Market share snapshot — leading segment in each dimension (2023)*
42%
64%
64%
32%
North America largest region
Public cloud largest deployment
Large enterprises largest buyer group
Security services largest service type
Industry ecosystem — how value flows Cloud platforms Public, private & hybrid infrastructure
›
Service providers
Managed services
End users
IT services firms, MSPs,
Security, network,
BFSI, healthcare, IT &
network vendors
›
infrastructure, mobility, business, collaboration
›
telecom, retail, government
• Investors: the market adds ~USD 120 B in new annual revenue between 2022 and 2030. • Strategy teams: security services already hold the largest service share — the natural anchor for bundled offers. • B2B buyers: managed services cut in-house IT workload through migration, maintenance, compliance and disaster-recovery support. • Tailwind: public cloud end-user spending is forecast at USD 723.4 B in 2025, up 21.5% (Gartner). Source: Next Move Strategy Consulting; *SNS Insider (2023 shares); Gartner (Nov 2024). 2023–2029 bars interpolated. Copyright © Next Move Strategy Consulting
Managed Cloud Services Market
Growth Drivers & Opportunities Cloud migration and data-driven IT are compounding demand; private cloud, SMEs and APAC grow fastest Demand drivers • Rising cloud adoption, especially in North America and Asia-Pacific
• Demand for cloud migration and subscription-based, on-demand IT • Big data, analytics and PaaS lifting cloud storage needs • Cyber threats and GDPR / HIPAA compliance pushing managed security
Growth opportunity map — today's leader vs. tomorrow's fastest riser* Dimension
Largest share (2023)
Fastest CAGR (2024–2032)
Region
42%
N. America
16.3%
Asia-Pacific
Deployment
64%
Public
16.1%
Private
Enterprise
64%
Large
15.7%
SMEs
Vertical
26%
BFSI
19.3%
Government
Service
32%
Security
18.1%
Mobility
Regional opportunities
North America
Asia-Pacific
India & China
Largest
Fastest
Emerging
Public cloud uptake, higher IT
China's 2021 plan expands
Rising cloud use and public /
spending and home to major
investment in cloud, AI and data
private infra investment open new
providers
centres
demand
Source: Next Move Strategy Consulting; *SNS Insider segment shares & CAGRs Copyright © Next Move Strategy Consulting
Managed Cloud Services Market
Competitive Scenario Hyperscalers, global IT services firms and network vendors compete through partnerships and M&A Competitive positioning matrix (illustrative)
Hyperscalers Own platforms; scale via partner
Infra owners
Full-stack leaders
infrastructure
Ownership of cloud infrastructure →
AWS Microsoft HPE
ecosystems and AI-ready
IT services firms Migration, integration and lifecycle
Cisco
IBM
management across clouds
Ericsson Accenture Rackspace
NTT DATA
Managed network, security and Capgemini
Cloudnexa
Network vendors hybrid infrastructure
Infosys · TCS · Wipro
Datacom
Specialists
Service integrators
Specialist MSPs Focused multicloud operations for
mid-market clients
Breadth of managed-service portfolio →
Key strategic moves — partnerships, launches and M&A Feb 2020
Oct 2021
Jan 2024
Dec 2024
Partnership NTT DATA signs 3-year
Partnership Wendy's adopts Google
Acquisition Accenture completes
Expansion IBM partners with AMD
strategic deal with AWS
Cloud analytics, AI/ML
Navisite deal, adding
to offer MI300X
to speed cloud
and hybrid tools
~1,500 cloud
accelerators on IBM
professionals
Cloud
transformations
• Profiled leaders: Accenture, Google, Cisco, Cloudnexa, Ericsson, IBM, AWS, Rackspace, Capgemini, NTT DATA, Infosys.
• Hyperscaler alliances are the main route to scale; M&A adds cloud talent and capacity. • Differentiation is moving to AI-ready infrastructure, security and multicloud operations. Source: Next Move Strategy Consulting; SNS Insider. Matrix based on business model, not market share. Copyright © Next Move Strategy Consulting
Thank You Connect with our analysts for in-depth market insights, custom data and strategic guidance on the Managed Cloud Services market.
Website
www.nextmsc.com
Phone
+1 857 758 5017
info@nextmsc.com
Click here for the complete report→
Click here for the complete report→ Follow Us
Copyright © Next Move Strategy Consulting
YouTube