Equipping the actuaries of tomorrow

Equipping the actuaries of tomorrow
The LSESU Actuarial Society is the largest actuarial student society in London. Throughout the years, our society has built upon its successes and advanced our mission to educate the actuaries of tomorrow Education and connection are the key value proposition that the LSESU Actuarial Society brings to its members As part of our broader strategy of looking into the future, we strive towards providing more professional development resources, opportunities, and actuarial insights for our members. Additionally, we seek to expand our coverage on emerging actuarial trends by hosting diversified events to further extend our reach on topics outside of the traditional actuarial professions.
We organise talks and workshops to raise commercial awareness among our members about pensions and insurance while exploring the way actuaries respond to challenges in this ever-evolving world with endless possibilities. There are various opportunities to ask seniors and alumni about their experiences working in actuarial placements, and providing members with advice about internships is also one of the great services our society can offer.
Additionally, we host networking events that connect students directly with industry professionals, providing them with the opportunity to foster relationships that are essential for career development We are committed to providing our members with memorable experiences and insights about Actuarial Science, and most importantly, ‘Equipping the Actuaries of Tomorrow’ .
To highlight some key successes from the 2024-2025 academic year, we proudly hosted our 12th annual Actuarial Conference at LSE, featuring the President of the Institute and Faculty of Actuaries (IFoA) as a distinguished guest. Additionally, we successfully organised our 3rd Actuarial Case Competition, supported by our sponsors and partners.
This academic year, the research division will be responsible for releasing a newsletter to members and non-members of the society Our members will get exclusive access to the newsletter a few days before public release and access to exclusive stories
Green economies aim to deliver economic growth while reducing emissions, improving resource efficiency, and supporting social equity - objectives captured in UNEP's (United Nations Environment Programme) definition With clean-energy investment hitting $1 8 trillion in 2023 (BloombergNEF), the global economic landscape is undergoing rapid restructuring This transformation represents a profound reorganisation of labour, supply chains, and social priorities Successfully navigating this new, complex risk landscape demands a strategic integration of finance, technology, and policy, elevating the role of actuaries as indispensable experts in managing long-term uncertainty
Green Investment & Economic Transformation
Global Investment Trends
Seizing the economic potential of green economies depends on large-scale capital mobilisation Cleanenergy investment must triple by 2030 to align with global pathways (IEA) Growth sectors such as solar, wind, EV manufacturing, sustainable finance, and resource-efficient infrastructure are becoming central drivers of global competitiveness. At the same time, traditional industries face structural risks The MIT Energy Initiative warns that fossil-fuel producers risk trillions in stranded assets, reflecting the financial consequences of shifting global growth models These dynamics highlight how building green economies reshapes investment patterns, alters asset valuations, and redefines long-term economic resilience, with new vulnerabilities tied to physical resource constraints
Economic Opportunities & Labour-Market Reconfiguration
The green transition is a major job creator, with cleanenergy sectors employing 13.7 million people globally (IRENA) and driving productivity and innovation. However, it simultaneously creates a complex labour reconfiguration, where growth in new industries coexists with job displacement in legacy sectors This geographic and skills mismatch is a core economic challenge, requiring precise demographic modelling to manage migration, reskilling, and social impacts
Actuarial Applications
Actuaries support green-economy investment through:
- Scenario modelling of long-term asset performance as economies transition.
- Monte Carlo simulations capturing volatility in greensector returns.
- Labour & Demographic Transition Modelling: Using demographic data to project skill gaps, regional migration patterns, and the long-term fiscal impacts on pension systems arising from sectoral shifts
- Mineral Supply-Chain Stress Testing: Incorporating correlated risks of critical mineral price volatility and supply disruptions into long-term project financing and insurance models Their ability to quantify long-range uncertainty makes them essential for investors, governments, and insurers navigating the risks and opportunities of green-economy growth
Actuarial Limitations
Modelling green-economy transitions is complicated by limited historical data for new labour markets and mineral-dependent industries, uncertain future policy environments, and complex interactions between markets, climate impacts, and technology adoption. Traditional actuarial tools struggle with systems undergoing this structural change
Building green economies requires large-scale deployment of renewable electricity, storage systems, and digitally optimised grids. The emphasis is shifting from simply generating clean power to designing resilient, flexible systems capable of supporting new industrial activity and future economic expansion
The Critical Mineral Bottleneck: A Foundational
A central constraint for this expansion is the availability of critical minerals - lithium, cobalt, graphite, and rare earth elements Demand is projected to grow from 4 7 million tonnes in 2022 to 30 million tonnes by 2030, a sixfold rise Such bottlenecks determine which technologies can realistically scale, shaping the industrial foundations of future green economies and introducing volatile input costs and project delays into core risk assessments.
Building green economies requires large-scale deployment of renewable electricity, storage systems, and digitally optimised grids. The emphasis is shifting from simply generating clean power to designing resilient, flexible systems capable of supporting new industrial activity and futureeconomic expansion
The Critical Mineral Bottleneck: A Foundational Risk
A central constraint for this expansion is the availability of critical minerals - lithium, cobalt, graphite, and rare earth elements Demand is projected to grow from 4 7 million tonnes in 2022 to 30 million tonnes by 2030, a sixfold rise. Such bottlenecks determine which technologies can realistically scale, shaping the industrial foundations of future green economies and introducing volatile input costs and project delays into core risk assessments.
Actuarial Applications
Actuaries contribute by:
- Underwriting large-scale green infrastructure projects, integrating mineral supply scenarios
- Designing weather-triggered parametric insurance products
- Building operational-risk models for emerging technologies that account for correlated supplychain failures.
These tools strengthen financial stability as economies increasingly depend on new and evolving infrastructures.
Actuarial Limitations
Changing climate patterns reduce the reliability of catastrophe models Sparse long-term data on emerging technologies, further complicated by resource volatility, limits actuarial precision
Social & Ethical Imperatives: The Core of Green Economy Building
A central pillar of green-economy construction is justice Intergenerational equity ensures that future populations are not burdened by today’s decisions. Social equity prevents vulnerable communities from bearing disproportionate costs through job loss, rising energy bills, or economic restructuring. A fair transition protects societal cohesion and strengthens public support for long-term green-economy development
Demographic Modelling for an Inclusive Pathway
The labour market shifts have stark demographic implications A just transition requires anticipating which groups are most vulnerable This is a precise modelling exercise Analysing demographic dataage structures, skill bases, regional economic dependencies - allows for the targeted design of reskilling programs, relocation support, and social safety nets.
Building green economies globally requires coherent international financial support Developing nations need an estimated $2 4 trillion per year by 2030 for mitigation and adaptation Without coordinated supplychain cooperation, technology transfer, and adaptation funding, the global green-economy transition risks deepening inequality and economic fragmentation
Actuarial Applications
Actuaries strengthen a just transition by using models to ensure equity and resilience. They analyse the financial impact of policies on different demographic groups to guide fair compensation, design accessible insurance for vulnerable communities, and forecast labour-market shifts to plan for reskilling and public finance needs This work is crucial for building a green economy that is both socially equitable and economically sound
Actuarial tools have difficulty quantifying ethical dimensions such as fairness, community well-being, or long-term justice Data scarcity in developing regions limits modelling accuracy, and complex socio-economic consequences - employment shocks, migration flows, social disruption - extend beyond traditional actuarial practice, requiring interdisciplinary collaboration
Building green economies is a complex undertaking that hinges on financial, technological, and social innovation Within this transformation, actuaries have become central for assessing long-term systemic risks - from labour shifts and mineral shortages to demographic changes Their expertise in scenario modelling and impact analysis is essential to ensure the transition is environmentally sound, economically resilient, and socially equitable.
The energy transition refers to the global shift from fossil fuels to low-carbon energy sources such as renewables, hydrogen, and nuclear power. It stands at the core of the global response to climate change, as the energy sector is responsible for roughly 75% of worldwide greenhouse gas emissions The success of this transition depends not only on technological innovation and policy reform but also on sophisticated risk assessment and financial modeling - areas where actuarial science plays a vital role Actuaries, skilled in quantifying uncertainty and modeling long-term financial outcomes, are increasingly central to ensuring the energy transition remains both economically viable and sustainable.
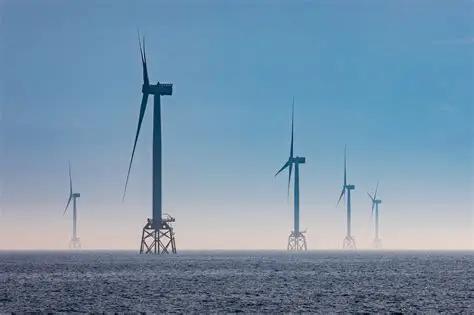
Achieving net-zero emissions by 2050 requires unprecedented financial and structural transformation. The International Energy Agency (IEA) projects that annual global energy investment must increase from current levels to about US$4 trillion per year by 2030more than triple present figures - to meet the net-zero target. This magnitude of capital mobilisation signifies a historic reallocation of global financial resources, demanding rigorous modelling of investment risk, longterm returns, and capital adequacy
The shift toward renewable infrastructure - such as offshore wind farms, solar parks, and large-scale battery storage - introduces a new spectrum of insurable risks
These technologies often lack sufficient operational history, making it challenging to develop reliable loss distributions for pricing and capital modelling. In addition, new renewable installations are exposed to evolving risks such as technology malfunction, weather variability, and regulatory shiftsThe protection gap - the difference between economic and insured lossesremains a major concern. In 2024, only 43% of global economic losses from natural catastrophes were insured, representing US$137 billion in insured losses compared to US$318 billion in total economic damages This underlines the need for innovative actuarial solutions to enhance climate and energy insurance coverage.
Actuaries are adapting to this emerging landscape by developing loss frequency–severity models tailored to renewable energy systems. Where empirical data are limited, Bayesian credibility models combine prior knowledge with emerging claims data to improve premium adequacy In addition, actuaries are instrumental in the design of parametric insurance, which provides rapid payouts based on measurable environmental triggers - such as wind speed, rainfall, or solar irradiance - rather than traditional damage assessments They construct stochastic models of these environmental variables using historical and climate-projected data to estimate payout probabilities and required reserves. Beyond pricing, actuaries perform climate catastrophe modelling to assess aggregate risk exposures from extreme weather events
Even with new tools and models, actuaries face real limits when working with renewable energy risks. The biggest challenge is simply the lack of reliable data many technologies are new, so there isn’t a long history of claims to learn from Climate patterns are also becoming less predictable, making it harder to build stable catastrophe models. And although parametric insurance is useful, it comes with basis risk, meaning payouts might not perfectly match actual losses These constraints mean actuarial work can guide decision making, but it cannot remove the uncertainty that comes with a fast-changing energy system.
Despite its potential, global low-carbon hydrogen production was under 1 million tonnes in 2023, representing only about 2% of total hydrogen output However, projects currently under development could expand capacity to 49 million tonnes by 2030 if all materialise . Hydrogen’s energy density and volatility also introduce new physical risks. It carries a higher explosion risk than natural gas, prompting insurers like Lloyd’s to begin quantifying these exposures in largescale hydrogen systems
According to the IEA’s Net Zero by 2050 scenario, hydrogen is expected to supply 10% of total final energy demand by 2050, up from less than 1% today. In the UK, the government’s Hydrogen Strategy targets up to 10 GW of low-carbon hydrogen production capacity by 2030 - a scale that will require extensive investment, risk management, and actuarial oversight.
Actuaries support hydrogen development through detailed project risk quantification Using Monte Carlo simulations, they model potential cost overruns, construction delays, and policy-driven subsidy variations to estimate expected returns and tail losses. Real options analysis - a technique borrowed from financial modelling; allows actuaries to quantify the value of managerial flexibility, such as deferring or expanding hydrogen production based on evolving market signals In insurance applications, actuaries design liability covers for hydrogen projects, pricing risks of explosion, leakage, and environmental contamination through compound Poisson–exponential models They also assess long-term project solvency by calculating Conditional Tail Expectation (CTE) metrics, ensuring sufficient capital allocation for extreme but plausible loss events. This actuarial precision allows both investors and insurers to confidently engage in hydrogen’s emerging market despite its uncertainty
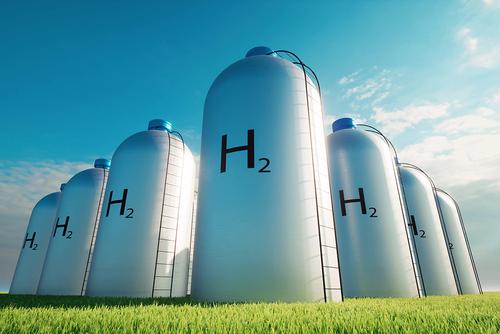
Hydrogen presents even more uncertainty. Because large-scale projects are only just emerging, actuaries have very little past experience to draw on. Much of the modelling relies on assumptions from engineers or early pilot projects, which naturally increases uncertainty Hydrogen also behaves differently from conventional fuels, and current databases don’t fully capture these risks. Add in shifting government subsidies and evolving regulation, and it becomes clear that actuarial estimates for hydrogen are helpful but still less reliable than those in more established sectors
Instruments like the UK Emissions Trading Scheme (ETS) create financial incentives for emissions reduction across power, industry, and transport sectors Mechanisms such as Contracts for Difference (CfD) guarantee revenue stability for low-carbon electricity producers, fostering private investment. Additionally, legally binding carbon budgets and sectoral emission targets ensure progress toward national and international climate goals
Actuaries play a growing role in climate policy analysis and regulation They model the long-term fiscal impacts of energy transition policies, assess redistributive effects of carbon pricing on households, and estimate how decarbonisation might influence pension fund liabilities or insurance affordability
Through climate scenario modelling, actuaries quantify both physical risks (e.g., flood, drought, storm intensity) and transition risks (e.g., policy shifts, asset revaluations) within financial systems. They also design disclosure and stresstesting methodologies consistent with frameworks such as the Task Force on Climate-related Financial Disclosures (TCFD). These actuarial insights provide governments, regulators, and investors with measurable indicators to guide ethical and economically balanced policy.
In climate policy work, actuaries face limitations because many of the variables they model are shaped by political and social decisions rather than stable financial patterns. For example, the future price of carbon under the UK ETS (UK Emissions Trading Scheme), or the long-term cost of Contracts for Difference, depends on government behaviour that cannot be forecast using traditional actuarial methods Similarly, modelling how carbon taxes affect household spending or pension liabilities requires assumptions about consumer behaviour and wage responses that are difficult to validate Scenario analysis helps, but these scenarios often rely on broad narratives rather than measurable probabilities. As a result, actuarial models can highlight the financial implications of policies, but they cannot fully account for the policy volatility, behavioural shifts, and macroeconomic feedback effects that shape the real-world outcomes of energy transition regulation
The energy transition represents not just a technological evolution but a systemic financial transformation. Its success relies on the alignment of global investment, insurance innovation, and ethical policy - domains where actuarial science provides critical analytical strength From pricing renewable risks and evaluating hydrogen investments to modelling carbon storage liabilities and assessing policy fairness, actuaries translate uncertainty into measurable financial outcomes Their models help societies allocate capital efficiently, protect against emerging risks, and ensure that the path to net zero remains both financially sound and socially just.
Between 2027 and 2030, four major regulatory changes will reshape how actuaries approach UK pension scheme work These reforms provide major challenges for actuaries, requiring new methods and the expansion of actuarial services in both defined benefit and defined contribution sectors
Inheritance tax on pensions
CURRENT SYSTEM (until April 2027): Unused pension pots are not part of your estate for inheritance tax (IHT), meaning they typically pass to beneficiaries without being taxed as part of the inheritance.
NEW SYSTEM (from April 2027): Most unused pension funds and death benefits WILL be included in estates for inheritance tax (IHT) purposes, making them taxable for beneficiaries as part of the overall estate. LCP estimates government revenue over two decades could exceed £40 billion Tim Camfield describes the process as a complex five-stage framework Pension scheme administrators are required to provide valuations within four weeks of death notification, with peak annual revenue estimated at £3 billion LCP recommends that trustees adopt policies on voluntary scheme pays elections for IHT liabilities of £4,000 or more Hyman argues that the six-month reporting deadline is "unrealistic" and recommends a 12-month deadline Their analysis reveals that defined benefit (DB) spouse and dependant pensions will not be subject to inheritance tax (IHT) As a result, DB pensions become a more attractive vehicle for passing on wealth compared with defined contribution (DC) retirement income Barnett Waddingham warns that urgent valuations of self-invested personal pensions (SIPP) and small self-administered schemes (SSAS) with illiquid assets will increase external valuation fees. However, the October 2026 Pensions Dashboard rollout may help locate deceased members' pensions.
CURRENT SYSTEM (until April 2029): Unlimited amounts of salary can be sacrificed for pension contributions with full exemption from both employer and employee National Insurance Contributions (NICs) NEW SYSTEM (from April 2029): Only the first £2,000 of employee contributions via salary sacrifice will be exempt from National Insurance Contributions (NICs) Amounts above £2,000 are subject to 15% employer NICs and 8% employee NICs.
The OBR estimates this affects 3.3 million workers and will raise £4.7 billion in 2029/30. LCP's Alasdair Mayes warns the cap "will kill off bonus sacrifice" as the £2,000 annual cap becomes £167 monthly. Sir Steve Webb suggests delayed implementation creates restructuring opportunities and predicts revenue "will only raise a fraction of the amount expected" . Barnett Waddingham's Mark Futcher states this "removes one of the most effective ways people boost their pension savings With adequacy levels already worryingly low, this change will hit average earners hardest" Technical analysis shows that an employee earning £50,000 who sacrifices 5% faces £40 in additional employee NICand £75 in employer NIC annually XPS Group warns this "risks impacting levels of pension saving" Industry research found 38% of workers would save less if capped AJ Bell modelling shows a 35-year-old earning £100,000 could see their pension pot £49,682 lower by age 65
Hymans Robertson's Laura McLaren notes the Pension Schemes Bill "leaves much of the detail to regulations." This includes minimum funding conditions (rules on how much pension schemes must hold relative to their liabilities) and the format of required actuarial certification (the specific way actuaries must formally approve or confirm pension funding levels) XPS Group shows an approximate surplus of £176 billion on long-term targets Partner Danny Vassiliades emphasises: "Any role played by DB (Defined Benefit) schemes in support of wider UK growth must not risk the hard-won security of members' benefits " An XPS survey found 76% of trustees intend to adopt the new statutory override (a legal provision that allows trustees to change scheme rules even without member or employer agreement)
The Pensions Regulator states: "A scheme may be materially overfunded for a long period Without a plan to distribute excess funding, this may not align with prudent risk management for members or the sponsor, and may indicate weak governance controls " New actuarial services include surplus extraction policy frameworks, low- dependency funding calculations, actuarial certification for surplus payments, and scenario stress testing for regulatory submissions.
Between 2027 and 2030, four major regulatory changes will reshape how actuaries approach UK pension scheme work. These reforms provide major challenges for actuaries, requiring new methods and the expansion of actuarial services in both defined benefit and defined contribution sectors.
CURRENT SYSTEM (until April 2027): Unused pension pots are not part of your estate for inheritance tax (IHT), meaning they typically pass to beneficiaries without being taxed as part of the inheritance
NEW SYSTEM (from April 2027): Most unused pension funds and death benefits WILL be included in estates for inheritance tax (IHT) purposes, making them taxable for beneficiaries as part of the overall estate
This affects approximately £160 billion in aggregate scheme surplus According to Steve Hodder at LCP, this enables what he terms "routine Christmas surplus bonuses " LCP's analysis indicates that the £160 billion low dependency surplus reduces to around £100 billion on a buy-out basis. Hymans Robertson's Laura McLaren notes the Pension Schemes Bill "leaves much of the detail to regulations." This includes minimum funding conditions (rules on how much pension schemes must hold relative to their liabilities) and the format of required actuarial certification (the specific way actuaries must formally approve or confirm pension funding levels). XPS Group shows an approximate surplus of £176 billion on long-term targets. Partner Danny Vassiliades emphasises: "Any role played by DB (Defined Benefit) schemes in support of wider UK growth must not risk the hard-won security of members' benefits." An XPS survey found 76% of trustees intend to adopt the new statutory override (a legal provision that allows trustees to change scheme rules even without member or employer agreement)
IFoA President Paul Sweeting emphasised: "Sustainability is central to impactful pension interventions Mitigating uncertainty is vital to maintaining public confidence " Actuaries are revising DC projection models to integrate NIC effects, developing dual-pathway models for alternative schemes, and modelling member behaviour to predict optout rates
CURRENT SYSTEM (until 2030): Defined contribution (DC) multi-employer schemes can operate at any size. Local Government Pension Scheme (LGPS) assets are managed across 86 separate local authority administering authorities. NEW SYSTEM (from 2030): DC multi-employer schemes must hold at least £25 billion in their main default fund, or £10 billion with a credible plan to reach £25 billion by 2035. LGPS assets must consolidate into six pools. LCP created a co-head of pensions consolidation position for this policy. Partner Laura Myers warns: "The threat of government telling trustees how they should invest is a step too far" .
Hymans Robertson's Robbie McInroy calls the timeline "hazardously ambitious " He notes that less than 50% of LGPS assets were pooled over a 9-year period Yet, the government expects the remaining 50%+ to be pooled by March 2026 Barnett Waddingham's Martin Willis says:
"While scale can bring benefits, it's not a silver bullet Many smaller, well-run schemes already deliver strong outcomes " XPS Group formed a strategic alliance with abrdn to launch the UK's first DB master trust, noting that over 4,000 smallto medium-sized DB schemes with nearly £200 billion in assets could benefit from consolidation The IFoA warns: "Compulsory investment in certain sectors may expose schemes to higher investment risk, costs, reduced liquidity, and lower diversification"
Emerging actuarial workstreams include bulk transfer valuations, Value for Money (VfM) assessments, private market risk modelling, and the management of triennial valuations, all of which are being undertaken in parallel with LGPS consolidation The March 2026 LGPS valuation coincides with pooling deadlines, intensifying resource constraints for actuarial teams
The four reforms present actuaries with a high workload concentration IHT changes and surplus extraction both take effect in April 2027, requiring simultaneous implementation. The megafunds timeline coincides with LGPS triennial valuations, creating resource constraints. Neither the IFoA nor FRC has issued comprehensive standards for actuarial certification for surplus extraction or IHT death benefit valuations. The consulting landscape is consolidating, creating larger entities but potentially reducing choice for actuarial professionals. Actuaries must develop new capabilities to respond to regulatory changes across the DB and DC sectors
Insurance is a system for sharing financial risks. By collecting premiums from many people exposed to similar risks, insurers can provide compensation to those few who actually suffer a loss. The question of how much each policyholder should pay is fundamental in insurance practice and actuarial science. Setting premiums too high makes insurance unaffordable; setting them too low puts the insurer at risk of being unable to meet its obligations.
In actuarial work, the net premium (also called the pure premium) is the theoretical amount an insurer should charge, on average, to cover the cost of claims only. It ignores expenses, profit and other business considerations, and is based purely on the mathematical expectation of the future claims. The key idea is that if we know all the possible claim amounts and how likely each one is, we can calculate an average, or expected, claim cost per policy
Suppose that a policy can lead to different possible claim amounts x , x , . . . , x , with corresponding probabilities p , p , . . . , p . The expected claim, and hence the net premium, is defined by 1 2 n 1 2 n
Net premium = E[Claim] = ∑ p x i=1 i i
Here, x represents a possible claim amount in pounds and pi represents the probability that that amount occurs, with ∑ p = 1. This expected value is usually not equal to any single observed claim in a given year, but it represents the long-run average claim per policy if many similar policies are written under the same conditions. i i=1 i
To see how this works in practice, consider a simple example of motor insurance. For a single year, assume that there is a 95% probability of no claim, a 4% probability of a minor claim of £2,500, and a 1% probability of a major claim of £10,000 The expected claim is then
E[Claim] = 0.95 × 0 + 0.04 × 2,500 + 0.01 × 10,000 = 0 + 100 + 100 = £200.
In this case, the net premium is £200 In other words, if the insurer sells a very large number of identical policies under these assumptions, the average claim cost per policy will tend to be close to £200 per year.
This behaviour is explained by the law of large numbers. For any single policyholder, the outcome in a year might be very different from £200: they may have no claim at all, or they may have a large claim. However, when the insurer issues thousands of similar policies, the random highs and lows tend to balance out, and the average claim per policy converges to the expected value This justifies using the expected claim as the net premium It provides a mathematical foundation on which all further adjustments such as expenses, profit and allowances for uncertainty, are built in later sections.
In the previous section, we treated the possible claim amounts as a short list of discrete outcomes with given probabilities. In practice, insurers deal with many policies and a wide range of possible claim patterns To capture this more realistically, actuaries model claims using probability distributions These distributions help to describe two main aspects of risk:
• Frequency: how many claims occur in a given period (for example, per year).
• Severity: how large each claim is when it occurs. By combining a model for frequency with a model for severity, insurers can obtain a more accurate estimate of the expected total claims and therefore a more reliable basis for premium calculation.
In many models, the total claim amount over a period is written as S = X + X + · · · + X , 1 2 N
where:
• N is the random number of claims (for example, Poisson distributed),
• X , X , . . . are the individual claim sizes. 1 2
Under these conditions,
E[S] = E[N] × E[X],
so the expected total claims are the product of the expected number of claims and the expected size of a claim.
From a premium-setting point of view, this means that:
• the net premium per policy can be obtained by dividing E[S] by the number of policies;
• more accurate modelling of both frequency and severity leads to a more realistic expected claim cost and therefore a more appropriate net premium.
This is known as a frequency–severity model Under suitable assumptions, we obtain a simple expression for the expected total claims.
The assumptions are:
• the claim sizes X , X , are independent and identically distributed, 1 2 each with mean E[X];
• the claim sizes X are independent of the claim count N i
Up to this point, we have implicitly assumed that the insurer pays the full amount of any claim. In practice, many insurance policies include features that share or cap the cost of claims Three common features are deductibles, policy limits, and coinsurance These terms directly affect the amount the insurer pays when a loss occurs, and therefore they also affect the expected claim cost and the premium.
A deductible (sometimes called an excess) is an amount which the policy-holder must pay out of their own pocket before the insurer pays anything.
If we let X denote the original claim amount and d the deductible, then the insurer’s payment can be written as
Insurer payment = max(X d, 0).
A policy limit places an upper bound on the amount the insurer will pay for any single claim. If L is the limit, the insurer’s payment is
Insurer payment = min(X, L).
A policy limit places an upper bound on the amount the insurer will pay for any single claim. If L is the limit, the insurer’s payment is
Insurer payment = min(X, L).
Under coinsurance, the insurer pays only a fixed proportion of each covered loss, and the policyholder pays the remaining proportion. Let c be the insurer’s coinsurance rate (for example, c = 0 8 if the insurer covers 80% of each loss) The insurer’s payment is then
Insurer payment = cX, possibly in combination with a deductible and a limit
All three features reduce the insurer’s share of the claim cost:
• Deductibles remove small claims entirely and reduce the size of larger claims
• Limits cap the maximum amount the insurer will pay.
• Coinsurance shares each loss between insurer and policyholder.
So far, our focus has been on the average cost of claims, leading to the net premium. However, insurance is not only about averages; it is also about uncertainty. In some years, total claims will be higher than expected, and in others they will be lower. In this section we introduce variance as measure of risk, explain how pooling many policies reduces uncertainty, and outline the basic idea of credibility, which combines individual and group experience to refine premiums.
The expected value of a claim tells us the average cost, but it does not describe how widely individual outcomes are spread around this average.
To quantify this spread, we use the variance of a random variable If X is a claim amount with mean μ = E[X], its variance is
Var(X) = E[(X − μ) ]2
A higher variance means that outcomes are more spread out and there is greater uncertainty about what will actually happen. For an insurer, this translates into greater risk that actual claims in a given year could be much higher than the expected value.
If S = X + X + · · · + X denotes the total claims from n independent policies, each with the same variance σ , then 1 2 n 2
Var(S) =∑ Var(Xi) = nσ i=1 2
Although the variance of the total S grows with n, the variance of the average claim per policy, x = S/n , is Var(X) = Var(S/n) = 1/n Var(S) = σ^2 2
Thus, as the number of policies n increases, the variance of the average claim per policy decreases. This is a mathematical expression of the idea of risk reduction through pooling.
The law of large numbers tells us that, as the number of independent, identically distributed risks increases, the sample average converges to the expected value In insurance terms, if an insurer writes a large portfolio of similar policies:
• the average claim per policy becomes more predictable;
• actual experience is less likely to deviate dramatically from the net premium
This justifies the whole concept of insurance: by pooling many risks, the insurer can transform individual uncertainty into a relatively stable average, and can base premiums on expected values with some confidence
Nevertheless, even with pooling, there remains uncertainty, particularly for rare but severe events. Insurers therefore often include a risk margin within the loading component of the gross premium to provide a buffer against adverse experience.
In practice, insurers do not rely only on overall averages They also use information about individual policyholders or subgroups. Credibility theory provides a systematic way to combine:
• an individual estimate of expected claims, based on that policyholder’s past experience;
• a group estimate, based on the experience of a wider portfolio of similar risks.
A simple credibility formula for a premium is
Premium = Z × Individual estimate + (1 Z) × Group estimate, where 0 ≤ Z ≤ 1 is the credibility factor.
When Z is close to 1, more weight is given to the individual’s own experience; when Z is close to 0, more weight is given to the group
In one common form, the credibility factor is defined as Z = N/(N+K), where:
• N is a measure of the volume of data for the individual (for example, the number of years of experience or number of claims observed);
• K is a constant representing the amount of data required for “full credibility” .
If N is small compared to K, then Z will be small and the individual experience will be given little weight As N increases, Z approaches 1, and the premium will be more heavily influenced by the individual’s actual claims history.
In the UK, the assessment of the “value for money (VFM)” in pensions is undergoing much closer scrutiny, particularly in the case of defined contribution (DC) schemes It is no longer solely about keeping costs low, but also about whether the members are getting good value for what they pay, taking into account costs, investment, and quality. Efforts are also being made to ensure that valuefor-money calculations are comparable, and that poor schemes are encouraged to either improve or merge with better-managed schemes.
Government discussions and reviews reflect a concern for the retirement adequacy of future generations. There is a concern that the younger generation are not saving enough or saving soon enough, and that they will end up worse off in retirement than the current generation of pensioners This has led to questions about whether the current balance of State Pension, auto-enrol schemes and private savings will be enough in the long term.
The second obvious trend is one of consolidation, especially on the DC side. There is an idea that is being pushed by policymakers and advisors, which means there could be fewer and larger schemes or “mega funds” . This could offer the benefits of scale in terms of better governance, lower costs per member, and better access to invest in long-term assets such as infrastructure and private markets.
However, at the same time, there are also questions about competition and member choice. There have been proposals that a number of large schemes could lead to a lack of diversity in the market and more similar solutions that are not appropriate for all members, especially if members are automatically enrolled into similar default solutions.
For defined benefit (DB) schemes, higher interest rates and previous de-risking mean that many are now in much better funding positions than a few years ago As a result, the key question has moved from how to repair past funding gaps to how the scheme should be brought to a long-term conclusion
There has also been rapid growth in buy-ins and buy-outs, where schemes transfer risks such as investment and longevity risk to insurers and effectively close their books. While the surveys suggest that members are generally confident about their pensions, some can still feel unsettled or confused when they hear that their scheme is moving towards buy-out This underlines the importance of clear and careful communication when making decisions for the schemes
DC pensions are now the primary method by which many people save for retirement in the UK In DC schemes, the final pension outcome is contingent on contributions, investment performance, and decisions made at retirement This means that more risk and more responsibility fall on the members themselves, rather than employers or the government.
There is a drive from regulators for DC schemes to show that they provide great value and a realistic income in retirement, rather than just a big “pot” of money on paper However, there is also a concern that many members are saving too little, or taking on too much risk in terms of investment and longevity risk, compared to what they actually understand.
International research such as the Mercer CFA Global Pension Index illustrates that many countries are facing the same issues arising from ageing populations and budget constraints Solutions include increasing retirement ages, promoting more private or occupational savings, and increasingly turning to capital markets for returns
Global reports on pension assets also highlight the themes of scale, diversification, and sustainable investment Large pension schemes are leveraging their scale to invest in infrastructure, private credit and ESG-themed investments, while also seeking to safeguard scheme members’ interests in the process The UK trends in pension consolidation and productive finance for DB schemes are part of this broader international trend
LSESU Actuarial Society’s Research Division
Ze Kai Ng (Research Co-Director)
Ying Zi Tang (Research Co-Director)
Mohammad Abdul Rahim
Jasmine Carpiz
Yichen Chong
Braxton Lim
April Phuan
Hassanal Safiullah
Sylvia Zhu
LSESU Actuarial Society’s Marketing Division
Nirah Rahman (Marketing Director)
Janusmmy Arulchelvan
Luvlynn Bholah
Sienna Singh
Ze Kai Ng (Research Co-Director) - Z.K.Ng@lse.ac.uk
Ying Zi Tang (Research Co-Director) - Y.Z.Tang@lse.ac.uk
Nirah Rahman (Marketing Director) - N.Rahman6@lse.ac.uk
@lsesuactsoc
www.linkedin.com/company/lsesuactsoc lsesuact@gmail.com
Please take a moment to fill in the short anonymous feedback form below. It will help us improve future editions of our newsletter and tailor our content better to you. Thank you! Click here for feedback form