(policy features & benefits may vary by state)
HonestLTC
Policy Type
Individually-Underwritten, Tax-Qualified, Reimbursement
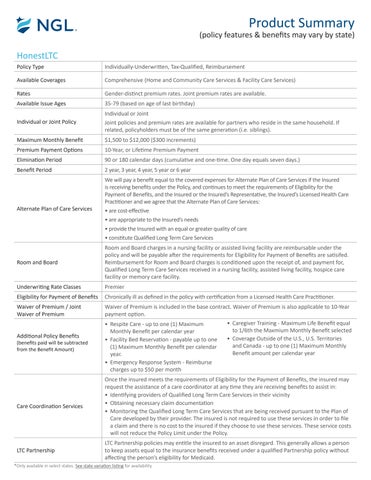
Available Coverages Comprehensive (Home and Community Care Services & Facility Care Services)
Rates Gender-distinct premium rates. Joint premium rates are available.
Available Issue Ages 35-79 (based on age of last birthday)
Individual or Joint Policy
Maximum Monthly Benefit
Individual or Joint
Joint policies and premium rates are available for partners who reside in the same household. If related, policyholders must be of the same generation (i.e. siblings).
$1,500 to $12,000 ($300 increments)
Premium Payment Options 10-Year, or Lifetime Premium Payment
Elimination Period
Benefit Period
Alternate Plan of Care Services
90 or 180 calendar days (cumulative and one-time. One day equals seven days.)
2 year, 3 year, 4 year, 5 year or 6 year
We will pay a benefit equal to the covered expenses for Alternate Plan of Care Services if the Insured is receiving benefits under the Policy, and continues to meet the requirements of Eligibility for the Payment of Benefits, and the Insured or the Insured’s Representative, the Insured’s Licensed Health Care Practitioner and we agree that the Alternate Plan of Care Services:
• are cost-effective
• are appropriate to the Insured’s needs
• provide the Insured with an equal or greater quality of care
• constitute Qualified Long Term Care Services
Room and Board charges in a nursing facility or assisted living facility are reimbursable under the policy and will be payable after the requirements for Eligibility for Payment of Benefits are satisifed.
Room and Board
Reimbursement for Room and Board charges is conditioned upon the receipt of, and payment for, Qualified Long Term Care Services received in a nursing facility, assisted living facility, hospice care facility or memory care facility.
Underwriting Rate Classes Premier
Eligibility for Payment of Benefits
Waiver of Premium / Joint
Waiver of Premium
Additional Policy Benefits
(benefits paid will be subtracted from the Benefit Amount)
Chronically ill as defined in the policy with certification from a Licensed Health Care Practitioner.
Waiver of Premium is included in the base contract. Waiver of Premium is also applicable to 10-Year payment option.
• Respite Care - up to one (1) Maximum Monthly Benefit per calendar year
• Facility Bed Reservation - payable up to one (1) Maximum Monthly Benefit per calendar year.
• Emergency Response System - Reimburse charges up to $50 per month
Care Coordination Services
• Caregiver Training - Maximum Life Benefit equal to 1/6th the Maxmium Monthly Benefit selected
• Coverage Outside of the U.S., U.S. Territories and Canada - up to one (1) Maximum Monthly Benefit amount per calendar year
Once the insured meets the requirements of Eligibility for the Payment of Benefits, the insured may request the assistance of a care coordinator at any time they are receiving benefits to assist in:
• Identifying providers of Qualified Long Term Care Services in their vicinity
• Obtaining necessary claim documentation
• Monitoring the Qualified Long Term Care Services that are being received pursuant to the Plan of Care developed by their provider. The insured is not required to use these services in order to file a claim and there is no cost to the insured if they choose to use these services. These service costs will not reduce the Policy Limit under the Policy.
LTC Partnership policies may entitle the insured to an asset disregard. This generally allows a person to keep assets equal to the insurance benefits received under a qualified Partnership policy without affecting the person’s eligibility for Medicaid.
Contingent Benefit Upon Lapse Endorsement
Association
Partner Discount
For no additional charge, if premium rates are increased resulting in a cumulative increase of the annual premium equal to or exceeding the percentage of the initial annual premium as set forth in the table on the endorsement that is attached to the policy, and the policy lapses within one hundred twenty (120) days of the due date for the payment of the increased premium, then the following options become available:
1. either the Monthly Benefit Amount and Benefit Period may be reduced (subject to availability), 2. or the policy may be converted to a paid-up status with the Shortened Benefit Period described in the endorsement. This option may be elected at any time during the one hundred twenty (120)-day period. In addition, if the Policy lapses for nonpayment of premium during this one hundred twenty (120)-day period, this option will automatically be provided under the Policy.
5% Association Group premium discount.
5% Discount is available to individual applicants when the individual has an eligible insured that is not applying for coverage.
Riders
Shared Additional Policy Limit Rider
Compound Inflation Protection Rider (1%, 2%, 3%, 4% or 5%)
First Day HCCS Rider
Shortened Benefit Period
Nonforfeiture Rider
If either or both insureds exhaust their own Policy Limit, a joint Shared Additional Policy Limit will become accessible which may be accessed by either or both insureds.
The joint Shared Additional Policy Limit will also increase due to an Inflation Protection Rider, if attached to the policy.
This option is only available on joint policies.
On each policy anniversary, the Maximum Monthly Benefit will increase by 1%, 2%, 3%, 4% or 5% of the previous year’s Maximum Monthly Benefit without regard to claims paid, with a corresponding increase in the Policy Limit, reduced by claims paid. Percentage of growth will be based on the chosen rider percentage.
Benefits will be payable on the first day the insured(s) is/are qualified to receive benefits for HCCS only.
If the policy lapses for nonpayment of premium after it has been in force for 3 years, coverage will continue, and benefits are payable equal to the greater of total of premiums paid, or one (1) times the Monthly Benefit Amount in effect at the time of lapse.