
Missouri
St. Louis – Olive
St. Louis – South County
St. Louis – Telegraph
Chesterfield – Score
Chesterfield - EHLT
Lake St. Louis
O’Fallon – Waterbury Falls
Florissant - Desk Rental
St. Louis – Baumgartner - Desk Rental
Illinois
Glen Carbon O’Fallon
Mt. Vernon
Champaign Springfield Knoxville
Bloomington
Champaign – ASA
Danville – ASA
Arkansas
Bentonville
Nebraska
Omaha
Iowa Ankeny Bettendorf
Cedar Rapids Council Bluffs
Des Moines
Glenwood West Des Moines
Indiana
Indianapolis
North Dakota
Minot Bismarck
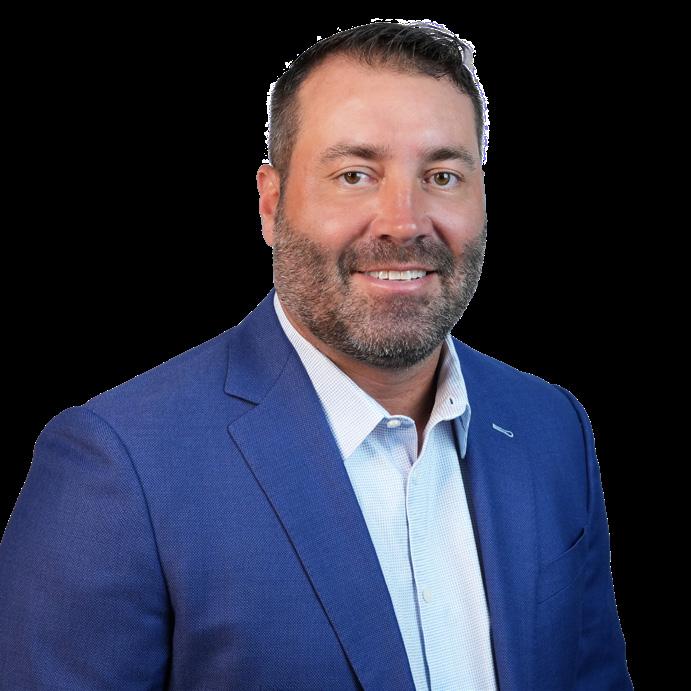
VP, Midwest
NMLS# 228046
As Vice President for the region, Tanner oversees all area functions for the Midwest. These areas include Sales, Operations and P & L management. His focus is pricing and helping each LO be as competitive as possible in the market place. He works with loan officers and managers daily on constructing ways to win each and every deal.
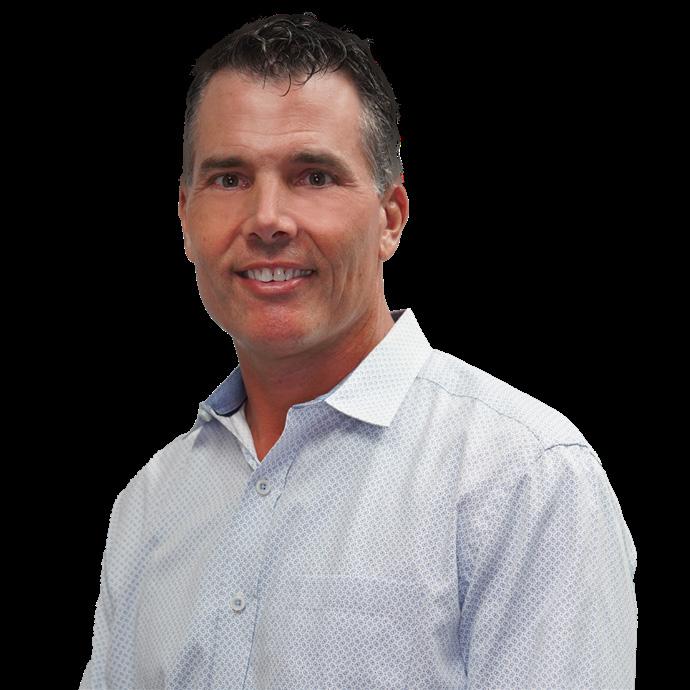
VP, Midwest
NMLS# 240288
As Vice President for the region, Tom oversees all area functions for the Midwest region. These areas include Sales, Operations and P & L management. His focus is on Sales growth, recruiting, teaching and training our sales force. We focus on strategies that have helped himself and many loan originators grow their business year over year.
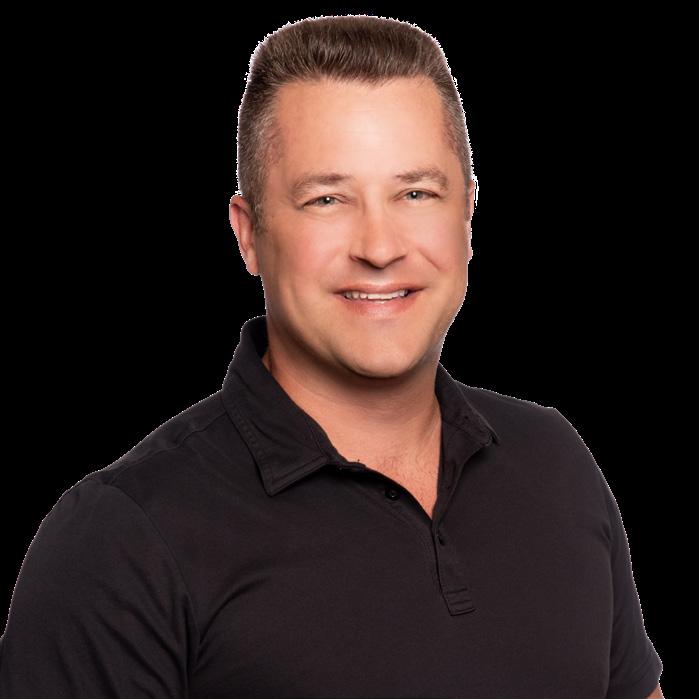
EVP, Retail Sales
NMLS# 72161
Tony oversees the company’s Retail Sales division, including a nationwide network of branch Loan Officers. Tony is responsible for implementing initiatives and procedures to drive successful growth and profitability in each region, and he collaborates with the Executive Team and Sales Leaders around the country to ensure continued growth, leadership, and retention.
NMLS# 328633
With over 33 years in the mortgage industry, Greg has established himself as a prominent Regional Manager with a remarkable track record. Over the past decade, he has funded more than $700 million in loans and has played a pivotal role in recruiting over $1 billion in new hires over the last four years, including $650 million since his return to New American Funding. Greg’s extensive experience also includes owning a mortgage company for 12 years and a real estate company for four years. After a brief hiatus, he rejoined NAF in 2022, bringing his total tenure with the company to over seven years—a decision he considers among the best he has ever made.
At NAF, Greg oversees strategic growth, embodying a commitment to excellence in the financial services sector. His proficiency in marketing and strong grasp of sales management have made his team a cornerstone for fostering robust growth and exceeding expectations. Greg has honed skills in customer service and recruitment, translating these into substantial contributions to the organization’s expansion. By collaborating closely with leadership, he has consistently delivered solutions that enhance customer satisfaction and drive sales performance. Passionate about recruiting and retention, Greg values the balance between professional success and personal life, striving to create a supportive work environment that reflects his belief in putting family first while driving growth and excellence within his team and the broader organization.
With over 30 years of experience in mortgage lending, Alexis is a highly accomplished underwriting professional with deep expertise in FHA, VA, USDA, and state bond programs. She holds FHA and VA underwriter designations, further enhancing her extensive knowledge of loan products. In addition to her underwriting background, Alexis brings seven years of experience in title insurance, having previously owned and operated a local title company.
In her current role, Alexis specializes in navigating complex loan scenarios, working closely with loan officers and underwriters to find solutions and make deals work. Her ability to review and assess loan structures for potential approvals is invaluable, ensuring that loans are positioned for success from the start.
• Primary Role: Find ways to make deals work by assisting both Loan Officers and Underwriters.
• Guideline Interpretation: Addresses escalated questions from Underwriters when guidelines are open to interpretation or unclear.
• Income Calculation: Provides initial income calculations for files including self-employed borrowers and unique income scenarios.
• Midwest Scenario Desk: Reviews loan scenarios to suggest ways to structure deals for approval.
• Guideline Research: Researches and clarifies guidelines for Loan Officers as needed.
• Manual Underwriting: Evaluates potential manual underwrites to determine if they can be approved manually or through Automated Underwriting Systems (AUS).
• Liaison Role: Serves as the communication bridge between Underwriting and Sales Teams.
Unchong oversees the mortgage process from application through to funding, ensuring that each step is completed efficiently and accurately. In addition to managing the loan pipeline to meet all necessary deadlines—such as loan contingency, closing, and lock expiration dates— Unchong is responsible for hiring, training, and managing Loan Officers Assistants (LOAs), Personal Assistants (PAs), and Processors. Unchong’s role also includes acting as a liaison between departments to foster a positive and collaborative work environment. This coordination is crucial in maintaining smooth operations across various teams.
With 23 years in the industry and 7 years at NAF, Unchong plays a pivotal role in mentoring, motivating, and assisting team members to achieve the monthly goals set for the region and the company. She ensures that the operations staff and the region stay updated on the latest compliance, regulation, and procedural changes. Additionally, Unchong addresses and resolves any customer and employee complaints, effectively managing and resolving issues to maintain high standards of service and operational efficiency.
Having local processing and underwriting is a significant advantage because it allows for faster decision-making and smoother communication. Our team understands the unique needs of the local market, ensuring a more personalized, efficient experience for both loan officers and borrowers. This localized approach helps resolve issues quickly and ensures faster turnarounds, giving us a competitive edge in providing exceptional service.
Our region utilizes an internal Appraisal Management Company (AMC), which is available to most branches. This gives our branches more control over the appraisal process, as the Branch Manager selects appraisers who are familiar with the local market and understand the unique dynamics of the area. By maintaining an Internal Appraisal Panel, we can ensure faster turnarounds, greater consistency in quality, and stronger relationships with trusted appraisers, all of which lead to a smoother transaction process for both Loan Officers and borrowers.
Our dedicated Condo Department handles all the necessary documentation and works to get the condo complex approved. The Loan Officer only needs to provide the HOA contact information. This process can be completed even before a loan application is submitted, enabling Loan Officers to get a condo complex approved and market it effectively to real estate agents and potential buyersDigital Closings
NAF has partnered with Snapdocs, a leading digital closing platform that facilitates over 3 million closings annually. This partnership allows our borrowers to preview key documents and digitize most of the paperwork, significantly reducing the time spent at the closing table.
LO receives application.
Loan is created, credit pulled and qualified/structured.
LOA prepares the file for initial disclosures and contacts borrowers for any supporting documents not already provided and moves the file to the PA.
Processor reviews and reaches out to the customer via email and phone call within 24-48 hours after initial underwriting review.
Processor discloses any COC LE’s, initial CD’s and any subsequent CD’s until the loan is sent to funding.
Assigned funder will review file same day or next day depending on closing date and other files funding that day.
Processor collects conditions and resubmits the file for midclear or CTC.
Funder will final balance the CD and communicate to LO and Processor the final amount to close.
LO and/or Processor will communicate to the borrower the funds to close.
PA moves documents into correct efolders and orders all third-party services and verifications - appraisal, title, VOE, VOD, VOR, etc and moved the file to the processor within 24-48 hours.
Processor works with title/ escrow to pre-balance the CD to ensure there are no cash to close issues.
If digital closing, borrower will esign on closing date prior to going to the title company to usually sign less than a dozen lender documents.
Processor reviews files within 24-48 hours and submits loan to underwriting.
Loan is assigned to an underwriter and reviewed within 24-48 hours (times may vary due to volume and PTO).
Once file is CTC, the file is prepared and sent to our funding dept.
Loan is assigned to a funder usually within the hour.
Your client is now a homeowner!
Lori is a seasoned professional with 25 years of experience in the mortgage industry, currently serving as the Regional Marketing Manager.
With most of that time spent as a successful Loan Officer, Lori brings a unique, firsthand understanding of the mortgage process, which has proven invaluable in crafting effective marketing strategies.
Lori specializes in building strong relationships with real estate agents and builders, using her deep knowledge of the industry to create targeted campaigns that resonate with key partners. Her dual expertise in loan origination and marketing helps drive business growth and strengthen partnerships across the region.
Senior Graphic Designer
Graphic Designer
Senior Marketing Specialist
Graphic Designer/Videographer
At New American Funding, our Regional Marketing team goes above and beyond traditional corporate marketing support. In addition to the comprehensive tools and resources provided at the corporate level, we offer a dedicated regional marketing team committed to your success. Our team specializes in creating personalized designs tailored to your unique needs, while offering co-branded solutions and value-added materials to strengthen referral partner relationships, helping you stand out in the market and grow your business.
As a loan officer considering joining a new mortgage company, a full-service onboarding department can make a significant difference in your success and experience. Here’s how:
• Seamless Transition: A dedicated onboarding team ensures your transition into the company is smooth and stress-free. They handle all administrative tasks, from paperwork to setting up your systems, so you can focus on what matters most—originating loans and building client relationships.
• Comprehensive Training: The onboarding team provides thorough training on the company’s technology, processes, and products. This means you’ll quickly get up to speed on how to navigate the systems and use the tools to boost your efficiency, saving you valuable time.
• Faster Start: With all your tools, resources, and systems set up and ready, you can start closing loans faster. The onboarding department gets you up and running quickly, minimizing downtime and maximizing your earning potential from day one.
• Ongoing Support: Even after the initial setup, a full-service onboarding team continues to offer support. They help with troubleshooting issues, provide updates on company processes, and ensure you’re always operating at peak performance.
• Professional Image: A well-organized onboarding process shows that the company values you and is committed to helping you succeed. It reflects a professional culture that focuses on supporting its loan officers from the very beginning.
A full-service onboarding department allows you to hit the ground running, empowers you with the right tools, and offers support throughout your journey, making your transition into a new company as smooth and productive as possible.
Regional Trainer
NMLS# 1534426
Benefits of a Dedicated Trainer for a Loan Officer Moving to a New Company
• Personalized Learning Experience
• In-Depth Product Knowledge
• Boosted Confidence
• Better Use of Technology and Tools
• Increased Productivity and Earnings
With 8 years at NAF and experience as a licensed originator, Paige brings valuable expertise to her role as a regional trainer, making her an exceptional asset to our team.
AMBER ERNST
Sales Manager
NMLS# 406037
Sr. Loan Consultant
NMLS# 316626
DAVID NELSON
Sr. Loan Consultant
NMLS# 1718338
Sr. Loan Consultant
NMLS# 2018724
Sr. Loan Consultant
NMLS# 1840439
Producing Area Sales Manager
NMLS# 623836
MIKE BERTARELLI
Sales Manager
NMLS# 1553457
Sr. Loan Consultant
NMLS# 1173204
DAN WEILER
Loan Consultant
NMLS# 1680769
Sr. Loan Consultant
NMLS# 400530
ALISHA
Branch Manager
NMLS# 1269995
Home Mortgage Advisor
NMLS# 521199
A Retail Branch at NAF is primarily a physical location where Loan Officers work directly with clients to provide mortgage solutions. These branches serve as local hubs, offering personalized service to borrowers throughout the loan process, from application to closing. Retail branches often focus on building strong relationships within the community, working closely with real estate agents, builders, and other referral partners to generate business and offer tailored mortgage products to meet the specific needs of local homebuyers.
NAF gives business owners the support they need to succeed, plus unparalleled flexibility and transparency that you won’t find anywhere else. Your business, your way. Backed by the power of NAF.
Producing Area Sales Manager
NMLS# 623836
Branch Manager
NMLS# 766557
VP, SCORE Mortgage Group
NMLS# 738508
VP, 217 Mortgage
NMLS# 611367
VP, EHLT
NMLS# 281228
VP, EHLT
NMLS# 289958
We proudly service over 90% of our Conventional, FHA, and VA loans in-house. We offer regionalized underwriting, processing, and an in-house condo approval team, enabling you to build your brand and area appraisal panel. And we have in-house experts who remove unnecessary red tape and make difficult things easier, helping you help your clients.
By servicing our own loans, we are able to build deeper relationships with our customers. Servicing isn’t just about making sure that homeowners’ taxes and insurance are paid on time. It’s also about supporting our customers through the highs and lows of life. As part of our commitment to creating a truly customer-centered experience for our borrowers, we’ve opened a Servicing Center in Austin, Texas.
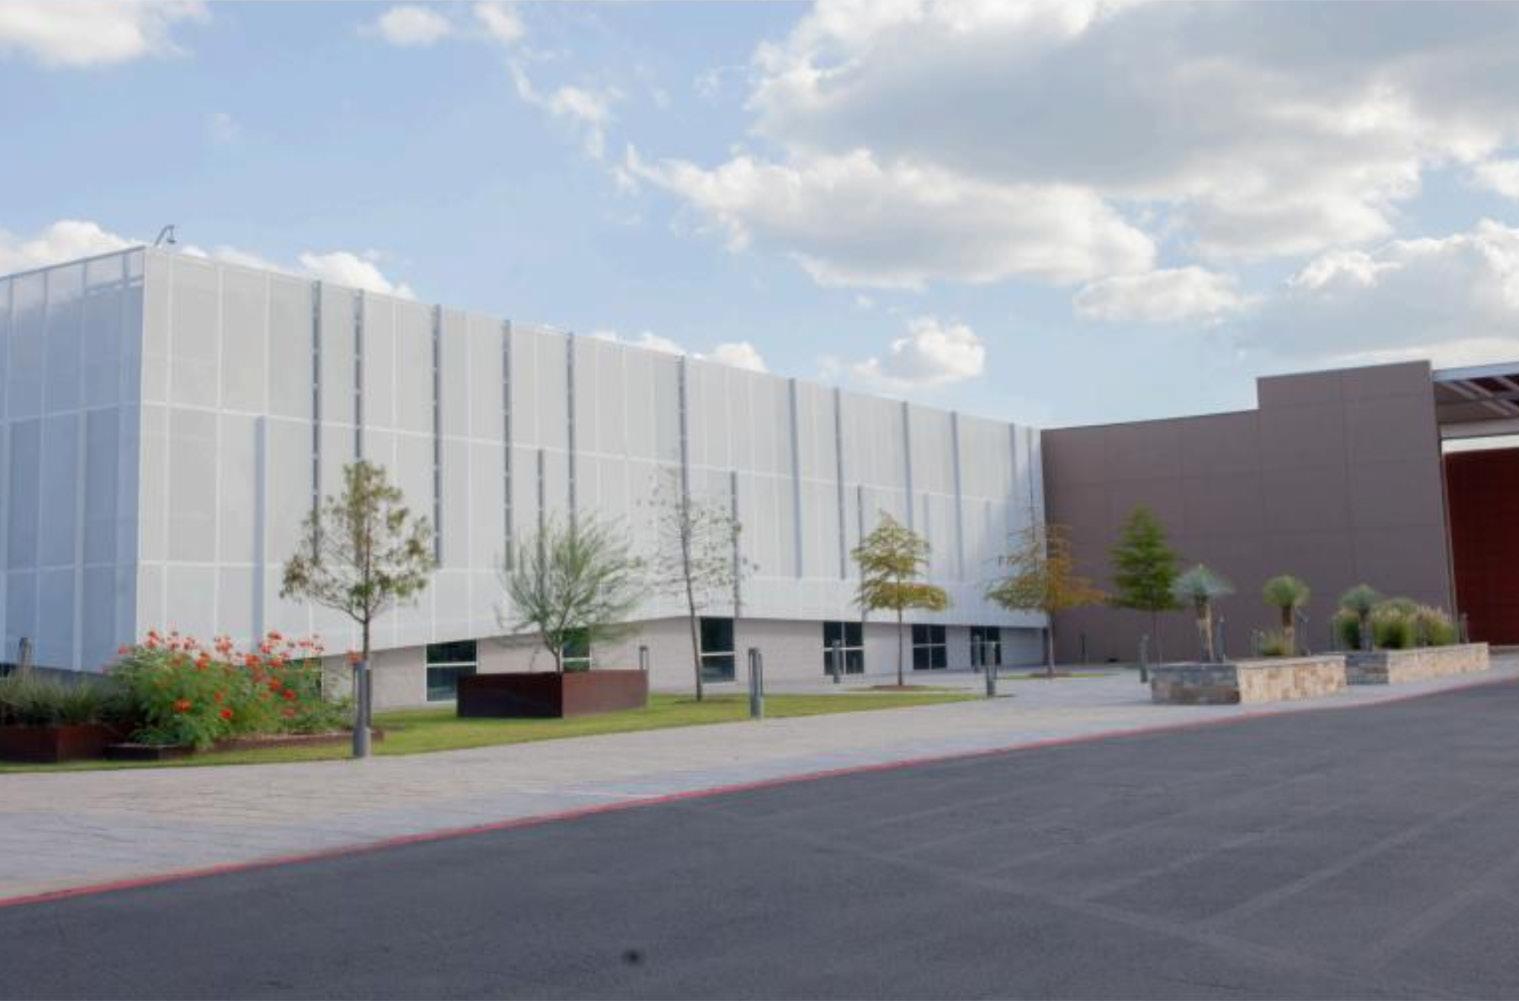
Our New Servicing Center In Austin, TX!
NAF proudly services approximately 80% of the loans we are eligible to service.
Total Loans in Servicing Center
280,000+
Servicing Portfolio $72.7 Billion Reviews 409,000+
As of 12/24
Employee retention is crucial because it fosters stability, builds a strong company culture, and ensures consistent service to clients. The fact that New American Funding has retained most of its employees, even in today’s challenging industry, speaks volumes about our supportive work environment, commitment to growth, and dedication to our team’s success. This high retention rate highlights our ability to provide both career longevity and professional fulfillment.
Out of 276 Employees...
15 have been here for 10+ Years
35 have been here for 7-9 Years
37 have been here for 5-6 Years
28 have been here for 3-4 Years
Clients can make a true cash offer that may not be contingent on the sale of their current home
Can provide funds to cover the purchase of a new home while finalizing the sale of their current home
A collection of specialized mortgage programs designed to help more borrowers achieve homeownership.
Can reduce buyers’ first-year, second-year, and third-year payment rate
Provides the ability to secure an interest rate with the option to lower it if the market improves before closing
Conventional, FHA 203(k), VA, HELOC and Cash-Out Refinance Options
We have a full suite of loans to fit borrowers of all shapes and sizes, no matter how unique their situation is
Enables older homeowners to convert a portion of their home equity into cash
Client may qualify for a home loan using the ITIN number
Self-employed clients may qualify using bank statements or asset depletion
Offers clients solutions for investment properties using non-traditional income sources
PATTY ARVIELO
Co-Founder, CEO
NMLS# 49166
Patty has been a leader in the mortgage industry for nearly 40 yeras. She has worked her way up from the bottom rung and gained extensive knowledge of the entire industry along the way. Over the course of her career, she functioned in a variety of capacities, from underwriting to processing to her current role as Co-Founder and CEO of New American Funding.
RICK ARVIELO
Co-Founder, CEO
NMLS# 6683
Rick transformed the company from a small call center into a leading national mortgage firm with over 260 branches. His focus on automating processes and integrating advanced technology streamlined operations and improved efficiency. Under his leadership, New American Funding expanded its services to include both refinances and purchase transactions, becoming a major direct lender and servicer.
CHRISTY BUNCE President
Christy is involved with every aspect of NAF’s business and has helped the company expand into the successful organization it is today. Christy oversees New American Funding’s entire mortgage lending pipeline, managing the lender’s operations, sales, and servicing operations.
PAT BOLAN
Chief Production Officer
NMLS# 732712
Pat leads the effort to grow the company’s retail lending platform and focuses on ensuring the long-term success of NAF’s retail division. He is passionate about recruiting and developing strong leaders.
TIM COTTEN SVP, Managing Director of Retail
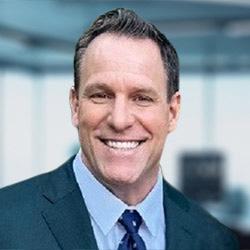
EVP, National Strategic Growth
NMLS# 230147
Tim has consistently delivered outstanding results and played a pivotal role in driving the growth of NAF’s Retail Division. His leadership, dedication, and collaborative approach have been exceptional. Tim maintains oversight of the Recruiting team and leads the Retail Onboarding team. He also serves as the key liaison for Marketing, Facilities, Compliance, Tech, Legal, HR, and Finance.
Sam works closely with the core sales force to increase their loan production while coming alongside regional managers to expand their market share. He also simultaneously recruits new loan teams to build upon New American Funding’s existing workforce and to continue increasing its profitability.
• Adding 250 loan officers and operations staff
• Increasing branch locations, concentrating on Nebraska, Indiana and Arkansas
• Adding $1B in additional production yearly
• Increasing our partnership group by 10
AND WE’RE JUST GETTING STARTED...
328633
Our loan officers are the number one customer! At New American Funding, we are dedicated to coaching and growing loan officers to help scale your business.
Our goal is to provide loan originators with the strongest array of products, technology, marketing, and support, so you can reclaim valuable time back into your day and spend more time doing what you do best: selling and providing high-value proposition to your clients and referral partners.
Midwest NMLS# 228046 Tanner.Hurrelbrink@NAFinc.com
SINAK
240288 Tom.Sinak@NAFinc.com TANNER HURRELBRINK
Equal Housing Opportunity. This is not a loan commitment or guarantee of any kind. Terms and conditions apply. Subject to borrower and property qualifications. Not all applicants will qualify. Rates and terms are subject to change without notice. All mortgage loan products are subject to credit and property approval. © 2026 New American Funding, LLC. NMLS #6606. nmlsconsumeraccess.org. 1 MacArthur Place, Suite 800, Santa Ana, CA 92707 naf.com. (800) 450-2010. NAF Cash, LLC (“NAF Cash”) is a real estate company that is an affiliated company of New American Funding, LLC. All products and services supplied by NAF Cash are subject to state availability and contractual terms and conditions. NAF Cash does not originate loans or issue loan commitments. NAF Cash charges a Transaction Fee of 1.50%-7.5% of the purchase price (fee varies by state and program). License: MI Real Estate Broker #6505431332.
Not available in: DC, NY, MA, TX, Guam, Puerto Rico, or U.S. Virgin Islands. Borrower is obtaining a bridge loan secured by their current primary residence to use the cash out proceeds towards the purchase of their new primary residence while they await the sale of their current primary residence. This loan product contains a balloon payment and requires no monthly payments during the 12-month term. The entire amount of outstanding principal and accrued interest is due at maturity or the sale of the property, if sooner than maturity. Payments do not include amounts for taxes and insurance premiums. Your actual payment obligation will be higher.
For a buydown, the seller or lender prepays a portion of the consumer’s monthly payments for the first 12, 24, or 36 months, reducing the interest rate 1%, 2%, or 3% below the note rate during that period. The note rate applies for the remainder of the term. Borrower must qualify based on the note rate.
06/2026