As we head into the second half of the year, I always find myself reflecting on how grateful we are to be a part of this incredible community Thank you for trusting Mortgage & Beyond with one of the biggest financial decisions you'll ever make Our relationship doesn't end at the closing table It's just the beginning Welcome to our Fall Edition, 3rd Issue of Mortgage & Beyond Magazine!
This season is bringing exciting opportunities for homeowners and buyers alike.
For homebuyers, today's market is creating a unique window of opportunity With more homes available and less competition than we've seen in recent years, buyers have more choices and greater negotiating power While homes in the most desirable neighborhoods are still selling quickly, many buyers are finding they have the time and flexibility to make smarter decisions without the intense bidding wars of the past
For homeowners, we're especially excited to introduce something we've never been able to offer before: Second Lien Home Equity Loans on primary residences, second homes, and investment properties.
If you've been hesitant to refinance because you have an amazing 3% first mortgage, you no longer have to choose between keeping your low rate and accessing your equity Now you can keep your existing first mortgage exactly as it is and simply add a second lien for the amount you need Whether you're planning a home renovation, consolidating high interest debt, or investing in additional real estate, this new option gives you flexibility while protecting the mortgage rate you've worked hard to secure Even better, many of these loans are closing in fewer than 15 days
As fall arrives, it's also a season of gathering together. We're looking forward to seeing many of you at our annual Client Appreciation Event this August. It's one of our favorite traditions, a chance to celebrate the friendships we've built and simply say thank you for allowing us to be part of your family's journey.
At Mortgage & Beyond, our mission has always been ab h h l i li b h W i d helping you make informed financial decisions, mana guidance on how to leverage your real estate to build
This isn't just a business to us, it's a community. Ever is a privilege We couldn't do what we love without yo
We hope you enjoy this issue, and as always, if you h equity, or your future plans, we're just a phone call aw
Wishing you and your family a wonderful fall seaso
Founder, Mortgage & Beyond
A warm message from our founder to our ever-growing community
A guide to your first year, and the financial journey that begins at closing
How investors and property owners can tap into home equity
What it is, how it protects you, and why it matters more than you think
Exemptions, appraisals, and how your tax bill affects your mortgage payment
Simple strategies that save you time and money
What the fall market is signaling for DFW buyers this season
The real costs and responsibilities that come with owning a home
Important deadlines and financial milestones to keep on your radar this quarter
A closer look at the underwriting process and what gets your loan approved
N T E N T S
Preparing for income changes and putting your home equity to work
Small maintenance steps that save you money later R
Two recipes worth firing up the grill for
NowLet’sTalkAboutWhat’sNext
Most conversations about homeownership focus on how to get there. The credit score, the down payment,theloanapproval,theclosingtable
Butwhathappensafterthekeysarehandedover isjustasimportant,andfarlesstalkedabout
Thefirstyearlooksdifferentthanyouexpect Thecostsarebroaderthanjustamortgage payment, and the financial opportunities that open up over time are ones every homeownershouldunderstandearly.
Whetheryou'recomingfromrentingorlivingwithfamily,becomingahomeownerisareal shift Notjustinwhereyoulive,butinhowyouthink,howyouspend,andhowyouplan
Forthefirsttime,you'refullyincontrolofyourspace.Nolandlordapprovals. Notemporaryarrangements.Thedecisions,bigandsmall,areyours.
There's also a shift in how money feels. Instead of paying rent toward someone else's investment, every payment you make is building something of your own. It can take a little adjusting to, but for most homeowners, it brings a stronger sense of stability andlong-termdirection
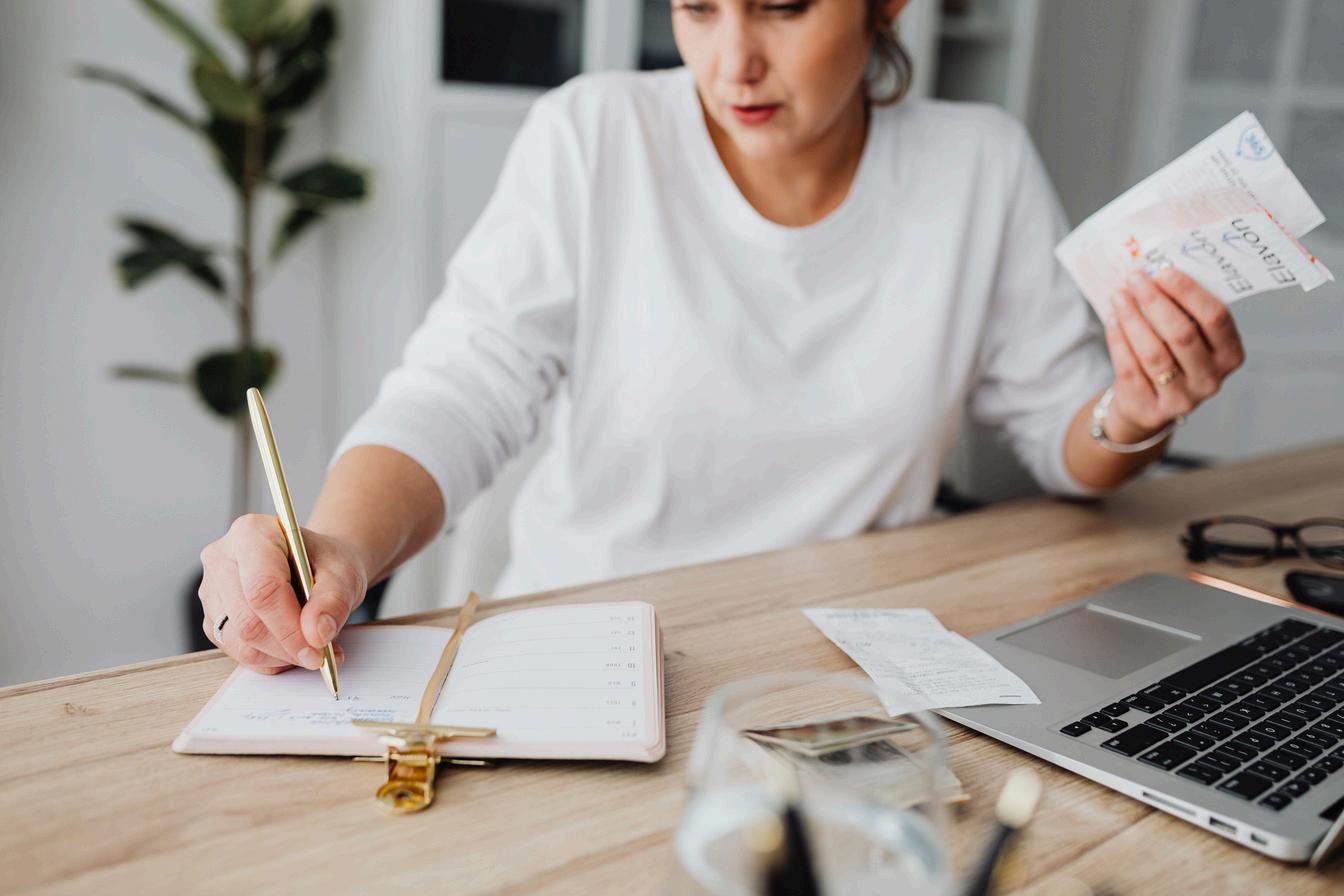
Oneofthebiggestadjustmentsafterbuyingisunderstandingthatyourmortgageisonlyone part of what homeownership costs. Unlike renting, where your monthly payment is largely predictableandfixed,owningahomemeanstakingonthefullfinancialresponsibilityofthe property That'snotareasontoworry It'sjustareasontoplan
Thereareotherongoingexpensestoplanfor:
Propertytaxes collectedmonthly throughescroworpaidannually dependingonyoursetup
Homeownersinsurance required byyourlenderandessentialfor protectingyourinvestment
Maintenanceandrepairs nota matterofif,butwhen Ageneralrule istosetaside1to2percentofyour home'svalueperyearforupkeep
Thesearen'tsurprises They're partofowningahome.The differencebetweenhomeowners whofeelfinanciallyconfident andthosewhofeelstretchedis almostalwayspreparation Whenyouunderstandthese costsearly,budgetingforthem becomesstraightforwardrather thanstressful.
Alotofpeoplethinkthehomebuyingprocess wraps up at closing In reality, closing is the beginning of a longer financial journey, one thatevolvesasyourlifedoes.
As time goes on, your situation will change Your income may grow. Your family may shift.Yourgoalswilllookdifferentinfiveyears than they do today, and your mortgage can adaptwithyou
These aren't decisions you need to make right away. They're tools that become available as your equity grows and your financial picture strengthens Knowing they existandknowingwhentousethemarepart of what makes homeownership such a powerfullong-termpositiontobein.
Optionsmaybecomeavailable toyouovertime,including:
Refinancingfora lowerinterestrate orshorterloanterm
Adjustingyourloan structuretobetter fityourcurrent financialsituation
Accessingyour home'sequityfor homeimprovements, debtconsolidation,or futureinvestments
AtMortgageandBeyond,ourroledoesn'tstopwhen yougetthekeys.Weworkwithhomeownerslong afterthepurchase,helpingthemunderstand whenopportunitiesareworthexploringand whenstayingthecourseisthesmartermove
Whetherit'ssixmonthsfromnoworseveralyearsdownthe road,youdon'thavetonavigatethesedecisionsalone

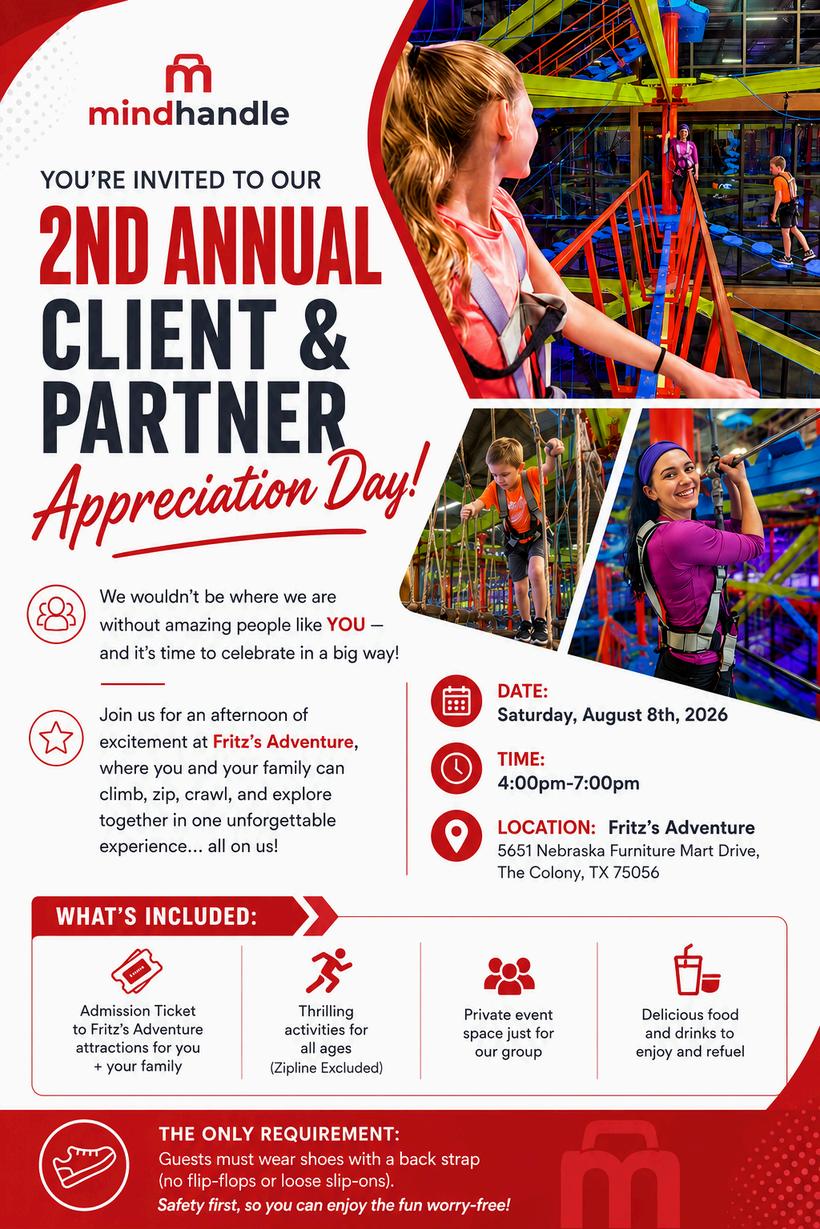



DATE
Saturday, August 8th, 2026
TIME
4:00pm-7:00pm
LOCATION
Fritz’s Adventure 5651 Nebraska Furniture Mart Drive, The Colony, TX 75056
Admission Ticket to Fritz’s Adventure attractions for you and your famiy
We wouldn't be where we are without amazing people like YOUand it's time to celebrate in a big way!
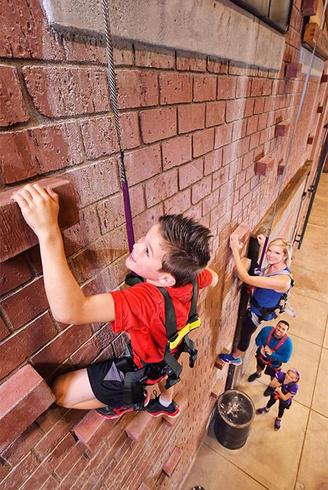
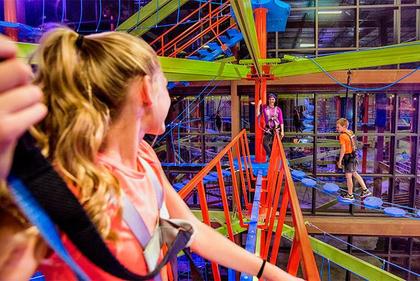
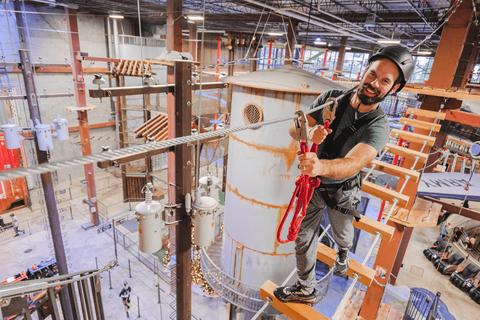
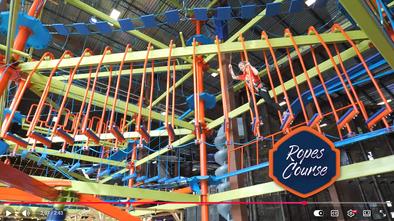
Join us for an afternoon of excitement at Fritz's Adventure, where you and your family can climb, zip, crawl, and explore together in one unforgettable experience... all on us!
Private event space just for our group Delicious food and drinks to enjoy and refuel W h at ’ s i n c l u d e d :
Thrilling activities for all ages (Zipline excluded)
THE ONLY REQUIREMENT:
Guests must wear shoes with a back strap (no flip-flops or loose slip-ons).
Safetyfirst, so you can enjoy thefun worry-free!
Atitleisthelegalrecordofhomeownership.Beforeclosing, atitlecompanysearchespublicrecordstoconfirmtheseller hastherighttosell,checkingforliens,unpaidtaxes, judgments,andownershipgaps.
Titleinsuranceprotectsyouifsomethingwasmissed,orifa problemsurfaceslater.Unlikemostinsurance,it'saone-time premiumpaidatclosing.Nomonthlyfees,norenewals,and itcoversyouforaslongasyouownthehome.
Protectsyou,thehomeowner Covers thefullpurchasepriceofthehome Thisistheonethatworksinyourfavor.
Apreviousowner hadanunpaid contractorlien thatwasn't recordedproperly
Anheircomes forward claimingpartial ownershipof theproperty
Aboundary errormeans partofyourlot waslegally someoneelse's
Ifyourefinance,anew lender'spolicyistypically required,butyourowner's policystaysinforceatno additionalcost.Youdon't needtorepurchase protectionfor yourself.
Protectsyourmortgagelender Requiredbyvirtuallyalllenders Itdoesnotprotectyou
Aforged signatureinthe chainoftitle createsan ownershipdispute
Unpaidtaxes fromaprior ownersurface afteryour purchase
Thesesituationsarerare.Butwithouttitleinsurance,thelegalandfinancialcostsfallentirelyonyou.
Youmayforgetyouhaveit. Butwhenyouneedit, you’llbegladyoudo.
AlreadyaMortgageandBeyondclient? Wepartnerwithtrustedtitle professionalsacrossDFW.Reachoutif youhavequestionsaboutyourcoverage
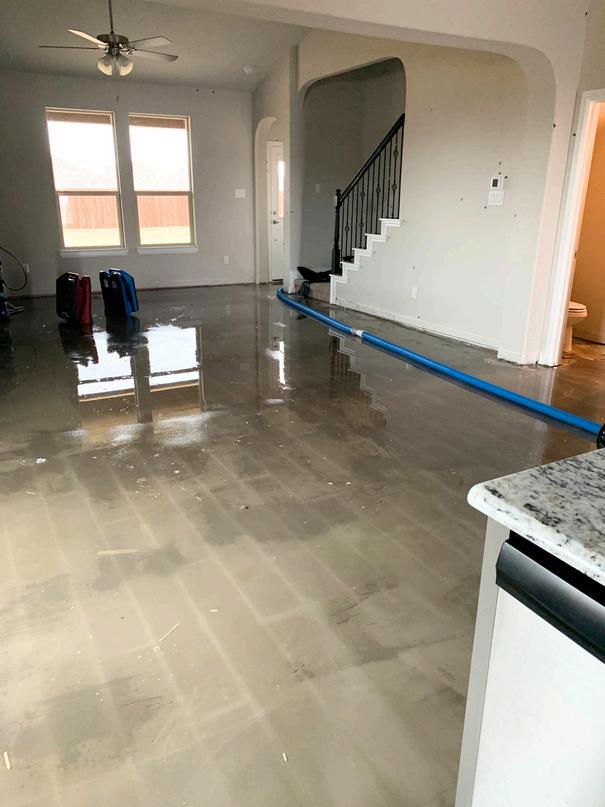
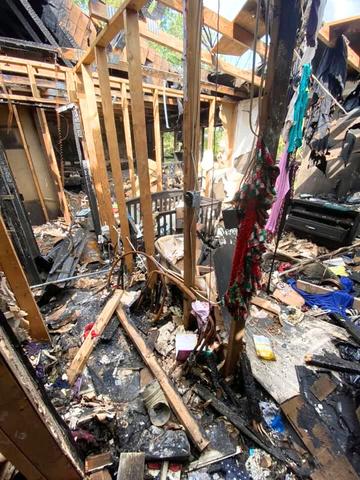
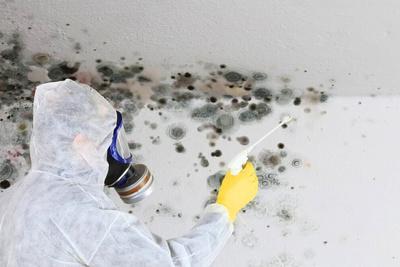
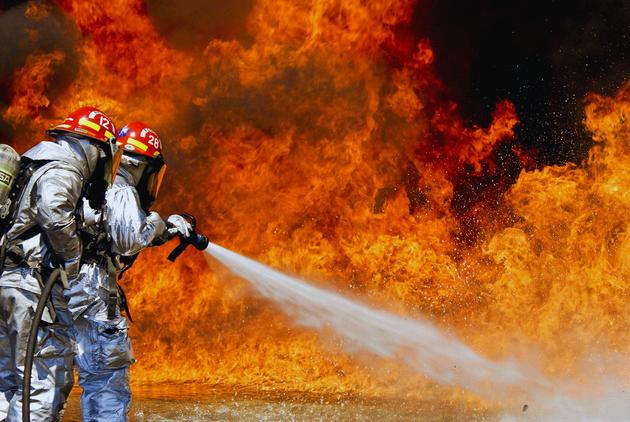
Our certified technicians offer immediate emergency response to handle the full restoration process. We work directly with your
company to restore your home and help protect your personal property From soaked floors to smoky walls, we return your property to its predamageconditionquicklyandefficiently.
Texas has no state income tax, and property taxes are a big reason why. They fund local schools, emergency services, roads, and more. For homeowners, understanding how they work and what you can do about them is one of the most practical financial moves you can make.
Your property tax bill is calculated by multiplying your home's appraised value by your local tax rate. Rates vary by county, city, and school district, and typically fall between 16 and 28 percent of your home's value
Many homeowners are leaving money on the table by not claiming every exemption they qualify for.
Homestead Exemption
If this is your primary residence and you owned it on January 1 of the tax year, you qualify This reduces your taxable value and caps annual appraisal increases at 10 percent for homesteaded properties
Over-65 or Disability Exemption
A $450,000 HOME THAT’S ANYWHERE FROM $7,200 to $12,600 PER YEAR
Often collected monthly through your escrow account. When your appraised value goes up, your monthly mortgage payment usually does too
Adds an additional reduction and freezes your school district taxes
Veterans Exemption
Texas offers partial to full exemptions for disabled veterans based on disability rating
Verifyyourexemptionsatyourcounty appraisaldistrict'swebsite.Ifanyare missing,fileimmediately Mostcanbe appliedretroactivelyuptotwoyears
Most Texas homeowners receive their final tax statements in October, with payment due by January 31.
FALLISTHERIGHTTIMETO:
Review your statement for accuracy
Confirm all exemptions are applied
COUNTY DISTRICT&WEBSITE
DALLAS
TARRANT
COLLIN
DENTON
Set aside funds or adjust escrow if your bill has increased
Explore installment payment options if needed; most counties allow them
DCAD dallascadorg
TCAD tadorg
CCAD collincadorg
DCAD dentoncadcom
If your lender collects taxes through escrow, a change in your tax bill will trigger an escrow analysis, usually once per year An increase in property taxes means an increase in your monthly mortgage payment, sometimes by $50 to $150 or more depending on your market.
Knowingthisinadvanceletsyou planratherthanbesurprised.
If you believe your home's appraised value is too high, you can protest it The deadline is typically May 15 each year, but the groundwork, gathering comparables and reviewing your appraisal record, is worth doing in the fall, so you're ready when notices arrive next spring
Property taxes are one of the largest ongoing costs of homeownership in Texas. Understanding them isn't just smart It's one of the best ways to protect what you've built
Have questions about how your property taxes affect your mortgage payment?

At Keyrenter, we transform your investment into a seamless, stressfree experience. Our full-service property management approach ensures your rental property is not just maintained but optimized for maximum profitability
21 Point Tenant Screening
Full-Service Property Management
Transparent Financial Reporting
Proactive Maintenance Planning
Efficient Rent Collection
Low Eviction Rate (469) 414-1000
Schedule a Call
6565 N MacArthur Blvd #225, Irving, TX 75039, United States info@keyrenterdfwmidcities.com Why Keyrenter
Every extra dollar you appl today becomes tomorrow. freedom
Refinancing gets all the attention, but it's not the only way to build equity faster and reduce what you pay in interest There are simpler strategies that cost very little to implement and can take years off your loan without changing it
MAKE ONE EXTRA PRINCIPAL PAYMENT PER YEAR
One extra payment a year can shave 4–6 years off a 30 year mortgage Apply a bonus, tax refund, or windfall directly to the principal and mark it “principal only” so it’s applied correctly
The sooner you start, the more you save in time and interest. 01 02 03 04 05
SWITCH TO BI-WEEKLY PAYMENTS
Make 26 half payments instead of 12 full ones adding one extra payment a year It can cut years off your mortgage and save thousands in interest Check with your servicer; some charge a setup fee
ROUND UP YOUR PAYMENT
If your mortgage is $2,340 a month, pay $2,500 The extra $160 goes entirely to principal It barely registers in your monthly budget, but over 10 to 15 years the compounding effect is significant
APPLY WINDFALLS TO PRINCIPAL
Tax refund Annual bonus Side income Even applying half of these to your mortgage principal each year can dramatically accelerate your payoff timeline
REFINANCE WITH A PURPOSE
Refinancing can help lower your payment reduce your rate consolidate debt, or access equity Before extending your loan term, talk with your lender about what best supports your long-term goals
Every homeowners situation is unique Whether you want to lower your payment, reduce your rate or access your home's equity, refinancing may help you reach your goals
Reachoutand we'llrunthe numbers.

Mortgagerateshavebeeninaslow, unevendeclineafterpeakingin2024. Theyhaven'tdroppeddramatically, butthedirectionmatters.Whenrates fall,morebuyersenterthemarket, competitionincreases,andhome pricesfollow
Waitingforthe"perfect"rateoften meansbuyinginamorecrowded marketatahigherprice
Waitingmakessenseifyourcredit, savings,orincomearen'treadyyet. Buyingbeforeyou'refinancially preparedcreatesmoreriskthan anyratemovementevercould. Preparationalwaysbeatstiming.
Timingthemarketperfectly isnearlyimpossible.But understandingwherethe marketisheadedcanhelp youmakeasmarter,more confidentdecision.
Hereiswhatfall2026is signalingforbuyersinDFW.
1 2 3 4 5
Inventorytendstoincreasein latesummerandearlyfall beforepullingbackinwinter
Motivatedsellerswhodidn'tclose oversummerareoftenmore willingtonegotiate
Lesscompetitionfromother buyerscomparedtospringand earlysummer
Builderincentivesandrate buydownsaremorecommon inQ3andQ4
Alowerpurchasepricetodaycan outweighaslightlyhigherrate, especiallyifyourefinancelater
ASIMPLEWAYTOTHINKABOUTIT
Therighttimetobuyisn'twhenrateshita specificnumber.It'swhenyourfinances areready,yourgoalsalign,andtheright homeisavailable.Falloftenchecksall threeboxesforbuyerswhoareprepared.
Homeownership doesn’t stay the same over time. It shifts as your life, finances, and priorities change.
This page gives a quick snapshot of what typically comes next after you move in.
Eventually, homeowners shift focus toward long-term stability and financial goals. 2 4 1 3
The beginning stage is about stability and understanding how everything fits together.
Understanding how your mortgage works
Getting used to monthly costs and responsibilities
Learning basic upkeep and home systems
Building early financial stability
The needs and priorities you have today may look different a few years from now.
Updating ownership when life changes happen
Refinancing or reviewing your mortgage terms
Making small financial adjustments over time
Watching how equity builds in your home
Major life and financial milestones often bring new housing decisions to consider.
Thinking about staying, selling, or relocating
Comparing rent, refinance, or sale options
Responding to life or financial changes
Considering timing and market conditions
Paying down your mortgage over time
Building long-term financial stability
Planning for future freedom or retirement
Using your home as part of your financial growth
Tax Planning & MidYear Financial Review
15
31
31
SEC Form 10-Q Filing Deadline (Accelerated Filers); large public companies submit second-quarter financial reports, providing insight into economic and market trends
SEC Form 10-Q Filing Deadline (Non-Accelerated Filers); smaller public companies report quarterly performance, offering additional indicators of business activity
Housing Market Checkpoint; buyers, sellers, and investors can review local market conditions, interest rate trends, and housing inventory before the fall season
Property Tax Delinquency Reminder; unpaid property taxes continue to accrue penalties and interest, making it important for homeowners and investors to stay current on obligations
Mid-Year Retirement Review; a good time to evaluate 401(k), IRA, and other retirement contributions to ensure savings goals remain on track
Mid-Year Business Financial Review; business owners can assess revenue, cash flow, and growth plans before entering the second half of the year
August
Housing & Financial Planning Checkpoint
15
September
Quarterly Taxes & Year-End Preparation
15
Estimated Tax Payment Due (Q3); self-employed individuals, investors, and small business owners submit their third quarterly tax installment to help avoid penalties
Business Tax Extension Deadline; partnerships and S corporations that filed extensions must submit their federal tax returns
End-of-Quarter Financial Review; a valuable opportunity to review budgets, savings progress, debt reduction goals, and year-end financial plans
What Really Happens When a Lender Reviews Your File
You've submitted your documents. Now you're waiting. What's happening on the other side is underwriting, and understanding it makes the whole process far less stressful
The underwriter isn't your loan officer They review your full file against strict program guidelines, whether FHA, conventional, VA, or jumbo. Their job isn't to deny your loan; it's to verify that everything checks out The goal is clarity and confidence in your file
Theirjob isn’tto denyyou. It’sto confirm you ’ re ready.
Key risk indicators:
Can you afford this loan?
Underwriters review your debt-to-income ratio (DTI): how much of your gross monthly income goes toward all debt payments, including the new mortgage Most programs allow up to 43 to 50 percent
Does your credit demonstrate reliability?
They're reading your full credit history, not just your score Payment patterns, credit age, utilization, and recent events all tell a story
Is the home worth what you're paying?
The appraisal answers this Underwriters confirm the value supports the loan amount and that the property type is acceptable.
Unexplained income gaps
New debt taken on during the process
Undocumented income sources
Key risk indicators:
Late payments in the past 12 months
Maxed-out cards
New credit applications opened/co-signed during the loan process
Key risk indicators:
A low appraised value
Non-standard property types
Undisclosed property issues
Anything outside your normal payroll needs to be sourced. A family gift requires a gift letter A transfer from another account means they'll want to see that account too.
Frequent overdrafts or irregular transfers signal financial instability
After down payment and closing costs, most programs require at least 2 months of mortgage payments still in your account.
Most loans come back as conditionally approved, meaning you're approved once certain items are resolved This is normal
APPLICATION SUBMITTED CONDITIONAL APPROVAL
Prior to Docs - Updated bank statements, explanation letters, proof of insurance
Prior to Funding - Final verifications, signed disclosures, updated title work
Respond to conditions quickly. Each day of delay pushes your closing back.
Underwriters have limited flexibility. When exceptions are possible, they're supported by compensating factors
This is why your loan officer matters A good one structures your file before it reaches underwriting, anticipates questions, and positions your strengths clearly
At Mortgage and Beyond, we prepare your file before it hits underwriting so nothing surprises you at the table
The holidays arrive fast. A little attention to your home this fall keeps surprises from turning into expensive emergencies, and sets you up financially for the new year.
HVAC System
Schedule a tune-up before temperatures drop Catching a small issue now costs far less than an emergency repair in December.
Gutters and Roof
Clear gutters of leaves and debris before winter rains arrive While you're at it, check for any missing or curling shingles.
Weatherstripping and Seals
Check doors and windows for drafts. Resealing gaps is a low-cost fix that can meaningfully reduce heating bills through winter.
Water Heater
Flush sediment and check the pressure relief valve Heaters work harder in colder months and tend to fail when demand is highest.
Set a firm holiday budget now, before the season starts
Home maintenance and holiday spending hit the budget at the same time. A few habits help you manage both.
Smoke and Carbon Monoxide Detectors
Test and replace batteries now, before guests arrive and before fireplaces get their first use of the season
A little attention now saves big later
Review your escrow account; fall is when many adjustments take effect.
Avoid putting large home repairs on high-interest credit; ask your lender about home equity options for larger projects.
January brings new loan limits and program updates; if buying or refinancing is on your 2027 list, now is the time to start the conversation.
Membership Tier
Vendor Type Elite Contractors Electricians
Plumbers
Roofers
Attorneys
To keep the list vetted and high value to our clients, we ask for an annual partnershipfee We are not looking to make a profit from the partnershipfee, thefee simply covers onboarding, quality control, and getting our partners to be visible to as many as good referral partners as possible. Here is the info:
Membership Tier
Scale
Vendor Type
Landscaping
Pool
Pest Control
Cleaning Services
Home Staging
Smart Home Install
Movers
Packers
Home Warranty
Water Treatment
Membership Tier
Foundation
Vendor Type
Real Estate Photographers
Drone Videographers
Marketing & Creative Vendors (flyers, websites, social media)
Event Planning
If you run a reputable service-based business and want to be considered for the next round of partners, your company will receive the following benefits:
1. Ad Placement in Mortgage and Beyond Magazine
A half-page or full-page ad featuring your current specials in our Magazine (published quarterly), mailed to 6,000 clients annually.
2. Direct Introductions to Top Agents
Connect with 150 high-producing realtors who closed 1,000+ transactions last year and get access to their partner group.
3. Marketing Opportunities With Builders & Offices
Get your flyers and promos into the hands of national builders and major local real estate teams through our partner network.
4. Monthly Homebuyer Guide Placement
Show up in a printed guide mailed to 200–300 new mortgage applicants every month.
5. Featured on Our Website
Your business will be listed as a trusted vendor visible to 10,000+ monthly visitors.
6. Newsletter Exposure
Be seen by 8,500+ homeowners and real estate pros through our weekly newsletter
An income disruption, whether from a layoff, career change, or medical leave, doesn't have to mean losing your home. The right preparation makes all the difference, and most homeowners have more options than they think
The biggest mistake homeowners make is waiting too longto contact their lender Most servicers have hardship and deferral options available, but they're far easier to access before you miss a payment than after
ACT RIGHT AWAY:
Financial stress is one of the leading causes of anxiety for homeowners. There's real value in having a plan, not just financially but emotionally. Knowing exactly who to call and what steps to take doesn't eliminate the
When income isn't guaranteed, preparation looks a little different Here is what to know about your mortgage options and how to stay ahead if your income doesn't follow a traditional path
Payments are temporarily paused or reduced Missed amounts are added to the end of your loan No immediate credit damage, and it buys time
A permanent change to your loan terms, such as a lower rate or extended repayment period Requires working directly with your servicer
If your credit is still intact, refinancing to a lower rate or longer term can reduce your monthly payment Best done before a crisis hits
A cash-out refinance or HELOC can serve as a financial bridge, but only if your credit and income still qualify Waiting until you're unemployed is usually too late
Income variability isn't only about job loss If your income fluctuates, these habits should already be in place
Keep at least 6 months of business and personal reserves Don't drain savings for a down payment; liquidity matters more than a lower loan amount
Use a lender who qualifies you on bank statements, not just tax returns
Keep your books organized and up to date; lenders will ask for documentation, and having clean records ready can significantly speed up the process
In Part One, we talked about preparing for income changes. One of the options mentioned was tapping home equity as a financial bridge But that only works if you understand what equity is and how to access it responsibly That starts here
SIMPLY PUT, IT'S THE PORTION OF YOUR HOME'S VALUE THAT YOU ACTUALLY OWN:
the difference between what your home is worth and what you still owe on your mortgage When you first buy a home, your equity is usually just your down payment, since the rest is still owed to your lender.
Example: $450,000 home $310,000 owed = $140,000 in equity
Over time, as you pay down the loan and your home's value shifts, that stake grows or shrinks along with it Markets can take equity away just as easily as they build it up, which is why checking in on your position now and then is worth the habit
You don't have to do anything dramatic to build equity
It grows through a combination of factors
Equity isn't something you see in a bank account or a monthly statement. It lives quietly in your property rather than sitting somewhere liquid You can't spend it directly, but you can put it to work through specific financial tools
YOU PAY DOWN YOUR LOAN
Computation:
HomeValue
- RemainingMortgageBalance
= YourEquity
Every payment reduces your balance Early on, more goes to interest, but over time more shifts to principal This is amortization working quietly in your favor
YOUR HOME APPRECIATES YOU MAKE IMPROVEMENTS YOU MAKE EXTRA PAYMENTS
Rising market values, especially in a growing market like DFW, increase your equity without any action on your part
Strategic upgrades like kitchens, bathrooms, and curb appeal can increase your home's market value and your equity along with it
Making even one extra principal payment per year reduces your balance faster and builds equity well ahead of your original loan schedule
Now that you know what home equity is and how it grows, it's time to put that knowledge to
Replaces your mortgage with a larger one You receive the difference in cash at closing Best for larger, one-time needs.
A lump-sum loan at a fixed rate, separate from your existing mortgage Predictable payments, good for defined expenses.
A revolving credit line you draw from as needed Flexible for staged projects or as a financial safety net. Rates are typically variable.
Once you've built meaningful equity, you have three main ways to use it
There's more than one way to access your home equity, and each option works differently. The right choice depends on how much you need, how you plan to use it, and what you can comfortably take on
TIMETOMAKE:25MIN
SERVES:4to6
FreshcornpeaksJuly throughSeptemberin
Texas.Smoky,fresh, andreadyinminutes.
Perfectforcookouts, potlucks,orasaside anynightoftheweek.
TOSERVE:
Topwithcrumbled cotijaorfetafor extraflavor Pairsperfectlywith thesteakkabobs Keepsinthe refrigeratorforupto 3days
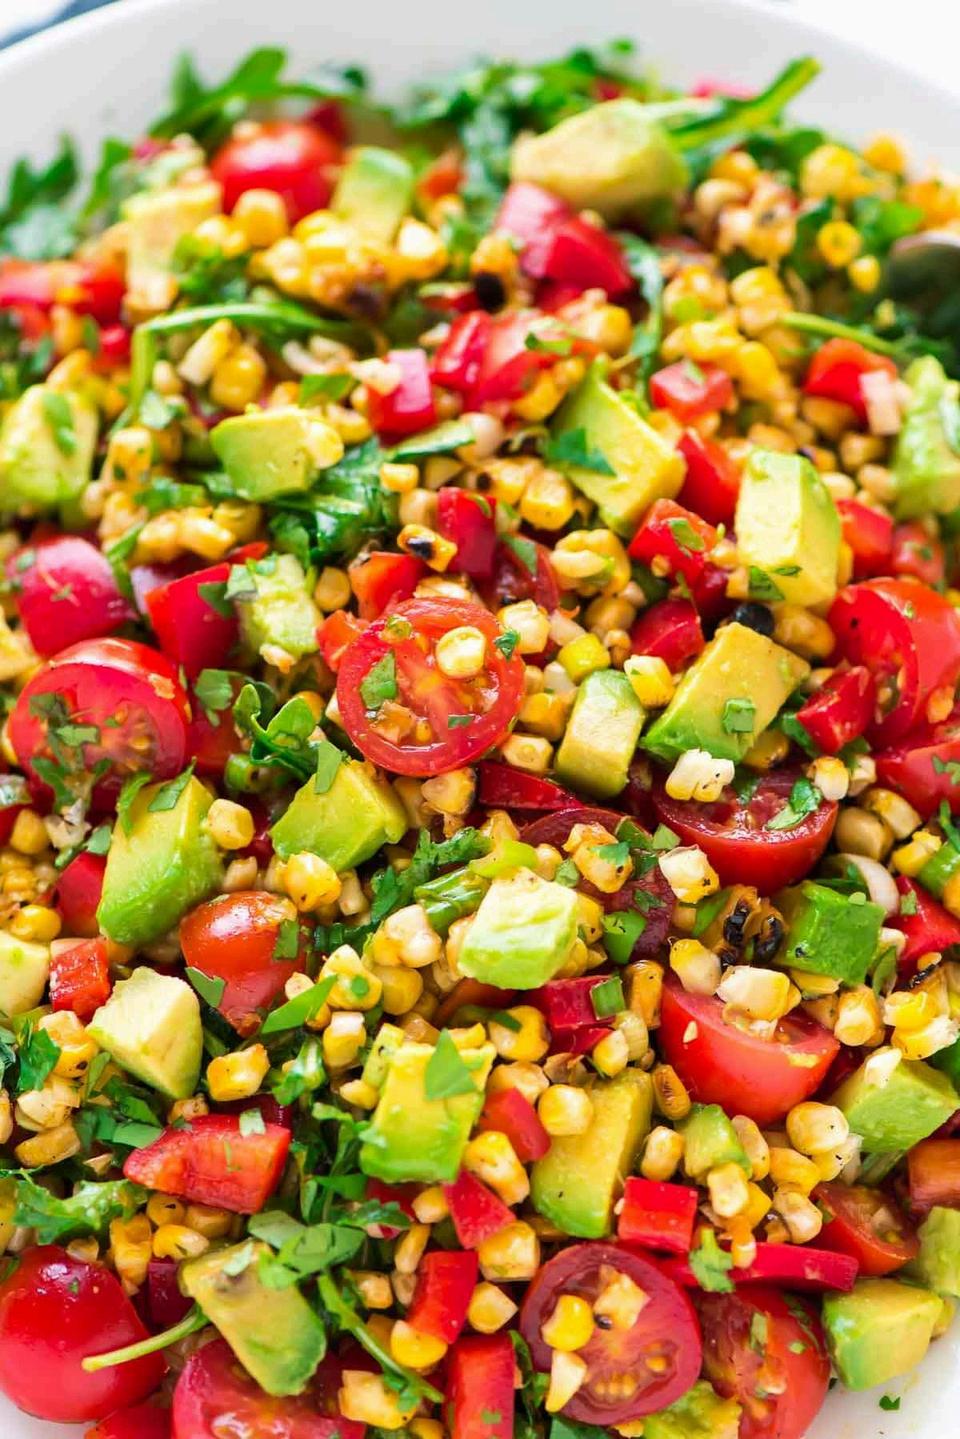
Salad
4earsfreshcorn,husked 1cupcherrytomatoes,halved 1avocado,diced 1redbellpepper,diced 3greenonions,sliced ¼cupfreshcilantro,roughlychopped
HoneyLimeDressing 3tbspfreshlimejuice 2tbspoliveoil 1tbsphoney ½tspsmokedpaprika Saltandpeppertotaste
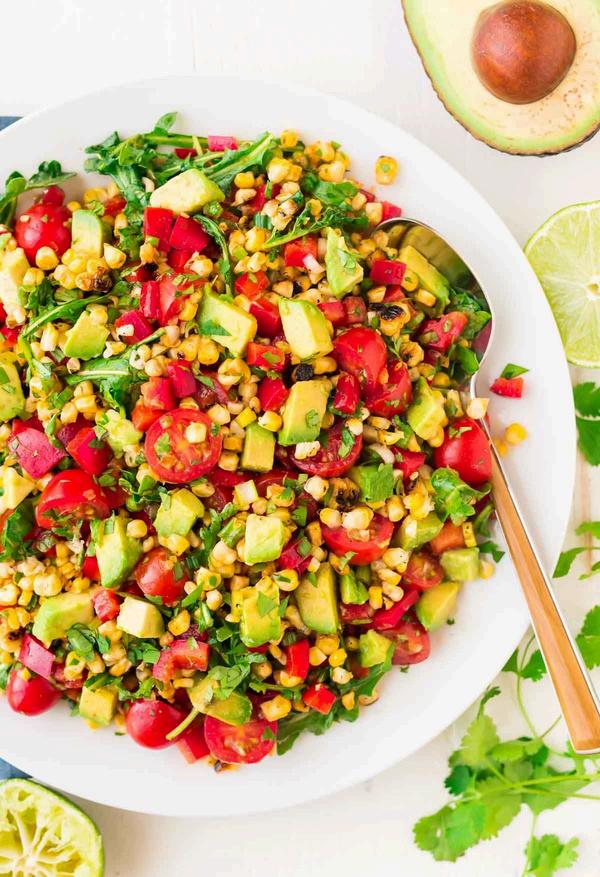
1. Preheatgrilltomedium,about400°F.Rubcorn witholiveoilandseasonwithsaltandpepper.
2 Grillcornfor7minutes,turningeveryfewminutes, untilearsarelightlycharred
3. Removefromgrillandletcool.Cutkernels carefullyfromthecobandtransfertoalargebowl.
4. Addcherrytomatoes,avocado,bellpepper,green onions,andcilantrotothebowl.
5 Whisktogetheralldressingingredientsinasmall bowluntilcombined
6. Pourdressingoverthesaladandtossgently tocombine.
7. Tasteandadjustseasoningasneeded. Serveatroomtemperature.
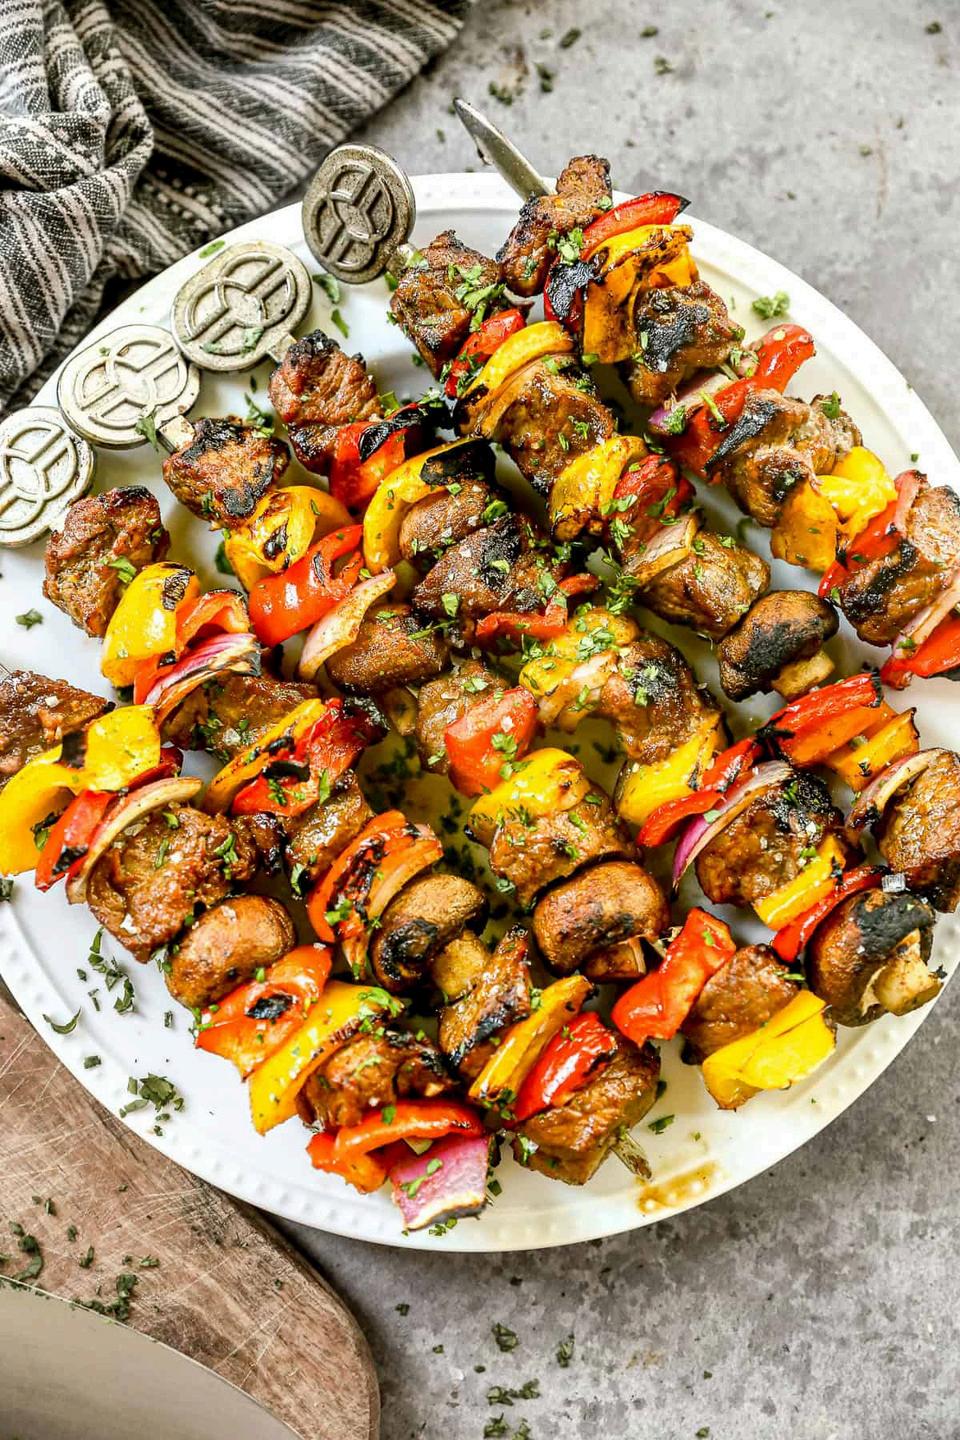
PeakgrillingseasonrunsthroughSeptemberinTexas.Nothingcaptures itbetterthanperfectlycharredsteakkabobsfreshoffthegrill.
TOSERVE:
Garnishwithfreshparsleyandasqueezeoflemon
Servewithsteamedrice,warmpita,orthegrilledcornsaladalongside
Kabobs
2lbssirloinsteak,cutinto1.5-inchchunks
1redand1greenbellpepper,cutintochunks
1redonion,cutintochunks
8ozcreminimushrooms,wholeorhalved
Saltandpeppertotaste
Marinade
3tbspeacholiveoilandsoysauce
2tbspWorcestershiresauce
3clovesgarlic,minced
1tspeachsmokedpaprikaanddriedoregano
Saltandpeppertotaste
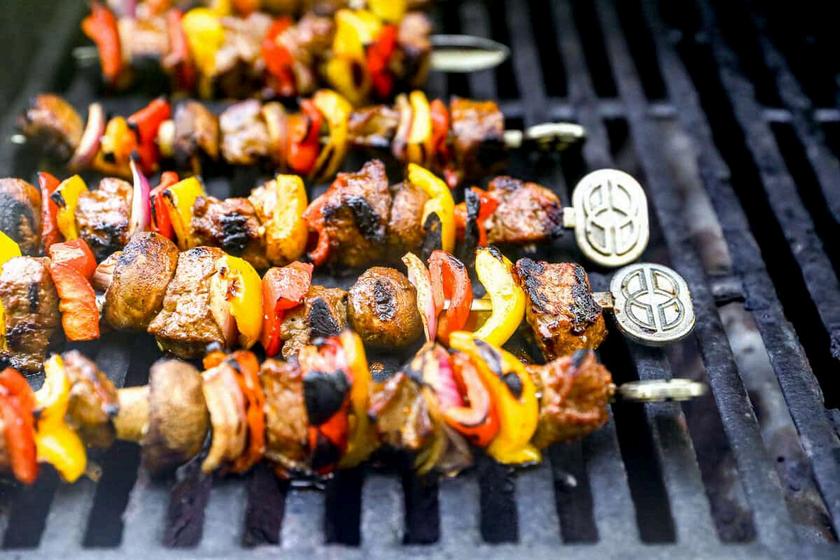
HOWTODOIT:
1 Whiskmarinadeingredientstogether Addsteak,cover,andrefrigerateforat least1hour.
2. Preheatgrilltomedium-high.Soak woodenskewersinwaterfor20 minutesifusing
3 Threadsteakandvegetablesonto skewers,alternatingasyougo.
4. Grillfor8to10minutes,turningevery fewminutes,untilsteakreaches desireddoneness
5 Restfor5minutesbeforeserving