Direct inquiries to: 713 Central Avenue, Fort Dodge, Iowa 50501 515-573-2141 Spotlight is published monthly by The Messenger with all rights reserved, Copyright, 2026
Funeral pre-planning with a professional eases anxiety
The death of a loved is difficult to confront. Emotions are elevated and grief is prominent. Which can make it hard to make important decisions. Quite often several people need to come together to make decisions necessary for a family member’s funeral arrangements. There also is a financial component to consider.
According to Lincoln Heritage Life Insurance Company, the average funeral costs between $7,000 and $12,000, which may or may not include viewing, burial, transport, casket, and other fees. Surviving family members responsible for planning a funeral may be asked to contribute a portion of these expenses if other arrangements have not already been made, which can exacerbate stressful feelings during an already difficult time.
Funeral pre-planning is a good way for individuals to make a difficult time a little more manageable for their survivors. Funeral homes frequently work hand-inhand with individuals and families to customize pre-planning packages and facilitate the process. Here’s a rundown of pre-planning as individuals consider their options.
Explore your options
Pre-planning a funeral enables people to consider all of the options without the time constraints of making funeral arrangements directly after the passing of a loved one.
A knowledgeable staff member at a funeral home, can explain the offerings and answer any questions.
Straightforward process
Unless an individual has planned a funeral in the past, there could be a lot of unknowns. Funeral homes handle these events every day and can guide families through the intricacies of the process with ease. Most have pre-planning kits that include all of the essentials of the process, such as choosing caskets, deciding on prayer cards and designing floral arrangements.
Avoid confrontations
Working directly with a professional also helps alleviate the burden on family members, who may not agree on arrangements or concur on what they believe would be a loved one’s final wishes. When pre-planning a funeral, individuals can spell out in their own words exactly what they desire and even finance the funeral in advance.
Establish a payment plan
A funeral home staff member can go over the various ways to fund funeral expenses, and may work out a payment schedule to spread out the expense over a period of time. He or she also may explain how funeral prearrangement can be a way to “spend down” assets in a way that protects those monies from look-back periods when determining eligibility for certain assisted living or nursing facilities should that be required in the future.
Works with religious officials
Very often a funeral home is a conduit that facilitates all facets of the funeral process. They may reach out to a preferred house of worship to organize a mass or other religious service, and will also contact the cemetery and work with them to secure a plot and deed. This also alleviates pressure down the line on grieving family members who need time to mourn. Pre-planning a funeral merits consideration. Working with a trusted funeral home removes much of the pressure during such difficult times.
Funeral homes frequently work hand-in-hand with individuals and families to customize pre-planning packages and facilitate the process.
Newspapers would like to extend our support at your time of loss.
How to schedule an obituary:
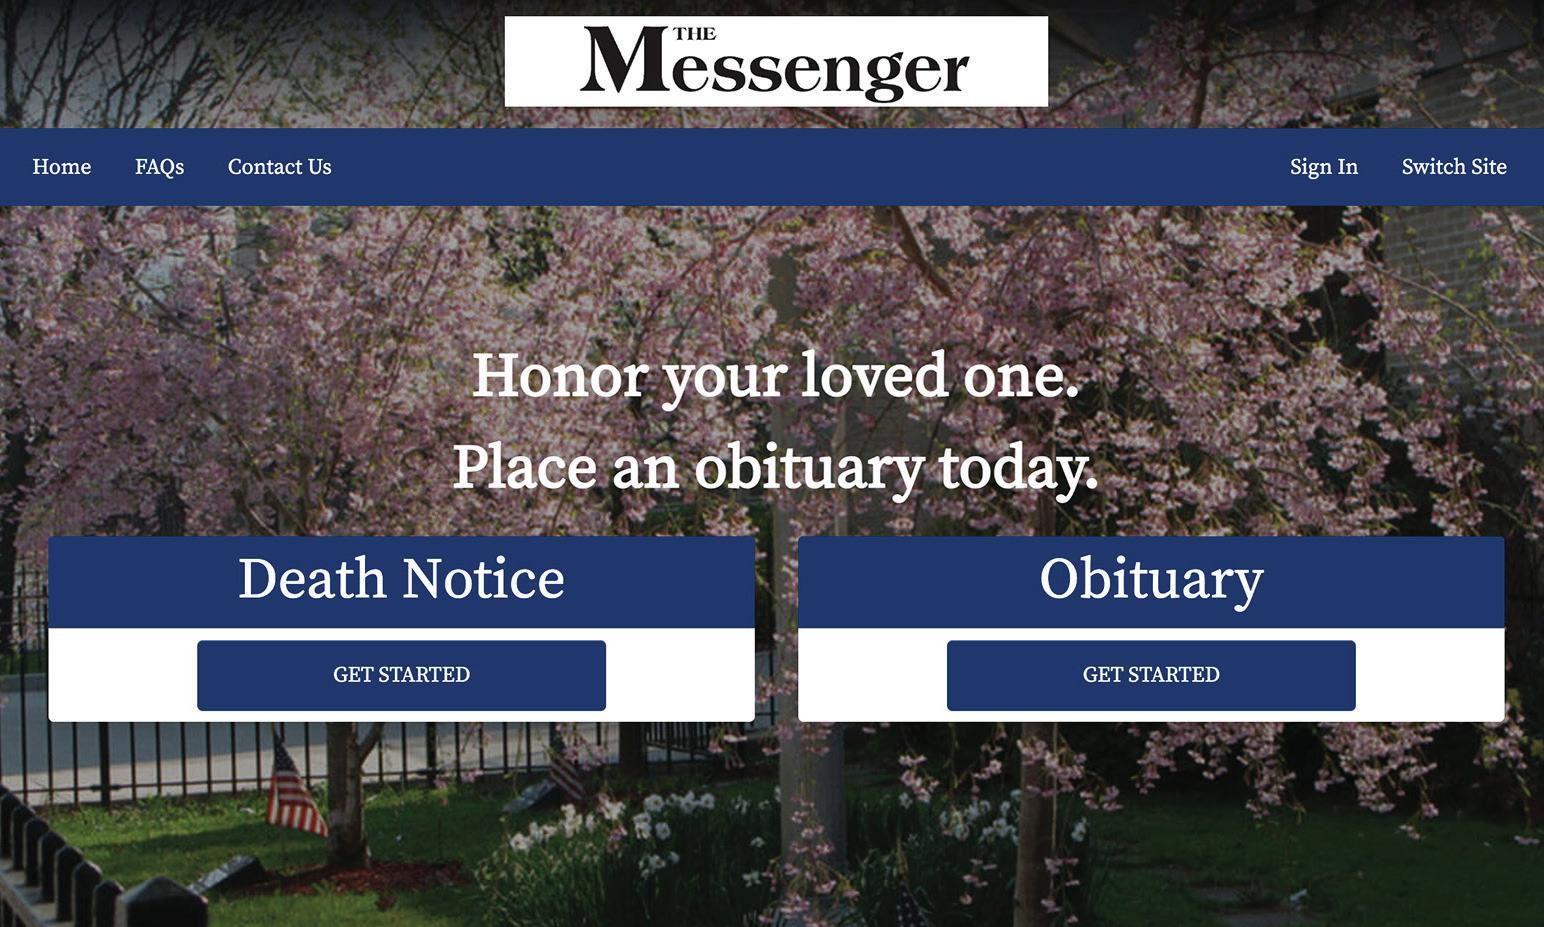
1. Visit obits@messengernews.net or go directly to https://placeanobit.ogdennews.com/obits/messenger/index.html
2. Sign in using your username and password. If you do not have one you will need to register.
3. Once logged in, click on the “Create a New Notice” link.
4. Select either a Death Notice or Obituary.
Death notices are free for up to 10 lines. They should include the name of the deceased, age, city of residence, date of death, and the funeral home handling arrangements. An obituary gives the families the ability to tell much more about their loved one.
5. For obituaries, select a template. There are three options. A pending notice is brief. It says the person has died and lists the funeral home. A standard obit (on the right) lists service information and the funeral home. It does not include biographical information or list survivors or predeceased by. The middle option is a regular obituary. A regular obituary can include service information, biographical information, list “survived by” or “predeceased by”, and may include a photo and/or emblem.
6. Complete the form, making sure all required fields are complete. Upload a photo and crop to a headshot if needed. All photos will publish in color, unless a black/white photo is submitted. Optional emblems can be chosen as well as funeral home logos if desired.
7. Select the date(s) you would like the obituary to appear in The Messenger, publishes Monday-Saturday.
Deadlines for publication are:
For a Tuesday-Friday publication, the deadline is 5 p.m. the day before.
For a Saturday publication, the deadline is Friday at 5 p.m.
The Saturday paper has a Sunday billing date, so choose Sunday when scheduling the obituary.
For a Monday publication, the deadline is Sunday at 5 p.m.
8. Click “Preview Your Notice” to look at how the obituary will appear.
9. Complete payment or billing information.
Farmers need a written estate and succession plan
ISU Extension can help
By ALAINA FRIESLEBEN and KRISTINE TIDGREN ISU Extension
AMES — None of us likes to think about death. It’s upsetting to acknowledge that dad or grandpa just had his second heart scare. He has a pacemaker now. Mom or grandma, too, can’t complete livestock chores like she once could. As older generations age, so do younger ones, and some aren’t sure if they want to return to the century-old family farm as generations before them have. Maybe some are prepared to pursue ownership — but need help getting started.
Legacy. Conflict. Discomfort.
Stress. Procrastination.
These are just a few of the reasons fewer than 44% of Iowa farmers with under 1,000 acres have a written estate and succession plan.
An Iowa woman puts it plainly when reflecting on her family farm’s impending transition: “We just don’t want to bring it up.”
The issue
Whether planned or not, a major transfer of agricultural assets is approaching within the next one to two decades.
Today, two-thirds of Iowa farmland is owned by individuals aged 65 and older. Landowners aged 75 and older now own a record 37% of all acres.
According to Kristine Tidgren, director of the Center for Agricultural Law and Taxation and Dolezal adjunct associate professor of agricultural education at Iowa State University, these demographics make farm transition planning increasingly urgent.
“I’ve learned that (retirement) is not always a goal for a lot of farmers, but nonetheless, for a lot of them, their health will cause them to have to slow down and not be able to do all the same things on the farm that they’ve been able to do in the past,” she said.
“Like it or not, things are going to have to transfer when we’re looking at that demographic.”
For many families, the question is both practical and deeply personal: How can this farm continue?
The barriers
Despite the inevitability of farm transition, estate and succession planning is often delayed.
One reason is purely emotional. Planning for the future requires people to confront mortality and a transfer of control in an operation they have spent decades building.
“I think we all realize it’s something that’s not very fun to do because it does make us think about things that are hard, like, ’I won’t be able to do this forever. I won’t be in charge of my farm forever,’” said Tidgren.
Family dynamics pose another significant barrier. Conversations about inheritance, ownership and management responsibilities can become uncomfortable.
Who gets what?
Who
is entitled to what?
Who will stay and who won’t?
Will anyone?
Fear of family conflict often stalls open, honest and equitable conversations.
“People are afraid that fights will erupt. So they just keep it secret and let the kids deal with it,” said Tidgren. “But that just means that after you’re gone, your kids likely won’t be connected very well because there might be disputes that didn’t need to happen.”
At its core, farm transition planning requires something many farmers find difficult: relinquishing control.
“It’s a very hard thing to do because it was in many ways that control that made the business successful,” Tidgren noted. “Part of the responsibility that comes along with that is the responsibility to learn, to turn it over and to relinquish.”
For farm families already managing demanding day-to-day operations, the process can feel overwhelming.
But what if it moved from reeling to rewarding? Confusing to clear? From existential to exciting?
That’s where education and preparation can make a difference.
“We’re here to help,” said Tidgren.
The solution
Tidgren and a team of 14 interdisciplinary specialists developed the Estate and Succession Planning for the Farm Portal, an interactive online resource designed to guide farm families through the planning process.
The portal includes hours of educational videos, case studies and practical resources covering the legal, financial and communication aspects of estate and succession planning. Users can explore the materials at their own pace and focus on the topics most relevant to their situation.
As an online resource, the team will continuously make updates to ensure it remains a reliable and evolving source of accurate information. It complements the Estate and Succession Planning for the Farm workbook, which has been used by many farm families planning for transition. The online platform expands on the workbook with an educational approach.
“We’ve never had a program where we brought everybody together and said, ’let’s just come together to try to make a very complete educational program,’” said Tidgren. “It’s much more in-depth than anything we found out there in terms of resources to educate farmers. We’re not selling anything. We are just objective extension professionals. You don’t pay us by the hour to find those things out.”
The portal features several types of resources:
Estate and Succession Planning Video Chapters. Approachable lectures from ISU attorneys guide users topic by topic. The chapters supplement the Estate and Succession Planning for the Farm workbook.
Frequently Asked Questions. In a conversational format, Tidgren and Kristiana Coutu, director of the Beginning Farmer Center at ISU, discuss the most common questions they receive about estate and succession planning for the farm.
Case Studies. Extension farm business specialists review various case studies. Topics include communication breakdowns, tragedies, contingency planning, blended families, labor management, and insurance options.
Communication Resources. Kiley Flemming, executive director of Iowa Mediation Service, guides learners through communication tools to address family communication conflicts and best practices.
Tools and Resources and Helpful Links. The portal provides a list of additional resources for users to learn beyond the portal.
The impact
Feedback suggests that the portal can help families save time and money as they prepare to work with tax professionals.
According to Tidgren, 56% of users said it would save between five and 15 hours of attorney work, and 25% said it would have an economic impact of more than $25,000.
“Those numbers are telling,” she said. The portal is not intended to replace professional legal or tax advice; rather, it prepares farm families for those conversations so they can work more efficiently and develop more thoughtful plans.
Previously available for a $75 lifetime subscription, the portal is now offered at no cost for users.
“Because we have gotten so much support for this project, we are going to be able to offer it free of charge to our people,” Tidgren shared.
“We want to close that gap. We want people to have written succession plans. We want to be that partner in their planning process.”
For Tidgren, estate and succession planning impacts more than the farm; it maintains the vitality of rural communities across Iowa.
“To keep the rural communities vibrant, we need to have the farm communities strong. The only way to do that is to have good planning in place that allows them to carry on and continue.”
To begin your Estate and Succession Planning journey, visit the Center for Agricultural Law and Taxation website.
For more information, contact Tidgren at ktidgren@iastate.edu.
How to write your own last will and testament
Few people, young or old, look forward to writing a will. A will is not an easy subject to broach, but it is important to have documents in place to ease the burden for family members.
When a person dies without a will, his or her assets might not go where he or she intended. In some instances, assets might go to the government. For parents who die before their children are grown, a will can also serve as a legal document indicating a plan for custody of the kids.
Although it is often preferable to consult with a local estate-planning attorney who understands the language and legalities surrounding a will, it is also possible to write a will yourself. There are forms that can be purchased from office-supply stores, or a will can be prepared online by answering questions and then generating a form to print. The will also can be typed or handwritten. Handwritten wills are called holographic wills and may not be recognized unless written during an emergency situation, such as a fatal illness.
Laws regarding wills vary based on where you live. Therefore, learn the legalities before preparing a will so you will have a document that holds up in a court of law and can be executed to your desires. Here is some of the basic information that may be included in your will.
* Include your name, address, date of birth, and social security numbers if they will better help identify you should there be confusion.
* State that you are of sound mind when writing this will and of contractual capacity.
* Write a statement indicating that this will revokes all other wills that may have been executed before.
* List the names and addresses of all of your children. If the children are minors, at this point you can also specify your wishes with regards to their guardianship. List the names and addresses of the people whom you wish to have custody of your children.
* Appoint an executor or executrix to carry out the affairs of your estate and instructions specified in the will. This person typically must be over the age of 18. Select someone whom you trust to honor your wishes.
* Indicate how you want the executor to handle your financial affairs, including paying taxes, funeral costs, final expenses, etc. At this point you also may want to spell out where you would like to be buried and any specific requests with regard to the funeral, viewing, and any other funeralrelated details.
* Indicate the executor has permission to sell your home and personal belongings that are not included in personal gifts to be distributed.
* List any gifts you would like to be distributed to certain people. This may be a doll collection to a daughter, coins to a son, china to an aunt, etc.
* Specify the percentages of your assets to be distributed should the listed beneficiaries survive you. Maybe you want to divide your estate evenly between two children. If so, allocate 50 percent to one and 50 percent to the other. You may have more specific breakdowns. Should these people not survive you, you can establish an alternate or list nothing, in which case the assets will be put back into the general pot.
* Include a residuary clause that states how to distribute any remaining assets.
* State whether you want the executor to be reimbursed for any expenses that result from executing the will.
* Indicate that you would like the executor to post bond as a form of insurance so that the executor can’t run off with the money for himself.
* Name an alternative executor should the first pass away before executing the will or if he or she is unable to serve upon your death.
* Sign the will in front of two or three witnesses (check what is required where you live) and a notary public. The witnesses cannot be anyone named in the will.
This article is intended as general information about what is typically covered in a standard will. It should not be taken as legal advice. Prior to implementing any of these tips, consult with an attorney certified in estate planning.
Financing funerals
Many people may think their funeral costs will be covered by their life insurance policies. However, that isn’t always the case and certain complications can arise. According to Lincoln Heritage Funeral Advantage, the average funeral costs between $7,000 and $10,000. It can be easy to overlook planning for such a large expense, and many people may think their funeral costs will be covered by their life insurance policies. However, that isn’t always the case and certain complications can arise. The funeral planning information guide Funeral Basics states that sometimes insurance policies become invalid if payments have not been made. Policies may have liens on them, or some named beneficiaries may no longer be alive. This can stall the process as issues are worked through. In addition, it can sometimes take between six and eight weeks for beneficiaries to receive life insurance policy payouts. Since many funerals take place within a week of a person’s death, it’s unlikely that surviving family members will be able to finance funerals with life insurance payouts. In addition, some policies may not be assignable, which means the benefits cannot be assigned to go to a third party who will file the claim for you (i.e., the funeral home or an assignment company with which the funeral home partners). It’s important to determine if an existing policy is assignable and to take appropriate measures if it is not. Individuals may want to consider burial insurance or preneed funeral insurance. Another option is to use preplanning services, which allow people to prepay for funeral expenses and make planning decisions regarding the services and burial so that family members will not be tasked with financing and/or planning a funeral during a difficult time in their lives.
WHY BUY LIFE INSURANCE?
Facing one’s mortality and the prospect of leaving family members behind is not always easy. Death, financial security and planning for the future are all difficult subjects, but planning ahead can make matters much easier in the long run.
Life insurance needs frequently come up when making plans, and many people find that purchasing a life insurance policy is a worthwhile investment. Life insurance holds an important place in overall financial planning. One of the most apparent benefits of life insurance is that it will provide a considerable sum of cash upon the insured’s death, which can be put toward the cost of funeral arrangements, housing and dependent care.
Beyond end-of-life bills and care, life insurance can offer other advantages, life insurance can provide a family with a financial safety net. When a beneficiary is named, life insurance can serve as an inheritance for that person or people. Heirs may face estate taxes after a loved one dies, and life insurance benefits may help offset all or a portion of the costs.
Business owners also can use life insurance policies to their advantage. Including life insurance with the list of other benefits
offered to prospective employees can entice top-notch candidates. Sole proprietors may use life insurance as a business continuation plan so that insurance proceeds can keep the business in the black until it is sold or a replacement owner is found.
Shopping for life insurance requires careful research and an understanding of the products available. Consumers should have a thorough understanding of term and whole life policies, what premiums will cost, what the death benefit will pay, and if there are any living benefits. For example, living benefits may cover some costs for chronically or terminally ill people.
Working with an experienced life insurance advisor can help people navigate the types of policies available to them.
Services offered by funeral homes
The period surrounding the death of a loved one can be difficult to navigate. Mourning a recently deceased family member or friend can dominate individuals’ thoughts, compromising their ability to devote much time and energy to anything else.
Some people decide to pre-plan their funerals in an effort to ensure their wishes are honored upon their death. Pre-planning also can afford survivors more time to grieve and ensure they won’t need to make hard decisions at a difficult time in their lives. When a deceased individual makes no such plans, family members are tasked with planning the funeral, a process that can be simplified with the help of experienced staff at a nearby funeral home. Funeral homes offer an array of services that can ensure ceremonies honor the life of the deceased and take some of the pressure off that person’s surviving family members.
• Honor the deceased:
No two people are the same, so there’s no one-size-fits-all template for a funeral service. Funeral home staff recognize that and can often help families identify unique traits about the deceased that can be conveyed during the ceremony. Whether it’s playing a favorite song or choosing an especially meaningful passage from a religious text or a favorite book, funeral home staff will work with families to personalize the ceremony as much as loved ones desire.
• Establish the desired ambiance:
Funerals tend to be somber, but they also can be celebratory. Funeral home staff can help families establish the desired tone of the service by showcasing how the viewing space can be decorated and prepared for visitations.
• Organize the ceremony:
Funeral home staff also can help grieving families organize the ceremony, including contacting clergy to preside over the service. Funeral staff also may reach out to extended family members who immediate family may want to perform certain functions in the ceremony, such as reading passages and serving as pallbearers. Funeral directors also may request military honors for the ceremony if the deceased is a veteran.
• Burial details:
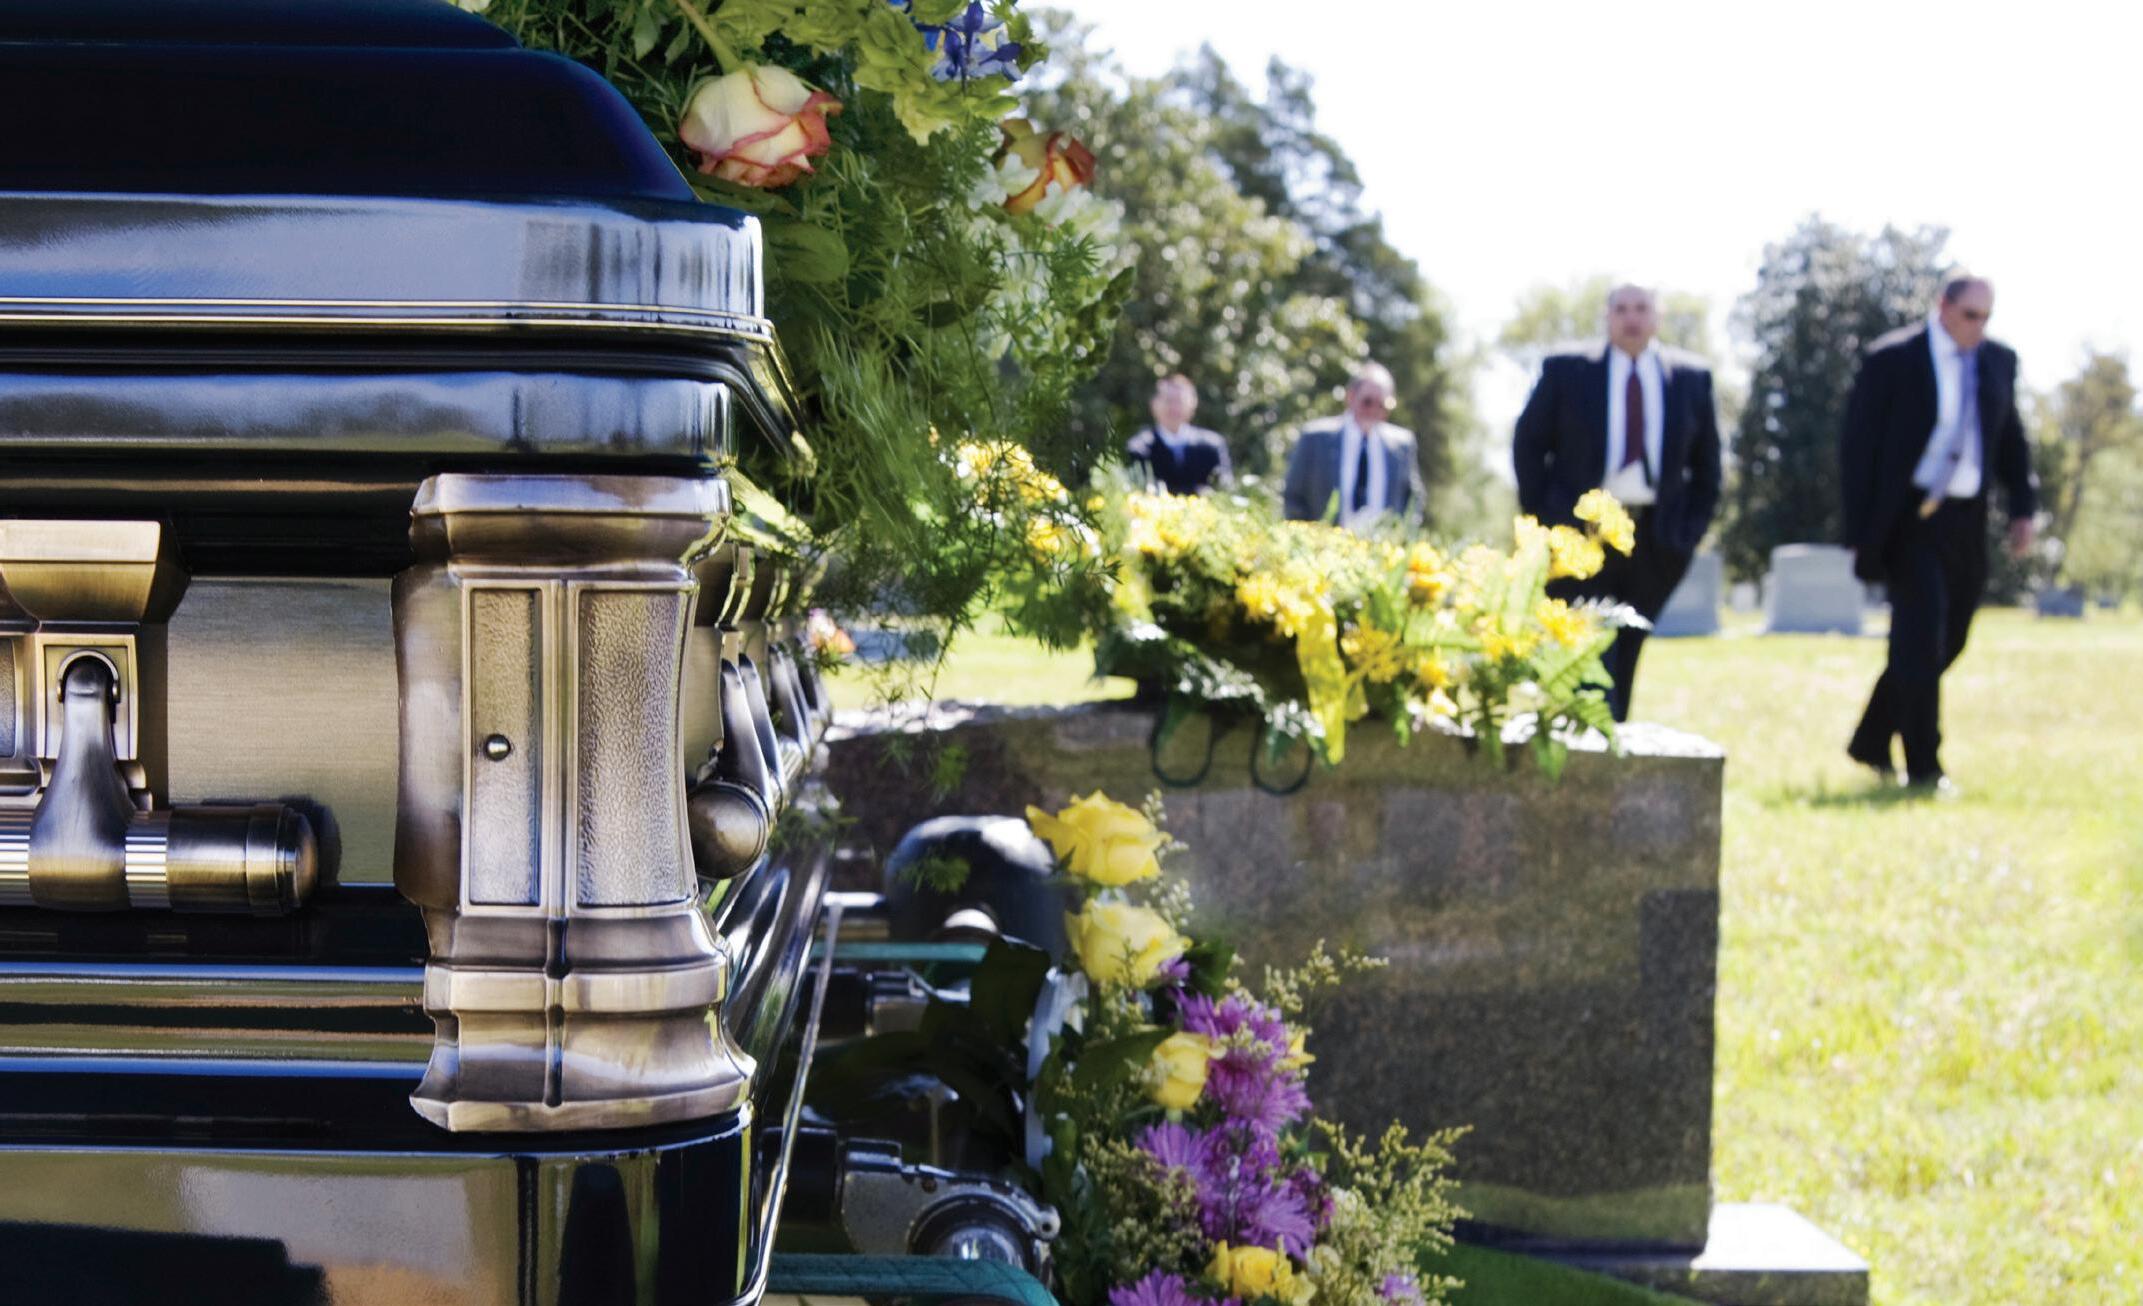
If the deceased is being buried, funeral staff can contact local cemetery officials and get the details on the purchase of a plot if no plot has been purchased previously. Funeral staff also can help families choose a casket and burial liner and organize additional details that grieving relatives may know little about. If the deceased is being cremated, funeral home staff can coordinate the cremation process and help family members choose an appropriate urn.
Funeral homes provide an array of invaluable services to families mourning the loss of a loved one.
Memorial Day
May 26th is a special day... May 25th is a special day... A time for memories, special tributes to those friends and loved ones who have
Take this opportunity to acknowledge that special someone by placing a photo and/or a brief message in The Messenger on May 23rd. Enclose your own verse with the following form, or verses
Hurry, Please submit by Wednesday May 6th, 2026
In my heart your memory is kept alive, cherished and never forgotten. Love and miss you, Jean