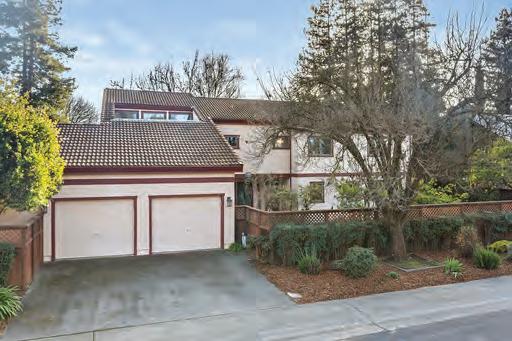












Q: I’m not sure if I should seek the advice of an attorney so your feed back would be greatly appreciated. My town house (in Vacaville) is cracking in several areas including the downstairs, upstairs and garage. I reported this to my homeowners association in June. A couple of contractors have come by and they suspect there’s a water leak below the foundation in my kitchen. I con tacted my personal household insurance agent and he seems to be the most effective person to get things rolling, meaning that the homeowners association has been dragging its heels.
A couple things that are note worthy: The president of the association is my neighbor and my Realtor. The vice president of the association is a Realtor who has sold these units over many years and has actually lived in my unit. She disclosed to me that there was a hot water leak here several years ago. She has also taken the initiative to have contractors come to look at my problem. Anyway, I realize the insurance agents for the association, as well as my own, will be looking out for their best interest and I should probably seek the advice of an attorney. Is there any advice you can provide me regarding this?
hold off considering any legal action until the contractors and insurance companies stop trying to work with you.
I’m guessing the biggest cause of the delay is that there is a factual debate regarding
If the problem occurred in a typical house, it’s pretty clear that the homeowner would
With condominiums and townhouses, the analysis
These types of developments utilize common areas which are shared by all the owners. They include walkways, driveways, swimming pools, and the like. The development’s roofs usually fall into this category as do the spaces between the walls, although not the inner surface of those walls.
Typically, owners of townhomes are responsible for repairs within their units.
For example, if the hose leading to your faucet ruptures beneath the sink, it’s pretty clear you would have to fix it.
Affordability is one of the key issues today for voters and homebuyers in our real estate market and all over the Bay Area and Sacramento region.
The U.S. government has been struggling with affordability, too, since 2001 when the Gross Domestic Product was worth around $10.6 trillion, and our total debt was $5.5 trillion.
Now, for the first time since World War II, the amount of our debt, $39 trillion, is more than the value of our entire GDP at $32 trillion. This is one of the reasons banks and countries all over the world are accumulating hard assets like gold, silver and real estate.
Our debt is up 700% since
our last balanced budget in 2001, and now the interest on this debt will cost us nearly $1 trillion next year, which is more than our budget for the military. Can you imagine owning a house worth $400,000 in 2001 and owing $250,000 on your mortgage and credit cards, and then 25 years later owing $1.75 million in debt and owning a house worth only $1.5 million?
This is called being upside down and moving in the wrong direction. This $300 billion to $500 billion in fraud we are all hearing about is serious business, and not only hurting the taxpayers, but it is also hurting the people that need federal help the most, the middle class
buyers who need affordable childcare and first-time homebuyer programs.
Buy a house and get it paid off, invest monthly, and stay out of bad debt like high-rate credit cards and personal loans, and let’s hope the GDP can double over the next 25 years and the debt can remain the same or go down because if not, we will be burnt toast.
Jim Porter, NMLS No. 276412, is the branch manager and senior loan adviser of Solano Mortgage, NMLS No. 1515497, a division of American Pacific Mortgage Corporation, NMLS No. 1850, licensed in California by the Department of Financial Protection and Innovation under the CRMLA / Equal Housing Opportunity. Jim can be reached at 707-449-4777.
A: Frankly, it sounds like people are working on the problem.
If contractors have looked at the situation and rendered opinions, and insurance investigators are indicating that they might be able to help, I’d suggest that you
If the copper pipe behind an interior wall leaks, it is often less certain who is responsible. But if a similar pipe breaks behind a wall that is shared between two units, the homeowners association is usually responsible for its repair.
In your case there is most likely a debate going on behind the scenes regarding whether your insurance company or the homeowners association’s
See Jones, Page 4
What are some overlooked
This time of year, many homeowners turn their attention to spring projects and outdoor upgrades. But before diving into what’s next, it’s impor tant to take a closer look at what the colder months may have left behind. Winter can quietly take a toll on your home – and some of the most common issues are also the easiest to overlook.
The freeze-thaw cycle can impact your home’s exterior in ways that aren’t immediately obvious. Small cracks in siding, driveways or your foundation can form as materials expand and contract in cold temperatures. These cracks may seem minor, but they can widen over
time, allowing water to seep in and cause more serious damage. Another commonly overlooked issue is flooring damage inside the home. Seasonal moisture changes can cause wood floors to expand, shift or become uneven, leading to loose boards or small gaps. While these issues may seem cosmetic at first, they can become safety hazards or worsen over time if not addressed early. Outdoor fixtures are another area where hidden damage can surface. Freezing temperatures can cause hoses, sprinkler systems and outdoor faucets to crack – even if they weren’t in use. These issues often go unno-
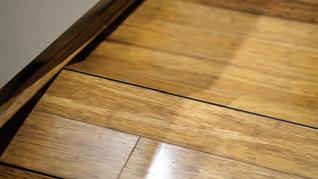
Loose or uneven floorboards are often overlooked after winter, but addressing them early can help prevent safety hazards and more costly repairs.
ticed until you turn the water back on, potentially leading to leaks and water waste.
Finally, don’t overlook decks, patios and walkways. Exposure to snow, ice and salt can weaken materials, loosen
Hicks,
TED ROSSMAN BANKRATE.COM
My wife and I bought our home in 2013 using a $417,000 30-year mortgage at a fixed rate of 4.625%. In 2020, we paid it off 23 years ahead of schedule, saving about a quarter of a million dollars in interest.
Owning our home without a monthly payment provides tremendous peace of mind. There’s a lot of “sleep at night” value associated with not worrying about those payments. Our shelter is secure even if I lose my job or the stock market tanks, you name it.
What worked for us understandably isn’t an option for everyone – and it admittedly required some thoughtful sacrifices on our part to make it happen – but if you can swing it, here’s what you stand to gain beyond those restful nights of sleep.
The savings sound impressive, but many financial experts would mathematically push back on our decision, pointing out that 4.625% is a relatively low cost to borrow money. Instead of paying off our mortgage early, some would say we should have invested the extra money in the stock market where historical returns have averaged about 10% a year.
But besides the peace of mind (which is considerable), the opportunity math works out better than some might think. Consider that we can now afford to take more risk with our investments. My wife and I are
Beyond the long-term benefits, being mortgage-free also means we’re able to spend more freely on shortterm opportunities, such as travel and after-school activities for our kids. If we still had a hefty monthly mortgage payment, we wouldn’t be able to do all those things.
in our early 40s, and our retirement plans are invested 100% in stocks. The conventional wisdom says your stock allocation should be 100% minus your age, or perhaps 110% minus your age given that people are living longer these days. Under that guidance, we should be invested about 60%-70% in stocks with the remainder in safer instruments like bonds and cash.
But we can push the pedal to the metal with a riskier (and, we hope, more rewarding) stock allocation in part because our mortgage is paid off, which removes considerable risk from other parts of our financial lives. The stock market is inherently risky in the short term, but his-
torically rewarding in the long run. You could lose money in stocks today or this month or even this year, but over a time horizon of 10 years or longer, it’s virtually certain you’ll come out ahead.
Beyond the long-term benefits, being mortgage-free also means we’re able to spend more freely on short-term opportunities, such as travel and after-school activities for our kids. If we still had a hefty monthly mortgage payment, we wouldn’t be able to do all those things.
Lastly, because our housing is secure, we can get by with a smaller emergency savings fund, freeing up that money for other
long- and short-term opportunities. The standard advice is to have three to six months’ worth of expenses in the bank. Without a $2,000+ monthly mortgage principal and interest payment, that’s $6,000 to $12,000 less that we need to incorporate into our rainy day fund.
We aren’t completely free from housing costs, of course. For starters, there’s the pesky issue of property taxes. We live in a New York suburb with high property taxes (approximately $20,000 per year, or an average of about $1,667 per month). We
also pay roughly $2,800 a year ($233 a month) for homeowners’ insurance. And there are the inevitable maintenance issues. This winter, for instance, we needed several thousand dollars’ worth of plumbing and heating repairs, plus a new dryer. Because of the hidden costs of homeownership, our housing isn’t completely free even though we paid off our mortgage. Still, doing so created a lot of room in our monthly budget for those other costs of homeownership. If we’d kept our 30-year mortgage, we’d be paying $2,144 per month in principal and interest, plus another roughly $1,900 in property taxes and homeowners’ insurance for a grand total of about $4,000 per month in housing costs (not including the more variable expenses of maintenance and repairs).
Eliminating our mortgage lowered our monthly housing payment by half. That’s like living in the New York City area but paying the housing costs of a much more affordable town in the South or Midwest.
So how, exactly, did I manage to pay off my mortgage early?
We were fortunate to be in a position to pay off our mortgage as quickly as we did. The breakthrough event came in 2017 when Bankrate was acquired, accelerating the vesting of several years’ worth of stock options. I used most of that money to recast our mortgage. With a recast, a little known cousin of refinancing, you put
Paying, Page
TOTAL SALES: 3
LOWEST AMOUNT: $600,000
HIGHEST AMOUNT: $900,000
MEDIAN AMOUNT: $610,000
AVERAGE AMOUNT: $703,333
258 East E Street - $610,000
03-03-26 [3 Bdrms - 1434 SqFt - 1998 YrBlt]
310 West M Street - $900,000
03-06-26 [4 Bdrms - 2675 SqFt - 1973 YrBlt], Previous Sale: 09-22-21, $1,000,000
2135 Via Alta - $600,000
03-05-26 [3 Bdrms - 1497 SqFt - 1969 YrBlt]
TOTAL SALES: 4
LOWEST AMOUNT: $550,000
HIGHEST AMOUNT: $801,000
MEDIAN AMOUNT: $603,500
AVERAGE AMOUNT: $639,500
1520 Abraham Court - $801,000
03-04-26 [4 Bdrms - 2302 SqFt - 1996 YrBlt], Previous Sale: 07-17-23, $700,000
635 Evans Road - $550,000
03-03-26 [3 Bdrms - 1462 SqFt - 1994 YrBlt], Previous Sale: 05-02-02, $240,000
830 Green Drive - $582,000
03-02-26 [3 Bdrms - 1389 SqFt - 1995 YrBlt], Previous Sale: 08-11-16, $360,000 690 Woodard Way - $625,000
03-03-26 [4 Bdrms - 1898 SqFt - 1997 YrBlt], Previous Sale: 02-14-23, $608,000
TOTAL SALES: 14
LOWEST AMOUNT: $340,000
HIGHEST AMOUNT: $915,000
MEDIAN AMOUNT: $605,750
AVERAGE AMOUNT: $612,464
4488 Avondale Circle - $730,000
03-06-26 [5 Bdrms - 3032 SqFt - 2006
YrBlt], Previous Sale: 04-17-20, $651,000 2903 Burbank Drive - $625,000
03-02-26 [4 Bdrms - 1738 SqFt - 1979
YrBlt], Previous Sale: 06-18-19, $405,000 2219 Channing Court - $548,000
03-04-26 [4 Bdrms - 2039 SqFt - 1973
YrBlt]
562 Citadel Court - $760,000
03-04-26 [4 Bdrms - 2356 SqFt - 1998
YrBlt], Previous Sale: 02-06-13, $375,000 1318 Cleveland Street - $440,000
03-03-26 [3 Bdrms - 1120 SqFt - 1954
YrBlt], Previous Sale: 10-16-25, $971,500
1419 Eisenhower Street - $340,000
03-03-26 [3 Bdrms - 923 SqFt - 1958
YrBlt], Previous Sale: 03-21-00, $116,950
901 Johnson Street - $475,000
03-04-26 [3 Bdrms - 980 SqFt - 1953
YrBlt], Previous Sale: 09-17-25, $300,000
382 Knoll Drive - $915,000
03-04-26 [3 Bdrms - 3111 SqFt - 2006
YrBlt], Previous Sale: 01-18-06, $965,000
4658 Lapis Court - $586,500
03-02-26 [3 Bdrms - 1784 SqFt - 2006
YrBlt], Previous Sale: 02-11-14, $320,000
1413 Maryland Street - $490,000
03-03-26 [3 Bdrms - 1824 SqFt - 1953
YrBlt], Previous Sale: 05-23-12, $100,000
415 Oakwood Circle - $795,000
03-05-26 [4 Bdrms - 2278 SqFt - 1988
YrBlt], Previous Sale: 10-11-23, $713,500
604 Oregon Street - $625,000
03-06-26 [7 Bdrms - 2595 SqFt - 1953
YrBlt], Previous Sale: 07-28-25, $390,000
2936 Sunbird Drive - $430,000
03-04-26 [2 Bdrms - 1603 SqFt - 1978
YrBlt], Previous Sale: 07-12-18, $322,500
2837 Watson Court - $815,000
03-03-26 [4 Bdrms - 2655 SqFt - 1995 YrBlt], Previous Sale: 04-29-08, $579,000
TOTAL SALES: 6
LOWEST AMOUNT: $320,000
HIGHEST AMOUNT: $595,000
MEDIAN AMOUNT: $399,500
AVERAGE AMOUNT: $421,500
949 Flores Way - $320,000
03-06-26 [3 Bdrms - 1667 SqFt - 1959 YrBlt]
423 Gardiner Way - $400,000
03-03-26 [3 Bdrms - 1092 SqFt - 1953 YrBlt]
2322 Melrose Landing - $399,000
03-06-26 [2 Bdrms - 2022 YrBlt], Previous Sale: 03-18-22, $425,500
422 Saddle Rock Lane - $350,000
03-02-26 [2 Bdrms - 1172 SqFt - 2013 YrBlt], Previous Sale: 08-17-18, $150,000
802 Summerset Drive - $465,000
03-06-26 [3 Bdrms - 2065 SqFt - 2000 YrBlt], Previous Sale: 07-29-05, $465,000
818 Thereza Way - $595,000
03-02-26 [4 Bdrms - 1932 SqFt - 1951 YrBlt]
TOTAL SALES: 8
LOWEST AMOUNT: $145,000
HIGHEST AMOUNT: $595,000
MEDIAN AMOUNT: $550,000
AVERAGE AMOUNT: $478,250
521 Cordelia Street - $145,000
03-03-26 [1 Bdrms - 406 SqFt - 1937
YrBlt], Previous Sale: 04-15-25, $260,000
1030 Driftwood Drive - $595,000
03-06-26 [4 Bdrms - 2030 SqFt - 2005 YrBlt], Previous Sale: 09-19-08, $295,000
942 Edgewood Circle - $408,000
03-06-26 [3 Bdrms - 1280 SqFt - 1988
YrBlt], Previous Sale: 04-04-06, $400,000
750 Harbor Park Drive - $550,000
03-05-26 [3 Bdrms - 1598 SqFt - 2003
YrBlt], Previous Sale: 05-14-18, $410,000
941 Mccoy Creek Circle - $550,000
03-02-26 [3 Bdrms - 1666 SqFt - 1994
YrBlt], Previous Sale: 07-20-22, $569,000
604 Seagull Drive - $570,000
03-03-26 [4 Bdrms - 1720 SqFt - 1977
YrBlt]
800 Spoonbill Lane - $445,000
03-06-26 [3 Bdrms - 1320 SqFt - 1976 YrBlt]
1019 Whistler Drive - $563,000
03-06-26 [3 Bdrms - 1544 SqFt - 1983
YrBlt], Previous Sale: 06-04-20, $430,000
TOTAL SALES: 17
LOWEST AMOUNT: $269,500
HIGHEST AMOUNT: $1,030,000
MEDIAN AMOUNT: $540,000
AVERAGE AMOUNT: $575,059
424 Beelard Drive - $545,000
03-03-26 [4 Bdrms - 1770 SqFt - 1967
YrBlt]
231 Berryessa Drive - $405,000
03-05-26 [3 Bdrms - 1270 SqFt - 1964
YrBlt], Previous Sale: 11-02-04, $312,500
456 Buckeye Street - $540,000
03-04-26 [3 Bdrms - 1014 SqFt - 1956
YrBlt], Previous Sale: 04-12-21, $455,000
192 Carlsbad Circle - $489,500
03-06-26 [3 Bdrms - 1598 SqFt - 1974
YrBlt], Previous Sale: 12-15-15, $300,000
107 Cavan Court - $560,000
03-05-26 [4 Bdrms - 1803 SqFt - 1978
YrBlt], Previous Sale: 09-05-17, $172,500
654 Corte Seville - $620,000
03-05-26 [4 Bdrms - 1851 SqFt - 1974
YrBlt]
451 Edgewood Drive - $410,000
03-06-26 [4 Bdrms - 1841 SqFt - 1973 YrBlt]
751 El Camino Avenue - $529,000
03-02-26 [3 Bdrms - 1376 SqFt - 1963
YrBlt], Previous Sale: 05-29-12, $194,000
7441 Leisure Town Road - $1,030,000
03-03-26 [4 Bdrms - 3137 SqFt - 1978
YrBlt]
171 Mckinley Circle - $375,000
03-04-26 [2 Bdrms - 918 SqFt - 1963
YrBlt], Previous Sale: 06-19-18, $290,000
124 Monterey Drive - $269,500
03-03-26 [1 Bdrms - 728 SqFt - 1964
YrBlt], Previous Sale: 02-19-19, $210,000
306 Oak Valley Drive - $652,000
03-02-26 [4 Bdrms - 1782 SqFt - 1990
YrBlt]
366 Peach Tree Avenue - $615,000
03-06-26 [4 Bdrms - 2386 SqFt - 1957
YrBlt], Previous Sale: 03-25-13, $315,000 1845 Quail Meadows Circle$536,000
03-06-26 [4 Bdrms - 1710 SqFt - 1994
YrBlt], Previous Sale: 07-25-17, $380,000
406 Stonecastle Way - $745,000
03-02-26 [4 Bdrms - 2110 SqFt - 1990 YrBlt], Previous Sale: 03-23-21, $628,000
319 Trinity Drive - $490,000
03-05-26 [4 Bdrms - 1402 SqFt - 1971 YrBlt]
1101 Wildplum Court - $965,000
03-03-26 [6 Bdrms - 3742 SqFt - 1999 YrBlt], Previous Sale: 06-30-99, $289,990
TOTAL SALES: 16
LOWEST AMOUNT: $180,000
HIGHEST AMOUNT: $2,100,000
MEDIAN AMOUNT: $500,000
AVERAGE AMOUNT: $605,844
91 14th Street - $389,000
03-06-26 [2 Bdrms - 886 SqFt - 1941 YrBlt], Previous Sale: 09-11-23, $384,000 1443 Alabama Street - $180,000
03-03-26 [2 Bdrms - 1158 SqFt - 1937 YrBlt]
748 Beechwood Avenue - $375,000
03-02-26 [3 Bdrms - 1250 SqFt - 1980 YrBlt], Previous Sale: 02-18-26, $356,000
853 Benicia Road - $365,000
03-06-26 [2 Bdrms - 1102 SqFt - 1934 YrBlt], Previous Sale: 03-01-17, $284,500 1435 Broadway Street - $412,000
03-05-26 [2 Bdrms - 1090 SqFt - 1942 YrBlt], Previous Sale: 10-30-25, $275,000
930 Brookwood Avenue - $350,000
03-04-26 [3 Bdrms - 1119 SqFt - 1955 YrBlt]
419 Clark Drive - $790,000
03-05-26 [5 Bdrms - 2984 SqFt - 1991 YrBlt], Previous Sale: 00/1990, $111,000 4118 Georgia Street - $632,500
03-02-26 [3 Bdrms - 1811 SqFt - 1963 YrBlt], Previous Sale: 11-09-21, $550,000 1466 Granada Street - $670,000
03-03-26 [4 Bdrms - 1931 SqFt - 1978 YrBlt], Previous Sale: 11-26-25, $435,000 116 Greeves Street - $655,000
03-06-26 [4 Bdrms - 1578 SqFt - 1972 YrBlt], Previous Sale: 05-16-23, $645,000 1014 Henry Court - $565,000
03-05-26 [3 Bdrms - 1298 SqFt - 1954 YrBlt], Previous Sale: 11-14-25, $375,000
113 Laguna Street - $405,000
03-04-26 [3 Bdrms - 1400 SqFt - 1944 YrBlt], Previous Sale: 09-25-02, $162,000
26 Laurel Street - $475,000
03-05-26 [3 Bdrms - 875 SqFt - 1944 YrBlt], Previous Sale: 04-17-19, $380,000
137 Pirates Cove - $2,100,000
03-06-26 [4 Bdrms - 1661 SqFt - 1987 YrBlt]
293 Saybrook Way - $805,000
03-06-26 [4 Bdrms - 2579 SqFt - 1988
YrBlt], Previous Sale: 05-10-21, $790,000
223 Wedgewood Court - $525,000
03-04-26 [3 Bdrms - 1008 SqFt - 1955
YrBlt], Previous Sale: 10-11-25, $350,000
From Page 2
boards and create uneven surfaces. Beyond appearance, this becomes a safety concern, increasing the risk of trips and falls as you begin to spend more time outside.
It’s also worth checking areas that are easy to ignore during colder months, like basements and attics. Look for signs of moisture, insulation issues or pests that may have taken refuge during the winter. Catching these early can help prevent more extensive damage as temperatures continue to rise.
The transition into spring is one of the most important times of year for home maintenance. Taking a proactive approach now can help you avoid emergency repairs, protect your investment and keep your home running smoothly. For anything beyond a quick fix, working with a skilled pro can help ensure the job is done right – saving you time, stress and often money in the long run.
Tweet your home care questions with #AskingAngi and we’ll try to answer them in a future column.
From Page 2
company is responsible.
In my experience this can take some time to sort out, although if your insurance company believes it’s not their responsibility, they will likely apply pressure on the HOA for you.
I suggest you give the process enough time to see if someone will step up to the plate and make the repair.
If, after another few months, nothing happens, you may be forced to consult an attorney.
Right now, time is on your side.
Tim Jones, Esq., is a real estate attorney in Fairfield. If you have any real estate questions you would like to have answered in this column, you can send an email to AllThingsRealEstate@ TJones-Law.com.
ABOVE
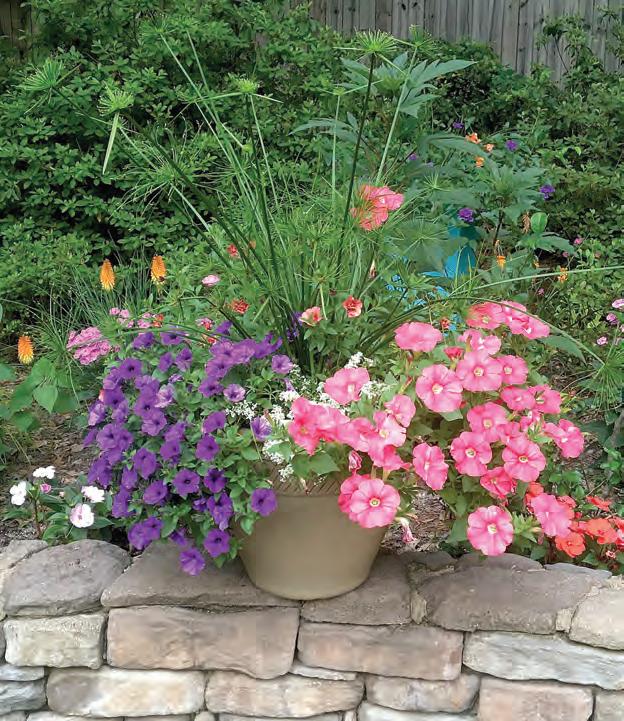
In recent years, Queen Tut papyrus has become one of my favorite thriller plants for my mixed container designs. If you are wondering how I can consider a grasslike plant as a thriller while surrounded by col orful flowers, then I challenge you to grow it. You too will see that it is not only a thriller but the ulti mate in art and architecture. It is cold in zones 9a-11b but then again, our application is usually as an annual anyway. With very little effort I can coax these through a zone 8 winter. If you fear needing the jaws-oflife to extract the frozen carcass (kidding) from last year’s pots, I assure you they are not nearly the challenge as some of the other papyrus relatives.
by accident. It stands to reason: If you are using Queen Tut mixed with flowers, something will happen. The key is just being there to witness it.
Catching an eastern tiger swallowtail feeding on the nectar of flowers below while the Queen Tut’s tufts of foliage above creates a memorable moment. But having a Rockin Fuchsia salvia blooming up among the Queen Tut tufts opens the door to see the acrobatic wonder of a ruby-throated hummingbird going for its happy meal.
The Garden Guy was giddy
See Winter, Page 6
They will reach 18 to 24 inches in height with a spread of 12 to 18 inches. In my containers they are milder mannered than that, though I suppose if you are measuring top spread, that is spot on.
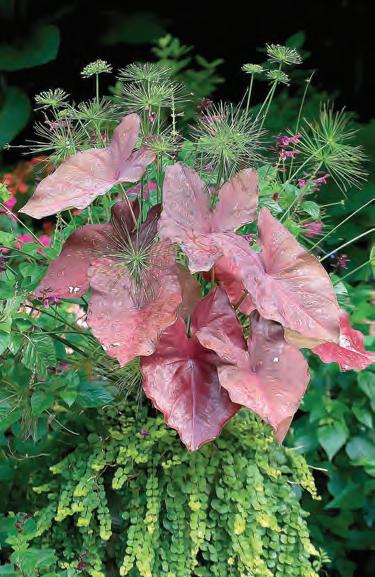
Though I have only used them in containers I can see how they will have an equally architectural look in beds too. The stems sturdily position themselves with their spider-like tufts mimicking miniature palms. But never underestimate their talent for bending ever so slightly toward colorful foliage or flowers to create a living piece of art. Such was the case of where I caught one bowing to the new Heart to Heart Crème Brulee caladiums.
Speaking of caladiums, one of my favorite planters featured Queen Tut papyrus and Heart to Heart Burning Heart caladiums with Goldilocks Creeping Jenny falling over the rim. It was absolutely riveting.
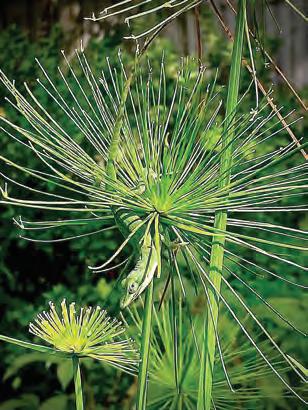
Some of my favorite compositions I would have to credit to wildlife, and thus it was quite

NORMAN WINTER/TNS/PHOTOS
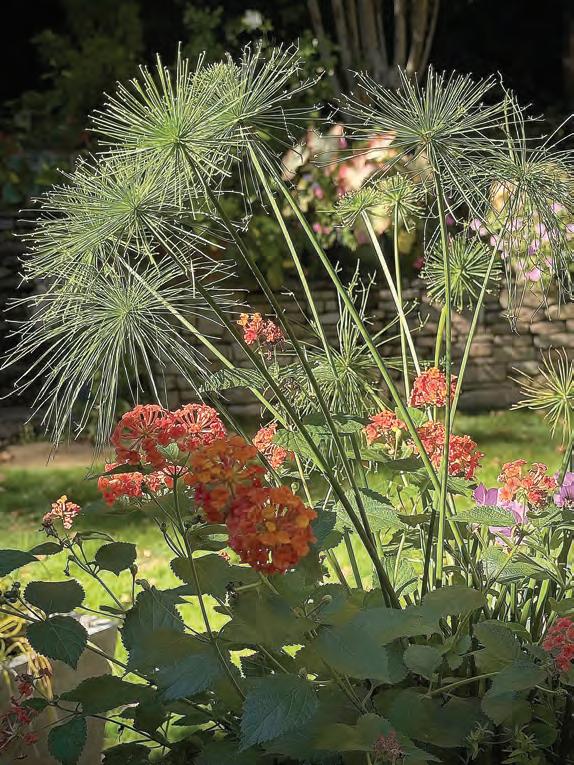
The sun captures the intricate design of Queen Tut papyrus tufts of foliage reaching above Luscious Marmalade lantana.
From Page 5
and surprised to find a green anole lizard draped through the Queen Tut tufts while on the hunt for his dining delight. It is a bird-eat-bug world out there or in this case, lizard-eatbug brunch.
So I’ll use the Graceful Grasses Queen Tut papyrus with Heart to Heart caladiums, Supertunia petunias, Luscious lantanas and countless others. The Queen Tut will immediately look effective while the partners are playing catch up. Oh yes, if you have a water feature at your home, then Queen Tut may be the plant for which you have been searching.
Planting season is at hand. I hope you will try Graceful Grasses Queen Tut papyrus. They have won awards from Canada to Florida including a Perfect Score at Oklahoma State University.
From Page 3
a lump sum toward your mortgage principal and the lender recalculates your remaining principal and interest fees over the existing term at the existing interest rate. I put $250,000 into a mortgage recast, lowering my mortgage payment by $1,400 per month. It was a quick and easy process. I paid a onetime $250 fee and filled out a short form.
Refinancing, on the other hand, involves taking out an entirely new loan. It’s a popular tactic when mortgage rates fall since refinancing pays off your old loan and gets you into a lower-rate product that reduces your monthly payments.
I preferred the recast for several reasons.
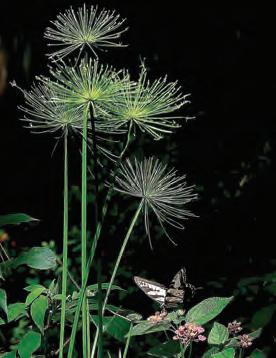
Queen Tut papyrus creates a magical look with an eastern tiger swallowtail feeding on Luscious Royale Cosmo lantana below.
Norman Winter is a horticulturist, garden speaker and author of “Tough-as-Nails Flowers for the South” and “Captivating Combinations: Color and Style in the Garden.” Follow him on Facebook @NormanWinterTheGardenGuy. He receives complimentary plants to review from the companies he covers.
One thing we didn’t do: Trade up to a more expensive home. Our income has risen substantially since we bought our house in 2013 (of course, many of our expenses have risen substantially as well – having a couple of kids will do that to you). Still, on paper, at least, we could qualify for a mortgage on a much more expensive property.
We have resisted the temptation. We got off the treadmill of monthly mortgage payments, and we don’t want to get back on it. We also genuinely like our home and have customized it in various ways over the years. Is it the fanciest house in the fanciest neighborhood? Hardly. But it suits us.
•Rates were actually a bit higher than our original loan when we did the recast in 2018.
•I didn’t want to restart the clock on another 30-year loan, or even a 15-year mortgage.
•I didn’t want to deal with refinancing’s considerable paperwork, closing costs, appraisal fees or other rigamarole.
In 2018, we didn’t have enough money to completely pay off the mortgage, but we knew we would benefit from the lower monthly payments resulting from the recast. And I figured that we could pay off the remaining mortgage principal in two or three years if we were disciplined about paying a bit extra from time to time. For example, by putting extra money in when we got a tax refund or a bonus. Or by paying more when our cash flow allowed for it, including the idea of trying to stick with the old payment at least some of the time, even though the recast meant we could pay $1,400 less that month.
ments would be $2,513. Paying an extra $2,513 in principal each year retires the loan almost six years early and saves nearly $110,000 in interest. That’s incredible, and it shouldn’t be that difficult to do.
If you get paid every two weeks, there are two months every year when you receive three paychecks. Consider putting some or all of that money toward your mortgage principal. You could also consider using other found money such as tax refunds, bonuses and gifts. Taking on a side hustle is another great way to drum up some extra cash. As is looking for ways to cut your expenses and wringing some extra savings out of your monthly cash flow.
If you’re enticed by the idea of becoming mortgage-free ahead of schedule, consider this mortgage prepayment example.
Even making just one extra monthly payment a year can trim a 30-year loan into a 24-year payback cycle.
If you borrowed $400,000 for 30 years at a fixed rate of 6.44% (the current average, according to Bankrate), your monthly principal and interest pay-
To be clear, paying off a mortgage ahead of schedule is a luxury. If you have credit card debt at 20% interest and a mortgage at 6%, put your extra money toward the credit cards. If you have a dangerously low emergency savings cushion, save for a rainy day before prepaying a 30-year loan.
But if you have a little extra money now or in the future, prepaying a mortgage provides tremendous peace of mind as well as tangible financial benefits.






















On the night of March 2, millions of workers around the world opened their laptops and found Claude – one of the world’s most widely used AI assistants – was down. The outage lasted hours. It was a small but pointed reminder of how dependent modern work has become on AI, and how fragile the infrastructure behind it can be. The grid that powers that infrastructure is under more strain than most people realize –and the vulnerabilities don’t stop at the data center door. They come home with us.
Today, the world is spending hundreds of billions of dollars building the energy infrastructure needed to power AI, including data centers, grid upgrades and new power plants. That scale is just beginning. Fast forward to 2030, when the International Energy Agency (IEA) projects global data center electricity consumption will nearly double.
Here’s why: A single AI hyperscaler (like Google Cloud, Microsoft Azure or AWS) consumes as much electricity as
100,000 households, driving an estimated $720 billion in grid spending through the end of the decade.
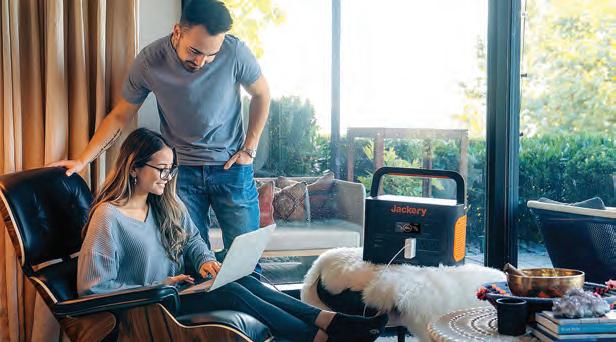
The world recognizes that AI needs a massive energy infrastructure. But what do homes need in this era of AI-powered functionality? Leading provider of innovative solar generators and renewable energy solutions Jackery has been anticipating this question for 14 years.
While data centers power the AI infrastructure, the AI revolution is rapidly moving into homes – and with it, each home needs what data centers need: reliable, always-on, clean power.
But that power is far from guaranteed. The tension between AI’s explosive energy appetite and the fragility of the grid it depends on is not a future concern – it’s playing out right now. A single AI workload consumes roughly 1,000 times more electricity than a traditional web search, while geopolitical instability, supply chain disruptions
resilience at home.
Smart homes need reliable power for optimal functionality, and this demand will be increasingly crucial over the next several years. Fortunately, Jackery has already built solutions homes need for the AI era.
and an already-strained electrical grid are exposing just how vulnerable that infrastructure is. Homes are no exception to this vulnerability. How fast is this happening? The average U.S. home has 21 connected devices today, which will only keep increasing. The AI smart home market is growing at 21.3% annually, toward $104 billion by 2034, with the smart home penetration
forecast to reach 92.5% globally by 2029.
The grid powering all of it is already under pressure. According to NERC’s 2025 Summer Reliability Assessment, several major U.S. regions – including Texas, the Midwest and the Southwest – face a real risk of supply shortfalls during peak demand periods. Most people can’t control what happens at the grid level.
But they can start building energy
The Jackery company anticipated this residential convergence 14 years ago, and has been building toward it ever since. Back in 2012, Jackery built a portable battery for outdoor adventures. Building on principles of flexibility, independence and reliability, the company’s strategy focused on developing products putting power safely and predictably in the hands of homeowners to meet growing energy needs.
Fourteen years later, the company has expanded its portfolio beyond solar generators, solar panels, and power stations into the Jackery Essential Home Backup Solution (EHB) – a whole-home energy category built around
See Energy, Page 9
From Page 8
what homeowners actually need. It matches the output of a tradi tional gas generator without the noise, fumes, fuel costs or safety hazards. It reduces dependence on an increasingly strained grid, putting control back in the hands of the homeowner. It’s a long-term investment that pays off through lower energy bills and lasting independence. And it runs on clean, renewable energy – silent, emissions-free and ready when the grid isn’t. Products like the HomePower 3600 Plus and the Solar Generator 5000 Plus bring that vision to life in homes today.
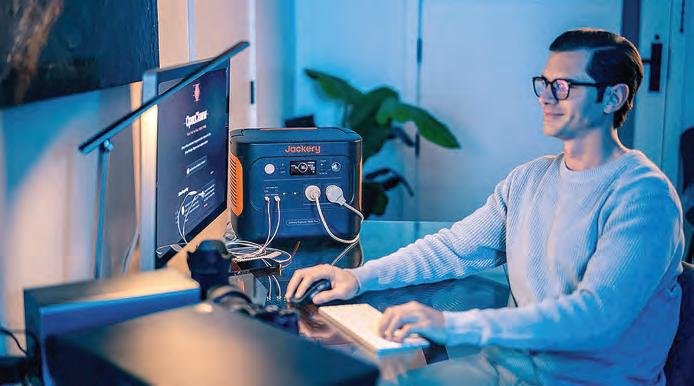
A man works at a multi-monitor computer setup illuminated in blue light, reflecting the growing technological infrastructure and energy demands behind the artificial intelligence revolution.
Summer is a season for entertaining. But as the cost of consumer goods and even necessities like food has risen in recent years, some people may be hosting a lot less often than they used to.
Today, Jackery’s vision includes groundbreaking energy solutions designed specifically for the AI era - including products on the horizon that will keep homes powered and connected even when the grid goes dark. That vision is already taking shape with innovations like the Solar Mars Bot, debuted at Consumer Electronics Show (CES) 2026, which uses AI-enhanced computer vision to autonomously drive as it offers mobile energy, intelligently repositioning itself based on light conditions and recharging using its own retractable solar panels.
The company also seeks effective global partnerships, signing a Proactive Safety Battery Cell R&D alliance with DeSay Battery to co-develop the world’s first safer and smarter DIY home energy storage solution. Jackery also founded a consortium of leading global consumer technology brands that run on its infrastructure. The Jackery Consortium shares Jackery’s commitment to catalyze the next era of energy storage, management and independence. It also helps consumers maximize energy independence by ensuring consumer devices and AI systems are compatible with their power stations.
These crucial milestones
highlight Jackery’s roadmap to the AI revolution, which the company has been actively preparing for over the past decade.
Success in times of rapid technological change depends on meeting the moment in terms of the details while also envisioning future needs. A proactive, whole-home approach anticipates energy requirements for multiple interconnected smart devices. Even better is a system that analyzes energy consumption, solar yield and live electricity prices in real time.
Anticipating problems and protecting power stations from potential safety hazards and structural damage, Jackery’s exclusive AI-powered ChargeShield 2.0 technology integrates 62 protective mechanisms, ensuring comprehensive battery management and enhanced safety for the power station and any connected devices. These technology advancements exemplify how the company invests its time and resources. Jackery sees the big picture - including the need to create a power infrastructure that other AI brands can depend on. From the R&D leadership exemplified by last year’s Desay Battery Proactive Safety AI Prismatic Cell alliance from
RE+2025 to the founding of the Jackery Consortium together with Rokid, Viture, XTOOL and Heybike, the company prioritizes strategic partnerships during this age of rapid tech developments.
Building on today’s technology, Jackery envisions the home of tomorrow as generating its own clean energy, managed with AI intelligence that’s shared across connected devices - and never going dark. Jackery is already working toward that vision.
“When Jackery started 14 years ago, our mission was simple: give people reliable power wherever life takes them. Over the past decade, we’ve earned trust by solving real problems with portable power as the way people live, work and rely on electricity has fundamentally shifted,” said Steven Wang, VP of Jackery’s Americas Business Department. “Looking ahead to the next 10 years, we’re expanding that original promise into a broader vision of power selfsufficiency, transforming the home into an intelligent, solarpowered ecosystem. This is the beginning of our next chapter, where energy is cleaner, smarter and firmly back in the hands of consumers.”
It’s important to keep in mind that memorable entertaining options are not only defined by cost. Sure that professional decorator or expensive catering service may be lavish, but it’s possible to host a gathering without putting a strain on your finances. Here are some strategies for budget-friendly summer entertaining.
• Buffets and bars: A complex, multi-course meal will be expensive, and some guests may even find it pretentious. Instead, reduce time spent in the kitchen and simplify meal service with buffet stations and food bars. Allow guests to customize their food with different toppings and ingredients, which can elevate even simple fare like tacos or burgers.
• Signature drinks: A full open bar is expensive. Keeping a few staples on hand, such as beer and red and white wine, should be sufficient. But hosts also can create a signature cocktail, make it in bulk and serve it in a pitcher. Spritzers also can stretch wine or liquor further because they are mixed with sparkling water. Remember to also make non-alcoholic offerings available. A pitcher of mineral water with fruit or cucumber slices is affordable and refreshing.
• Affordable atmosphere: There’s no need to hire a party planner to transform an entertaining space. Inexpensive tricks can go a long way. Lighting is important, and repurposed holiday lights or bistro lights will make the space intimate as the sun goes down. Even tea candles in scat-
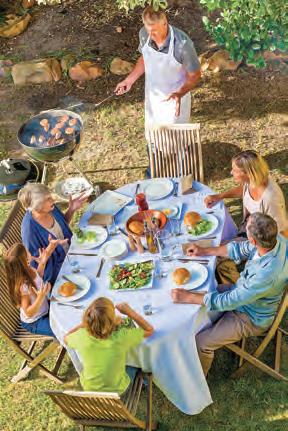
A family enjoys a backyard BBQ, embracing the carefree spirit and outdoor activities that define the summer season.
tered mason jars will create a relaxing ambiance. Utilize found items for decor, like seasonal fruits in a bowl for a vibrant centerpiece or clippings from the garden instead of costly bouquets picked up from the store.
• Music: Music is an useful means to set the mood and help guests feel comfortable, while silent space can be austere and awkward. Hosts can curate a party playlist via a free or paid music app rather than spending money on live entertainment.
• Low-cost activities: Keeping guests occupied doesn’t have to be expensive. Pass around lyrics to songs so everyone can join in on a group karaoke sessions. Board games, lawn games like cornhole, or even card games are some additional low-cost options. Pool owners have an ultimate source of entertainment without any new expenses.
Entertaining during the summer doesn’t have to be expensive. By focusing on company, fun and casual food, hosts and their guests are likely to have a good time.





$940,000
$1,025,000
$1,107,500 3182 Olympic Rd Fairfield 4 3/0 2997 326012029
$1,300,000 3114 Lomita Ct Fairfield 4 2 /2 3,200 0.95 325051938
$1,395,000
$1,445,000
$2,895,000 1783 Green Acres Lane Fairfield 5 5/1 7065 94,961 326002065
$665,000 828 Laguna St Napa 3 2 /0 1,374 0.14 325099692
$729,000 1763 E St Napa 2 1/0
$360,000