











Q: I am a senior and spend a lot of time out of town. I have been holding off selling my house in Fairfield because the market is so bad. Now I’m con cerned because the minimum payment on my adjustable-rate mortgage goes up $270 next month. Since I am holding off selling my home until, hope fully, the market improves, my adjustable mortgage is going to go up and up.
Based on my good credit, and lots of equity, the lender has offered me a five-year fixed, interest-only mort gage at 6.5%. After five years it becomes a Libor adjust able-rate mortgage. The lower payment they are quoting would really make things easier because I cannot do the $270 extra every month. I’m spoiled because I was used to the low interest rates when my adjustable mortgage started out. Since the bank’s offer includes not charging me for the escrow, appraisal, points, closing costs, all I have to do is “just sign the paper.”
Do you see any problem with this, or is there a better way to go? I realize you are a real estate attorney and not a mortgage broker, but I totally trust you, based on your clear and meaningful columns. And by the way, there is a part of me that wants to just rent the whole house out for two years, but I hate tenant stuff, and I don’t know if it’s practical.
A: Last question first: Renting out the house isn’t necessarily impractical, just nerve racking if you’re not comfortable with the potential risks.
A good tenant could pay the mortgage, or a significant part
If you think renting might be a viable alternative, I’d strongly suggest you speak to a couple of
nies and hire one to handle the the day-to-day affairs of managing the property.
Now, about your loan situation: You’re absolutely right, I’m not a mortgage broker and I don’t keep up on the loan products that are available out there. However, the loan that is being proposed to you sounds reasonable considering your ultimate goal is to sell the property before the five-year interest-only loan period expires.
Having to pay the interestonly won’t reduce the size of your payment by much, since in the early years of a loan most of the payment goes toward the interest rather than the principle anyway, but it certainly won’t hurt. There used to be loans out
See Jones, Page 4
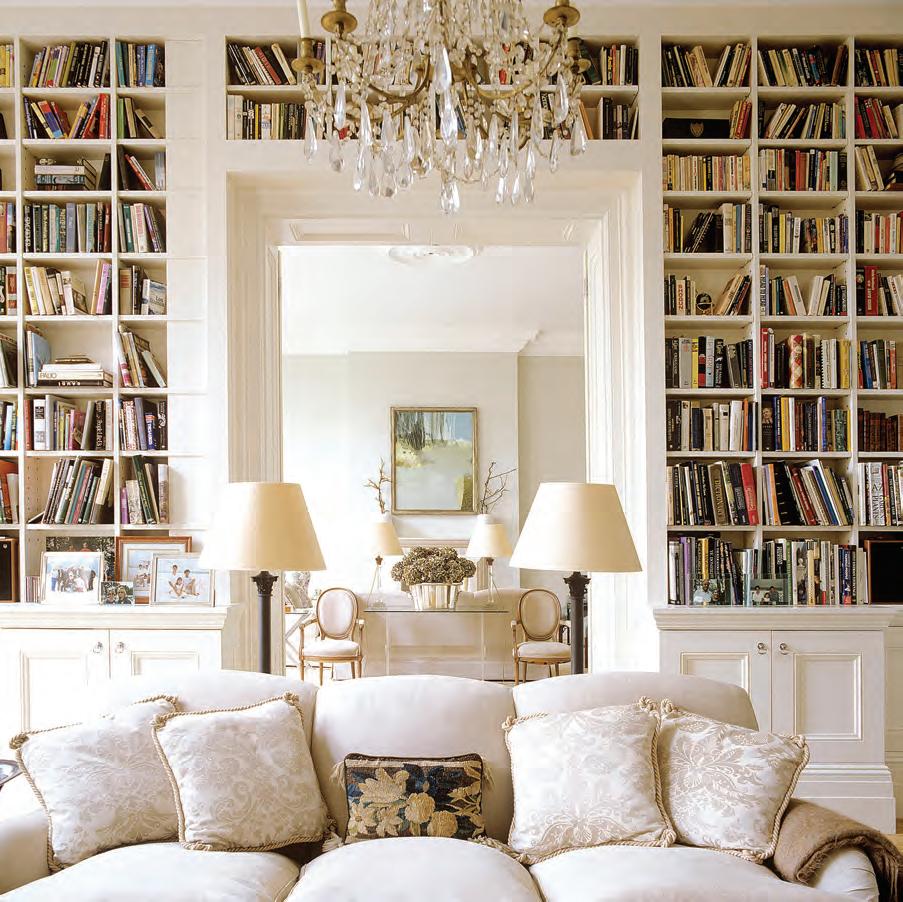
A library can feature floor-to-ceiling bookshelves and comfortable reading chairs stationed
Traditional formal dining rooms are not as necessary as they were a generation or two ago.
A recent study by Realtor.com found formal dining rooms are often the most underutilized square footage in homes, and a significant percentage of Millennial and Gen Z homeowners prefer flexible “lifestyle rooms” over dining spaces. So what can homeowners whose dining room tables are covered in mail or the kids’ homework do to repurpose the space into something they will actually use? The following are five ideas to repurpose a formal dining room into a more usable space.
Those who enjoy hosting friends or family without sitting down to formal dinners might appreciate transforming the dining space into a cocktail lounge. Swapping the dining room table and chairs for low swivel chairs around a coffee table or high-backed bar stools around bar tables easily converts the seating space. A built-in wet bar or a bar cart helps complete this social hub for intimate conversation. Paint the room in darker colors or use textured wallpaper to simulate an after-hours feel that separates the space from the rest of the house.
Homeowners can create a digital detox zone by way of a cozy library. A timeless choice, a library can feature floor-to-ceiling bookshelves or built-ins and comfortable reading chairs stationed by a window.
Homeowners who play an instrument may appreciate a designated space for jam sessions. Dining rooms with high ceilings and bare floors often provide excellent acoustics for music. Complement the space with a high-tech audio system and sound
See Dining, Page 4
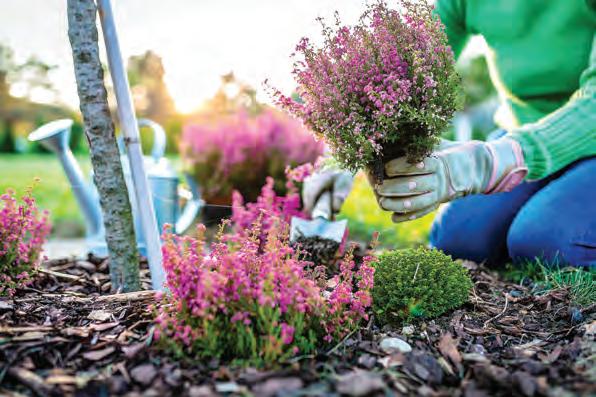
Spring is the perfect time to reset your outdoor space and give your garden some much-needed attention. A little planning and preparation now can result in beautiful blooms for the rest of the year.
I recommend starting by assessing the current state of your garden and tidying up where possible. If you covered your plants in the winter months, uncover them and inspect them for damage. Remove old plants, mulch and any weeds that have already popped up. This is also a good time to test the pH of your soil, so you can make adjustments if necessary.
Once your garden is cleaned up and you know what you’re working with, you can start to plan your spring gardening projects. Luckily, spring is the ideal time to plant most plants, so you have an endless number of choices. If you haven’t already,
I recommend looking up your USDA hardiness zone. Knowing your hardiness zone will help you choose plants that will work best in your area. You should also determine how much sun your garden receives, so you can pick plants that will thrive in your space. Try to plant large plants like trees, bushes, and shrubs first, and then move on to smaller plants like flowers. Once you’ve added all your plants, add some mulch to your garden to prevent weeds and keep your garden as healthy as possible. Make sure you grade the mulch away from your house to direct rainwater away from your home and promote proper drainage. Water is your home’s worst enemy, so now is also a good time to clean your gutters and ensure your downspouts are clear and ready to direct rainwater away from your home and garden. If you
See Hicks, Page 4


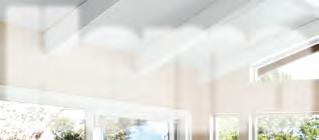




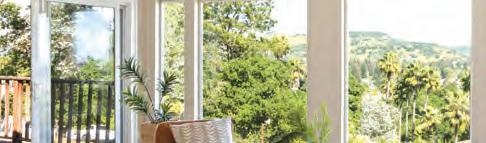

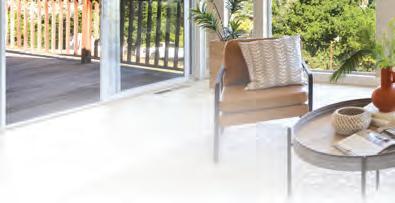
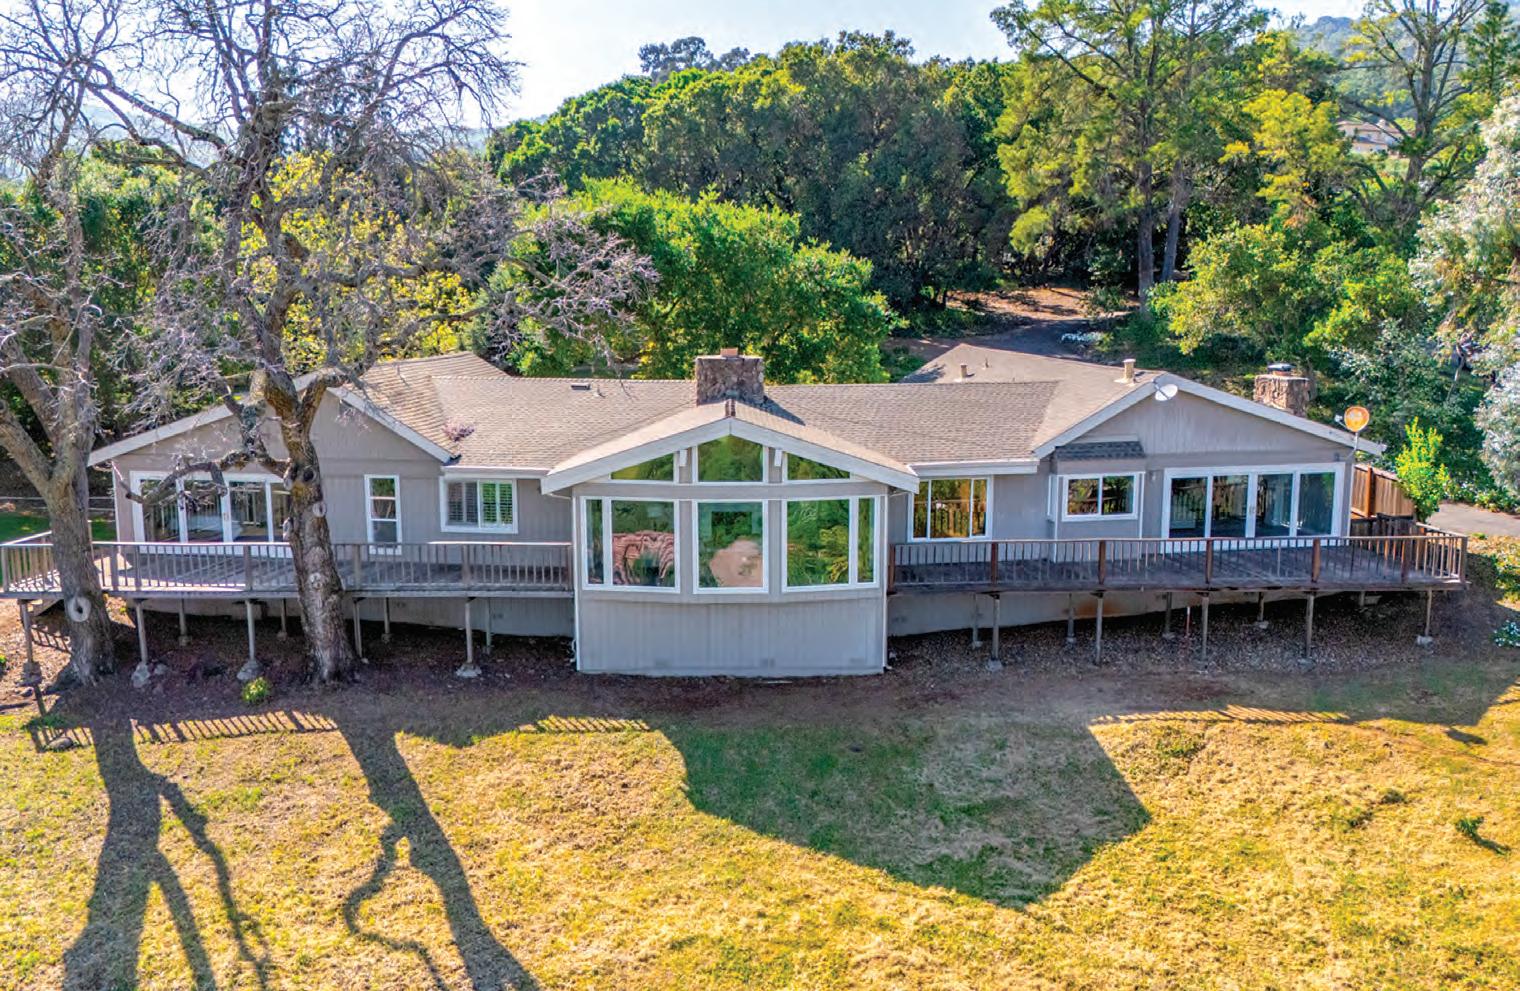
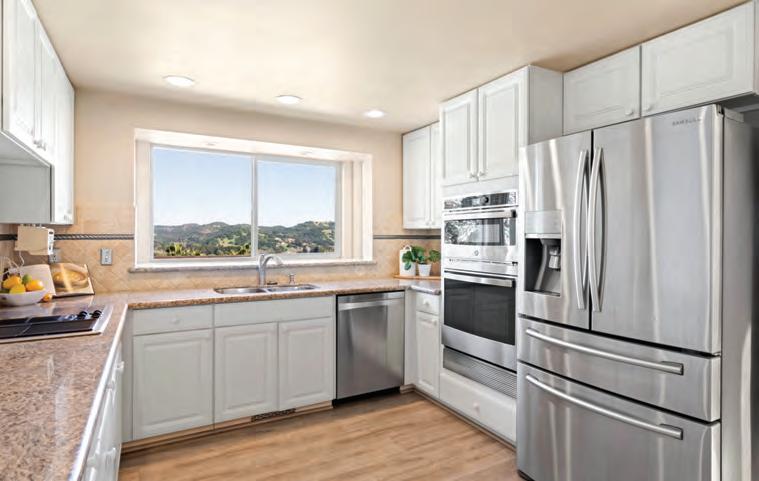
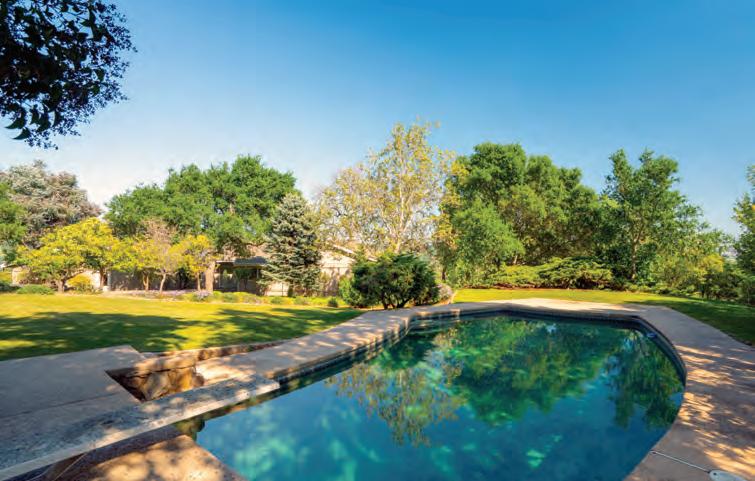
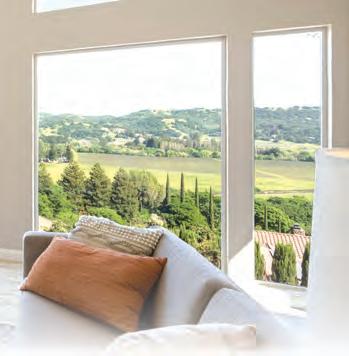
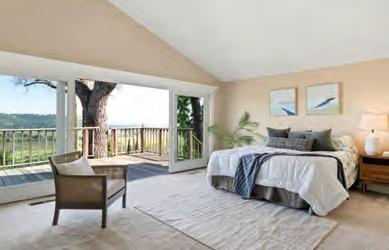
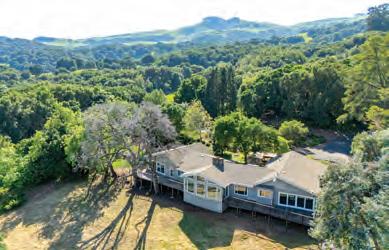
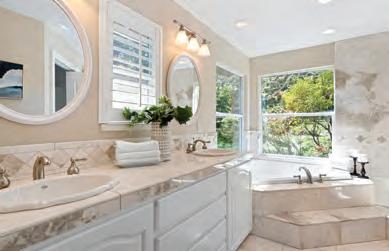
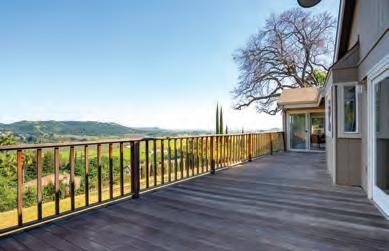
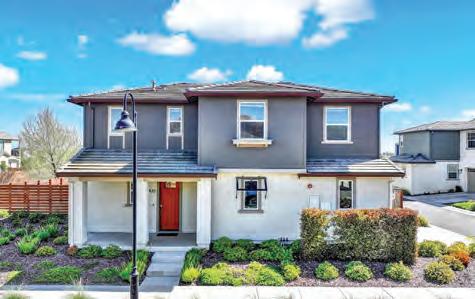
Welcome to one of Green Valley’s most extraordinary properties, nestled in the prestigious Green Valley Ranch Estates. This breathtaking single-level 4-bedroom, 3 full bathrooms masterpiece spans 2950 square feet on 2.5 beautifully usable acres, offering sweeping, unobstructed views of Green Valley from virtually every room in the home. Park-like setting and mature landscaping set the tone for something truly special. Soaring exposed beam ceilings, custom lighting, and walls of oversized windows flood the interior with natural light while framing the stunning surroundings like living artwork. Two grand fireplaces anchor the main living spaces, creating a warm and inviting atmosphere perfect for both quiet evenings and entertaining on a grand scale. The updated kitchen features granite countertops, custom cabinetr y, and stainless steel appliances. The spa-like primary suite is a true retreat. Wake up to stunning views, step through the private slider onto your own deck, and unwind in a bathroom that rivals any luxur y resort complete with a deep soaking tub, exquisite custom tile work, and a spacious open tile shower. Outside, the property transforms into a private sanctuary. Expansive decks invite you to soak in the scenery, while the sparkling pool and lush, mature landscaping including a variety of trees, fruit trees, colorful flowers, and rich ground cover create a resort-like ambiance year-round. A generous flat and open half-acre provides endless possibilities for equestrian use, hobby farming, or simply enjoying wide open space with room to roam. Additional highlights include a new septic system. Location is equally impressive just seconds from the Green Valley Country Club and the region’s finest wineries. Expansive views, refined finishes, resort-style outdoor living, and an unmatched setting in one of Green Valley’s most coveted neighborhoods. Opportunities like this don’t come around often. Come experience it for yourself.
O ered at $1,550,000 Bobby Schultze DRE #02059665 707.389.9331
bobby.schultze@kappelgateway.com bobbyschultze.com
These are the local homes sold recently, provided by California Resource of Lodi. The company can be reached at 209.365.6663 or CalResource@aol.com.
TOTAL SALES: 2
LOWEST AMOUNT: $335,000
HIGHEST AMOUNT: $375,000
MEDIAN AMOUNT: $355,000
AVERAGE AMOUNT: $355,000
735 Buchanan Street #221 - $375,000
01-23-26 [1 Bdrms - 846 SqFt - 1990 YrBlt], Previous Sale: 11-02-20, $360,000
900 Cambridge Drive #184 - $335,000
01-23-26 [2 Bdrms - 1087 SqFt - 1984 YrBlt], Previous Sale: 11-05-19, $299,000
TOTAL SALES: 1
LOWEST AMOUNT: $580,000
HIGHEST AMOUNT: $580,000
MEDIAN AMOUNT: $580,000
AVERAGE AMOUNT: $580,000
240 Fuller Lane - $580,000
01-21-26 [3 Bdrms - 1757 SqFt - 1990 YrBlt], Previous Sale: 00/1990, $164,000
TOTAL SALES: 8
LOWEST AMOUNT: $233,000
HIGHEST AMOUNT: $800,000
MEDIAN AMOUNT: $592,500
AVERAGE AMOUNT: $556,000
401 Brevard Court - $635,000
01-22-26 [4 Bdrms - 2100 SqFt - 2017
YrBlt], Previous Sale: 08-04-20, $565,000 124 Cannes Court - $725,000
01-20-26 [4 Bdrms - 2036 SqFt - 1989 YrBlt], Previous Sale: 03-30-98, $234,900 985 Chalice Court - $585,000
01-21-26 [4 Bdrms - 2035 SqFt - 1989 YrBlt], Previous Sale: 07-17-14, $365,000 762 Dynasty Drive - $800,000
01-23-26 [4 Bdrms - 2539 SqFt - 2000
From Page 2
YrBlt], Previous Sale: 03-28-00, $320,900
2800 Elmhurst Circle - $600,000
01-20-26 [4 Bdrms - 1894 SqFt - 1976
YrBlt], Previous Sale: 05-20-25, $385,000
40 Manchester Lane - $450,000
01-22-26 [3 Bdrms - 1341 SqFt - 1992 YrBlt], Previous Sale: 07-23-18, $340,000
793 Marigold Drive - $420,000
01-23-26 [4 Bdrms - 1556 SqFt - 1978 YrBlt]
55 Villa Circle - $233,000
01-22-26 [2 Bdrms - 968 SqFt - 1971 YrBlt], Previous Sale: 09-11-08, $58,000
TOTAL SALES: 1
LOWEST AMOUNT: $525,000
HIGHEST AMOUNT: $525,000
MEDIAN AMOUNT: $525,000
AVERAGE AMOUNT: $525,000
353 Desert Forest Court - $525,000
01-21-26 [2 Bdrms - 1767 SqFt - 2014 YrBlt], Previous Sale: 07-05-17, $435,000
TOTAL SALES: 2
LOWEST AMOUNT: $495,000
HIGHEST AMOUNT: $545,000
MEDIAN AMOUNT: $520,000
AVERAGE AMOUNT: $520,000
907 Shelduck Court - $545,000
01-23-26 [4 Bdrms - 1308 SqFt - 1981 YrBlt], Previous Sale: 03-28-25, $408,000
145 Summertime Lane - $495,000
01-20-26 [3 Bdrms - 1412 SqFt - 2013 YrBlt], Previous Sale: 10-08-21, $530,000
TOTAL SALES: 7
LOWEST AMOUNT: $275,000
Hybrid work is a permanent fixture in today’s career landscape. A dining room located near the front of the home presents a prime location for a professional workspace. Replace a table with a sleek executive desk. An existing buffet or sideboard can be repurposed as printer storage or for filing. Consider adding French doors or partitions
HIGHEST AMOUNT: $650,000
MEDIAN AMOUNT: $620,000
AVERAGE AMOUNT: $562,143
809 Cookson Street - $620,000
01-22-26 [3 Bdrms - 1633 SqFt - 1989 YrBlt], Previous Sale: 12-17-08, $294,500
632 Cordelia Circle - $645,000
01-20-26 [4 Bdrms - 1817 SqFt - 1986
YrBlt], Previous Sale: 01-22-14, $285,000
124 Del Rio Circle #1 - $275,000
01-23-26 [2 Bdrms - 820 SqFt - 1971
YrBlt], Previous Sale: 05-13-11, $54,000
731 La Cruz Lane - $620,000
01-21-26 [4 Bdrms - 2865 SqFt - 2022
YrBlt], Previous Sale: 11-07-22, $560,000
221 Livingston Avenue - $555,000
01-23-26 [3 Bdrms - 1602 SqFt - 1978 YrBlt]
3091 Red Maple Court - $570,000
01-20-26 [2 Bdrms - 1468 SqFt - 2008
YrBlt], Previous Sale: 10-11-18, $460,000
312 Summerfield Drive - $650,000
01-20-26 [5 Bdrms - 2148 SqFt - 1986
YrBlt], Previous Sale: 09-02-25, $455,000
TOTAL SALES: 16
LOWEST AMOUNT: $170,000
HIGHEST AMOUNT: $800,000
MEDIAN AMOUNT: $409,500
AVERAGE AMOUNT: $427,563
837 6th Street - $450,000
01-21-26 [3 Bdrms - 1032 SqFt - 1961
YrBlt], Previous Sale: 02-21-23, $425,000
3554 Calm Breeze Court - $800,000
01-21-26 [4 Bdrms - 3230 SqFt - 2000 YrBlt], Previous Sale: 07-11-17, $195,500 123 Campbell Avenue - $312,000
01-20-26 [2 Bdrms - 934 SqFt - 1951 YrBlt]
401 Central Avenue - $419,000
01-20-26 [3 Bdrms - 1388 SqFt - 1935
to provide privacy without compromising on light flow.
Active families may need to transform the dining room into a homework lab that offers a quiet space for educational pursuits. Organized cabinetry can house school materials, craft supplies, and much more, confining it all to one room. Locating the computer in the space creates a centralized “safe” spot for internet browsing and monitoring young children in the process.
Dining spaces may be going the way of the dinosaur, reflecting modern homeowners’ preferences for more flexible and useful spaces.
YrBlt], Previous Sale: 09-27-17, $273,000
247 Coughlan Street - $510,000
01-20-26 [2 Bdrms - 1008 SqFt - 1954 YrBlt], Previous Sale: 11-27-24, $300,000
112 Dyer Court - $470,000
01-23-26 [4 Bdrms - 1247 SqFt - 1962 YrBlt]
1 Frisbie Street #207 - $220,000
01-22-26 [2 Bdrms - 964 SqFt - 1991 YrBlt],
Previous Sale: 03-08-11, $60,000 1244 Georgia Street - $170,000
01-21-26 [1 Bdrms - 684 SqFt - 1921 YrBlt],
Previous Sale: 09-19-00, $95,000
237 Grapewood Street - $390,000
01-20-26 [3 Bdrms - 1008 SqFt - 1955 YrBlt]
127 Lighthouse Drive - $250,000
01-23-26 [3 Bdrms - 1058 SqFt - 1988
YrBlt], Previous Sale: 03-31-08, $250,000
111 Milita Street - $639,000
01-21-26 [3 Bdrms - 1641 SqFt - 1928 YrBlt], Previous Sale: 01-20-15, $360,000
914 Pine Street - $355,000
01-20-26 [3 Bdrms - 1798 SqFt - 1949 YrBlt], Previous Sale: 01-15-26, $250,000
40 Sandy Beach Road - $235,000
01-22-26 [2 Bdrms - 1124 SqFt - 1937 YrBlt], Previous Sale: 05-09-23, $575,000
8 Santa Paula Way - $546,000
01-21-26 [2 Bdrms - 1086 SqFt - 1928
YrBlt], Previous Sale: 03-15-23, $502,000
617 Sheldon Avenue - $400,000
01-20-26 [2 Bdrms - 821 SqFt - 1952
YrBlt], Previous Sale: 01-21-16, $174,000
559 Topley Court - $675,000
01-23-26 [4 Bdrms - 2380 SqFt - 1991
YrBlt], Previous Sale: 00/1991, $266,500
From Page 3
aren’t able (or just don’t have the time) to refresh your garden yourself, bring in a landscaping pro to do it for you. To make the most of your efforts, you should keep a close eye on your garden for the next few months to make sure everything is healthy and growing properly. Keep your plants well-hydrated (but don’t drown them!) and keep the area surrounding the new plants weed-free. If you want to take it a step further, you can also add other features to your garden, like path
From Page 2
there known as negative amortization loans in which you don’t even need to pay all of the interest each month. I think most of them disappeared after the Great Recession of 2008-2013, but I’m not sure. The problem with them was that every month the unpaid interest was added to the balance of the loan. So, every month you owe more and more despite the fact that you are making payments.
Double check and make sure that isn’t the type of loan you’re being offered.
Also, check to see if the loan has a prepayment penalty, typically three years. If so, I’d probably not be excited about it since you don’t know exactly when you might sell and pay off the loan.
One last piece of advice; don’t let the loan exceed five years and turn into a Libor-type loan. These loans are typically very volatile and you just don’t know what the housing market will look like in five years and where interest rates will be by then.
Tim Jones, Esq., is a real estate attorney in Fairfield. If you have any real estate questions you would like to have answered in this column, you can send an email to AllThingsRealEstate@ TJones-Law.com.
lights or a birdbath. This will elevate the space and put the finishing touches on your new-and-improved garden. If you don’t already have a garden, spring is the perfect time to create one. Find an area in your yard that gets a lot of sun and map out the space to determine where to put your garden. I recommend hiring a pro to remove the grass and get your soil ready for plants. Once the prep work is done, you can move on to the fun part –designing your brand-new garden and choosing your first plants.
Tweet your home care questions with #AskingAngi and we’ll try to answer them in a future column.
LINDA BELL
A home equity loan and HELOC are the two most common ways to borrow against your home’s value. Both are forms of second mortgages, but they differ in some significant ways.
A home equity loan provides a lump sum of money at a fixed interest rate. You have to repay it over a set period with regular fixed payments. The loan is ideal for homeowners who need a specific amount for a large, onetime expense that it’s best to pay all at once.
A HELOC offers a revolving line of credit, similar to a credit
card, with a variable interest rate.
The line of credit gives borrowers flexibility, as they can withdraw money as needed during a set period, typically 10 years; they can repay those funds, replenishing the balance, and then draw again. Or, they may opt to make minimal, interest-only payments.
After the draw period ends, they must start paying back the borrowed funds in full.
Applying for a home equity loan involves several key stages on the road to approval. Here’s a detailed breakdown of each step in the process.
1. Determine your eligibility
Before you apply for a home equity loan, make sure you can meet the minimum requirements:
•Home equity: Equity is the
difference between what your home is worth and whatever you owe on your mortgage. You should have at least 20% equity in your home, though some lenders will allow you to have as little as 10% . Even better if your stake equals over half of your home’s worth (aka being “equity-rich”): the more you own, the more you can borrow. Typically, the longer you’ve been in your home, the more equity and borrowing
power you have.
•Credit score: Your credit score gives lenders an indication of how reliably you repay debt. A credit score in the mid600s is usually the minimum to get you approved. But a score in the 700s will get you the best rate and terms.
•Debt-to-income (DTI) ratio: Your DTI measures your gross monthly income relative to your monthly debts. Lenders want your DTI to be no more than 43%, as it shows your obligations are less than half your earnings, and you have the wherewithal to take on additional debt. A lower DTI signals that you’re not overextended and can comfortably manage an additional loan.
•Combined loan-to-value ratio (LTV): Your CLTV compares the amount you want to borrow against the value of your home, factoring all the loans backed by your home (including your mortgage). Lenders typically limit the CLTV to 80-85%. The rationale: You maintain a cushion of untapped equity, so that if property values fall, you won’t end up owing more on the home than it’s worth.
•Income: While there are no set income requirements to get approved, you have to demonstrate that your income is stable and consistent enough to handle the loan payments comfortably (and, in the case of HELOCs, if you can handle a rise in payments due to interest-rate jumps). Lenders will also verify how long you’ve been in your current job.
2. Research and compare lenders
Compare offers from at least three lenders, including banks, credit unions and mortgage/home
From Page 5
lending companies; be sure to include both bricks-and-mortar and online lenders. Each lender sets its own interest rates and its own fees, which vary greatly; so be sure to compare the advertised APR, which takes both into account.
3. Submit an application and documents
Depending on the lender, you will be able to complete the application online, on the phone or in person. This process typically includes providing personal information, details about your home, and financial documents (see “Information you must provide” below). The lender will check your credit history, with its list of your accounts and debt obligations, and credit score. But you should be prepared to provide proof of income and homeownership.
4. Go through underwriting
The underwriting review is one of the most critical steps in the home equity loan process. During this phase, the lender evaluates your creditworthiness, home value, assets, debts and ability to repay the loan. They will verify everything in the paperwork you submitted, and may request additional documentation.
As part of the underwriting process, the lender will want to make sure the amount you are borrowing aligns with your available equity. To do that, it will require an appraisal of your home to determine its current market value. Some lenders still order up in-person evaluations, but automated valuation models (AVM), computer programs that use an algorithm to determine the home’s worth, have become more popular for home equity financing of late. If the appraisal comes in lower than expected, you may have to reduce your loan request. If you don’t agree with the lender’s decision, you can always dispute it, or ask for another appraisal.
5. Receive loan approval and close your loan
Once approved, you’ll receive a loan estimate outlining the terms of your HELoan or HELOC and the various closing costs. After agreeing to them, you’ll attend a closing meeting to sign the final documents and pay any fees or upfront charges. Funds are typically received within a few business days after that.
To apply for a home equity loan, you will have to gather several documents to verify your identity, income and assets. Here is a checklist of what you need:
•Proof of identity/personal information: You will need to provide your Social Security number, date of birth and a government-issued photo ID (such as a driver’s license or passport).
•Income documentation : Depending on your employment status, you may need recent paystubs, two of the most recent years of W-2s, business and federal tax returns, your Social Security income or pension award letter, investment statements, or rental income agreements.
•Property information : Among the documents you should have on hand are the homeowners insurance declaration, property tax statement, home title and title insurance policy (if any) and a record of your flood insurance (if your home is in a flood zone).
Nearly half (48%) of Americans who’ve applied for a loan or financial product over the past 12 months have been rejected. No one wants to be turned down for a home equity loan, or any loan for that matter. Your credit profile plays a big role in getting approved. About half (47%) of American credit card holders have credit card debt –22% of debtors don’t think they will ever pay it off, according to Bankrate’s 2026 Credit Card Debt
order: Have your W2s, primary mortgage details, and all relevant documents and information ready ahead of time to speed up the process. The sooner you get it in, the sooner they start underwriting.
Survey. But don’t be discouraged. Taking steps like reviewing your credit score and improving your debt-to-income ratio, can make a big difference before applying. Let’s dive into some of the tips to boost your chances:
•Check your credit score: Ensure your credit report is accurate and resolve (or at least dispute) any inaccuracies before you apply. Higher scores can increase your chances of approval and help you secure better rates and terms. If you find errors, it can take several weeks to resolve them and get a “clean” report, so start this well in advance of actually applying.
•Lower your debt: If a big chunk of your monthly income is going toward credit cards, loans or other debts, lenders may see you as stretched too thin. Improve your eligibility by paying down outstanding balances as much as you can. Doing so will also improve your credit score. Again, get this going in advance: a few months at least before you submit any applications.
•Get your paperwork in
•Pause major financial moves: Before your loan closes, don’t make large purchases, open new credit cards or take on big new debts. Even small changes can impact your credit profile and derail your approval at the last minute.
• How long does it take to get a home equity loan? The time it takes to get a home equity loan typically ranges from two to six weeks, though it varies depending on the lender. Avoid delays by getting your documents ready and checking your credit score ahead of time. Responding quickly to lender requests can also speed up the process. Some online lenders, like Better or Figure, promise decisions in as little as a few days – provided you get them all the paperwork promptly (Better, for example, mandates 24 hours after you apply).
• Why would a home equity loan be denied? Poor credit, a high DTI, insufficient equity or unstable income are among the reasons applicants may not be approved for a HELOC or home equity loan. If you fall into this
boat, focus on the reason for the denial and try improving it – like increasing your equity stake (by paying down your mortgage) or improving your credit score before reapplying. Or try another lender. Remember, just because one denies your loan, it doesn’t mean another one will.
• Who’s most likely to get a home equity loan? Home equity loan borrowers tend to be a wellheeled, highly creditworthy lot, with qualifications far above the minimum requirements – or even the average homeowner’s. The best person to take out a home equity loan has paid off a large chunk of their mortgage, owning at least half of the home outright. That often means they’ve owned the home a while, for a decade or so (or they bought it mostly with cash). Their debt-to-income ratio is around 40%. But what really sets them apart is superb credit: We’re talking about 750 or higher.
• How can I improve my chances of being approved for a home equity loan? Start by keeping your credit score in good shape and checking for errors beforehand to make sure everything goes smoothly. It’s also important to pay down high-interest debt and make sure your home has enough equity. Lenders also look at your income and debt-toincome ratio, so showing steady income and manageable monthly obligations can go a long way toward getting approved.
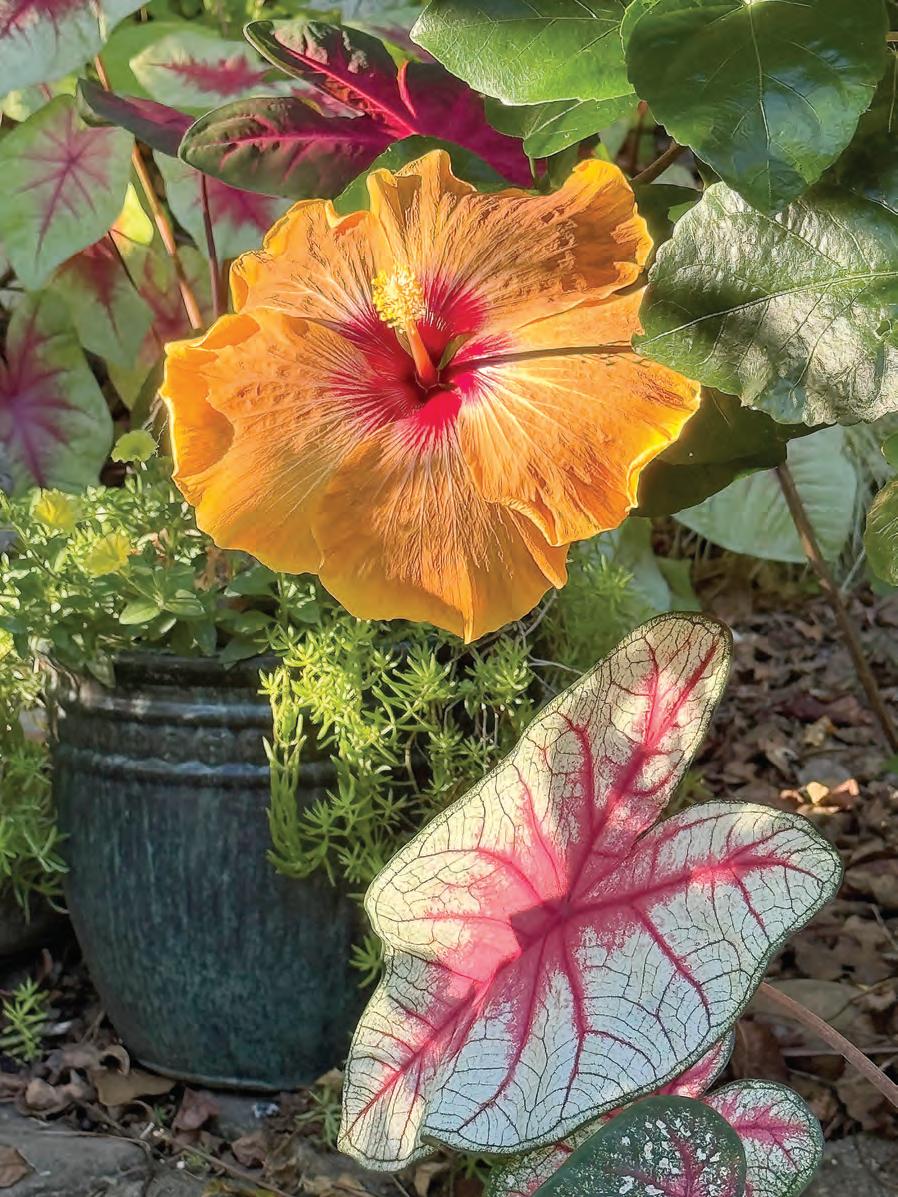
Zone 8 gardeners may feel a little timid when it comes to growing tropical hibiscus. That is somewhat understand able, but as I wrote about creating a hydrangea heaven, your hibiscus dazzle may come from the partnerships you choose.
This will be my third year growing four selections of the Hollywood Hibiscus series. The series now totals 14, if you can believe it. The series, and the fact that it’s under the Proven Winners logo, will open the door for gardeners to choose the hibiscus that fits their color palette and motif. What I mean by that is that hibiscus shopping has always been kind of potluck or limited by what the retailer can get and has on the bench.
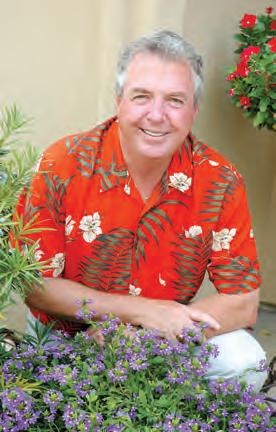
in a pot on the patio, put on my Hawaiian shirt and embraced the island life atmosphere.
Now I have started thinking about combinations. The Hollywood Hibiscus are in containers too, but my backyard is set up so that they still allow for stunning combinations. Once you start doing this you will feel more like an artist or designer, and the hibiscus becomes part of a plan.
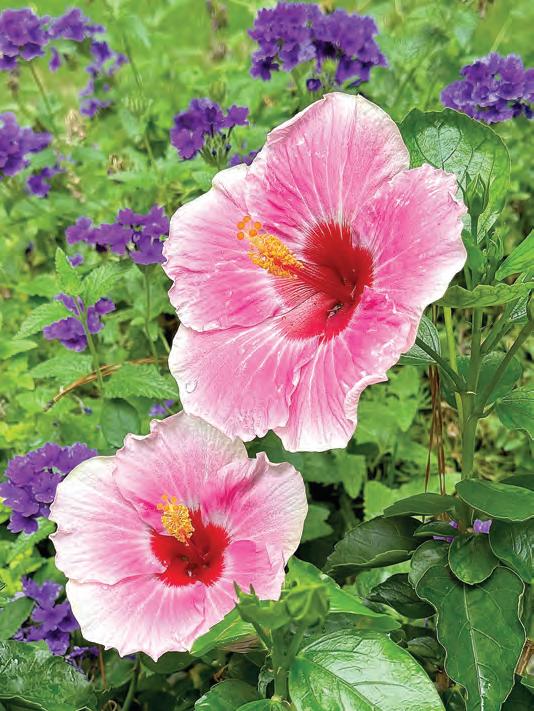
Hollywood Hibiscus VIP is truly one of the most beautiful I have ever grown. The flowers are large and the color is so rare in the garden. The colors also change throughout the day, featuring yellow gold and darker honey gold with a magentared throat. Hollywood Hibiscus
Most of my life I have simply bought a tropical hibiscus, put it























With warmer weather here, spring cleaning and hosting season are in full swing. While you prep your home for guests, you may also be seeing an uptick of insect activity.
Unfortunately, insects tend to gather in the same areas of the home where household members and guests do – anywhere there is food. So, rather than let bugs disrupt your spring gatherings, act right away. Doing so is important, as insects reproduce rapidly. In fact, it only takes one week for two fruit flies to multiply to 500 fruit flies!
By using these tips to banish bugs from your kitchen this spring, you can enjoy the feeling you get when your space is truly clean and guest-ready:
In addition to regular kitchen upkeep, be sure to do a deep clean in spring and every time you host. This is a great way to finally tackle those corners, crevices and seldom-addressed surfaces in the fridge, oven and pantry, where pest-attracting food residue and grease can build up.
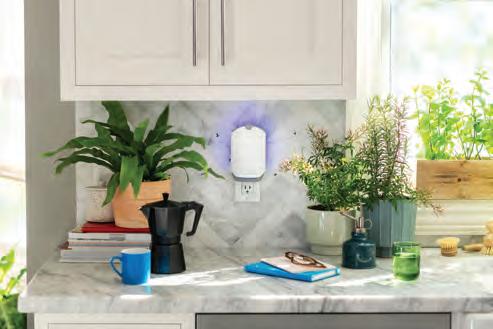
A fly trap for indoors is a necessary addition to your kitchen spring cleaning and hosting routine. Zevo catches what you can’t clean – working continuously to trap those pesky flies and gnats that linger around sinks, trash cans, and countertops even after you’ve scrubbed. Simply plug in a Zevo Flying Insect Trap near high-traffic areas, such as near party spreads, fruit bowls or garbage, and doors that are opened throughout the day. Its
blue and UV light attract and catch fruit flies, gnats, house flies and other flying insects 24/7 and its sleek, discreet design will look good in your kitchen.
“Plugging in a Zevo Insect Trap is an easy way to achieve that level of cleanliness you’re looking for, so you have more time for what matters – enjoy ing the spring season with friends and family,” says Rob Reiner man, Vice President of Procter & Gamble Ventures, parent company of Zevo, a line of worryfree pest solutions.
If you have a leak under your kitchen sink, you may unwittingly be creating an inviting habitat for bugs, which are drawn to water sources. Fix the leak so you invite only human guests to your kitchen and home this spring. Doing so will have the added benefit of preventing water damage and mold.
Take a quick look at your pantry to assess your food storage
containers. Transfer all items like flour and sugar out of paper packaging and into tightly-sealed jars. Not only will this help keep bugs at bay, but your essential ingredients will stay fresher for improved hosting.
For more information about pest control in the kitchen and other areas of your home, visit zevoinsect.com.
Maintaining a tidy kitchen is just the first step in banishing bugs. Simple additional measures that require very little effort can help you truly keep the spaces where you prep, host, and enjoy your food clean, fresh and insect-free.
hen there is fear in the stock market, investors take flight to quality and buy treasury bonds and notes, and mortgage rates come down. Today, the yield on the 10-year treasury bond has risen from 3.95% in late February to 4.3% today, and mortgage rates have jumped from a national average just below 5.85% in February to 6.5% today.
The reason for this is fear that inflation will possibly skyrocket if a gallon of gas continues to cost $6 per gallon. The Fed will not be able to cut rates if inflation is a big problem, and the new Fed chair will be handcuffed no matter how much he wants to cut rates.
One thing for sure is President Trump wants lower rates ASAP because the mid-terms are coming in November. I could be wrong, but I believe the Strait of Hormuz will be wide open by Easter and the tankers will pay a small toll
to Iran like we have going on with FasTrak over bridges and now all these HOV toll lanes on Interstate 80 here in Solano County. This conflict will be resolved, and the mortgage rates will come down sooner than later, and our real estate market will be just fine.
Jim Porter, NMLS No. 276412, is the branch manager and senior loan adviser of Solano Mortgage, NMLS No. 1515497, a division of American Pacific Mortgage Corporation, NMLS No. 1850, licensed in California by the Department of Financial Protection and Innovation under the CRMLA / Equal Housing Opportunity. Jim can be reached at 707-449-4777.






There’s no shortage of ways to utilize interior spaces in a home. Interior spaces have grown considerably in recent decades. According to the U.S. Census Bureau, the median size of a new home in 1980 was 1,595 square feet. By 2018, the median size of a newly constructed home was 2,386 square feet. Though Realtor. com data indicates the median home size started to shrink between 2015 and 2025, modern homes continue to provide lots of room to maneuver.
When confronted with ample interior space, homeowners may wonder what to do with all that extra room. Playrooms can be a great way to utilize extra space to
the fullest, particularly in homes with children. Parents planning a playroom in their homes can consider these tips to ensure the space becomes a fun room everyone can enjoy.
Measuring the dimensions in a prospective playroom can erase any doubts homeowners may have regarding how much space they have to work with. Taking measurements also makes it easier to identify which furnishings, including couches and storage units, will fit comfortably into the space. Homeowners who plan to install new flooring or carpeting also will need to know the dimensions to get an accurate idea of how much that portion of
the conversion project will cost.
A basement playroom may work as children enter their tweens and early adolescence, but such separation from the rest of the home may compel young children to avoid the space. Elementary school children and younger kids generally like to stay close to Mom and Dad, so a basement playroom may not be ideal for such youngsters. In such instances, converting a seldom-used formal dining room into a temporary playroom may be a better option. As children age, the basement can be utilized as a playroom with greater fre-
quency until it becomes the lone play space in the home.
Playrooms can quickly be overrun by toys. Though no two children are exactly the same, the professionals at Brain Balance Achievement Centers note the expected attention span of a twoyear-old is four to six minutes.
A four-year-old’s expected attention span may peak at 12 minutes, while an eight-year-old’s expected attention span is between 16 and 24 minutes. That means kids will pivot from one toy to another with frequency, which underscores the need for ample storage. Storage should be built into the design of the space after measuring its dimensions. Avoid storage solu-
A playroom can make for a fun way to utilize extra space inside a home.
tions that extend too high up the wall, as that’s hard for children to reach and might lead to accidents. Creative storage solutions abound online, and parents are urged to exercise due diligence to find the safest, most effective units for their children and their space.
Free play is important for youngsters, but kids will want Mom or Dad and even older siblings nearby even when they’re playing on their own. So it makes sense to equip the space with areas that accommodate everyone in the household. A reading chair for adults and a ping pong table and arcade game for older kids can ensure everyone gets to have fun in the playroom.
Refinancing a home can be a smart move – if you time it well and understand the factors involved.
Refinancing means replacing your current mortgage with a new one, and doing so will result in a new rate, term and monthly payment. While refinancing does have some upfront costs, taking this step could improve your financial situation.
Some of the best times to consider refinancing include:
• When mortgage rates are lower than the rate of your current mortgage. Even small differences in mortgage rates can have a big impact on your monthly payment, and the total cost of your loan.
• When your financial situation has improved and you can secure a loan with a shorter term to build equity in your home faster.
• When your adjustable-rate mortgage is adjusting upward and you want to convert to a fixed-rate mortgage for the security of consistent payments.
• When you’ve built up significant equity in your home and could use the money from a cash-out refinance for home improvements or to improve your financial situation. With a cashout refinance, you’re refinancing your mortgage for more than you currently owe. In return, you’re getting a portion of your equity back in cash.
Although refinancing your mortgage could save you money in the long and short term, it isn’t free. The total cost to refinance
your mortgage will be determined by your lender, credit score and location. As a general rule, you can expect to spend 3-6% of your loan principal on a refinance.
A quick check to see if refinancing makes financial sense for you is to calculate how long it will take to recoup the costs of the refinance. To do this, take the total cost associated with the refinance and divide it by your monthly savings. Note that this model will not work for cash-out refinances or if you are refinancing to reduce the term of your loan.
You’ll also want to consider when you plan to move, and whether you’re going to significantly extend your loan term. For example, if you have 20 years left on your 30-year fixed-rate mortgage and you refinance into a 30-year fixed-rate mortgage,
you’ve essentially extended the term of your loan and will pay more interest over the life of the loan as a result.
You should work closely with a lender to discuss options that fit your goals. You can refinance through your existing lender or a new lender. What’s most important is that the lender you choose is trustworthy and offers competitive rates and terms.
To determine how much it will cost you to refinance your mortgage, and how much money you can save by doing so, lean on free online resources. Freddie Mac’s tools and refinance calculators can help you estimate payments,
See Smart, Page 14
Real estate has long been considered a good investment. Whether people are buying a home they intend to live in or purchasing investment properties they hope to flip or rent out, real estate tends to provide a strong return on investment.
Maximizing the investment value of a property is wise regardless of how buyers intend to use it. With that in mind, buyers can consider these strategies to make the most of a real estate investment.
Though no room of a home in need of work should be ignored, various studies have identified the rooms buyers emphasize most when looking for a new home. Kitchens and primary suites tend to make the most lasting impressions on home buyers, and that can offer a strong return on investment (ROI). And the good news for homeowners hoping to sell a property they currently own is that minor kitchen remod-
els, which require a smaller financial investment than major overhauls, offer stronger returns. According to the Cost vs. Value Report 2025 from the Journal of Light Construction, a minor kitchen remodel offers an average return of 113%t compared to a 36% average return for a major upscale remodel.
Real estate investors who aren’t looking to sell but buy can maximize their investment by prioritizing location as they search for properties. Though the real estate market is everchanging, the importance of location remains a constant. Investopedia notes that a “good” location for prospective buyers typically is near access to transportation (be it public transportation or highways that can help cut down on commute times), well-regarded schools, and community involvement. While the importance of location is a constant, Investopedia notes that a given neighborhood’s reputation can go from “good” to
Buying a home is one of the most significant financial commitments a person can make. Individuals may wonder when is the right time to jump in to the real estate market. The answer may boil down to affordability.
The housing market is continually evolving. Buying a home now is a little bit different than it was even a few years ago, as inventory is starting to recover from a lengthy period with limited offerings, according to Realtor. com. But even though inventory may have increased, home prices have not come down. The median home price now sits at around $410,000 in the United States, and interest rates hover around 6% for a 30-year fixed rate.
Before it’s time to sign a contract and get the keys, potential buyers can follow this guide as they navigate buying a home for the first time.
Before browsing home listings, buyers should conduct a financial audit to see how they stack
up. It’s worthwhile to sit down with a mortgage broker who can run your numbers. Credit score is a significant variable that will be checked during such consultations. If necessary, identify ways to boost that score in the months before applying for a mortgage.
Rocket Mortgage says the 30% rule dictates that total monthly housing costs, including principal, interest, taxes, and insurance (PITI) should not exceed 30 percent of a borrower’s gross monthly income to maintain financial stability.
Buyers should concern themselves with all of the costs that go into buying a home. In addition to the down payment, closing costs can come in at around 2 to 5% of the home’s price. An inspection and appraisal can run around
$1,000. Additional costs may include termite inspection, and other out-of-pocket costs to get the home up to code.
A rising trend in home buying is a surge in down payment assistance (DPA). Bankrate says DPAs provide eligible individuals, typically first-time or low-tomoderate-income buyers, with assistance that covers costs like down payments and closing fees. These programs may be offered by the government, non-profits or private lenders.
A home may seem like a dream until a person pulls back the curtain on some hidden red flags. It’s always worth the expense
to have a housing inspector or a trusted contractor walk through the property prior to making an offer to ensure that the home is in good condition.
First-time home buyers may want to select metro areas that offer the best balance of earnings versus home prices. According to a 2026 report from Realtor. com, areas that provide the best value in the U.S. are largely concentrated in the Northeast and Midwest. Hartford, CT; Rochester, NY; Worcester, MA; Toledo, OH; and Providence, RI, are some of the top housing markets for the year.
From Page 13
compare options and ultimately evaluate whether refinancing aligns with your financial goals. Visit My Home by Freddie Mac at myhome.freddiemac.com to access these resources. When it comes to refinancing, timing is everything. Before taking this step, ensure it’s the right move for you now.
From Page 13
First-time home buyers must consider a range of variables as they inch closer to making their home ownership dreams a reality.
“bad” or vice versa. Identifying an emerging “good” neighborhood can be a tall order, but prospective real estate investors are urged to consider a range of variables about each location in an effort to maximize their investments. Recent investment in local infrastructure and a growth in local employment opportunities are two variables that can help a given area quickly transform into a place people want to live.
When selling a home with the intent of maximizing a real estate investment, it’s important that owners recognize certain times of year are better for sellers than others. A 2024 report from the real estate curator ATTOM indicated that listing a property in May, February or April can yield the best returns for sellers. May is a particularly good time to sell, as the ATTOM analysis of 59 million home sales between 2011 and 2023 found that homes sold in May sold for 13.1% above market value, which was the highest of any month.
Real estate has long been considered a great investment, and various strategies can help investors bolster their returns.
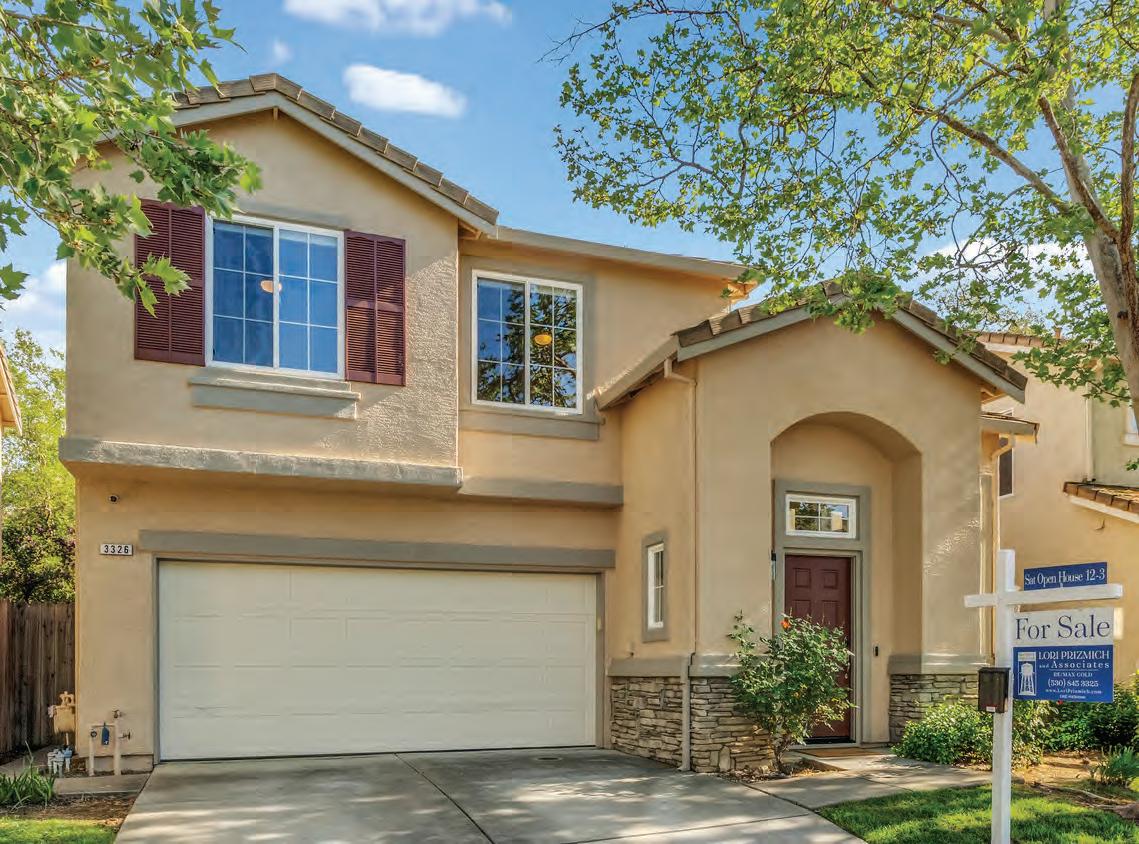
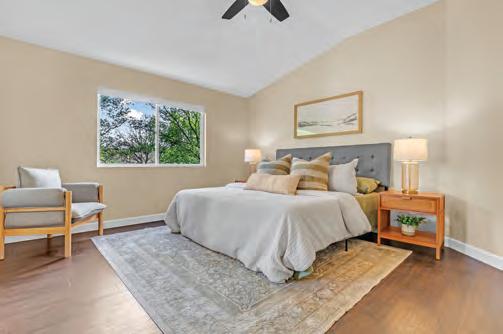
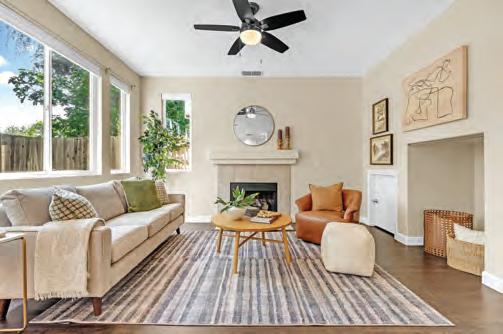
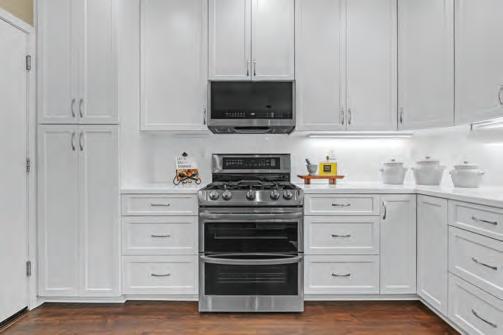
4bed3bath1,830sf OPENHOUSE
LocatedinMaceRanch,thismove-inreadyhomeoffersaprofessionally remodeledkitchenandprimarybathroom,soaringceilingsthatfillthespace withnaturallight,plusownedsolar.
Fortheconvenienceofthenextowners,thesellershaveprovidedclearpest, roof,HVAC,andsoontobeclearedCityofDavisResaleinspection.
Don’tmissthebestvalueonthemarket!
this Saturday& Sunday 12-3PM