Whether you are new to homebuying or have multiple properties, purchasing a home is a significant life decision and a major investment. With the ever-changing array of listings and the complexity of the process, it can feel daunting. I am equipped with the knowledge and skills to provide an exceptional experience for my clients, acting as a trusted advisor throughout the entire transaction and beyond. We lead with integrity and quality service, strategizing and negotiating each deal as if it were our own.
My success comes from a meticulous approach, effective marketing, and a vast network. Every detail is carefully managed. My philosophy has always been to build relationships over merely closing deals. My mission is to help buyers find a place they can call home and to help people achieve their dreams. While many agents overlook the importance of the initial consultation, I see it as a crucial step to understand your unique needs. I recognize the importance of buying, selling, or leasing a home in your life, and I am here to provide expert guidance every step of the way.
Brian Meier
Leading the New York City real estate industry, The Meier Team expertise as your liaison brings established roots with trusted principals every step of the way. We bring value to our clients not just by bringing market identity to their spaces but by bringing peace of financial security. Our market and value acquisition analysis remains a trusted resource in our clients’ portfolios. Our vigorous presence in each borough enables the effective understanding of new market entrants and economic issues to guide our proactive approach. We stand behind our beliefs, values and standards of authentic commitment which led us to the top of our industry. We take your vested interest as our own. With us it’s not just a transaction, it’s your future.
Be your personal source of knowledge about the buying process, individual homes, condominiums vs. coops, new development properties, neighborhood amenities, and market dynamics.
Help you clarify your real estate goals in relation to the local market and set your expectations on price, home size, and more.
Provide you with access to a network of agents, sellers, mortgage brokers, real estate attorneys, and contractors and keep you updated on off-market properties that have not been listed.
Schedule showings that align with your schedule and keep you informed about open houses.
4 5 6 7 8 9 10
Attend showings with you in order to facilitate a smooth showing process and give you a different perspective than that of the selling agent.
Submit offers on your behalf and negotiate with the seller/seller’s agent to get you the best possible deal.
Manage the contractual process and the back-and-forth negotiation between you, the seller, and the attorneys that represent each side.
Offer support and guidance in filling out applications for financing, buyer packages, and board interviews
Coordinate your closing and final walk-through.
Be a future resource to you should you ever want information about the market or ever consider selling your home.
STEP 1:
Pre-approval
Determine your buying power:
The first step is to get preapproved for a mortgage. This process usually takes 1 to 3 days and will help you understand how much you can afford to spend on a new home.
Making an Offer:
Once you find a property you want to buy, your agent will present your offer to the seller’s agent or the seller directly.
Negotiation Process:
The seller might counter your offer, initiating negotiations. This phase involves discussions to agree on the price, terms, and closing date.
Property Search
Define Your Preferences:
Identify what you are looking for in your new home. This includes factors such as location, size, style, and any specific features you desire.
Contract Review Securing Your Dream Home:
Finalize the Agreement:
At this stage, you will typically need to provide a deposit. The signed contract and deposit are then sent to the seller for their signature. The deposit will be held in the seller’s attorney’s escrow account until closing. It’s important to note that until all parties have signed the contract and it has been delivered, the seller can still consider and accept other offers.
7: Complete Purchase Application
You will receive the necessary documents and requirements from your agent, which usually include an application form, a financial statement signed by you or a CPA, and supporting documents for your financial statement. This often involves providing 2 to 3 years of tax returns, recent bank statements, letters of professional reference, and the contract of sale. If you are financing, you will also need to submit bank documents indicating that your loan is secured. In the case of a co-op purchase, if your application meets the initial approval, you will be invited to an interview with the board or an interviewing committee.
STEP 6:
Loan Application
Proceed with Financing:
During this stage, it is crucial to have an attorney experienced in New York City real estate to represent you. They will review the contract of sale, the building’s bylaws, and its financial condition to ensure everything is satisfactory before you sign the contract.
If you need financing, proceed with your loan application and arrange for an appraisal through your financial institution.
STEP 8: Board-Approval
For co-op purchases, you need to get approval from the board.
STEP 9: Bank Clearance
Clearance to close:
Your bank will issue a clearance to close once all conditions are met.
STEP 11:
Final Walk-through & Closing Inspect and Close:
Conduct a final walk-through of the property and then proceed to the closing to finalize the purchase.
STEP 10:
Set the Closing Date:
Coordinate with all parties to schedule the closing date.
STEP 12:
Celebrate!
Enjoy Your New Home:
Celebrate the successful completion of your home buying process. All our hard work has paid off!
Let’s
When looking for an apartment, it’s important to have a clear idea of what you want in terms of the number of bedrooms, bathrooms, and so on. But don’t forget to think about the neighborhoods you’re interested in living in. Consider your daily commute, proximity to friends, and amenities like restaurants, schools, transportation, and grocery stores. Your agent will be there to help you every step of the way, showing you the homes that best fit your criteria. When you find a place you love, it’s time to make an offer! Your agent will put together a written offer that includes your pre-approval letter (if you’re financing), a REBNY form that shows your assets and liabilities, and your attorney’s information. Keep in mind that not everything will be negotiable, and the seller may come back with a counteroffer. But with your agent’s guidance, you can work toward a deal that works for everyone.
• Agent and transaction team prepare official offer
• You sign the offer electronically
• Agent and transaction team send to listing agent along with pre-qualification letter
• Agent will stay in close contact with listing agent to confirm receipt and get feedback as to our offer strength (if in a multiple offer situation)
When your offer is presented, the seller’s options are to:
ACCEPT IT: If, after reviewing your written offer, the seller’s sign, then you will have an executed contract!
COUNTER: If the sellers like some aspects of your offer, they may present a written (or verbal) counteroffer that includes the changes the sellers want to make. You are then free to accept their counteroffer, reject it, or make your own counteroffer.
Once everything is agreed upon and executed – Congratulations! It is time to move on to the “under contract” steps. . .
It’s essential to understand the available options for structuring your offer. The Three main offer types seen in NYC real estate are all-cash, non-contingent, and contingent. The word “contingent” means a condition must be met before a contract s legally binding.
An all-cash offer is precisely what it sounds like- an offer fully in cash without any financing. This option is often the most attractive to sellers because it can expedite the process (no need to deal with banks or uncertainties.)
Putting forth a non-contingent offer means you are prepared to move forward with the purchase regardless of loan approval. In the unlikely event that you are not fully approved, you will be required to put down a larger deposit or pay all cash.
A contingent offer means that you must fulfill specific criteria before the contract is considered fully executed. You may think of a contingency as a safeguard or provision against an unforeseen event. Possible contingencies to an offer may include: financial contingency (the offer is dependent on a loan approval), an inspection contingency (the offer is dependent on a successful inspection), or a “need to sell” contingency (the offer is dependent on the buyer first selling their own home). Sellers are least attracted to contingent offers as they carry the most risk.
Preparation is critical in the fast-moving world of New York City real estate. It’s in your best interest to have the following paperwork primed for a quick dispersal to a seller’s agent. It is also sensible to retain an attorney early on (you will include their contact information in your offer).
Your agent can help you compile the following documents so that when you are ready to make an offer, it will reach the seller as fast as possible.
FINANCIAL STATEMENT: a standardized financial overview. Your agent will provide the template for you to fill out. Sellers use this to analyze the strength of your offer, your level of financial qualification, and the likelihood you will pass the board (in a co-op).
MORTGAGE PRE-APPROVAL LETTER: a mortgage pre-approval letter verifies the amount a bank or lending institution has cleared your to borrow. This document proves to sellers that you are a serious, well-qualified buyer who can afford the purchase.
PERSONAL LETTER/BRIEF BIO: You may want to include a short note to the seller, making a sincere appeal for your offer’s consideration. Co-ops often require a short bio explaining who you are, your employment status, and why you are interested in the property.
AGENCY DISCLOSURE: New York State law requires an agency disclosure be provided to buyers and sellers to avoid potential confusion over respective representation.
Your agent will submit all offers on your behalf and keep you apprised of responses from the seller’s side.
Due diligence refers to research conducted by your attorney to help you determine whether you should sign a sales contract. It is an essential component of any real estate transaction and protects you from possible fraud. The process begins in earnest after you receive an accepted offer and should always be completed before any contract are signed.
Due diligence is an extensive investigation for any information that might lead you to amend the contract or refrain from signing it altogether.
your attorney will review an immense amount of paperwork to verify the seller’s claims about the property, including:
• At least two most recent years of building financial statements
• Board minutes
• Building questionnaire, completed by management
• Alteration policies
• Sublet policies
• Lien search
• Tax information
• Certificate of occupancy
Due Diligence in real estate transactions can be highly subjective. Conditions that bother one individual may not be an issue fro another. However, some situations may be “red flags” that warrant further consideration. These include:
• Ongoing Litigiation in the building
• Noise or other complaints in regards to the unit or any applicable neighbors (same floor, directly above/below)
• Rodents, bed bugs, or other pests issues
• Maximum percentage of financing allowed (if you are financing)
• Low reserves vs. expenses
• Substantial, consisten increases in monthly harges
Due diligence reports will help you understand the property’s present and future value, allowing you to make fully informed, evidence-based decisions regarding the sales contract.
If you’re planning to finance your purchase, it’s important to have your pre-approval letter from your mortgage banker in hand before you start searching for a home. Once you find the right apartment, the board will require a commitment letter from your lender. This commitment letter is usually the final piece of a board package or condo application. If the board is satisfied with your application, they will issue an approval, also known as the First Right of Refusal.
Assembling a board package or condo application can be a detailed process. You’ll need to provide financial statements, three years of tax returns, bank statements, and personal and professional references (although the exact requirements can vary depending on the building). If you’re purchasing a co-op, you’ll also need to prepare for an interview with the board. But don’t worry, your agent will guide you through the process, helping you put together your application and preparing you for the interview if necessary.
Being invited to a board interview a good sign, typically indicating your board package made a positive impression. Board interviews range in formality and size. You may meet the entire board in an office or conference room, or you may be interviewed by a few board members in an apartment.
Here’s our advice to se you up for success at a board interview
Dress professionally and be prompt.
Regarding dress and timeless, you should treat a board interview as you would a job interview. Dress appropriately, and arrive on time.
Be prepared for personal questions.
The co-op board has considerable leeway in the types of questions it can ask. Refrain from getting defensive, and do your best to answer all questions with poise and charm.
Know your application
Your should be able to quickly and accurately answer any questions about your board package. Bring a physical copy of your package in case you need to reference it.
Cooperate with any co-applicants
If you are being joined by another individual (i.e., your spouse), discuss beforehand which types of questions each of you will answer. Take care to avoid talking over each other or conferring about an answer in front of the board.
Don’t ask questions
Besides dress and promptness, do not think of your board interview as a job interview. Do not offer any personal information that isn’t explicitly asked for or thy to make small talk. Remember, this is the board’s interview - not yours.
Enjoy it!
Stay relaxed, confident, and polite. The board’s goal is to determine what kind of neighbor you’d be, so do your best to make a good impression!
Questions the board may ask include:
• Do you feel you can comfortably carry the mortgage and maintenance?
• Why did you choose this building/ neighborhood/apartment?
• Do you have any pets?
• Do you play instruments?
• Do you smoke?
• Do you entertain often?
• Are you planning on completing any renovations? so, what kind?
• Do you work from home?
Expect to wait at least one day to a week before you receive word of the board’s decision.
Your agent will accompany you on a final visit to survey the property and assemble a list of any outstanding items to be resolved before closing.
• Confirm outlets are in working order
• Test all light switches and light bulbs
• Check that outlet plates are straight and secure
• Turn oven, microwave, and any other kitchen appliances on and off
• Run dishwasher
• Confirm refrigerator and freezer are in working order
• Test garbage disposal
• Check vents and lighting
• Test each stove burner
• Check hinges and slides on cabinets and drawers
• Run hot and cold water in faucets, showers and/or bath, check the water pressure
• Open and close all windows
• Confirm windows properly seal when closed
• Test doorbell, intercom, alarm, etc.
• Flush all toilets
• Check for water damage or mold
• Check the condition of caulking, seals, and grout
• Test air conditioning and heating
• Check walls and floors for marks, stains dents, or other damage
• Run washer and dryer
• Test all locks
Once you receive board approval, the managing agents will usually set a closing date, which your attorneys will coordinate with the banks to ensure availability. After closing, you will officially own your new home. Congratulations, your search has finally come to an end! It’s time to celebrate this exciting milestone in your life.
“This is a great apartment. The rooms are enormous and the location is perfect. Thank you for finding it for us and expediting the process” DANNY DEVITO
“Brian Meier did what can only be called an outstanding job of selling our home in SoHo. He is an intelligent, hardworking agent who knows his field and every market very well.” MICHAEL CAPILOUTO
“Brian, you stood by us during all of the ups and downs. You found us the perfect short-term rental, then found us our dream cottage in the middle of New York City. You have been amazing.” GAVIN BONNAR
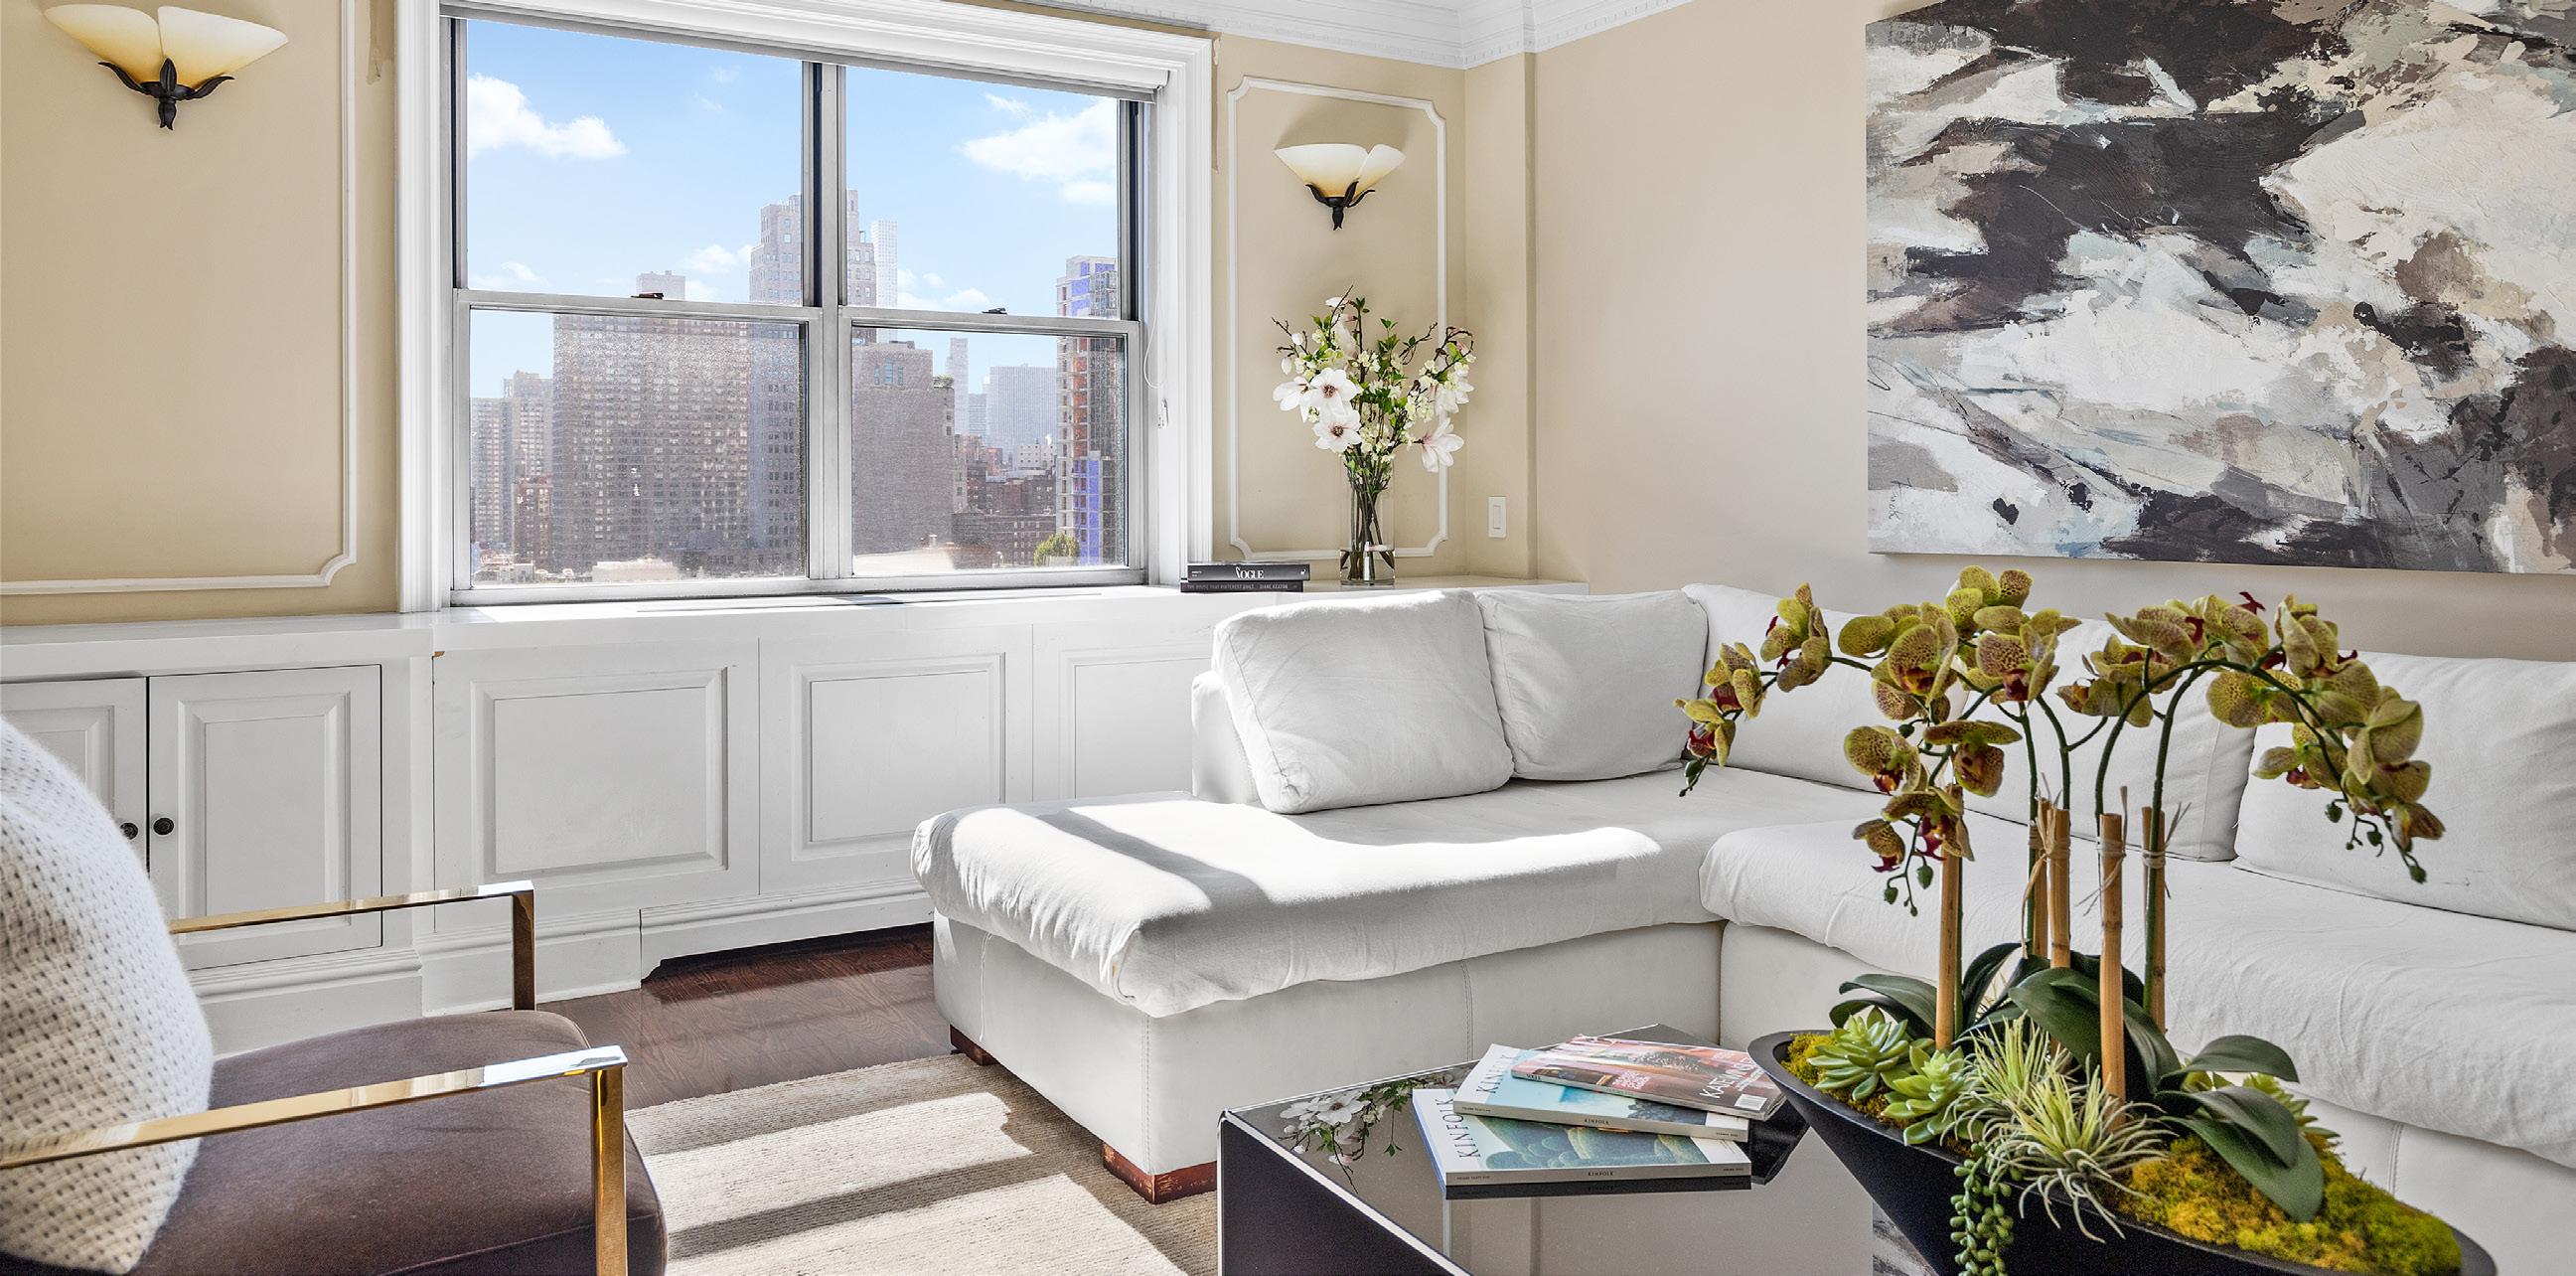
As new buildings continue to rise in New York, condominiums are becoming increasingly popular. Unlike co-ops, which are a different form of property ownership, a condominium represents real property ownership, akin to buying a house. Each condominium unit receives its own tax bill, while there is also a monthly common charge, similar to a co-op’s maintenance fee. However, these common charges do not cover real estate taxes and are not tax-deductible. Generally, common charges for condominiums are lower than those for co-ops, as there is no underlying mortgage for the building. The straightforward nature of purchasing a condo, combined with the ability to finance up to 90% of the purchase price and the freedom to sublet at will, makes condominiums a top choice for those seeking flexibility.
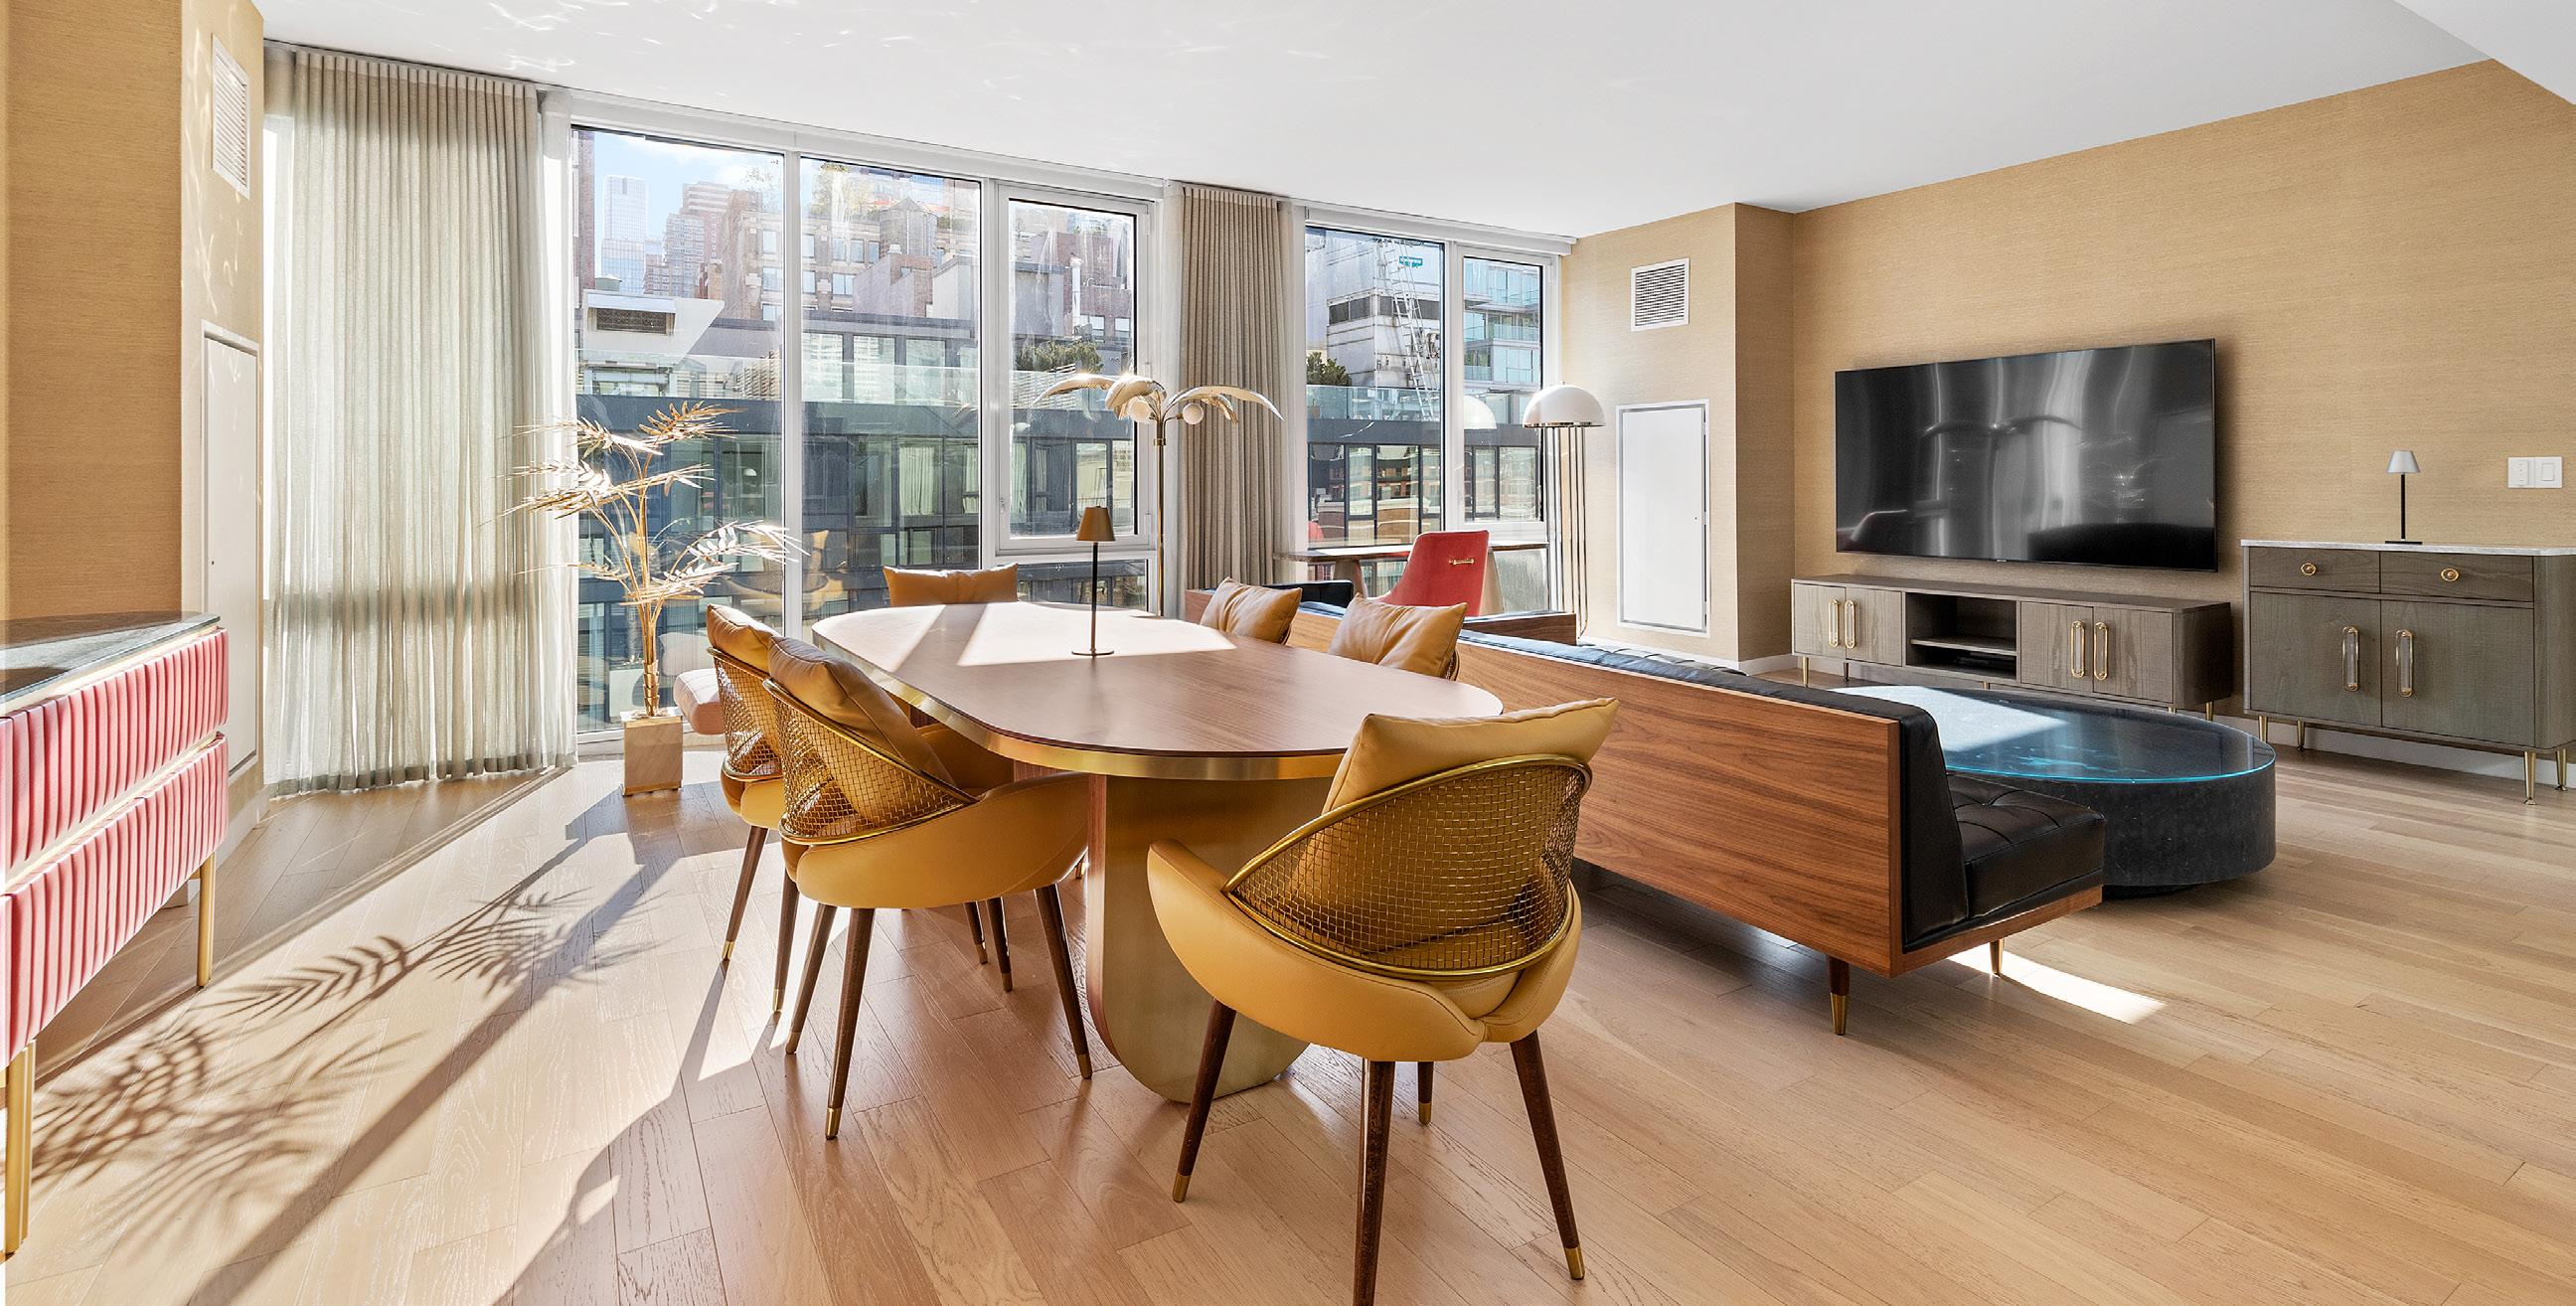
A phenomenon predominantly found in Manhattan, cooperative apartments have been a traditional way to own upscale residences for nearly a century. In New York City, 85% of all available apartments for purchase, and nearly all of the prestigious pre-war apartments on Fifth, Park, and Central Park West, are located in co-op buildings. When you buy into a co-op, you are purchasing shares in a corporation that grants you a proprietary lease. Generally, the larger the apartment, the more shares you own.
Co-op shareholders pay a monthly maintenance fee to cover building expenses, including heat, hot water, insurance, staff salaries, real estate taxes, and the building’s mortgage. Portions of these maintenance fees are tax-deductible due to the mortgage interest and real estate taxes of the building. The co-op board of directors decides the maximum amount of the purchase price that can be financed and sets minimum cash requirements. Subletting in a co-op can be challenging, as each building has its own rules that should be thoroughly reviewed before making an application.
Prospective buyers must undergo an interview with the board of directors and prepare a comprehensive board package, which typically includes personal and professional references, as well as detailed information on income and assets. Working with an experienced broker is invaluable in this process. Your broker can assist in finding a suitable apartment and preparing a board package that effectively presents your qualifications to the board of directors once you find the right home for you and your family.
The following information is typically needed when applying for a mortgage:
PURCHASE CONTRACT AND PROPERTY INFORMATION
• Copy of sales contract
• Mailing address and property description
• Contact information for access to the property
• Plans and specifications (new construction only)
PERSONAL INFORMATION
• Social Security number
• Age
• Years of schooling
• Marital status
• Number and ages of dependents
• Current address and telephone numbers
• Addresses for the past seven years
• Current housing expenses (rent, mortgage, insurance, taxes)
• Name and address of landlord or mortgage holder for past two years
EMPLOYMENT HISTORY AND INCOME
• Two years of employment history, with complete details of each job
• Recent pay stubs and two years of W-2 forms
• Complete tax returns and financial statements (if self-employed)
• Written explanation of employment gaps
• Records of dividends and interest received
• Proof of other income
• Complete information on all bank and money market accounts
• Two months of bank statements
• Current values of stocks, bonds, mutual funds and other investments
• Vested interest in retirement funds
• Value of life insurance
• Information on vehicles you own
• Information on any other real estate you own
• Value of significant personal property you own
• Itemized list of all current debts (loans, credit cards, and other bills) Written explanation of past credit problems
• Full details of bankruptcy during the last seven years
• Credit report and appraisal fees (usually $500 or less)
TIPS TO FOLLOW PRIOR TO PURCHASING YOUR HOME:
• Refrain from changing jobs
• Hold off on buying or leasing a car
• Be sure to maintain bank accounts at the same bank
• Hold onto your savings
• Avoid large credit card purchases
• Decline cosigning on loans
• Hold off on applying for new credit cards
Bank Fees: Varies according to bank and loan product
Bank Attorney $900 - $1,250
UCC-1 Filing Fee
- $125
Purchase Application Fee: $800 - $1,250
Mansion Tax:
Purchaser’s Attorney Fee Charge Adjustment Consult with attorney
Maintenance or Common
Audit Credit Fee
reimburses Seller for any prepaid maintenance or common charge payments
- $150 Move-In Fee
- $1,000
Cooperative Apartment Purchases Only Judgment and Lien Search
Financing/Recognition Agreement Fee
- $500
Managing Agent/Transfer Agent’s Fee $500 - $1,200
Condominium Apartment Purchases Only Title
Title and Municipal Search Fee
Deed Recording Fee
Mortgage Recording Fee
Unit Owner’s POA Recording Fee $100
Title Closer Attendance Fee $300
Purchaser’s Additional Closing CostsNew Construction:
Sponsor’s Attorney Fees (negotiable) $2,500 - $3,500
Sponsor’s NYC and NYS Transfer Taxes If paid by Purchaser, transfer taxes are
Resident Manager’s Apartment (if applicable) Calculated based upon Purchaser’s percentage of common interest in the building
A partnership with one world-class organization opens the door to a seamless partnership with our family of services companies. Berkshire Hathaway HomeServices New England, New York and Hudson Valley Properties and our partner companies are with you every step of the way.
Prosperity Home Mortgage (PHM) is a licensed mortgage banker offering free pre-approval. Mortgage & Financing Services
Marc Kunen
347.992.6846 | Marc.kunen@phmloans.com
HomeServices Insurance provides personal insurance coverage for home, auto, umbrella, and more written with top-rated local and national insurance companies.
Shawn Goode
917.743.1341 | Sean.goode@homeservices-ins.com
Providing a full suite of corporate mobility services associated with relocating a new hire candidate or transferring an employee. No opportunity too big or too small, from a single move to complex multi-state, group move programs
Jim LaBanca, Senior Vice President of Operations (800) 579-4432 | jimlabanca@bhhsne.com
The Berkshire Hathaway HomeServices Forever Concierge will help you manage your move and home management needs, all in one place. Your online dashboard includes access not only to vendor recommendations, but also a week by week task checklist that keeps track and suggests your next steps in the process.
GLOBAL RELATIONSHIPS
Built for a new era in residential real estate, the Berkshire Hathaway HomeServices brand has grown to over 50,000 agents worldwide and has presence across the U.S. and the globe. Berkshire Hathaway HomeServices New England, New York, and Hudson Valley Properties’ global reach can help you find properties anywhere in the world.
50,000+ AGENTS | 1,500+ OFFICES | 50 STATES 12 COUNTRIES & 3 CONTINENTS
United States, Canada, Mexico, Europe, Middle East, India & Bahamas
LOCAL EXPERTISE
Locally, Berkshire Hathaway HomeServices New England, New York and Hudson Valley Properties has nearly 2,200+ agents in 63 offices in Connecticut, New York, and Rhode Island. From Woodstock Connecticut to Woodstock New York and Narragansett Rhode Island to Manhattan, we share in our heritage and esteemed reputation as one of the most respected and admired companies in the world.
2,200+ AGENTS | 63 OFFICES | 3 STATES
Berkshire Hathaway HomeServices New York Properties opened its flagship office at 590 Madison Avenue in 2017. Led by industry icon Steven James, the 75 sales associates work closely with the New England and Hudson Valley Properties offices and agents.
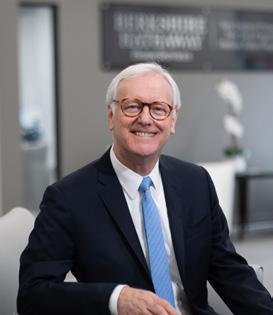
STEVEN JAMES President & CEO, BHHS
New York Properties
Having a trusted advisor guiding you through the homebuying process is crucial. With the right team by your side, what is often a stressful experience can become an exciting journey. Even after the purchase is complete, I look forward to maintaining our professional relationship and continuing to support you in any future needs.
To your home journey success... Let’s stay connected!