Smarter, Safer Logistics for the Data Centers of Tomorrow Worldwide Marketing Plan
1. Index & Objective
1 Index & Objective p 1-2
2. Executive Summary p.3-4
3 Situational Analysis p 6
4. Target Markets & Customer Segments p. 7-8
5 Marketing Objectives (SMART) p 9-10
6 Marketing Strategy p 11-12
7 Tactical Plan (7A-7F) 13-19
8 Implementation Timeline p 20
9. Budget Allocation p.21
10 Key Performance Indicators (KPIs) p 22
11. Risk Management & Mitigation Strategies p. 23-24
12 NEXUS Chart p 25-26
13 Key Target Customers p 27-33
14 Appendix 1: Global Datacenter Distribution p 35-36
15 Appendix 2: Global Datacenter Market 2025-2030 p 37-38
16. Appendix 3: Key Media Contacts p. 39-40
NEX·US ˈnek-səs plural nexuses or nexus -səs,ˌ süs : a connection or link between things, persons, or events especially that is or is part of a chain of causation.
NEXUS Mission Statement
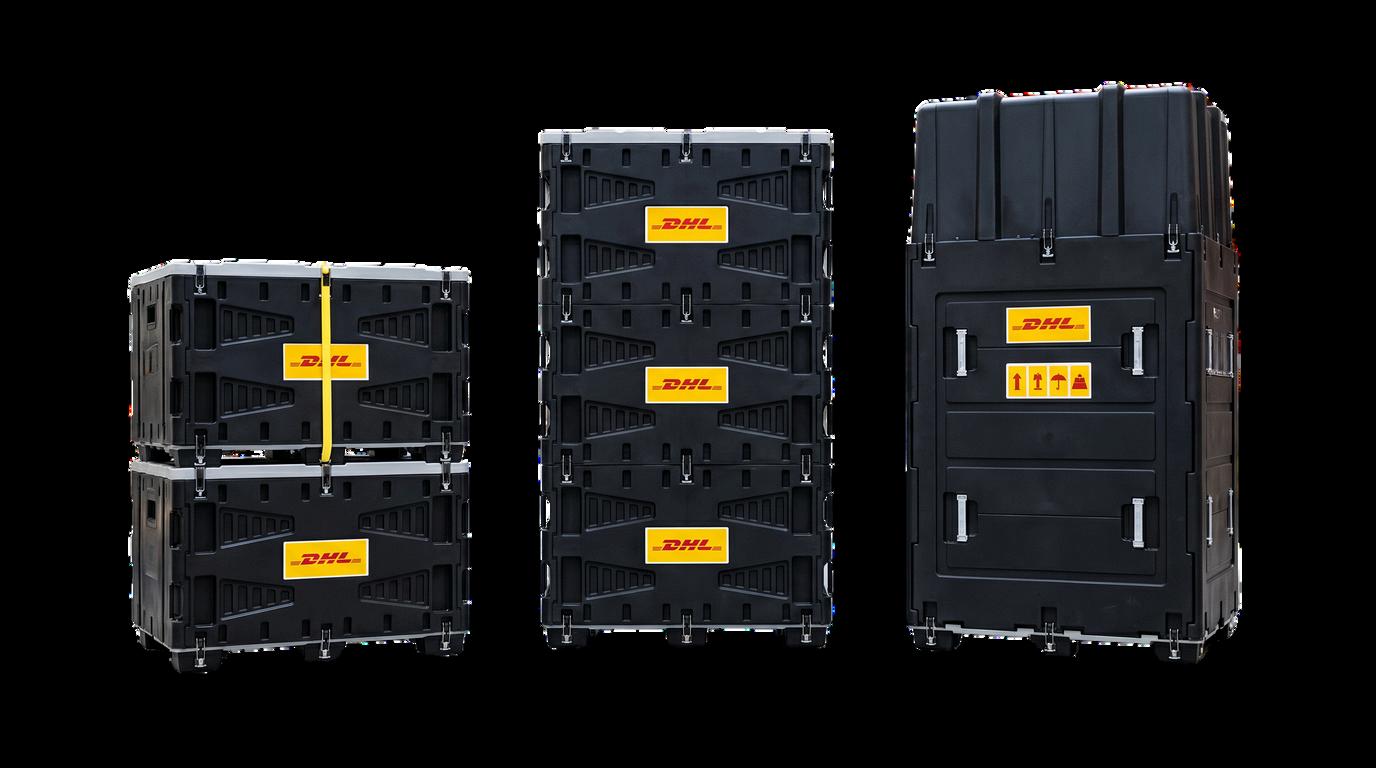
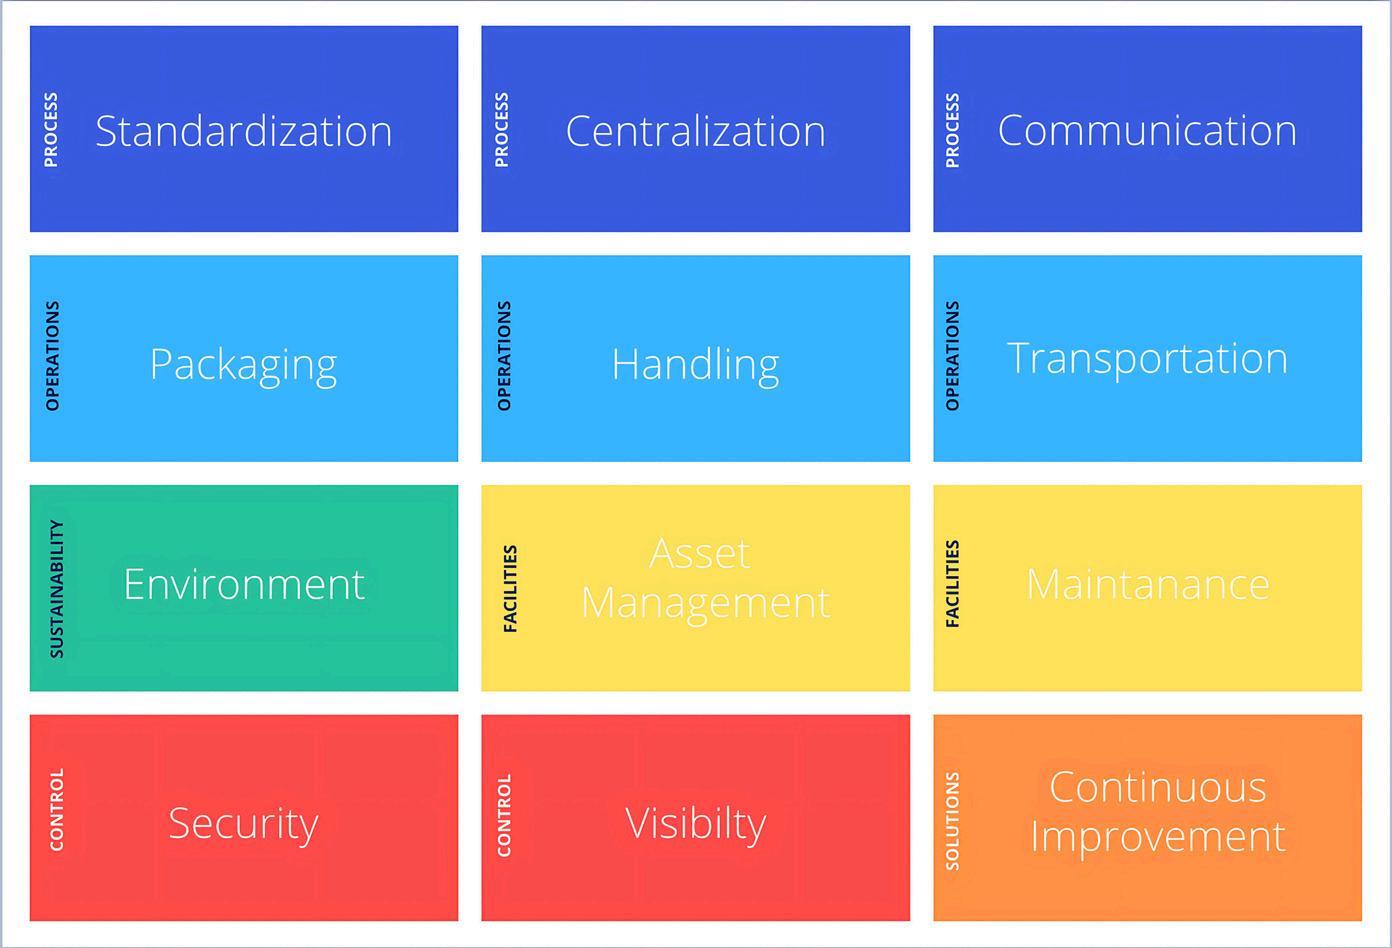
DHL + LARC “NEXUS”; a holistic, end-to-end solution for transporting Cloud, Datacenter, and AI products, designed as a fully integrated system that standardizes every step from loading to unloading. This solution centralizes packaging, handling, transport, and real-time communications, ensuring enhanced security, visibility, and efficiency. With a single-source point of contact, customers benefit from seamless coordination, continuous improvement, and a streamlined process that optimizes logistics while reducing risks and inefficiencies.
Worldwide Marketing Plan
Objective: Establish DHL + LARC NEXUS Product as the leading global solution for secure, sustainable, and efficient, lower cost transportation of high-value data center equipment, such as server racks, targeting data center operators, tech manufacturers, and logistics decision-makers.
Timeline: 12-month rollout starting Q3 2026 (August 2026) and concluding May 2027
Logistics for the AI Era
2. Executive Summary
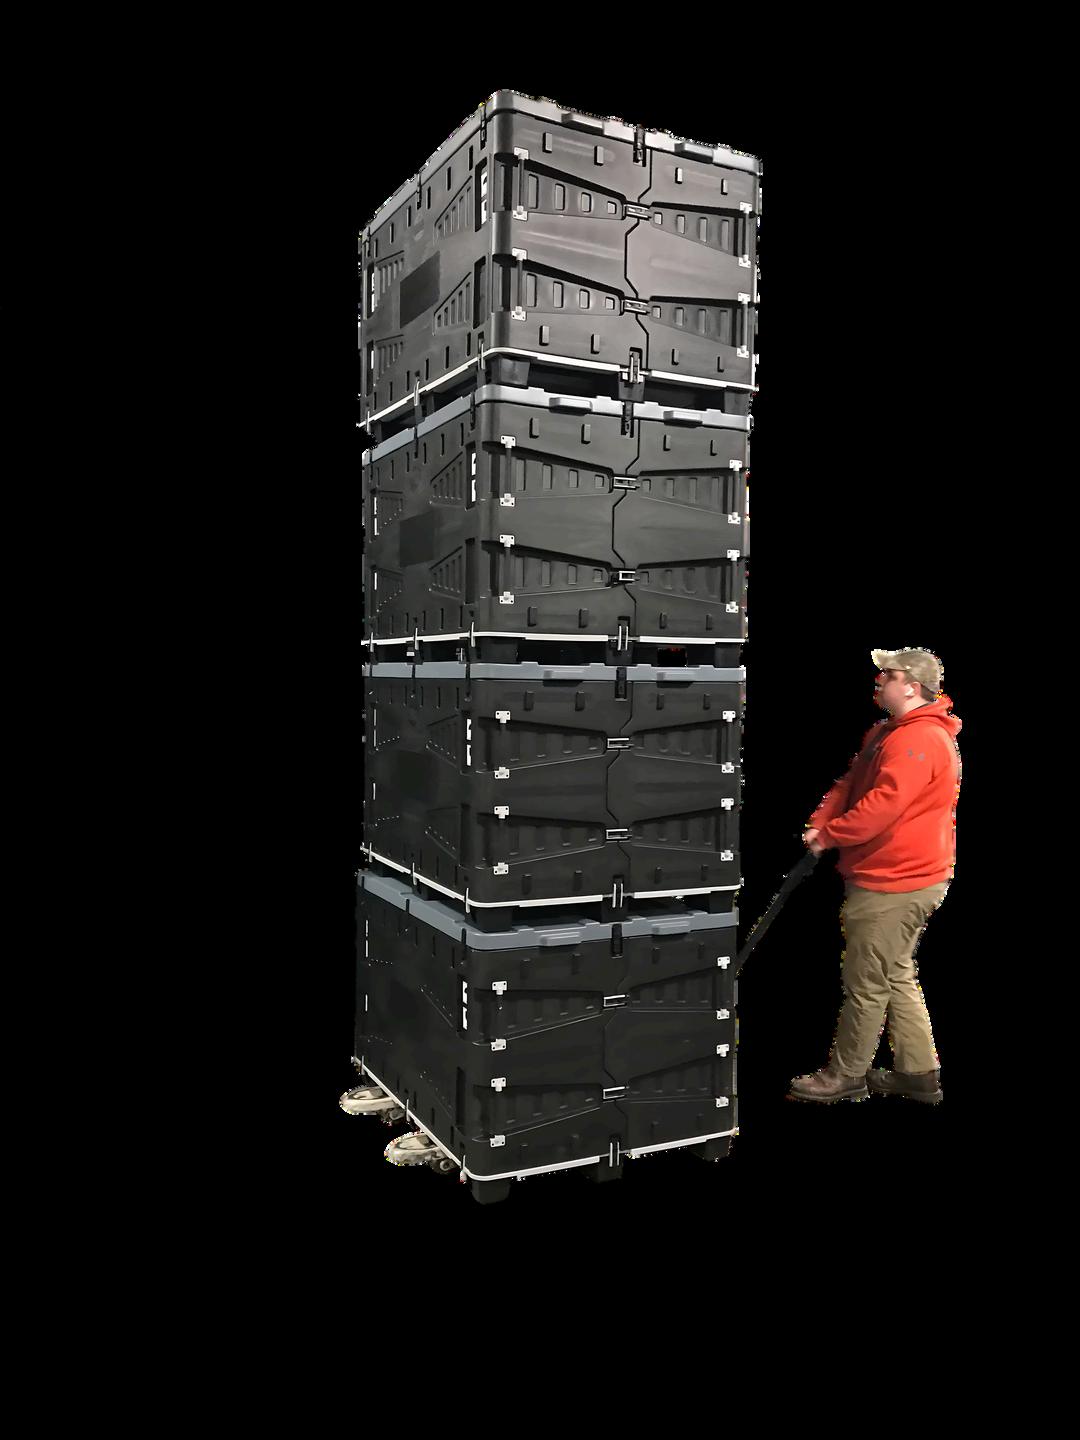
The partnership between LARC’s reusable, highly engineered crates and DHL’s unmatched global logistics network offers a differentiated solution for transporting server racks and other high-value data center equipment. This marketing plan leverages a multi-channel approach, PR, social media, direct email campaigns, road shows, and trade shows to build brand awareness, generate leads, and secure contracts with key stakeholders in North America, Europe, Asia-Pacific, and emerging markets With a focus on lower cost, standardization, sustainability, security, and scalability, the campaign targets the booming data center industry, projected to reach between US$700 billion and $1 1 Trillion by 2030
We call this overall product “NEXUS”.
3. Situational Analysis
Market Opportunity: The global data center market is expanding rapidly due to cloud computing, AI, and edge computing, driving demand for reliable, sustainable transportation solutions for server racks
Competitive Landscape: Competitors include traditional crate manufacturers (e g , TransPak, NEFAB) and other logistics players that offer undifferentiated solutions and services that are fragmented. DHL and LARC stand out with reusable crates and a fully integrated logistics ecosystem This NEXUS of product and logistics services can provide a complete holistic worldwide solution for this specific industry
Unique Selling Proposition:
LARC: Durable, reusable crates custom-engineered for high-value, fragile equipment, reducing waste and costs
DHL: Global reach with expertise in time-critical, high-value shipments across air, sea, and road.
Combined: A seamless, eco-friendly, and secure end-to-end solution for data center supply chains that is standardized, faster, more reliable, secure, visible and lower cost.
4. Target Markets & Customer Segments
Primary Target Customers
1. Cloud Service Providers:
Examples: AWS, Microsoft Azure, Google Cloud, Oracle, IBM.
Needs: Efficient logistics for rapid data center build-outs
Relevant: Address the growing need for sustainable logistics in the tech sector.
Time-bound: Achieve objectives by May 31, 2027
6. Marketing Stratagy
Positioning
Tagline: “Savings, Security, Sustainability – Powering Data Center Logistics."
Core Message: DHL and LARC (Nexus) provide a reliable, eco-friendly, and globally scalable solution for transporting server racks, reducing operational costs and environmental impact.
Execution: In-house DHL Social Team (LinkedIn Sponsored Content, YouTube)
7C. Tactical Plan - Road Shows
Goals:
Demonstrate the DHL-LARC solution in key markets, secure direct sales meetings. Target senior level operators/decision makers at each customer Engage in a “partnership” model
Locations & Dates:
Bonn, Germany: TBD (DHL Global HQ)
Silicon Valley, USA: TBD (Data Center Development Hub)
Frankfurt, Germany: TBD (European Data Center Capital)
Subject: "DHL Nexus: Revolutionizing Data Center Logistics"
Content: Partnership intro, 3 key benefits (secure, sustainable, global), link to landing page
Frequency: Weekly (4 emails), 50,000 total sends.
Consideration Phase (September 2026):
Subject: "See How DHL & LARC Protect Your Server Racks"
Content: Case study, demo video link, white-paper CTA
Frequency: Bi-weekly (4 emails), 40,000 total sends
Decision Phase (October 2026-January 2027):
Subject: "Ready to Partner?”
Content: Pricing teaser, demo booking link, urgency (e g , “Limited Q1 slots”)
Frequency: Monthly + drip campaigns for engaged leads, 30,000 total sends
7F. Tactical Plan - Digital Marketing
Goals:
Drive traffic to co-branded (white-labeled) landing page (dhl.com/larc).
Actions:
SEO: Optimize for “Data Center Logistics,” “Server Rack Shipping,” “sustainable crates ”
PPC: Google Ads targeting tech/logistics keywords, retargeting event
attendees
Email Integration: Sync with direct email campaigns for consistent messaging.
Landing Page: Features demo sign-up, case studies, contact form (tracked via Google Analytics)
Budget: TBD, DHL Marketing , ad spend, web development
8. Implementation Timeline (OPEN)
ResponsibleParty
9. Budget Allocation (TBD) - DHL Marketing Team
Phase 1
PR: (Partnership Release).
Social Media: (ads, content creation)
Road Shows: (1 event, DHL HQ)
Trade Shows: (No trade shows this Phase)
Direct Email Campaigns: (lists, tools, design).
Digital Marketing: (DHL Website/LARC)
Collateral: (videos, brochures, giveaways)
Direct Customer Email Blast:
Phase 2
PR: (DHL Marketing, media, white-papers).
Social Media: (ads, content creation, post)
Road Shows: (1 event)
Trade Shows: (booths, travel, staffing)
Direct Email Campaigns: (lists, tools, design).
Digital Marketing: (SEO, PPC)
Collateral: (videos, brochures, giveaways)
Direct Customer Email Blast:
Phase 3
PR: (DHL Marketing, media, white-papers)
Social Media: (ads, content creation).
Road Shows: (2 events, each)
Trade Shows: (2; booths, travel, staffing)
Direct Email Campaigns: (lists, tools, design)
Digital Marketing: (SEO, PPC).
Collateral: (videos, brochures, giveaways)
Direct Customer Email Blast:
Phase 4
PR: (DHL Marketing, media, white-papers)
Social Media: (ads, content creation)
Road Shows: (2 events)
Trade Shows: (2; booths, travel, staffing)
Direct Email Campaigns: (lists, tools, design)
Digital Marketing: (SEO, PPC, website)
Collateral: (videos, brochures, giveaways).
Direct Customer Email Blast:
3:1 ROI: x CRATES in Service
10. Key Performance Indicators (KPIs)
Leads Generated: 1,200+ (600 from email, 600 from events/social/PR)
Contracts Signed: 20 new clients (10% conversion from qualified leads).
Email Metrics: Open rate 25%, click-through 5%, conversion 2%
Social Engagement: 10,000 interactions (likes, shares, comments)
Event Attendance: 50+ decision-makers per road show/trade show.
Website Traffic: 25,000 visits to la
ROI: 3:1 return on marketing spe
11. Risk Management & Mitigation Strategies
Market Acceptance Risk: Customers may resist reusable crates due to cost or habit.
Mitigation: Educate on cost savings and sustainability; offer trials via DHL’s network
Competitive Pressure Risk: Rivals with alternative solutions may rise.
Mitigation: First mover advantage Patent Protection
Supply Chain Disruption Risk: Production or delivery delays could harm reputation
Mitigation: Forward load Crates at DHL hubs; use real-time tracking to manage issues
Cost Perception Risk: Buyers feel the superior performance will be more expensive
Mitigation: Educate on Packaging as a Service Model
Regulatory Compliance Risk: Global packaging laws may restrict market entry
Mitigation: Audit compliance across DHL’s regions; promote adherence as a strength.
Brand Alignment Risk: DHL and LARC messaging may confuse customers
Mitigation: White Label as DHL offering with LARC as support - NEXUS
Customer Adoption Logistics Risk: Reverse logistics for crate returns may falter
Mitigation: Use DHL’s network for efficient returns; offer managed services
Partnership Coordination Risk: Misaligned efforts could weaken marketing.
Mitigation: Form a joint task force; set clear KPIs and use DHL’s digital tools
Economic Fluctuation Risk: Downturns may cut demand for premium crates.
Mitigation: Target stable industries; adjust pricing as needed
Technological Obsolescence Risk: New packaging tech could outdate crates.
Mitigation: Innovate with smart features; market adaptability
Intellectual Property Risk: Competitors may copy LARC’s designs
Mitigation: Patent innovations; build loyalty via service excellence and Nexus offering
Scalability Risk: LARC’s production may not match DHL’s demand generation
Mitigation: Phase rollouts; scale production with DHL’s forecasting
Public Perception Risk: A crate failure could damage credibility
Mitigation: Ensure quality control; prepare crisis PR and showcase reliability.
NEXUS
NEXUS: A Seamless Logistics Solution
DHL and LARC have partnered to create NEXUS, a holistic, end-to-end solution for transporting Cloud, Datacenter, and AI products Combining LARC’s highly engineered reusable crates with DHL’s global logistics expertise, NEXUS standardizes every step from loading to unloading. This fully integrated system offers unmatched security, real-time visibility, and efficiency, with a single point of contact to simplify coordination Customers benefit from a streamlined process that reduces risks and inefficiencies, letting them focus on their core business while we handle the rest
Sustainable, Smart, and Future-Ready
NEXUS delivers massive environmental benefits through reusable crates and optimized transport, cutting waste and emissions while aligning with sustainability goals. With smart asset management, a unified data platform, and continuous improvement, it ensures cost savings, transparency, and innovation From protecting high-value tech to managing reverse logistics, NEXUS takes problems off your hands, offering a single, reliable solution that evolves with your needs and powers the future of logistics
Key Target Customers
Data Center Operators
Equinix - 240+ data centers globally, leader in interconnection and sustainability
Digital Realty - 300+ facilities, major REIT with hyperscale and colocation focus.
CyrusOne - 55+ data centers, scalable solutions across North America and Europe
NTT Global Data Centers - 95 data centers, 1,100 MW capacity, strong APAC presence
GDS Holdings - China’s top operator, serving hyperscalers like Alibaba.
QTS Realty Trust - 7M+ sq ft, Blackstone-owned, U S and Europe expansion
Black Box Corporation - Provides rack integration, cabling, and IT infrastructure solutions globally.
Vertiv - Designs and integrates rack enclosures, power, and cooling systems for data centers
Rittal - Specializes in server rack systems, enclosures, and climate control integration
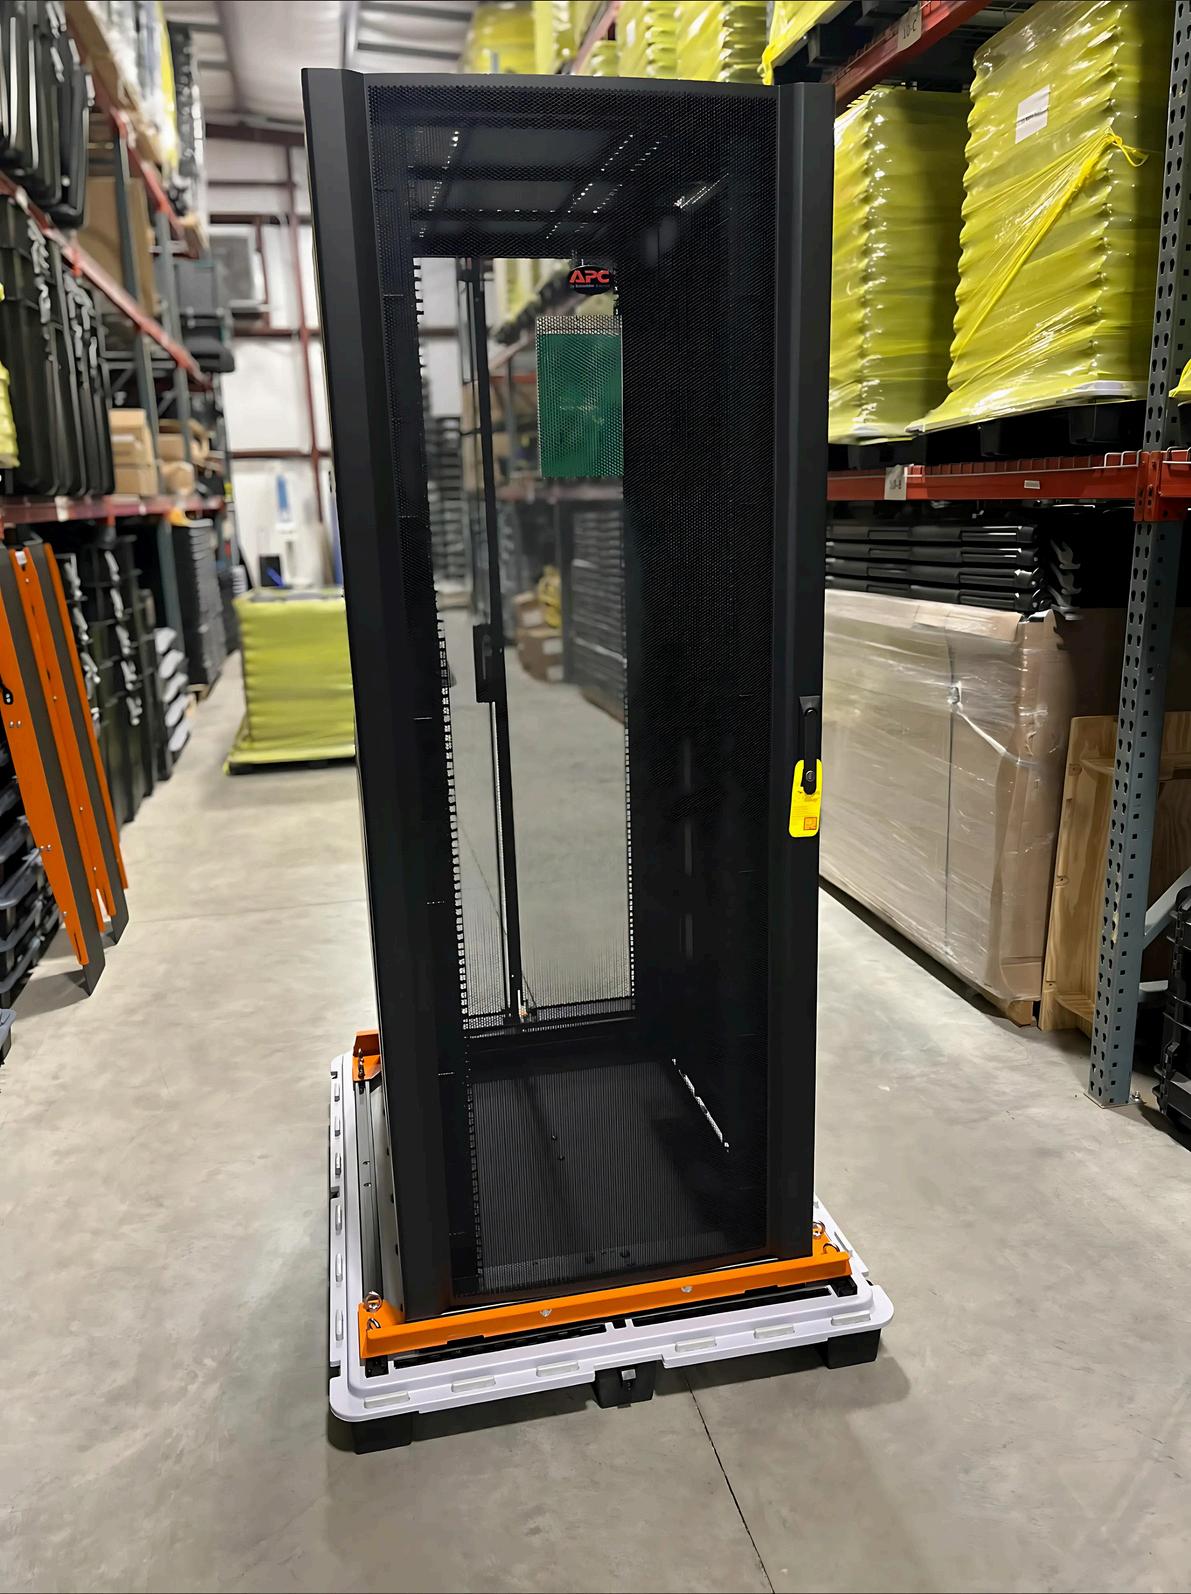
Schneider Electric/APC - Offers rack solutions via its APC brand, integrating power and IT equipment.
Tripp Lite (Eaton) - Integrates server racks, PDUs, and UPS systems for IT deployments
Panduit - Delivers rack and cabling infrastructure solutions for data centers.
Belden - Integrates server racks with connectivity and networking solutions
Chatsworth Products (CPI) - Custom rack systems and thermal management for data centers
Legrand - Provides rack integration through its AV and data center divisions (e.g., Middle Atlantic).
CommScope - Integrates racks with structured cabling and network infrastructure
Anixter (WESCO) - Distributes and integrates rack solutions for IT and data center clients
Graybar - Integrates server racks and electrical infrastructure for enterprise deployments.
CDW - IT solutions provider offering rack integration and data center services
SHI International - System integrator with rack deployment for enterprise IT.
Presidio - Integrates racks as part of managed IT and data center solutions
Rack Integrators
Insight Enterprises - Provides rack integration for data center and cloud deployments.
Connection (PC Connection) - IT integrator with server rack and hardware solutions
Zones - Integrates racks and IT equipment for enterprise and public sector clients
Softchoice - Canadian-based integrator for rack and data center infrastructure
Ahead - Specializes in data center modernization, including rack integration
Sirius Computer Solutions - IBM partner integrating racks for hybrid IT environments.
ePlus - Integrates server racks with networking and storage solutions
Converge Technology Solutions - Multi-regional integrator for rack and IT deployments
Logicalis - Global IT integrator with rack and data center services.
Atos - Integrates racks as part of IT infrastructure and digital transformation services
Dimension Data (NTT) - IT integrator with rack solutions for enterprise data centers.
Cannon Technologies - UK-based rack integrator with modular data center solutions
RahRah Technologies - Integrates high-density racks for AI and HPC workloads
Server Technology (Legrand) - Focuses on rack-level power distribution integration.
Enconnex - Custom rack solutions and integration for data center clients
RackSolutions - Designs and integrates custom server racks and mounting systems
Hypertec - Canadian integrator for rack-based IT and high-performance computing.
Avaap - Integrates racks as part of IT infrastructure consulting services
Curvature (Park Place Technologies) - Refurbished rack integration and support services.
Mainline Information Systems - IBM-focused integrator with rack deployment expertise
Trace3 - IT integrator with rack solutions for AI and cloud infrastructure
Redapt - Integrates racks for hyperscale and enterprise data centers.
Viaduct Technologies - Custom rack integration for specialized IT environments
Iron Systems - Integrates racks with OEM hardware for global deployments
Rack Integrators
Equus Compute Solutions - Custom server and rack integration for data centers.
Sabey Data Centers - Integrates racks within its colocation and design services
Great Lakes Data Racks & Cabinets - Manufactures and integrates custom rack solutions
ServerLIFT - Integrates rack handling and deployment solutions for data centers
AisleLok - Provides rack containment and integration for airflow optimization
Datacenter Dynamics (DCD) - Integrates racks as part of consulting and deployment services.
Cologix - Integrates racks within its colocation and interconnect offerings
Zayo Group - Integrates racks with network and colocation infrastructure
ColoHouse - Integrates racks for colocation and managed IT services.
Appendix 1: Global Datacenter Distribution
North America
Approximate Share: ~40-45% of global data centers
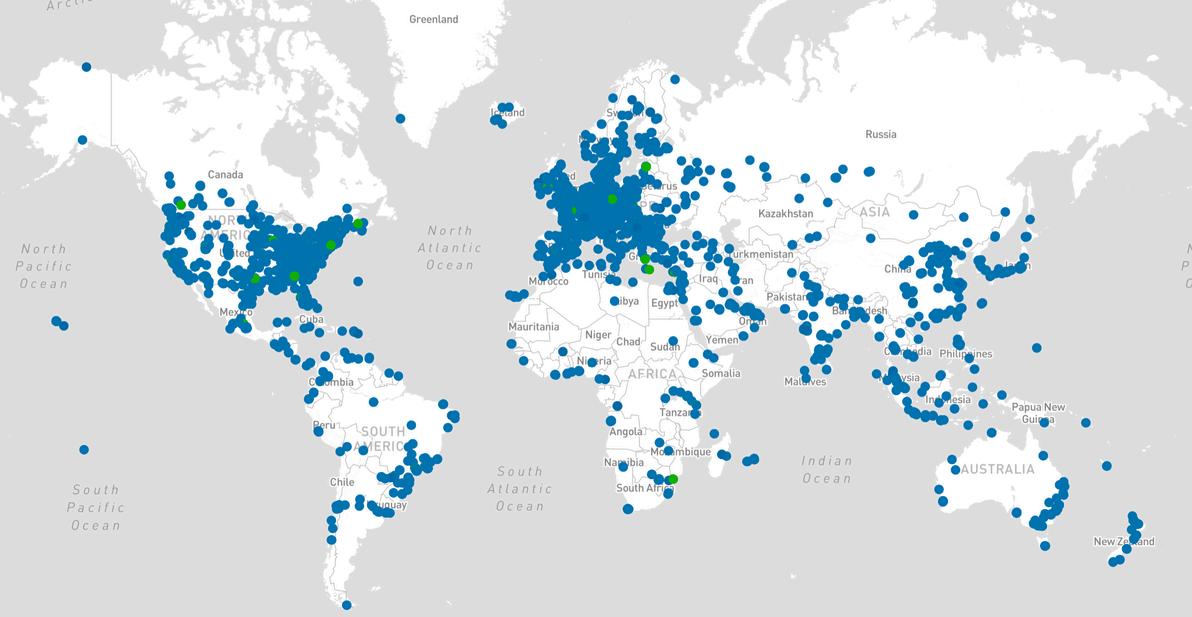
Key Details: North America, particularly the United States, dominates the global data center landscape. As of March 2024, the U.S. alone had around 5,381 data centers, accounting for roughly 45% of the world’s total according to some estimates. This region benefits from a mature tech ecosystem, abundant power resources, and major markets like Northern Virginia, Dallas, and Silicon Valley. Canada also contributes significantly, with over 300 data centers.
Europe
Approximate Share: ~25-30% of global data centers
Key Details: Europe hosts a substantial number of data centers, with around 1,500-2,000 facilities as of recent reports Major hubs include Germany (520+), the United Kingdom (510+), France (300+), and the Netherlands (280+) The "FLAP" markets (Frankfurt, London, Amsterdam, Paris) are particularly prominent, though growth is also strong in the Nordics and secondary markets like Madrid and Warsaw due to power availability and cooler climates
Souce: datacentermaps com
Asia-Pacific (APAC)
Approximate Share: ~20-25% of global data centers
Key Details: The Asia-Pacific region is the fastest-growing area for data center development, with approximately 1,800-2,000 facilities China leads with around 449 data centers, followed by Japan (200+), Australia (300+), and India (150+) Emerging markets like Singapore (99), Hong Kong (120+), and Southeast Asian countries (e g , Malaysia, Thailand) are seeing rapid expansion driven by cloud adoption and AI demand
Latin America
Approximate Share: ~3-5% of global data centers
Key Details: Latin America has a smaller but growing presence, with an estimated 500-650 MW of capacity across key markets like São Paulo (Brazil), Santiago (Chile), and Querétaro (Mexico). Brazil alone has around 163 data centers. Growth is fueled by increasing digitalization, though power constraints limit scale compared to other regions.
Middle East & Africa (MEA)
Approximate Share: ~2-5% of global data centers
Key Details: This region has the fewest data centers, with Africa accounting for less than 1% of global supply in some analyses. South Africa dominates the African market with about 50% of the continent’s capacity (e.g., facilities in Johannesburg). The Middle East, including hubs like Dubai and Riyadh, is emerging due to strategic location and cloud investments, but the total number remains low, likely under 300 facilities combined
Global Total
Estimates suggest there are between 10,000 and 11,800 data centers worldwide as of March 2024, with the number growing due to demand from AI, cloud computing, and digital transformation Hyperscale data centers (operated by giants like AWS, Microsoft Azure, and Google Cloud) are a significant subset, numbering over 1,100 globally, with more than 50% in the U S
Notes on Distribution
Concentration: The U S skews North America’s dominance, while Europe and APAC have more distributed growth across multiple countries.
Trends: APAC is projected to see the highest growth rate through 2030, potentially overtaking Europe in capacity as hyperscalers expand into markets like India and Southeast Asia. MEA and Latin America are also rising but from a smaller base.
Power and Size: This distribution reflects the number of facilities, not capacity or size. Hyperscale facilities in regions like North America and APAC tend to be larger and more powerintensive than smaller enterprise or edge data centers elsewhere.
Global Data Center CapEx (2025-2030)
The global data center industry is poised for significant growth between 2025 and 2030, driven by the escalating demand for data processing and storage. A substantial portion of this investment will be allocated to acquiring new servers to meet the increasing computational needs
Hyperscale Data Centers: The global hyperscale data center market is projected to grow from $162 79 billion in 2024 to $608.54 billion by 2030, reflecting a compound annual growth rate (CAGR) of 24 6% This surge underscores the substantial investments anticipated in expanding large-scale data center infrastructures GlobeNewswire
Data Center Support Infrastructure: Spending on data center support infrastructure, which includes critical components such as power systems, cooling solutions, and racks, is expected to reach $92 22 billion by 2030, growing at a CAGR of 8 2% from 2025 This indicates a parallel investment in the foundational elements that complement server installations Grand View Research
AI-Related Infrastructure: The proliferation of artificial intelligence is driving significant capital allocation, with global spending on AI-related infrastructure projected to exceed $300 billion in 2025. This encompasses investments in servers optimized for AI workloads, highlighting the critical role of advanced server technologies in supporting AI applications.
Appendix 3: Media Targets
Magazines and Blogs:
Data Centre Magazine: Connects leading data center executives globally, covering topics like edge computing, cloud, ESG, and hyperscale developments
DatacenterDynamics (DCD): Offers news, analysis, and opinion pieces on various aspects of the data center industry, including energy sustainability, cooling, and construction.
Mission Critical Magazine: Focuses on emergency backup, disaster recovery, security, and solutions for rising energy costs in the data center sector
InterGlobix Magazine: Dedicated to data centers, connectivity, luxury, and lifestyle, highlighting key industry players and innovations
Data Centre Review: Provides updates on the latest data center news, products, projects, and expert commentary
Data Centre & Network News (DCNN) Magazine: Covers industry news, product developments, insights, and opinions on data centers and networking.
Podcasts:
Inside Data Centre Podcast: Hosted by Andy Davis, this podcast explores trends in the data center industry through conversations with global industry leaders
DatacenterHawk: Provides insights into data center real estate, market trends, and industry analysis
Data Center Revolution: Focuses on innovations and transformations within the data center industry.
Not Your Father's Data Center: Discusses modern data center challenges and solutions
Appendix 3: Key Media Contacts
LinkedIn Groups:
Data Center Professionals: A private group with over 40,000 members, including directors, managers, operators, and technicians responsible for data center uptime
Data Center Pulse: A global group of data center owners, operators, and users focusing on discussions about the industry's future.
Data Center Engineering: Over 18,000 members discussing data center power infrastructure and related topics.
Data Center Knowledge: A companion group to the Data Center Knowledge publication, facilitating discussions on industry news and developments
Data Center Advisors: An open group with nearly 3,000 members, created for managers, operators, end-users of data centers, and vendors of data center products and services Discussions include data center conferences, design questions, migrations, power, product advice, security, and site selection
DatacenterDynamics: Global Discussion: A private group with over 16,000 members supporting a global conference producer of events for the data center industry Open to any data center professional, not just those attending DatacenterDynamics conferences.
DCRE | Colocation & Data Center Real Estate: Advertised as the largest data center real estate community, this open group has over 8,000 members and focuses on colocation and data center real estate topics.
Hosting Industry: A private group supporting over 19,000 members, addressing challenges surrounding connectivity, data centers, dedicated servers, rack space, and shared web hosting
Data Center Coalition: A membership association serving as the voice for the data center sector, representing and advancing the interests of the data center community
Data Center Group: Focused on consulting, design, professional construction, and operation of IT infrastructures and data centers
Data Center Service Group: Concentrates on servicing modern facilities, planning for future technologies, and working closely with facility teams to exceed expectations.
There are many other groups within LinkedIn to target