MARKET RESEARCH BRIEFING · 01
GLOBAL INDUSTRY ANALYSIS & FORECAST · 2026 –2035
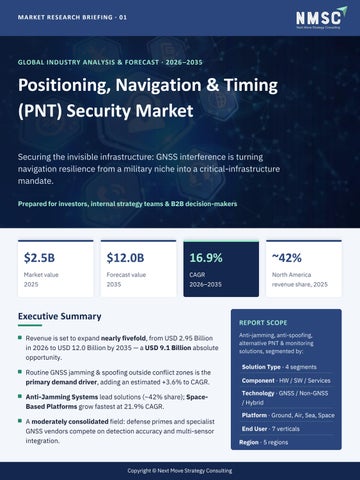
Positioning, Navigation & Timing (PNT) Security Market Securing the invisible infrastructure: GNSS interference is turning navigation resilience from a military niche into a critical-infrastructure mandate. Prepared for investors, internal strategy teams & B2B decision-makers
$2.5B
$12.0B
16.9%
~42%
Market value
Forecast value
CAGR
North America
2025
2035
2026–2035
revenue share, 2025
Executive Summary
REPORT SCOPE
Revenue is set to expand nearly fivefold, from USD 2.95 Billion in 2026 to USD 12.0 Billion by 2035 — a USD 9.1 Billion absolute opportunity. Routine GNSS jamming & spoofing outside conflict zones is the primary demand driver, adding an estimated +3.6% to CAGR. Anti-Jamming Systems lead solutions (~42% share); SpaceBased Platforms grow fastest at 21.9% CAGR. A moderately consolidated field: defense primes and specialist GNSS vendors compete on detection accuracy and multi-sensor integration.
Copyright © Next Move Strategy Consulting
Anti-jamming, anti-spoofing, alternative PNT & monitoring solutions, segmented by:
Solution Type · 4 segments
Component · HW / SW / Services Technology · GNSS / Non-GNSS / Hybrid Platform · Ground, Air, Sea, Space End User · 7 verticals Region · 5 regions
MARKET LANDSCAPE · 02
A nearly fivefold expansion: USD 2.5B in 2025 to USD 12.0B 12.0B by 2035 Global Revenue Forecast (USD Billion) KEY INSIGHTS 16.9% CAGR over 2026–2035, with value doubling by 2030 (USD 5.51B).
12.00 10.29 8.80
USD 9.1B absolute dollar opportunity added across the forecast window.
7.53 6.44 5.51
2.95
2.50
2025
2026
4.71
4.03
3.45
2027
2028
2029
U.S. is the single largest country market at ~USD 900 Million (2025).
2030
2031
2032
2033
2034
2035
Market Share Leaders vs. Fastest-Growing Segments Segment
Largest share (2025)
Share / value
Fastest growing (CAGR)
Solution
Anti-Jamming Systems
42% · $1.05B
Alternative PNT · 18.1%
Component
Hardware
58% · $1.45B
Software · 19.6%
Technology
GNSS-Based PNT Security
62% · $1.55B
Non-GNSS · 19.6%
Platform
Ground-Based Platforms
46% · $1.15B
Space-Based · 21.9%
End User
Defense & Military
46% · $1.15B
Gov. & Critical Infra. · 21.7%
Industry Ecosystem Hardware Suppliers
›
Software Developers
›
System Integrators
›
Network Operators
›
Defense Contractors & Critical Infrastructure
Regulatory bodies (DHS Resilient PNT framework, European Commission, FAA, EASA, ICAO) set protection baselines across the chain
Scope has evolved from niche military navigation warfare into a broad critical-infrastructure protection requirement spanning defense, aerospace, telecom, finance and GPS-tracking applications, with adoption shifting to multi-sensor fusion of GNSS, inertial and terrestrial timing. Source: Next Move Strategy Consulting
Copyright © Next Move Strategy Consulting
GROWTH DRIVERS & OPPORTUNITIES · 03
Interference has become routine — resilience is now a a procurement mandate Impact on CAGR — Drivers vs. Restraints (percentage points) +3.6
GNSS jamming & spoofing incidents outside conflict zones +2.8
Government resilient PNT mandates for critical infrastructure +2.1
Aviation regulator interference-detection guidance +1.7
Defense navigation-warfare investment +1.2
Finance & telecom reliance on precise timing +0.8
Government authentication infrastructure
−1.4
High multi-sensor fusion integration cost
−0.9
Fragmented national interference-reporting standards
−0.6
Limited vulnerability awareness (non-defense operators)
Demand Signals Reshaping Procurement Maritime: Baltic & North Sea
Aviation regulators
13 European coastal nations & Iceland issued a joint GNSS interference warning (Jan 2026); Sweden activated groundbased radio beacons.
FAA updated its GPS/GNSS Interference Resource Guide (2026); EASA revised its Safety Information Bulletin on jamming & spoofing.
Multi-sensor fusion as baseline
Authenticated signals
GNSS + inertial + precision timing is becoming a standard specification rather than a premium add-on.
European Commission anti-spoofing authentication service (Sep 2025); interference monitoring service planned for 2026.
WHITESPACE OPPORTUNITIES 2026–2035 01 Terrestrial backup networks — recurring contracts as coastal nations expand ground-based navigation. 02 Financial-sector timing — exchanges & clearinghouses need synchronized, resilient timestamps. 03 Authentication-ready receivers — early compatibility differentiates with government buyers.
Copyright © Next Move Strategy Consulting
HIGH-GROWTH SEGMENTS & REGIONS · 04
North America holds scale; Asia-Pacific sets the pace Growth Opportunity Map EUROPE · REGULATORY HOTSPOT HOTSPOT
NORTH AMERICA · LARGEST
Baltic interference & EC
~42% share (USD 1.05B, 2025). U.S.
authentication service drive
leads at ~USD 900M; DHS resilient-
urgent maritime/aviation demand.
PNT mandates.
ASIA-PACIFIC · FASTEST Highest regional CAGR of 19.0%; India is the fastest-growing country at 22.4%.
MIDDLE EAST & AFRICA Interference-led driver (+3.6 pts,
LATIN AMERICA Awareness-building market; cost and awareness restraints slow
with Europe); integration cost a key restraint.
adoption.
Segments Outpacing the 16.9% Market CAGR (2026–2035) India (country)
22.4%
WHERE CAPITAL SHOULD LOOK
Space-Based Platforms
21.9%
Gov. & Critical Infra.
21.7%
▸ Software & non-GNSS layers grow faster than hardware — recurring, higher-margin exposure.
Software
19.6%
Non-GNSS PNT Security
19.6%
Asia-Pacific (region)
19.0%
Alternative PNT Systems
18.1%
▸ Space-based platforms show the steepest platform trajectory. ▸ Civil critical infrastructure is the fastestrising buyer base beyond defense.
Mandate-led regions (North America, Europe) gain +2.8 pts from resilient-PNT conformance frameworks through 2033. Global aviation guidance adds +2.1 pts, pushing anti-spoofing receivers into commercial fleets. Asia-Pacific & Latin America remain awareness-constrained — first movers can shape specifications. Source: Next Move Strategy Consulting · Map is indicative; regional callouts summarize report findings
Copyright © Next Move Strategy Consulting
COMPETITIVE SCENARIO · 05
Defense primes vs. GNSS specialists: integration depth depth decides the winners Competitive Positioning Matrix WHITESPACE
DIVERSIFIED DEFENSE & AEROSPACE PRIMES
Authentication-ready receivers for government & defense
Integrated navigation-warfare & resilient timing
buyers — early movers differentiate on verified, tamper-
portfolios; long-term military contracts.
resistant data.
Edge: extensive military qualification credentials and
Also open: exchange & clearinghouse precision-timing
combined inertial + resilient timing delivery.
contracts, and terrestrial backup beacon networks for
Safran
Honeywell
RTX
Defense qualification ↑
coastal nations.
SPECIALIZED GNSS TECHNOLOGY VENDORS
ASSURED-PNT PLATFORM EXPANDERS
Receiver & antenna-level anti-jamming / anti-spoofing
Scaling GNSS+INS fusion via acquisition for aerospace,
chipset performance.
defense, robotics & UAV.
Edge: verified interference mitigation at component level,
Edge: 30,000+ deployed tactical-grade inertial systems
sold into OEM and civil infrastructure demand.
added for GPS-challenged environments.
Septentrio
u-blox
Infinidome
Hexagon
Component / receiver focus → Multi-sensor integration depth
Key Strategic Moves M&A
PRODUCT LAUNCH
INNOVATION & PARTNERSHIP
Safran acquired Orolia for an integrated resilient timing & navigation portfolio. Hexagon closed Inertial Sense (Apr 2026), adding 30,000+ deployed inertial systems.
u-blox launched ZED-X20P-01B (Apr 2026): global PPP, Galileo HAS and stronger jamming/spoofing resilience, verified at Jammertest 2025.
Honeywell is developing inertial systems, anti-spoofing receivers & sensor fusion after joint EASA–IATA workshops (2026).
MARKET STRUCTURE
20 VALIDATED KEY PLAYERS
Moderately consolidated Profiled leaders hold a majority of revenue; competition centers on detection accuracy, multi-sensor depth & chip-scale atomic clocks.
Safran S.A.
RTX Corporation
L3Harris Technologies
Northrop Grumman
Honeywell International
Hexagon AB
Trimble Inc.
u-blox Holding AG
Septentrio NV
Spirent Communications
Microchip Technology
Frequency Electronics
Chronos Technology
Infinidome Ltd
Rohde & Schwarz
Thales Group
BAE Systems plc
General Dynamics
Lockheed Martin
Leonardo S.p.A.
Copyright © Next Move Strategy Consulting
CONNECT WITH US · 06
Thank You Connect with our analysts for in-depth insights, custom segmentation and strategic guidance on the PNT Security Market.
OFFICIAL WEBSITE
CONTACT NUMBER
www.nextmsc.com
+1 857 758 5017
info@nextmsc.com
What the Full Report Delivers Investors: single-point market size & CAGR estimates for valuation and
$9.1B
capital allocation. Strategy teams: segment, end-user and regional forecasts for sourcing &
Absolute dollar opportunity, 2026–2035, with above-average growth in Asia-Pacific and government critical infrastructure.
resilience planning. B2B vendors: design requirements — sensor fusion, chip-scale atomic clocks, authentication compatibility. Custom deep-dives: threat-driven demand, defense procurement tracker, company product share.
Click here for the complete report → FOLLOW US gen-dedup-63b409fee2184c1cf53514e90cd05f53.png
gen-dedup-9cdb5b4ad6c11efaa59a12b4b80ec592.png gen-dedup-36349813c27d09978df16dfa34daa978.png
YouTube
gen-dedup-d7c128120f976aa58c328b4a55302f28.png
Copyright © Next Move Strategy Consulting
gen-dedup-905a6fe9d9fe45b77a06baca5fa8a960.png